
Pub 17, Appeals Procedures: Sales and Use Taxes and Special Taxes and Fees, is the California Department of Tax and Fee Administration (CDTFA) publication that explains how to dispute a decision about taxes or fees you owe. It follows an appeal from a Notice of Determination through the petition for redetermination, the appeals conference, the Office of Tax Appeals (OTA), the claim for refund and a court action, and it covers settlement and offers in compromise. On this page you can fill out the document online on FillingPDF and download or print the PDF; the CDTFA publishes the original and the forms it mentions at cdtfa.ca.gov.
Last updated
What is Pub 17?
Pub 17, Appeals Procedures: Sales and Use Taxes and Special Taxes and Fees, is the California Department of Tax and Fee Administration (CDTFA) publication that explains how to dispute a tax or fee decision, from a petition for redetermination to a claim for refund and court action.
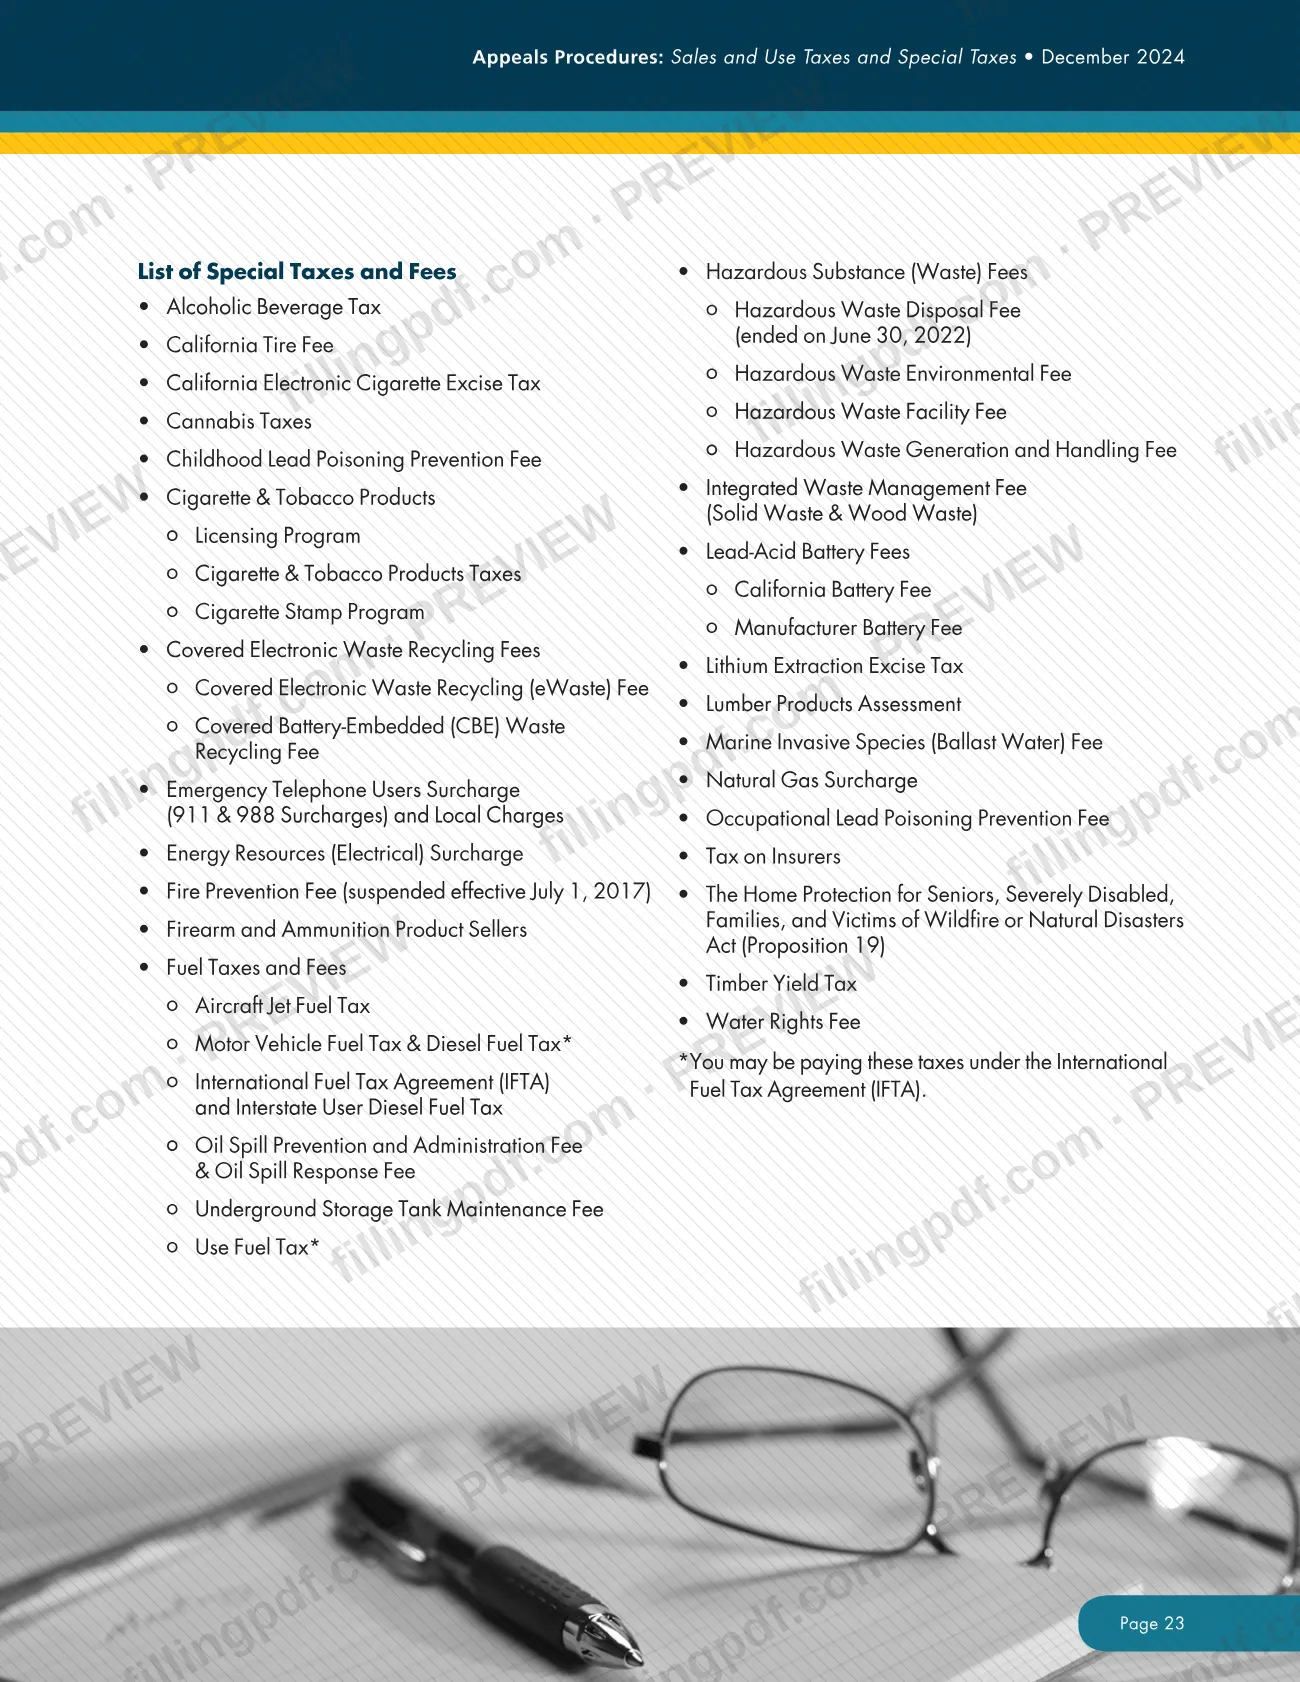
The CDTFA uses "special taxes and fees" to mean the business taxes and fees it administers other than sales and use taxes; the list is on page 23 of the publication. Pub 17 gives general information only. It says that if it conflicts with the law or regulations, decisions follow the law and regulations, and that procedures can differ slightly between sales and use tax appeals and special tax and fee appeals.
The publication covers these topics:
- Appealing a Notice of Determination by petition for redetermination, including the appeals conference, the Appeals Bureau decision and an appeal to the OTA.
- Filing a claim for refund, and filing a lawsuit if the claim is denied.
- Appealing a finding of successor's liability, an administrative protest and a jeopardy determination.
- Proposing a settlement, and the Offer in Compromise program.
- What happens to an appeal if you file a bankruptcy petition.
It points to related CDTFA forms: CDTFA-416, Petition for Redetermination; CDTFA-101, Claim for Refund or Credit; CDTFA-101-DMV; CDTFA-393, Settlement Review Request; CDTFA-392, Power of Attorney; and the Offer in Compromise applications CDTFA-490 and CDTFA-490-C. The CDTFA also lists Chinese, Korean, Spanish and Vietnamese editions (Pub 17-C, 17-K, 17-S and 17-V).
Who needs to file Pub 17?
Taxpayers and feepayers who disagree with a CDTFA decision about their liability for sales and use tax or for a special tax or fee are the main readers of Pub 17. Within that group:
- Businesses that received a Notice of Determination after an audit or other CDTFA finding and want to file a petition for redetermination.
- Anyone who paid an amount they believe they did not owe, whether under a Notice of Determination, with a return or otherwise, and wants to claim a refund.
- Buyers of a business or stock of goods who received a Notice of Successor's Liability.
- Taxpayers served with a Notice of Jeopardy Determination.
- Taxpayers with a pending appeal who want to propose a settlement. The settlement program does not apply to jet fuel taxes, motor vehicle fuel taxes or fire prevention fees.
- Taxpayers who cannot pay a final liability in full and want to know whether an Offer in Compromise fits. One requirement is that you are not currently disputing the liability.
You may act through an authorized representative; a petition or refund claim may be signed by you or your representative. For procedural questions about a specific tax or fee, Pub 17 tells you to call the CDTFA unit that administers it rather than rely on the publication alone.
When to file Pub 17
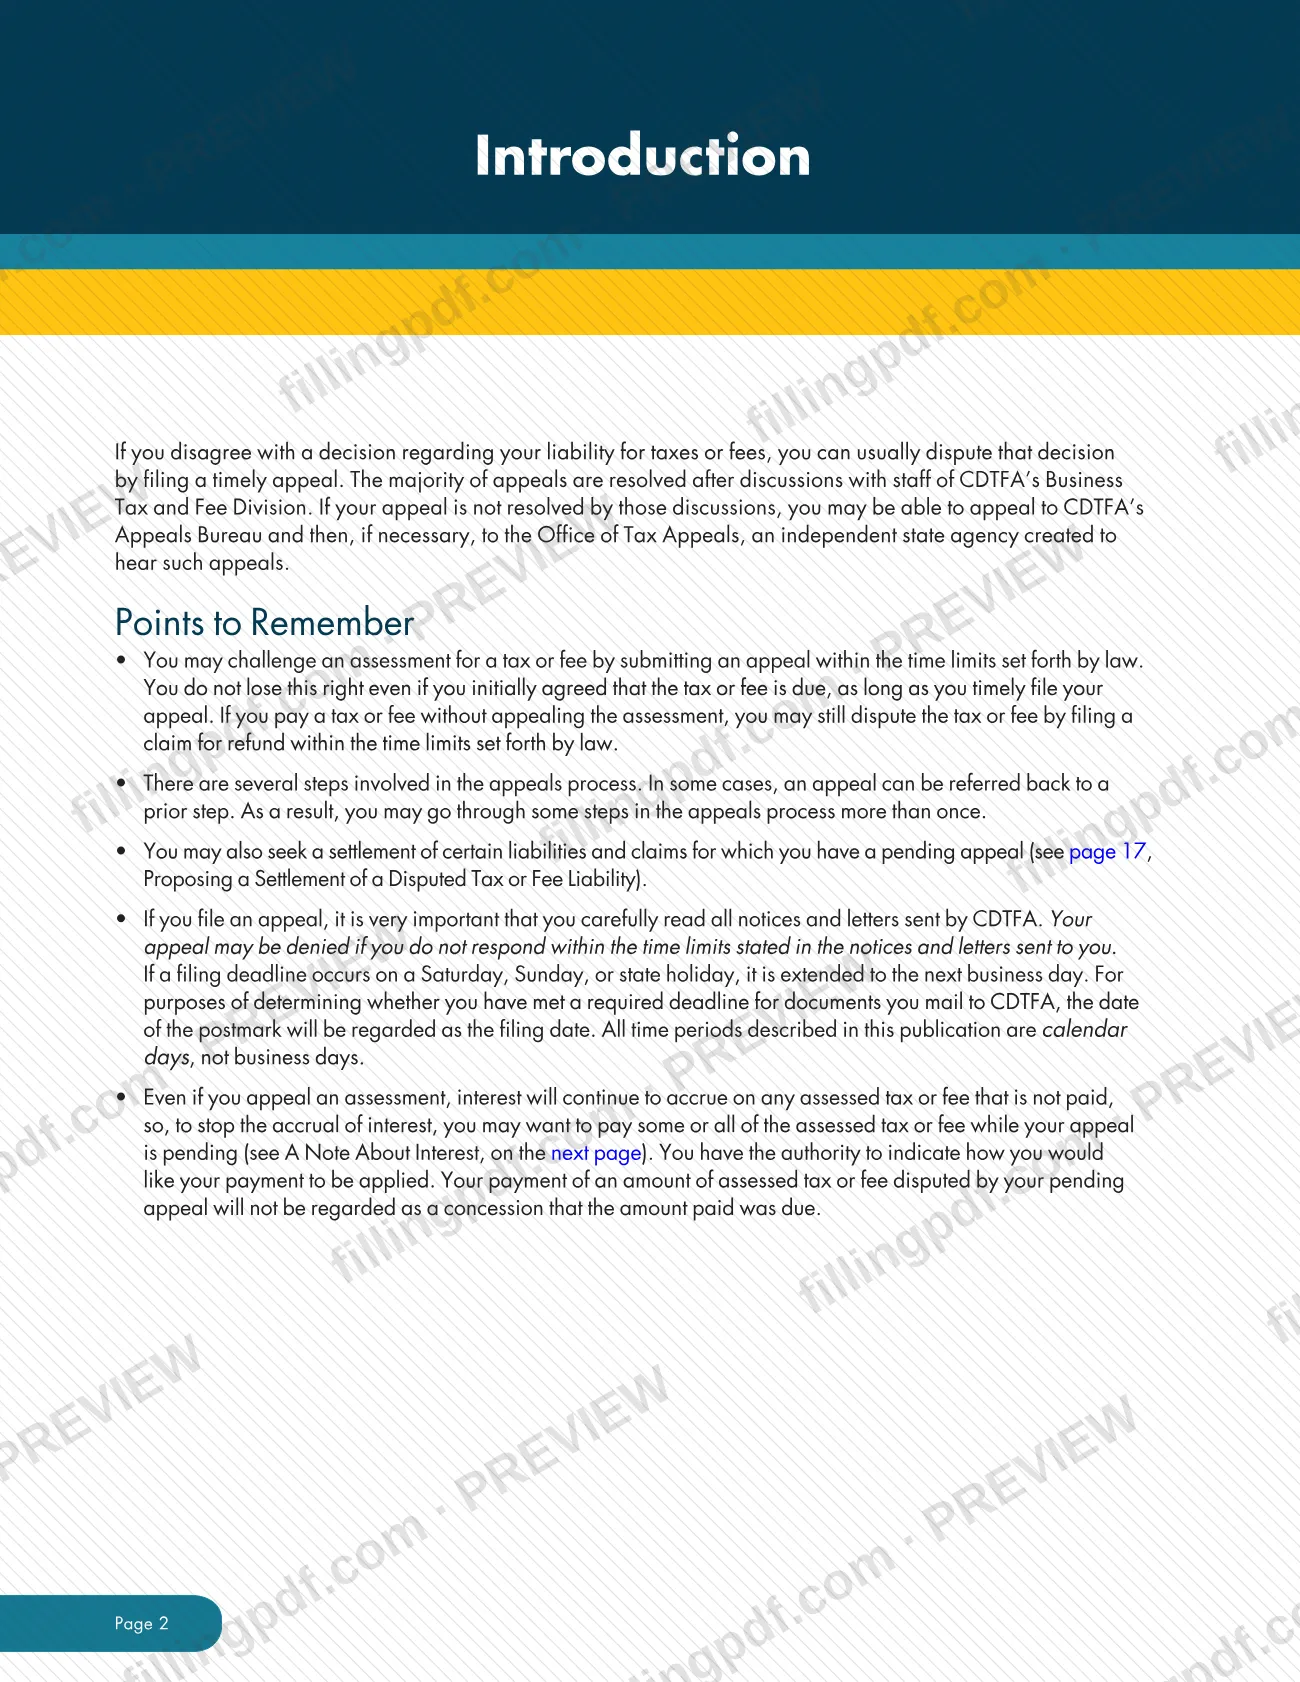
The clock starts when CDTFA sends you a notice, and each step has its own deadline. Generally you have 30 days from the date a Notice of Determination was mailed to file a petition for redetermination; a petition filed before the notice is issued is not valid. After a Notice of Jeopardy Determination you have ten days to file a petition with the required security deposit.
Other periods in Pub 17:
- Respond to a Business Tax and Fee Division letter within 30 days to request or confirm an appeals conference.
- Ask for reconsideration or appeal to the OTA within 30 days of the Appeals Bureau's letter on appeal options.
- File a lawsuit for refund within 90 days after CDTFA mails a Notice of Denial of Claim for Refund.
- Claims for refund of sales and use tax and most special taxes and fees are generally due by the later of three years from the return due date, six months from payment, or other dates the publication lists; check the law for your tax or fee.
Deadlines falling on a weekend or state holiday move to the next business day. The postmark date counts for mailed documents. All periods are calendar days.
Documents you need
- A written petition for redetermination, signed by you or your authorized representative, that includes your account number, the amounts you dispute if known, and the specific grounds. CDTFA-416 may be used, but no specific form is required.
- A written claim for refund, signed by you or your representative, stating all grounds, the reporting period, the refund amount if known, and contact information. CDTFA-101 or CDTFA-101-DMV may be used; a letter also works.
- Specific CDTFA claim forms for refunds of cigarette tax stamps and diesel fuel tax; contact the Appeals and Data Analysis Branch for them.
- The Verification of Appeals Conference form sent when your case is referred to the Appeals Bureau, returned within 15 days.
- The Response to Notice of Appeals Conference form sent with the conference notice, returned within 15 days.
- For a jeopardy determination: a petition filed with the deposit of security in the amount specified in the notice.
- For a settlement request: your contact details, taxpayer account number, type of tax or fee and periods, and CDTFA-392, Power of Attorney, if a representative acts for you.
How to fill out Pub 17
Read your CDTFA notice and deadline
Identify the notice you received, such as a Notice of Determination or Notice of Jeopardy Determination, and note its mailing date. Count the periods in Pub 17 in calendar days.
Choose petition or claim for refund
If you disagree with a determination, file a petition for redetermination. If you already paid an amount you believe you did not owe, file a claim for refund.
Prepare your written petition
State your tax or fee program account number, the amounts you dispute and the specific grounds. Sign it yourself or have your authorized representative sign.
Add conference or settlement requests
You may request an appeals conference in the petition, and ask for review under the Administrative Settlement Program by checking the box on CDTFA-416.
Prepare a claim for refund if needed
Write or complete CDTFA-101 (or CDTFA-101-DMV for use tax paid to the DMV) with all grounds, the reporting period, the refund amount if known and contact information.
Pick the right CDTFA unit
Sales and use tax petitions and refund claims go to different units than special tax and fee ones. Check the addresses under How to submit.
Return conference forms on time
If your case is referred to the Appeals Bureau, return the Verification of Appeals Conference and later the Response to Notice of Appeals Conference within 15 days each.
Review and download the PDF
Check names, account numbers and deadlines, then fill out the PDF online on FillingPDF and download or print it. Submit documents through the CDTFA channels described under How to submit.
How to submit Pub 17
Pub 17 is a guide and is not itself filed. The documents it describes go to CDTFA through your online account at www.cdtfa.ca.gov, or by email, fax or mail.
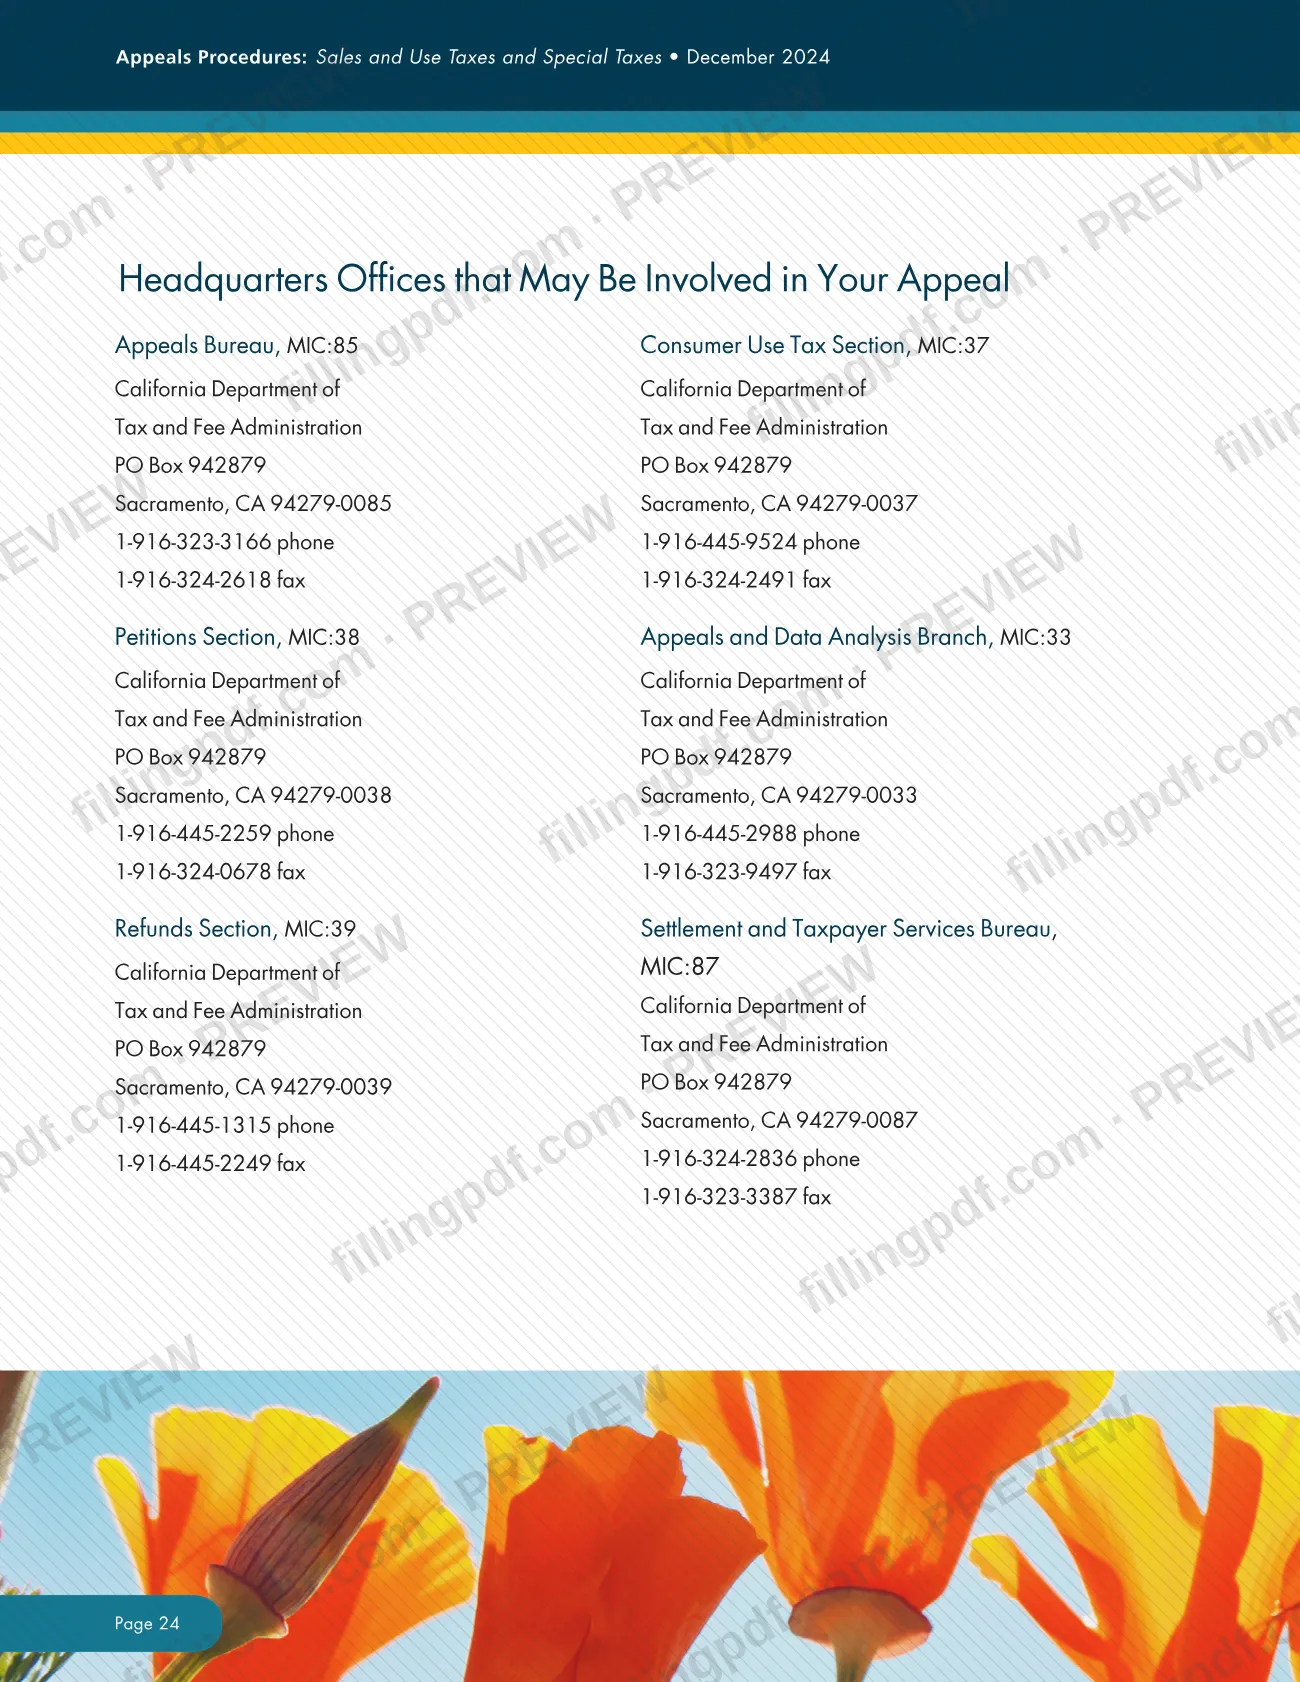
- Petition for redetermination, sales and use tax: email [email protected], fax 1-916-324-0678, or mail Petitions Section, MIC:38, California Department of Tax and Fee Administration, PO Box 942879, Sacramento, CA 94279-0038.
- Petition, special tax or fee: email [email protected], fax 1-916-323-9497, or mail Appeals and Data Analysis Branch, MIC:33, California Department of Tax and Fee Administration, PO Box 942879, Sacramento, CA 94279-0033.
- Claim for refund, sales and use tax: email [email protected], fax 1-916-445-2249, or mail Refunds Section, MIC:39, PO Box 942879, Sacramento, CA 94279-0039. Use tax paid to the DMV and special taxes and fees have separate units; see page 11.
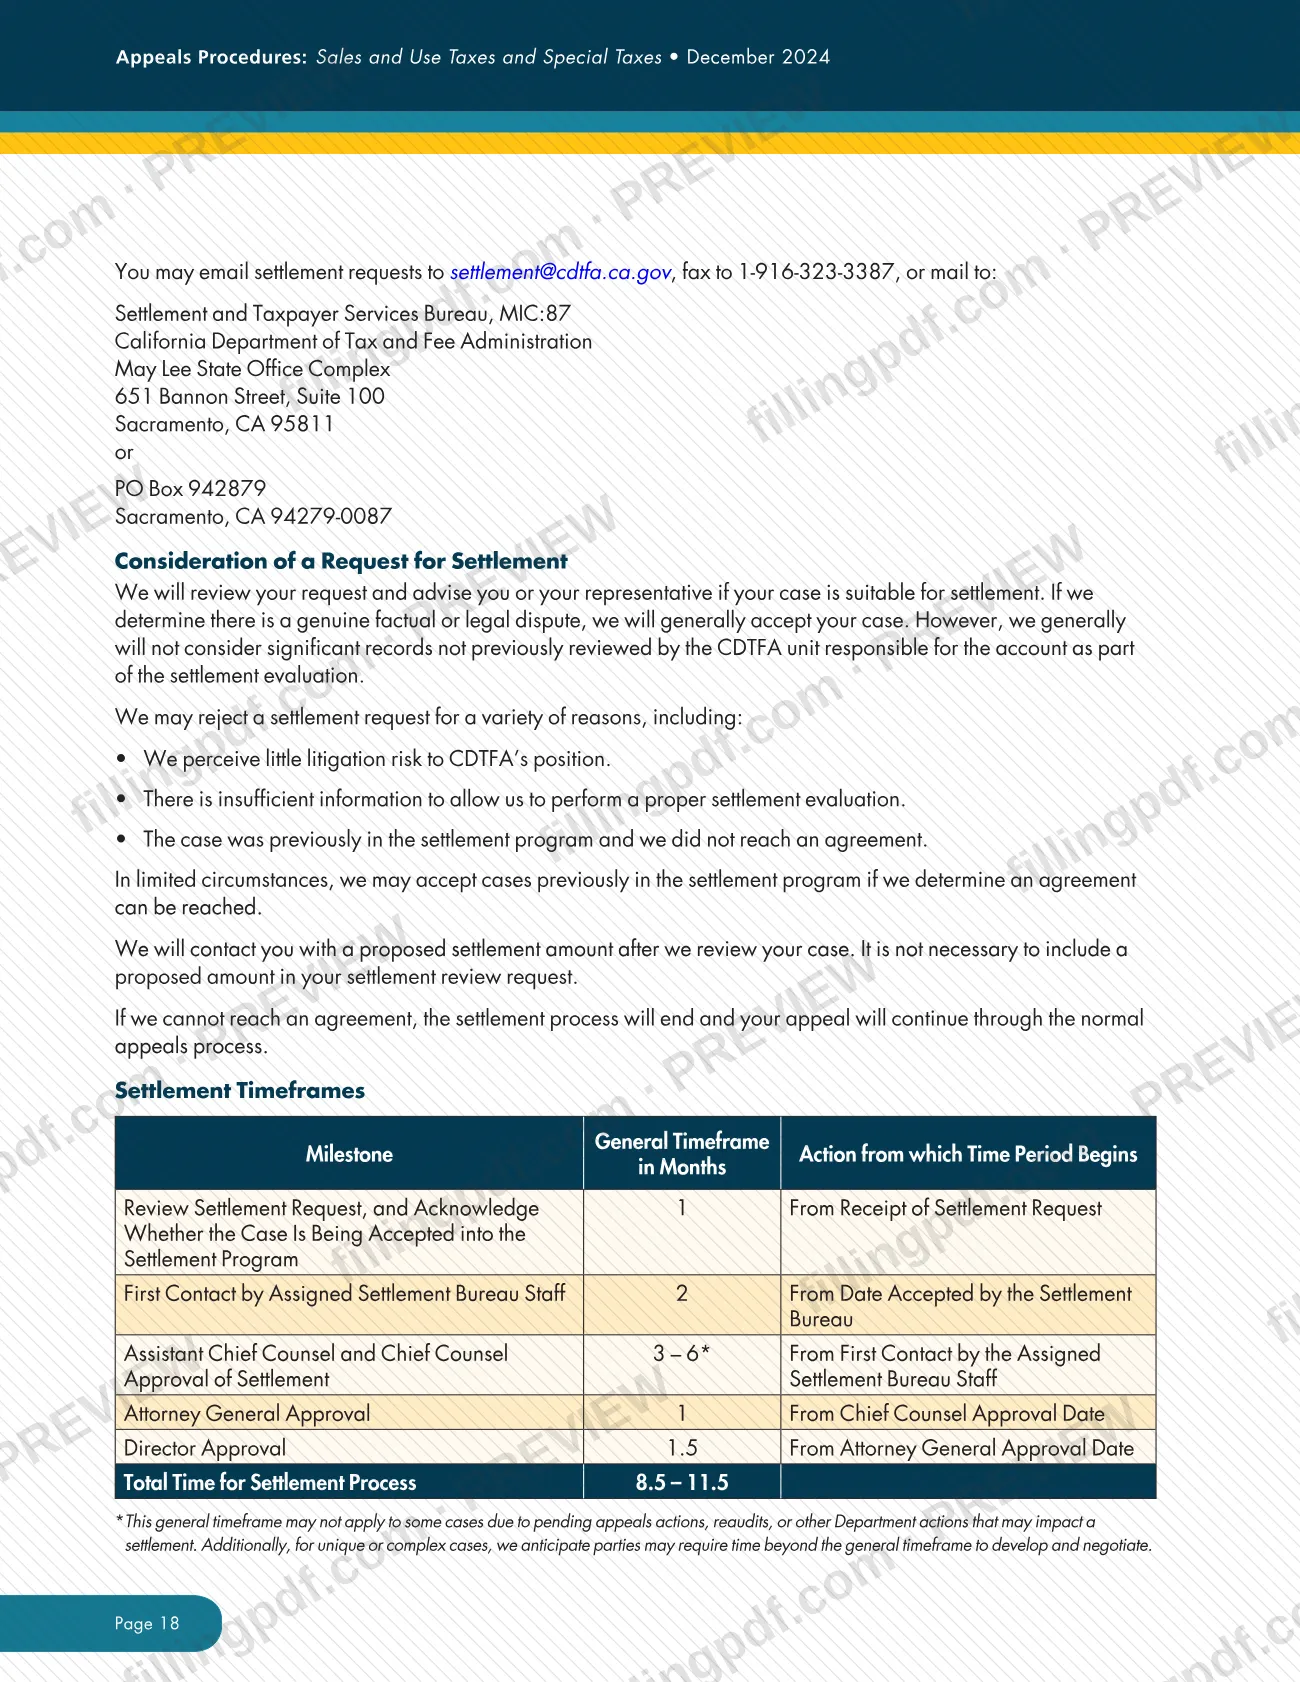
- Settlement request: email [email protected], fax 1-916-323-3387, or mail Settlement and Taxpayer Services Bureau, MIC:87, 651 Bannon Street, Suite 100, Sacramento, CA 95811, or PO Box 942879, Sacramento, CA 94279-0087.
A petition or refund claim properly submitted through your online account counts as written and signed. The Customer Service Center is 1-800-400-7115 (TTY:711). FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Filing a petition before the Notice of Determination is issued; an appeal filed that early is not a valid petition.
- Filing a petition after the 30-day deadline and expecting it to count; a late appeal is not a valid petition and the liability becomes final.
- Not answering the Business Tax and Fee Division letter within 30 days; the appeal ends and a Notice of Redetermination is issued.
- Assuming an appeal stops interest; interest keeps accruing on unpaid assessed amounts while the appeal is pending.
- Missing the filing period for a claim for refund; CDTFA cannot refund any amount without a timely claim.
- Filing a lawsuit for refund more than 90 days after the Notice of Denial of Claim for Refund was mailed.
- Expecting an administrative protest or hearing application to cover amounts already paid; a refund claim is still needed for those.
- Submitting a settlement proposal less than five days before an OTA hearing, which may be found not conducive to settlement.
- Stopping settlement deadline tracking; you must keep meeting appeal deadlines while a settlement request is pending.
Frequently asked questions
What is CDTFA Pub 17?
Pub 17 is the CDTFA publication titled Appeals Procedures: Sales and Use Taxes and Special Taxes and Fees. It explains how to dispute a tax or fee decision through a petition for redetermination, a claim for refund, the Office of Tax Appeals and court, plus settlement and Offer in Compromise options.
How long do I have to file a petition for redetermination?
Generally 30 days from the date the Notice of Determination was mailed to you. For a Notice of Jeopardy Determination it is ten days, and the petition must come with the required deposit of security. A petition filed late is not valid.
Do I have to pay the tax while my appeal is pending?
No, but interest keeps accruing on unpaid assessed amounts. You may pay some or all while the appeal is pending to stop interest, and you can say how the payment is applied. Paying is not a concession that the amount was due.
Can I still appeal if I missed the 30-day deadline?
Possibly. You can pay the tax or fee and file a timely claim for refund. CDTFA may also accept a late appeal as an administrative protest if there may be an error, but you then have no absolute right to a conference or OTA appeal.
Where do I send a petition for redetermination?
File through your online account at www.cdtfa.ca.gov, or for sales and use tax email [email protected], fax 1-916-324-0678 or mail Petitions Section, MIC:38, PO Box 942879, Sacramento, CA 94279-0038. Special taxes and fees use the Appeals and Data Analysis Branch.
What is the deadline for a claim for refund?
For sales and use tax and most special taxes and fees it is generally the later of three years from the return due date or six months from payment, with other rules for determinations and collections. Pub 17 says to check the law for your tax or fee.
What if CDTFA denies my claim for refund?
You may request an appeals conference, which CDTFA grants at its discretion, or file a lawsuit for refund within 90 days after the Notice of Denial of Claim for Refund was mailed. Missing that 90-day period ends your appeal.
Is there a Spanish version of Pub 17?
Yes. The CDTFA lists Pub 17-S, Procedimientos de apelación, along with Chinese (Pub 17-C), Korean (Pub 17-K) and Vietnamese (Pub 17-V) editions. Those are dated December 2024, while the English edition is dated November 2025.
Can I fill out Pub 17 online on FillingPDF?
You can fill out the PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file anything with the CDTFA; petitions and claims go through the CDTFA channels.
Ready to fill out Pub 17?
Fill out Pub 17 now