
Pub 47, Mobilehomes and Factory-Built Housing, is the publication in which the California Department of Tax and Fee Administration (CDTFA) explains how California's sales and use tax laws apply to mobilehomes and factory-built housing. Dealers, manufacturers, lessors, contractors and buyers use it to work out whether sales tax or use tax applies and on what amount. Its appendix holds a sample transaction and two certificates. On this page you can fill out the form online on FillingPDF and download or print the completed PDF; the CDTFA publishes the original at cdtfa.ca.gov.
Last updated
What is Pub 47?
Publication 47, Mobilehomes and Factory-Built Housing, is the CDTFA publication explaining how California's sales and use tax laws apply to mobilehomes and factory-built housing, including dealer sales, leases, used mobilehomes and exemptions.
The California Department of Tax and Fee Administration (CDTFA) uses the term "mobilehome" instead of "manufactured home" because related state regulations do. The publication covers dealer sales and leases of new mobilehomes, dealer purchases and use, consumer purchases from out-of-state dealers and manufacturers, related exemptions, mobilehomes and accessories installed as real property, used mobilehomes, factory-built housing, and general tax information such as sales tax reimbursement, bad debts and recordkeeping.
It supplements publication 73, Your California Seller's Permit. It is a guide, not a return: it does not address property tax, mobilehome registration or building permits. If its text conflicts with the law, decisions are based on the law and regulations.
The appendix contains a sample transaction, a sample 60% exclusion certificate for factory-built housing, and CDTFA-47, Certification of Exemption for Mobilehome Residence Purchase. Recreational vehicles and commercial coaches are covered in publication 34, Motor Vehicle Dealers, not here.
Who needs to file Pub 47?
Mobilehome dealers and manufacturers use Pub 47 to learn when they are a "retailer-consumer" that owes use tax on 75 percent of its purchase price, and which accessories and charges are taxed as retail sales.
Other readers it addresses:
- Lessors of new or used mobilehomes.
- Consumers who buy a new mobilehome from an out-of-state dealer or manufacturer for delivery in California.
- Construction contractors who install mobilehomes or accessories on permanent foundations.
- Buyers and sellers of used mobilehomes, including family sales that may be exempt.
- Native American purchasers living on a reservation, and retailers who sell to them.
- Sellers and buyers of factory-built housing, including factory-built school buildings.
Purchasers who buy a mobilehome for residential use sign the appendix certification CDTFA-47. Buyers of factory-built housing for residential or patient-care use give the seller a 60% exclusion certificate.
Questions about property tax go to the county assessor. Registration and licensing questions go to the Department of Housing and Community Development (HCD).
When to file Pub 47
Pub 47 sets no filing deadline of its own; timing depends on the transaction it describes. A dealer who is a retailer-consumer must obtain and keep written certification at the time of the sale that the customer will use the mobilehome as a residence, and generally owes the use tax as of the date of sale.
For an out-of-state purchase, use tax is due when the mobilehome is first used in California, and HCD collects it at first registration. A dealer who puts a mobilehome bought for resale to another use pays use tax with the sales and use tax return for the period of first use. For factory-built housing, obtain the 60% exclusion certificate from the customer to pay tax on only 40 percent of the sales price.
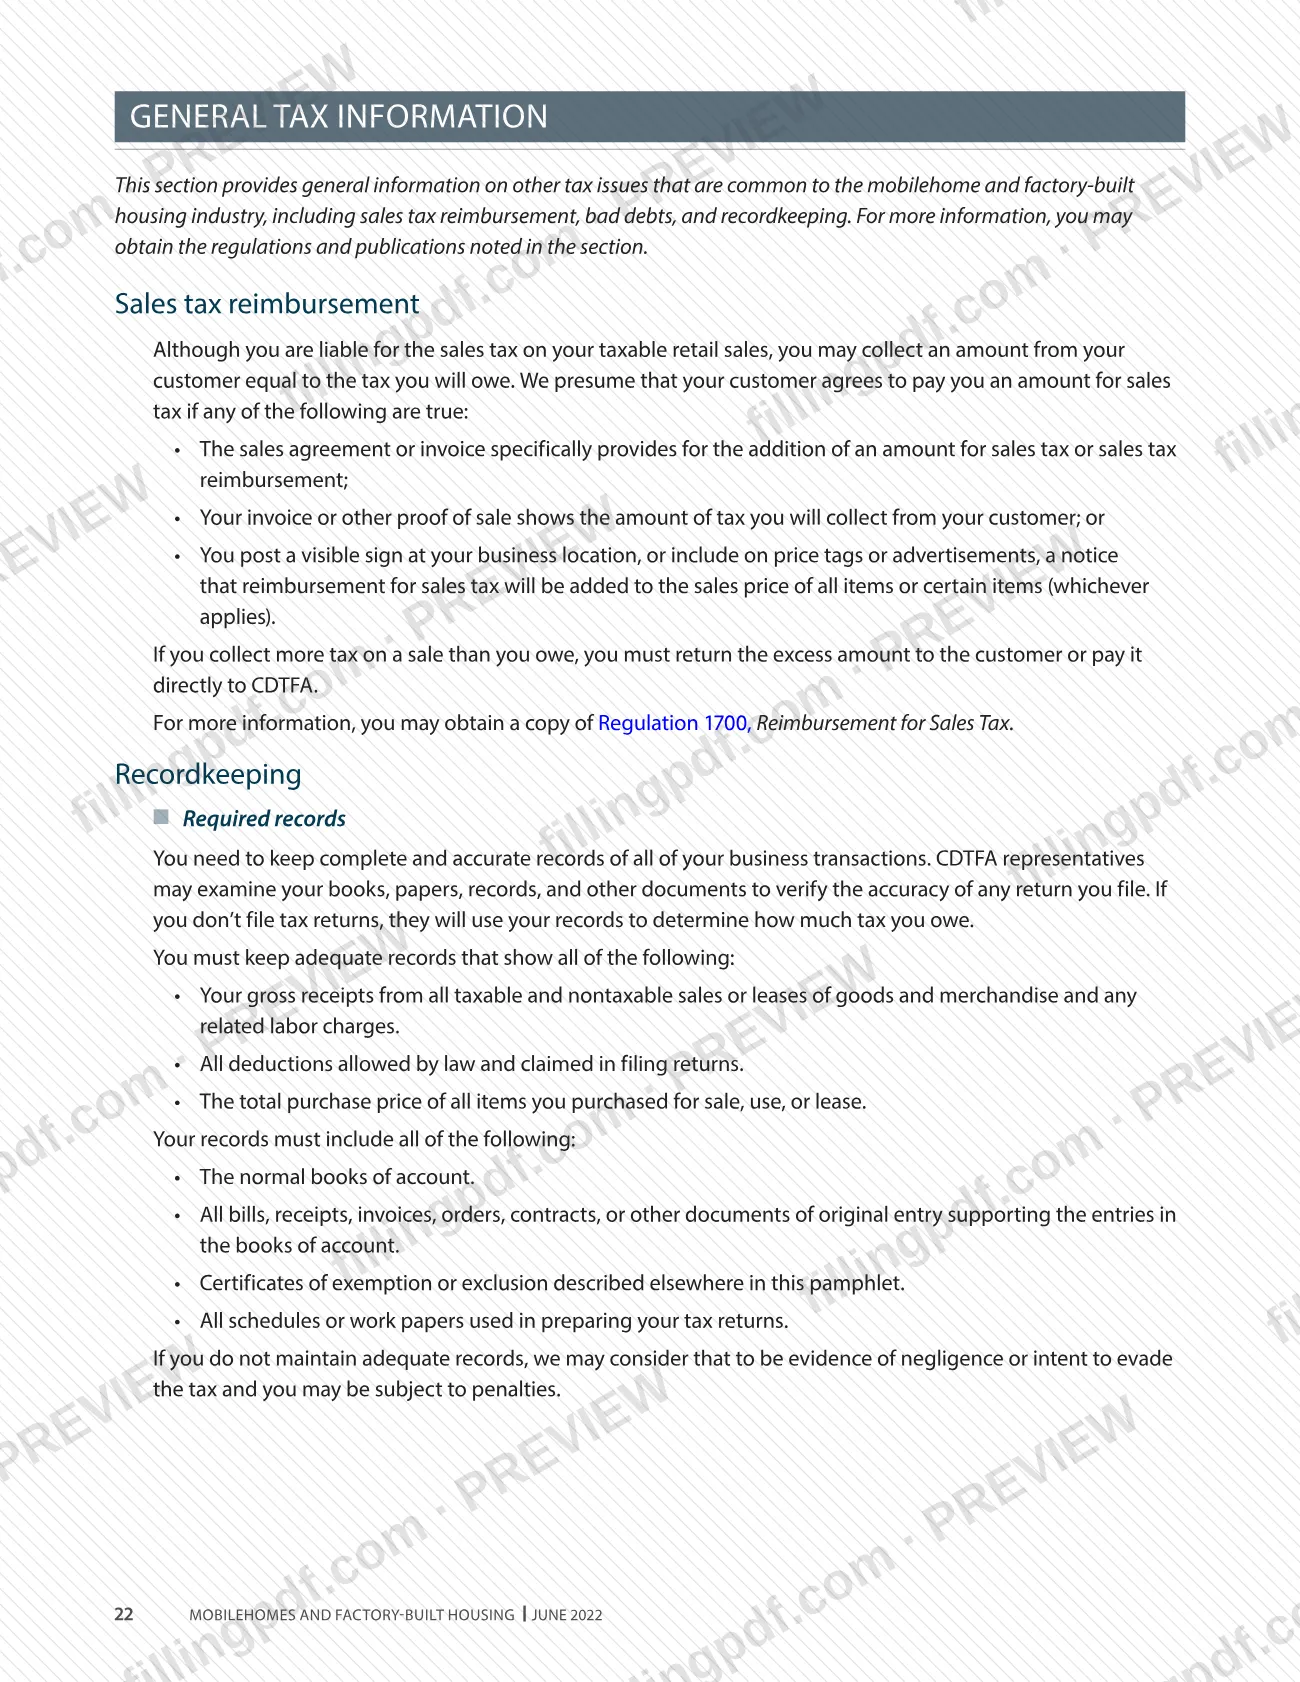
Keep required records for at least four years unless the CDTFA authorizes earlier destruction.
Documents you need
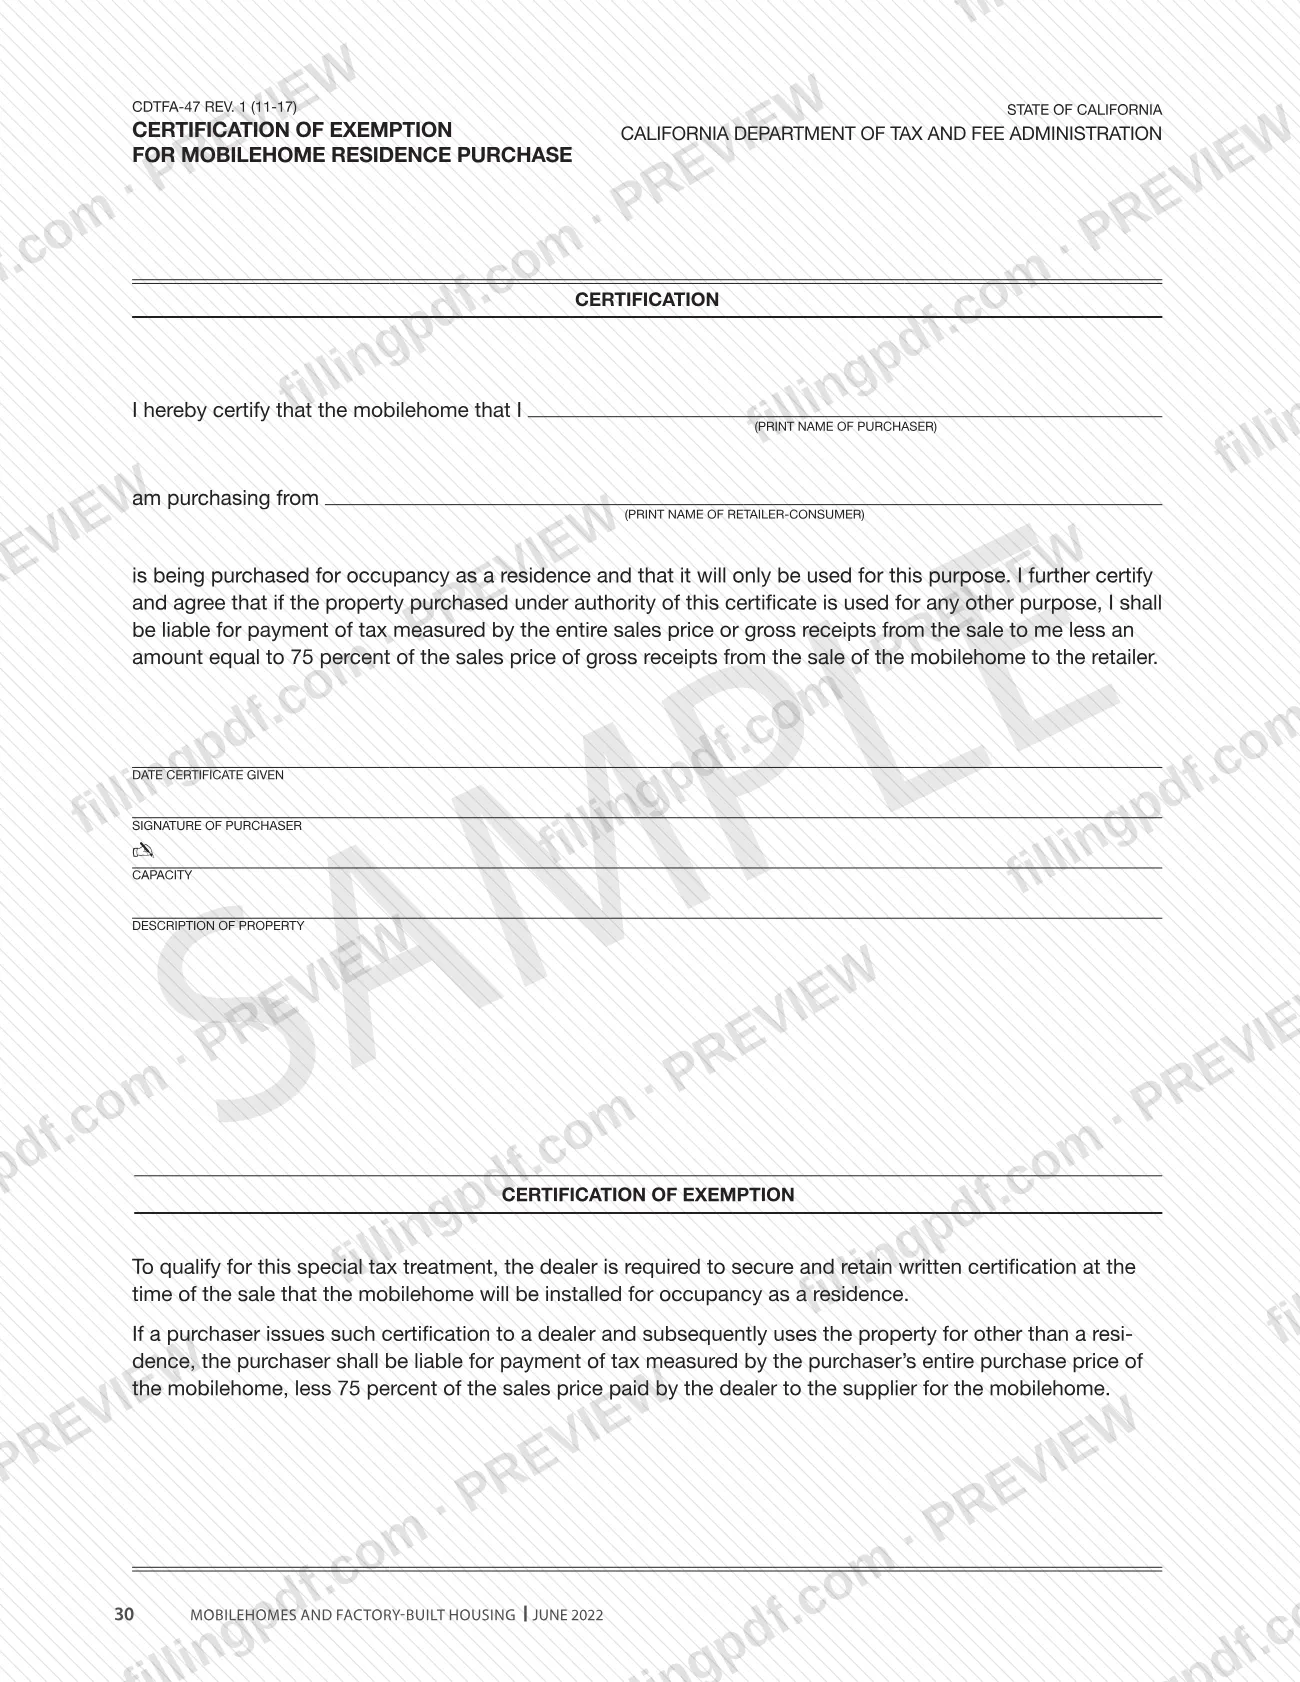
- CDTFA-47, Certification of Exemption for Mobilehome Residence Purchase: written certification from the purchaser, obtained at the time of sale, that the mobilehome is bought for occupancy as a residence.
- 60% exclusion certificate from the customer: needed to pay tax on only 40 percent of the sales price of factory-built housing sold for residential or patient-care use.
- Resale certificate: a dealer may issue it to manufacturers and suppliers for items it will sell as a retailer or retailer-consumer.
- Bills of lading or other delivery evidence: retained by the retailer to support exempt interstate sales or exports.
- U.S. government purchase order or other proof of direct payment by the government: retained to document exempt sales to the United States government.
- For sales to a Native American living on a reservation: a document showing Native American status, documents showing title and delivery on the reservation, and an exemption certificate such as CDTFA-146-RES.
- Proof of family relationship when registering a used mobilehome: needed to claim the family-sale use tax exemption.
- CDTFA-106, Vehicle/Vessel Use Tax Clearance Request: used to apply for a CDTFA-111 use tax clearance for an exempt used mobilehome purchase.
How to fill out Pub 47
Match your transaction to a section
Use the table of contents to find your case: dealer sale or lease, out-of-state purchase, used mobilehome, real property installation or factory-built housing. Note whether you are a retailer, retailer-consumer or consumer.
Complete the CDTFA-47 certification
On the Certification of Exemption for Mobilehome Residence Purchase, print the name of the purchaser and the name of the retailer-consumer the mobilehome is bought from.
Date, sign and describe the property
Enter the date the certificate is given, the purchaser's signature, the capacity in which the purchaser signs, and the description of the property.
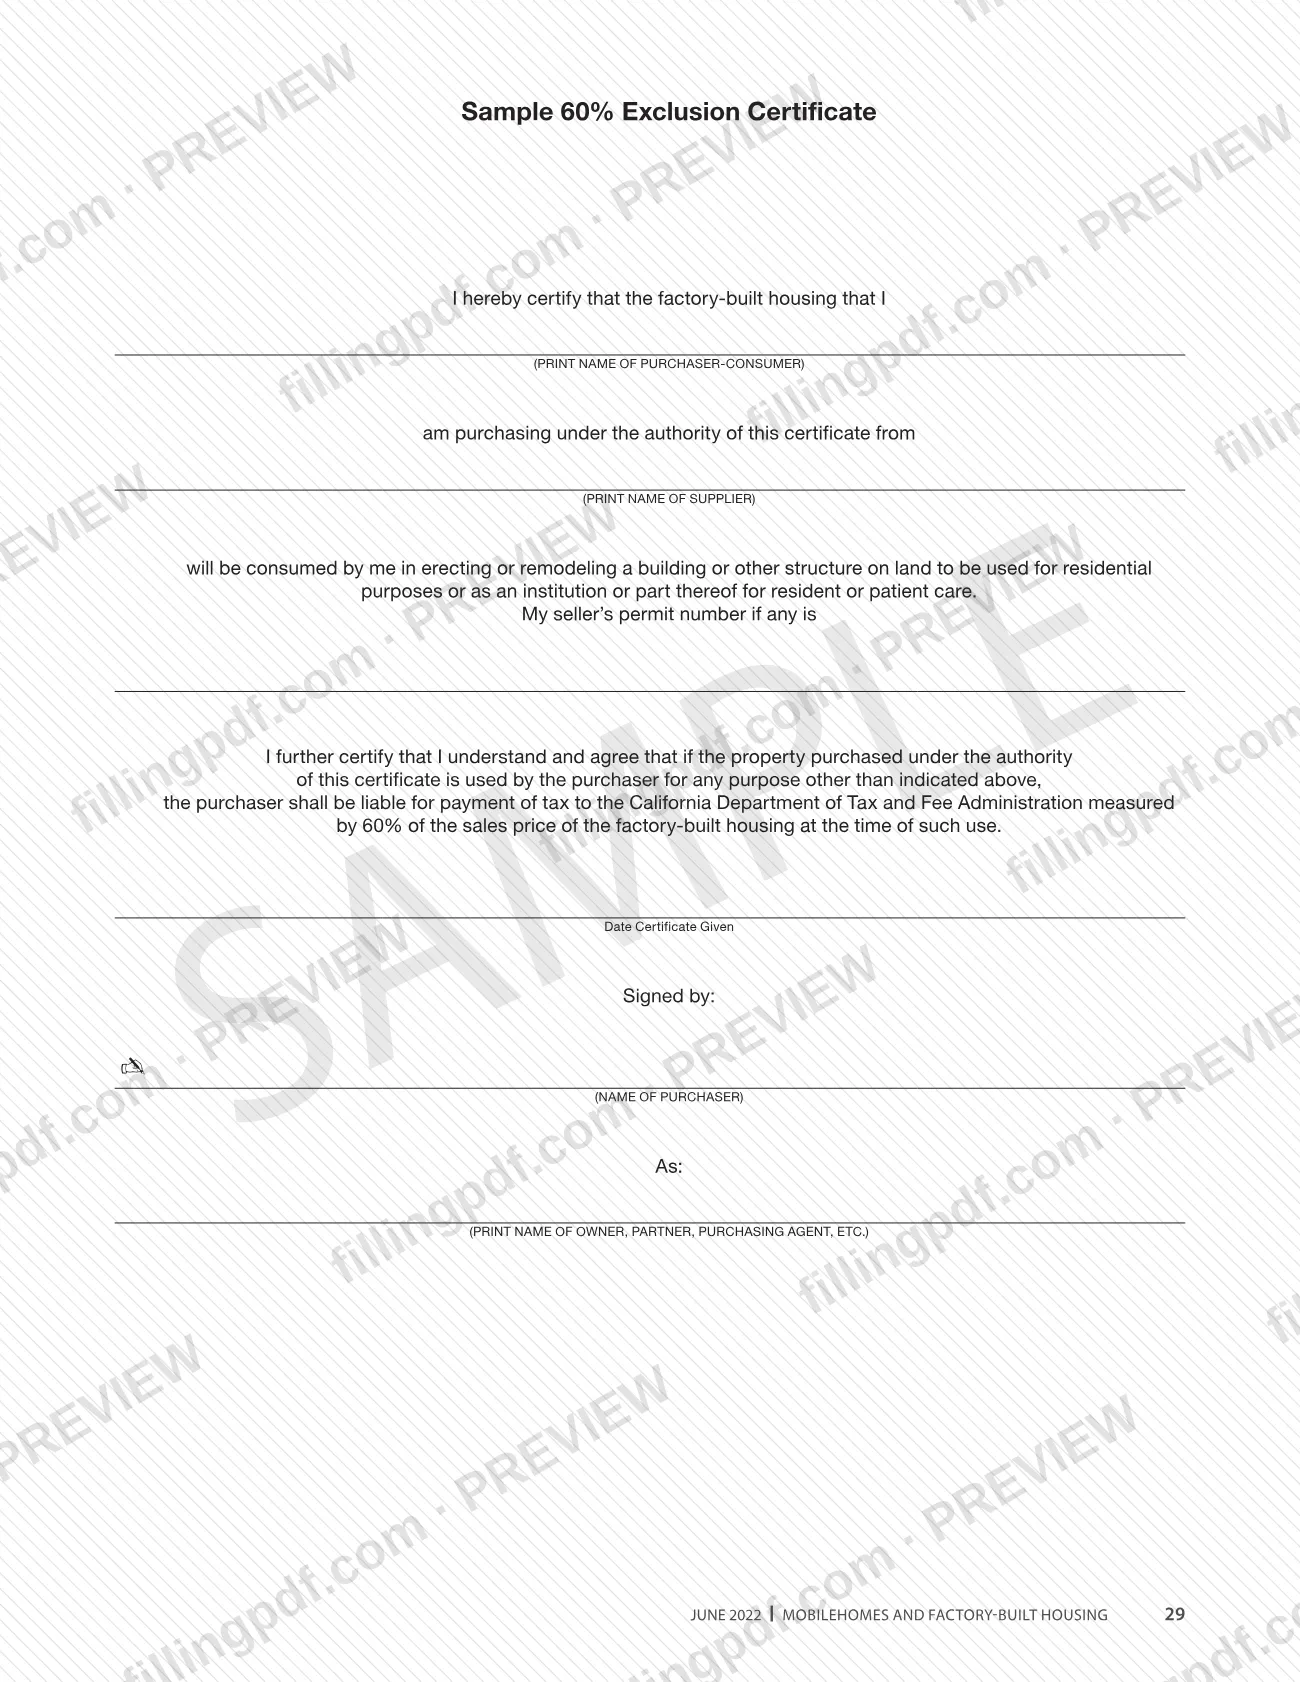
Complete the 60% exclusion certificate
For factory-built housing, print the purchaser-consumer name and the supplier name, add the seller's permit number if any, and enter the date the certificate is given. Add the signature, the purchaser's name and the title or capacity (owner, partner, purchasing agent, etc.).
Check amounts against the sample transaction
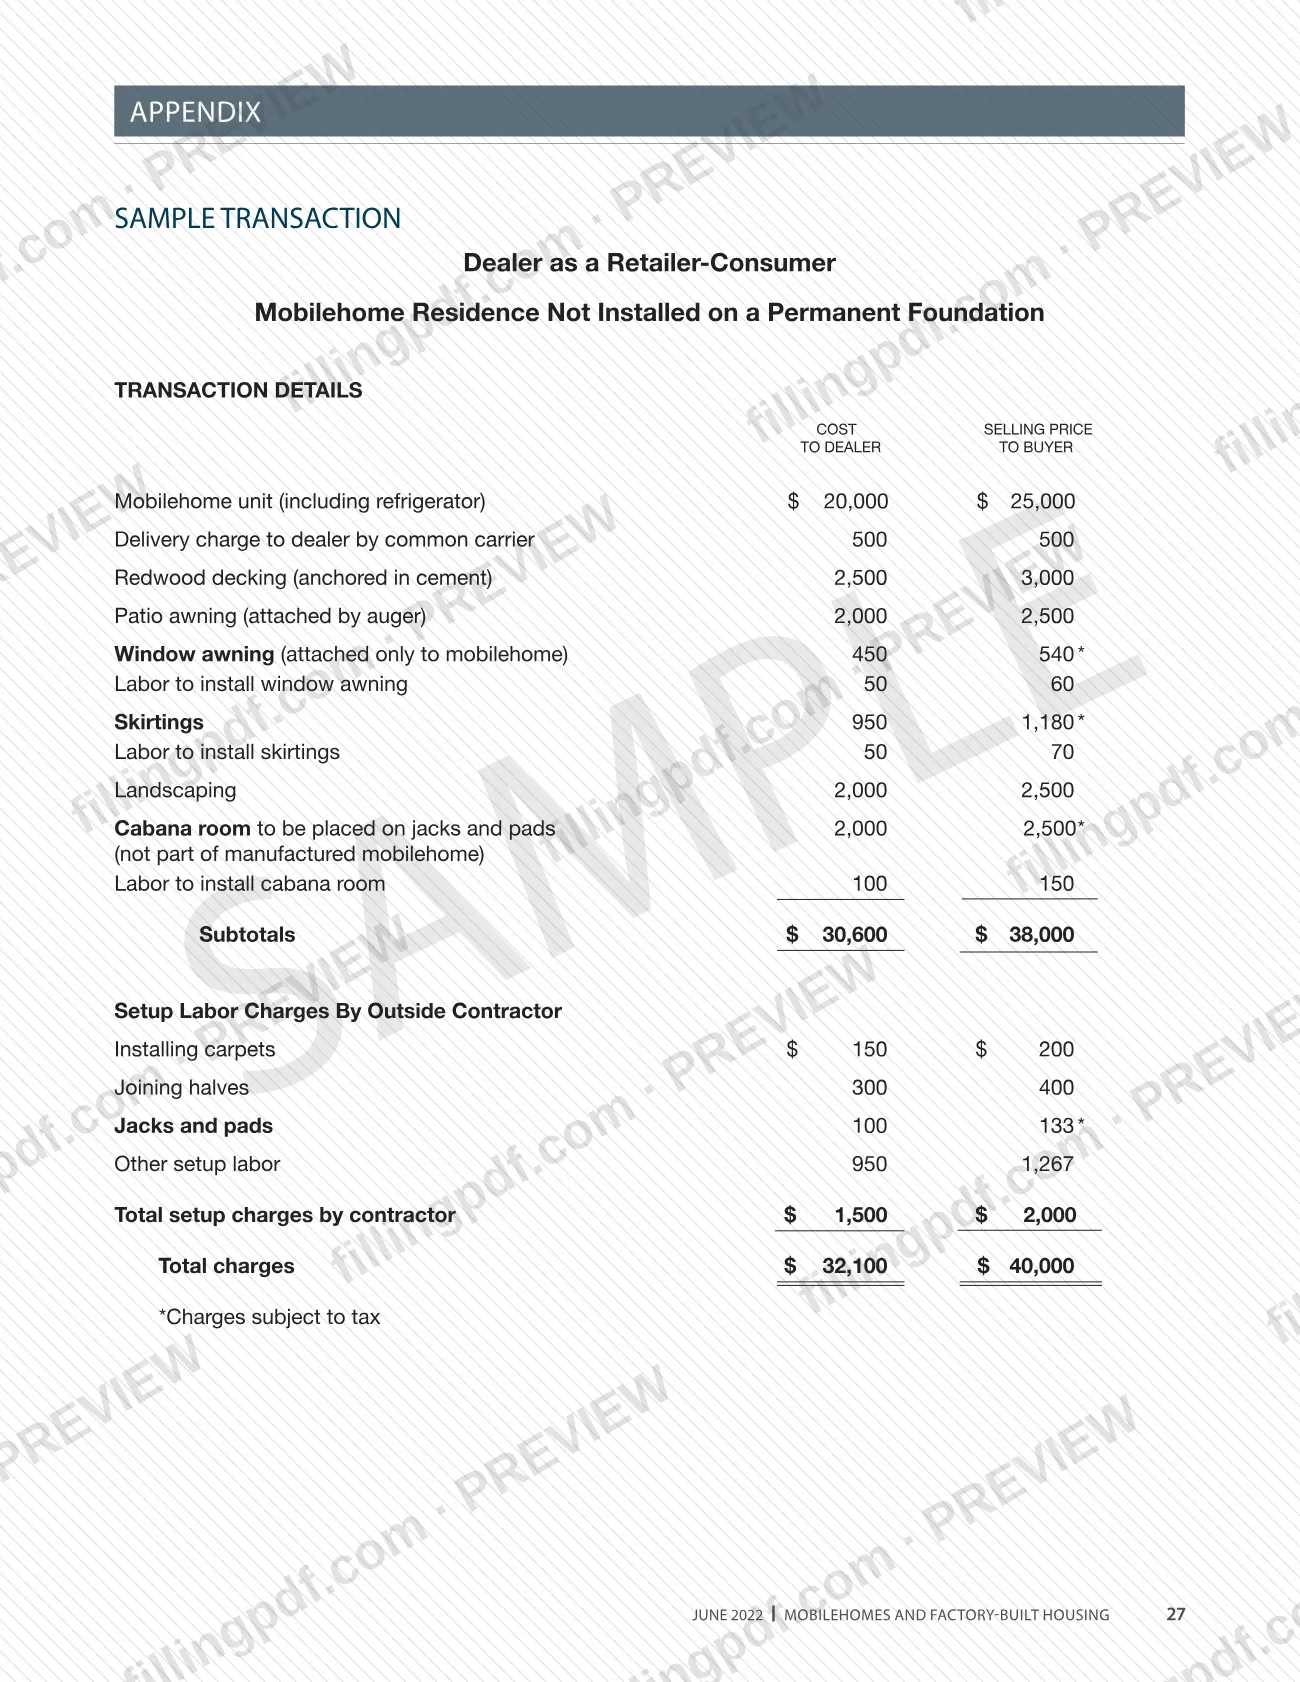
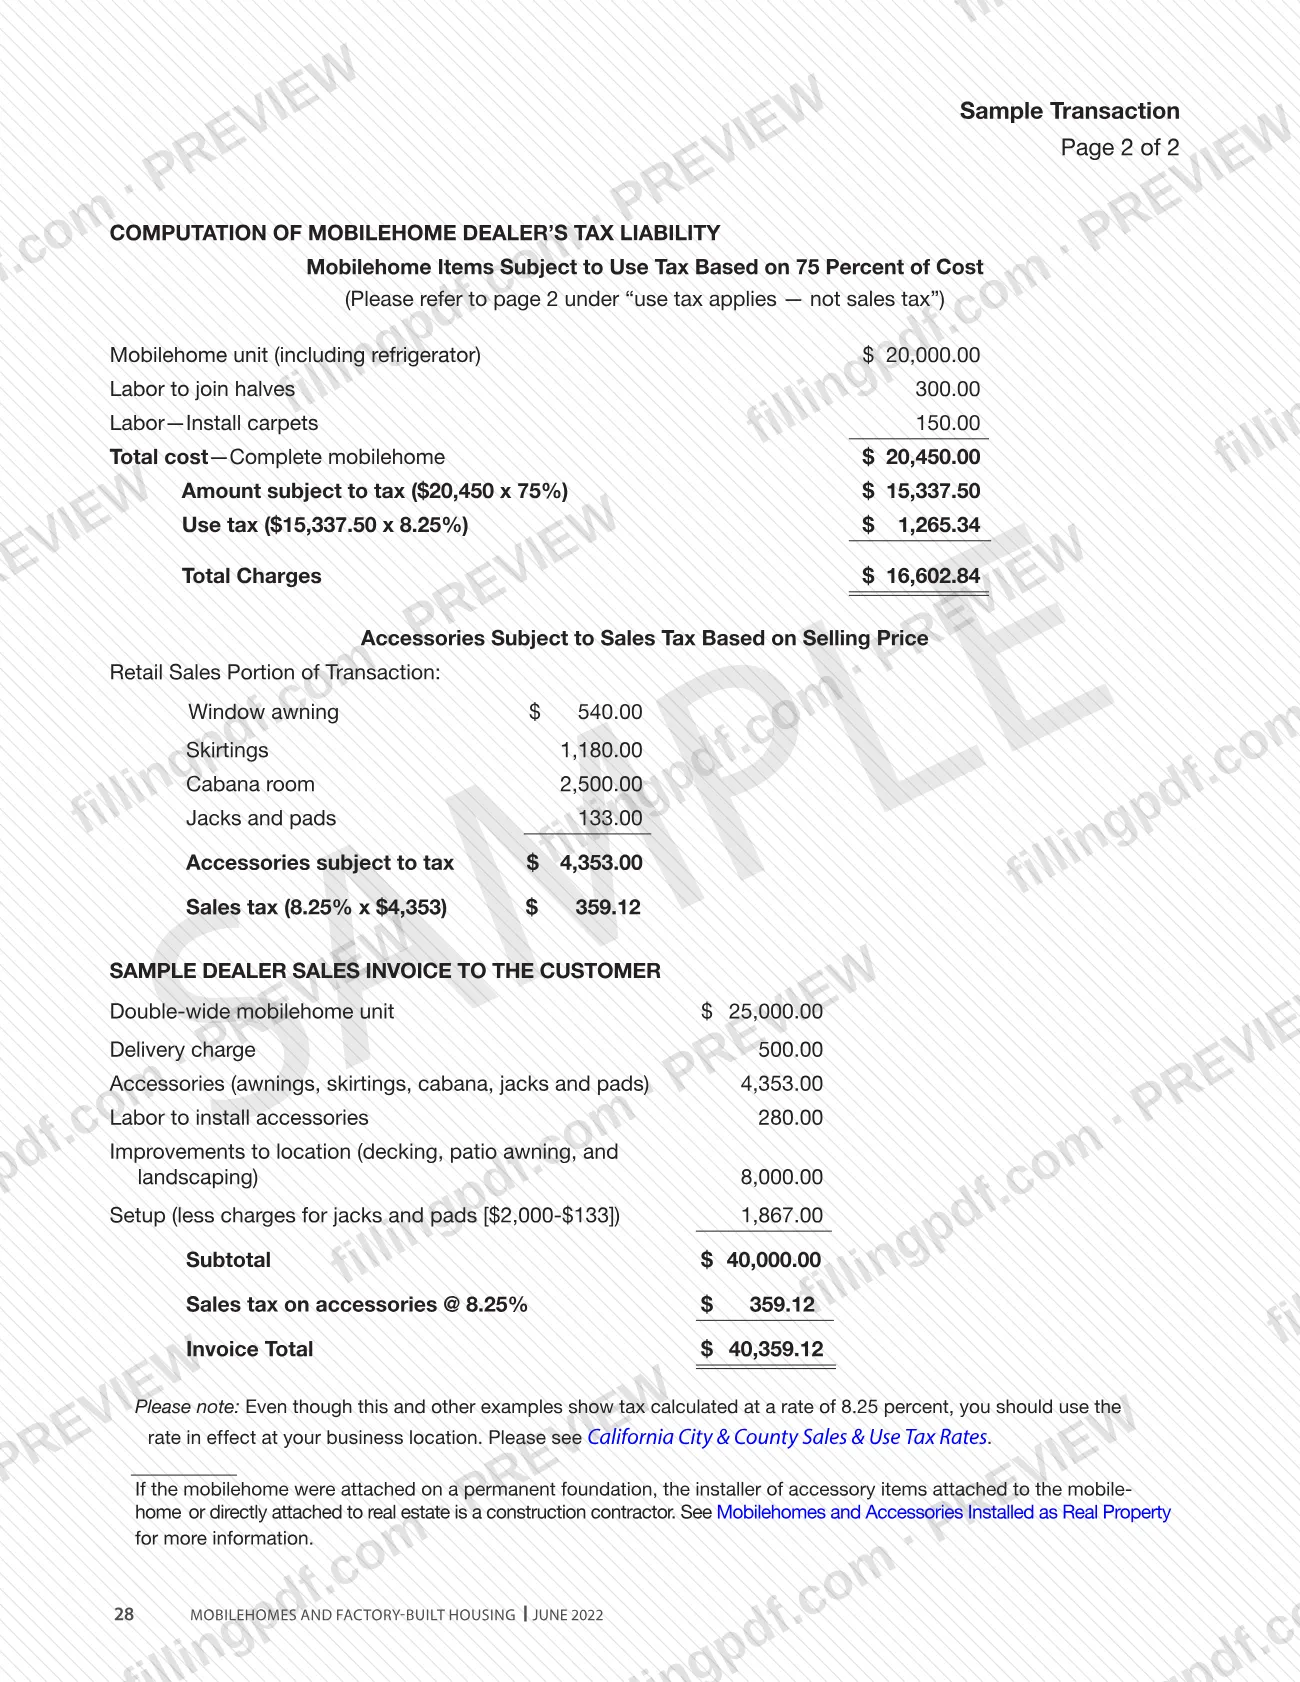
The appendix shows how the 75 percent use tax base is built from the mobilehome, labor to join halves and carpet installation, with accessories taxed separately on selling price. Use it as a reference; apply the rate in effect at your business location.
Review and download the completed PDF
Check every name, date and signature entry, then download or print the completed PDF from FillingPDF. Give the certificate to the seller and keep your copy as described under How to submit.
How to submit Pub 47
Pub 47 is a guide, and the certificates in its appendix are not mailed to the CDTFA. They are kept by the seller.
- Certificates: the dealer keeps the written certification (CDTFA-47) obtained at the time of sale. The seller of factory-built housing keeps the 60% exclusion certificate in its records.
- Use tax on a mobilehome: dealers report it on their sales and use tax return. For an out-of-state purchase, HCD collects the use tax at first registration. A Native American buyer who owes use tax can use the CDTFA Online Services Portal (File a Return or Claim an Exemption for a Vehicle, Vessel, Aircraft, or Mobile Home), report it on the Sales and Use Tax Return if they hold a California seller's permit, or visit any CDTFA office.
- Questions: Customer Service Center, 1-800-400-7115 (CRS:711), Monday through Friday, 7:30 a.m. to 5:00 p.m. Pacific time, except state holidays.
- Comments on the publication or written tax advice: Audit and Information Section, MIC:44, California Department of Tax and Fee Administration, PO Box 942879, Sacramento, CA 94279-0044.
FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Charging a customer an amount for tax reimbursement on a mobilehome sold for residence when you are the retailer-consumer; the publication says you cannot collect it.
- Failing to obtain and keep written certification at the time of sale that the customer will use the mobilehome as a residence.
- Including furniture and other unattached accessories in the 75 percent use tax base instead of listing them separately and charging sales tax on their selling price.
- Treating a mobilehome on piers or jacks and pads as real property; only a permanent foundation qualifies.
- Assuming a sale to a Native American buyer is exempt when the mobilehome is used outside the reservation more than half the time in the first 12 months.
- A construction contractor not licensed as a mobilehome dealer issuing a resale certificate for a mobilehome to be installed on a permanent foundation.
- Withdrawing a mobilehome from resale inventory for another use, such as an office or a gift, without reporting use tax on its full purchase price.
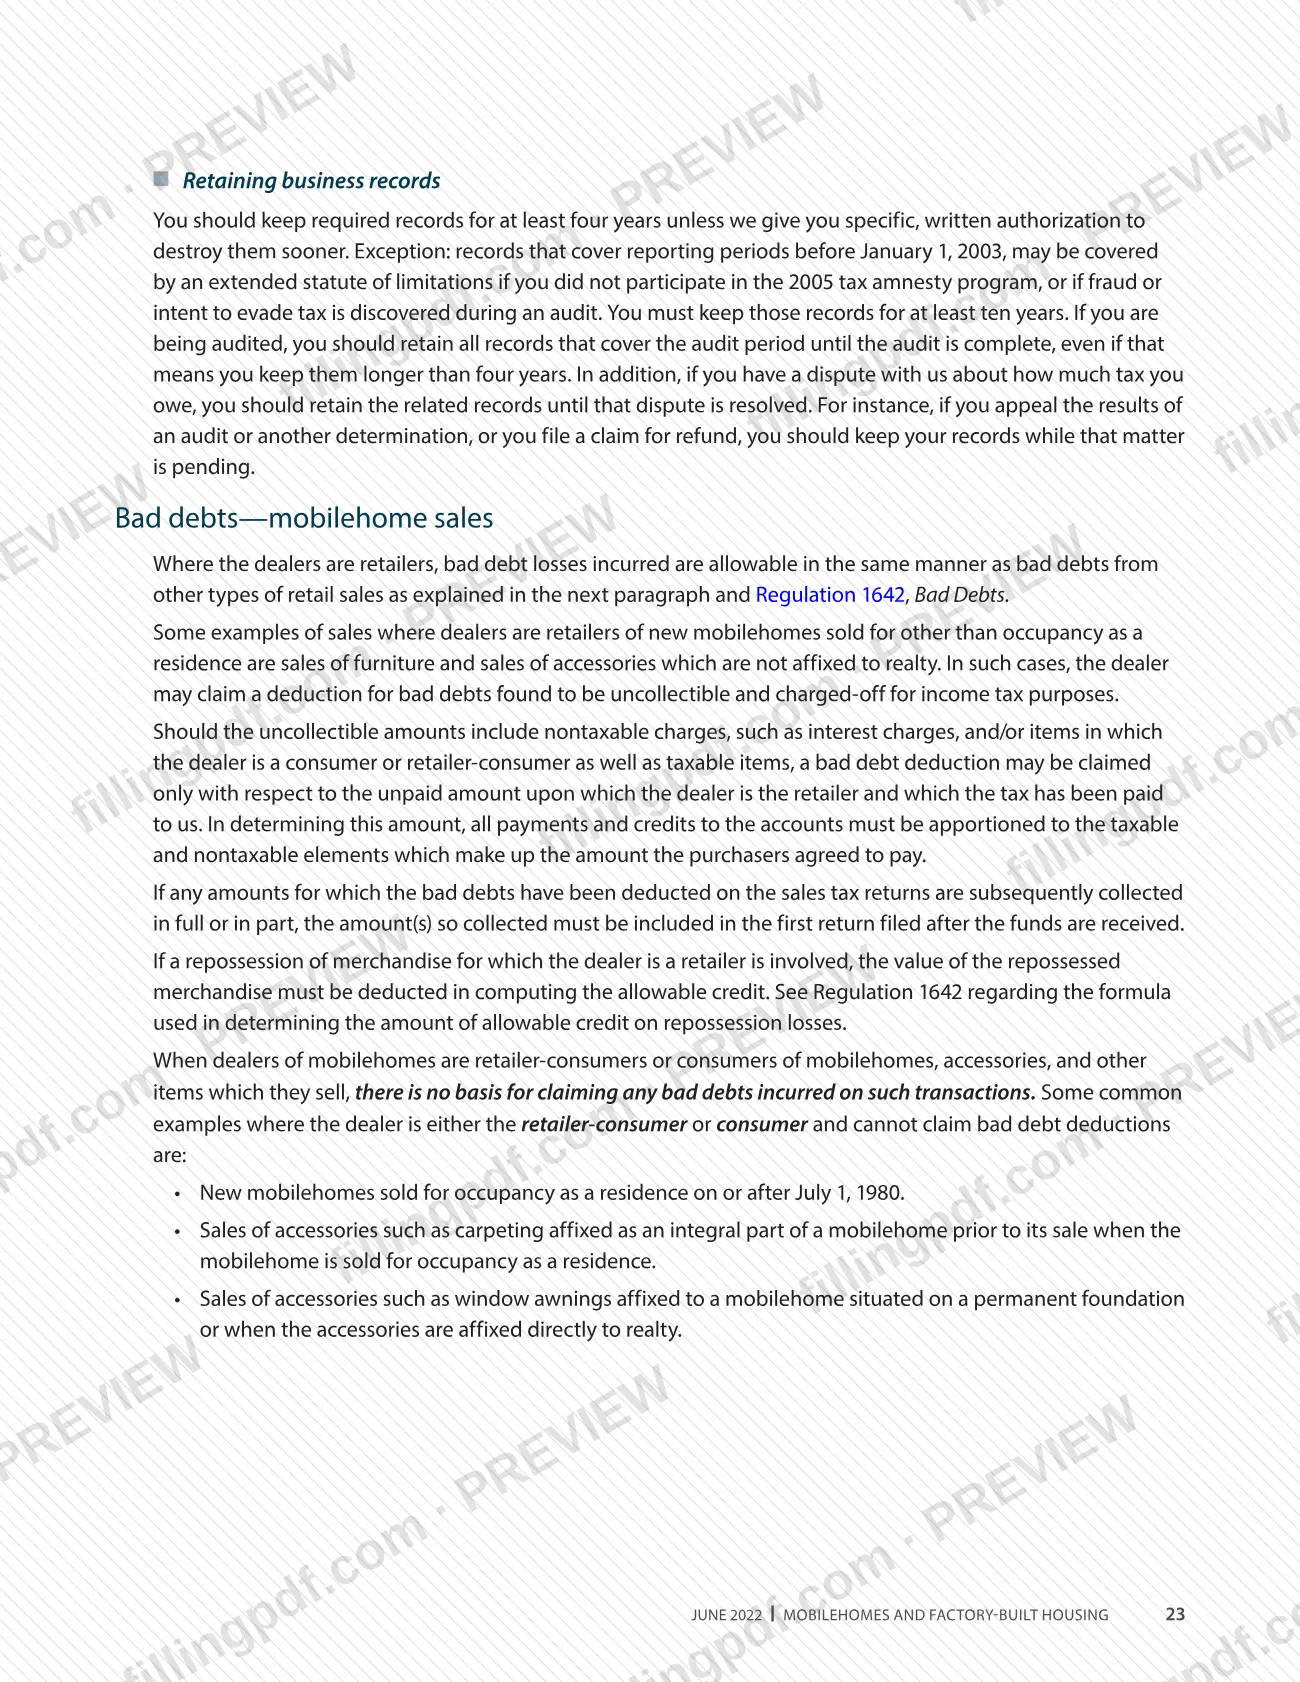
- Claiming bad debt deductions on transactions where you are the retailer-consumer or consumer, such as new mobilehomes sold for residence on or after July 1, 1980.
- Treating a factory-built housing sale as taxable on only 40 percent without the customer's 60% exclusion certificate on file.
Frequently asked questions
What is Pub 47?
Pub 47 is the CDTFA publication Mobilehomes and Factory-Built Housing, June 2022. It explains how California sales and use tax applies to dealer sales and leases, out-of-state purchases, used mobilehomes, real property installations and factory-built housing.
What is a retailer-consumer in a mobilehome sale?
A dealer is a retailer-consumer when it sells a new mobilehome for residential use that will be subject to property tax and whose sale would ordinarily be taxable. The dealer then owes use tax on 75 percent of its purchase price, not sales tax, and cannot collect tax reimbursement from the customer.
Do I need a certificate when selling a mobilehome for residence?
Yes, to qualify for the special treatment the dealer must obtain and keep written certification at the time of sale that the customer will use the mobilehome as a residence. The appendix provides CDTFA-47, Certification of Exemption for Mobilehome Residence Purchase, for this purpose.
How is factory-built housing taxed under Pub 47?
A sale to a consumer is subject to sales tax, but tax applies to only 40 percent of the sales price when the housing is for residential use on land or an institution for resident or patient care. The seller must hold the customer's 60% exclusion certificate.
Who collects use tax on a mobilehome bought from an out-of-state dealer?
The Department of Housing and Community Development (HCD) collects the use tax when the mobilehome is first registered in California. For residential use it is based on 75 percent of the price the dealer paid, or 60 percent of the amount paid to the dealer without satisfactory proof.
Does Pub 47 cover property tax or registration?
No. The publication does not address property tax, mobilehome registration or building permits. Contact the county assessor for property tax, and HCD for registration and licensing. For tax questions it covers, call the CDTFA at 1-800-400-7115 (CRS:711).
How long must I keep records for mobilehome sales?
Keep required records, including exemption and exclusion certificates, for at least four years unless the CDTFA gives written authorization to destroy them sooner. Keep them longer during an audit, a dispute or a pending refund claim.
Can I fill out the Pub 47 certificates on FillingPDF?
You can fill out the form online on FillingPDF and download or print the completed PDF. FillingPDF is an independent service, not affiliated with the CDTFA, and does not file or submit anything; the certificates are given to the seller and kept in its records.
Ready to fill out Pub 47?
Fill out Pub 47 now