
Pub 52, Vehicles and Vessels: Use Tax, is the California Department of Tax and Fee Administration (CDTFA) publication that lists common vehicle and vessel transfers not subject to California use tax and explains how to request a use tax clearance. It is used by people who register a vehicle or vessel with the Department of Motor Vehicles (DMV) and think an exemption applies. On FillingPDF you can fill out the form online and download or print the completed PDF; the original PDF is published by CDTFA.
Last updated
What is Publication 52?
Publication 52, Vehicles and Vessels: Use Tax, is the California Department of Tax and Fee Administration (CDTFA) publication that gives examples of vehicle and vessel transfers not subject to California use tax and explains how to apply for a use tax clearance.
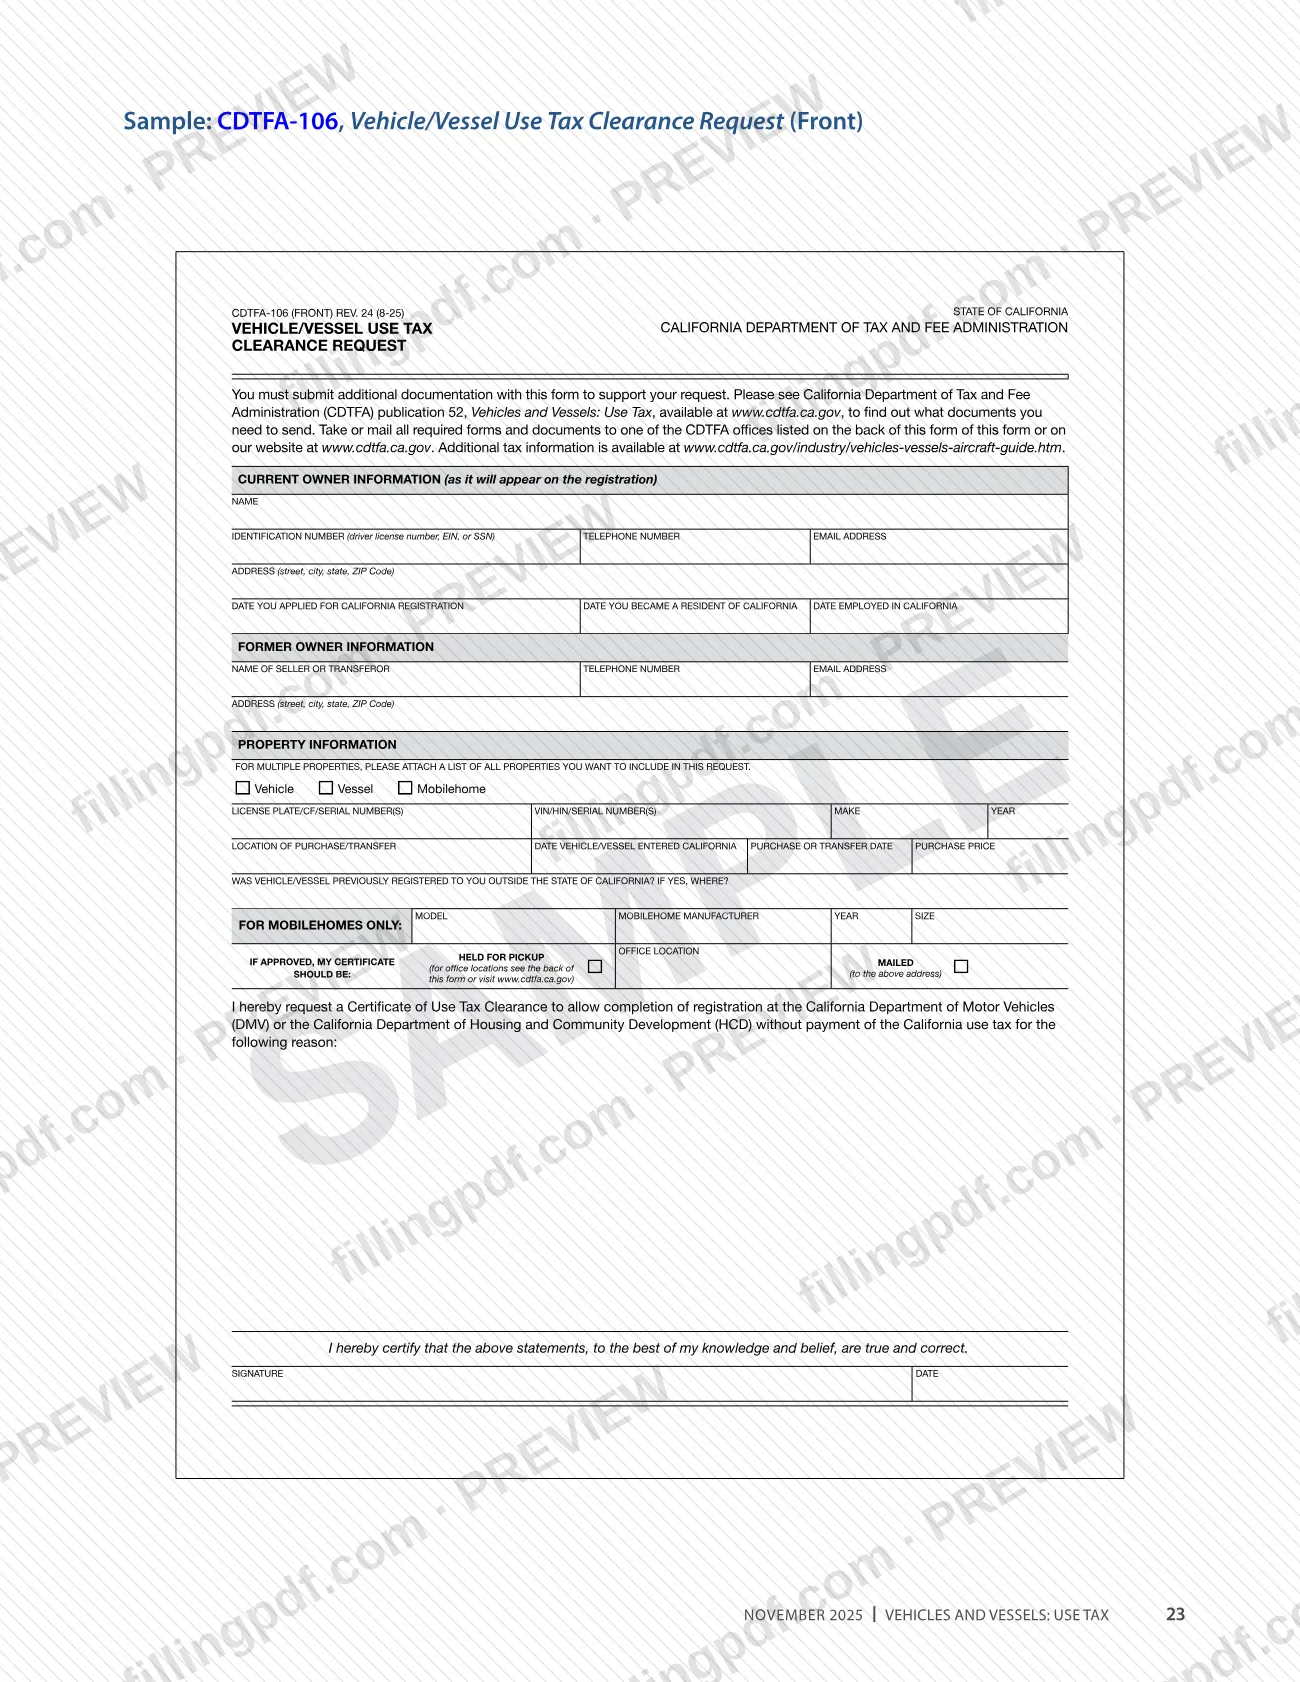
A use tax clearance is a document issued by CDTFA stating that you qualify for a specific exemption and may register your vehicle or vessel without paying use tax. CDTFA issues two certificates: CDTFA-111, Certificate of Vehicle, Mobilehome or Commercial Coach Use Tax Clearance, and CDTFA-111-B, Certificate of Vessel Use Tax Clearance. You ask for either one with CDTFA-106, Vehicle/Vessel Use Tax Clearance Request, a sample of which is printed at the end of the publication.
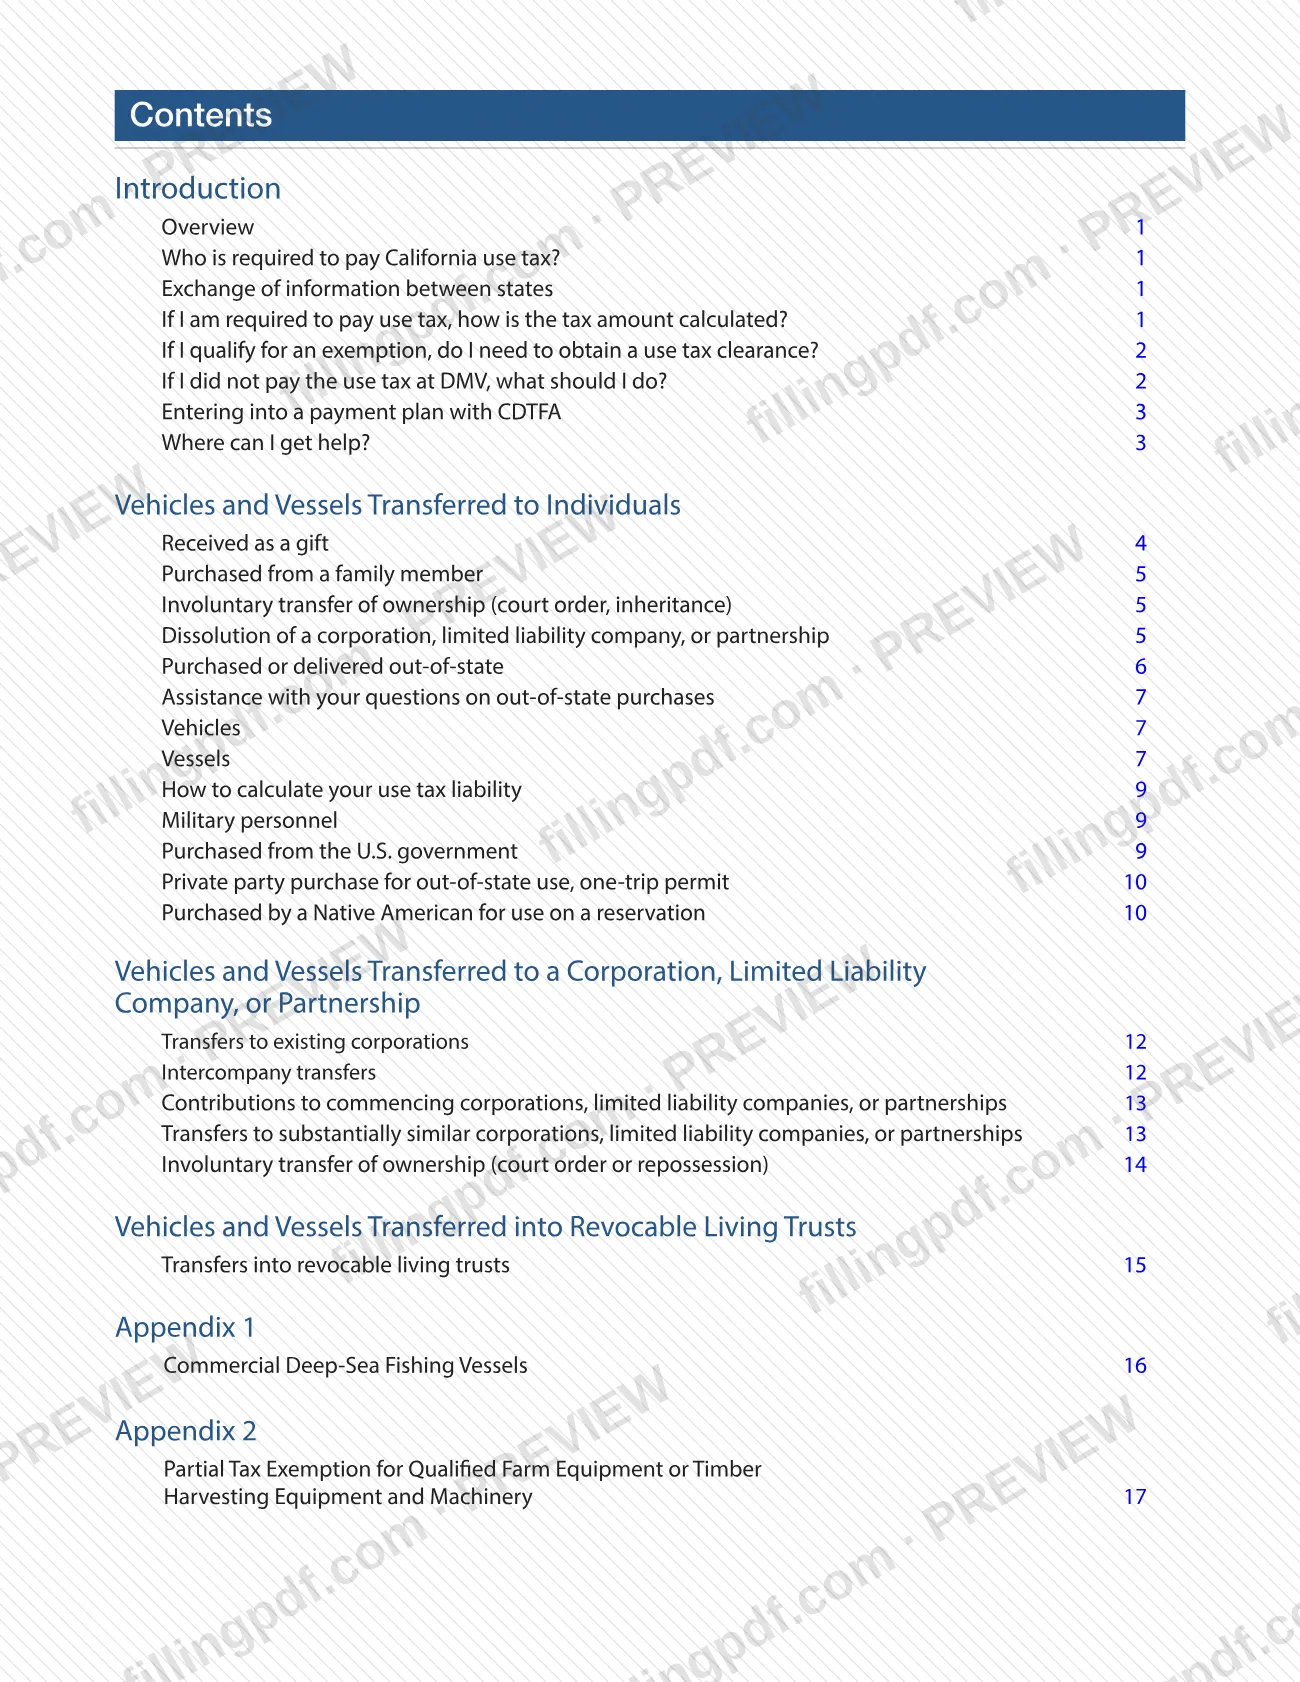
The publication covers only the more common exemptions. Its sections deal with:
- transfers to individuals: gifts, purchases from family members, involuntary transfers, dissolutions, out-of-state purchases, military personnel, purchases from the U.S. government, private party purchases for out-of-state use, and purchases by Native Americans for use on a reservation;
- transfers to corporations, limited liability companies and partnerships;
- transfers into revocable living trusts;
- appendices on commercial deep-sea fishing vessels, the partial exemption for farm and timber harvesting equipment, incorrect tax rates charged by DMV, and interstate and foreign commerce.
It does not apply to documented vessels registered with the U.S. Coast Guard; the publication refers those to publication 40, Watercraft Industry. It is guidance, not the request itself: the request is the CDTFA-106.
Who needs to file Publication 52?
You use Publication 52 if you buy a vehicle or vessel, or receive one as compensation, from someone who is not a California dealer, to use it in California, and you think the transfer is exempt from use tax. Unless an exemption applies, sales or use tax applies to such purchases. If you buy from a California vehicle or vessel dealer, the dealer is responsible for reporting and paying sales tax.
The publication has a section for each of these situations:
- you received a vehicle or vessel as a gift;
- you bought from a parent, grandparent, grandchild, child, spouse or domestic partner;
- you acquired ownership involuntarily, for example by court order, divorce settlement, inheritance or repossession;
- you received it in the dissolution of a corporation, LLC or partnership;
- you bought or took delivery outside California, including active duty service members and purchases from the U.S. government;
- you are a Native American, Indian organization or Indian couple buying for use on a reservation;
- a corporation, LLC, partnership or revocable living trust is the transferee;
- you register a commercial deep-sea fishing vessel, farm or timber harvesting equipment, or a vehicle or undocumented vessel used in interstate or foreign commerce.
Do not rely on it for documented vessels registered with the U.S. Coast Guard. You need a use tax clearance only if DMV asks for one.
When to file Publication 52
You request a use tax clearance when DMV asks you for one while you register a vehicle or vessel; the publication sets no calendar deadline for the request itself. DMV can process many nontaxable transfers, such as transfers between qualified family members, without a clearance, and in most gift and family-purchase cases it does not ask.
Pay your DMV transfer fee on time even if CDTFA has not yet replied, to avoid penalty charges. DMV returns your registration application when you apply for a clearance and asks you to resubmit it after CDTFA replies.
If you did not pay, or did not fully pay, use tax to DMV at registration, report and pay it directly to CDTFA. For a refund of tax paid to DMV, a claim generally must be filed no later than three years from the last day of the month following the close of the reporting period of the overpayment, or six months from the date of payment, whichever expires later. For out-of-state purchases the presumption of use in California looks at the first 12 months of ownership. Keep supporting records at least eight years.
Documents you need
- Certificate of title, or the current registration if title is not available: requested in most categories, such as gifts, family purchases, involuntary transfers, military and government purchases.
- Gift from an individual: signed statement from the donor that the property was a gift, with the VIN, plate, CF or HIN and the donor's mailing address and telephone number. Notarized is preferable, not required.
- Gift from a business: minutes of the board or governing body authorizing the gift, or a signed officer or member statement if minutes are unavailable. Gift from a licensed dealer: bill of sale or dealer statement that tax will be paid.
- Purchase from a family member: proof of the relationship, and of age if the transfer is between minors, such as a marriage license, Franchise Tax Board return showing spouses, domestic partnership certificate, birth certificate or adoption certificate.
- Involuntary transfer: court property settlement documents or a certificate of repossession describing the vehicle or vessel, or properly endorsed documents from the court or DMV.
- Dissolution of an entity: minutes authorizing the distribution (or a signed statement if minutes are unavailable) and dissolution documents carrying a Secretary of State filing stamp showing liabilities were satisfied.
- Military personnel: the purchase contract showing the date of purchase and your official military transfer orders.
- Purchase from the U.S. government: transfer documents issued by the government, the purchase invoice, and documentation of the authority (U.S. Code title and section) under which the property was sold.
- Native American purchase for reservation use: purchase invoice showing title date and date and place of delivery, plus a Tribal Council residency letter, tribal ID card, or U.S. Department of the Interior letter.
- Transfers to corporations, LLCs or partnerships: signed statements from the entity and the donor, or minutes, formation documents with a Secretary of State filing stamp, and ownership records, depending on the category.
- Revocable living trust: Certificate of Trust or the title and signature pages, sections on transfers of property, loan assumption papers, and documentation of the donor's relationship to the trust.
- Commercial deep-sea fishing vessel: Statement of Origin with the HIN and a purchase invoice from a dealer, or a bill of sale or invoice with price and delivery date from a private party.
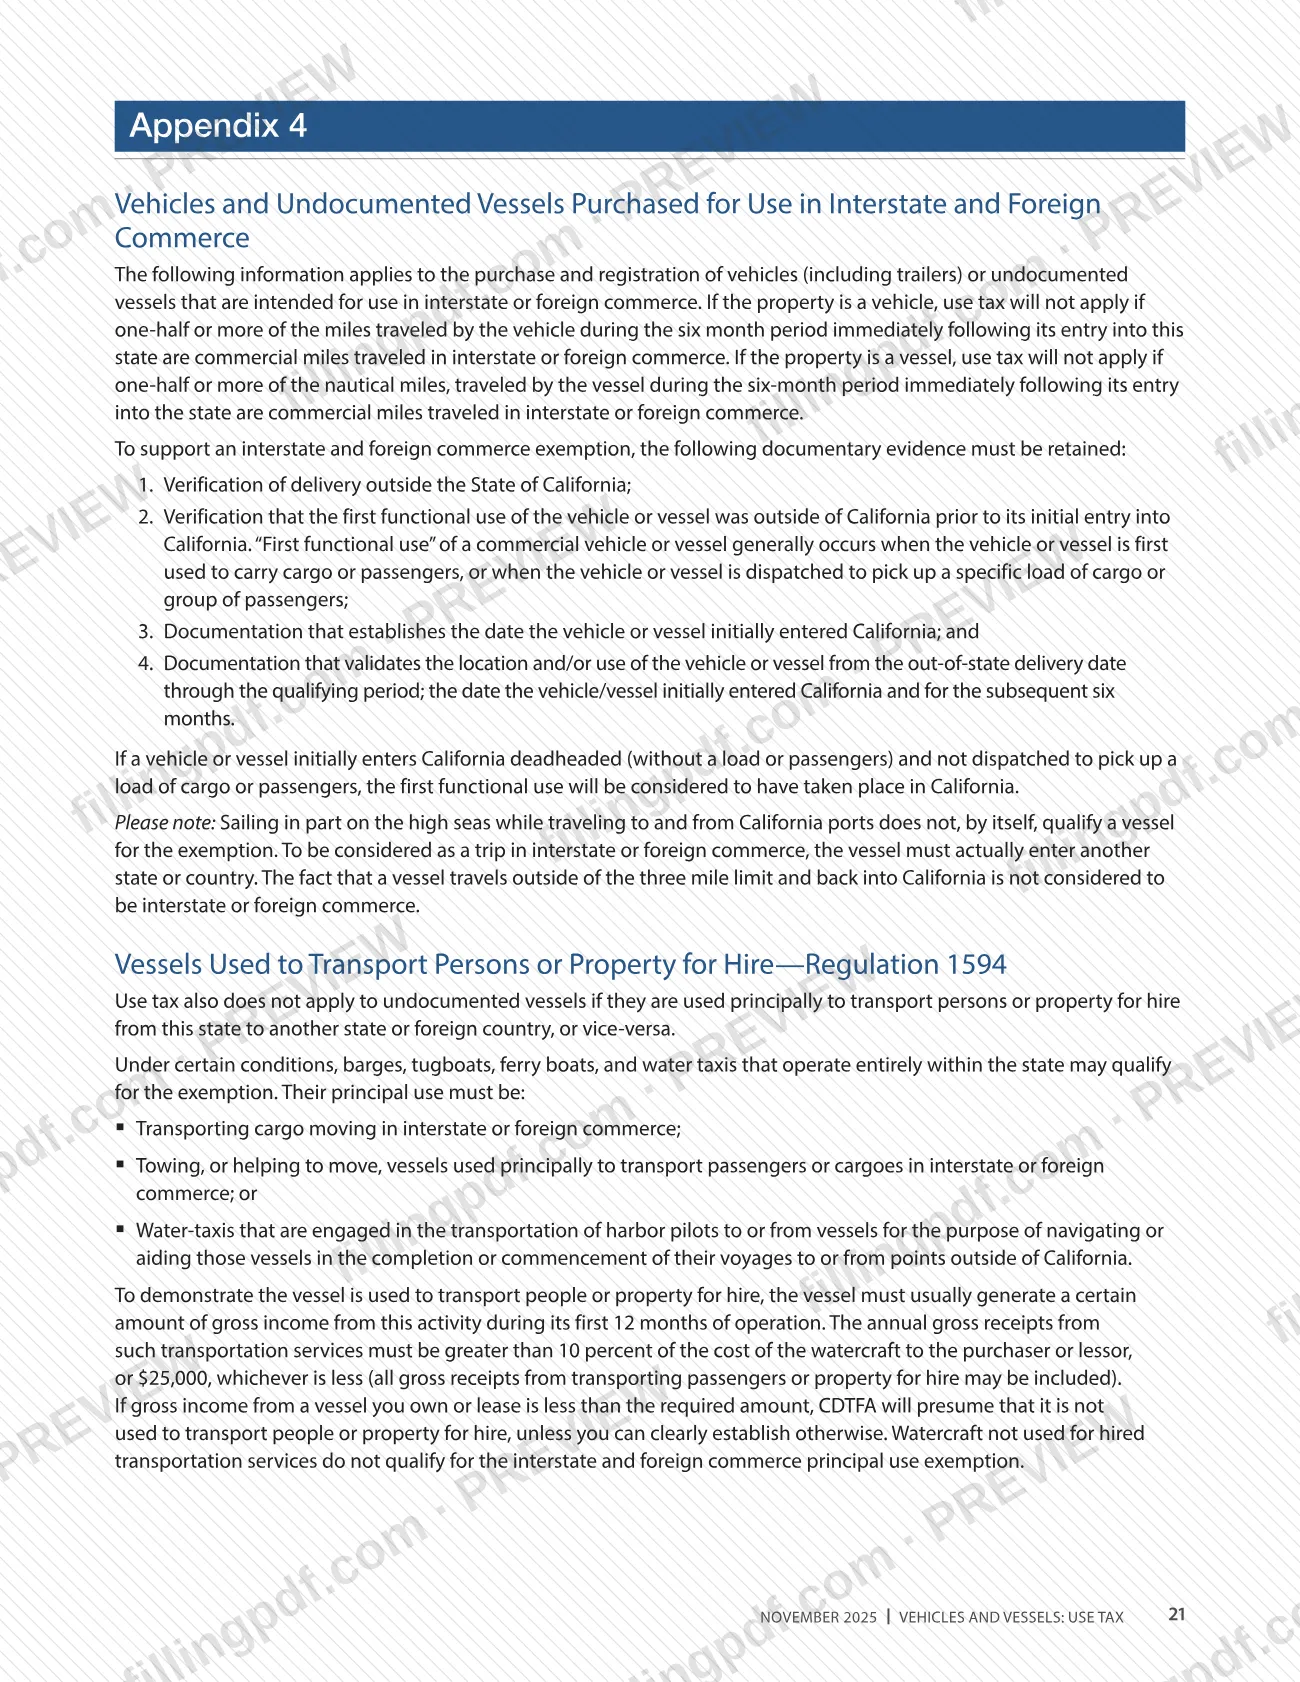
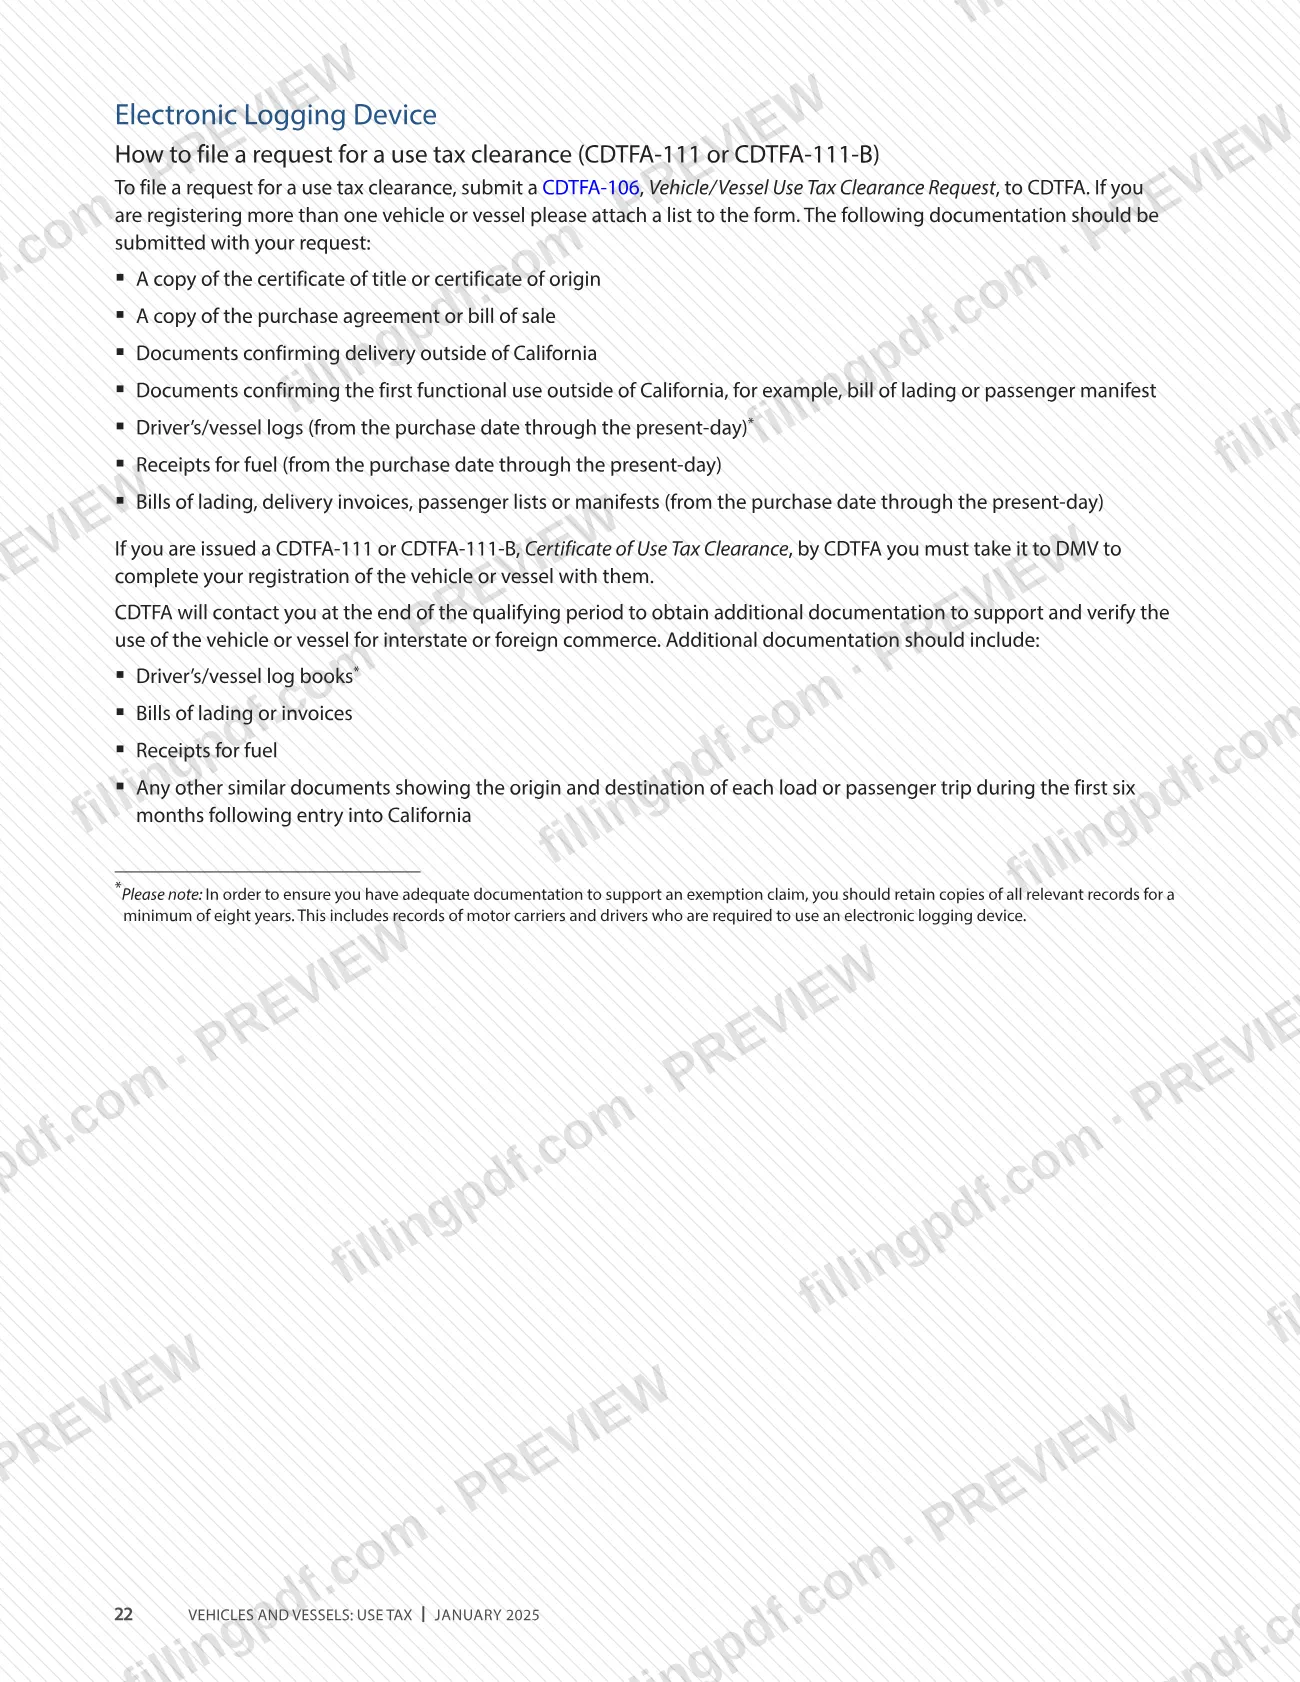
- Interstate or foreign commerce: title or certificate of origin, purchase agreement or bill of sale, proof of delivery and first functional use outside California, and logs, fuel receipts and bills of lading from the purchase date.
- Incorrect tax rate paid directly to CDTFA: title or current registration plus a property tax statement showing physical address and parcel number, or a utility bill showing your name and address.
- Farm or timber harvesting partial exemption refund: bill of sale or invoice, evidence of a qualifying industry, and a completed partial exemption certificate (CDTFA-230-D or CDTFA-230-H).
How to fill out Publication 52
Identify your transfer type
Find the section of Publication 52 that matches your situation, such as gift, family purchase, involuntary transfer, out-of-state purchase, entity transfer or revocable living trust. Each section states the conditions and the documents to copy.
Confirm DMV requires a clearance
DMV can process many nontaxable transfers without a use tax clearance. Request one with CDTFA-106 only if DMV asks you for it.
Enter current owner information
On the sample CDTFA-106, enter your name as it will appear on the registration, your identification number (driver license number, EIN, or SSN), telephone, email and address, plus the date you applied for California registration, became a resident and were employed in California.
Enter former owner information
Under Former Owner Information, give the seller's or transferor's name, telephone number, email and address.
Describe the vehicle, vessel or mobilehome
Check Vehicle, Vessel or Mobilehome and enter the plate, CF or serial number, VIN, HIN or serial number, make and year. For multiple properties, attach a list of all of them to the request.
Enter purchase and entry details
Give the location of purchase or transfer, the date the property entered California, the purchase or transfer date and price, and whether it was previously registered to you outside California and where.
Choose how to receive the certificate
Indicate whether the certificate should be held for pickup at a CDTFA office location or mailed to the address above.
State the reason for exemption
Complete the line requesting a Certificate of Use Tax Clearance to allow registration without payment of use tax, giving the exemption reason. For a gift, include a signed statement that you did not pay for the property, trade for it, assume a debt or receive it as a dividend or compensation.
Sign and date the certification
Sign and date the certification that the statements are true and correct to the best of your knowledge and belief.
Gather photocopies of supporting documents
Copy the documents Publication 52 lists for your transfer type. Do not send originals.
Review and download the completed PDF
Check every entry against your title and purchase papers, then download or print the completed PDF from FillingPDF and assemble the package described under How to submit.
How to submit Publication 52
A use tax clearance is requested through CDTFA Online Services, or with a paper CDTFA-106 sent by mail, fax or in person to CDTFA.
- Online: in CDTFA's Online Services, under Limited Access Functions, select Request Use Tax Clearance for Registration with DMV/HCD.
- By mail: send CDTFA-106 with photocopies of your supporting documents to Consumer Use Tax Section MIC:37, California Department of Tax and Fee Administration, PO Box 942879, Sacramento, CA 94279-0037. Do not send original documents.
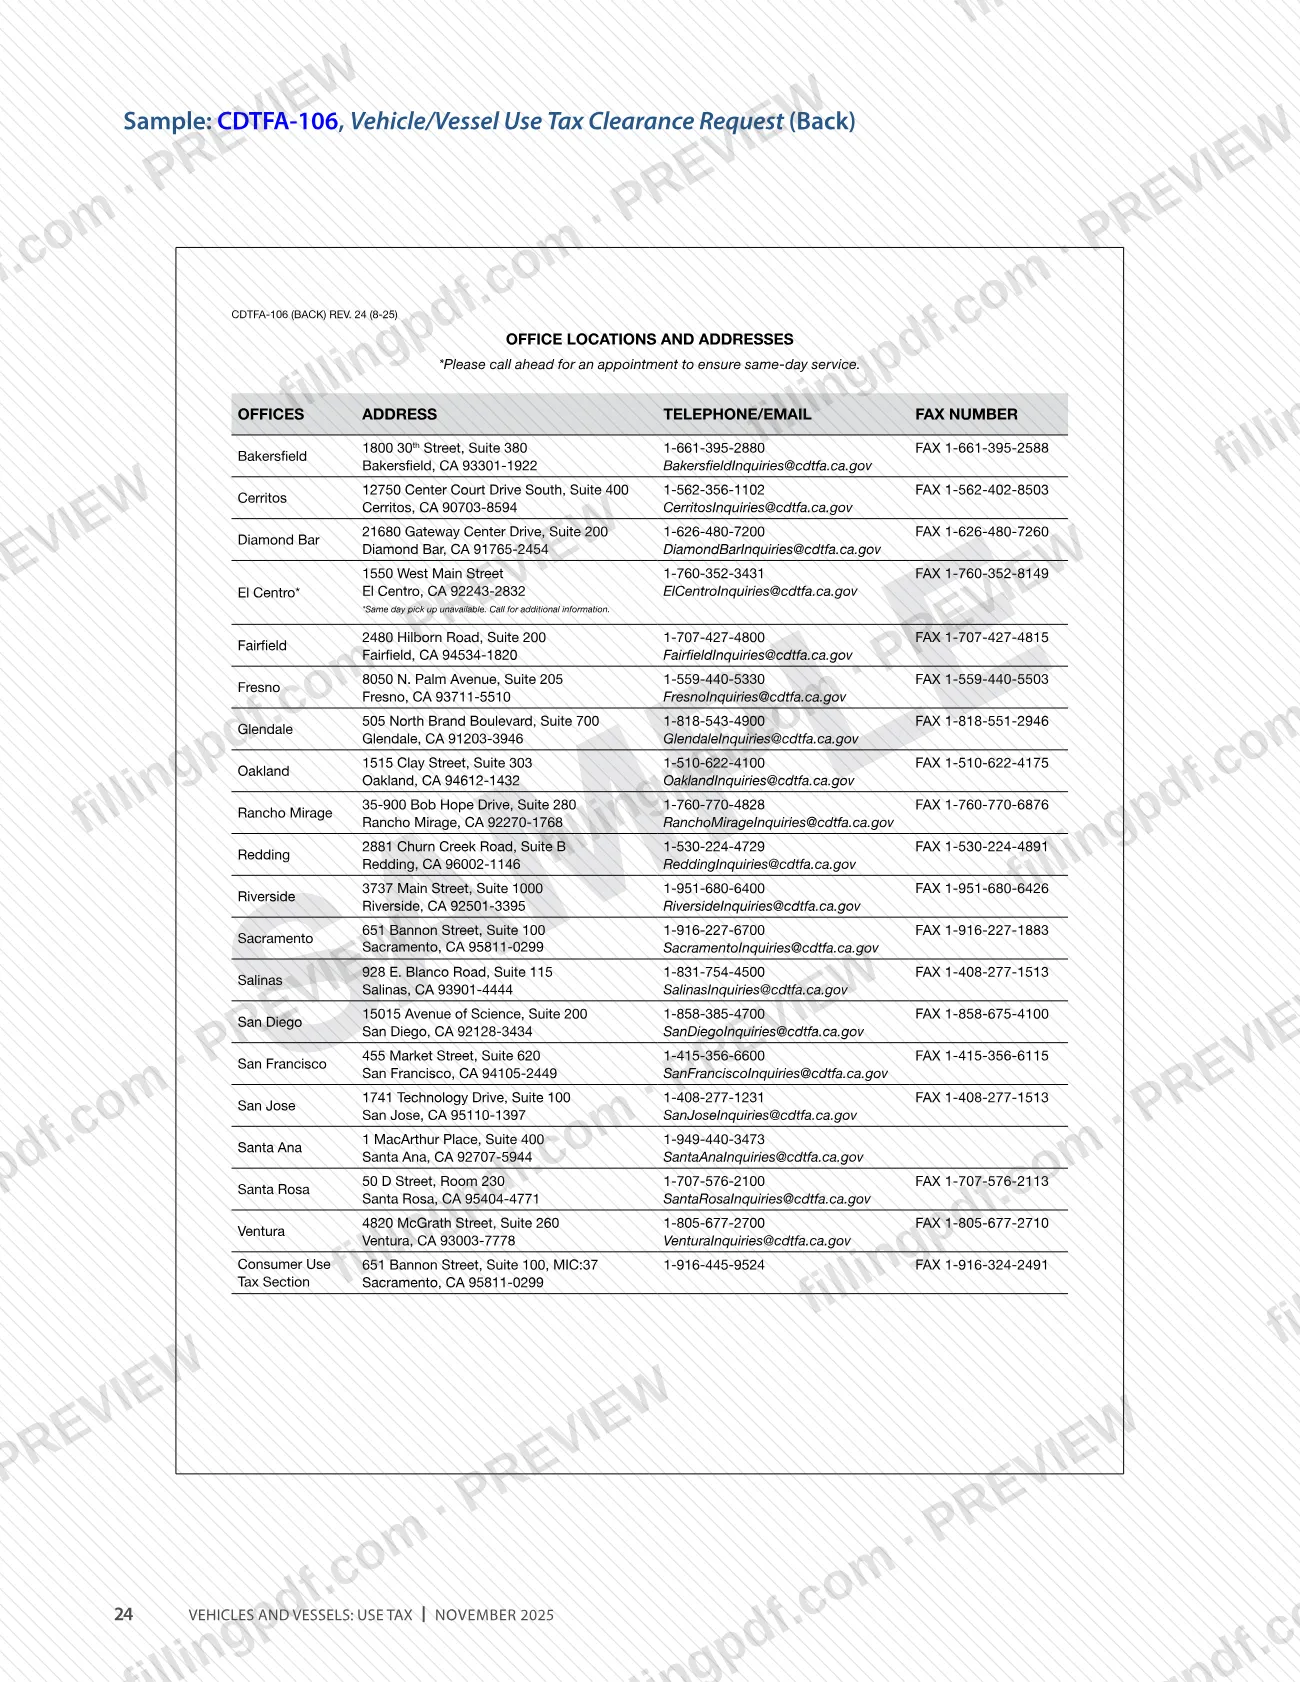
- By fax or in person: deliver CDTFA-106 to your local CDTFA office or the Consumer Use Tax Section in Sacramento. The back of CDTFA-106 lists office addresses, telephone and fax numbers; some offices ask you to call ahead for an appointment.
- To pay use tax directly: use the CDTFA website at www.cdtfa.ca.gov (Register, then Pay Use Tax or File an Exemption for a Vehicle, Vessel, Aircraft, or Mobile Home) or visit a field office.
If CDTFA approves, return the original CDTFA-111 or CDTFA-111-B to DMV with your registration application and keep copies. If the request is denied, pay the use tax to DMV; you may file a claim for refund with Refunds Section MIC:39, California Department of Tax and Fee Administration, PO Box 942879, Sacramento, CA 94279-0039. Questions: Consumer Use Tax Section, 1-916-445-9524, or the Customer Service Center, 1-800-400-7115 (CRS:711).
FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Holding back the DMV transfer fee until CDTFA replies; the fee must be paid on time even while a clearance request is pending, or penalty charges can apply.
- Sending original documents with CDTFA-106; CDTFA asks for photocopies only.
- Calling a transfer a gift when you took over the loan, paid or traded something, or got it as employer compensation; use tax then applies to the consideration given.
- Expecting the family exemption for a stepparent, stepchild or similar step relation without a legal adoption, or for a purchase from a family member who is a licensed dealer.
- Transferring a vehicle or vessel into an irrevocable trust and expecting an exemption; the publication says the law has none.
- Having a friend or agent deliver the vehicle or vessel to you in California and claiming out-of-state delivery; diverted delivery means use tax applies.
- Using Publication 52 for a documented vessel registered with the U.S. Coast Guard; it does not apply to those vessels.
- Not keeping records of out-of-state use, or of interstate commerce use, for at least eight years.
- Filing a claim for refund after the deadline; after it passes, CDTFA generally cannot refund overpayments.
Frequently asked questions
What is Pub 52 used for?
Pub 52 is CDTFA's publication Vehicles and Vessels: Use Tax. It gives examples of vehicle and vessel transfers not subject to California use tax and explains how to apply for a use tax clearance with CDTFA-106, so you can register without paying use tax when an exemption applies.
Do I need a use tax clearance to register my vehicle with DMV?
Only if DMV asks for one. DMV can process many nontaxable transfers, such as transfers between qualified family members, without a clearance. If DMV does ask, you request it from CDTFA and give DMV the original CDTFA-111 or CDTFA-111-B with your registration application.
Is a vehicle I received as a gift subject to California use tax?
No, a true gift is not subject to use tax. It is not a gift if you paid cash, traded property, provided services or assumed a liability for it, or if your employer gave it to you as compensation. Taking over a loan means use tax applies to the balance owed.
Which family members qualify for the family purchase exemption?
A purchase from a parent, grandparent, grandchild, child, spouse or domestic partner is exempt. Minors can also buy from a minor brother or sister related by blood or adoption. It does not apply to a family member who is a licensed dealer, or to step relations without a legal adoption.
What if CDTFA denies my use tax clearance request?
Use tax is then due and you must pay it to DMV, even if you disagree with CDTFA's findings. You may then file a claim for refund with CDTFA; the publication refers to publication 117, Filing a Claim for Refund.
Is a vehicle bought outside California subject to use tax?
It can be. If you first used it in California, use tax applies. If you first used it elsewhere and brought it in within 12 months of purchase, it is presumed purchased for use in California under certain conditions, but you can rebut that with documentation of use outside the state.
What should I do if I did not pay use tax at DMV?
Report and pay the use tax directly to CDTFA on www.cdtfa.ca.gov, or in person at a field office. Have both parties' names and addresses, the VIN, plate, CF or HIN, make, model, year, purchase date, total purchase price and registration or mooring address ready.
Does Pub 52 cover vessels documented with the U.S. Coast Guard?
No. Pub 52 does not apply to documented vessels registered with the U.S. Coast Guard. For those, the publication refers you to publication 40, Watercraft Industry, or to CDTFA's Customer Service Center at 1-800-400-7115 (CRS:711).
Can I fill out Pub 52 online on FillingPDF?
You can fill out the PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file anything with CDTFA or DMV; you submit the CDTFA-106 request through CDTFA's channels.
Ready to fill out Publication 52?
Fill out Publication 52 now