
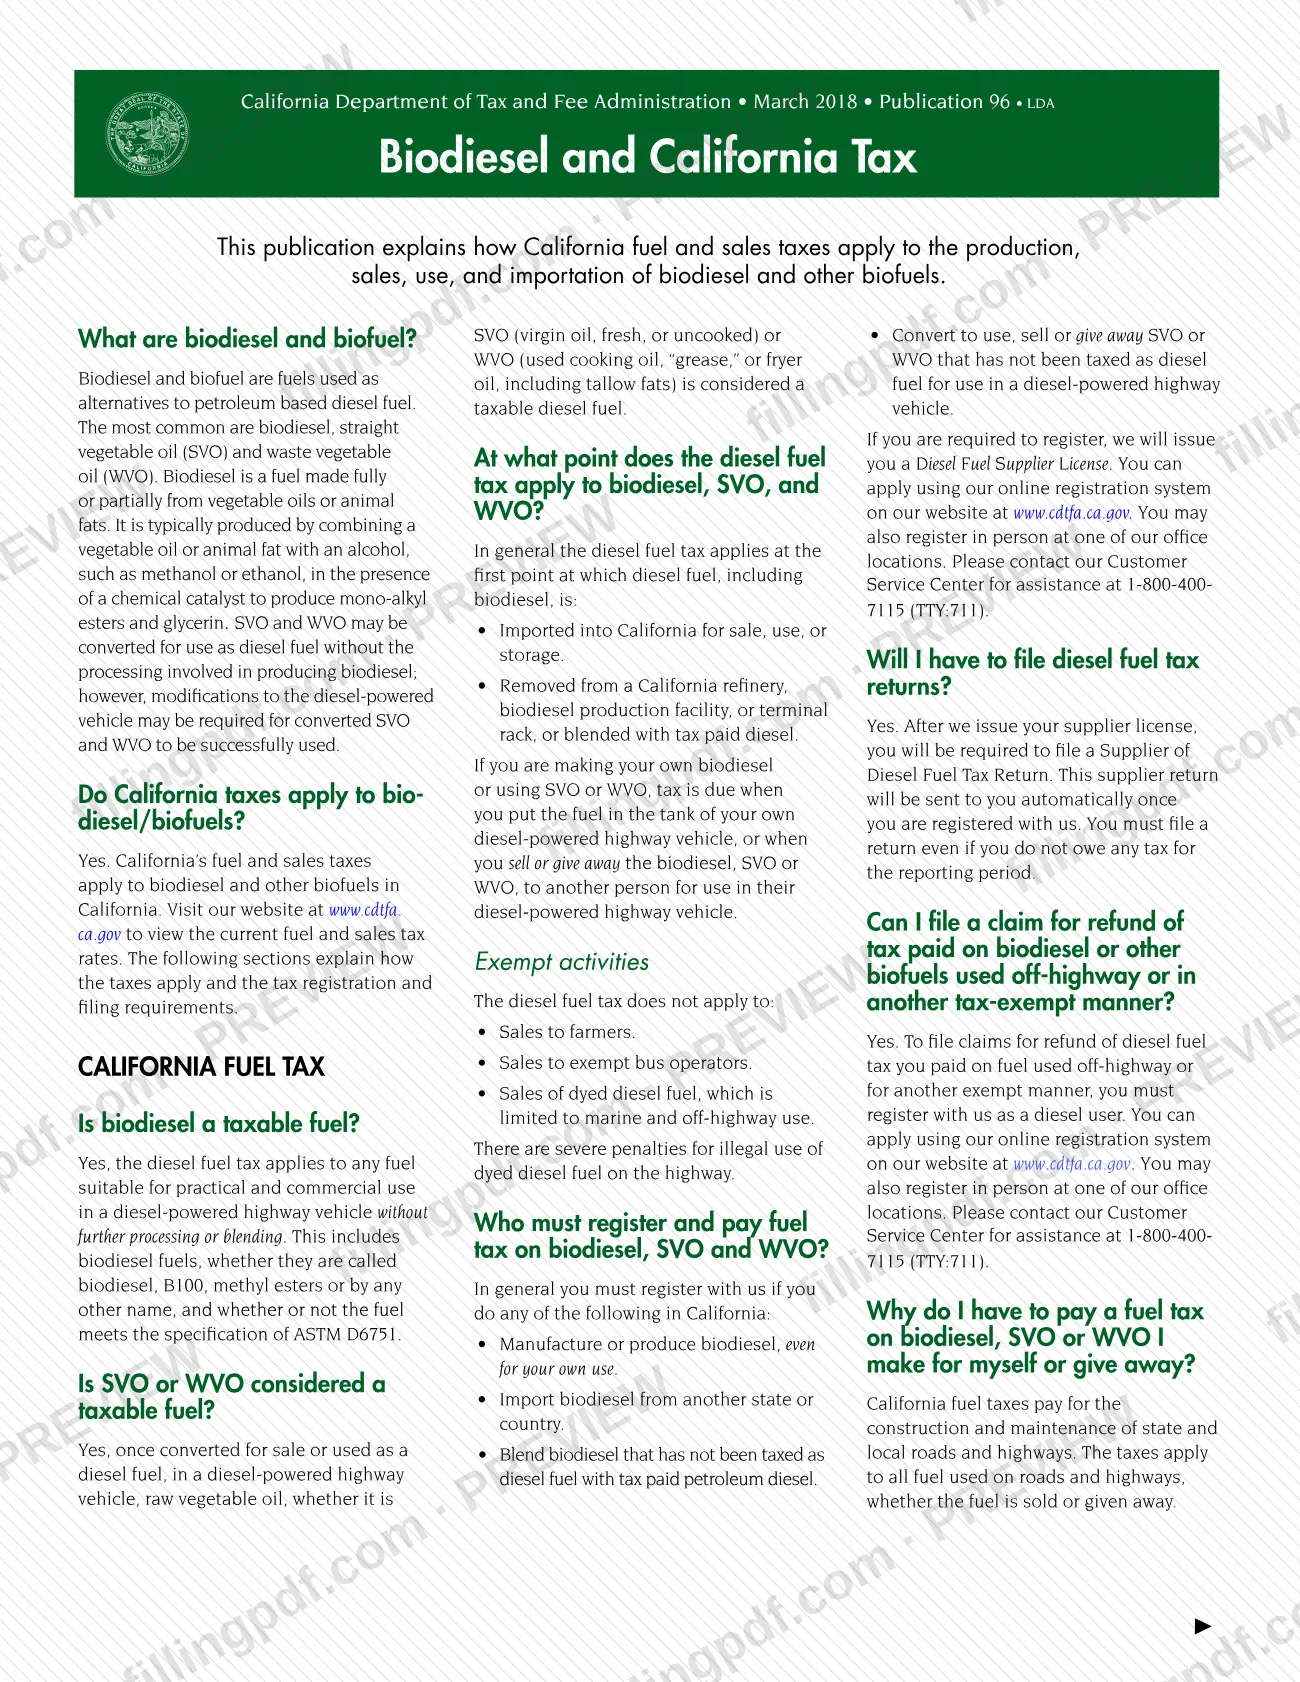
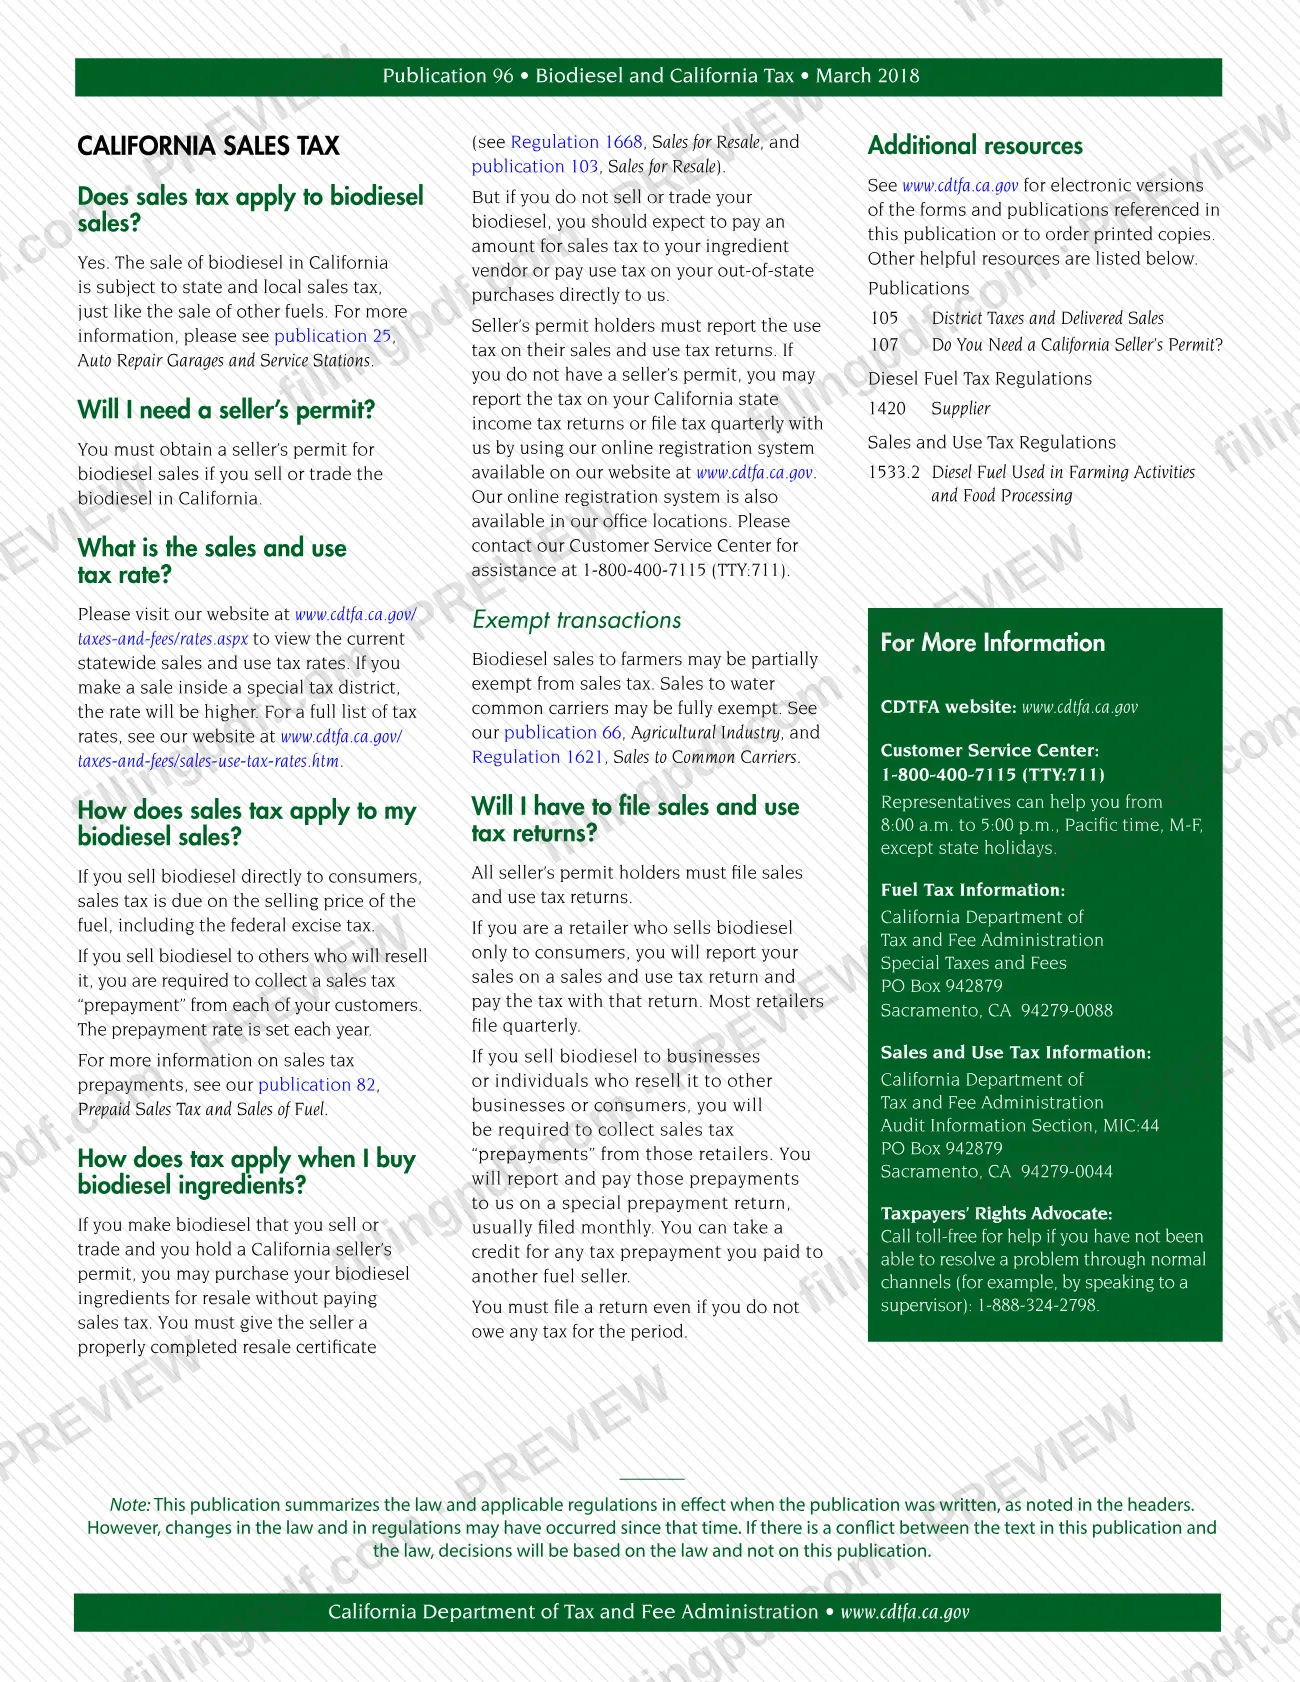
Pub 96, Biodiesel and California Tax, is a publication of the California Department of Tax and Fee Administration (CDTFA) that explains how California fuel and sales taxes apply to producing, selling, using and importing biodiesel and other biofuels. It is written for people who make their own biodiesel, run diesel vehicles on straight or waste vegetable oil, or sell biodiesel to others. On this page you can view and download the official PDF; it is a guide, not a form to submit, and the CDTFA publishes it at cdtfa.ca.gov.
Last updated
What is Publication 96?
Publication 96, Biodiesel and California Tax, is a California Department of Tax and Fee Administration (CDTFA) publication that explains how California's fuel and sales taxes apply to the production, sale, use and importation of biodiesel and other biofuels.
The publication defines the fuels it covers. Biodiesel is a fuel made fully or partially from vegetable oils or animal fats. SVO is straight vegetable oil (virgin, fresh or uncooked), and WVO is waste vegetable oil (used cooking oil, "grease" or fryer oil, including tallow fats). SVO and WVO are taxable diesel fuel once they are converted for sale or used in a diesel-powered highway vehicle.
It is organized in two parts. The California fuel tax part covers when the diesel fuel tax applies, who must register and receive a Diesel Fuel Supplier License, supplier returns, exempt activities, and refund claims for fuel used off-highway or in another tax-exempt manner. The California sales tax part covers sales of biodiesel, the seller's permit, tax on biodiesel ingredients, prepayments and sales and use tax returns.
The publication gives no tax rates; it sends readers to the CDTFA website for current rates. It summarizes the law in effect when it was written (March 2018) and says that if it conflicts with the law, decisions are based on the law. It is not a return, an application or a registration form.
Who needs to file Publication 96?
The main audience is anyone who makes, imports, blends, sells, gives away or burns biodiesel, SVO or WVO in California. The publication says you must generally register with the CDTFA if you do any of the following in California:
- Manufacture or produce biodiesel, even for your own use.
- Import biodiesel from another state or country.
- Blend biodiesel that has not been taxed as diesel fuel with tax-paid petroleum diesel.
- Convert to use, sell or give away SVO or WVO that has not been taxed as diesel for use in a diesel-powered highway vehicle.
Sellers of biodiesel in California must obtain a seller's permit if they sell or trade it. Buyers who use biodiesel off-highway or in another tax-exempt manner and want a refund of diesel fuel tax must register as a diesel user.
The diesel fuel tax does not apply to sales to farmers, sales to exempt bus operators, or sales of dyed diesel fuel, which is limited to marine and off-highway use. Biodiesel sales to farmers may be partially exempt from sales tax, and sales to water common carriers may be fully exempt.
When to file Publication 96
Publication 96 is a guide, so it has no filing deadline of its own. The timing rules it describes are tied to your activity. Diesel fuel tax generally applies at the first point the fuel is imported into California for sale, use or storage, removed from a California refinery, biodiesel production facility or terminal rack, or blended with tax-paid diesel. If you make your own biodiesel or use SVO or WVO, tax is due when you put the fuel in your own diesel-powered highway vehicle tank, or when you sell or give it to another person for use in a diesel-powered highway vehicle.
After the CDTFA issues your supplier license, a Supplier of Diesel Fuel Tax Return is sent to you automatically and you must file it even if you owe no tax for the period. Most retailers file sales and use tax returns quarterly; prepayment returns are usually filed monthly.
Documents you need
- A properly completed resale certificate, given to your ingredient seller, if you make biodiesel that you sell or trade and hold a California seller's permit and want to buy ingredients for resale without paying sales tax.
How to fill out Publication 96
Download the official publication
Open the CDTFA's Publication 96 PDF (March 2018). It is an informational guide with no lines to complete.
Identify which fuel you handle
Read the definitions of biodiesel, SVO and WVO, and check whether your fuel is taxable diesel fuel when used in a diesel-powered highway vehicle.
Check fuel tax registration and returns
Compare your activity with the list of those who must register, and note whether a Diesel Fuel Supplier License, supplier return or diesel user registration applies.
Review sales and use tax rules
If you sell or trade biodiesel, read the seller's permit, resale certificate, prepayment and sales and use tax return sections.
Contact the CDTFA for current details
Use the CDTFA website or Customer Service Center at 1-800-400-7115 (TTY:711) for current rates and registration, since the publication reflects the law as of March 2018.
How to submit Publication 96
Publication 96 itself is not filed. The actions it describes go through the CDTFA's online registration system, its office locations, its Customer Service Center and its mailing addresses.
- Online: register for a Diesel Fuel Supplier License, diesel user registration or a seller's permit through the online registration system at www.cdtfa.ca.gov.
- In person: register at one of the CDTFA office locations.
- By phone: call the Customer Service Center at 1-800-400-7115 (TTY:711). Representatives are available 8:00 a.m. to 5:00 p.m., Pacific time, Monday to Friday, except state holidays.
- By mail, fuel tax questions: California Department of Tax and Fee Administration, Special Taxes and Fees, PO Box 942879, Sacramento, CA 94279-0088.
- By mail, sales and use tax questions: California Department of Tax and Fee Administration, Audit Information Section, MIC:44, PO Box 942879, Sacramento, CA 94279-0044.
If normal channels have not resolved a problem, the Taxpayers' Rights Advocate can be reached toll-free at 1-888-324-2798. FillingPDF lets you view and download the official PDF; any registration or return follows the CDTFA channels above.
Common mistakes to avoid
- Assuming biodiesel, SVO or WVO you make for yourself or give away is untaxed; the publication says fuel tax applies to all fuel used on roads and highways, whether sold or given away.
- Skipping the Supplier of Diesel Fuel Tax Return in a period with no tax due; the return must be filed even if you owe nothing.
- Using dyed diesel fuel on the highway; the publication warns of severe penalties for illegal use.
- Buying biodiesel ingredients without paying sales tax and without giving the seller a properly completed resale certificate and holding a seller's permit.
- Claiming a refund of diesel fuel tax paid on off-highway or other exempt use without first registering with the CDTFA as a diesel user.
- Treating SVO or WVO as untaxed once it is used in a diesel-powered highway vehicle; it is taxable diesel fuel when converted for sale or use.
- Relying on this March 2018 publication for current tax rates; it directs you to the CDTFA website for them.
- Not reporting use tax on out-of-state ingredient purchases when you do not sell or trade your biodiesel.
Frequently asked questions
What is CDTFA Pub 96?
Pub 96 is the CDTFA publication titled Biodiesel and California Tax. It explains how California fuel and sales taxes apply to producing, selling, using and importing biodiesel, straight vegetable oil (SVO) and waste vegetable oil (WVO). It is a guide, not a form you complete.
Do California taxes apply to biodiesel?
Yes. The publication says California's fuel and sales taxes apply to biodiesel and other biofuels in California. The diesel fuel tax applies to any fuel suitable for use in a diesel-powered highway vehicle without further processing or blending, whatever it is called.
Do I pay fuel tax on biodiesel I make for myself?
Yes. If you make your own biodiesel or use SVO or WVO, tax is due when you put the fuel in the tank of your own diesel-powered highway vehicle, or when you sell or give it to another person for highway use. You generally must register with the CDTFA.
Do I need a seller's permit to sell biodiesel in California?
Yes, if you sell or trade biodiesel in California. Sales of biodiesel are subject to state and local sales tax, and all seller's permit holders must file sales and use tax returns, even when they owe no tax for the period.
Can I get a refund of diesel fuel tax on off-highway biodiesel use?
Yes. You can file a claim for refund of diesel fuel tax paid on fuel used off-highway or in another exempt manner, but you must first register with the CDTFA as a diesel user, online, in person at an office or with help from the Customer Service Center.
Does Pub 96 list current tax rates?
No. The publication directs readers to the CDTFA website, www.cdtfa.ca.gov, for current fuel and sales tax rates. It is dated March 2018 and says that if it conflicts with the law, decisions will be based on the law.
Can I fill out Pub 96 online on FillingPDF?
Pub 96 is an informational publication with no lines to complete, so FillingPDF lets you view and download the official PDF. FillingPDF is independent of the CDTFA and does not register you, file returns or submit anything for you.
Ready to fill out Publication 96?
Fill out Publication 96 now