
LTA 2021/026 is Letter To Assessors No. 2021/026, dated June 25, 2021, in which the California State Board of Equalization (BOE) Property Tax Department explains three base year value transfers for property damaged or destroyed in a Governor-proclaimed disaster. It is useful for anyone looking into Santa Barbara County property tax relief after a disaster, because the claims it describes are filed with the county Assessor. On FillingPDF you can open the PDF online and download or print it. The letter is guidance for assessors, not a claim form; the claim forms it names are BOE-65-P, BOE-65-PT and BOE-19-V.
Last updated
What is LTA 2021/026?
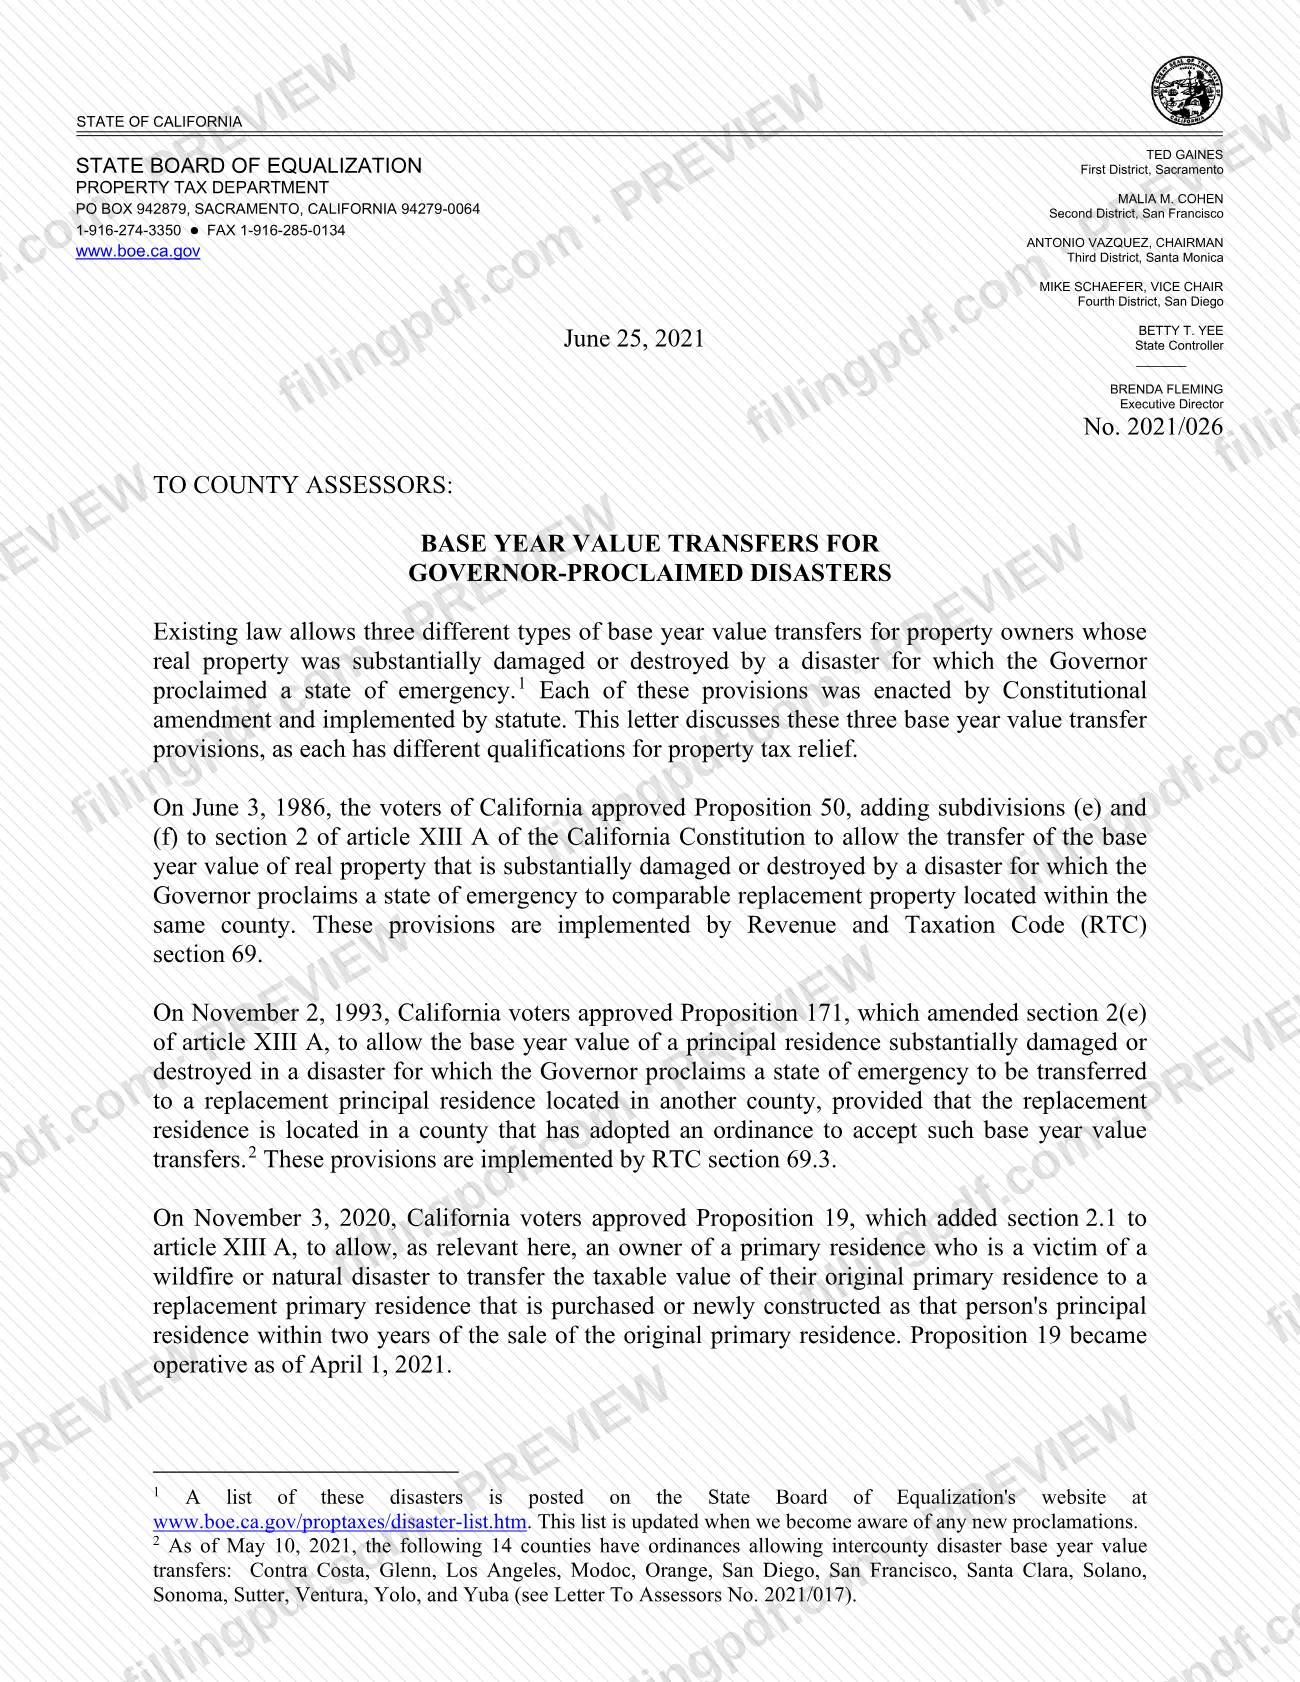
Base Year Value Transfers for Governor Proclaimed Disasters LTA 2021/026 is a letter from the California State Board of Equalization (BOE) Property Tax Department to county assessors, comparing the three base year value transfers available when real property is substantially damaged or destroyed in a Governor-proclaimed state of emergency.
The letter explains that each transfer was enacted by Constitutional amendment and implemented by statute, and that each has different qualifications:
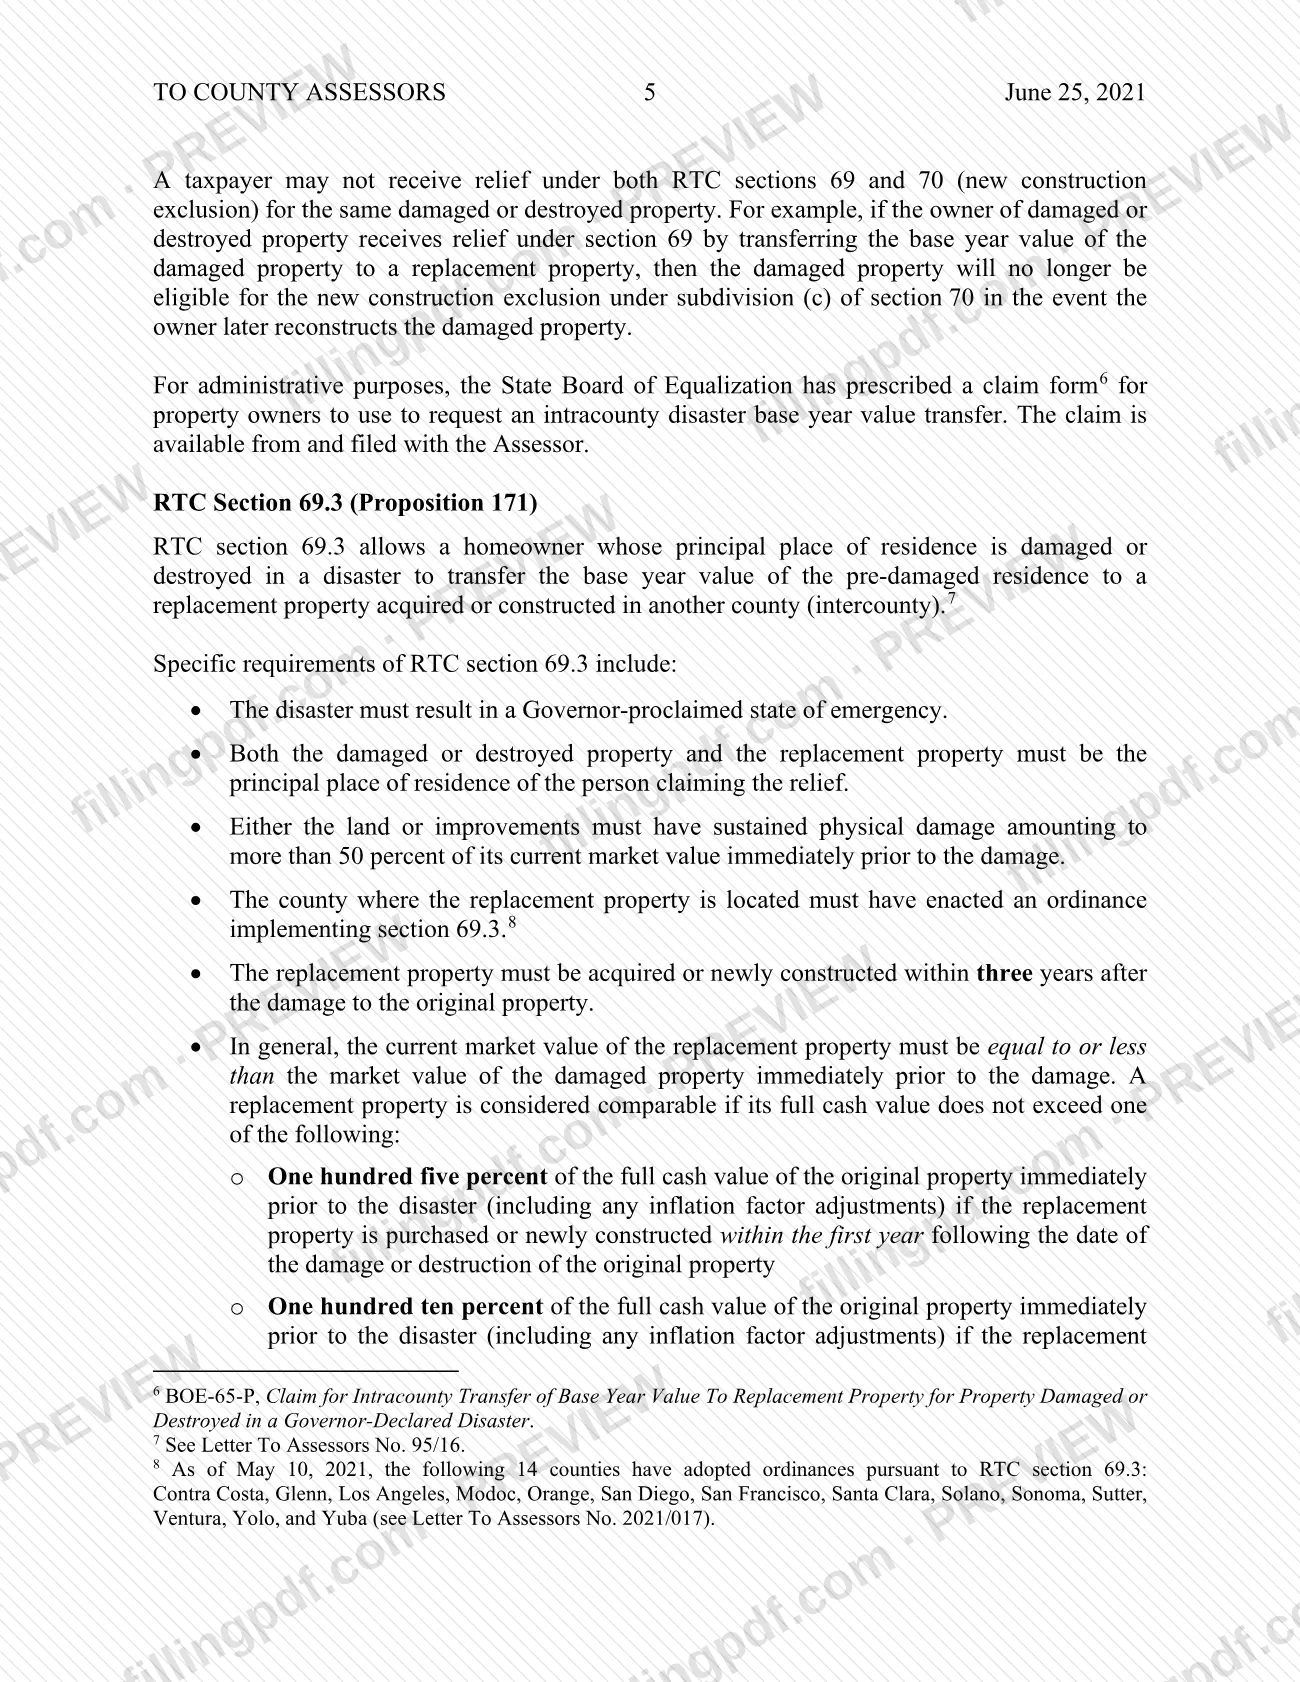
- Revenue and Taxation Code (RTC) section 69 (Proposition 50): transfer to comparable replacement property in the same county, for all property types.
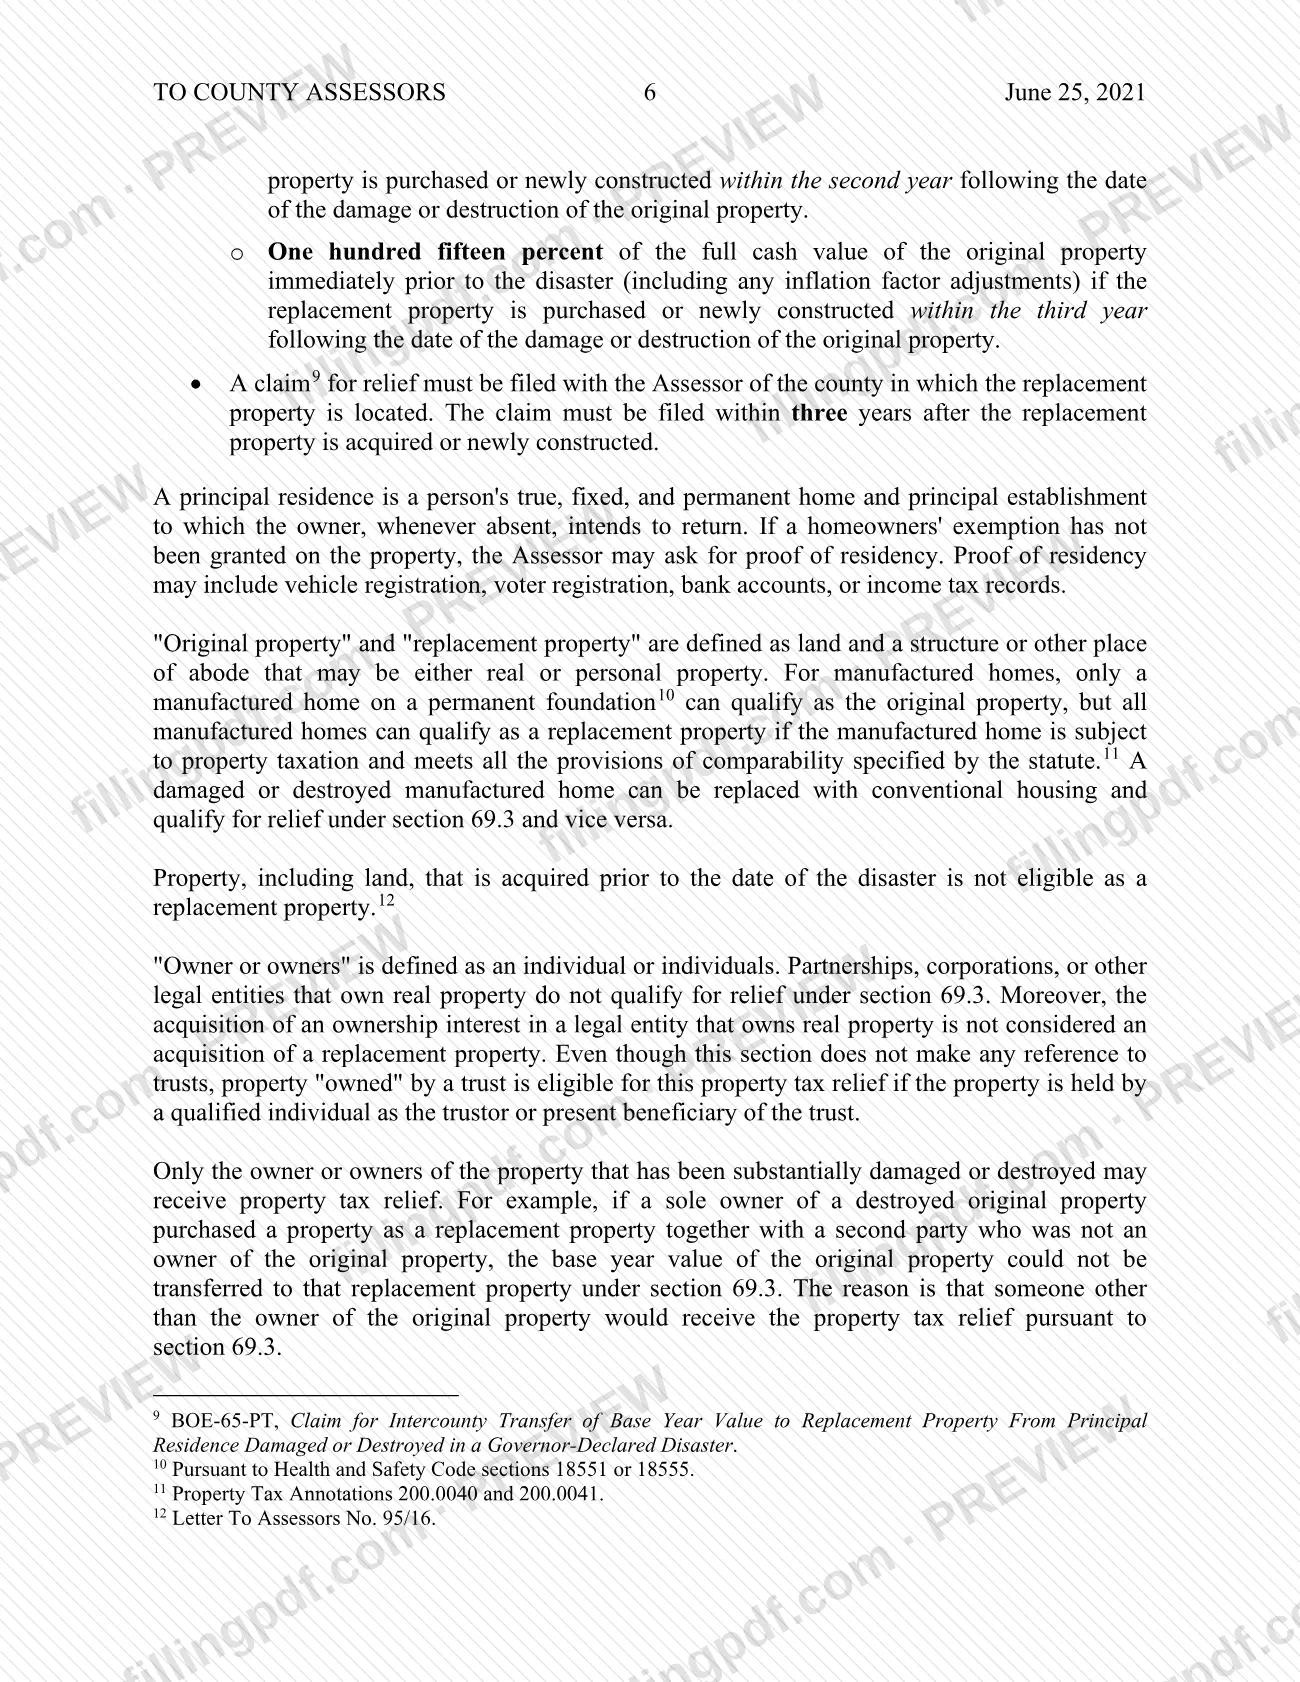
- RTC section 69.3 (Proposition 171): transfer of a principal residence's base year value to a replacement residence in another county, if that county has adopted an implementing ordinance.
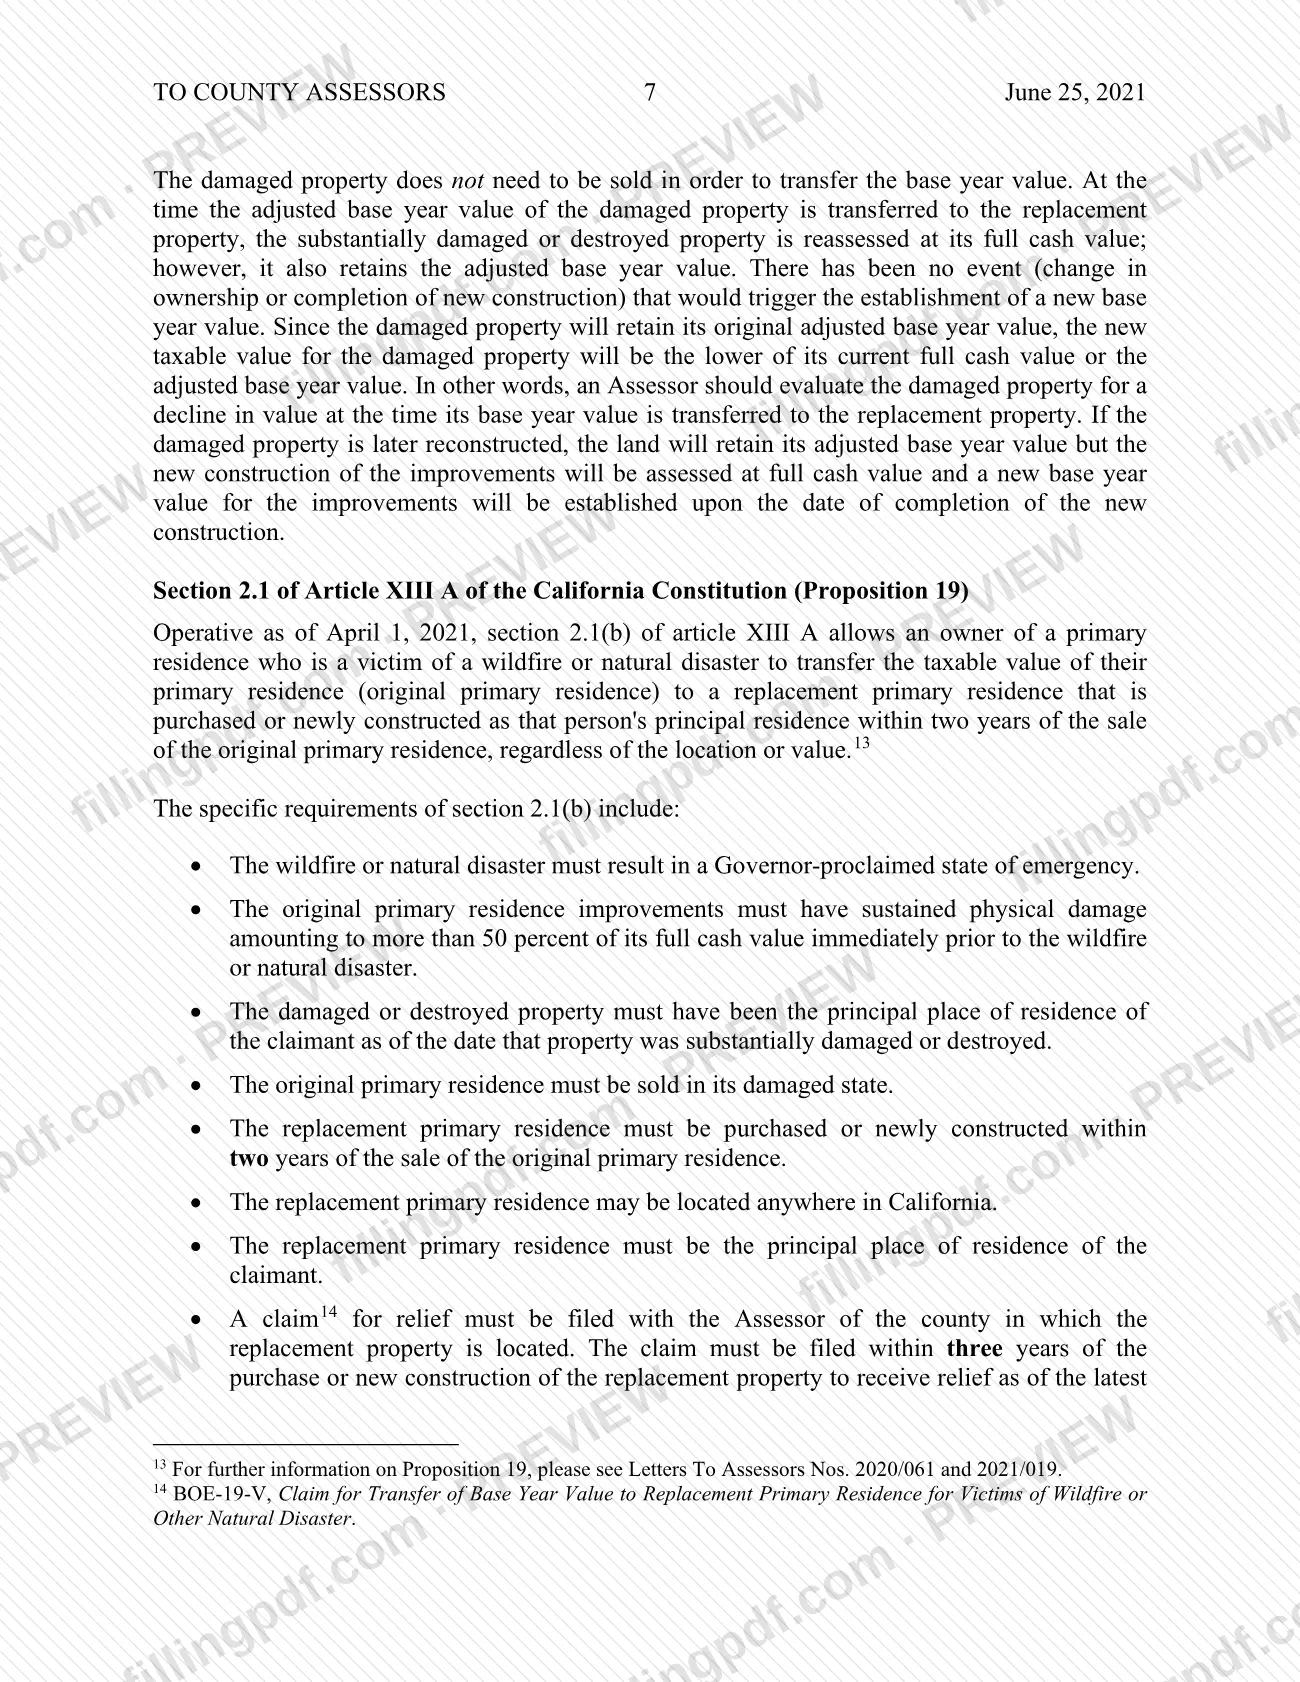
- Article XIII A, section 2.1(b) of the California Constitution (Proposition 19), operative April 1, 2021: transfer of the taxable value of a primary residence to a replacement primary residence anywhere in California.
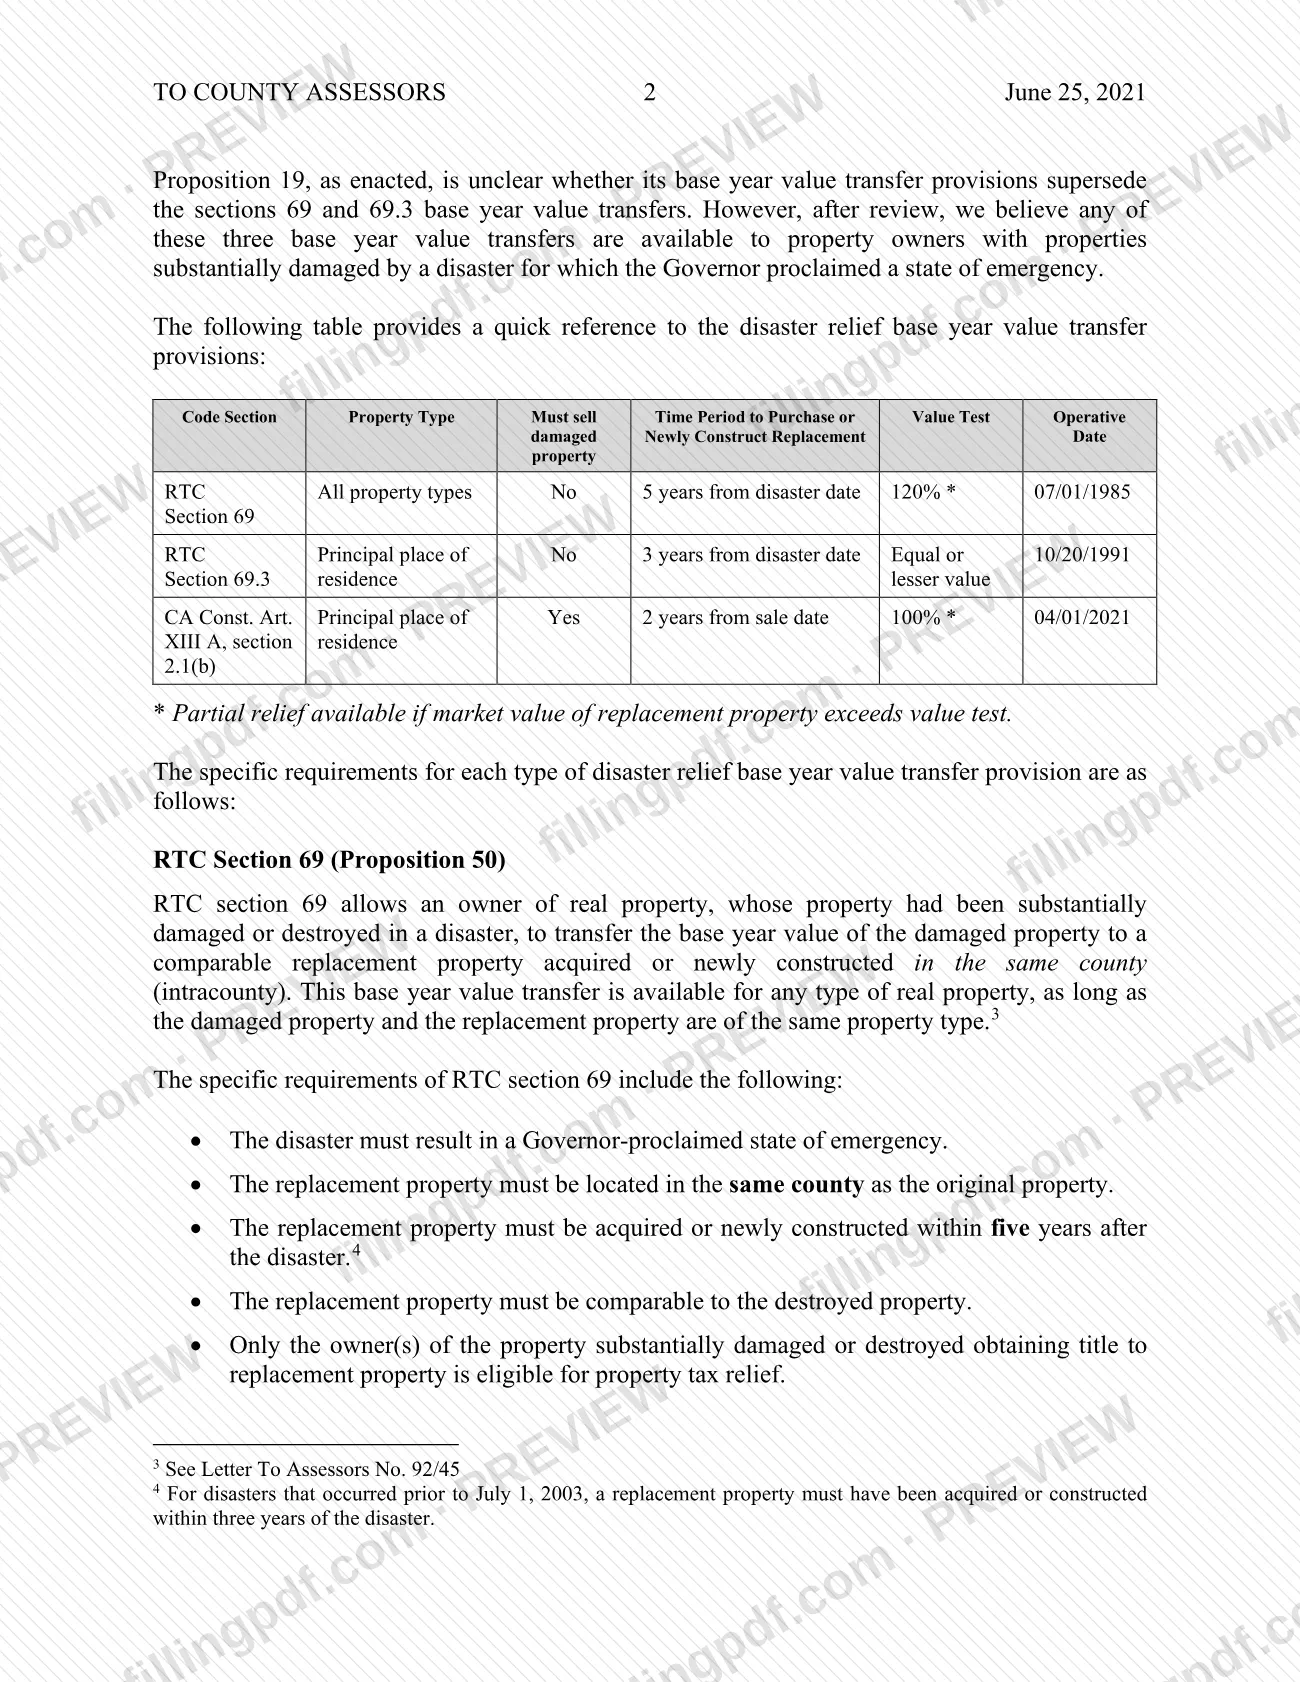
A quick-reference table compares property type, whether the damaged property must be sold, the purchase or construction period, the value test and the operative date. The letter also states that all three transfers are available to owners of qualifying damaged property. It is not itself a claim: owners request a transfer on the BOE claim forms BOE-65-P, BOE-65-PT or BOE-19-V.
Who needs to file LTA 2021/026?
The main readers are owners of real property that was substantially damaged or destroyed by a disaster for which the Governor proclaimed a state of emergency, and the county assessors the letter is addressed to. Which transfer fits depends on the property and the replacement.
- Section 69: owners of any type of real property, if the replacement is in the same county and of the same property type. A licensed manufactured home is not eligible because it has no base year value.
- Section 69.3: individuals whose principal place of residence was damaged by more than 50 percent of its market value, moving to a county that has adopted an ordinance. Partnerships, corporations and other legal entities do not qualify; property held by a qualified individual as trustor or present beneficiary of a trust can.
- Section 2.1(b): owners of a primary residence who are victims of a wildfire or natural disaster and who sold the original residence in its damaged state.
Only the owner of the damaged property can receive relief, and property acquired before the disaster date is not eligible as a replacement. As of May 10, 2021, the letter's list of 14 counties with intercounty ordinances does not include Santa Barbara; ask the Assessor about current status.
When to file LTA 2021/026
The triggering event is substantial damage to or destruction of property in a disaster with a Governor-proclaimed state of emergency; claims follow once a replacement is acquired or built. The letter itself has no filing date, but each transfer sets its own windows.
- Section 69: the replacement must be acquired or newly constructed within five years after the disaster (three years for disasters before July 1, 2003).
- Section 69.3: the replacement must be acquired or newly constructed within three years after the damage, and the claim must be filed within three years after the replacement is acquired or newly constructed.
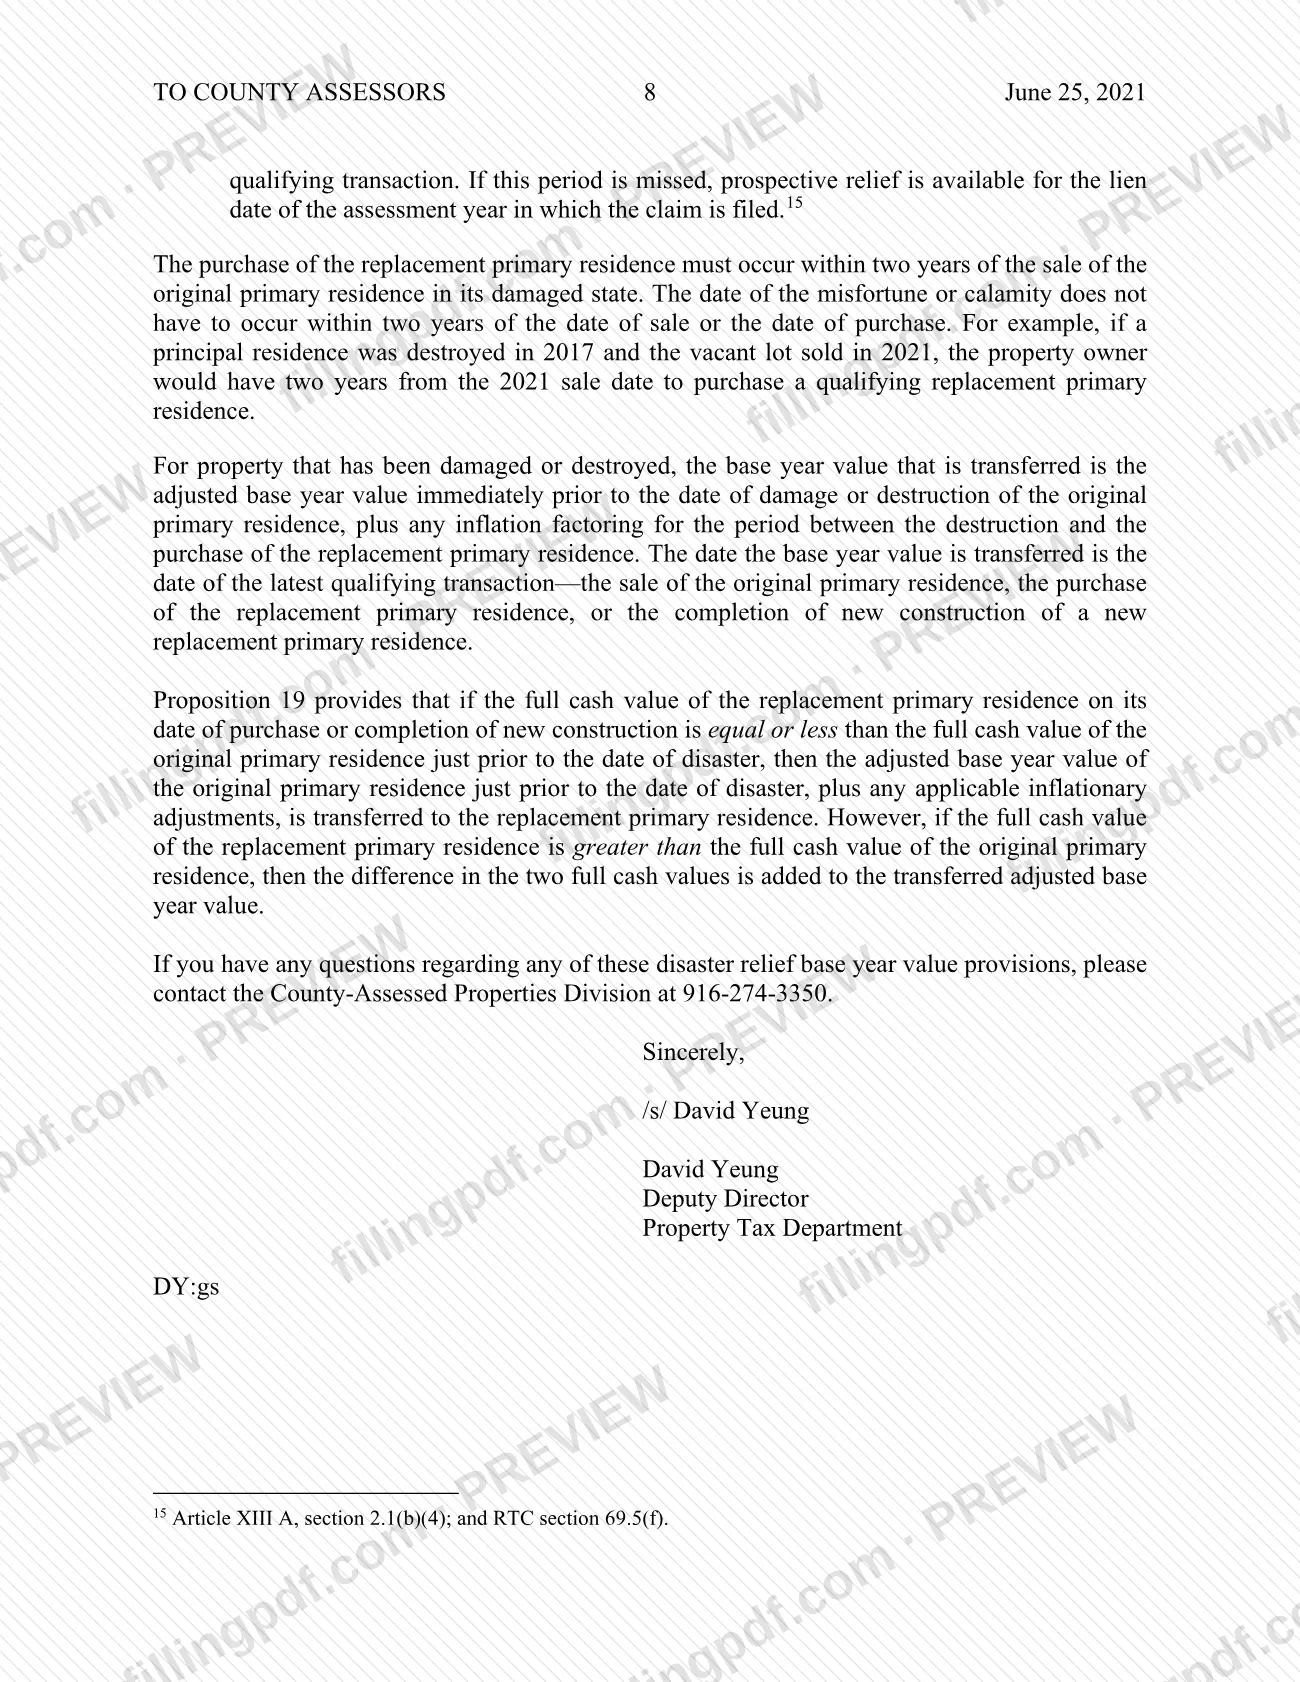
- Section 2.1(b): the replacement must be purchased or newly constructed within two years of the sale of the original residence. File the claim within three years of the purchase or new construction to receive relief as of the latest qualifying transaction. If that period is missed, relief is prospective, from the lien date of the assessment year in which the claim is filed.
The disaster itself need not fall within two years of the sale or purchase under section 2.1(b).
Documents you need
- BOE-65-P, Claim for Intracounty Transfer of Base Year Value To Replacement Property for Property Damaged or Destroyed in a Governor-Declared Disaster: the claim for a section 69 transfer within the same county.
- BOE-65-PT, Claim for Intercounty Transfer of Base Year Value to Replacement Property From Principal Residence Damaged or Destroyed in a Governor-Declared Disaster: the claim for a section 69.3 transfer.
- BOE-19-V, Claim for Transfer of Base Year Value to Replacement Primary Residence for Victims of Wildfire or Other Natural Disaster: the claim for a section 2.1(b) transfer.
- Proof of residency, only if the Assessor asks and no homeowners' exemption has been granted on the property: for example vehicle registration, voter registration, bank accounts or income tax records.
How to fill out LTA 2021/026
Confirm a Governor-proclaimed disaster
All three transfers require a disaster for which the Governor proclaimed a state of emergency. The BOE posts the list at www.boe.ca.gov/proptaxes/disaster-list.htm.
Compare the three transfer provisions
Use the letter's quick-reference table to compare section 69, section 69.3 and Article XIII A, section 2.1(b) by property type, sale requirement, replacement period and value test.
Check section 69 requirements
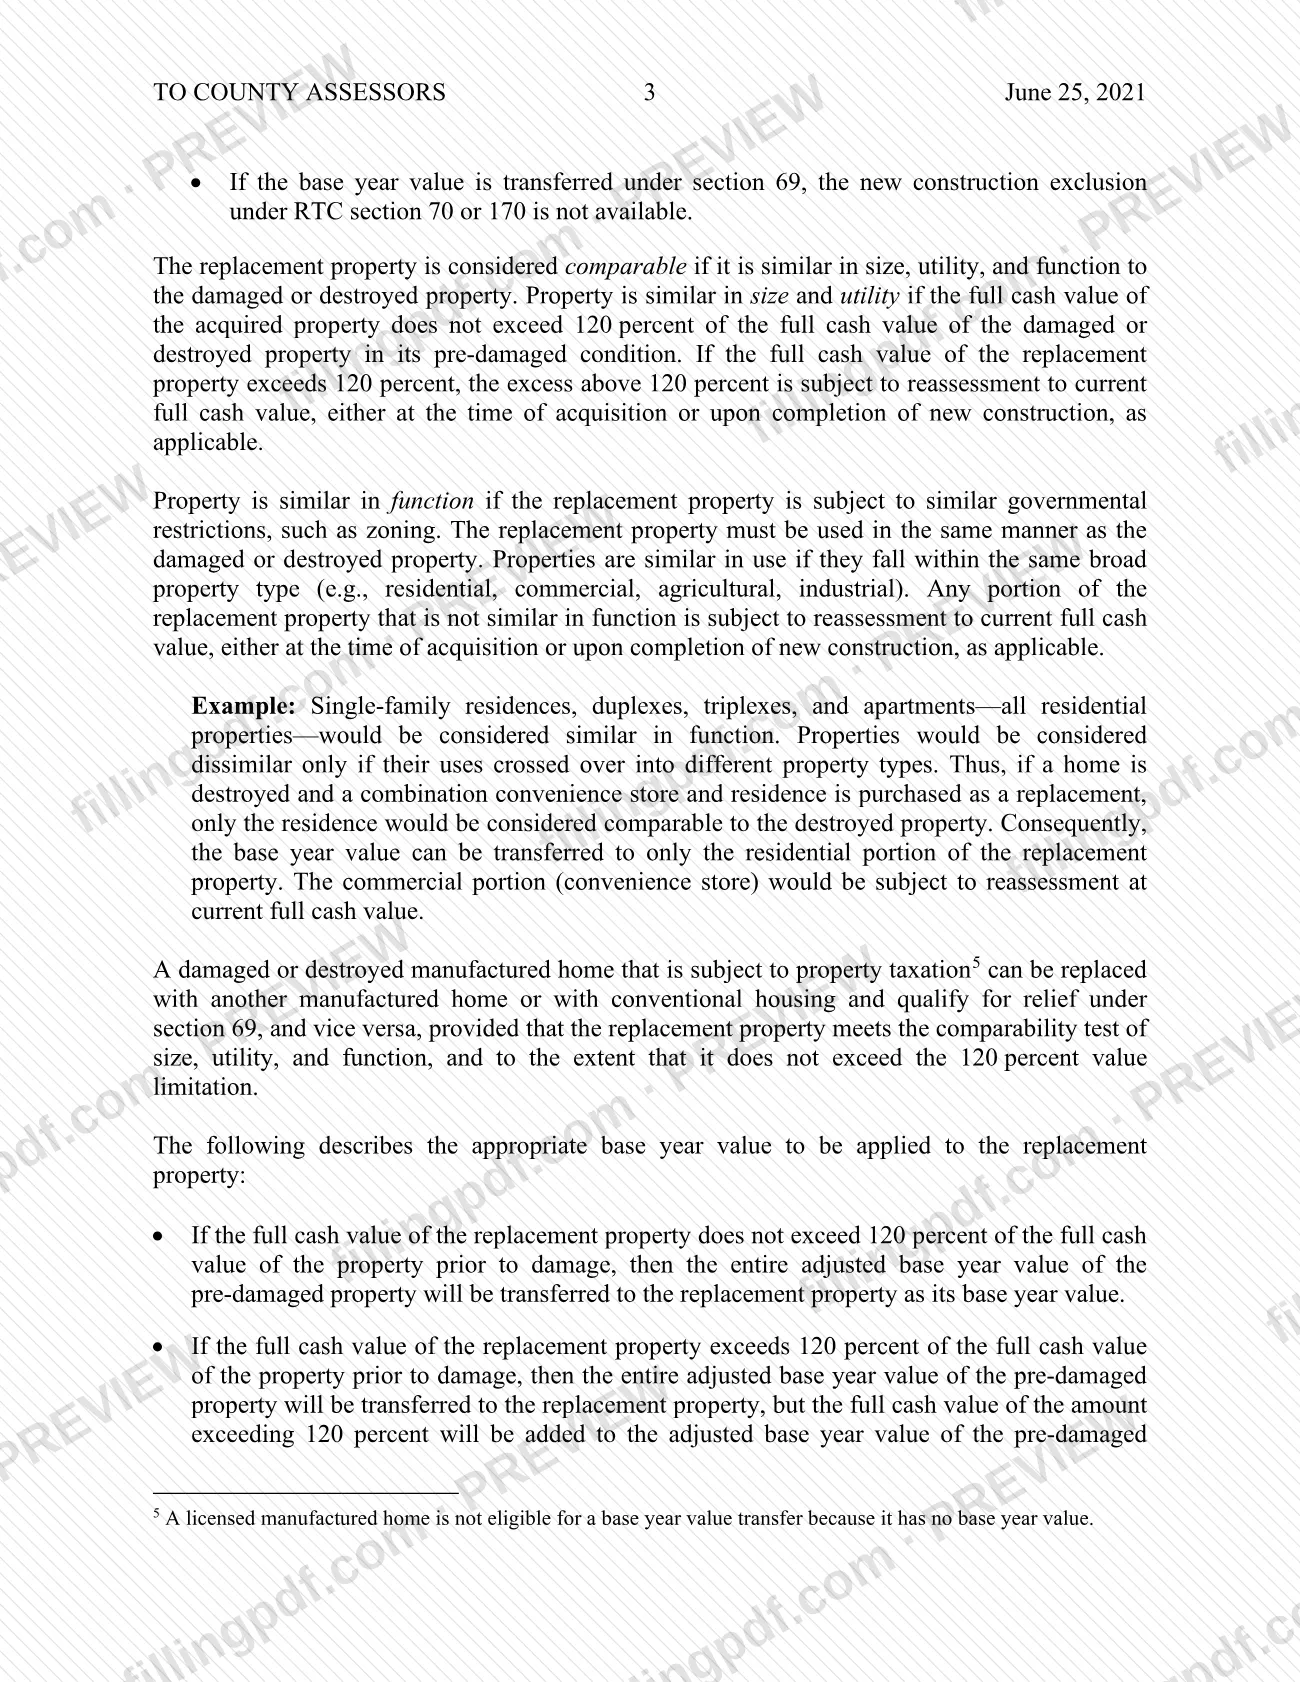
For a same-county replacement, confirm it is comparable, of the same property type, acquired or built within five years of the disaster and within 120 percent of the damaged property's full cash value, with partial relief above that.
Check section 69.3 requirements
For another county, confirm both properties are your principal residence, damage exceeds 50 percent of market value, the county has an ordinance, and the replacement value falls within the 105, 110 or 115 percent limit for the year it is bought.
Check section 2.1(b) requirements
Confirm the original residence was sold in its damaged state and the replacement primary residence in California was purchased or built within two years of that sale.
Get the matching claim form
Use BOE-65-P for section 69, BOE-65-PT for section 69.3 or BOE-19-V for section 2.1(b), obtained from the Assessor.
File the claim in time
File with the Assessor of the county where the replacement property is located. For sections 69.3 and 2.1(b), file within three years of acquiring or completing the replacement.
Review and download the PDF
Read the letter, then download or print the PDF from FillingPDF to keep with your records. Any claim is filed separately as described under How to submit.
How to submit LTA 2021/026
The letter is not submitted. Claims for the transfers it describes go to the county Assessor on the BOE claim forms.
- Section 69 (same county): the BOE-prescribed claim, BOE-65-P, is available from and filed with the Assessor.
- Section 69.3 (another county): file BOE-65-PT with the Assessor of the county where the replacement property is located.
- Section 2.1(b): file BOE-19-V with the Assessor of the county where the replacement property is located.
The Santa Barbara County Assessor's Forms Library at https://www.countyofsb.org/296/Assessor-Forms has a Disaster Relief section. Questions about the transfer provisions can go to the BOE County-Assessed Properties Division at 916-274-3350. The list of Governor-proclaimed disasters is at www.boe.ca.gov/proptaxes/disaster-list.htm. FillingPDF lets you view and download the PDF; any claim is submitted through the Assessor's channels above.
Common mistakes to avoid
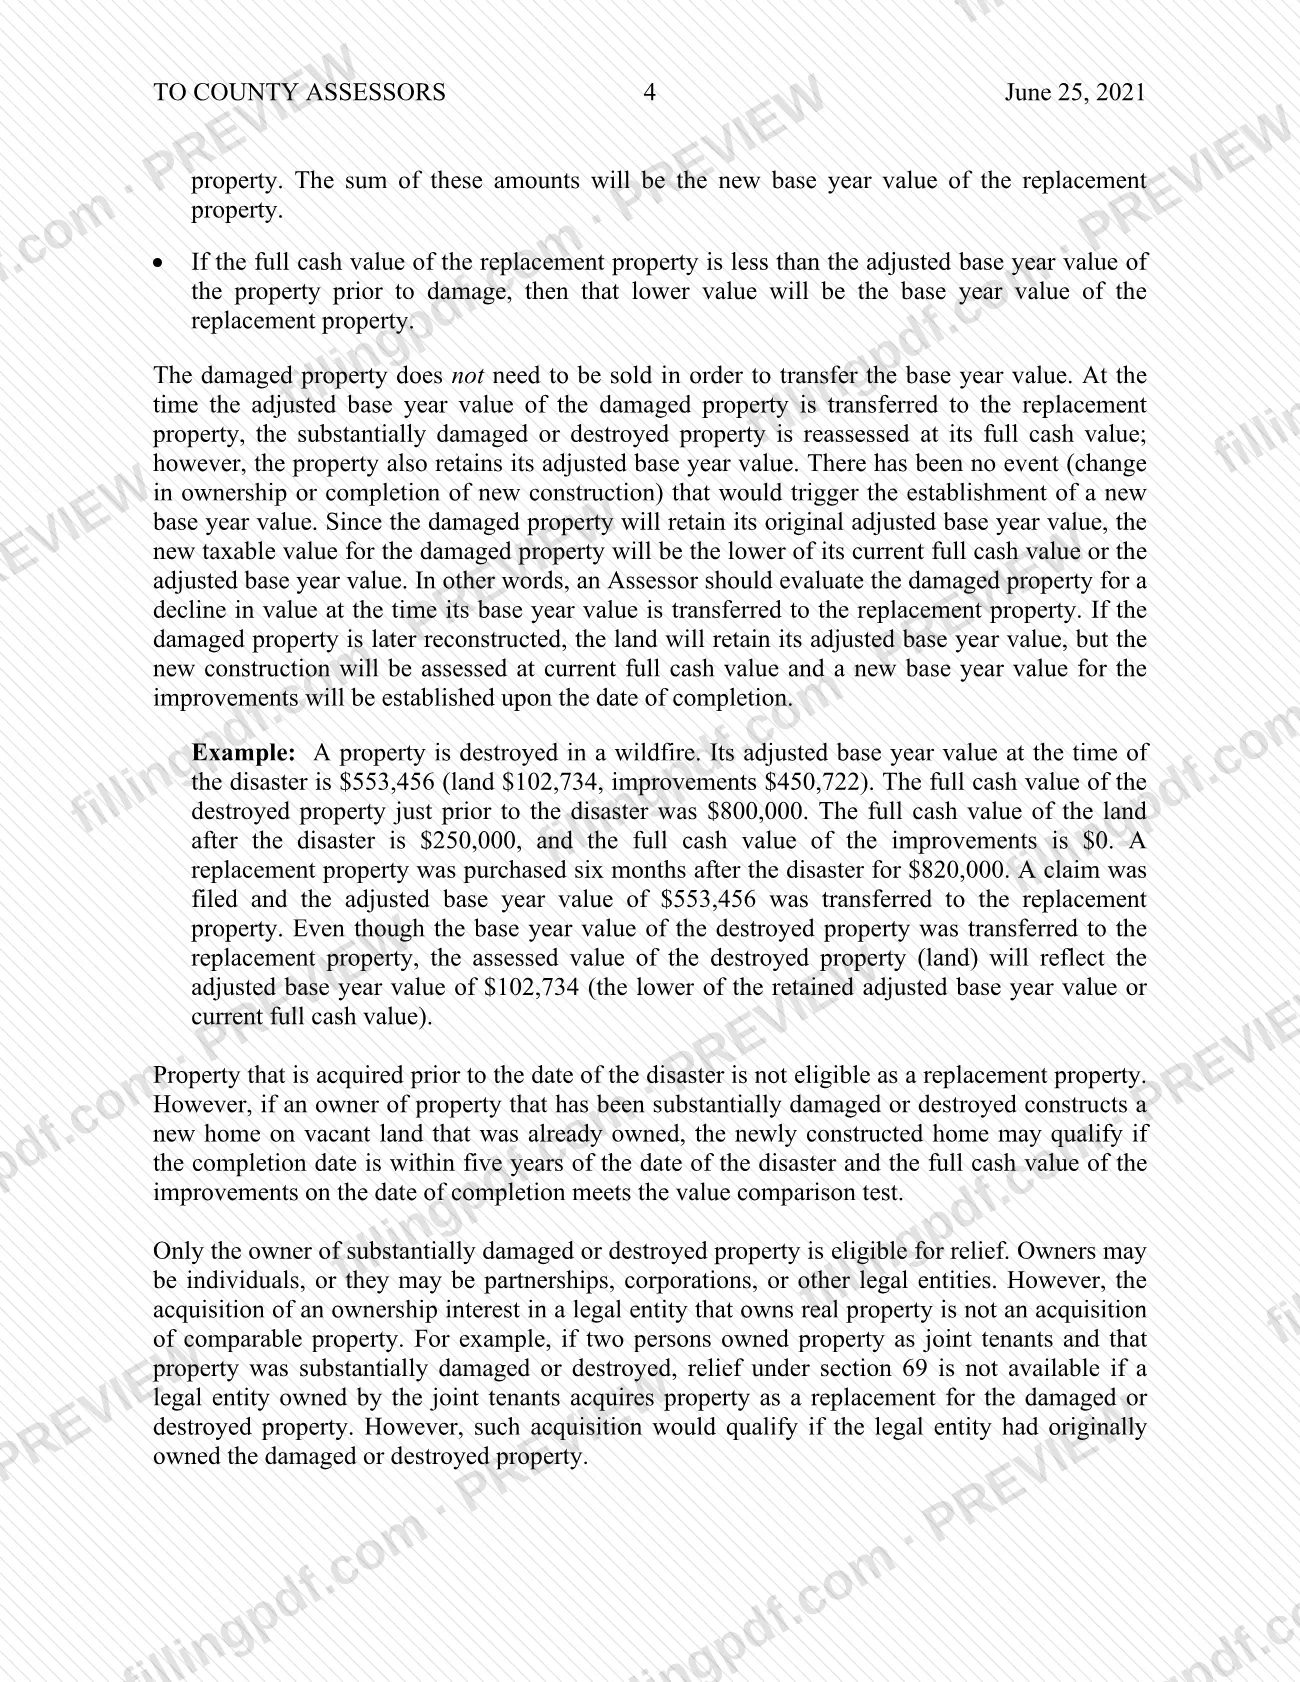
- Buying a replacement property before the date of the disaster; property acquired before that date is not eligible as a replacement.
- Acquiring an ownership interest in a legal entity that owns the replacement instead of acquiring the property itself; the letter says this is not an acquisition of comparable property.
- Buying the replacement home together with someone who did not own the original property; under section 69.3 the original value could not be transferred.
- Expecting an intercounty transfer into a county that has not adopted a section 69.3 ordinance; the letter lists 14 counties as of May 10, 2021.
- Claiming under section 2.1(b) without selling the original primary residence in its damaged state.
- Counting the two-year section 2.1(b) period from the disaster date instead of from the sale of the original residence.
- Missing the three-year claim period under section 69.3 or section 2.1(b); under section 2.1(b) only prospective relief remains.
- Relying on a section 69 transfer and then expecting the section 70 new construction exclusion on the same damaged property.
- Treating a licensed manufactured home as eligible under section 69; it has no base year value.
Frequently asked questions
What is LTA 2021/026?
LTA 2021/026 is Letter To Assessors No. 2021/026, issued June 25, 2021 by the California State Board of Equalization Property Tax Department. It explains the three base year value transfers available after a Governor-proclaimed disaster and the different qualifications of each.
Is LTA 2021/026 a form I fill out and file?
No. It is a letter of guidance addressed to county assessors. Owners request a transfer on a BOE claim form: BOE-65-P for the same county, BOE-65-PT for a principal residence moving to another county, or BOE-19-V under Proposition 19.
Where do I file a claim for Santa Barbara County property tax relief after a disaster?
File with the Assessor of the county where the replacement property is located. For a section 69 transfer the BOE-65-P claim is available from and filed with the Assessor. The Santa Barbara County Assessor's Forms Library has a Disaster Relief section.
What is the difference between section 69, section 69.3 and Proposition 19?
Section 69 covers any property type with a replacement in the same county, within 5 years. Section 69.3 covers a principal residence moving to a county with an ordinance, within 3 years. Proposition 19 requires selling the damaged residence and buying a replacement anywhere in California within 2 years of the sale.
Do I have to sell the damaged property to transfer its base year value?
Not under section 69 or section 69.3. Under Article XIII A, section 2.1(b), the original primary residence must be sold in its damaged state, and the replacement must be bought or built within two years of that sale.
How long do I have to file a base year value transfer claim?
Under section 69.3 and section 2.1(b), within three years of acquiring or completing the replacement property. If the section 2.1(b) period is missed, prospective relief is available from the lien date of the assessment year in which the claim is filed.
Can I transfer my base year value to a home in another county?
Yes, under section 69.3 or section 2.1(b). Section 69.3 requires the replacement county to have adopted an implementing ordinance, and 14 counties were listed as of May 10, 2021. Section 2.1(b) allows a replacement anywhere in California.
Can I fill out LTA 2021/026 on FillingPDF?
FillingPDF lets you open the PDF online and download or print it, but the letter has no claim to complete. FillingPDF is independent, is not affiliated with the BOE or the Santa Barbara County Assessor, and does not file claims.
Ready to fill out LTA 2021/026?
Fill out LTA 2021/026 now