
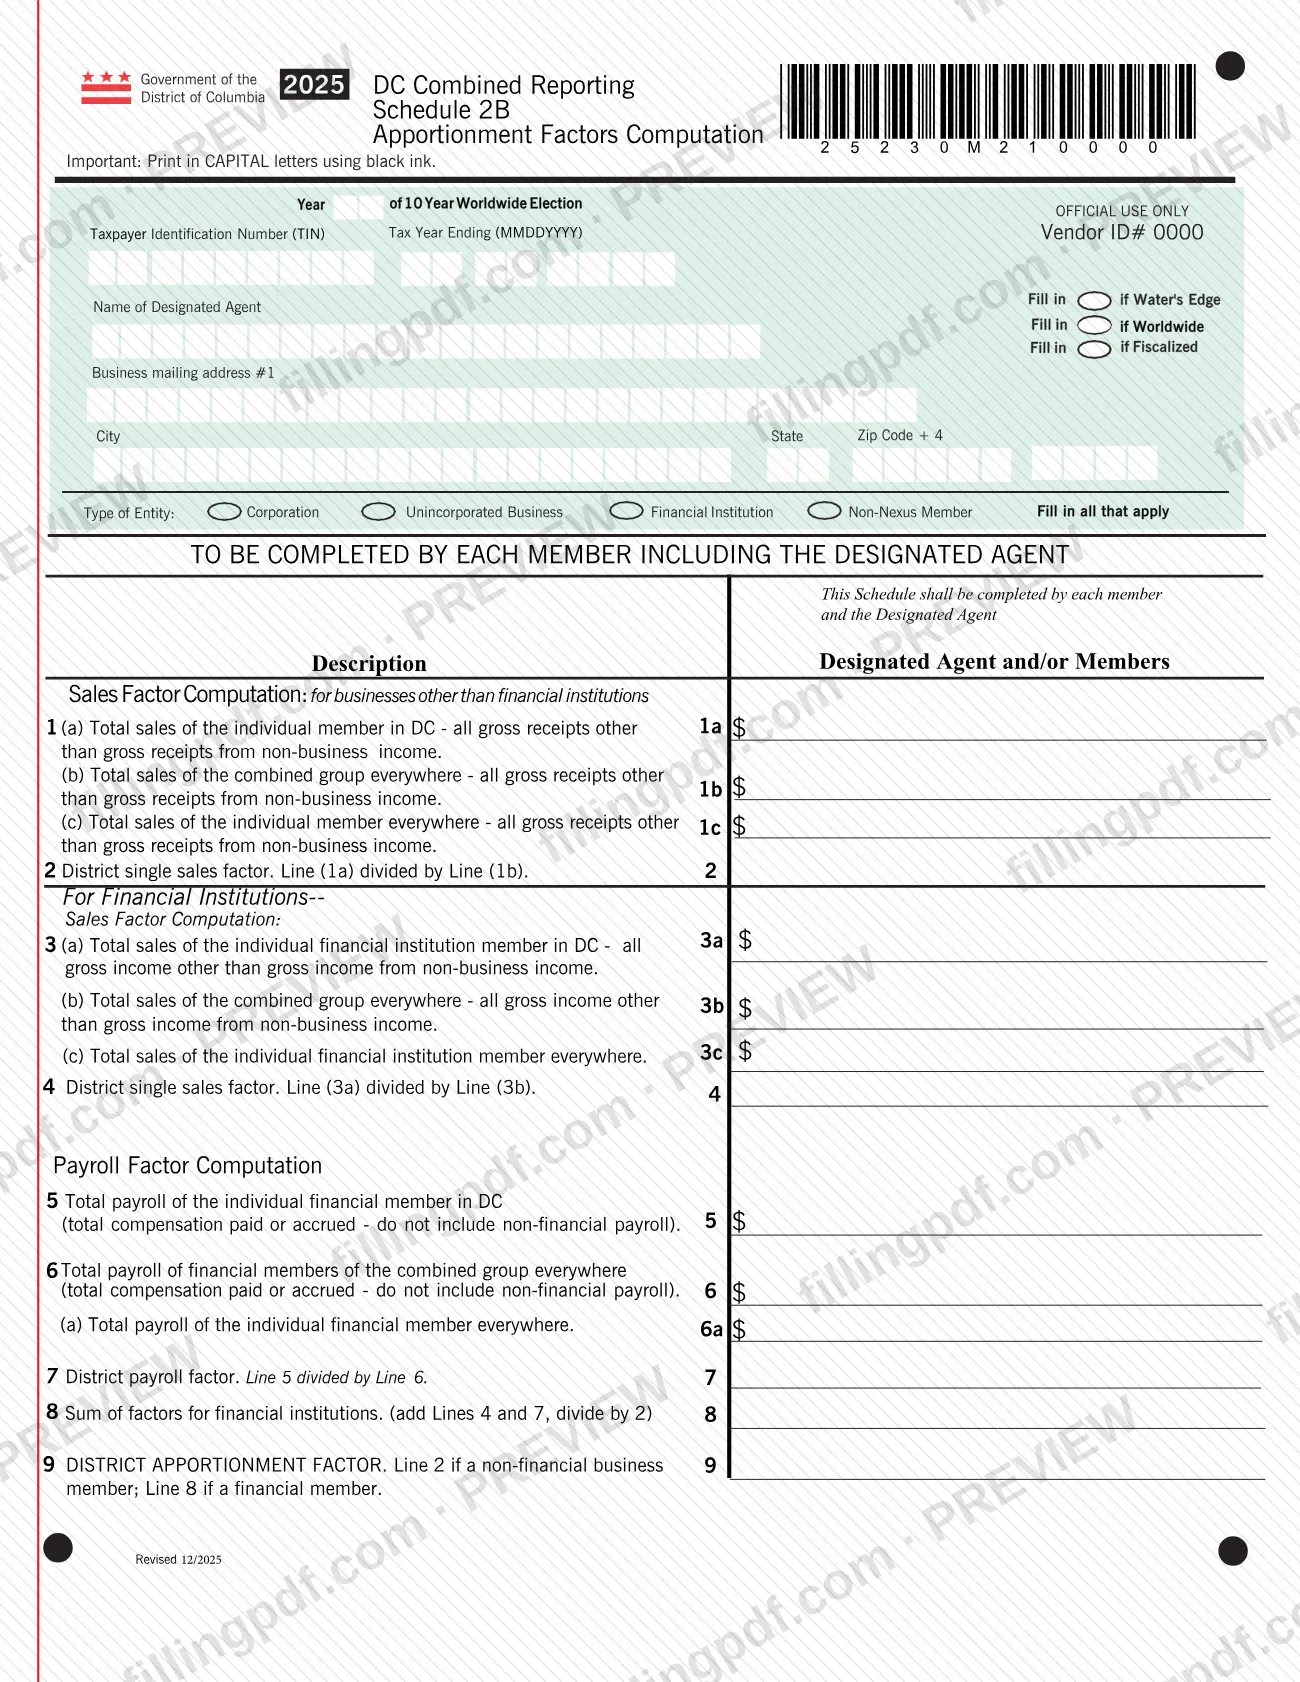
The 2025 Combined Reporting Instructions, published by the District of Columbia Office of Tax and Revenue (OTR) as "2025 Instructions and Schedules for Completing the DC Combined Report for Franchise Tax Returns," explain how a unitary group of businesses reports DC franchise tax on one combined report. The designated agent of the group files it with Form D-20 or Form D-30 and completes the combined reporting schedules. On this page you can fill out the form online on FillingPDF and download or print the completed PDF; the booklet and the fill-in schedules are published by OTR at otr.cfo.dc.gov.
Last updated
What is 2025 Combined Reporting Instructions – Washington, DC?
The 2025 Instructions and Schedules for Completing the DC Combined Report for Franchise Tax Returns is the District of Columbia Office of Tax and Revenue (OTR) booklet that explains combined reporting for DC franchise tax and supplies the schedules a combined group files for tax year 2025.
DC no longer permits consolidated filing for tax years beginning after December 31, 2010. A corporation or unincorporated business entity subject to DC tax and engaged in a unitary business with other corporations or entities must file a combined report under D.C. Code § 47-1805.02a. A combined report is not the same as a federal consolidated return, and each taxpayer member stays responsible for the tax on its own income apportioned or allocated to the District.
The booklet covers who is included in or excluded from a combined group, the designated agent, water's-edge versus worldwide reporting, taxable year, net operating losses, credits, apportionment, extensions, and the Sports Facilities Fee. It then gives line-by-line instructions for these forms and schedules:
- Worldwide Combined Reporting Election Form
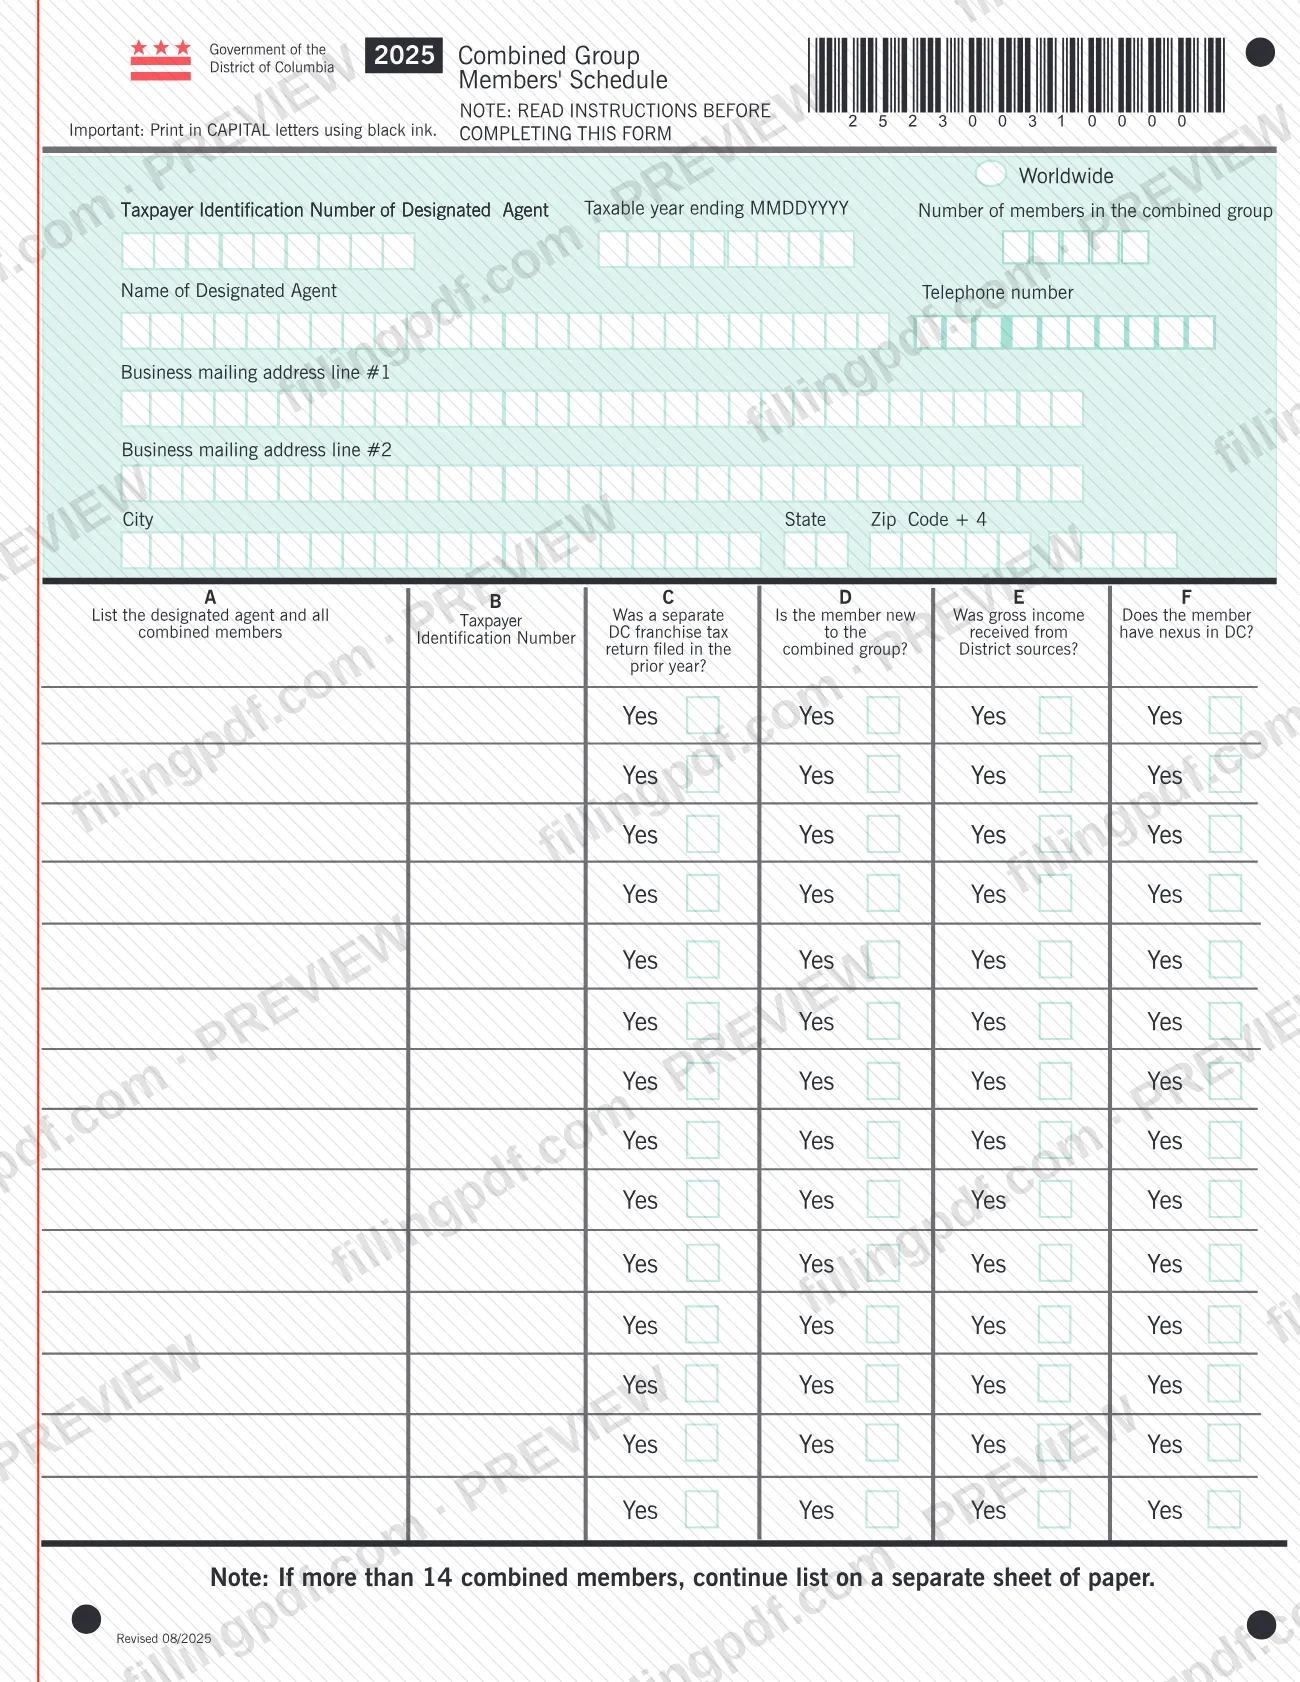
- Combined Group Members' Schedule
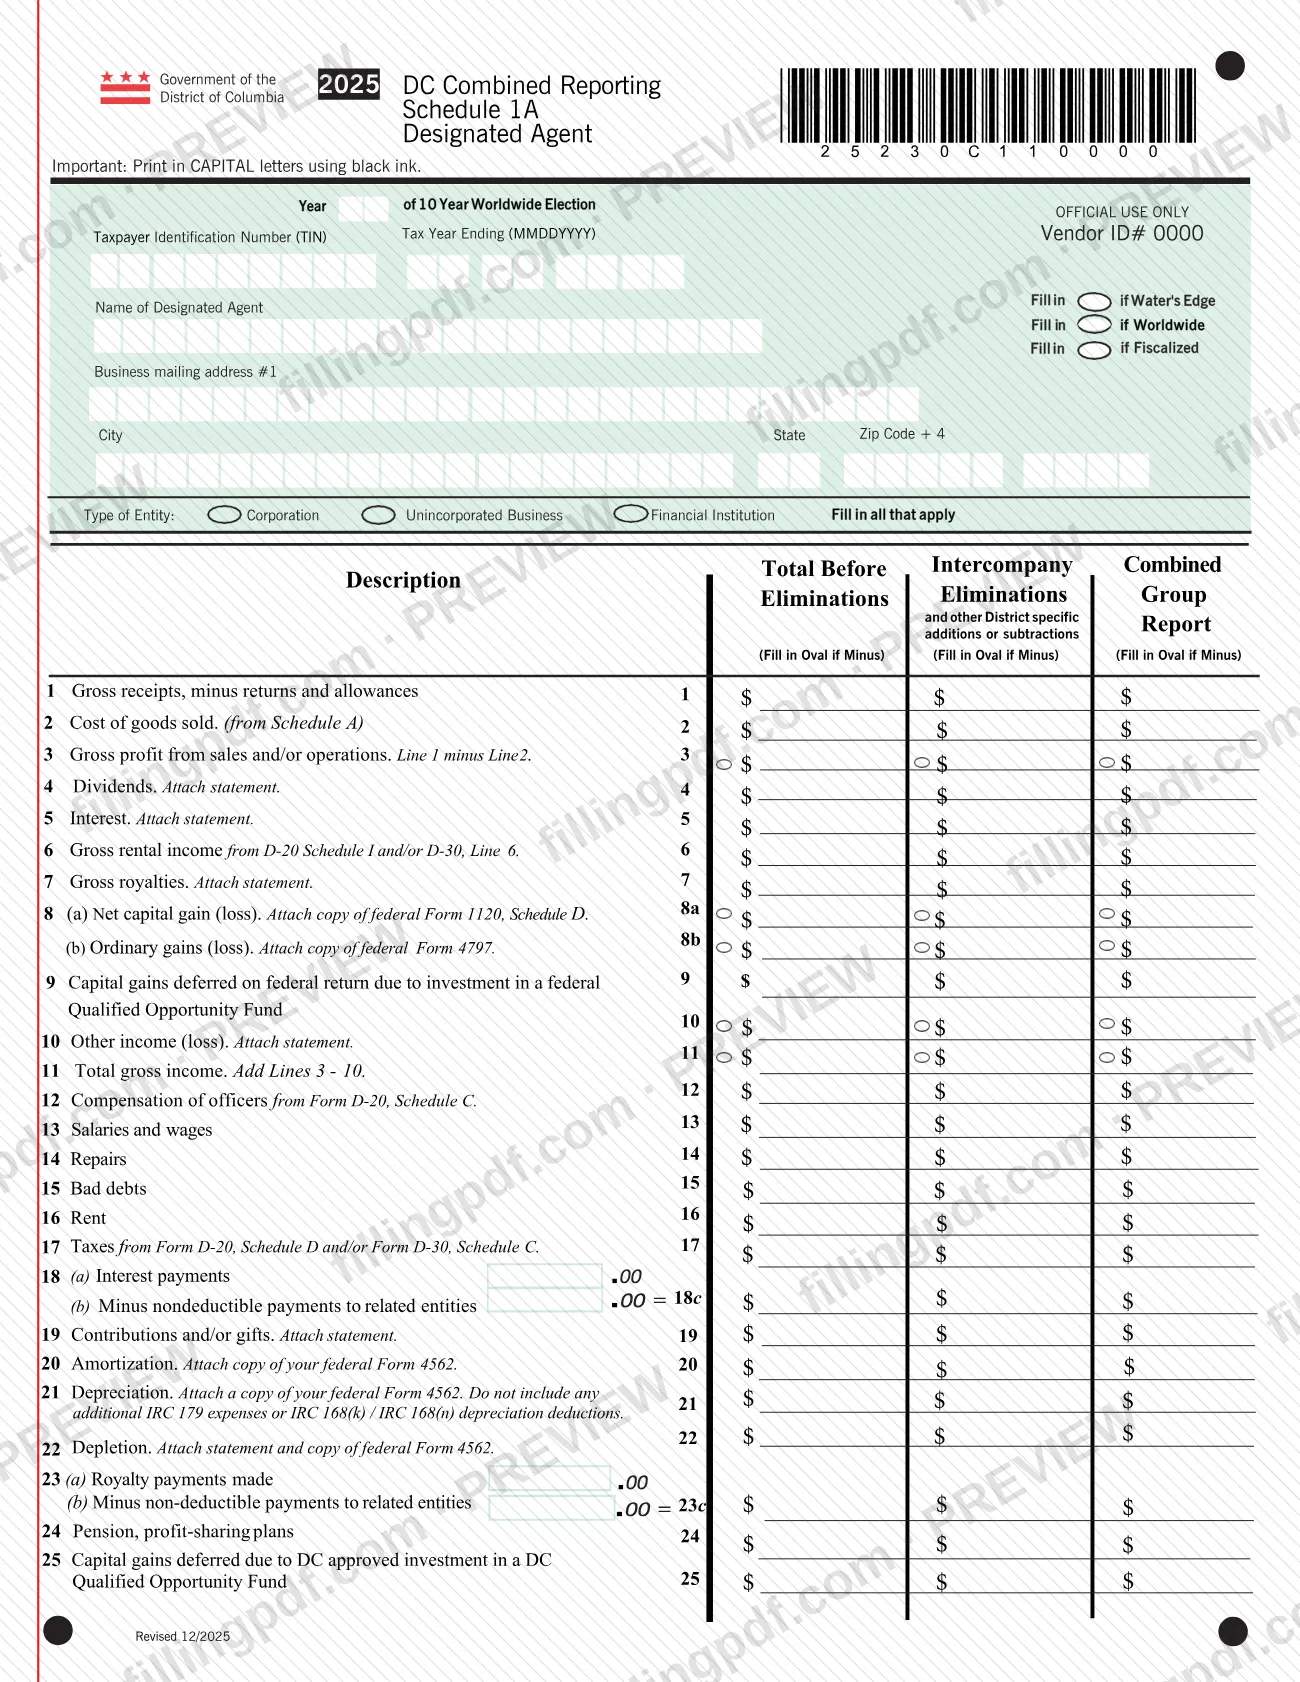
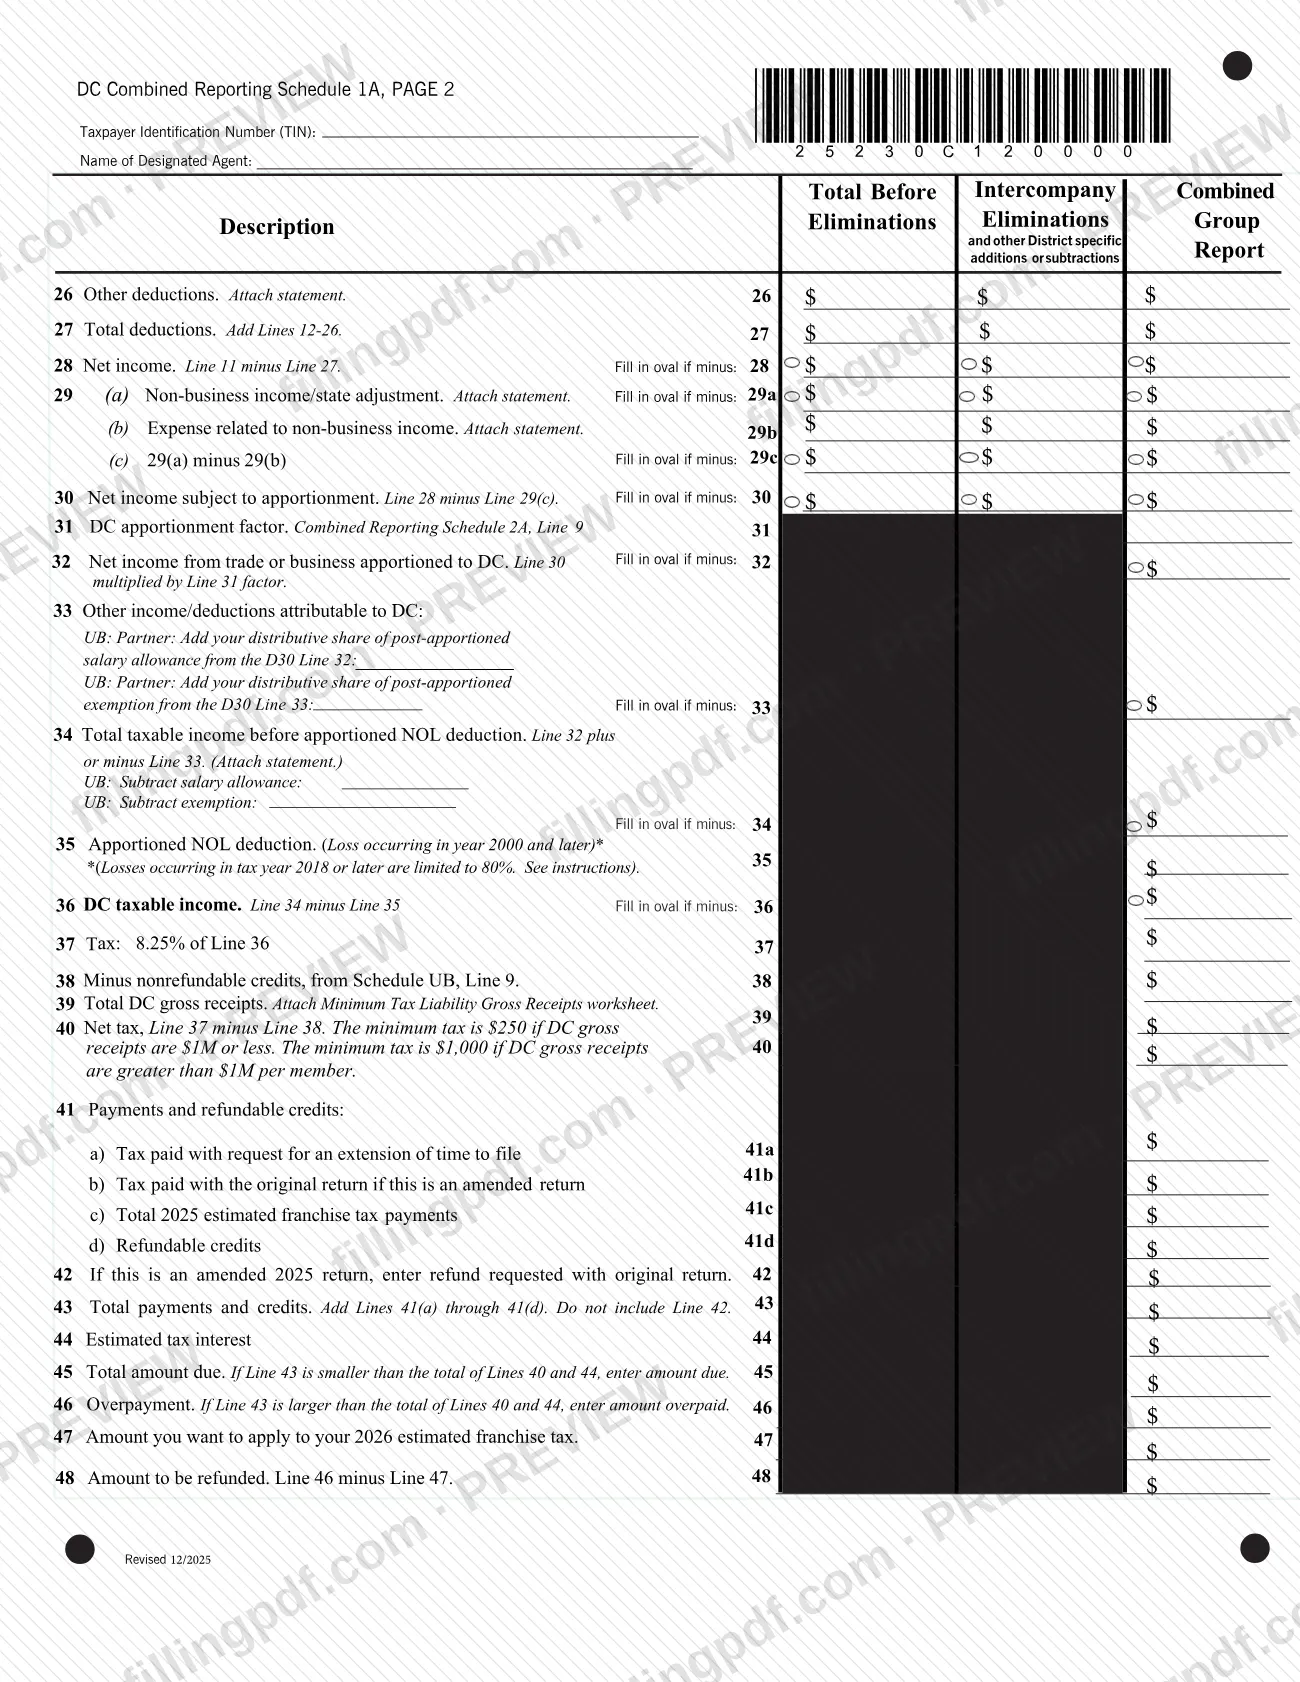
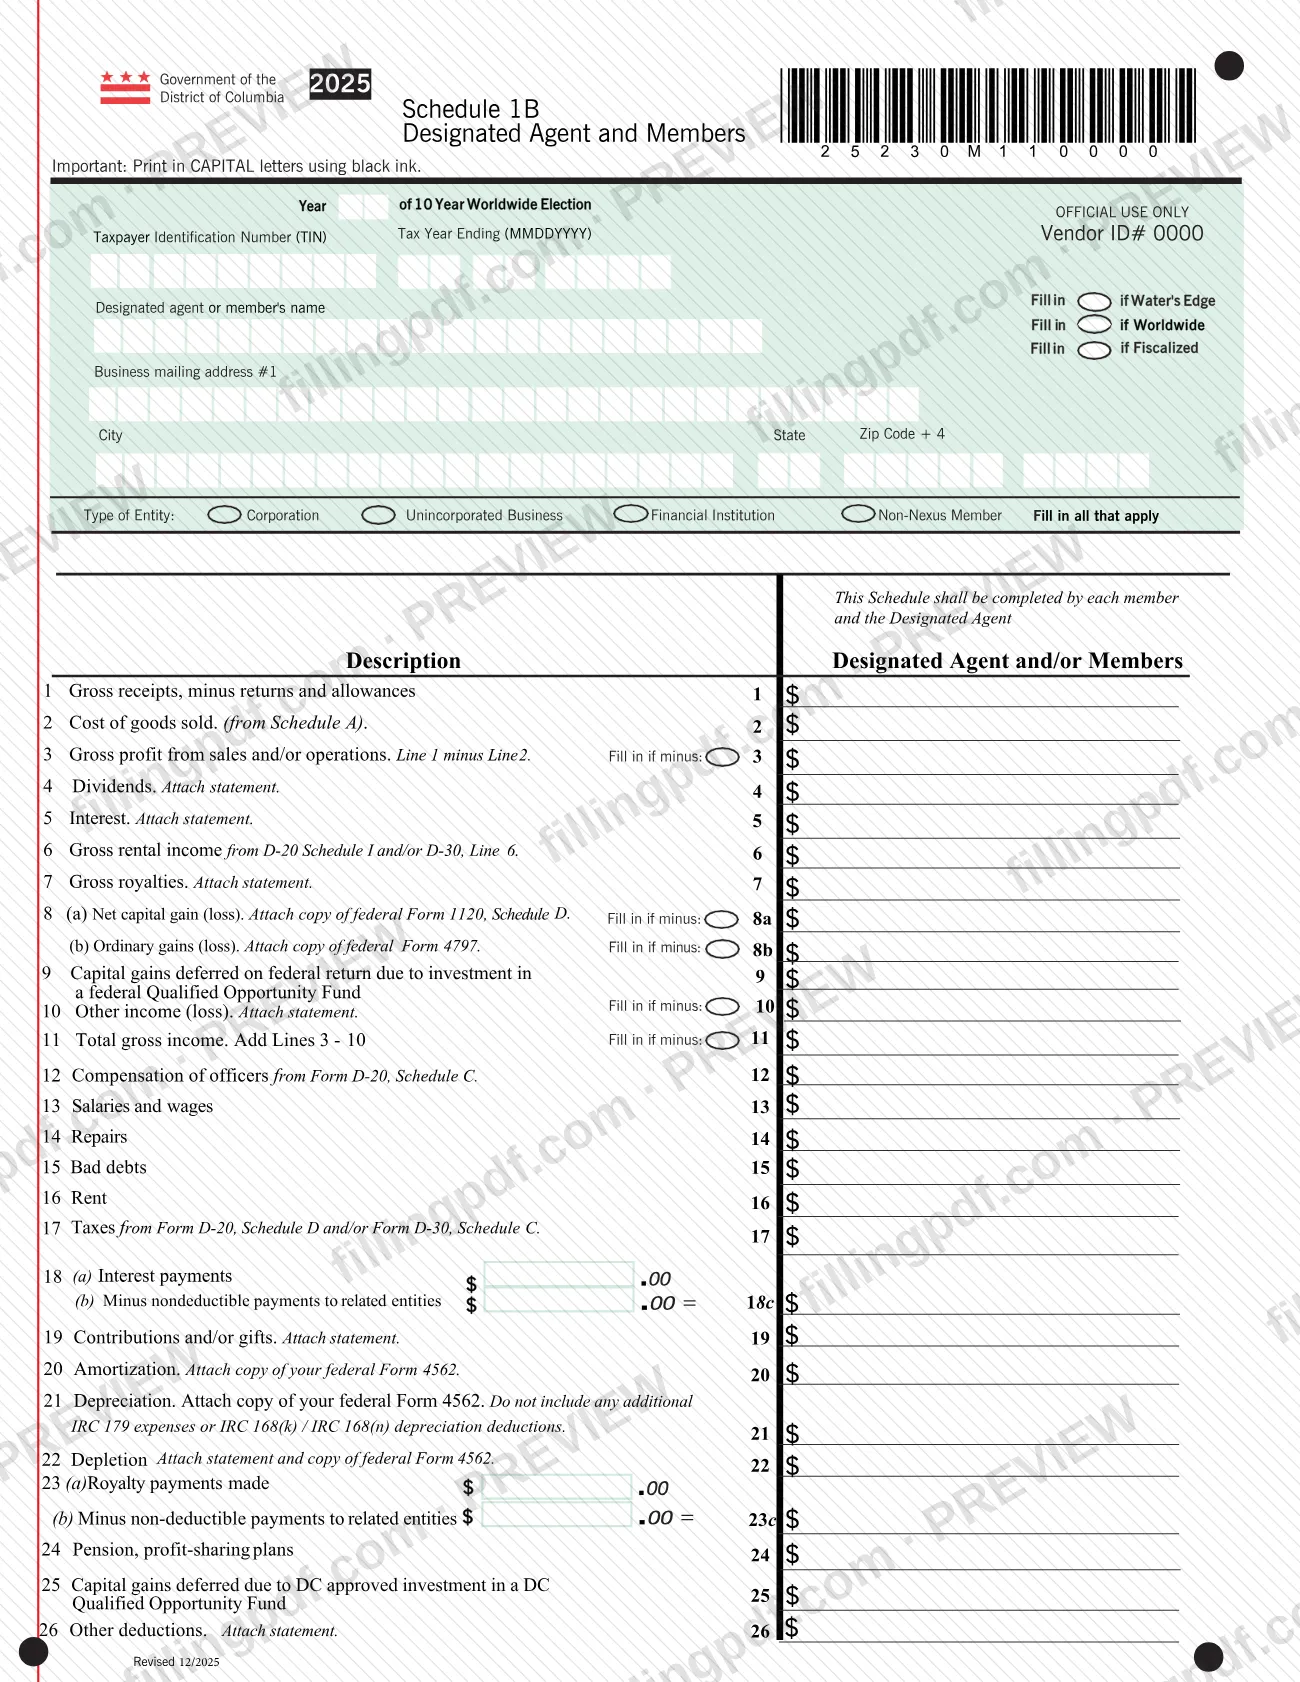
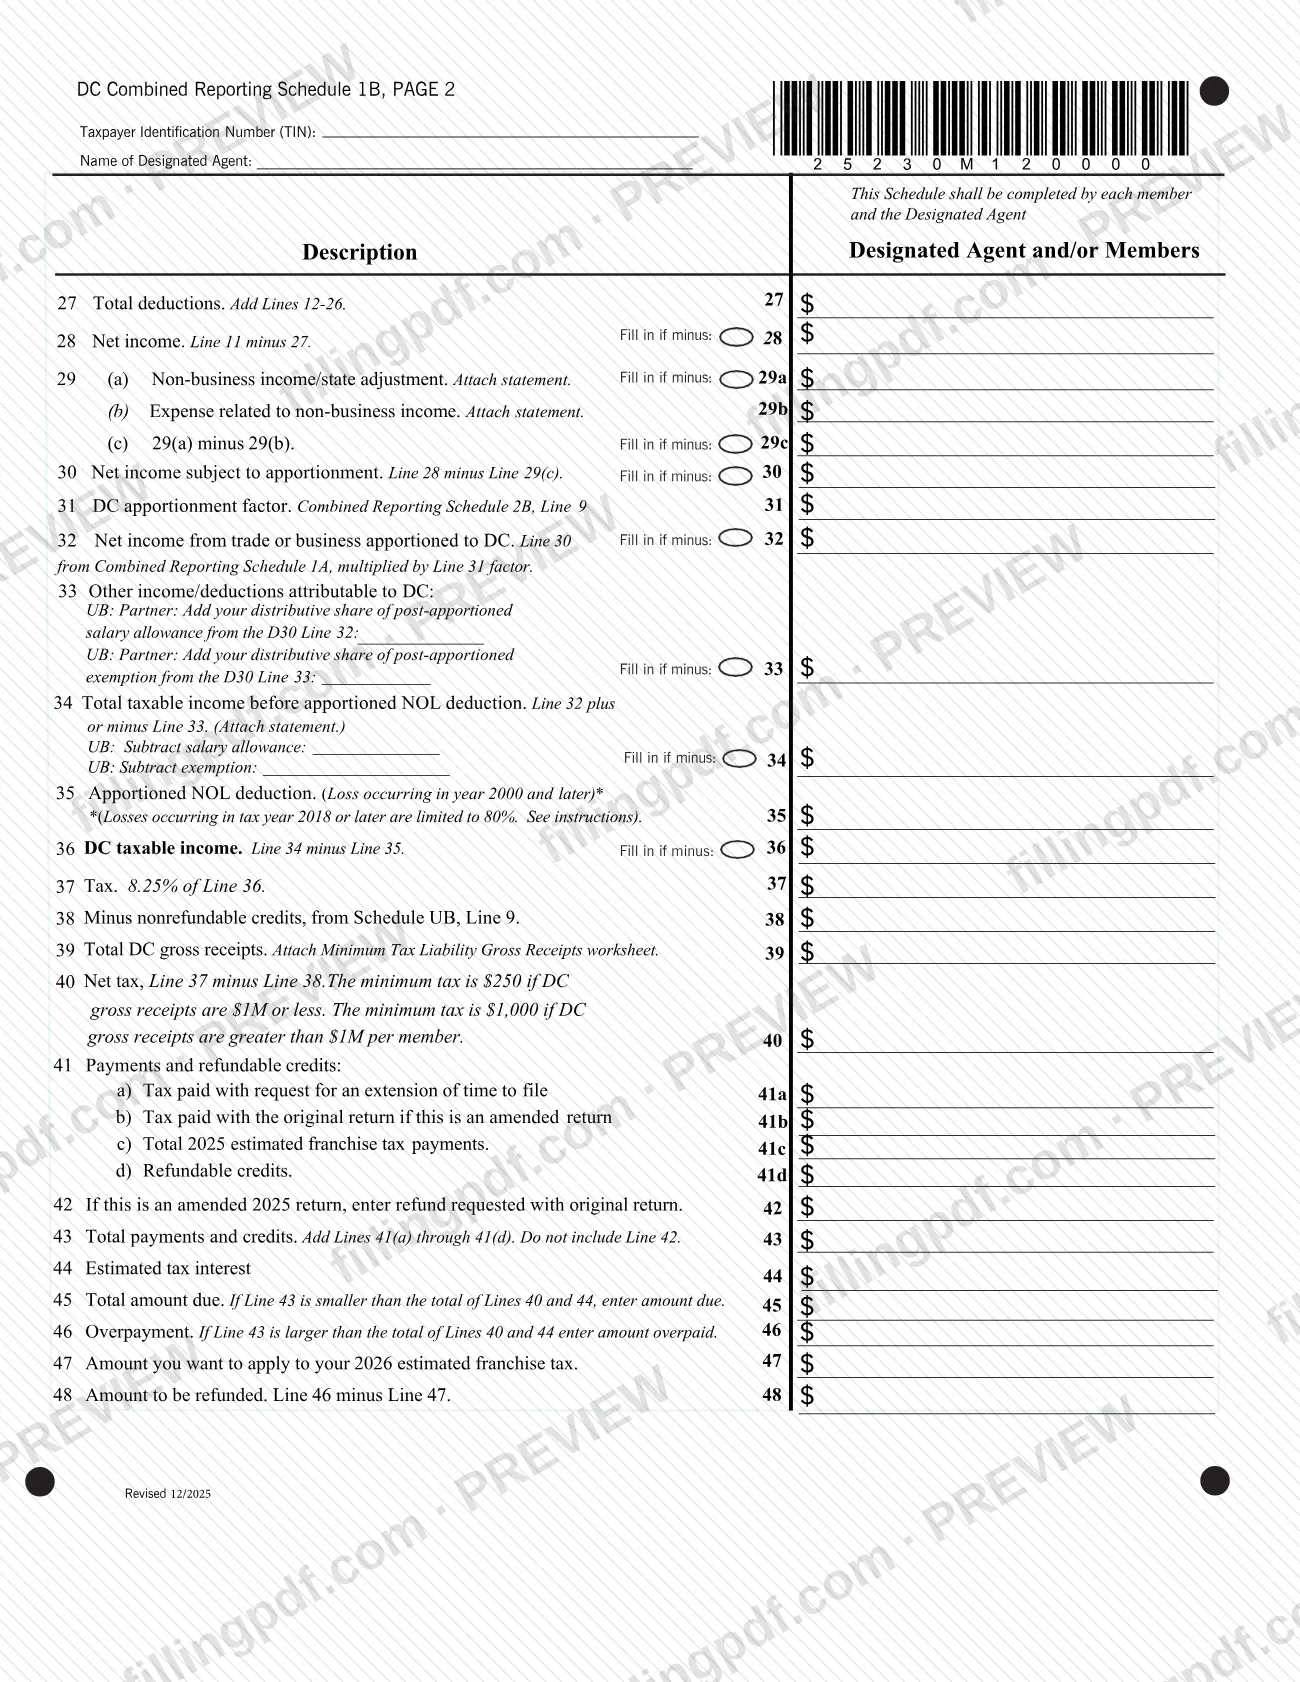
- DC Combined Reporting Schedule 1A (group totals) and Schedule 1B (each member)
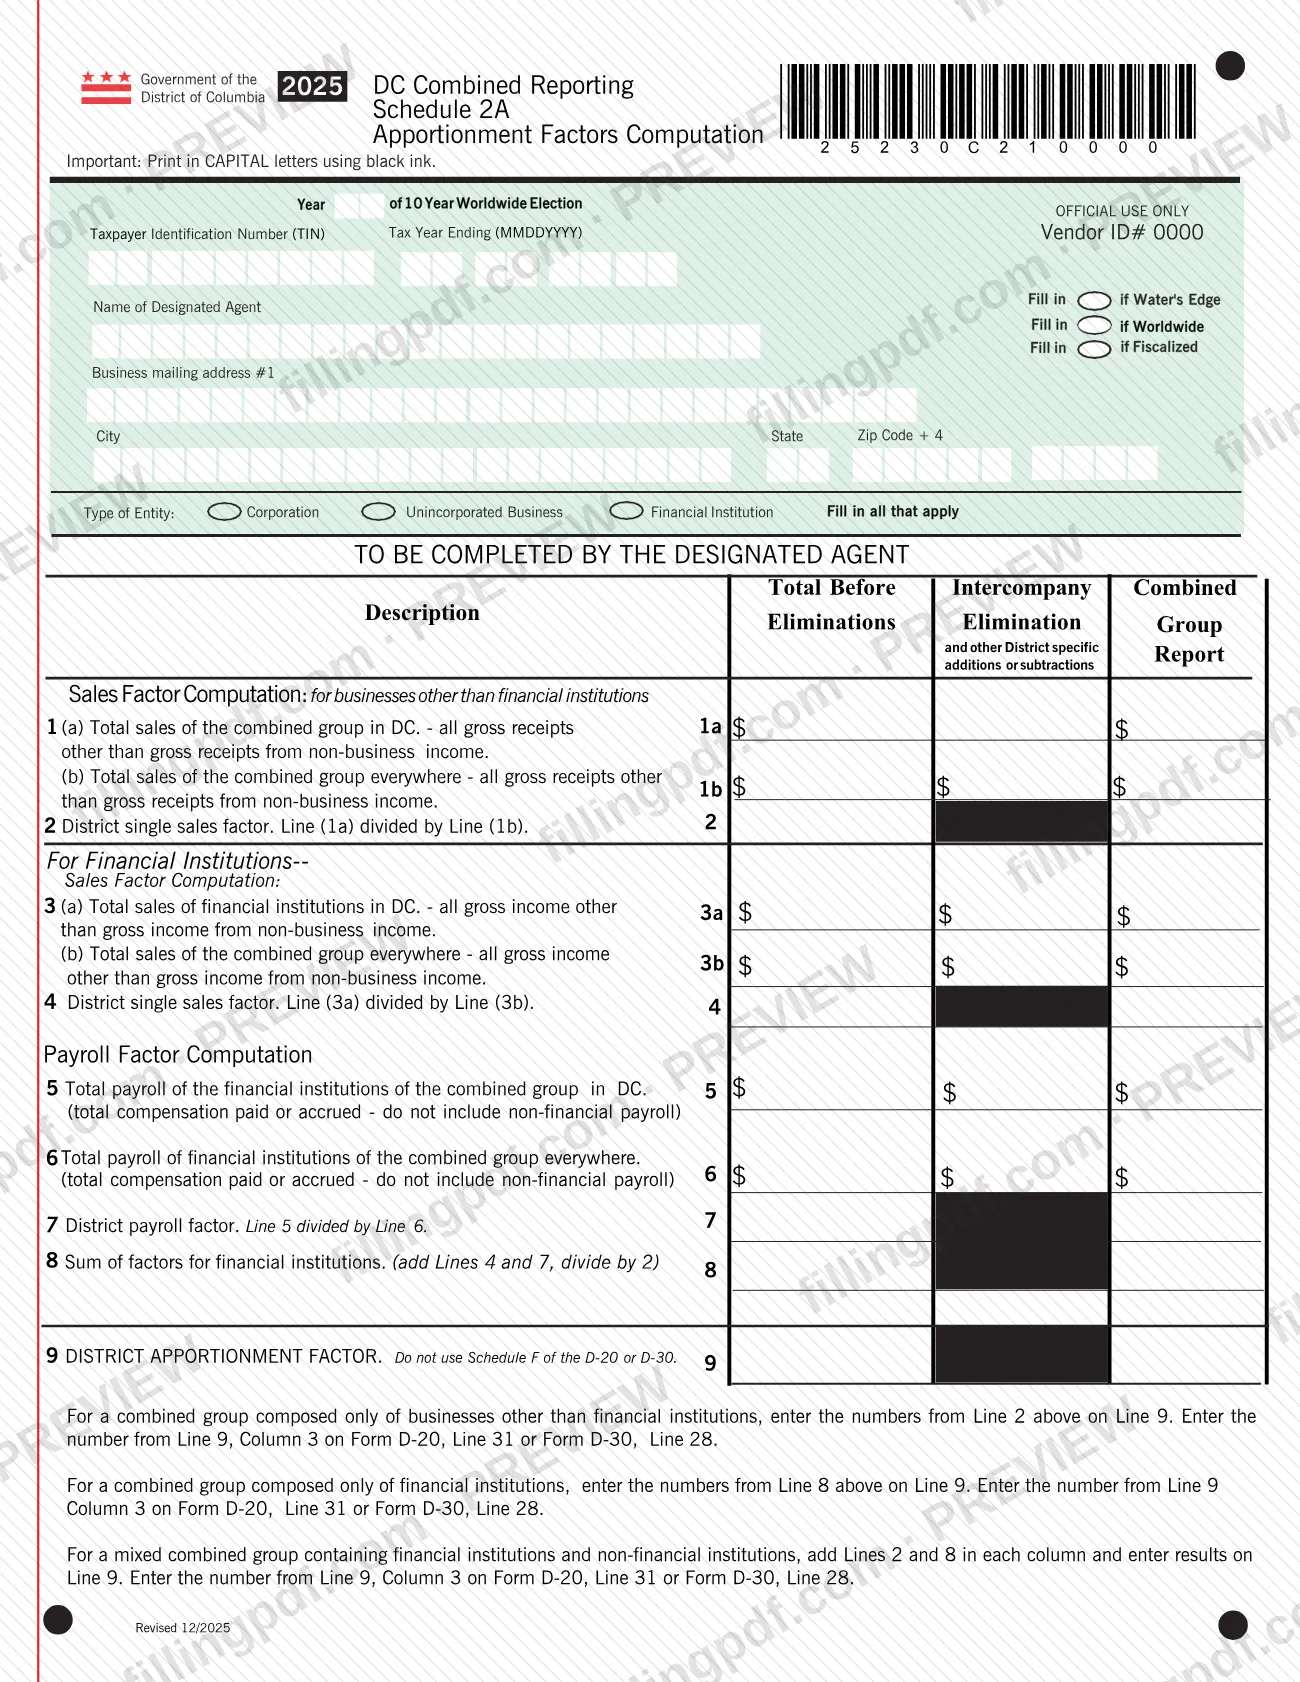
- DC Combined Reporting Schedule 2A (group apportionment factor) and Schedule 2B (each member)
The report travels with the designated agent's Form D-20 (Corporate Franchise Return) or Form D-30 (Unincorporated Business Franchise Tax Return); line item instructions come from those booklets. It is a franchise tax document, not a DC property tax form.
Who needs to file 2025 Combined Reporting Instructions – Washington, DC?
The main filer is the designated agent of a combined group: the one taxpayer member that files a single return for all members in place of their own returns. A corporation or unincorporated business entity subject to DC tax that is engaged in a unitary business with one or more related corporations or entities is required to file a combined report.
- Included persons: all persons of the kind subject to tax under chapter 18 of title 47 of the D.C. Official Code, or that would be if doing business in the District, even without nexus. Examples named include unincorporated businesses, financial institutions, utility and transportation companies, S corporations, REITs and RICs.
- Excluded persons: unless otherwise required under D.C. Official Code § 47-1805.02a, insurance companies subject to premium tax, exempt organizations (including those with unrelated business income taxed under I.R.C. § 511), Qualified High Technology Companies, and persons whose average property, payroll and sales factors outside the U.S. are 80% or more.
- Each member: prepares its own Schedule 1B and Schedule 2B for the designated agent.
A non-nexus member cannot be the designated agent. Entities that filed separately last year file a final zero return along with the combined report, except the designated agent.
When to file 2025 Combined Reporting Instructions – Washington, DC
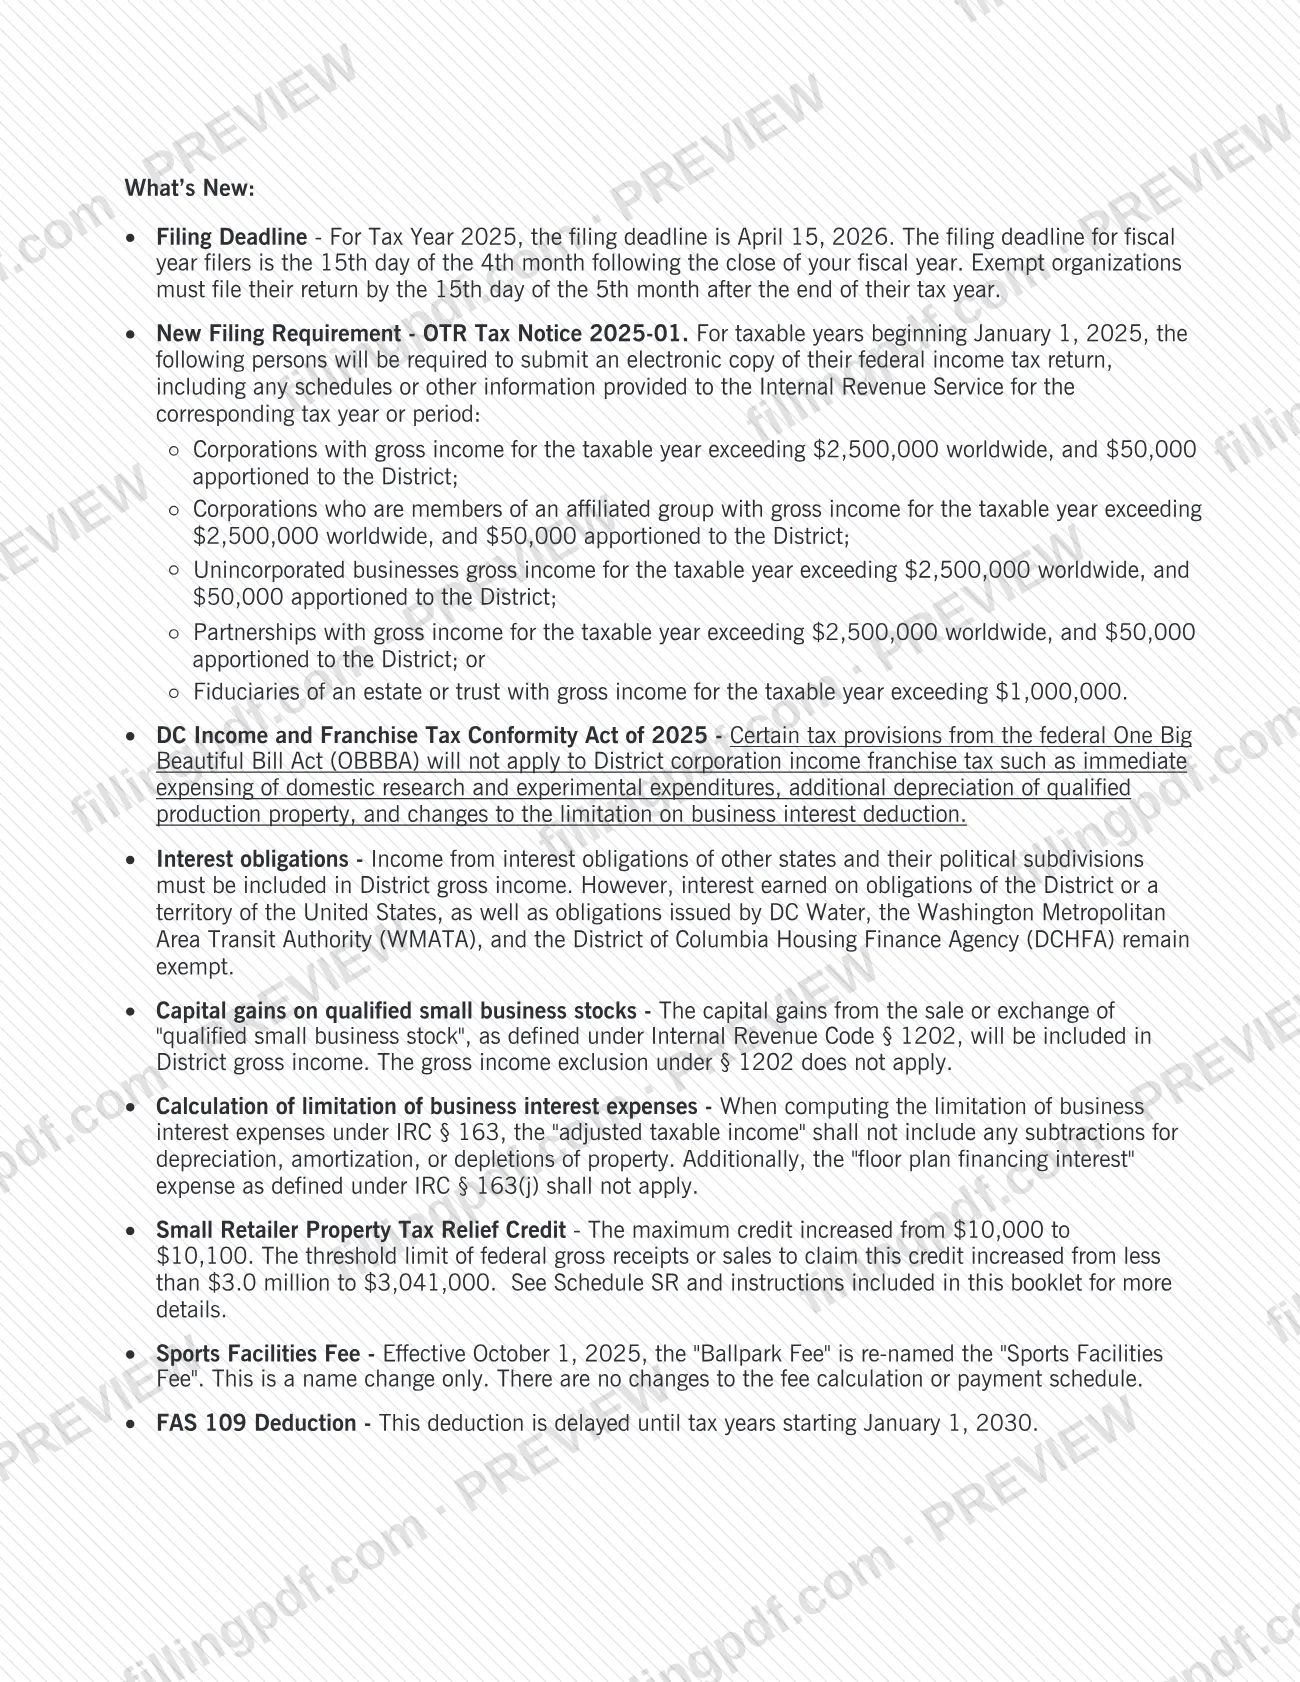
For tax year 2025, the filing deadline is April 15, 2026. Fiscal year filers file by the 15th day of the 4th month following the close of the fiscal year. Exempt organizations file by the 15th day of the 5th month after the end of their tax year.
A group may request an extension to file for seven months, no later than the due date of the return, and never for more than one year. An extension to file is not an extension of time to pay: the tax must be paid when the extension request is submitted. Do not use the federal extension form; the designated agent files one request for the whole group.
The Combined Group Members' Schedule must be filed each year a DC Combined Report is filed. A worldwide election is effective only if made on a timely filed original return.
Documents you need
- Form D-20 or Form D-30 filed by the designated agent: D-20 if the agent is a corporation or financial institution, D-30 if it is an unincorporated business.
- Combined Group Members' Schedule, Schedule 1A and Schedule 2A, filed once by the designated agent each year a combined report is filed.
- A Schedule 1B and a Schedule 2B for each member, including the designated agent.
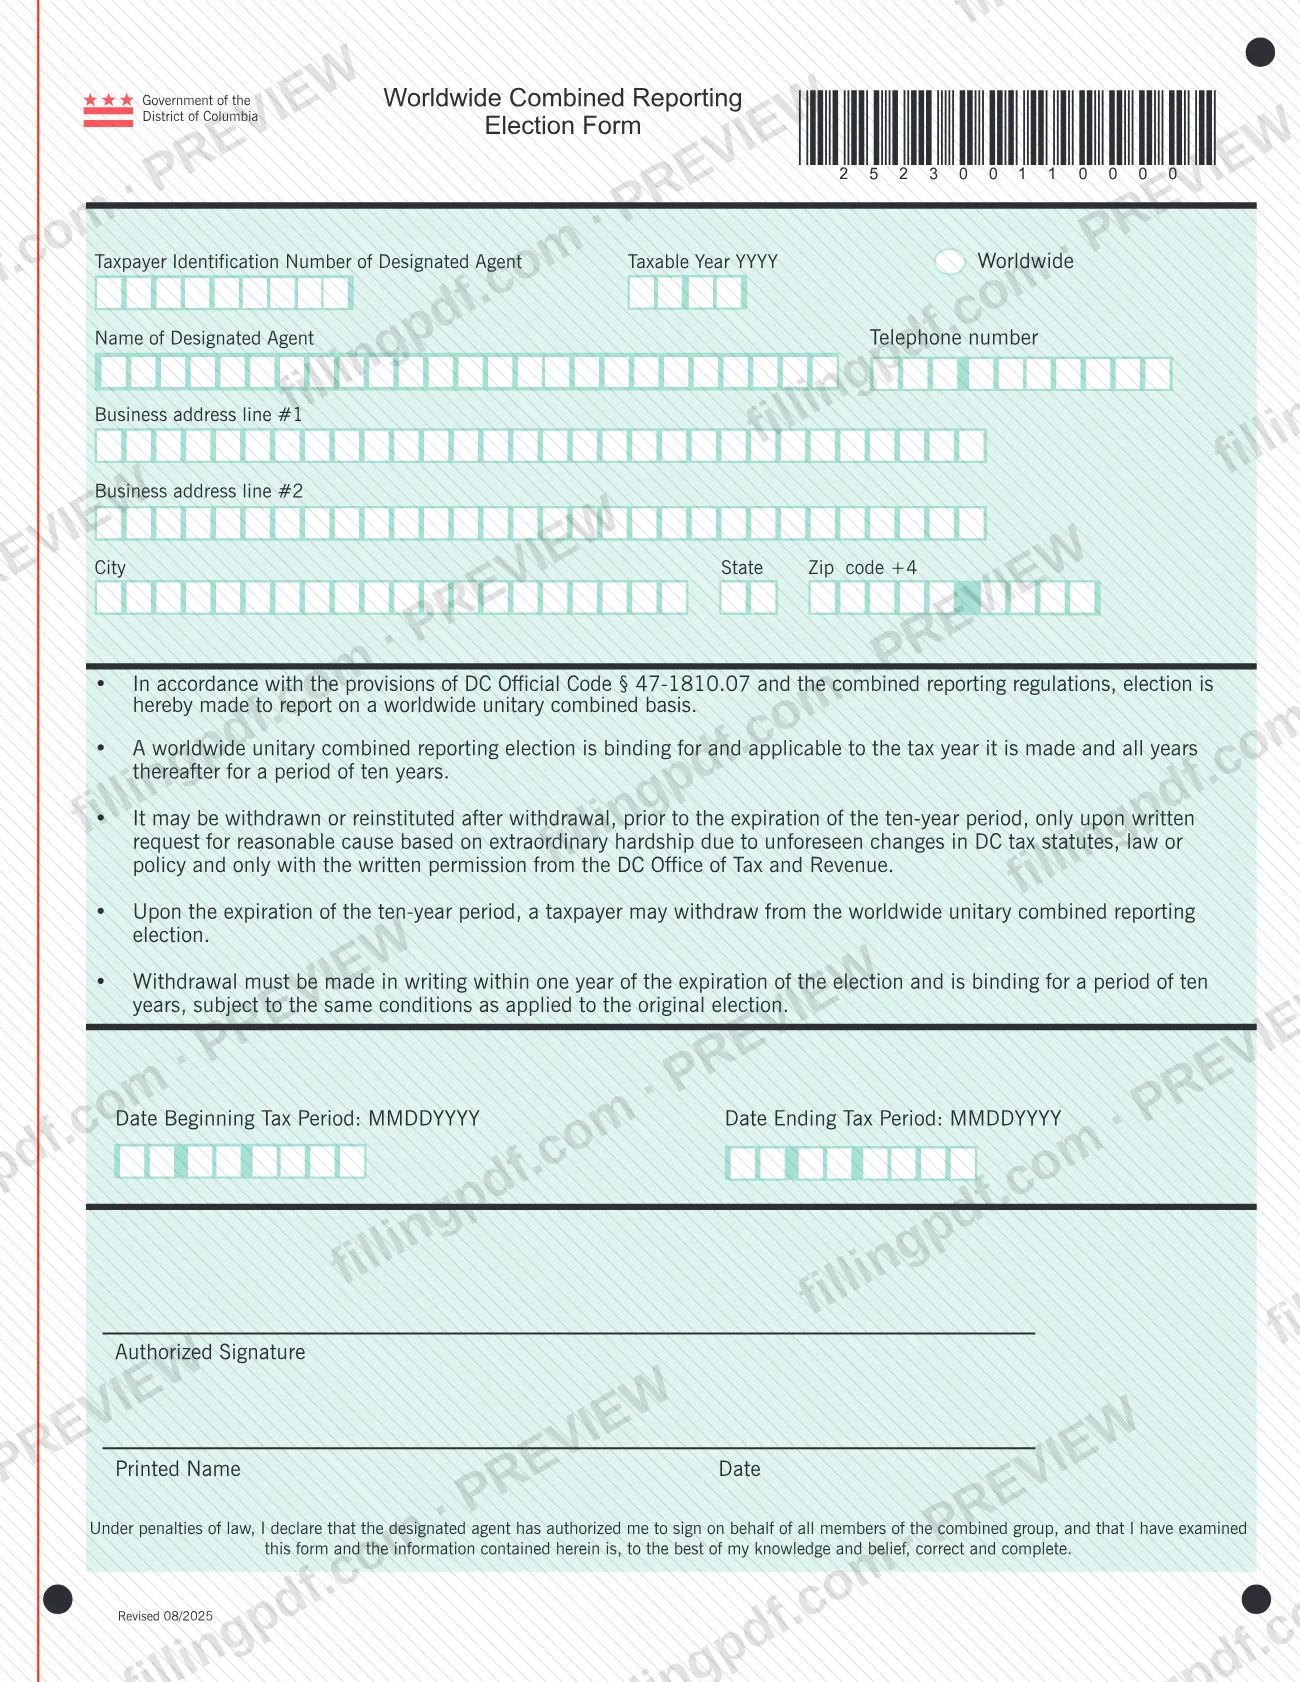
- Worldwide Combined Reporting Election Form, only if the group elects worldwide unitary combined reporting.
- Federal Schedules J, M, M-3 and Federal UTP, and Forms 851, 5471, 5472, 8833, 8868, 8886 and 8975 (including Schedule A), each if applicable.
- Statement of intercompany eliminations and other additions or subtractions for each member's Schedules 1B and 2B, since those schedules have no column for them.
- Statement showing the write-off or depreciation amount, if additional federal bonus depreciation or additional IRC § 179 expenses were claimed federally.
- Schedule SR, one for each member claiming the Small Retailer Property Tax Relief Credit, only if a member is eligible.
- DC QOF Approval letter from DMPED and IRS Forms 8996 and 8997, only for taxpayers seeking DC Opportunity Zone tax benefits.
- Separate final zero return for each entity that filed separately last year, except the designated agent.
How to fill out 2025 Combined Reporting Instructions – Washington, DC
Confirm the designated agent and form
Identify the designated agent, then use Form D-20 if it is a corporation or financial institution, or Form D-30 if it is an unincorporated business. On page 1 enter the agent's name and TIN and shade the 'fill in if Combined Report' oval.
Complete the Combined Group Members' Schedule
Enter the number of members. In Column A list the designated agent and all members, in Column B each TIN, and in Columns C to F answer Yes for each member as asked. Continue on a separate sheet if there are more than 14 members.
Prepare Schedule 1B for each member
Enter the member's name, TIN, address, tax year ending and type of entity, plus the designated agent's TIN. Complete Lines 1 through 48, using the D-20 or D-30 line item instructions.
Prepare Schedule 2B for each member
Enter Lines 1(a) to 1(c) for a non-financial business, or Lines 3(a) to 3(c) and 5 to 6(a) for a financial institution. Line 9 is Line 2 for a non-financial member or Line 8 for a financial member.
Write the intercompany elimination statement
Each member prepares a statement showing amounts and descriptions of intercompany eliminations and other additions or subtractions, because Schedules 1B and 2B have no column for them.
Complete Schedule 1A for the group
Enter the designated agent's TIN, name, address and tax year ending. Fill in the oval for 'Water's Edge' or 'Worldwide' and, if applicable, 'Fiscalized'. Complete Lines 1 through 48 from the summation of all members' returns.
Compute the group factor on Schedule 2A
Complete Lines 1 to 8 as they apply to the group, then Line 9. Enter the Line 9 result on Form D-20, Line 31 or Form D-30, Line 28.
Add the worldwide election form if needed
If a worldwide election is made, the designated agent files the Worldwide Combined Reporting Election Form with the taxable year, tax period dates, and an authorized signature. Skip this if the group reports on a water's-edge basis.
Add Schedule SR for eligible members
If a member claims the Small Retailer Property Tax Relief Credit, file a separate Schedule SR in that member's name and TIN, listing the designated agent's TIN.
Review, attach and download the PDF
Check that the oval choices match across Schedules 1A, 1B, 2A and 2B, then attach the federal forms and statements the instructions require. Download or print the completed PDF from FillingPDF and submit it through the OTR channels described under How to submit.
How to submit 2025 Combined Reporting Instructions – Washington, DC
The booklet points to these channels and contacts; it prints no separate mailing address for the combined report.
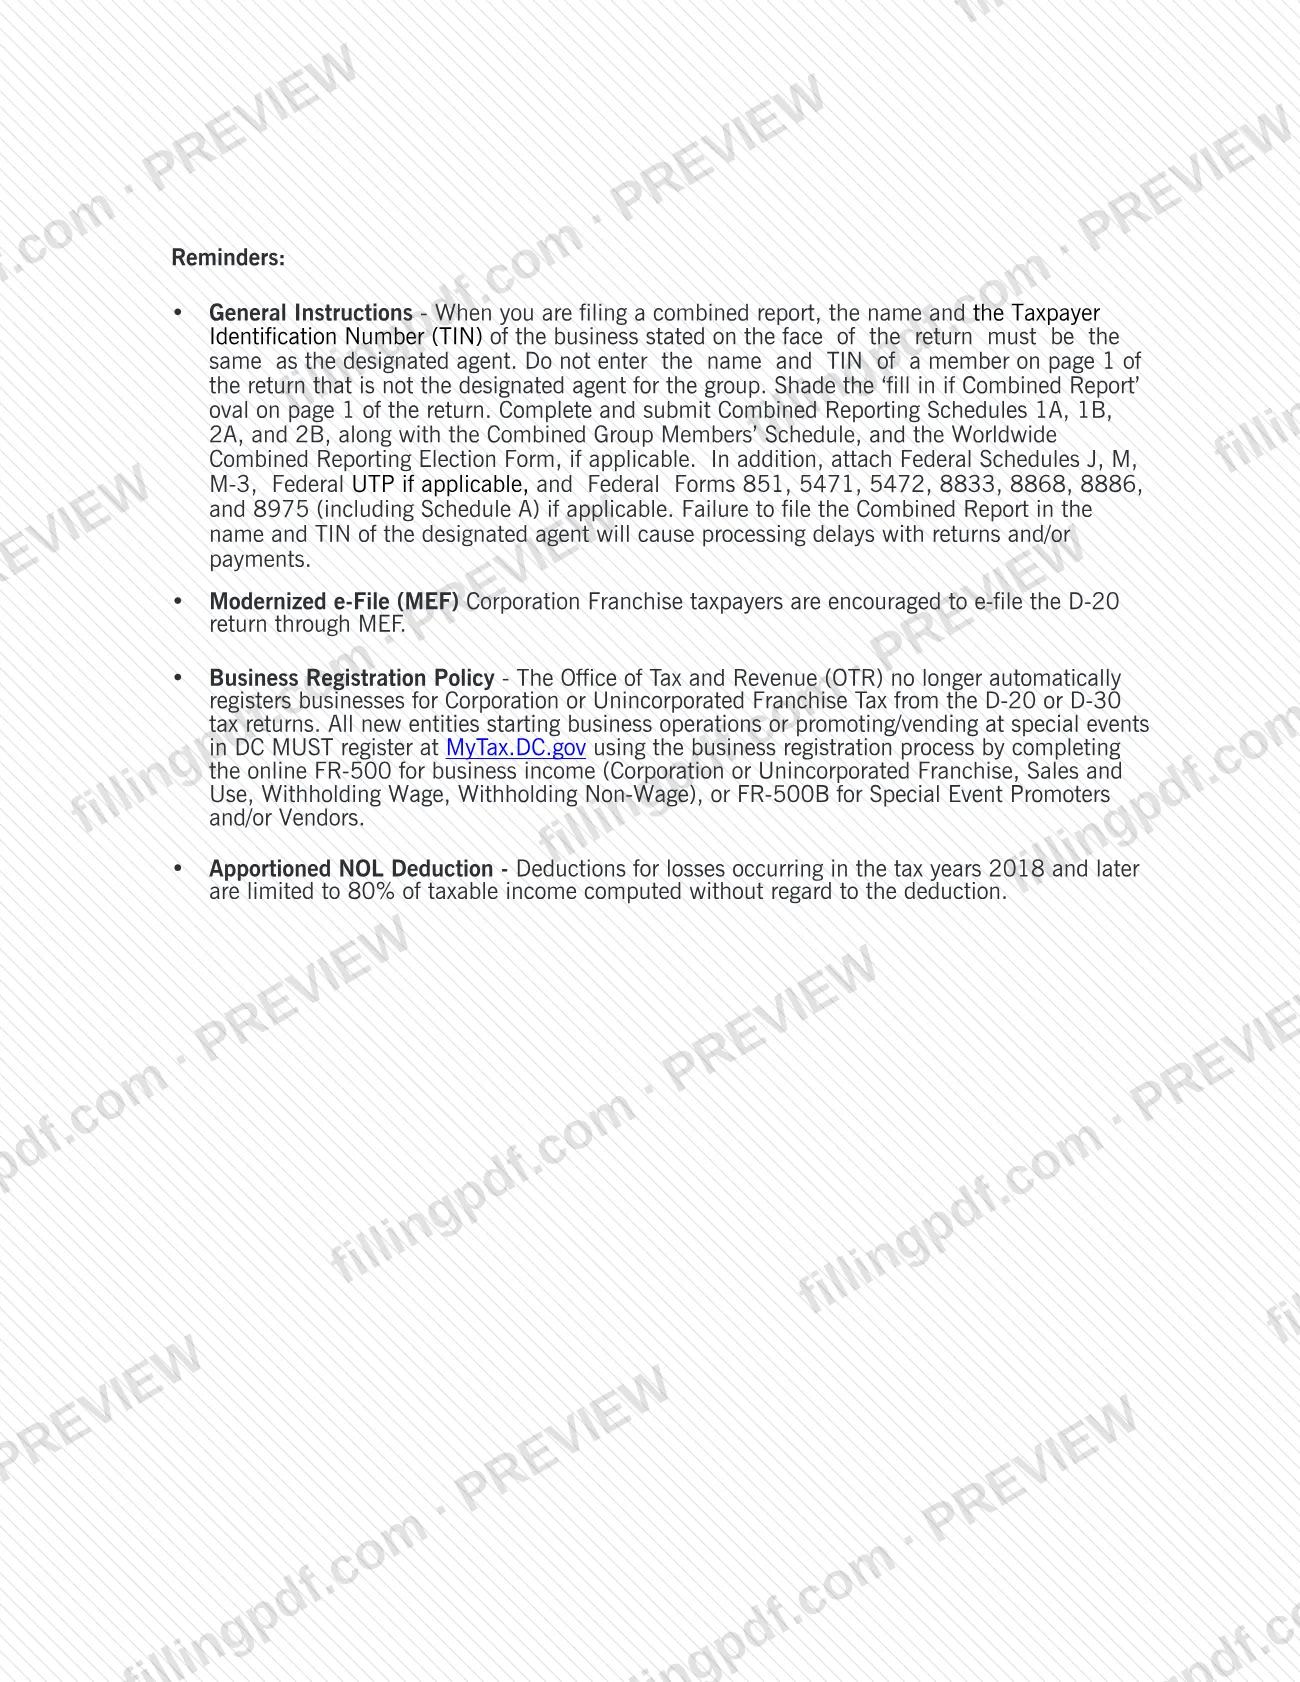
- Modernized e-File (MEF): corporation franchise taxpayers are encouraged to e-file the D-20 return through MEF.
- Electronic copy of the federal return: under OTR Tax Notice 2025-01, certain filers above the gross income thresholds in the booklet must submit an electronic copy of their federal income tax return, with its schedules, for taxable years beginning January 1, 2025.
- Business registration: new entities register at MyTax.DC.gov by completing the online FR-500 (FR-500B for Special Event Promoters and/or Vendors); OTR no longer registers businesses automatically from D-20 or D-30 returns.
- Questions: District of Columbia, Office of Tax and Revenue, 1101 4th Street, SW, Washington, DC 20024; MyTax.DC.gov; (202) 759-1946; [email protected].
File the combined report in the name and TIN of the designated agent; otherwise returns and payments may be delayed. FillingPDF lets you fill out and download the PDF; submission follows the OTR channels above.
Common mistakes to avoid
- Entering the name and TIN of a member that is not the designated agent on page 1 of the return; this causes processing delays with returns and payments.
- Forgetting to shade the 'fill in if Combined Report' oval on page 1 of the D-20 or D-30.
- Using Schedule F on page 4 of the D-20 or D-30 to derive the apportionment factor instead of Combined Reporting Schedule 2A or 2B.
- Using the federal extension form, or assuming an extension to file also extends the time to pay.
- Claiming federal bonus depreciation, additional depreciation for qualified production property, or additional IRC § 179 expenses on the DC return.
- Naming a non-nexus member as the designated agent.
- Letting one member use another member's net operating loss carryforward or unused tax credit; both belong to the member that earned them.
- Filing the Sports Facilities Fee on a combined group basis; each member that meets the criteria files and pays it individually.
- Relying on the D-20 or D-30 to register a new business instead of registering at MyTax.DC.gov with the FR-500.
Frequently asked questions
What is the DC combined report?
It is the single franchise tax report that a unitary group of corporations or unincorporated businesses files under D.C. Code § 47-1805.02a. The designated agent files it with Form D-20 or D-30. Members compute net income on the group's combined activity, but each remains responsible for its own DC tax.
Who has to file a DC combined report?
A corporation or unincorporated business entity subject to DC tax and engaged in a unitary business with one or more related corporations or entities. Insurance companies subject to premium tax, exempt organizations and Qualified High Technology Companies are among those excluded, unless otherwise required to be included.
Is this a DC property tax form?
No. This booklet covers DC franchise tax combined reporting, not DC property tax. Its only property-related item is Schedule SR, the Small Retailer Property Tax Relief Credit, which a qualified business claims against business franchise taxes for rent or real property taxes paid.
When is the 2025 DC combined report due?
April 15, 2026 for tax year 2025. Fiscal year filers file by the 15th day of the 4th month after year-end, and exempt organizations by the 15th day of the 5th month. A seven-month extension to file can be requested by the due date.
Does an extension give me more time to pay DC franchise tax?
No. An extension to file is not an extension of time to pay, and the tax must be paid when the extension request is submitted. Do not use the federal extension form; the designated agent files the request for the entire group.
Who is the designated agent of a combined group?
It is the common parent if it is a taxpayer member. Otherwise it is the taxpayer member with the greatest District business activity in the first year a combined report is required, measured by District sales and payroll. Once appointed, it stays the agent for all future years.
What is the difference between Schedule 1A and Schedule 1B?
Schedule 1A is filed once by the designated agent and totals the entire group, including intercompany eliminations. Schedule 1B is filed for each member, including the designated agent, and reports that member's own tax information on Lines 1 through 48.
How long does a worldwide combined reporting election last?
Ten years. The election is binding for the tax year it is made and the years after, and it works only if every member subject to DC tax makes it on a timely filed original return. Early withdrawal needs written approval from the Chief Financial Officer for extraordinary hardship.
Can I fill out the DC combined reporting schedules online on FillingPDF?
Yes, you can fill out the PDF online on FillingPDF and download or print it. FillingPDF is an independent service, not affiliated with OTR, and does not file or submit anything; you submit through the OTR channels described under How to submit.
Ready to fill out 2025 Combined Reporting Instructions – Washington, DC?
Fill out 2025 Combined Reporting Instructions – Washington, DC now