
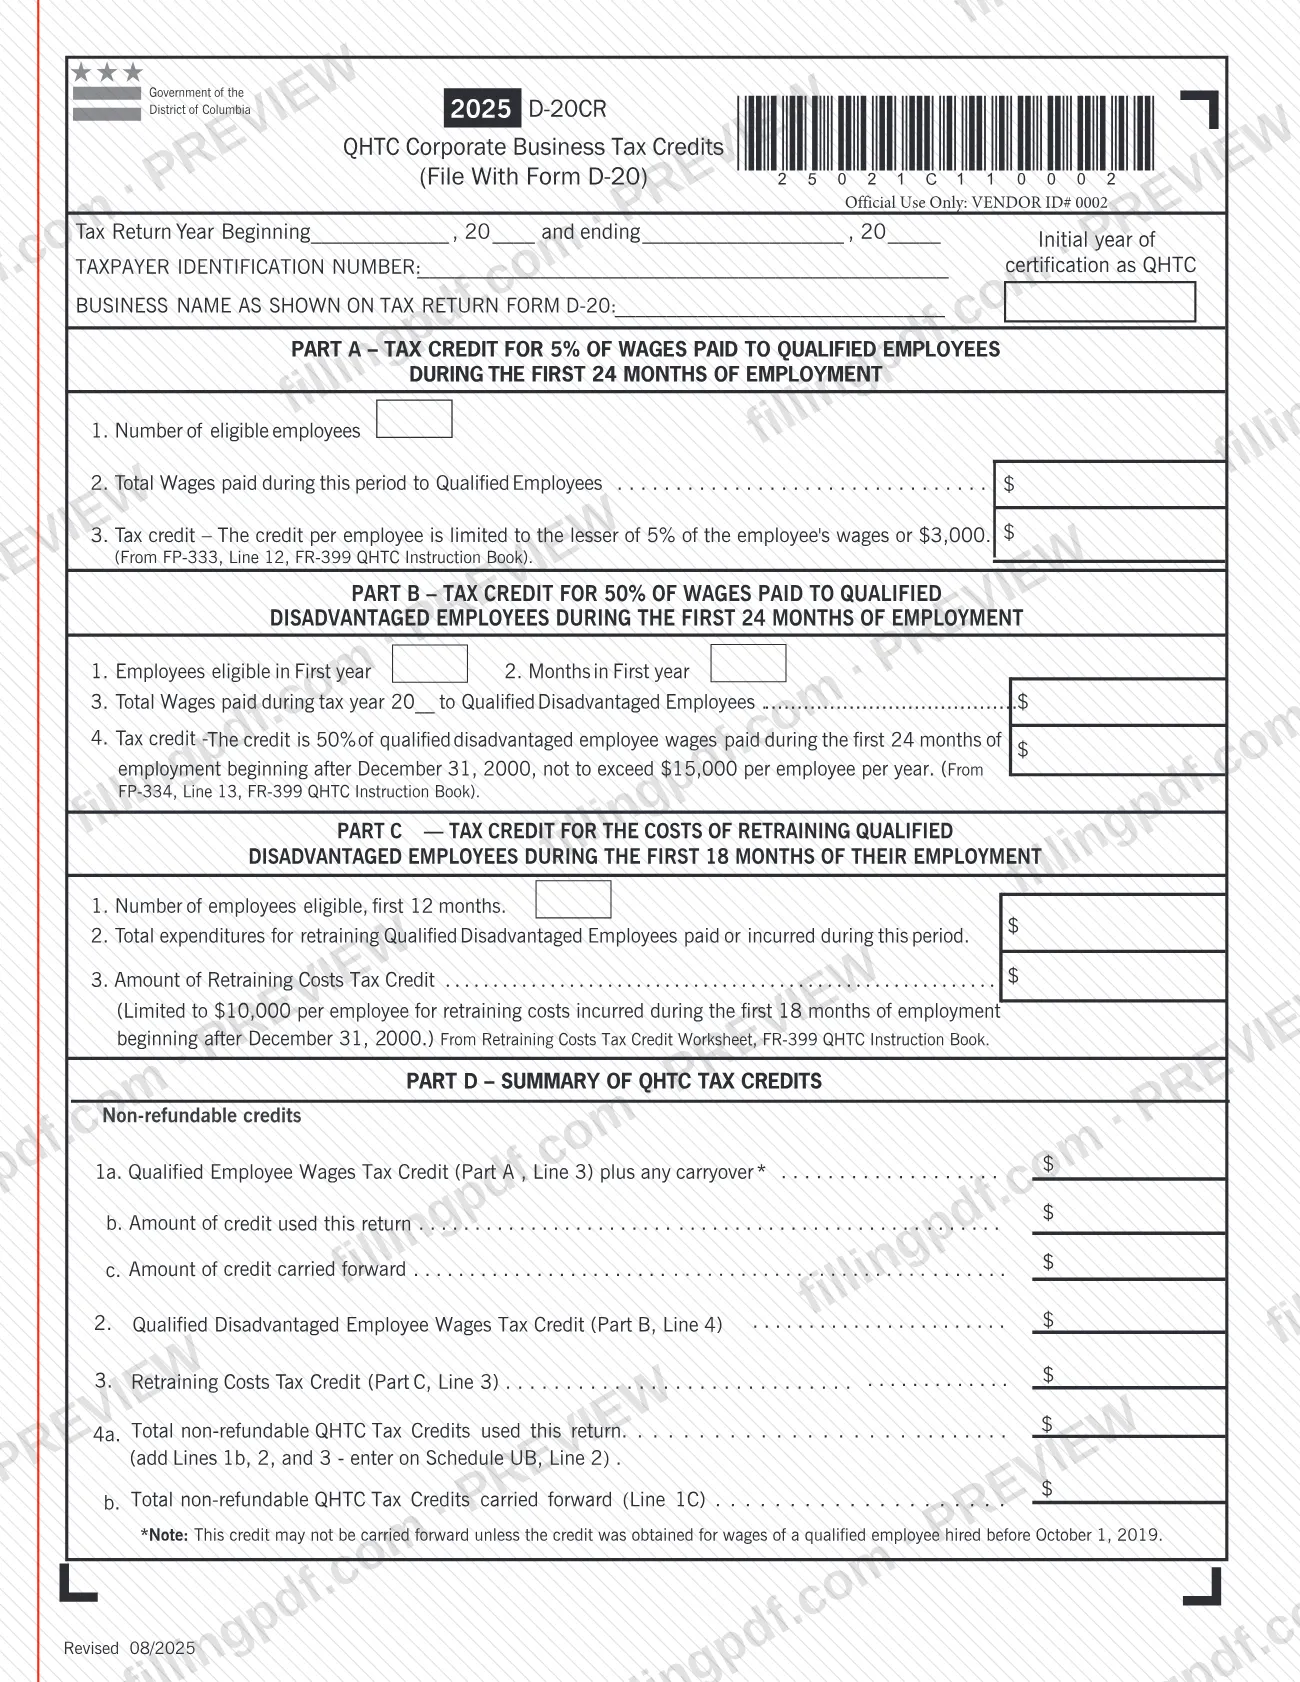
The 2025 D-20CR, QHTC Corporate Business Tax Credits, is a District of Columbia tax schedule issued by the DC Office of Tax and Revenue (OTR) and filed with Form D-20. Corporations use it to figure wage-based and retraining-based QHTC credits and to total the amounts that go to Schedule UB. On this page you can fill out Form D-20CR online on FillingPDF and download or print the completed PDF; the form itself is published by the OTR.
Last updated
What is D-20CR?
The 2025 D-20CR, QHTC Corporate Business Tax Credits, is the Government of the District of Columbia schedule on which a corporation computes its QHTC tax credits for a tax return year and summarizes the amounts it uses or carries forward. Its printed subtitle is "File With Form D-20".
The form has four parts:
- Part A: tax credit for 5% of wages paid to qualified employees during the first 24 months of employment.
- Part B: tax credit for 50% of wages paid to qualified disadvantaged employees during the first 24 months of employment.
- Part C: tax credit for the costs of retraining qualified disadvantaged employees during the first 18 months of their employment.
- Part D: summary of the QHTC tax credits, split into the amount used on this return and the amount carried forward.
The credit amounts in Parts A, B and C come from worksheets in the FR-399 QHTC Instruction Book: FP-333 (Line 12) for Part A, FP-334 (Line 13) for Part B and the Retraining Costs Tax Credit Worksheet for Part C. The total of non-refundable credits used is entered on Schedule UB, Line 2.
Form D-20CR is a credit schedule, not a license or registration. It does not stand alone: it accompanies the corporate return, Form D-20. The revision printed on this version is Revised 08/2025.
Who needs to file D-20CR?
Corporations that file Form D-20 for the 2025 tax return year and claim QHTC credits for wages paid to qualified employees, wages paid to qualified disadvantaged employees, or retraining costs for qualified disadvantaged employees complete this schedule and file it with that return.
Conditions printed on the form:
- Part A applies to wages paid to qualified employees during the first 24 months of employment.
- Part B applies to qualified disadvantaged employees during the first 24 months of employment beginning after December 31, 2000.
- Part C applies to retraining costs for qualified disadvantaged employees during the first 18 months of employment beginning after December 31, 2000.
- A Part A credit may be carried forward only if it was obtained for wages of a qualified employee hired before October 1, 2019.
Taxpayers with no QHTC credit to claim have no reason to complete it. The form names no representative or signer of its own: it is filed with Form D-20. Do not use it as a business license application; it only reports tax credits.
When to file D-20CR
File Form D-20CR at the same time as Form D-20 for the tax return year it covers, because the form is headed "File With Form D-20". No separate due date is printed on the schedule itself.
The top of the form asks for the tax return year, with its beginning and ending dates, so the schedule matches the period of the D-20 you are filing. Have your FP-333, FP-334 and retraining worksheet results ready beforehand, since Parts A, B and C take their credit amounts from them. For the deadline of Form D-20, check the OTR.
Documents you need
- Form D-20, the corporate return this schedule is filed with; Form D-20CR is not filed on its own.
- FP-333 from the FR-399 QHTC Instruction Book: the Part A, line 3 credit comes from its Line 12.
- FP-334 from the FR-399 QHTC Instruction Book: the Part B, line 4 credit comes from its Line 13.
- Retraining Costs Tax Credit Worksheet from the FR-399 QHTC Instruction Book: the Part C, line 3 credit comes from it, if you claim retraining costs.
- Schedule UB: the total of non-refundable QHTC credits used (Part D, line 4a) is entered on its Line 2.
How to fill out D-20CR
Enter the tax year and taxpayer details
At the top, fill in the Tax Return Year Beginning and ending dates, your taxpayer identification number and the business name as shown on tax return Form D-20.
Complete Part A, qualified employee wages
On line 1 enter the number of eligible employees and on line 2 the total wages paid during the period to qualified employees. On line 3 enter the tax credit from FP-333, Line 12, which is limited to the lesser of 5% of wages or the per-employee cap printed on the form.
Complete Part B employee and wage lines
On line 1 enter employees eligible in the first year and on line 2 the months in the first year. On line 3 enter the total wages paid during the tax year (fill in the year) to qualified disadvantaged employees.
Enter the Part B tax credit
On line 4 enter the credit from FP-334, Line 13. The credit is 50% of qualified disadvantaged employee wages paid during the first 24 months of employment beginning after December 31, 2000, subject to the per-employee yearly limit printed on the form.
Complete Part C retraining costs
On line 1 enter the number of employees eligible in the first 12 months and on line 2 the total retraining expenditures paid or incurred. On line 3 enter the credit from the Retraining Costs Tax Credit Worksheet, within the per-employee limit printed on the form.
Fill in Part D, line 1
On line 1a enter the Part A, line 3 credit plus any carryover. On line 1b enter the amount of credit used on this return and on line 1c the amount carried forward.
Fill in Part D, lines 2 and 3
On line 2 enter the Part B, line 4 credit. On line 3 enter the Part C, line 3 credit.
Total the non-refundable credits
On line 4a add lines 1b, 2 and 3 and enter the total on Schedule UB, Line 2. On line 4b enter the total non-refundable QHTC credits carried forward (line 1c).
Check the carryforward rule
Confirm that any Part A carryforward relates to wages of a qualified employee hired before October 1, 2019, as the form's note requires.
Review and download the completed PDF
Check names, dates and each total against your worksheets, then download or print the completed PDF from FillingPDF and file it with Form D-20.
How to submit D-20CR
Form D-20CR is submitted together with Form D-20; the form prints no separate address, portal or appointment rule of its own.
- With Form D-20: include the completed schedule in the same filing as your corporate return for the tax return year shown at the top.
- Schedule UB: enter the total on Part D, line 4a (lines 1b, 2 and 3 added) on Schedule UB, Line 2, as the form directs.
- Where to look for filing details: the form is published by the DC Office of Tax and Revenue (OTR) at otr.cfo.dc.gov; use the channels the OTR gives for Form D-20.
FillingPDF lets you fill out and download the PDF; submission follows the OTR channels that apply to Form D-20.
Common mistakes to avoid
- Filing Form D-20CR without Form D-20; the form says to file it with Form D-20.
- Entering a credit that ignores the limit printed on Part A, line 3 or Part B, line 4 instead of taking the figure from worksheet FP-333 or FP-334.
- Carrying forward a Part A credit when the qualified employee was hired on or after October 1, 2019; the form allows carryforward only for employees hired before that date.
- Leaving the business name different from the name on Form D-20, when the form asks for the name as shown on Form D-20.
- Omitting the tax return year beginning and ending dates at the top of the form.
- Adding the wrong lines on Part D, line 4a; the form says to add Lines 1b, 2 and 3.
- Forgetting to carry the line 4a total to Schedule UB, Line 2.
- Computing the Part C retraining credit without the Retraining Costs Tax Credit Worksheet, or beyond the per-employee limit printed on the form.
Frequently asked questions
What is Form D-20CR?
Form D-20CR, QHTC Corporate Business Tax Credits, is the DC Office of Tax and Revenue schedule on which a corporation figures its QHTC credits for wages of qualified employees, wages of qualified disadvantaged employees and retraining costs. It is filed with Form D-20.
Is Form D-20CR a DC business license?
No. The form is a tax credit schedule filed with the corporate return, Form D-20, and it licenses or registers nothing. It reports QHTC credits in four parts and summarizes the amounts used and carried forward in Part D.
Do I file Form D-20CR by itself?
No. The form is headed "File With Form D-20", so it goes in with your corporate return for the same tax return year. The total non-refundable credit used on line 4a also goes on Schedule UB, Line 2.
Where do the credit amounts on Form D-20CR come from?
They come from worksheets in the FR-399 QHTC Instruction Book: FP-333, Line 12 for Part A, FP-334, Line 13 for Part B and the Retraining Costs Tax Credit Worksheet for Part C. Compute them first, then enter the results.
Can I carry a QHTC credit forward on Form D-20CR?
Only in a limited case. The form's note says the Part D, line 1 wage credit may not be carried forward unless it was obtained for wages of a qualified employee hired before October 1, 2019. Enter any carried-forward amount on line 1c.
What is the difference between Part A and Part B?
Part A is a credit for 5% of wages paid to qualified employees in their first 24 months of employment. Part B is a credit for 50% of wages paid to qualified disadvantaged employees in the first 24 months, with its own per-employee yearly limit.
Can I fill out Form D-20CR online?
Yes. You can complete the fillable PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the form with the OTR; you submit it with Form D-20 through the OTR's channels.
Ready to fill out D-20CR?
Fill out D-20CR now