
Form FR-399, Qualified High Technology Companies (QHTC), is the booklet the DC Office of Tax and Revenue (OTR) publishes for tax years 2021, 2022 and 2023 (Rev. 03/2025). It sets out who qualifies as a QHTC and which DC tax benefits apply, and it contains the credit claim forms FP-332, FP-333 and FP-334 and the Certification of Gross Revenue worksheet. It is one of the DC property tax resources only in part: it also states that the personal property tax exemption for QHTCs ended effective July 1, 2021. On this page you can fill out the form online on FillingPDF and download or print the completed PDF; OTR publishes the original at the official URL.
Last updated
What is FR-399?
Form FR-399, Qualified High Technology Companies (QHTC), is the Office of Tax and Revenue (OTR) booklet for tax years 2021, 2022 and 2023 that explains how a business qualifies as a Qualified High Technology Company in the District of Columbia and how it claims the related tax benefits.
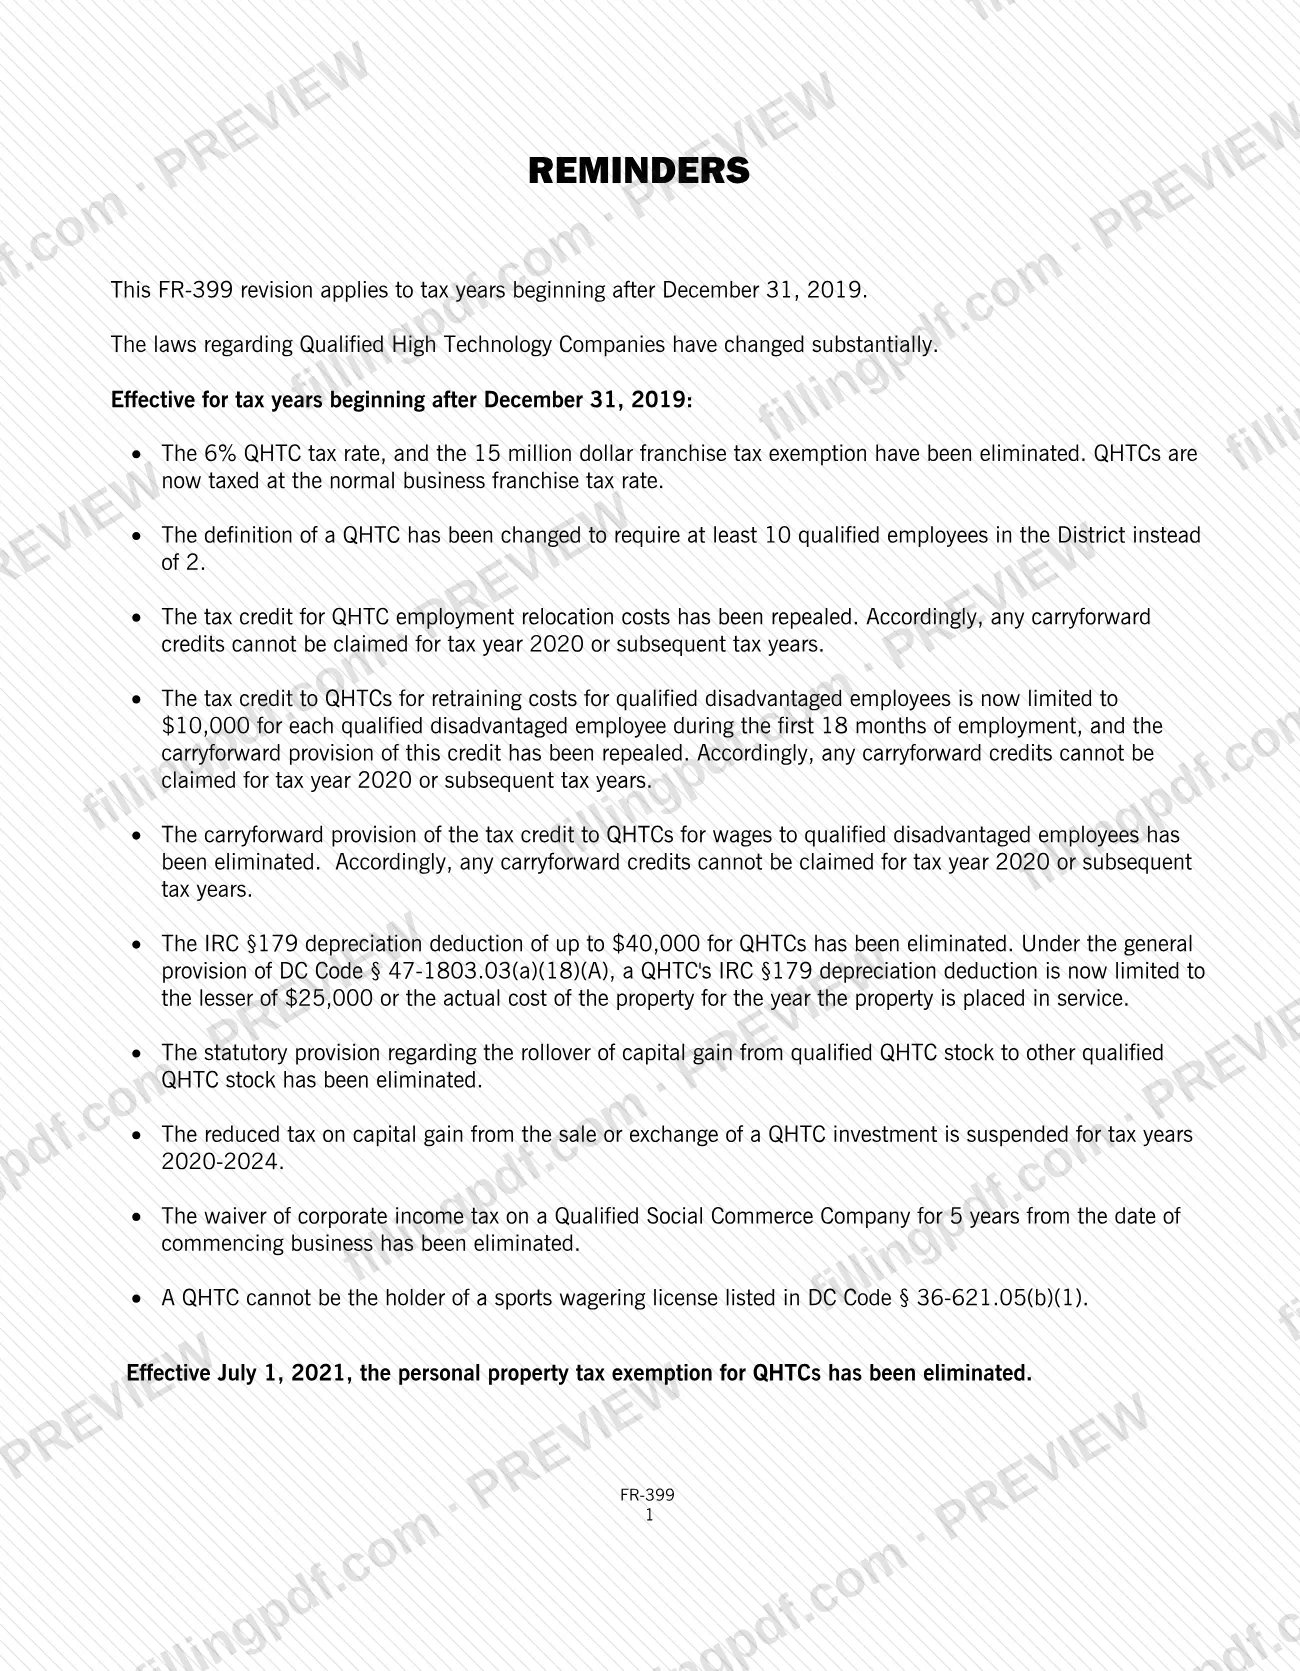
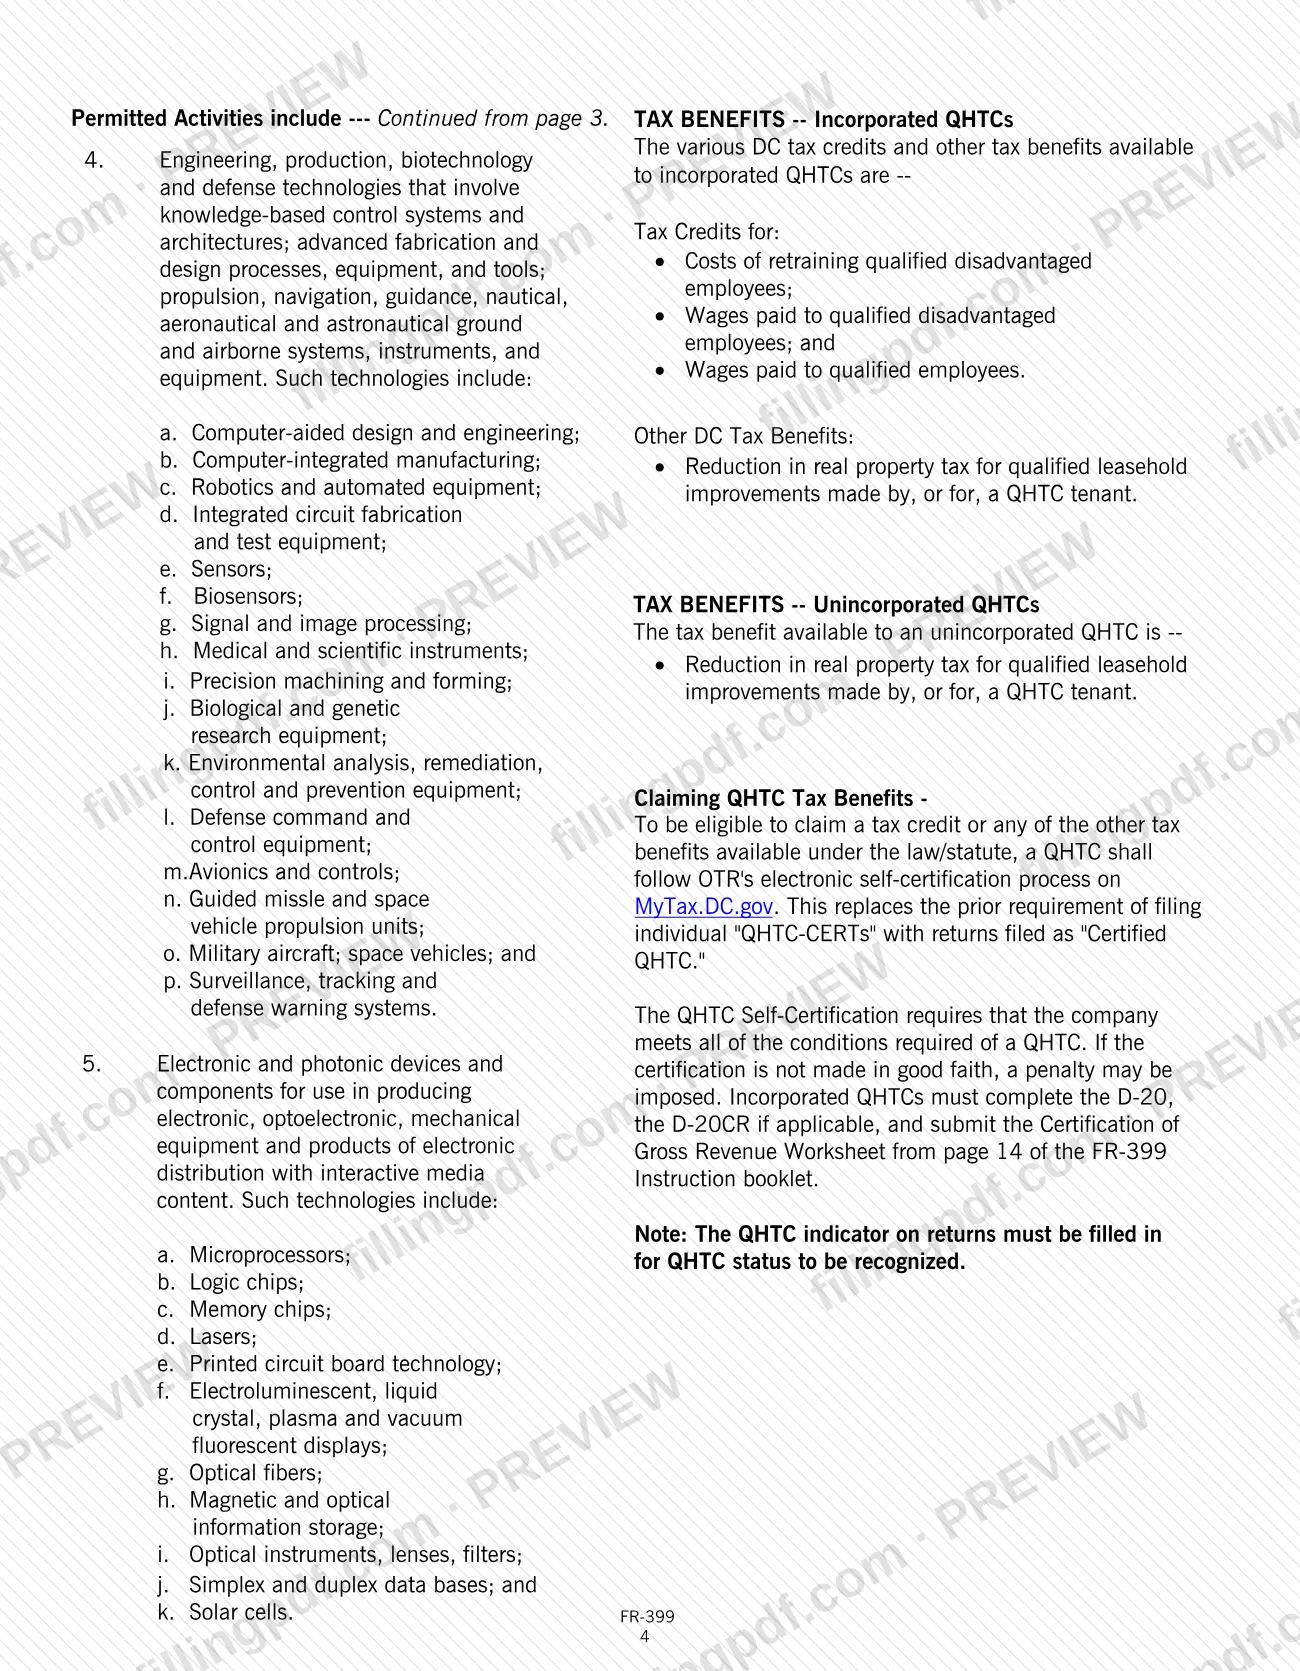
The booklet applies to tax years beginning after December 31, 2019, and reflects the QHTC Tax Incentives Modification Amendment Act of 2020. Among the changes it lists: QHTCs are taxed at the normal business franchise tax rate, a QHTC needs at least 10 qualified employees in the District, the relocation-cost credit was repealed, and the personal property tax exemption for QHTCs was eliminated effective July 1, 2021.
Inside the booklet you will find:
- the definition of a QHTC, the businesses it excludes and the list of permitted activities;
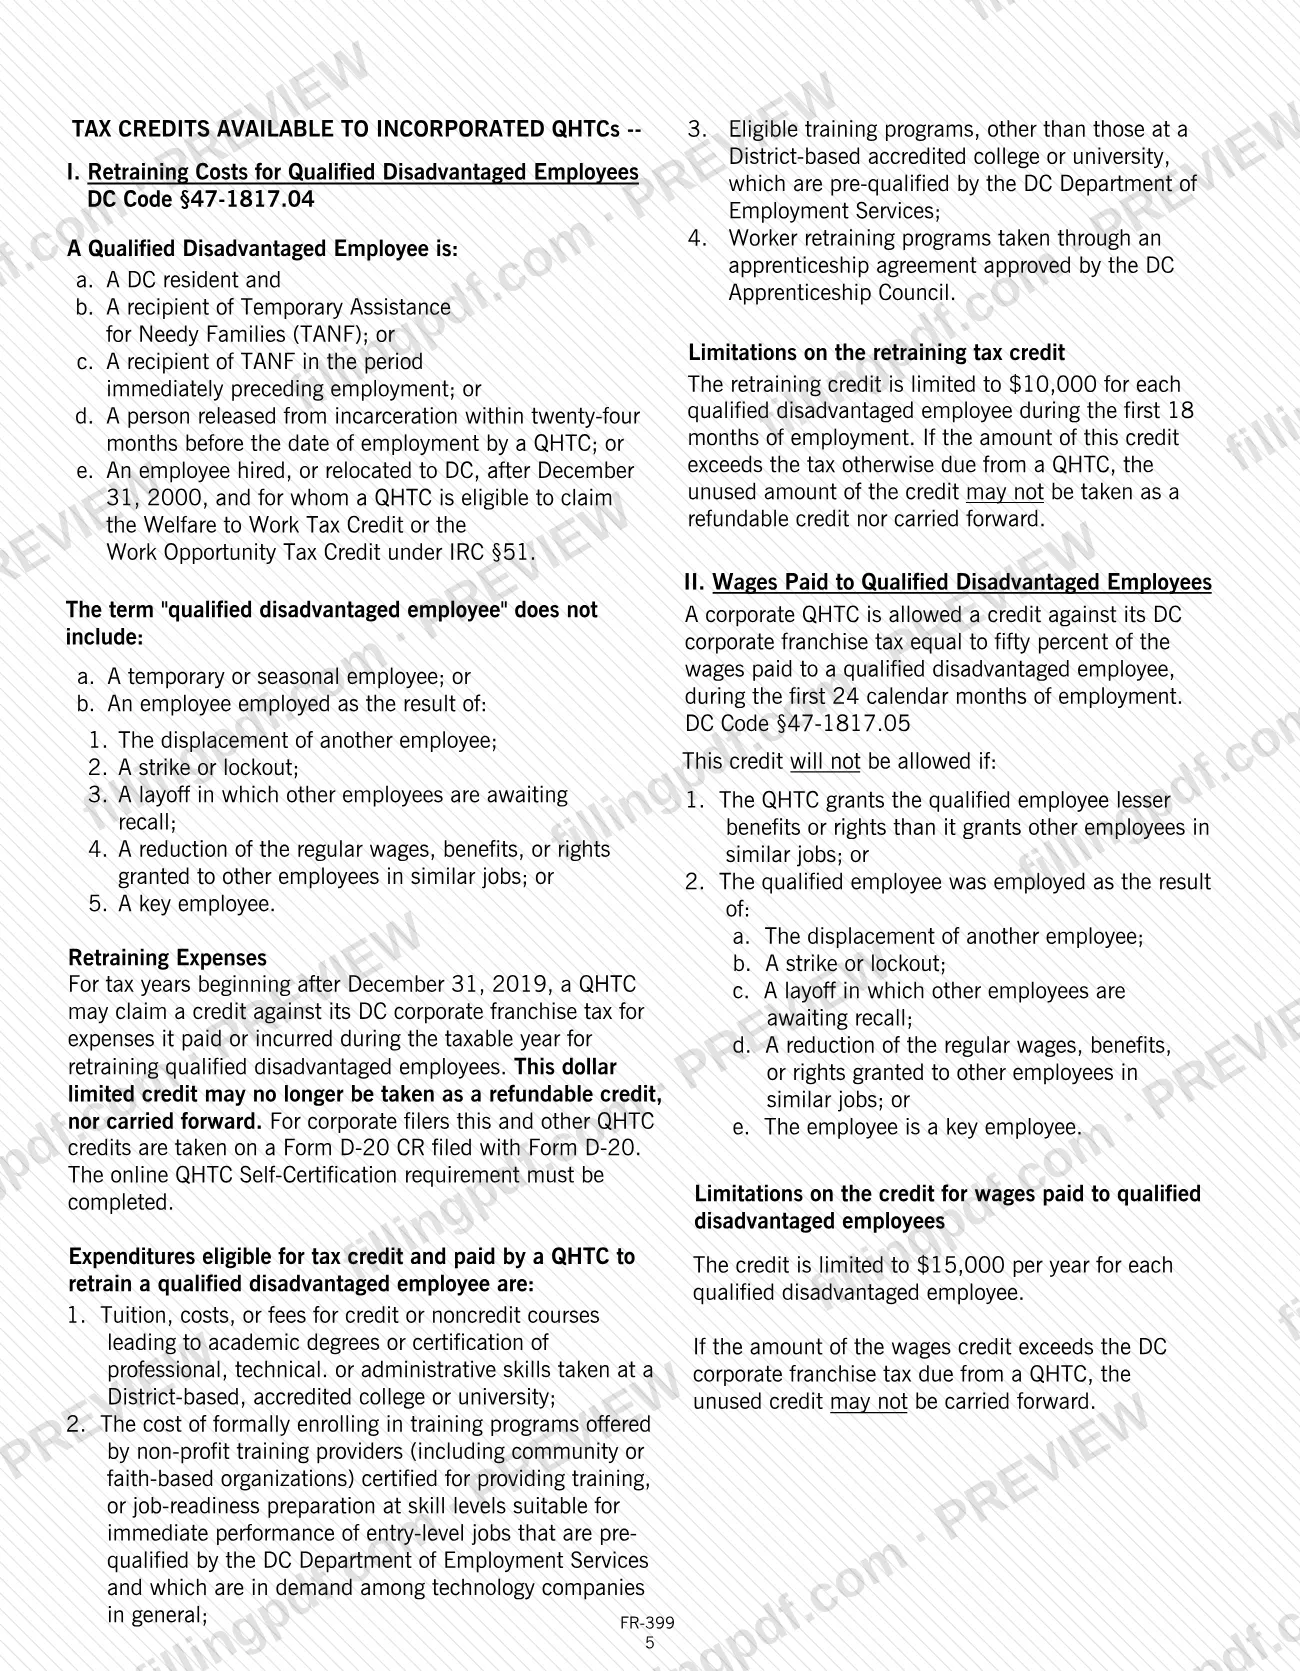
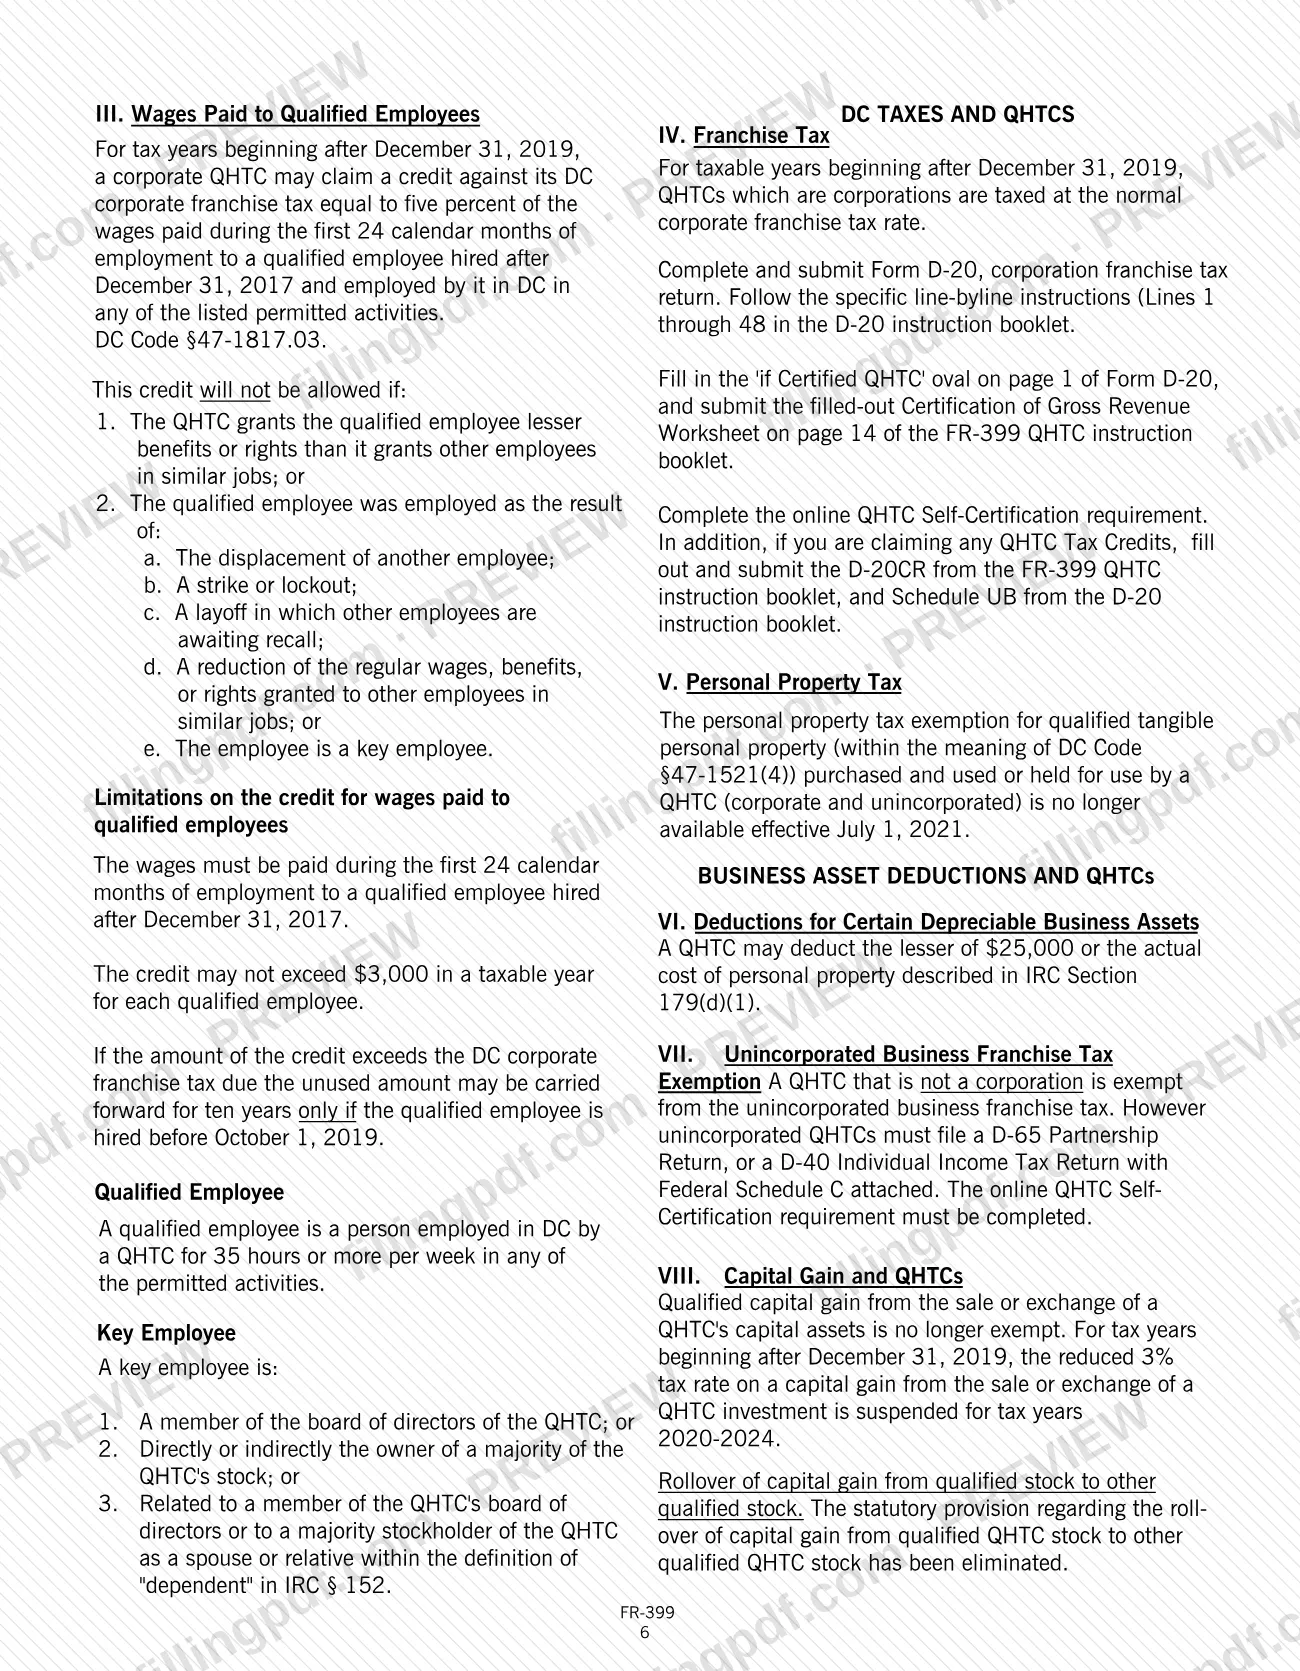
- the tax credits for retraining costs, for wages paid to qualified disadvantaged employees and for wages paid to qualified employees;
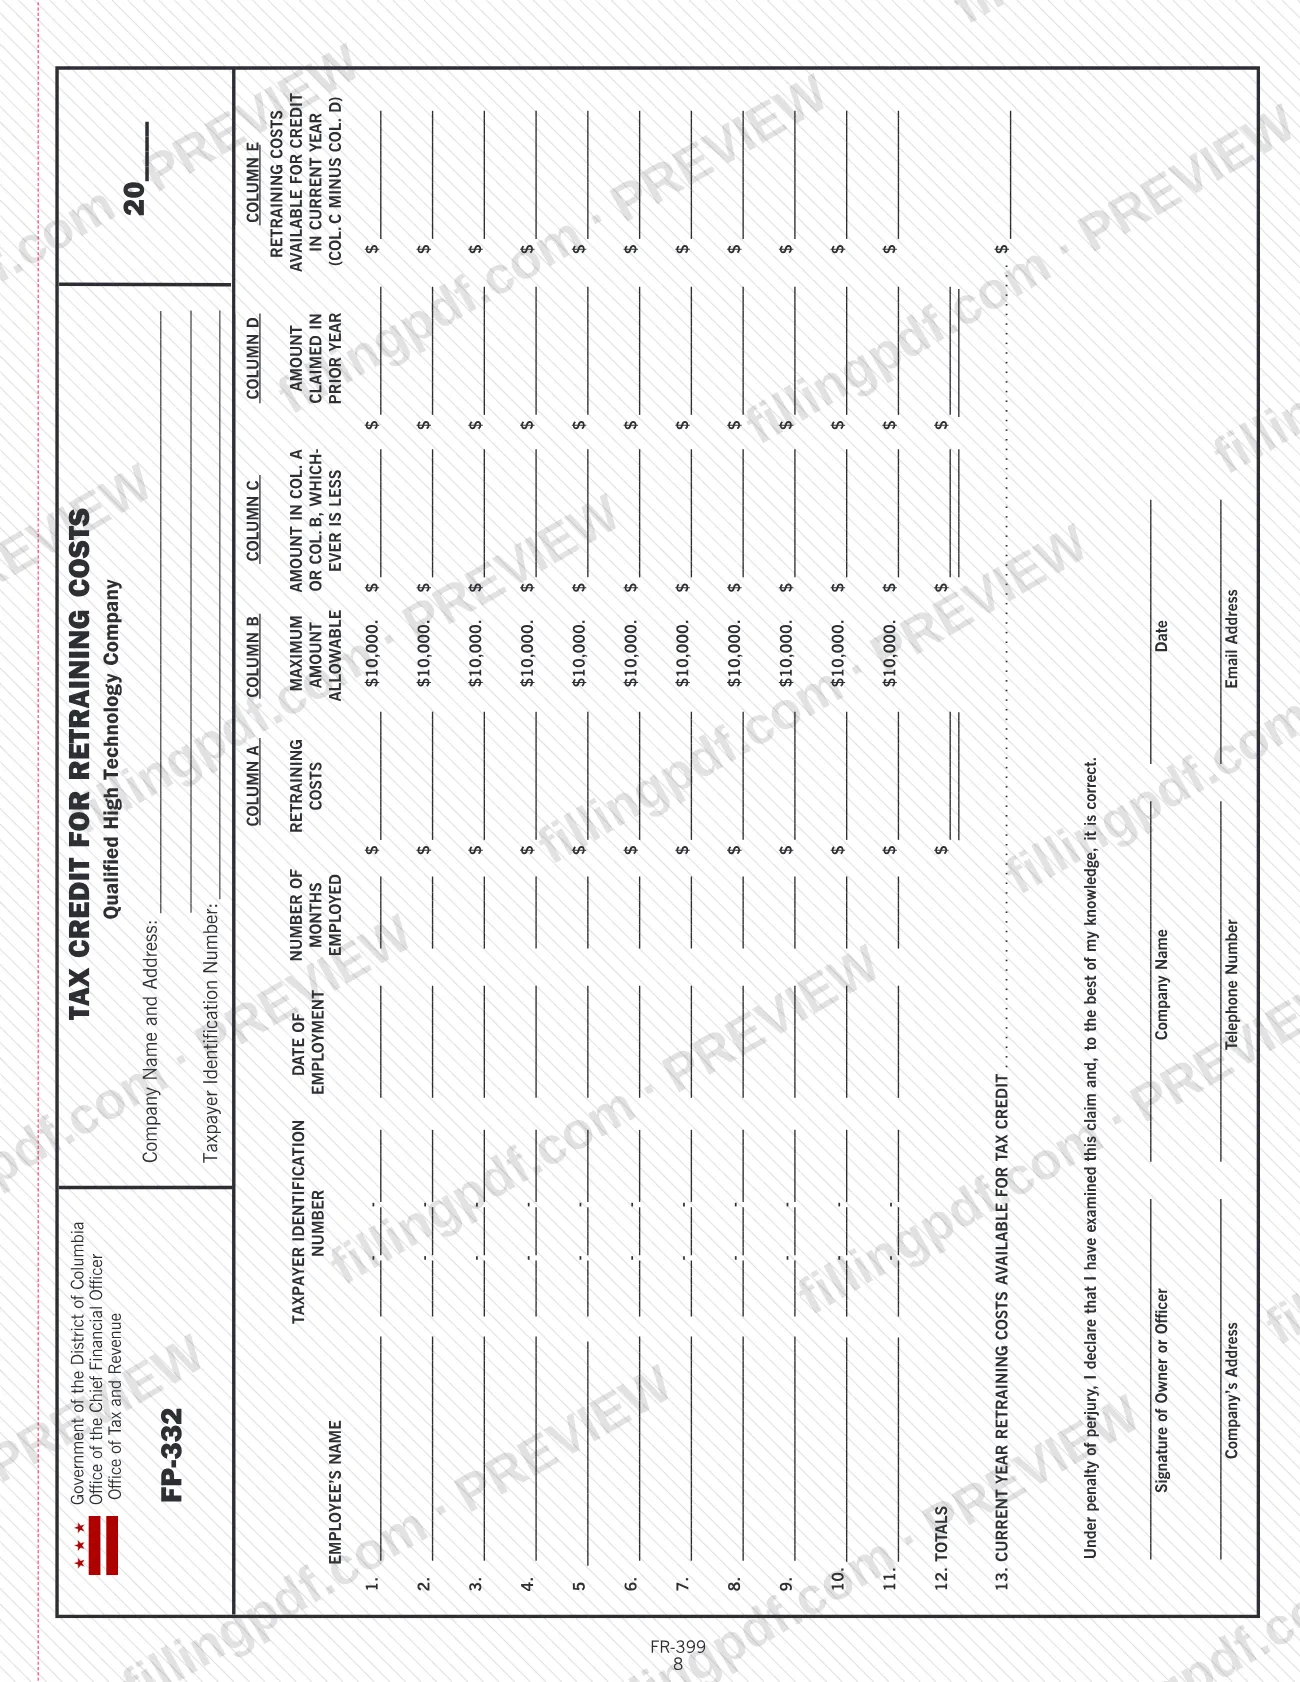
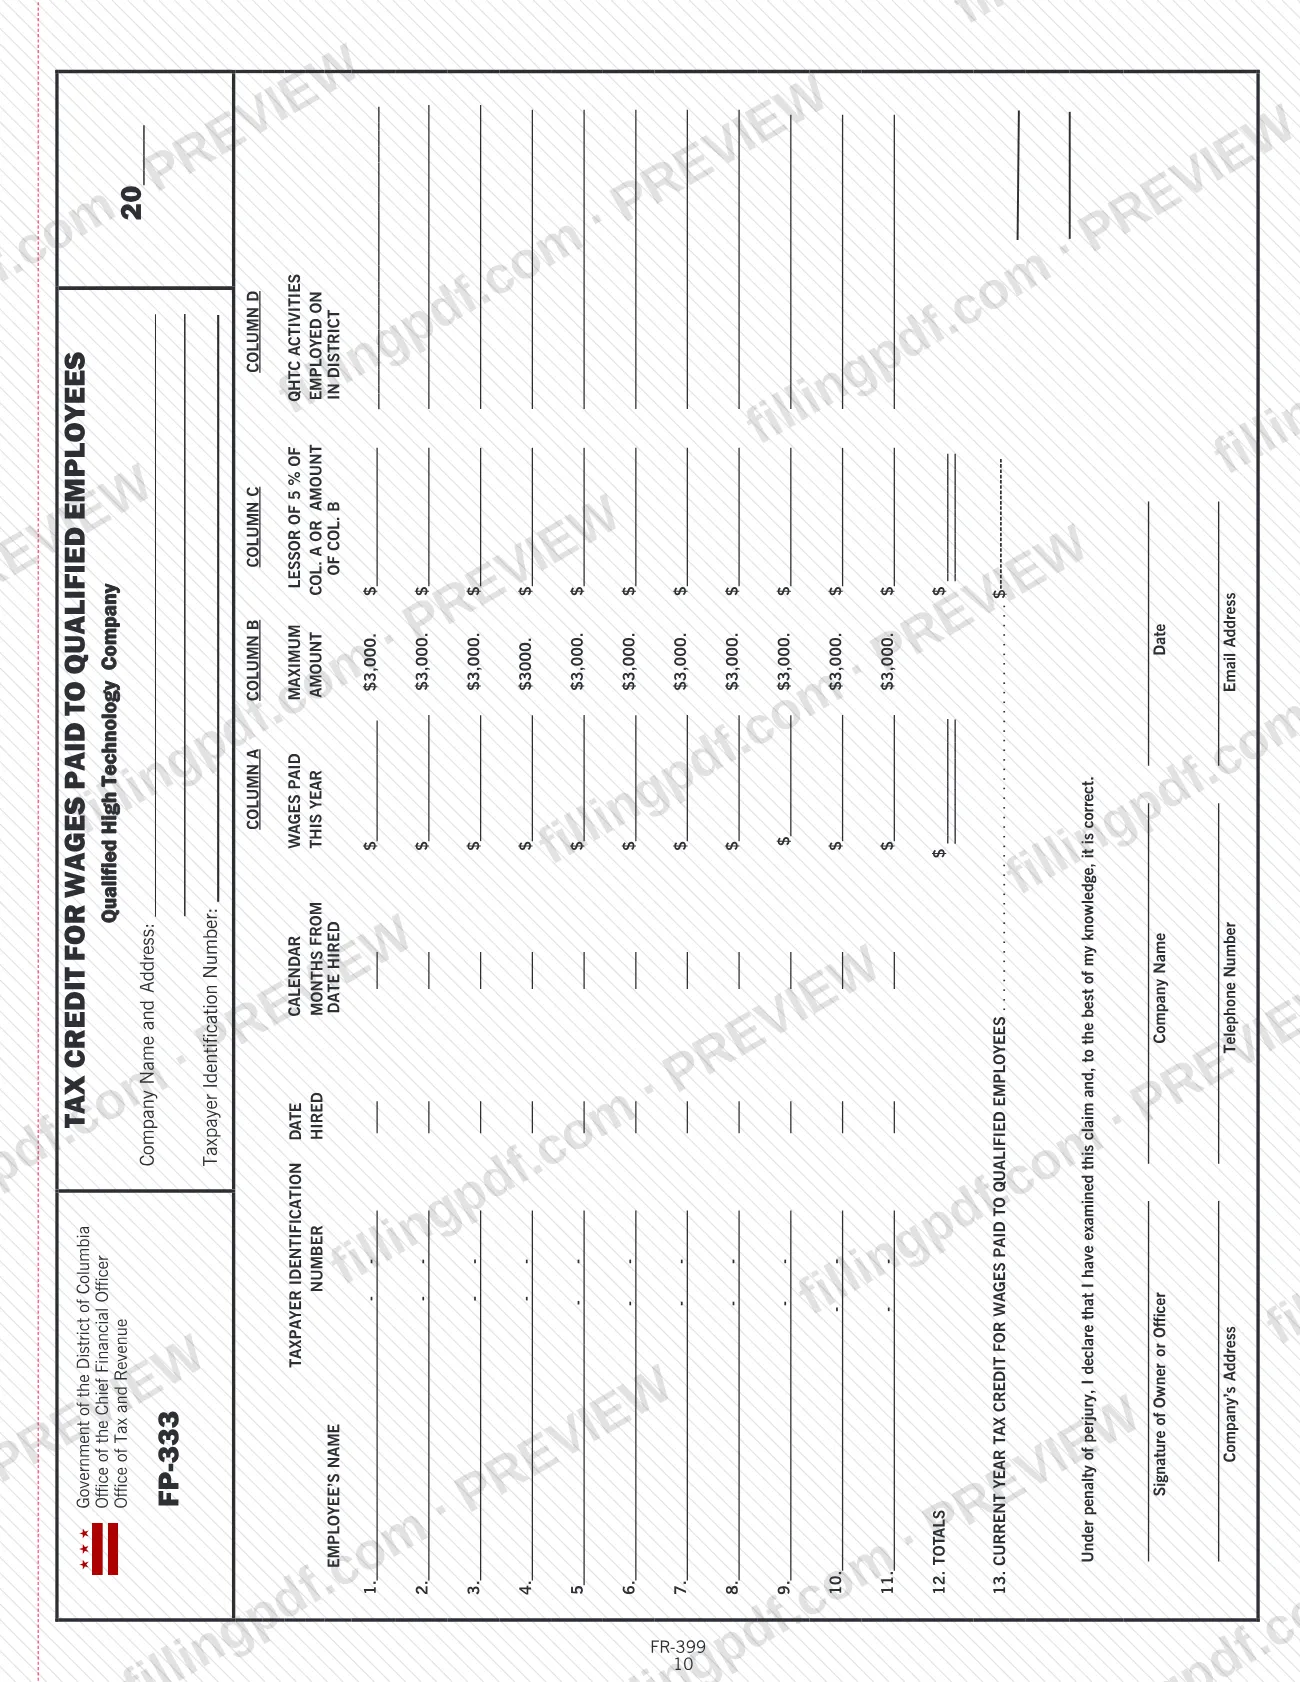
- Form FP-332 (retraining costs), Form FP-333 (wages paid to qualified employees) and Form FP-334 (wages paid to qualified disadvantaged employees);
- the QHTC Certification of Gross Revenue worksheet.
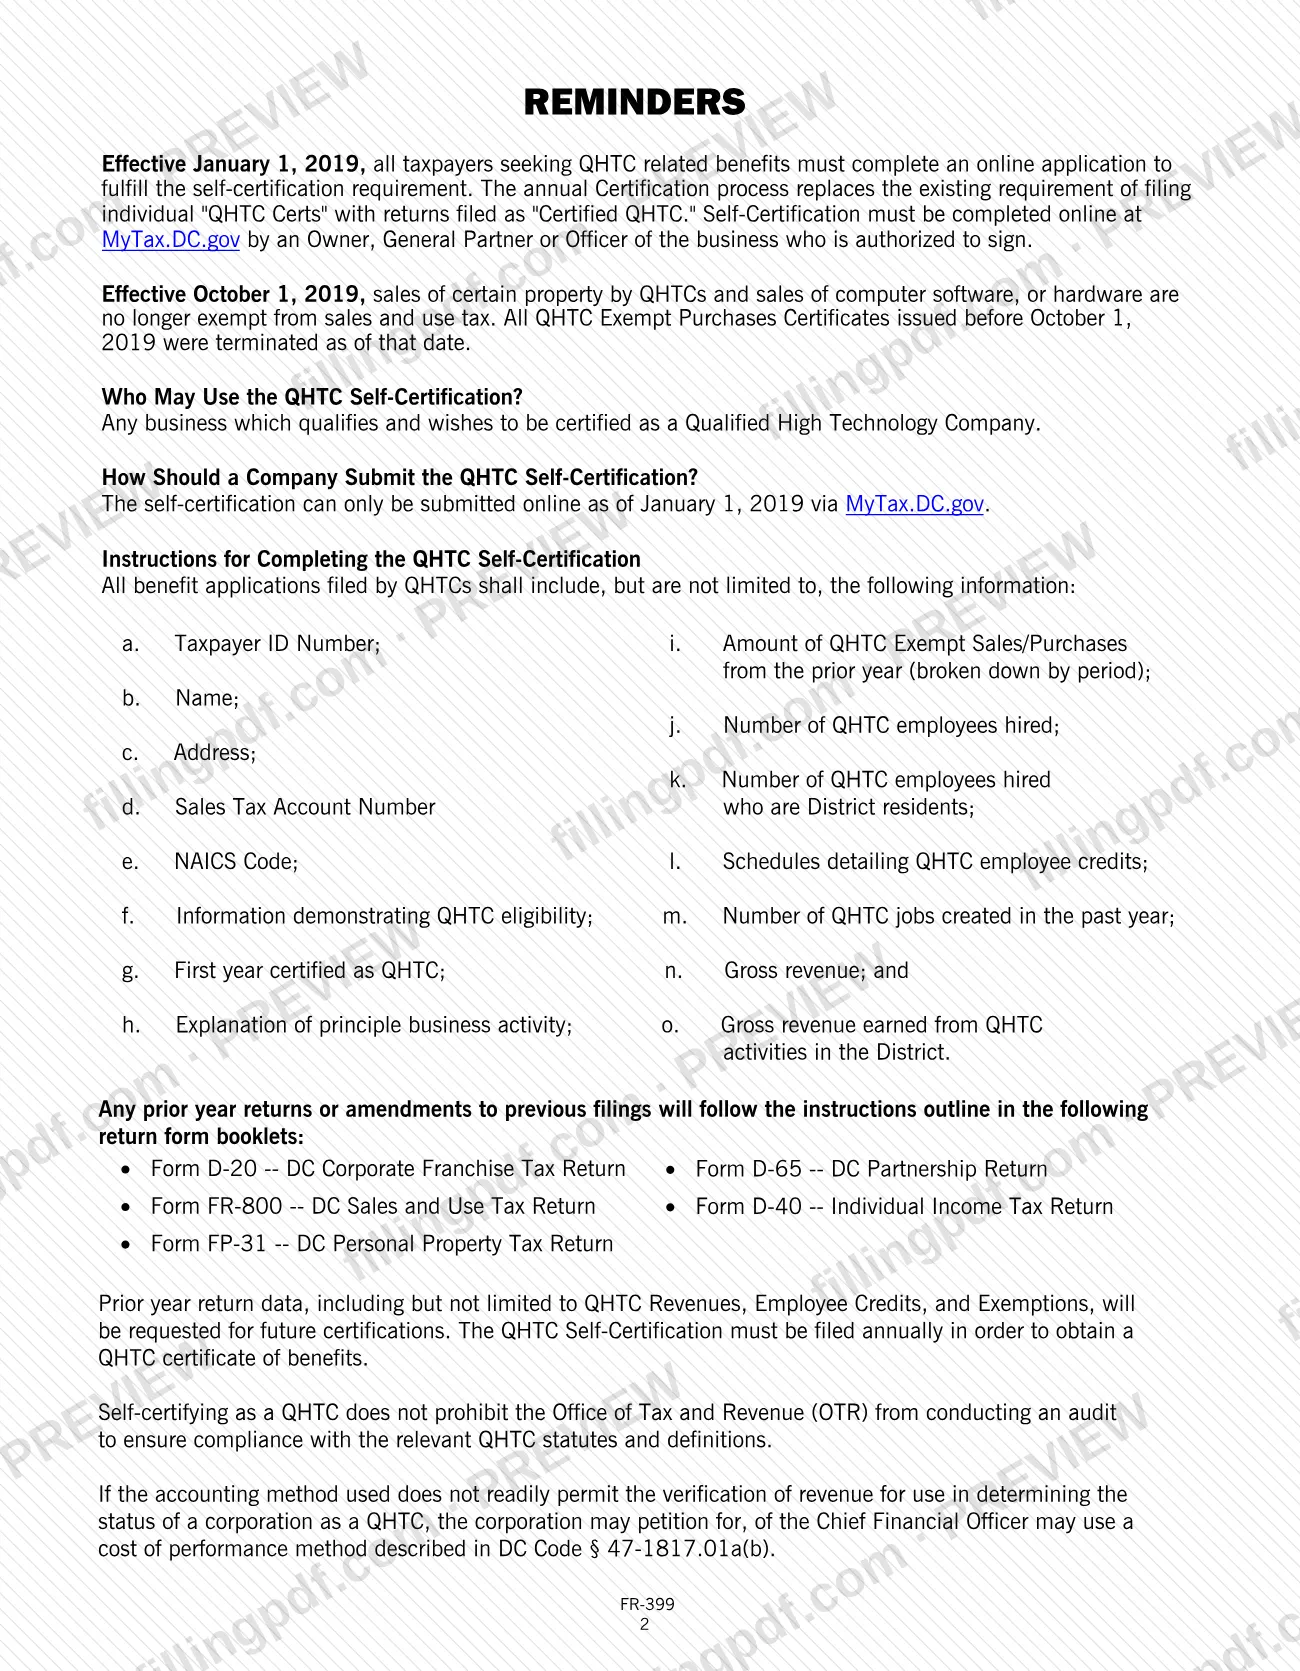
FR-399 is not a return. Corporations claim the credits on Form D-20CR filed with Form D-20, and the benefits depend on the annual online QHTC Self-Certification at MyTax.DC.gov, which replaced the old "QHTC-CERT" filing.
Who needs to file FR-399?
Any business that qualifies and wants to be certified as a Qualified High Technology Company uses the self-certification described in this booklet. Corporations that are certified QHTCs and claim one of the credits use the matching claim form: FP-332 for retraining costs, FP-333 for wages paid to qualified employees, FP-334 for wages paid to qualified disadvantaged employees.
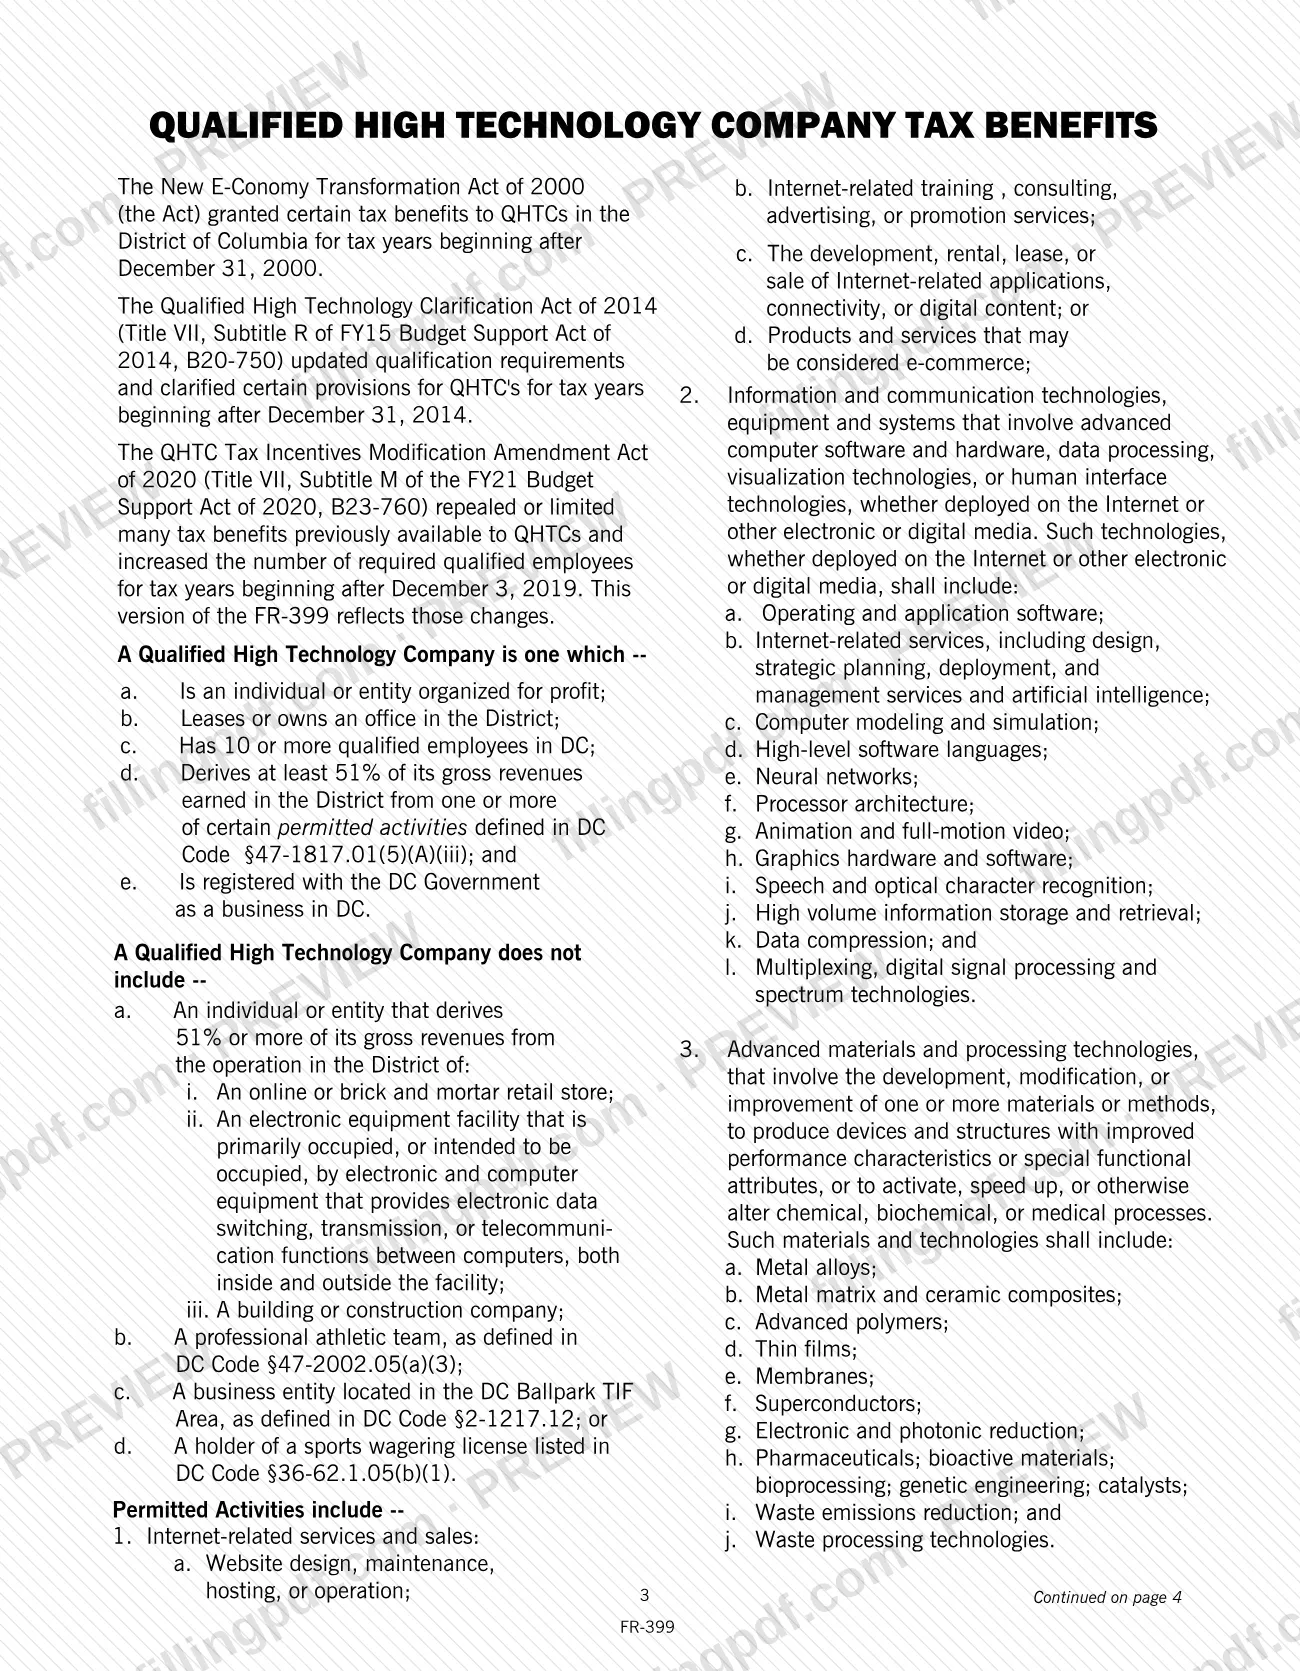
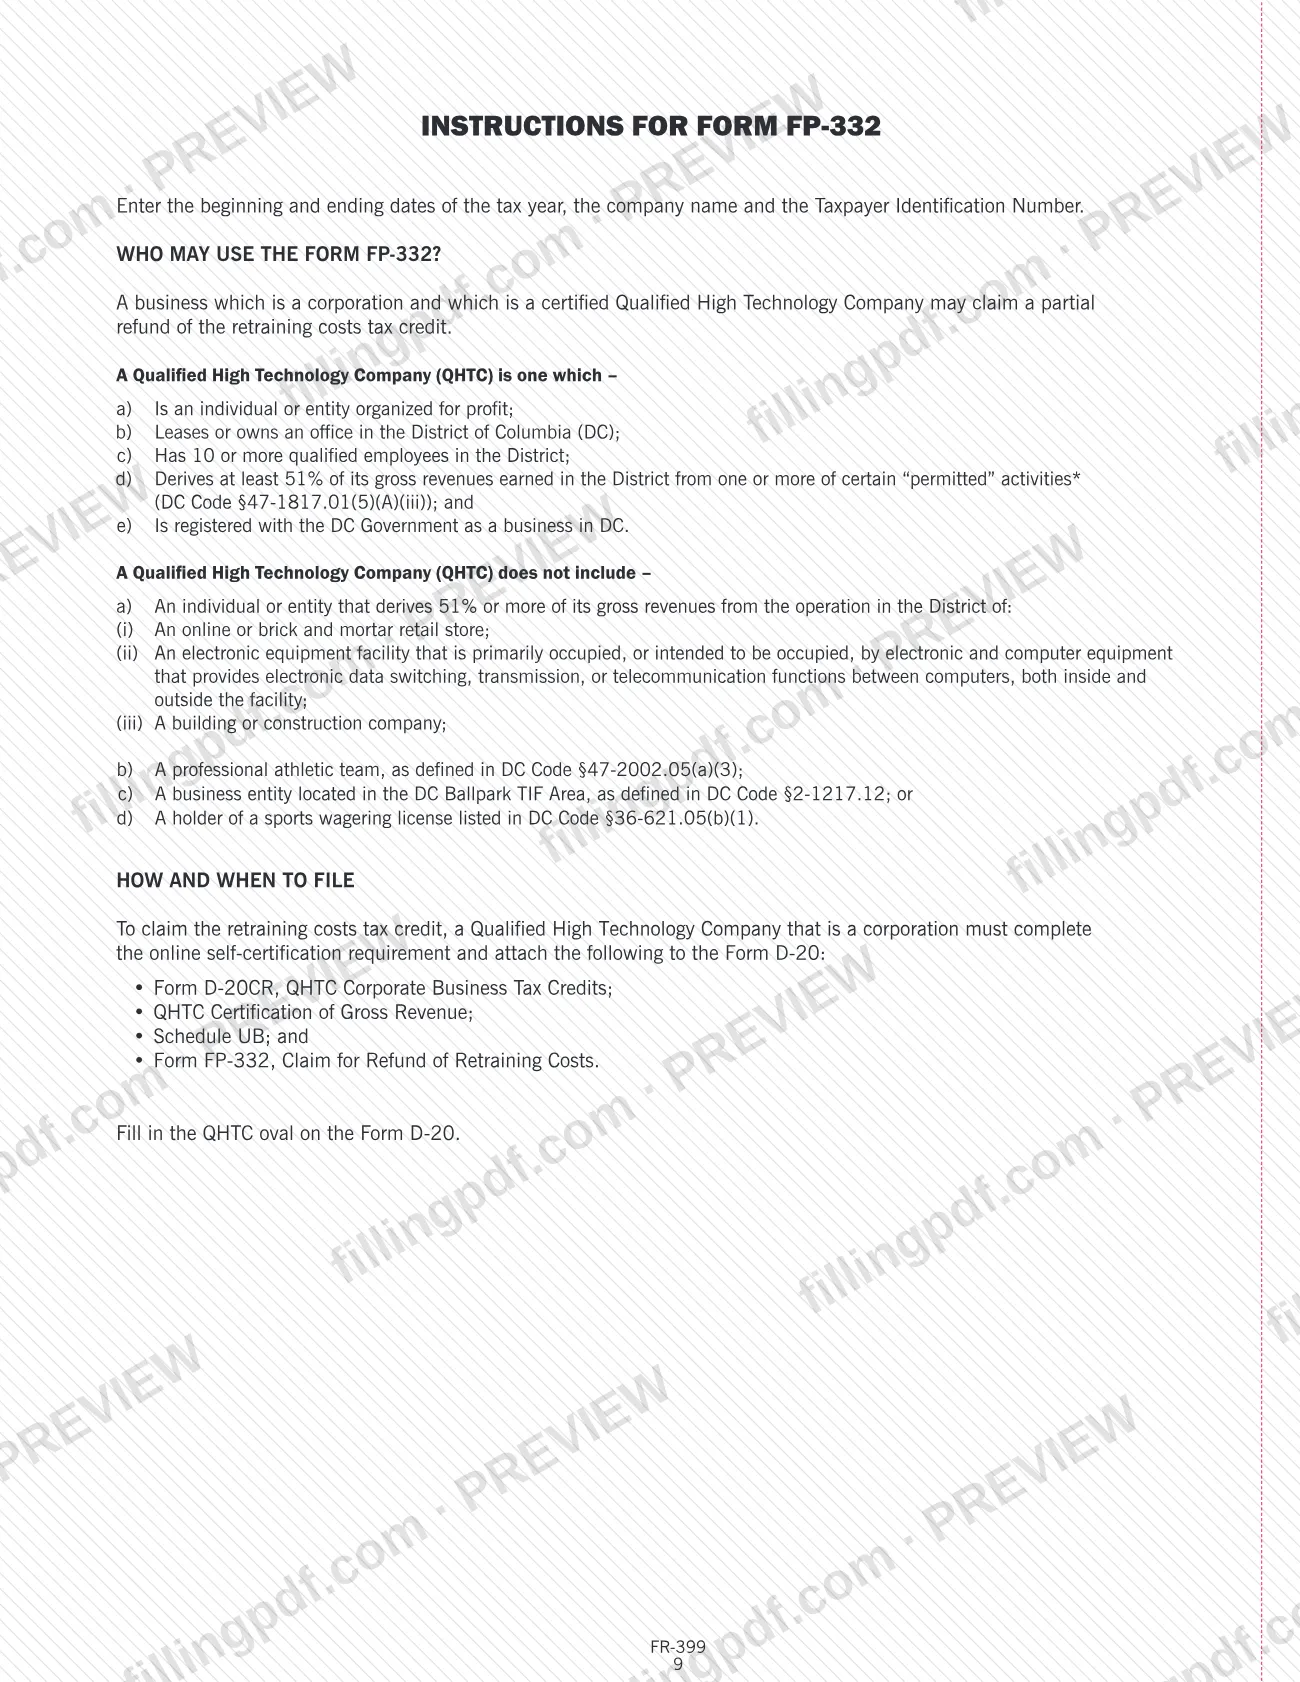
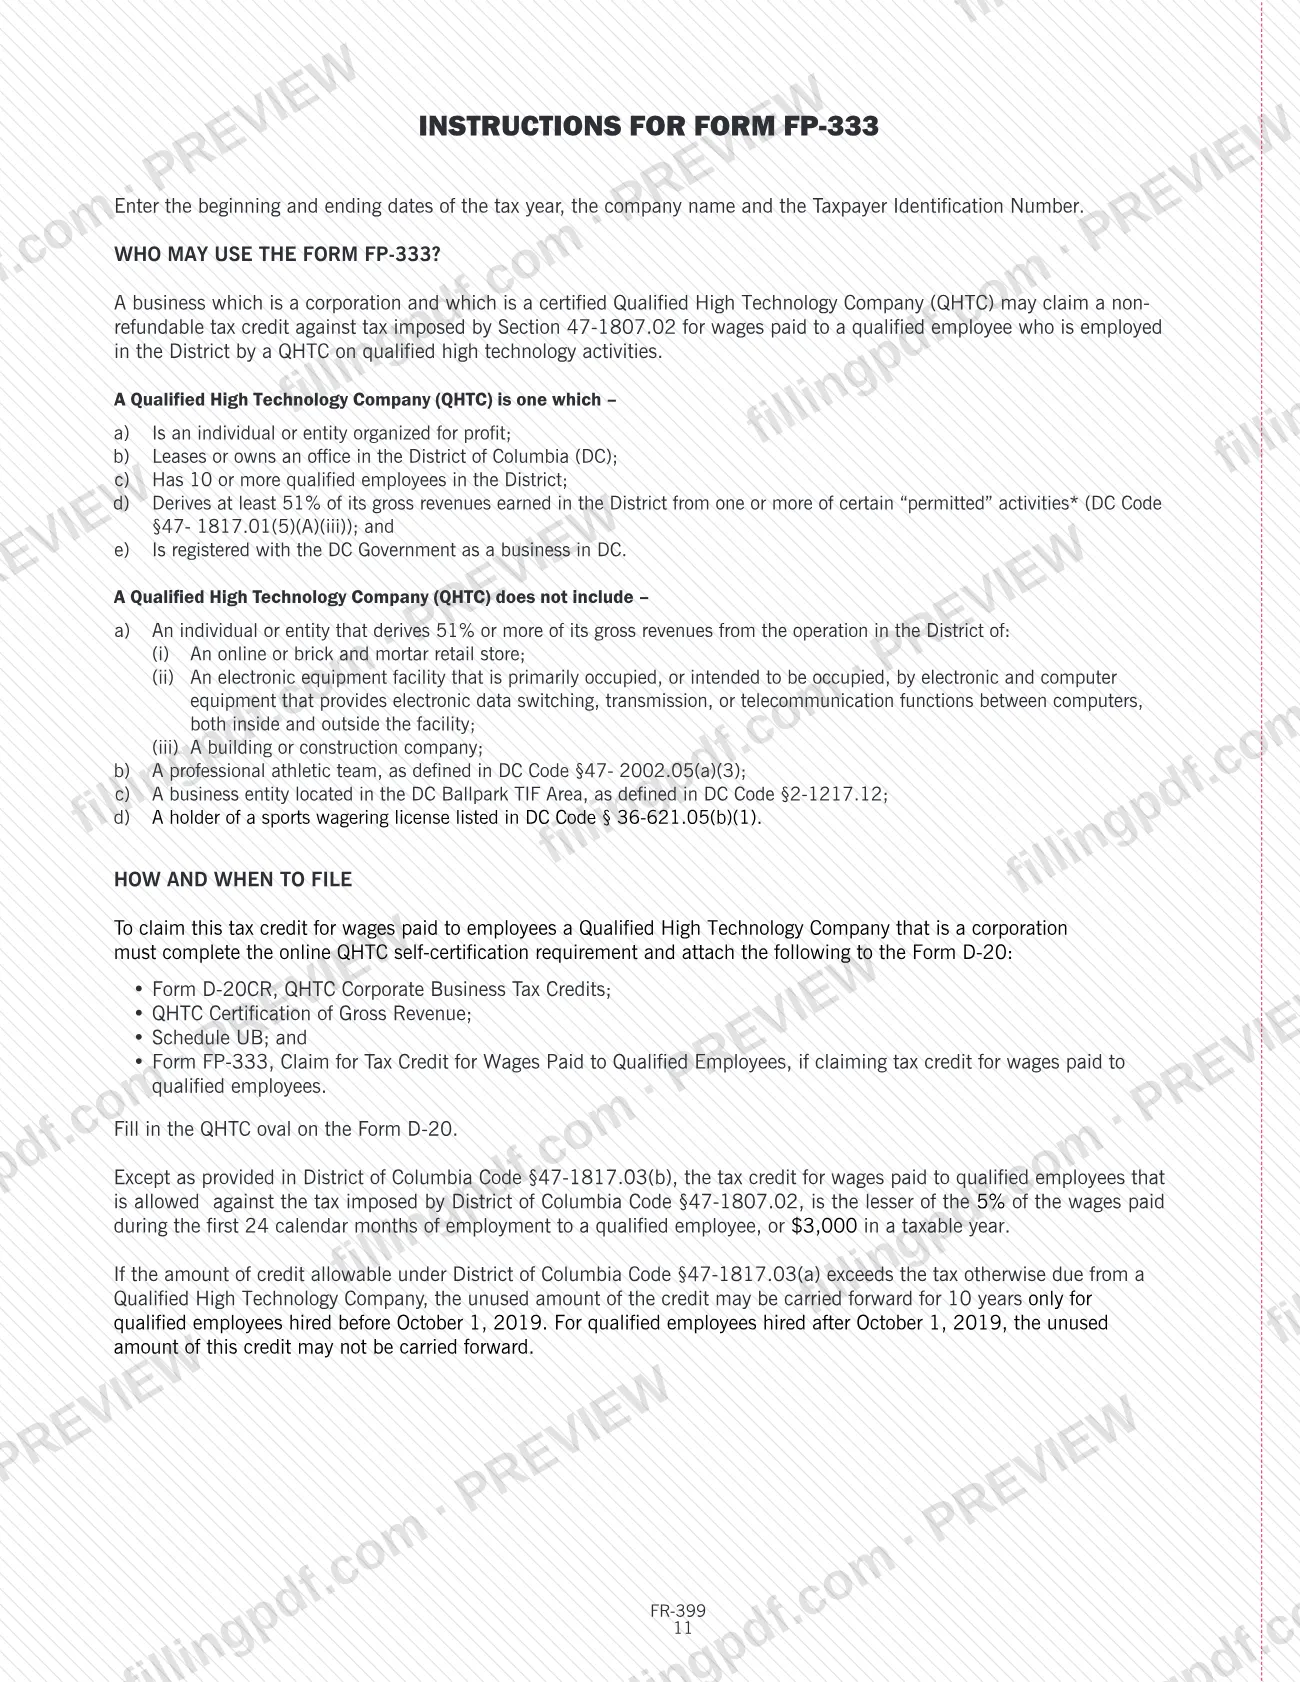
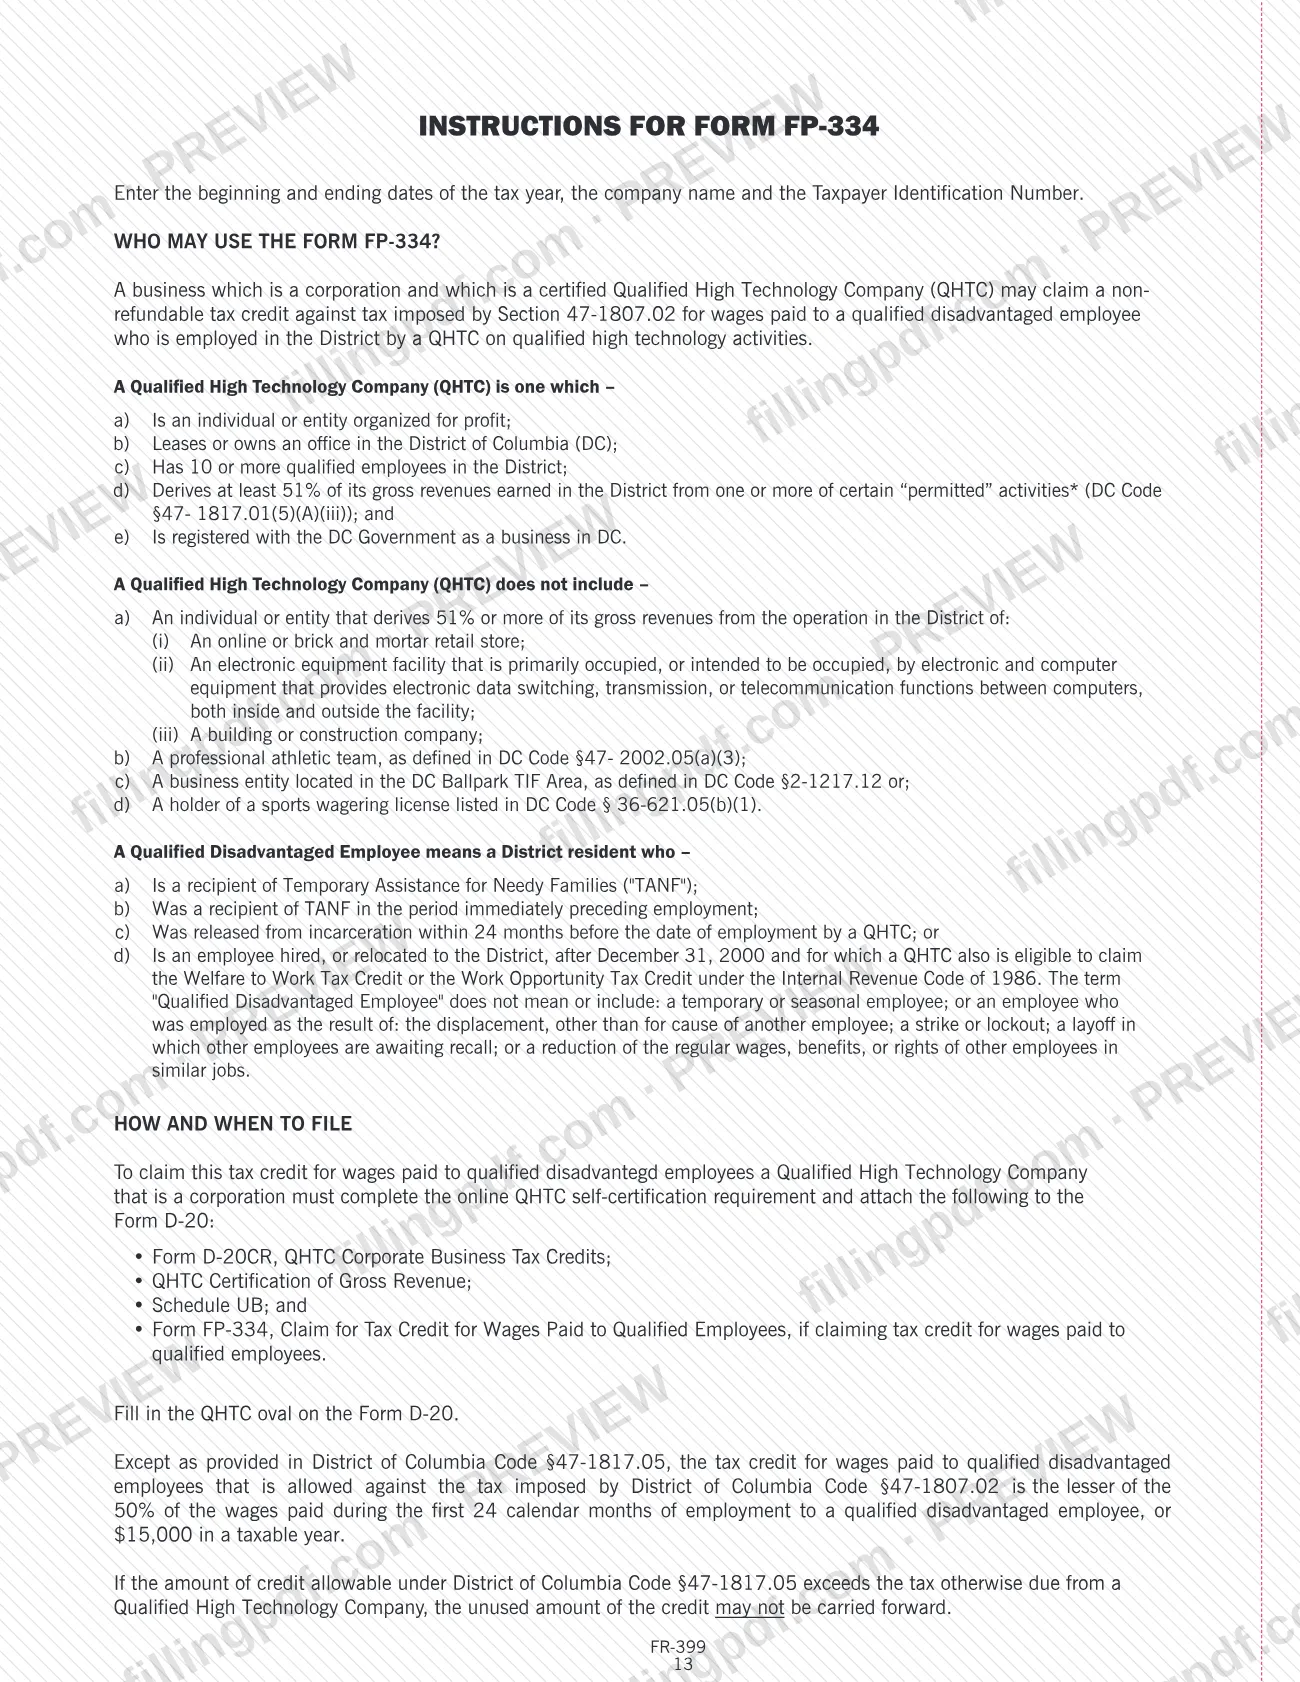
A QHTC is organized for profit, leases or owns an office in the District, has 10 or more qualified employees in DC, derives at least 51% of its gross revenues earned in the District from permitted activities, and is registered with the DC Government as a business.
The booklet excludes:
- a business that derives 51% or more of its gross revenues from operating a retail store (online or brick and mortar), an electronic equipment facility or a building or construction company in the District;
- a professional athletic team;
- a business entity located in the DC Ballpark TIF Area;
- a holder of a sports wagering license listed in DC Code § 36-621.05(b)(1).
Unincorporated QHTCs do not claim the corporate credits. They file a D-65 Partnership Return, or a D-40 Individual Income Tax Return with Federal Schedule C attached.
The online self-certification is completed by an owner, general partner or officer of the business who is authorized to sign.
When to file FR-399
The QHTC Self-Certification must be filed every year to obtain a QHTC certificate of benefits, and the booklet's claim forms are submitted with the tax return that claims the benefit. Corporations attach Form FP-332, FP-333 or FP-334 to Form D-20, together with Form D-20CR, the QHTC Certification of Gross Revenue and Schedule UB. The Certification of Gross Revenue worksheet is filed with Form D-20, D-65 or D-40 with Federal Schedule C. The booklet sets no separate due date; the due date follows the return it accompanies. This revision covers tax years 2021, 2022 and 2023. Carryforward credits cannot be claimed for tax year 2020 or later years, except that unused credit for wages paid to qualified employees may be carried forward for 10 years only for employees hired before October 1, 2019.
Documents you need
- Form D-20, DC Corporate Franchise Tax Return, when an incorporated QHTC claims credits; the QHTC oval on page 1 must be filled in.
- Form D-20CR, QHTC Corporate Business Tax Credits, when a corporate QHTC claims any QHTC tax credit.
- QHTC Certification of Gross Revenue worksheet, filed with Form D-20, D-65, or D-40 with Federal Schedule C.
- Schedule UB from the D-20 booklet, when a corporate QHTC claims a QHTC credit.
- Form FP-332, FP-333 or FP-334, only for the credit being claimed: retraining costs, wages to qualified employees, or wages to qualified disadvantaged employees.
- Form D-65 Partnership Return, or Form D-40 with Federal Schedule C attached, for an unincorporated QHTC.
How to fill out FR-399
Confirm your business is a QHTC
Check the conditions in the booklet: organized for profit, office in the District, 10 or more qualified employees in DC, at least 51% of DC gross revenue from permitted activities, and registered with the DC Government. Make sure none of the exclusions applies.
Complete the online self-certification
An owner, general partner or officer authorized to sign completes the QHTC Self-Certification at MyTax.DC.gov. It is separate from this PDF and must be filed annually.
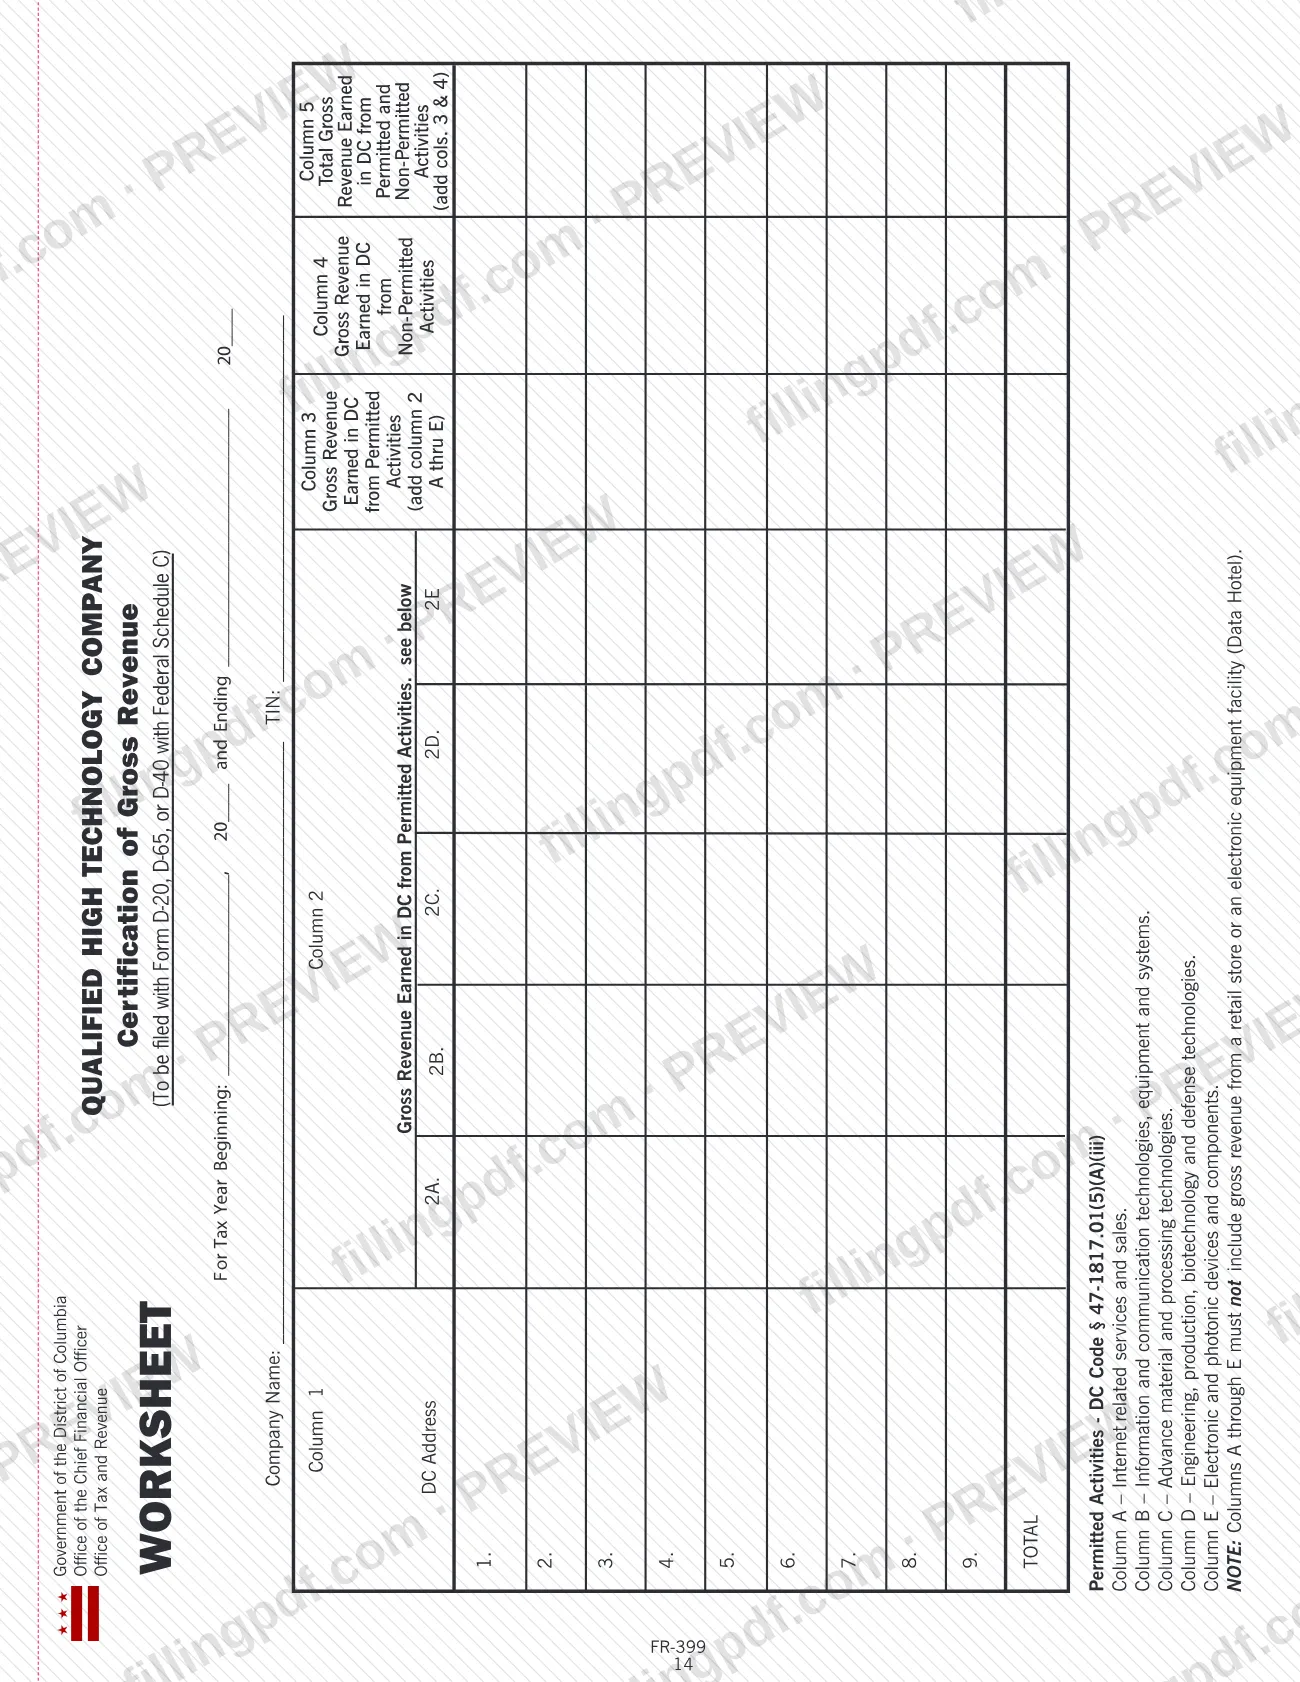
Fill in the Certification of Gross Revenue
Enter the tax year dates, company name and TIN. In column 1 list each DC location; in column 2 enter DC gross revenue by permitted activity (A through E); column 3 totals them, column 4 holds non-permitted revenue, column 5 adds columns 3 and 4.
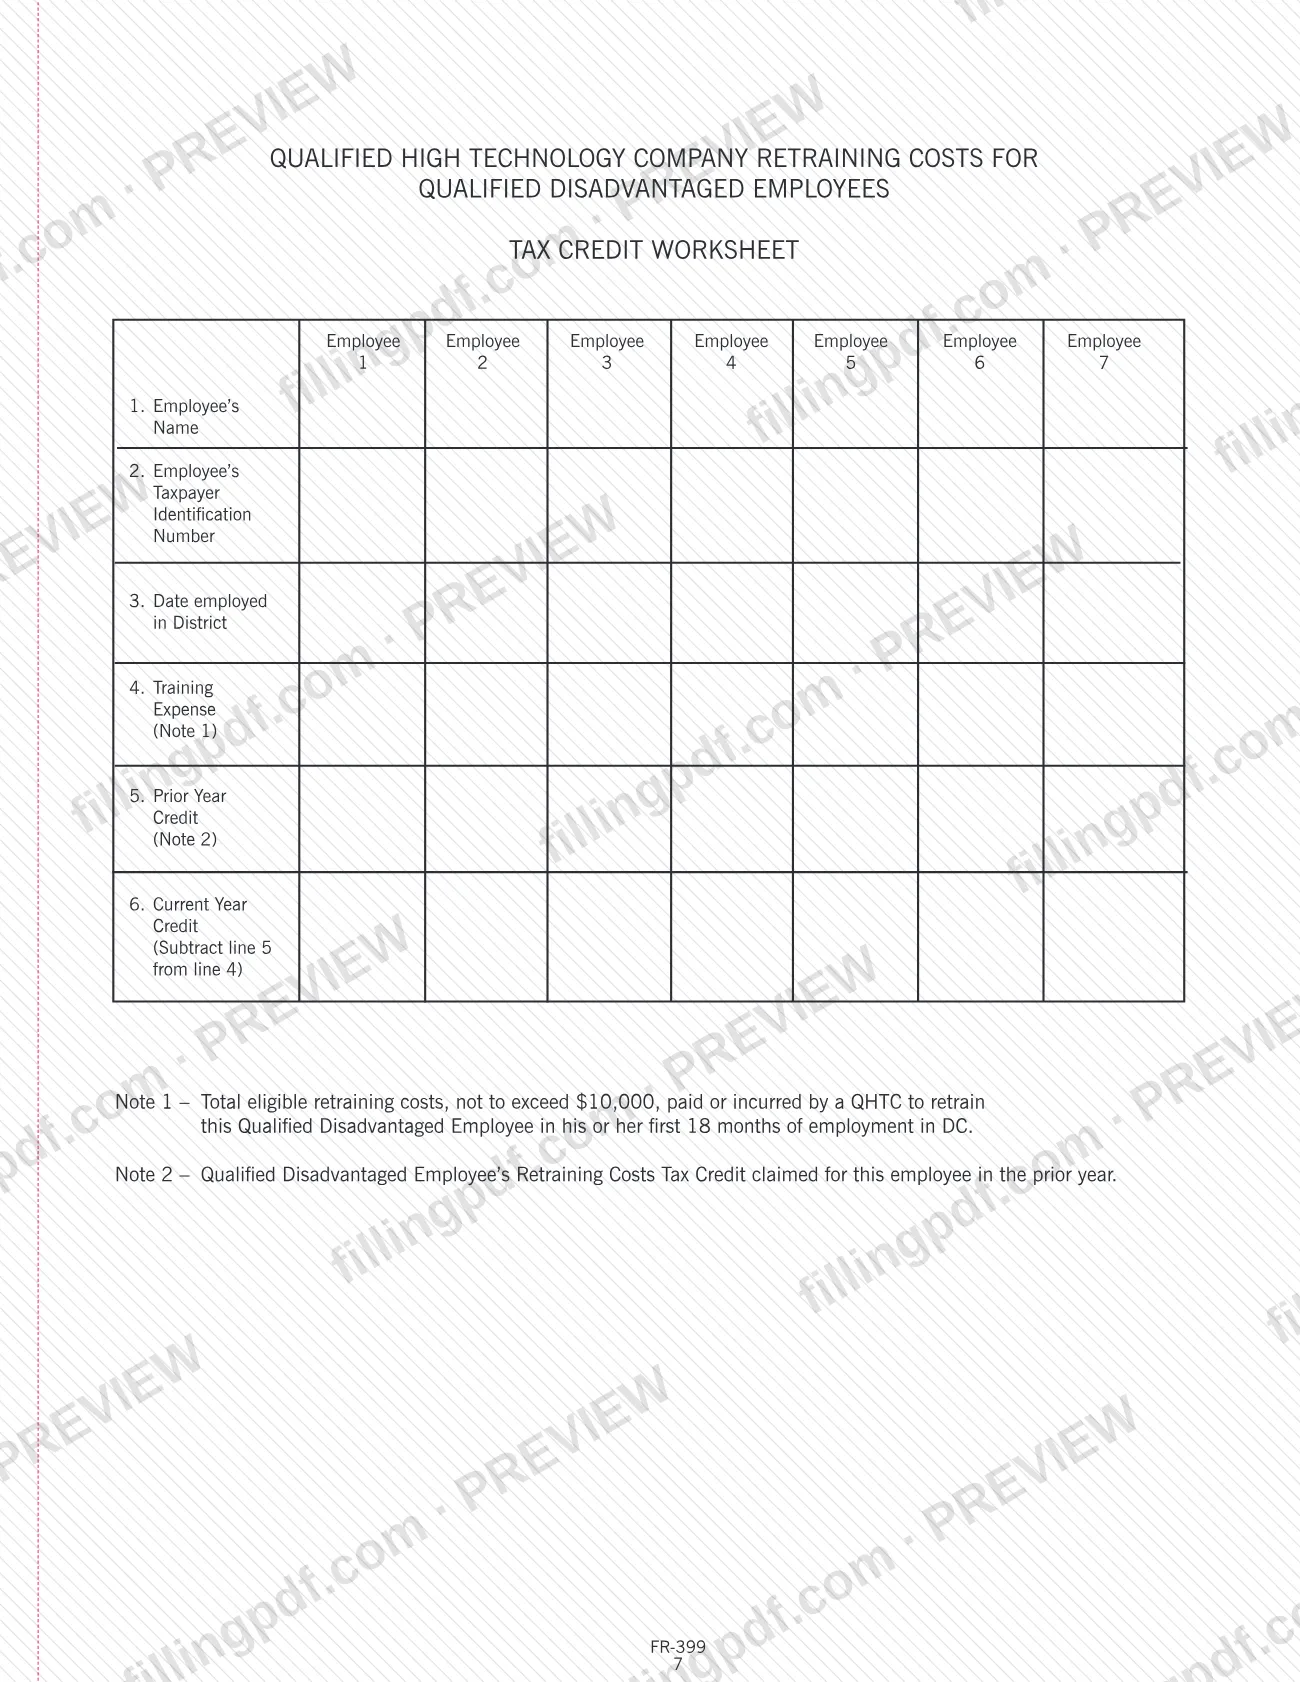
Complete the retraining credit worksheet
On the QHTC retraining worksheet, enter each employee's name, TIN, date employed in the District and training expense, subtract the prior year credit on line 5 from line 4 for the current year credit on line 6.
Complete Form FP-332 for retraining costs
Enter the tax year, company name and TIN. For each employee give name, TIN, date of employment, months employed and retraining costs; Columns C to E give the allowable amount, prior year claim and amount available. Total on lines 12 and 13.
Complete Form FP-333 for qualified employees
For each qualified employee enter name, TIN, date hired, calendar months of the year, and wages paid. Columns C and D apply the form's limits and the QHTC activities employed in the District. Total on line 12 and enter the credit on line 13.
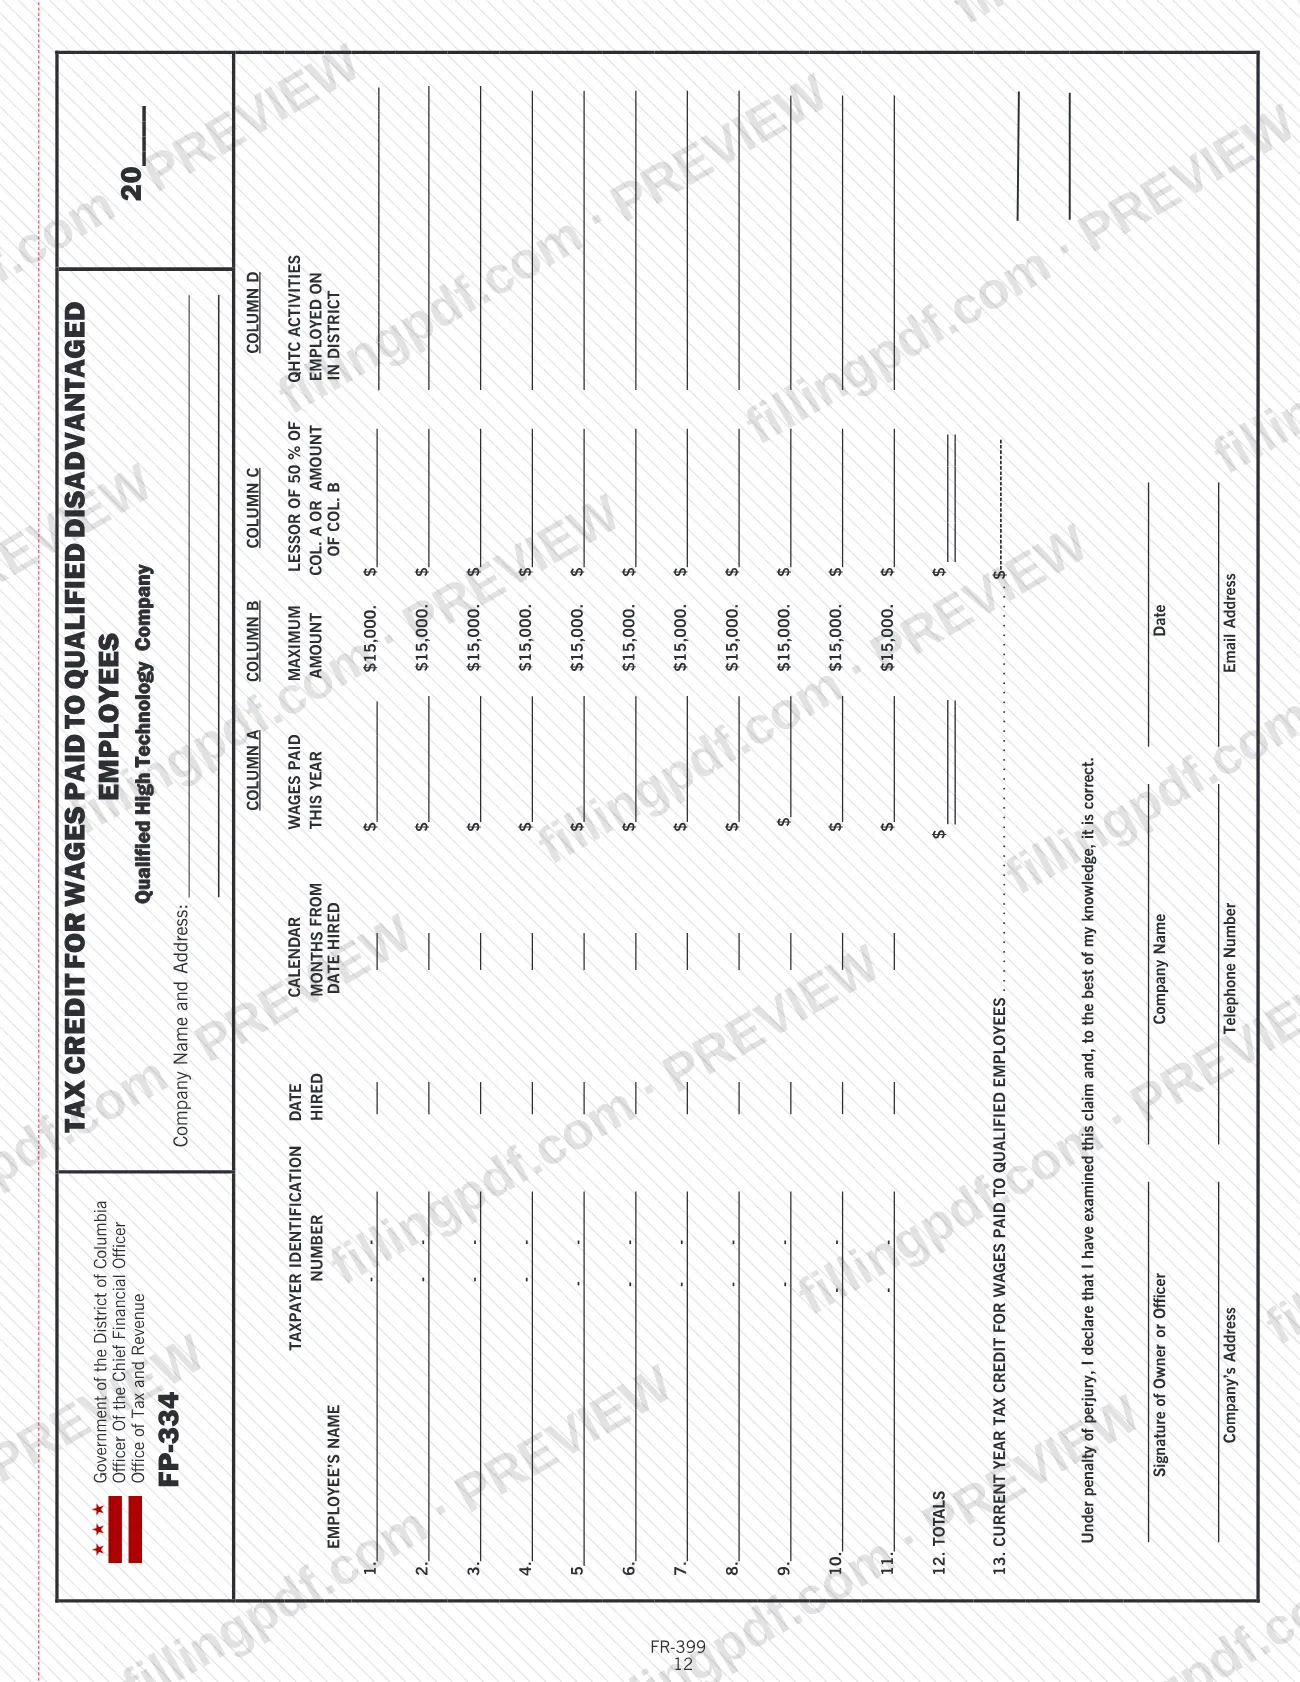
Complete Form FP-334 for disadvantaged employees
For each qualified disadvantaged employee enter name, TIN, date hired, calendar months and wages paid, applying the limits in Column C. Total on line 12 and enter the credit on line 13.
Sign and date each claim form
Each claim form carries a declaration under penalty of perjury. The owner or officer signs, then adds company name, date, address, telephone number and email address.
Attach the package to the return
A corporation attaches Form D-20CR, the Certification of Gross Revenue, Schedule UB and the FP-332, FP-333 or FP-334 it needs to Form D-20, with the QHTC oval filled in.
Review and download the completed PDF
Check names, TINs, dates and totals on every page you used, then download or print the completed PDF from FillingPDF and file it as described under How to submit.
How to submit FR-399
There are two channels: the online self-certification and the tax return the forms accompany.
- Online self-certification: the QHTC Self-Certification can only be submitted online at MyTax.DC.gov, by an owner, general partner or officer authorized to sign. Paper filing of individual "QHTC-CERTs" was replaced by this annual process.
- With the return: a corporation attaches Form D-20CR, the QHTC Certification of Gross Revenue, Schedule UB and the FP-332, FP-333 or FP-334 claim it needs to Form D-20, and fills in the QHTC oval (the "if Certified QHTC" oval on page 1 of Form D-20). An unincorporated QHTC files Form D-65, or Form D-40 with Federal Schedule C, with the Certification of Gross Revenue.
The booklet gives no mailing address of its own; follow the filing instructions in the return booklets (D-20, D-65, D-40) for where and how to file. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Skipping the online QHTC Self-Certification at MyTax.DC.gov; the credit claims require it to be completed first.
- Leaving the "if Certified QHTC" oval on Form D-20 unfilled, so QHTC status is not recognized on the return.
- Claiming a carryforward of the retraining credit or the credit for wages to qualified disadvantaged employees; the carryforward was eliminated.
- Carrying forward unused wages credit for a qualified employee hired on or after October 1, 2019; that carryforward is allowed only for earlier hires.
- Including revenue from a retail store or an electronic equipment facility (data hotel) in columns A through E of the Certification of Gross Revenue worksheet.
- Listing several DC locations on one row of the worksheet; column 1 asks for each location separately.
- Claiming the QHTC personal property tax exemption after July 1, 2021, when it was eliminated.
- Filing as a QHTC when the business draws 51% or more of its DC gross revenue from retail, an electronic equipment facility or construction.
Frequently asked questions
What is Form FR-399 used for?
FR-399 is the OTR booklet for Qualified High Technology Companies for tax years 2021 to 2023. It explains QHTC eligibility and DC tax benefits, and it contains claim forms FP-332, FP-333 and FP-334 and the Certification of Gross Revenue worksheet. It is not a tax return.
Do I file the QHTC self-certification on paper?
No. Since January 1, 2019 the QHTC Self-Certification can only be submitted online at MyTax.DC.gov, by an owner, general partner or officer authorized to sign. It must be filed annually to obtain a QHTC certificate of benefits.
Does a QHTC still get a DC personal property tax exemption?
No. The booklet states that the personal property tax exemption for qualified tangible personal property of a QHTC is no longer available effective July 1, 2021. A reduction in real property tax for qualified leasehold improvements made by or for a QHTC tenant remains listed as a benefit.
What forms do I attach to claim a QHTC credit?
A corporate QHTC attaches Form D-20CR, the QHTC Certification of Gross Revenue, Schedule UB and the matching claim form (FP-332, FP-333 or FP-334) to Form D-20, and fills in the QHTC oval. The self-certification must be completed first.
How many employees does a business need to be a QHTC?
At least 10 qualified employees in the District. This replaced the earlier requirement of 2 for tax years beginning after December 31, 2019. A qualified employee works in DC for the QHTC 35 hours or more per week in a permitted activity.
Can an unincorporated QHTC use Forms FP-332 to FP-334?
No. Those forms are for corporations. An unincorporated QHTC is exempt from the unincorporated business franchise tax but must file a D-65 Partnership Return, or a D-40 with Federal Schedule C attached, and complete the online self-certification.
Can I fill out FR-399 online on FillingPDF?
You can fill out the PDF online on FillingPDF and download or print it. FillingPDF is an independent service: it does not file anything with OTR or complete the MyTax.DC.gov self-certification, so you submit through the agency's channels.
Can I carry forward unused QHTC credits?
Mostly no. The retraining credit and the credit for wages to disadvantaged employees cannot be carried forward. Unused credit for wages to qualified employees may be carried forward for 10 years only for employees hired before October 1, 2019.
Ready to fill out FR-399?
Fill out FR-399 now