
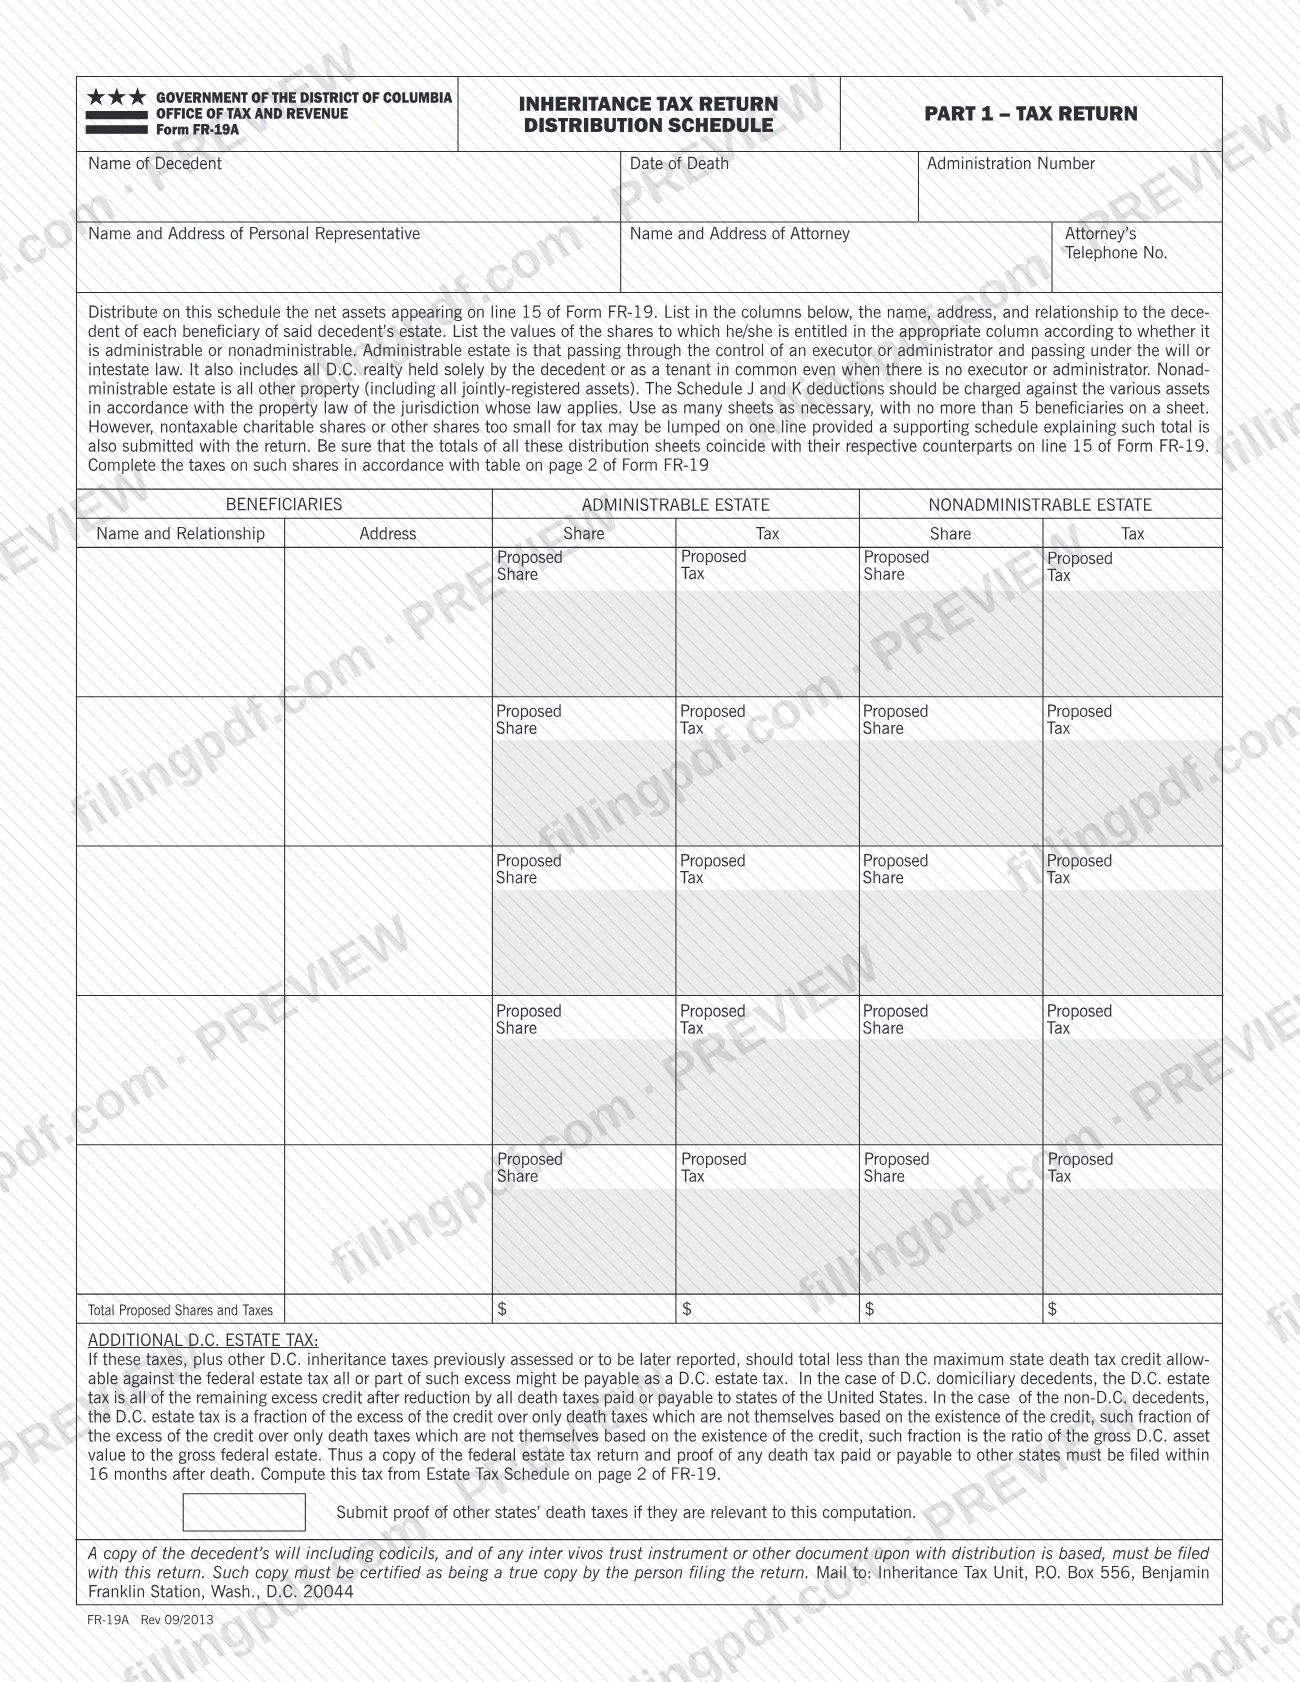
Form FR-19A, the Inheritance Tax Return Distribution Schedule, is the schedule the Government of the District of Columbia's Office of Tax and Revenue (OTR) uses to distribute the net assets shown on line 15 of Form FR-19 among the beneficiaries of a decedent's estate. A personal representative or an attorney fills it in to list each beneficiary, each share and the proposed tax on it. On this page you can fill out the form online on FillingPDF and download or print the completed PDF; the official PDF is published by OTR at otr.cfo.dc.gov.
Last updated
What is FR-19A?
Form FR-19A, Inheritance Tax Return Distribution Schedule, is the District of Columbia Office of Tax and Revenue (OTR) schedule, printed as Part 1 of the tax return, on which the net assets from line 15 of Form FR-19 are assigned to each beneficiary of a decedent's estate, with the proposed tax on each share.
The schedule is built around two kinds of estate property, and every share goes in one column or the other:
- Administrable estate: property passing through the control of an executor or administrator and under the will or intestate law. It also includes all D.C. realty held solely by the decedent or as a tenant in common, even when there is no executor or administrator.
- Nonadministrable estate: all other property, including all jointly-registered assets.
For each beneficiary the form asks for the name, relationship to the decedent and address, then a proposed share and proposed tax in the applicable column. The Schedule J and K deductions are charged against the various assets under the property law of the jurisdiction whose law applies. Taxes on the shares are completed with the table on page 2 of Form FR-19.
The form also explains the additional D.C. estate tax, which is computed from the Estate Tax Schedule on page 2 of Form FR-19, not on this schedule. FR-19A is a companion of Form FR-19 and is not filed on its own.
Who needs to file FR-19A?
The people who prepare the D.C. inheritance tax return for a decedent's estate use Form FR-19A. The form identifies them in its header: the personal representative and the attorney, whose names, addresses and the attorney's telephone number are entered at the top. It tells the filer to distribute on this schedule the net assets appearing on line 15 of Form FR-19, so anyone completing Form FR-19 for an estate completes FR-19A as well.
Conditions the form attaches:
- If the estate has more than 5 beneficiaries, use as many sheets as necessary, with no more than 5 beneficiaries on a sheet.
- Nontaxable charitable shares, and other shares too small for tax, may be lumped on one line, provided a supporting schedule explaining the total is submitted with the return.
- For the additional D.C. estate tax, the form distinguishes D.C. domiciliary decedents from non-D.C. decedents; the computation is made on page 2 of Form FR-19.
The form names no group excused from using it. The person filing the return is the one who certifies the copy of the will and of any trust instrument as a true copy.
When to file FR-19A
Form FR-19A is completed and submitted with the D.C. inheritance tax return, Form FR-19; the form says the copy of the will, codicils and any trust instrument must be filed with this return. No separate due date for the schedule itself is printed on it.
One time limit is stated: a copy of the federal estate tax return and proof of any death tax paid or payable to other states must be filed within 16 months after death. These items bear on the additional D.C. estate tax, which is figured from the Estate Tax Schedule on page 2 of Form FR-19.
Before filing, check that the totals of all distribution sheets coincide with their counterparts on line 15 of Form FR-19. For the due date of the inheritance tax return itself, consult the OTR instructions for Form FR-19.
Documents you need
- Copy of the decedent's will, including codicils, certified as a true copy by the person filing the return; the form says it must be filed with the return.
- Copy of any inter vivos trust instrument or other document on which distribution is based, certified as a true copy by the person filing the return.
- Supporting schedule explaining the total, only if you lump nontaxable charitable shares or shares too small for tax on one line.
- Proof of other states' death taxes, only if relevant to the computation of the additional D.C. estate tax.
- Copy of the federal estate tax return, to be filed within 16 months after death.
- Additional distribution sheets, only if the estate has more than 5 beneficiaries; each sheet holds no more than 5.
How to fill out FR-19A
Enter the decedent's details
At the top, enter the Name of Decedent, the Date of Death and the Administration Number.
Enter representative and attorney
Give the name and address of the personal representative, then the name and address of the attorney and the attorney's telephone number.
Sort assets by estate type
Decide for each asset whether it is administrable estate (passing through an executor or administrator, plus D.C. realty held solely or as a tenant in common) or nonadministrable estate (all other property, including jointly-registered assets).
List each beneficiary
In the Beneficiaries columns, enter each beneficiary's name and relationship to the decedent, and the address. Use no more than 5 beneficiaries per sheet and add sheets as needed.
Enter administrable shares and taxes
In the Administrable Estate columns, enter the proposed share and the proposed tax for each beneficiary entitled to administrable property.
Enter nonadministrable shares and taxes
In the Nonadministrable Estate columns, enter the proposed share and proposed tax for each beneficiary entitled to nonadministrable property.
Apply the tax table and deductions
Complete the taxes on the shares using the table on page 2 of Form FR-19. Charge the Schedule J and K deductions against the assets under the property law of the jurisdiction whose law applies.
Lump small or charitable shares
If you combine nontaxable charitable shares or shares too small for tax on one line, prepare a supporting schedule explaining the total and submit it with the return.
Complete the totals line
On the line Total Proposed Shares and Taxes, enter the totals for each of the four columns. Check that the totals of all sheets coincide with their counterparts on line 15 of Form FR-19.
Address the additional D.C. estate tax
If other D.C. inheritance taxes total less than the maximum state death tax credit allowable against the federal estate tax, compute the additional tax from the Estate Tax Schedule on page 2 of Form FR-19 and gather proof of other states' death taxes if relevant.
Review and download the completed PDF
Check every beneficiary, share and total, then download or print the completed PDF from FillingPDF. Assemble the will copy and other attachments described under How to submit.
How to submit FR-19A
The form names one channel, mail. Mail the completed return, with Form FR-19A and its attachments, to: Inheritance Tax Unit, P.O. Box 556, Benjamin Franklin Station, Wash., D.C. 20044.
The package must contain:
- The distribution sheets, with no more than 5 beneficiaries on each sheet.
- A copy of the decedent's will, including codicils, and of any inter vivos trust instrument or other document on which distribution is based, certified as a true copy by the person filing the return.
- A supporting schedule, if you lumped nontaxable charitable shares or shares too small for tax on one line.
- Proof of other states' death taxes, if relevant to the computation of the additional D.C. estate tax.
- A copy of the federal estate tax return, filed within 16 months after death.
The form prints no portal, fee, appointment rule or telephone number for submission. Contact OTR through otr.cfo.dc.gov for anything it does not cover. FillingPDF lets you fill out and download the PDF; submission follows the channel above.
Common mistakes to avoid
- Listing more than 5 beneficiaries on one sheet instead of using additional sheets.
- Submitting distribution totals that do not coincide with the counterparts on line 15 of Form FR-19.
- Lumping charitable or very small shares on one line without a supporting schedule explaining the total.
- Placing jointly-registered assets in the administrable column; the form defines them as nonadministrable estate.
- Leaving out D.C. realty held solely by the decedent or as a tenant in common from the administrable estate, even when there is no executor or administrator.
- Sending a copy of the will or trust instrument that the person filing has not certified as a true copy.
- Omitting proof of other states' death taxes when it is relevant to the additional D.C. estate tax computation.
- Filing the copy of the federal estate tax return later than 16 months after death.
- Computing the tax on shares without using the table on page 2 of Form FR-19.
Frequently asked questions
What is Form FR-19A used for?
Form FR-19A is the Distribution Schedule of the D.C. inheritance tax return. It distributes the net assets shown on line 15 of Form FR-19 among the decedent's beneficiaries, with each beneficiary's name, relationship, address, proposed share and proposed tax.
Is Form FR-19A a DC property tax form?
No. FR-19A belongs to the D.C. inheritance tax return filed with the Office of Tax and Revenue. D.C. realty appears on it only as part of the estate: realty held solely by the decedent or as a tenant in common counts as administrable estate.
What is the difference between administrable and nonadministrable estate?
Administrable estate passes through an executor or administrator under the will or intestate law, and includes D.C. realty held solely or as a tenant in common. Nonadministrable estate is all other property, including all jointly-registered assets.
How many beneficiaries fit on one FR-19A sheet?
No more than 5 beneficiaries per sheet. For more, use as many sheets as necessary. Nontaxable charitable shares or shares too small for tax may be lumped on one line if a supporting schedule explaining the total is submitted.
Where do I mail Form FR-19A?
Mail it with the inheritance tax return to Inheritance Tax Unit, P.O. Box 556, Benjamin Franklin Station, Wash., D.C. 20044. That is the only channel printed on the form.
What must I attach to Form FR-19A?
Attach a copy of the will, including codicils, and of any inter vivos trust instrument or other document on which distribution is based, certified as a true copy by the person filing. Add a supporting schedule for lumped shares and proof of other states' death taxes if relevant.
What is the 16-month deadline on Form FR-19A?
A copy of the federal estate tax return and proof of any death tax paid or payable to other states must be filed within 16 months after death. They support the additional D.C. estate tax, computed from the Estate Tax Schedule on page 2 of Form FR-19.
Can I fill out Form FR-19A online?
You can fill out the PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the form with OTR; you mail the completed return to the Inheritance Tax Unit yourself.
Ready to fill out FR-19A?
Fill out FR-19A now