
ROD 8 - Exemptions (Transfer Tax) is a DC Office of Tax and Revenue (OTR) publication that lists the transfers of real property exempt from the District's transfer tax. It is one of the DC property tax materials OTR publishes, and it matters to anyone recording a deed for a family, trust, estate, divorce, nonprofit or government transfer. On this page you can fill out the form online on FillingPDF and download or print the completed PDF; the original is published by OTR at the official link.
Last updated
What is ROD 8?
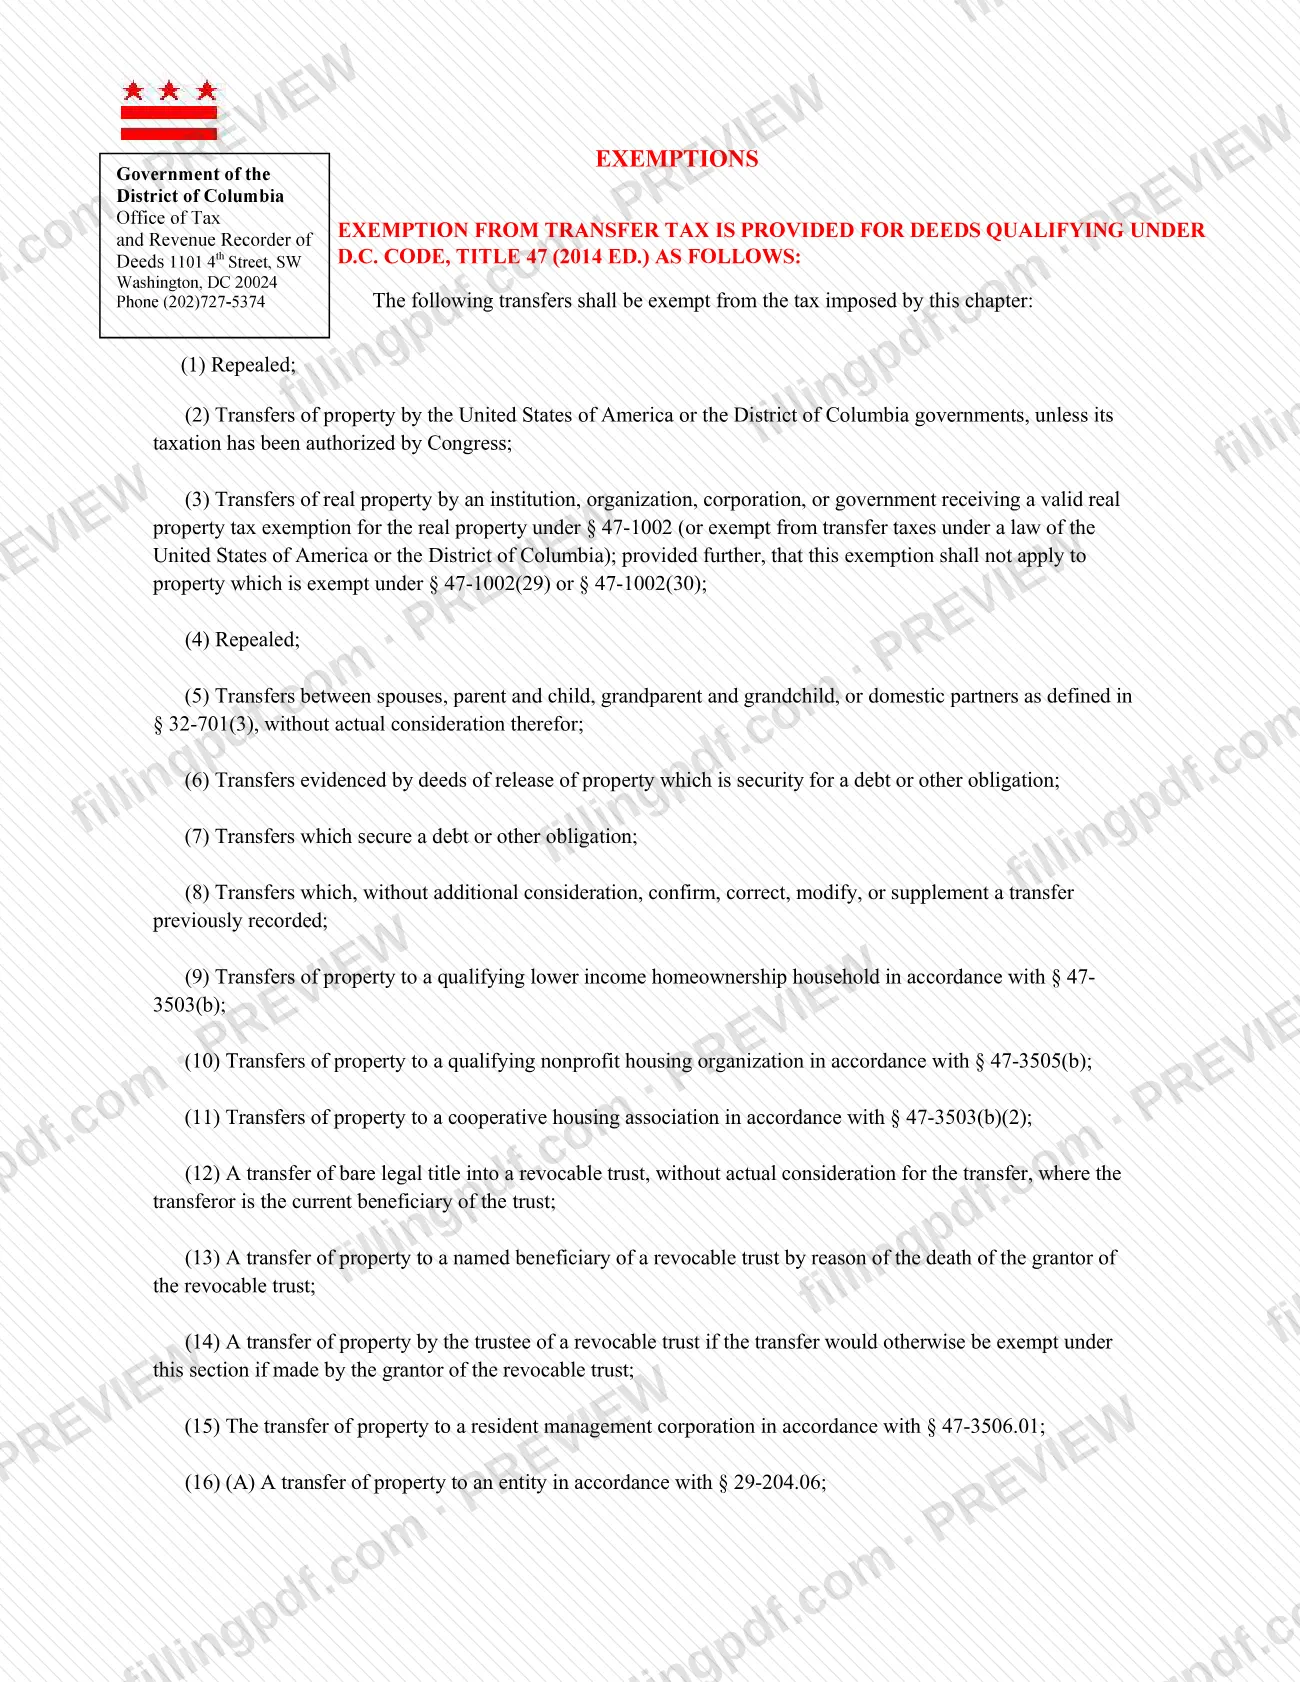
ROD 8 - Exemptions (Transfer Tax) is the DC Office of Tax and Revenue (OTR) document that sets out which transfers are exempt from the District of Columbia's transfer tax on real property, numbering each exemption as a separate paragraph.
The text opens with the rule that the listed transfers are exempt from the tax. Paragraphs (1) and (4) are marked repealed. The paragraphs that remain cover, among others:
- transfers by the United States or District governments, and by exempt institutions, organizations, corporations or governments (paragraphs 2, 3 and 21);
- transfers without actual consideration between spouses, parent and child, grandparent and grandchild, or domestic partners (paragraph 5);
- deeds of release, transfers that secure a debt, and transfers that confirm, correct, modify or supplement a prior recorded transfer without additional consideration (paragraphs 6 to 8);
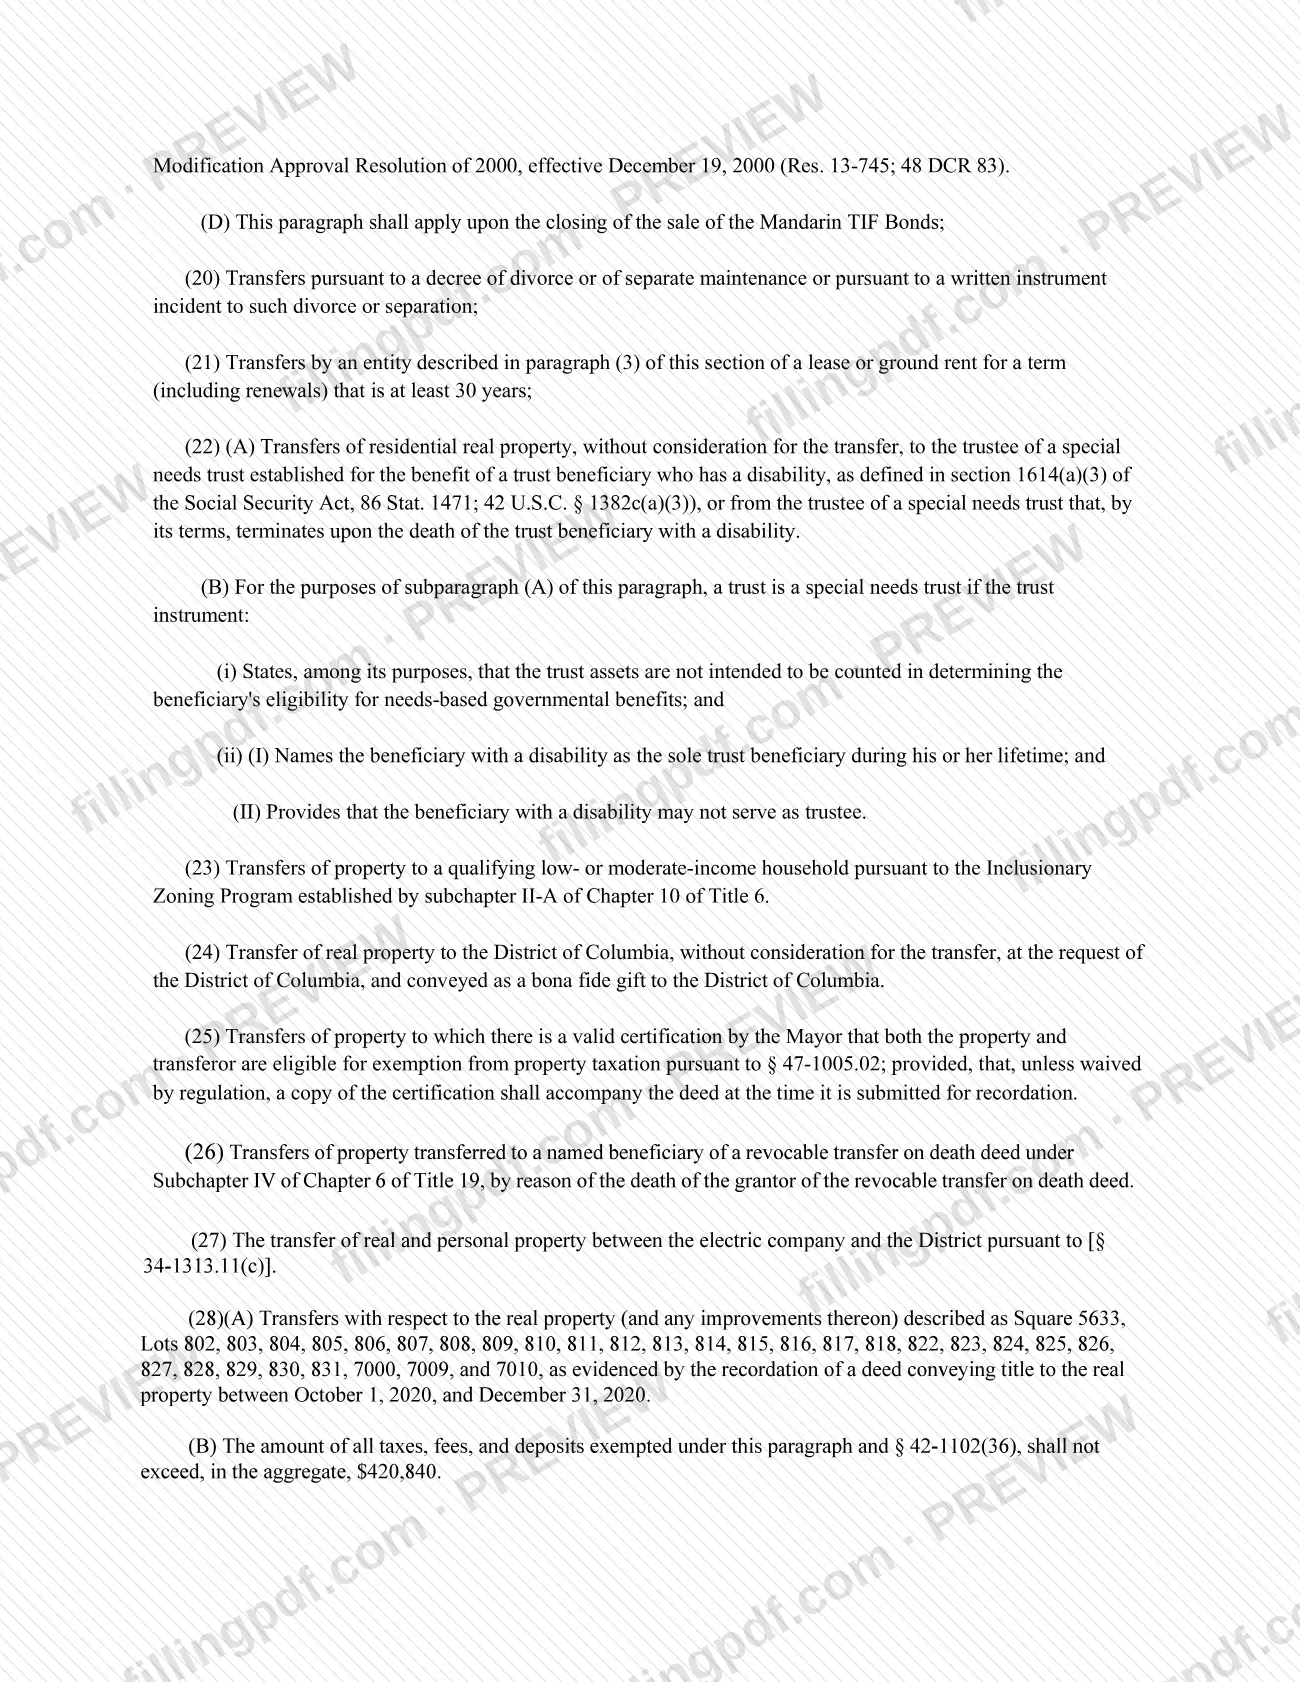
- transfers into, out of and by revocable trusts (paragraphs 12 to 14) and to special needs trusts (paragraph 22);
- deeds of personal representatives of decedents (paragraph 18) and transfers under a divorce or separate maintenance decree (paragraph 20);
- transfers tied to housing programs, such as qualifying lower income homeownership households, nonprofit housing organizations, cooperative housing associations, resident management corporations and the Inclusionary Zoning Program (paragraphs 9, 10, 11, 15 and 23);
- transfers of property certified by the Mayor as eligible for property tax exemption (paragraph 25).
Several paragraphs apply to named properties or projects. The document is a list of exemptions and their conditions; it does not compute any tax.
Who needs to file ROD 8?
Anyone who is recording a transfer of real property in the District of Columbia and believes it falls under one of the listed exemptions should review ROD 8 to find the paragraph that fits.
The groups and conditions the text names include:
- Family and domestic partner transfers: spouses, parent and child, grandparent and grandchild, or domestic partners as defined in § 32-701(3), but only when there is no actual consideration (paragraph 5).
- Revocable trusts: transfers of bare legal title into a revocable trust without actual consideration when the transferor is the current beneficiary; transfers to a named beneficiary on the grantor's death; and transfers by the trustee that would be exempt if made by the grantor (paragraphs 12 to 14).
- Estates: personal representatives transferring a decedent's real property or life estate to a distributee without additional consideration (paragraph 18).
- Divorce or separation: transfers under a decree or a written instrument incident to it (paragraph 20).
- Special needs trusts: residential real property transferred without consideration, where the trust meets the conditions in paragraph 22.
- Government, exempt entities and nonprofit housing groups, as described in paragraphs 2, 3, 10, 11, 15, 21 and 24.
Paragraph 3 does not apply to property exempt under § 47-1002(29) or § 47-1002(30). Transfers for consideration are outside the family and trust exemptions that require none.
When to file ROD 8
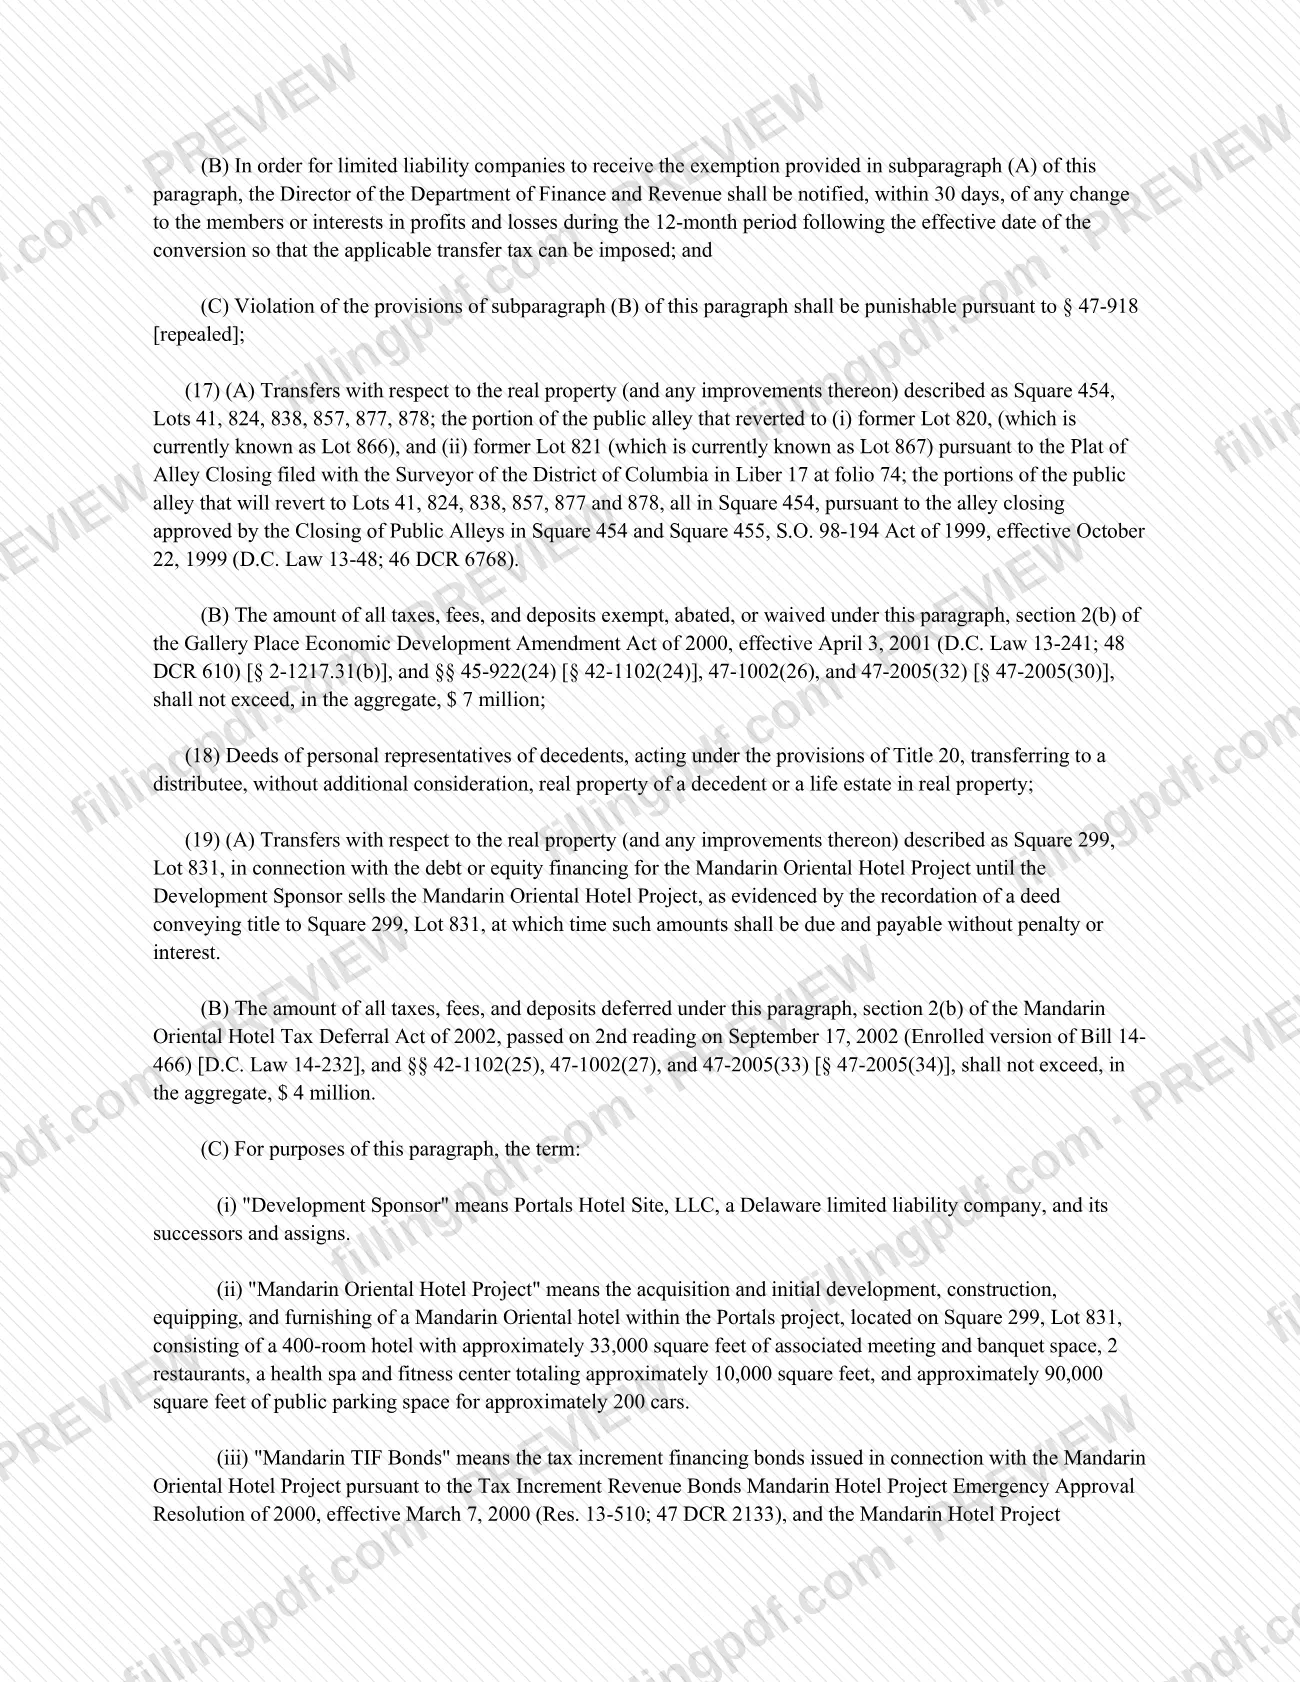
The triggering event is a transfer of real property that you intend to treat as exempt; the document prints no filing deadline of its own. Two paragraphs carry timing rules. Under paragraph 16, a limited liability company that receives the exemption for a conversion must notify the Director of the Department of Finance and Revenue within 30 days of any change to the members or interests in profits and losses during the 12-month period after the effective date of the conversion, so the applicable transfer tax can be imposed. Under paragraph 25, a copy of the Mayor's certification must accompany the deed at the time it is submitted for recordation, unless waived by regulation. Under paragraph 19, deferred amounts for the named hotel project become due, without penalty or interest, when a deed conveying title to Square 299, Lot 831 is recorded.
Documents you need
- A copy of the Mayor's certification that both the property and the transferor are eligible for exemption from property taxation, for a transfer claimed under paragraph (25); it accompanies the deed when submitted for recordation, unless waived by regulation.
How to fill out ROD 8
Open the exemption list
Read the opening statement that the listed transfers are exempt from the transfer tax, then go through the numbered paragraphs (1) to (25).
Skip the repealed paragraphs
Paragraphs (1) and (4) are marked Repealed and cannot support an exemption.
Match your transfer to a paragraph
Identify the paragraph that describes your transfer, such as (5) for family and domestic partner transfers, (12) to (14) for revocable trusts, (18) for personal representatives or (20) for divorce.
Check the conditions in that paragraph
Confirm each condition it states, such as no actual consideration in (5) and (12), no additional consideration in (8) and (18), or the trust terms in (22).
Check entity and program exemptions
For government, exempt-entity or housing transfers, read paragraphs (2), (3), (9) to (11), (15), (21), (23) and (24) for who qualifies and any exclusions.
Prepare the certification if required
For paragraph (25), obtain a copy of the Mayor's certification to accompany the deed, unless waived by regulation.
Review and download the completed PDF
Check that the paragraph you rely on matches the transfer, then download or print the completed PDF from FillingPDF and keep it with the deed documents.
How to submit ROD 8
ROD 8 names no mailing address, portal or office of its own, so there is no separate channel for the form itself; it is a reference to the exemptions that apply when a transfer is recorded.
- With the deed: for paragraph (25), a copy of the Mayor's certification that both the property and the transferor are eligible for exemption from property taxation must accompany the deed when it is submitted for recordation, unless waived by regulation.
- Notice for LLC conversions: under paragraph (16)(B), notify the Director of the Department of Finance and Revenue within 30 days of any change to the members or interests in profits and losses during the 12 months after the conversion's effective date.
- Questions: OTR publishes the document at https://otr.cfo.dc.gov/publication/rod-8-exemptions-transfer-tax; contact OTR through its website for filing details not printed on the form.
FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Claiming the spouse, parent and child, grandparent and grandchild, or domestic partner exemption when actual consideration is paid; paragraph (5) covers only transfers without it.
- Relying on paragraph (1) or (4), which are marked repealed.
- Submitting a paragraph (25) deed without a copy of the Mayor's certification, unless a regulation waives it.
- Using the revocable trust exemption for a transfer in which the transferor is not the current beneficiary, or for which consideration is given (paragraph 12).
- Applying paragraph (3) to property exempt under § 47-1002(29) or § 47-1002(30), which the paragraph excludes.
- Treating a special needs trust as qualifying when the beneficiary may serve as trustee or is not the sole lifetime beneficiary (paragraph 22).
- Failing to notify the Director within 30 days of a change in LLC members or profit interests during the 12 months after a conversion (paragraph 16).
- Claiming paragraph (8) for a corrective or confirming deed that carries additional consideration.
Frequently asked questions
What is ROD 8 - Exemptions (Transfer Tax)?
It is a DC Office of Tax and Revenue (OTR) document listing the transfers of real property exempt from the District's transfer tax. Each exemption is a numbered paragraph with its own conditions, such as no actual consideration or a required certification.
Are transfers between spouses exempt from DC transfer tax?
Yes, under paragraph (5), transfers between spouses, parent and child, grandparent and grandchild, or domestic partners are exempt, but only when made without actual consideration. If consideration is paid, this paragraph does not apply.
Is putting my home into a revocable trust exempt?
Paragraph (12) exempts a transfer of bare legal title into a revocable trust, without actual consideration, where the transferor is the current beneficiary of the trust. Paragraphs (13) and (14) cover transfers on the grantor's death and by the trustee.
Are transfers under a divorce exempt?
Yes. Paragraph (20) exempts transfers made under a decree of divorce or of separate maintenance, or under a written instrument incident to the divorce or separation.
Do I need to attach a certification for the paragraph (25) exemption?
Yes, unless waived by regulation. For a transfer certified by the Mayor as eligible for property tax exemption, a copy of the certification must accompany the deed when it is submitted for recordation.
Do LLCs have to notify anyone after a conversion?
For the paragraph (16) exemption, the Director of the Department of Finance and Revenue must be notified within 30 days of any change to members or interests in profits and losses during the 12 months after the conversion's effective date.
Can I fill out ROD 8 online?
You can fill out the PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file anything with OTR or record your deed; you follow the agency's channels.
Ready to fill out ROD 8?
Fill out ROD 8 now