
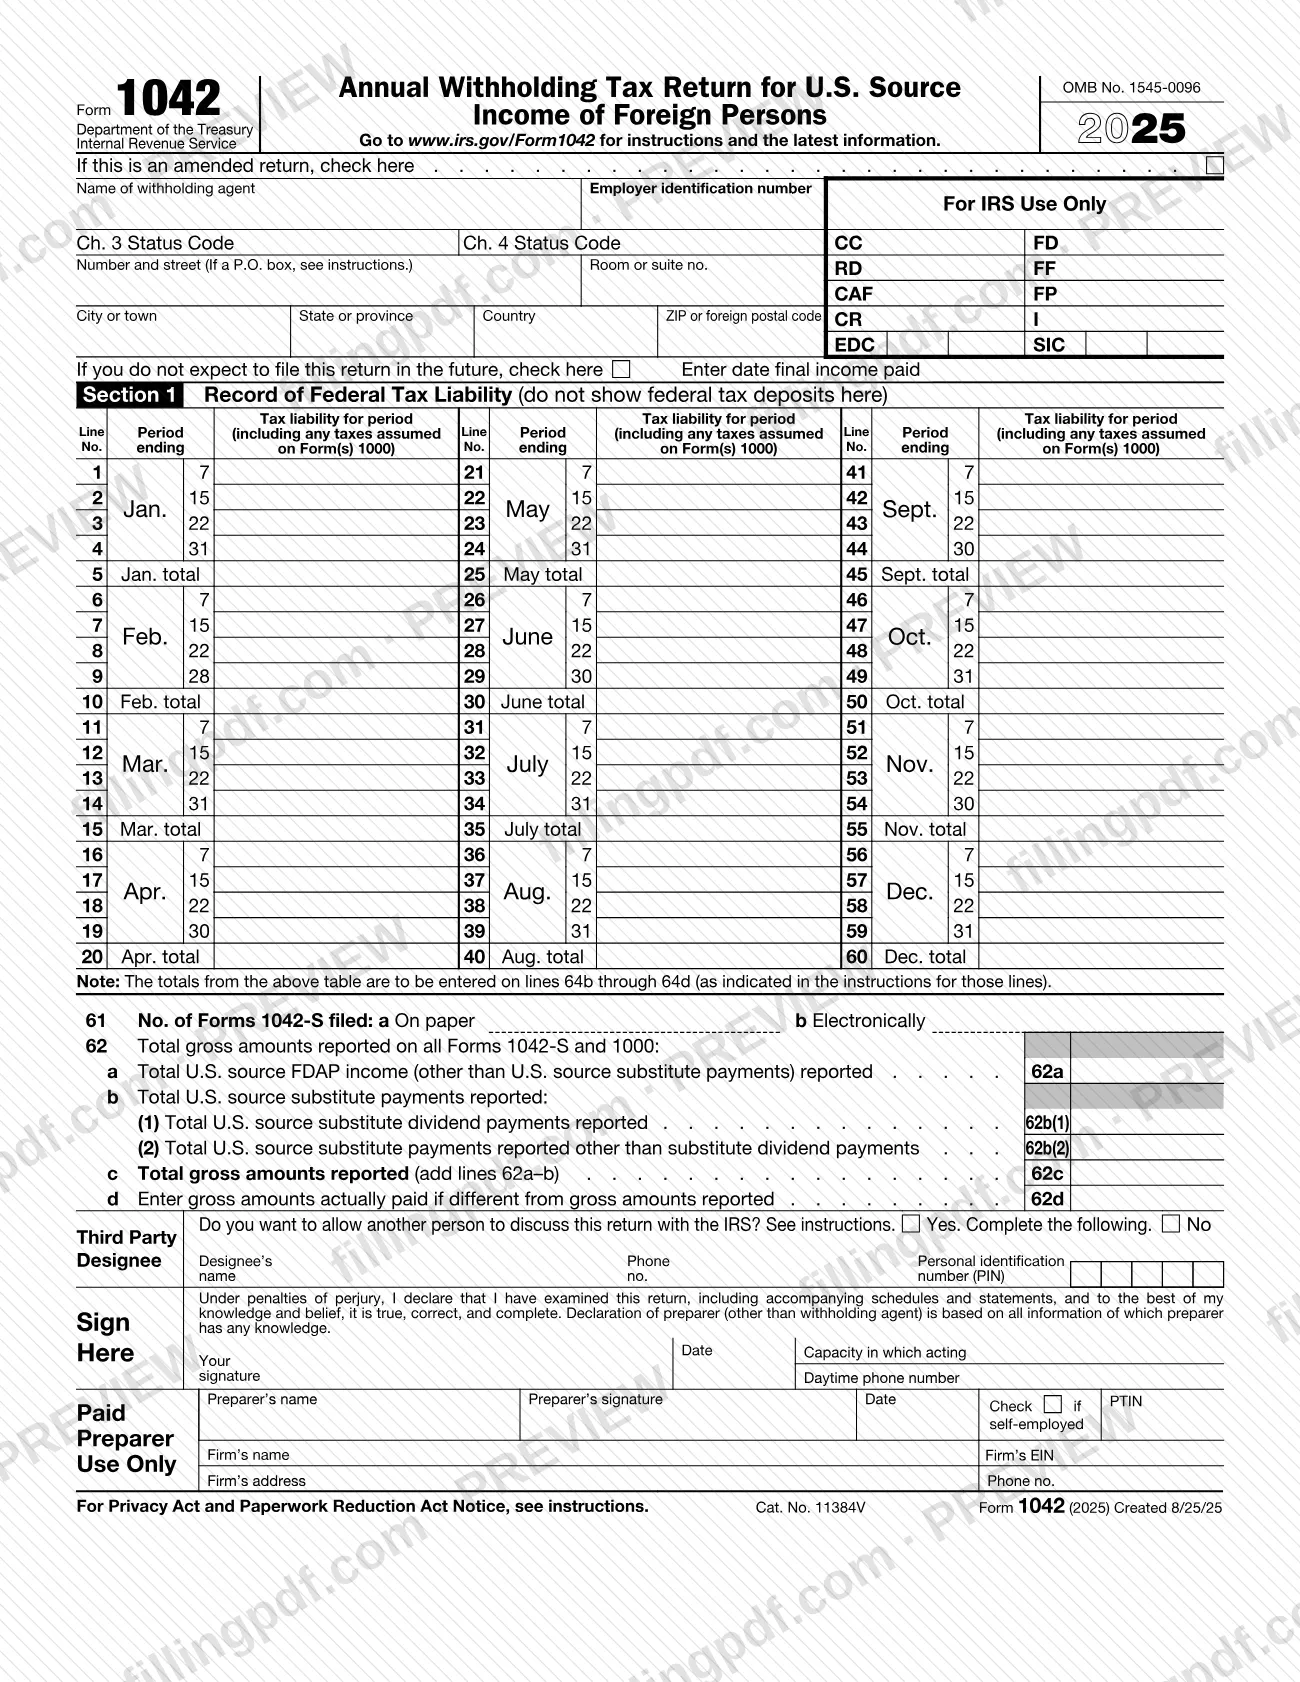
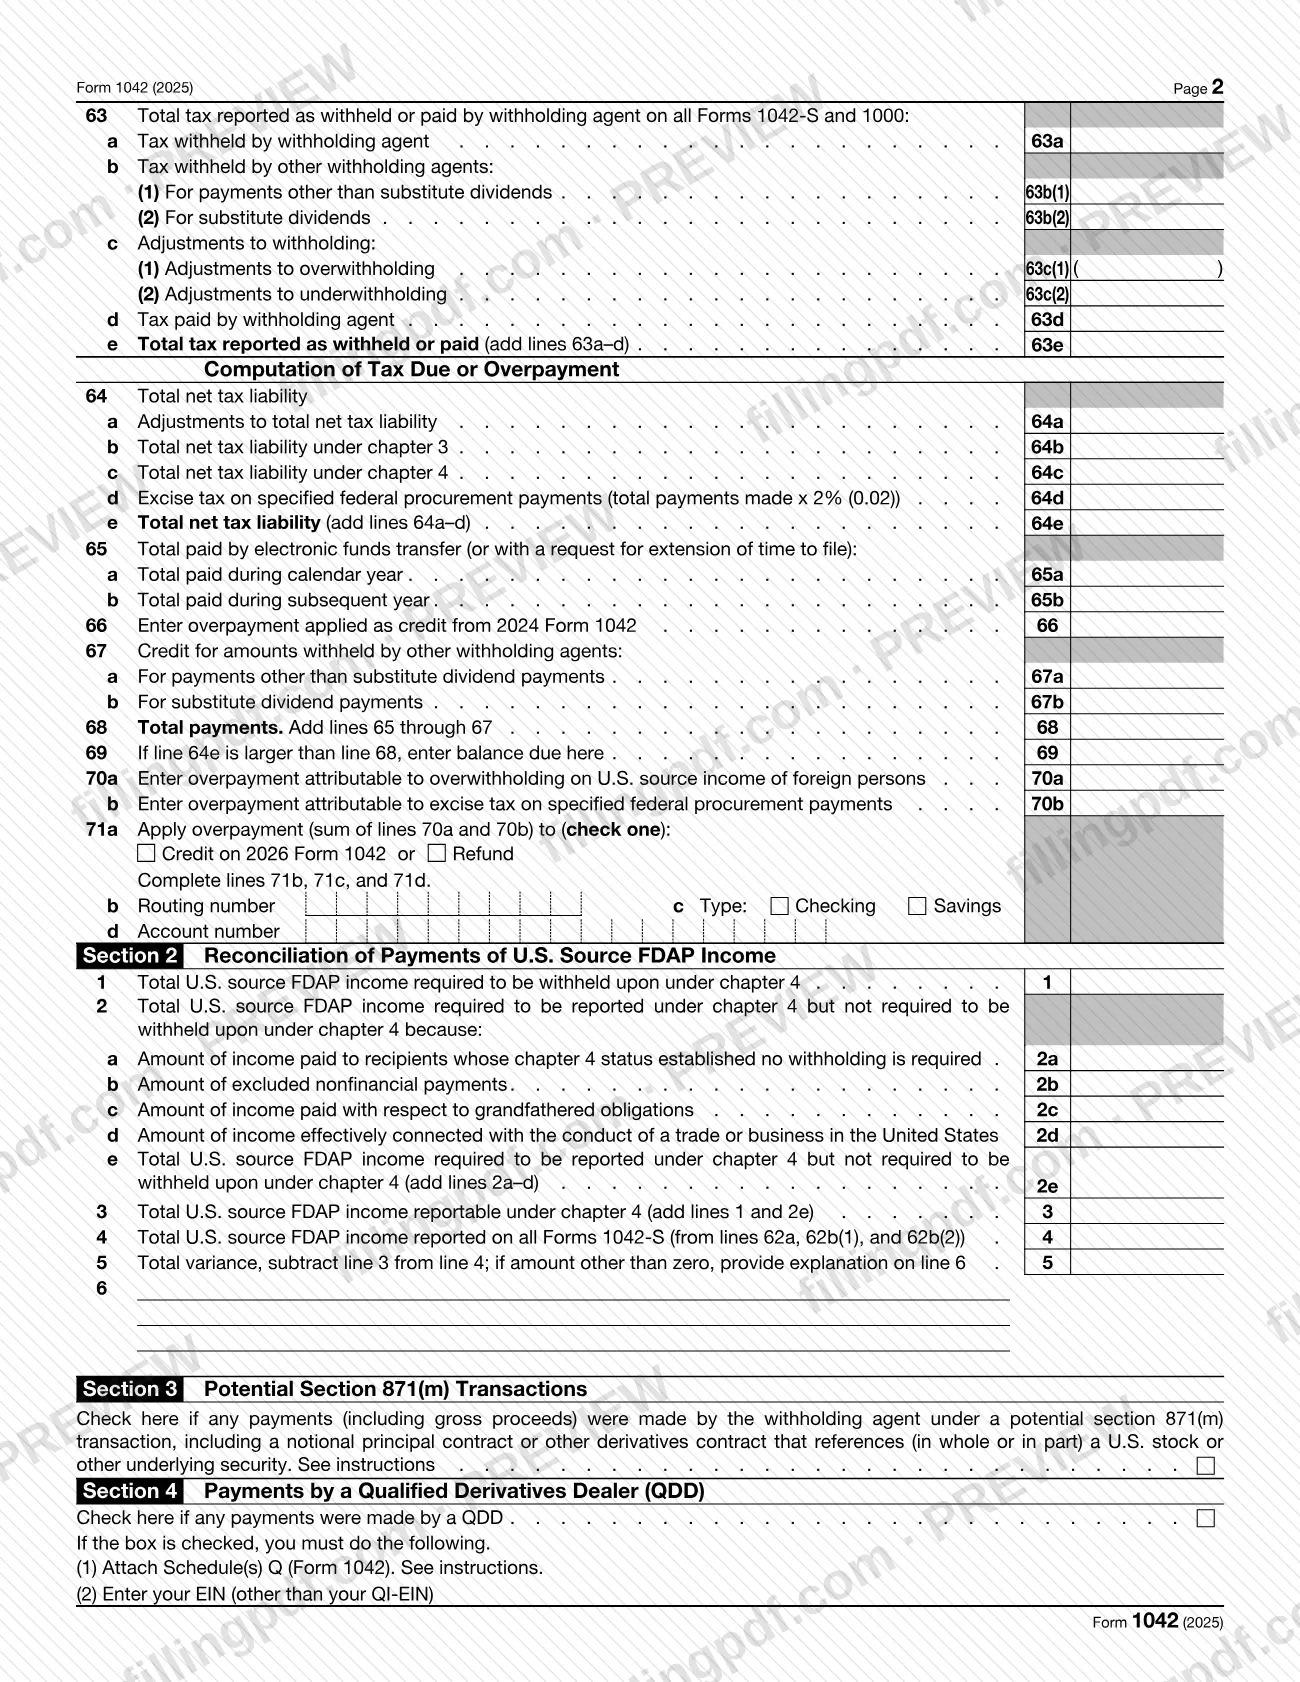
Form 1042 is the annual return the Internal Revenue Service (IRS) requires from withholding agents to report tax withheld on certain U.S. source income paid to foreign persons. Every withholding agent or intermediary that handles a withholdable payment or an amount subject to withholding files it for the preceding calendar year, unless an exception applies. On this page you can fill out the form online on FillingPDF and download or print the completed PDF; the IRS publishes the form and the Instructions for Form 1042 at irs.gov.
Last updated
What is 1042?
Form 1042, Annual Withholding Tax Return for U.S. Source Income of Foreign Persons, is the Internal Revenue Service (IRS) return on which a withholding agent reports, for one calendar year, the tax it withheld on certain income of foreign persons and the payments it reported on Form 1042-S.
According to the IRS instructions, Form 1042 reports:
- tax withheld under chapter 3 on certain income of foreign persons, including nonresident aliens, foreign partnerships, foreign corporations, foreign estates and foreign trusts (excluding withholding under sections 1445 and 1446 except as the instructions indicate);
- tax withheld under chapter 4 on withholdable payments;
- tax withheld under section 5000C on specified federal procurement payments;
- tax withheld under section 877A on eligible deferred compensation items or distributions from nongrantor trusts to a covered expatriate;
- payments reported on Form 1042-S under chapter 3 or 4.
The return has a Record of Federal Tax Liability (Section 1, lines 1 through 60), gross amounts and tax withheld reconciled to Forms 1042-S, net tax liability, deposits, and an overpayment or balance due. Section 2 reconciles U.S. source FDAP income, Section 3 flags potential section 871(m) transactions and Section 4 covers payments by a qualified derivatives dealer (QDD). Form 1042-S reports income and withholding to each payee; Form 1042 is the single annual summary filed with the IRS.
Who needs to file 1042?
Every withholding agent or intermediary that receives, controls, has custody of, disposes of or pays a withholdable payment (to which chapter 4 withholding applies) or an amount subject to withholding must file Form 1042 for the preceding calendar year, unless an exception to filing applies. A publicly traded partnership (PTP) or nominee making a distribution of effectively connected taxable income under section 1446, and any entity required to report a distribution on Form 1042-S that is subject to section 1445 withholding, must also file.
You must file if any of these apply:
- you are required to file, or otherwise file, Form(s) 1042-S for chapter 3 or 4 purposes, whether or not tax was withheld;
- you pay gross investment income to foreign private foundations subject to tax under section 4948(a);
- you pay specified federal procurement payments subject to section 5000C withholding;
- you pay an eligible deferred compensation item to a covered expatriate, or are a trustee distributing from a nongrantor trust to one;
- you are a QI, withholding foreign partnership, withholding foreign trust, participating FFI or reporting Model 1 FFI claiming a collective refund under your agreement with the IRS.
Do not use Form 1042 for wages paid to a nonresident alien employee (Form 941), wages to a nonresident alien household employee (Schedule H (Form 1040)), or section 3406 backup withholding by an electing PFFI (Form 945). Other than a PTP, a partnership reports section 1446 withholding on Form 8804. File one Form 1042 per capacity in which you act.
When to file 1042
File Form 1042 by March 15, the 15th day of the 3rd month after the end of the calendar year being reported. If that date falls on a Saturday, Sunday or legal holiday, file by the next business day.
If you need more time, submit Form 7004, Application for Automatic Extension of Time To File Certain Business Income Tax, Information, and Other Returns. Form 7004 does not extend the time to pay tax, and interest is charged on tax not paid by the due date even when an extension is granted.
Deposits of tax withheld come due before the return does. Their frequency depends on the amount of tax you are required to withhold: after quarter-monthly periods, after month-end, or with the return when the year-end balance is small. A late return, or late payment or deposit, can bring penalties and interest unless you show reasonable cause and not willful neglect. The IRS figures them and sends a bill.
Documents you need
- Schedule(s) Q (Form 1042), Tax Liability of Qualified Derivatives Dealer (QDD): attach at least one for each QDD if the taxpayer or any branch is a QDD, even if the QDD has zero tax liability.
- Form(s) 1042-S or 1099: attach to support any credit claimed on line 67 for tax withheld by other withholding agents; without them the refund or credit is denied.
- Copies of Form(s) 1042-S and a statement of reliance on Notice 2025-63: attach when claiming a collective refund of tax withheld on borrow fees under an agreement with the IRS, with the amount of income subject to withholding for each payment.
- An explanation sheet: attach if the variance on line 5 is other than zero and line 6 does not give enough space.
- A statement explaining why you are filing an amended return: attach to an amended Form 1042, with the Amended Return box checked.
- A copy of the return for the withholding agent or intermediary: provide it in addition to the IRS copy when a paid preparer completes the form.
How to fill out 1042
Enter withholding agent identification
Enter your name, address (suite or unit number after the street address; a P.O. box only if the post office does not deliver to the street), country code and EIN. A QI, WP or WT enters its QI-EIN, WP-EIN or WT-EIN. Round all amounts to whole dollars.
Enter chapter 3 and 4 status codes
Enter both a chapter 3 and a chapter 4 withholding agent status code from the Form 1042-S list of Type of Recipient, Withholding Agent, Payer, or Intermediary Code, using the most specific code for your status. Both codes are required whatever payments you made.
Mark amended return if needed
Check the Amended Return box only when correcting a Form 1042 you already submitted. Complete the whole form, sign it and attach a statement explaining the change.
Complete Section 1, lines 1 through 60
Enter the tax liability for each quarter-monthly period in which income was paid or distributed, with monthly totals on lines 5, 10, 15, 20, 25, 30, 35, 40, 45, 50, 55 and 60. Enter liability, not deposits, and no negative amounts.
Report special timing cases on line 59
Use line 59 for withholding made in the year after the payment and for QIs without primary chapter 3 and 4 responsibility. Reductions from the reimbursement or set-off procedure also affect line 59.
Enter Forms 1042-S counts and gross amounts
On line 61 enter the number of Forms 1042-S filed on paper and electronically. On lines 62a through 62d enter gross amounts from all Forms 1042-S and Forms 1000, reconciling them with box 2 of Form 1042-S.
Report tax withheld on lines 63a–63e
Enter amounts withheld, repaid or withheld in the following year, and amounts paid from your own funds, matching boxes 7a, 8, 9 and 11 of Forms 1042-S. Do not report escrowed amounts until the year they are deposited.
Figure total net tax liability
Enter adjustments on line 64a, the Section 1 chapter 3 total on line 64b, the chapter 4 total on line 64c and specified federal procurement payment tax on line 64d. Line 64e is the sum of lines 64a through 64d.
Enter deposits, credits and payments
Line 65a is deposits for tax withheld during the payment year, line 65b deposits made the following year, line 66 an overpayment credited from the 2024 return, and line 67 credit for tax withheld by other agents, supported by attached forms.
Complete balance due or overpayment
Enter any balance due on line 69, without interest or penalties. Enter overpayments on lines 70a and 70b, choose refund or credit on line 71a, and for direct deposit complete lines 71b through 71d (nine-digit routing number, one account type box).
Complete Sections 2, 3 and 4
In Section 2, reconcile U.S. source FDAP income on lines 1 through 6 and explain any variance on line 5. Check the Section 3 box for potential section 871(m) transactions and the Section 4 box for QDD payments, attaching Schedule(s) Q (Form 1042).
Review, sign and download the PDF
Complete the Third Party Designee section if you want the IRS to discuss the return with someone, then sign and date; a paid preparer completes the preparer section with a PTIN. Download or print the completed PDF from FillingPDF and send it through the channels under How to submit.
How to submit 1042
Form 1042 is filed electronically or on paper, and the tax is paid separately through electronic deposits.
- Electronic filing: required for a withholding agent that is a financial institution, for withholding agents required to file 10 or more information returns under Regulations section 301.6011-2 during the year, and for a partnership with more than 100 partners. See Pub. 4163, Modernized e-File (MeF) Information for Authorized IRS e-File Providers for Business Returns. The IRS page about Form 1042 lists information on requesting a waiver from the e-filing requirement.
- Paper filing: mail the return by March 15 to Internal Revenue Service, P.O. Box 409101, Ogden, UT 84409.
- Extension: submit Form 7004 to request more time to file.
- Deposits and payment: use the Electronic Federal Tax Payment System (EFTPS) or IRS Direct Pay for deposits of tax withheld. Do not mail deposits to the IRS. For a balance due on line 69, the IRS recommends paying electronically; see IRS.gov/Payments.
- Help: call 267-941-1000 (not a toll-free number) from 6:00 a.m. to 11:00 p.m. Eastern time, or write to Internal Revenue Service, International Accounts, Philadelphia, PA 19255-0725. Do not send the form to that address.
Give the withholding agent or intermediary a copy if a paid preparer completed the return. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Entering negative amounts on lines 1 through 60; if a reduction on line 59 would make a period negative, report the negative amount in the next earlier period instead.
- Reporting tax actually deposited on lines 1 through 60 instead of the tax liability for each quarter-monthly period.
- Leaving out the chapter 3 and chapter 4 withholding agent status codes, which are required whatever types of payments are reported.
- Entering the wrong EIN: a QI, WP or WT enters its QI-EIN, WP-EIN or WT-EIN, and a financial institution filing for non-U.S. branches cannot use the U.S. branch EIN.
- Skipping Section 2 because no chapter 4 withholding occurred; it must be completed regardless.
- Including the line 64a adjustments in the Record of Federal Tax Liability, or letting lines 5 through 60 monthly totals differ from lines 64b through 64d.
- Mailing tax deposits to the IRS instead of using EFTPS or IRS Direct Pay, which can lead to a penalty.
- Claiming a credit on line 67 without attaching the supporting Form(s) 1042-S or 1099.
- Filing an amended Form 1042 to recover tax overwithheld in a prior year, or including interest and penalties in the line 69 balance due.
- Checking more than one account type box on line 71c, or filing separate returns by client or branch rather than one Form 1042 per capacity.
Frequently asked questions
What is Form 1042 used for?
Form 1042 is the IRS annual return that withholding agents use to report tax withheld under chapter 3 and chapter 4, section 5000C and section 877A on U.S. source income paid to foreign persons, and the payments reported on Form 1042-S, for the preceding calendar year.
Who has to file Form 1042?
Every withholding agent or intermediary that receives, controls, has custody of, disposes of or pays a withholdable payment or an amount subject to withholding must file, unless an exception applies. You must file whenever you file Forms 1042-S, even if no tax was withheld.
When is Form 1042 due?
Form 1042 is due March 15 following the calendar year reported. If March 15 is a Saturday, Sunday or legal holiday, file by the next business day. Form 7004 gives an extension of time to file, but it does not extend the time to pay.
Do I have to e-file Form 1042?
Electronic filing is required for a withholding agent that is a financial institution, for those required to file 10 or more information returns during the year, and for a partnership with more than 100 partners. Others may file on paper; see Pub. 4163 for e-file details.
Where do I mail Form 1042?
Mail a paper Form 1042 by March 15 to Internal Revenue Service, P.O. Box 409101, Ogden, UT 84409. Do not mail tax deposits there or to any IRS address; deposits go through EFTPS or IRS Direct Pay.
What is the difference between Form 1042 and Form 1042-S?
Form 1042-S reports to each recipient the income paid and tax withheld. Form 1042 is the single annual return you file with the IRS that summarizes and reconciles those amounts and reports tax liability, deposits and any balance due or overpayment.
Can I fill out Form 1042 online?
You can fill out the Form 1042 PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the return or make deposits; you submit it to the IRS electronically or by mail.
How do I correct a Form 1042 I already filed?
File an amended Form 1042 for the same year, check the Amended Return box, complete the entire form, sign it and attach a statement explaining the change. Do not amend it to recover tax overwithheld in a prior year.
Ready to fill out 1042?
Fill out 1042 now