
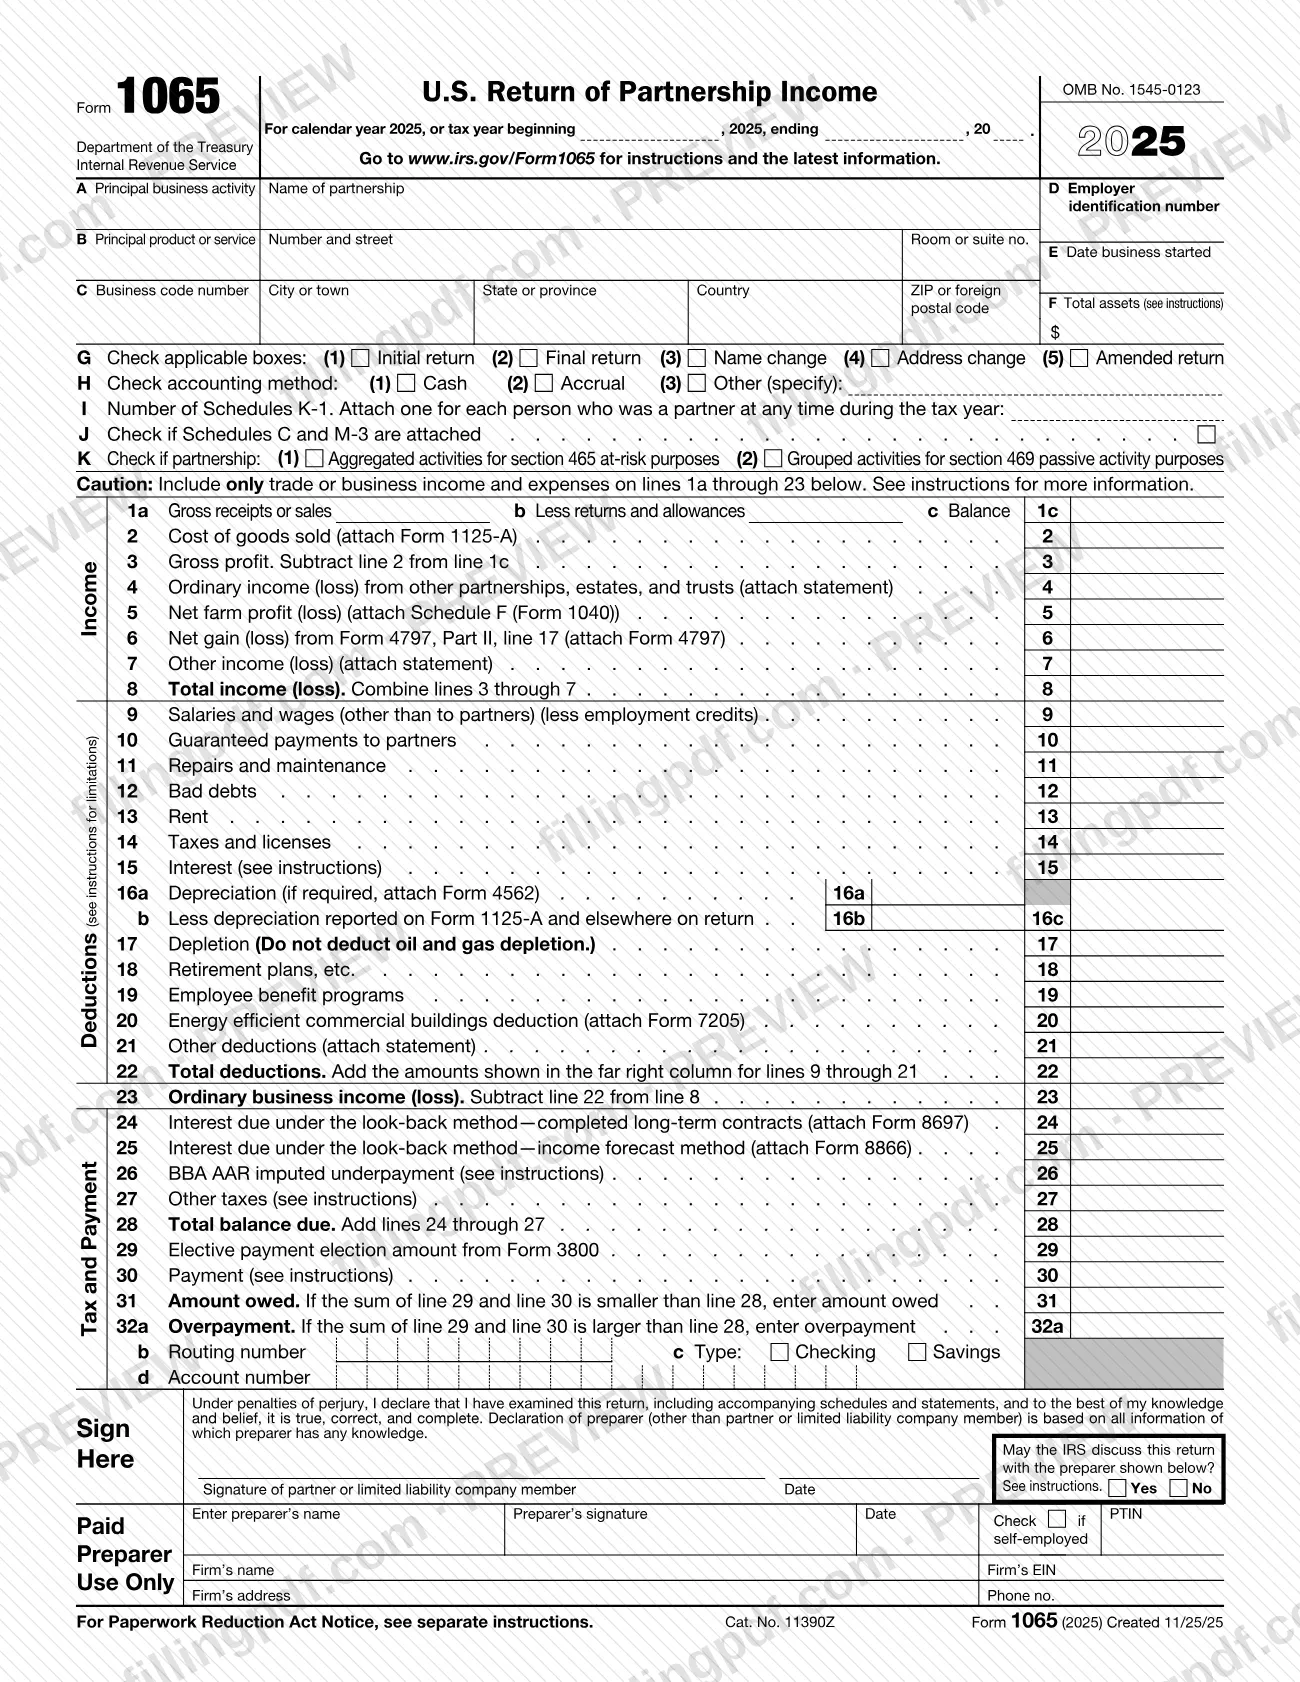
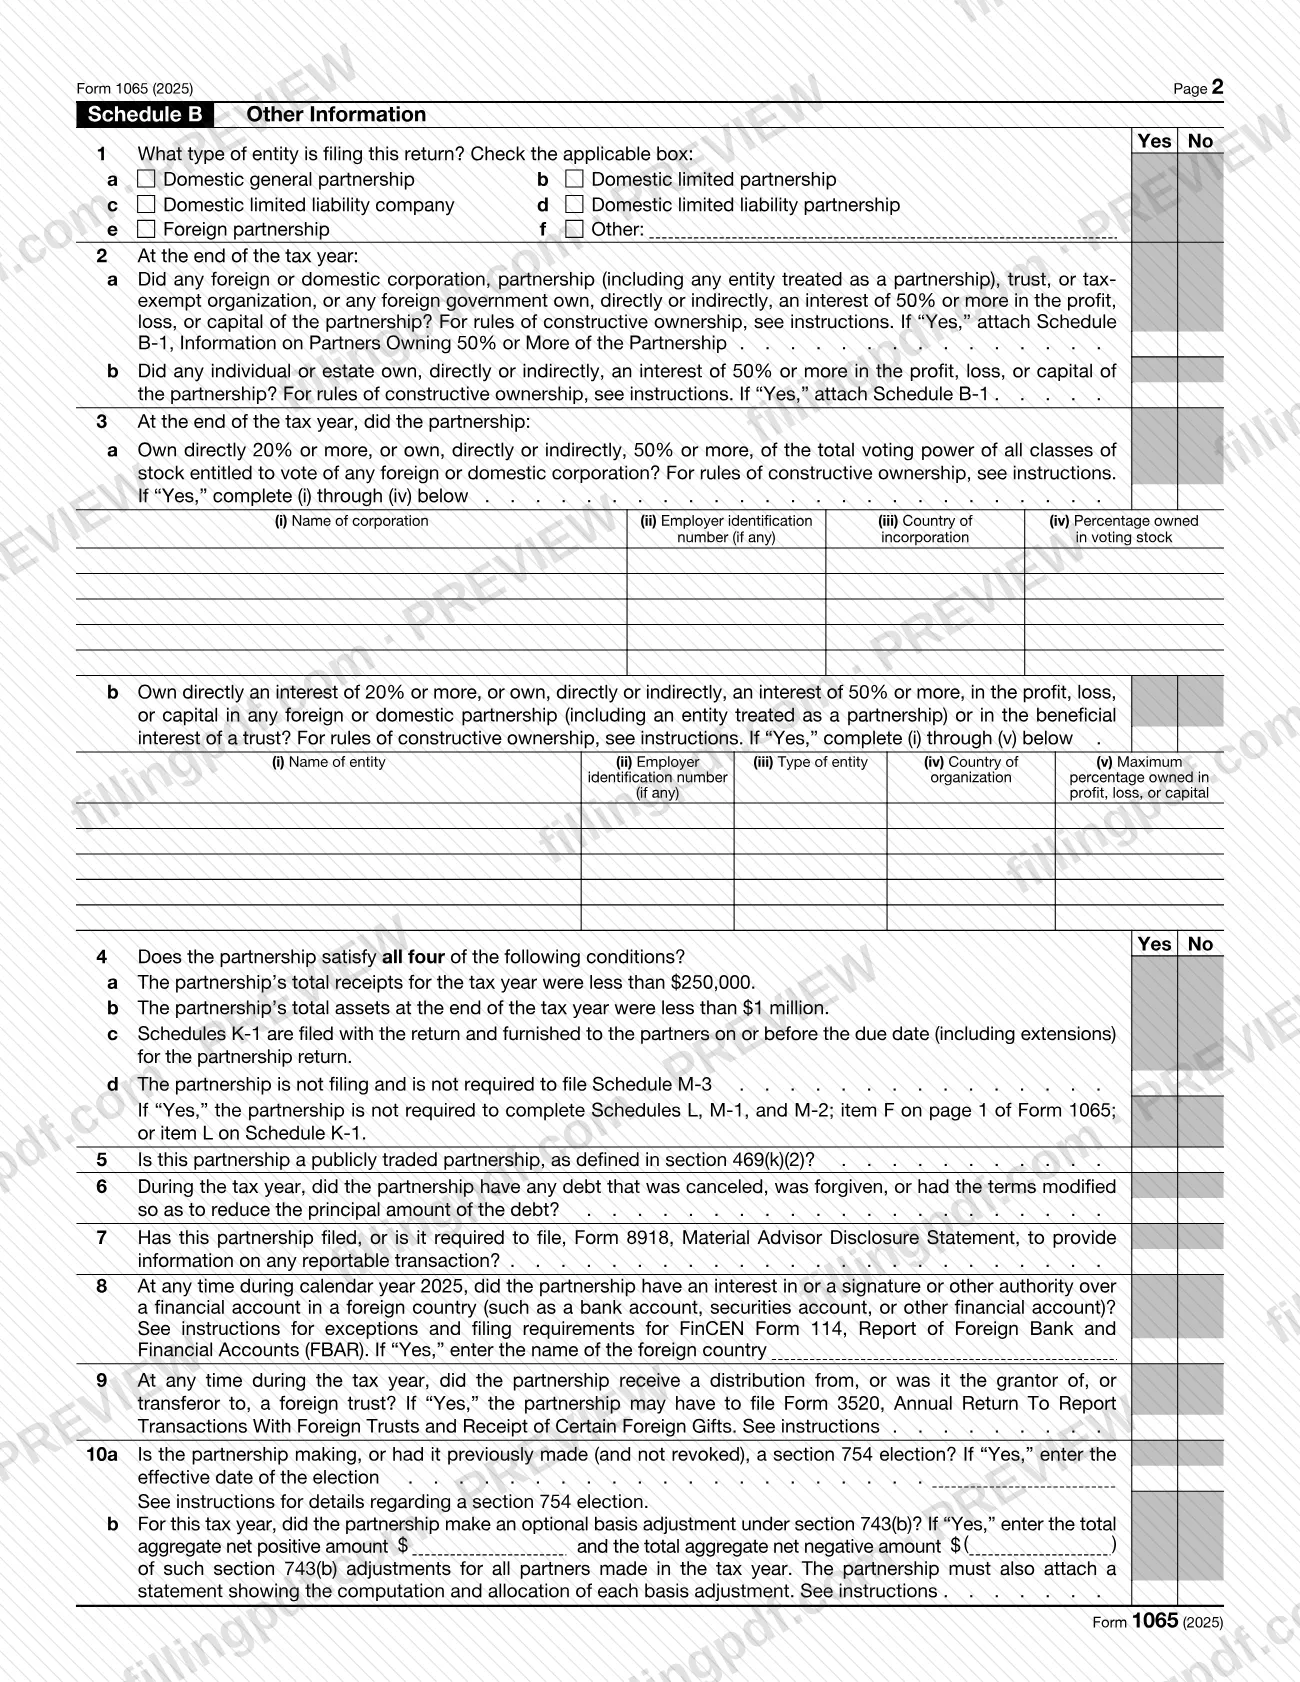
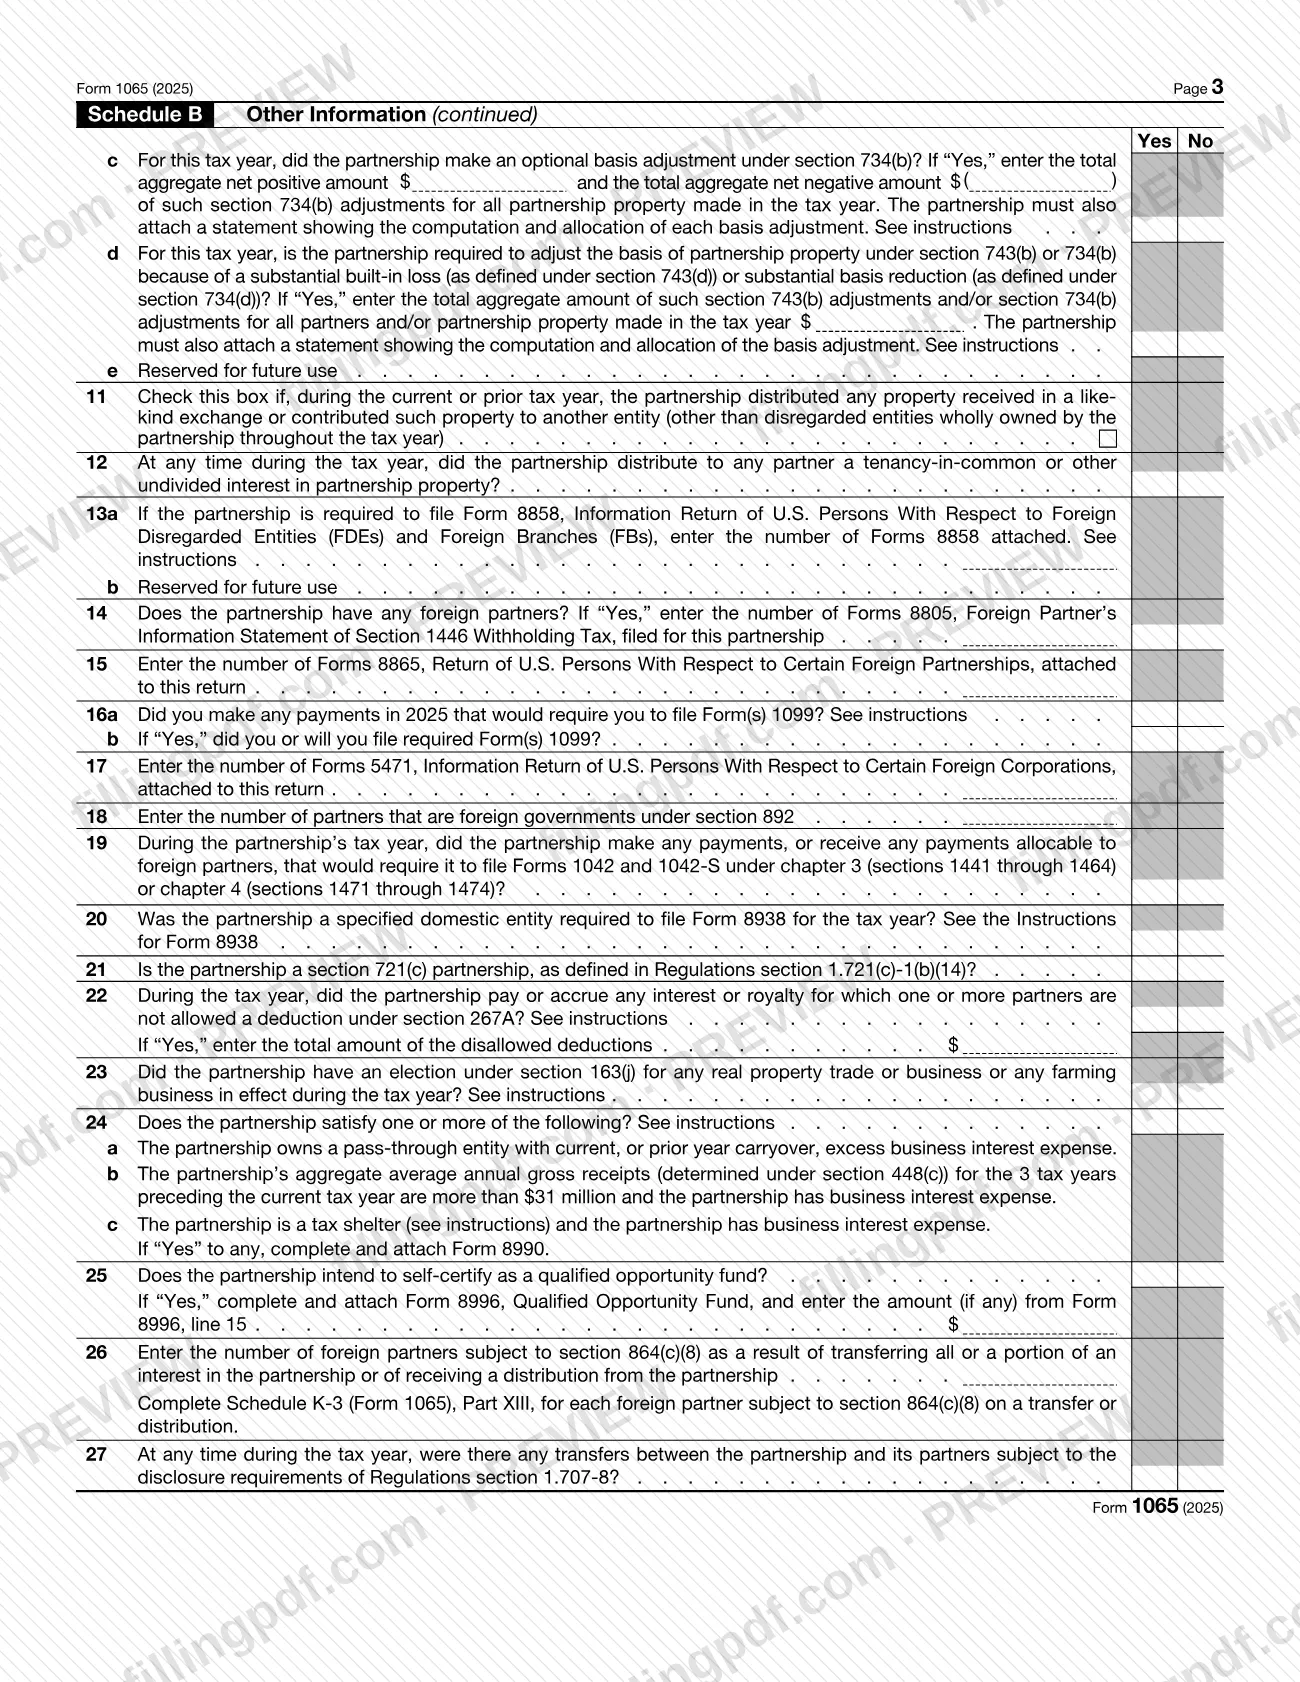
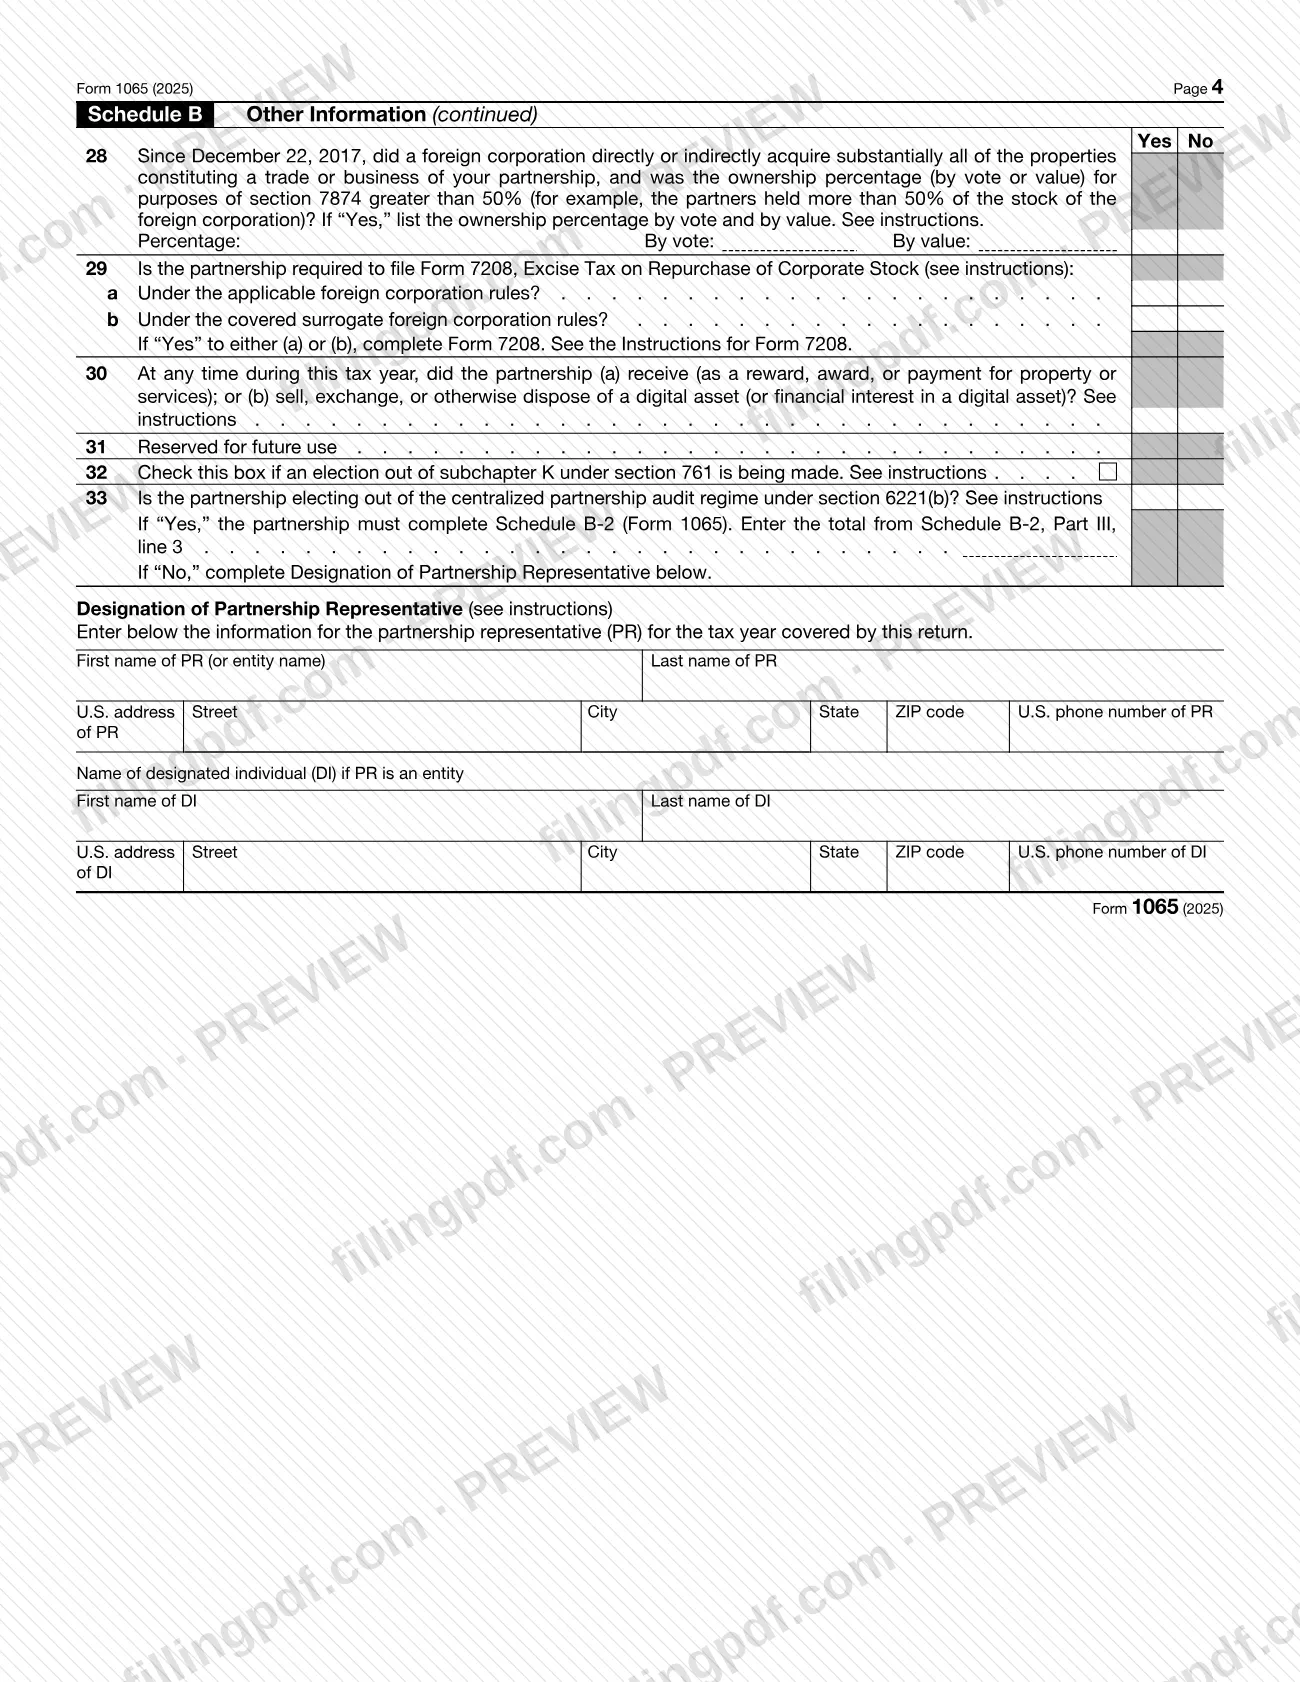
Form 1065 is the Internal Revenue Service (IRS) return on which a partnership reports its income, gains, losses, deductions and credits for the tax year. Domestic partnerships, including LLCs taxed as partnerships, generally file it, and certain foreign partnerships do too. On this page you can fill out Form 1065 online on FillingPDF and download or print the completed PDF. The form, the Instructions for Form 1065 and the latest updates are published by the IRS at www.irs.gov/Form1065, and the return reaches the IRS only through the channels described under How to submit.
Last updated
What is 1065?
Form 1065, U.S. Return of Partnership Income, is the IRS information return a partnership uses to report the income, gains, losses, deductions, credits and other information from its operation; the partnership generally pays no tax itself and passes profits and losses through to its partners.
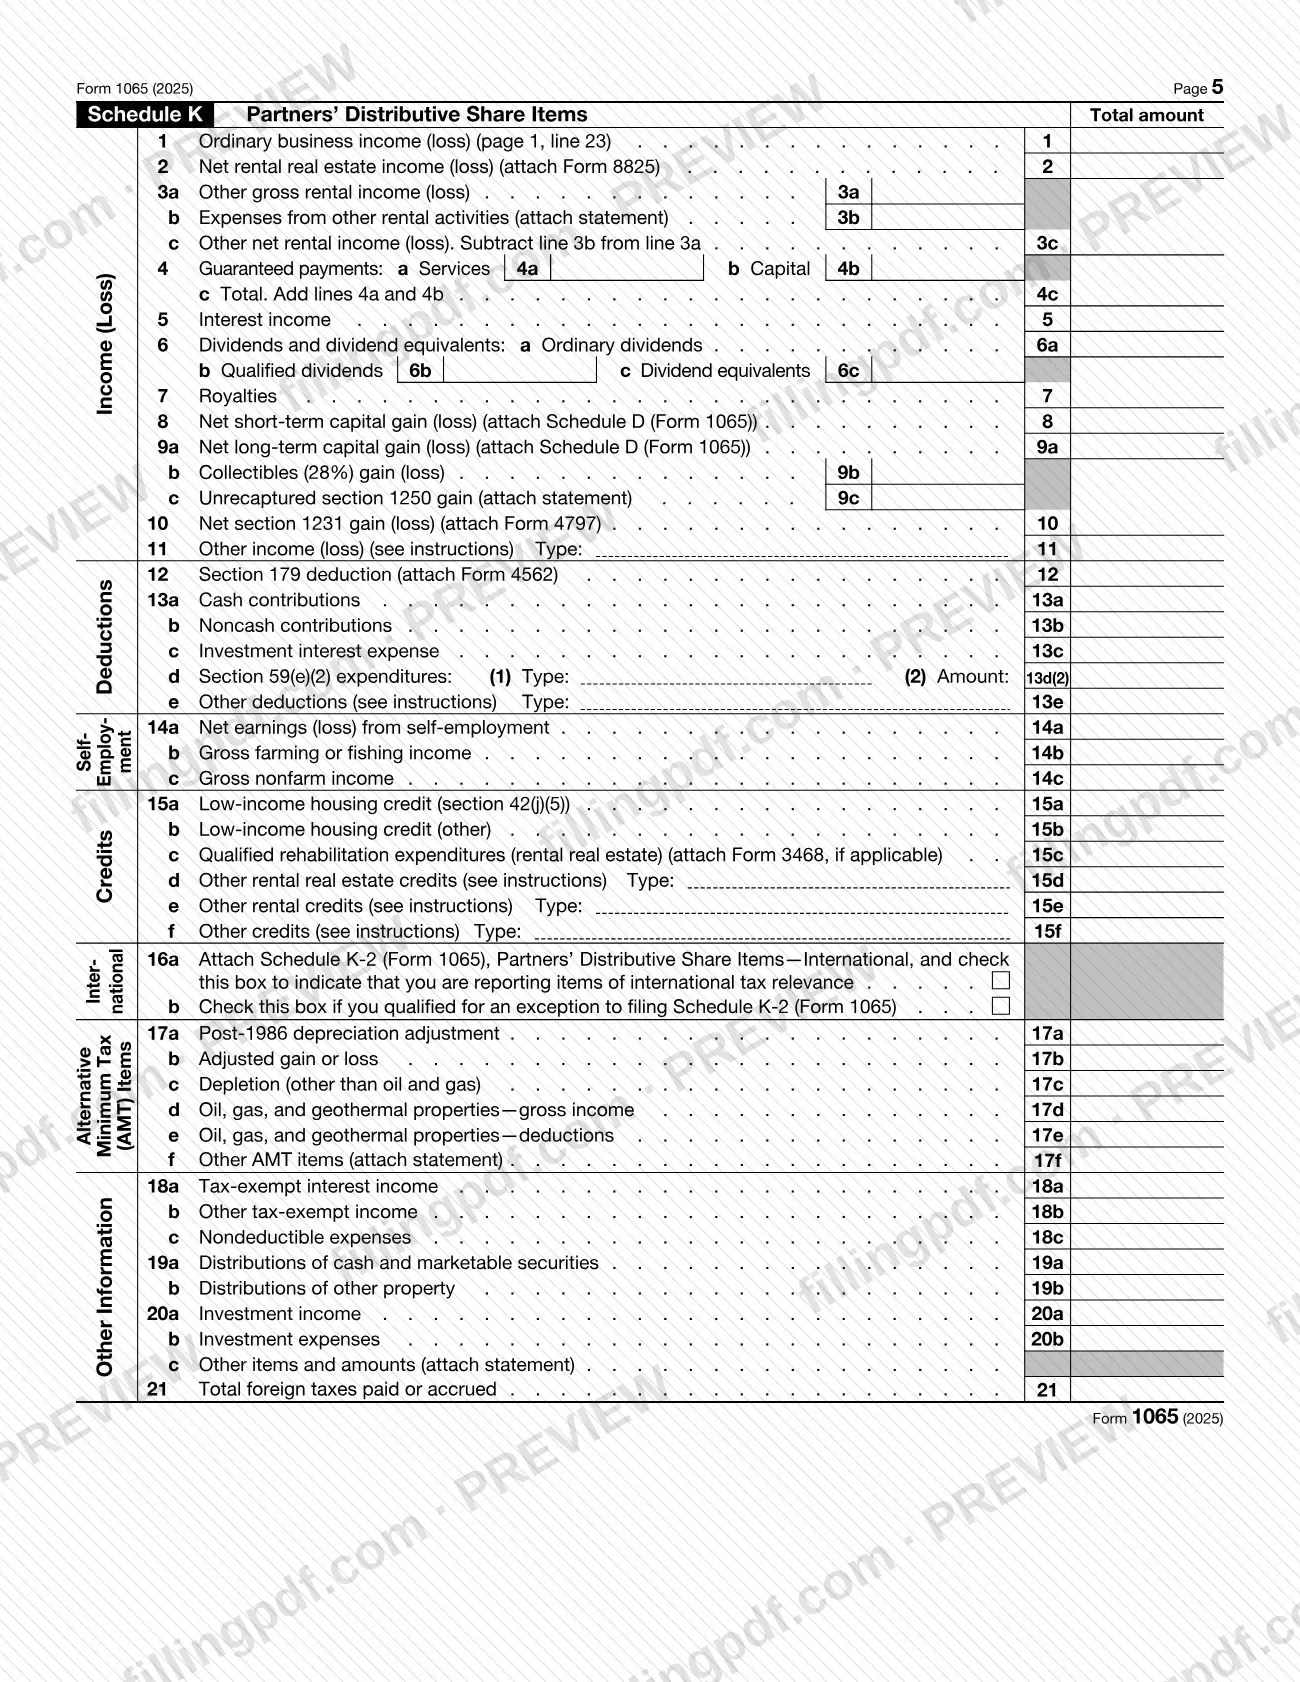
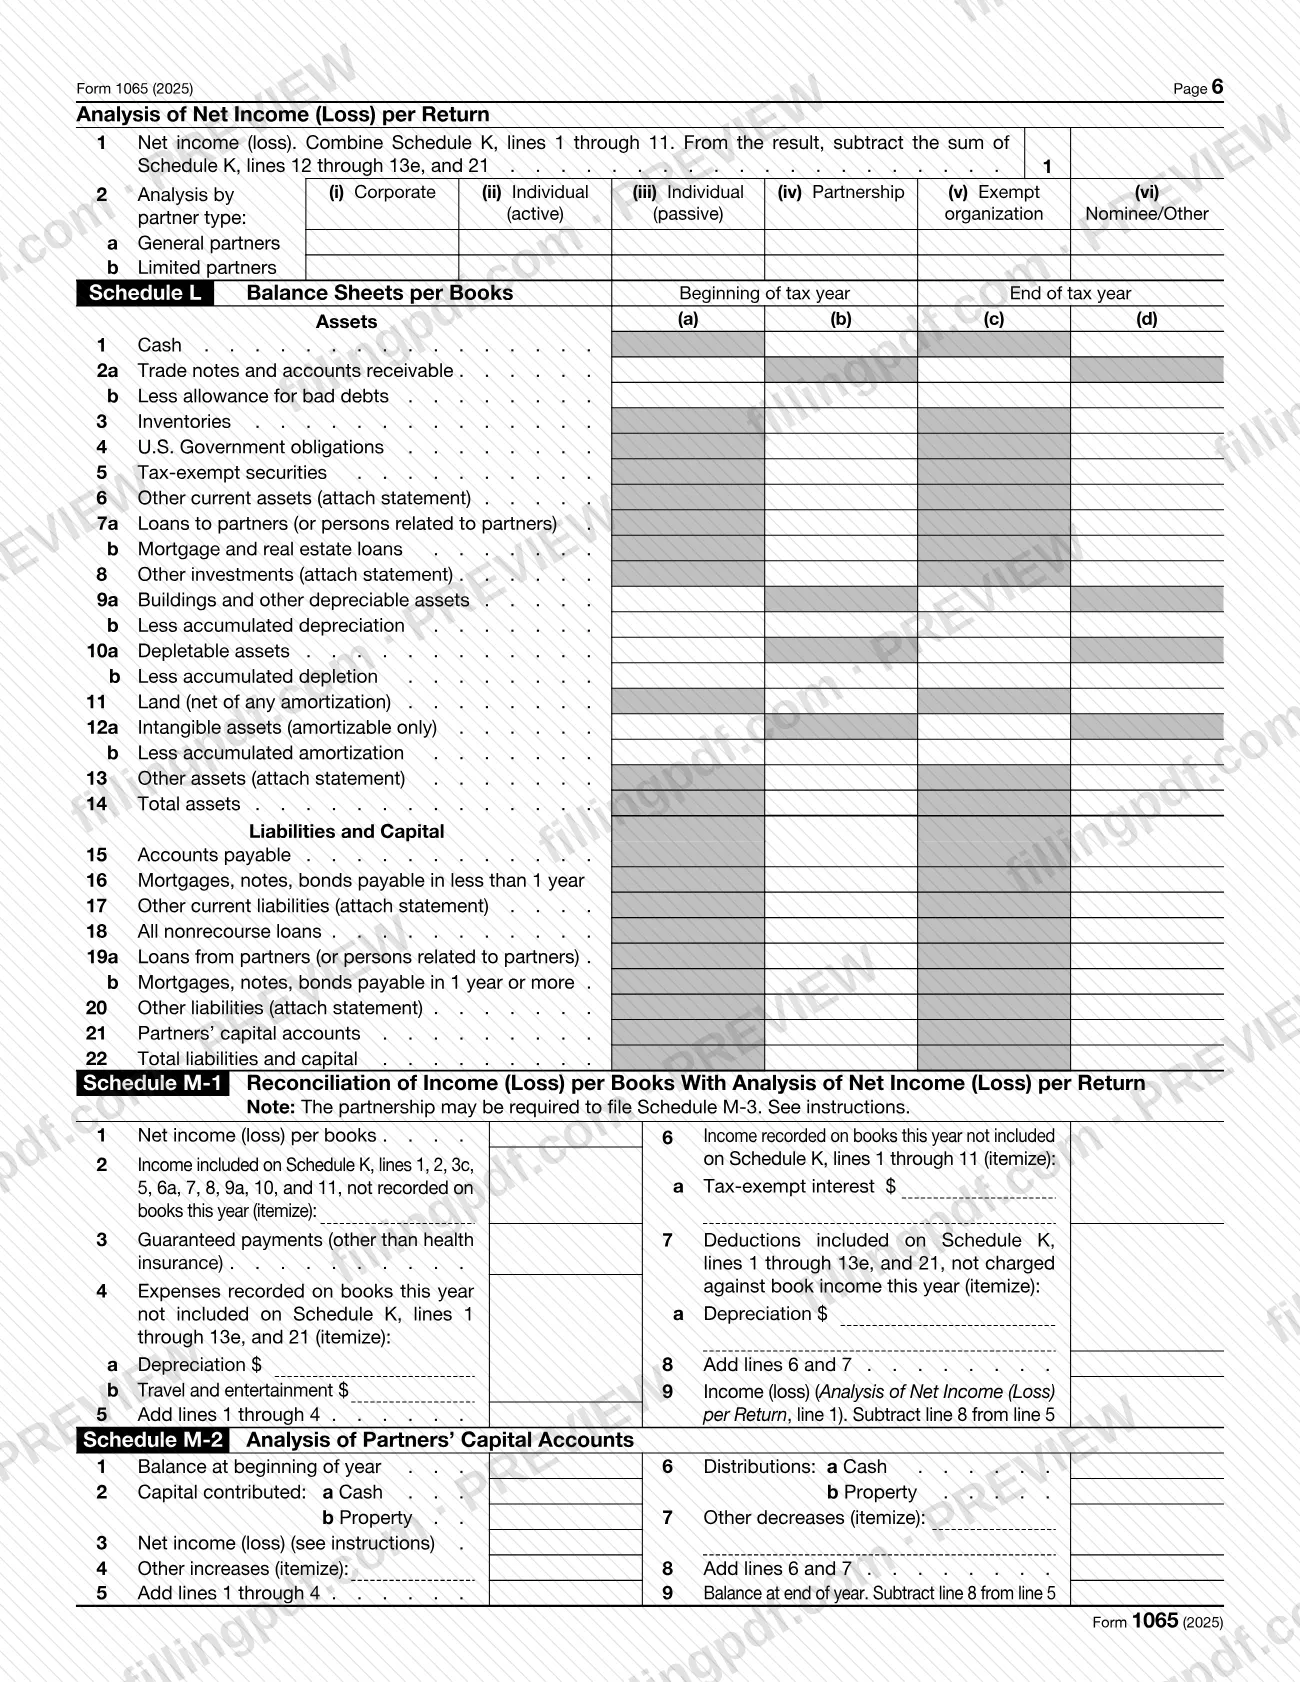
Partners must include partnership items on their own tax or information returns. To make that possible, Form 1065 carries Schedule K (partners' distributive share items), and the partnership attaches a Schedule K-1 for each person who was a partner at any time during the tax year. The return also contains Schedule B (other information, including the designation of the partnership representative), the analysis of net income (loss) per return, Schedule L (balance sheets per books), Schedule M-1 and Schedule M-2.
The 2025 form is an information return for calendar year 2025 and for fiscal years that begin in 2025 and end in 2026. It differs from neighboring returns the instructions name: Form 1065-X is used for a paper-filed amended return or administrative adjustment request (AAR), Form 1066 is for real estate mortgage investment conduits (REMICs), and certain publicly traded partnerships treated as corporations file Form 1120 instead.
Who needs to file 1065?
Every domestic partnership must file Form 1065, unless it neither receives income nor incurs any expenditures treated as deductions or credits for federal income tax purposes. An entity formed as an LLC and classified as a partnership has the same filing requirements, and a domestic LLC with at least two members that does not file Form 8832 is classified as a partnership.
Other groups the IRS instructions name:
- Foreign partnerships with income effectively connected with a U.S. trade or business, or with U.S. source income, unless they meet one of the two exceptions described in the instructions.
- Partnerships that are, or have a branch that is, a qualified derivatives dealer (QDD).
- A partnership seeking certification as a qualified opportunity fund (QOF), which must file Form 1065 with Form 8996 even with no income or expenses.
- A religious or apostolic organization exempt under section 501(d).
Who does not file: spouses who qualify and elect to be treated as a qualified joint venture instead of a partnership; REMICs, which file Form 1066; certain publicly traded partnerships treated as corporations, which file Form 1120; and a qualifying syndicate, pool or joint venture that elects under section 761(a), except for the year of election.
A partner or LLC member must sign. A receiver, trustee or assignee signs for the partnership instead when the return is made by that fiduciary.
When to file 1065
A domestic partnership must generally file Form 1065 by the 15th day of the 3rd month after its tax year ends. For calendar-year partnerships the due date is March 15. When the due date falls on a Saturday, Sunday or legal holiday, the next day that is not one is timely, so calendar-year partnerships could file the 2025 return by March 16, 2026.
To request more time, file Form 7004, Application for Automatic Extension of Time To File Certain Business Income Tax, Information, and Other Returns, by the regular due date of the return; it can be filed electronically.
A late return, or one missing required information, can bring a penalty for each month or part of a month, up to 12 months, multiplied by the number of partners; a separate penalty applies to each Schedule K-1 not furnished on time. The instructions say not to attach an explanation when filing: respond if the IRS sends a penalty notice.
Documents you need
- Schedule K-1 (Form 1065) for each person who was a partner at any time during the tax year; the number is entered in item I on page 1.
- Form 1125-A, Cost of Goods Sold, when you report cost of goods sold on line 2.
- Form 4562 when depreciation is required to be reported on line 16a, and for a section 179 deduction on Schedule K, line 12.
- Form 8825 for net rental real estate income (loss) on Schedule K, line 2.
- Schedule D (Form 1065) for net short-term and long-term capital gain (loss) on Schedule K, lines 8 and 9a.
- Form 4797 for the gain (loss) on line 6 and for the net section 1231 gain (loss) on Schedule K, line 10.
- Schedule B-1 if you answer "Yes" to Schedule B, question 2a or 2b (50% or more ownership of the partnership).
- Schedule B-2 (Form 1065) if the partnership elects out of the centralized partnership audit regime under Schedule B, question 33.
- Schedule K-2 (Form 1065) and Schedule K-3 when reporting items of international tax relevance, unless an exception to filing applies.
- Form 8996 for a partnership self-certifying as a qualified opportunity fund, even if it has no income or expenses to report.
- Form 8990 if you answer "Yes" to any item of Schedule B, question 24.
- Form 8082 with Form 1065 for an electronically filed administrative adjustment request (AAR).
- A copy of Form 8832 for the tax year in which an entity classification election is made.
- A statement on separate sheets for any line that says "attach statement", showing the partnership's name and EIN.
How to fill out 1065
Enter the tax year and partnership identity
At the top, fill in the tax year (fiscal-year dates if not calendar year 2025), then the partnership's name, address and EIN (item D). Add the principal business activity (A), principal product or service (B), business code number (C), date business started (E) and total assets (F, see instructions).
Complete items G through K
Check the applicable boxes in item G (initial, final, name change, address change, amended return) and the accounting method in item H. Enter the number of Schedules K-1 in item I, check item J if Schedules C and M-3 are attached, and check item K for section 465 or 469 aggregation or grouping.
Report income on lines 1a through 8
Enter gross receipts, returns and allowances (1a to 1c), cost of goods sold (line 2, attach Form 1125-A) and gross profit (line 3). Add other income on lines 4 to 7 and combine lines 3 through 7 on line 8.
Enter deductions on lines 9 through 23
Enter deductions on lines 9 to 21, such as salaries, guaranteed payments to partners, rent and depreciation (16a to 16c). Add the far right column on line 22 and subtract it from line 8 for ordinary business income (loss) on line 23.
Complete tax and payment lines 24 through 32
Enter any look-back interest (lines 24, 25), BBA AAR imputed underpayment (26) and other taxes (27), then total on line 28. Use lines 29 to 31 for the elective payment amount, payments and amount owed, and 32a to 32d for an overpayment and direct deposit details.
Sign and complete the preparer section
A partner or LLC member signs and dates the return and answers whether the IRS may discuss it with the preparer. A paid preparer completes the Paid Preparer Use Only section with a PTIN; leave it blank if someone at the partnership prepared the return.
Answer Schedule B, other information
Answer questions 1 through 33 with the entity type, ownership, foreign activity, elections, digital assets and audit-regime questions. Attach the form or schedule that each "Yes" answer calls for, such as Schedule B-1 or Form 8990.
Designate the partnership representative
If you answered "No" to question 33, enter the partnership representative's name, U.S. address and U.S. phone number. If the representative is an entity, also enter the designated individual's details.
Complete Schedule K
Report the partners' distributive share items in total: ordinary business income (line 1), rental income, guaranteed payments, interest, dividends, capital gains, deductions, credits, international and AMT items, other information such as distributions (line 19) and foreign taxes (line 21).
Complete the analysis and Schedules L, M-1, M-2
Fill in the Analysis of Net Income (Loss) per Return, Schedule L balance sheets, Schedule M-1 and Schedule M-2. If you answered "Yes" to Schedule B, question 4, the form says Schedules L, M-1 and M-2, item F and item L of Schedule K-1 are not required.
Prepare Schedules K-1 and attachments
Complete a Schedule K-1 for each partner and add the statements and forms the lines call for. Round all amounts to whole dollars or use cents throughout, and put the name and EIN on each supporting statement.
Review and download the completed PDF
Check totals, signature, item I against the Schedules K-1 and the attachments. Download or print the completed PDF from FillingPDF and assemble the return in the order the instructions give.
How to submit 1065
Form 1065 is filed electronically or, where electronic filing is not required, on paper by mail.
- Electronic filing. Since 2024, partnerships must e-file Form 1065 and related forms if they file 10 or more returns of any type during the year, and partnerships with more than 100 partners must e-file. E-file declarations use Form 8453-PE or Form 8879-PE. For help call the e-Help Desk at 866-255-0654 or go to IRS.gov/Filing.
- Paper by mail. Use the address for your principal business location. If it is in Connecticut, Delaware, the District of Columbia, Georgia, Illinois, Indiana, Kentucky, Maine, Maryland, Massachusetts, Michigan, New Hampshire, New Jersey, New York, North Carolina, Ohio, Pennsylvania, Rhode Island, South Carolina, Tennessee, Vermont, Virginia, West Virginia or Wisconsin, and total assets (item F) are under $10 million with no Schedule M-3 filed, mail to Department of the Treasury, Internal Revenue Service Center, Kansas City, MO 64999-0011. In those states with $10 million or more, or under $10 million with Schedule M-3 filed, and in every other state with any amount, mail to Department of the Treasury, Internal Revenue Service Center, Ogden, UT 84201-0011. For a foreign country or U.S. territory, mail to Internal Revenue Service, P.O. Box 409101, Ogden, UT 84409.
- Private delivery services. Only IRS-designated services count for timely mailing; see IRS.gov/PDS and IRS.gov/PDSStreetAddresses. They cannot deliver to P.O. boxes.
- E-file waiver. Hardship waiver requests go in writing to the Ogden Submission Processing Center (Attn: Form 1065 e-file Waiver Request) or by fax to 877-477-0575. Partners with a religious conflict write "Religious Exemption" at the top of page 1 of a paper return.
Assemble the pages in the order the instructions list, with Schedules K-1 included. If a balance is due on line 31, go to IRS.gov/Payments. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Writing "See attached" instead of completing the entry spaces on Form 1065 and Schedule K-1; the instructions warn that penalties may be assessed for an incomplete return.
- Including portfolio or other non-trade-or-business income on lines 1a through 23; the form cautions that only trade or business income and expenses belong there.
- Filing a paper return when electronic filing is required, such as for partnerships filing 10 or more returns of any type or with more than 100 partners.
- Filing the return unsigned: it is not considered a return unless a partner or LLC member signs it.
- Entering a Social Security number in the Paid Preparer Use Only section; a paid preparer must use a PTIN.
- Attaching an explanation of reasonable cause for a late-filing penalty to the return instead of responding after the IRS sends a notice.
- Sending a return with Schedule M-3 to the Kansas City address instead of the Ogden address.
- Using a private delivery service for an IRS P.O. box address; only the U.S. Postal Service can deliver there.
- Filing a new Form 1065 for a paper amended return or AAR instead of Form 1065-X, Amended Return or Administrative Adjustment Request (AAR).
- Leaving the Designation of Partnership Representative blank when answering "No" to Schedule B, question 33.
Frequently asked questions
What is Form 1065 used for?
Form 1065 is the IRS information return a partnership files to report its income, gains, losses, deductions, credits and other information. The partnership generally pays no tax on its income; it passes profits and losses to partners, who report their shares on their own returns using Schedule K-1.
When is Form 1065 due for 2025?
For a calendar-year partnership the due date is March 15; because that date fell on a weekend, the instructions treat a 2025 return filed by March 16, 2026 as timely. Other tax years are due by the 15th day of the 3rd month after the year ends.
How do I get an extension to file Form 1065?
File Form 7004, Application for Automatic Extension of Time To File Certain Business Income Tax, Information, and Other Returns, by the regular due date of the partnership return. Form 7004 can be filed electronically; see the Instructions for Form 7004 for details.
Where do I file Form 1065?
Electronically if required, otherwise by mail to the IRS address for your principal business location, total assets and Schedule M-3 status: Kansas City, MO 64999-0011, Ogden, UT 84201-0011, or P.O. Box 409101, Ogden, UT 84409 for a foreign country or U.S. territory. See How to submit for the conditions.
Do I have to file Form 1065 electronically?
Yes if the partnership files 10 or more returns of any type during the tax year, or has more than 100 partners. The IRS may waive the rule for hardship, and partnerships with a religious conflict are exempt and may file on paper marked "Religious Exemption".
Do spouses who own a business together file Form 1065?
Generally yes, if they jointly own and operate an unincorporated business and share profits and losses. The exception is a qualified joint venture: spouses who both materially participate and file a joint return can elect to be treated as one and report on Schedule C or F instead.
What is the difference between Form 1065 and Form 1065-X?
Form 1065 is the original partnership return. Form 1065-X, Amended Return or Administrative Adjustment Request (AAR), is used for paper-filed amended returns and AARs. For electronic amendments, complete Form 1065 and check box G(5), with a statement explaining each change.
Can I fill out Form 1065 online on FillingPDF?
Yes. You can fill out the fillable PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the return with the IRS; you submit it through the electronic or mailing channels the IRS instructions describe.
Ready to fill out 1065?
Fill out 1065 now