
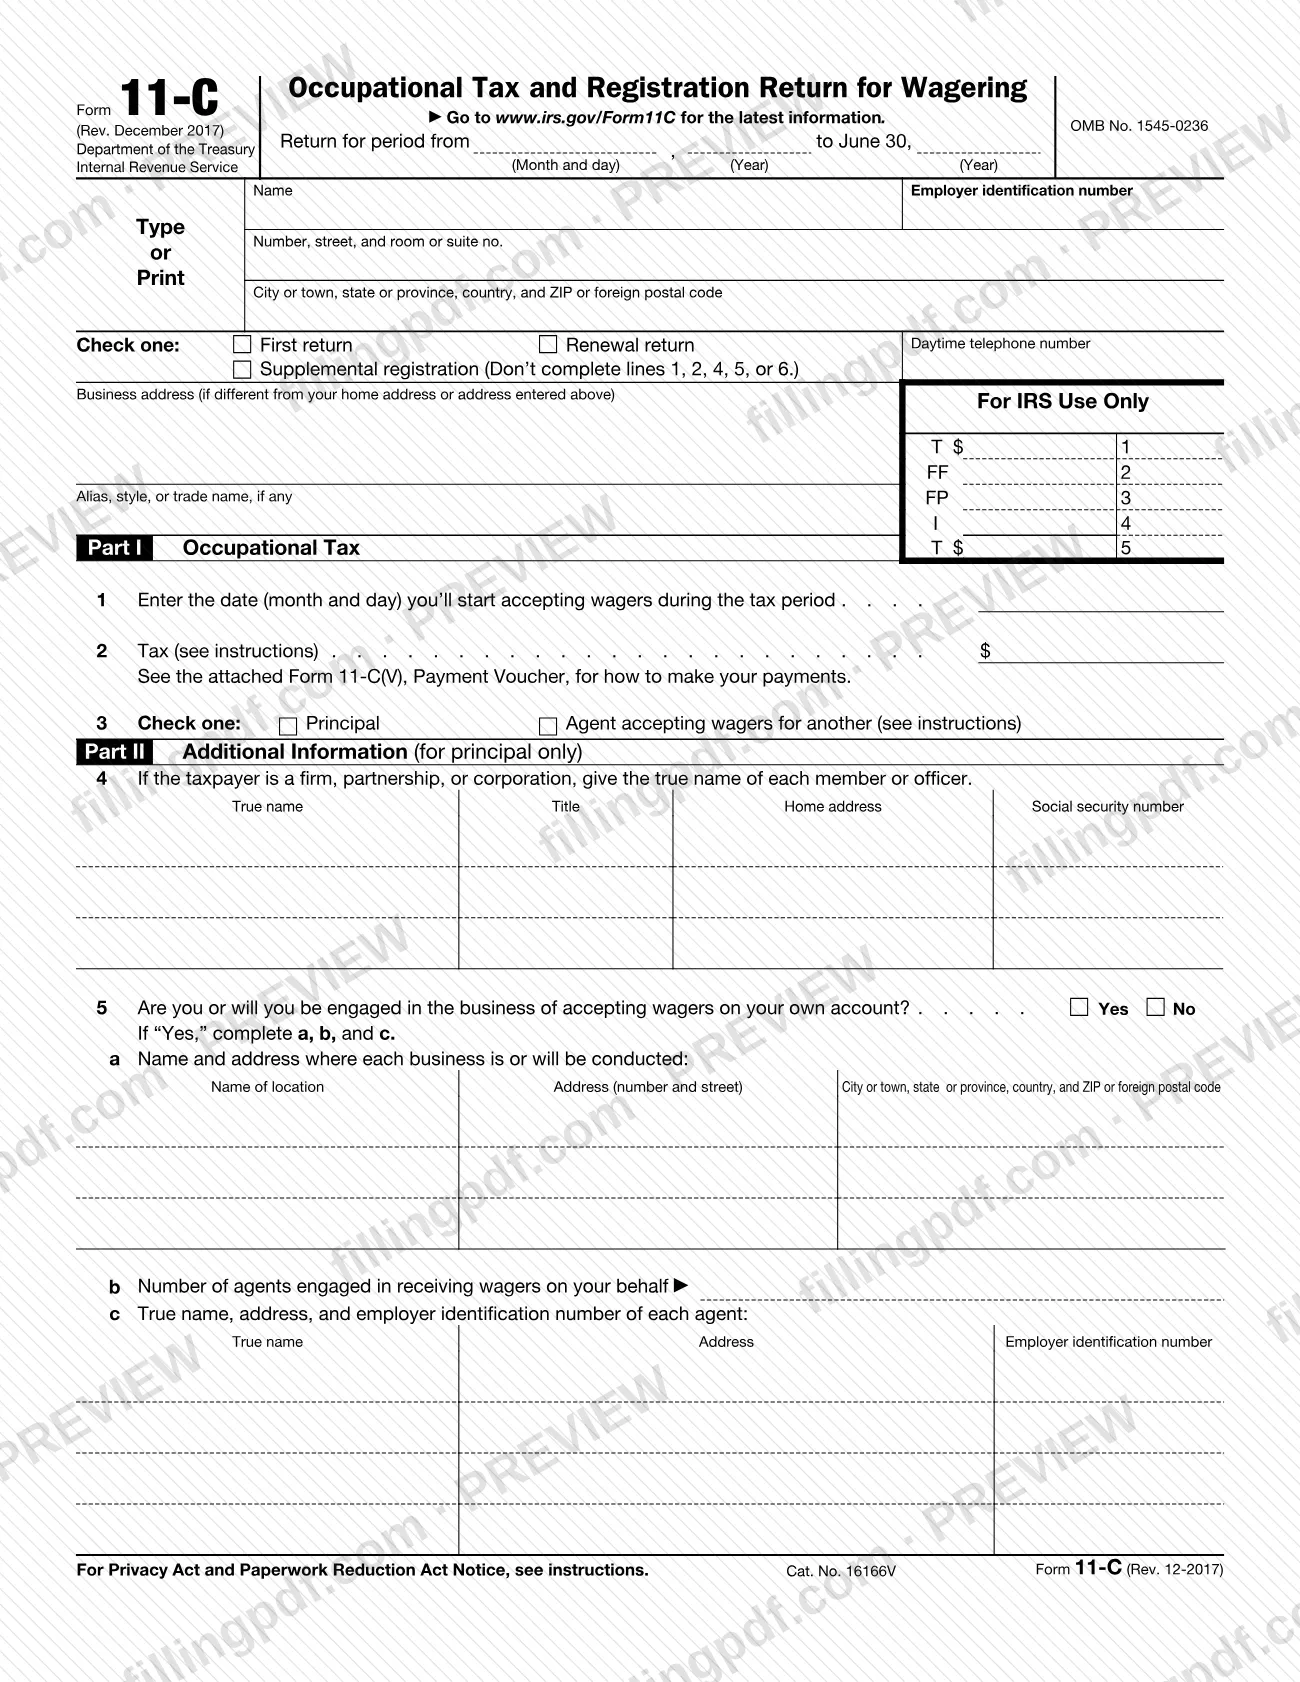
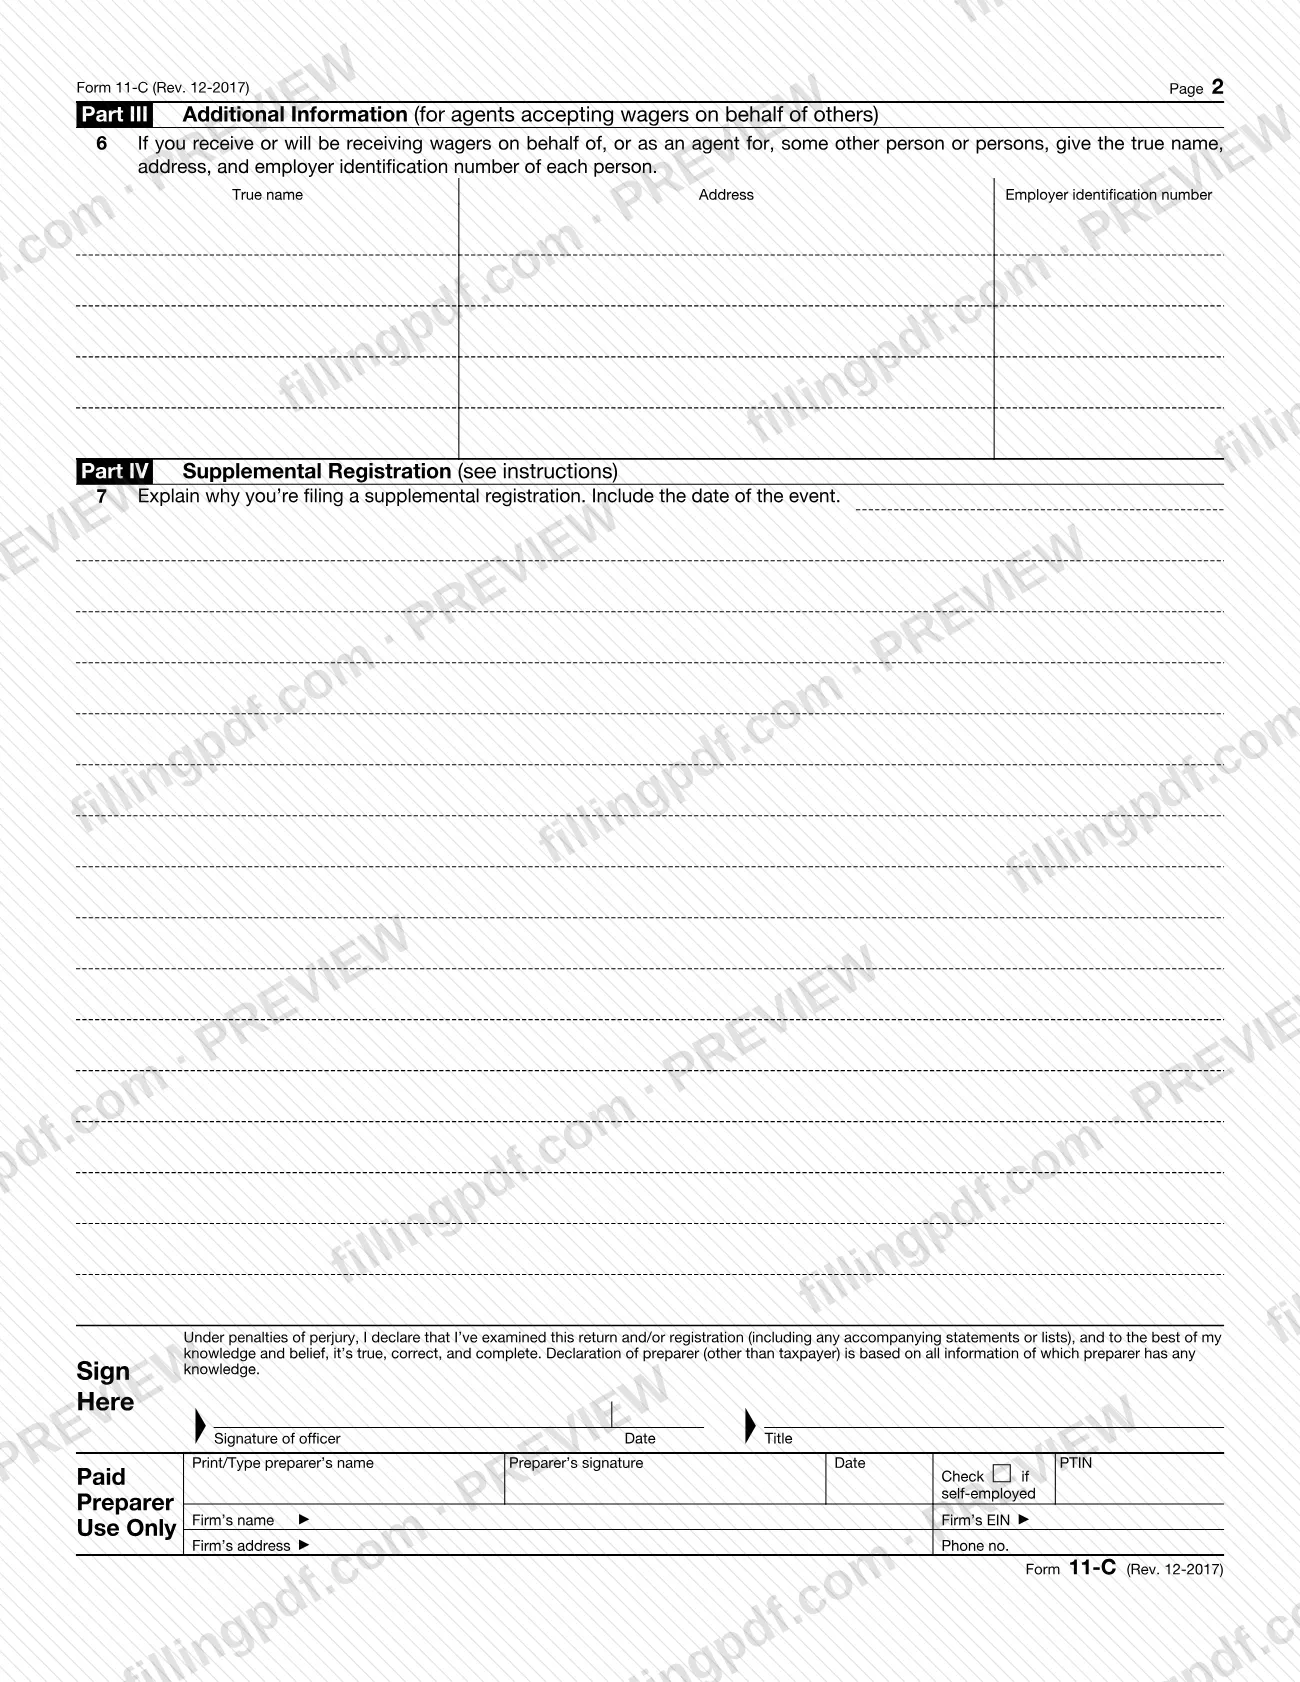
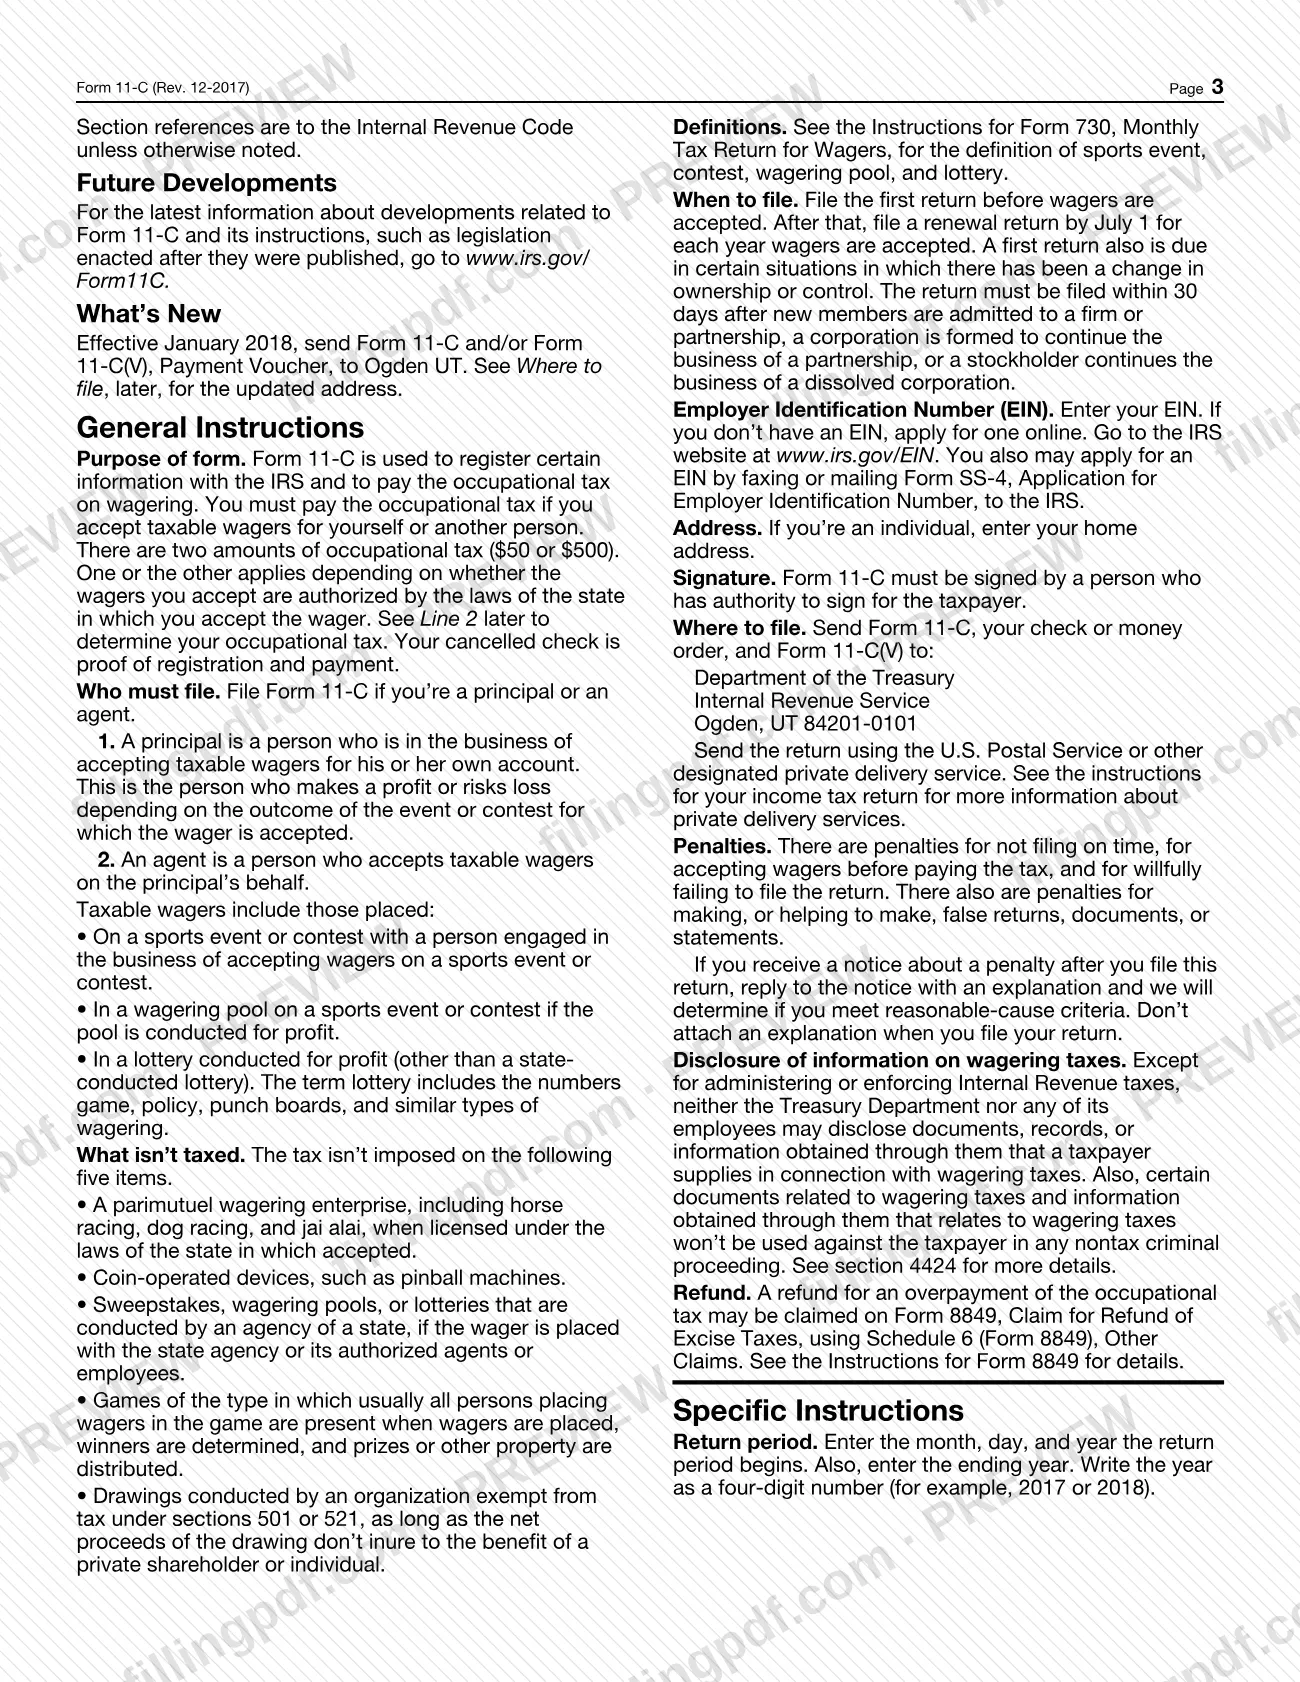
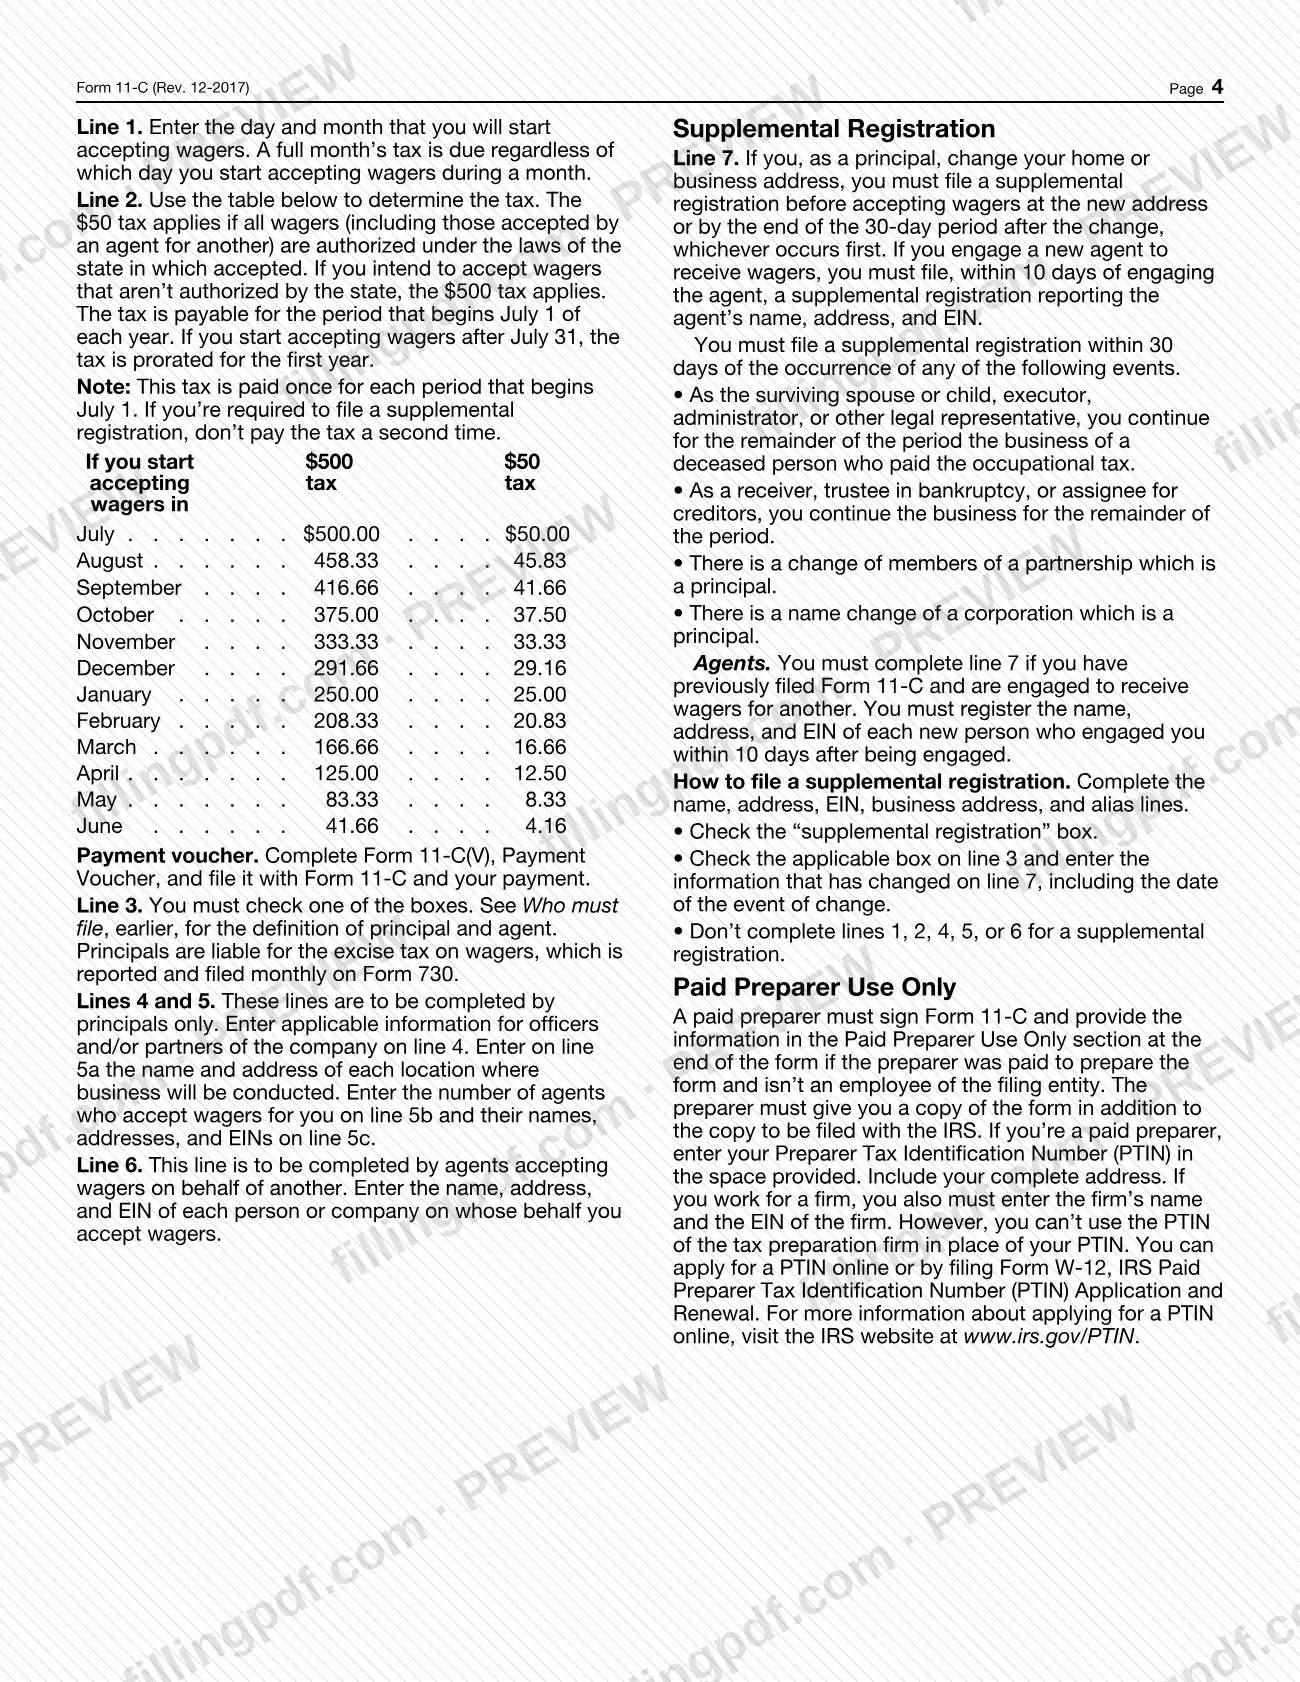
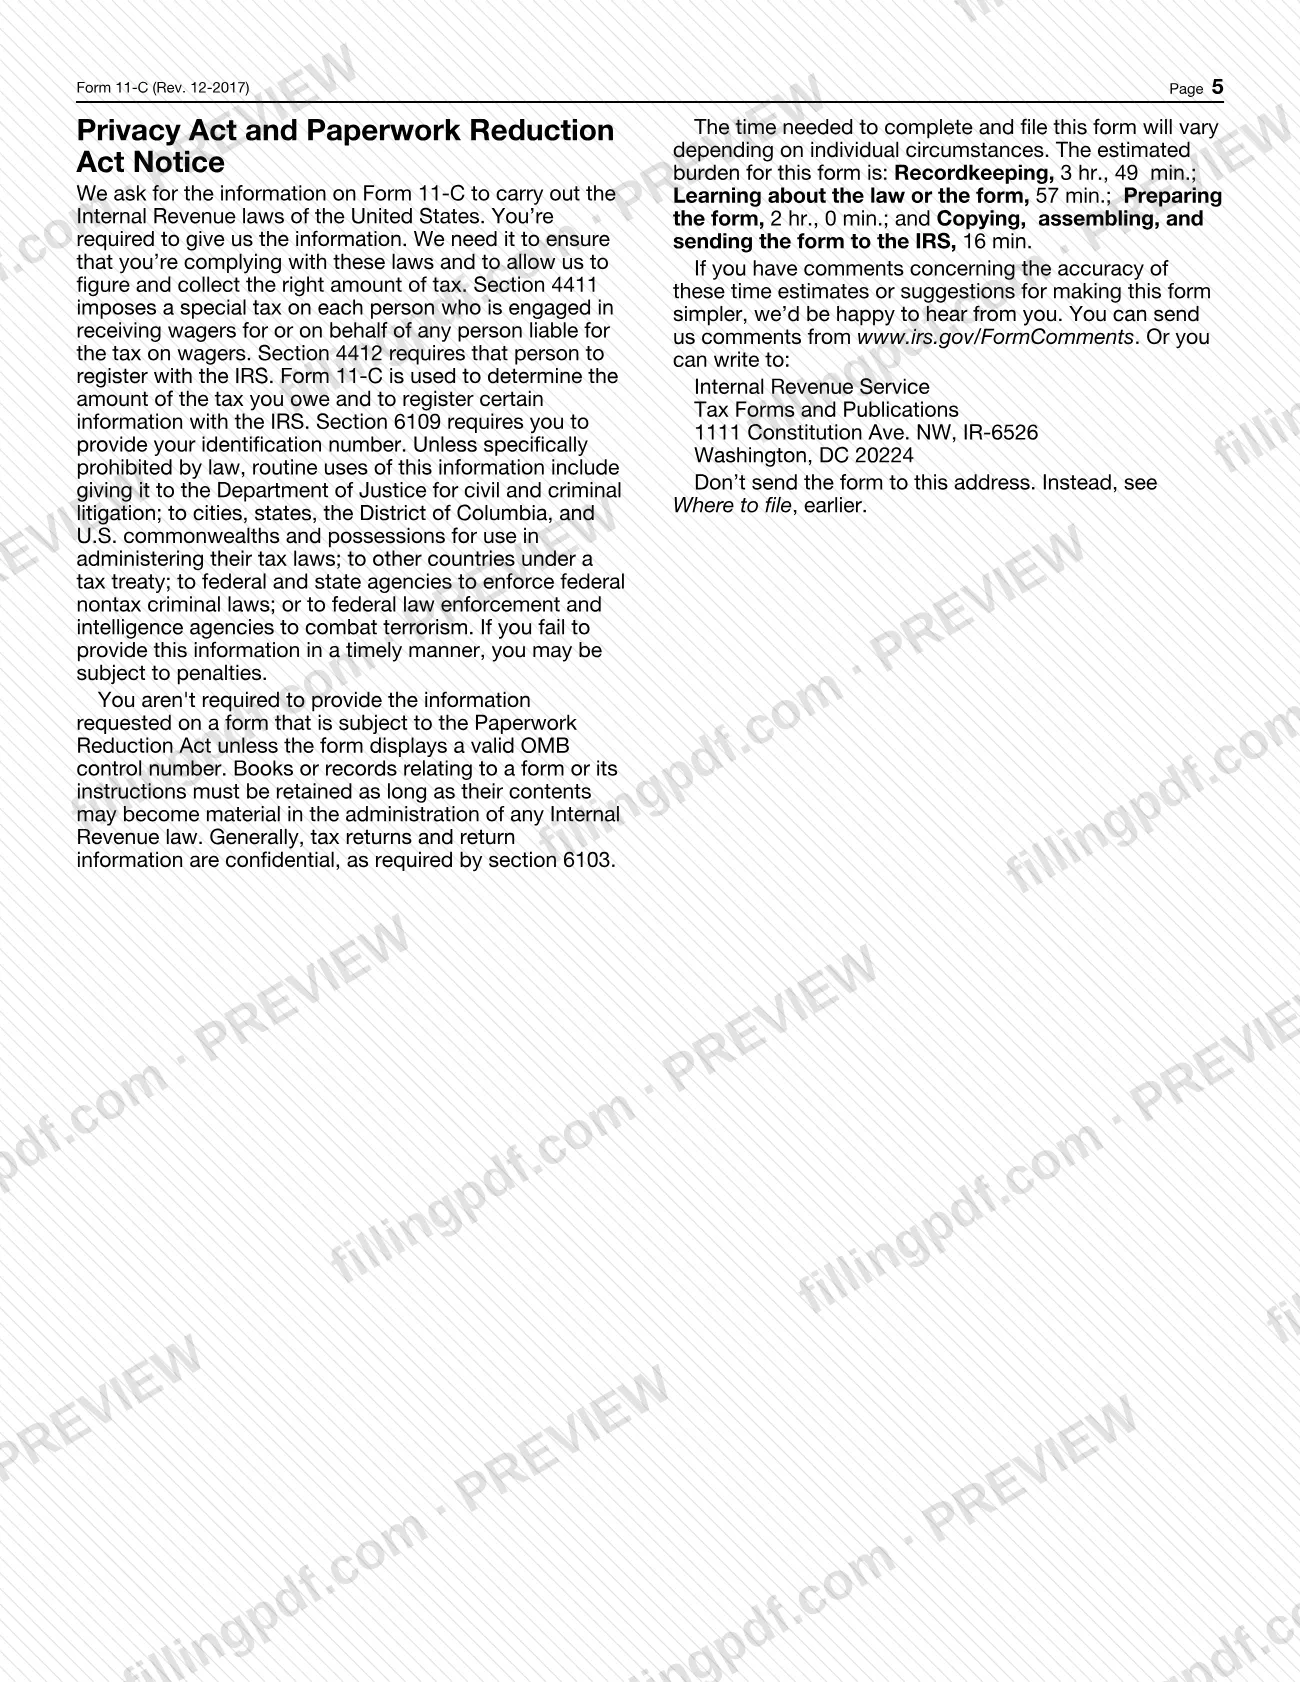
Form 11-C (often searched as 11C) is the Internal Revenue Service (IRS) return that registers a person who accepts taxable wagers and pays the occupational tax on wagering. Principals, who take wagers for their own account, and agents, who take wagers for someone else, both use it. On this page you can fill out Form 11-C online on FillingPDF and download or print the completed PDF. The IRS sets the filing rules, which are summarized below, and publishes the form and its latest information at www.irs.gov/Form11C.
Last updated
What is 11-C?
Form 11-C, Occupational Tax and Registration Return for Wagering, is the IRS form used to register certain information about a wagering business and to pay the occupational tax on wagering. It applies to anyone who accepts taxable wagers for themselves or for another person.
Two amounts of occupational tax exist, and which one applies depends on whether the wagers you accept are authorized by the laws of the state in which you accept them. The tax is paid once for each period that begins July 1. Your cancelled check is proof of registration and payment.
Taxable wagers include bets placed on a sports event or contest with a person in the business of accepting such wagers, wagers in a wagering pool on a sports event or contest conducted for profit, and wagers in a lottery conducted for profit, other than a state-conducted lottery. The instructions list what is not taxed, including parimutuel enterprises licensed under state law, coin-operated devices, state-agency sweepstakes, pools or lotteries, and certain drawings by tax-exempt organizations.
The form has four parts: Part I (occupational tax), Part II (additional information for principals), Part III (additional information for agents) and Part IV (supplemental registration). It travels with Form 11-C(V), Payment Voucher. Form 11-C is not the monthly excise tax return: principals report the excise tax on wagers monthly on Form 730, Monthly Tax Return for Wagers.
Who needs to file 11-C?
File Form 11-C if you are a principal or an agent who accepts taxable wagers.
- Principal: a person in the business of accepting taxable wagers for his or her own account, who makes a profit or risks a loss depending on the outcome of the event or contest.
- Agent: a person who accepts taxable wagers on the principal's behalf.
Principals complete Part II (lines 4 and 5). Agents accepting wagers for others complete Part III (line 6). Check one box on line 3 to say which you are.
You also use the form for a supplemental registration (Part IV) if you have already registered and a reportable change occurs, such as a new home or business address, a new agent, a change of members of a partnership that is a principal, a name change of a corporation that is a principal, or when you continue a business as a surviving spouse, executor, receiver, trustee in bankruptcy or assignee for creditors.
The return must be signed by a person who has authority to sign for the taxpayer. A paid preparer who is not an employee of the filing entity must also sign and complete the Paid Preparer Use Only section.
When to file 11-C
File the first Form 11-C before you accept wagers. After that, file a renewal return by July 1 for each year in which wagers are accepted. The tax period begins July 1, and if you start accepting wagers after July 31 the tax for the first year is prorated; a full month's tax is due for the month you start, whatever the day.
A first return is also due after certain changes in ownership or control, within 30 days after new members are admitted to a firm or partnership, a corporation is formed to continue a partnership's business, or a stockholder continues the business of a dissolved corporation.
A supplemental registration has its own timing. A principal who changes a home or business address files before accepting wagers at the new address or by the end of the 30 days after the change, whichever comes first. A new agent must be reported within 10 days of being engaged. The events listed for Part IV call for a filing within 30 days. The IRS instructions describe penalties for late filing and for accepting wagers before paying the tax.
Documents you need
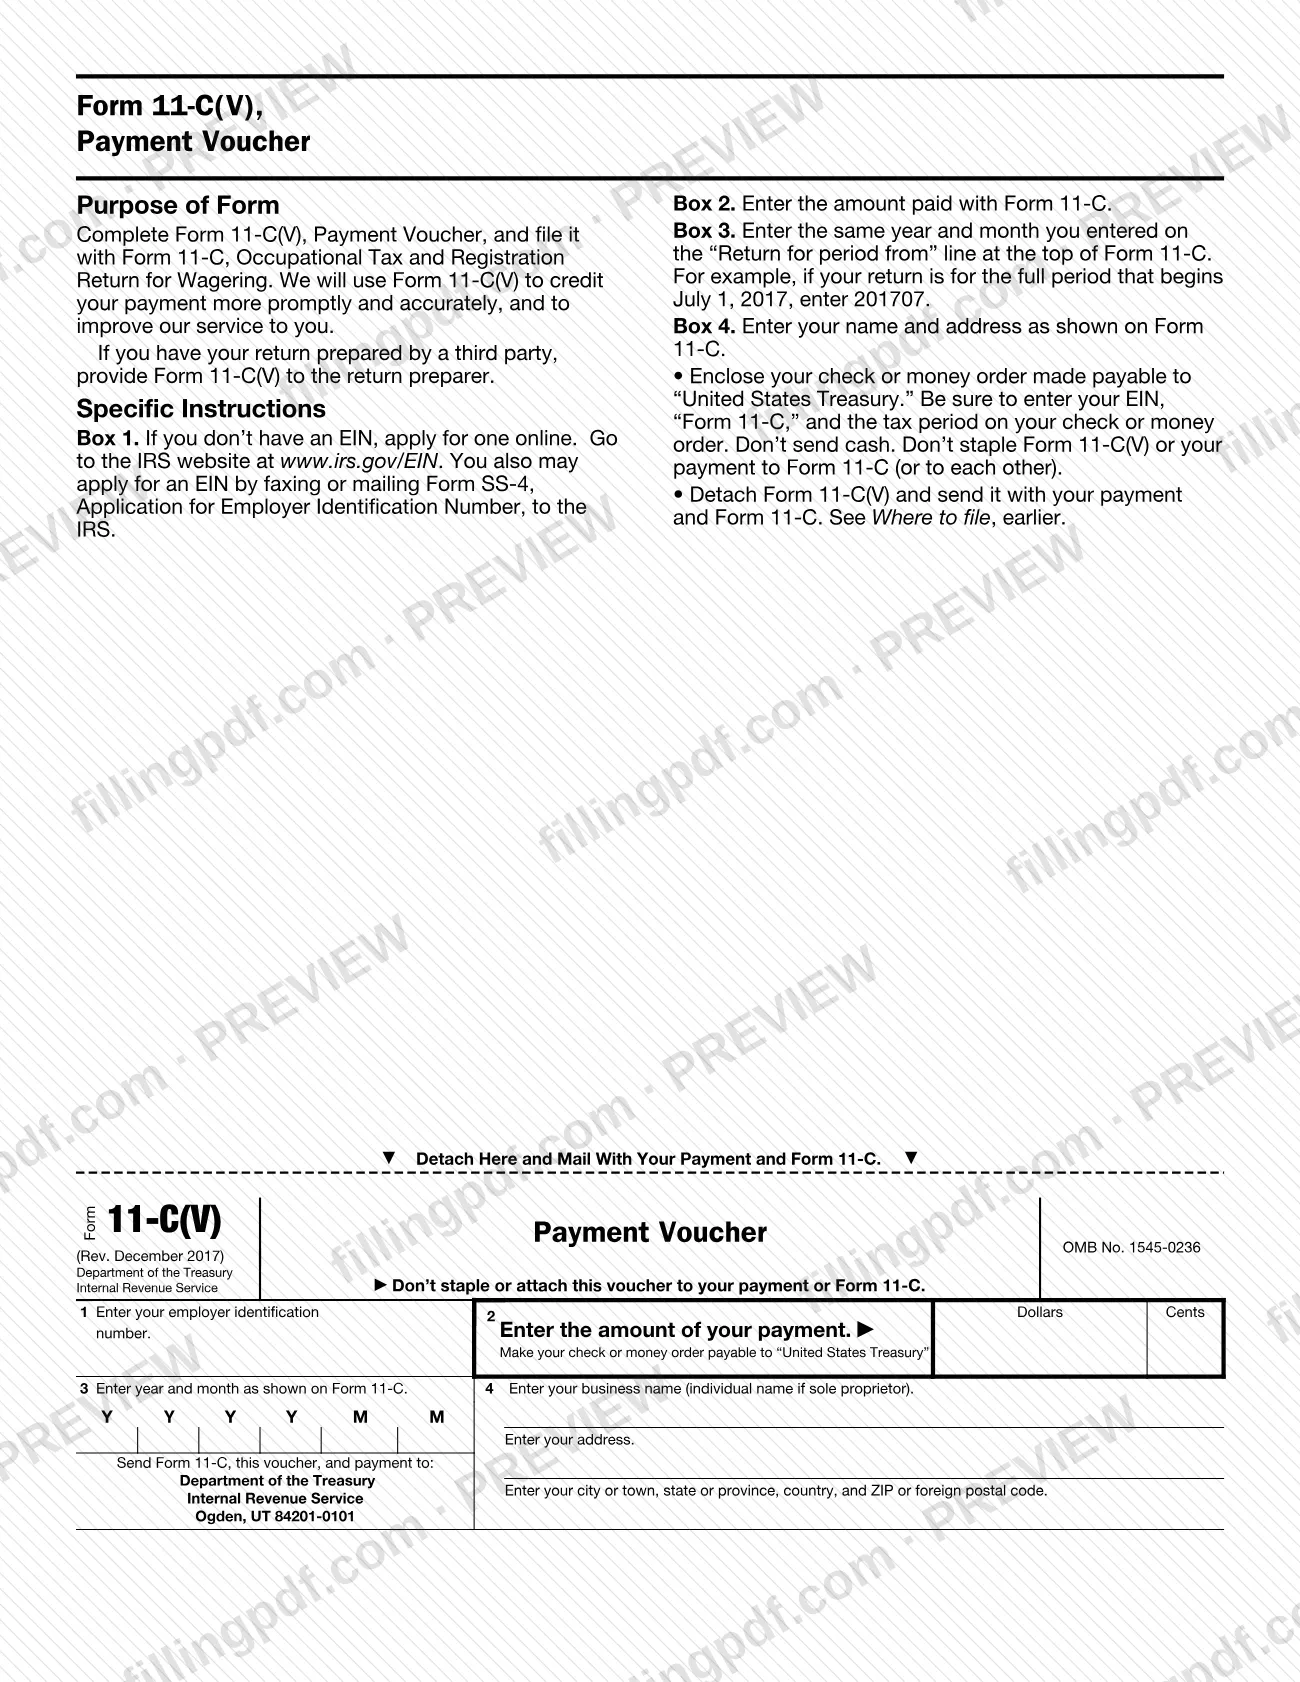
- Form 11-C(V), Payment Voucher: complete it and file it with Form 11-C and your payment; it is used to credit your payment.
- A check or money order payable to "United States Treasury" for the occupational tax, showing your EIN, "Form 11-C" and the tax period. Not required with a supplemental registration, where the tax is not paid a second time.
How to fill out 11-C
Enter the return period
At the top, enter the month, day and year the return period begins and the ending year (June 30 of that year). Write years as four digits.
Enter name, EIN and address
Type or print your name, employer identification number (EIN) and address; an individual enters a home address. If you have no EIN, apply at www.irs.gov/EIN or with Form SS-4.
Check the return type
Check one: First return, Renewal return or Supplemental registration. Add your daytime telephone number, any different business address and any alias, style or trade name.
Enter the start date on line 1
Line 1: enter the month and day you will start accepting wagers during the tax period. A full month's tax is due whatever the day you start.
Figure the tax on line 2
Line 2: use the table in the IRS instructions. The lower tax applies if all wagers are authorized under the laws of the state where accepted; the higher tax applies if any are not.
Check principal or agent on line 3
Check Principal or Agent accepting wagers for another. You must check one box.
Complete Part II if you are a principal
Line 4: give the true name, title, home address and Social Security number of each member or officer of a firm, partnership or corporation. Line 5: answer Yes or No; if Yes, complete 5a (locations), 5b (number of agents) and 5c (agents' names, addresses and EINs).
Complete Part III if you are an agent
Line 6: enter the true name, address and EIN of each person for whom you receive wagers.
Complete Part IV for a supplemental registration
Line 7: explain why you are filing and include the date of the event. Leave lines 1, 2, 4, 5 and 6 blank.
Prepare Form 11-C(V)
Enter your EIN in box 1, the payment amount in box 2, the year and month matching the return period in box 3 (YYYYMM) and your name and address in box 4.
Sign, review and download the PDF
An officer or authorized person signs and dates; a paid preparer completes the preparer section with a PTIN. Review every entry, then download or print the completed PDF from FillingPDF and assemble the package described under How to submit.
How to submit 11-C
Form 11-C is filed by mail, together with your payment and Form 11-C(V).
- Mail: send Form 11-C, your check or money order, and Form 11-C(V) to Department of the Treasury, Internal Revenue Service, Ogden, UT 84201-0101. Use the U.S. Postal Service or another designated private delivery service; the IRS refers you to the income tax return instructions for details on private delivery services.
- Payment: make the check or money order payable to "United States Treasury". Write your EIN, "Form 11-C" and the tax period on it. Do not send cash.
- Voucher: detach Form 11-C(V) and send it with the payment and the return. Do not staple the voucher or the payment to Form 11-C or to each other.
- Supplemental registration: do not pay the tax a second time.
Do not mail the form to the Washington, DC address printed for comments on the form; it is for comments only. An overpayment of the occupational tax can be claimed on Form 8849, Claim for Refund of Excise Taxes, using Schedule 6 (Form 8849). Do not attach an explanation of reasonable cause when you file; answer any penalty notice instead. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Stapling Form 11-C(V) or the payment to Form 11-C, or to each other; the instructions say not to.
- Sending cash instead of a check or money order payable to "United States Treasury".
- Mailing the return to the Washington, DC address for form comments instead of Ogden, UT 84201-0101.
- Completing lines 1, 2, 4, 5 or 6 on a supplemental registration; the form says not to.
- Paying the occupational tax again with a supplemental registration; the tax is paid once for each period beginning July 1.
- Accepting wagers before paying the tax, which the instructions list as a penalty situation.
- Leaving the line 3 box unchecked; you must check Principal or Agent accepting wagers for another.
- Entering a tax preparation firm's PTIN in place of the individual paid preparer's PTIN.
- Attaching a reasonable-cause explanation to the return instead of replying to a penalty notice.
Frequently asked questions
What is Form 11-C used for?
Form 11-C registers a person who accepts taxable wagers with the IRS and pays the occupational tax on wagering. Principals, who take wagers for their own account, and agents, who take them for others, both file it.
What is the 11c form people search for?
The 11c form is IRS Form 11-C, Occupational Tax and Registration Return for Wagering (Rev. December 2017). It is separate from Form 730, the monthly return on which principals report the excise tax on wagers.
When is Form 11-C due?
File the first return before you accept wagers, then a renewal return by July 1 for each year wagers are accepted. Changes in ownership or control, new agents and address changes carry shorter deadlines of 10 or 30 days, as described in the instructions.
Where do I mail Form 11-C?
Mail Form 11-C, your check or money order and Form 11-C(V) to Department of the Treasury, Internal Revenue Service, Ogden, UT 84201-0101, by U.S. Postal Service or another designated private delivery service.
Who is a principal and who is an agent on Form 11-C?
A principal is in the business of accepting taxable wagers for his or her own account and profits or risks loss from the outcome. An agent accepts taxable wagers on the principal's behalf. Check one box on line 3.
What is a supplemental registration on Form 11-C?
A supplemental registration reports a change after you have registered, such as a new address, a new agent or a change of partners. Check the supplemental box, complete line 3 and line 7, skip lines 1, 2, 4, 5 and 6, and do not pay the tax again.
Can I fill out Form 11-C online?
You can fill out the PDF online on FillingPDF and download or print it. FillingPDF does not file the return or accept payment for you; you mail the return, voucher and payment to the IRS.
How do I get a refund of the wagering occupational tax?
Claim an overpayment of the occupational tax on Form 8849, Claim for Refund of Excise Taxes, using Schedule 6 (Form 8849), Other Claims. The Instructions for Form 8849 give the details.
Ready to fill out 11-C?
Fill out 11-C now