
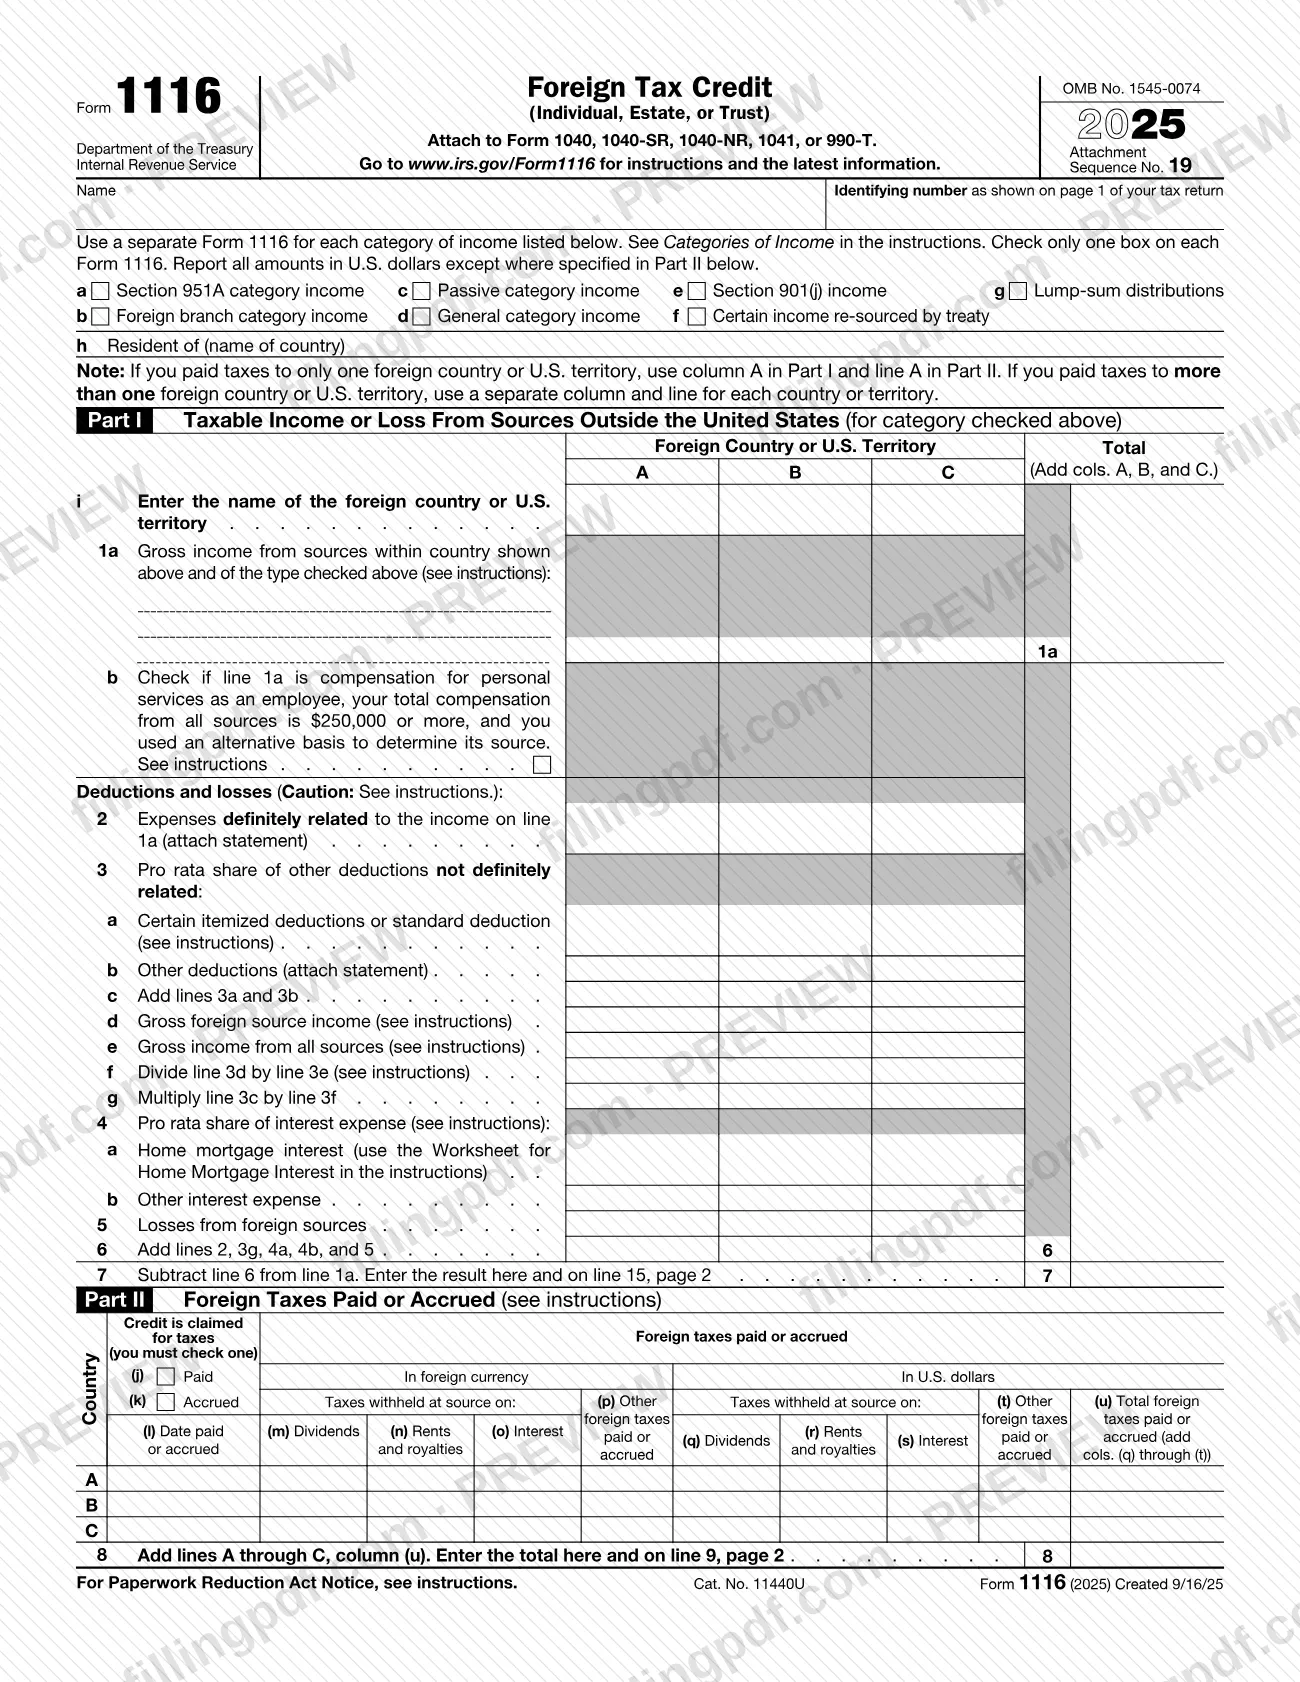
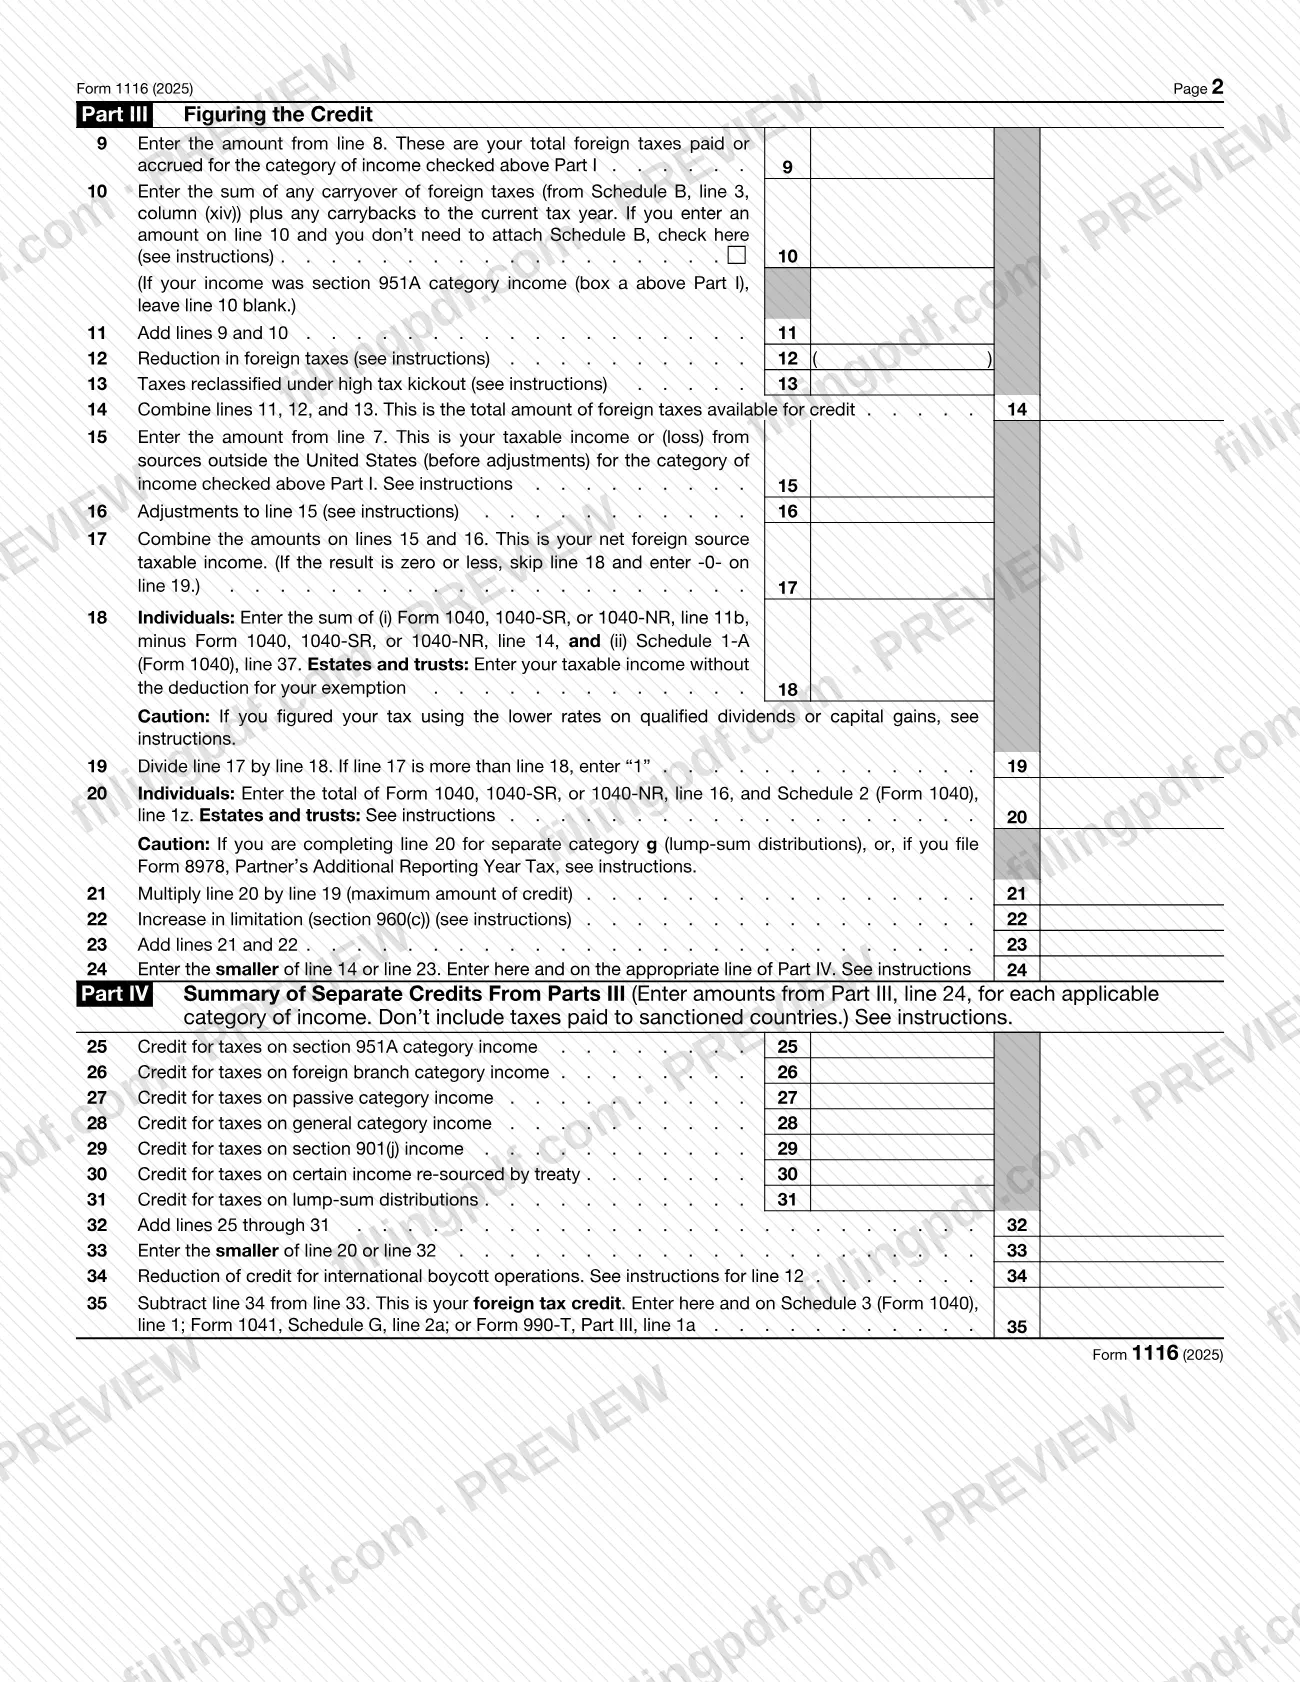
Form 1116, Foreign Tax Credit (Individual, Estate, or Trust), is the Internal Revenue Service (IRS) form that individuals, estates and trusts use to claim a credit for income taxes paid or accrued to a foreign country or U.S. territory. You complete a separate Form 1116 for each category of income and attach it to Form 1040, 1040-SR, 1040-NR, 1041 or 990-T. On this page you can fill out Form 1116 online on FillingPDF and download or print the completed PDF; the IRS publishes the form and its instructions at www.irs.gov/Form1116.
Last updated
What is 1116?
Form 1116, Foreign Tax Credit (Individual, Estate, or Trust), is the IRS form used to figure and claim the foreign tax credit for income, war profits and excess profits taxes paid or accrued to a foreign country or U.S. territory, attached to the filer's income tax return.
The Internal Revenue Service (IRS) issues the 2025 form under OMB No. 1545-0074 (Attachment Sequence No. 19). It has four parts. Part I reports taxable income or loss from sources outside the United States, after deductions and losses. Part II lists the foreign taxes paid or accrued, country by country. Part III figures the credit and applies the limitation that caps it. Part IV summarizes the separate credits and gives the final foreign tax credit.
A separate Form 1116 is needed for each category of income: section 951A category income, foreign branch category income, passive category income, general category income, section 901(j) income, certain income re-sourced by treaty, and lump-sum distributions. You check only one category box on each form.
Claiming the credit is an alternative to deducting foreign income taxes on Schedule A (Form 1040). Related schedules and forms include Schedule B (Form 1116) for carryovers, Schedule C (Form 1116) for foreign tax redeterminations and Form 7204 for contested foreign taxes. Form 1116 is not used for taxes paid to the U.S. Virgin Islands (Form 8689), and a filer who elects section 962 treatment claims the credit on Form 1118. The 2025 instructions add that lines 25 through 32 of Part IV must now be completed even when you file only one Form 1116.
Who needs to file 1116?
File Form 1116 if you are an individual, estate or trust that paid or accrued certain foreign taxes to a foreign country or U.S. territory and you want the foreign tax credit. The IRS instructions first ask whether you can use the election to claim the credit without filing the form.
You may not need the form. The election is available only if all of these are true:
- all of your foreign source gross income was passive category income;
- the income and the foreign taxes on it were reported to you on a qualified payee statement, such as Form 1099-DIV or 1099-INT;
- your total creditable foreign taxes are within the dollar limit given in the instructions.
Estates and trusts cannot make this election.
Exclusions and special cases:
- Do not use Form 1116 for taxes paid to the U.S. Virgin Islands; use Form 8689.
- Nonresident aliens generally cannot take the credit. Exceptions apply if you were a resident of Puerto Rico for your entire tax year, or if you paid tax on foreign source income effectively connected with a U.S. trade or business.
- If you make the section 962 election, you claim the credit based on your controlled foreign corporation's taxes on Form 1118. You still file Form 1116 for taxes imposed on distributions of earnings previously included in income and for other foreign taxes you paid or accrued.
When to file 1116
File Form 1116 with the income tax return for the year in which you claim the credit; it has no separate due date and travels with Form 1040, 1040-SR, 1040-NR, 1041 or 990-T. Generally the credit is taken in the year you paid or accrued the foreign taxes, depending on your accounting method. If you report on the cash basis, you can choose accrued taxes by checking the Accrued box in Part II on a timely filed original return, not on an amended return. Once you choose it, you credit foreign taxes in the year they accrue on all future returns.
You can make or change an election between credit and deduction within the limitation periods in the instructions: before the end of the 10-year period under section 6511(d)(3) to claim a credit, or the standard 3-year period under section 6511(a) to claim a deduction. Unused foreign taxes can generally be carried back 1 year and forward 10 years; section 951A category income has no carryovers. After a foreign tax redetermination, such as a refund of foreign tax, you generally file an amended return with a revised Form 1116.
Documents you need
- A statement listing the separate expenses included on line 2 (expenses definitely related to the foreign income on line 1a).
- A statement listing the separate expenses included on lines 3a and 3b (pro rata share of other deductions).
- Schedule B (Form 1116) for each applicable category, if you enter a carryover of foreign taxes on line 10 or generated a foreign tax carryover in the current year.
- Schedule C (Form 1116) for each applicable category, to report foreign tax redeterminations that occurred in the current year and relate to prior years.
- Form 7204, only if you elect to claim a provisional credit for contested foreign income taxes.
- A statement for line 1b, only if you check the box because you used an alternative basis to source employee compensation; the instructions list the details it must contain.
- A detailed explanation of how you figured the conversion rate, if you had to convert from foreign currency.
- A detailed statement of your computation on line 16, if you have more than one adjustment to line 15.
- A statement showing how you figured the reduction for international boycott operations, if line 34 applies (with Form 5713 as the instructions require).
- A statement identifying taxes, if you claim additional taxes from a foreign audit or are filing an amended return reflecting a foreign tax refund.
How to fill out 1116
Enter name, ID and category box
Enter your name and the identifying number shown on page 1 of your tax return. Check only one box, a through g, for the category of income on this form, and enter your country of residence on line h if it applies.
Identify the country and gross income
On line i enter the foreign country or U.S. territory, one per column (A, B, C). On line 1a enter gross income from that country of the type checked, and check line 1b only if the compensation conditions in the instructions apply.
Enter deductions on lines 2 to 5
Line 2: expenses definitely related to the line 1a income, with a statement. Lines 3a to 3g: your pro rata share of other deductions, including the standard deduction on 3a if you don't itemize; line 3f is line 3d divided by 3e, rounded to four places, no more than 1. Lines 4a, 4b and 5: interest expense and foreign losses.
Figure Part I taxable income
On line 6 add lines 2, 3g, 4a, 4b and 5. On line 7 subtract line 6 from line 1a, and carry the result to line 15 on page 2.
Complete Part II foreign taxes
For each country on lines A to C, check whether you claim the credit for taxes paid or accrued, give the date in column (l), and enter taxes in foreign currency (columns m to p) and in U.S. dollars (columns q to t). Column (u) totals each line; add lines A through C on line 8.
Figure foreign taxes available on lines 9–14
Line 9 is the line 8 amount. Add any carryover or carryback on line 10 (leave it blank for section 951A category income), then enter reductions on line 12 and any high tax kickout on line 13. Line 14 is the total available for credit.
Compute the limitation on lines 15–19
Enter line 7 on line 15, adjustments on line 16 and combine them on line 17; if zero or less, enter -0- on line 19. Line 18 is your taxable income figure as the form describes; divide line 17 by line 18 on line 19, entering "1" if line 17 is larger.
Finish Part III lines 20–24
Line 20: your total tax amount as the form describes for individuals, or see the instructions for estates and trusts. Multiply line 20 by line 19 on line 21, add any line 22 increase under section 960(c) on line 23, and enter the smaller of line 14 or line 23 on line 24.
Complete Part IV and the final credit
Enter each category's line 24 amount on lines 25 to 31 (excluding taxes paid to sanctioned countries) and total on line 32. Line 33 is the smaller of line 20 or line 32; subtract any line 34 boycott reduction to get the credit on line 35, and carry it to Schedule 3 (Form 1040), line 1; Form 1041, Schedule G, line 2a; or Form 990-T, Part III, line 1a.
Prepare attachments for each category
Complete a separate Form 1116 for each category of income, with Part IV on the form that has the larger line 24 amount. Prepare the statements and schedules your entries require, such as Schedule B (Form 1116) for carryovers.
Review and download the completed PDF
Check that only one category box is marked, that amounts are in U.S. dollars except in Part II, and that the line 35 total matches your return. Download or print the completed PDF from FillingPDF and attach it to your return as described under How to submit.
How to submit 1116
Form 1116 has no filing address of its own: you submit it as an attachment to the return it accompanies, Form 1040, 1040-SR, 1040-NR, 1041 or 990-T, through whichever channel you use for that return.
- With your return: attach each completed Form 1116, and the statements and schedules described under required documents, to the return. Enter the result of line 35 on Schedule 3 (Form 1040), line 1; Form 1041, Schedule G, line 2a; or Form 990-T, Part III, line 1a.
- Contested taxes: if you elect a provisional credit for contested foreign income taxes, file Form 7204 with the Form 1116 for the year the contested amount is paid.
- Questions: the instructions list Pub. 514, Foreign Tax Credit for Individuals. You can write to Internal Revenue Service, International Accounts, Philadelphia, PA 19255-0725, or call 267-941-1000 (not toll free) if you are overseas.
FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Using one Form 1116 for several categories of income; the form says to check only one box and use a separate form for each category.
- Entering foreign currency amounts outside Part II; the form says to report all amounts in U.S. dollars except where Part II specifies otherwise.
- Entering a carryover on line 10 of a Form 1116 for section 951A category income; the line must be left blank because carrybacks and carryovers aren't allowed.
- Claiming a credit for taxes paid to a sanctioned country (section 901(j) income) or including them in Part IV; that category is generally completed only through line 17.
- Entering more state and local taxes on lines 2 and 3a than the amount on Schedule A (Form 1040), line 5e.
- Leaving out the statements for lines 2, 3a and 3b that list the separate expenses.
- Entering on line 1a earned income you excluded on Form 2555.
- Using Form 1116 for taxes paid to the U.S. Virgin Islands instead of Form 8689.
- Skipping Part IV lines 25 through 32 because you file only one Form 1116; for 2025 they must be completed.
- Choosing the Accrued box on an amended return; the choice must be made on a timely filed original return.
Frequently asked questions
What is Form 1116 used for?
Form 1116 is the IRS form for claiming the foreign tax credit. Individuals, estates and trusts use it to figure the credit for income, war profits and excess profits taxes paid or accrued to a foreign country or U.S. territory, and attach it to their income tax return.
Do I have to file Form 1116 to claim the foreign tax credit?
Not always. You may claim the credit without the form if all your foreign source gross income was passive, it was reported on a qualified payee statement such as Form 1099-DIV, and your creditable foreign taxes stay within the instructions' dollar limit. Estates and trusts cannot use this election.
Do I need a separate Form 1116 for each type of income?
Yes. Use a separate Form 1116 for each category of income and check only one category box on each. If you had foreign dividends (passive) and wages (general), you complete two forms, then complete Part IV on the form with the larger line 24 amount.
Can I deduct foreign taxes instead of taking the credit?
Yes. You can choose to deduct foreign income taxes instead, on Schedule A (Form 1040) for Form 1040 or 1040-SR filers. Generally, if you take the credit for any eligible foreign taxes, you can't deduct any part of that year's foreign taxes, apart from the exceptions in the instructions.
Where do I send Form 1116?
You do not send it alone. Attach it to Form 1040, 1040-SR, 1040-NR, 1041 or 990-T and submit that return through its usual channel. Enter the line 35 credit on Schedule 3 (Form 1040), line 1; Form 1041, Schedule G, line 2a; or Form 990-T, Part III, line 1a.
Can a nonresident alien claim the foreign tax credit on Form 1116?
Generally no. The instructions allow it only if you were a resident of Puerto Rico for your entire tax year, or if you paid tax on foreign source income effectively connected with a U.S. trade or business. Section 906 and Pub. 514 give more detail.
What is the difference between Form 1116 and Form 1118?
Form 1116 is for individuals, estates and trusts. If you make the section 962 election to be taxed at corporate rates on certain controlled foreign corporation inclusions, the instructions say you claim the credit for that corporation's taxes by filing Form 1118.
What if I receive a refund of foreign taxes after claiming the credit?
You must file an amended return reducing the credited taxes by the refunded amount. Attach a revised Form 1116 and a statement. You may also need Schedule C (Form 1116) for redeterminations; failing to notify the IRS can bring a penalty unless there is reasonable cause.
Can I fill out Form 1116 online on FillingPDF?
Yes. You can fill out the fillable PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the form with the IRS; you submit it with your tax return through the IRS channels.
Ready to fill out 1116?
Fill out 1116 now