
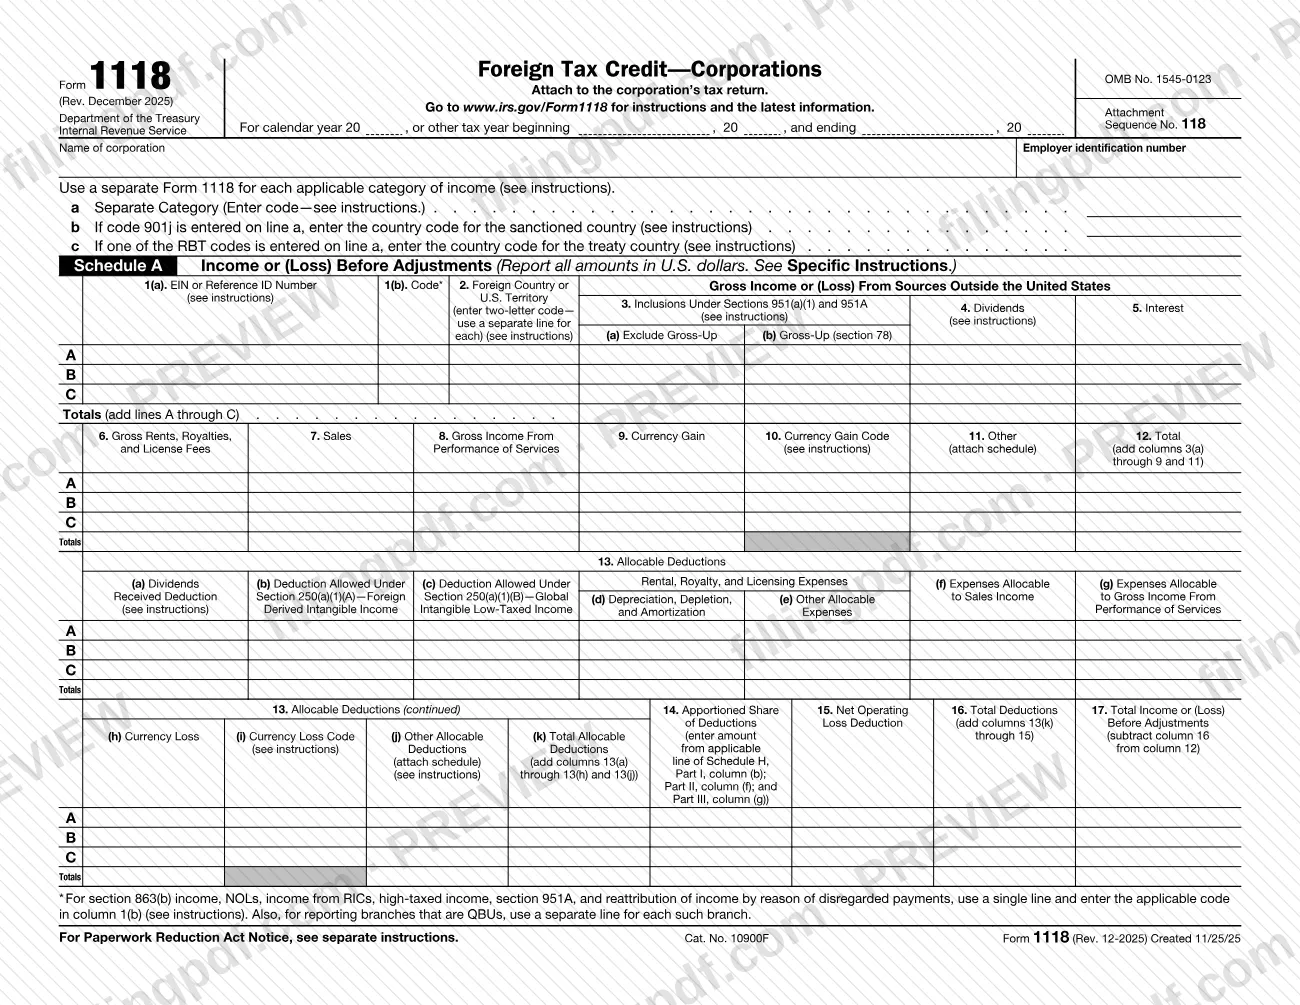
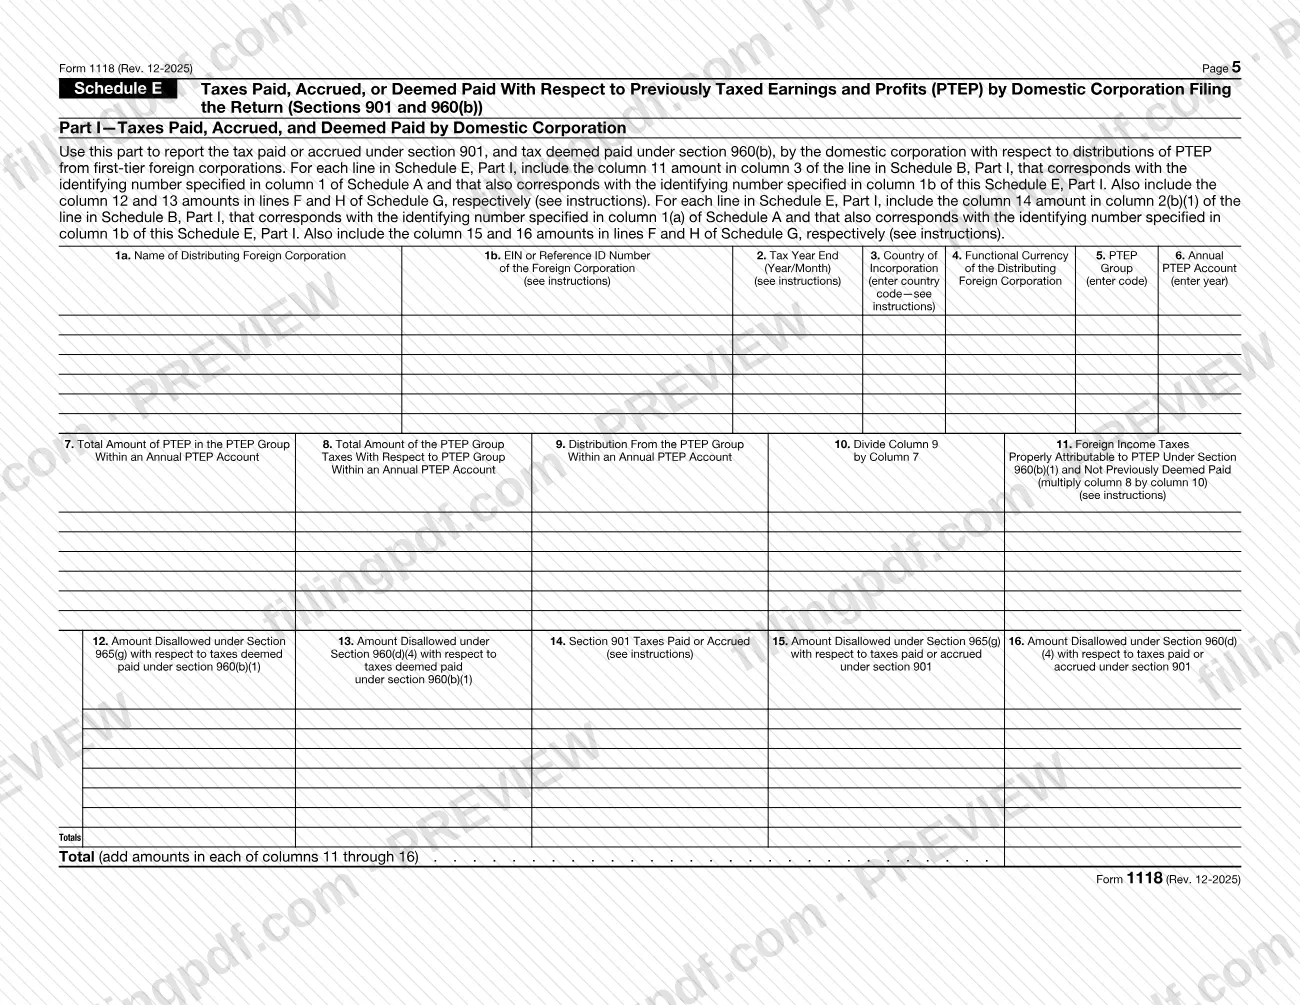
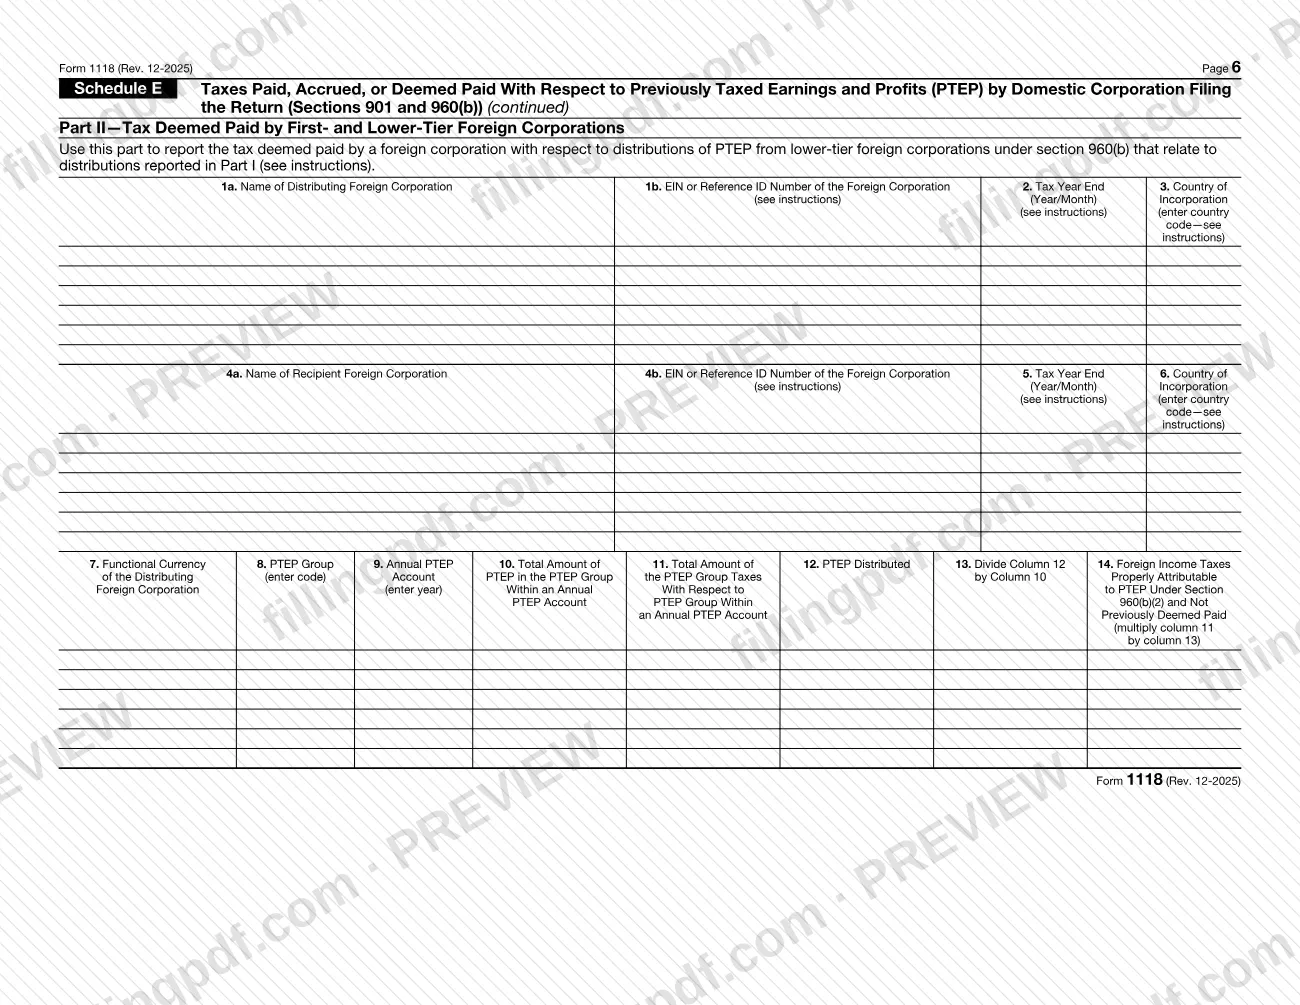
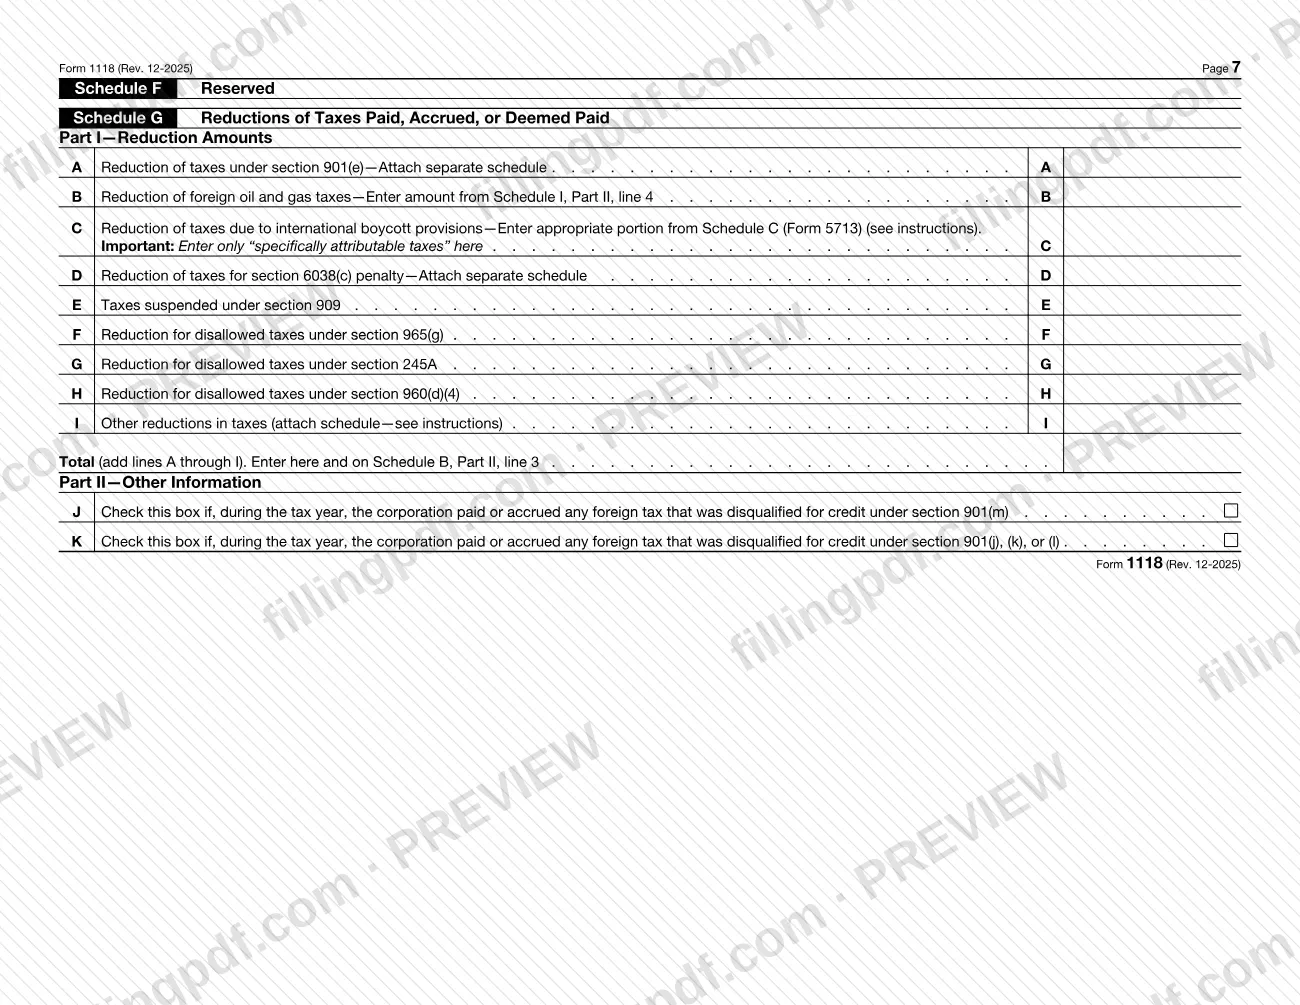
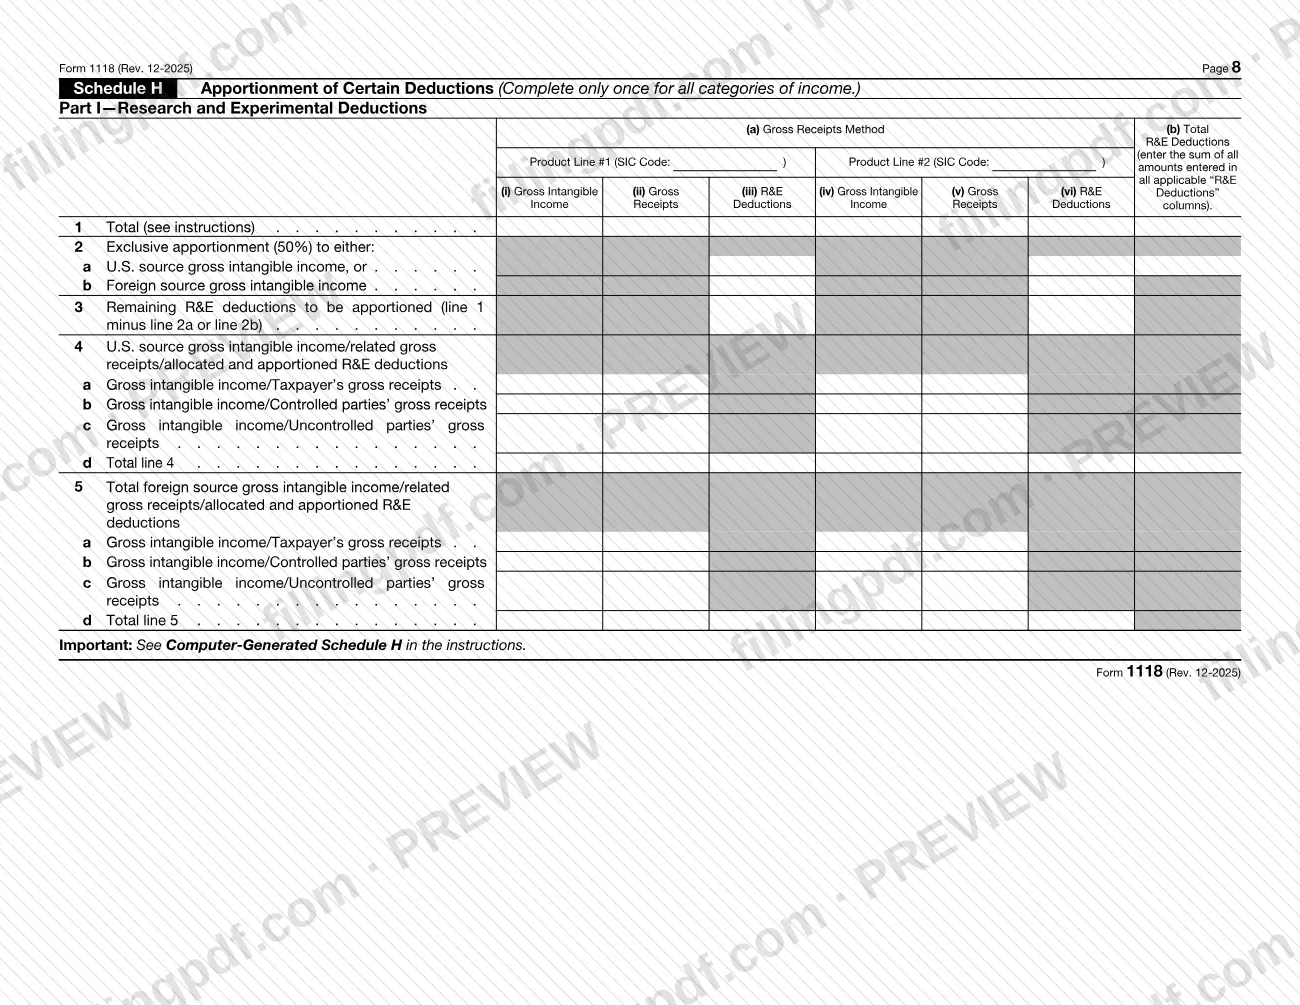
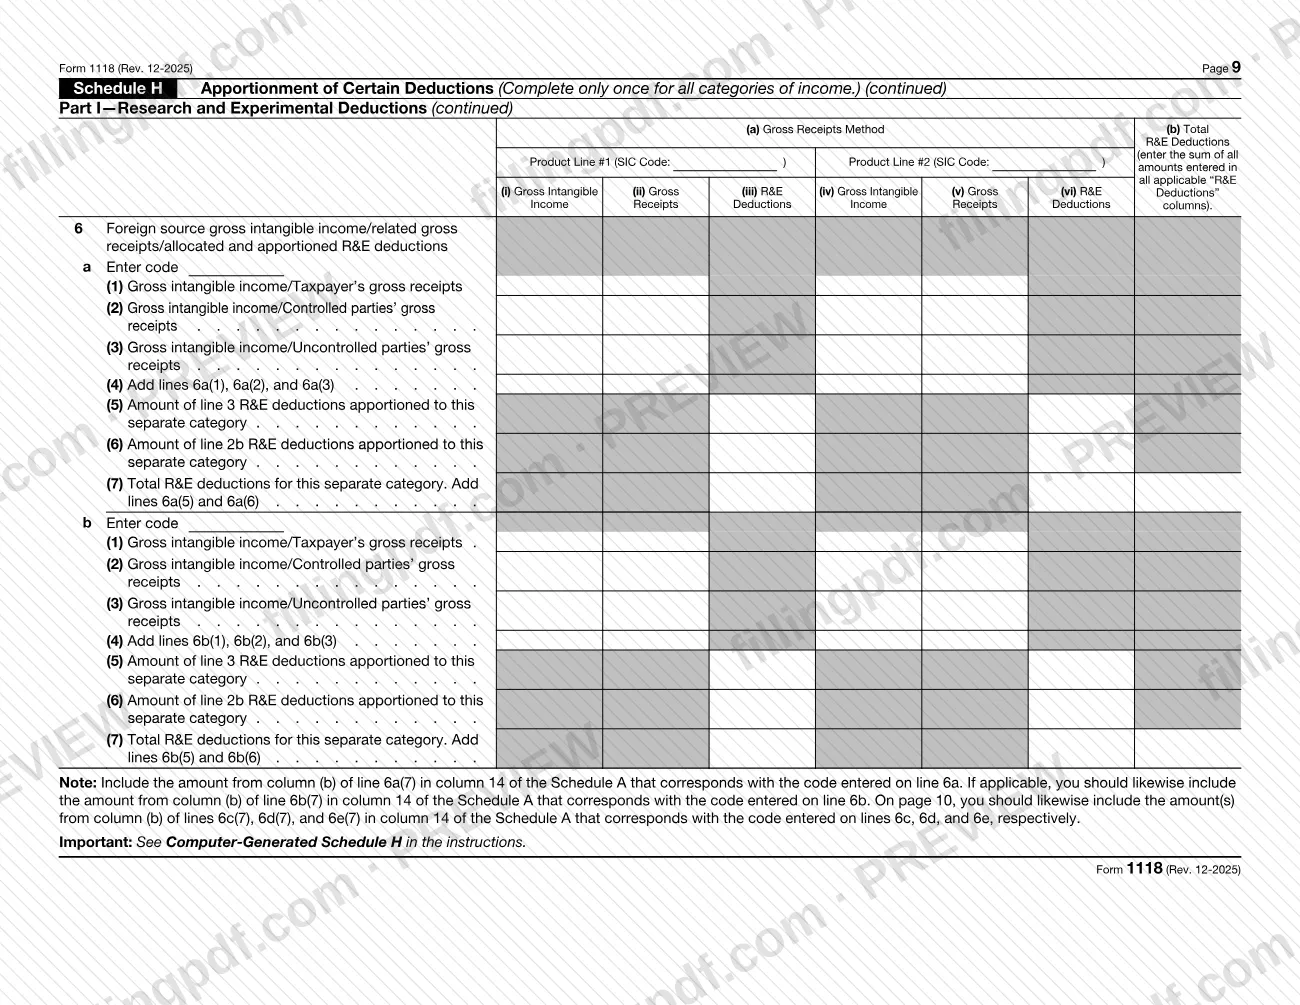
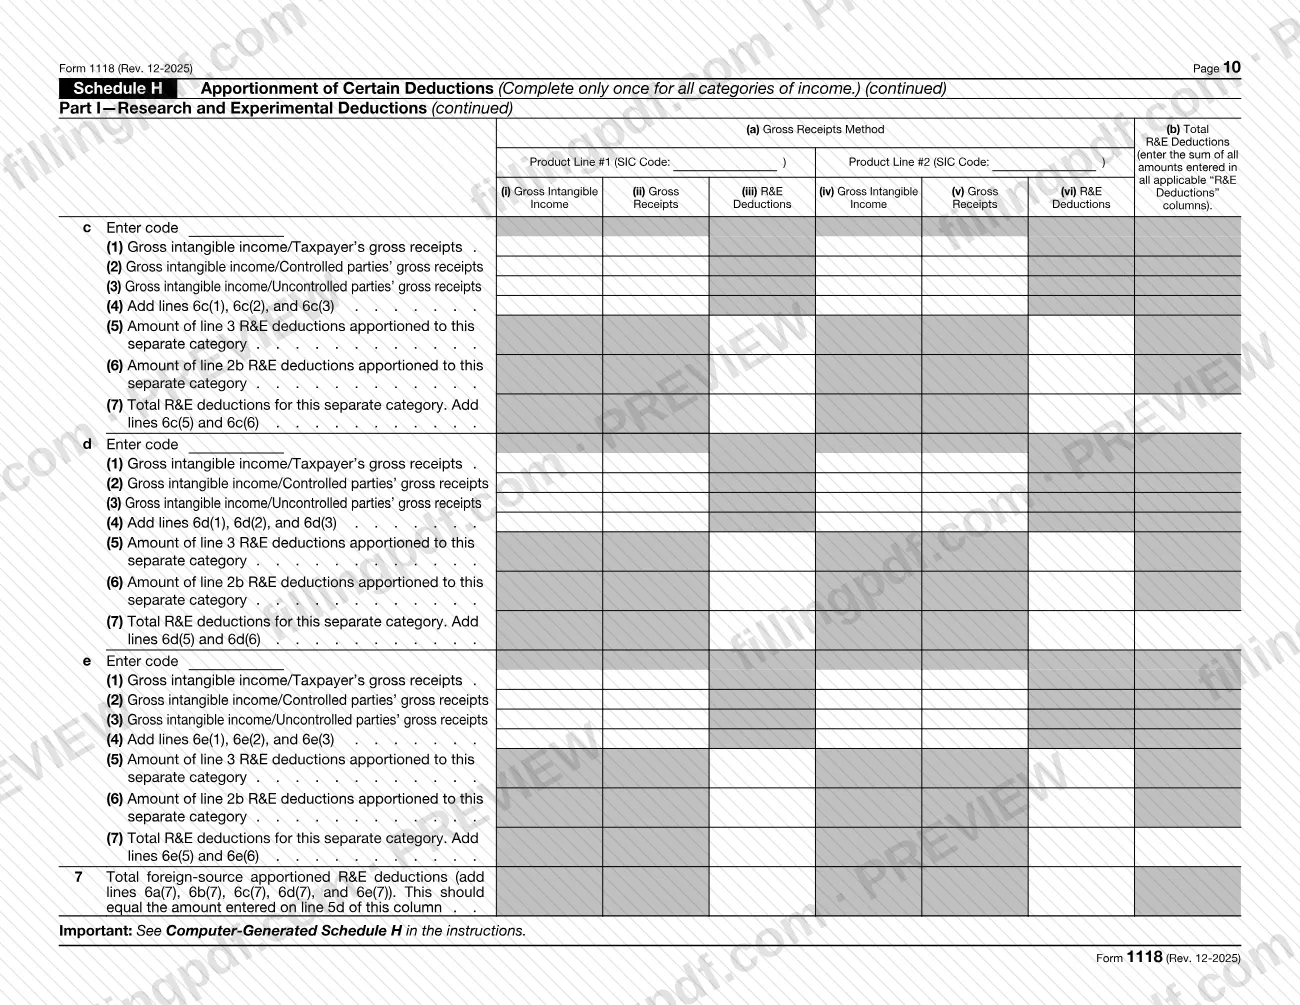
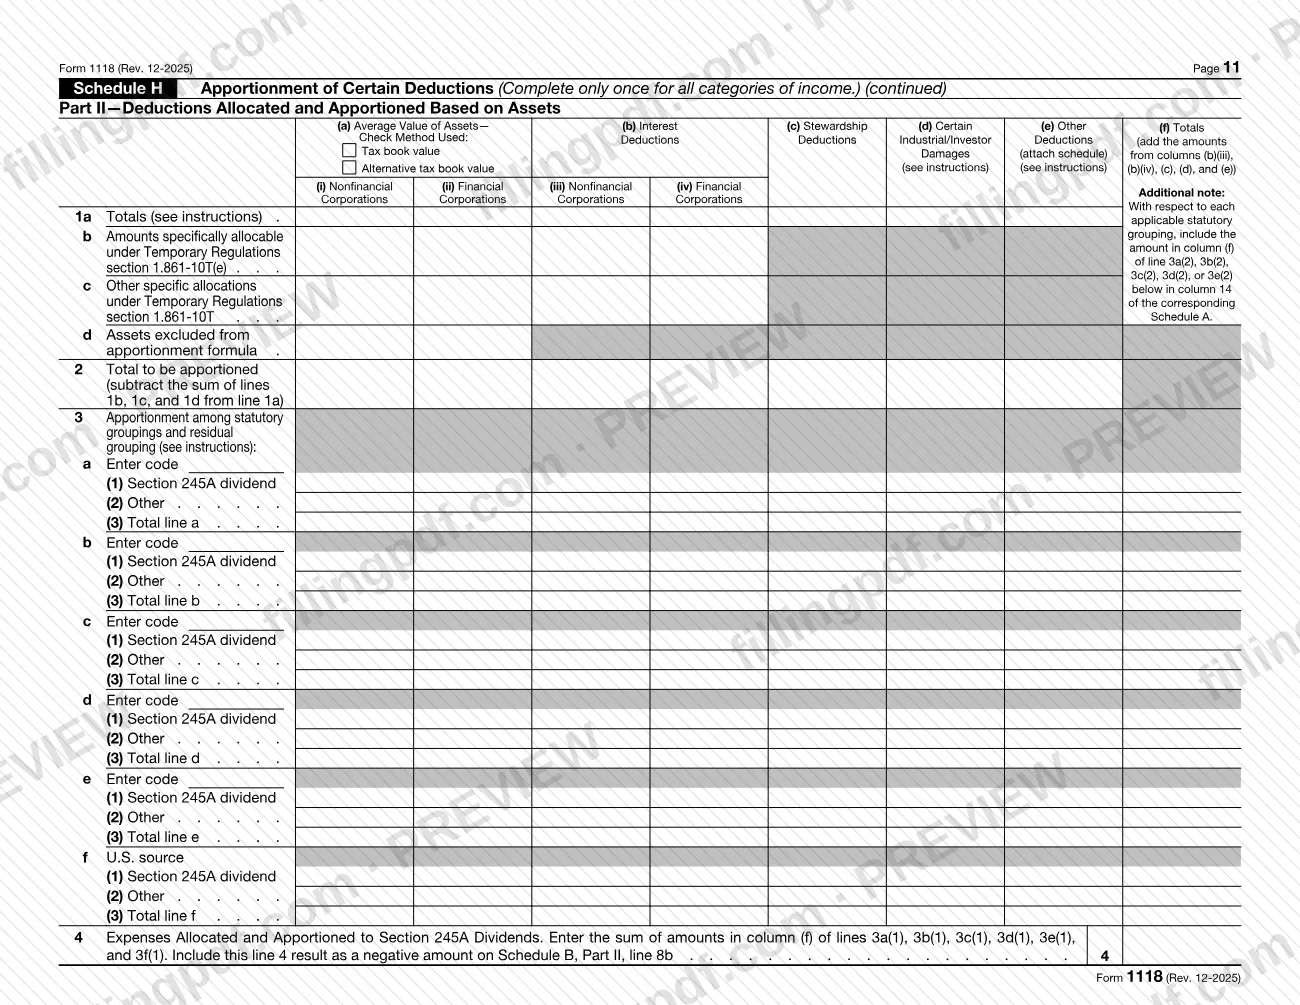
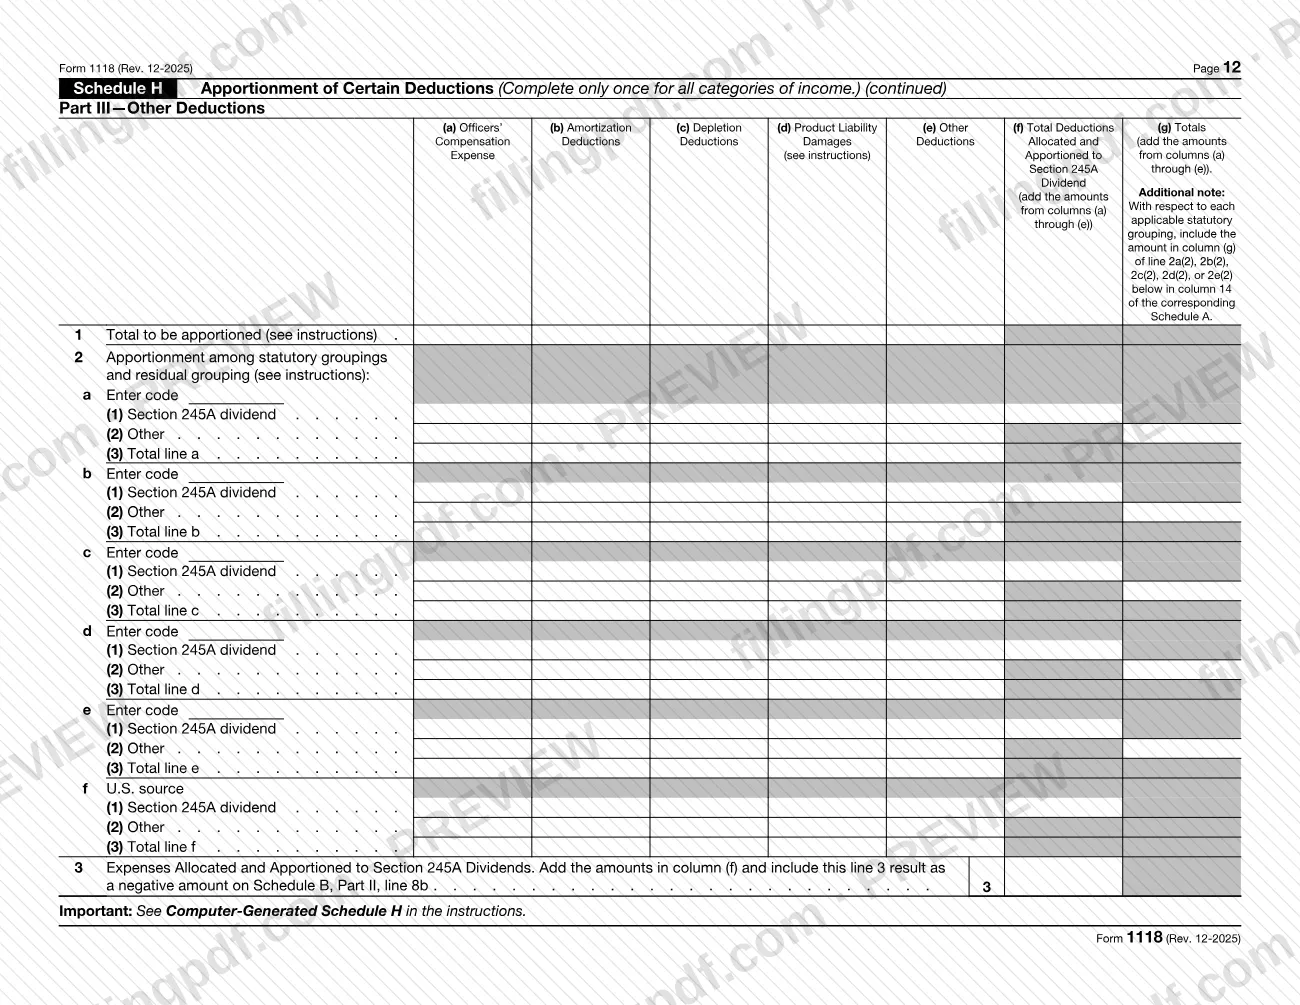
Form 1118, Foreign Tax Credit—Corporations, is the Internal Revenue Service (IRS) form a corporation attaches to its income tax return to compute the credit for income taxes paid or accrued to foreign countries or U.S. territories. A corporation that elects the foreign tax credit under section 901 completes a separate Form 1118 for each applicable category of income. On FillingPDF you can fill out the form online and download or print the completed PDF; the form and its instructions are published by the IRS at www.irs.gov/Form1118.
Last updated
What is 1118?
Form 1118, Foreign Tax Credit—Corporations, is the IRS form a corporation completes and attaches to its income tax return to compute the credit for income taxes paid or accrued to foreign countries or U.S. territories, and for taxes deemed paid under section 960.
The form is printed under OMB No. 1545-0123 and says to attach it to the corporation's tax return. It is built from schedules:
- Schedule A figures income or (loss) before adjustments for one category of income.
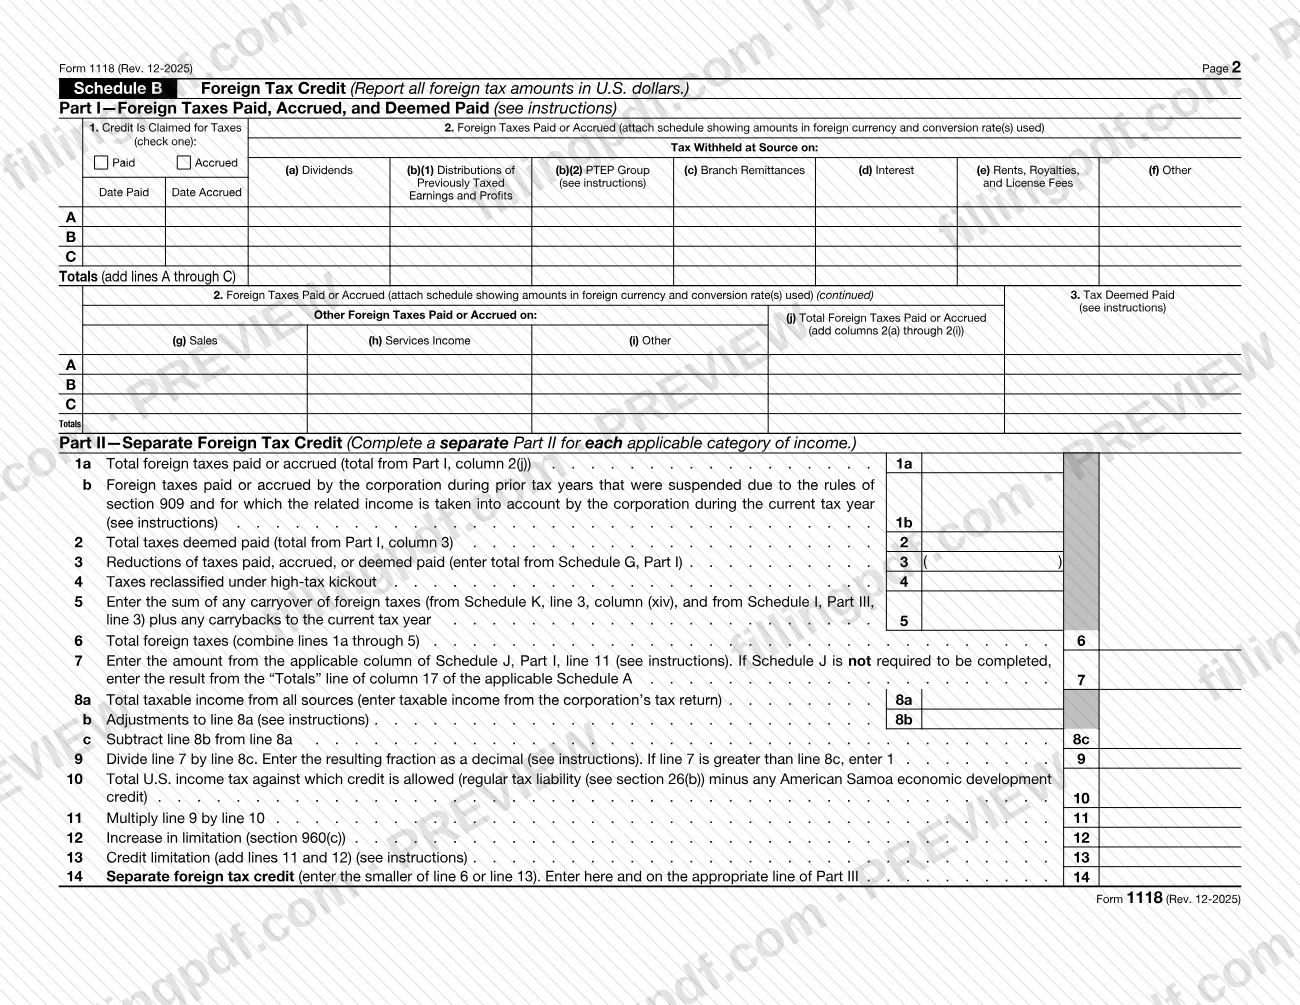
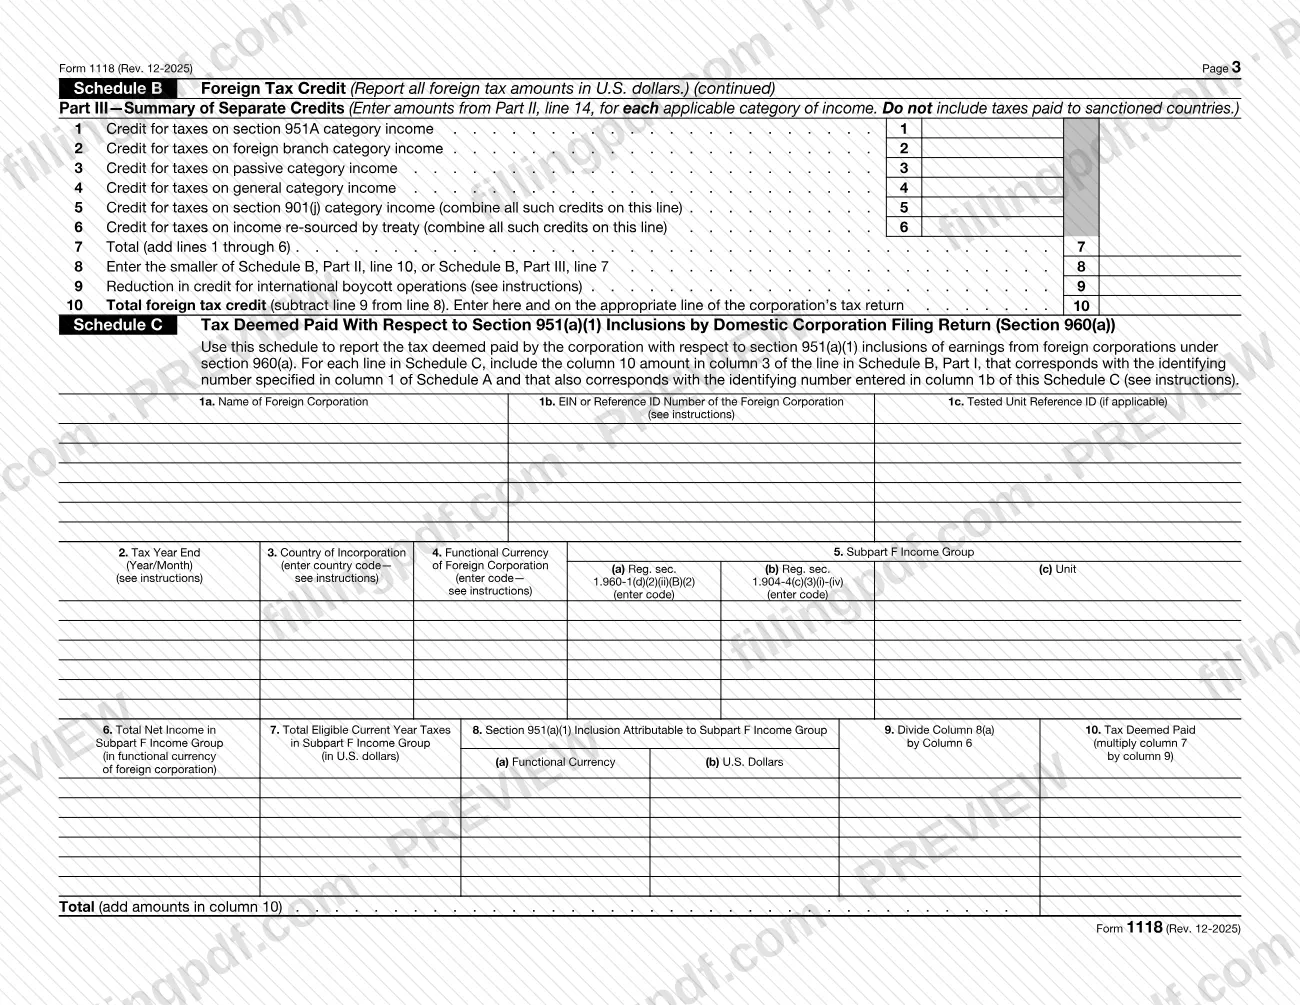
- Schedule B reports foreign taxes paid, accrued and deemed paid (Part I), computes the separate credit and its limitation (Part II) and summarizes the separate credits (Part III).
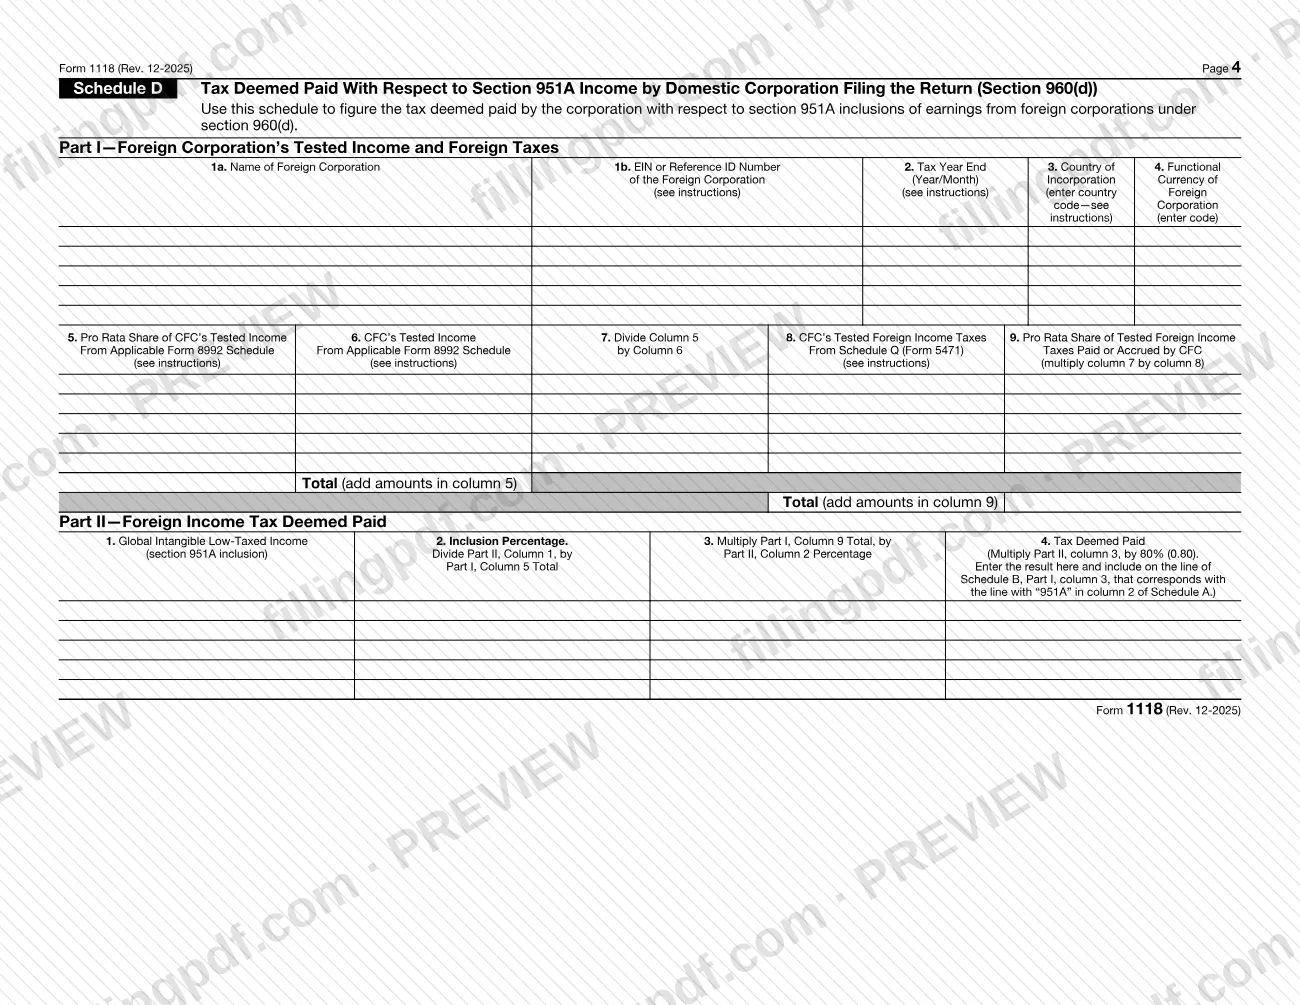
- Schedules C, D and E report taxes deemed paid on section 951(a)(1) inclusions, on section 951A income and on previously taxed earnings and profits (PTEP).
- Schedule G reports required reductions of taxes, and Schedule H apportions certain deductions. Schedule F is marked Reserved.
Separate schedules published by the IRS accompany the form: Schedule I (foreign oil and gas reductions), Schedule J (adjustments to separate limitation income or losses), Schedule K (foreign tax carryover) and Schedule L (foreign tax redeterminations). The December 2025 revision reflects new section 960(d)(4), a new line H on Schedule G, and a split of Schedule B, Part I, column 2(b).
Form 1118 is not used to determine foreign tax credits for the corporate alternative minimum tax (CAMT) under section 55; the instructions point to a revised Form 4626 for that.
Who needs to file 1118?
Any corporation that elects the benefits of the foreign tax credit under section 901 must complete Form 1118 and attach it to its income tax return.
Some corporations must attach part of the form even without electing the credit:
- A corporation with additions to, reductions to, or recapture of any new or existing overall foreign loss, overall domestic loss or separate limitation loss account must complete and attach Schedule A and Schedule J (Form 1118).
- A corporation with a foreign tax redetermination under section 905(c) must attach Schedule L (Form 1118) for the year the redetermination occurs, whether or not it changed U.S. tax liability.
Individuals must also complete and attach Form 1118 if they make the section 962 election to be taxed at corporate rates on amounts included under sections 951(a) and 951A from controlled foreign corporations, in order to claim a credit for their share of the foreign taxes. Foreign corporations can claim a credit under section 906 for foreign income taxes on income effectively connected with a U.S. trade or business.
A corporation that chooses to deduct foreign income taxes instead of claiming the credit does not elect the credit; the choice is made annually.
When to file 1118
Form 1118 is filed with the corporation's income tax return for the tax year of the credit, so it has no separate due date of its own.
The election to claim the credit for any tax year can be made or changed at any time before the end of the special 10-year period described in section 6511(d)(3) (or section 6511(c) if that period is extended by agreement). The election to deduct foreign income taxes instead of crediting them can be made or changed before the end of the period in section 6511(a) or 6511(c).
If a foreign tax redetermination changes U.S. tax liability for any year, the corporation must file an amended return with Form 1118 and a statement. If it changes nothing, the corporation attaches a completed Schedule L (Form 1118) to the original return for the year the redetermination occurs. Excess credits carried back to an earlier year require an amended return with a revised Form 1118 and Schedule K.
Documents you need
- A separate Form 1118 for each applicable category of income, attached to the corporation's income tax return.
- A schedule showing foreign-currency amounts and the conversion rates used, when you convert foreign taxes to U.S. dollars on Schedule B, Part I.
- A statement explaining how the conversion rate was determined, when amounts on the form are converted from a foreign currency.
- A schedule identifying the gross income by type for Schedule A, column 11, and a schedule listing the deductions in column 13(j).
- Schedule I (Form 1118) and Schedule K (Form 1118), when Schedule B, Part II, line 5 includes a carryover of foreign taxes.
- Form 8833, Treaty-Based Return Position Disclosure Under Section 6114 or Section 7701(b), when the corporation relies on a U.S. treaty to claim a credit for a foreign tax.
- Form 5713, International Boycott Report, when the corporation participates in or cooperates with an international boycott and the credit may be reduced.
- Schedule L (Form 1118), when a foreign tax redetermination occurred, and Form 7204 when electing a provisional credit for contested foreign income taxes.
- Receipts or a foreign tax return are not attached, but must be provided on IRS request to substantiate the credit; the IRS may also require a bond on Form 1117 for taxes accrued but not paid.
How to fill out 1118
Enter the tax year and corporation
At the top, enter the calendar year or the beginning and ending dates of the tax year, the name of the corporation and its employer identification number.
Enter the category code on line a
Complete a separate form for each category and enter its code on line a, such as 951A, FB, PAS, GEN, 901j or an RBT code. For code 901j, enter the sanctioned country code on line b; for an RBT code, enter the treaty country code on line c.
Report income on Schedule A
For each line A, B or C, enter the EIN or reference ID in column 1(a), any aggregation code in column 1(b) and the two-letter country code in column 2. Report gross income in columns 3(a) through 11 and total it in column 12, in U.S. dollars.
Report deductions on Schedule A
Enter allocable deductions in columns 13(a) through 13(j), the apportioned share from Schedule H in column 14 (totals line only) and any NOL deduction in column 15. Add columns 13(k) through 15 in column 16 and subtract it from column 12 in column 17.
Enter foreign taxes on Schedule B, Part I
Check Paid or Accrued in column 1 and show the dates. Enter taxes paid or accrued in columns 2(a) through 2(i), the total in 2(j), and taxes deemed paid in column 3, on lines matching Schedule A.
Compute the separate credit in Part II
Total the taxes on lines 1a through 6, enter the limitation figures on lines 7 through 13, and enter the smaller of line 6 or line 13 on line 14. Line 9 is line 7 divided by line 8c, as a decimal.
Summarize credits in Schedule B, Part III
On one Form 1118 only, enter each Part II, line 14 amount on lines 1 through 6, total them on line 7, complete lines 8 through 10, and carry line 10 to the corporation's tax return. Do not include taxes paid to sanctioned countries.
Complete Schedules C and D if they apply
Use Schedule C for tax deemed paid on section 951(a)(1) inclusions under section 960(a) and Schedule D for section 951A income under section 960(d). Carry the results to Schedule B, Part I, column 3.
Complete Schedule E for PTEP taxes
Use Part I for taxes on PTEP distributions from first-tier foreign corporations and Part II for tax deemed paid by first- and lower-tier foreign corporations. Follow the cross-references to Schedule B and Schedule G printed in the Part I heading.
Report reductions on Schedule G
Enter reductions on lines A through I of Part I and total them for Schedule B, Part II, line 3. Check box J or K in Part II if a tax was disqualified under section 901(m) or 901(j), (k) or (l).
Apportion deductions on Schedule H
Complete Schedule H once for all categories: Part I for research and experimental deductions, Part II for asset-based deductions and Part III for other deductions. Carry the amounts to column 14 of the matching Schedule A.
Review and download the completed PDF
Check each category form, the schedule totals and the attachments the instructions require, then download or print the completed PDF from FillingPDF and attach it to the corporation's tax return.
How to submit 1118
Form 1118 is not filed on its own: you attach it to the corporation's income tax return and send the package through the channels that apply to that return.
- With the original return: attach a separate Form 1118 for each applicable category of income, plus the schedules and statements that apply, such as a schedule showing foreign-currency amounts and the conversion rates used.
- With an amended return: for a foreign tax redetermination that increases U.S. tax liability, attach an amended Form 1118 and the required statement to Form 1120-X, and enter on page 2 of Form 1120-X the sentence the instructions give. For a carryback, file an amended return with a revised Form 1118 and Schedule K.
- Computer-generated forms: the IRS accepts them if they conform to the IRS version; software must be approved by the IRS for substitute forms (see Pub. 1167).
Receipts or foreign tax returns do not have to be attached, but you must produce them if the IRS asks. The form prints no separate mailing address. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Combining several categories of income on one Form 1118; the instructions require a separate form, with its own line a code, for each applicable category.
- Entering "FOREIGNUS" or "APPLIED FOR" in an EIN column; use a reference ID number that uniquely identifies the entity instead.
- Using a reference ID number with spaces or special characters, or longer than 50 characters; it must be alphanumeric.
- Reporting the section 951A inclusion net of the section 250 deduction in Schedule A, column 3(a); the deduction goes in column 13(c).
- Completing Schedule B, Part III on every form; it is completed only once, on the Form 1118 with the largest Part II, line 14 amount.
- Skipping the schedule of foreign-currency amounts and conversion rates when foreign taxes are converted to U.S. dollars.
- Entering line 8b adjustments with the wrong sign: taxable income that should not count is positive; adjustments that increase net worldwide income are negative.
- Using Form 1118 to compute foreign tax credits for the corporate alternative minimum tax; the instructions direct taxpayers to a revised Form 4626.
- Relying on a U.S. treaty to claim a credit without attaching Form 8833 to Form 1118.
Frequently asked questions
What is Form 1118 used for?
Form 1118 is the IRS form a corporation uses to compute its foreign tax credit for income taxes paid or accrued to foreign countries or U.S. territories, and taxes deemed paid under section 960. It is attached to the corporation's income tax return.
Who has to file Form 1118?
Any corporation that elects the foreign tax credit under section 901 must complete and attach it. Without the election, a corporation still attaches Schedule A and Schedule J in the loss-account cases, and Schedule L for a foreign tax redetermination. Individuals with a section 962 election also file it.
Do I need a separate Form 1118 for each category of income?
Yes. The form says to use a separate Form 1118 for each applicable category of income, with the code on line a: 951A, FB, PAS, 901j, an RBT code or GEN. Schedule B, Part III, Schedule H and Schedule J are completed only once.
Do I attach foreign tax receipts to Form 1118?
No. The instructions say documentation such as receipts or a foreign tax return is not required to be attached. You must present proof if the IRS asks for it to substantiate the credit, and the IRS may require a bond on Form 1117 for taxes accrued but not paid.
How long do I have to claim or change the foreign tax credit election?
You can make or change the election to claim the credit at any time before the end of the special 10-year period in section 6511(d)(3), or section 6511(c) if extended by agreement. The election to deduct instead of credit uses the period in section 6511(a) or (c).
Where do I send Form 1118?
You do not send it separately. Attach it to the corporation's income tax return and file the return through its usual channels. For an amended return, attach the amended Form 1118 to Form 1120-X. The form prints no address of its own.
What happens to excess foreign taxes I cannot use this year?
Excess taxes in a separate category are carried back 1 year, then forward 10 years, within the same category. These carryover rules do not apply to foreign income taxes assigned to section 951A category income. A carryback requires an amended return with a revised Form 1118.
Can I fill out Form 1118 online on FillingPDF?
Yes. You can fill out the fillable PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the form; you attach it to the corporation's return and submit it through the IRS channels.
Ready to fill out 1118?
Fill out 1118 now