
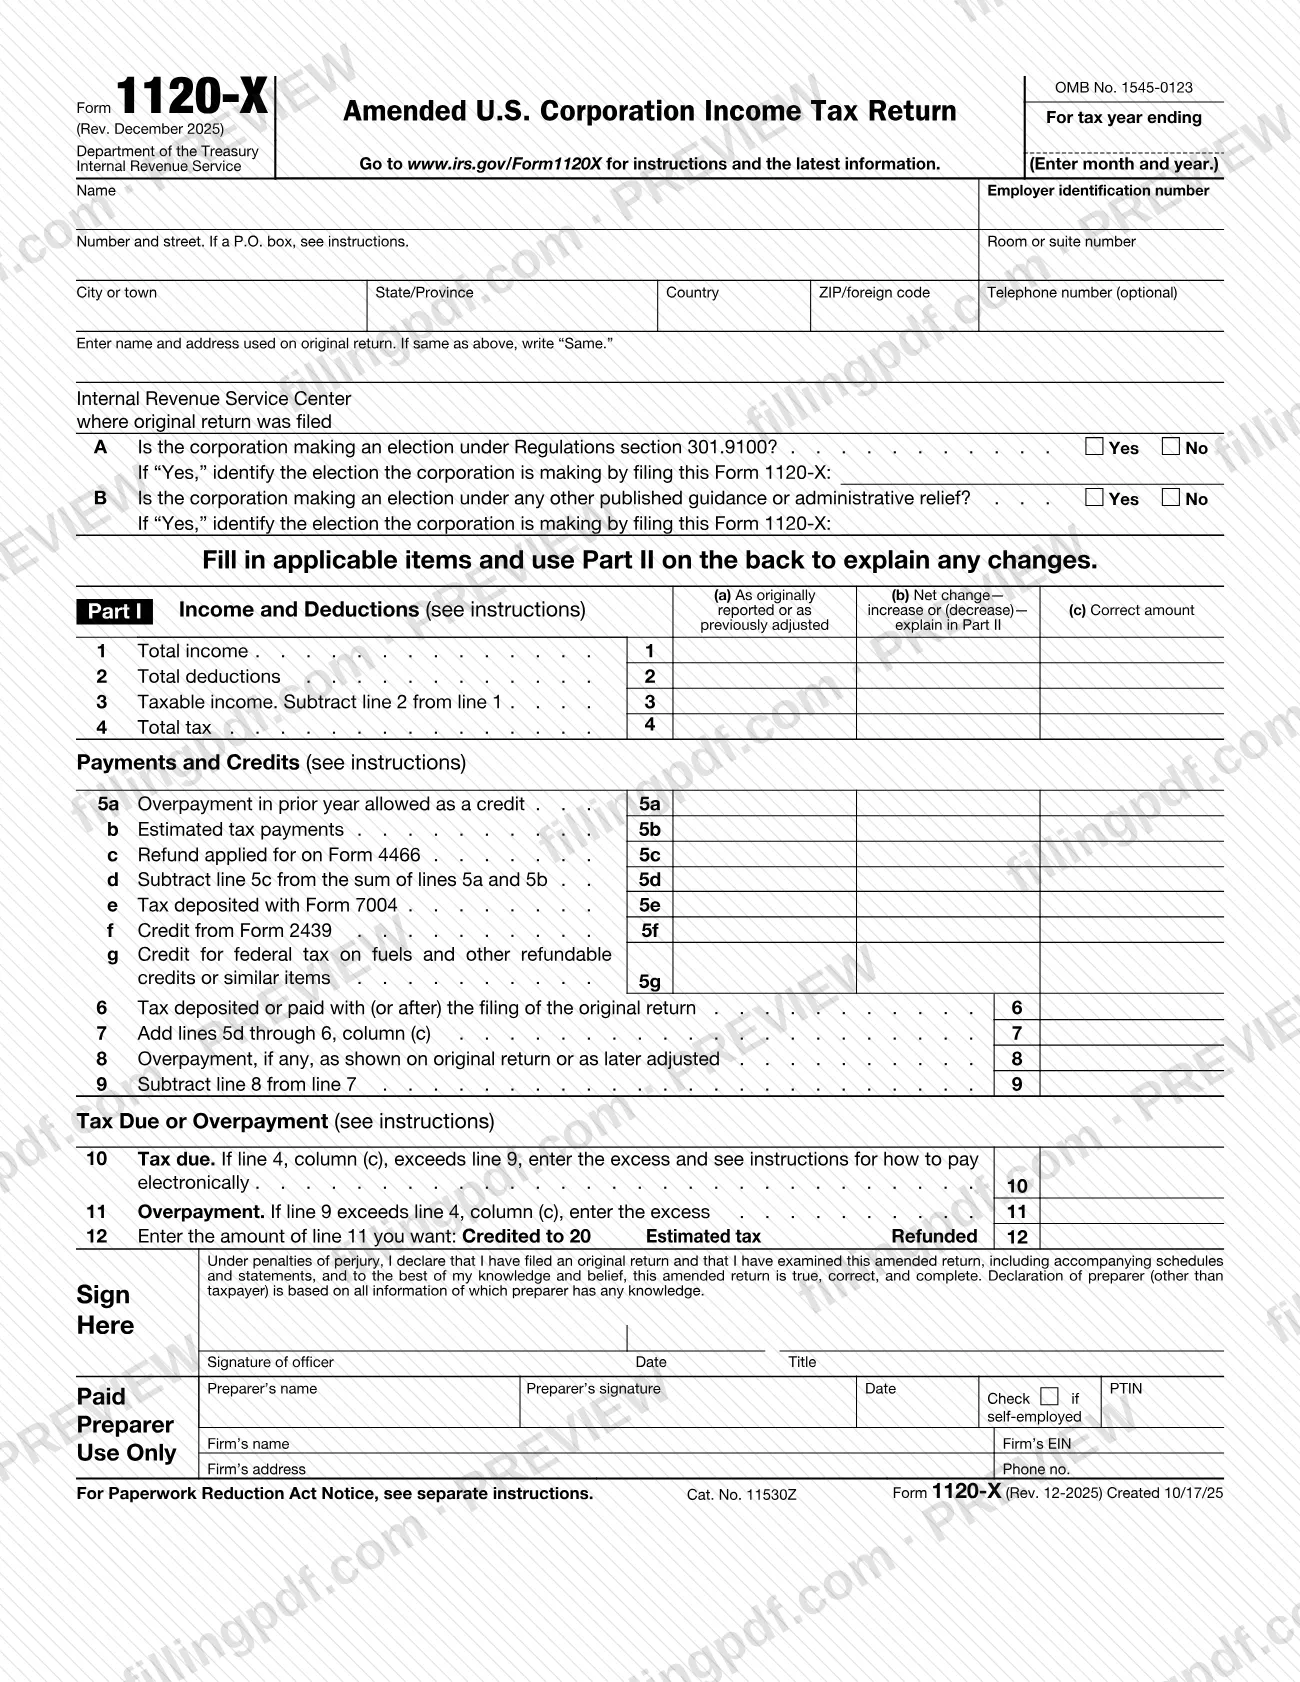
The 1120X, officially Form 1120-X, Amended U.S. Corporation Income Tax Return, is the Internal Revenue Service (IRS) form a corporation files to correct a Form 1120 or Form 1120-A it has already filed. It is also used to make certain elections after the prescribed deadline. On this page you can fill out Form 1120-X online on FillingPDF and download or print the completed PDF; the form and its instructions are published by the IRS at irs.gov, and the return goes to the IRS only through the channels described below.
Last updated
What is 1120-X?
Form 1120-X, Amended U.S. Corporation Income Tax Return, is the IRS form a corporation uses to correct a previously filed Form 1120 (or Form 1120-A, if applicable) or to make certain elections after the prescribed deadline.
The form corrects the return as originally filed, or as later adjusted by an amended return, a claim for refund or an examination. It can also carry a late election under Regulations sections 301.9100-1 through 3 or under other published guidance or administrative relief; questions A and B on the form ask whether the corporation is making one.
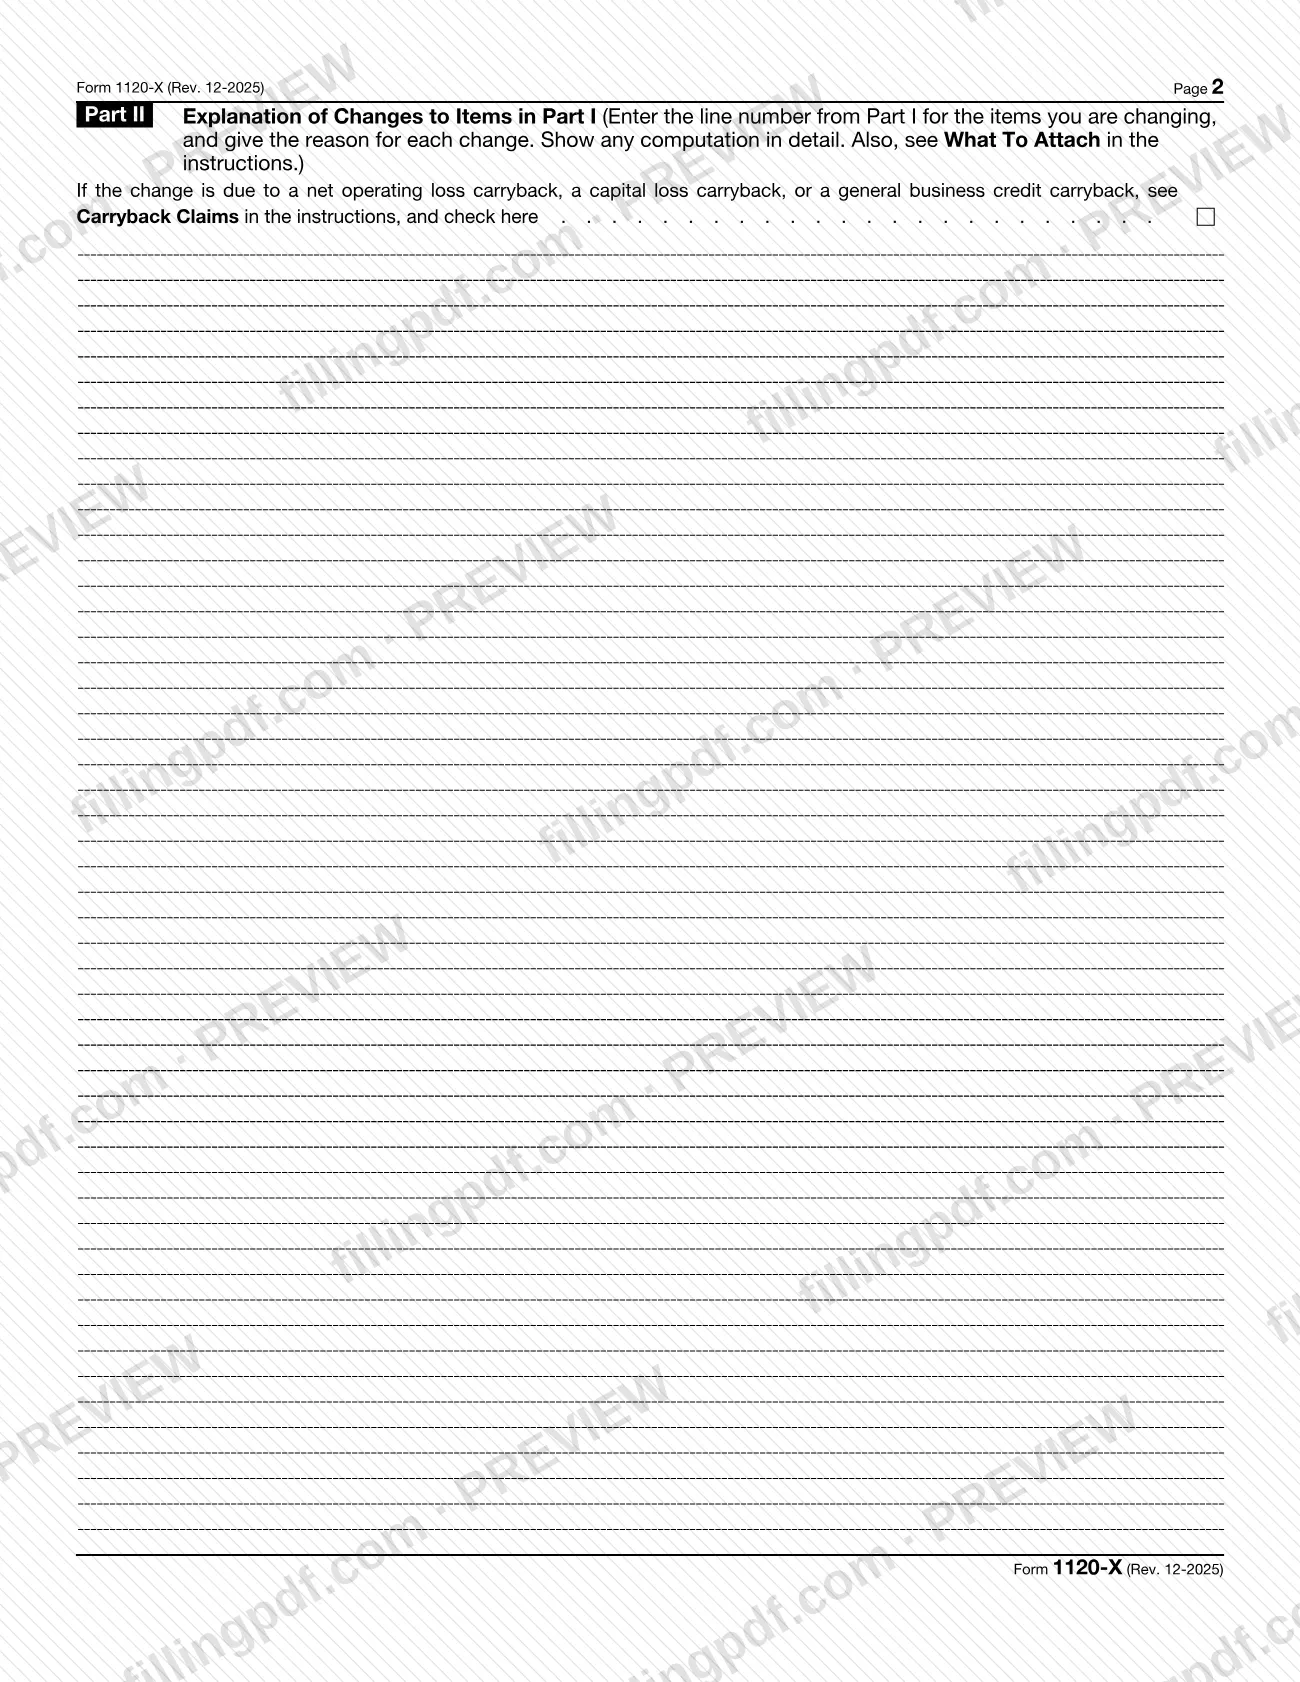
Part I compares three columns for total income, total deductions, taxable income and total tax: (a) as originally reported or as previously adjusted, (b) net change, and (c) the correct amount. Lines 5a through 9 rework payments and credits, and lines 10 to 12 show the tax due or the overpayment. Part II, on the back, is where you explain every change.
Examples of corrections the IRS instructions give are a clerical or mathematical error, a missed deduction or credit, an adjustment for a net operating loss (NOL) or credit carryback, and a change to an accounting election the IRS permits on an amended return.
The instructions also name forms that this one is not: Form 4466 for a quick refund of estimated tax overpayment, Form 1139 for a tentative refund, and Form 3115 for a change in accounting method.
Who needs to file 1120-X?
A corporation that has already filed its original return uses Form 1120-X when it needs to correct that return, or to make a late election, as the IRS instructions describe:
- a corporation correcting a Form 1120 or Form 1120-A as originally filed, or as later adjusted by an amended return, a claim for refund or an examination;
- a corporation making an election after the prescribed deadline under Regulations sections 301.9100-1 through 3, or under other published guidance or administrative relief;
- a corporation claiming a refund from an NOL, net capital loss or general business credit carryback, when Form 1139 is not available because more than 1 year has passed since the tax year in which the carryback or adjustment occurred.
Do not use Form 1120-X to apply for a quick refund of estimated tax overpayment (use Form 4466), to obtain a tentative refund within the 1-year window (use Form 1139), or to request approval for a change in accounting method (use Form 3115).
The return must be signed and dated by the president, vice president, treasurer, assistant treasurer, chief accounting officer or another authorized corporate officer. If a receiver, trustee or assignee files for the corporation, the fiduciary signs instead.
When to file 1120-X
File Form 1120-X only after the corporation has filed its original return. Generally, it must be filed within 3 years after the date the original return was filed, or within 2 years after the date the tax was paid if you are claiming a refund, whichever is later. A return filed before the due date is considered filed on the due date.
Two special periods apply. A Form 1120-X based on an NOL carryback, a capital loss carryback or a general business credit carryback generally must be filed within 3 years after the due date, including extensions, of the return for the tax year of the NOL, capital loss or unused credit. One based on a bad debt or worthless security must be filed within 7 years after the due date of the return for the tax year in which the debt or security became worthless. See section 6511 for more details and other special rules.
The instructions note that it often takes 3 to 4 months to process Form 1120-X.
Documents you need
- Any schedule, statement or form that supports a corrected item of income, deduction or credit; include the corporation's name and employer identification number on each attachment.
- Form 8886, Reportable Transaction Disclosure Statement, if the return is amended for a tax year in which the corporation participated in a reportable transaction; also for carryback years if the transaction results in a carried-back loss or credit.
- For a carryback claim: copies of Form 1120, page 1, and the tax computation page for both the year the loss or credit originated and the carryback year, marked "Copy Only—Do Not Process" at the top.
- For a carryback claim: any other forms, schedules or statements that support it, including a statement showing all adjustments required to figure any NOL carried back.
- A copy of the court order or instructions authorizing the signing, if a receiver or trustee in bankruptcy signs on behalf of the corporation.
How to fill out 1120-X
Enter tax year and corporation details
Enter the ending month and year of the tax year being amended in the space above the employer identification number. Then enter the corporation's name, employer identification number, address, and optional telephone number.
Enter the address from the original return
Enter the name and address used on the original return, or write "Same" if it matches the address above. Enter the Internal Revenue Service Center where the original return was filed.
Answer questions A and B
Check Yes for question A if you are making an election under Regulations section 301.9100, and for question B if you are making an election under other published guidance or administrative relief; identify the election in the space. Otherwise check No.
Fill columns (a) and (b) of Part I
In column (a), enter the amounts as originally filed or as later adjusted, including any IRS changes. In column (b), enter the net increase or decrease for each line you change, with decreases in parentheses.
Complete column (c) for lines 1 to 4
For lines 1 and 2, add or subtract column (b) from column (a). Line 3 is line 1 minus line 2. For line 4, figure the new tax on the column (c) taxable income using Schedule J of the original Form 1120.
Enter payments and credits on lines 5 to 9
Complete lines 5a through 5g (including line 5e for tax deposited with Form 7004 and write-in credits on line 5g), line 6, and add lines 5d through 6 on line 7. Enter the original return's overpayment on line 8, then subtract line 8 from line 7 on line 9.
Figure tax due or overpayment
If line 4, column (c), exceeds line 9, enter the excess as tax due on line 10. If line 9 exceeds line 4, column (c), enter the excess as an overpayment on line 11.
Choose credit or refund on line 12
Enter the part of line 11 to be credited to estimated tax, with the tax period, and the part to be refunded. The election to credit estimated tax is irrevocable and earns no interest.
Explain each change in Part II
On page 2, enter the Part I line number for each item you change and give the reason, showing computations in detail. Check the box if the change is due to an NOL, capital loss or general business credit carryback.
Sign and date the return
An authorized corporate officer signs, dates and enters a title. A paid preparer completes the Paid Preparer Use Only area; leave it blank if an employee or an unpaid person prepared the form.
Review and download the completed PDF
Check that column (c) on lines 1 through 4 matches what the original return would show with all corrections, then download or print the PDF from FillingPDF. Add the required attachments and submit it as described under How to submit.
How to submit 1120-X
Form 1120-X is filed on paper at the Internal Revenue Service Center where the corporation filed its original return. The form prints no mailing address; the IRS instructions say to file it at the applicable service center.
- By mail: send the signed form, with the attachments the change requires, to the service center where the original return was filed. Enter that center on the form where it asks for the Internal Revenue Service Center where the original return was filed.
- By private delivery service: the instructions say corporations can use certain IRS-designated private delivery services to meet the "timely mailing as timely filing" rule; see the Instructions for Form 1120 for details.
- Paying tax due (line 10): a corporation with access to U.S. banking services or electronic payment systems should pay electronically, for example through EFTPS (EFTPS.gov), IRS Direct Pay (IRS.gov/Direct Pay) or its IRS business tax account (IRS.gov/BusinessAccount). Other options are at IRS.gov/Pay. A corporation that does not use electronic funds transfers encloses a check payable to the "United States Treasury"; see IRS.gov/PayByMail.
Do not send the form to the Tax Forms and Publications address in the Paperwork Reduction Act notice; that address is for comments only. For the latest information, go to www.irs.gov/Form1120X. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Using Form 1120-X to ask for a quick refund of estimated tax overpayment or a tentative refund within the 1-year window; the instructions point to Form 4466 and Form 1139 for those.
- Filing Form 1120-X before the original return has been filed; the instructions say to file it only after the original return.
- Entering a decrease in column (b) without parentheses; the instructions say to put parentheses around all amounts that are decreases.
- Leaving a changed line unexplained; Part II must give the line number and the reason for each change, with computations in detail.
- Entering in column (a) the corrected figures instead of the amounts as originally filed or as later adjusted, including any IRS changes.
- Omitting the line 8 overpayment from the original return, even if the corporation credited it to next year's estimated tax.
- Mailing the form to a service center other than the one where the original return was filed.
- Attaching carryback copies without writing "Copy Only—Do Not Process" at the top, or leaving off the corporation's name and EIN on attachments.
- Completing the Paid Preparer section for an employee or unpaid preparer; the instructions say that space stays blank in those cases.
Frequently asked questions
What is the 1120X form used for?
Form 1120-X, often typed 1120X, is the IRS form a corporation uses to correct a Form 1120 (or Form 1120-A, if applicable) it already filed, or to make certain elections after the prescribed deadline. Part II explains each change.
How long do I have to file Form 1120-X?
Generally within 3 years after the original return was filed, or within 2 years after the tax was paid for a refund claim, whichever is later. Carryback claims and bad-debt claims have their own periods, stated in the IRS instructions.
Where do I send Form 1120-X?
Send it to the Internal Revenue Service Center where the corporation filed its original return. The form prints no address; the IRS instructions say to file at the applicable center. Do not send it to the Tax Forms and Publications comment address.
Can I file Form 1120-X for a net operating loss carryback?
Yes, if Form 1139 is not available. Form 1139 can be used only if 1 year or less has passed since the tax year of the carryback or adjustment; otherwise use Form 1120-X, attach the carryback copies, and check the box on Part II.
How long does the IRS take to process Form 1120-X?
The IRS instructions say it often takes 3 to 4 months to process Form 1120-X. Refunds on line 11 show only the additional overpayment and are paid separately from any refund on the original return, with interest figured by the IRS.
Who has to sign Form 1120-X?
A corporate officer authorized to sign: the president, vice president, treasurer, assistant treasurer, chief accounting officer or another such officer. A receiver, trustee or assignee filing for the corporation signs in the officer's place.
Can I fill out Form 1120-X online on FillingPDF?
Yes. You can fill out the fillable PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the return with the IRS; you submit it through the IRS channels described on this page.
How do I pay tax due on Form 1120-X?
Enter the amount on line 10 and, if you have access to U.S. banking services, pay electronically through EFTPS, IRS Direct Pay or your IRS business tax account. Otherwise enclose a check payable to the "United States Treasury."
Ready to fill out 1120-X?
Fill out 1120-X now