
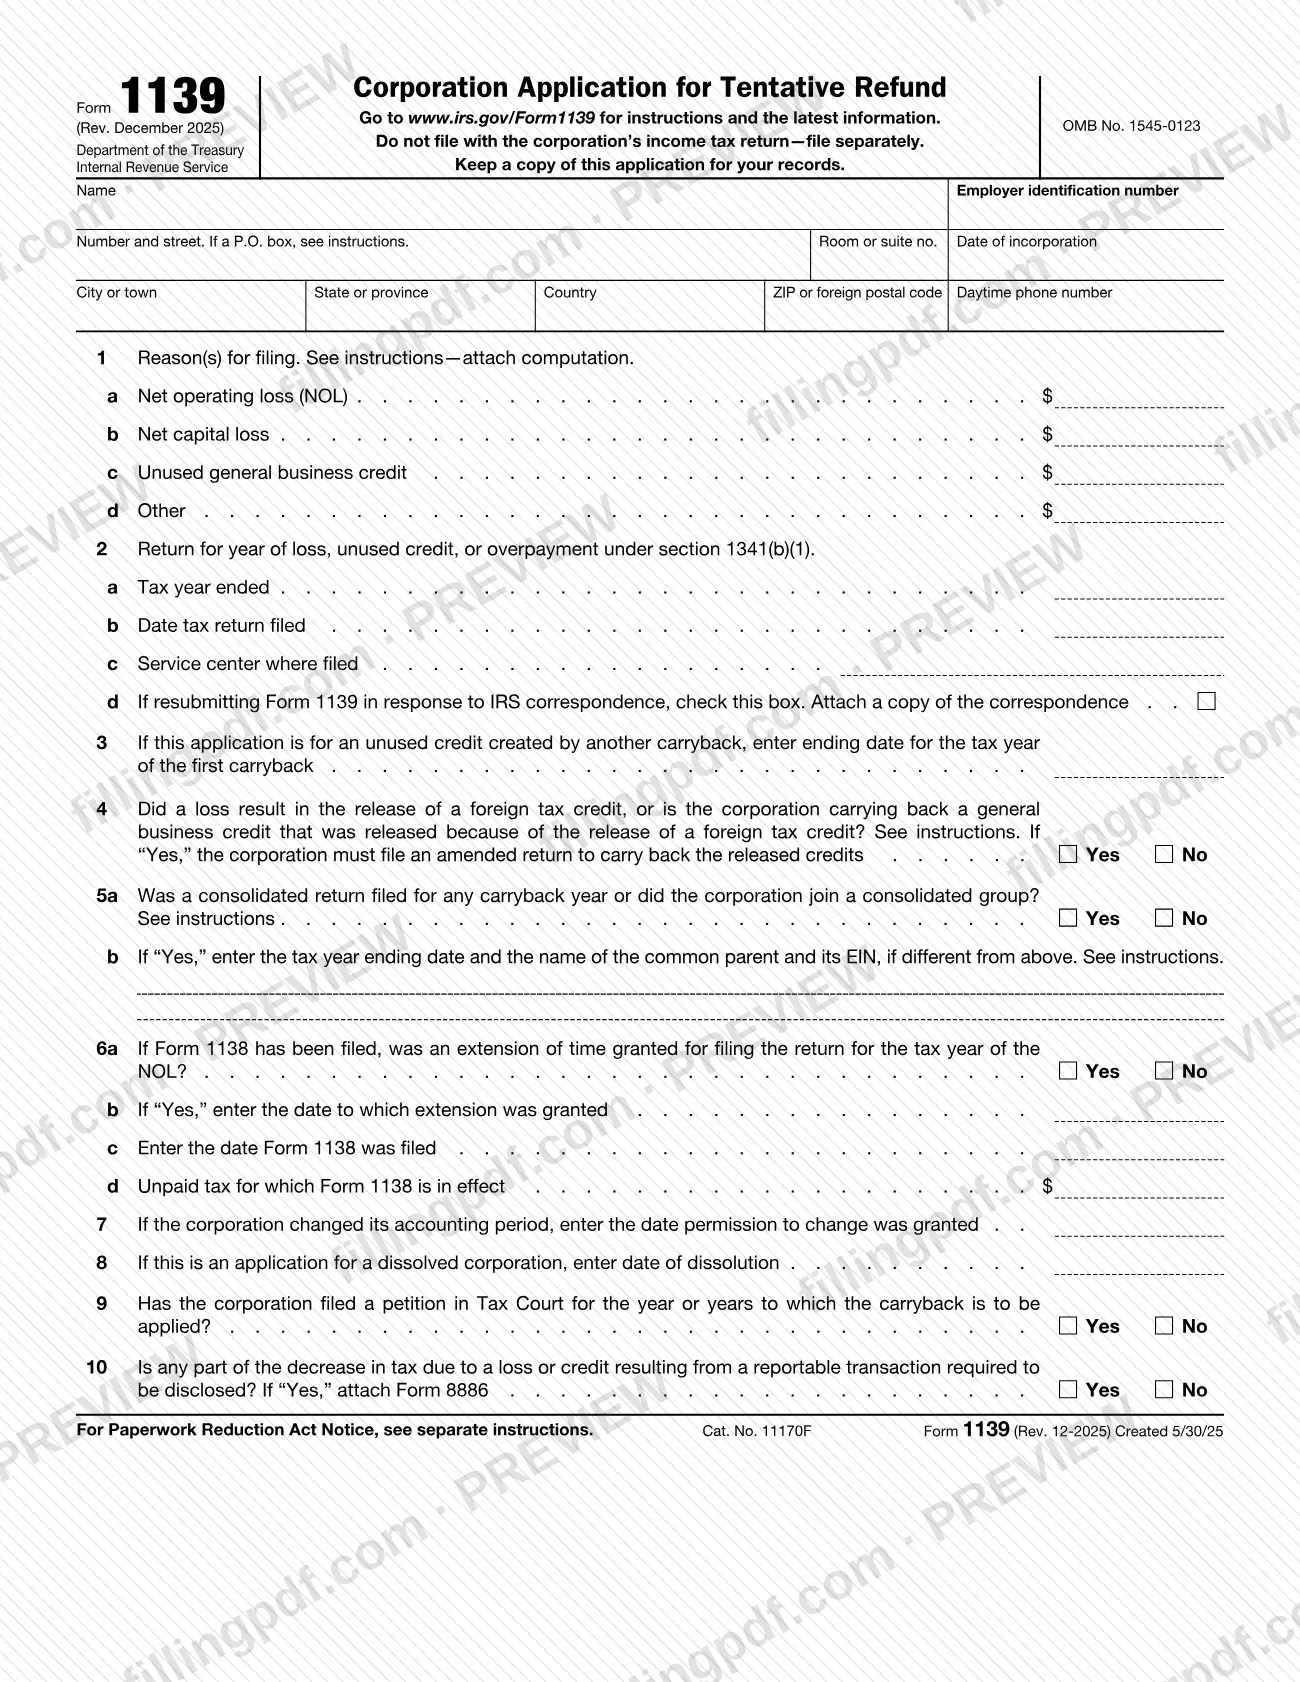
Form 1139 is the Internal Revenue Service (IRS) application that a corporation files to get a quick refund when a net operating loss (NOL), net capital loss or unused general business credit is carried back to an earlier tax year. It is filed separately from the corporation's income tax return, and S corporations do not use it. On FillingPDF you can fill out the form online and download or print the completed PDF; the IRS publishes the original form and its instructions at www.irs.gov/Form1139.
Last updated
What is 1139?
Form 1139, Corporation Application for Tentative Refund, is the IRS form a corporation other than an S corporation files to apply for a quick refund of taxes from a carryback of a net operating loss, net capital loss or unused general business credit.
The IRS instructions list the situations it covers:
- the carryback of an NOL;
- the carryback of a net capital loss;
- the carryback of an unused general business credit;
- an overpayment of tax due to a claim of right adjustment under section 1341(b)(1); and
- an election under section 53(e)(5) to claim 100% of prior year minimum tax for a tax year beginning in 2018.
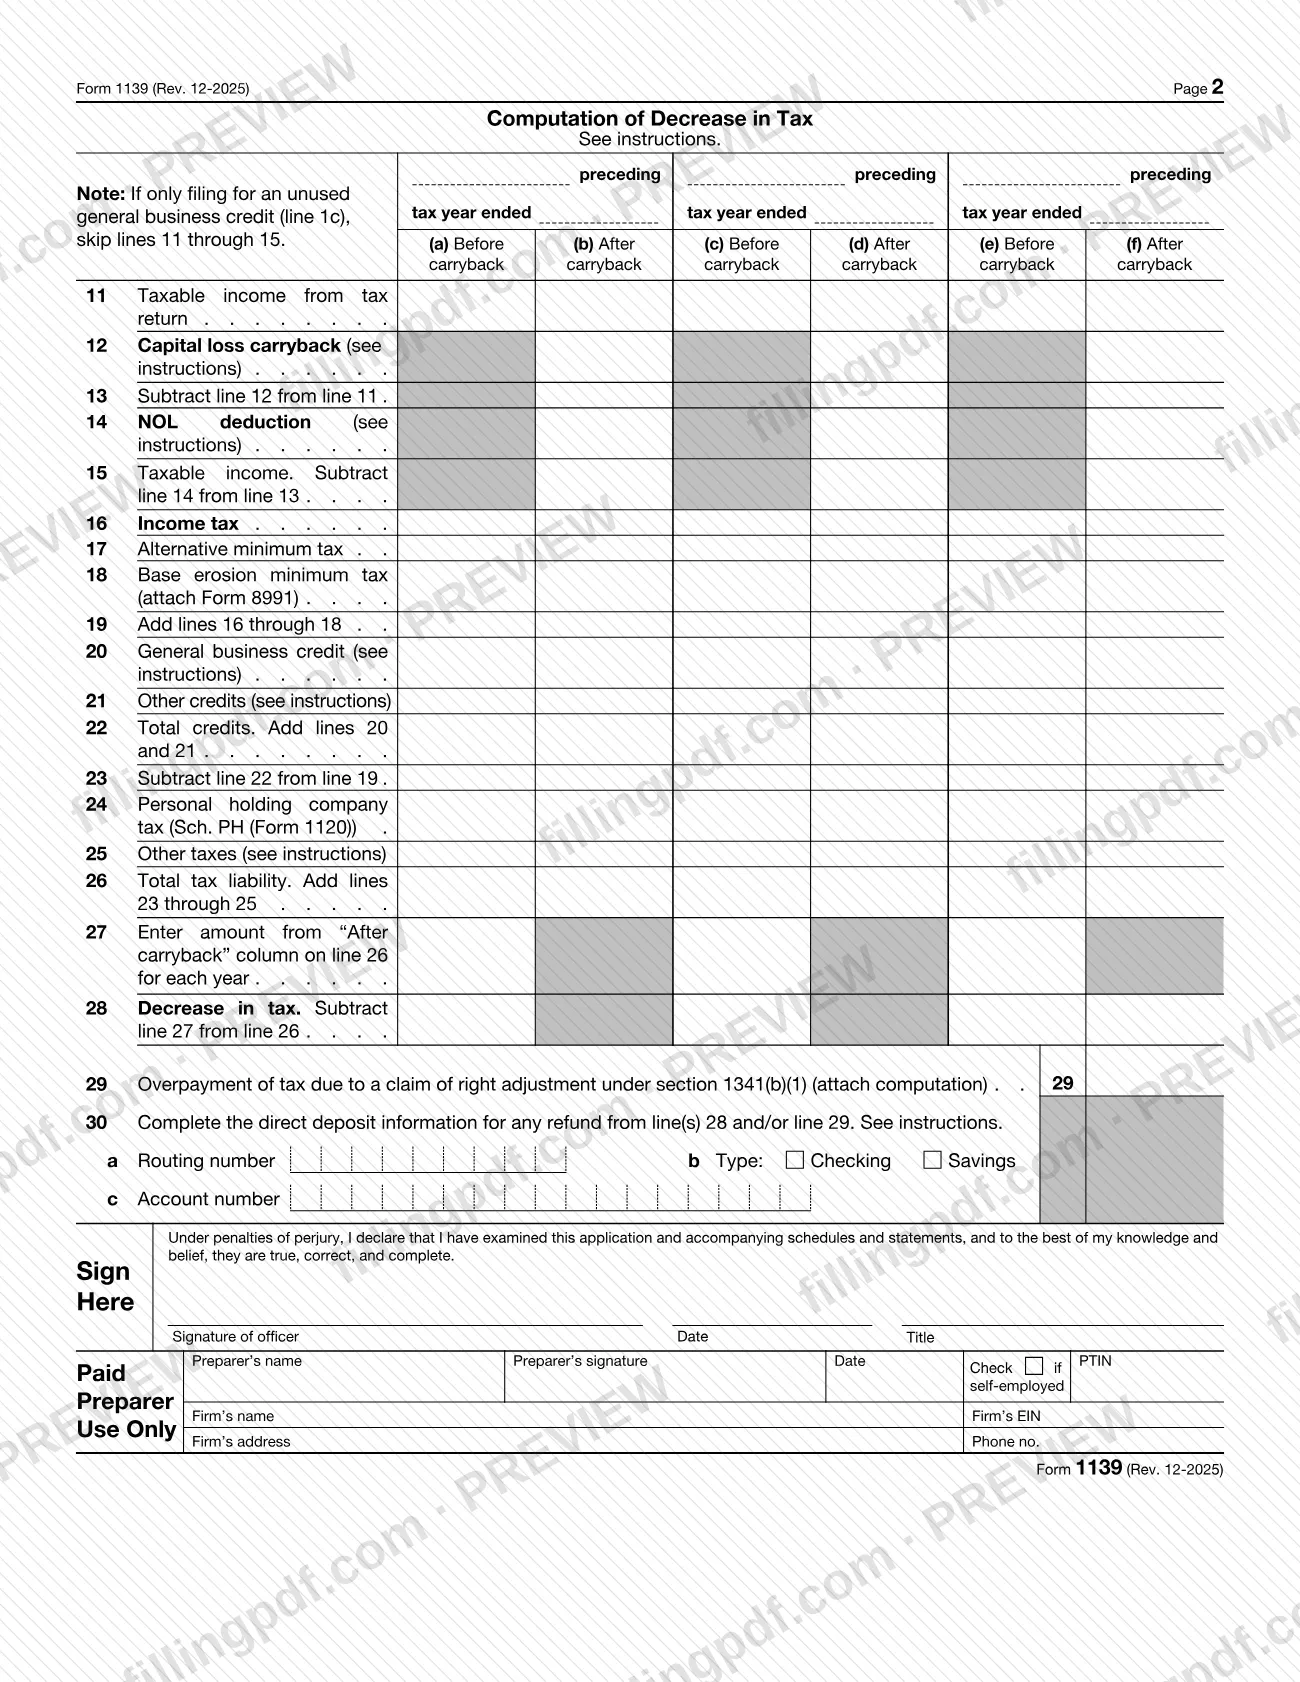
Page 1 collects the corporation's identifying data, the reason for filing and a set of yes/no questions. Page 2 is the computation of decrease in tax: for each carryback year you enter figures before and after the carryback (lines 11 through 28), then any claim of right overpayment (line 29) and direct deposit details (line 30).
An application for a tentative refund is not treated as a claim for credit or refund. A regular claim is made on Form 1120X (or another amended return), which the instructions require instead of Form 1139 for certain items, such as carrying a prior year foreign tax credit released by an NOL or net capital loss carryback. Tax-exempt organizations claiming a refund of taxes reported on Form 990-T use the Instructions for Form 990-T.
Who needs to file 1139?
A corporation, other than an S corporation, that wants a quick refund from one of the carrybacks or the claim of right adjustment described in the IRS instructions files Form 1139.
- Corporations with an NOL. For losses in tax years beginning after 2020, the instructions say only farming losses and losses of insurance companies other than life insurance companies can be carried back, for 2 years. A corporation can elect to waive the carryback period when it has such a loss.
- Corporations with a net capital loss or an unused general business credit. The instructions describe a 3-year carryback for a net capital loss and a 1-year carryback for an unused general business credit.
- Corporations with a claim of right overpayment under section 1341(b)(1), entered on line 1d and line 29.
- Consolidated groups. Line 5 asks whether a consolidated return was filed for a carryback year or the corporation joined a consolidated group.
Do not use Form 1139 where the instructions require Form 1120X or another amended return instead: carrying any item other than an NOL to a section 965 year, a prior year foreign tax credit released due to an NOL or net capital loss carryback, or a prior year general business credit released because of the release of the foreign tax credit. To designate an attorney or representative, attach Form 2848.
When to file 1139
Generally, file Form 1139 within 12 months of the end of the tax year in which the NOL, net capital loss, unused credit or claim of right adjustment arose. The corporation must file its income tax return for that tax year no later than the date it files Form 1139.
If the corporation filed Form 1138 and wants the additional extension of time to pay, it files Form 1139 by the last day of the month that includes the due date (including extensions) for filing the return for the year from which the NOL carryback arose.
The IRS says it will process the application within 90 days of the later of the date the complete application is filed or the last day of the month that includes the due date (including extensions) of the return for the loss or credit year. Payment of the refund does not mean the IRS accepted the application as correct.
If the 12-month window is missed, the instructions allow a refund claim on Form 1120X (or another amended return), generally within 3 years after the return was due for the year the loss or credit arose, or, if later, the date the return was filed.
Documents you need
- The first two pages of the corporation's income tax return for the year of the loss or credit (copy), if applicable.
- All other forms and schedules from which a carryback results, such as Schedule D (Form 1120) or Form 3800, General Business Credit (copies, for the year of the loss or credit).
- All Forms 8886, Reportable Transaction Disclosure Statement, attached to the corporation's tax return; also required if you answer "Yes" on line 10.
- Any applicable election statement, such as the statement for waiving the NOL carryback period when the instructions require one.
- All carryback year forms and schedules for which items were refigured.
- A computation supporting the reason(s) for filing on line 1, and a computation of the refigured tax for line 16.
- A computation showing the information required by Regulations section 5.6411-1(d), for an overpayment under section 1341(b)(1) on line 29.
- A statement identifying the credit(s) on line 21 or the taxes on line 25, if you make an entry there.
- Form 4626 for the appropriate tax years before 2018 or after 2022, when you refigure the alternative minimum tax on line 17.
- Form 8991, when you enter base erosion minimum tax on line 18.
- A copy of the IRS correspondence, if you check the box on line 2d when resubmitting Form 1139.
- Form 2848, Power of Attorney and Declaration of Representative, only if you designate an attorney or representative.
How to fill out 1139
Enter corporation name and address
At the top, enter the corporation's name, employer identification number, address, date of incorporation and daytime phone number. Enter a P.O. box only if the post office does not deliver to the street address, and use "C/O" with the third party's name if mail goes through an accountant or attorney.
State the reason for filing on line 1
Enter the carryback amount on line 1a (NOL), 1b (net capital loss), 1c (unused general business credit) or 1d (other, such as a section 1341(b)(1) claim of right adjustment). Attach the computation.
Identify the loss-year return on line 2
Enter the tax year ended (2a), the date the return was filed (2b) and the service center where it was filed (2c). Check the box on line 2d only if you are resubmitting in response to IRS correspondence, and attach a copy.
Complete lines 3 and 4
On line 3, enter the ending date of the first carryback year if the application is for an unused credit created by another carryback. On line 4, answer Yes or No about the release of a foreign tax credit; if Yes, the corporation must file an amended return.
Answer the consolidated return question
On line 5a, check Yes or No. If Yes, enter on line 5b the tax year ending date and the name and EIN of the common parent, if different from above.
Complete the Form 1138 lines
If Form 1138 was filed, answer line 6a and, if Yes, enter the extension date on line 6b. Enter the date Form 1138 was filed on line 6c and the unpaid tax it covers on line 6d.
Report accounting period and dissolution
On line 7, enter the date permission was granted if the corporation changed its accounting period. On line 8, enter the date of dissolution if the application is for a dissolved corporation.
Answer Tax Court and reportable transaction questions
Line 9 asks whether the corporation filed a Tax Court petition for the year or years to which the carryback applies. Line 10 asks about a reportable transaction; if Yes, attach Form 8886.
Fill in before and after carryback columns
On page 2, start with the earliest carryback year, enter the ordinal number of years back and the year-end date above the columns, and use columns (a)/(b), (c)/(d) or (e)/(f). Enter original amounts in columns (a), (c) and (e) and copy line 11 across to the "After" columns. Skip lines 11 through 15 if you are filing only for an unused general business credit.
Refigure income, credits and total tax
Complete lines 12 through 26: capital loss carryback, NOL deduction, taxable income, income tax, alternative minimum tax, base erosion minimum tax, credits, personal holding company tax and other taxes. Attach the computation, statements and forms the instructions require for lines 16 through 25.
Figure the decrease in tax
On line 27, enter the "After carryback" amount from line 26 for each year, then subtract it from line 26 on line 28. If you have a claim of right overpayment, enter it on line 29 and attach the computation.
Add direct deposit information
On line 30, enter the routing number, check Checking or Savings, and enter the account number for any refund from line 28 and/or line 29.
Review, sign and download the PDF
An officer signs and dates the application and enters a title; a paid preparer completes the preparer section. Check every line against your attachments, then download or print the completed PDF from FillingPDF and keep a copy.
How to submit 1139
You can file Form 1139 on paper with the IRS or electronically.
- By mail or delivery: file it with the Internal Revenue Service Center where the corporation files its income tax return. The form itself does not print a separate address; the IRS instructions at www.irs.gov/Form1139 point to that service center.
- Electronically: the instructions say to use Form 8453-TR, E-file Declaration or Authorization for Form 1045/1139, for e-filing the application.
Do not file Form 1139 with the corporation's income tax return: the form says to file it separately. Keep a copy for your records. Attach the items listed under required documents, and attach Form 2848 if you designate an attorney or representative. If you are resubmitting in response to IRS correspondence, check the box on line 2d, attach a copy of the correspondence and send only the requested missing or corrected documentation.
For any refund, the instructions encourage direct deposit (lines 30a through 30c) if the corporation has access to U.S. banking services. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Filing Form 1139 together with the corporation's income tax return; the form says to file it separately.
- Filing more than 12 months after the end of the tax year in which the NOL, net capital loss, unused credit or claim of right adjustment arose, or before the income tax return for that year is filed.
- Using Form 1139 as an S corporation; the instructions say a corporation other than an S corporation files it.
- Using Form 1139 to carry back a prior year foreign tax credit released by an NOL or net capital loss, when the instructions require Form 1120X or another amended return.
- Leaving out the computation that supports line 1 or the refigured tax on line 16.
- Making an entry on line 21 or line 25 without attaching a statement identifying the credits or taxes.
- Answering "Yes" on line 10 without attaching Form 8886.
- Resubmitting in response to IRS correspondence without checking line 2d and attaching a copy, or resending the entire package instead of only the missing or corrected documents.
- Filling in lines 11 through 15 when filing only for an unused general business credit (line 1c); the form says to skip them.
Frequently asked questions
What is Form 1139 used for?
Form 1139 is the IRS application a corporation, other than an S corporation, uses to request a quick refund of taxes from a carryback of an NOL, net capital loss or unused general business credit, or from a section 1341(b)(1) claim of right overpayment.
What is the deadline to file Form 1139?
Generally within 12 months of the end of the tax year in which the NOL, net capital loss, unused credit or claim of right adjustment arose. The corporation's income tax return for that year must be filed no later than the date it files Form 1139.
Do I file Form 1139 with my corporate tax return?
No. The form states that it must not be filed with the corporation's income tax return and must be filed separately. File it with the IRS Service Center where the corporation files its income tax return, or e-file it using Form 8453-TR.
How long does the IRS take to process Form 1139?
The IRS says it will process the application within 90 days of the later of the date the complete application is filed or the last day of the month that includes the return's due date for the loss or credit year. Payment does not mean the IRS accepted it as correct.
What is the difference between Form 1139 and Form 1120X?
Form 1139 is a tentative refund application and is not treated as a claim for credit or refund. Form 1120X is an amended return, required instead for certain items such as released foreign tax credits. The IRS need not process an amended return within 90 days.
Can a corporation still carry back an NOL to get a refund?
For losses in tax years beginning after 2020, only farming losses and losses of insurance companies other than life insurance companies can be carried back, for 2 years. The instructions note a 5-year carryback for NOLs from tax years beginning after 2017 and before 2021.
What happens if the IRS disallows my Form 1139?
It may be disallowed for material omissions or math errors not corrected within the 90-day period. No suit challenging the disallowance may be brought, but the corporation can file a regular claim for credit or refund on Form 1120X or another amended return.
Can I fill out Form 1139 online?
Yes. You can fill out the fillable PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the application with the IRS; you file it through the IRS channels, mail or e-file with Form 8453-TR.
Ready to fill out 1139?
Fill out 1139 now