
Form 2555, Foreign Earned Income, is the Internal Revenue Service (IRS) form for figuring the foreign earned income exclusion and the housing exclusion or deduction. U.S. citizens and resident aliens who live and work in a foreign country attach it to Form 1040 or 1040-SR. On this page you can fill out the 2025 form online on FillingPDF and download or print the completed PDF. The official PDF and the Instructions for Form 2555 are published by the IRS at www.irs.gov/Form2555.
Last updated
What is 2555?
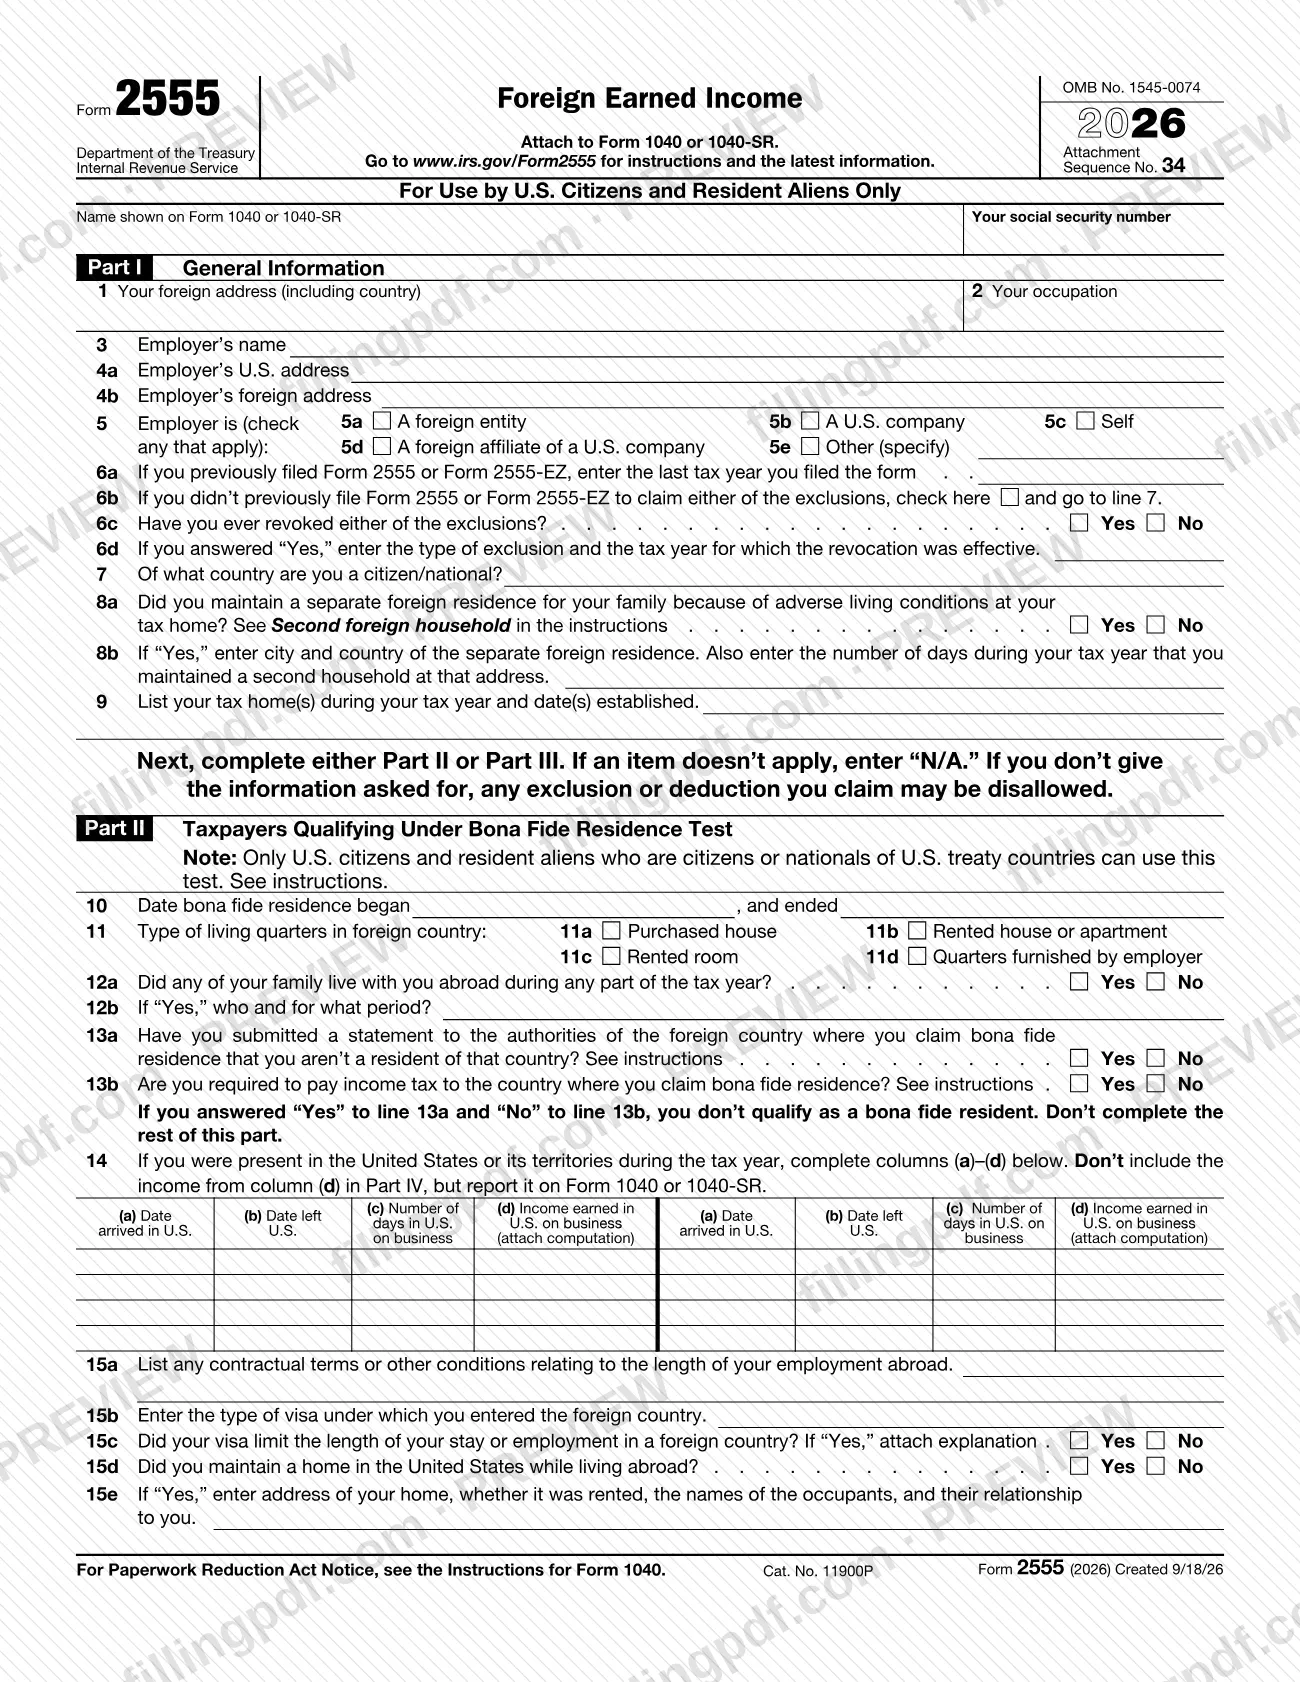
Form 2555, Foreign Earned Income, is the IRS form that U.S. citizens and resident aliens living abroad attach to Form 1040 or 1040-SR to figure the foreign earned income exclusion and the housing exclusion or deduction.
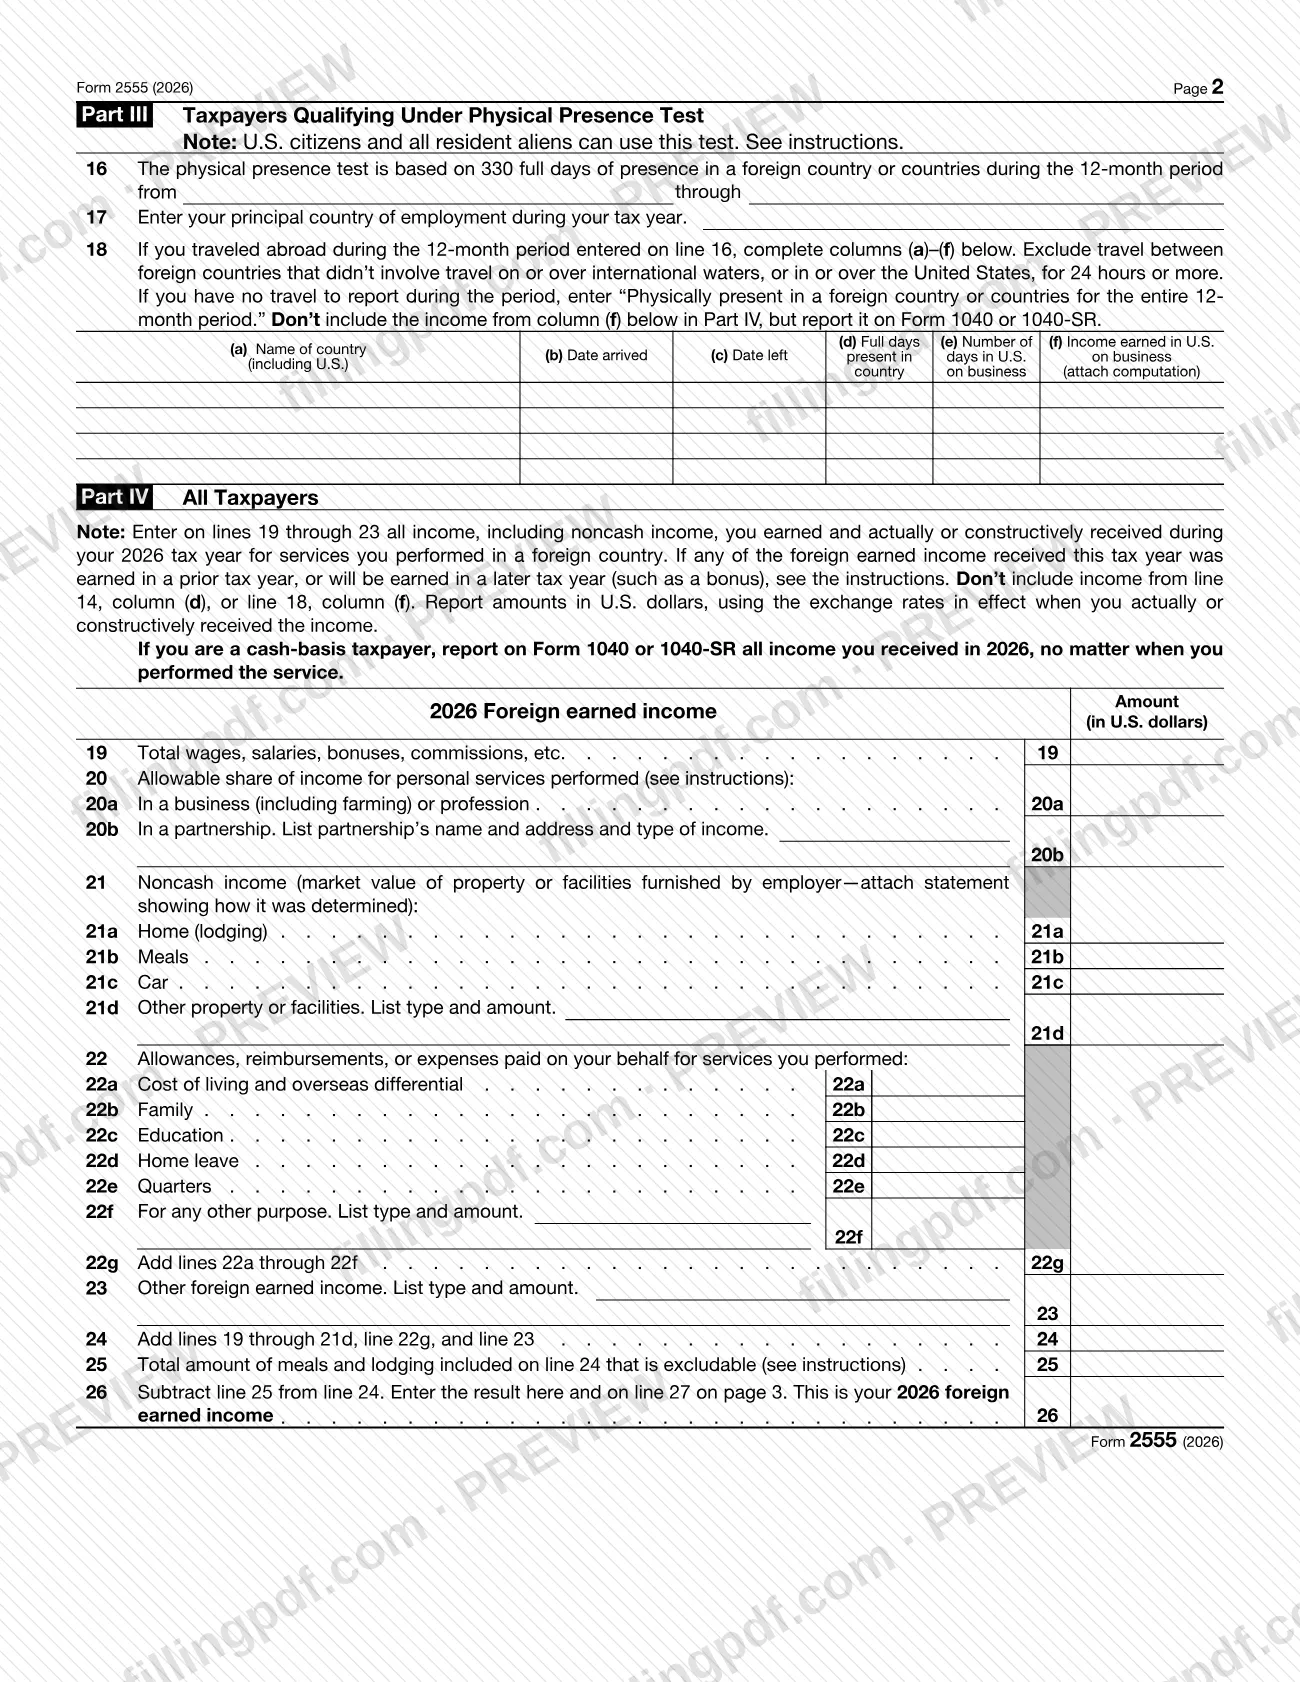
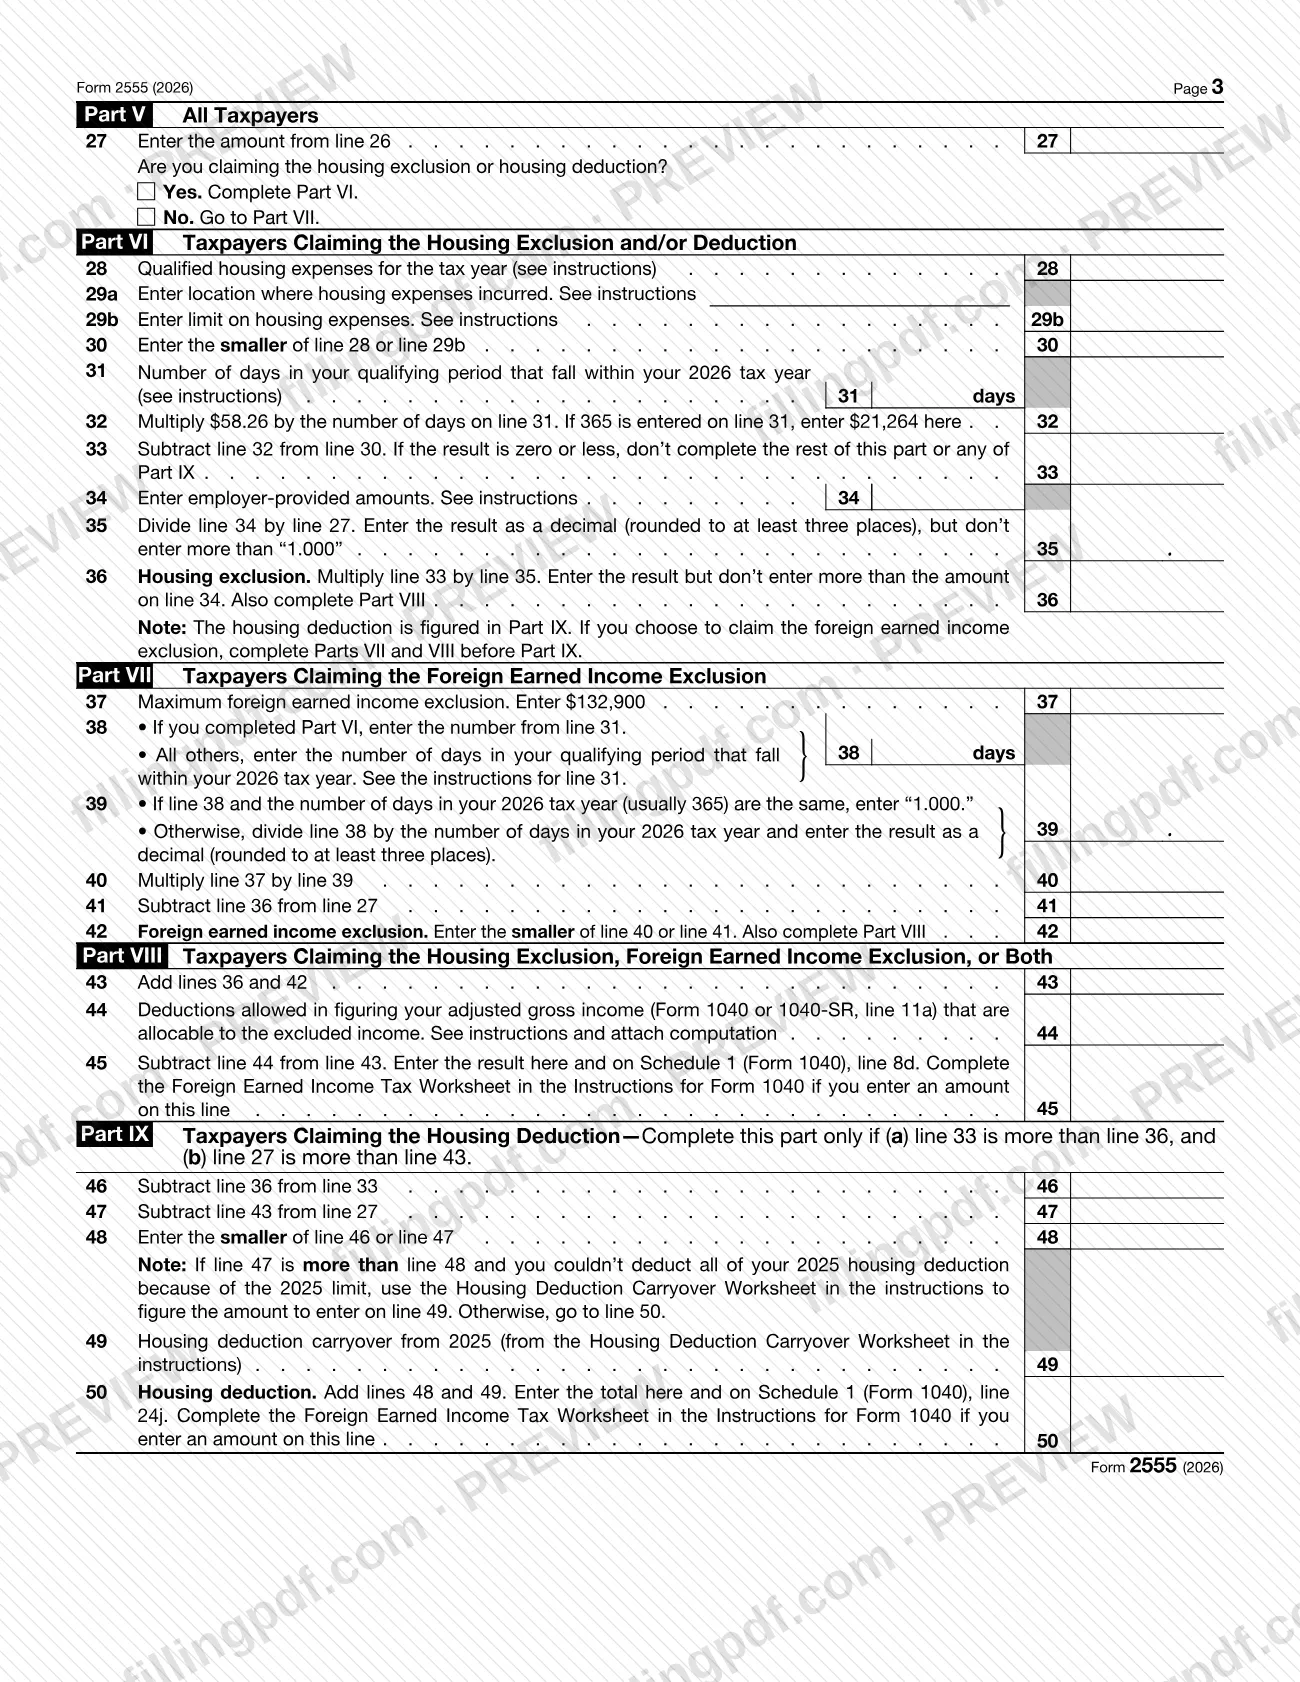
The form is built in nine parts. Part I collects general information, including your foreign address, employer and tax home. You then complete either Part II (bona fide residence test) or Part III (physical presence test), but not both. Part IV totals your foreign earned income. Part V carries that total forward. Part VI figures the housing exclusion, Part VII the foreign earned income exclusion, and Part VIII combines them. Part IX figures the housing deduction.
The result of Part VIII goes on Schedule 1 (Form 1040), line 8d, and the housing deduction from Part IX goes on Schedule 1 (Form 1040), line 24j. If you enter an amount on either line, the instructions send you to the Foreign Earned Income Tax Worksheet in the Instructions for Form 1040 to figure the tax on your income that is not excluded.
You cannot exclude or deduct more than your foreign earned income for the year. The form is not a standalone return: it travels with Form 1040 or 1040-SR. It is also not for income from working abroad as an employee of the U.S. Government, which does not qualify for either exclusion or the housing deduction. Pub. 54 gives further detail on the tests, the exclusions and the housing deduction.
Who needs to file 2555?
U.S. citizens and resident aliens who live and work in a foreign country and want to claim the foreign earned income exclusion, the housing exclusion or the housing deduction use Form 2555. The printed form is marked "For Use by U.S. Citizens and Resident Aliens Only."
To qualify you must meet both of these:
- The tax home test: your tax home must be in a foreign country throughout your period of bona fide residence or physical presence.
- Either the bona fide residence test or the physical presence test. A U.S. citizen can use the bona fide residence test. A resident alien can use it only if they are a citizen or national of a country with which the United States has an income tax treaty in effect. The physical presence test is open to U.S. citizens and all resident aliens and requires at least 330 full days in a foreign country during a 12-month period.
Do not file Form 2555 for income from working abroad as an employee of the U.S. Government. If your abode is in the United States, you do not meet the tax home test, except in the combat-zone situation the instructions describe.
If you and your spouse both qualify and both claim the foreign earned income exclusion, each of you completes Part VII on a separate Form 2555.
When to file 2555
File Form 2555 with your Form 1040 or 1040-SR; a 2025 calendar year return is generally due April 15, 2026. The form has no separate due date.
You get an automatic 2-month extension to file, to June 15, 2026 for a 2025 calendar year return, if on the due date you live outside the United States and Puerto Rico and your tax home is outside them as well. Attach a statement to the return explaining that you meet both conditions. The extension also covers paying the tax, but interest runs on any tax not paid by the regular due date.
In the first year you plan to claim the exclusion or deduction, you may not yet meet the physical presence or bona fide residence test by the due date. You can then either apply for a special extension on Form 2350, filed before the due date of your return, or file on time without claiming the exclusion and amend with Form 1040-X after you qualify. The initial choice to claim the exclusion must usually be made on a timely filed return, including extensions.
Documents you need
- Form 1040 or 1040-SR: Form 2555 is attached to it and is not filed alone.
- Computation of income earned in the U.S. on business: attach it if you list days and income in line 14, column (d), or line 18, column (f).
- Explanation for line 15c: attach it if your visa limited the length of your stay or employment in a foreign country.
- Statement showing how the market value was determined: attach it if you report noncash income on lines 21a to 21d.
- Computation of deductions allocable to the excluded income: attach it to line 44 if you enter an amount there.
- Statement for the automatic 2-month extension: attach it to the return if you use the extension, explaining that you live and have your tax home outside the United States and Puerto Rico.
- Waiver statement: attach it if you claim the waiver of time requirements, explaining that conditions in the foreign country prevented normal conduct of business, and enter "Claiming Waiver" in the top margin of page 1.
- Statement showing how you figured the exclusion: attach it if you exclude income earned or received in a different tax year under the prior-year rules.
- Statement of revocation: attach it to your return for the first year you no longer wish to claim the exclusion(s), if you revoke your earlier choice.
How to fill out 2555
Enter your name and Social Security number
At the top of page 1, write your name as shown on Form 1040 or 1040-SR and your Social Security number. Enter "N/A" on any item that does not apply.
Complete Part I, lines 1 to 5
On line 1 enter your entire foreign address, including country. Then give your occupation (line 2), your employer's name and U.S. and foreign addresses (lines 3, 4a, 4b), and check each box on line 5 that describes your employer.
Answer prior-filing and citizenship questions
On lines 6a to 6d, enter the last year you filed Form 2555 or Form 2555-EZ, or check the box if you did not, and say whether you ever revoked an exclusion. On line 7 enter your country of citizenship or nationality.
Report second household and tax home
Line 8a asks whether you kept a separate foreign residence for your family because of adverse living conditions; if Yes, give the city, country and number of days on line 8b. On line 9 list your tax home(s) and the date(s) established.
Choose Part II or Part III
Complete Part II if you qualify under the bona fide residence test, or Part III if you qualify under the physical presence test. Do not complete both.
Complete Part II if you use it
Enter the dates your bona fide residence began and ended on line 10, writing "Continues" if it has not ended. Then answer lines 11 to 15, listing time in the U.S. on line 14 and attaching a computation for U.S. business income.
Complete Part III if you use it
On line 16 enter the 12-month period, with both a start and an end date. Enter your principal country of employment on line 17, and list trips abroad in columns (a) to (f) of line 18 or enter the entire-period statement the form gives.
Total your foreign earned income in Part IV
Report amounts in U.S. dollars on lines 19 to 23: wages, business or partnership income, noncash income, allowances and other income. Add them on line 24, subtract the excludable meals and lodging on line 25, and enter the result on line 26.
Carry the total into Part V
Enter the amount from line 26 on line 27. Check Yes to claim the housing exclusion or deduction and complete Part VI, or No to go to Part VII.
Figure housing amounts in Part VI
Enter qualified housing expenses on line 28, the location on line 29a only if it is listed in Notice 2025-16, and the limit on line 29b. Complete lines 30 to 36 to find the housing exclusion.
Figure the exclusion in Parts VII and VIII
In Part VII, enter your qualifying days (line 38) and the resulting fraction (line 39) to find the foreign earned income exclusion on line 42. In Part VIII, add lines 36 and 42, subtract allocable deductions on line 44 and carry line 45 to Schedule 1 (Form 1040), line 8d.
Complete Part IX for a housing deduction
Complete Part IX only if line 33 is more than line 36 and line 27 is more than line 43. Enter the carryover from 2024 on line 49 using the Housing Deduction Carryover Worksheet, and carry line 50 to Schedule 1 (Form 1040), line 24j.
Review, download and attach to your return
Check that every part is complete or marked "N/A" and that required computations and statements are attached. Download or print the completed PDF from FillingPDF and attach it to Form 1040 or 1040-SR.
How to submit 2555
Form 2555 has no filing channel of its own: attach it to Form 1040 or 1040-SR and file the return.
- By mail: send your Form 1040 or 1040-SR with Form 2555 attached to one of the special addresses designated for taxpayers filing Form 2555. Do not use the addresses tied to your state of residence. The addresses are in the Instructions for Form 1040 and at IRS.gov/Filing/International-Where-To-File-Form-1040-Addresses-for-Taxpayers-and-Tax-Professionals.
- Changing a filed return: use Form 1040-X. It generally must be filed within 3 years after the original return was filed or within 2 years after the tax was paid, whichever is later.
- Special extension (Form 2350): if you need more time to meet a test, file Form 2350 with the Department of the Treasury, Internal Revenue Service Center, Austin, TX 73301-0045, before the due date of your return.
Attach every computation or statement the form asks for. The instructions do not state a separate way to file Form 2555 on its own. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Completing both Part II and Part III. The instructions say to complete one of them, not both.
- Mailing the return to the address for your state of residence. When Form 2555 is attached, use the special addresses designated for those filing it.
- Including taxes your employer withheld that were paid to the foreign tax authority in Form 1040 line 25a or 25b, which are for federal income tax withheld.
- Leaving an item blank instead of entering "N/A". The form warns that an exclusion or deduction may be disallowed if you don't give the information asked for.
- Putting income from line 14, column (d), or line 18, column (f), in Part IV. That U.S. business income is reported on Form 1040 or 1040-SR instead.
- Entering "Continues" as the ending date on line 16. Both dates are required there. "Continues" is accepted only on line 10.
- Claiming a foreign tax credit or deduction, the earned income credit or the additional child tax credit on income you exclude or while claiming the exclusions or housing deduction.
- Filling in line 29a when your location is not listed in Notice 2025-16. In that case the instructions say to leave it blank.
- Filing Form 2555 for pay as a U.S. Government employee, which does not qualify for either exclusion or the housing deduction.
Frequently asked questions
What is Form 2555 used for?
Form 2555 is the IRS form used to figure the foreign earned income exclusion and the housing exclusion or deduction. U.S. citizens and resident aliens who qualify attach it to Form 1040 or 1040-SR. You cannot exclude or deduct more than your foreign earned income for the year.
Who qualifies to claim the foreign earned income exclusion?
You must meet the tax home test, with your tax home in a foreign country, and either the bona fide residence test or the physical presence test. The physical presence test requires at least 330 full days in a foreign country during a 12-month period. Income as a U.S. Government employee does not qualify.
Do I complete Part II or Part III of Form 2555?
Complete one of them, never both. Part II is the bona fide residence test, open to U.S. citizens and to resident aliens who are citizens or nationals of a treaty country. Part III is the physical presence test, open to U.S. citizens and all resident aliens.
Can I fill out Form 2555 online?
Yes. You can fill out the PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file anything with the IRS. You attach the completed form to Form 1040 or 1040-SR and file it through the IRS channels.
Where do I mail Form 2555?
Attach it to your Form 1040 or 1040-SR and mail the return to one of the special addresses designated for taxpayers filing Form 2555, not the address tied to your state of residence. The Instructions for Form 1040 list them, as does the IRS international where-to-file page.
When is Form 2555 due?
It is due with your return, which for a 2025 calendar year return is generally April 15, 2026. If you live and have your tax home outside the United States and Puerto Rico, you get an automatic extension to June 15, 2026, with a statement attached. Interest still runs on unpaid tax.
What if I haven't met the residence or presence test by the due date?
You have two options. File Form 2350 before the due date to apply for a special extension to a date after you expect to qualify. Or file your return on time without claiming the exclusion, then file Form 1040-X to amend it after you qualify.
Can I still claim the earned income credit if I use Form 2555?
No. The instructions say you can't take the earned income credit or the additional child tax credit if you claim either exclusion or the housing deduction. You also can't take a foreign tax credit or deduction on the income you exclude.
Can I revoke my choice to claim the exclusion?
Yes. Attach a statement to your return for the first year you don't want to claim it. Once you revoke, you can't claim the exclusion(s) for your next 5 tax years without IRS approval. You don't need to revoke just because you have no foreign earned income or housing costs that year.
Ready to fill out 2555?
Fill out 2555 now