
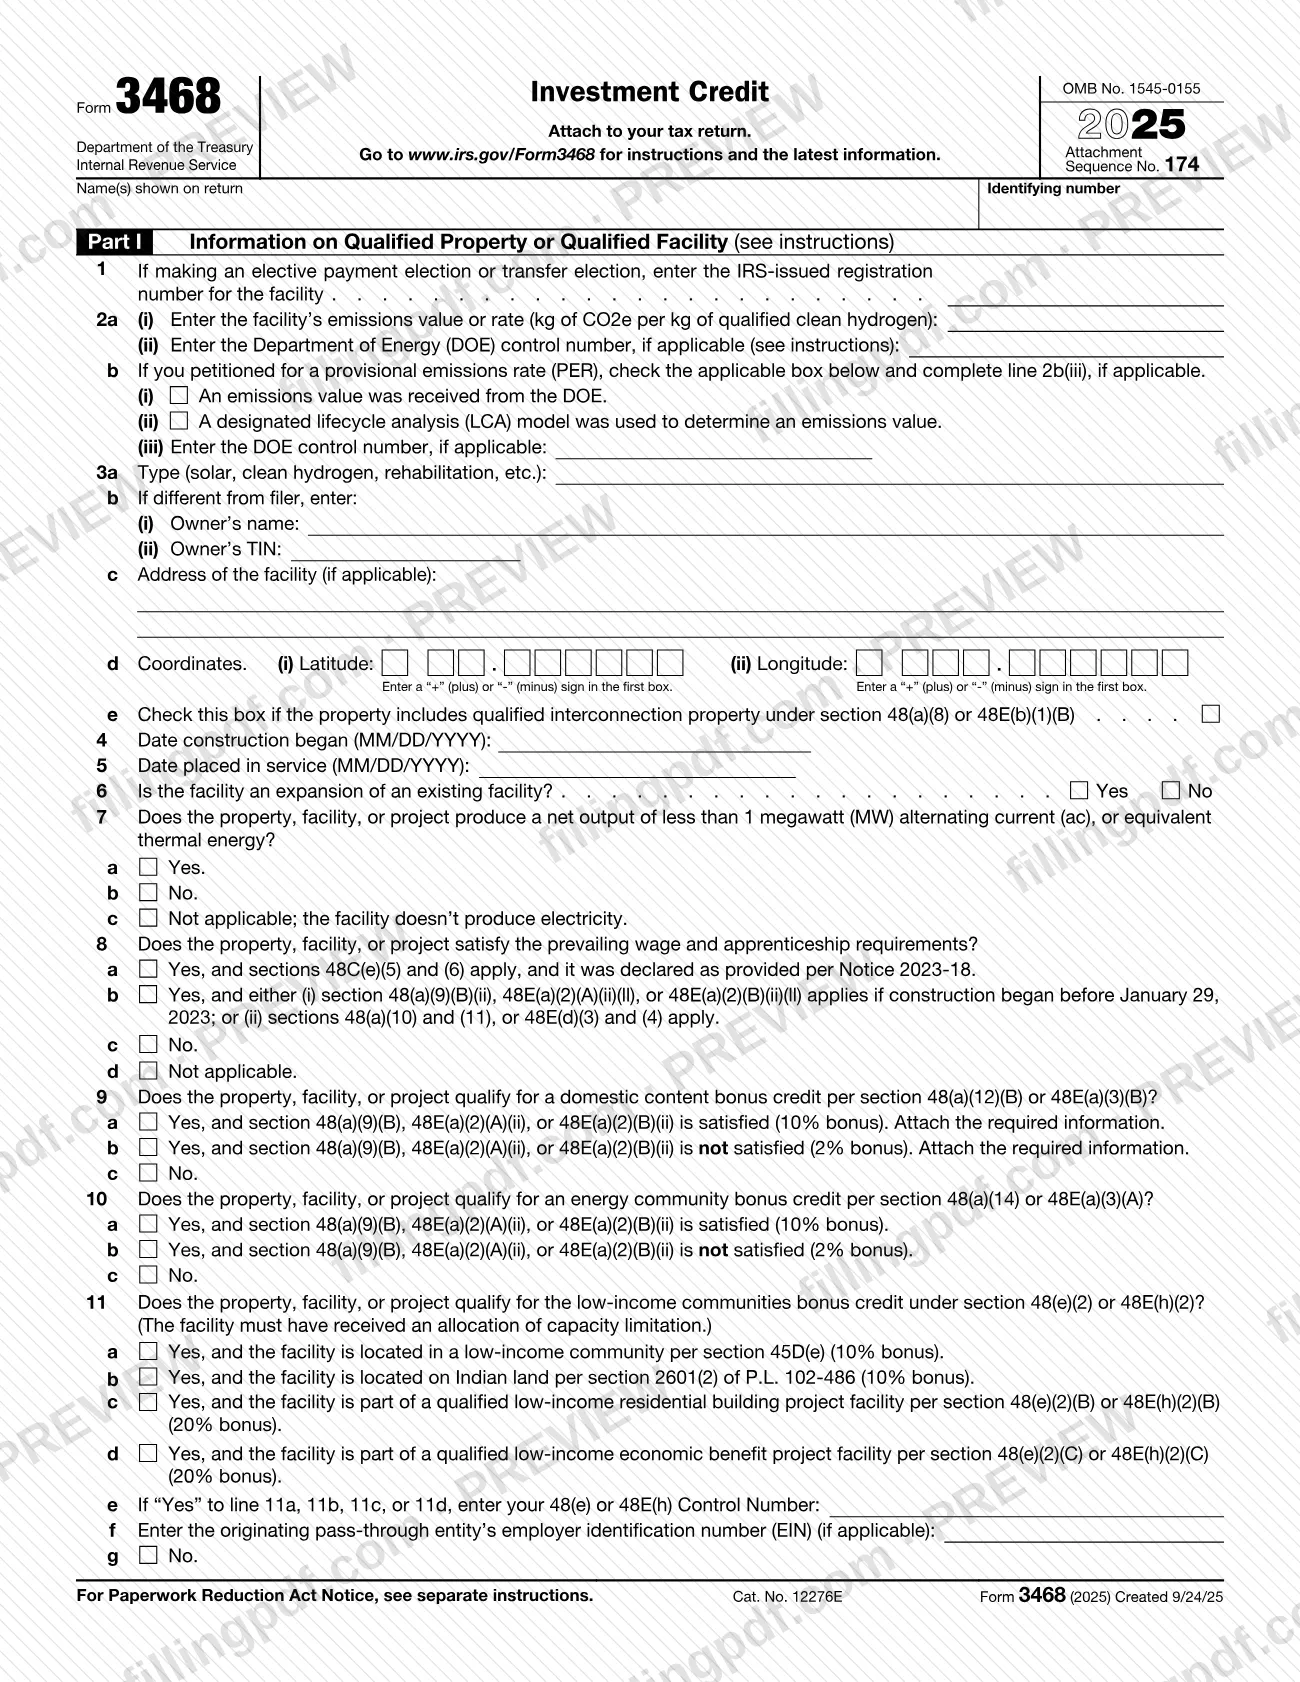
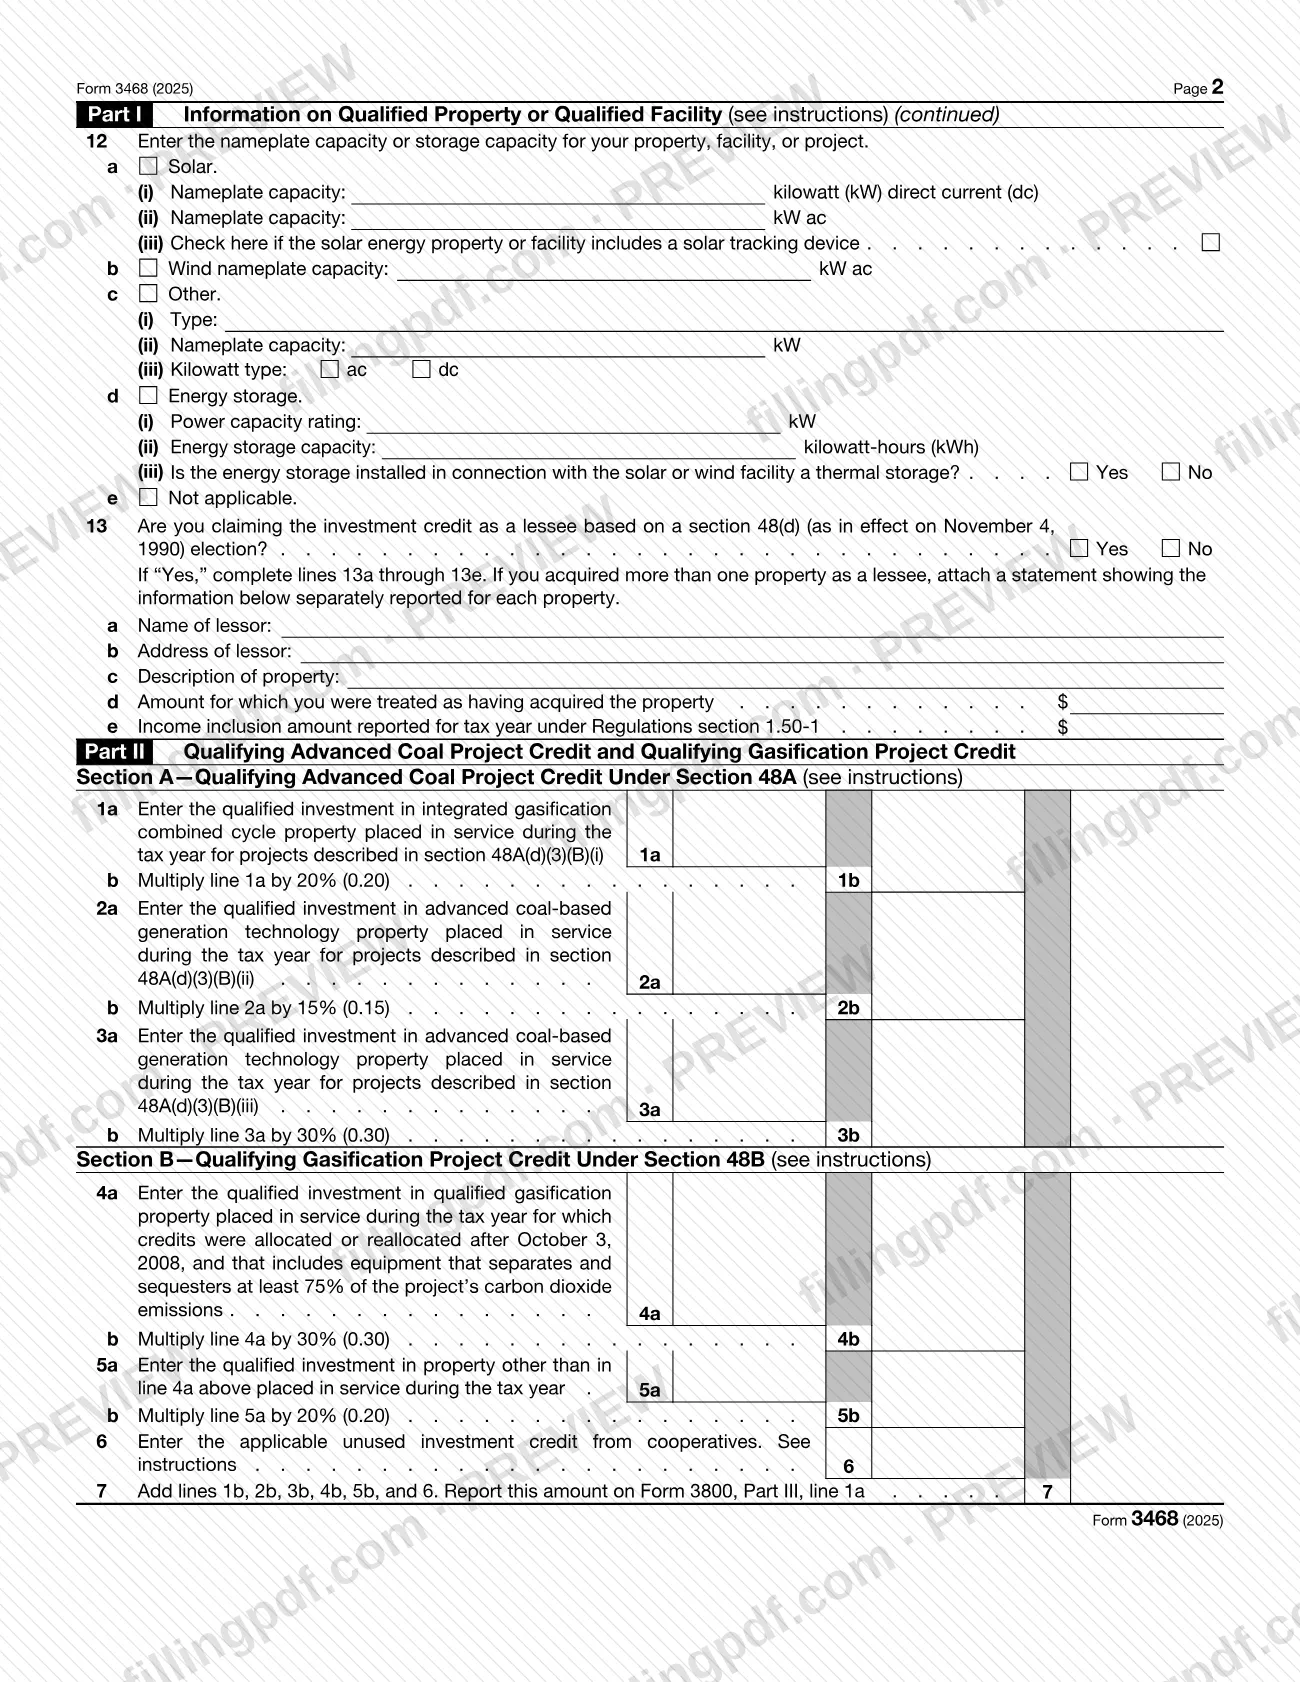
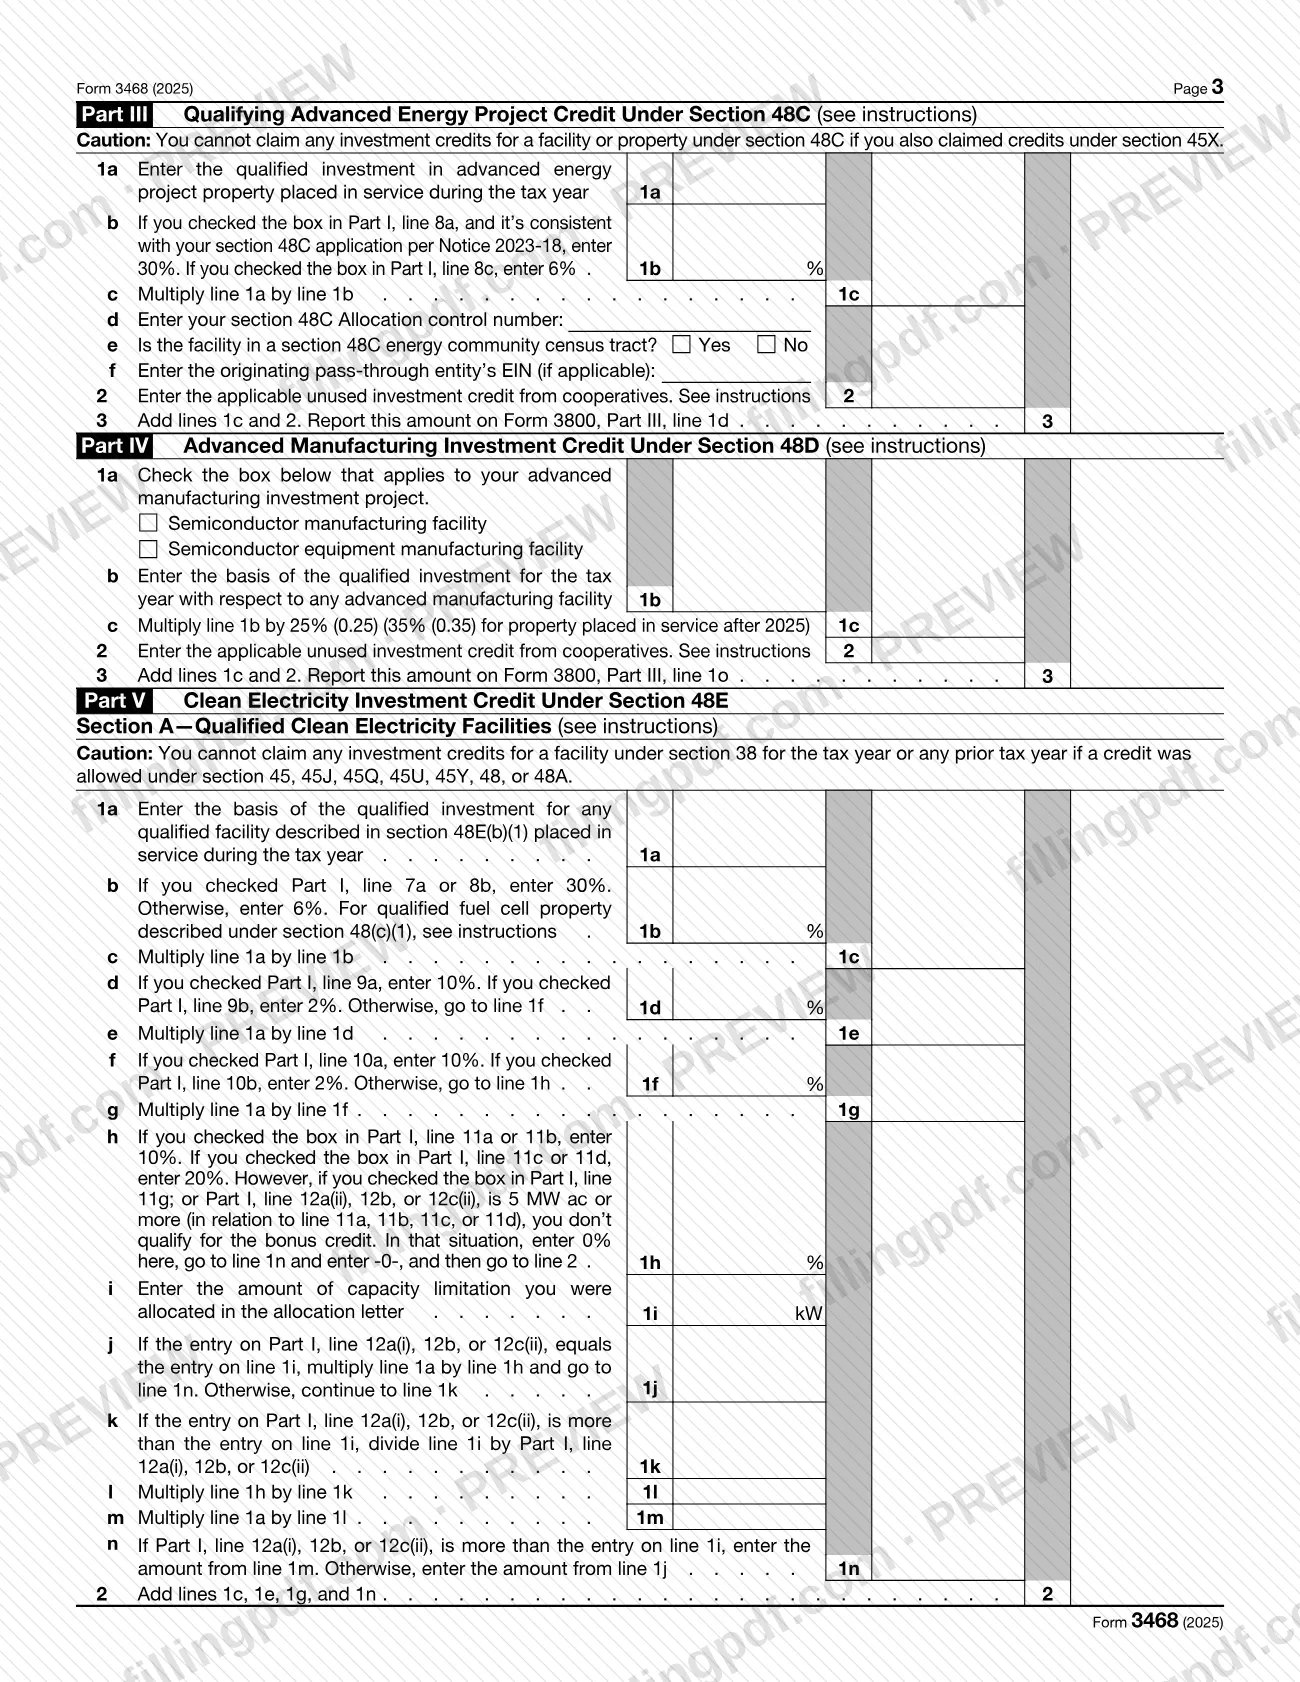
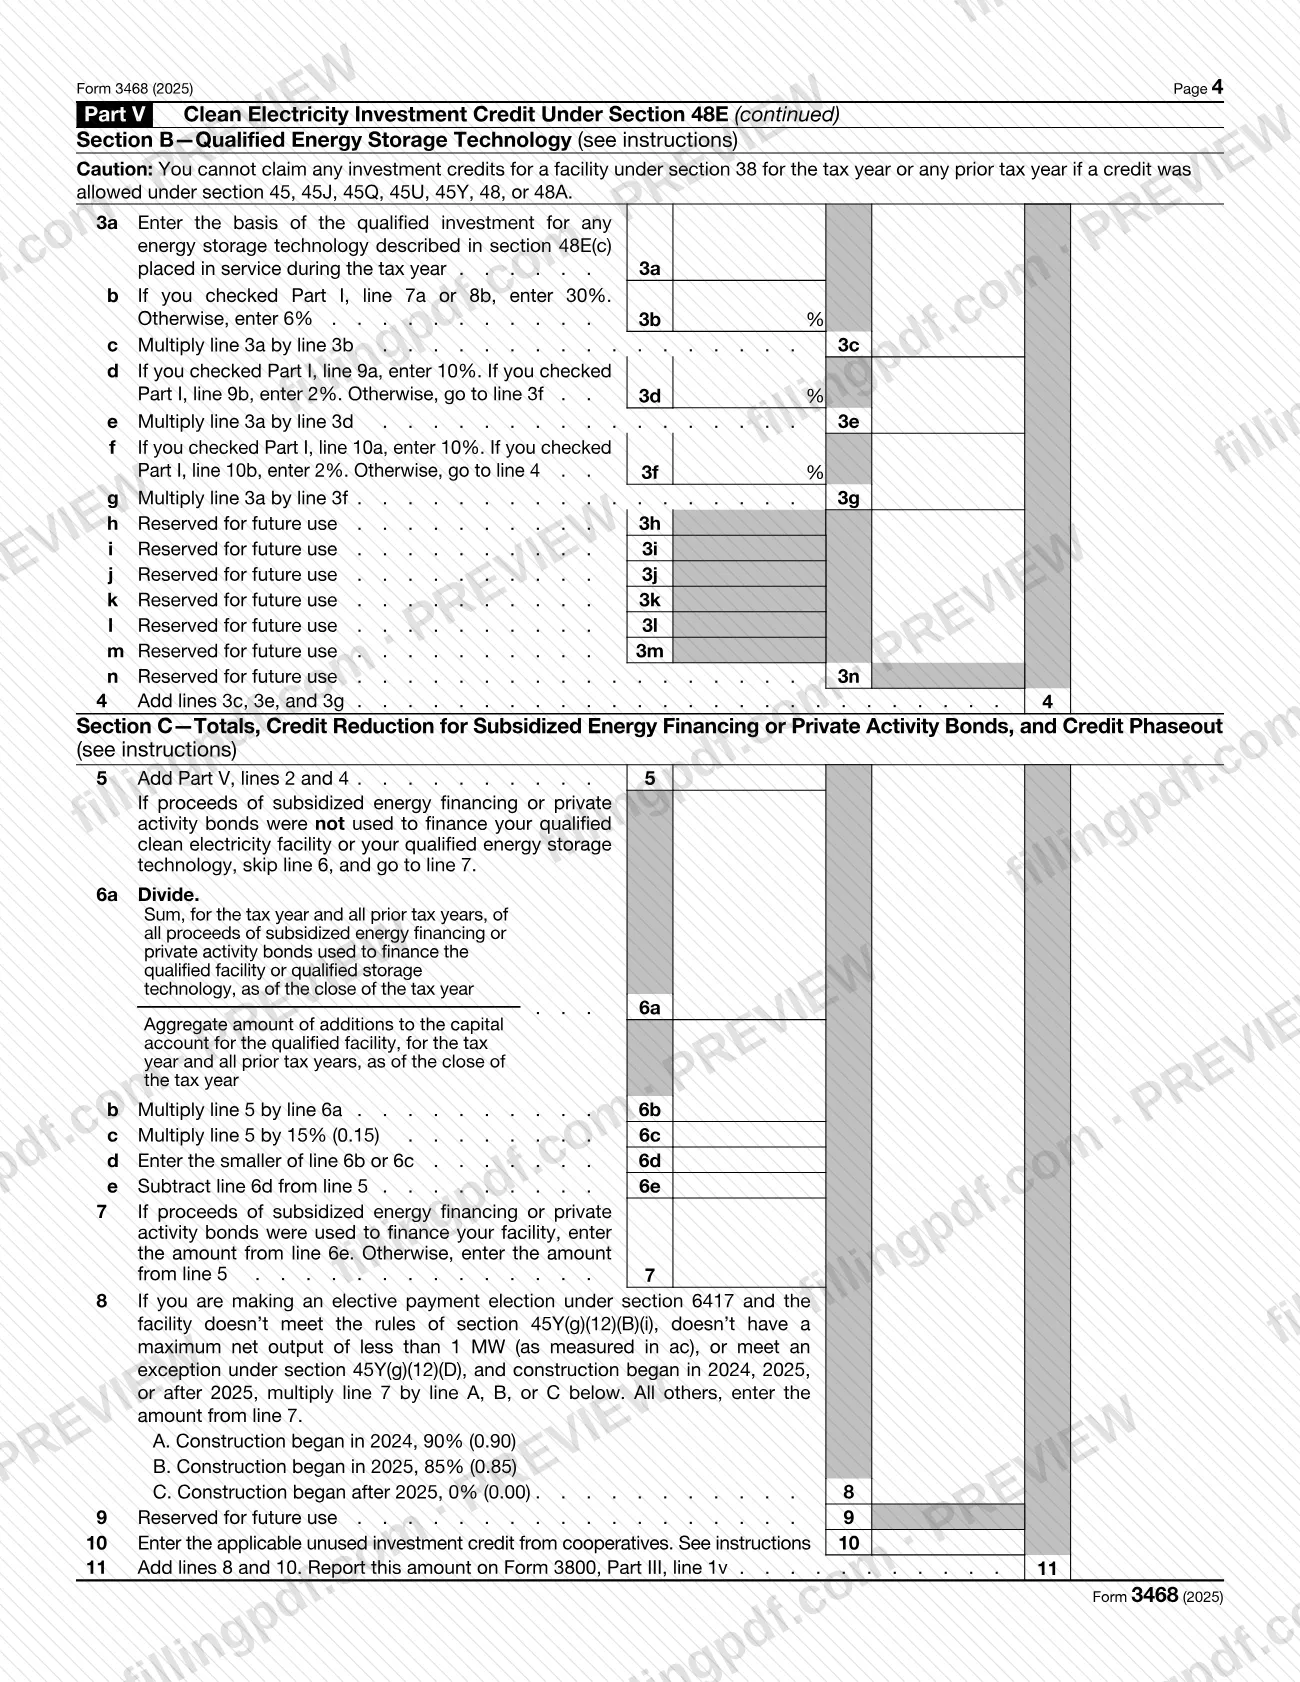
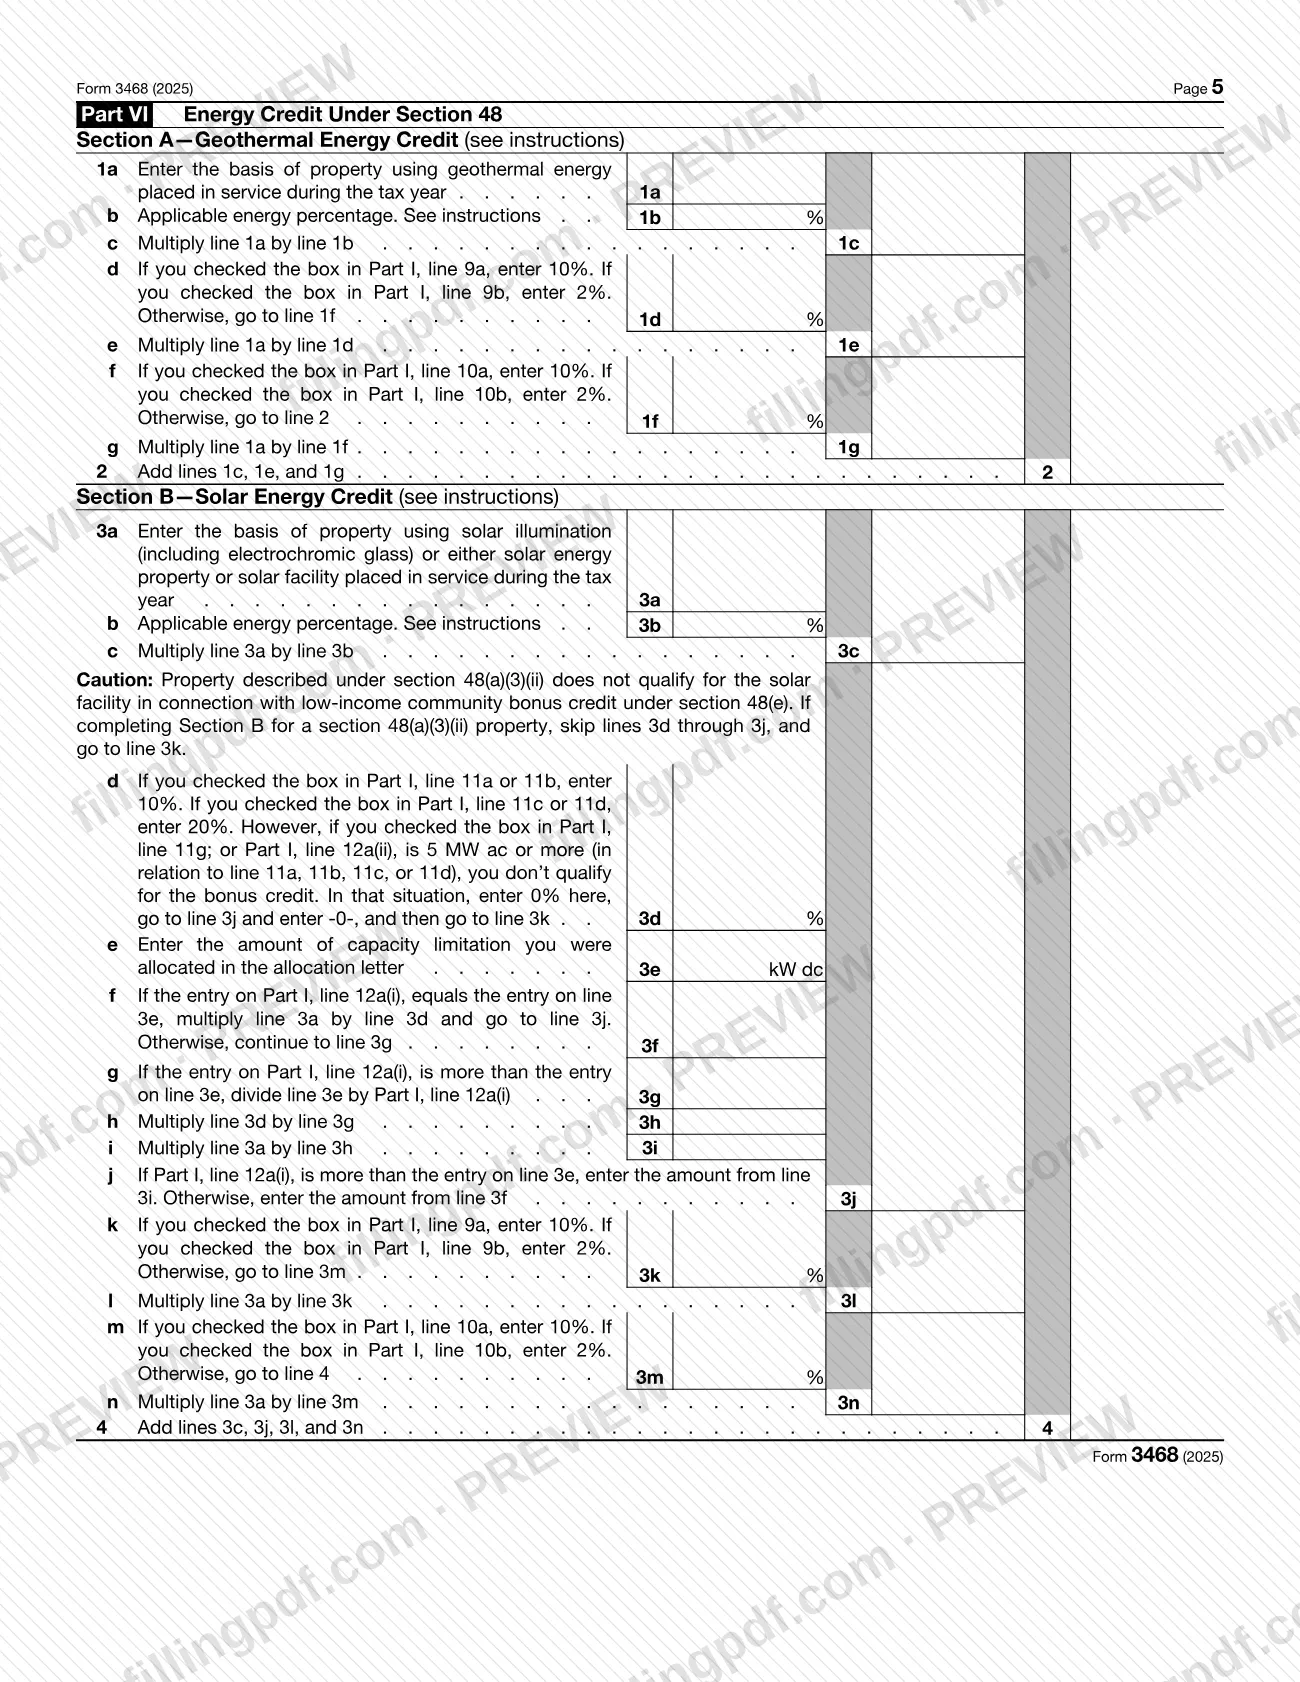
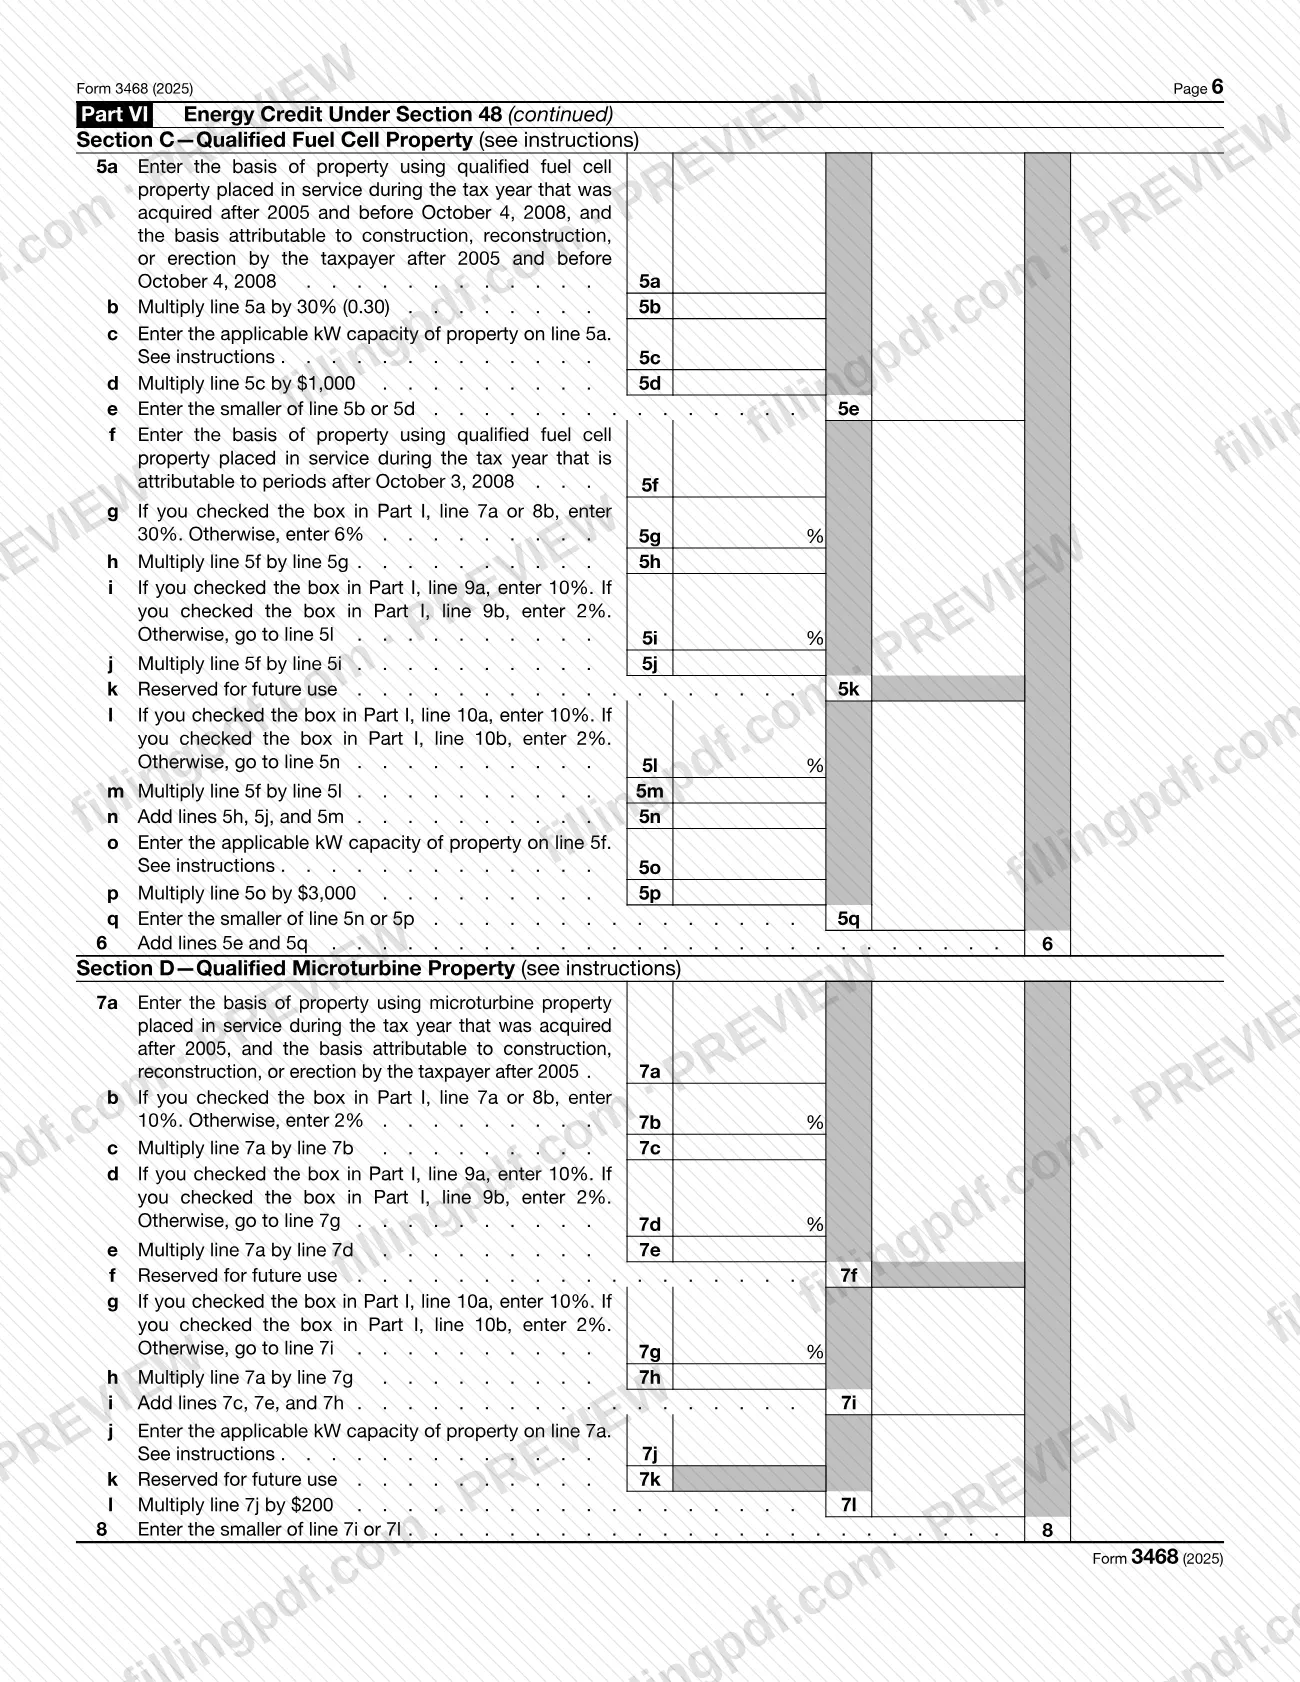
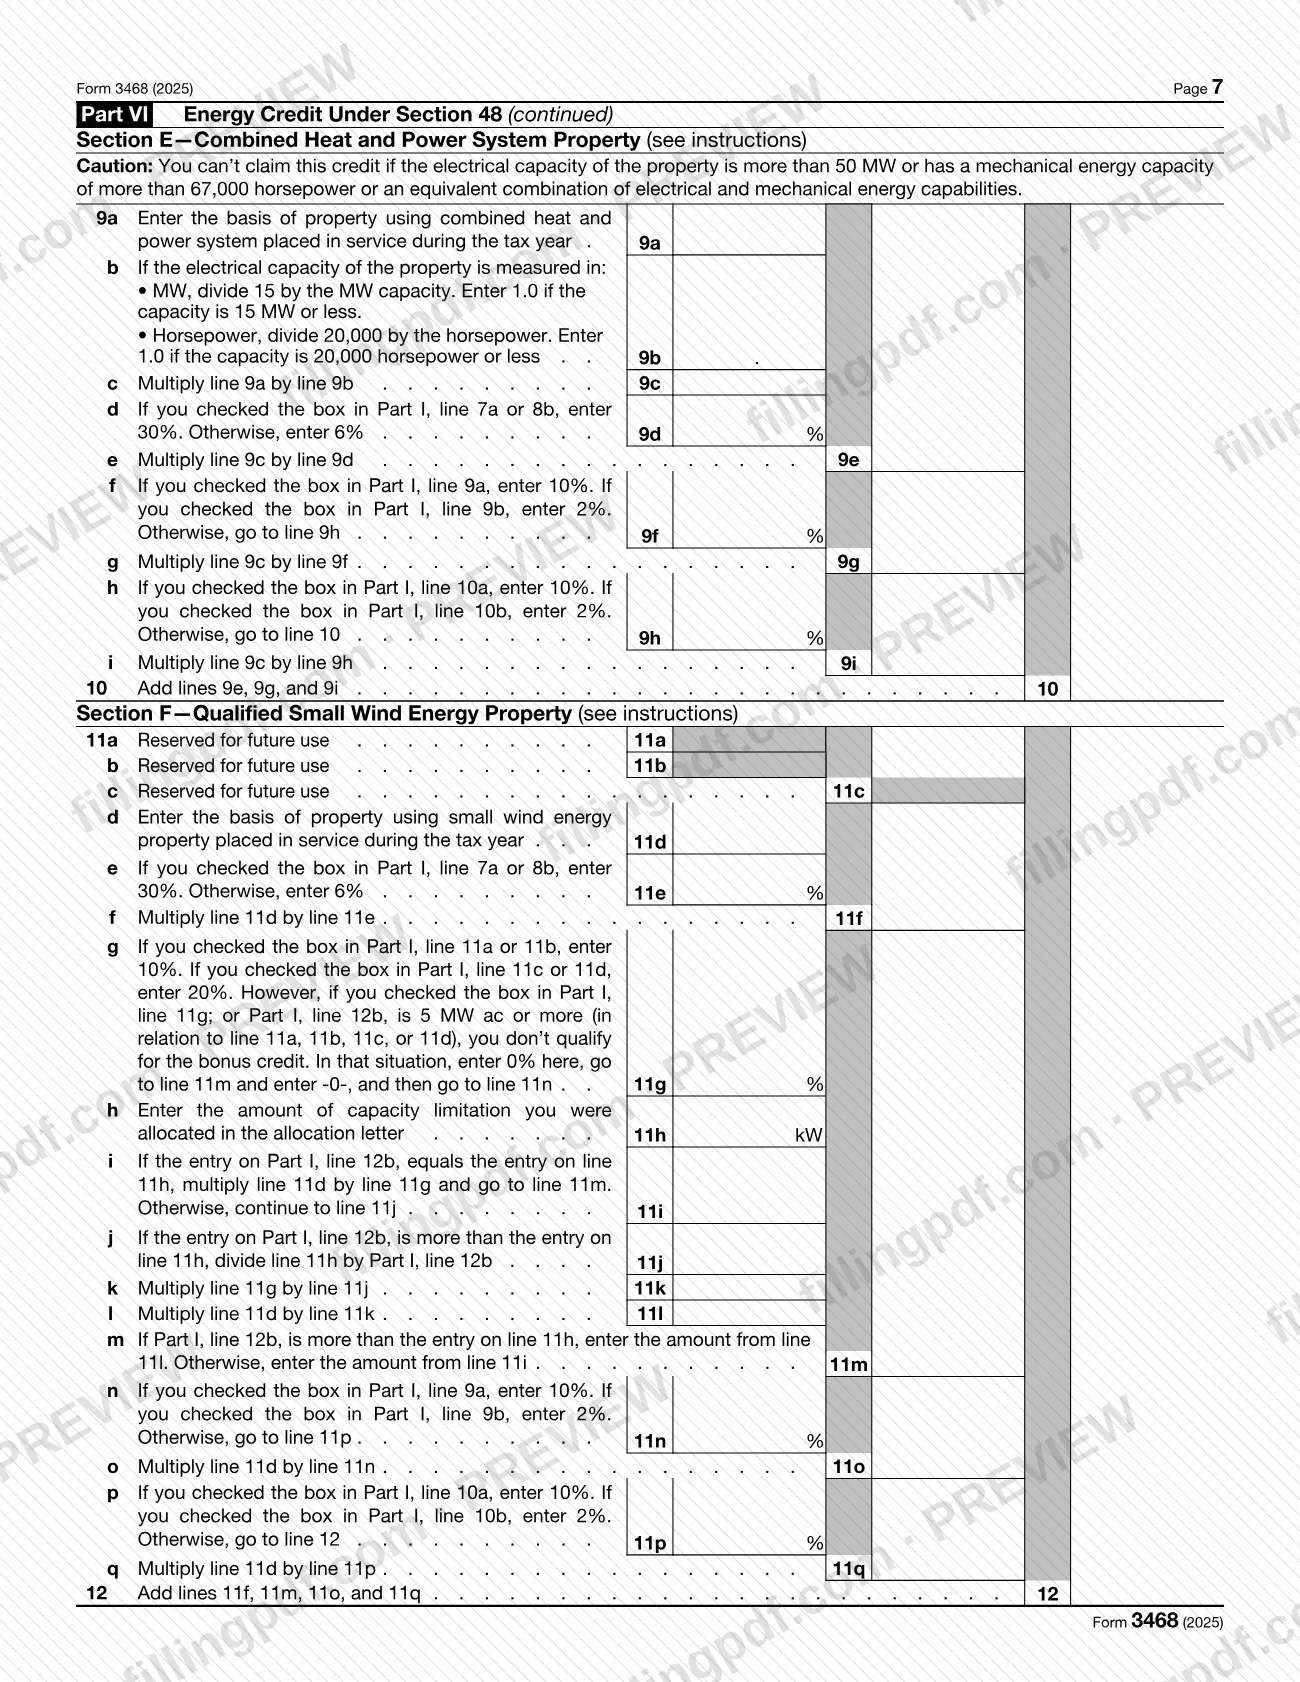
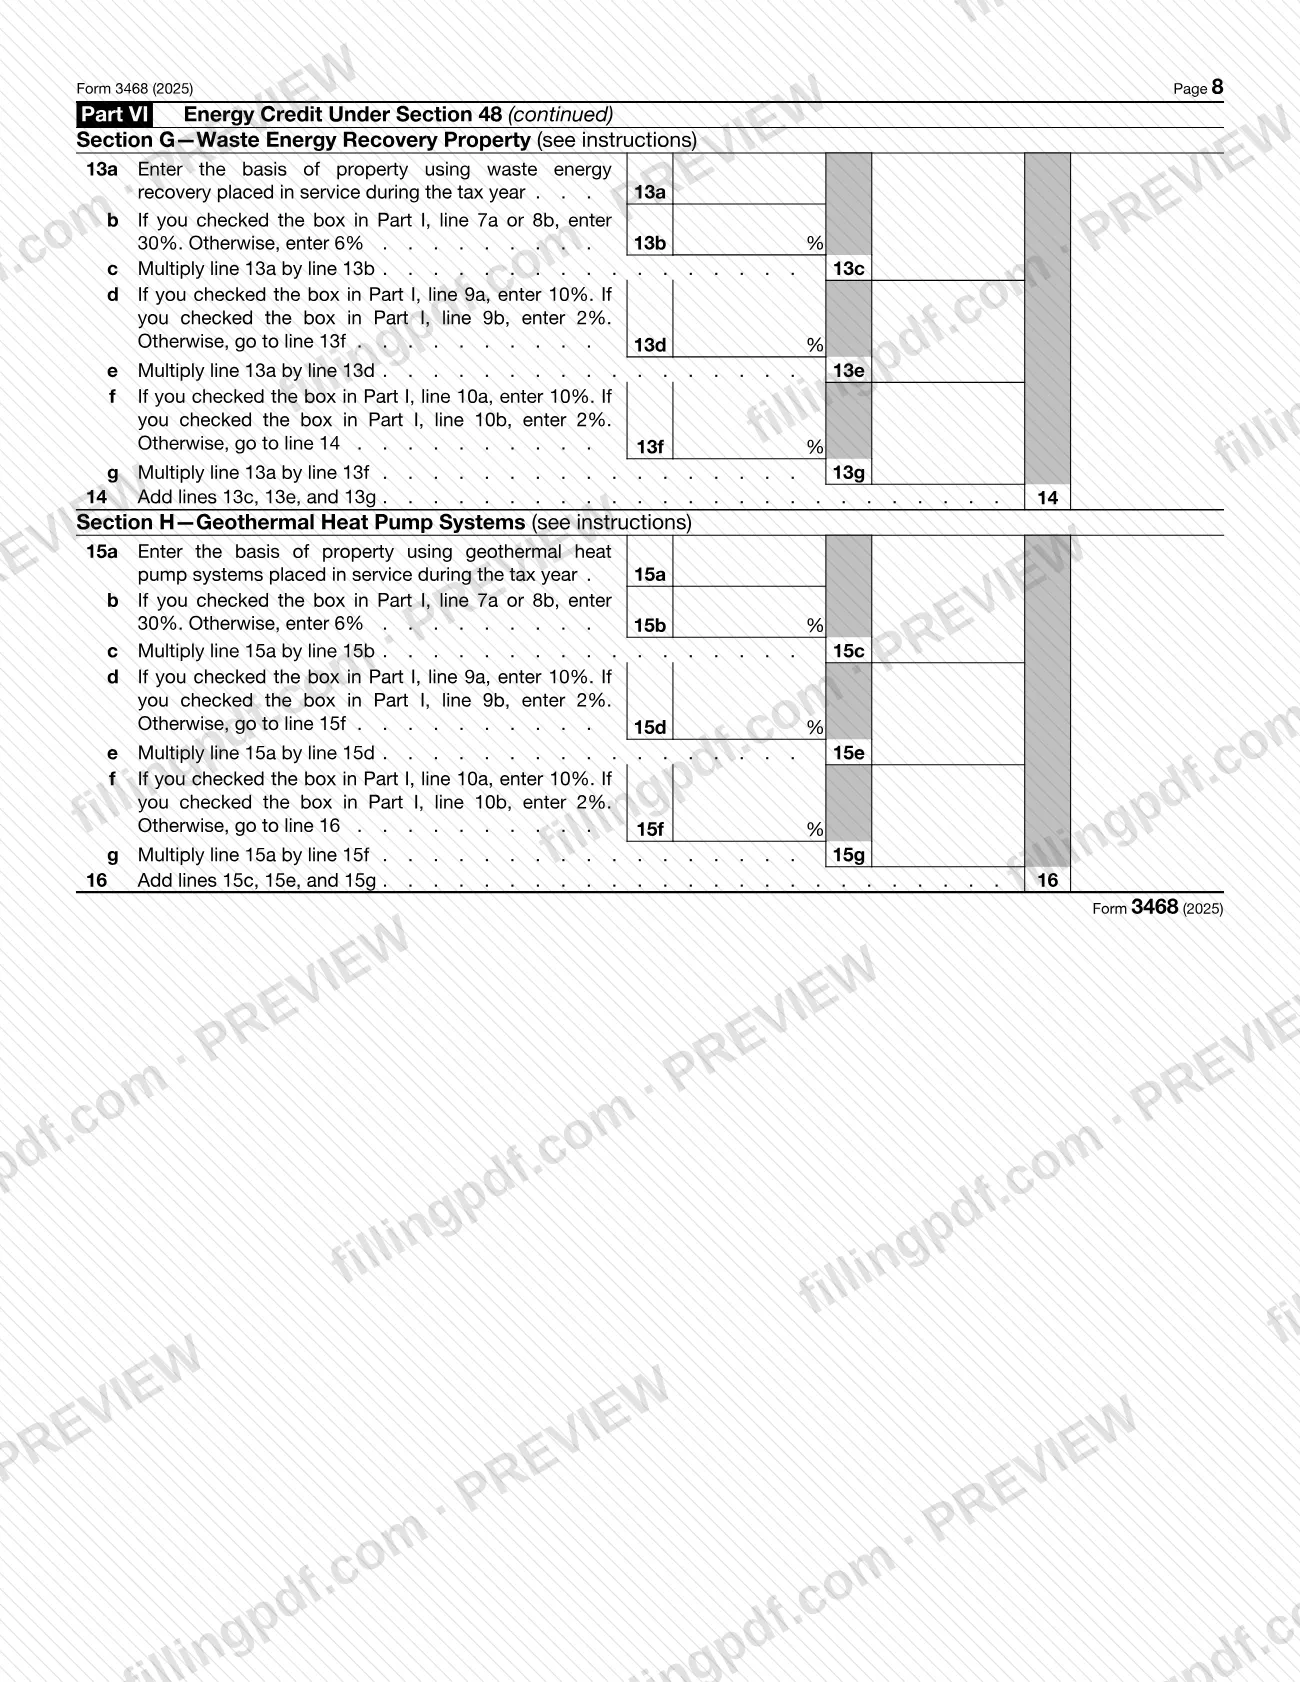
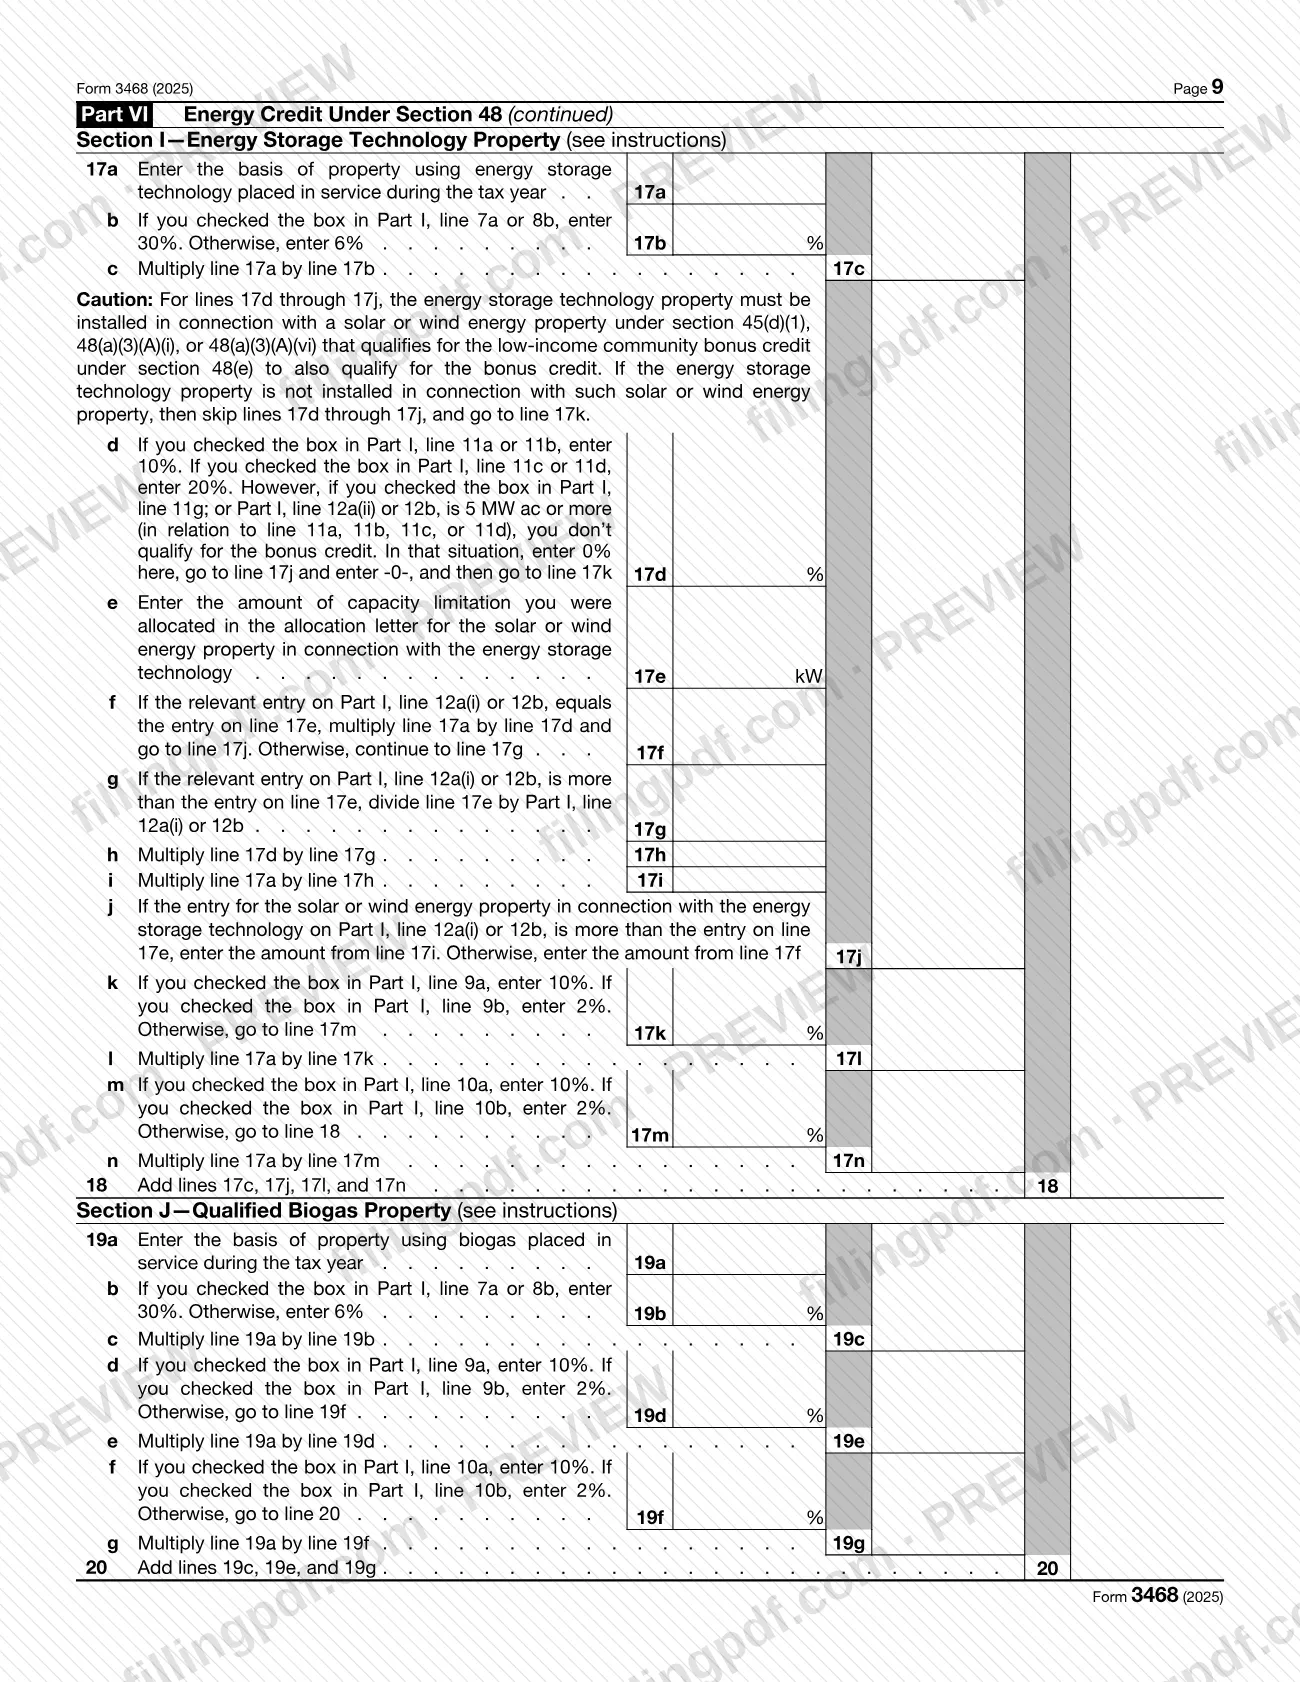
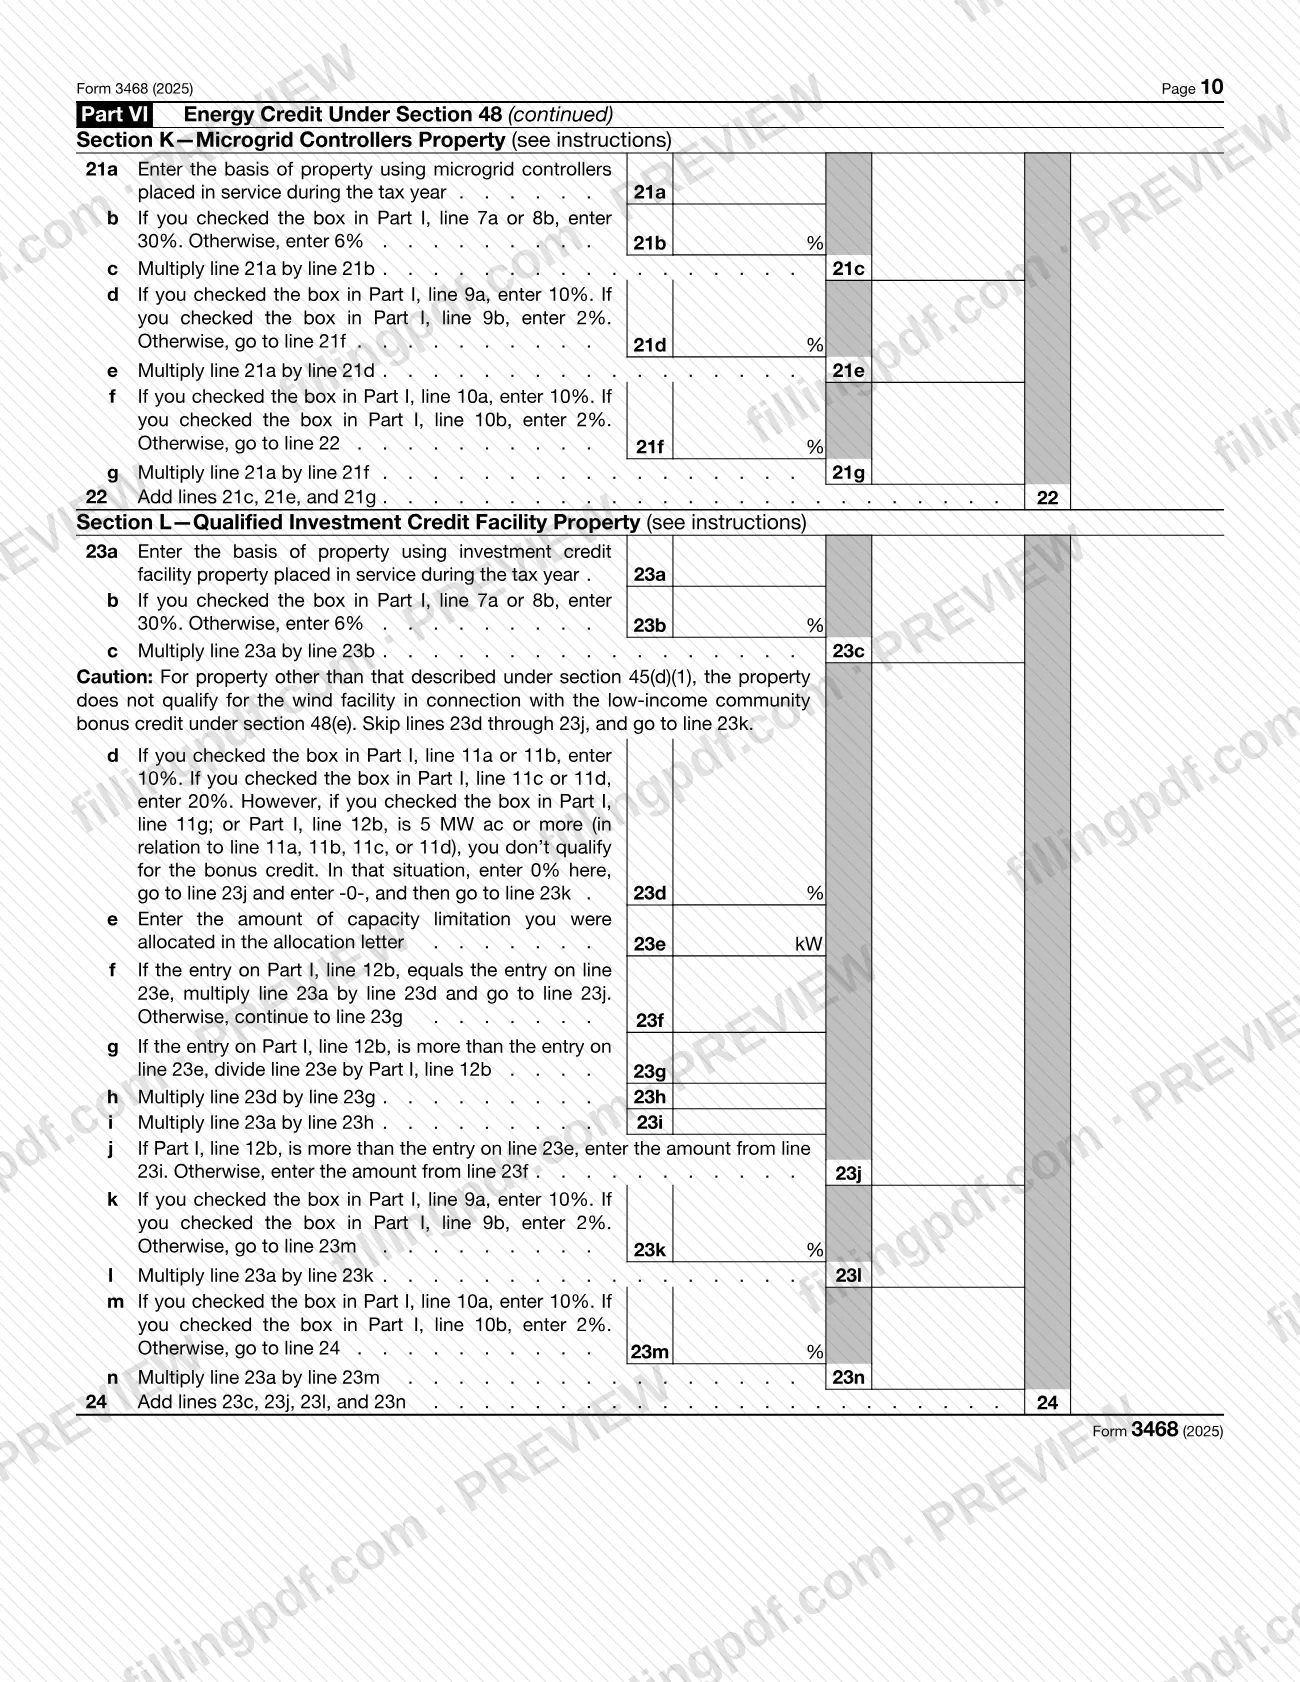
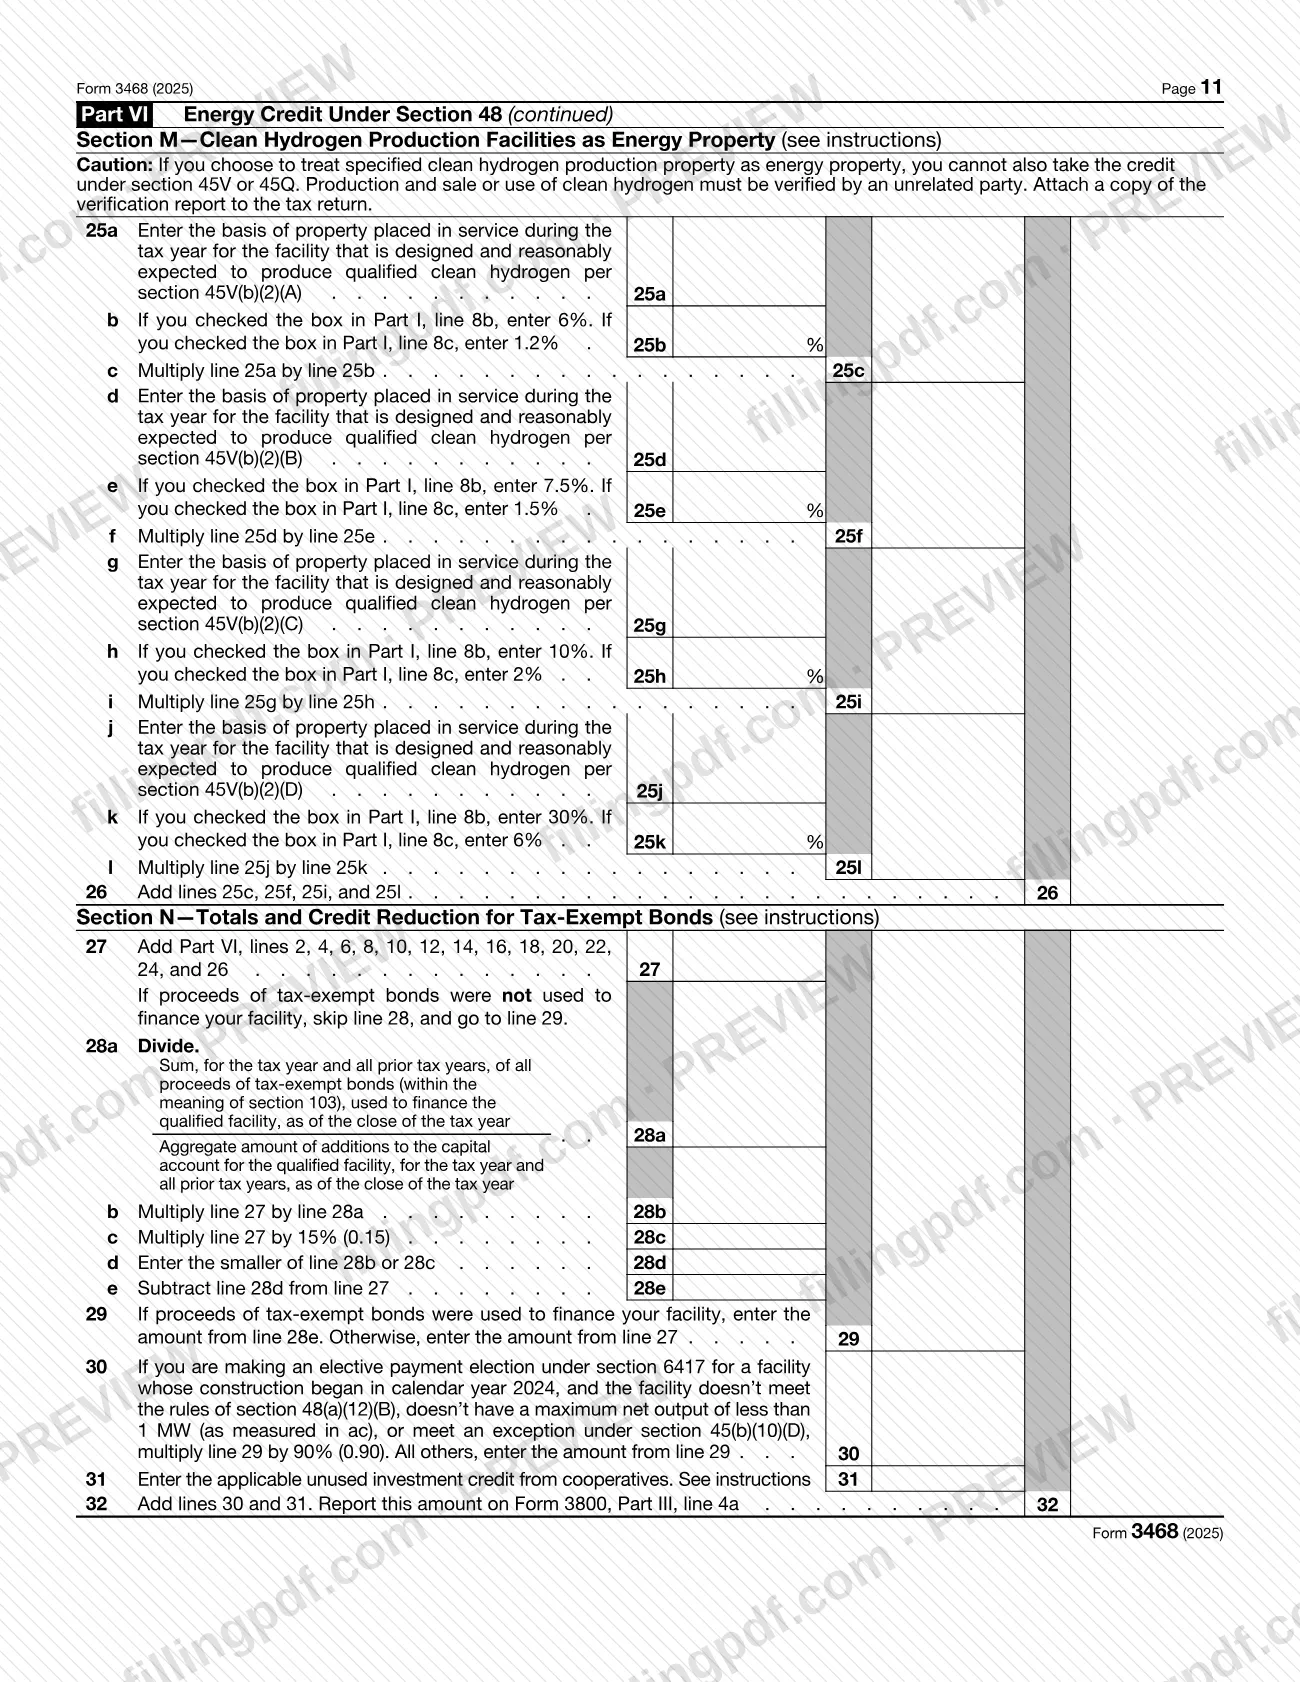
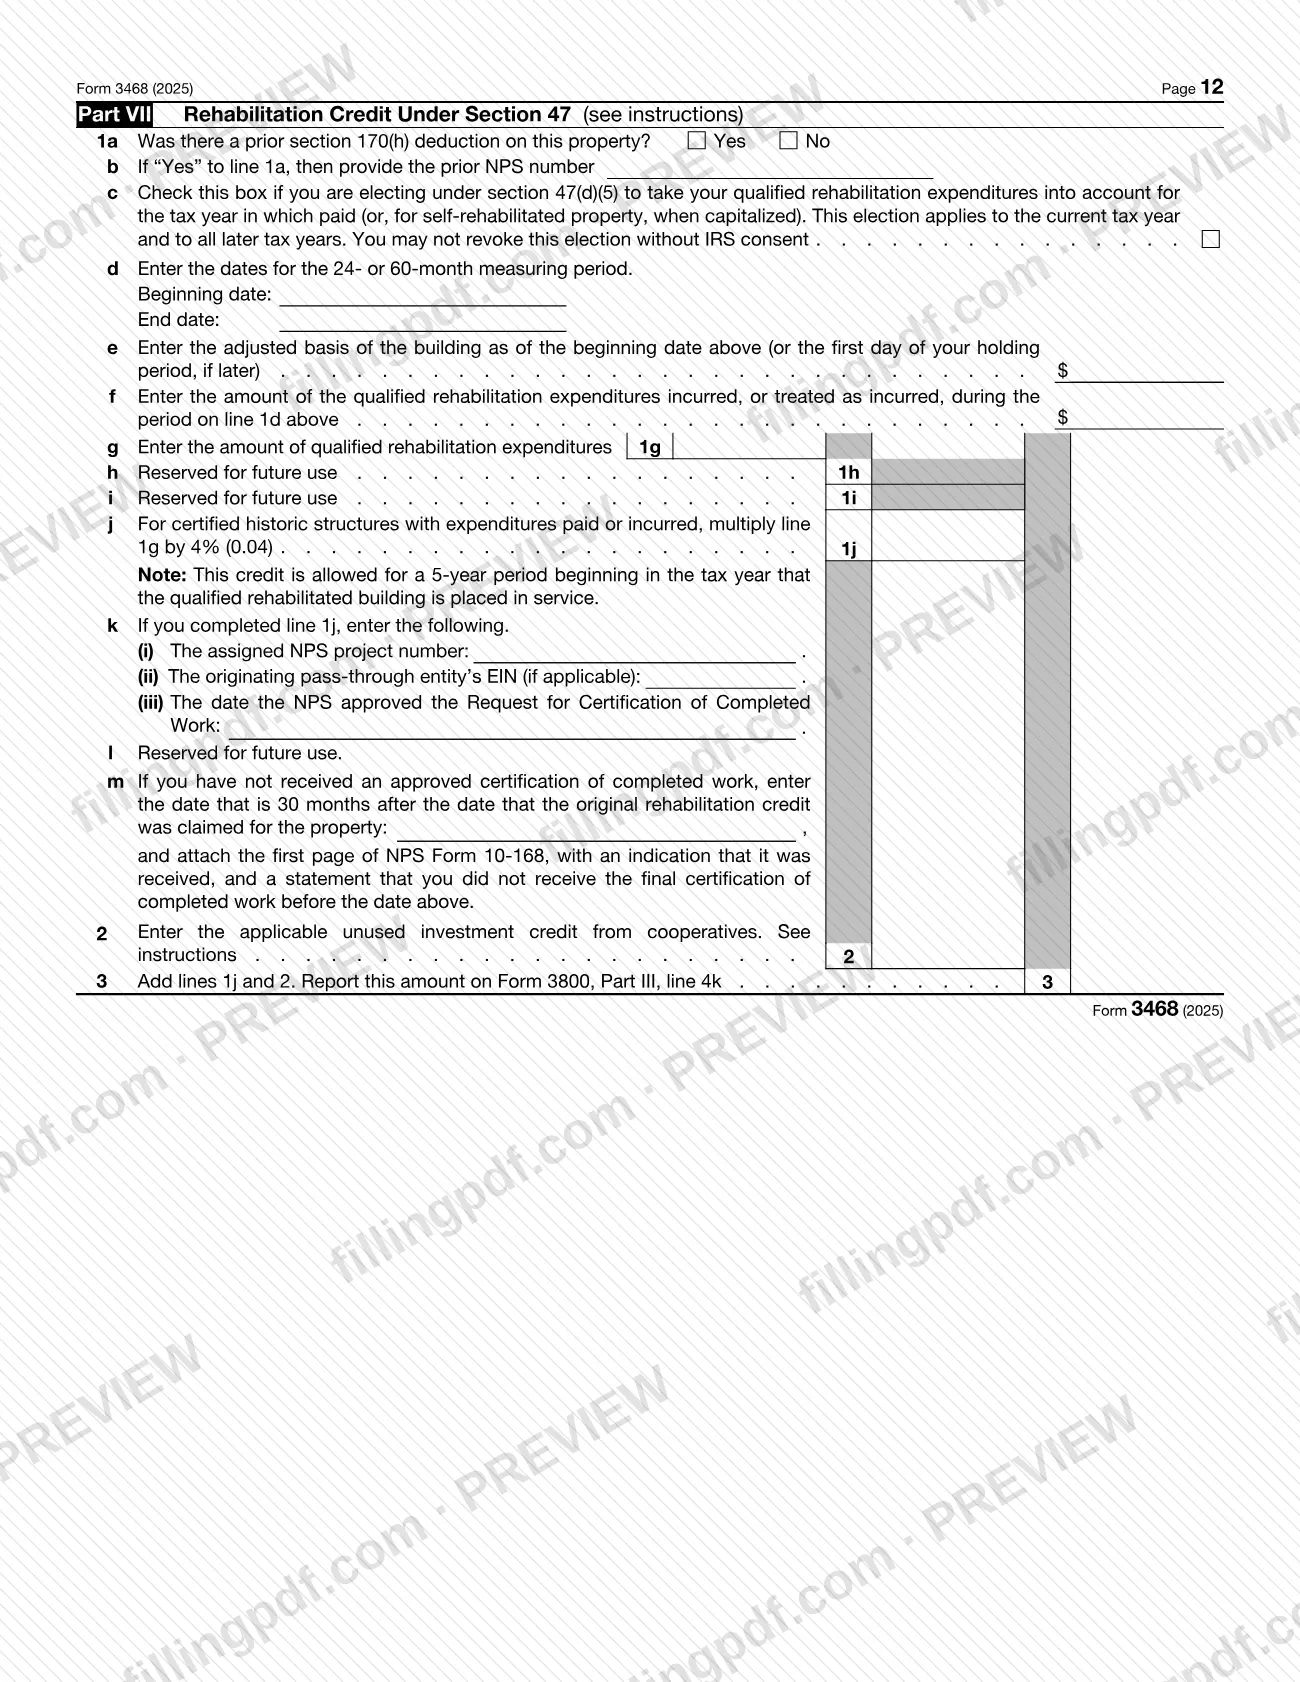
Form 3468, Investment Credit, is the Internal Revenue Service (IRS) form on which you describe a qualified facility or property and figure the investment credit for it. You use one Form 3468 for each facility or property and attach it to your tax return; the credit amount then carries to Form 3800. On FillingPDF you can fill out Form 3468 online and download or print the completed PDF. The form and its instructions are published by the IRS at www.irs.gov/Form3468.
Last updated
What is 3468?
Form 3468, Investment Credit, is the Internal Revenue Service (IRS) form used to report information about a qualified facility or property and to compute an investment credit for it, attached to your tax return.
Part I collects the facility or property information: registration number, type, owner, address, coordinates, construction and placed-in-service dates, the prevailing wage and apprenticeship (PWA) answer, bonus credit answers and capacity. You then complete the part that matches your credit:
- Part II: qualifying advanced coal project credit (section 48A) and qualifying gasification project credit (section 48B).
- Part III: qualifying advanced energy project credit (section 48C).
- Part IV: advanced manufacturing investment credit (section 48D).
- Part V: clean electricity investment credit (section 48E).
- Part VI: energy credit (section 48), Sections A through N.
- Part VII: rehabilitation credit (section 47).
The IRS instructions say to complete a separate Form 3468 for each facility or property. The credit totals are reported on the matching lines of Form 3800, Part III. Form 7220, Prevailing Wage and Apprenticeship (PWA) Verification and Corrections, is filed for each facility or property when you claim the increased credit for meeting the PWA requirements under Part III, V or VI. A recapture of the credit is reported on Form 4255, Certain Credit Recapture, Excessive Payments, and Penalties. The form is OMB No. 1545-0155, Attachment Sequence No. 174.
Who needs to file 3468?
You use Form 3468 if you claim one of the investment credits it covers for a facility or property: the advanced coal project, gasification project, advanced energy project, advanced manufacturing investment, clean electricity investment, energy or rehabilitation credit.
- Partnerships, S corporations, estates and trusts attach a separate Form 3468 for each facility or property used in the business even if they cannot claim the credit, did not elect payment under section 48D(d), or did not elect a transfer under section 6418. They complete the required Part I lines and only the lines the instructions list, then attach a statement to Schedule K-1.
- Tax-exempt organizations and governmental entities that make an elective payment election under section 6417 for a section 48C, 48E or 48 credit attach Form 3468 and Form 3800 to Form 990-T or another applicable income tax return.
- Cooperative patrons file a separate Form 3468 to report unused investment credit allocated from cooperatives.
You cannot claim a credit for property used mainly outside the United States, used by a governmental unit or foreign person or entity (with exceptions), used for lodging, or certain MACRS business property expensed under section 179. You also cannot claim section 48C credits for a facility or property if you claimed credits under section 45X.
When to file 3468
Form 3468 is filed with the tax return for the year in which the credit is claimed; it has no separate due date. Each part figures the investment in property placed in service during the tax year, so the credit is reported on the return for that year.
If you intend to make an elective payment election or transfer election on Form 3800 for a credit in Part III, IV, V or VI, you must first complete the IRS pre-filing registration for each property or facility, before you file your tax return.
Watch the recapture period. The instructions say you may have to refigure and recapture all or part of the credit if you dispose of the property, or change its use, before the end of 5 full years after it was placed in service.
Documents you need
- Form 3800, General Business Credit, attached with Form 3468 so the credit amount is reported on the applicable line of Form 3800, Part III.
- Form 7220, Prevailing Wage and Apprenticeship (PWA) Verification and Corrections, for each facility or property when you claim the increased credit for meeting the PWA requirements under Part III, V or VI.
- Increased credit amount statement for each facility, energy storage technology or energy project, when you check line 7a or 8b to claim an increased credit in Part V or Part VI.
- Domestic content certification statement for each applicable project, attached at filing, when you check line 9a or 9b in Part V or Part VI.
- Provisional emissions rate (PER) petition, with the DOE letter if applicable, when you complete Part I, line 2b in Part V, Section A and petitioned for a PER.
- Copy of the verification report for the production and sale or use of clean hydrogen, when you complete Part VI, Section M.
- First page of NPS Form 10-168, marked as received, plus a statement that you did not receive the final certification, when you complete Part VII, line 1m.
- Statement showing lessor name, address, property description and amounts for each property, when you acquired more than one property as a lessee and answer Yes on line 13.
- Statement attached to Schedule K-1 with the facility information and distributive share of amounts, for partnerships, S corporations, estates and trusts.
- Form 990-T or other applicable income tax return, for tax-exempt and governmental entities making an elective payment election.
How to fill out 3468
Enter your name and identifying number
At the top, enter the name(s) shown on your return and your identifying number. Use a separate Form 3468 for each facility or property.
Identify the facility in Part I
Line 1: the IRS-issued registration number, if making an elective payment or transfer election. Line 3a: the type of facility, such as solar, clean hydrogen or rehabilitation. Complete 3b if the owner differs from you, and 3c, 3d and 3e for the address, coordinates and interconnection property.
Report clean hydrogen emissions data
Line 2a: for Part VI, Section M filers, the emissions value or rate and the DOE control number. Line 2b: for Part V, Section A filers who petitioned for a provisional emissions rate, check the applicable box and give the DOE control number.
Enter dates and expansion status
Line 4: the date construction began, in MM/DD/YYYY format. Line 5: the date placed in service, MM/DD/YYYY. Line 6: check Yes or No for whether the facility is an expansion of an existing facility.
Answer the PWA and bonus credit lines
Line 7: whether net output is under 1 MW ac. Line 8: PWA requirements. Lines 9, 10 and 11: domestic content, energy community and low-income communities bonus credits. Check the box the instructions assign to your part, and enter the control number on line 11e where required.
Enter capacity and lessee information
Line 12: nameplate or storage capacity for solar, wind, other property or energy storage. Line 13: check Yes only if you claim the credit as a lessee under a section 48(d) election, then complete lines 13a through 13e.
Complete Part II for coal or gasification
Section A (section 48A): enter qualified investment on lines 1a, 2a and 3a and multiply by 20%, 15% and 30%. Section B (section 48B): lines 4a and 5a. Add lines 1b, 2b, 3b, 4b, 5b and 6 on line 7 and report it on Form 3800, Part III, line 1a.
Complete Part III for advanced energy
Enter the qualified investment on line 1a and the percentage on line 1b (30% if you checked line 8a consistent with your section 48C application, 6% if line 8c). Enter your allocation control number on line 1d. Line 3 goes to Form 3800, Part III, line 1d.
Complete Part IV for advanced manufacturing
Line 1a: check the semiconductor manufacturing or semiconductor equipment manufacturing box. Line 1b: enter the basis of qualified investment. Line 1c: multiply by 25%, or 35% for property placed in service after 2025. Line 3 goes to Form 3800, Part III, line 1o.
Complete Part V for clean electricity
Section A covers qualified facilities (lines 1a through 2), Section B energy storage technology (lines 3a through 4) and Section C the totals and credit reductions (lines 5 through 11). Report line 11 on Form 3800, Part III, line 1v.
Complete Part VI for the energy credit
Use the Section A through M that matches your property, such as geothermal, solar, fuel cell or microturbine. Section N totals them: line 27, the tax-exempt bond reduction on line 28, and line 32, reported on Form 3800, Part III, line 4a.
Complete Part VII for rehabilitation
Line 1a: prior section 170(h) deduction. Lines 1d to 1g: measuring period dates, adjusted basis and qualified rehabilitation expenditures. Line 1j: 4% of line 1g for certified historic structures. Line 3 goes to Form 3800, Part III, line 4k.
Review, attach statements and download
Check that each part you completed carries to Form 3800 and that required statements and forms are ready. Download or print the completed PDF from FillingPDF and attach it to your tax return as described under How to submit.
How to submit 3468
Form 3468 is not sent on its own: you attach it to your tax return. The instructions give no separate mailing address for it.
- With your return: attach the completed Form 3468, and Form 3800 where the instructions require it, to the return you file for the tax year.
- Individuals who e-file: if attachments are required for Form 3468, you must send a paper Form 8453, U.S. Individual Income Tax Transmittal for an IRS e-file Return.
- Tax-exempt and governmental entities: attach Form 3468 and Form 3800 to Form 990-T or the other applicable income tax return.
- Partnerships, S corporations, estates and trusts: attach the form to your return and add the required statement to Schedule K-1.
Elective payment and transfer elections require the IRS-issued registration number on Part I, line 1, obtained through the pre-filing registration at IRS.gov/Register. Attach the statements and forms the instructions require for your lines. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Combining several facilities or properties on one Form 3468; the instructions require a separate form for each facility or property.
- Skipping Form 3468 as a partnership, S corporation, estate or trust because the credit cannot be claimed; a separate form is still attached for each facility used in the business.
- Claiming a section 48C credit for a facility or property when you also claimed credits under section 45X for it.
- Checking line 7a or 8b to claim an increased credit without attaching the increased credit amount statement, or without Form 7220 where it applies.
- Checking line 9a or 9b for the domestic content bonus without attaching the domestic content certification statement at filing.
- Making an elective payment or transfer election without completing the pre-filing registration and entering the IRS-issued registration number on Part I, line 1.
- Completing the credit parts but not reporting the total on the matching line of Form 3800, Part III (for example Part V, line 11 to line 1v).
- Claiming the Part IV advanced manufacturing credit when construction of the qualified property begins after 2026; the instructions bar it.
- Using the address of the lessor's registered agent on line 13b instead of the lessor's principal office or place of business.
- Choosing to treat clean hydrogen property as energy property in Part VI, Section M while also taking the section 45V or 45Q credit.
Frequently asked questions
What is Form 3468 used for?
Form 3468 is the IRS form you attach to your tax return to report a qualified facility or property and compute the investment credit for it. Depending on the part completed, it covers the section 48A, 48B, 48C, 48D, 48E, 48 or 47 credit.
Do I need a separate Form 3468 for each facility?
Yes. The IRS instructions say to complete a separate Form 3468 to claim an investment credit for each facility or property. Each form has Part I for the facility information plus the part that computes the credit for it.
Where does the credit on Form 3468 go?
Each part's total is reported on Form 3800, Part III: Part II line 7 to line 1a, Part III line 3 to line 1d, Part IV line 3 to line 1o, Part V line 11 to line 1v, Part VI line 32 to line 4a and Part VII line 3 to line 4k. Attach both forms to your return.
Do I have to register before electing a payment or transfer?
Yes. Before you file your return, you must complete a pre-filing registration for each property or facility if you intend to make an elective payment or transfer election for a credit in Part III, IV, V or VI. You then enter the IRS-issued registration number on Part I, line 1.
What do I attach to claim the increased credit or bonus credits?
For an increased credit on line 7a or 8b in Part V or VI, attach an increased credit amount statement and, where it applies, Form 7220. For a domestic content bonus on line 9a or 9b, attach a domestic content certification statement at filing.
Can a partnership or S corporation skip Form 3468 if it cannot claim the credit?
No. Partnerships, S corporations, estates and trusts attach a separate Form 3468 for each facility or property used in the business even if they cannot claim the credit. They complete Part I and only the lines the instructions list, then attach a statement to Schedule K-1.
When can the investment credit be recaptured?
You may have to recapture all or part of the credit if you dispose of the property or change its use before the end of 5 full years after it was placed in service, among other listed events. Recapture is reported on Form 4255.
Where do I send Form 3468?
You do not send it separately. Form 3468 is attached to your tax return, with Form 3800 where required. Individuals who e-file must send a paper Form 8453 if attachments are required, and tax-exempt entities attach both forms to Form 990-T or another applicable return.
Can I fill out Form 3468 online on FillingPDF?
Yes. You can fill out the Form 3468 PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the form with the IRS; you submit it with your tax return through the IRS channels.
Ready to fill out 3468?
Fill out 3468 now