
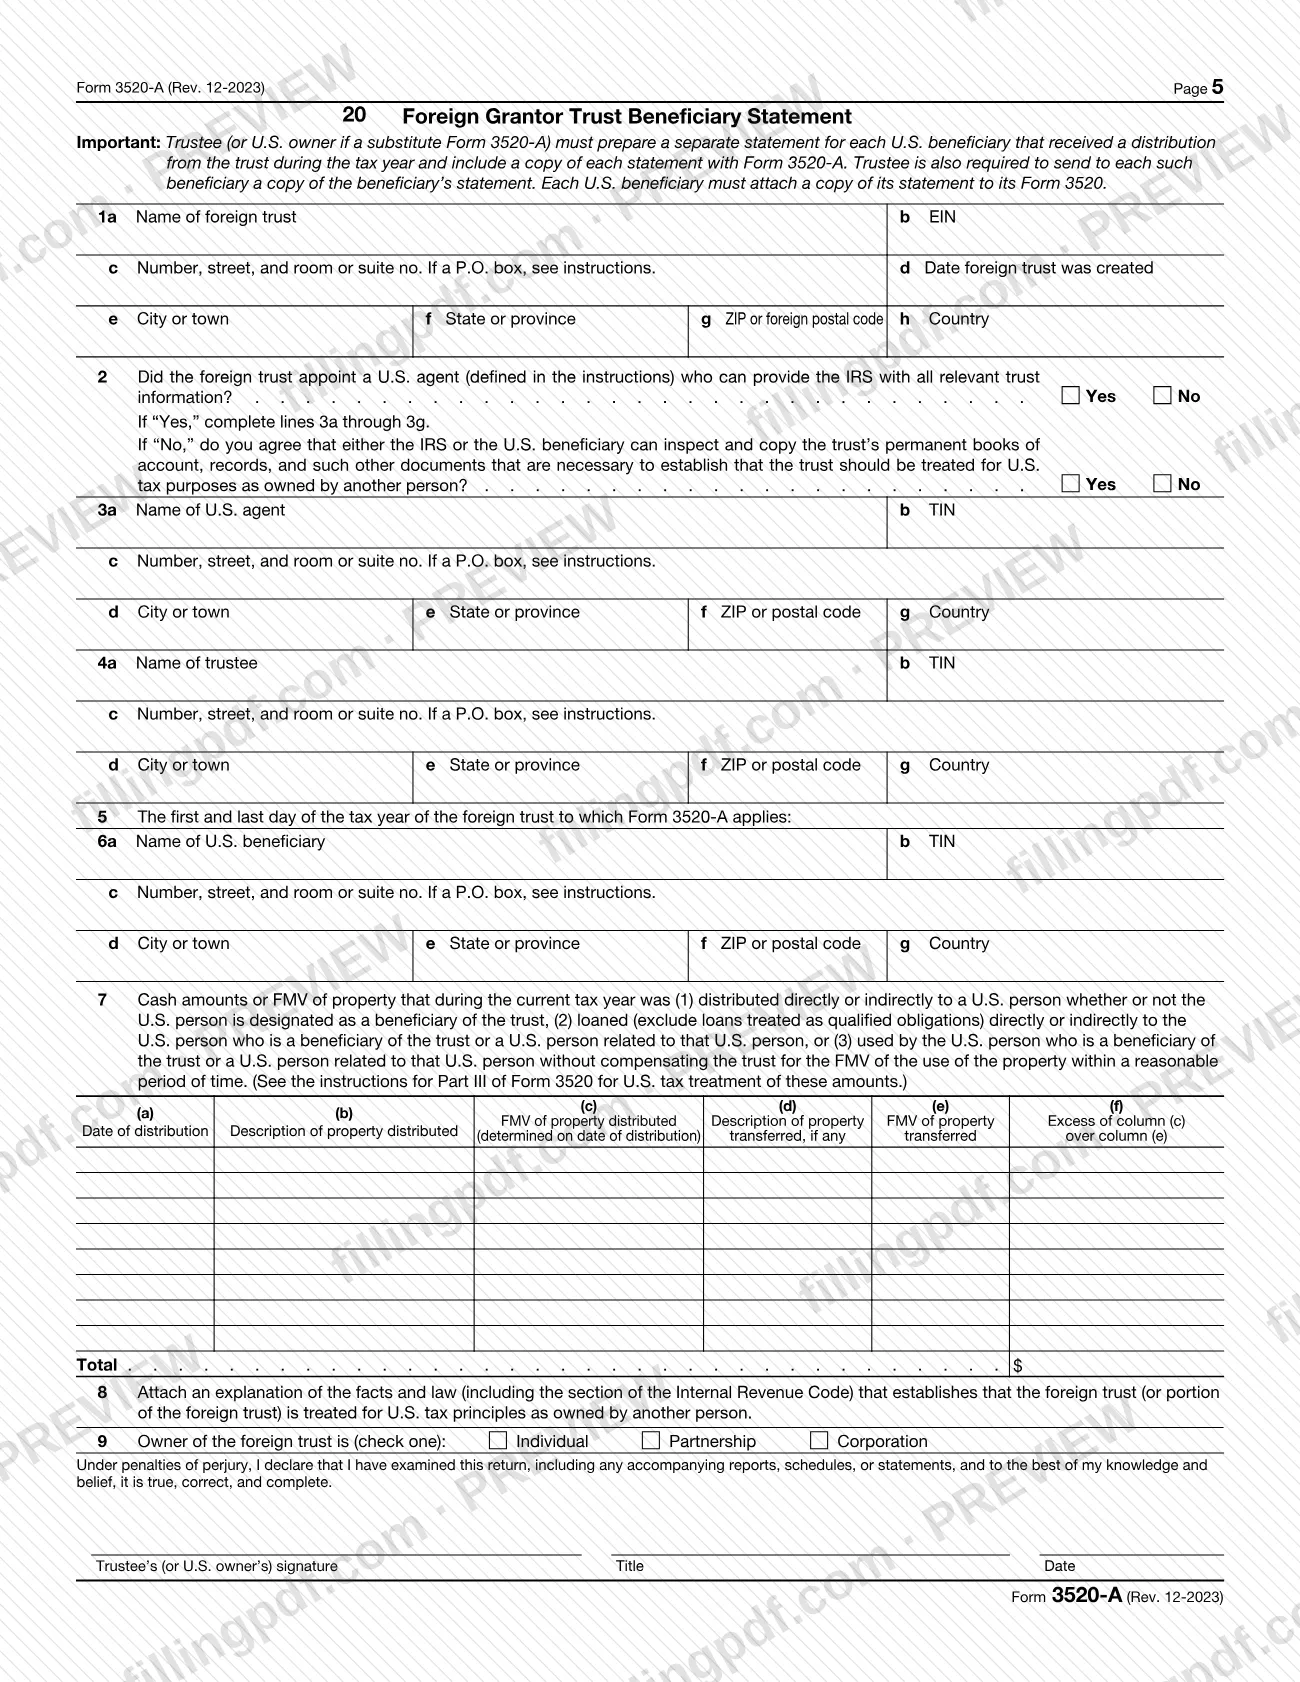
Form 3520-A is the Internal Revenue Service (IRS) annual information return that a foreign trust with at least one U.S. owner files under section 6048(b). It reports the trust's income and balance sheet and supplies statements for each U.S. owner and each U.S. beneficiary who received a distribution. On this page you can fill out Form 3520-A online on FillingPDF and download or print the completed PDF; the form and its instructions are published by the IRS at www.irs.gov/Form3520A.
Last updated
What is Form 3520-A?
Form 3520-A, Annual Information Return of Foreign Trust With a U.S. Owner, is the IRS form on which a foreign trust with at least one U.S. owner reports information about the trust, its U.S. beneficiaries and any U.S. person treated as owner of part of the trust under the grantor trust rules (sections 671 through 679).
A foreign trust with a U.S. owner files it so that the U.S. owner satisfies the annual information reporting requirement of section 6048(b). The IRS instructions treat each U.S. owner as responsible for making sure the trust files the form and furnishes the required statements.
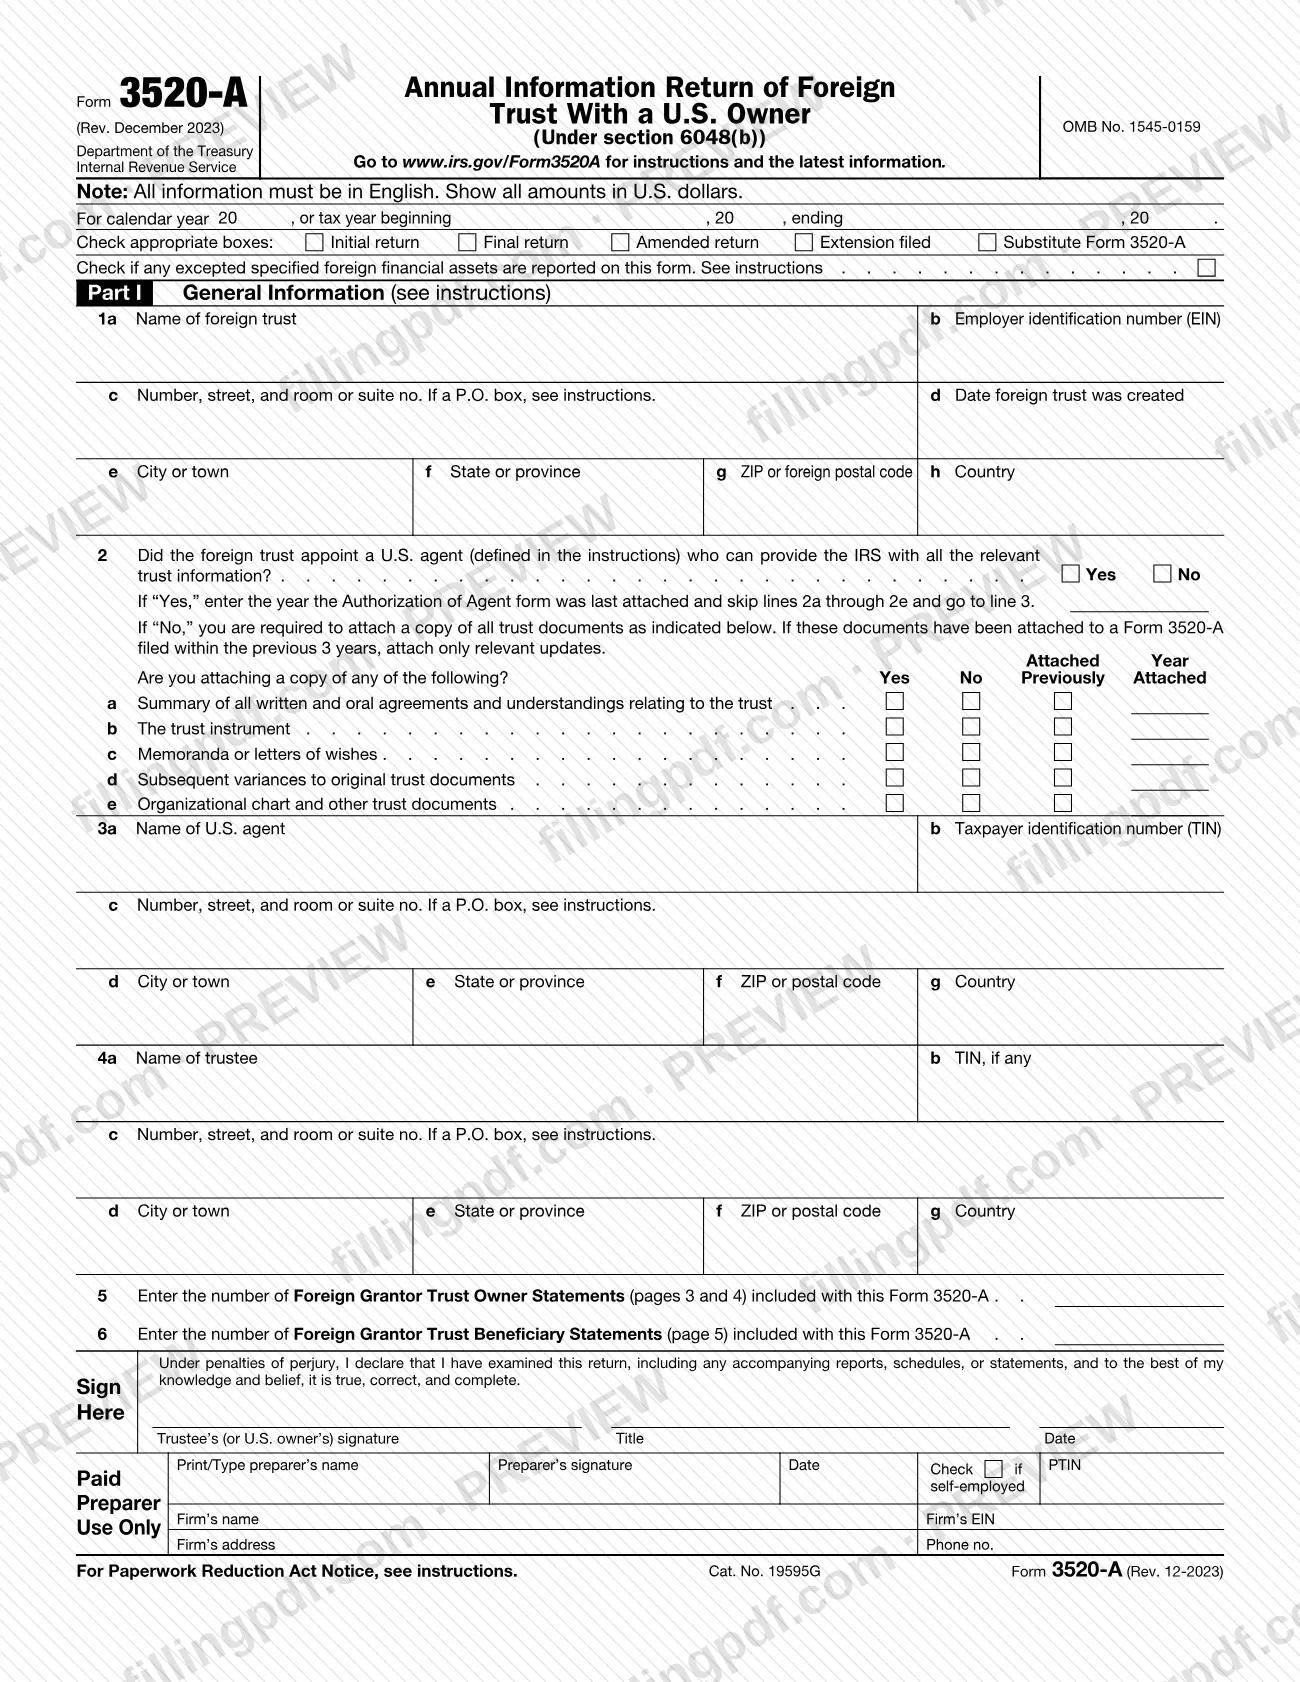
The return has five pages:
- Page 1: Part I, General Information (trust, U.S. agent, trustee), the counts of statements enclosed, and the signature block.
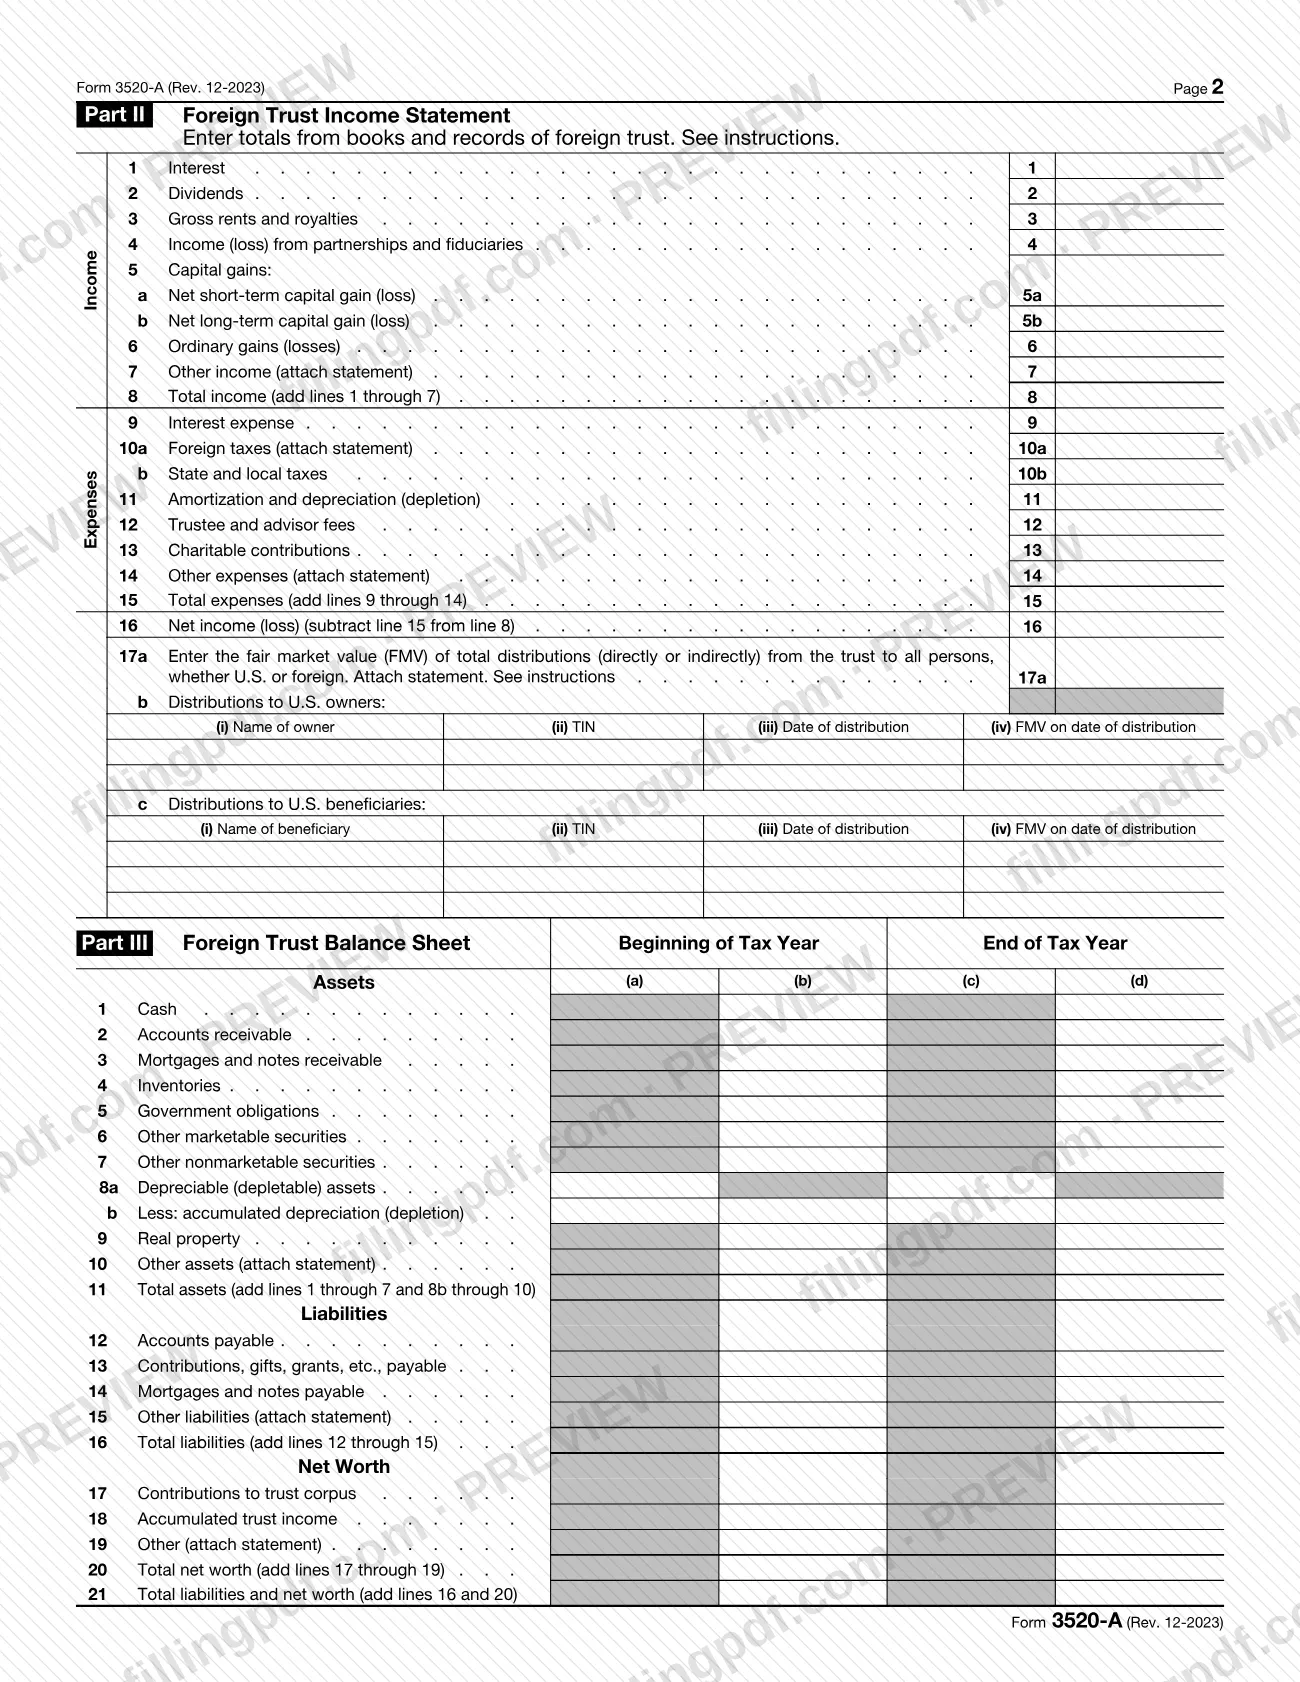
- Page 2: Part II, Foreign Trust Income Statement, and Part III, Foreign Trust Balance Sheet.
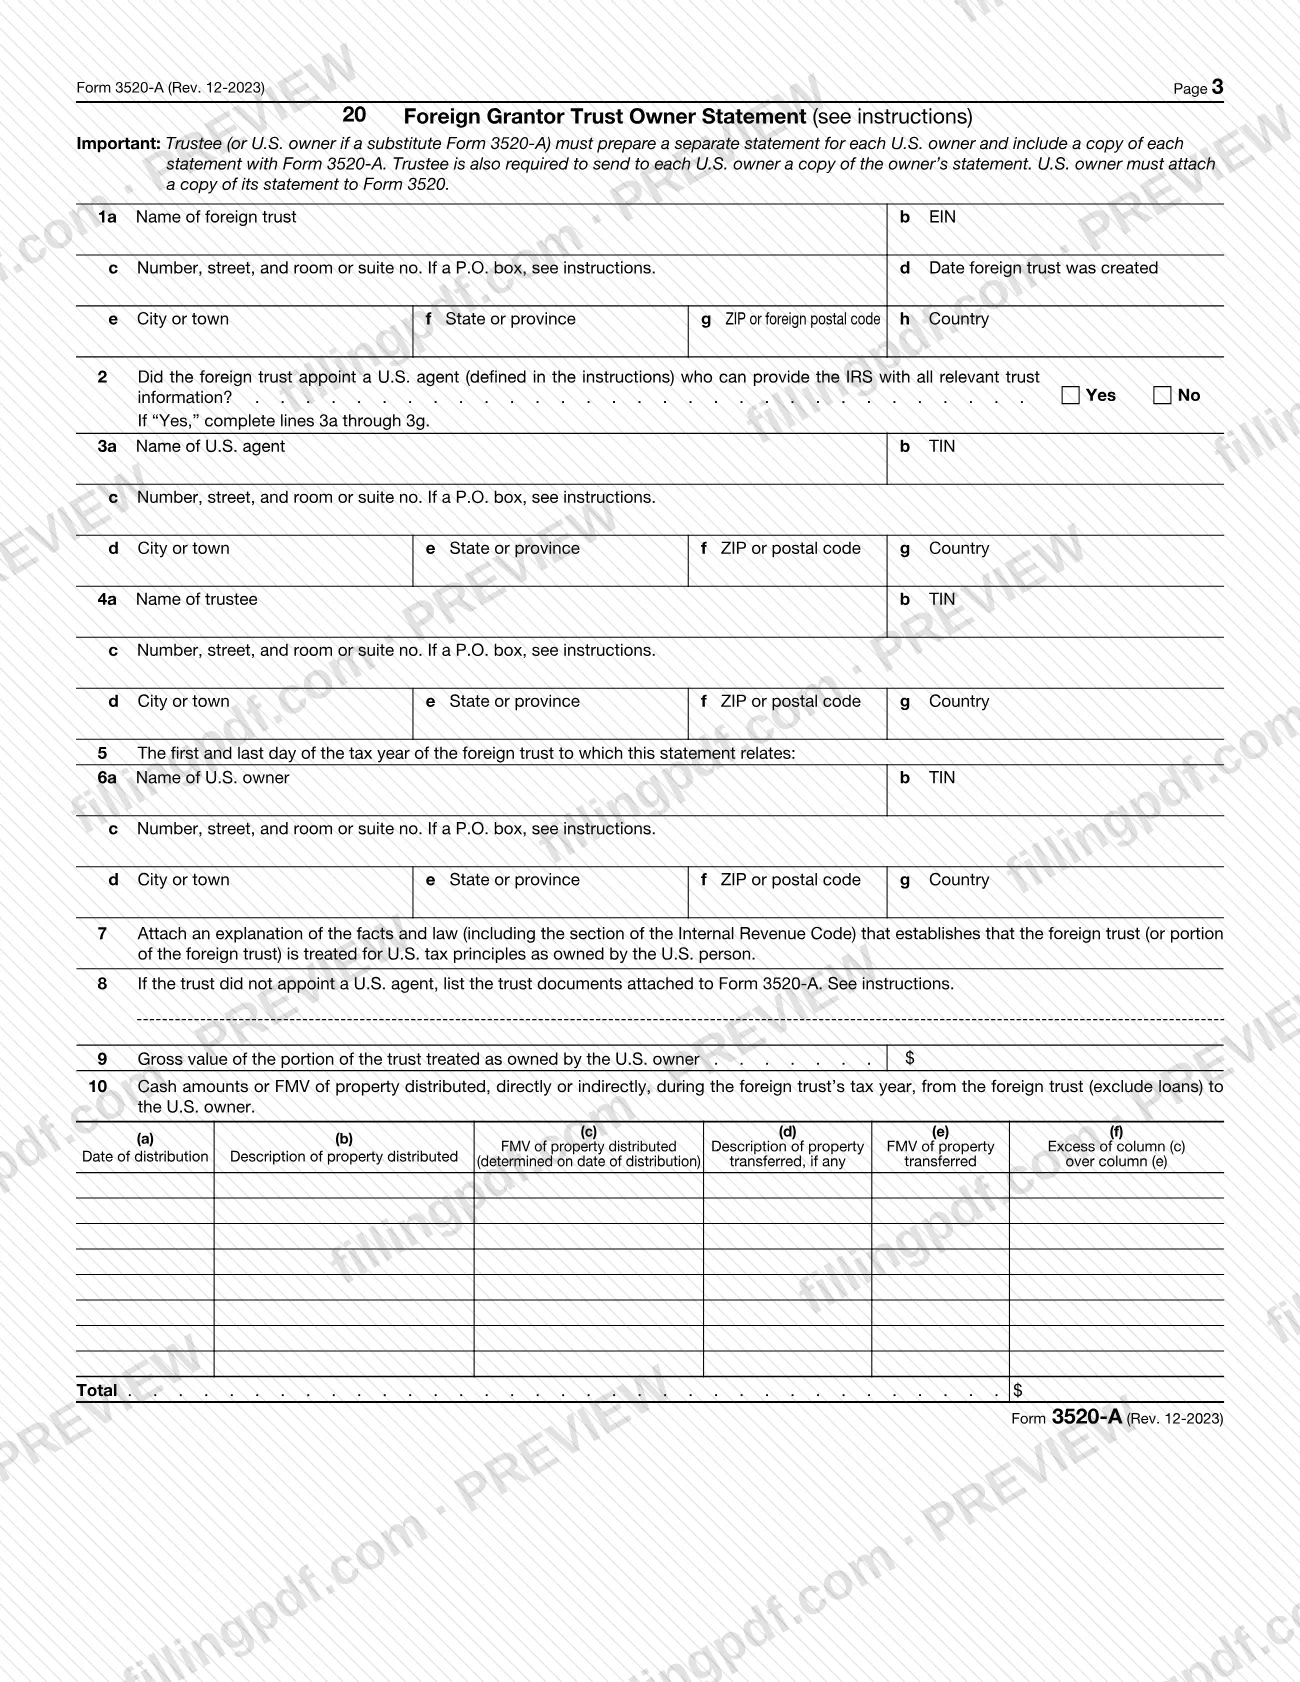
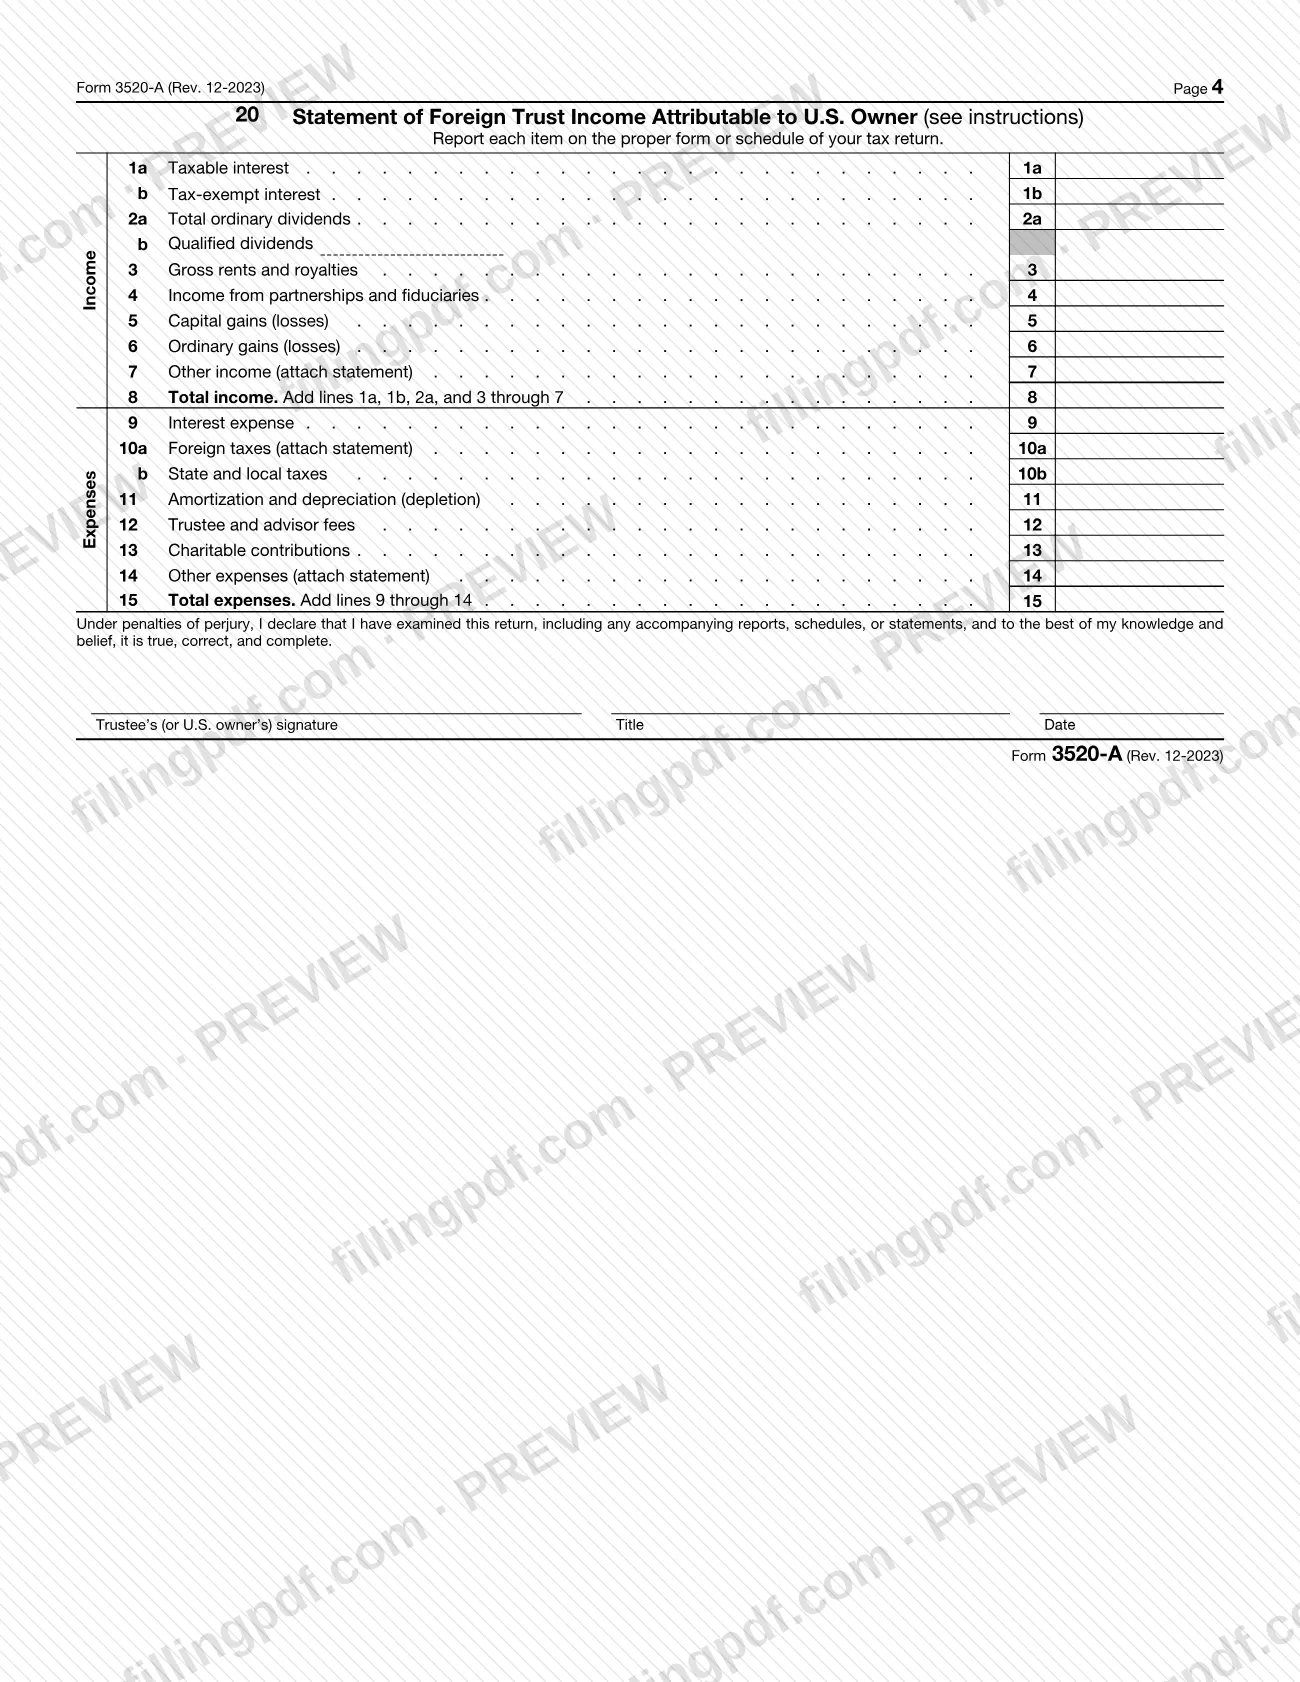
- Pages 3 and 4: the Foreign Grantor Trust Owner Statement and the Statement of Foreign Trust Income Attributable to U.S. Owner.
- Page 5: the Foreign Grantor Trust Beneficiary Statement.
If the foreign trust does not file, the U.S. owner completes a substitute Form 3520-A and attaches it to the owner's Form 3520, Annual Return To Report Transactions With Foreign Trusts and Receipt of Certain Foreign Gifts. Form 3520-A is therefore different from Form 3520: the first is the trust's own information return, the second is the U.S. person's return.
Who needs to file Form 3520-A?
A foreign trust with a U.S. owner must file Form 3520-A. A U.S. owner is any U.S. person treated as owner of any portion of a foreign trust under the grantor trust rules (sections 671 through 679).
- The foreign trust: files the form, signed by the trustee. If the trustee is a partnership, a partner or LLC member signs; if a corporation, an authorized corporate officer signs.
- A U.S. owner: is responsible for ensuring the trust files and furnishes the statements. If the trust fails to file, the U.S. owner completes and attaches a substitute Form 3520-A to Form 3520 and signs it, entering the owner's name and TIN on the Title line of the signature box.
- A paid preparer: completes the preparer section, including the PTIN, and signs when one is used.
Exceptions: Rev. Proc. 2014-55 exempts reporting for certain Canadian retirement plans, including RRSPs and RRIFs. Rev. Proc. 2020-17 and the proposed regulations under section 6048 exempt certain eligible individuals' dealings with certain tax-favored foreign trusts that provide pension, retirement, medical, disability or educational benefits. These exemptions do not affect reporting under section 6038D or the FBAR requirement. Check the IRS instructions before relying on one.
When to file Form 3520-A
Form 3520-A is due by the 15th day of the 3rd month after the end of the foreign trust's tax year, including the Foreign Grantor Trust Owner Statement (pages 3 and 4) and the Foreign Grantor Trust Beneficiary Statement (page 5). The trust must give copies of those statements to the U.S. owners and U.S. beneficiaries by the same date.
A substitute Form 3520-A attached to a U.S. owner's Form 3520 is due on the Form 3520 due date instead. Only a complete Form 3520-A, with all required attachments, is considered timely filed.
To extend the time, file Form 7004 using the foreign trust's EIN, by the 15th day of the 3rd month after the trust's tax year ends. An extension for an income tax return does not extend the time to file Form 3520-A. Check the Extension filed box if Form 7004 was timely filed.
Documents you need
- Foreign Grantor Trust Owner Statement (pages 3 and 4): a separate statement for each U.S. owner, included with Form 3520-A.
- Foreign Grantor Trust Beneficiary Statement (page 5): a separate statement for each U.S. beneficiary that received a distribution, included with Form 3520-A.
- Authorization of Agent form, when the trust appoints a U.S. agent; enter on line 2 the year it was last attached. The instructions say to attach it every 3 years unless there is a change.
- If no U.S. agent is appointed: a summary of the trust's terms and any oral agreements, all trust documents (trust instrument, memoranda or letters of wishes, variances), and an organizational chart. Within 3 years of a prior filing, attach only relevant updates.
- Statement for line 17a describing each transfer and its fair market value; attach more pages for line 17b and 17c if space is short.
- Statements for lines 7, 10a and 14 of Part II (and the matching lines of page 4) when other income, foreign taxes or other expenses are reported.
- Attached explanation of the facts and law (including the Code section) showing the trust is treated as owned by the U.S. person, on line 7 of the owner statement or line 8 of the beneficiary statement.
- Copy of the court order authorizing the signature, when a receiver or trustee in bankruptcy signs for a trustee that is a partnership or corporation.
- Form 3520, when a U.S. owner files a substitute Form 3520-A; the substitute is attached to it.
How to fill out Form 3520-A
Enter the period and check boxes
At the top, fill in the calendar year, or the tax year beginning and ending dates for a fiscal year. Check Initial return, Final return, Amended return, Extension filed or Substitute Form 3520-A as they apply, and the excepted-assets box only if the instructions' Form 8938 condition is met.
Identify the foreign trust
On lines 1a through 1h of Part I, enter the trust's name, EIN (never an SSN or ITIN), address, date created and country. Do not abbreviate the country.
Answer the U.S. agent question
On line 2, check Yes or No. If Yes, enter the year the Authorization of Agent form was last attached; if No, answer lines 2a through 2e on the trust documents you attach and the years previously attached.
Enter U.S. agent and trustee details
Complete lines 3a through 3g for the U.S. agent, if any, and lines 4a through 4g for the trustee, with names, TINs and addresses. A trust is not treated as having a U.S. agent unless these entries are made.
Count the enclosed statements
Line 5: the number of Foreign Grantor Trust Owner Statements (pages 3 and 4). Line 6: the number of Foreign Grantor Trust Beneficiary Statements (page 5).
Complete the income statement
In Part II, lines 1 through 8, enter income from books and records in U.S. dollars, then expenses on lines 9 through 15 and net income on line 16. Attach statements for lines 7, 10a and 14 when needed.
Report distributions
Line 17a: the fair market value of total distributions, with the required attached statement. Lines 17b and 17c: name, TIN, date and FMV for each U.S. owner and U.S. beneficiary who received a distribution.
Complete the balance sheet
In Part III, fill columns (a) through (d) for assets on lines 1 through 11, liabilities on lines 12 through 16 and net worth on lines 17 through 21, using FMV for the beginning and end of the tax year.
Prepare each Owner Statement
On page 3, fill in the tax year and lines 1 through 10 for each U.S. owner: trust, agent, trustee, tax year dates, owner details, the attached explanation on line 7, line 9 gross value and line 10 distributions.
Prepare the owner income statement
On page 4, report the income attributable to the U.S. owner on lines 1a through 8 and expenses on lines 9 through 15, and sign the statement.
Prepare each Beneficiary Statement
On page 5, complete lines 1 through 9 for each U.S. beneficiary who received a distribution: the agent answers, distributions on line 7, the attached explanation on line 8 and the owner type on line 9.
Sign, review and download the PDF
The trustee (or the U.S. owner for a substitute form) signs and dates; a paid preparer completes the preparer block. Check every line, then download or print the completed PDF from FillingPDF and assemble the attachments.
How to submit Form 3520-A
The IRS instructions give one filing address for Form 3520-A, which is a mail address. The form is not described as filed online.
- By mail (the foreign trust's return): File Form 3520-A, including the Foreign Grantor Trust Owner Statement (pages 3 and 4) and the Foreign Grantor Trust Beneficiary Statement (page 5), with the Internal Revenue Service Center, P.O. Box 409101, Ogden, UT 84409.
- Substitute Form 3520-A: Attach it to the U.S. owner's Form 3520 and send it where the Instructions for Form 3520 say to file that form.
- Extension: File Form 7004 with the foreign trust's EIN; it is a separate filing, not an attachment.
Send the owner and beneficiary statement copies to each U.S. owner and beneficiary by the due date. Attach the explanations and statements the lines call for, because a return missing required attachments is not complete. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Relying on an income tax return extension; it does not extend Form 3520-A, and Form 7004 must be filed with the foreign trust's EIN.
- Filing without all required attachments; the IRS considers only a complete Form 3520-A timely filed.
- Entering an SSN or ITIN on line 1b instead of the foreign trust's EIN, or an SSN in place of an EIN.
- Entering a PTIN anywhere other than the PTIN space at the bottom of page 1, or on the Authorization of Agent form.
- Abbreviating the country name on a foreign address.
- Leaving out the owner or beneficiary statement for a U.S. person, or not sending that person a copy by the due date.
- Completing a Beneficiary Statement for a U.S. person who is treated as owner of the trust portion; that person gets an Owner Statement instead.
- Signing the form without a trustee's signature, or a substitute form without the U.S. owner's signature, name and TIN on the Title line.
- Entering amounts in a foreign currency or filling the form in another language; all amounts must be in U.S. dollars and all information in English.
- Checking Yes on line 2 for a U.S. agent without entering the agent's name, address and TIN on lines 3a through 3g.
Frequently asked questions
What is Form 3520-A used for?
Form 3520-A is the annual information return of a foreign trust with at least one U.S. owner. It reports the trust's income and balance sheet and gives the IRS information about the trust, its U.S. beneficiaries and any U.S. person treated as an owner under the grantor trust rules.
Who has to file Form 3520-A?
The foreign trust files it, signed by its trustee, so that the U.S. owner meets the section 6048(b) reporting requirement. If the trust does not file, the U.S. owner must complete a substitute Form 3520-A and attach it to Form 3520.
When is Form 3520-A due?
By the 15th day of the 3rd month after the end of the foreign trust's tax year. A substitute Form 3520-A attached to a U.S. owner's Form 3520 is due the same day as Form 3520. Filing Form 7004 with the trust's EIN extends the time.
Where do I mail Form 3520-A?
Mail it to the Internal Revenue Service Center, P.O. Box 409101, Ogden, UT 84409, with the owner and beneficiary statements. A substitute Form 3520-A goes with the U.S. owner's Form 3520; see the Instructions for Form 3520 for that address.
What is the difference between Form 3520 and Form 3520-A?
Form 3520-A is the foreign trust's own annual information return. Form 3520 is the U.S. person's return reporting transactions with foreign trusts. A U.S. owner attaches a substitute Form 3520-A to Form 3520 when the trust has not filed its own.
What happens if Form 3520-A is late or incomplete?
The U.S. owner is subject to an initial penalty based on the gross value of the trust portion treated as owned by that person, with more penalties if noncompliance continues after an IRS notice. No penalty applies if reasonable cause is shown. See section 6677 and the IRS instructions.
Does an extension of my tax return extend Form 3520-A?
No. An extension to file an income tax return does not extend Form 3520-A. File Form 7004 using the foreign trust's EIN by the 15th day of the 3rd month after the trust's tax year ends, and check the Extension filed box.
Can I fill out Form 3520-A online?
Yes. You can fill out the fillable PDF on FillingPDF and download or print it. FillingPDF is an independent service and does not file the form with the IRS; you mail it through the IRS channel described in the instructions.
Ready to fill out Form 3520-A?
Fill out Form 3520-A now