
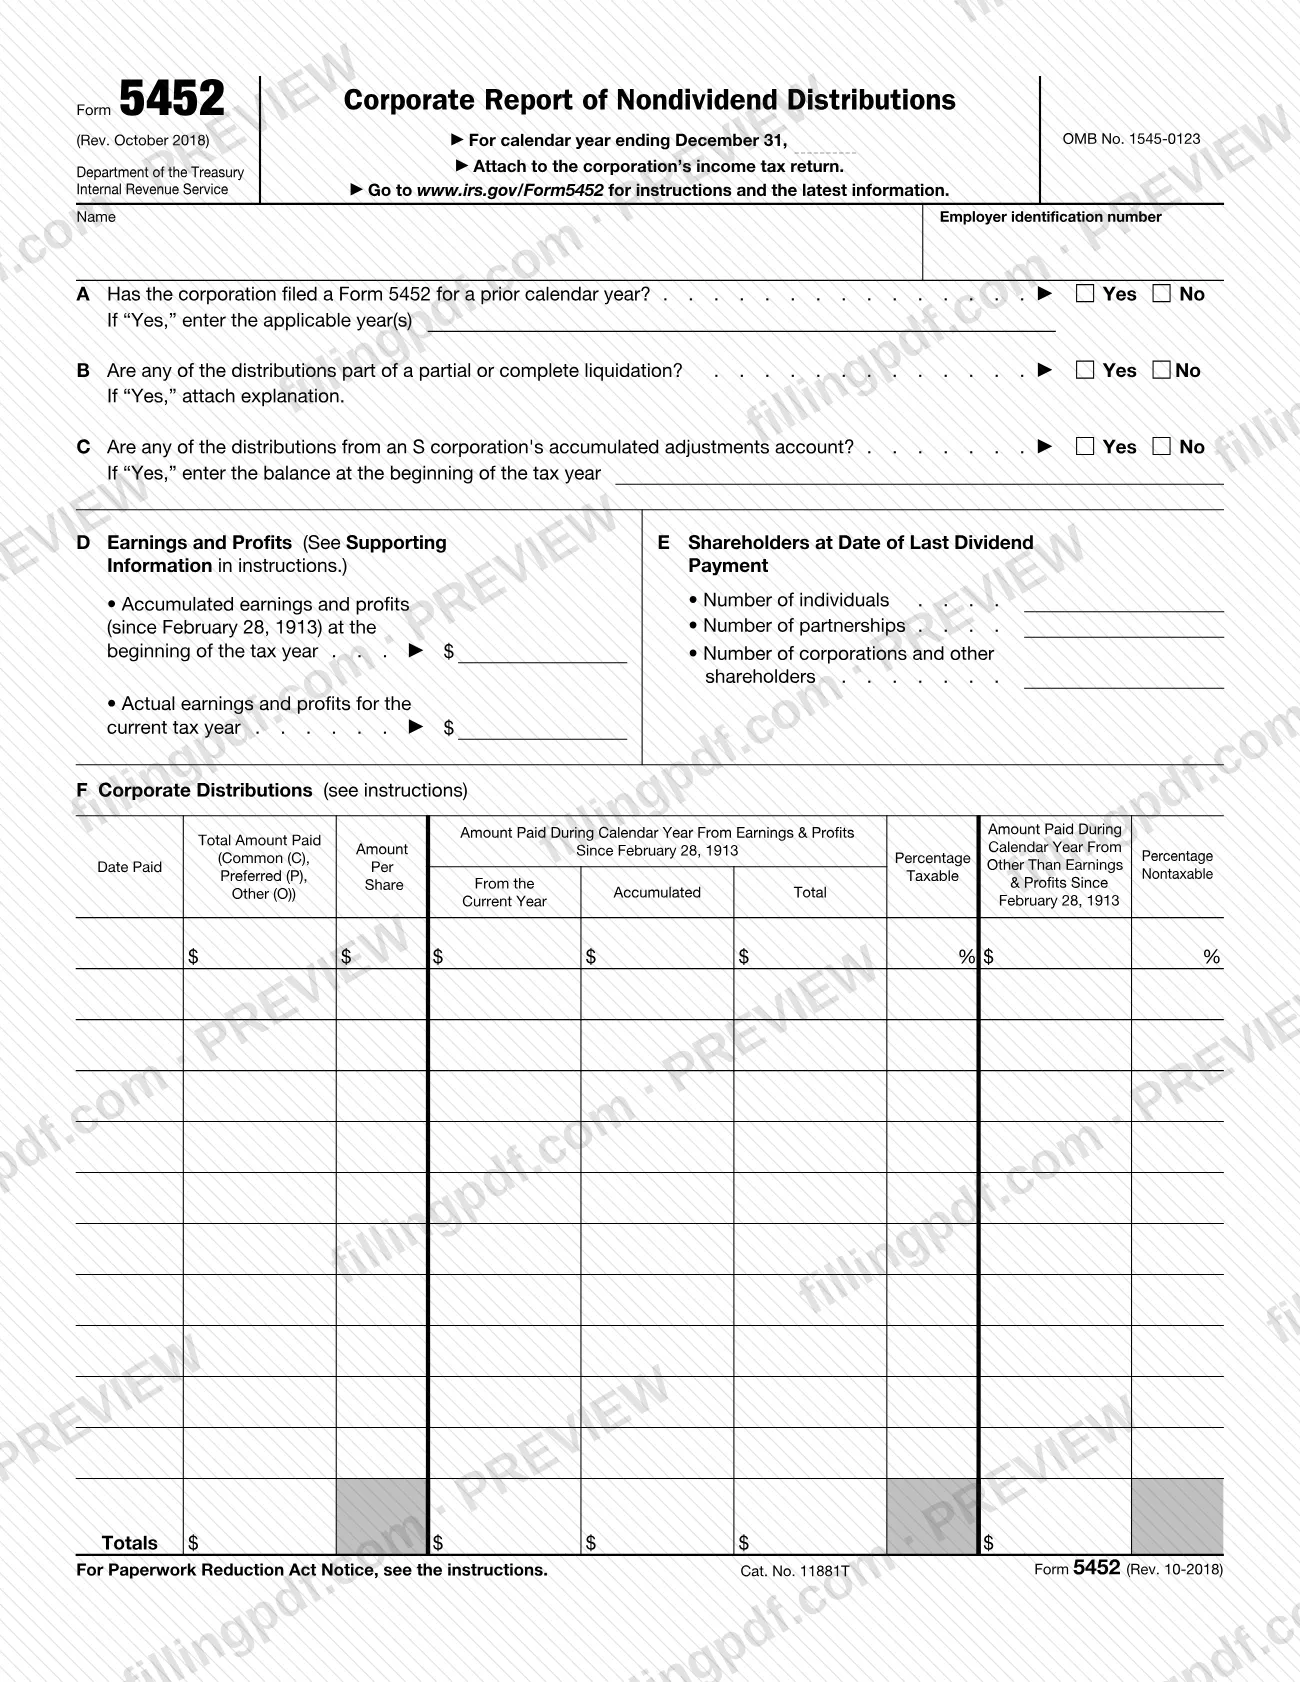
Form 5452, Corporate Report of Nondividend Distributions, is the Internal Revenue Service (IRS) form a corporation attaches to its income tax return when it has paid distributions to shareholders that are not dividends. It reports the corporation's earnings and profits, its shareholders at the last dividend payment, and the taxable and nontaxable share of each distribution. On this page you can fill out form 5452 online on FillingPDF and download or print the completed PDF; the IRS publishes the form and its instructions at www.irs.gov/Form5452.
Last updated
What is Form 5452?
Form 5452, Corporate Report of Nondividend Distributions, is the Internal Revenue Service (IRS) form a corporation completes when it has made nondividend distributions to shareholders under section 301, section 1368(c)(3), section 1371(e) or section 1371(f). It is attached to the corporation's income tax return.
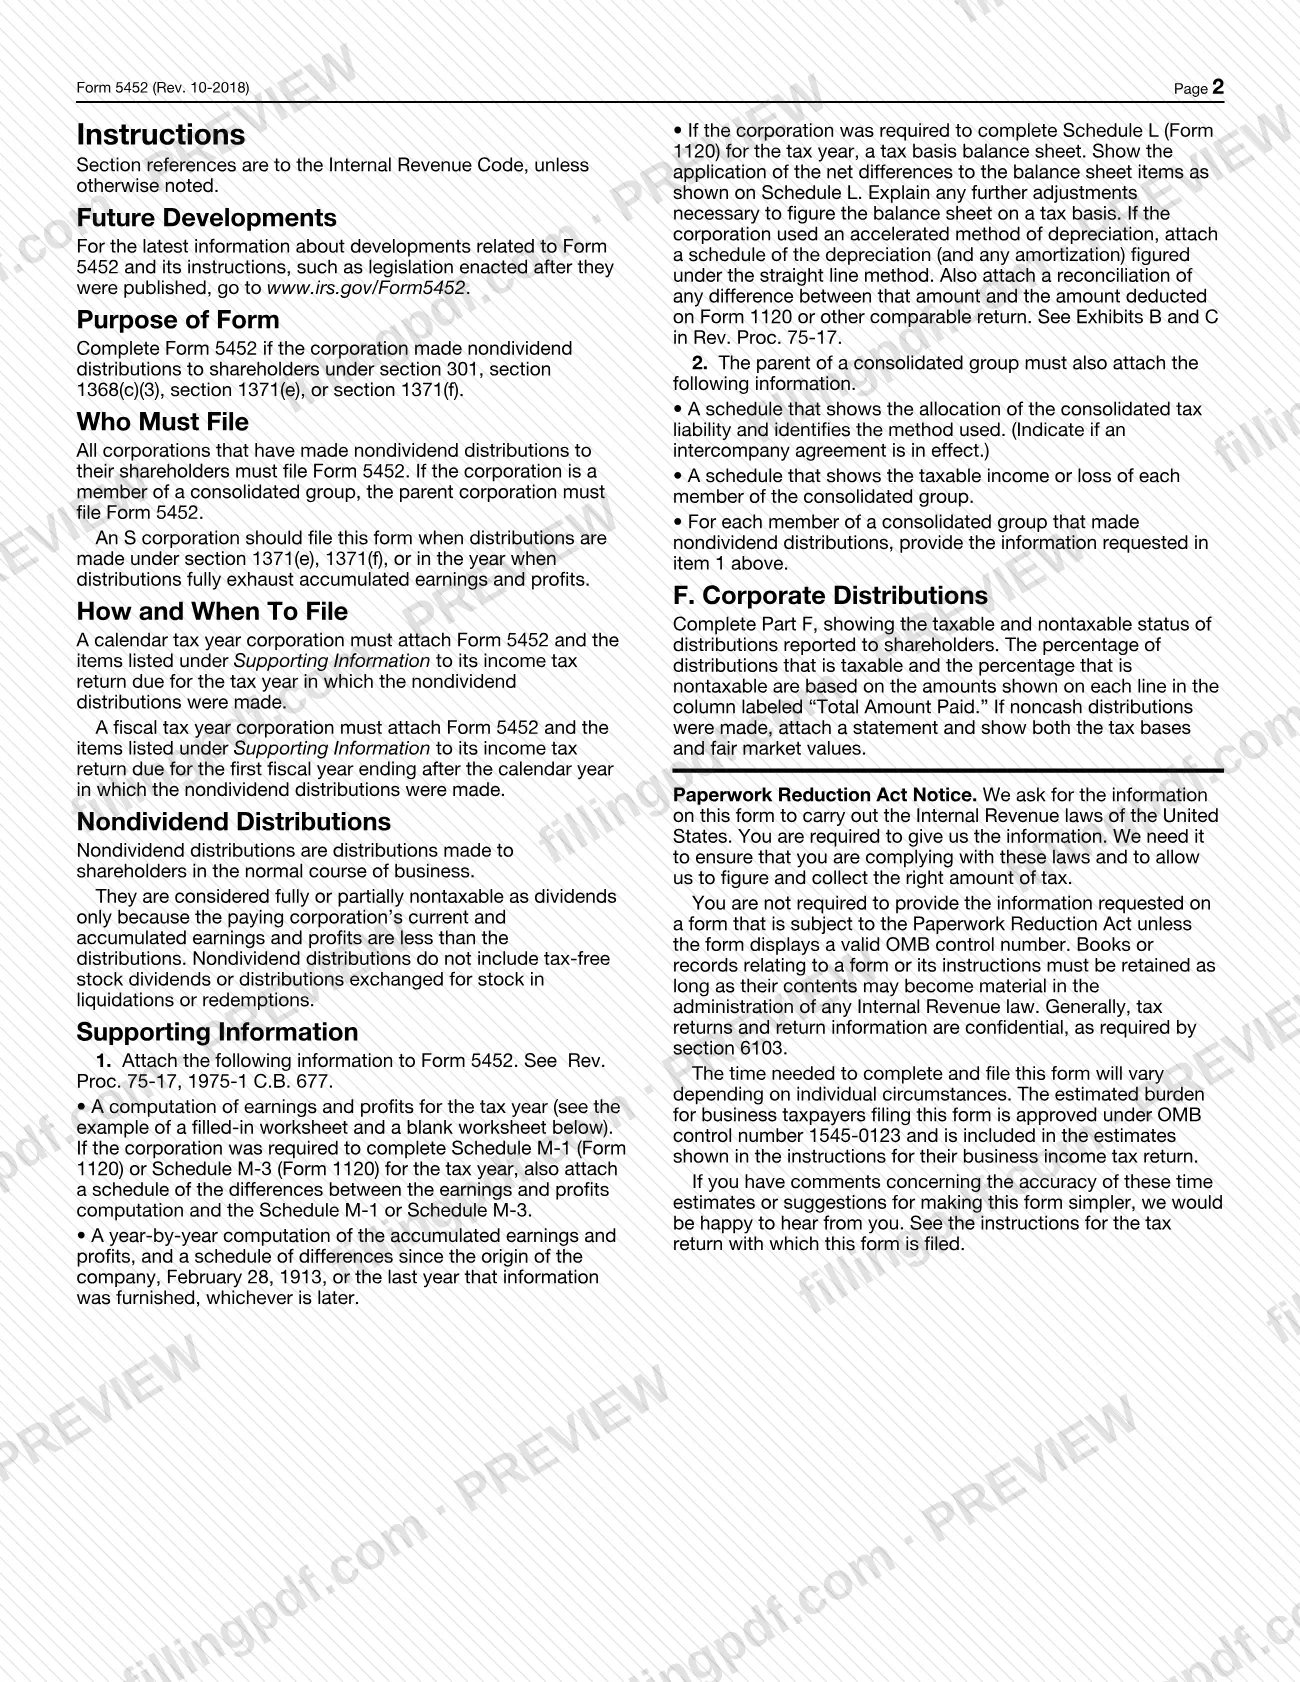
The IRS instructions define nondividend distributions as distributions made to shareholders in the normal course of business that are fully or partially nontaxable as dividends only because the paying corporation's current and accumulated earnings and profits are less than the distributions. They do not include tax-free stock dividends or distributions exchanged for stock in liquidations or redemptions.
The form is a single report with these parts:
- Questions A to C: prior Form 5452 filings, liquidations, and S corporation accumulated adjustments account distributions.
- Part D: accumulated earnings and profits (since February 28, 1913) at the start of the tax year, and actual earnings and profits for the current tax year.
- Part E: the number of individuals, partnerships, and corporations and other shareholders at the date of the last dividend payment.
- Part F: each distribution, with its taxable and nontaxable percentages.
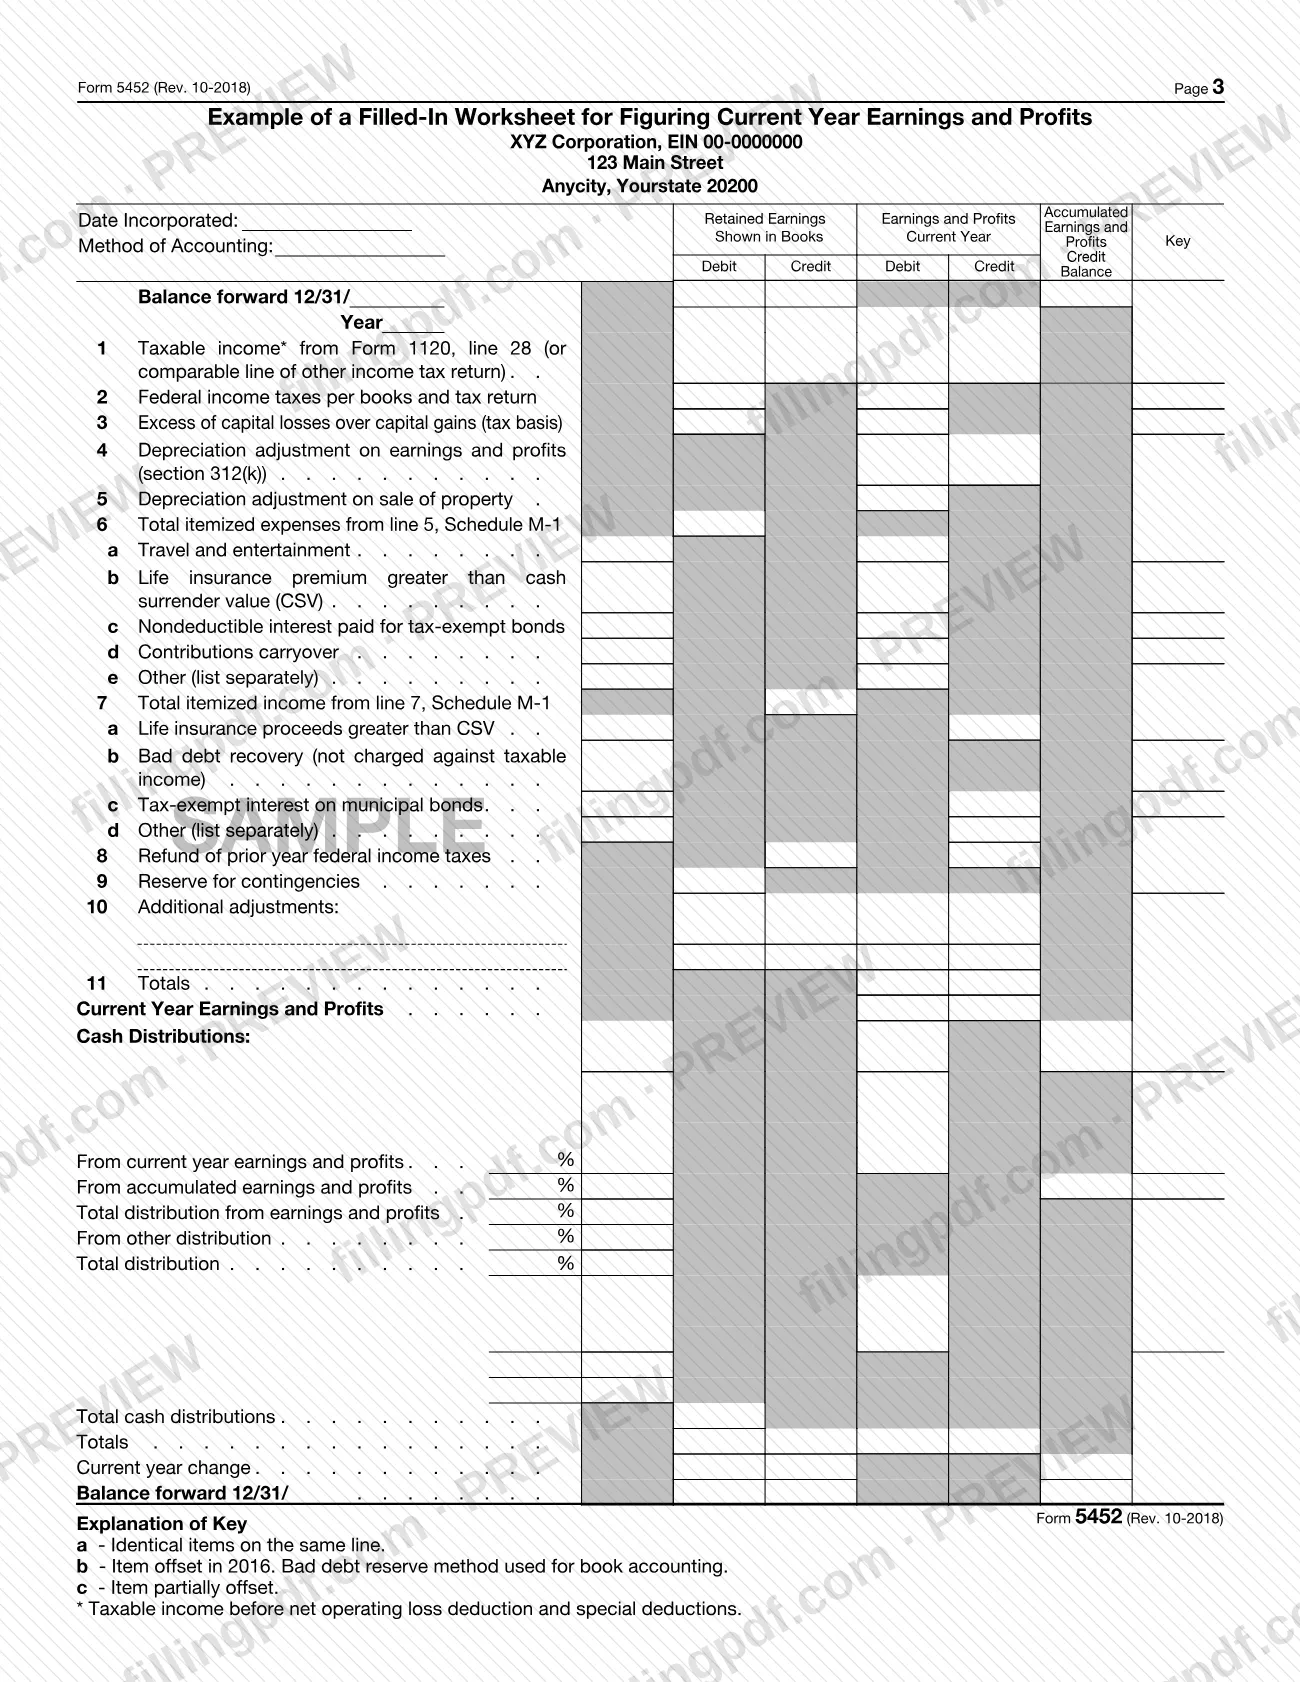
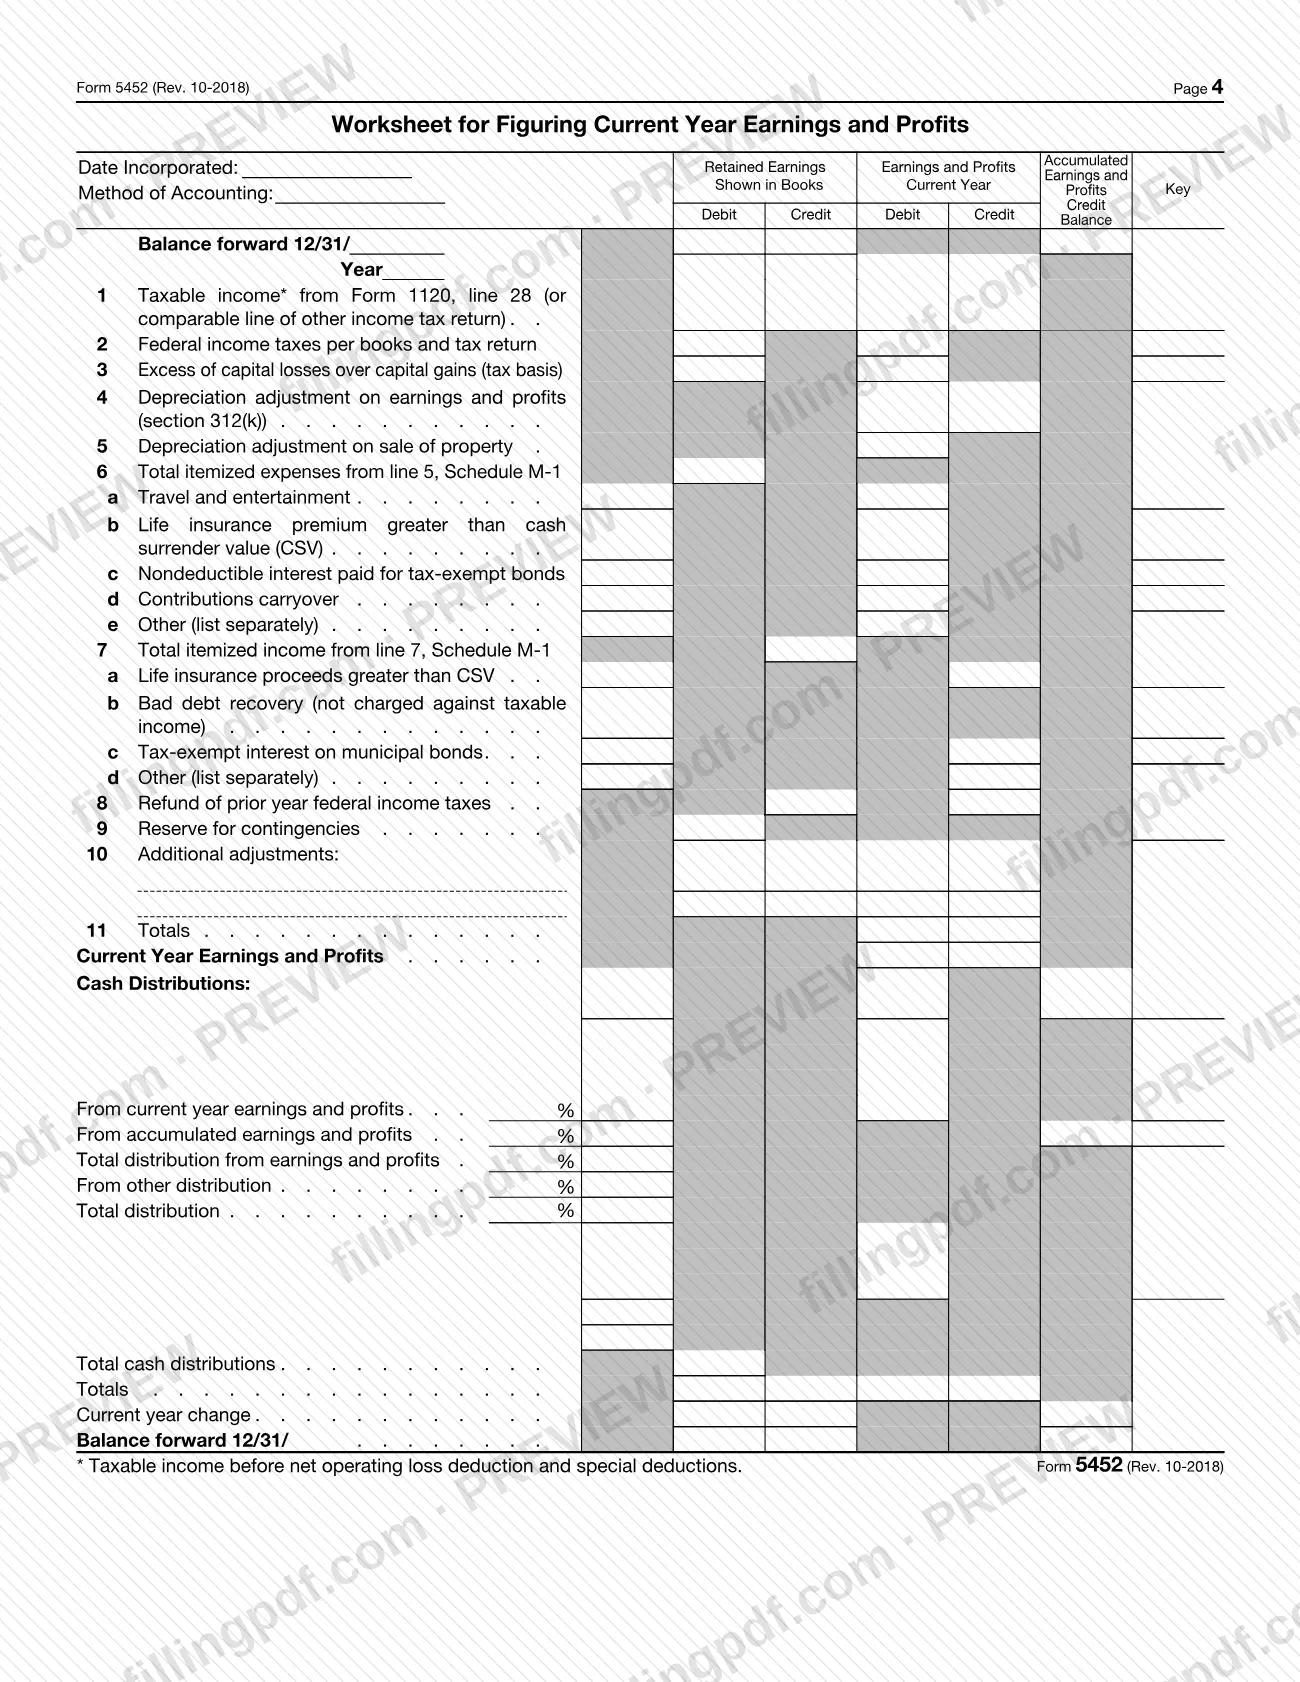
The form is identified as OMB No. 1545-0123, Rev. October 2018, for the calendar year ending December 31. The instructions on pages 2 to 4 include a filled-in sample and a blank worksheet for figuring current year earnings and profits. The IRS lists Form 1120, U.S. Corporation Income Tax Return, and Form 1120-S, U.S. Income Tax Return for an S Corporation, as related products.
Who needs to file Form 5452?
All corporations that have made nondividend distributions to their shareholders must file Form 5452. The IRS instructions say the form is completed when distributions are made under section 301, section 1368(c)(3), section 1371(e) or section 1371(f).
- Members of a consolidated group: the parent corporation must file Form 5452. The parent must also attach a schedule allocating the consolidated tax liability and naming the method used (indicating if an intercompany agreement is in effect), a schedule of the taxable income or loss of each member, and, for each member that made nondividend distributions, the supporting information described in item 1 of the instructions.
- S corporations: an S corporation should file the form when distributions are made under section 1371(e) or 1371(f), or in the year when distributions fully exhaust accumulated earnings and profits. Question C asks about distributions from an S corporation's accumulated adjustments account.
The form is a corporate filing. It is signed off by being attached to the corporation's own income tax return; it has no separate signature block, and the instructions do not describe any other person filing in the corporation's place.
When to file Form 5452
Form 5452 is due with the corporation's income tax return for the year in which the nondividend distributions were made; it has no separate due date.
- Calendar tax year corporation: attach Form 5452 and the items listed under Supporting Information to the income tax return due for the tax year in which the nondividend distributions were made.
- Fiscal tax year corporation: attach Form 5452 and the supporting items to the income tax return due for the first fiscal year ending after the calendar year in which the nondividend distributions were made.
The form is headed "For calendar year ending December 31," so the distributions it reports are those paid during the calendar year. For deadlines and extensions of the return itself, use the instructions for the tax return with which the form is filed.
Documents you need
- A computation of earnings and profits for the tax year; the instructions include a blank worksheet and a filled-in sample for figuring current year earnings and profits.
- A schedule of the differences between the earnings and profits computation and Schedule M-1 or Schedule M-3 (Form 120), only if the corporation was required to complete Schedule M-1 or Schedule M-3 for the tax year.
- A year-by-year computation of accumulated earnings and profits, and a schedule of differences since the origin of the company, February 28, 1913, or the last year that information was furnished, whichever is later.
- A tax basis balance sheet showing the net differences applied to the Schedule L items, with any further adjustments explained, only if the corporation was required to complete Schedule L (Form 1120).
- A schedule of depreciation (and any amortization) figured under the straight line method, plus a reconciliation of any difference from the amount deducted, only if the corporation used an accelerated method of depreciation.
- An explanation of the liquidation, only if you answer Yes to question B (distributions part of a partial or complete liquidation).
- A statement showing both tax bases and fair market values, only if noncash distributions were made.
- For the parent of a consolidated group: a schedule allocating the consolidated tax liability and the method used, and a schedule of the taxable income or loss of each member.
- For the parent of a consolidated group: for each member that made nondividend distributions, the same supporting information required of a single corporation.
How to fill out Form 5452
Enter the corporation's name and EIN
At the top, enter the corporation's name and its employer identification number, and the calendar year ending December 31 that the form covers.
Answer question A on prior filings
Check Yes or No for whether the corporation filed a Form 5452 for a prior calendar year. If Yes, enter the applicable year(s).
Answer question B on liquidations
Check Yes or No for whether any distributions are part of a partial or complete liquidation. If Yes, attach an explanation.
Answer question C for S corporations
Check Yes or No for whether any distributions came from an S corporation's accumulated adjustments account. If Yes, enter the balance at the beginning of the tax year.
Complete Part D, Earnings and Profits
Enter the accumulated earnings and profits (since February 28, 1913) at the beginning of the tax year, and the actual earnings and profits for the current tax year. Use the worksheet in the instructions to figure them.
Complete Part E, Shareholders
Enter, as of the date of the last dividend payment, the number of individuals, the number of partnerships, and the number of corporations and other shareholders.
List each distribution in Part F
For each distribution enter the date paid, the class of stock (Common (C), Preferred (P) or Other (O)), the amount per share and the total amount paid. Attach a statement with tax bases and fair market values for any noncash distribution.
Split each distribution by source
Enter the amount paid from earnings and profits (current year and accumulated) with its taxable percentage, and the amount paid from sources other than earnings and profits with its nontaxable percentage. Base the percentages on the "Total Amount Paid" column.
Total the columns
Enter the totals on the Totals line at the bottom of Part F.
Prepare the supporting information
Prepare the earnings and profits computation and the other items listed under Supporting Information in the instructions. A consolidated group parent adds the schedules the instructions require.
Review and download the completed PDF
Check each answer and total against the supporting schedules, then download or print the completed PDF from FillingPDF and attach it, with the supporting items, to the corporation's income tax return as described under How to submit.
How to submit Form 5452
Form 5452 is not filed on its own. The form says to attach it to the corporation's income tax return, and it goes to the IRS through whatever channel that return uses.
- Attach to the return: include the completed Form 5452 and the items listed under Supporting Information in the IRS instructions with the corporation's income tax return, such as Form 1120 or Form 1120-S. The form prints no mailing address, portal or appointment rule of its own.
- Follow the return's instructions: the form's Paperwork Reduction Act notice sends you to the instructions for the tax return with which it is filed. Use the filing method and address those instructions give.
- Find current information: the form and the IRS page about it point to www.irs.gov/Form5452 for instructions and the latest developments.
If the corporation made noncash distributions, include the statement showing tax bases and fair market values; if you answered Yes to question B, include the explanation. FillingPDF lets you fill out and download the PDF; submission follows the channels used for the corporation's income tax return.
Common mistakes to avoid
- Filing Form 5452 separately instead of attaching it to the corporation's income tax return.
- Leaving out the earnings and profits computation or the year-by-year accumulated earnings and profits schedule listed under Supporting Information.
- Answering Yes to question B (liquidation) without attaching an explanation.
- Reporting noncash distributions without a statement showing both tax bases and fair market values.
- Basing the taxable and nontaxable percentages in Part F on anything other than the amounts in the column labeled "Total Amount Paid" on each line.
- A subsidiary in a consolidated group filing instead of the parent, which must file Form 5452 for the group.
- Attaching the form to the wrong year's return; a fiscal year corporation attaches it to the return for the first fiscal year ending after the calendar year of the distributions.
- Omitting the straight line depreciation schedule and reconciliation when the corporation used an accelerated depreciation method.
Frequently asked questions
What is Form 5452 used for?
Form 5452 is the IRS Corporate Report of Nondividend Distributions. A corporation completes it when it made nondividend distributions to shareholders under section 301, 1368(c)(3), 1371(e) or 1371(f), and attaches it to its income tax return.
Who has to file Form 5452?
All corporations that made nondividend distributions to shareholders must file it. If the corporation belongs to a consolidated group, the parent corporation files. An S corporation files when distributions are made under section 1371(e) or 1371(f), or in the year distributions fully exhaust accumulated earnings and profits.
When is Form 5452 due?
It is due with the corporation's income tax return for the year of the distributions. A calendar year corporation attaches it to the return for the year the distributions were made; a fiscal year corporation uses the return for the first fiscal year ending after that calendar year.
Where do I send Form 5452?
You do not send it separately. Attach it, with the supporting information, to the corporation's income tax return and file that return as its instructions direct. The form itself prints no address or portal of its own.
What do I have to attach to Form 5452?
Attach an earnings and profits computation and a year-by-year accumulated earnings and profits computation, plus the schedules the instructions require in your situation, such as a tax basis balance sheet or a straight line depreciation schedule. A consolidated parent adds more schedules.
Do I need a statement for noncash distributions?
Yes, if noncash distributions were made. The instructions say to attach a statement showing both the tax bases and the fair market values of the property distributed.
Can I fill out Form 5452 online?
You can fill out the PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the form with the IRS; you attach it to the corporation's income tax return.
Where can I find the 5452 instructions?
The instructions are printed on pages 2 to 4 of the form itself, including a filled-in sample worksheet and a blank worksheet for current year earnings and profits. The IRS also publishes the form and latest information at www.irs.gov/Form5452.
Ready to fill out Form 5452?
Fill out Form 5452 now