
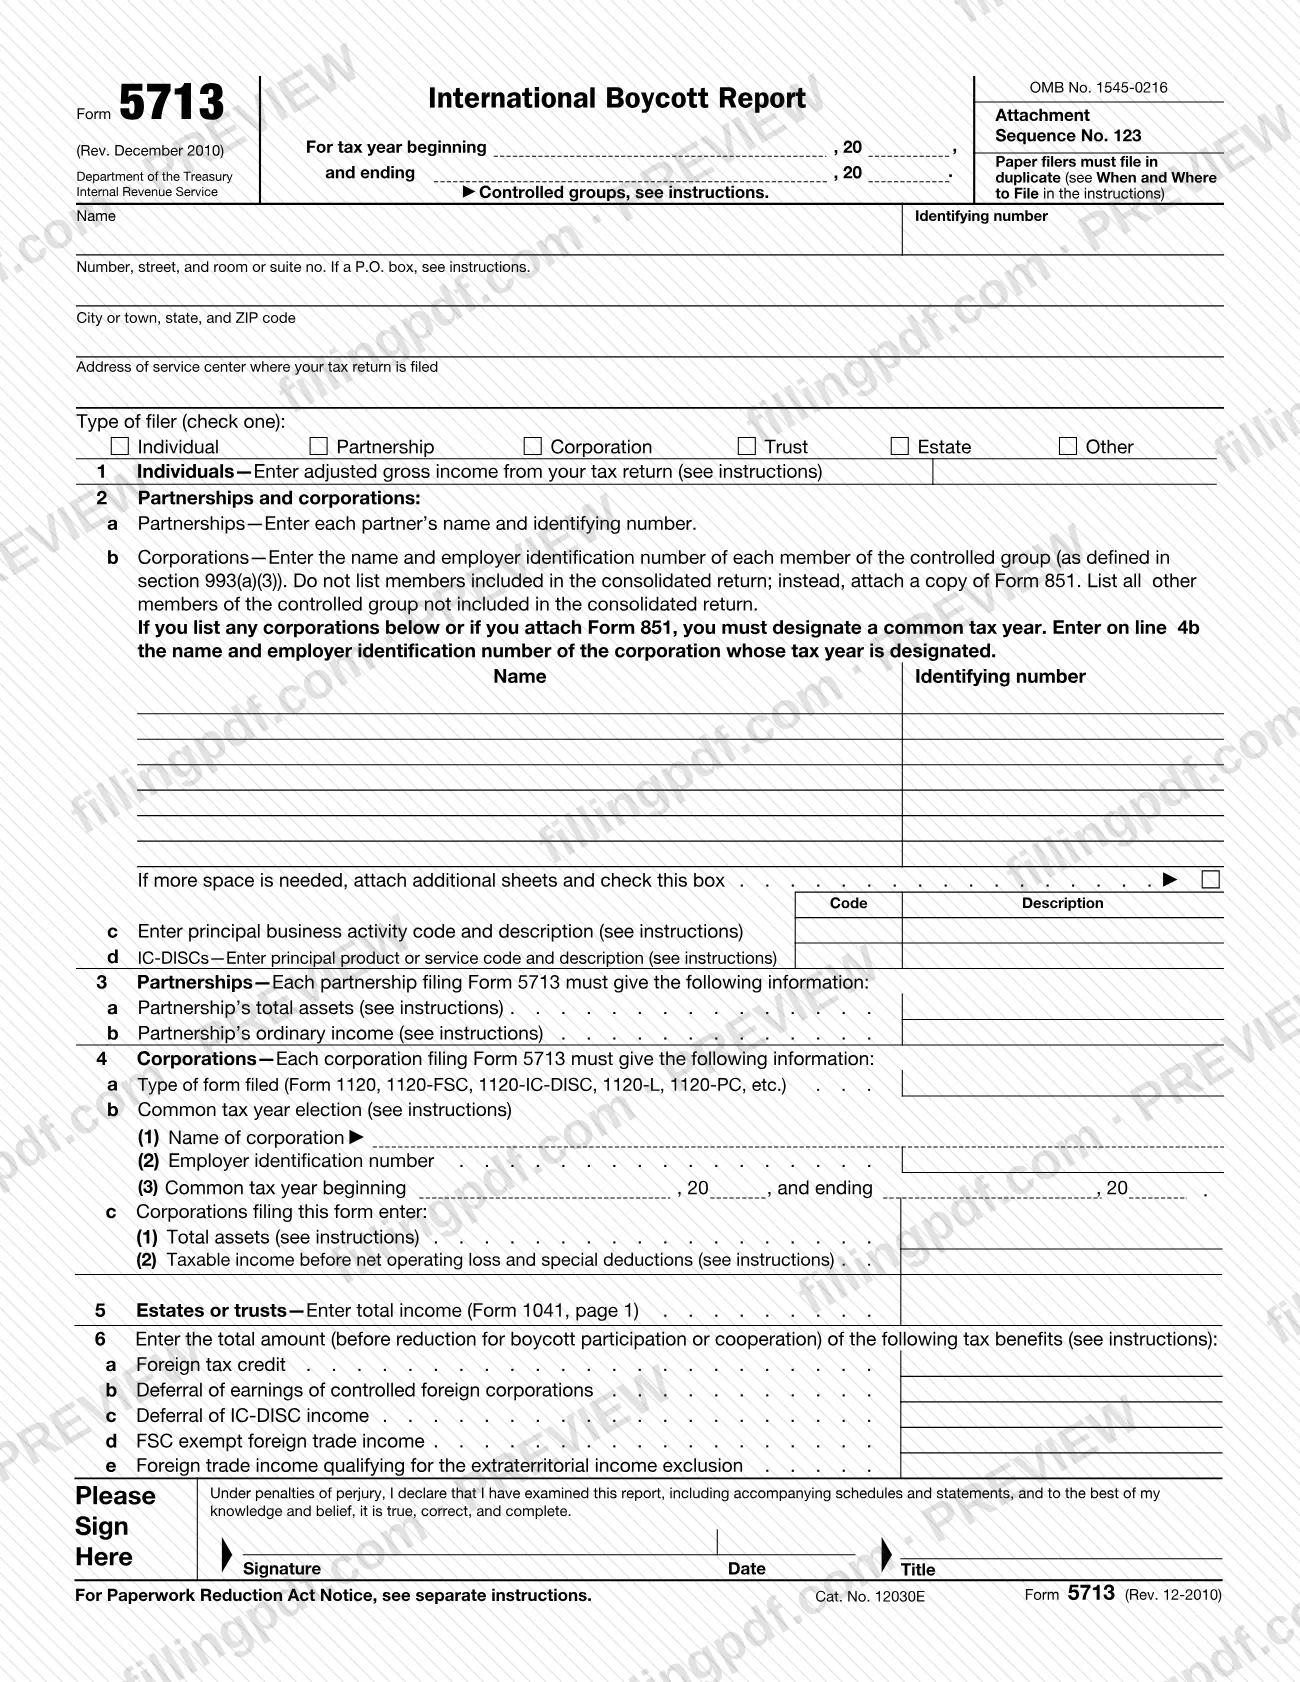
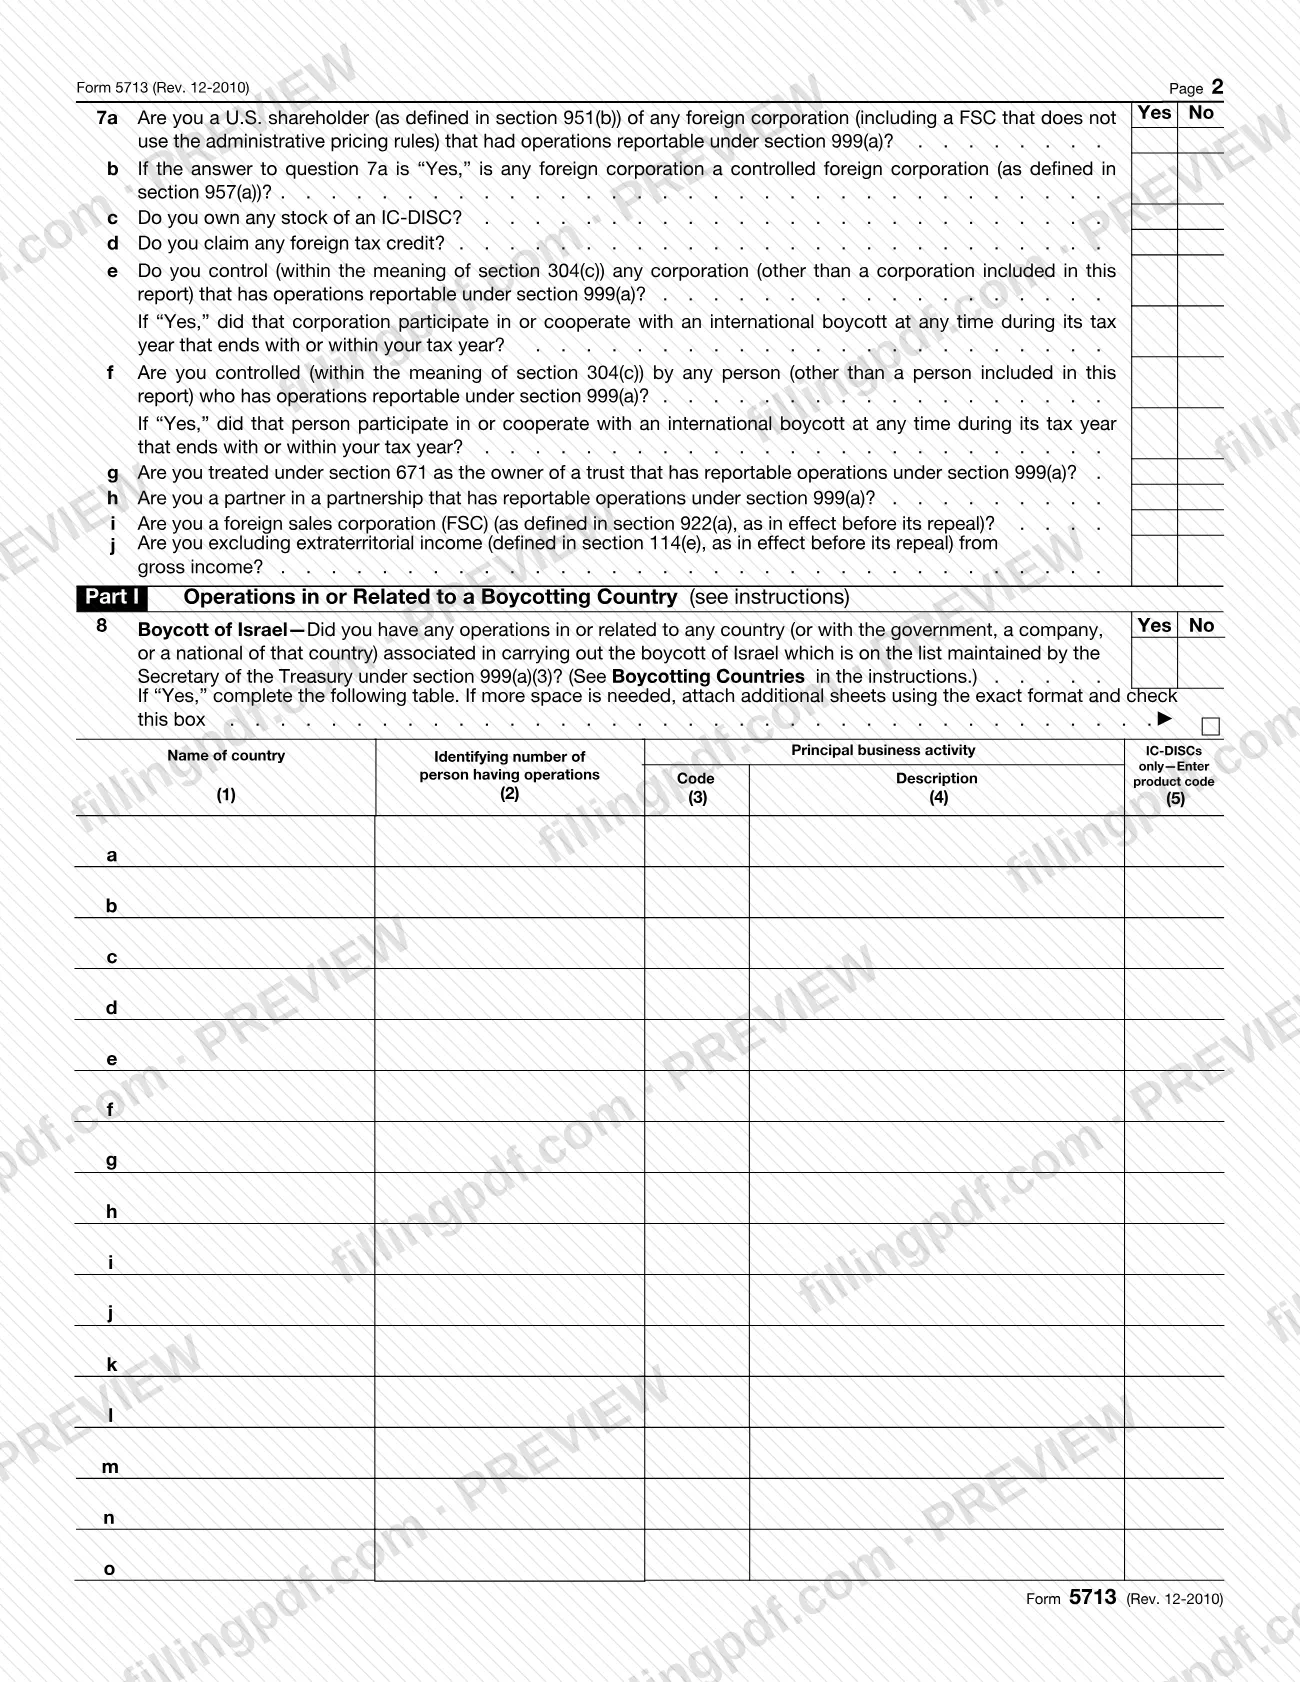
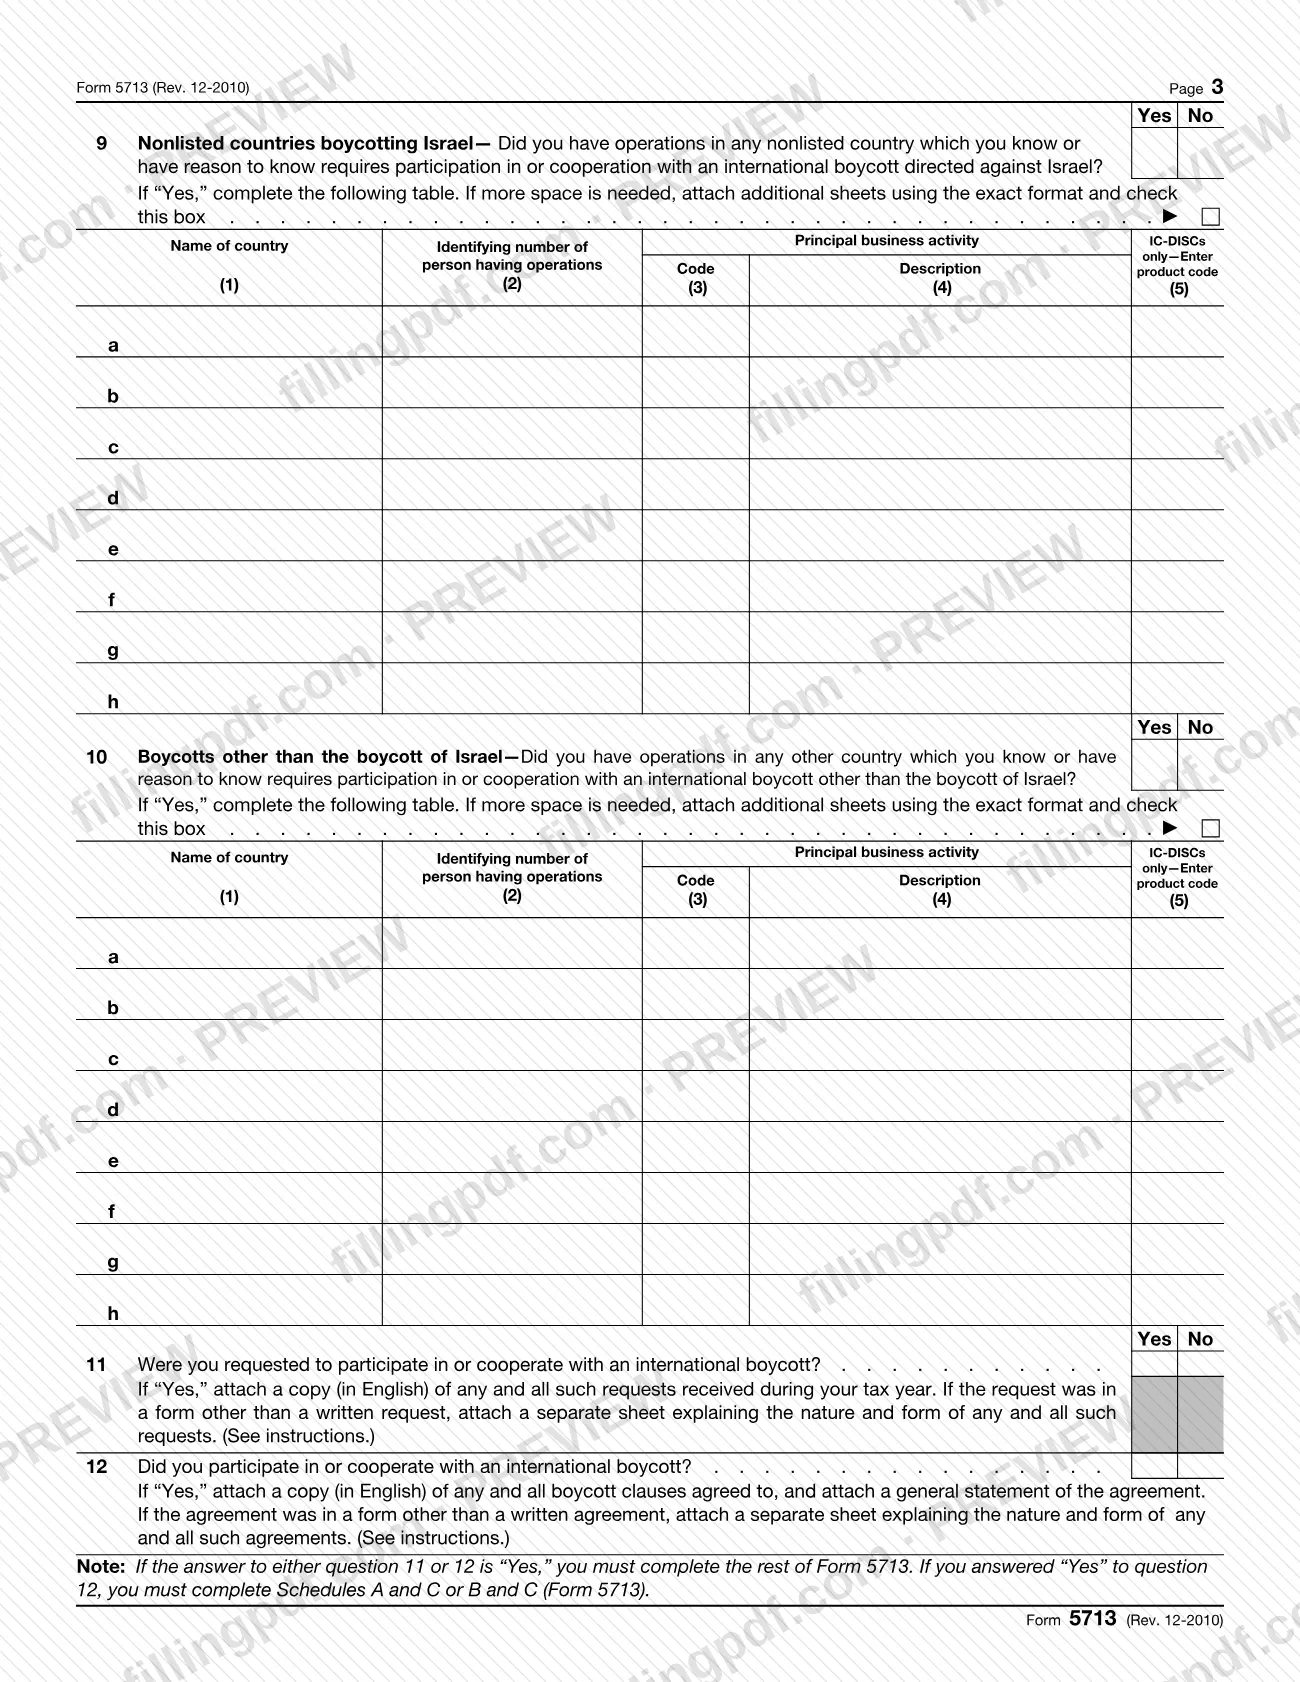
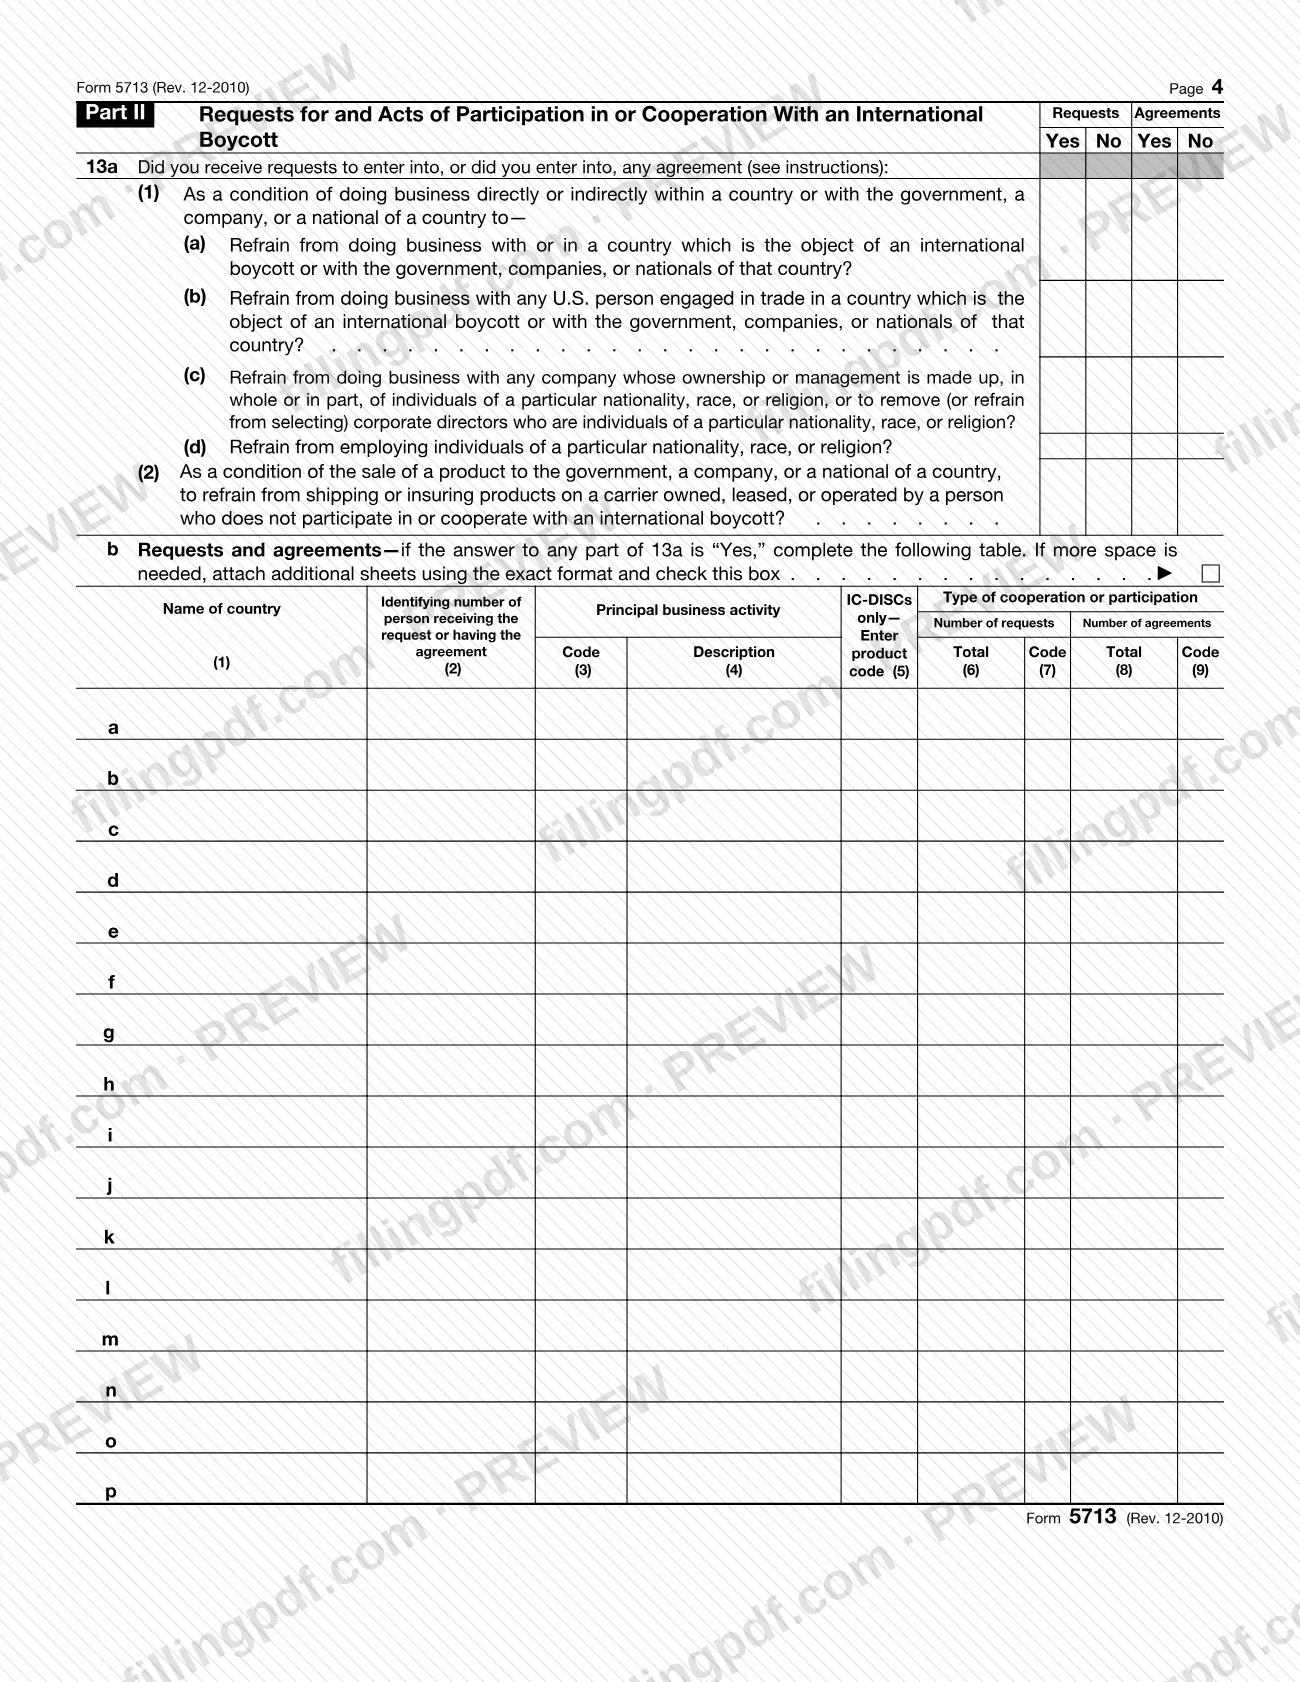
Form 5713, International Boycott Report, is the Internal Revenue Service (IRS) form on which a U.S. person reports operations in or related to boycotting countries and any boycott requests received or boycott agreements made. It is attached to the filer's income tax return, and it feeds Schedules A, B and C (Form 5713), which figure any loss of tax benefits. On this page you can fill out the form online on FillingPDF and download or print the completed PDF; the IRS publishes the original form and its instructions at irs.gov.
Last updated
What is 5713?
Form 5713, International Boycott Report, is the IRS form a U.S. person uses to report operations in or related to boycotting countries and the receipt of boycott requests and boycott agreements made. It accompanies the filer's income tax return.
The form has two parts. Part I (lines 8 through 10) asks about operations in or related to countries on the list the Secretary of the Treasury maintains under section 999(a)(3), nonlisted countries that boycott Israel, and boycotts other than the boycott of Israel. Part II (line 13) records the requests received and the agreements entered into, with a code for the type of participation or cooperation. Lines 11 and 12 ask whether you were requested to participate or did participate, and a "Yes" on either means you must complete the rest of the form.
The form also gathers identifying information: type of filer, controlled group members, total assets or income, and the tax benefits that could be reduced (foreign tax credit, deferral of CFC earnings, deferral of IC-DISC income, FSC exempt foreign trade income and extraterritorial income exclusion).
Form 5713 only reports the facts. The loss of tax benefits is figured on separate schedules: Schedule A (international boycott factor), Schedule B (taxes and income specifically attributable to boycott operations) and Schedule C, which computes the loss. The IRS says you complete Schedules A and C, or B and C, if you answered "Yes" to line 12.
Who needs to file 5713?
You must file Form 5713 if you are a U.S. person (as defined in section 7701(a)(30)) with operations in or related to a boycotting country, or with the government, a company or a national of one. The IRS instructions also name these U.S. persons:
- a member of a controlled group (section 993(a)(3)) that has operations;
- a U.S. shareholder (section 951(b)) of a foreign corporation with operations, but only if you own its stock within the meaning of section 958(a);
- a partner in a partnership that has operations;
- a person treated under section 671 as the owner of a trust that has operations;
- a foreign corporation engaged in a U.S. trade or business through a U.S. branch, which generally reports the boycott activities of its controlled group, including the branch.
Exceptions in the instructions:
- A foreign person need not file unless it claims the foreign tax credit, owns IC-DISC stock, is an FSC with exempt foreign trade income, or excludes extraterritorial income from gross income.
- A controlled group member need not file if all members joined in a consolidated return and the common parent files for the group, or if it meets the listed no-operations conditions and attaches the required certificate.
- A partner need not file if it has no independent boycott operations and the partnership files Form 5713 with Form 1065 and did not cooperate with or participate in a boycott.
- If you receive an unsolicited invitation to bid containing a boycott request, you file only if you accept it.
- Do not report U.S. approved boycotts.
When to file 5713
Form 5713 is due when your income tax return is due, including extensions. It is not filed on its own schedule: you attach it to the return it supports.
The form is tied to a tax year, shown at the top as "For tax year beginning ... and ending ...". Lines 8 through 13 reflect your boycott information for your tax year, and members of a controlled group report on the basis of the group's common tax year, as the instructions explain with an example. An agreement to participate in or cooperate with a boycott continues for the entire period it is in effect and must be reported each year it is in effect.
Willful failure to file Form 5713 can lead to a fine, imprisonment of no more than 1 year, or both.
Documents you need
- A copy of Form 851 for corporations included in a consolidated return, attached in place of listing those members on line 2b.
- A copy (in English) of any and all boycott requests received during your tax year, if you answered "Yes" to line 11.
- A separate sheet explaining the nature and form of each request, if a request was in a form other than a written request.
- A copy (in English) of any and all boycott clauses agreed to, plus a general statement of the agreement, if you answered "Yes" to line 12.
- A separate sheet explaining the nature and form of each agreement, if an agreement was in a form other than a written agreement.
- Additional sheets in the exact format of the table, with the "more space" box checked, if the line 2 list or the tables on lines 8, 9, 10 or 13b need more room.
- Schedules A and C, or Schedules B and C (Form 5713), if you answered "Yes" to line 12.
- A copy of each member's written consent to the common tax year election, attached to the Form 5713 each member files for the first tax year the election applies.
- A certificate stating that Form 5713 was filed on the member's behalf, for a controlled group member relying on the exception for members with no boycott operations.
How to fill out 5713
Enter the tax year
At the top, enter the tax year beginning and ending dates. Controlled groups also read the instructions on the common tax year before answering.
Enter name, address and service center
Enter your name, identifying number and address, adding the suite or room number. In the service center line, give the address of the center where your return was filed, or "e-file" if it was e-filed.
Check the type of filer
Check one box: Individual, Partnership, Corporation, Trust, Estate or Other.
Complete the line 1 and 2 entries
Line 1 (individuals): enter your adjusted gross income from Form 1040. Line 2: partnerships list each partner on 2a; corporations list controlled group members on 2b; then enter the principal business activity code and description on 2c and, for IC-DISCs, the product code on 2d.
Complete lines 3 to 5
Partnerships enter total assets (3a) and ordinary income (3b). Corporations enter the type of form filed (4a), the common tax year election (4b) and total assets and taxable income before NOL and special deductions (4c). Estates or trusts enter total income on line 5.
Enter the tax benefits on line 6
Enter the totals, before reduction for boycott participation or cooperation, for the foreign tax credit (6a), deferral of CFC earnings (6b), deferral of IC-DISC income (6c), FSC exempt foreign trade income (6d) and extraterritorial income exclusion income (6e).
Answer the line 7 questions
Check Yes or No for each of lines 7a through 7j, covering U.S. shareholder status, IC-DISC stock, foreign tax credit claims, control relationships, trust or partnership interests, FSC status and extraterritorial income exclusion.
Report operations in Part I
Answer lines 8, 9 and 10. For each Yes, complete the table with the country, the identifying number of the person having operations, the principal business activity code and description, and the IC-DISC product code if applicable.
Answer lines 11 and 12
Check Yes or No for whether you were requested to participate in, or participated in, an international boycott. If Yes, attach the English copies and statements described on the form and complete the rest of the form.
Complete Part II, line 13
Answer 13a for requests and agreements. For each Yes, complete the 13b table, using a separate line per country, person and type of participation and the code 01 to 05 for the type requested or agreed to.
Add the schedules if required
If you answered Yes to line 12, complete Schedules A and C or B and C (Form 5713) to figure the loss of tax benefits. Partnerships do not complete Schedule C.
Review, sign and download the PDF
Check the entries against the instructions, then sign, date and enter your title under the penalties of perjury statement. Download or print the completed PDF from FillingPDF, in duplicate if you file on paper.
How to submit 5713
You submit Form 5713 as an attachment to your income tax return, either on paper or electronically with an e-filed return.
- On paper: attach the original Form 5713, and Schedules A, B and C if they apply, to your income tax return. The form header says paper filers must file in duplicate, and the instructions say not to sign the copy attached to your return. Send the return to the address given in the instructions for that return.
- Electronically: if you file the original Form 5713 as an attachment to your e-filed income tax return, you do not have to file a duplicate. Follow the e-filing instructions for your return.
The form does not have a separate mailing address. On the form, enter the address of the service center where your return was filed; if the return was e-filed, the instructions say to enter "e-file". The instructions caution against sending the form to the Tax Forms and Publications Division address used for comments.
FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Signing the copy of Form 5713 that is attached to the income tax return; the instructions say not to sign that copy.
- Filing a paper Form 5713 without a duplicate; paper filers must file in duplicate, while an e-filed original needs no duplicate.
- Reporting U.S. approved boycotts, which the instructions say not to report on Form 5713.
- Using separate lines on line 8 for separate operations by the same person in the same country; use one line per country or per person having operations.
- Answering "Yes" to line 11 or 12 but not completing the rest of the form, or answering "Yes" to line 12 without Schedules A and C or B and C.
- Listing corporations on line 2b without designating a common tax year on line 4b, or listing members already included in the consolidated return instead of attaching Form 851.
- Omitting English copies of boycott requests (line 11) or of boycott clauses and a general statement (line 12).
- Leaving the line 6 amounts unreduced: they are the totals before reduction for boycott participation or cooperation.
- Not reporting an ongoing boycott agreement in a later year; it must be reported each year it is in effect.
- Entering a street address when the Post Office does not deliver there and the filer has a P.O. box; the instructions say to show the box number.
Frequently asked questions
What is Form 5713 used for?
Form 5713 is the IRS International Boycott Report. U.S. persons use it to report operations in or related to boycotting countries and the boycott requests they received and agreements they made. It is attached to the filer's income tax return.
Who has to file Form 5713?
A U.S. person with operations in or related to a boycotting country must file. So must controlled group members with operations, U.S. shareholders of such foreign corporations, partners in such partnerships, and owners of such trusts. Exceptions exist, such as the consolidated-return rule for controlled groups.
When is Form 5713 due?
It is due when your income tax return is due, including extensions. You attach the original to the return, so it travels with the return and has no separate due date.
Where do I send Form 5713?
You do not send it separately. Attach the original to your income tax return and file the return as its instructions direct. If you e-file the return, you attach the form to it electronically and need not file a duplicate.
Do I file Form 5713 in duplicate?
Paper filers must file Form 5713 in duplicate; the form header says so. If you file the original electronically as an attachment to your e-filed return, you are not required to file a duplicate. Do not sign the copy attached to your return.
What are Schedules A, B and C of Form 5713?
They figure the loss of tax benefits from boycott participation. Schedule A uses the international boycott factor, Schedule B uses taxes and income specifically attributed to boycott operations, and Schedule C computes the loss. If you answered Yes to line 12, complete A and C or B and C.
What is the penalty for not filing Form 5713?
Willful failure to file Form 5713 may result in a fine, imprisonment of no more than 1 year, or both, according to the IRS instructions. Cooperating with an international boycott can also cost you part of certain tax benefits.
Can I fill out Form 5713 online on FillingPDF?
You can fill out the Form 5713 PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the form with the IRS; you attach it to your income tax return.
Ready to fill out 5713?
Fill out 5713 now