
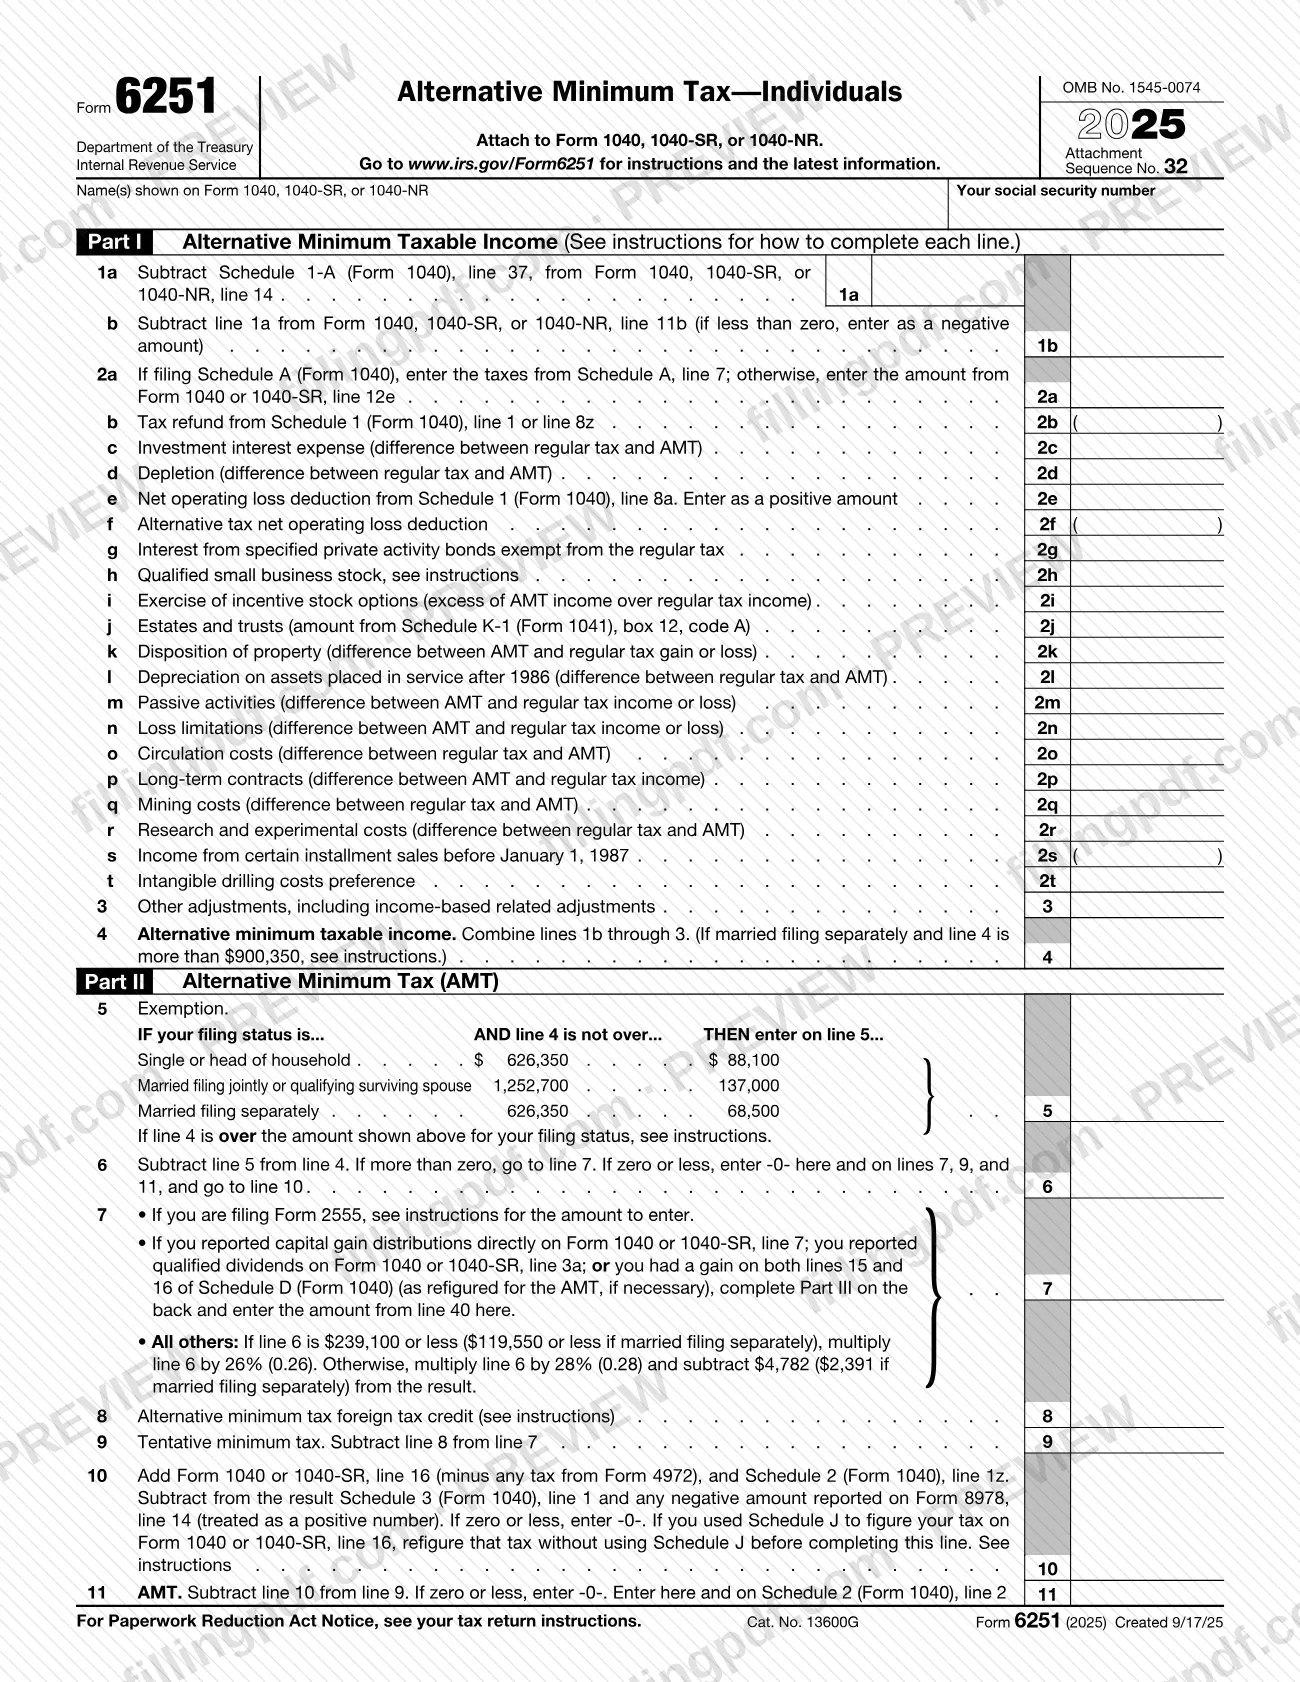
Form 6251, Alternative Minimum Tax—Individuals, is the Internal Revenue Service (IRS) form you use to figure the amount, if any, of your alternative minimum tax (AMT). It is attached to Form 1040, 1040-SR, or 1040-NR when one of the conditions in the IRS instructions applies to you. On this page you can fill out Form 6251 online on FillingPDF and download or print the completed PDF; the original form and its instructions are published by the IRS at www.irs.gov/Form6251.
Last updated
What is 6251?
Form 6251, Alternative Minimum Tax—Individuals, is the Internal Revenue Service (IRS) attachment to Form 1040, 1040-SR, or 1040-NR on which an individual figures the alternative minimum tax (AMT), a separate tax imposed in addition to the regular tax, and the tentative minimum tax.
The IRS explains that the AMT applies to taxpayers who have certain types of income that receive favorable treatment, or who qualify for certain deductions, under the tax law. It sets a limit on how far those benefits can reduce total tax. For the AMT, some items of income and deductions are treated differently, so you refigure them starting from the regular-tax amounts.
The form has three parts:
- Part I, Alternative Minimum Taxable Income: lines 1a through 4 start from your return, apply the adjustments and preferences on lines 2a through 2t and line 3, and end with alternative minimum taxable income on line 4.
- Part II, Alternative Minimum Tax (AMT): lines 5 through 11 apply the exemption, compute the tentative minimum tax on line 9, compare it with your regular tax on line 10 and give the AMT on line 11, which is also entered on Schedule 2 (Form 1040), line 2.
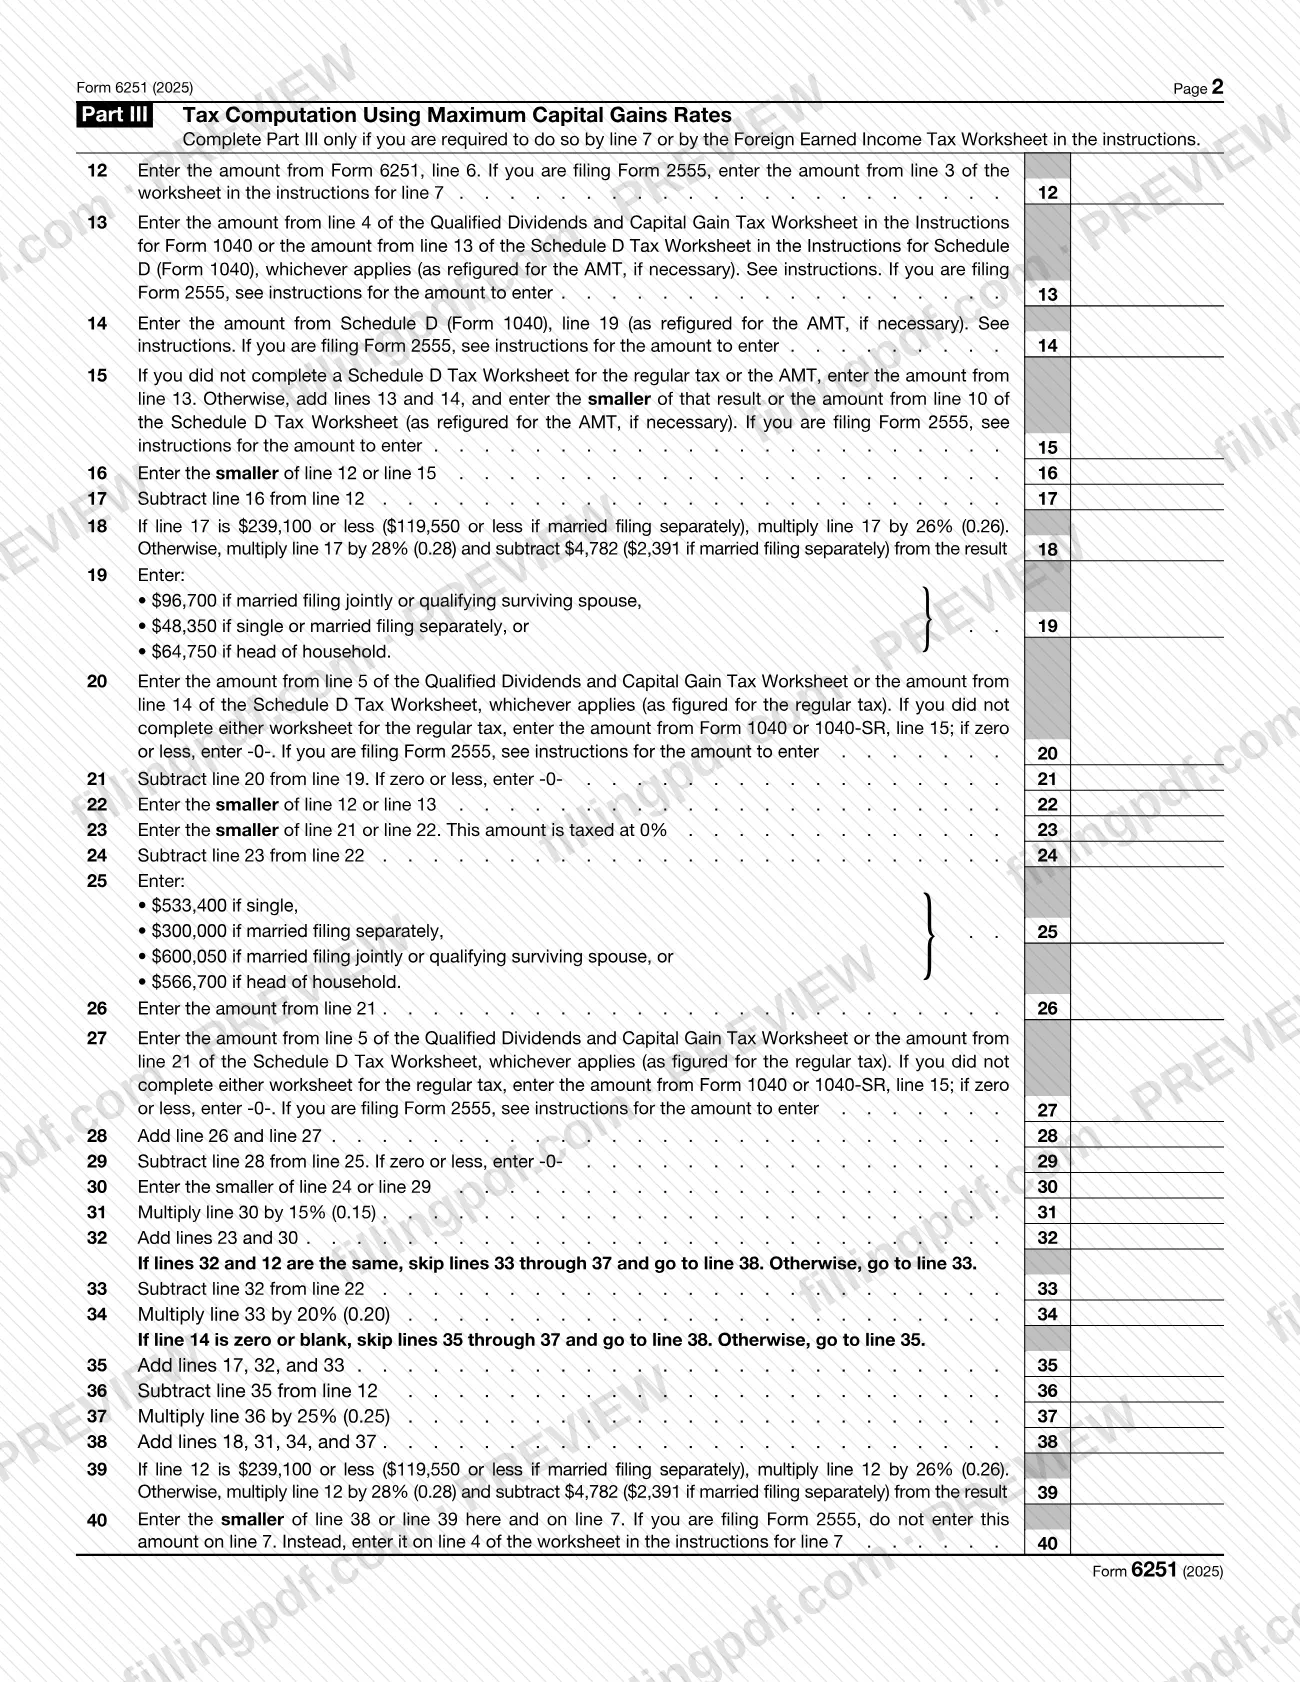
- Part III, Tax Computation Using Maximum Capital Gains Rates: lines 12 through 40, completed only when line 7 or the Foreign Earned Income Tax Worksheet requires it.
You also use Form 6251 to figure your tentative minimum tax (line 9), which you may need to limit certain credits. It is not the form for the credit for prior year minimum tax, which is claimed on Form 8801.
Who needs to file 6251?
You attach Form 6251 to your return if any of these statements is true, according to the IRS instructions:
- Form 6251, line 7, is greater than line 10.
- You claim any general business credit, and either line 6 (in Part I) of Form 3800 or line 25 of Form 3800 is more than zero.
- You claim the qualified electric vehicle credit (Form 8834), the personal-use part of the alternative fuel vehicle refueling property credit (Form 8911), or the credit for prior year minimum tax (Form 8801).
- The total of Form 6251, lines 2c through 3, is negative, and line 7 would be greater than line 10 if you didn't take lines 2c through 3 into account.
Use the form too if you only need to know your tentative minimum tax (line 9) to limit the credits listed above.
Special groups: nonresident aliens who disposed of U.S. real property interests at a gain must make a special computation on line 6 and write "RPI" next to it. Form 1040-NR filers follow the 1040-NR chart for line 5 and the 1040-NR notes for Part III. Partners and S corporation shareholders take their adjustments and preferences from Schedule K-1 and its instructions. Holders of a residual interest in a REMIC have a minimum for line 4.
When to file 6251
Form 6251 has no separate due date: you attach it to your Form 1040, 1040-SR, or 1040-NR whenever one of the "Who Must File" conditions applies, so it is due when that return is due. The 2025 form and instructions cover the 2025 tax year.
If you paid AMT for 2024 or had a minimum tax credit carryforward on your 2024 Form 8801, see Form 8801. If you pay AMT for 2025, you may be able to take a credit on Form 8801 for 2026.
Keep records that support the items you report on Form 6251, including the AMT versions of forms and worksheets you complete but do not attach, in case the IRS asks you to explain an item.
Documents you need
- Form 1040, 1040-SR, or 1040-NR: Form 6251 is attached to your return, and its lines start from amounts on that return.
- AMT Form 1116 (and Schedule B (Form 1116), if applicable): attach after Form 6251 only if you figure an AMT foreign tax credit on line 8 that differs from your regular-tax foreign tax credit.
- Records of your AMT computations, AMT versions of forms and worksheets, and AMT carryover and basis amounts: keep them for your records; do not attach them unless instructed.
How to fill out 6251
Enter your name and Social Security number
At the top, enter the name(s) shown on Form 1040, 1040-SR, or 1040-NR and your social security number.
Complete lines 1a and 1b
Line 1a: subtract Schedule 1-A (Form 1040), line 37, from line 14 of your return. Line 1b: subtract line 1a from line 11b of your return, entering a negative amount if the result is less than zero.
Enter taxes and refunds on lines 2a and 2b
Line 2a: the taxes from Schedule A, line 7, or, if you do not file Schedule A, the line 12e amount from Form 1040 or 1040-SR. Line 2b: enter the tax refund from Schedule 1, line 1 or 8z, as a negative amount, and add a description next to the entry space if you include a line 8z amount.
Complete adjustments on lines 2c through 2t
Line 2c to 2t each cover one item, such as investment interest, depletion, incentive stock options, depreciation, passive activities and intangible drilling costs. Follow the instruction for each line, entering the difference between the AMT and regular-tax amount and using a negative amount where the instructions say so.
Enter other adjustments on line 3
Enter the total of other adjustments that apply, such as pre-1987 depreciation, pollution control facilities, tax shelter farm activities, mortgage interest on a non-qualified dwelling and related adjustments. Do not repeat an item already refigured on another line.
Figure alternative minimum taxable income on line 4
Combine lines 1b through 3. If you are married filing separately and line 4 is over the amount printed beside it, add the additional amount the instructions describe.
Determine your exemption on line 5
Use the chart printed on line 5 for your filing status. If line 4 is over the amount shown for your filing status, figure line 5 with the Exemption Worksheet in the instructions.
Complete lines 6 and 7
Line 6: subtract line 5 from line 4; if zero or less, enter -0- on lines 6, 7, 9 and 11 and go to line 10. Line 7: use Part III (line 40) if you have capital gain distributions, qualified dividends or a Schedule D gain on lines 15 and 16, the Foreign Earned Income Tax Worksheet if you filed Form 2555, or the computation printed on line 7 otherwise.
Enter the AMT foreign tax credit on line 8
Enter your AMT foreign tax credit, or leave line 8 blank if line 10 is greater than or equal to line 7. If your credit differs from your regular-tax credit, complete AMT Forms 1116 and attach them after Form 6251.
Complete lines 9 through 11
Line 9: subtract line 8 from line 7 to get the tentative minimum tax. Line 10: figure your regular tax as the line directs. Line 11: subtract line 10 from line 9, entering -0- if zero or less, and enter the result on Schedule 2 (Form 1040), line 2.
Complete Part III only if required
Complete lines 12 through 40 only if line 7 or the Foreign Earned Income Tax Worksheet tells you to. Enter the smaller of line 38 or line 39 on line 40 and on line 7; if you filed Form 2555, enter it on line 4 of the worksheet instead.
Review and download the completed PDF
Check that each line follows its instruction and that negative amounts are marked. Download or print the completed PDF from FillingPDF, then attach it to your return as described under How to submit.
How to submit 6251
Form 6251 is not filed on its own: you attach it to your Form 1040, 1040-SR, or 1040-NR, and it is submitted through the same channel as that return. The form prints no separate address, portal or appointment rule.
- With your return: attach the completed Form 6251 to the return. Enter the AMT from line 11 on Schedule 2 (Form 1040), line 2.
- AMT foreign tax credit: if you figure an AMT foreign tax credit on line 8, attach to your return, after Form 6251, all AMT Forms 1116 (and Schedule B (Form 1116), if applicable) you used. Do not attach them if your AMT foreign tax credit is the same as your regular-tax foreign tax credit.
- Other AMT versions: do not attach AMT versions of other forms or worksheets (such as Form 8949, Schedule D or Form 8582) unless instructed. Keep them with your records.
The IRS publishes instructions and the latest information at www.irs.gov/Form6251. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Attaching AMT versions of Form 8949, Schedule D, Form 8582, Form 4952 or worksheets to the return; the instructions say not to attach them unless instructed, and to keep them with your records.
- Counting the same adjustment on two lines; the caution on lines 2m, 2n, 2p, 2l and 3 says an amount taken into account on one line must not be used on another adjustment line.
- Entering line 2b, 2f or 2s amounts as positive numbers; these lines are shown in parentheses and the instructions say to enter them as negative amounts.
- Putting depreciation for a passive activity on line 2l instead of line 2m, or depreciation limited by at-risk or basis rules on line 2l instead of line 2n.
- Filing as married filing separately without adding the extra amount to line 4 when line 4 exceeds the threshold printed on that line.
- Using the line 7 percentage computation when you filed Form 2555; the instructions require the Foreign Earned Income Tax Worksheet.
- Skipping Part III when line 7 requires it, for example when you reported capital gain distributions directly on Form 1040 or 1040-SR, line 7, or qualified dividends on line 3a.
- Figuring line 10 with Schedule J; the instructions say to refigure the line 16 tax without Schedule J for Form 6251 only, without changing your return.
- Omitting "RPI" next to line 6 or "Sch. Q" next to line 4 when the nonresident alien or REMIC residual interest rules apply.
Frequently asked questions
What is Form 6251 used for?
Form 6251 is used to figure the amount, if any, of your alternative minimum tax (AMT), a separate tax imposed in addition to your regular tax. You also use it to figure your tentative minimum tax on line 9, which may be needed to limit certain credits.
Who has to file Form 6251?
You must attach it if line 7 is greater than line 10, if you claim a general business credit with Form 3800 amounts above zero, if you claim Form 8834, 8911 or 8801 credits, or if lines 2c through 3 total a negative amount and line 7 would otherwise exceed line 10.
Do I file Form 6251 separately or with my tax return?
You attach it to Form 1040, 1040-SR, or 1040-NR; the form itself says to attach it to the return. It has no separate address or filing channel, and the AMT on line 11 is carried to Schedule 2 (Form 1040), line 2.
Can I fill out Form 6251 online?
Yes. You can fill out the PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the form with the IRS; you submit it with your return through the IRS channels.
When do I complete Part III of Form 6251?
Only if line 7 or the Foreign Earned Income Tax Worksheet requires it. Line 7 sends you to Part III if you reported capital gain distributions on line 7 of Form 1040 or 1040-SR, qualified dividends on line 3a, or had a gain on both lines 15 and 16 of Schedule D.
What do I do if I filed Form 2555?
Do not use the simple computation on line 7. The instructions direct you to the Foreign Earned Income Tax Worksheet, and Part III has special instructions for lines 12 through 15, 20 and 27. If Part III applies, line 40 goes on line 4 of the worksheet, not on line 7.
Can itemizing lower my total tax when I owe AMT?
It may. The standard deduction is not allowed for the AMT, and if you claim it on your return you cannot claim itemized deductions for the AMT. The instructions say you may lower total tax by itemizing even when itemized deductions are less than the standard deduction.
Do I attach the AMT versions of other forms to Form 6251?
No, not unless instructed. Keep AMT versions of forms such as Form 8949 or Schedule D with your records. The exception is AMT Form 1116, which you attach after Form 6251 when your AMT foreign tax credit differs from your regular foreign tax credit.
Ready to fill out 6251?
Fill out 6251 now