
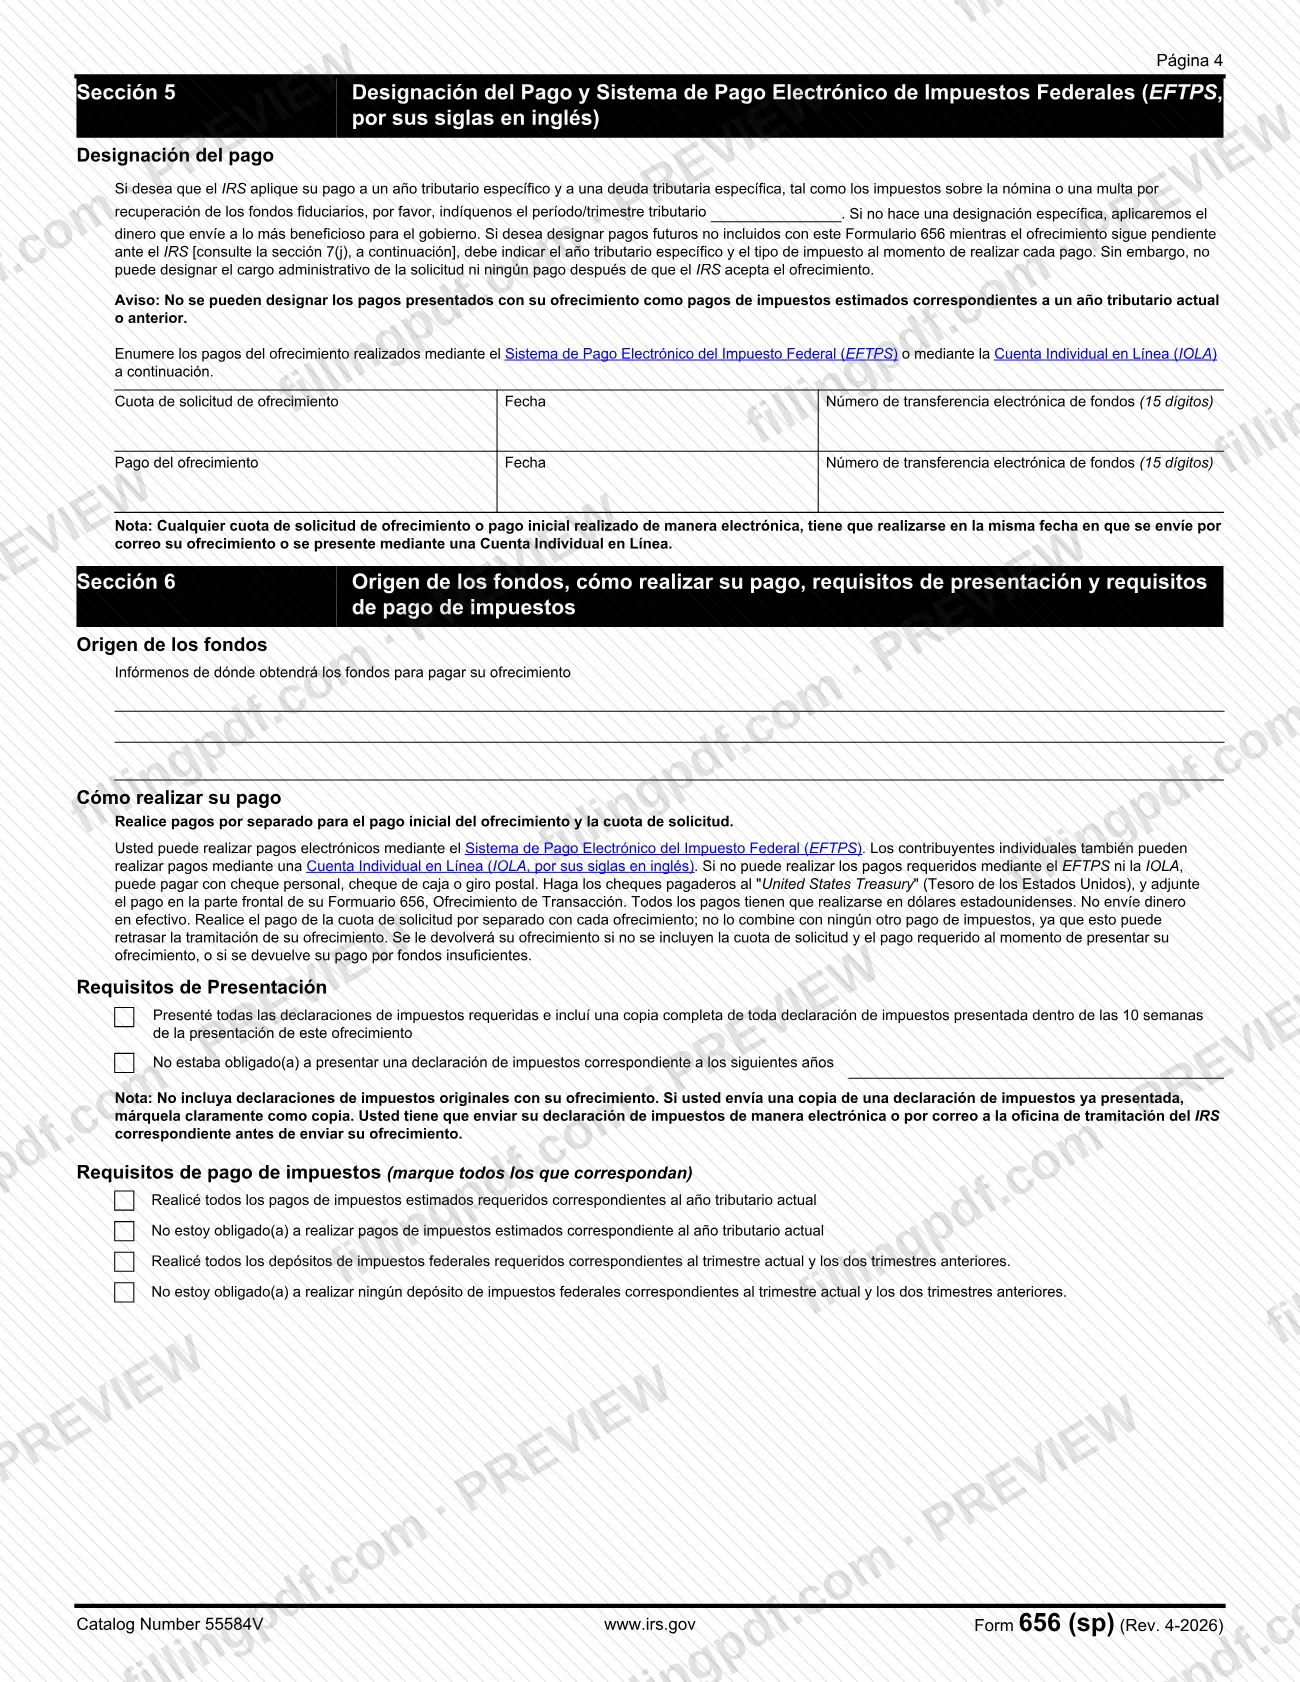
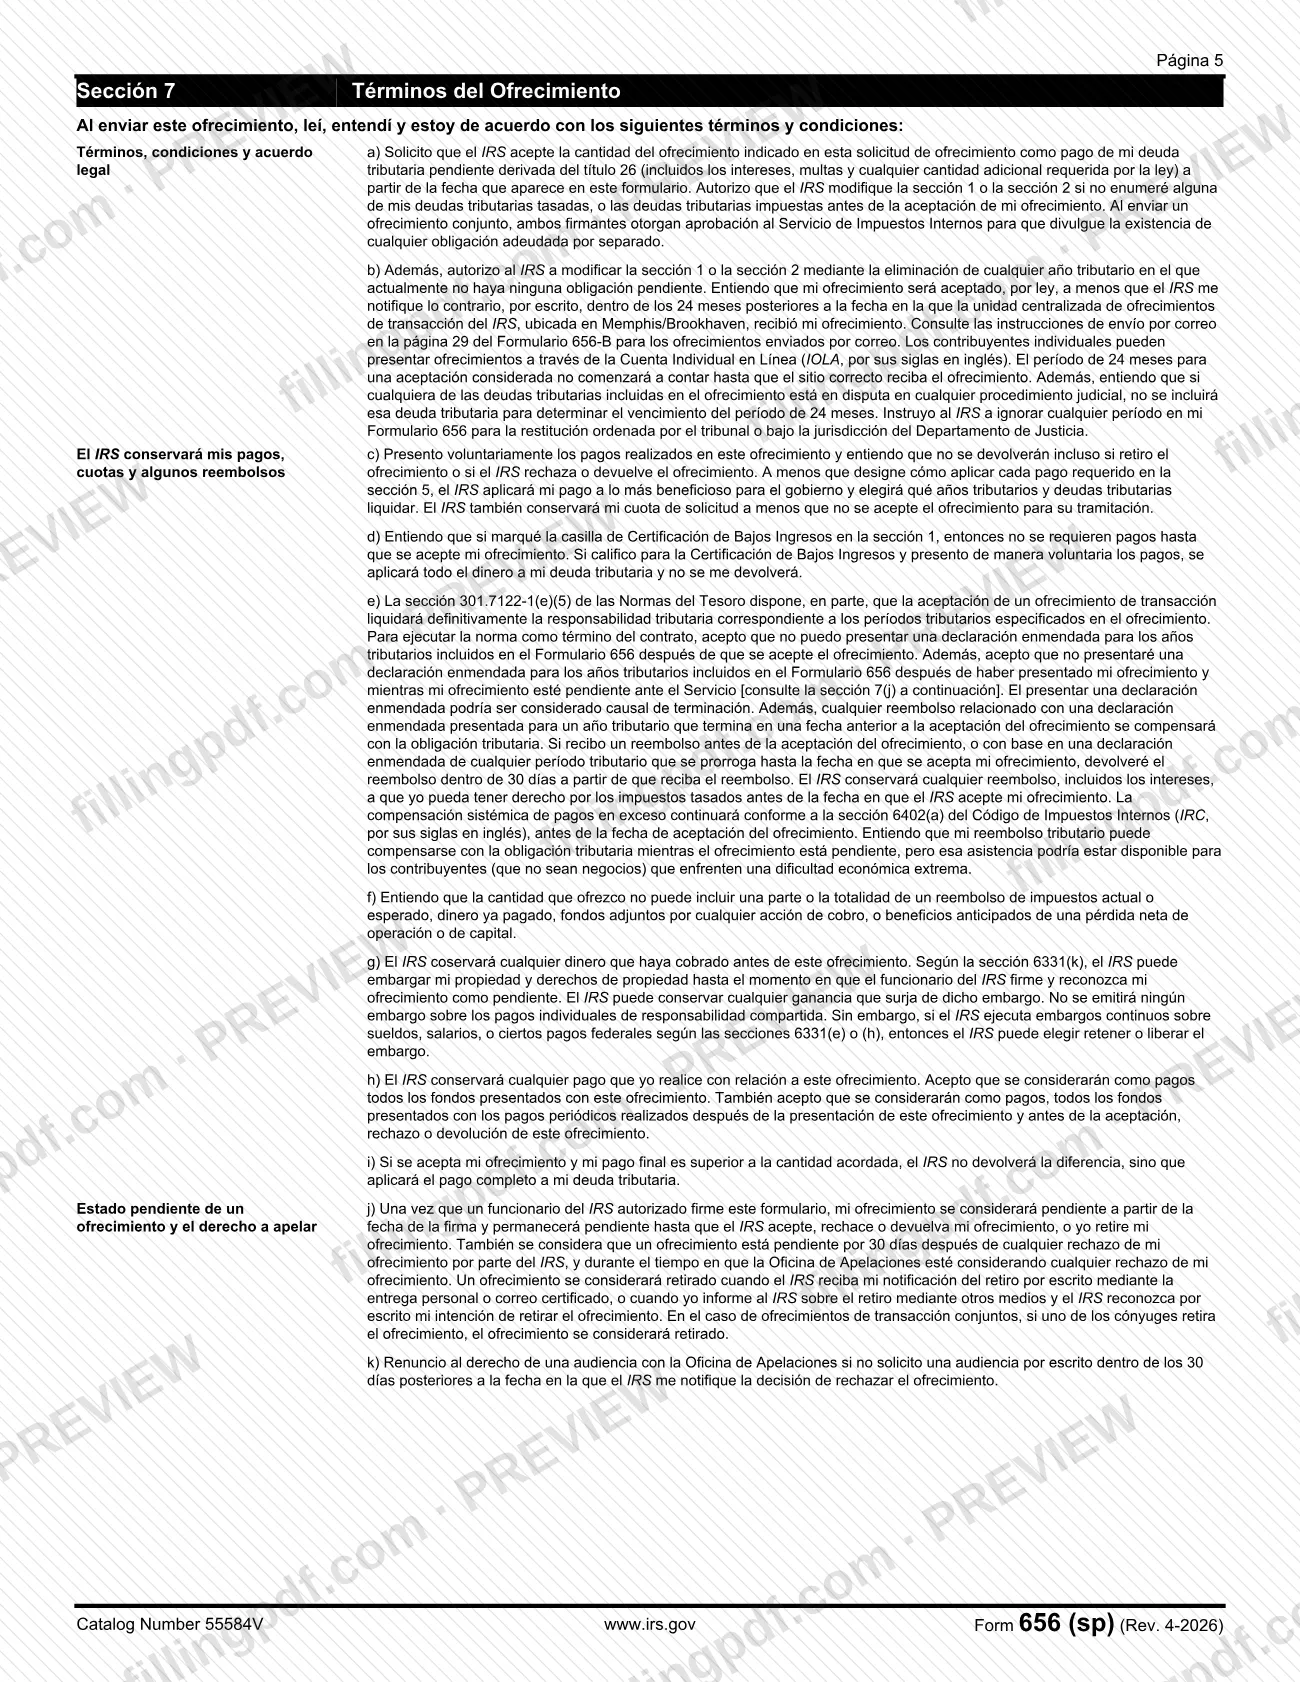
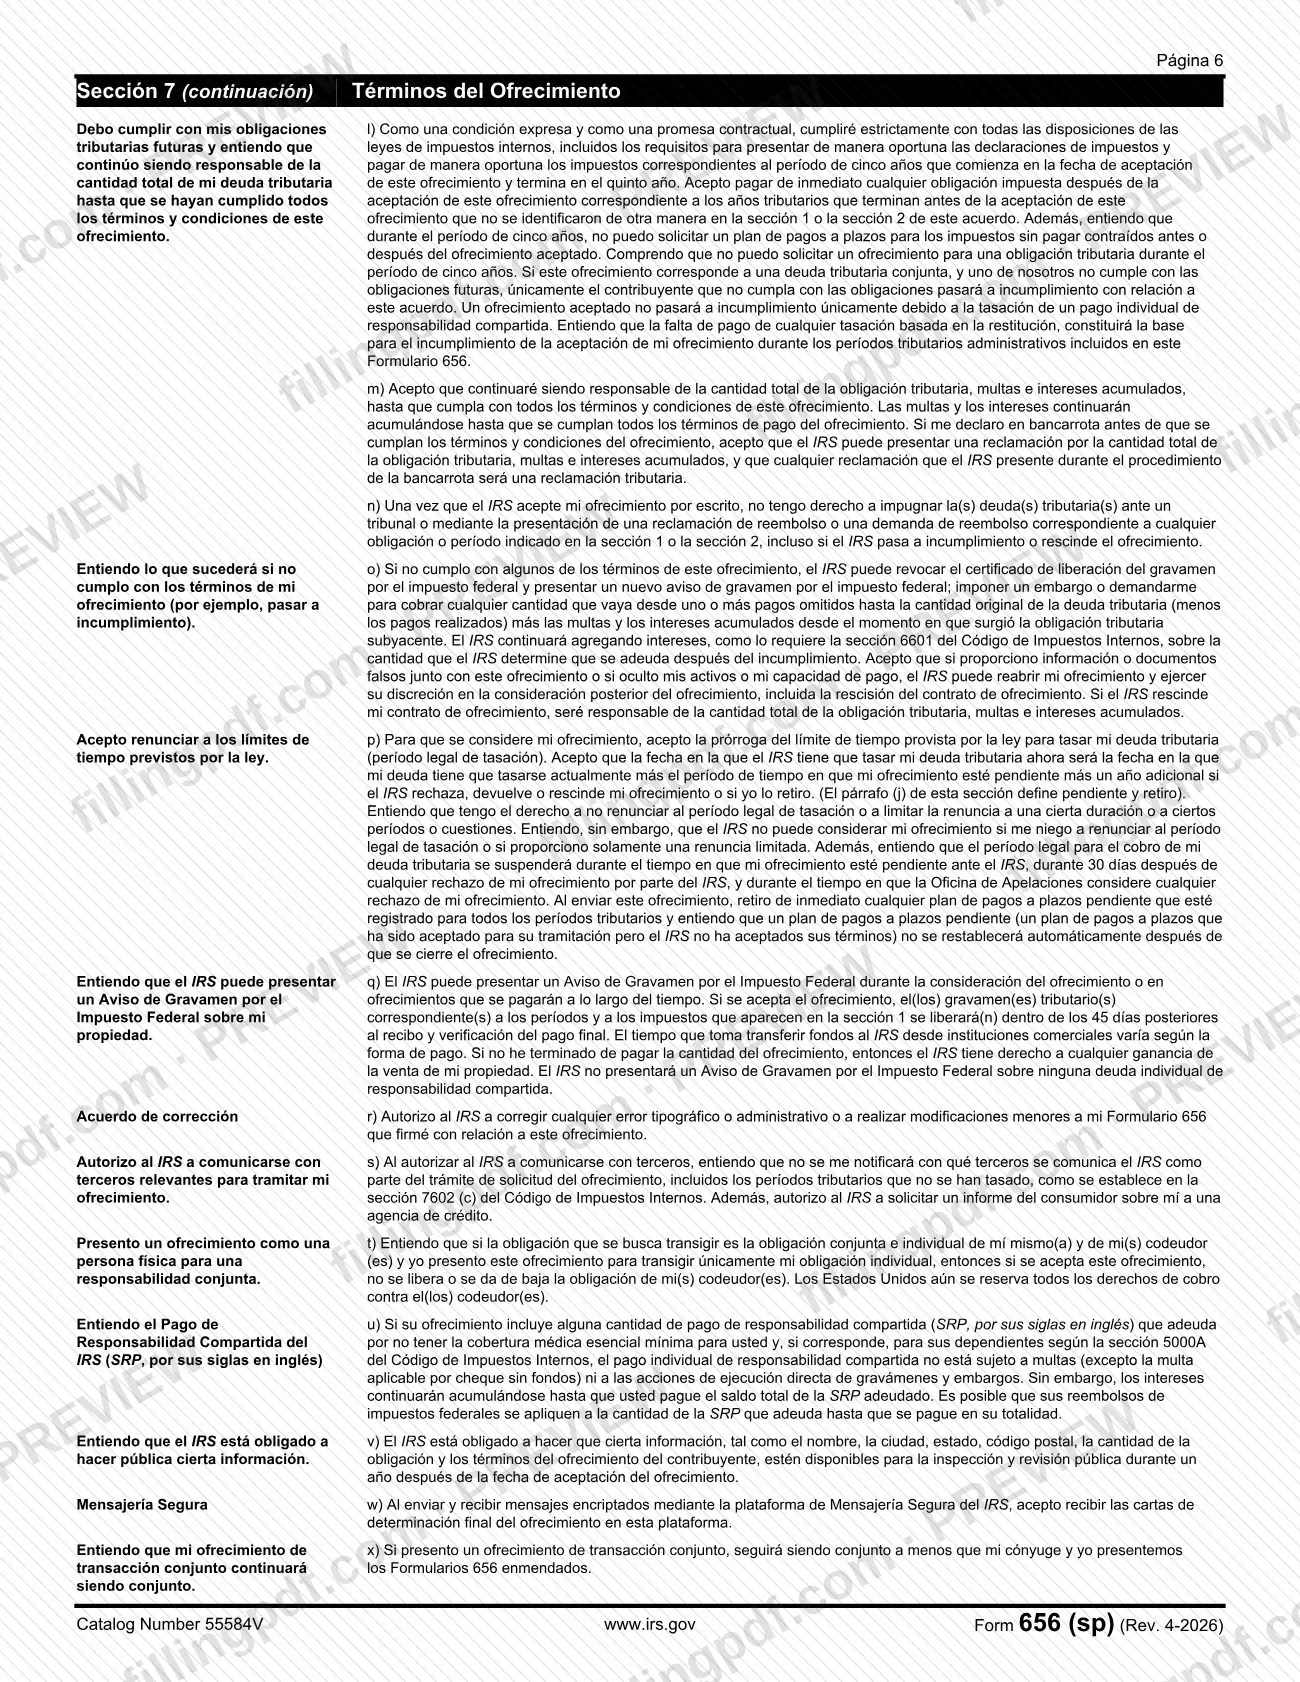
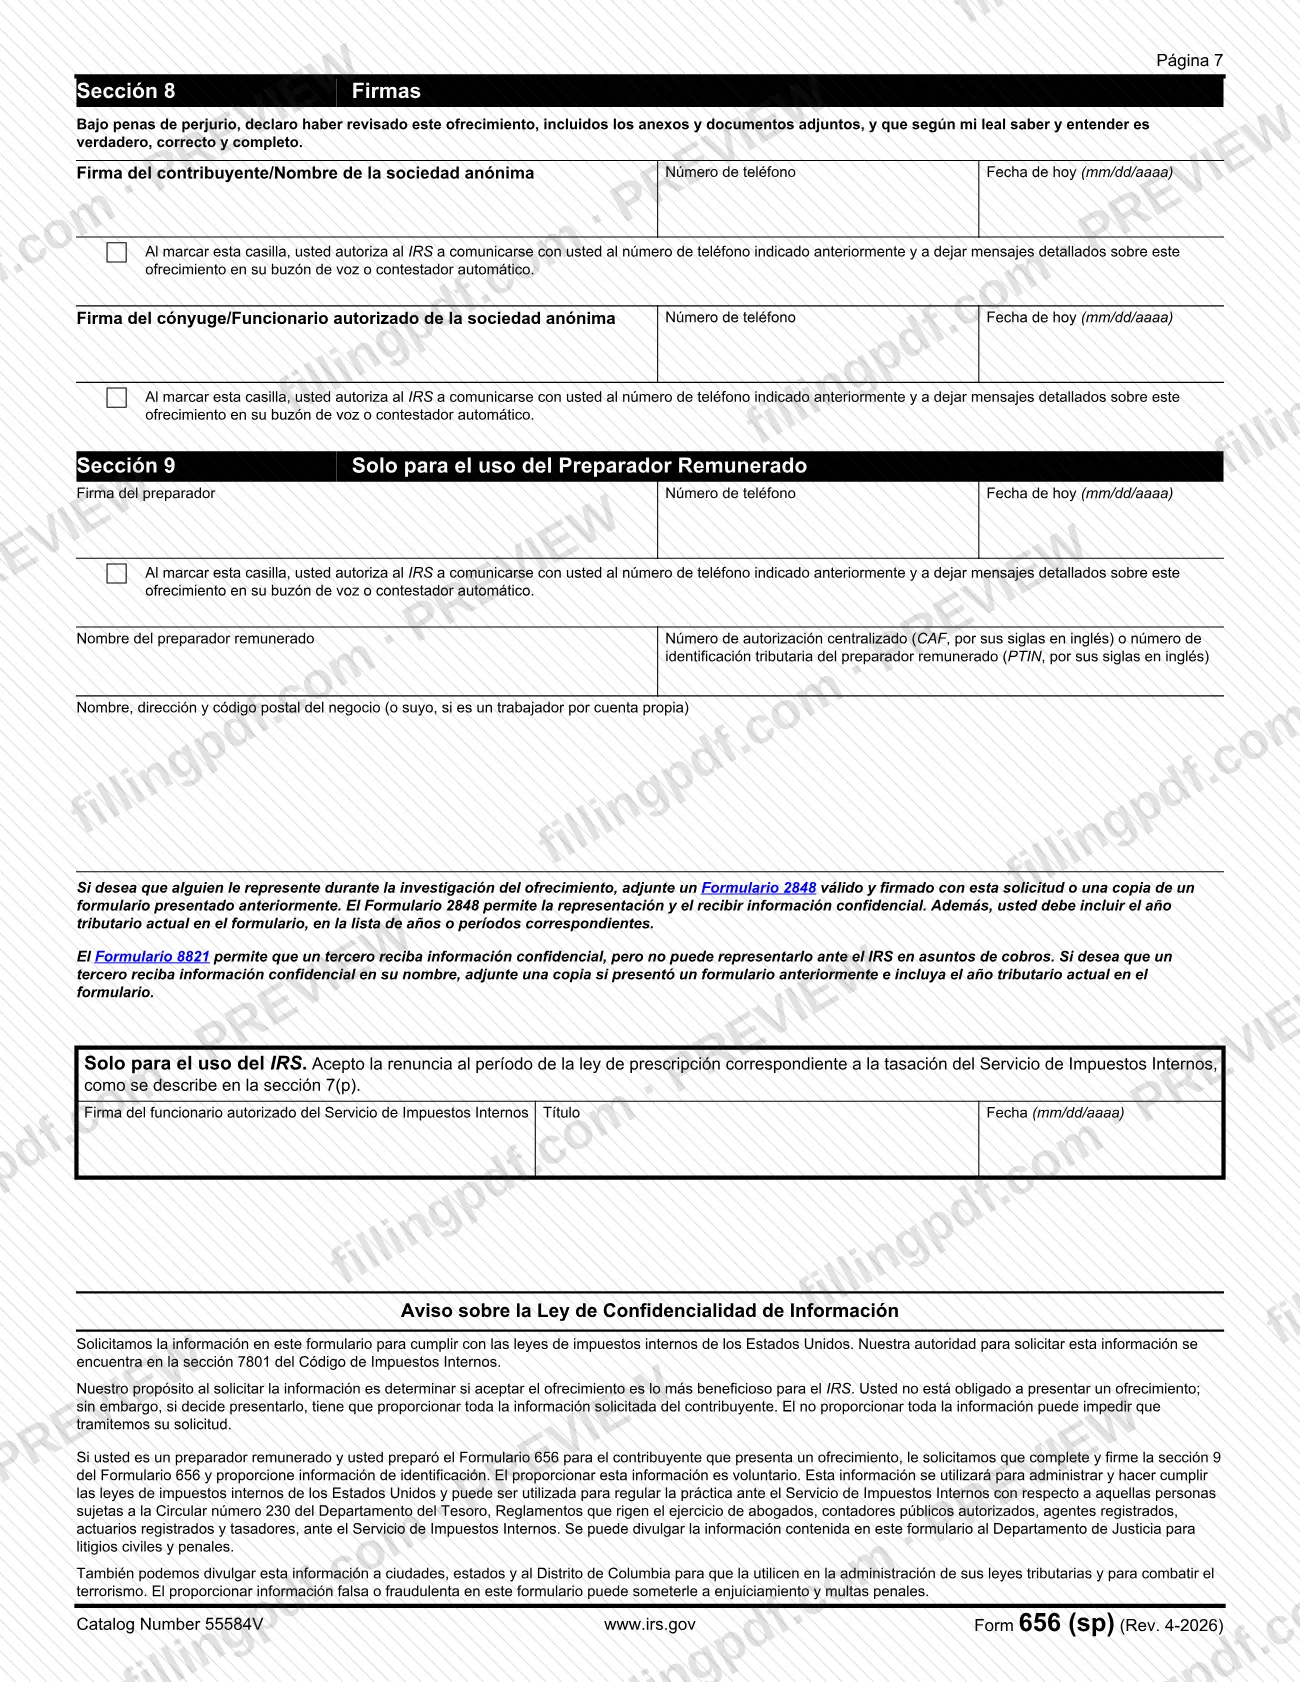
Form 656 (sp), Offer in Compromise (Spanish Version), is the Spanish-language edition of the IRS offer form (printed title "Ofrecimiento de Transacción") used to propose settling federal tax debt for less than the full amount owed. The form carries a warning that it is not a standalone document and is meant for tax professionals; individuals applying for an offer use Form 656-B. On this page you can fill out the form online on FillingPDF and download or print the completed PDF. The original PDF is published by the Internal Revenue Service (IRS).
Last updated
What is 656 (sp)?
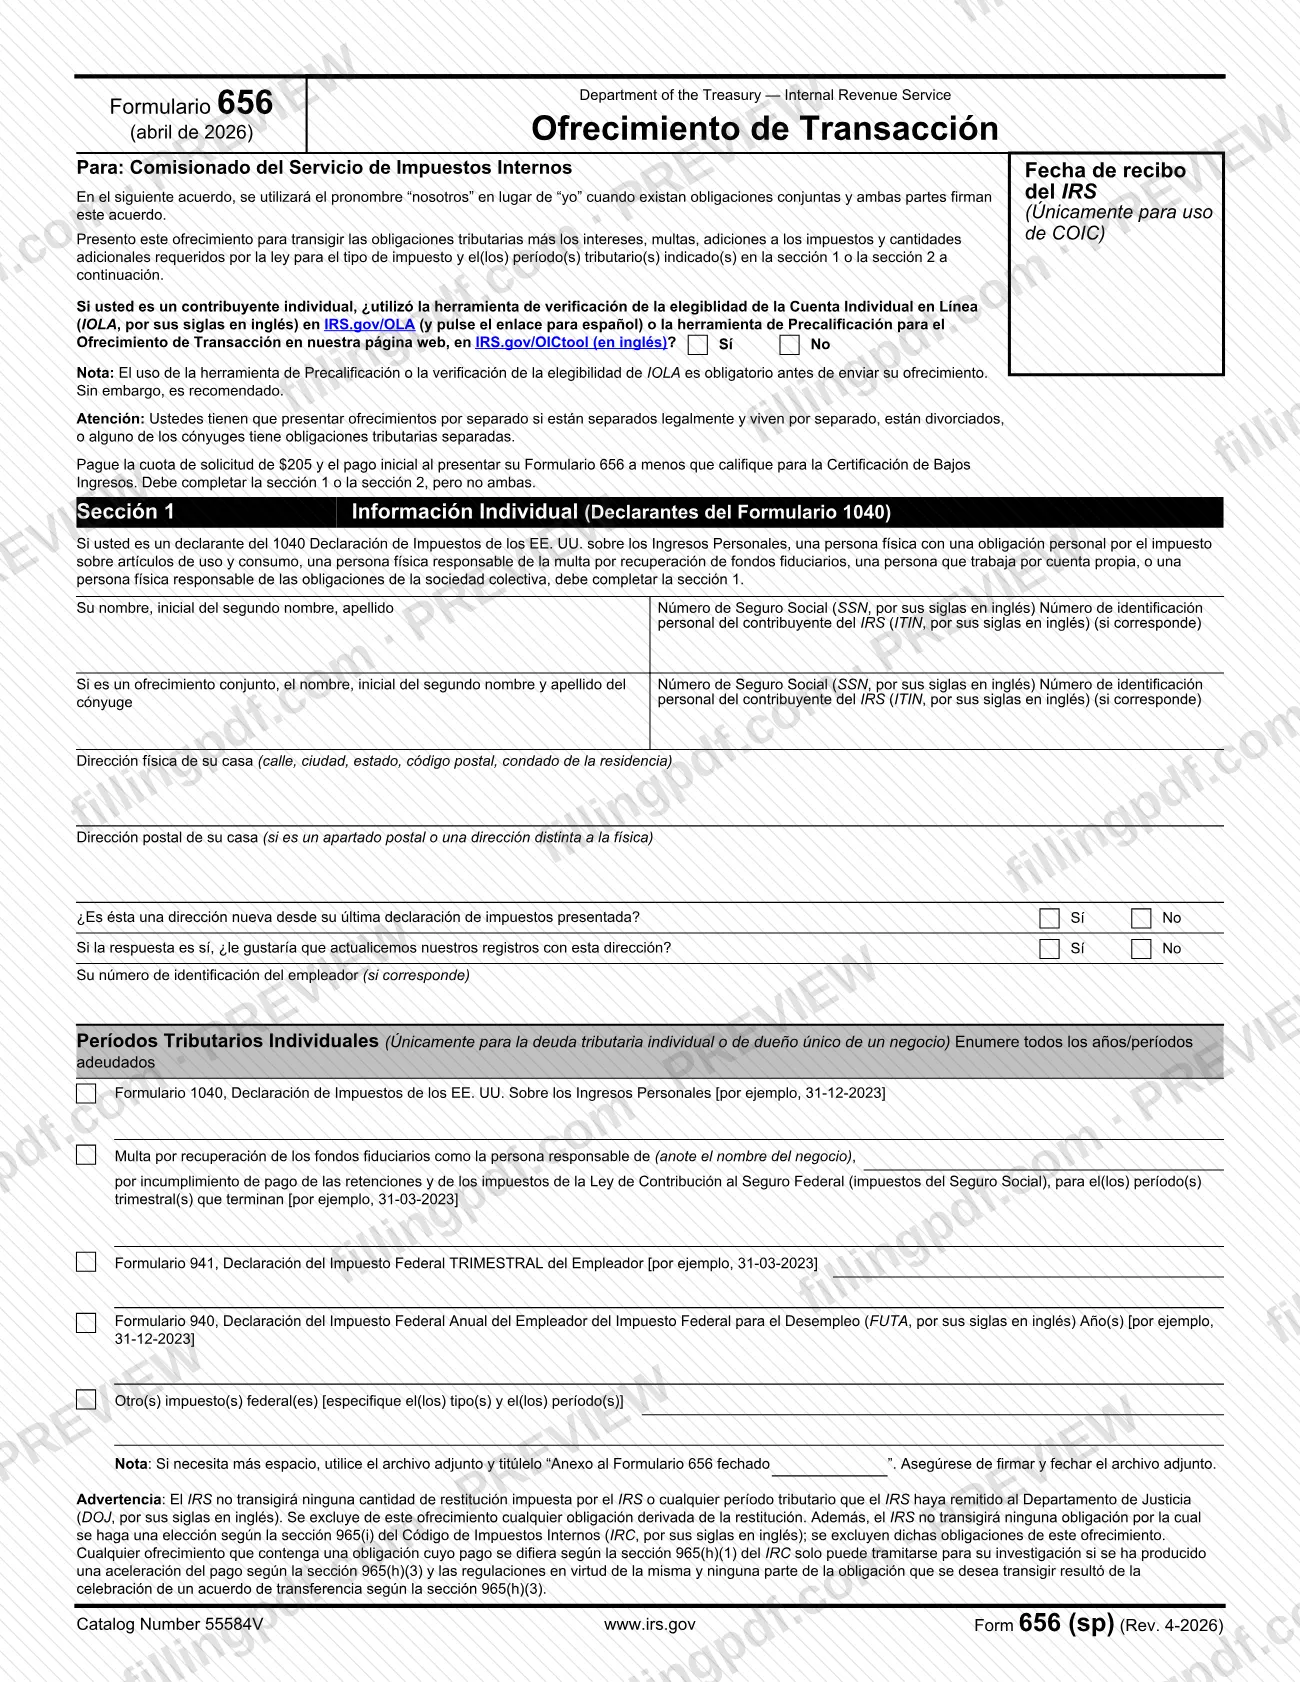
Form 656 (sp), Offer in Compromise (Spanish Version), is the Spanish-language version of the IRS form on which a taxpayer proposes to settle tax liabilities, plus interest, penalties and additional amounts, for the type of tax and periods listed in Section 1 or Section 2.
The IRS agency page describes an offer in compromise (OIC) as an agreement between you and the IRS that settles your tax liabilities for less than the full amount you owe. The form is addressed to the Commissioner of Internal Revenue and is built in nine sections: individual or business information, reason for the offer, payment terms, payment designation, source of funds and compliance statements, the terms of the offer, signatures and a paid preparer block.
This version is the form-only edition. The warning printed at the top says it is not a standalone form and is meant only for tax professionals. Complete financial statements and the required application fee and initial payment must accompany it, or consideration of the offer will be delayed. Individuals use Form 656-B, the information booklet, which includes Form 656 together with Form 433-A (OIC) and Form 433-B (OIC). An offer based on doubt as to liability uses Form 656-L instead.
The IRS will not compromise court-ordered restitution or any period it has referred to the Department of Justice, and it excludes liabilities for which a section 965(i) election was made.
Who needs to file 656 (sp)?
The form is intended for tax professionals preparing an offer in compromise for a client. The IRS warns that individuals who want their offer considered must use Form 656-B, the information booklet, rather than this form-only version.
Within the form, you complete one of two sections, never both:
- Section 1, Individual Information: Form 1040 filers, individuals with a personal excise tax liability, individuals responsible for the trust fund recovery penalty, self-employed people, and individuals responsible for partnership liabilities.
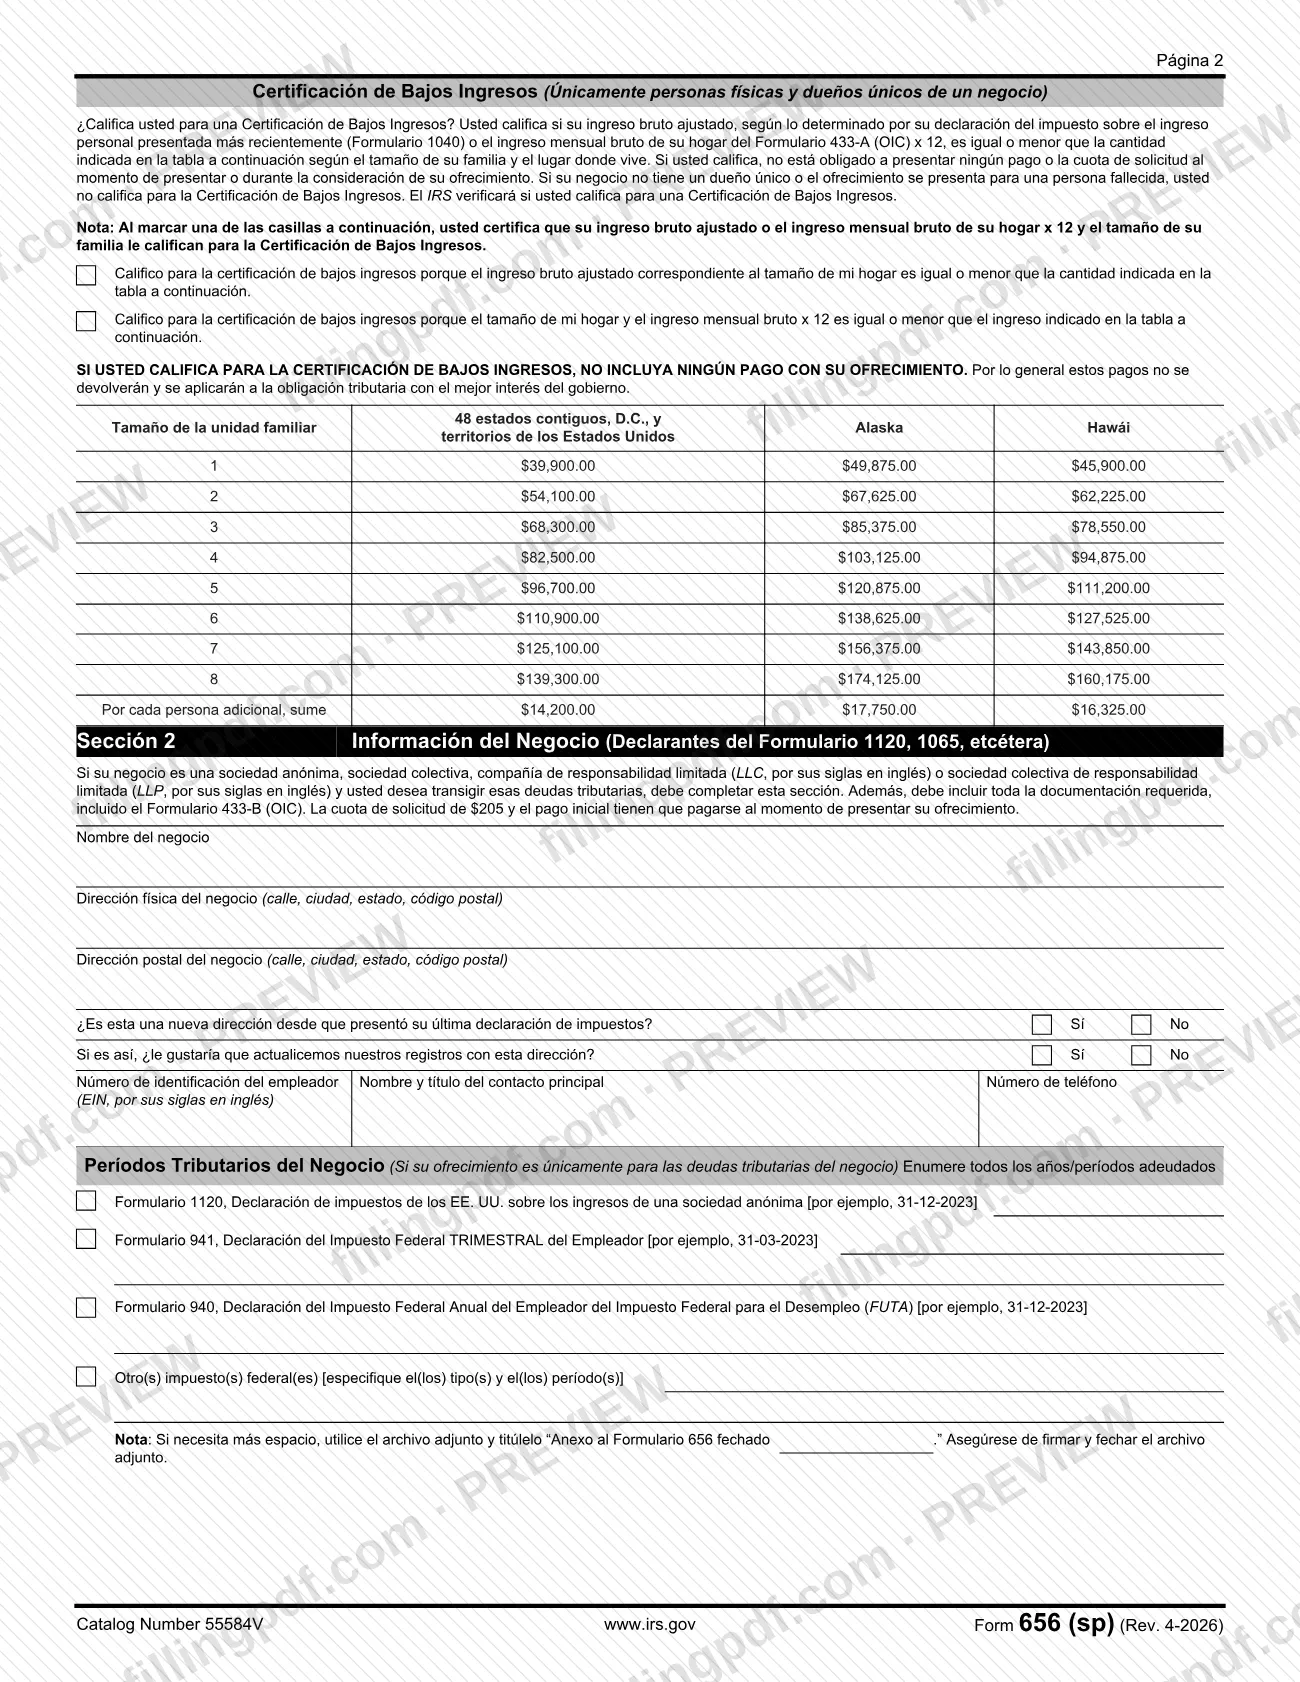
- Section 2, Business Information: a corporation, partnership, LLC or LLP settling the business's tax debts. Form 433-B (OIC) and all required documentation must be included.
Spouses file separate offers if they are legally separated and live apart, are divorced, or one spouse has separate tax liabilities. Only individuals qualify for the effective tax administration reason based on economic hardship. The Low-Income Certification is available only to individuals and sole proprietors; a business that is not a sole proprietorship, or an offer for a deceased person, does not qualify.
Someone who represents you during the investigation of the offer needs a valid, signed Form 2848 attached. Form 8821 only lets a third party receive confidential information.
When to file 656 (sp)
Use Form 656 (sp) when you are ready to propose an offer in compromise; the form prints no deadline of its own. Before sending it, all required tax returns must be filed, and current-year estimated tax payments and federal tax deposits for the current and two prior quarters must be made or not required.
Once the offer is filed, the form says the IRS accepts it by law unless it notifies you otherwise in writing within 24 months of the date its centralized offer unit received it. The period does not start until the correct site receives the offer. If you choose periodic payments, you must keep making monthly payments while the IRS considers the offer, unless you qualified under the Low-Income Certification; otherwise the offer is returned without appeal rights. A low-income filer's first payment is due 30 calendar days after acceptance. If the IRS rejects the offer, you have 30 days from the notice to request an Appeals hearing in writing.
Documents you need
- Form 433-A (OIC), Collection Information Statement for Wage Earners and Self-Employed Individuals: the complete financial statement for an individual offer based on doubt as to collectability or effective tax administration.
- Form 433-B (OIC), Collection Information Statement for Businesses: required with Section 2 when a corporation, partnership, LLC or LLP makes the offer.
- A detailed explanation of special circumstances: required for the effective tax administration reasons (economic hardship or public policy or equity), and when special circumstances keep you from paying the minimum offer amount under the doubt as to collectability reason.
- A complete copy of each tax return filed within 10 weeks of submitting the offer, clearly marked as a copy. Do not send original returns.
- Form 2848, valid and signed, or a copy of one filed earlier: only if you want someone to represent you during the investigation of the offer; the current tax year must be listed.
- Form 8821 or a copy of one filed earlier: only if you want a third party to receive your confidential information; the current tax year must be listed.
- An attachment titled "Addendum to Form 656 dated" with the date, signed and dated: only if you need more space to list tax periods.
How to fill out 656 (sp)
Confirm this is the right form
Read the warning at the top: Form 656 (sp) is for tax professionals, and individuals use Form 656-B. Make sure the complete financial statements, the application fee and the initial payment will accompany the offer.
Answer the eligibility tool question
If you are an individual taxpayer, check Yes or No to say whether you used the IOLA eligibility checker (IRS.gov/OLA) or the Offer in Compromise Pre-Qualifier tool (IRS.gov/OICtool). The form recommends using one.
Complete Section 1 or Section 2
Fill in Section 1 for Form 1040 filers and related individual liabilities, or Section 2 for a corporation, partnership, LLC or LLP; never both. Enter names, SSN or ITIN or EIN, addresses, and the address-change questions.
List the tax periods
Check each applicable type of tax and enter all years or periods owed in the format shown, such as 31-12-2023: Form 1040, trust fund recovery penalty, Form 941, Form 940 or other federal taxes. Use a signed, dated addendum if you need more room.
Check Low-Income Certification if it applies
Individuals and sole proprietors check one box on page 2 only if adjusted gross income, or monthly gross household income times 12, is at or below the table amount for their household size and location. If you check one, include no payment.
Select the reason for the offer
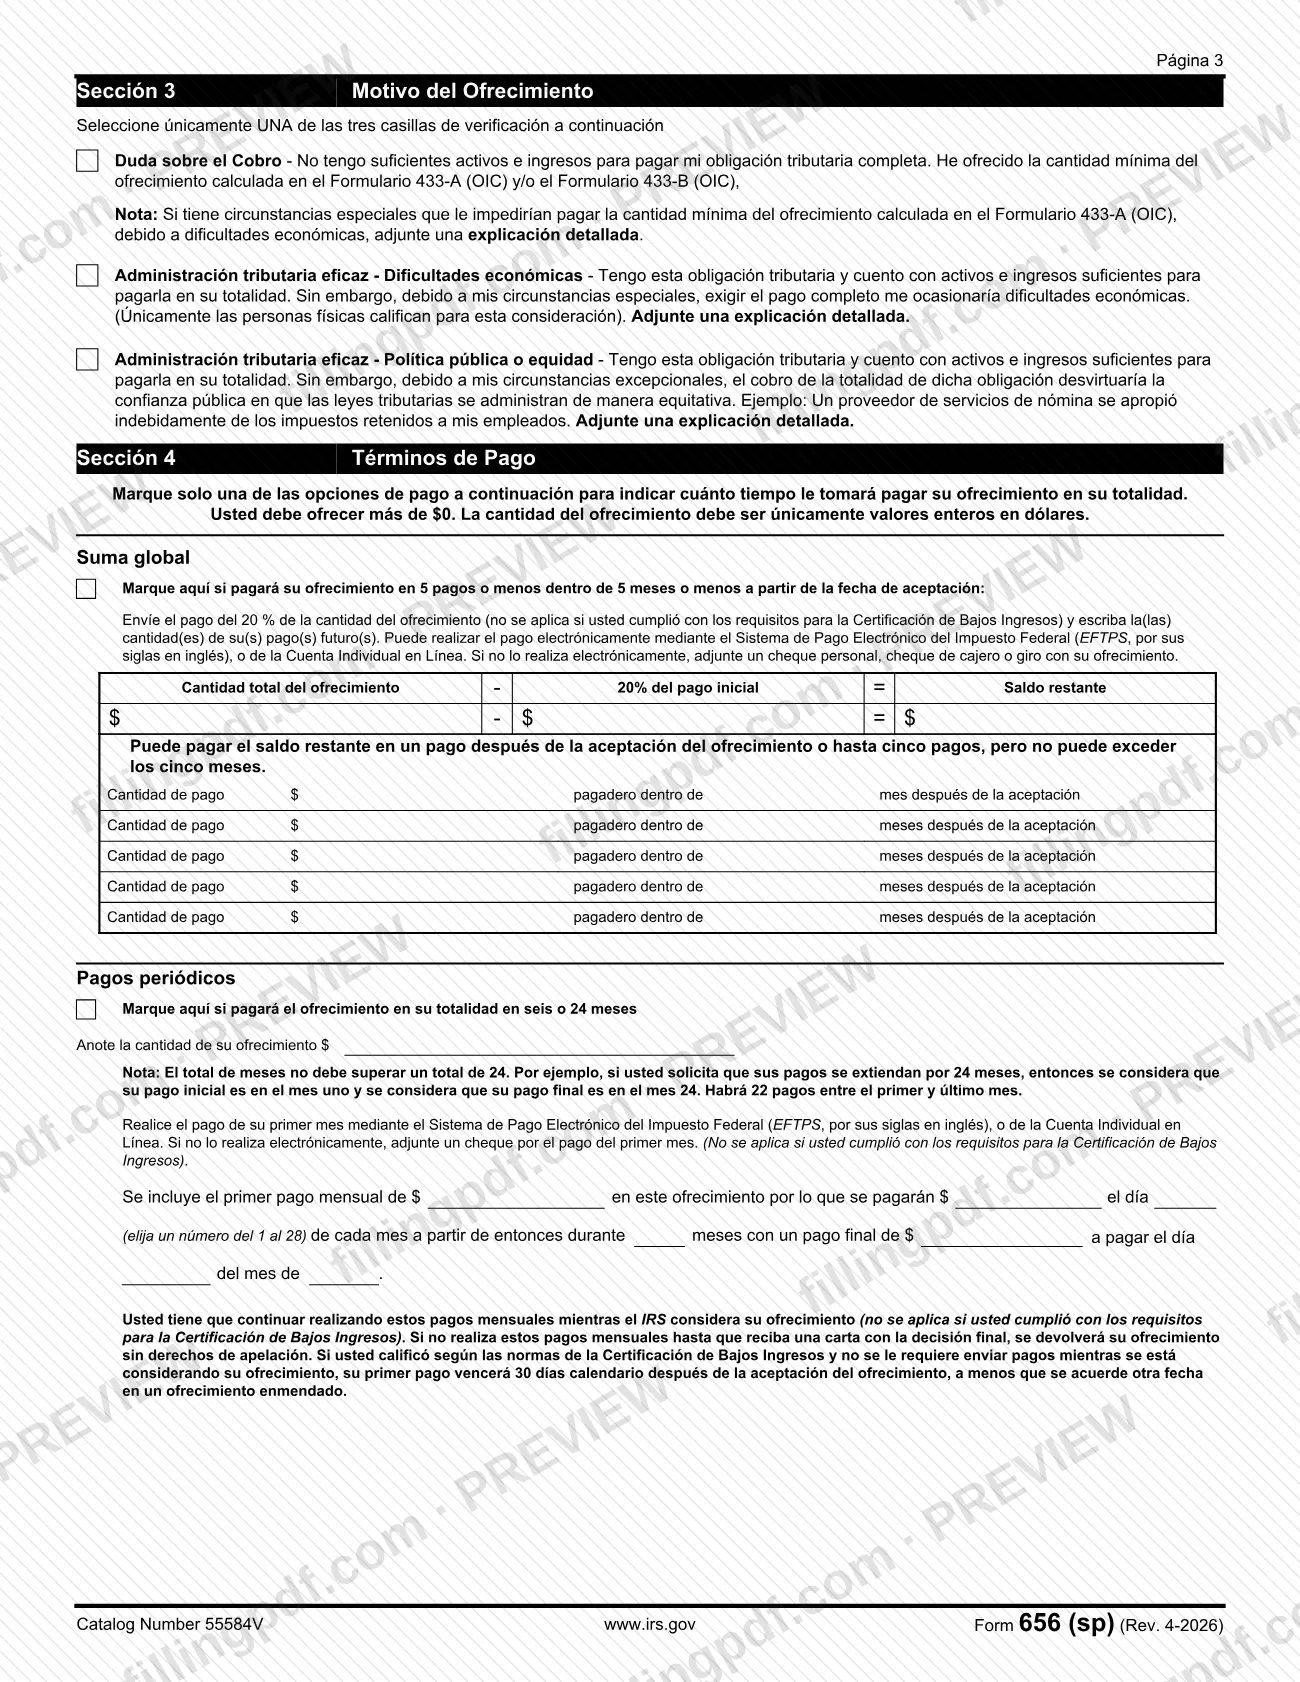
In Section 3, check only one: Doubt as to Collectability, Effective Tax Administration for economic hardship (individuals only), or Effective Tax Administration for public policy or equity. Attach the detailed explanation where the form requires it.
Choose payment terms
In Section 4, enter an offer above zero in whole dollars and check Lump Sum (up to five payments within five months, with a 20% initial payment) or Periodic Payments (six to 24 months, payment day from 1 to 28). Fill in the amounts and dates.
Designate payments and list electronic ones
In Section 5, name a specific tax year or period if you want payments applied that way; the application fee cannot be designated. List any EFTPS or IOLA payments with date and the 15-digit transfer number.
State the source of funds and compliance
In Section 6, say where the funds will come from, then check the filing requirements and the tax payment requirements that apply to you.
Read the Section 7 terms
Section 7, paragraphs a through x, sets the terms you agree to, including the statute of limitations waiver in 7(p) and the five-year future compliance condition in 7(l). Read them before you sign.
Sign and add preparer details
In Section 8, sign and date in mm/dd/yyyy format with phone numbers; the spouse or an authorized corporate officer signs the second line. A paid preparer completes Section 9, including CAF or PTIN.
Review and download the completed PDF
Check every section, the single-box choices and the attachments, then download or print the completed PDF from FillingPDF and assemble the package described under How to submit.
How to submit 656 (sp)
Form 656 (sp) can be mailed to the IRS or, for individual taxpayers, submitted through the Individual Online Account (IOLA).
- By mail: send the offer to the IRS centralized offer in compromise unit in Memphis/Brookhaven. The form refers to the mailing instructions on page 29 of Form 656-B; use those for the current address.
- Online (individuals only): individual taxpayers may file through IOLA at IRS.gov/OLA.
An application fee and an initial payment are due at filing, unless you qualify for the Low-Income Certification, in which case you send no payment. Make the application fee and the initial payment separately. Pay electronically through the Electronic Federal Tax Payment System (EFTPS) or, for individuals, IOLA; if you cannot, attach a personal check, cashier's check or money order payable to "United States Treasury" to the front of the form. Pay in U.S. dollars and never send cash. Do not combine the fee with other tax payments. Electronic payments must be made on the day you mail or file the offer. The IRS returns an offer that arrives without the fee and required payment, or whose payment is returned for insufficient funds. For the fee amount, see Form 656-B or the IRS offer in compromise page.
FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Using this form-only version as an individual instead of Form 656-B; the printed warning says individuals must use the booklet.
- Completing both Section 1 and Section 2; the form says to complete one or the other, not both.
- Checking more than one box in Section 3 or more than one payment option in Section 4; each asks for only one.
- Sending a payment with an offer when you certified low income; those payments are generally not returned and are applied to the tax debt.
- Combining the application fee with the initial offer payment or with other tax payments; the form says to pay them separately and not to mix them with other taxes.
- Enclosing original tax returns, or leaving out the required returns, instead of marked copies of returns filed within 10 weeks.
- Filing an amended return for a tax year in the offer while it is pending; the form treats this as possible grounds for termination.
- Entering an offer of zero or an amount with cents; it must be more than zero and in whole dollars only.
- Omitting the signatures, or the current tax year on an attached Form 2848 or Form 8821.
Frequently asked questions
What is Form 656 (sp)?
Form 656 (sp), Offer in Compromise (Spanish Version), is the Spanish edition of the IRS form used to propose settling tax debt for less than the full amount owed. This form-only version is intended for tax professionals; individuals use Form 656-B.
Can an individual use Form 656 (sp) to apply for an offer in compromise?
The form says it is not a standalone form and is for tax professionals only. Individuals who want an offer considered must use Form 656-B, the IRS information booklet, which includes Form 656 and the Form 433-A (OIC) and 433-B (OIC) financial statements.
Is there a fee to submit an offer in compromise?
Yes, an application fee and an initial payment are due when you file, unless you qualify for the Low-Income Certification, in which case you send no payment. The amount is not repeated here; check Form 656-B or the IRS offer in compromise page.
How do I pay with Form 656 (sp)?
Pay the application fee and the initial payment separately, electronically through EFTPS (individuals may also use IOLA). Otherwise attach a personal check, cashier's check or money order payable to "United States Treasury" to the front of the form, in U.S. dollars. Do not send cash.
How long does the IRS have to decide on my offer?
The form says the offer is accepted by law unless the IRS notifies you otherwise in writing within 24 months of the date its centralized offer unit received it. The clock does not start until the correct site receives the offer, and disputed tax debts are not counted.
Can I fill out Form 656 (sp) online?
Yes. You can fill out the fillable PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not submit offers to the IRS; individuals can file through IOLA, or you can mail the offer.
Can I file an amended return while my offer is pending?
No. Under Section 7(e), you agree not to file an amended return for the tax years in the offer once it is submitted, and doing so could be grounds for termination. Refunds received before acceptance must be returned within 30 days.
What is the difference between Form 656 (sp) and Form 656-B?
Form 656-B is the IRS booklet with instructions that includes Form 656 and the Form 433-A (OIC) and 433-B (OIC) financial statements, and individuals must use it. Form 656 (sp) is the Spanish form-only edition for tax professionals.
Ready to fill out 656 (sp)?
Fill out 656 (sp) now