
Form 673 is the statement a U.S. citizen completes and gives to a U.S. employer so the employer can exclude all or part of wages for services performed outside the United States from income tax withholding. The Internal Revenue Service (IRS) publishes it for people who expect to qualify for the foreign earned income exclusion, the foreign housing exclusion, or both. On this page you can fill out the form online on FillingPDF and download or print the completed PDF; the IRS publishes the original form and its latest information at www.irs.gov/Form673.
Last updated
What is Form 673?
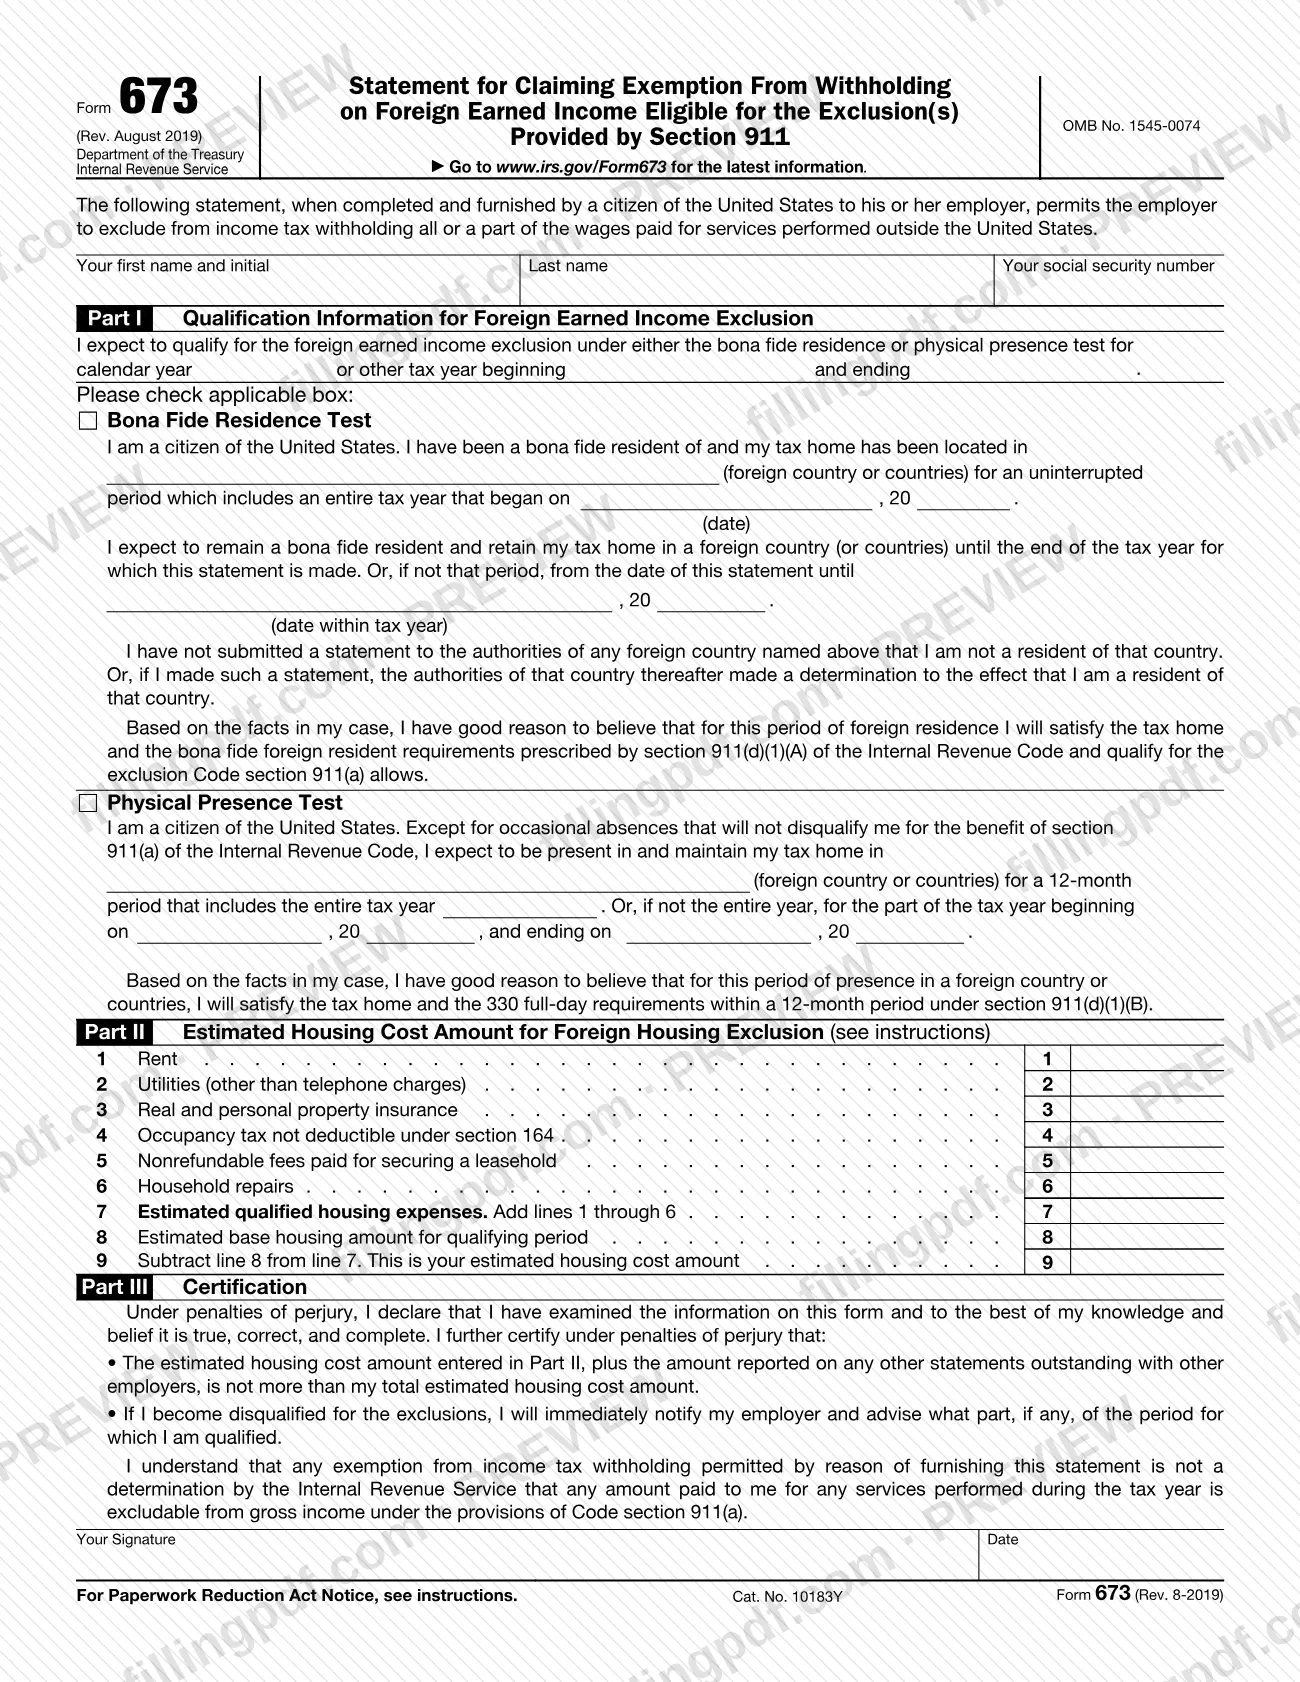
Form 673, Statement for Claiming Exemption from Withholding on Foreign Earned Income Eligible for the Exclusion(s) Provided by Section 911, is the Internal Revenue Service (IRS) statement a U.S. citizen furnishes to an employer so the employer may exclude wages for services performed outside the United States from income tax withholding.
The form has three parts. Part I states that you expect to qualify for the foreign earned income exclusion under either the bona fide residence test or the physical presence test for a calendar year or other tax year. Part II estimates your housing cost amount for the foreign housing exclusion, on lines 1 through 9. Part III is your certification under penalties of perjury, with signature and date.
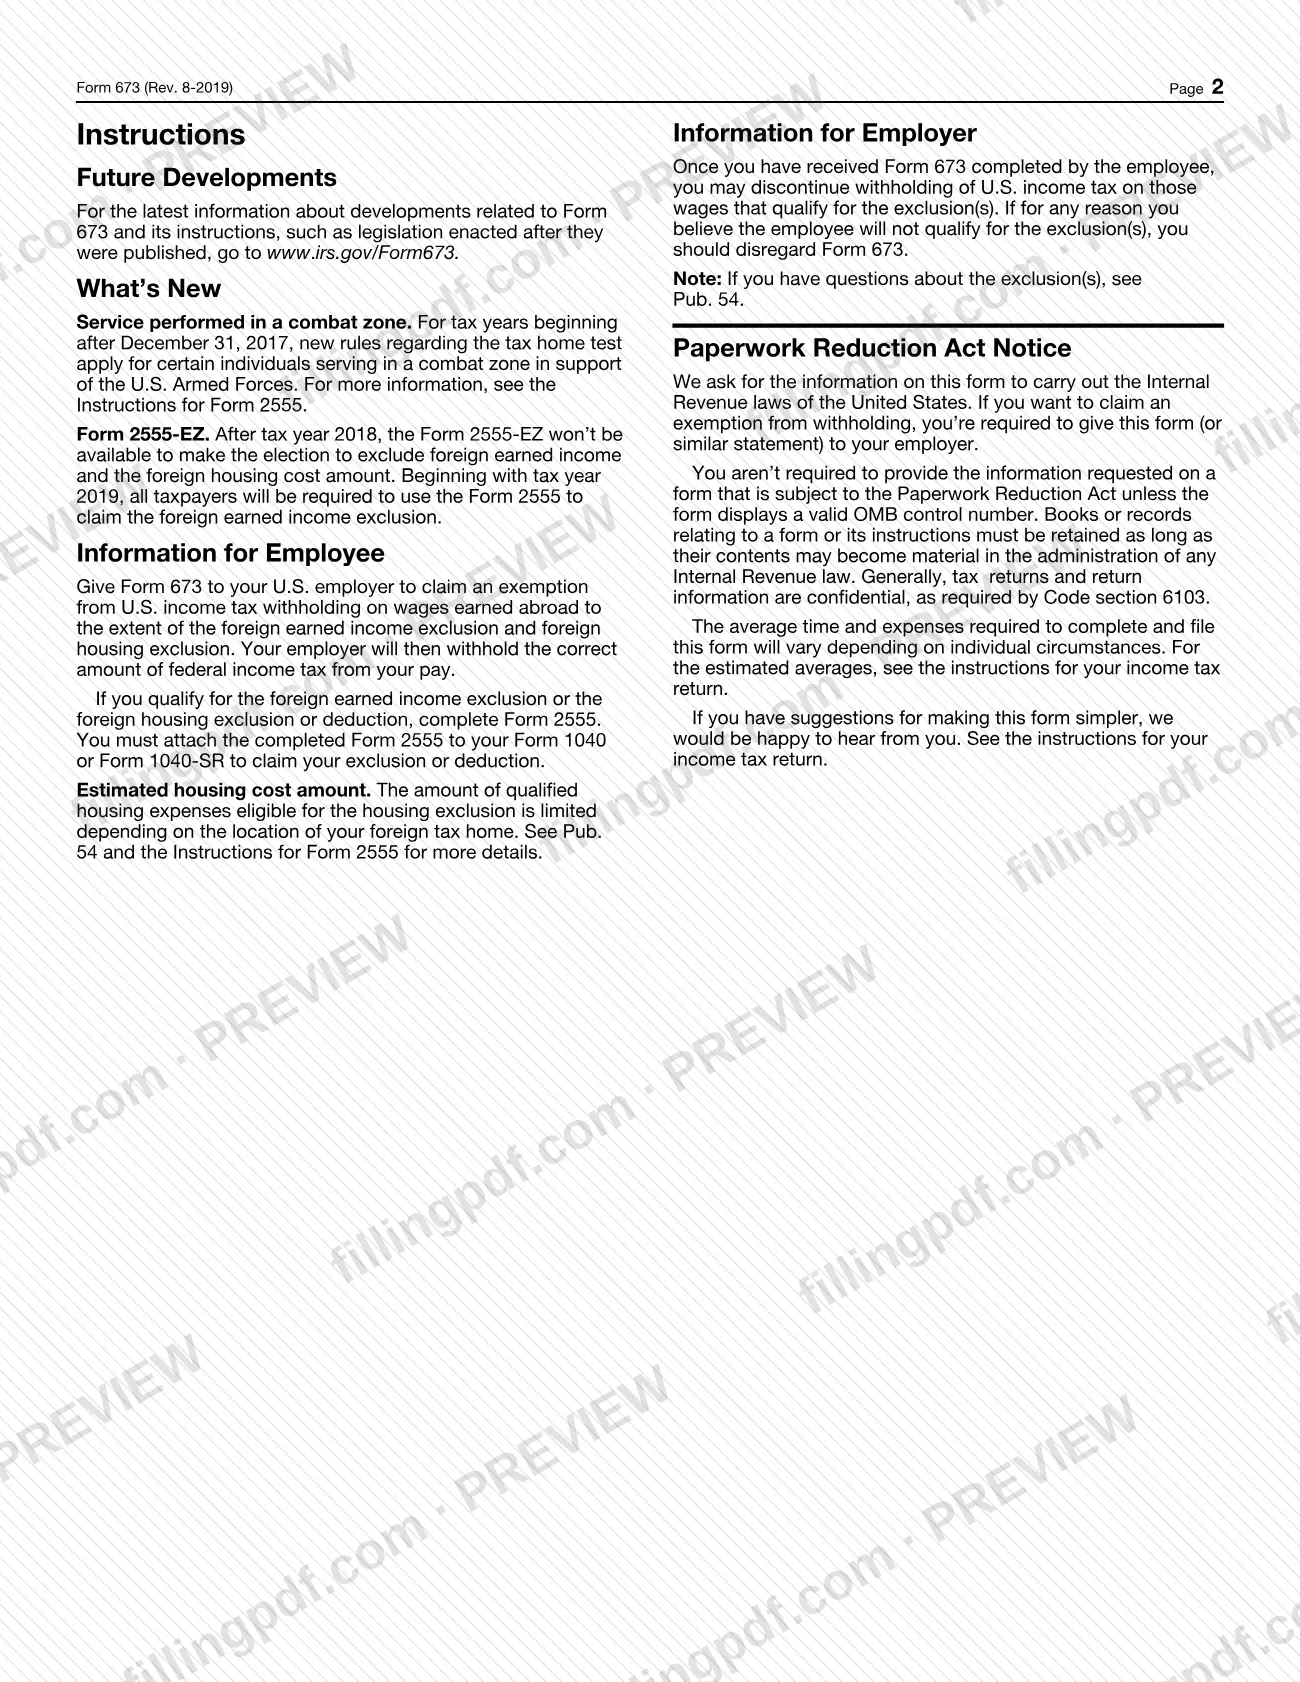
The employer keeps the form. Once the employer receives it completed, the employer may stop withholding U.S. income tax on the wages that qualify for the exclusion(s). The IRS instructions on the form add that the employer should disregard it if for any reason the employer believes the employee will not qualify.
The exemption is not a determination by the IRS that any amount is excludable from gross income under Code section 911(a). To claim the exclusion or deduction itself, you complete Form 2555 and attach it to your Form 1040 or Form 1040-SR. Form 673 is not that claim. The form's instructions point to Pub. 54 for questions about the exclusions.
Who needs to file Form 673?
A citizen of the United States who works for a U.S. employer outside the United States and expects to qualify for the foreign earned income exclusion, the foreign housing exclusion, or both, completes Form 673 and gives it to that employer to claim an exemption from U.S. income tax withholding.
The form recognizes two ways to qualify:
- Bona Fide Residence Test: you expect to be a bona fide resident of a foreign country (or countries), with your tax home there, for an uninterrupted period that includes an entire tax year.
- Physical Presence Test: you expect to be present in a foreign country (or countries) and keep your tax home there for a 12-month period that includes the entire tax year, or for part of the tax year, meeting the 330 full-day requirement within a 12-month period.
Complete Part II only if you are estimating a housing cost amount for the foreign housing exclusion.
Employers use the form on the other side of the exchange: once they receive it completed, they may stop withholding on wages that qualify, and they should disregard it if they believe the employee will not qualify. The form is written for U.S. citizens, so it does not cover people who are not citizens.
When to file Form 673
Give Form 673 to your employer when you expect to qualify for the exclusion(s) for a tax year and want withholding on qualifying foreign wages to stop. Part I asks for the calendar year or other tax year, with its beginning and ending dates, and the form has no separate due date printed on it.
Timing also depends on your situation. If you do not expect to remain a bona fide resident until the end of the tax year, the form lets you name a date within the tax year as the end of the period. Under the physical presence test, you can enter the part of the tax year that applies instead of the entire year.
If you become disqualified for the exclusions, the certification in Part III requires you to notify your employer immediately and say what part, if any, of the period you are qualified. The IRS page for the form lists no recent developments at this time.
How to fill out Form 673
Enter your name and Social Security number
At the top, write your first name and initial, your last name and your social security number.
State the tax year in Part I
Enter the calendar year or other tax year for which you expect to qualify, with its beginning and ending dates.
Check the test you expect to meet
Check either Bona Fide Residence Test or Physical Presence Test, then complete only the statements under the box you checked.
Complete the bona fide residence statements
Enter the foreign country or countries where you are a bona fide resident and keep your tax home, and the date the tax year began. Then give the date within the tax year until which you expect to remain, if the period is shorter than the tax year.
Complete the physical presence statements
Enter the foreign country or countries where you expect to be present and maintain your tax home. Choose the entire tax year or enter the start and end dates of the part of the year that applies.
Enter housing expenses on lines 1 to 6
In Part II, enter estimated rent (line 1), utilities other than telephone charges (line 2), insurance (line 3), occupancy tax not deductible under section 164 (line 4), nonrefundable leasehold fees (line 5) and household repairs (line 6). Skip Part II if you are not estimating a housing cost amount.
Total your housing expenses on line 7
Add lines 1 through 6 and enter the estimated qualified housing expenses on line 7.
Figure the housing cost amount
Enter the estimated base housing amount for the qualifying period on line 8. Subtract line 8 from line 7 and enter the result on line 9 as your estimated housing cost amount.
Read the Part III certification
Check that your housing amount plus any outstanding statements with other employers is not more than your total estimated housing cost amount, and that you will notify your employer if you become disqualified.
Sign and date the form
Sign and date Part III. The declaration is made under penalties of perjury.
Review, download and give it to your employer
Check each entry against the tax year and test you chose, then download or print the completed PDF from FillingPDF and give it to your employer as described under How to submit.
How to submit Form 673
Form 673 goes to your U.S. employer, not to the IRS. The form's instructions say you give it to your employer to claim an exemption from U.S. income tax withholding on wages earned abroad, up to the foreign earned income exclusion and foreign housing exclusion.
- To your employer: hand or send the signed, completed form to your U.S. employer. The employer then decides whether to stop withholding on the wages that qualify.
- With your tax return: Form 673 is not attached to your return. To claim the exclusion or deduction, complete Form 2555 and attach it to your Form 1040 or Form 1040-SR.
The form prints no mailing address, portal or fee, and no IRS address for this statement. If your situation changes and you become disqualified, tell your employer right away, as Part III requires. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Checking both the Bona Fide Residence Test and the Physical Presence Test; the form asks you to check the applicable box for the test you expect to meet.
- Leaving the tax year dates blank in Part I, where you must enter the calendar year or other tax year with its beginning and ending dates.
- Signing without confirming the Part III certification: the housing amount plus any other outstanding statements with other employers must not exceed your total estimated housing cost amount.
- Entering Part II amounts without subtracting line 8 (estimated base housing amount) from line 7 to get the estimated housing cost amount on line 9.
- Treating Form 673 as the claim for the exclusion; you must still complete Form 2555 and attach it to Form 1040 or Form 1040-SR.
- Not telling your employer right away after becoming disqualified for the exclusions, as the Part III certification requires.
- Submitting the form without a signature and date, since Part III is a declaration under penalties of perjury.
- Entering utilities that are telephone charges on line 2; the form excludes telephone charges from utilities.
Frequently asked questions
What is Form 673 used for?
Form 673 is the IRS statement a U.S. citizen gives to an employer to claim an exemption from U.S. income tax withholding on wages for services performed abroad, to the extent of the foreign earned income exclusion and foreign housing exclusion.
Do I send Form 673 to the IRS?
No. The form's instructions say you give Form 673 to your U.S. employer. The employer may then stop withholding on the wages that qualify. The form prints no IRS address for it and is not attached to your tax return.
What is the difference between Form 673 and Form 2555?
Form 673 asks your employer to stop withholding during the year. Form 2555 is the form you complete to claim the foreign earned income exclusion or housing exclusion, and you attach it to your Form 1040 or Form 1040-SR.
Which test should I check on Form 673?
Check the Bona Fide Residence Test if you expect to be a bona fide foreign resident with your tax home abroad for a period that includes an entire tax year. Check the Physical Presence Test if you expect to meet the 330 full-day requirement within a 12-month period.
Does Form 673 guarantee that my foreign wages are excluded?
No. Part III states that the exemption from withholding is not an IRS determination that any amount is excludable from gross income under Code section 911(a). Your employer may also disregard the form if it believes you will not qualify.
What if I stop qualifying for the exclusion?
Notify your employer immediately. In Part III you certify that if you become disqualified for the exclusions, you will tell your employer right away and say what part, if any, of the period you are qualified.
Do I have to fill in Part II of Form 673?
Part II is the estimated housing cost amount for the foreign housing exclusion. Complete it if you are estimating that amount; it runs from rent on line 1 to your estimated housing cost amount on line 9.
Can I fill out Form 673 online?
You can fill out the Form 673 PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not send it to your employer or the IRS; you give the completed form to your employer yourself.
Ready to fill out Form 673?
Fill out Form 673 now