
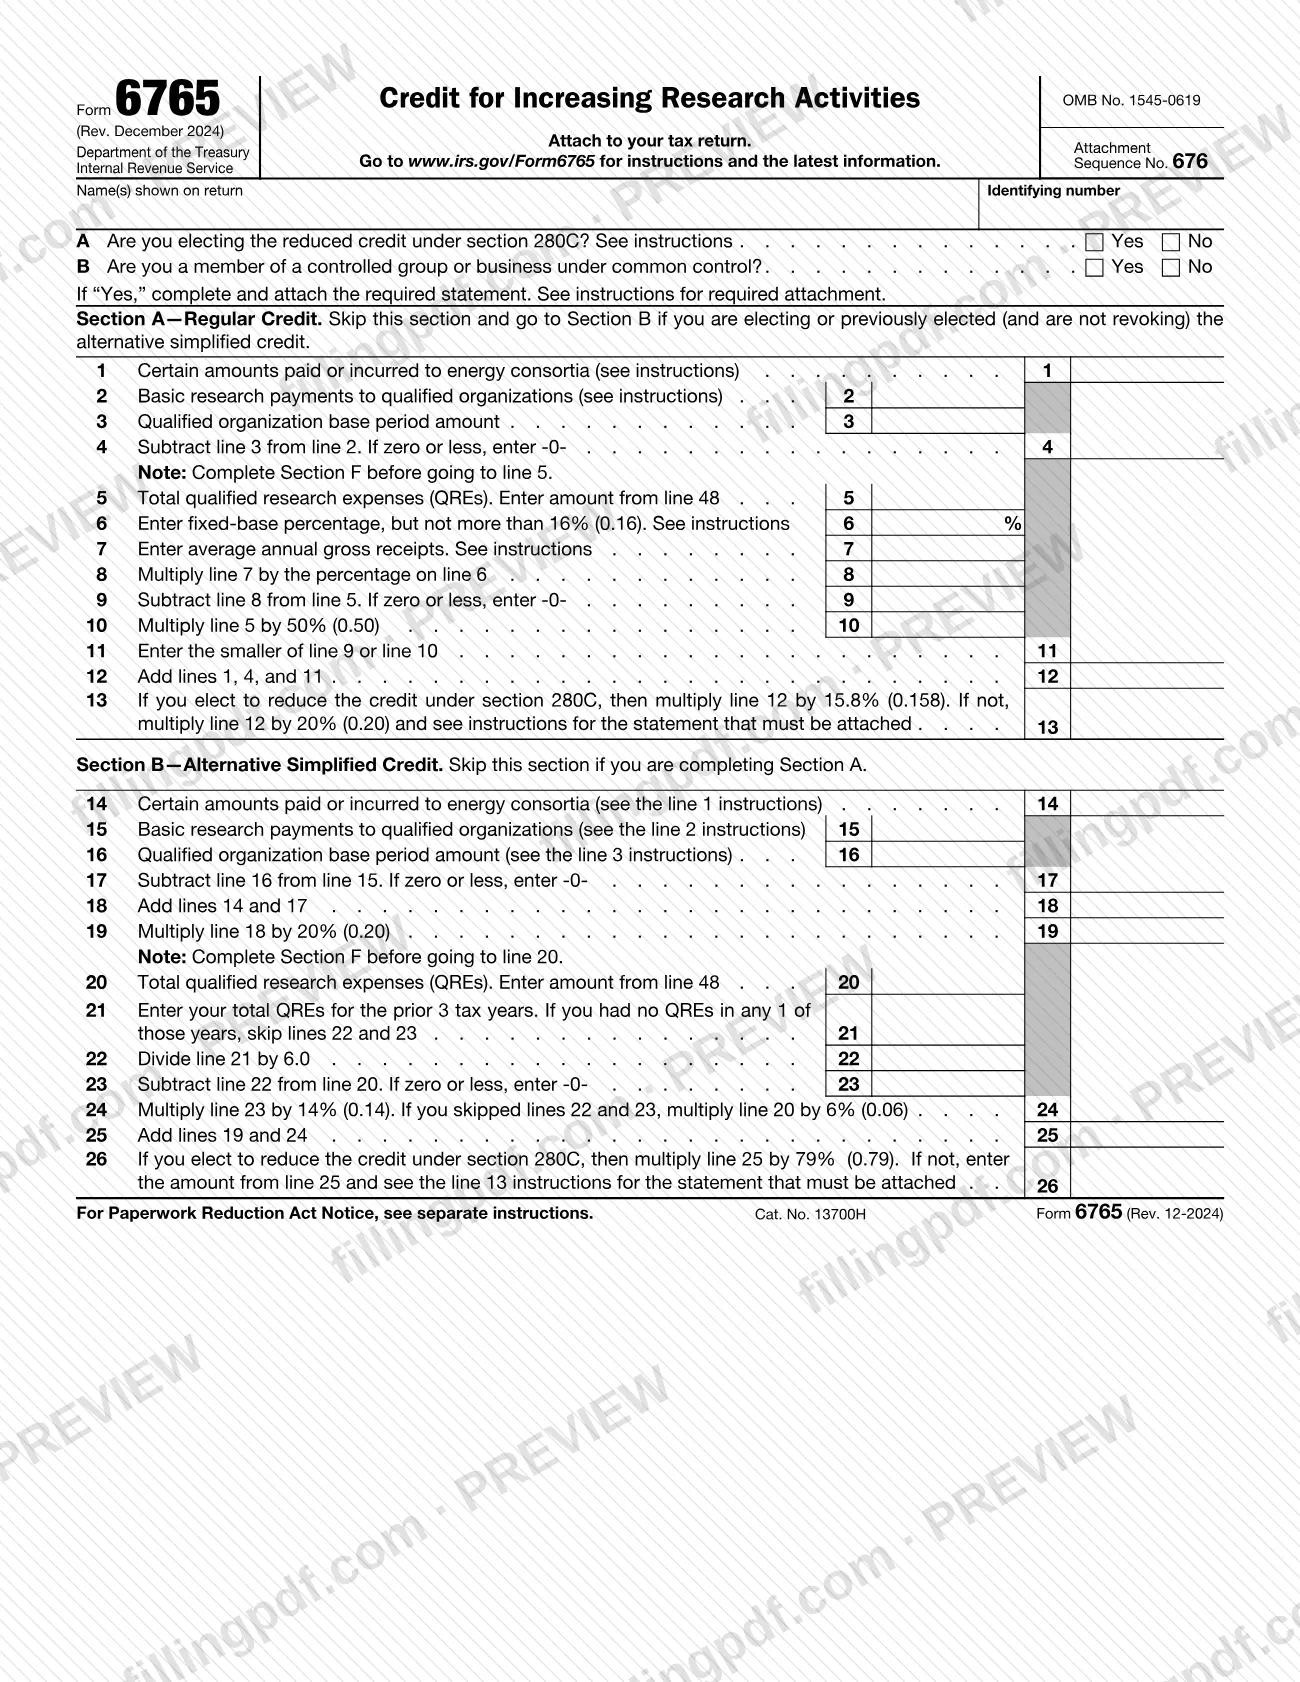
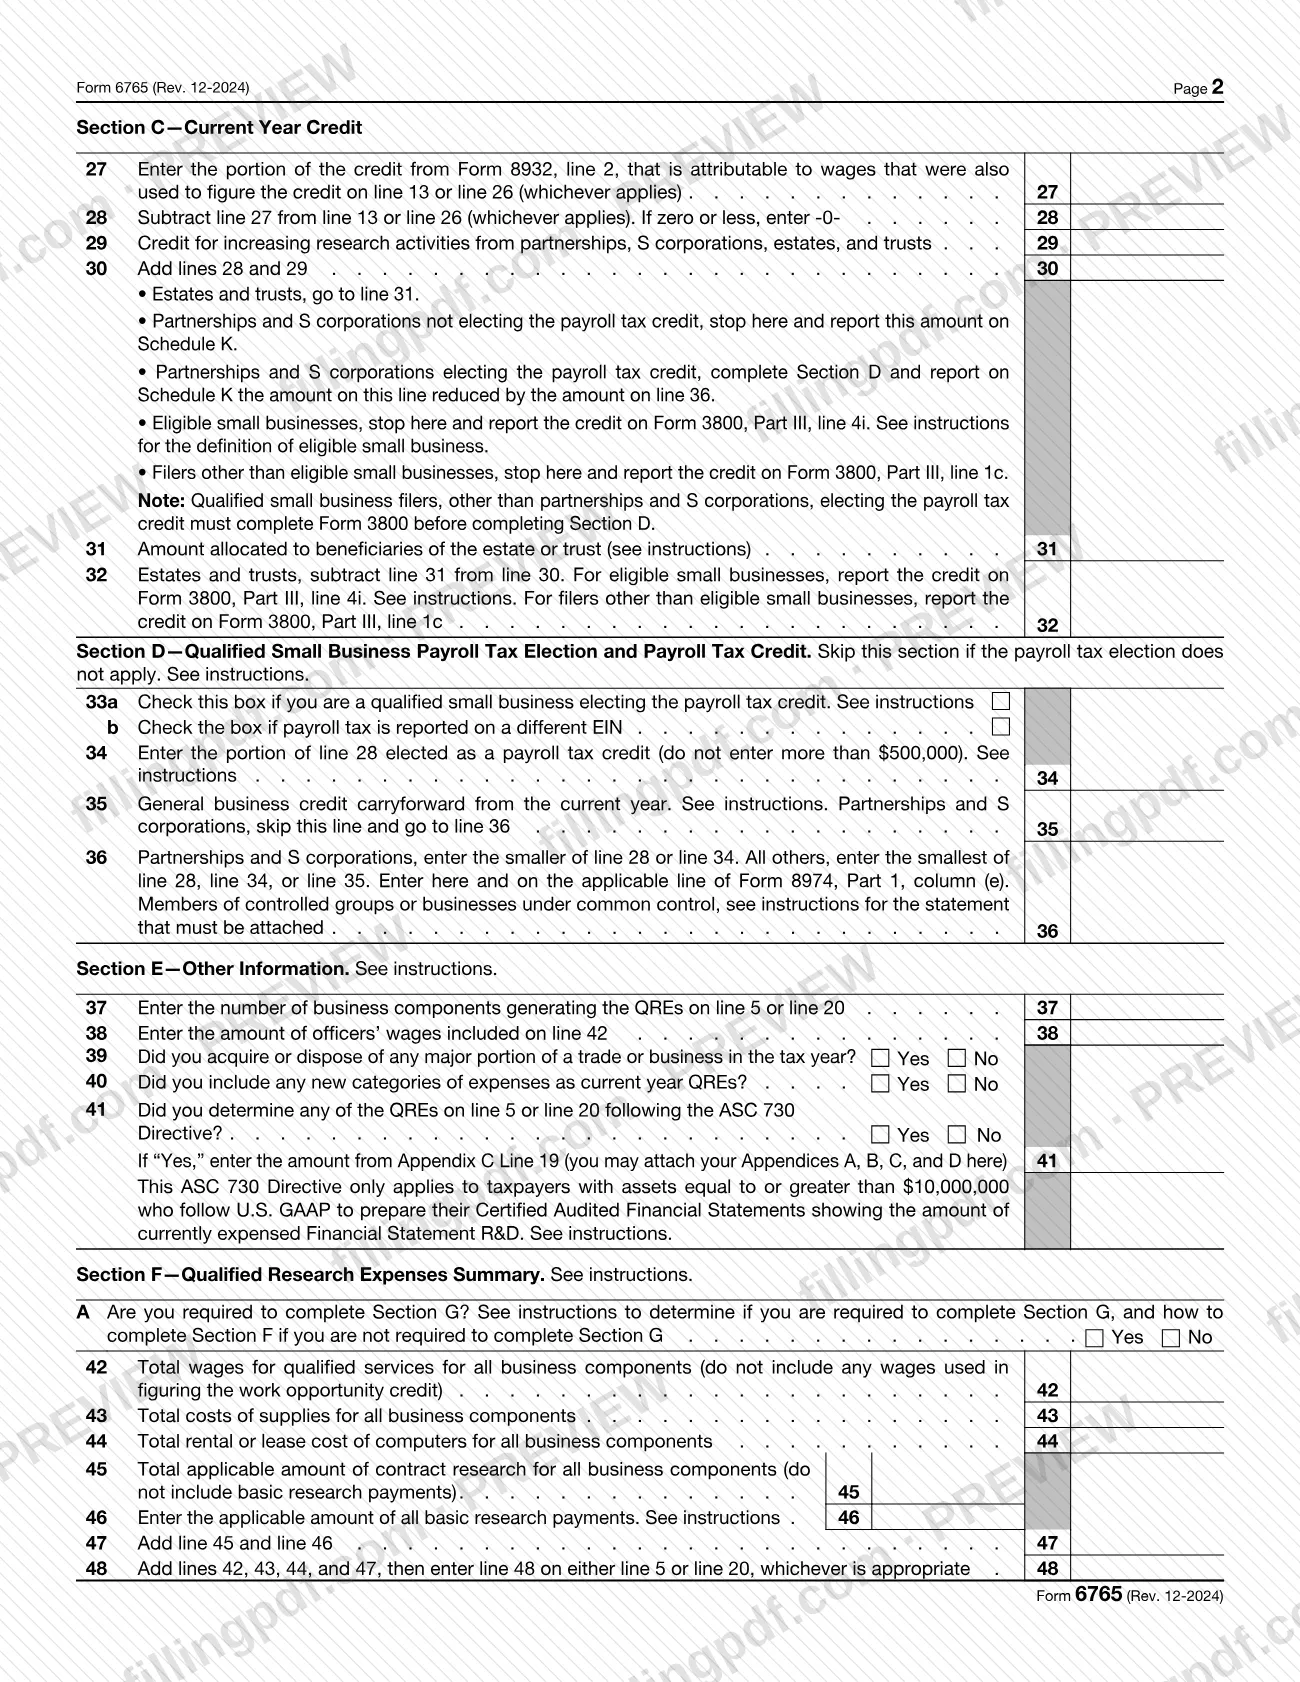
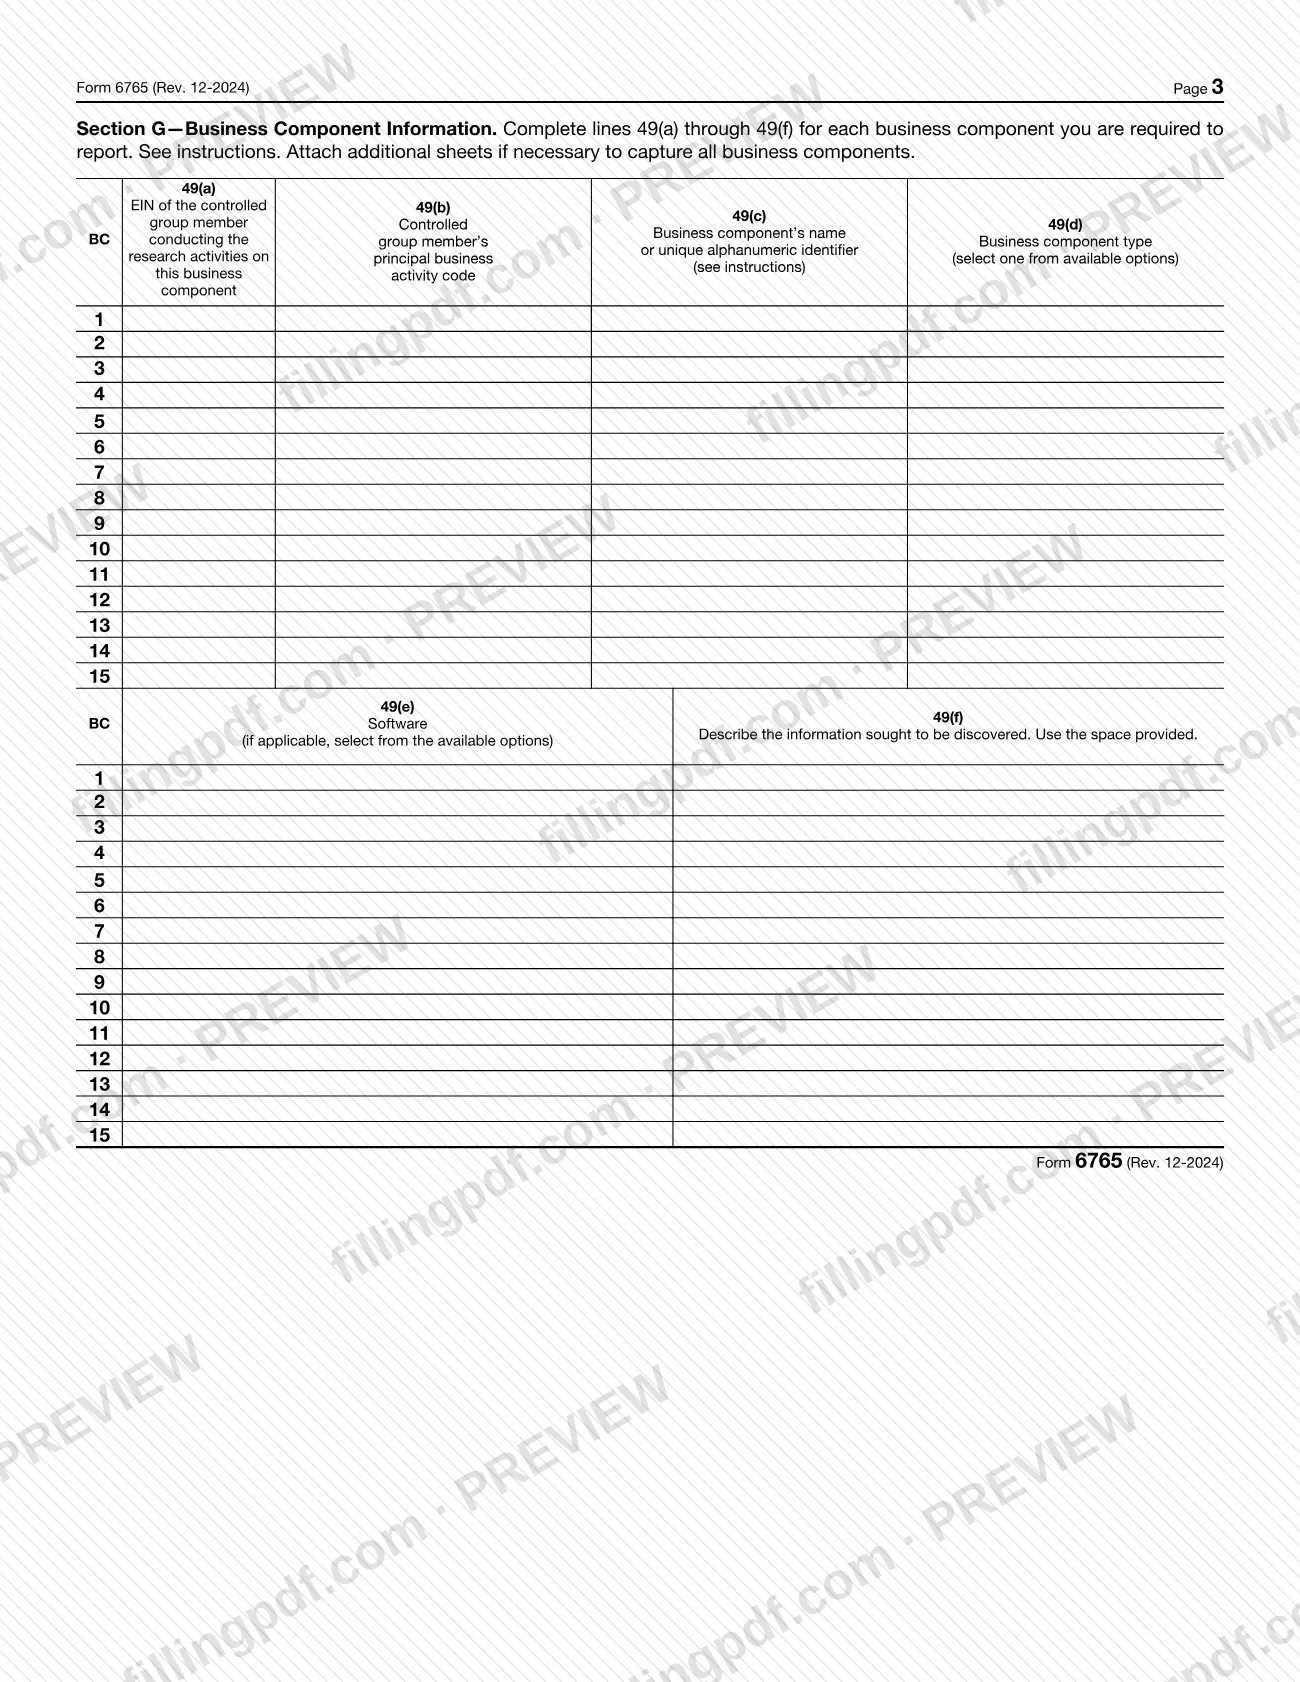
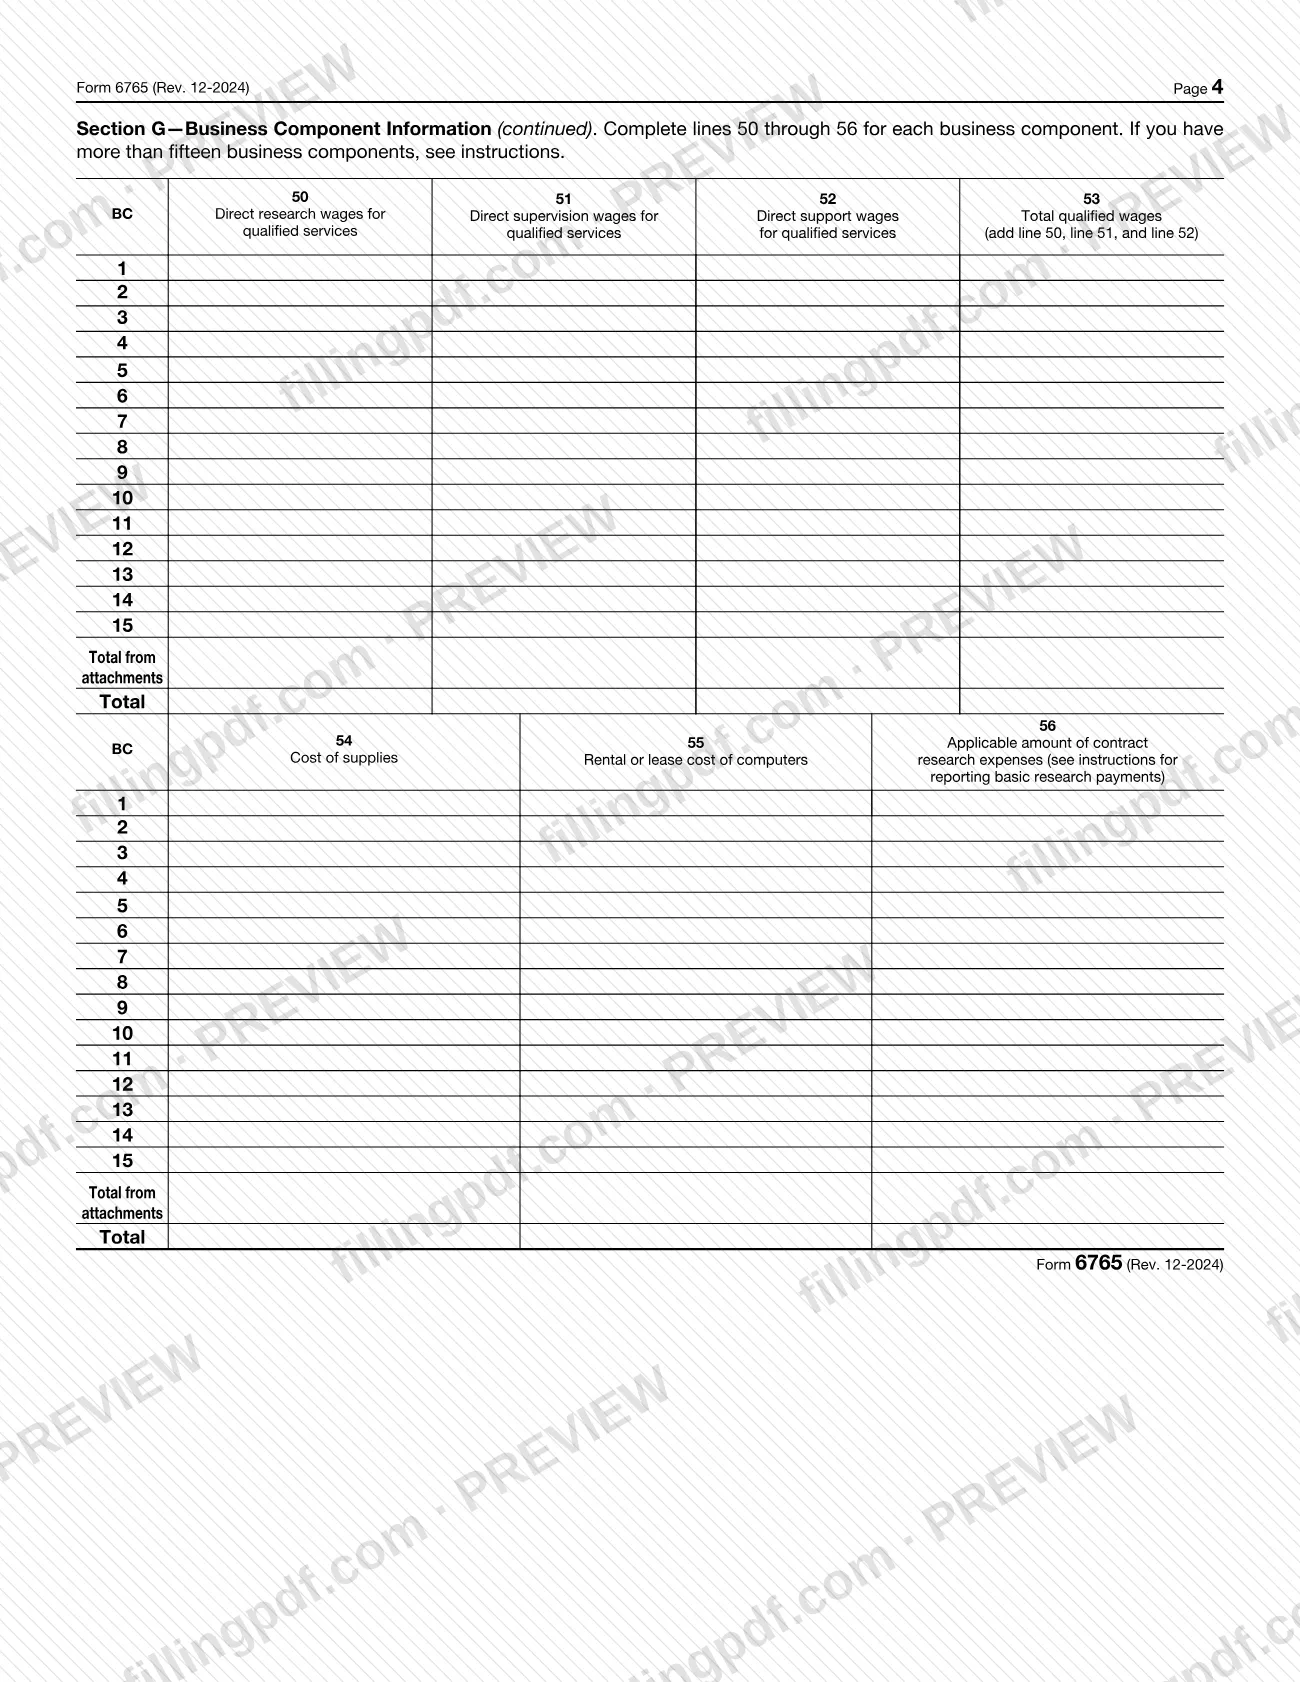
Form 6765, Credit for Increasing Research Activities, is the Internal Revenue Service (IRS) form that figures the research credit, records the section 280C reduced credit election and lets a qualified small business elect the payroll tax credit. You attach it to your income tax return, and partnerships and S corporations must file it to claim the credit. On this page you can fill out Form 6765 online on FillingPDF and download or print the completed PDF; the IRS publishes the form and its instructions at www.irs.gov/Form6765.
Last updated
What is 6765?
Form 6765, Credit for Increasing Research Activities, is the Internal Revenue Service (IRS) form used to figure and claim the credit for increasing research activities, to elect the reduced credit under section 280C, and to elect to treat part of the credit as a payroll tax credit against the employer portion of social security taxes.
The form is attached to your tax return (OMB No. 1545-0619, Attachment Sequence No. 676). It is built in sections:
- Items A and B: the section 280C election and the controlled group question.
- Section A: the regular credit.
- Section B: the alternative simplified credit (ASC). You complete either Section A or Section B, not both.
- Section C: the current year credit, including amounts from partnerships, S corporations, estates and trusts.
- Section D: the qualified small business payroll tax election.
- Section E: other information about the qualified research expenses (QREs).
- Section F: the QREs summary, which ends on line 48.
- Section G: business component information, reported for up to 50 business components.
The IRS instructions explain that qualified research generally has to pass a four-part test applied separately to each business component. Research is not credited in situations such as research conducted after commercial production begins or outside the United States. Clinical testing costs for certain rare-disease drugs can instead be claimed on Form 8820, Orphan Drug Credit. The credit is then carried to Form 3800, General Business Credit; the payroll tax portion is carried to Form 8974.
Who needs to file 6765?
Partnerships and S corporations must file Form 6765 to claim the credit for increasing research activities. Other taxpayers who figure their own credit use it too, and so does any qualified small business that elects the payroll tax credit.
The IRS instructions set these conditions:
- Pass-through credit only: taxpayers other than partnerships and S corporations are generally not required to complete or file the form if their only source of the credit is a partnership, S corporation, estate or trust. They report the credit directly on Form 3800.
- Estates and trusts: a credit can be allocated to beneficiaries on line 31.
- Section 280C election: anyone electing the reduced credit must complete Form 6765 with the original timely filed return, even if no credit is claimed on it.
- Controlled groups: members of a controlled group or businesses under common control answer Yes on Item B and attach the required statement. They are treated as a single taxpayer to figure the credit.
- Payroll tax election: only a qualified small business, defined in the instructions as a corporation (including an S corporation) or partnership that meets the gross receipts tests. A tax-exempt organization under section 501 does not qualify.
Section G is required unless you are a qualified small business that checked the box for the payroll tax credit, or you meet the QRE and gross receipts limits set out in the instructions and report a credit on an original return.
When to file 6765
File Form 6765 with the tax return that claims the credit; the form says to attach it to your tax return. The IRS instructions tie several elections to that original filing:
- The Item A section 280C election must be made on your original timely filed return, including extensions. It cannot be made or changed on an amended return and is irrevocable for that tax year.
- The alternative simplified credit is elected by completing Section B and attaching the form to your timely filed original return, including extensions. No extension of time to make the election is granted.
- The payroll tax election must be made on or before the due date of the originally filed return, including extensions. It cannot be made for a tax year if it was made for 5 or more preceding tax years.
For tax years beginning before 2026, Section G is optional for all filers. It is required for tax years beginning after 2025, subject to the exceptions in the instructions. On an amended return that claims a new or increased research credit, column 49(f) and additional claim information are required.
Documents you need
- Your income tax return: Form 6765 is attached to it, as the form states.
- Statement for a controlled group or business under common control, required if you answer Yes on Item B; it lists the entity, QRE and credit items named in the instructions.
- Statement listing the deductions or capitalized expenses that were reduced, required if you do not elect the reduced credit under section 280C.
- Form 3800, General Business Credit, where you carry the credit; a qualified small business other than a partnership or S corporation completes it before Section D.
- Form 8974, for a qualified small business claiming the payroll tax credit; it is attached to the employment tax return.
- Additional sheets of Section G, if you do not e-file and report more than 15 business components.
- Statistical sampling plan, if you used statistical sampling under Rev. Proc. 2011-42 to determine QREs.
- Claim information and, if you submit one, a credit study with the exact pages identified, for an amended return or AAR claiming a new or increased research credit.
- Form 8582-CR results, for an estate or trust subject to the passive activity rules that must allocate the allowed credit to beneficiaries.
How to fill out 6765
Enter your name, number and Items A–B
At the top, enter the name(s) shown on your return and your identifying number. Check Yes or No for Item A (section 280C reduced credit election) and for Item B (controlled group or common control); if Item B is Yes, prepare the required statement.
Complete Section G first if required
Section G, lines 49(a) through 56, is completed before Section F unless you are not required to complete it. List business components in descending order of QREs, up to 50 and covering at least 80% of total QREs, and enter "Aggregate Business Components" in column 49(c) for the rest.
Complete the Section F QREs summary
Answer the question at the top of Section F, then enter wages on line 42, supplies on line 43, computer rental or lease cost on line 44, contract research on line 45 and basic research payments on line 46. Add lines 45 and 46 on line 47 and lines 42, 43, 44 and 47 on line 48.
Choose Section A or Section B
Complete Section A (regular credit) or Section B (alternative simplified credit), not both. Skip Section A if you are electing, or previously elected and are not revoking, the alternative simplified credit.
Figure the regular credit in Section A
Enter energy consortia and basic research amounts on lines 1 to 3 and subtract on line 4. Enter line 48 on line 5, the fixed-base percentage on line 6 and average annual gross receipts on line 7, then follow lines 8 to 12. On line 13, apply the factor the form gives depending on whether you elected the section 280C reduced credit.
Figure the alternative simplified credit
Complete lines 14 to 19, enter line 48 on line 20, and enter your QREs for the prior 3 tax years on line 21. Skip lines 22 and 23 if you had no QREs in any one of those years, then follow lines 24 to 26.
Complete Section C current year credit
On line 27 enter any Form 8932 wage portion. Subtract it on line 28, add credits from partnerships, S corporations, estates and trusts on line 29, and total on line 30. Estates and trusts continue to lines 31 and 32; the form says where each other filer reports the result.
Complete Section D only for the payroll election
Skip Section D if the payroll tax election does not apply. Otherwise check line 33a, check 33b if payroll tax is reported on a different EIN, and enter the elected amount on line 34 within the limit printed there. Enter the general business credit carryforward on line 35 and the line 36 amount, which also goes on Form 8974, Part 1, column (e).
Complete Section E other information
Enter the number of business components on line 37 and officers' wages included in line 42 on line 38. Check Yes or No on lines 39 and 40, and on line 41 if you follow the ASC 730 Directive, enter the Appendix C line 19 amount.
Review, sign off and download the PDF
Check that Section F totals carry to line 5 or line 20, that every question is answered, and that the required statements are ready. Download or print the completed PDF from FillingPDF and attach it to your tax return as described under How to submit.
How to submit 6765
Form 6765 is not sent on its own: you attach it to your tax return and submit that return, either e-filed or on paper, through the IRS channels for that return. The form prints no separate mailing address.
- E-file: the instructions give file names for attachments, for example "Form6765ItemASection280C.pdf" for the section 280C statement and "Form6765ItemBGroupCredit.pdf" for the controlled group statement. Other names include "Form6765StatSamplePlan.pdf" (statistical sampling plan), "Form6765ClaimInformation.pdf" and "Form6765Study.pdf" (amended return claims), and "Form6765ASC730AppendixA.pdf" through "Form6765ASC730AppendixD.pdf".
- Paper: if you have more than 15 business components and do not e-file, attach additional sheets of Section G and enter their sum on the "Total from Attachments" line.
- Payroll tax credit: a qualified small business also completes Form 8974 and attaches it to its employment tax return for the first quarter that begins after it files the return reflecting the election.
- Amended returns: corporations claiming a refund or credit of the research credit on an amended return should see Notice 2008-39 for where to file.
For the latest instructions, go to IRS.gov/Form6765. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Completing both Section A and Section B; the form says to skip Section B if you complete Section A, and to skip Section A if you elect the alternative simplified credit.
- Trying to make or change the section 280C election on an amended return; it must be made on the original timely filed return.
- Filling in line 5 or line 20 before completing Section F and, where required, Section G; the form tells you to complete Section F first.
- Answering Yes on Item B without attaching the required controlled group statement.
- Entering the combined group QREs instead of only your own on line 5 or line 20 when you are a controlled group member filing a separate return.
- Entering on line 34 more than the limit printed on that line for the payroll tax credit.
- Starting Section D before completing Form 3800 when you are a qualified small business other than a partnership or S corporation.
- Skipping Section E when you reported QREs on line 48.
- Listing business components in Section G in any order other than descending by total QREs, or leaving the remaining ones unreported instead of entering "Aggregate Business Components" in column 49(c).
- Including an amount from line 1 elsewhere on the return; the instructions say it cannot be used again.
Frequently asked questions
What is Form 6765 used for?
Form 6765 is used to figure and claim the credit for increasing research activities, to elect the reduced credit under section 280C, and to elect to claim part of the credit as a payroll tax credit against the employer portion of social security taxes. You attach it to your tax return.
Who has to file Form 6765?
Partnerships and S corporations must file it to claim the credit. Other taxpayers are generally not required to complete or file it if their only source of the credit is a partnership, S corporation, estate or trust; they report the credit directly on Form 3800.
What is the difference between Section A and Section B on Form 6765?
Section A figures the regular credit and Section B figures the alternative simplified credit (ASC). You complete one or the other. Once you elect the ASC, it applies to the current year and all later years, and the election for the current year cannot be revoked.
Can I fill out Form 6765 online?
Yes. You can fill out the PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file anything with the IRS; the form is submitted as an attachment to your tax return through the IRS channels.
Can I make the section 280C election on an amended return?
No. The instructions say the Item A election must be made on your original timely filed return, including extensions, and cannot be made or changed on an amended return. Once made, it is irrevocable for that tax year.
Is Section G of Form 6765 required?
For tax years beginning before 2026, Section G is optional for all filers. For tax years beginning after 2025 it is required, except for a qualified small business claiming the payroll tax credit and filers who meet the QRE and gross receipts limits in the instructions.
How do I claim the payroll tax credit on Form 6765?
A qualified small business completes Section D, checking line 33a and entering the elected amount on line 34. The election must be made on or before the due date of the original return, including extensions, and the credit is then claimed on Form 8974 with the employment tax return.
What do I attach to Form 6765 if I am in a controlled group?
If you answer Yes on Item B, attach the required group credit statement showing each member's QREs and credit. If you e-file, the instructions name it "Form6765ItemBGroupCredit.pdf". A member filing separately enters only its own QREs on line 5 or line 20.
Ready to fill out 6765?
Fill out 6765 now