
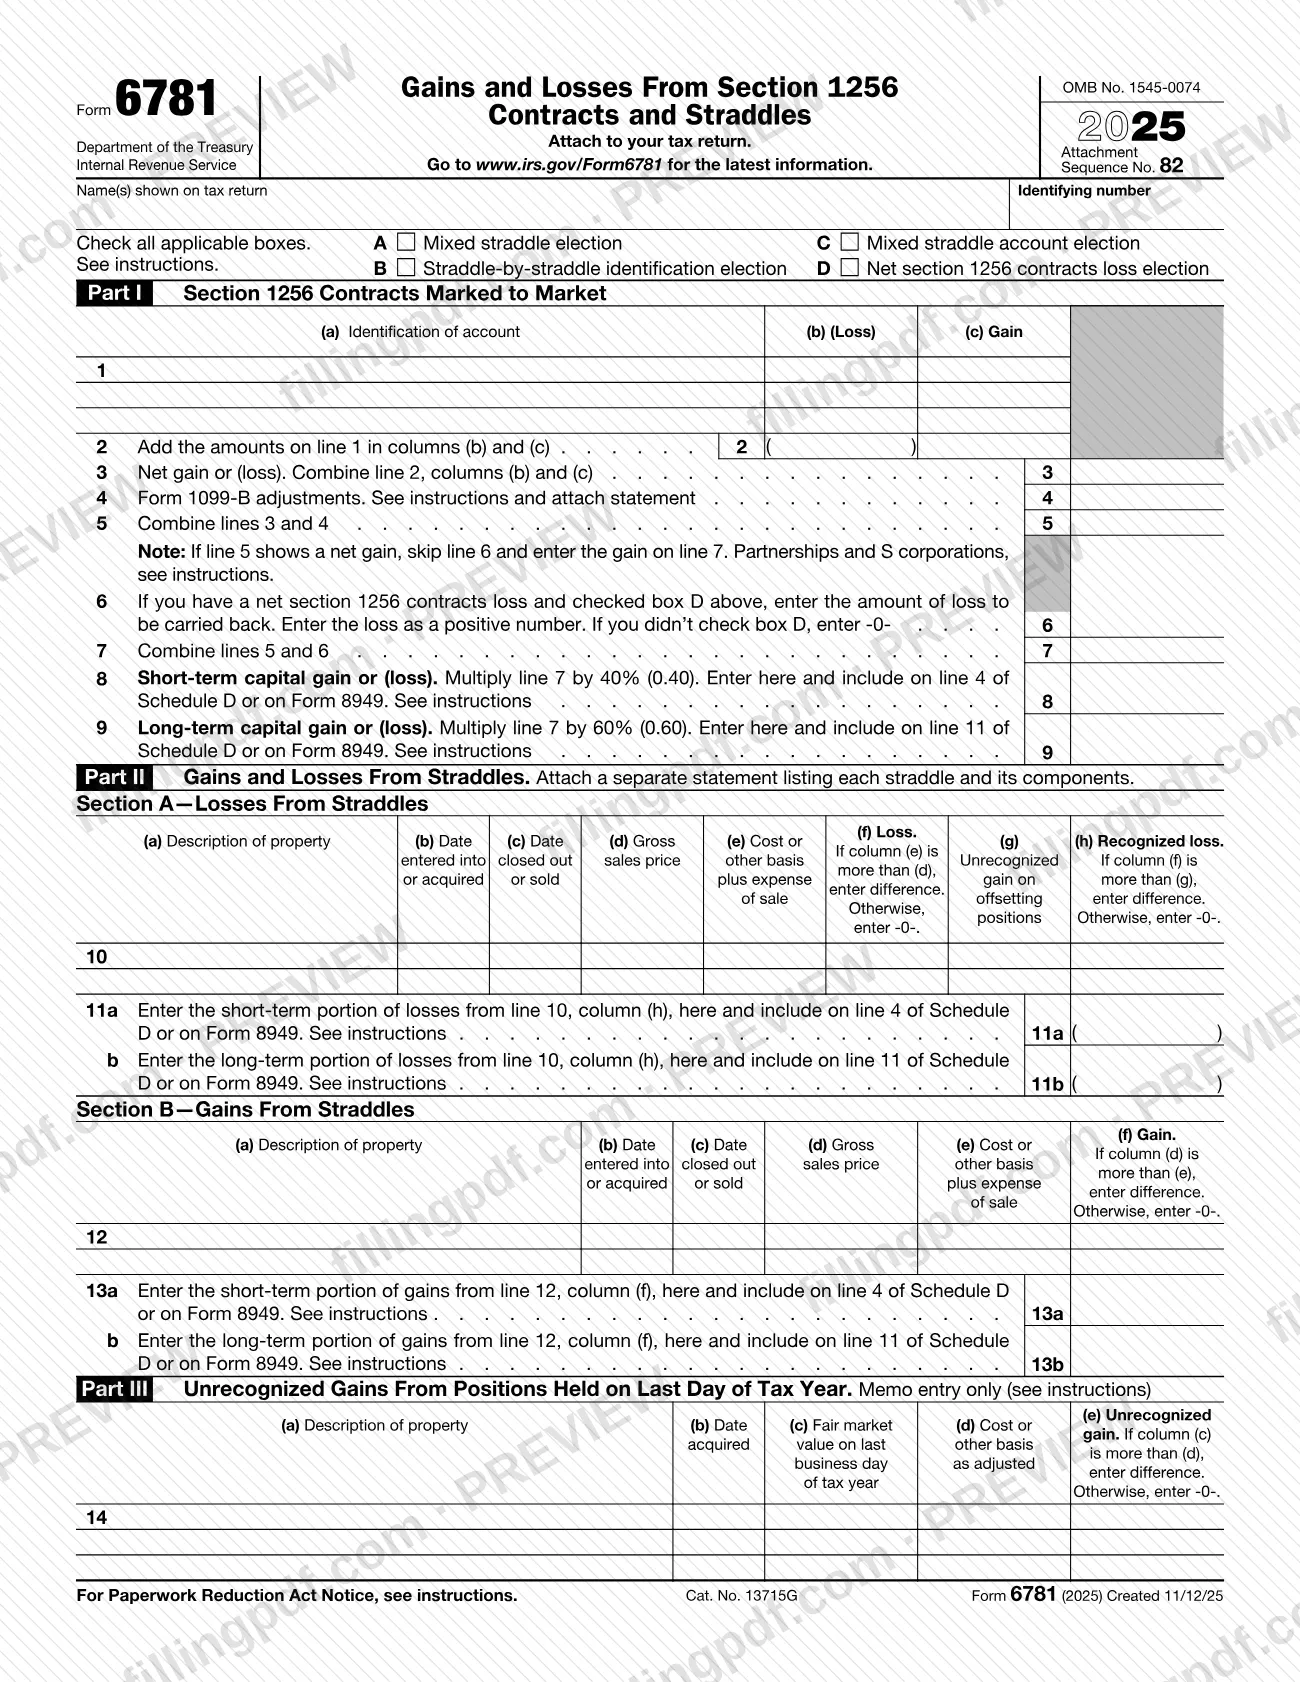
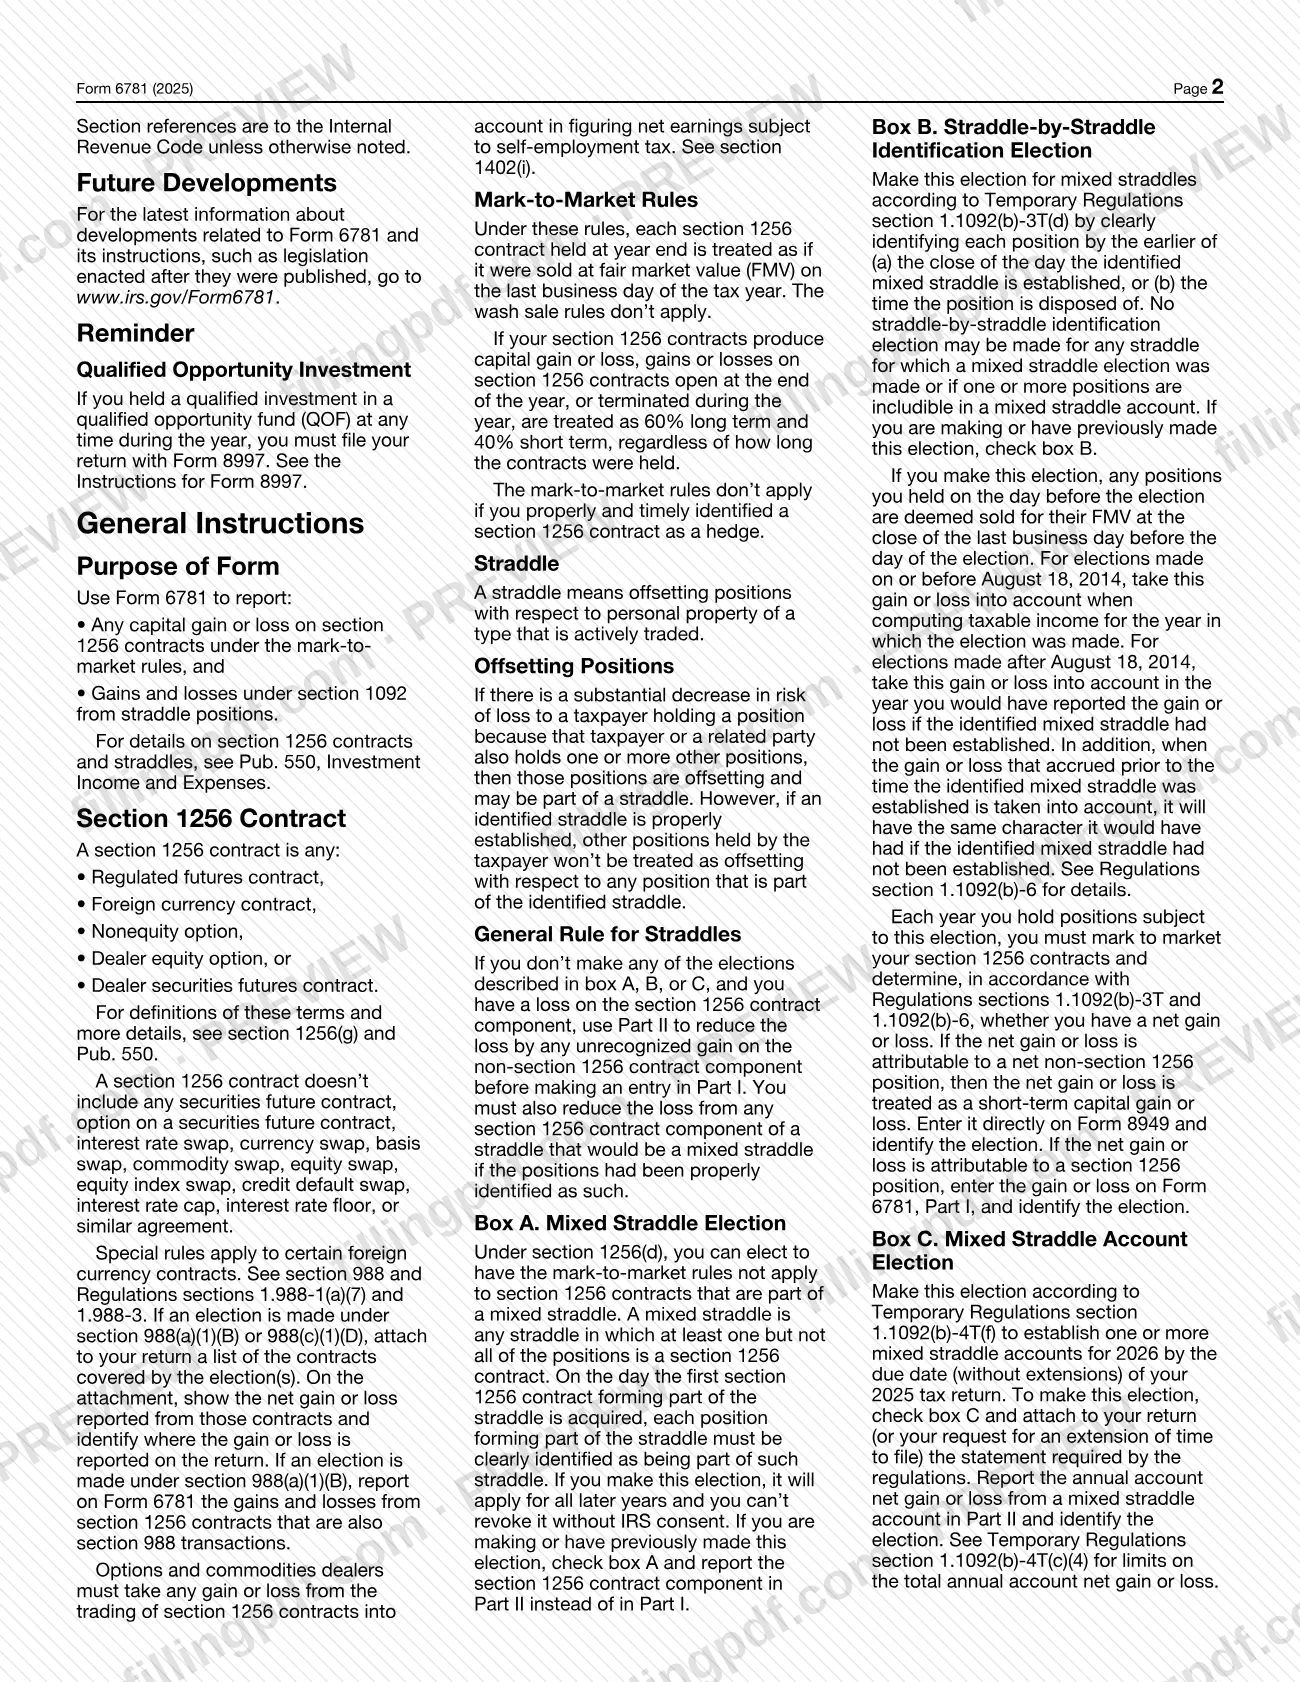
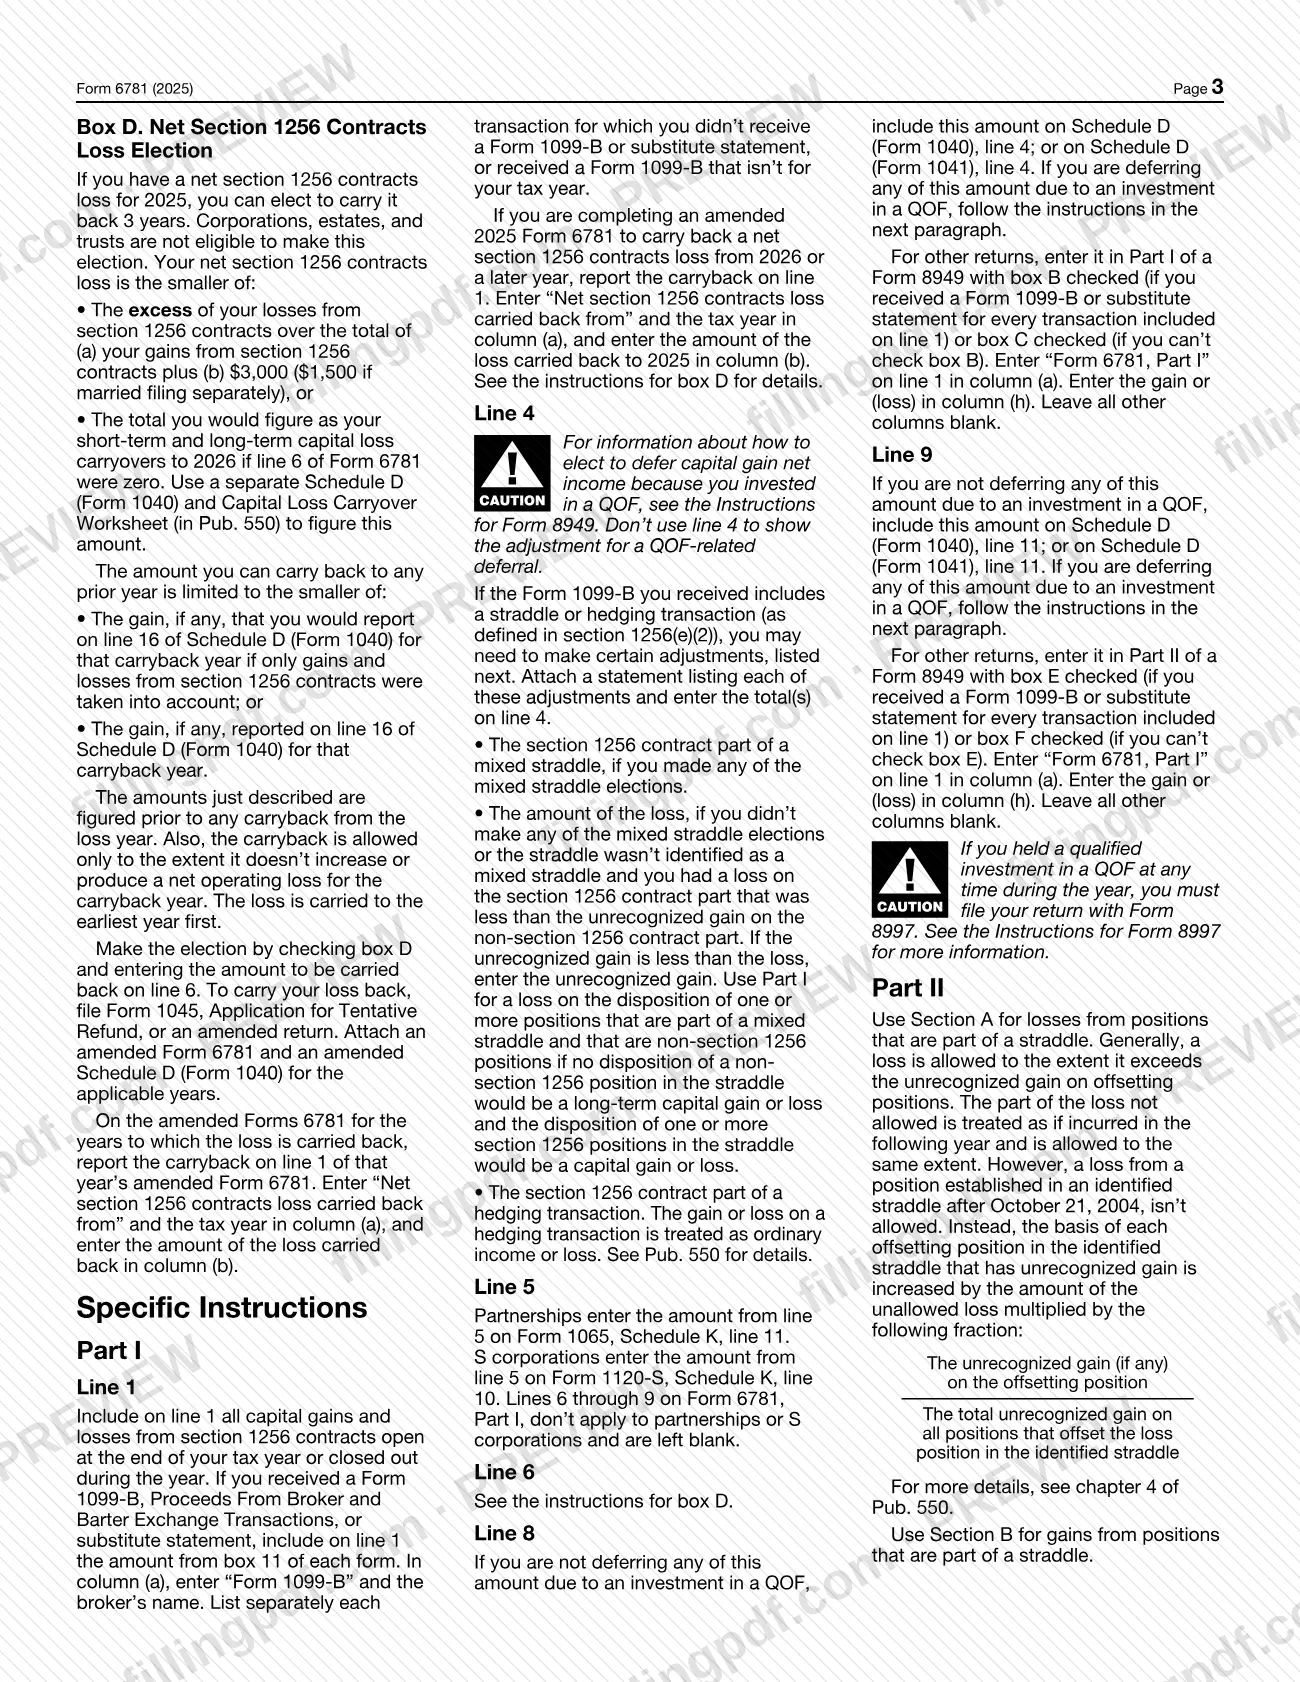
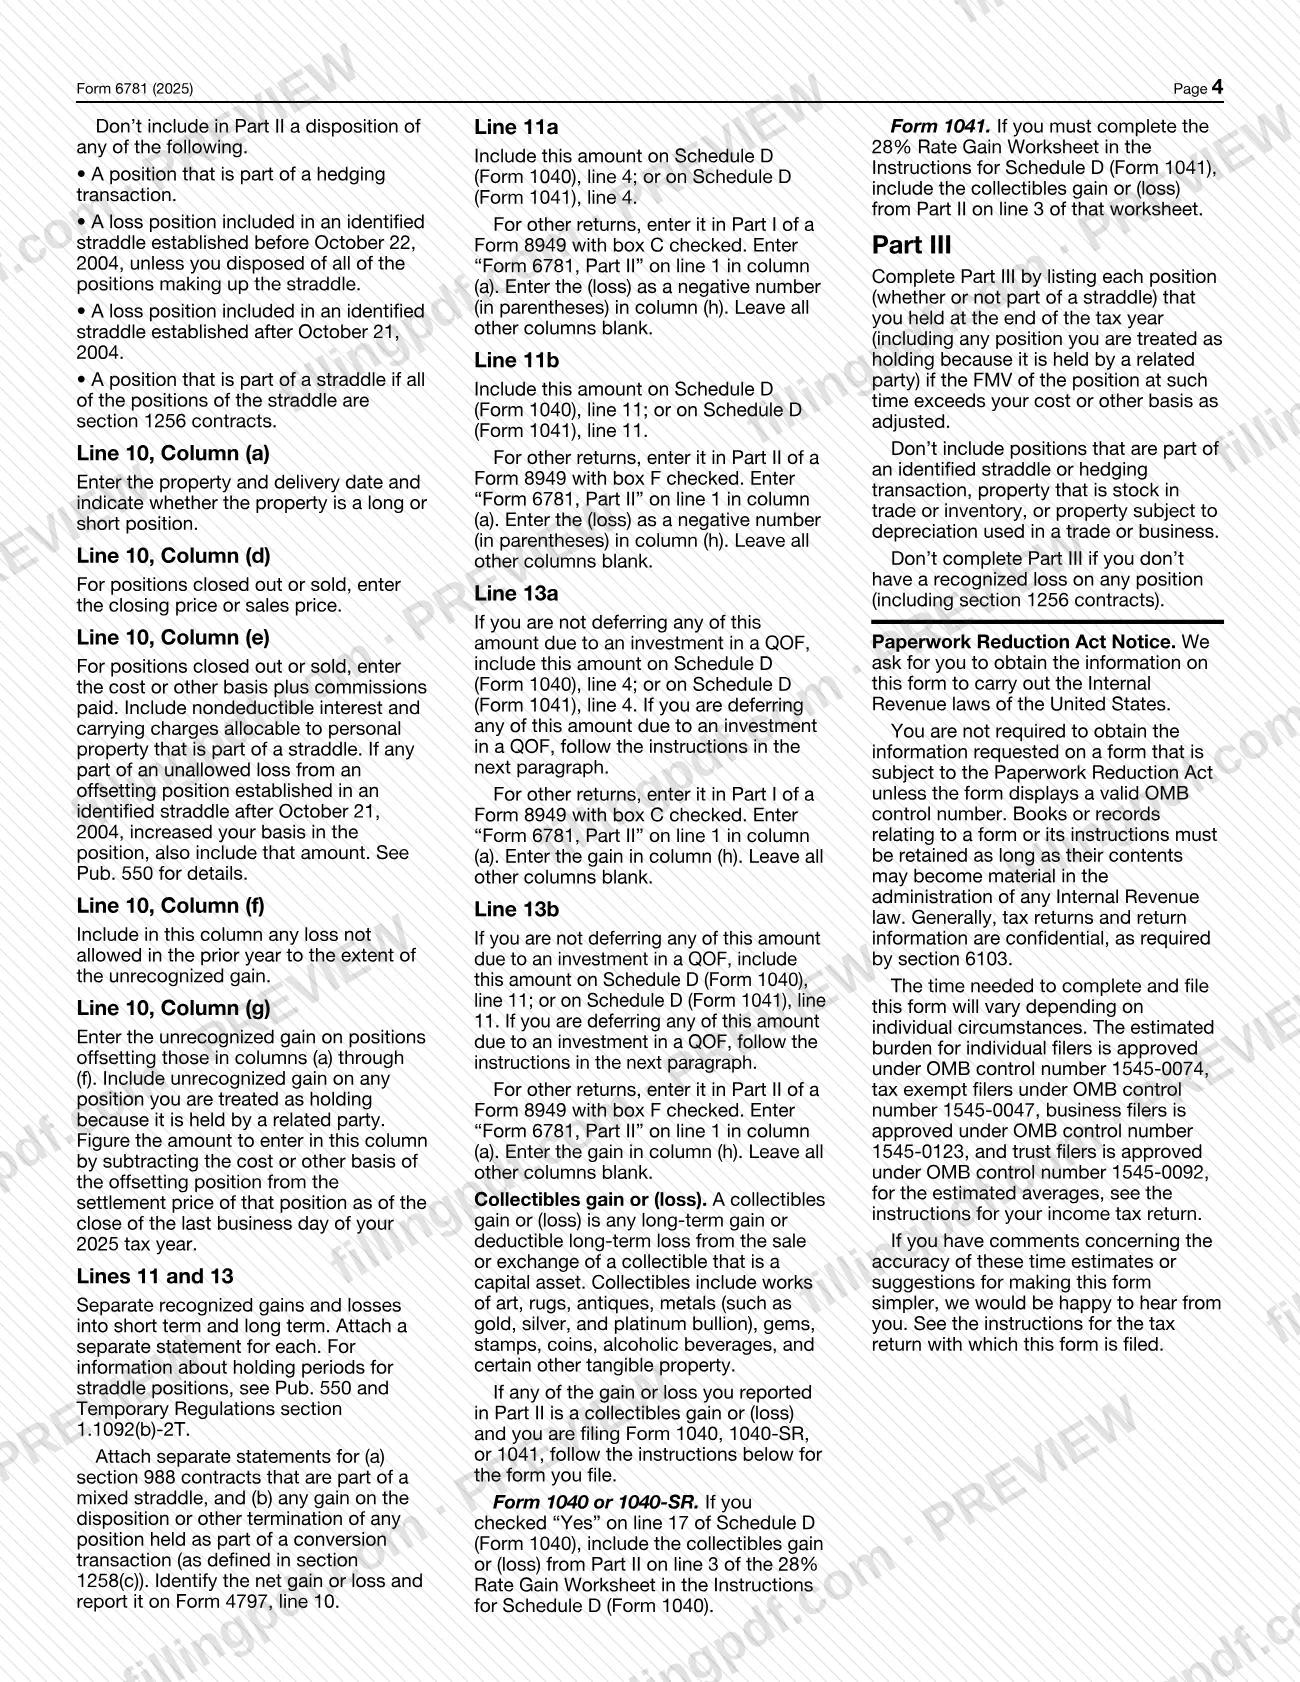
Form 6781, Gains and Losses from Section 1256 Contracts and Straddles, is the Internal Revenue Service (IRS) form used to report capital gains and losses on section 1256 contracts under the mark-to-market rules and gains and losses under section 1092 from straddle positions. You attach it to your tax return. On this page you can fill out Form 6781 online on FillingPDF and download or print the completed PDF; the form and its instructions are published by the IRS at www.irs.gov/Form6781.
Last updated
What is Form 6781?
Form 6781, Gains and Losses from Section 1256 Contracts and Straddles, is the IRS form that reports capital gains and losses on section 1256 contracts under the mark-to-market rules, and gains and losses under section 1092 from straddle positions. It is attached to your tax return (OMB No. 1545-0074, Attachment Sequence No. 82).
The form has three parts:
- Part I, Section 1256 Contracts Marked to Market. Lines 1 to 9 total the gains and losses, apply any Form 1099-B adjustments, and split the result 40% short term (line 8) and 60% long term (line 9).
- Part II, Gains and Losses From Straddles. Section A (lines 10 and 11) covers losses and Section B (lines 12 and 13) covers gains, with a separate statement listing each straddle and its components.
- Part III, Unrecognized Gains From Positions Held on Last Day of Tax Year. A memo entry only (line 14).
A box at the top of the form records the elections you make: A (Mixed straddle election), B (Straddle-by-straddle identification election), C (Mixed straddle account election) and D (Net section 1256 contracts loss election).
Under the IRS instructions, a section 1256 contract is a regulated futures contract, foreign currency contract, nonequity option, dealer equity option or dealer securities futures contract. Securities futures contracts and swaps, among other agreements, are not section 1256 contracts. The results carry to Schedule D or Form 8949. For details, the IRS points to Publication 550, Investment Income and Expenses.
Who needs to file Form 6781?
File Form 6781 if you have capital gain or loss on section 1256 contracts, or gains and losses from straddle positions under section 1092, to report with your tax return. The IRS instructions list the section 1256 contracts as regulated futures contracts, foreign currency contracts, nonequity options, dealer equity options and dealer securities futures contracts.
- Individuals, estates and trusts report the results on Schedule D (Form 1040) or Schedule D (Form 1041), or on Form 8949, as the line instructions direct.
- Partnerships enter the line 5 amount on Form 1065, Schedule K, line 11. S corporations enter it on Form 1120-S, Schedule K, line 10. Lines 6 through 9 do not apply to them and are left blank.
- Net section 1256 contracts loss election (box D): corporations, estates and trusts are not eligible to make it.
- Qualified opportunity fund (QOF) investors: if you held a qualified investment in a QOF at any time during the year, you must file your return with Form 8997.
Do not use Part II for dispositions of a position that is part of a hedging transaction, or of a straddle whose positions are all section 1256 contracts. Other exclusions for loss positions in identified straddles are listed in the Part II instructions.
When to file Form 6781
Form 6781 has no separate due date: you attach it to your tax return, so it is due with that return. The 2025 form applies to the 2025 tax year.
Some elections have their own timing. To make the mixed straddle account election (box C), which establishes one or more mixed straddle accounts for 2026, check box C and attach the statement required by the regulations to your return, or to your request for an extension of time to file. The election must be made by the due date, without extensions, of your 2025 tax return.
The mixed straddle election (box A) applies to all later years and cannot be revoked without IRS consent. If you have a net section 1256 contracts loss for 2025, you can elect to carry it back 3 years by checking box D and entering the amount on line 6; carrying the loss back is done with Form 1045 or an amended return.
Documents you need
- A statement listing each straddle and its components, attached for Part II (Gains and Losses From Straddles).
- A statement listing each Form 1099-B adjustment, with the total entered on line 4, when the Form 1099-B includes a straddle or hedging transaction.
- The statement required by the regulations for the mixed straddle account election, attached to your return or extension request, when you check box C.
- A list of the contracts covered by an election under section 988(a)(1)(B) or 988(c)(1)(D), showing the net gain or loss and where it is reported on the return, if you made such an election.
- Separate statements for section 988 contracts that are part of a mixed straddle, and for any gain on a position held as part of a conversion transaction (as defined in section 1258(c)).
- Form 8997, filed with your return, if you held a qualified investment in a qualified opportunity fund (QOF) at any time during the year.
- Form 1045 or an amended return, with an amended Form 6781 and amended Schedule D (Form 1040), to carry a net section 1256 contracts loss back (box D).
How to fill out Form 6781
Enter name and identifying number
At the top, enter the name(s) shown on your tax return and your identifying number.
Check the election boxes
Check all applicable boxes: A (Mixed straddle election), B (Straddle-by-straddle identification election), C (Mixed straddle account election) or D (Net section 1256 contracts loss election). See the instructions for each box.
List section 1256 contracts on line 1
In Part I, include all capital gains and losses from section 1256 contracts open at year end or closed out during the year. For a Form 1099-B, enter the box 11 amount, "Form 1099-B" and the broker's name in column (a), losses in column (b) and gains in column (c).
Total Part I on lines 2 to 5
Line 2 adds columns (b) and (c) of line 1, line 3 combines them, line 4 is the Form 1099-B adjustments (attach a statement), and line 5 combines lines 3 and 4.
Handle the loss carryback on line 6
If you have a net section 1256 contracts loss and checked box D, enter the loss to be carried back as a positive number on line 6; otherwise enter -0-. Partnerships and S corporations leave lines 6 through 9 blank.
Split the gain or loss on lines 7 to 9
Line 7 combines lines 5 and 6. Multiply line 7 by 40% for line 8 (short term) and by 60% for line 9 (long term), then carry them to Schedule D or Form 8949 as instructed.
Enter straddle losses on lines 10 and 11
In Part II, Section A, list each position on line 10 with columns (a) through (h), and attach a separate statement listing each straddle and its components. Enter the short-term portion on line 11a and the long-term portion on line 11b.
Enter straddle gains on lines 12 and 13
In Section B, list each position on line 12, columns (a) through (f), where (f) is the gain if (d) is more than (e). Enter the short-term portion on line 13a and the long-term portion on line 13b.
Complete the Part III memo entry
On line 14, list each position held on the last day of the tax year whose fair market value exceeds its adjusted cost or other basis, and enter the unrecognized gain in column (e). Skip Part III if you have no recognized loss on any position.
Carry amounts to your return
Follow the instructions for lines 8, 9, 11a, 11b, 13a and 13b to enter the amounts on Schedule D (Form 1040), Schedule D (Form 1041) or Form 8949. Partnerships and S corporations carry line 5 to Schedule K.
Review and download the PDF
Check every line and the attached statements, then download or print the completed PDF from FillingPDF and attach it to your tax return.
How to submit Form 6781
Form 6781 is not filed on its own: you attach it to your tax return and submit it through whatever channel you use for that return.
- Individuals, estates and trusts: attach Form 6781 to the return, and enter the results on Schedule D (Form 1040), Schedule D (Form 1041) or Form 8949 as the instructions for lines 8, 9, 11a, 11b, 13a and 13b direct.
- Partnerships: carry the line 5 amount to Form 1065, Schedule K, line 11.
- S corporations: carry the line 5 amount to Form 1120-S, Schedule K, line 10.
- Carrying back a net section 1256 contracts loss: file Form 1045, Application for Tentative Refund, or an amended return, with an amended Form 6781 and an amended Schedule D (Form 1040) for each affected year.
Attach the statements the form requires, such as the statement listing each straddle and its components, the Form 1099-B adjustments statement and the box C statement. The form prints no mailing address of its own; use the filing instructions for the return it accompanies. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Entering the line 6 carryback amount as a negative number; the form says to enter the loss as a positive number, and to enter -0- if you did not check box D.
- Completing lines 6 through 9 as a partnership or S corporation; those lines do not apply to them and are left blank.
- Making the net section 1256 contracts loss election (box D) as a corporation, estate or trust, which are not eligible.
- Skipping the attached statement listing each straddle and its components in Part II.
- Including in Part II a disposition of a hedging transaction position, or of a straddle in which all positions are section 1256 contracts.
- Leaving out the Form 1099-B adjustments statement when the Form 1099-B includes a straddle or hedging transaction.
- Using line 4 to show a QOF-related deferral adjustment; the instructions say not to.
- Entering other columns on Form 8949 when reporting Form 6781 amounts; the instructions say to enter "Form 6781, Part I" or "Part II" in column (a), the amount in column (h), and leave the rest blank.
- Completing Part III when you have no recognized loss on any position; the instructions say not to.
Frequently asked questions
What is Form 6781 used for?
Form 6781 reports any capital gain or loss on section 1256 contracts under the mark-to-market rules, and gains and losses under section 1092 from straddle positions. You attach it to your tax return, and the results carry to Schedule D or Form 8949.
What is a section 1256 contract?
Under the IRS instructions, it is a regulated futures contract, foreign currency contract, nonequity option, dealer equity option or dealer securities futures contract. Securities futures contracts, options on them and swaps such as interest rate or credit default swaps are not included.
How are gains and losses split on Form 6781?
Gains or losses on section 1256 contracts open at year end or terminated during the year are treated as 60% long term and 40% short term, regardless of how long you held them. Line 8 is line 7 times 40%, and line 9 is line 7 times 60%.
Can I carry back a section 1256 contracts loss?
Yes, if you have a net section 1256 contracts loss for 2025 you can elect to carry it back 3 years by checking box D and entering the amount on line 6. Corporations, estates and trusts are not eligible. Carry it back with Form 1045 or an amended return.
When is the mixed straddle account election (box C) due?
By the due date, without extensions, of your 2025 tax return. Check box C and attach the statement required by the regulations to your return or to your request for an extension of time to file. The election establishes mixed straddle accounts for 2026.
Do partnerships and S corporations complete all of Form 6781?
No. Lines 6 through 9 do not apply to them and are left blank. A partnership enters the line 5 amount on Form 1065, Schedule K, line 11, and an S corporation enters it on Form 1120-S, Schedule K, line 10.
Where do I send Form 6781?
You do not send it separately. Attach Form 6781 to your tax return and submit it through the same channel as that return; the form prints no address of its own. Carrybacks go on Form 1045 or an amended return.
Can I fill out Form 6781 online on FillingPDF?
Yes. You can fill out the PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the form with the IRS; you submit it with your tax return through the IRS channels.
Ready to fill out Form 6781?
Fill out Form 6781 now