
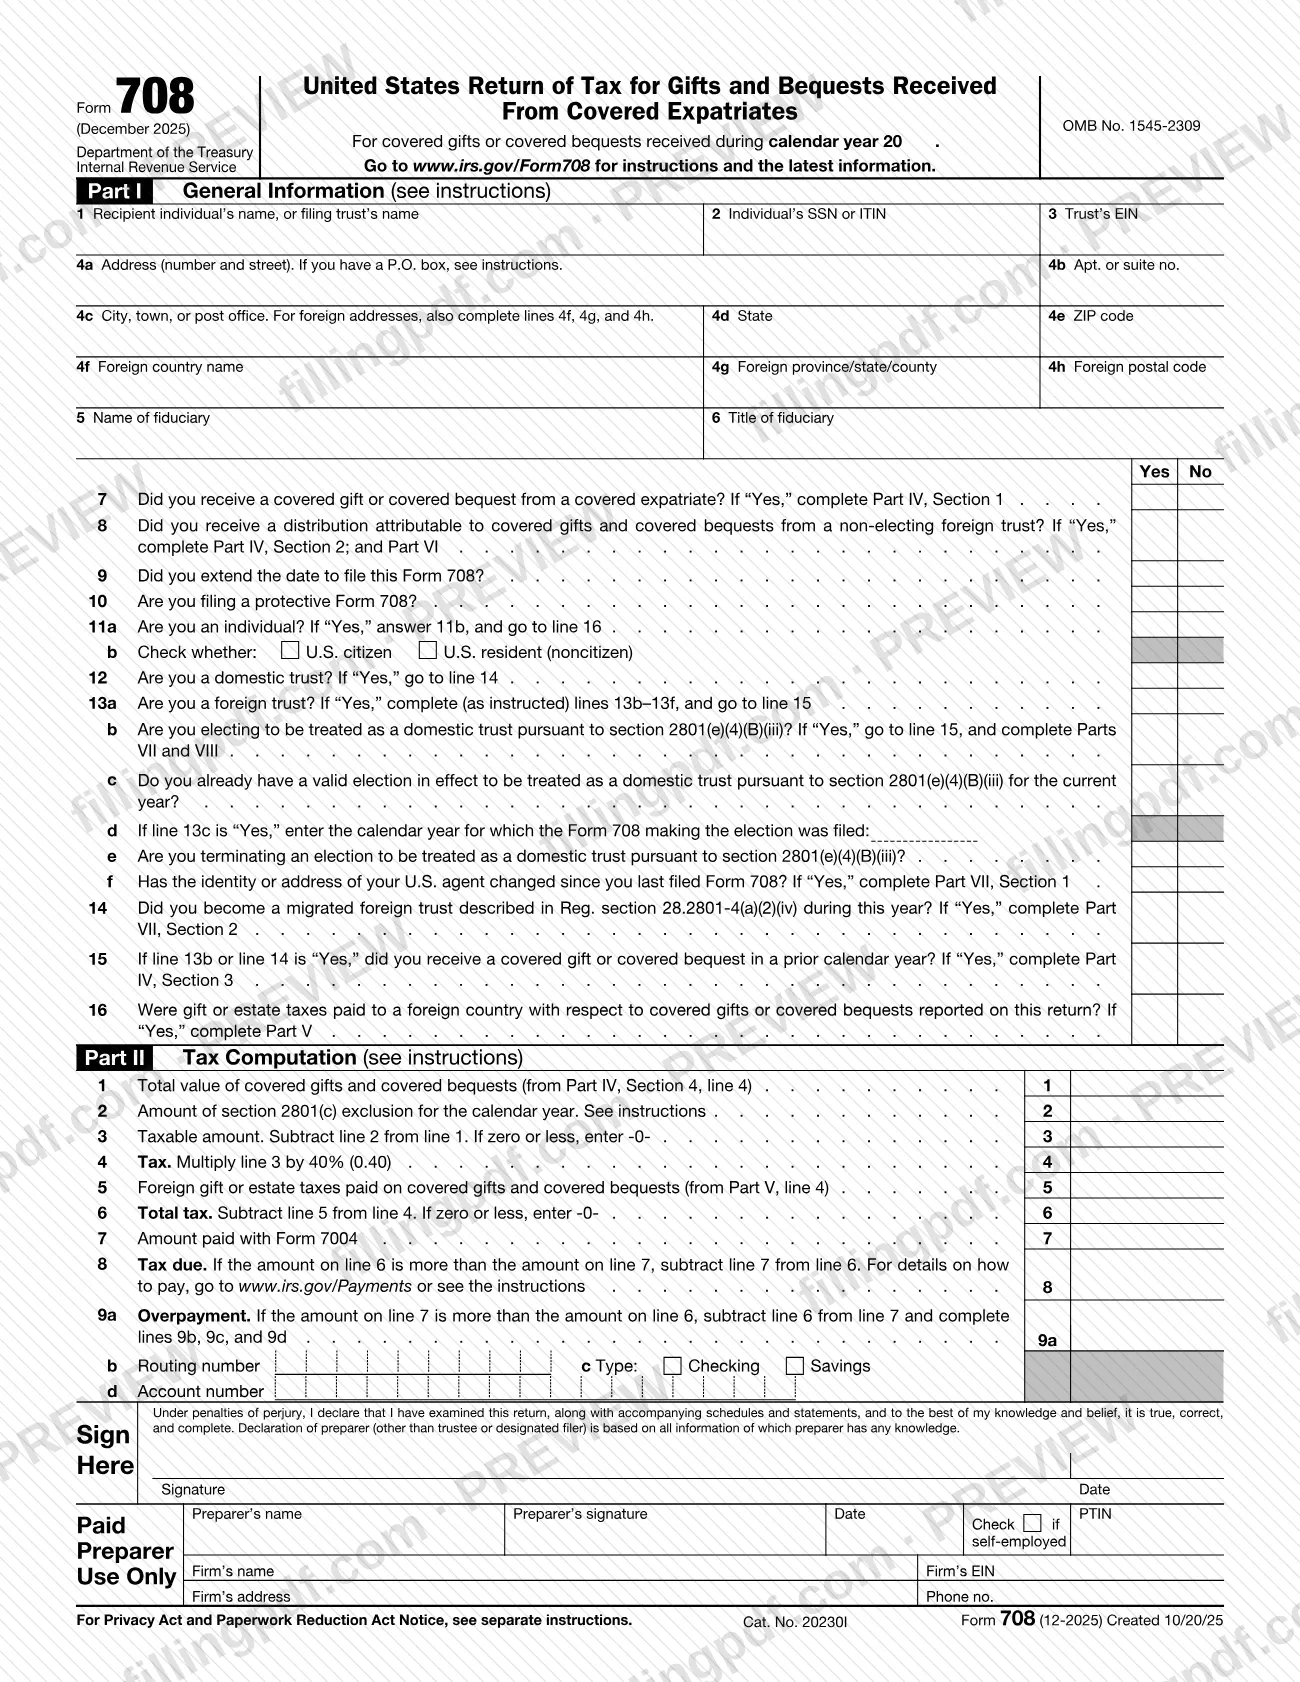
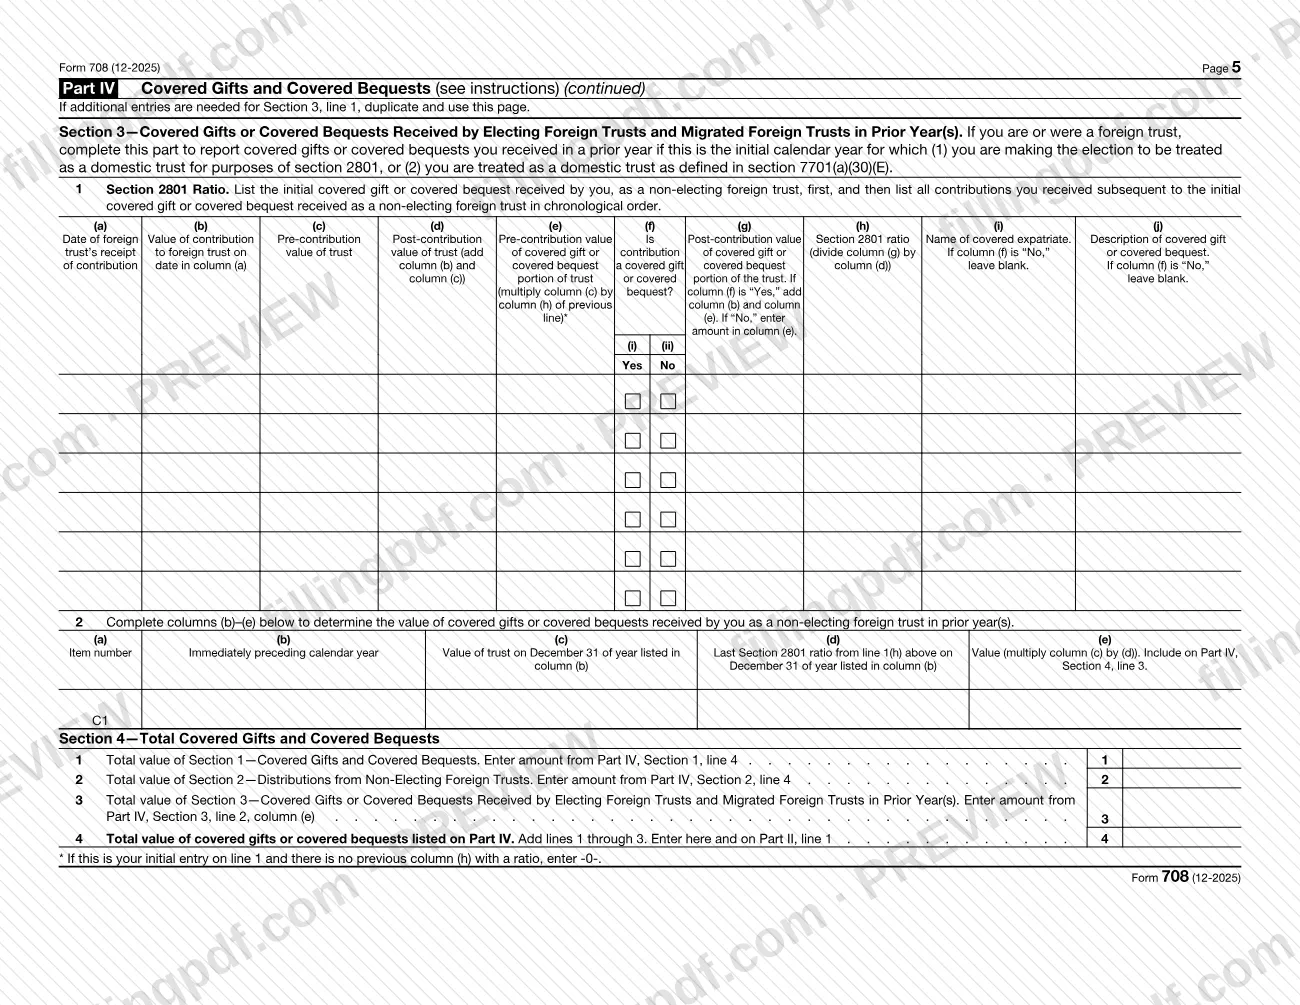
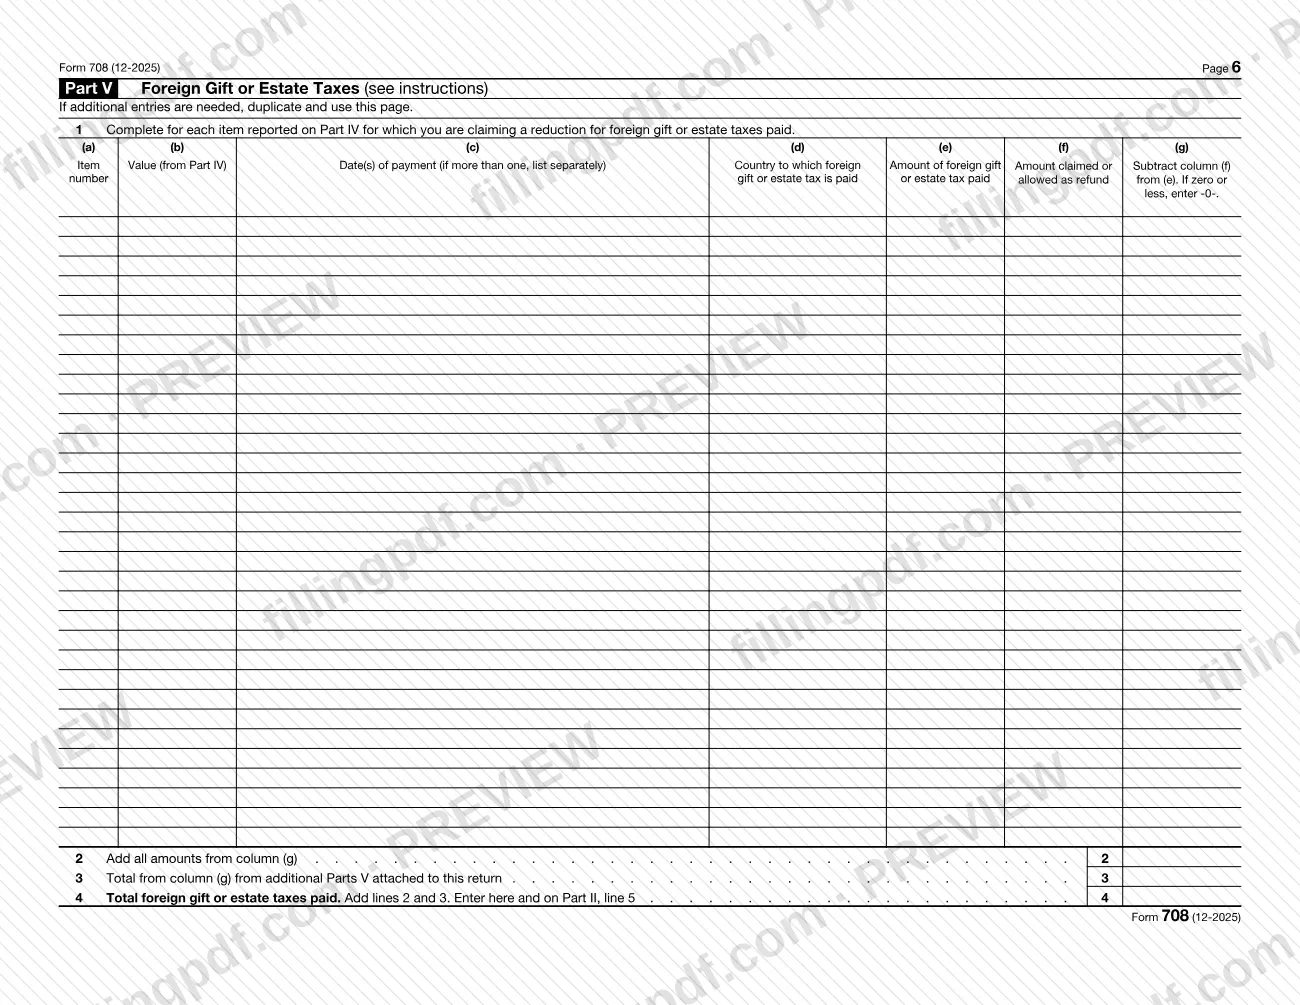
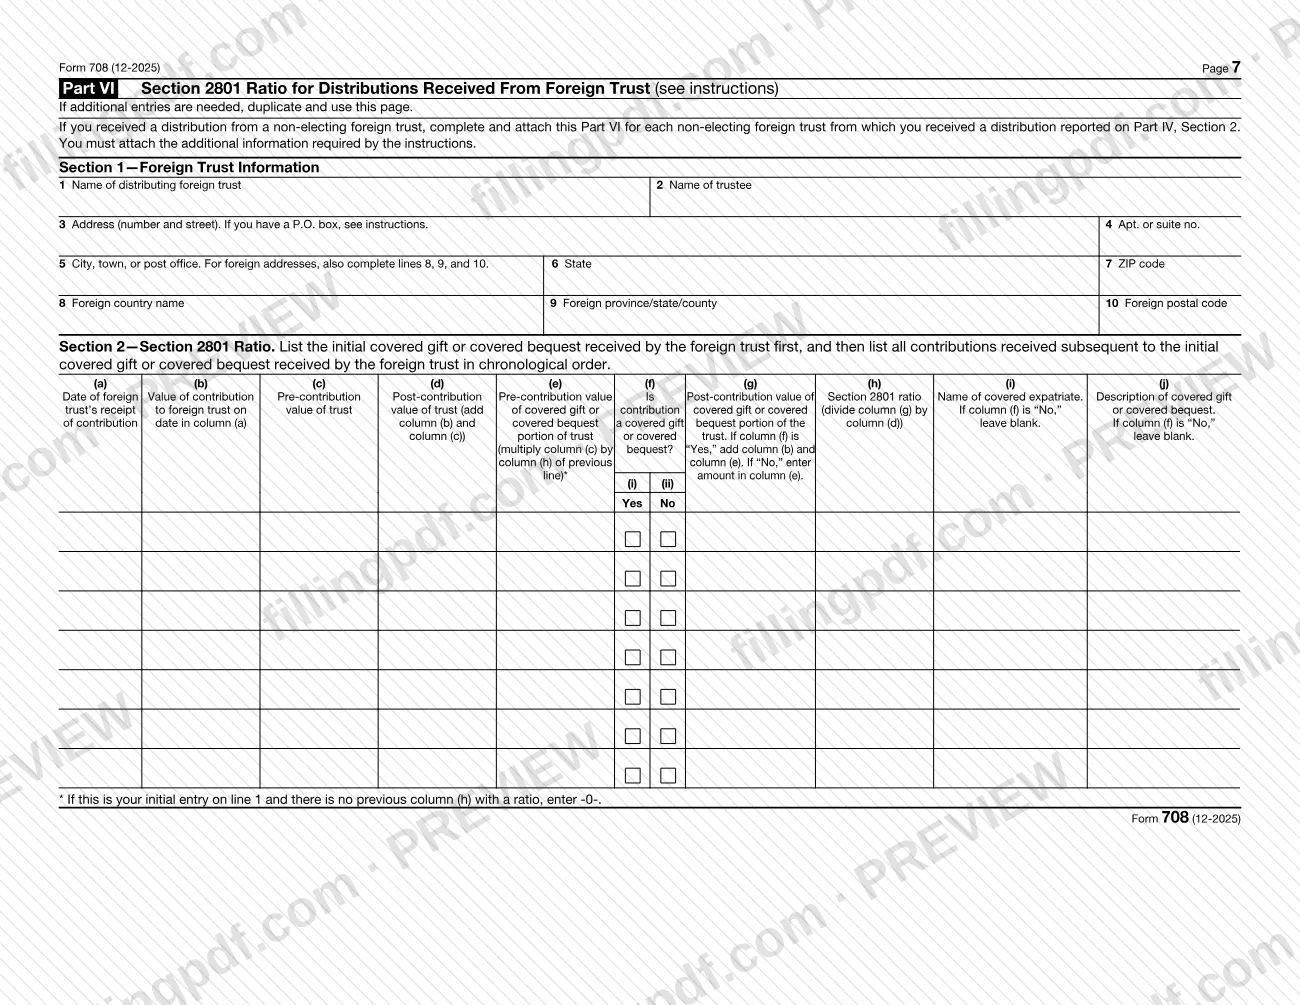
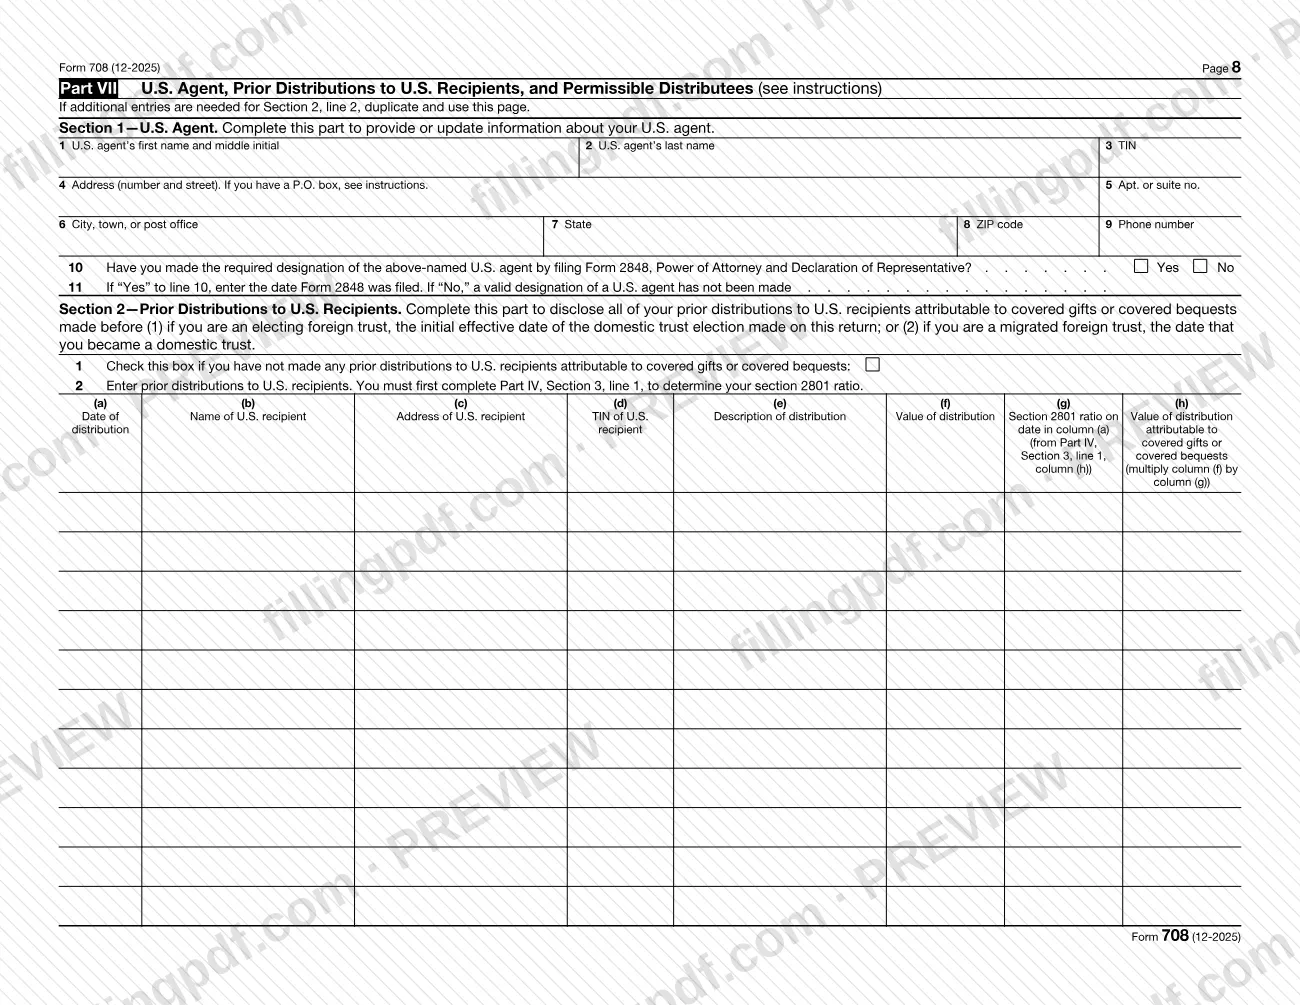
Form 708 is the Internal Revenue Service (IRS) return that reports covered gifts and covered bequests received from covered expatriates and figures the section 2801 tax on them. U.S. citizens and residents, domestic trusts and certain foreign trusts use it, with one return for each calendar year in which they receive reportable gifts or bequests. On this page you can fill out the form online on FillingPDF and download or print the completed PDF; the form and its instructions are published by the IRS at www.irs.gov/Form708.
Last updated
What is Form 708?
Form 708, United States Return of Tax for Gifts and Bequests Received from Covered Expatriates, is the IRS return for reporting covered gifts and covered bequests received from covered expatriates in a calendar year and figuring the section 2801 tax due, if any.
The Internal Revenue Service (IRS) instructions define the terms. A covered gift or covered bequest is property received on or after June 17, 2008 from a covered expatriate, directly or indirectly. It also includes certain distributions from non-electing foreign trusts that are attributable to such gifts and bequests. A covered expatriate is a former U.S. citizen or former long-term resident whose expatriation date falls after June 16, 2008 and who meets one of the tests in the instructions. Some gifts and bequests are excluded, such as certain transfers to charity or to the covered expatriate's spouse; see Regulations section 28.2801-3.
Form 708 is an annual return. The tax is figured on the net amount of covered gifts and bequests received during the year, reduced by any foreign gift or estate tax paid on them, and the recipient is liable for it. The form has eight parts: general information, tax computation, covered expatriates, covered gifts and bequests, foreign gift or estate taxes, the section 2801 ratio for foreign trust distributions, U.S. agent and permissible distributee information, and the declaration of a foreign trustee.
Foreign trusts also use Form 708 to elect to be treated as a domestic trust for section 2801 purposes. The instructions reflect final regulations (TD 10027), effective January 14, 2025. Form 708 is separate from Form 3520, which U.S. persons may also need for gifts or distributions from foreign persons or trusts.
Who needs to file Form 708?
File Form 708 if you are a U.S. citizen or resident, or a trust, and you receive a covered gift or covered bequest. The instructions list these groups:
- An individual who is a U.S. citizen or resident (based on domicile) and receives one or more covered gifts or covered bequests during the calendar year, including foreign trust distributions attributable to them.
- A domestic trust that receives a covered gift or covered bequest during the year.
- An electing foreign trust that receives a covered gift or covered bequest during the year.
- A non-electing foreign trust that becomes a domestic trust during the year (a migrated foreign trust) and has received a covered gift or covered bequest in that year or earlier.
- A non-electing foreign trust that is making the election to be treated as a domestic trust.
For section 2801, "resident" follows the gift and estate tax definition, which is based on domicile, so you can be a resident here and a nonresident for income tax.
You do not need to file if you are a U.S. citizen or resident, domestic trust or electing foreign trust and the total fair market value of covered gifts and bequests for the year does not exceed the section 2801(c) amount. That exception does not apply to a trust becoming a migrated foreign trust or to a foreign trust making the election. If you reasonably conclude that a gift is not from a covered expatriate, you may file a protective Form 708. The U.S. recipient signs the return.
When to file Form 708
File Form 708 on or before the 15th day of the 18th month after the close of the calendar year in which you received the covered gift or covered bequest. For covered gifts and bequests received during 2025, the due date is June 15, 2027. If the due date falls on a Saturday, Sunday or legal holiday, the return is due the next business day.
Different rules apply in three cases:
- Covered bequests received on a date other than the covered expatriate's date of death: the due date is the later of two dates set out in the instructions.
- Migrated foreign trusts: the 15th day of the sixth month after the close of the year the trust becomes a domestic trust.
- Foreign trusts electing domestic treatment in a year with no covered gift or bequest: the 15th day of the sixth month after the close of the first election year.
You can request an automatic 6-month extension by filing Form 7004 on or before the due date, with an estimate of your section 2801 tax. The extension does not extend the time to pay. The instructions state that section 6651 penalties for late filing and late payment apply unless there is reasonable cause.
Documents you need
- A copy of the foreign trust's governing instrument, if you received a distribution from a non-electing foreign trust, are an electing foreign trust, or became a migrated foreign trust during the year.
- Part VI for each non-electing foreign trust that distributed property to you, with a copy of that trust's governing instrument, completed before Part IV, Section 2.
- Information showing how you determined the value of each covered gift or bequest, plus any appraisal used for real estate or other property; otherwise Part IV must fully explain the valuation.
- A copy of the foreign gift or estate tax return and a copy of the receipt or canceled check for each payment, if you claim a reduction for foreign gift or estate tax on Part V.
- Form 2848, Power of Attorney and Declaration of Representative, designating a U.S. agent, if you are a foreign trust electing to be treated as a domestic trust (or updating the agent).
- A statement explaining why no number is given, if the covered expatriate has neither an SSN nor an ITIN and Part III, column (c) is left blank.
- For a protective Form 708: an affidavit signed under penalties of perjury stating why the donor was not a covered expatriate, any information received from the IRS, and a copy of the completed Part III or Part IV of Form 3520.
- For a supplemental return: a statement of what has changed, with supporting information and a copy of the original Form 708.
How to fill out Form 708
Enter the calendar year
On the line under the form title, write the calendar year in which you received the covered gifts or covered bequests. Use one Form 708 for that whole year.
Identify the recipient on Part I
Line 1: your name, or the filing trust's name. Line 2: your SSN, or an ITIN only if you previously used it on other U.S. returns. Line 3: the trust's EIN, if applicable.
Enter address and fiduciary details
Lines 4a through 4h: your current mailing address; for a foreign address, enter only the city on line 4c, complete lines 4f through 4h and do not abbreviate the country name. Lines 5 and 6: the name and title of the trustee or other fiduciary, if you file for a trust.
Answer lines 7 through 10
Check Yes or No for a covered gift or bequest received (line 7), a distribution from a non-electing foreign trust (line 8), an extension (line 9) and a protective Form 708 (line 10). Each Yes tells you which part to complete.
Complete your status on lines 11 to 16
Individuals answer 11a and 11b, skip lines 12 through 15, and go to line 16. Trusts answer lines 12 through 15 as the form directs, including the domestic trust election on 13b to 13f, then answer line 16 on foreign taxes.
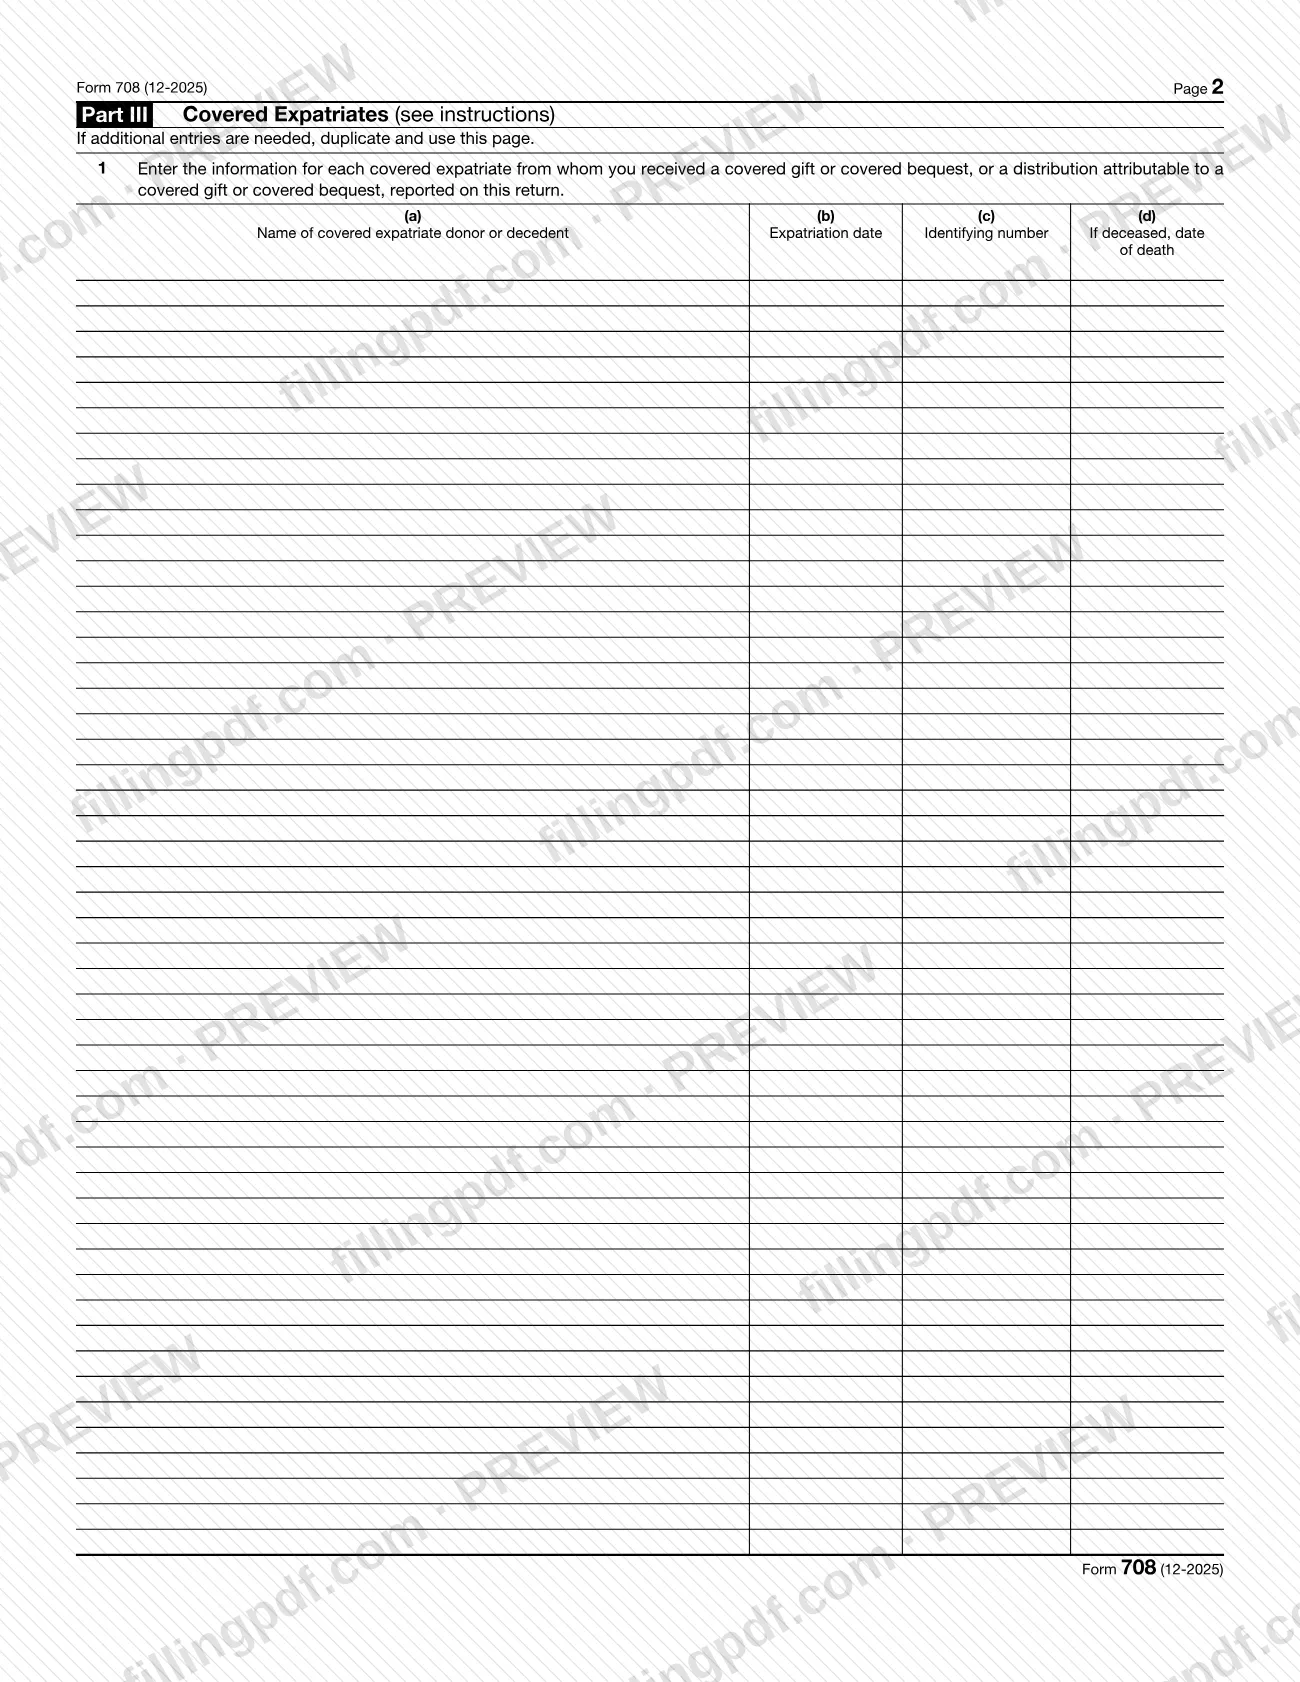
List covered expatriates in Part III
For each covered expatriate, enter the name (a), expatriation date (b), identifying number (c) and date of death if deceased (d). Duplicate page 2 if you need more entries.
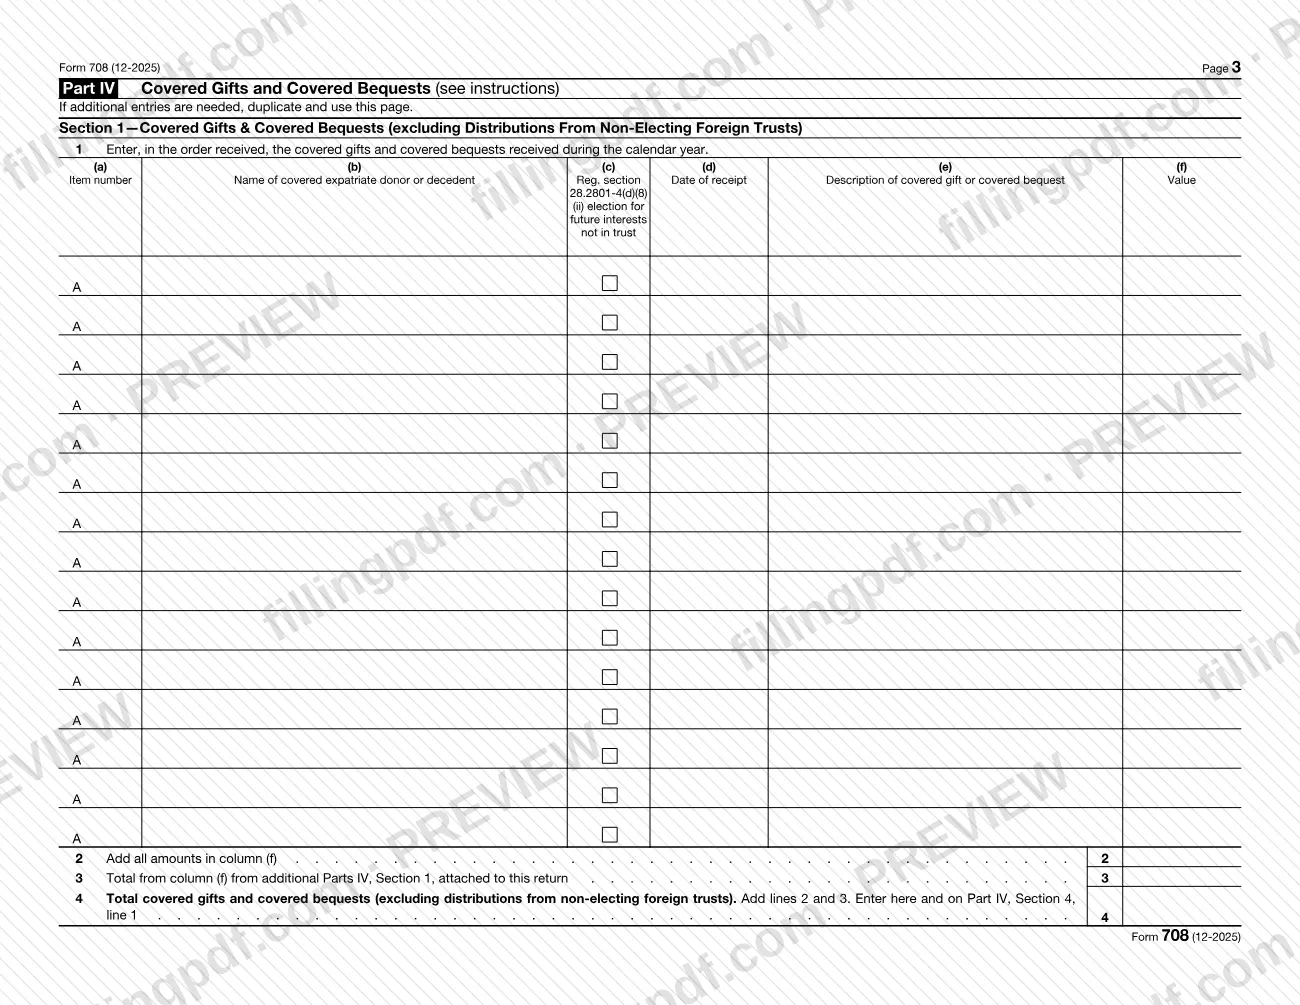
Report gifts and bequests in Part IV, Section 1
List each item in the order received, numbered A1, A2 and so on. Enter the expatriate's name, the date of receipt, a description and the value on the date of receipt, then complete lines 2 through 4.
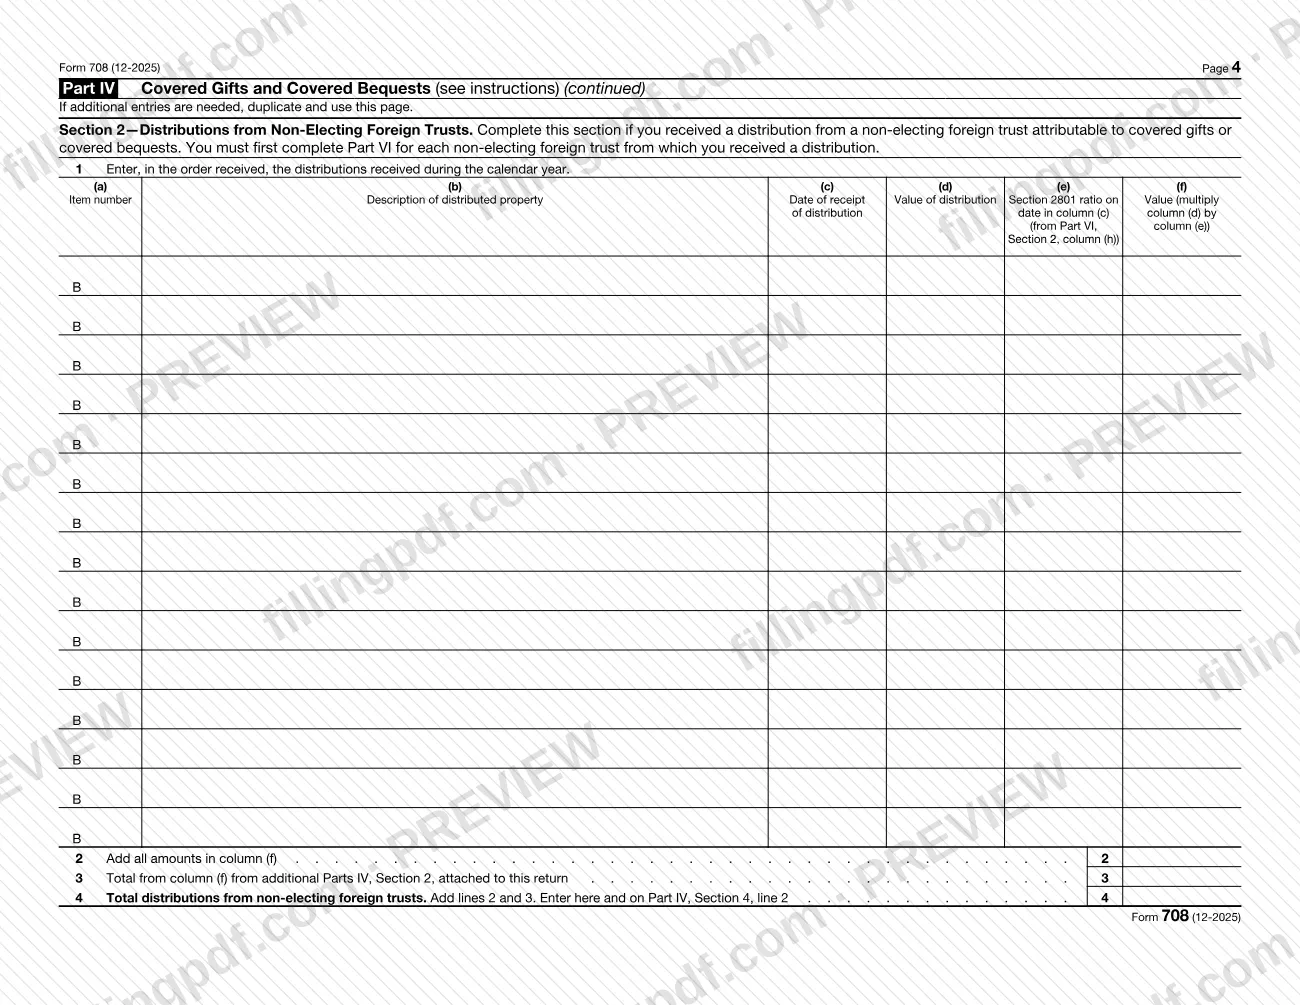
Complete Part VI, then Part IV, Section 2
For each non-electing foreign trust that distributed property to you, complete Part VI to find the section 2801 ratio, then list the distributions as B1, B2 and so on in Part IV, Section 2.
Complete Part IV, Sections 3 and 4
Foreign trusts that elect domestic treatment or migrated to domestic status complete Section 3 for prior-year receipts, with the ratio to two decimal places. Everyone completes Section 4, entering zero on any line with nothing to report.
Claim foreign taxes in Part V
If you answered Yes on line 16, list each item by its item number, its value, payment dates, country and amounts, then total on lines 2 through 4. Attach the foreign return and proof of payment.
Complete Parts VII and VIII for trusts
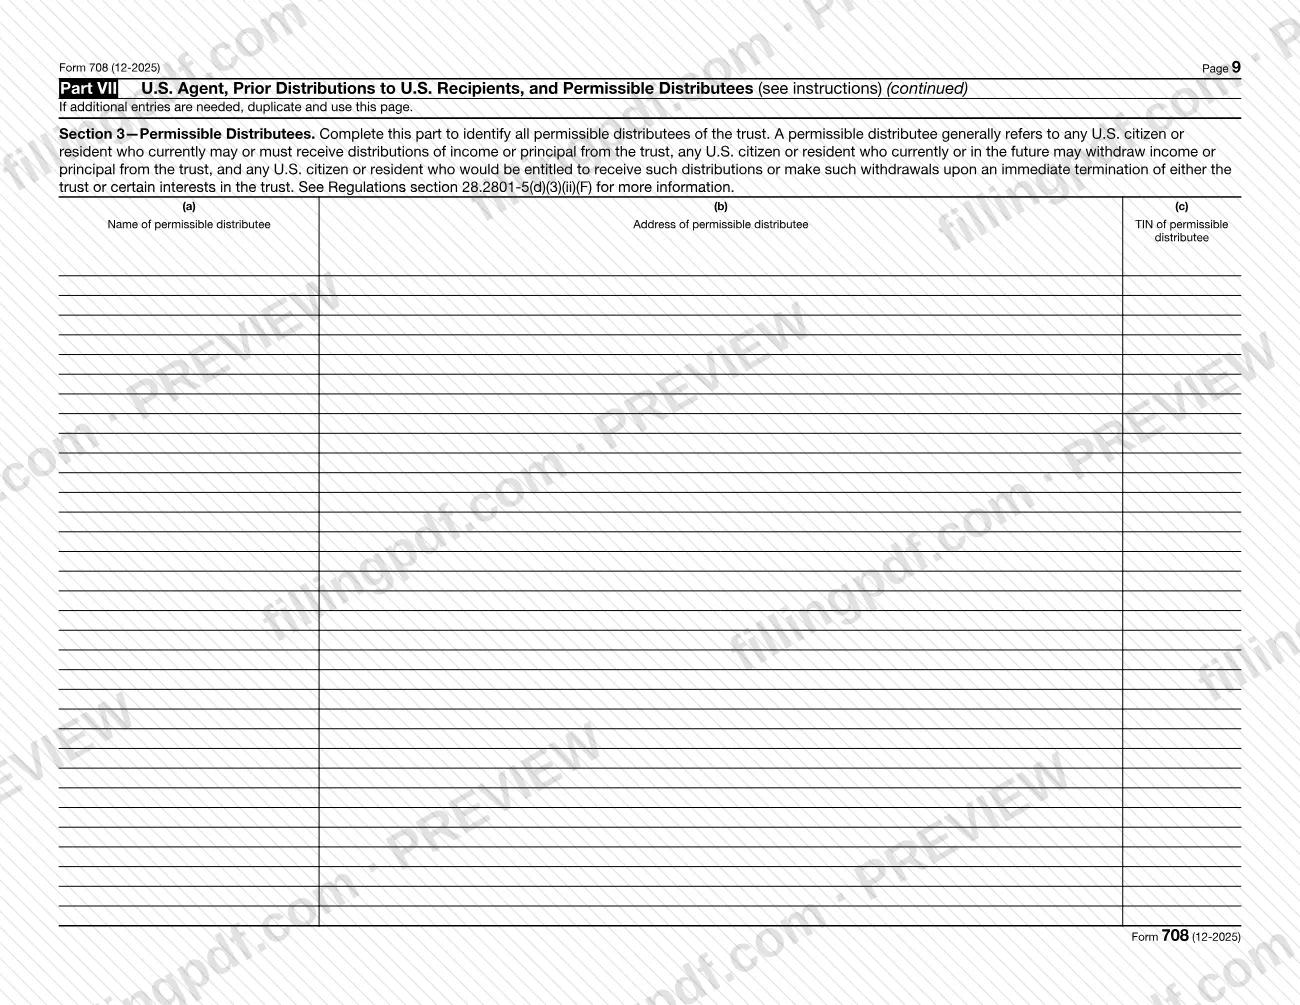
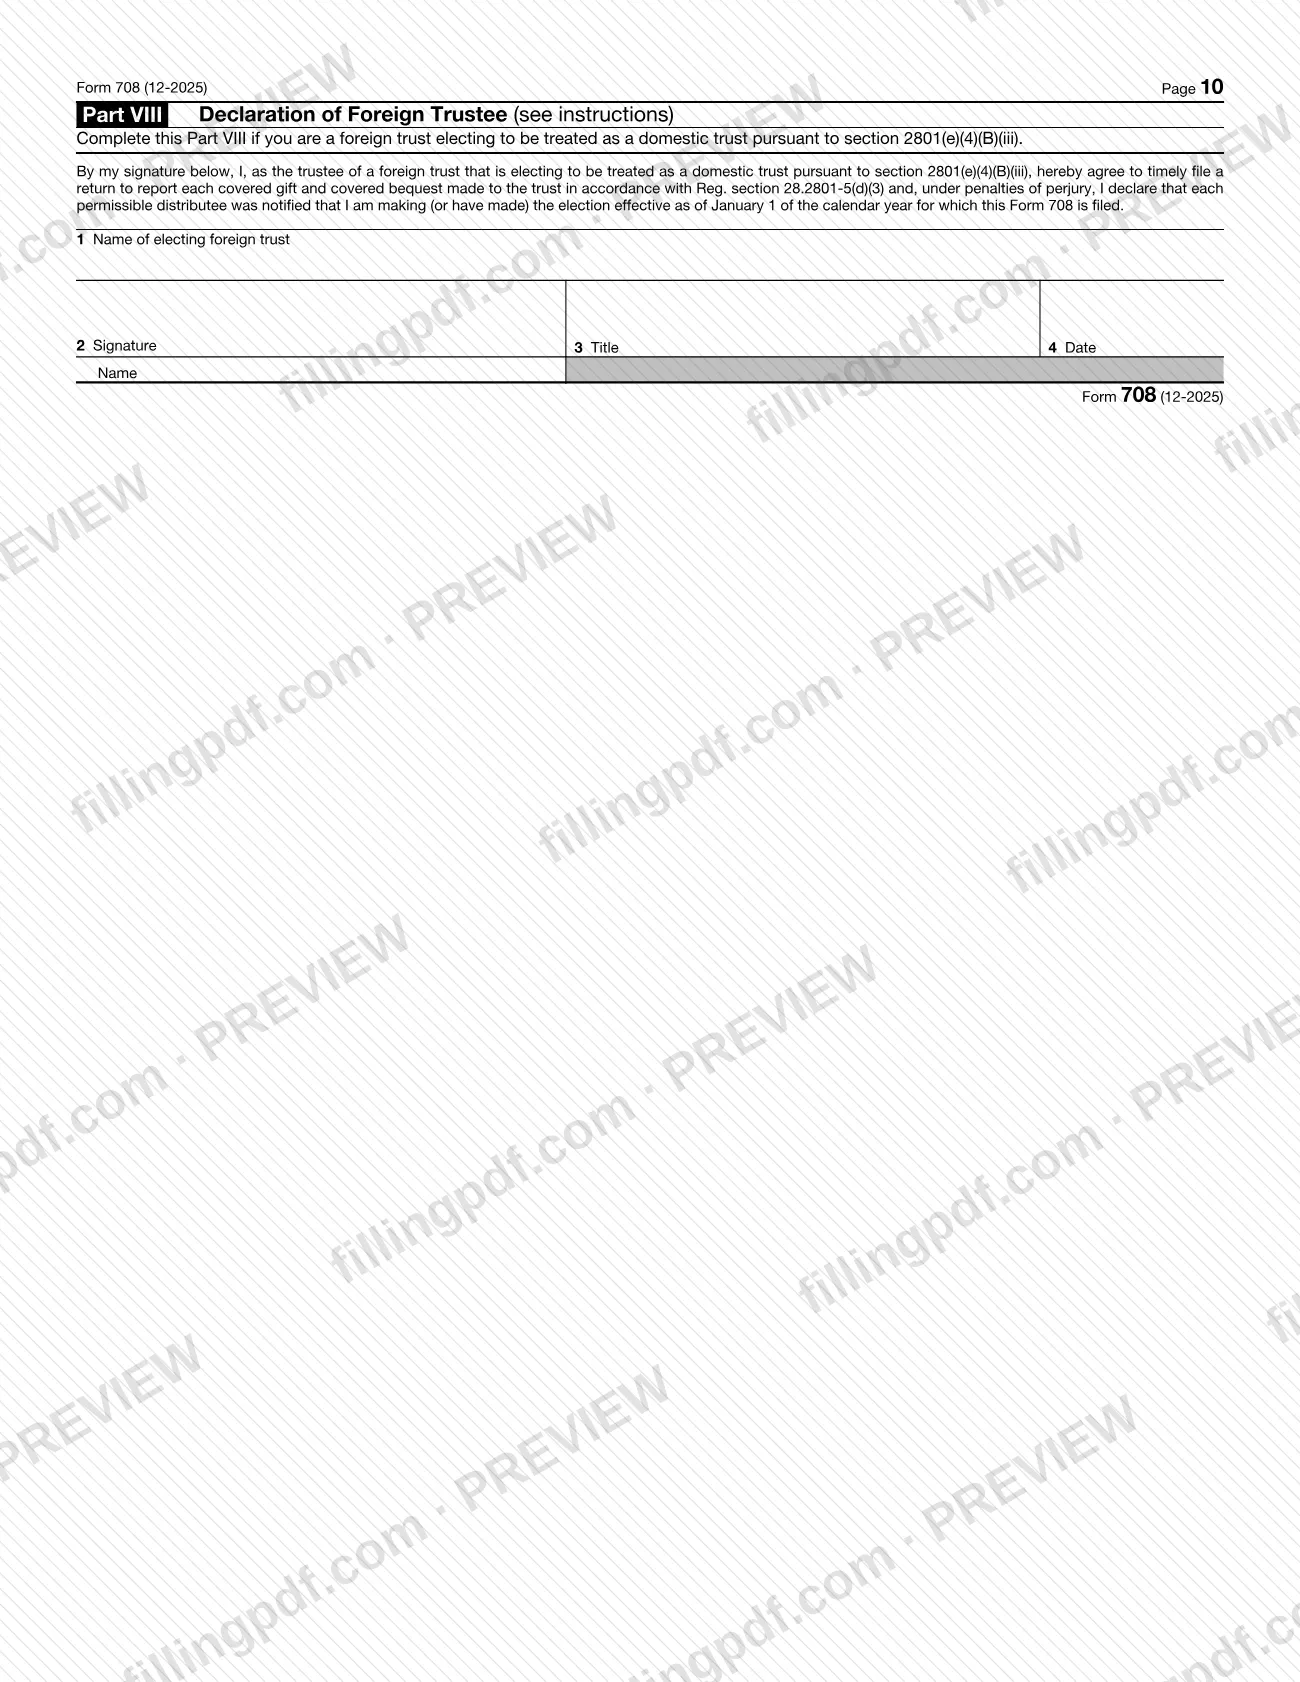
A foreign trust electing domestic treatment completes all three sections of Part VII (U.S. agent, prior distributions, permissible distributees) and the trustee signs Part VIII. Complete Section 1 if the U.S. agent changed, and Section 2 if you became a migrated foreign trust.
Compute the tax in Part II
Enter total value from Part IV on line 1 and the section 2801(c) exclusion on line 2, then follow lines 3 through 6 to the total tax. Lines 7 through 9d cover the amount paid with Form 7004, tax due, and any overpayment with direct deposit details.
Review, sign and download the PDF
Sign and date the return; the U.S. recipient must sign, and a paid preparer completes the Paid Preparer Use Only area. Check that every required field has an entry, then download or print the completed PDF from FillingPDF and assemble the attachments for mailing.
How to submit Form 708
You file Form 708 by mail, either through the U.S. Postal Service or through an IRS-designated private delivery service (PDS). The instructions give no electronic filing channel.
- U.S. mail: Department of the Treasury, Internal Revenue Service, Kansas City, MO 64999.
- Private delivery service: Internal Revenue Service, 333 W. Pershing Road, Kansas City, MO 64108. The current list of designated services is at IRS.gov/PDS. A PDS cannot deliver to a P.O. box, so use the U.S. Postal Service for any IRS P.O. box address.
- Supplemental return: to change a return already filed, file another Form 708 marked "Supplemental Information" across the top of page 1, with a statement of the change and a copy of the original, to Internal Revenue Service Center, Attn: E&G, Stop 824G, 7940 Kentucky Drive, Florence, KY 41042-2915 (same street address for a PDS).
Pay any tax due through EFTPS, a same-day wire from your financial institution, a check payable to "United States Treasury" (write your TIN and "Form 708" on it), or cash at participating retail stores. If you have an overpayment, direct deposit is available on lines 9b through 9d. Form 7004 goes to the address in its own instructions. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Filing more than one Form 708 for the same calendar year. The instructions say to list all reportable gifts and bequests for the year on one return and not to file more than one.
- Leaving required fields blank: the instructions state that returns filed without entries in each required field will not be processed.
- Leaving a line of Part IV, Section 4 empty. You must make an entry on each of lines 1 through 4, entering zero where nothing was received.
- Completing Part IV, Section 2 before Part VI. Part VI must be completed first for each non-electing foreign trust that made a distribution.
- Assuming Form 7004 extends the time to pay. It extends only the time to file; the section 2801 tax is still due with the return.
- Sending a PDS package to an IRS P.O. box, or mailing to the PDS address. Private delivery services cannot deliver to P.O. boxes.
- Attaching a reasonable-cause explanation for late filing. The instructions say not to attach one; send it only after receiving a penalty notice.
- Answering lines 12 through 15 when you are an individual. After line 11b you go straight to line 16.
- Omitting the foreign trust's governing instrument when line 8 or 13a is "Yes", or when you are a migrated foreign trust.
- Entering an ITIN on line 2 that you have not previously used on other U.S. tax returns.
Frequently asked questions
What is Form 708 used for?
Form 708 is the IRS return for reporting covered gifts and covered bequests received from covered expatriates and figuring the section 2801 tax on them. It is filed annually by U.S. citizens and residents, domestic trusts and certain foreign trusts that received such property.
Who has to file Form 708?
U.S. citizens and residents (based on domicile), domestic trusts and electing foreign trusts that receive a covered gift or covered bequest, plus migrated foreign trusts and foreign trusts electing domestic treatment. Receipts at or below the section 2801(c) amount are exempt unless you are a migrated or electing foreign trust.
When is Form 708 due?
On or before the 15th day of the 18th month after the close of the calendar year in which you received the gift or bequest, so June 15, 2027 for 2025 receipts. Special due dates apply to certain bequests, migrated foreign trusts and some electing foreign trusts.
Can I get an extension to file Form 708?
Yes. File Form 7004 on or before the due date, with an estimate of your section 2801 tax, to get an automatic 6-month extension to file. It does not extend the time to pay any tax due with the return.
Where do I mail Form 708?
Mail it to Department of the Treasury, Internal Revenue Service, Kansas City, MO 64999. A private delivery service uses Internal Revenue Service, 333 W. Pershing Road, Kansas City, MO 64108. Supplemental returns go to the Florence, KY address in the instructions.
What is a protective Form 708?
It is a return you may file if you reasonably conclude a gift or bequest you received is not from a covered expatriate. It starts the period of limitations for assessment of tax if it includes all required information and an affidavit under penalties of perjury explaining your conclusion.
Do I file a new Form 708 every year?
You file a separate Form 708 for each calendar year in which you receive reportable covered gifts or covered bequests, including reportable foreign trust distributions. Never file more than one Form 708 for a single calendar year.
How do I correct a Form 708 I already filed?
File another Form 708 with "Supplemental Information" written across the top of page 1, a statement of what changed with supporting information, and a copy of the original. Mail it to the Florence, KY service center address given in the instructions.
Can I fill out Form 708 online on FillingPDF?
Yes. You can fill out the PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file or send the return to the IRS; you mail it through the channels in the instructions.
Ready to fill out Form 708?
Fill out Form 708 now