
Form 7217 is the Internal Revenue Service (IRS) form on which a partner reports the basis of property received from a partnership, including any basis adjustment required by section 732(a)(2) or (b). You file a separate Form 7217 for each date on which you received distributed property, and you attach it to your tax return. On this page you can fill out the form online on FillingPDF and download or print the completed PDF; the form and its instructions are published by the IRS at www.irs.gov/Form7217.
Last updated
What is Form 7217?
Form 7217, Partner's Report of Property Distributed by a Partnership, is the IRS form a partner attaches to a tax return to report the basis of property received in a liquidating or non-liquidating partnership distribution, including basis adjustments required by section 732(a)(2) or (b).
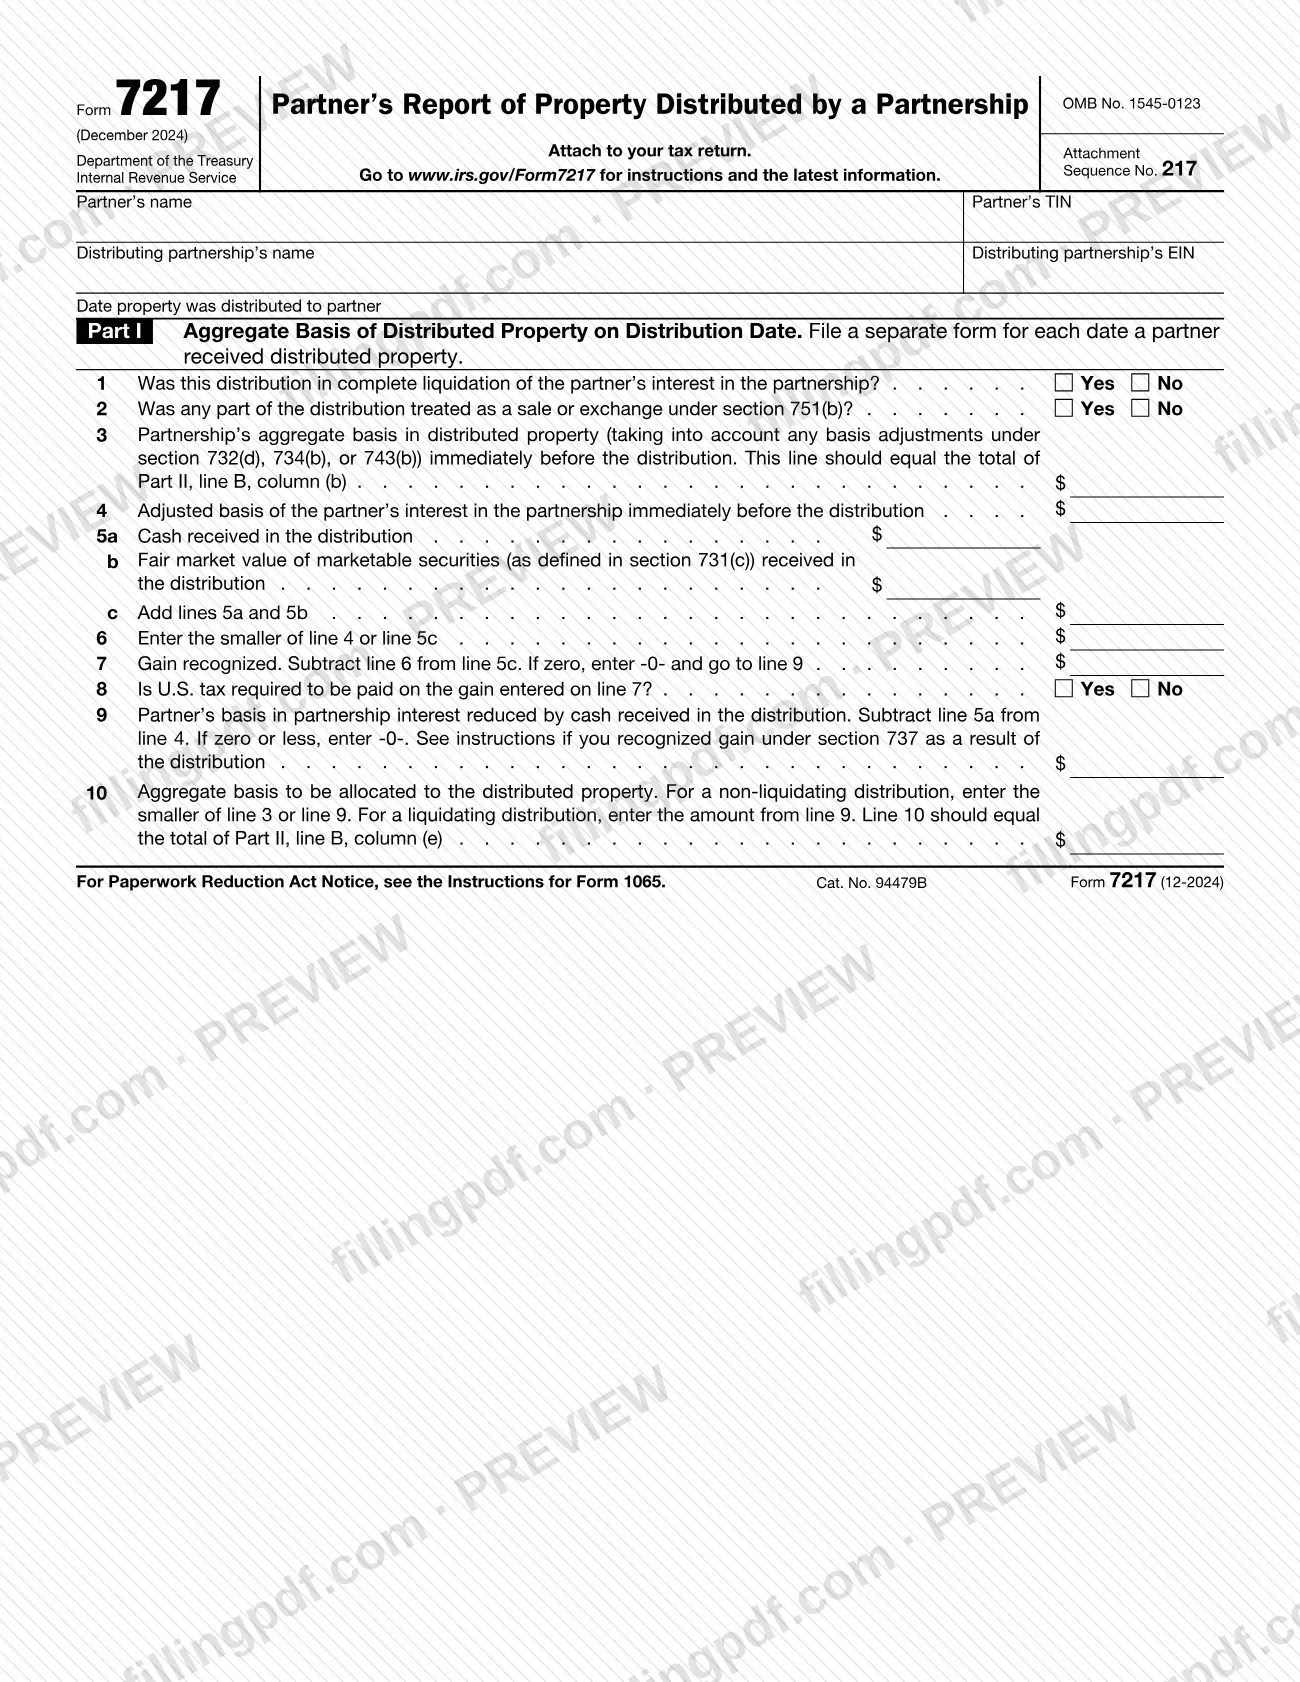
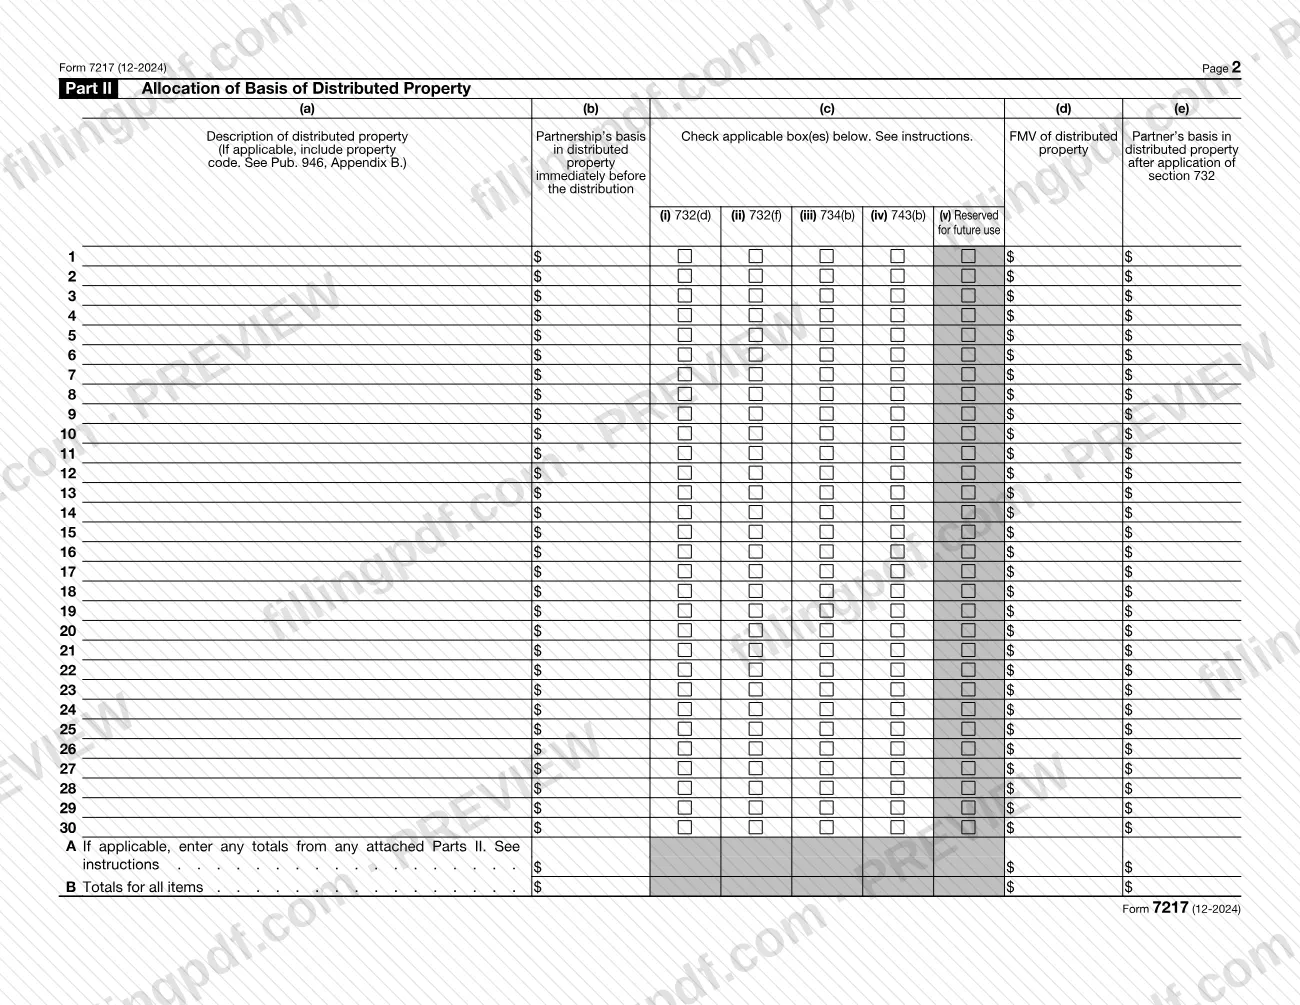
The Internal Revenue Service (IRS), part of the Department of the Treasury, issues it under OMB No. 1545-0123 as Attachment Sequence No. 217. The form has two parts. Part I (lines 1 to 10) works out the aggregate basis of the distributed property on the distribution date: whether the distribution liquidated your interest, whether section 751(b) applies, the partnership's basis in the property, your outside basis, cash and marketable securities received, any gain recognized, and the aggregate basis to be allocated. Part II lists each distributed property and allocates that basis among them, in columns (a) through (e).
The numbers come from two places. The partnership reports most of them on your Schedule K-1 (Form 1065), box 19, codes A, B and C, or in a section 732(d) statement attached to the K-1. The basis of your partnership interest is not on the K-1: you calculate it yourself.
Form 7217 is a partner's report. It is not a partnership return, and it is not filed for distributions of money only.
Who needs to file Form 7217?
Any partner who receives a distribution of property from a partnership, in a liquidating or non-liquidating distribution, and whose property is subject to section 732 files Form 7217. File a separate form for each date during the tax year on which you received distributed property, even if the distributions are part of the same transaction.
Do not file Form 7217 if:
- the distribution consisted only of money or marketable securities treated as money under section 731(c);
- the payment was made to you for services other than in your capacity as a partner under section 707(a)(1);
- the transfer is treated as a disguised sale under section 707(a)(2)(B).
The form is completed by the partner who received the property, using the partner's own name and taxpayer identification number (TIN), which can be a Social Security number. The instructions name no other person who may complete it on your behalf; the form is attached to your own tax return.
When to file Form 7217
Attach Form 7217 to your tax return for the tax year in which you received distributed property subject to section 732. It is due when that return is due, including extensions; the form has no separate due date.
Because you need one form per distribution date, a year with property distributions on several days produces several Forms 7217, all attached to the same return.
Use the December 2024 version for tax years beginning in 2024 or later, until the IRS issues a later revision. The IRS says later revisions will be posted at IRS.gov/Form7217, and its Form 7217 page lists an update, dated April 23, 2026, to the instructions about new reporting codes in box 19 of Schedule K-1 (Form 1065). Check that page before you complete the form.
Documents you need
- A statement showing the calculation of any income, gain or loss under section 751(b), only if any part of the distribution was treated as a sale or exchange under that section (line 2).
- Additional copies of Part II, only if the distribution includes more properties than fit on one page; report the totals from attached Parts II on Part II, line A.
How to fill out Form 7217
Enter partner and partnership details
At the top, enter your name, your TIN (which can be an SSN), the distributing partnership's name and EIN, and the date the property was distributed to you. Complete one form for each distribution date.
Answer lines 1 and 2
Line 1: check Yes or No for whether the distribution completely liquidated your interest. Line 2: check Yes or No for whether any part was treated as a sale or exchange under section 751(b); if Yes, attach the calculation statement.
Enter basis amounts on lines 3 and 4
Line 3: the partnership's aggregate basis in the distributed property (other than cash) immediately before the distribution, shown on Schedule K-1 (Form 1065), box 19, code C. Line 4: your adjusted outside basis immediately before the distribution, which you calculate yourself and which excludes any section 737 gain.
Report cash and securities on line 5
Line 5a: money received, including deemed distributions under section 752(b) (K-1 box 19, code A). Line 5b: fair market value of marketable securities under section 731(c). Line 5c: add lines 5a and 5b.
Figure gain on lines 6 to 8
Line 6: the smaller of line 4 or line 5c. Line 7: subtract line 6 from line 5c; if zero, enter -0- and go to line 9. Line 8: check Yes or No for whether U.S. tax is required on the gain on line 7.
Reduce your basis by cash on line 9
Subtract line 5a from line 4; if zero or less, enter -0-. If you recognized gain under section 737, include it, using the section 737 information on K-1 box 19, code B.
Find the aggregate basis on line 10
For a non-liquidating distribution, enter the smaller of line 3 or line 9. For a liquidating distribution, enter the amount from line 9. It should equal Part II, line B, column (e).
Describe each property in Part II
For each property, enter a description in column (a), with the asset class code from Pub. 946, Appendix B if applicable. In column (b), enter the partnership's basis immediately before the distribution, including any 732(d), 734(b) or 743(b) adjustments.
Check the column (c) boxes
Check any that apply: (i) 732(d), (ii) 732(f), (iii) 734(b), (iv) 743(b). Box (v) is reserved for future use. The 732(f) box applies to stock of another corporation held by a corporate partner that meets the instructions' 80% test.
Enter values in columns (d) and (e)
Column (d): fair market value of each property, reported on K-1 box 19, code C. Column (e): your basis in each property after applying section 732, using 732(a)(2) and (c) for non-liquidating distributions limited by outside basis, or 732(b) and (c) for liquidating ones.
Total Part II and check the match
Enter totals for all items on line B, and on line A any totals from attached Parts II. Confirm that line B, column (b) equals line 3 and column (e) equals line 10.
Review and download the completed PDF
Check every line against your Schedule K-1 (Form 1065) and your own basis calculation, then download or print the completed PDF from FillingPDF and attach it to your tax return.
How to submit Form 7217
Form 7217 has no filing channel of its own: you attach it to your tax return, and it is submitted through whatever channel you use to file that return. The form is marked "Attach to your tax return," and the instructions say it is due when the return is due, including extensions.
- With your return: attach one Form 7217 for each date you received distributed property. Add as many copies of Part II as you need if the distribution includes more than the 30 properties one page can list.
- Statement for section 751(b): if any part of the distribution was treated as a sale or exchange under section 751(b), attach a statement showing the calculation of your income, gain or loss under that section.
- Where to look for details: the instructions for the tax return you file with it explain how and where to send the return. The IRS publishes Form 7217, its instructions and the latest information at www.irs.gov/Form7217.
FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Combining distributions received on different dates on one form; the instructions require a separate Form 7217 for each date, even if the distributions are part of the same transaction.
- Filing Form 7217 when the distribution was only money or marketable securities treated as money under section 731(c).
- Filing the form for a payment for services under section 707(a)(1) or a transfer treated as a disguised sale under section 707(a)(2)(B).
- Including gain recognized under section 737 in line 4, the outside basis before the distribution; that gain is added on line 9 instead.
- Entering marketable securities as cash on line 5a; line 5a is money other than marketable securities treated as money, and securities go on line 5b at fair market value.
- Leaving line 3 different from the total of Part II, line B, column (b), or line 10 different from the total of line B, column (e); the form says each pair should be equal.
- Checking the 743(b) box in column (c) when you have no section 743(b) basis adjustment for that distributed property.
- Including in column (e) an increase in basis of marketable securities from gain recognized under section 731(c)(4); the instructions exclude it.
- Omitting the section 751(b) calculation statement when line 2 is answered Yes.
Frequently asked questions
What is Form 7217 used for?
Form 7217 is used by a partner who receives a property distribution from a partnership to report the basis of that property, including any basis adjustment required by section 732(a)(2) or (b). It applies to both liquidating and non-liquidating distributions and is attached to the partner's tax return.
Who has to file Form 7217?
Any partner who received distributed property subject to section 732 during the tax year files it, one form per distribution date. You do not file it if you received only money or marketable securities treated as money under section 731(c), or for service payments under section 707(a)(1) or disguised sales.
When is Form 7217 due?
It is due when your tax return is due, including extensions, because you attach it to the return for the tax year in which you received the distributed property. The form has no separate due date or filing address of its own.
Where do I find the numbers for Form 7217?
The partnership reports most of them on your Schedule K-1 (Form 1065), box 19: code A for money and marketable securities, code B for section 737 property, code C for basis and fair market value of distributed property. Your outside basis is not on the K-1; you calculate it.
Can I fill out Form 7217 online?
Yes. You can fill out the fillable PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the form for you; you attach it to your tax return and submit it through the IRS channels for that return.
Do I file one Form 7217 for several distributions?
Only if they happened on the same date. The instructions require a separate Form 7217 for each date you received distributed property during the tax year, even when the distributions are part of the same transaction.
What is the difference between lines 3 and 10 on Form 7217?
Line 3 is the partnership's aggregate basis in the distributed property before the distribution. Line 10 is the basis you allocate to that property: the smaller of line 3 or line 9 for a non-liquidating distribution, or the line 9 amount for a liquidating one. They can differ.
Where can I find the latest Form 7217 instructions?
The IRS posts the form, instructions and the latest information at www.irs.gov/Form7217. The December 2024 version is used for tax years beginning in 2024 or later until a later revision is issued, and the IRS page lists an April 23, 2026 update about new box 19 codes.
Ready to fill out Form 7217?
Fill out Form 7217 now