
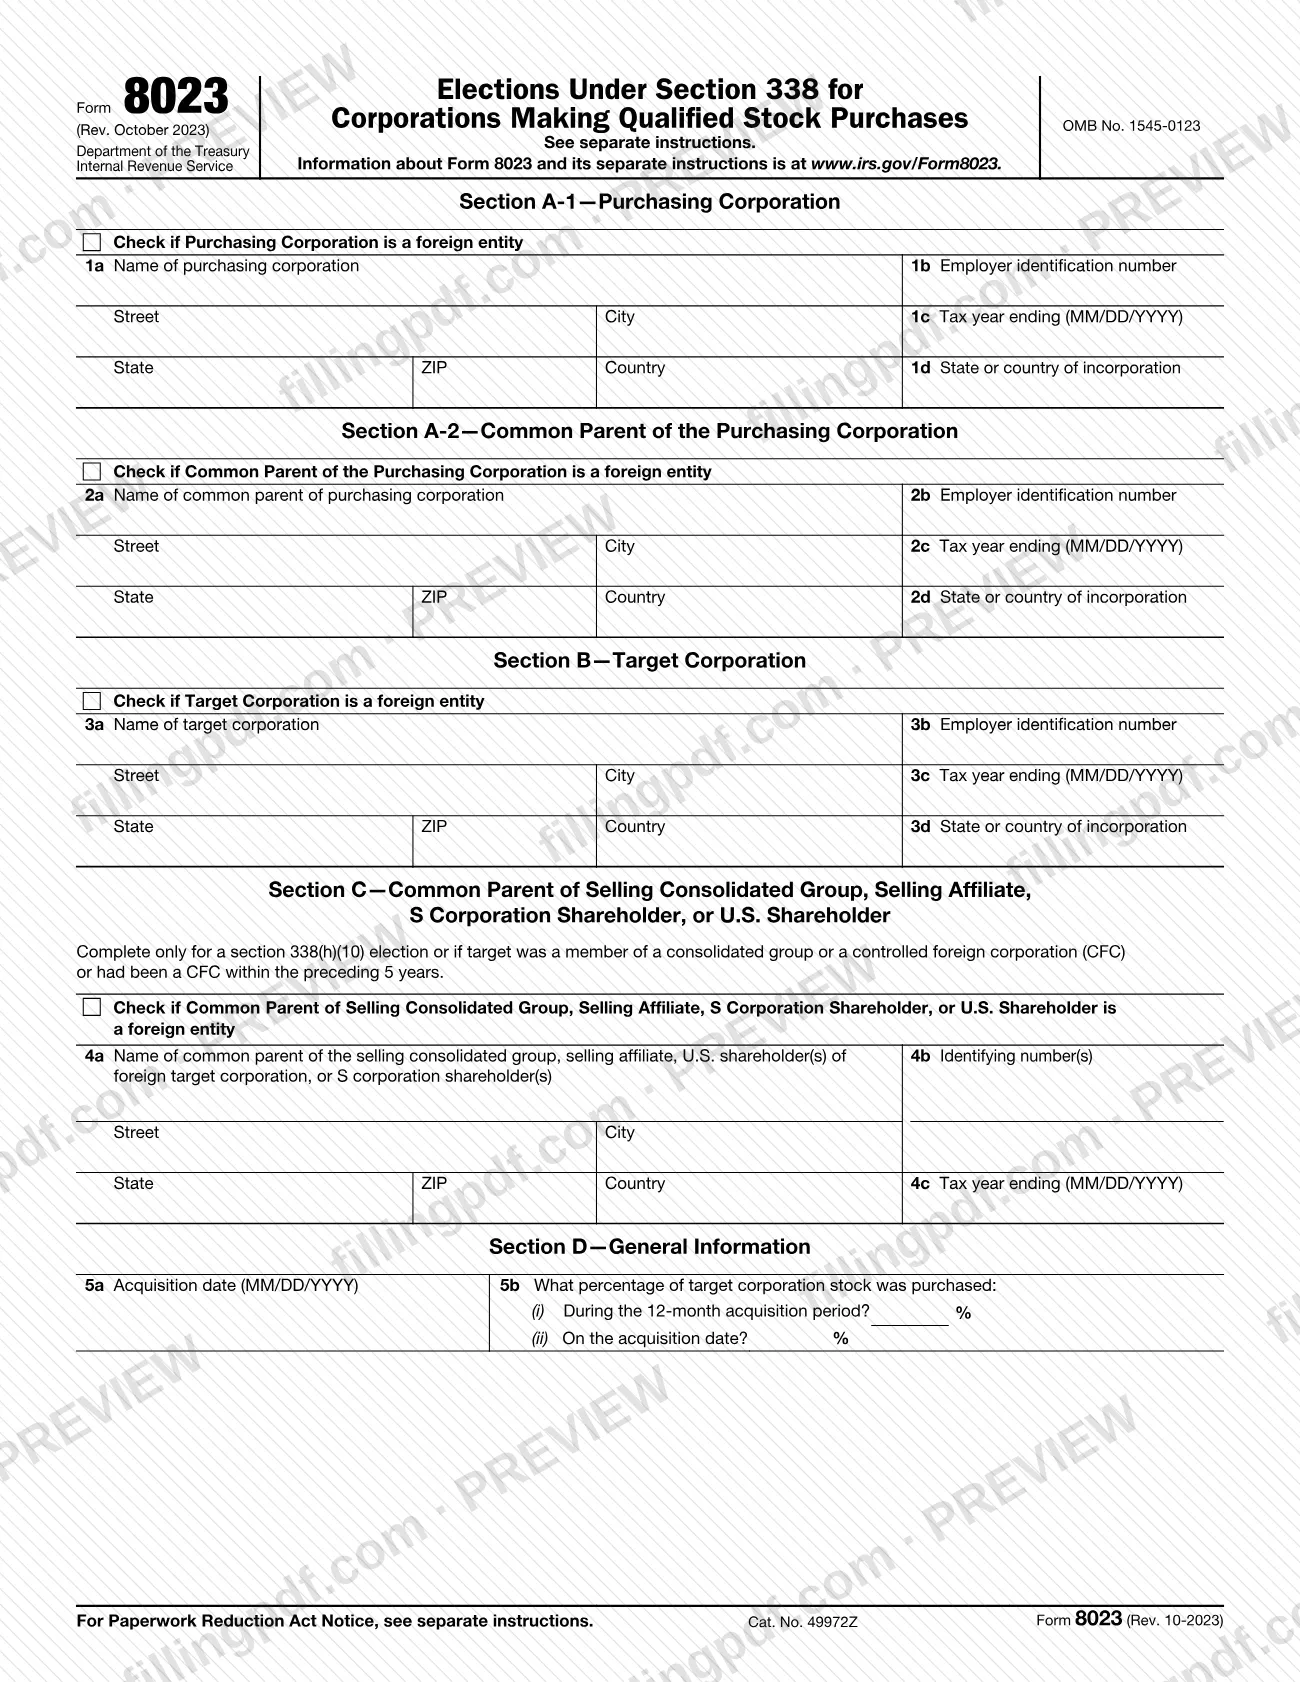
Form 8023 is the Internal Revenue Service (IRS) form that a purchasing corporation uses to make elections under section 338 for a target corporation after it has made a qualified stock purchase (QSP). It also carries the joint section 338(h)(10) election, which the selling side signs together with the purchaser. On this page you can fill out the form online on FillingPDF and download or print the completed PDF; the form and its separate instructions are published by the IRS at www.irs.gov/Form8023.
Last updated
What is 8023?
Form 8023, Elections Under Section 338 for Corporations Making Qualified Stock Purchases, is the IRS form used to make elections under section 338 for a "target" corporation when a purchasing corporation has made a qualified stock purchase (QSP) of that target.
The instructions define a QSP as the purchase by one corporation of at least 80% of the total voting power and value of another corporation's stock during a 12-month acquisition period. Preferred stock described in section 1504(a)(4) is not counted. The acquisition date is the first day on which a QSP has occurred.
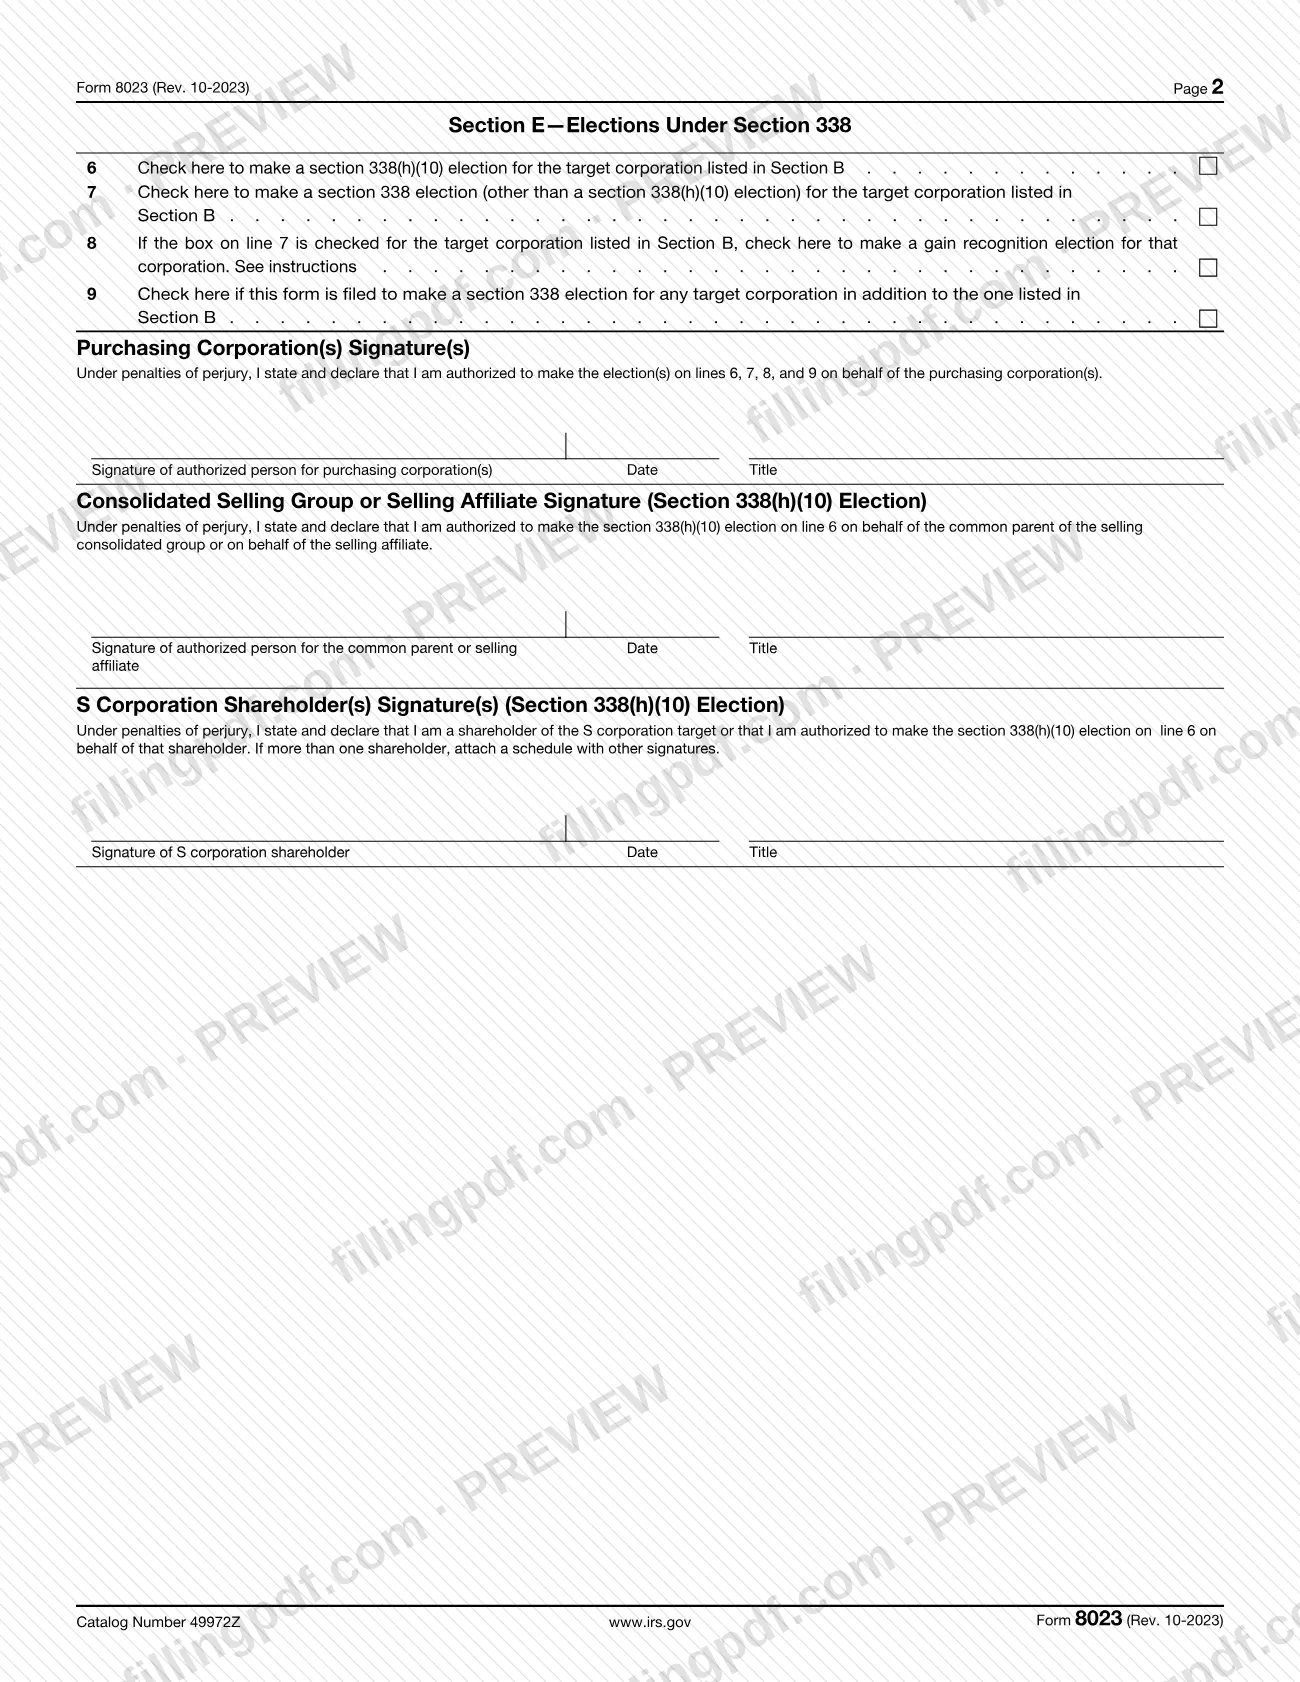
The form offers three elections on Section E:
- Line 6: a section 338(h)(10) election for the target in Section B.
- Line 7: a section 338 election other than a section 338(h)(10) election.
- Line 8: a gain recognition election, available when line 7 is checked.
Line 9 is checked when the form also covers other targets. With a section 338(g) election, the target is treated as having sold all of its assets on the acquisition date and then as a new corporation the next day. With a section 338(h)(10) election, the target is generally treated as making the deemed sale and liquidating. A section 338(h)(10) election can be made only for a target acquired from a selling consolidated group, a selling affiliate or an S corporation shareholder or shareholders.
The form has three pages: the form itself on pages 1 and 2, and a barcode page 3 added in the October 2023 revision.
Who needs to file 8023?
Generally, the purchasing corporation must file Form 8023 for the target corporation it acquired in a QSP.
- Section 338(h)(10) election: the form must be filed jointly by the purchasing corporation and the common parent of the selling consolidated group, the selling affiliate, or the S corporation shareholder(s). If the target is an S corporation, every S corporation shareholder must sign, including shareholders who do not sell stock in the QSP.
- Several purchasing affiliates: if members of an affiliated group buy target stock, a person authorized for each corporation signs; in a non-consolidated group the form is signed on behalf of each corporation.
- Foreign purchasing corporation: the U.S. shareholders of certain controlled foreign purchasing corporations described in Regulations section 1.338-2(e)(3) may make the election for it, but only if the purchasing corporation is not required under Regulations section 1.6012-2(g) to file a U.S. income tax return for the year that includes the acquisition date.
- Lower-tiered targets: if a section 338 election for a target results in a deemed QSP of a lower-tier target, a separate election for that lower-tier target is made on Form 8023, completed as if the purchasers of the directly purchased target were its purchasers.
One Form 8023 can cover several targets only if they share the same acquisition date and were in the same affiliated group both immediately before and immediately after that date.
When to file 8023
File Form 8023 by the 15th day of the 9th month after the acquisition date to make a section 338 election for the target corporation. The acquisition date is the first day on which a QSP has occurred, so the deadline runs from that date.
A foreign purchasing corporation may be subject to special timing. The instructions say that the period in which a qualifying foreign purchasing corporation may make a section 338 election for a qualifying foreign target is described in Regulations section 1.338-2(e)(1). For a foreign purchasing corporation, file Form 8023 for its tax year that includes the acquisition date.
The instructions set no other deadline and state no processing time for the form.
Documents you need
- Schedule for additional targets: when line 9 is checked, attach a schedule with the Section A-1, A-2, B, C and D information for each target other than the one in Section B, plus the elections (lines 6, 7, 8, 9) made for each, with its signature or signature attachment.
- Schedule for other purchasing corporations: when more than one affiliated group member buys target stock, attach the Section A-1 information for each purchaser other than the one listed, and a schedule showing which target stock each acquired.
- Schedule of other S corporation shareholders: for a section 338(h)(10) election on an S corporation target, attach the Section C information for each shareholder not listed on the form, with their signatures.
- Schedule of other U.S. shareholders: for a controlled foreign corporation (CFC) target, attach the requested information for each U.S. shareholder other than the one in Section C, and the name and EIN of the common parent of a shareholder's consolidated group where applicable.
- Gain recognition schedule: when a gain recognition election is actually made on line 8, attach the target's name and the name, address and EIN of each purchasing group member holding nonrecently purchased stock, with the declaration in the instructions, signed for each such member.
- Signature attachment: when multiple signatures are required, attach a "SIGNATURE ATTACHMENT" under the matching penalties-of-perjury declaration and write "See attached" in the form's signature area.
- Statement of U.S. shareholders: for an election made by the U.S. shareholders of a controlled foreign purchasing corporation, attach a statement with each shareholder's name, address, identifying number, country of organization and stock interest, signed by each.
- Schedule of foreign target stock purchases: for a foreign target, list each purchase date, each purchaser's name and percentage, and the name and place of incorporation of selling entities; add a schedule of the name and EIN or SSN of each notified affected U.S. person.
- Form 8883, Asset Allocation Statement Under Section 338: each U.S. shareholder of a foreign purchasing corporation or foreign target must file it with Form 5471, as the instructions state.
How to fill out 8023
Enter the purchasing corporation
In Section A-1, enter the name (line 1a), EIN (1b), address, tax year ending in MM/DD/YYYY format (1c) and state or country of incorporation (1d). Check the foreign-entity box if the purchasing corporation is foreign.
Complete the common parent section
If the purchasing corporation belongs to a consolidated group, complete Section A-2 with lines 2a to 2d for the common parent. Check the foreign-entity box if the common parent is foreign.
Identify the target corporation
In Section B, enter the target's name (line 3a), EIN (3b), address, tax year ending (3c) and state or country of incorporation (3d). The tax year ending date is determined without regard to any QSP.
Complete Section C when it applies
Complete Section C only for a section 338(h)(10) election, or if the target was a member of a consolidated group or a CFC or had been a CFC within the preceding 5 years. Enter the name on line 4a, the SSN (individual) or EIN (corporation) on line 4b, and the tax year ending on line 4c.
Enter acquisition date and percentages
On line 5a enter the acquisition date as MM/DD/YYYY. On line 5b give the percentage of target stock purchased (i) during the 12-month acquisition period and (ii) on the acquisition date.
Choose the section 338 election
On Section E, check line 6 for a section 338(h)(10) election, or line 7 for a section 338 election other than a section 338(h)(10) election. These are the elections for the target listed in Section B.
Decide on gain recognition and extra targets
Check line 8 for a gain recognition election only if line 7 is checked; attach the required schedule with its declaration. Check line 9 if the form also makes an election for any additional target, and attach the schedules.
Sign for the purchasing corporation
The authorized person for the purchasing corporation(s) signs, dates and enters a title under the penalties-of-perjury statement covering lines 6, 7, 8 and 9.
Add the selling-side signatures
For a section 338(h)(10) election, the common parent of the selling consolidated group or the selling affiliate signs in its block, and each S corporation shareholder signs in theirs. With multiple signatures, write "See attached" and attach a SIGNATURE ATTACHMENT.
Review, download and assemble
Check every line, the schedules and the signatures, then download or print the completed PDF from FillingPDF. Assemble the package for submission through the channels described under How to submit.
How to submit 8023
The IRS instructions give two channels for Form 8023: electronic fax and mail.
- Electronic fax: send the form and its attachments to 844-253-9765 (toll free). This fax line is only for Form 8023 and related attachments; other items will not be processed. The cover sheet should show the subject "Form 8023", the sender's name, title, phone number and street address, the date, and the number of pages faxed including the cover sheet. Do not put sensitive information such as an employer identification number (EIN) or Social Security number (SSN) on the cover sheet. A fax may not exceed 100 pages.
- Mail: if you do not have access to electronic fax, mail the completed form to Internal Revenue Service, OTSA Mail Stop 4916, 1973 Rulon White Blvd., Ogden, UT 84201.
Do not send Form 8023 to the Tax Forms and Publications Division address in Washington, DC, which is only for comments on the form. Schedules and signature attachments travel with the form. A U.S. shareholder of a controlled foreign purchasing corporation must also attach Form 8023 to Form 5471 for the tax year that includes the acquisition date. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Filing after the 15th day of the 9th month following the acquisition date, the deadline stated in the instructions.
- Sending Form 8023 to the Tax Forms and Publications Division address in Washington, DC; that address is only for comments, not filings.
- Putting an EIN or SSN on the fax cover sheet, which the instructions say must not include sensitive information.
- Faxing items other than Form 8023 and its attachments to 844-253-9765, or exceeding the 100-page fax limit.
- Leaving out the S corporation shareholders' signatures on a section 338(h)(10) election; every shareholder must sign, even one who does not sell stock in the QSP.
- Using one Form 8023 for several targets without checking line 9 or without attaching the schedule of Sections A-1, A-2, B, C and D information for each additional target.
- Entering more than one purchasing corporation in Section A-1; enter the member that bought the largest percentage by value and list the others on a schedule.
- Filing a gain recognition election on line 8 without the attached schedule and its required declaration.
- Entering multiple signatures in the signature area instead of writing "See attached" and using a signature attachment.
Frequently asked questions
What is Form 8023 used for?
Form 8023 is used to make elections under section 338 for a target corporation when a purchasing corporation has made a qualified stock purchase (QSP) of it. Section E offers a section 338(h)(10) election, another section 338 election, and a gain recognition election.
When is Form 8023 due?
By the 15th day of the 9th month after the acquisition date, which is the first day on which a QSP has occurred. Foreign purchasing corporations may have special timing; the instructions point to Regulations section 1.338-2(e)(1).
Where do I send Form 8023?
Fax it to 844-253-9765, or, if you have no electronic fax access, mail it to Internal Revenue Service, OTSA Mail Stop 4916, 1973 Rulon White Blvd., Ogden, UT 84201. Do not send it to the Washington, DC comments address in the instructions.
Who has to sign Form 8023 for a section 338(h)(10) election?
The purchasing corporation signs, the common parent of the selling consolidated group or the selling affiliate signs, and for an S corporation target every S corporation shareholder signs, even one who does not sell stock in the QSP.
What is a qualified stock purchase?
A QSP is the purchase by one corporation of at least 80% of the total voting power and value of another corporation's stock during a 12-month acquisition period. Preferred stock described in section 1504(a)(4) is not counted.
Can one Form 8023 cover more than one target corporation?
Yes, if each target has the same acquisition date and was a member of the same affiliated group immediately before and after that date. Check line 9 and attach schedules with the Section A-1, A-2, B, C and D information and the elections for each added target.
What goes on the fax cover sheet for Form 8023?
The subject "Form 8023", the sender's name, title, phone number and street address, the date, and the page count including the cover sheet. Do not include an EIN or SSN on the cover sheet, and keep the fax within 100 pages.
Can I fill out Form 8023 online on FillingPDF?
You can fill out the Form 8023 PDF online on FillingPDF and download or print it. FillingPDF is independent of the IRS and does not file or fax the form; you submit it through the IRS fax or mail channels.
Ready to fill out 8023?
Fill out 8023 now