
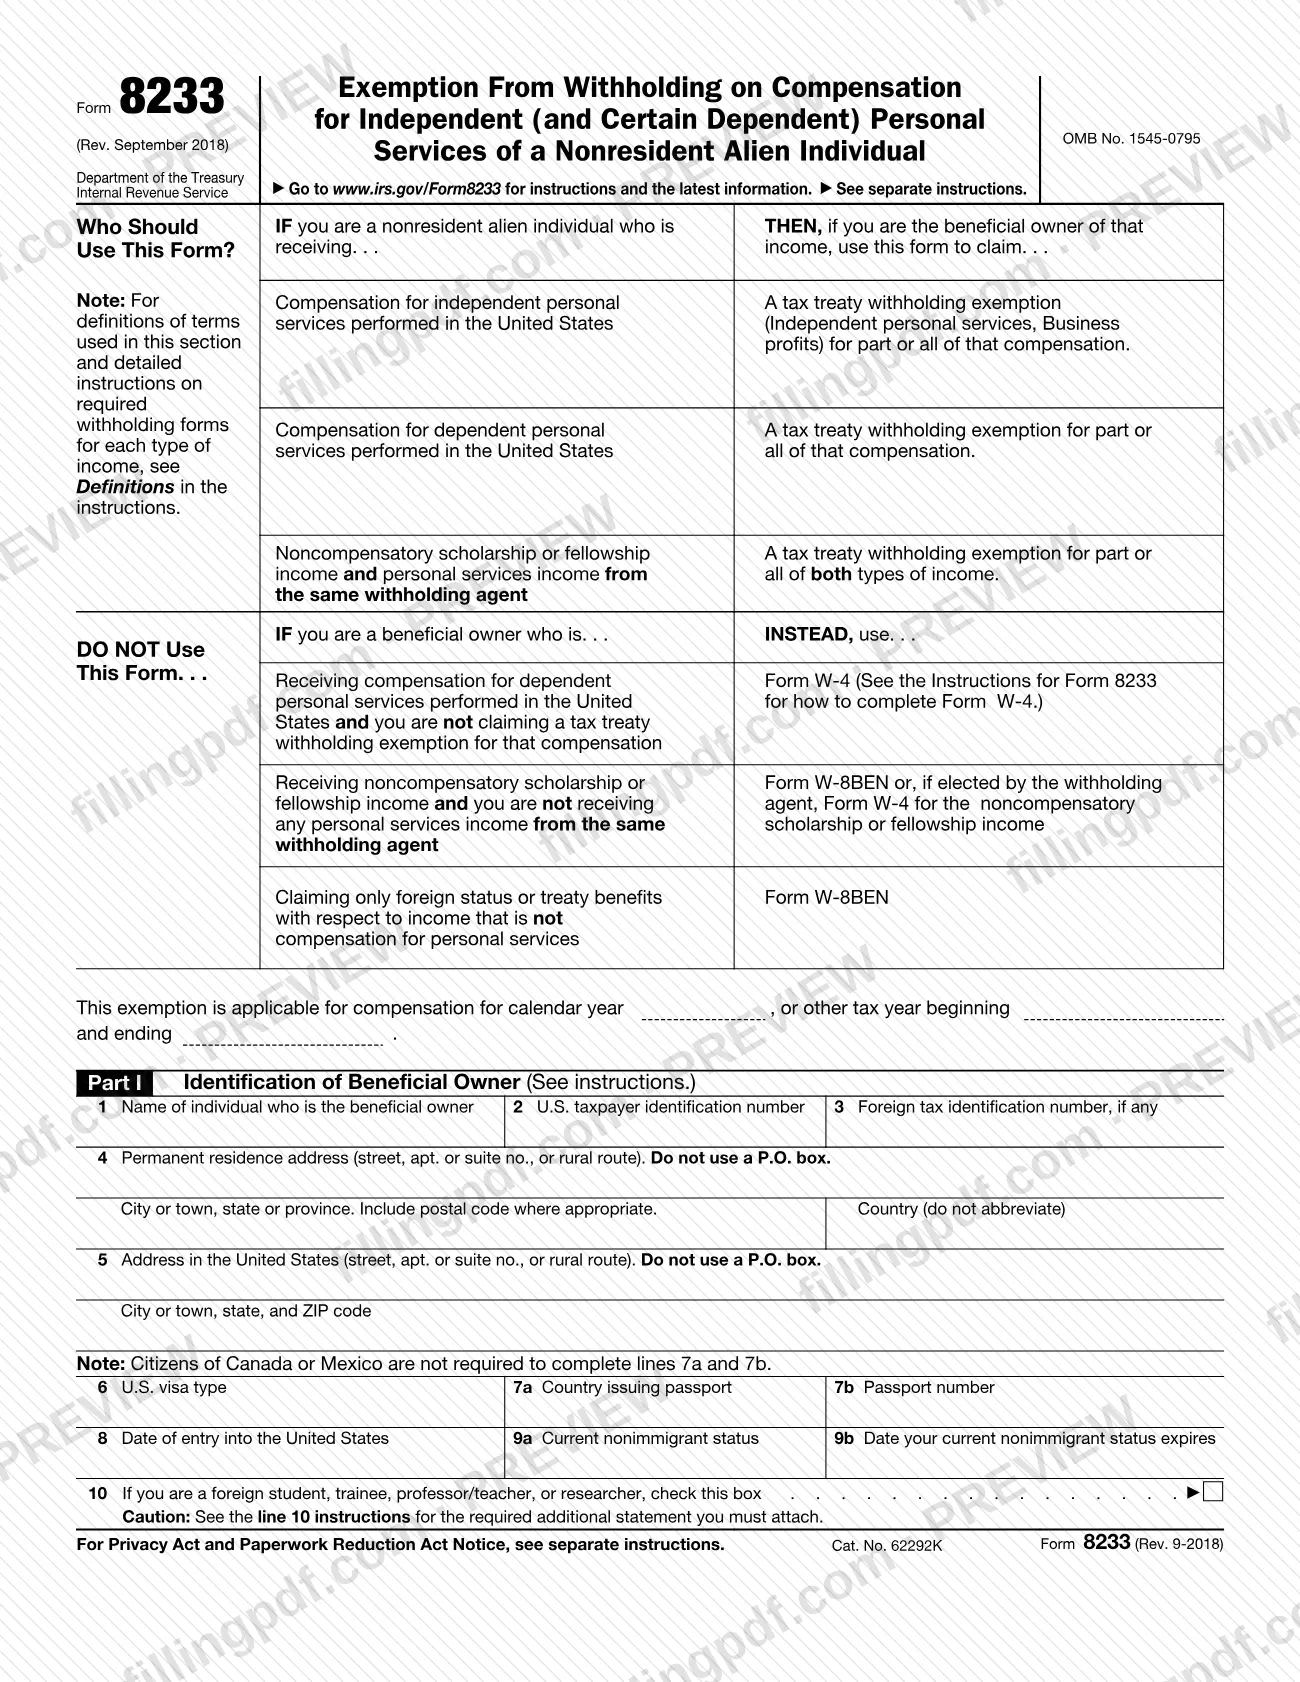
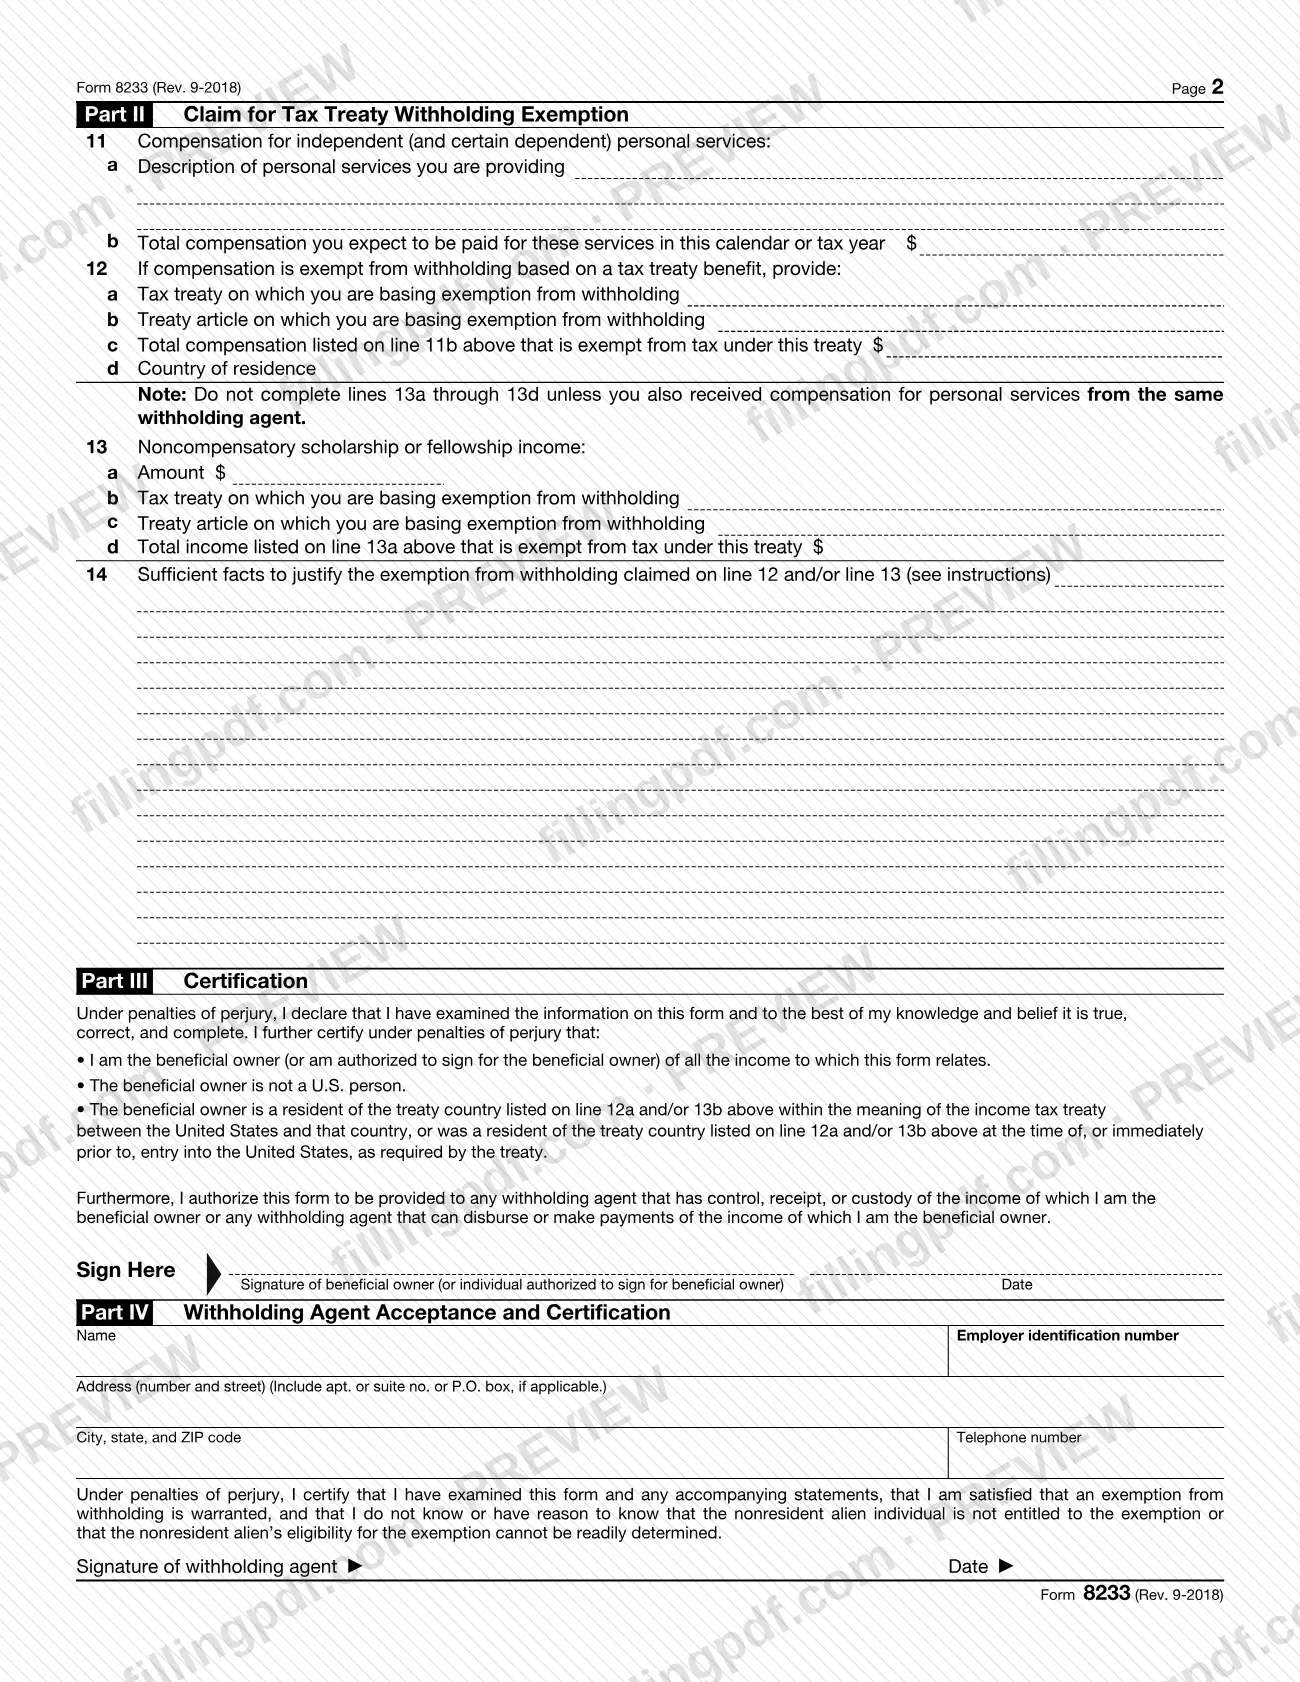
Form 8233 is the Internal Revenue Service (IRS) form a nonresident alien completes to claim a tax treaty exemption from withholding on compensation for personal services performed in the United States. You do not send it to the IRS yourself: you give the completed form to your withholding agent, who reviews it, completes Part IV and forwards a copy to the IRS. On this page you can fill out the form online on FillingPDF and download or print the completed PDF. The IRS publishes the form and its instructions at www.irs.gov/Form8233.
Last updated
What is 8233?
Form 8233 is the IRS form a nonresident alien gives a withholding agent to claim a tax treaty exemption from withholding on pay for personal services performed in the United States.
The Internal Revenue Service (IRS) issues it under OMB No. 1545-0795. The form has four parts: Part I identifies the beneficial owner of the income, Part II states the treaty claim, Part III is the beneficial owner's certification under penalties of perjury, and Part IV is the withholding agent's acceptance and certification.
The form covers three kinds of income: compensation for independent personal services, compensation for dependent personal services (including compensatory scholarship or fellowship income), and noncompensatory scholarship or fellowship income, but only when you also claim an exemption for personal services pay from the same withholding agent.
It is not the only withholding form. The form itself points to Form W-4 for dependent services pay without a treaty claim, and to Form W-8BEN for noncompensatory scholarship or fellowship income alone and for foreign status or treaty benefits on income that is not compensation for personal services.
Who needs to file 8233?
Use Form 8233 if you are a nonresident alien individual and the beneficial owner of income that falls into one of these groups:
- compensation for independent personal services performed in the United States, to claim a tax treaty withholding exemption for part or all of it;
- compensation for dependent personal services performed in the United States, to claim a tax treaty withholding exemption for part or all of it;
- noncompensatory scholarship or fellowship income, together with personal services income from the same withholding agent, to claim a treaty exemption for both.
Do not use Form 8233 in these cases:
- dependent personal services pay with no treaty exemption claimed (use Form W-4);
- noncompensatory scholarship or fellowship income with no personal services income from the same withholding agent (use Form W-8BEN, or Form W-4 if the withholding agent elects it);
- foreign status or treaty benefits only on income that is not compensation for personal services (use Form W-8BEN).
The instructions add limits. Independent contractors with an office or fixed base in the United States generally cannot claim a treaty exemption. The IRS typically cannot accept Form 8233 from athletes and entertainers. Spouses and dependents on secondary visas such as F-2, J-2, H-4 and O-3 are usually not eligible for the primary visa holder's treaty benefits. The beneficial owner or an authorized agent signs.
When to file 8233
Complete Form 8233 when some or all of your compensation for personal services is exempt from withholding under a tax treaty, and give it to your withholding agent before the payments it covers. The instructions set no calendar due date; the timing follows your payments.
You must complete a separate form for each tax year, each withholding agent and each type of income, and you enter the tax year in the space above Part I.
After the withholding agent accepts the form, the agent forwards a copy to the IRS within 5 days of acceptance. The exemption applies retroactively to the first payment the form covers, even though the agent must wait at least 10 days after properly mailing the form to the IRS to see whether the IRS has objections.
Documents you need
- The statement required by the line 10 instructions, if you are a foreign student, trainee, professor/teacher or researcher claiming a treaty exemption on personal services pay; its format is in Appendix A and Appendix B of Pub. 519.
- A copy of a completed Form W-7 or Form SS-5, only if you have applied for an ITIN or SSN but have not yet received it, to show that a number has been applied for.
How to fill out 8233
Enter the tax year
In the line above Part I, enter the calendar year, or the other tax year's beginning and ending dates, for which the exemption applies. Use a separate form for each tax year.
Identify yourself in lines 1 to 3
Line 1: your name as the beneficial owner. Line 2: your U.S. taxpayer identification number, in most cases your SSN, or an ITIN if you cannot get an SSN. Line 3: the tax ID issued by your country of tax residence, if any.
Enter your addresses
Line 4: your permanent residence address in the country where you claim residence, with no P.O. box and the country not abbreviated. Line 5: your address in the United States, also with no P.O. box.
Enter visa and entry details
Line 6: your U.S. visa type, or "None". Lines 7a and 7b: passport country and number; citizens of Canada or Mexico need not complete them. Lines 8, 9a and 9b: date of entry, current nonimmigrant status and its expiration date, or "DS" for duration of status.
Check line 10 if it applies
If you are a foreign student, trainee, professor/teacher or researcher, check the box and attach the statement described in the line 10 instructions.
Describe the services on line 11
Line 11a: a short description of the personal services you are providing, such as "teaching at ABC University". Line 11b: the total compensation you expect from this withholding agent during the year; an estimate is acceptable.
Complete the treaty claim on line 12
Line 12a: the specific treaty, such as "U.S.–Germany tax treaty". Line 12b: the article and paragraph. Line 12c: write "All" if all the income is exempt, or the exact exempt dollar amount. Line 12d: your country of residence.
Complete line 13 only if it applies
Fill in lines 13a through 13d for noncompensatory scholarship or fellowship income only if you also receive personal services pay from the same withholding agent. Give the amount, treaty, article and exempt amount.
Justify the exemption on line 14
Give enough facts to support the exemption claimed on line 12 and/or line 13 so the IRS can determine the treaty benefit.
Sign and date Part III
Sign and date the certification as the beneficial owner, or as an authorized agent. Leave Part IV blank: the withholding agent completes it.
Review and download the completed PDF
Check each line against your visa and treaty details, then download or print the completed PDF from FillingPDF. Give it, with any attachments, to your withholding agent as described under How to submit.
How to submit 8233
You give Form 8233 to your withholding agent; the agent forwards it to the IRS. You do not mail it to the IRS yourself.
- To the withholding agent: hand over the completed and signed form with any required attachments, such as the line 10 statement. The agent reviews it and, if satisfied that the exemption is warranted, completes and signs Part IV.
- Copies: the agent needs three copies of the completed form, each with your attachments. One goes to you, one stays with the agent, and one goes to the IRS.
- By mail from the agent: within 5 days of acceptance, to Department of the Treasury, Internal Revenue Service, Philadelphia, PA 19255-0725.
- By fax from the agent: 267-941-1365, limited to 25 pages at one time.
The IRS says not to send the form to its Tax Forms and Publications address in Washington, DC; give it to your withholding agent instead. If the IRS finds a form unacceptable, it notifies the withholding agent, who must begin withholding immediately. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Leaving the tax year blank in the space above Part I; the form is effective only for the year you specify.
- Using one form for several tax years, withholding agents or types of income; a separate Form 8233 is required for each.
- Forgetting the line 10 statement when you are a foreign student, trainee, professor/teacher or researcher.
- Claiming treaty benefits for a country with no ratified U.S. tax treaty, or benefits that do not exist in your treaty.
- Entering a P.O. box on line 4 or line 5, which both say not to use one, or abbreviating the country name on line 4.
- Giving too little detail on lines 11 through 14 for the IRS to determine the treaty benefit claimed.
- Completing lines 13a through 13d without also receiving personal services pay from the same withholding agent.
- Skipping the Part III certification or signature; an incomplete form cannot be accepted and the agent must withhold.
- Using Form 8233 for dependent services pay with no treaty claim, when the form directs you to Form W-4.
Frequently asked questions
What is Form 8233 used for?
Form 8233 is used by a nonresident alien to claim a tax treaty exemption from withholding on compensation for personal services performed in the United States. You give it to the withholding agent that pays you, not to the IRS directly.
What is the difference between Form 8233 and Form W-8BEN?
Form 8233 claims a treaty exemption on pay for personal services. Form W-8BEN is used for noncompensatory scholarship or fellowship income alone, and for foreign status or treaty benefits on income that is not compensation for personal services.
Do I send Form 8233 to the IRS?
No. You give the completed form to your withholding agent. If the agent is satisfied, the agent completes Part IV and, within 5 days of acceptance, forwards a copy to the IRS in Philadelphia, PA 19255-0725 or by fax to 267-941-1365.
Do I need a separate Form 8233 for each employer?
Yes. The instructions require a separate form for each tax year, for each withholding agent and for each type of income. A professor who also lectures at other institutions gives each institution its own form.
Do I need a Social Security number to complete Form 8233?
You must give a U.S. taxpayer identification number on line 2, in most cases your SSN. If you cannot get an SSN, you need an ITIN, applied for with Form W-7. If your number is pending, attach a copy of the completed Form W-7 or SS-5.
What do I attach to Form 8233 as a foreign student or researcher?
If you are a foreign student, trainee, professor/teacher or researcher, check line 10 and attach the required statement. Its format and contents are shown in Appendix A and Appendix B of Pub. 519.
Who signs Form 8233?
The beneficial owner signs and dates Part III, or an authorized agent may sign for the beneficial owner. The withholding agent separately signs Part IV. The instructions refer to Regulations section 1.1441-7(c) for authorized agents.
Can I fill out Form 8233 online?
You can fill out the Form 8233 PDF online on FillingPDF and download or print it. FillingPDF is independent of the IRS and does not submit the form; you give it to your withholding agent.
Ready to fill out 8233?
Fill out 8233 now