
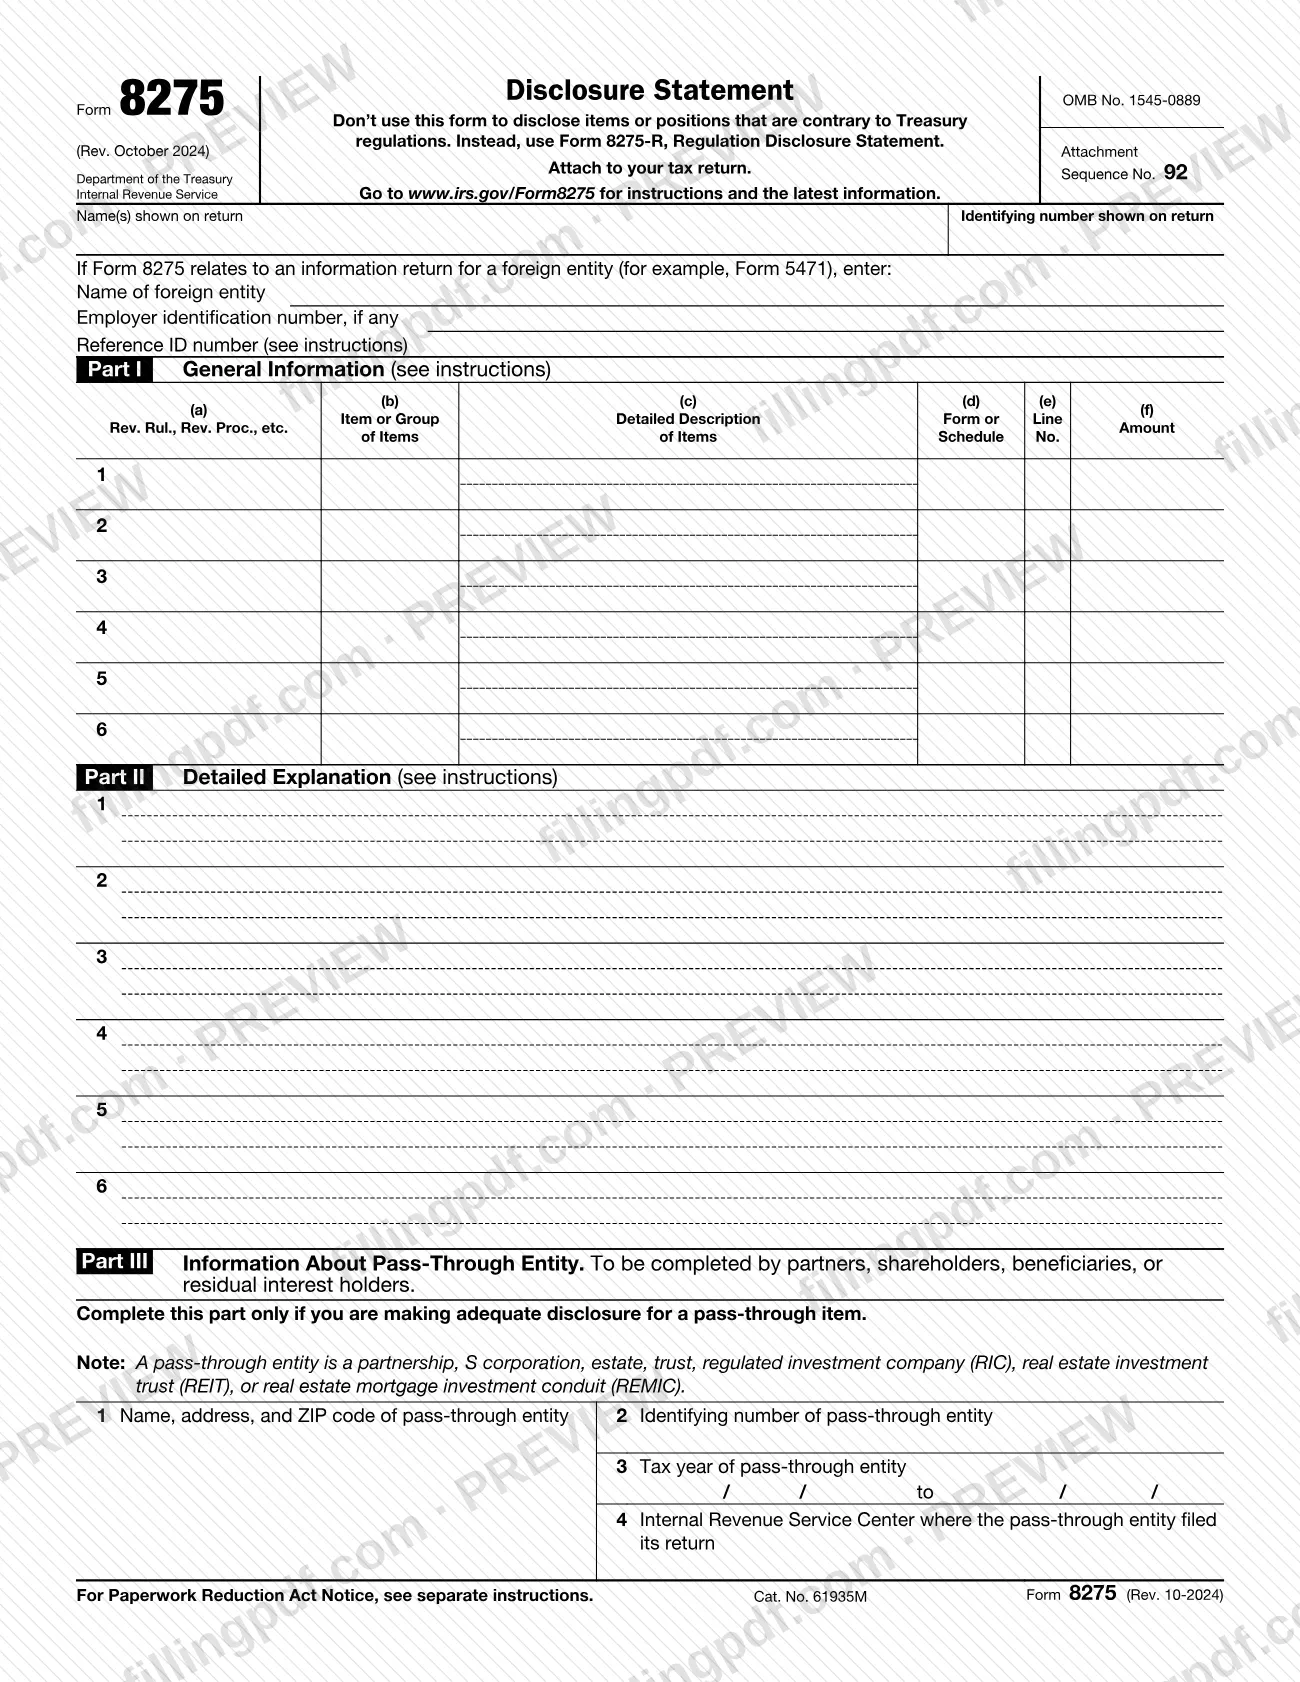
Form 8275, Disclosure Statement, is the Internal Revenue Service (IRS) form used to disclose items or positions on a tax return that are not otherwise adequately disclosed, so that certain penalties can be avoided. Individuals, corporations, pass-through entities and tax return preparers use it, except for positions taken contrary to a regulation, which go on Form 8275-R. On this page you can fill out the form online on FillingPDF and download or print the completed PDF. The form and its instructions are published by the IRS at www.irs.gov/Form8275.
Last updated
What is 8275?
Form 8275, Disclosure Statement, is the IRS form that taxpayers and tax return preparers attach to a tax return to disclose items or positions that are not otherwise adequately disclosed, in order to avoid certain penalties.
The instructions explain that the form is filed to avoid the portions of the accuracy-related penalty due to disregard of rules or to a substantial understatement of income tax for non-tax shelter items, when the return position has a reasonable basis. It can also be used for disclosures relating to the economic substance penalty and to the preparer penalties for tax understatements due to unreasonable positions or disregard of rules.
Disclosure on this form has limits. The instructions say it cannot avoid the portion of the accuracy-related penalty attributable to negligence, disregard of regulations, a substantial understatement on a tax shelter item, valuation misstatements, or a transaction lacking economic substance, among other listed types of misconduct. If you failed to keep proper books and records or to substantiate the items, disclosure does not avoid the penalty.
The form is not for positions taken contrary to a regulation: the form itself directs those to Form 8275-R, Regulation Disclosure Statement.
The form has four parts: Part I (general information about each item), Part II (detailed explanation), Part III (information about a pass-through entity) and Part IV (continued explanations). It is OMB No. 1545-0889, Attachment Sequence No. 92, Rev. October 2024.
Who needs to file 8275?
The IRS instructions say Form 8275 is filed by individuals, corporations, pass-through entities and tax return preparers who want to disclose an item or position, other than one taken contrary to a regulation, that is not otherwise adequately disclosed on a return.
- Partners, shareholders, beneficiaries and residual interest holders complete Part III when making adequate disclosure for a pass-through item. Disclosure for such items should be made on the entity's own return; if the entity does not make it, the partner or shareholder can. A pass-through entity is a partnership, S corporation, estate, trust, regulated investment company (RIC), real estate investment trust (REIT) or real estate mortgage investment conduit (REMIC).
- Filers with foreign entities that are the subject of an information return, such as Form 5471, complete the foreign entity block at the top of the form.
Do not use Form 8275 for a position contrary to a regulation; use Form 8275-R. You also do not have to file it for items that meet the requirements of the annual revenue procedure published in the Internal Revenue Bulletin. For example, the instructions say a charitable contribution deduction is generally adequately disclosed if you complete the Gifts to Charity section of Schedule A (Form 1040), supply all required information and attach the required related forms.
If the position relates to a reportable transaction, you must also make the disclosure described in Regulations section 1.6011-4(d); see Form 8886.
When to file 8275
File Form 8275 with your original tax return. The instructions also say you may be able to file it with an amended return; they refer to Regulations sections 1.6662-4(f)(1) and 1.6664-2(c)(3). For the economic substance rules, disclosure can be made with a timely filed original return (determined with regard to extensions) or a qualified amended return.
Timing differs by type of item:
- Carryovers and carrybacks: disclose them for the tax year in which they originated. You do not have to file another Form 8275 for the years in which the carryover or carryback is taken into account.
- Recurring items, such as depreciation expense: file Form 8275 for each tax year in which the item occurs.
If you filed a Schedule UTP (Form 1120), you may not need Form 8275 to meet the economic substance disclosure requirements; see the Instructions for Schedule UTP (Form 1120).
Documents you need
- The tax return to which Form 8275 is attached; the disclosure is made with the return, and it is not valid unless the completed form is attached.
- Continuation sheets, only if you need more room than Parts I and II give; Part IV or extra sheets must show your name and identifying number and the matching part and line number.
- Form 8886, Reportable Transaction Disclosure Statement, only if the position relates to a reportable transaction under Regulations section 1.6011-4(b).
- Form 8275-R, Regulation Disclosure Statement, instead of Form 8275, only when the position is contrary to a regulation.
How to fill out 8275
Enter your name and identifying number
At the top, enter the name(s) shown on your return and the identifying number shown on the return.
Complete the foreign entity block
Fill this in only if Form 8275 relates to an information return for a foreign entity, such as Form 5471. Enter the name of the foreign entity, its employer identification number if any, and the same Reference ID number used on the information return.
Identify the rule in column (a)
In Part I, column (a) (Rev. Rul., Rev. Proc., etc.), identify the rule, such as a statutory provision or IRS revenue ruling, if you are disclosing a position contrary to a rule.
Name and describe each item
In column (b), identify the item by name, and mark it as a pass-through item if it comes from a pass-through entity. In column (c), give a complete description; for a group of similar items with the same tax treatment, describe the group.
Enter form, line and amount
In Part I, enter the form or schedule number in column (d), the line number in column (e) and the amount of the item(s) in column (f).
Write the detailed explanation
In Part II, for each item number from Part I, describe the relevant facts affecting its tax treatment. Include enough to tell the IRS the identity of the item, its amount and the nature of the controversy or potential controversy.
Complete the pass-through entity part
Part III is for partners, shareholders, beneficiaries or residual interest holders disclosing a pass-through item. Enter the entity's name, address and ZIP code (line 1), its identifying number (line 2) and its tax year (line 3).
Show where the entity filed
On Part III, line 4, enter the IRS Service Center where the entity filed its return, which you can find on the Schedule K-1 for partners and S corporation shareholders. If the entity e-filed, enter "e-file".
Use Part IV for extra space
Continue Parts I and/or II in Part IV on page 2, with the part and line number from page 1. Put your name and identifying number on each additional sheet.
Review and download the completed PDF
Check that every part you need is complete and that each pass-through or foreign entity has its own form. Download or print the completed PDF from FillingPDF and attach it to your tax return as described under How to submit.
How to submit 8275
Form 8275 is not filed on its own: it is attached to your tax return and goes to the IRS with that return. The form prints no separate address, portal or appointment rule.
- With the original return: attach the completed Form 8275 to the return and file the return through the channel that return uses. Keep a copy for your records.
- With an amended return: the instructions say you may be able to file Form 8275 this way; see Regulations sections 1.6662-4(f)(1) and 1.6664-2(c)(3).
- Separate forms: complete and file a separate Form 8275 for each pass-through entity whose items you disclose, and a separate form for each foreign entity.
- Extra space: use Part IV on page 2 or continuation sheets, with your name and identifying number on each sheet.
The disclosure counts only if Form 8275 is completed and attached to the return; the instructions say a letter or another form attached instead is not a valid disclosure. For the latest information, go to www.irs.gov/Form8275. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Using Form 8275 to disclose a position contrary to a regulation; the form directs those disclosures to Form 8275-R.
- Attaching a letter, an acquisition agreement or another form instead of Form 8275; the instructions say the disclosure is not valid unless Form 8275 is completed and attached.
- Combining items from more than one pass-through entity, or more than one foreign entity, on a single Form 8275; each entity needs its own form.
- Not filing Form 8275 for each year a recurring item, such as depreciation expense, occurs.
- Assuming disclosure avoids the penalty for negligence, disregard of regulations or a tax shelter item; the instructions list types of misconduct it cannot cure.
- Leaving out the rule in column (a) when disclosing a position contrary to a rule such as a statutory provision or revenue ruling.
- Not identifying an item from a pass-through entity as such in column (b).
- Omitting your name and identifying number on a continuation sheet or Part IV page.
- Entering a reference ID number for a foreign entity that differs from the one on its information return, such as Form 5471.
Frequently asked questions
What is Form 8275 used for?
Form 8275 is the IRS Disclosure Statement used to disclose items or positions that are not otherwise adequately disclosed on a tax return, to avoid certain penalties. Taxpayers and tax return preparers file it, except for positions contrary to a regulation, which use Form 8275-R.
What is the difference between Form 8275 and Form 8275-R?
Form 8275 discloses items or positions other than those taken contrary to a regulation. Form 8275-R, Regulation Disclosure Statement, is the form for positions contrary to a regulation. The instructions and the form itself both direct regulation positions to Form 8275-R.
When do I file Form 8275?
File it with your original tax return. The instructions say you may be able to file it with an amended return, and refer to Regulations sections 1.6662-4(f)(1) and 1.6664-2(c)(3). Recurring items, such as depreciation, need a Form 8275 for each year they occur.
Where do I send Form 8275?
You attach it to your tax return and file it with that return; the form prints no separate address. Keep a copy for your records. Instructions and the latest information are at www.irs.gov/Form8275.
Does disclosing on Form 8275 avoid every accuracy-related penalty?
No. Disclosure helps with the disregard of rules and substantial understatement portions when the position has a reasonable basis. It cannot avoid the portion tied to negligence, disregard of regulations or tax shelter understatements, among others, and does not help if books and records were not kept.
Do I need a separate Form 8275 for each pass-through entity?
Yes. To adequately disclose items reported by a pass-through entity, complete and file a separate Form 8275 for items from each entity. The same applies to positions related to more than one foreign entity: one form per foreign entity.
Can I skip Form 8275 for some items?
Yes, for items that meet the requirements of the annual revenue procedure published in the Internal Revenue Bulletin that identifies when a reported item counts as adequately disclosed. The instructions give the Gifts to Charity section of Schedule A (Form 1040) as an example.
Can I fill out Form 8275 online?
You can fill out the Form 8275 PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the form with the IRS; you attach it to your tax return and submit that return through the IRS channels.
Ready to fill out 8275?
Fill out 8275 now