
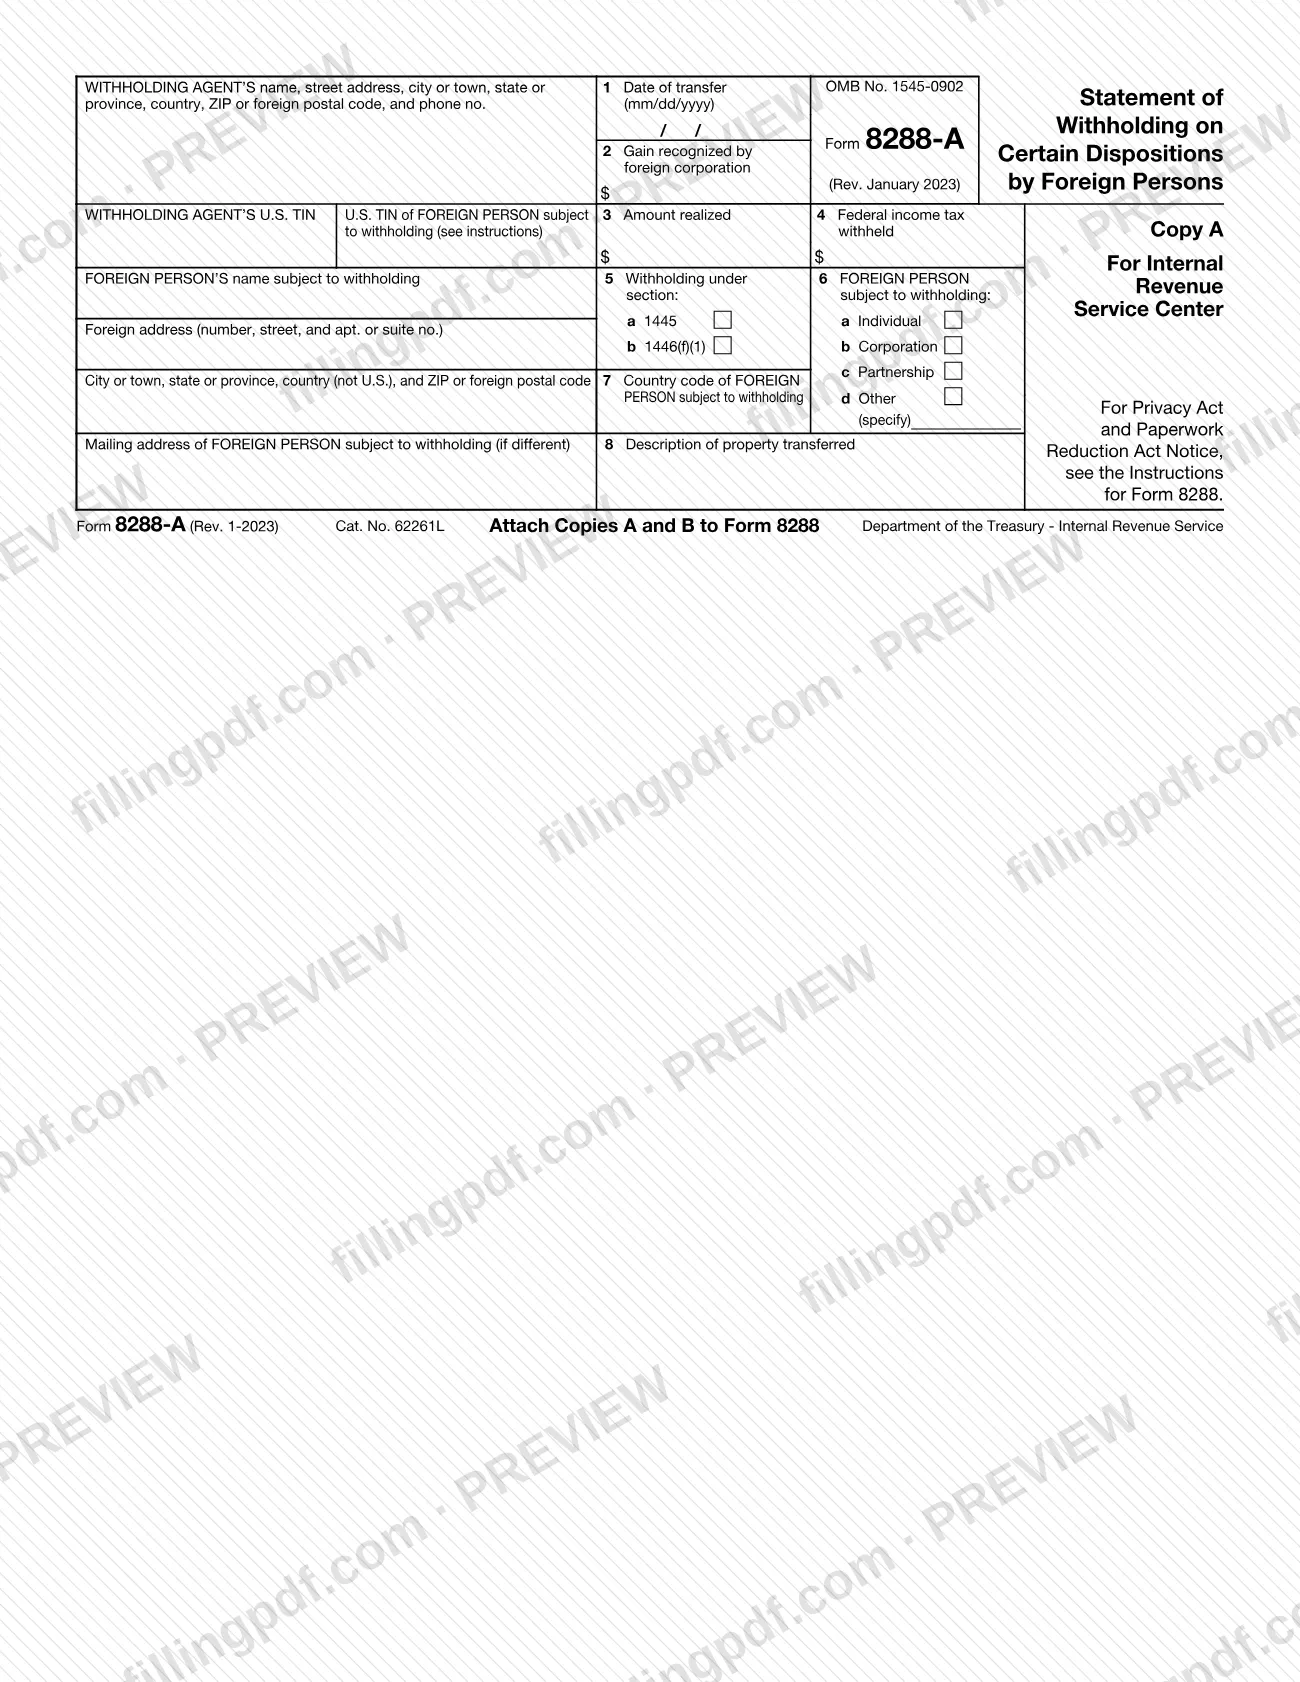
Form 8288-A is the Internal Revenue Service (IRS) statement that reports the tax withheld when a foreign person disposes of a U.S. real property interest. The buyer or other withholding agent prepares one for each foreign person subject to withholding and attaches Copies A and B to Form 8288. On this page you can fill out Form 8288-A online on FillingPDF and download or print the completed PDF; the IRS publishes the original form and the Instructions for Form 8288 at irs.gov.
Last updated
What is 8288-A?
Form 8288-A, Statement of Withholding on Dispositions by Foreign Persons of U.S. Real Property Interests (printed on the form as Statement of Withholding on Certain Dispositions by Foreign Persons), is the IRS form on which a withholding agent reports the federal income tax withheld for one foreign person.
The IRS agency page describes it this way: buyers and transferees use it with Form 8288 for each foreign person that disposes of real property located in the United States, to report withholding on the amount realized. Form 8288 is the U.S. Withholding Tax Return for Certain Dispositions by Foreign Persons; Form 8288-A is the per-person statement attached to it.
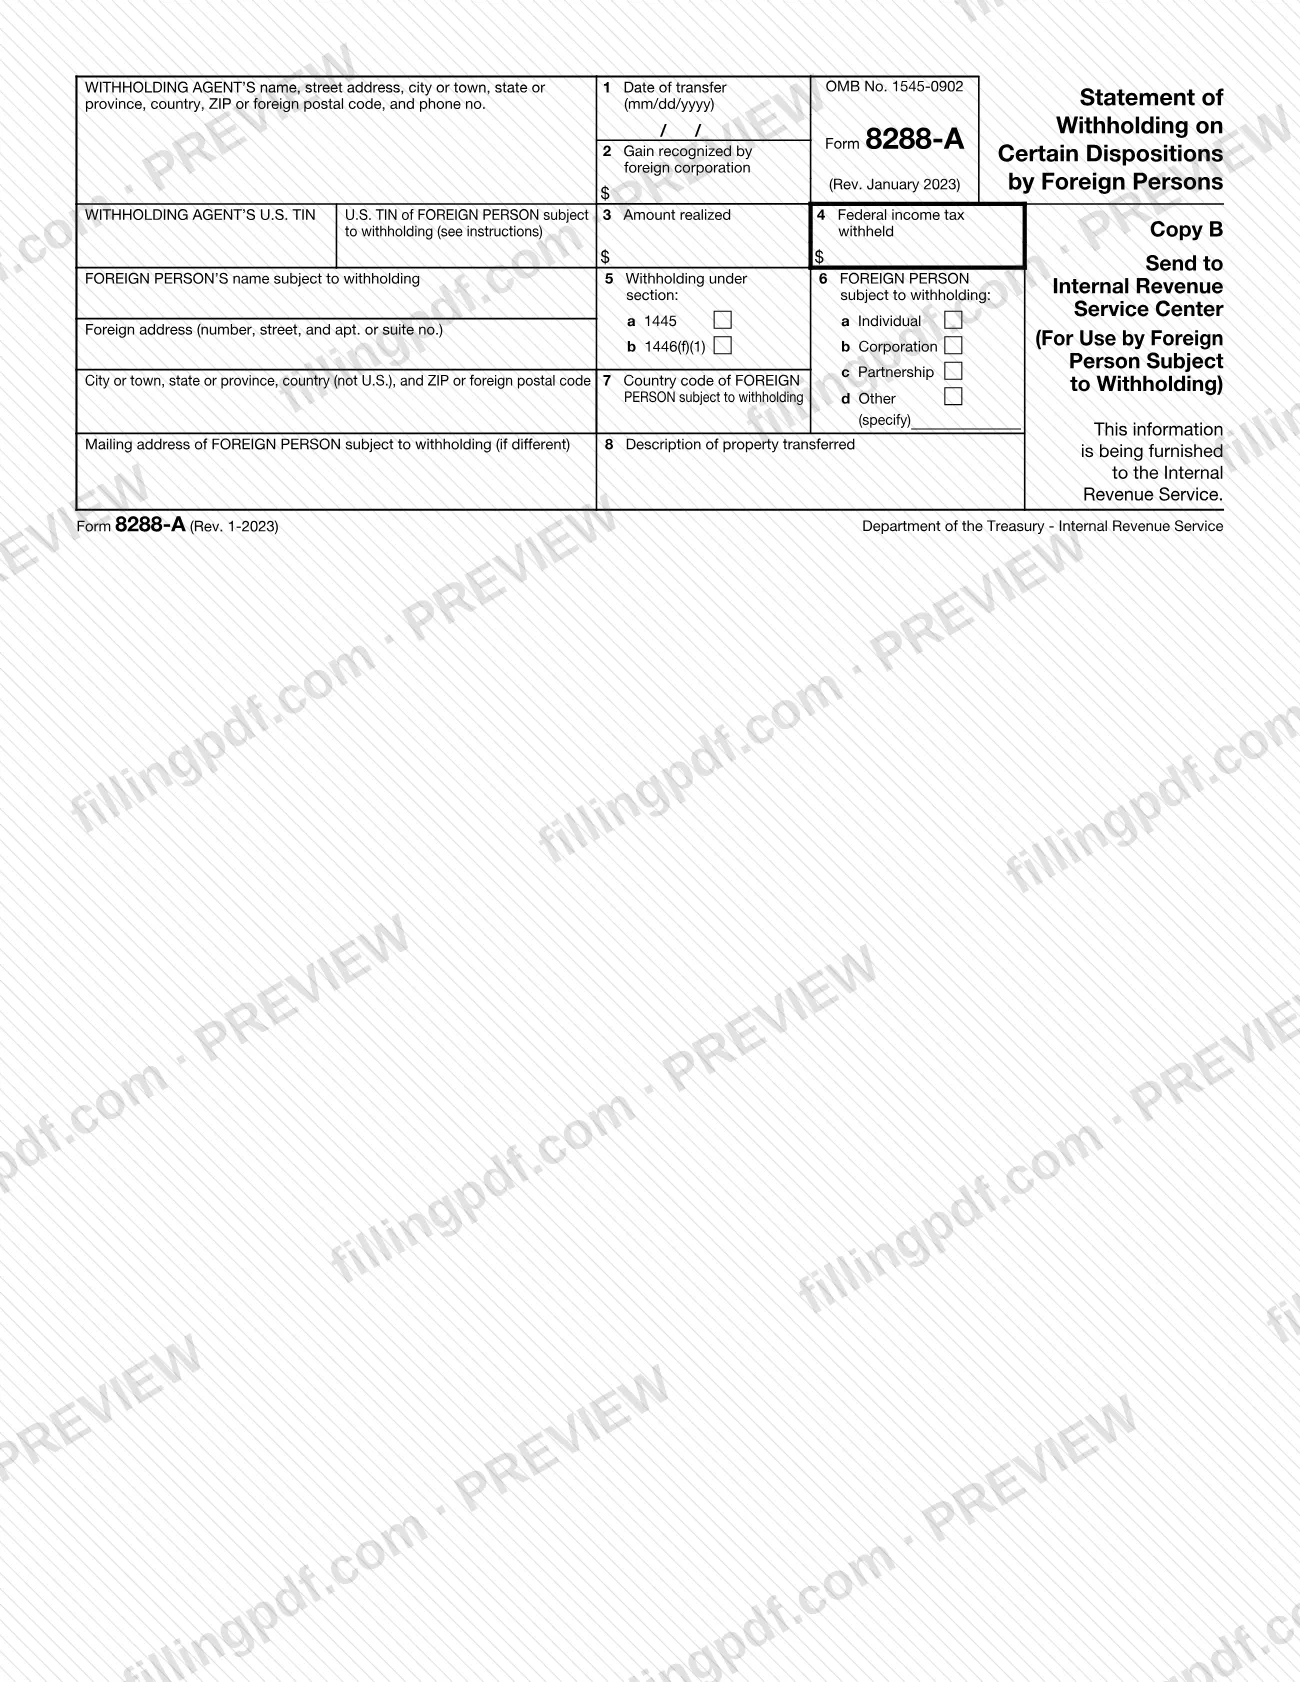
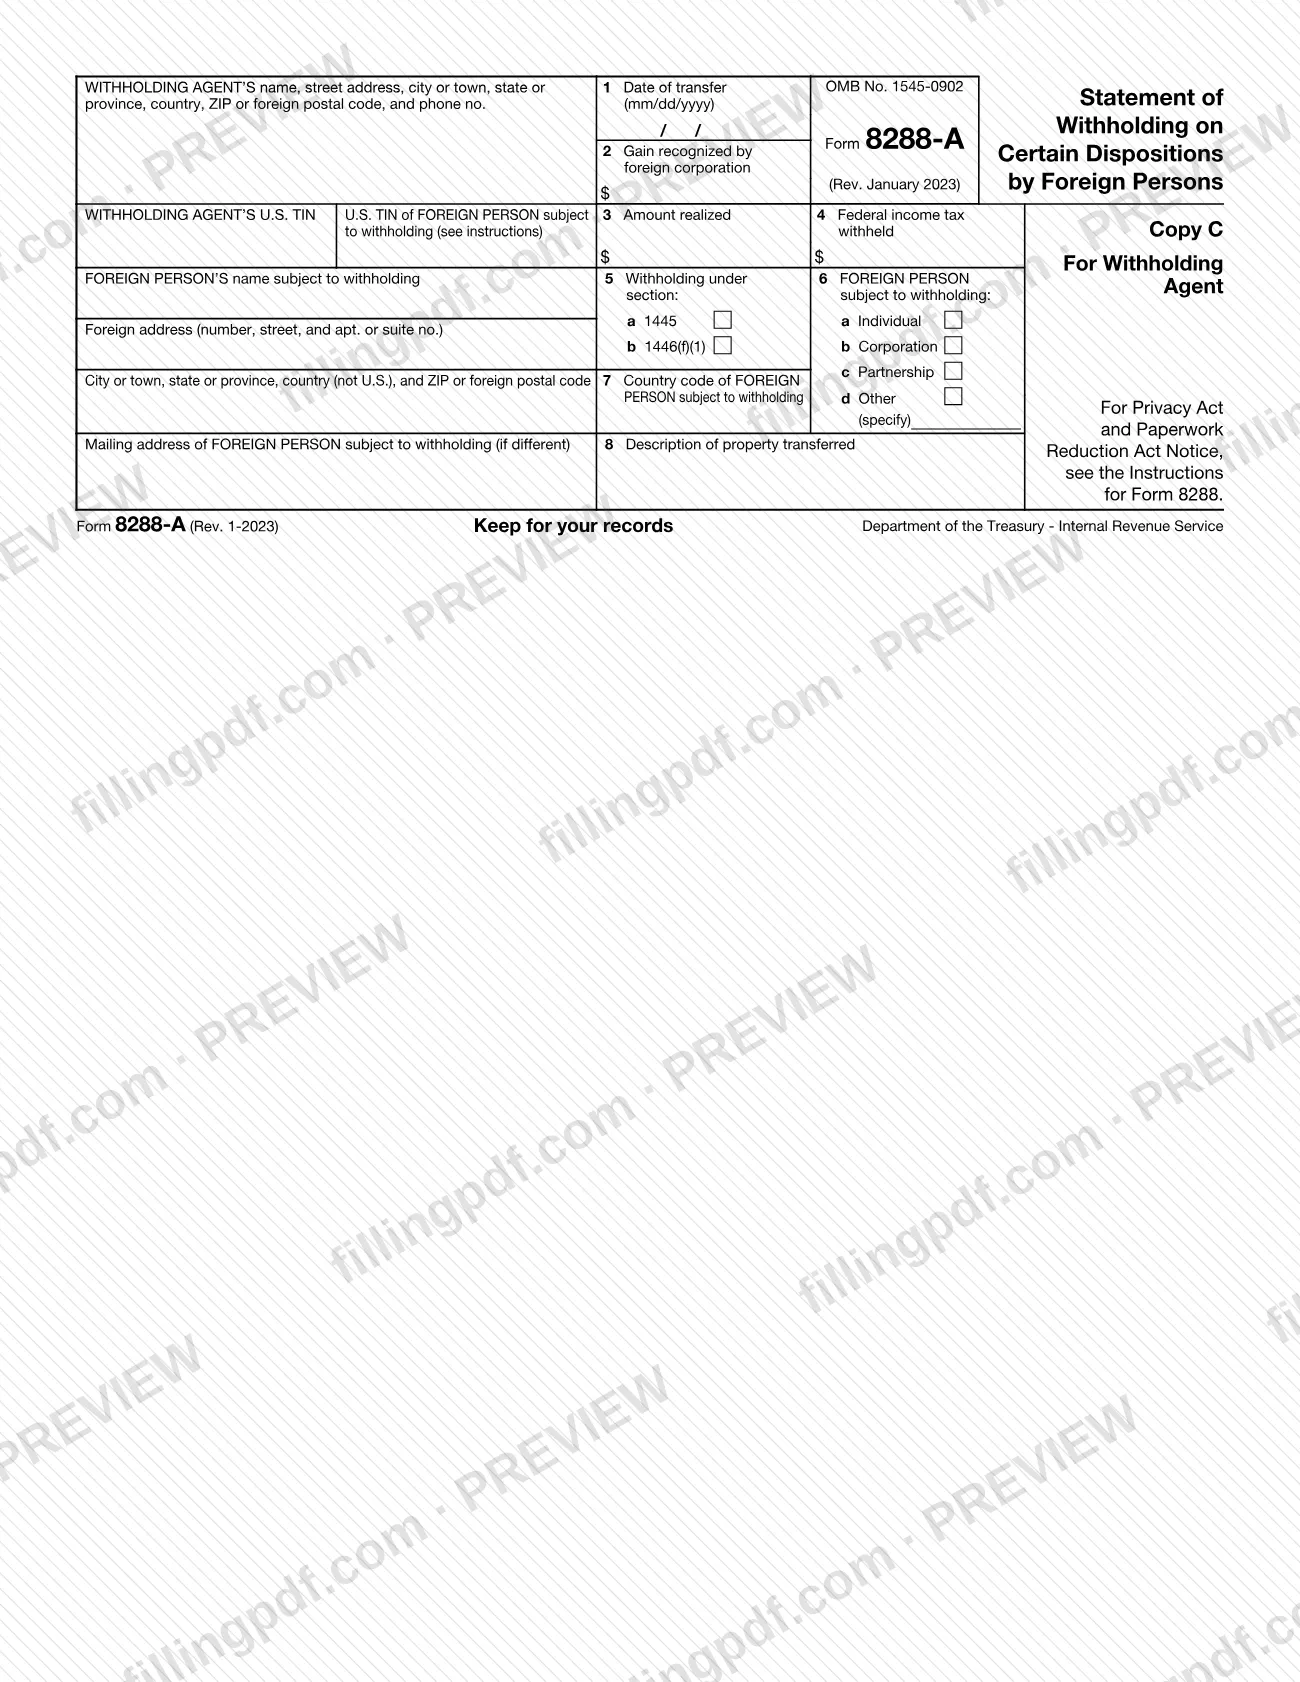
The form is issued under OMB No. 1545-0902 and has three copies on one PDF:
- Copy A goes to the IRS Service Center and is attached to Form 8288.
- Copy B is also attached to Form 8288. The IRS stamps it and sends it to the foreign person when the form is complete, including the transferor's taxpayer identification number (TIN).
- Copy C is kept by the withholding agent.
The withholding it reports is made under section 1445 or section 1446(f)(1). Publicly traded partnerships (PTPs) and their nominees do not use this form: they report withholding on Forms 1042 and 1042-S. The foreign person later uses the stamped Copy B to claim credit for the tax withheld on a U.S. tax return.
Who needs to file 8288-A?
The withholding agent, usually the buyer or other transferee, completes Form 8288-A. Prepare one form for each foreign person subject to withholding under section 1445 or 1446(f)(1).
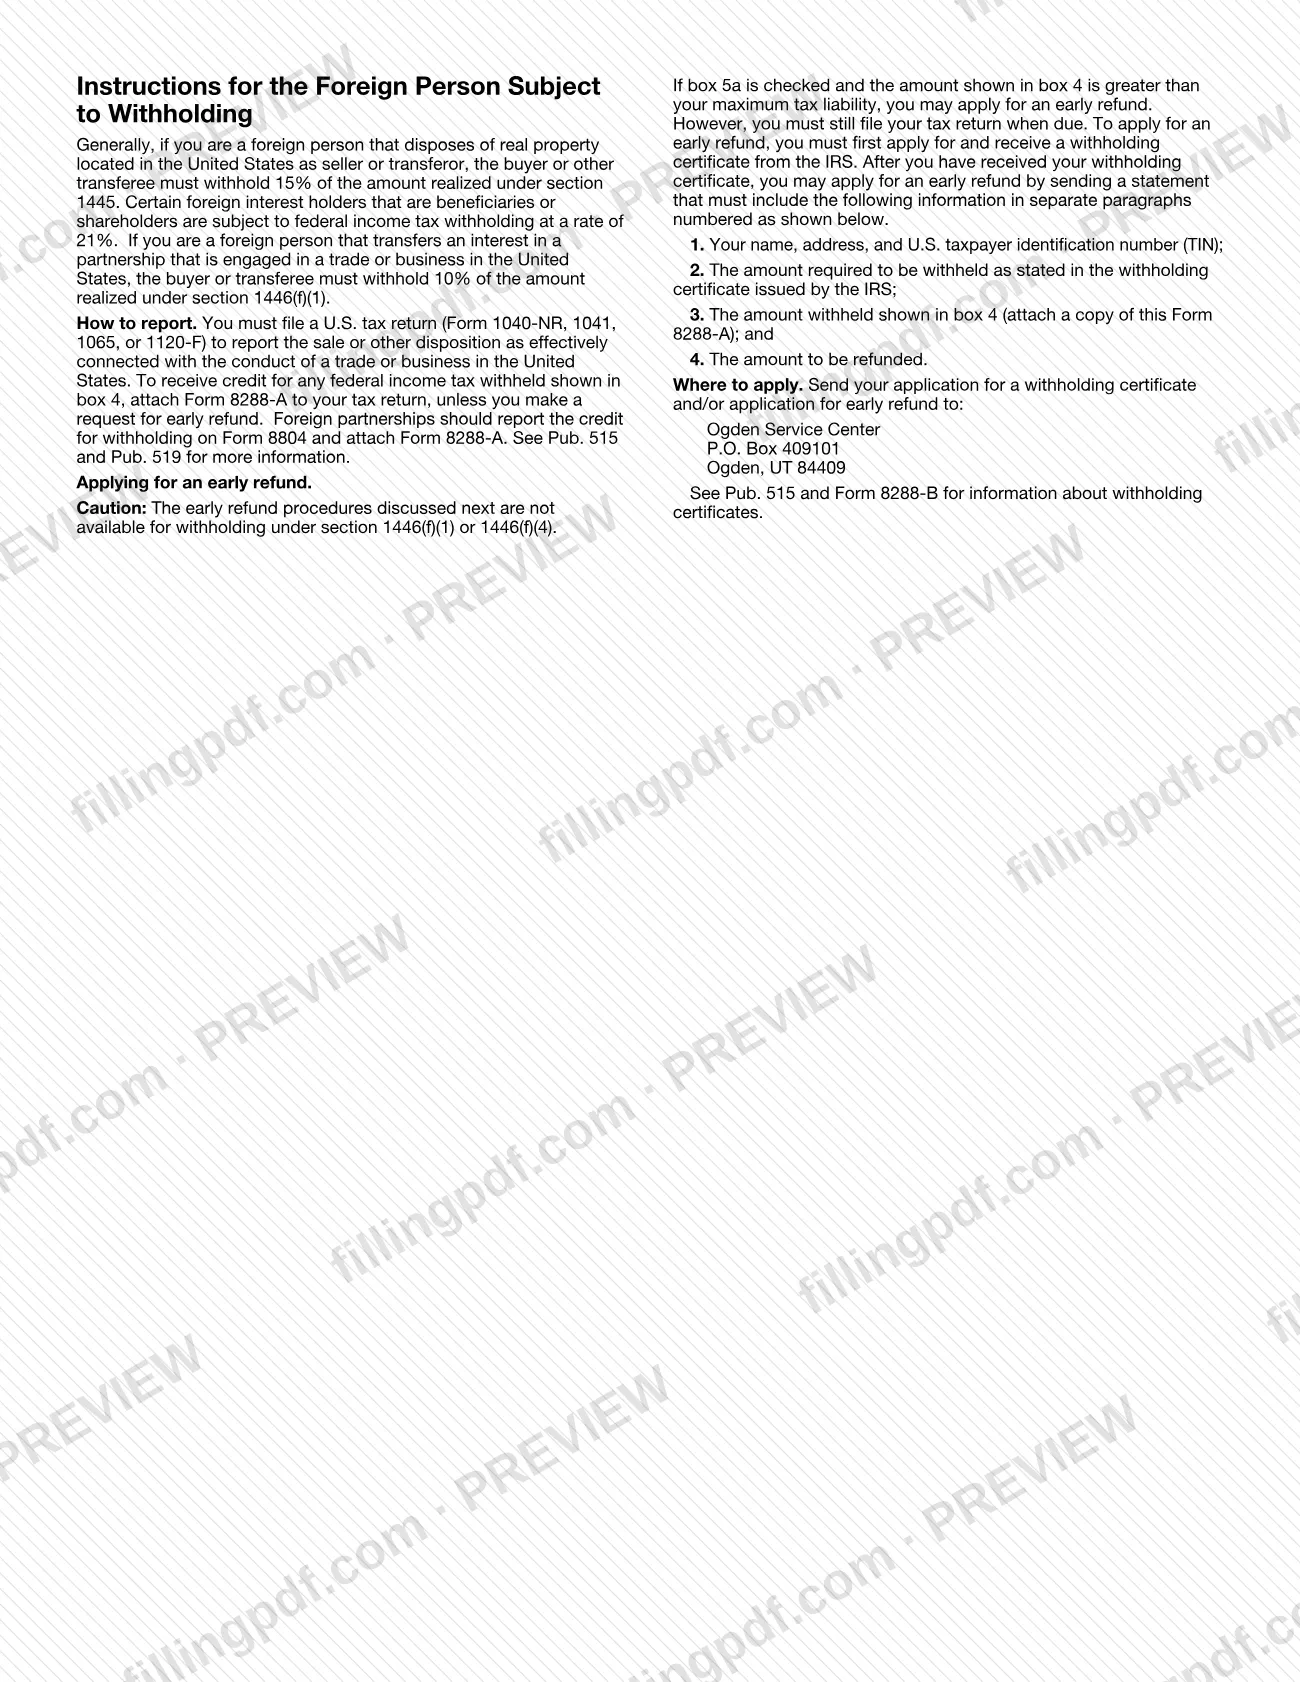
The foreign person whose name appears on the form receives Copy B from the IRS and uses it to claim credit for the tax withheld. The IRS instructions for that person explain the rates: the buyer or transferee generally withholds 15% of the amount realized under section 1445, certain foreign interest holders that are beneficiaries or shareholders are subject to 21%, and a transfer of an interest in a partnership engaged in a U.S. trade or business is subject to 10% under section 1446(f)(1). The foreign person must file a U.S. tax return (Form 1040-NR, 1041, 1065 or 1120-F) and attach Form 8288-A to it, unless requesting an early refund. Foreign partnerships report the credit on Form 8804 and attach Form 8288-A.
Who should not use it: PTPs and their nominees report withholding on Forms 1042 and 1042-S. Box 2 is completed only by a foreign corporation required to withhold under section 1445(e)(2). The foreign person's address must be outside the United States.
When to file 8288-A
Prepare Form 8288-A when you withhold on a disposition by a foreign person, because it travels with Form 8288: Copies A and B are attached to that return. Form 8288-A has no separate due date printed on it, so the timing follows Form 8288; check the Instructions for Form 8288 at irs.gov for that date.
Box 1 asks for the date of transfer. Enter the date of distribution instead if you withheld under section 1445(e)(2), (e)(3) or (e)(6), or section 1446(f)(1), or if you made the large trust election to withhold at the date of distribution.
The foreign person attaches the stamped copy to the U.S. tax return that reports the sale. Anyone requesting an early refund instead must still file the return when it is due.
Documents you need
- Form 8288, U.S. Withholding Tax Return for Certain Dispositions by Foreign Persons: Copies A and B of Form 8288-A are attached to it.
- The foreign person's U.S. taxpayer identification number (SSN, EIN or ITIN), entered on the form so the IRS can forward Copy B.
- For an early refund request by the foreign person: a statement with the four numbered items in the instructions, a copy of Form 8288-A and the IRS withholding certificate already received.
How to fill out 8288-A
Enter the withholding agent's details
In the top-left block, enter the withholding agent's name, street address, city or town, state or province, country, ZIP or foreign postal code, and phone number. Add the withholding agent's U.S. TIN below it: an SSN, EIN or ITIN.
Enter the foreign person's identity
Enter the name of the foreign person subject to withholding and that person's U.S. TIN. Prepare a separate form for each foreign person.
Enter the foreign and mailing addresses
Enter the foreign home address (individual) or foreign office address (other than an individual); it must be outside the United States. If the person has none, enter the country of residence and a complete mailing address. A separate mailing address is optional and is used to forward Copy B.
Enter the date of transfer in box 1
Enter the date in mm/dd/yyyy format. Use the date of distribution instead if you withheld under section 1445(e)(2), (e)(3) or (e)(6), or section 1446(f)(1), or made the large trust election.
Complete box 2 only if it applies
Enter the gain recognized by the foreign corporation only if you are a foreign corporation required to withhold under section 1445(e)(2). Otherwise leave it blank.
Enter amounts in boxes 3 and 4
Box 3: the amount realized by the foreign person named on the form. Box 4: the federal income tax you withheld for that person.
Check the withholding section in box 5
Check box 5a for section 1445 or box 5b for section 1446(f)(1), whichever section you withheld under.
Check the type of foreign person in box 6
Check Individual, Corporation, Partnership or Other. If you check Other, specify whether the foreign person is a trust or estate.
Enter the country code and property
Box 7: the two-letter code for the foreign home or office address, from the list at www.irs.gov/countrycodes. Box 8: a description of the property transferred.
Review and download the completed PDF
Check names, TINs, dates and amounts on all three copies. Download or print the completed PDF from FillingPDF, attach Copies A and B to Form 8288 and keep Copy C.
How to submit 8288-A
Form 8288-A is not filed on its own: the withholding agent attaches Copies A and B to Form 8288, U.S. Withholding Tax Return for Certain Dispositions by Foreign Persons, and sends them to the IRS with that return. The form names no other channel or address for the agent, so follow the Instructions for Form 8288 for where and how to send the return and make the payment.
- Copy A and Copy B: attach both to Form 8288. The IRS stamps Copy B and forwards it to the foreign person if the form is complete, including the transferor's TIN. If the foreign person gave a separate mailing address, the IRS uses it.
- Copy C: keep it for your records. You do not have to give a copy of the form to the foreign person.
- Foreign person's return: the foreign person attaches Form 8288-A to the tax return (Form 1040-NR, 1041, 1065 or 1120-F, or Form 8804 for a foreign partnership) to receive credit for the tax shown in box 4.
- Early refund or withholding certificate applications: send them to Ogden Service Center, P.O. Box 409101, Ogden, UT 84409.
FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Entering a U.S. address as the foreign person's home or office address; the instructions require an address outside the United States, or the country of residence plus a complete mailing address.
- Leaving out the foreign person's TIN; Copy B is stamped and sent on only if the form is complete, including the transferor's TIN.
- Completing box 2 when you are not a foreign corporation required to withhold under section 1445(e)(2).
- Using the date of transfer in box 1 when the instructions call for the date of distribution, such as withholding under section 1446(f)(1).
- Using Form 8288-A for a publicly traded partnership or its nominee, which report withholding on Forms 1042 and 1042-S.
- Entering a country name in box 7 instead of the two-letter code from the list at www.irs.gov/countrycodes.
- Attaching only one copy to Form 8288; Copies A and B both go with the return, and Copy C stays with you.
- Asking for an early refund for withholding under section 1446(f)(1) or 1446(f)(4); the instructions say those procedures do not apply.
Frequently asked questions
What is Form 8288-A used for?
Form 8288-A is the IRS statement of withholding that a buyer or other withholding agent prepares for each foreign person that disposes of U.S. real property. It reports the amount realized and the tax withheld, and its copies go with Form 8288.
Who has to fill out Form 8288-A?
The withholding agent, usually the buyer or transferee, completes it, one form per foreign person subject to withholding under section 1445 or 1446(f)(1). Publicly traded partnerships and their nominees use Forms 1042 and 1042-S instead.
What do I do with Copies A, B and C of Form 8288-A?
Attach Copies A and B to Form 8288. The IRS stamps Copy B and sends it to the foreign person if the form is complete, including the TIN. Keep Copy C for your records; you do not have to give the foreign person a copy.
When do I complete box 2 on Form 8288-A?
Only if you are a foreign corporation required to withhold under section 1445(e)(2). In every other case the instructions give no reason to enter anything in box 2, so leave it blank.
Can the foreign person claim credit for the tax withheld?
Yes. The foreign person files a U.S. tax return (Form 1040-NR, 1041, 1065 or 1120-F) and attaches Form 8288-A to receive credit for box 4. Foreign partnerships report the credit on Form 8804 and attach the form.
Can a foreign person get an early refund of the withheld tax?
Possibly, if box 5a is checked and the box 4 amount exceeds the person's maximum tax liability. They must first get an IRS withholding certificate, then send a statement to Ogden Service Center, P.O. Box 409101, Ogden, UT 84409. It is not available under section 1446(f)(1) or (f)(4).
Where do I get the country code for box 7?
Use the two-letter code for the foreign home or office address from the list at www.irs.gov/countrycodes. Enter the code, not the country name.
Can I fill out Form 8288-A online on FillingPDF?
Yes. You can fill out the fillable PDF on FillingPDF and download or print it. FillingPDF is an independent service and does not file the form or send it to the IRS; you attach the copies to Form 8288 and submit them through the IRS channels.
Ready to fill out 8288-A?
Fill out 8288-A now