
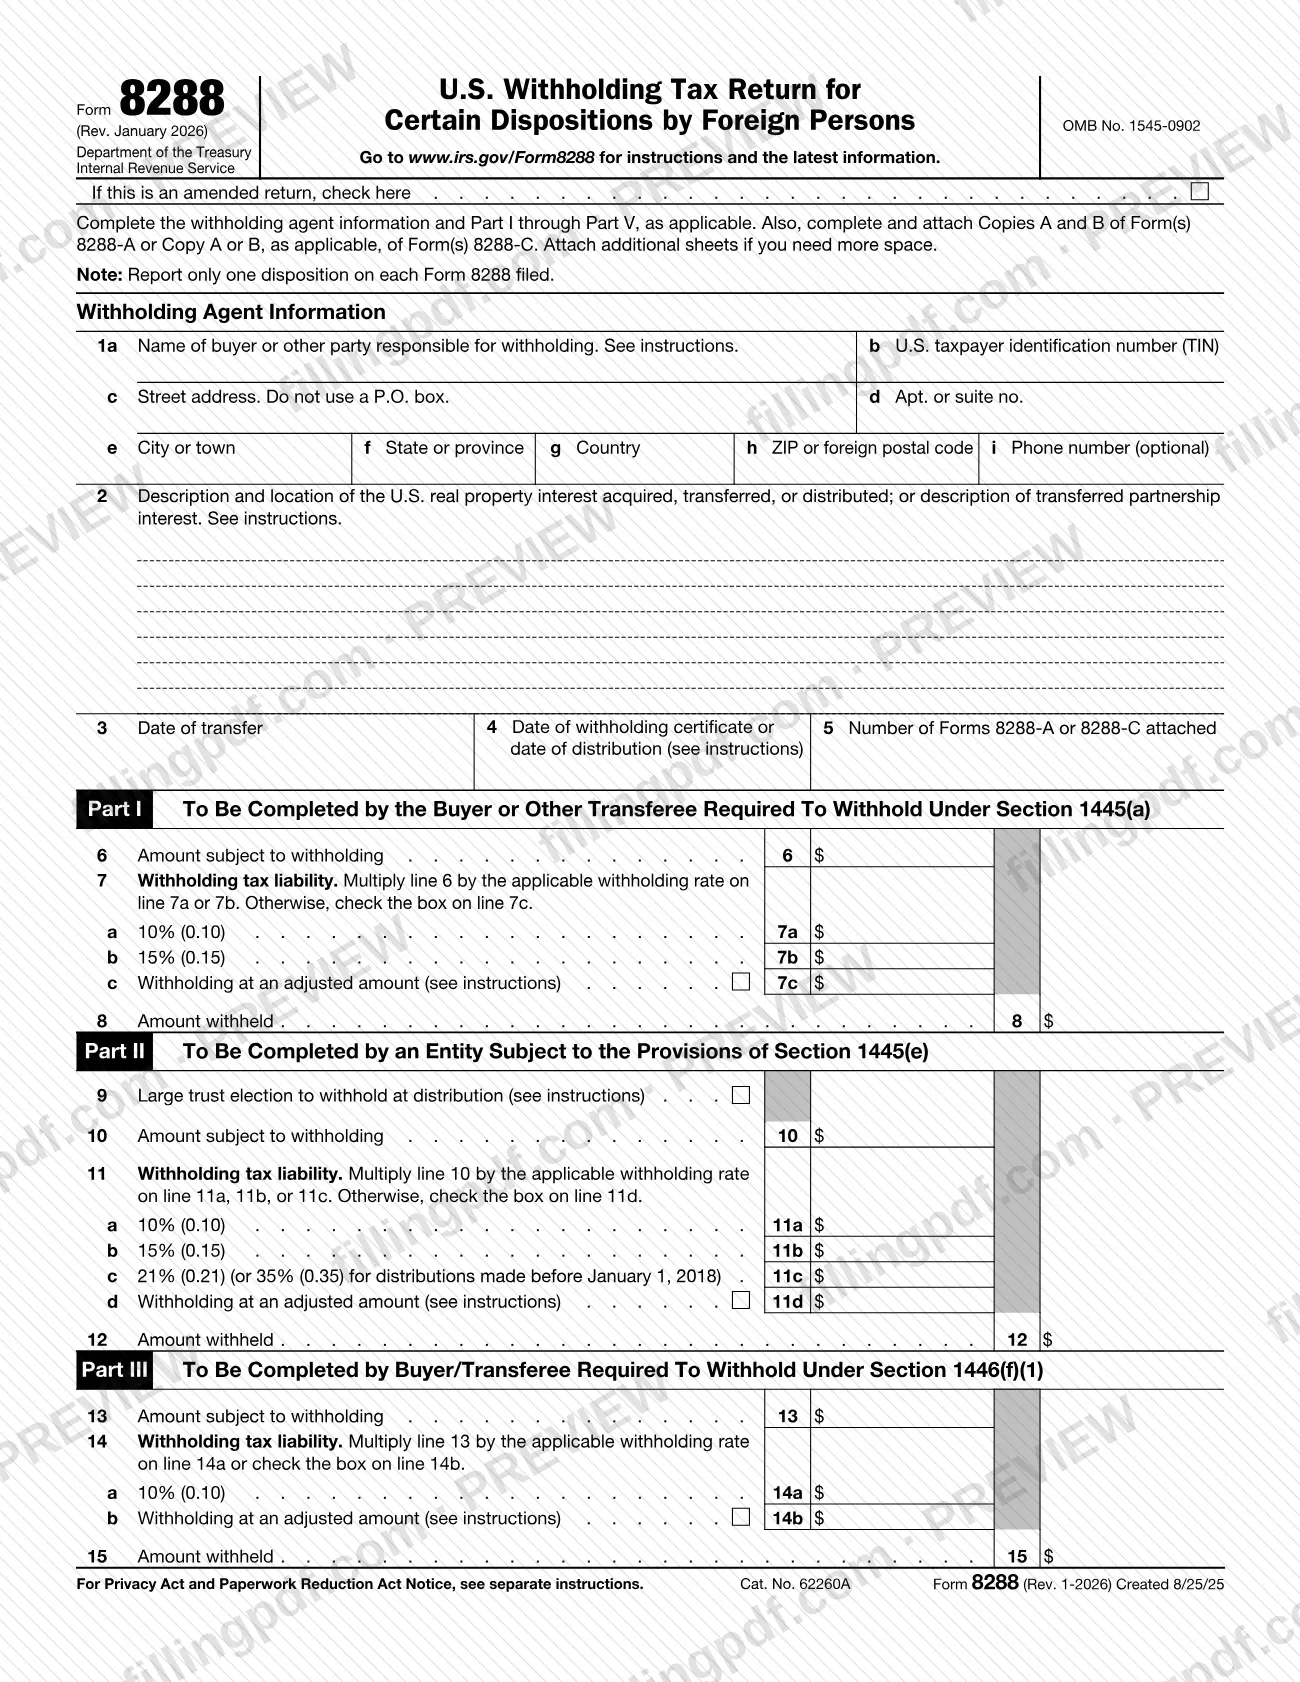
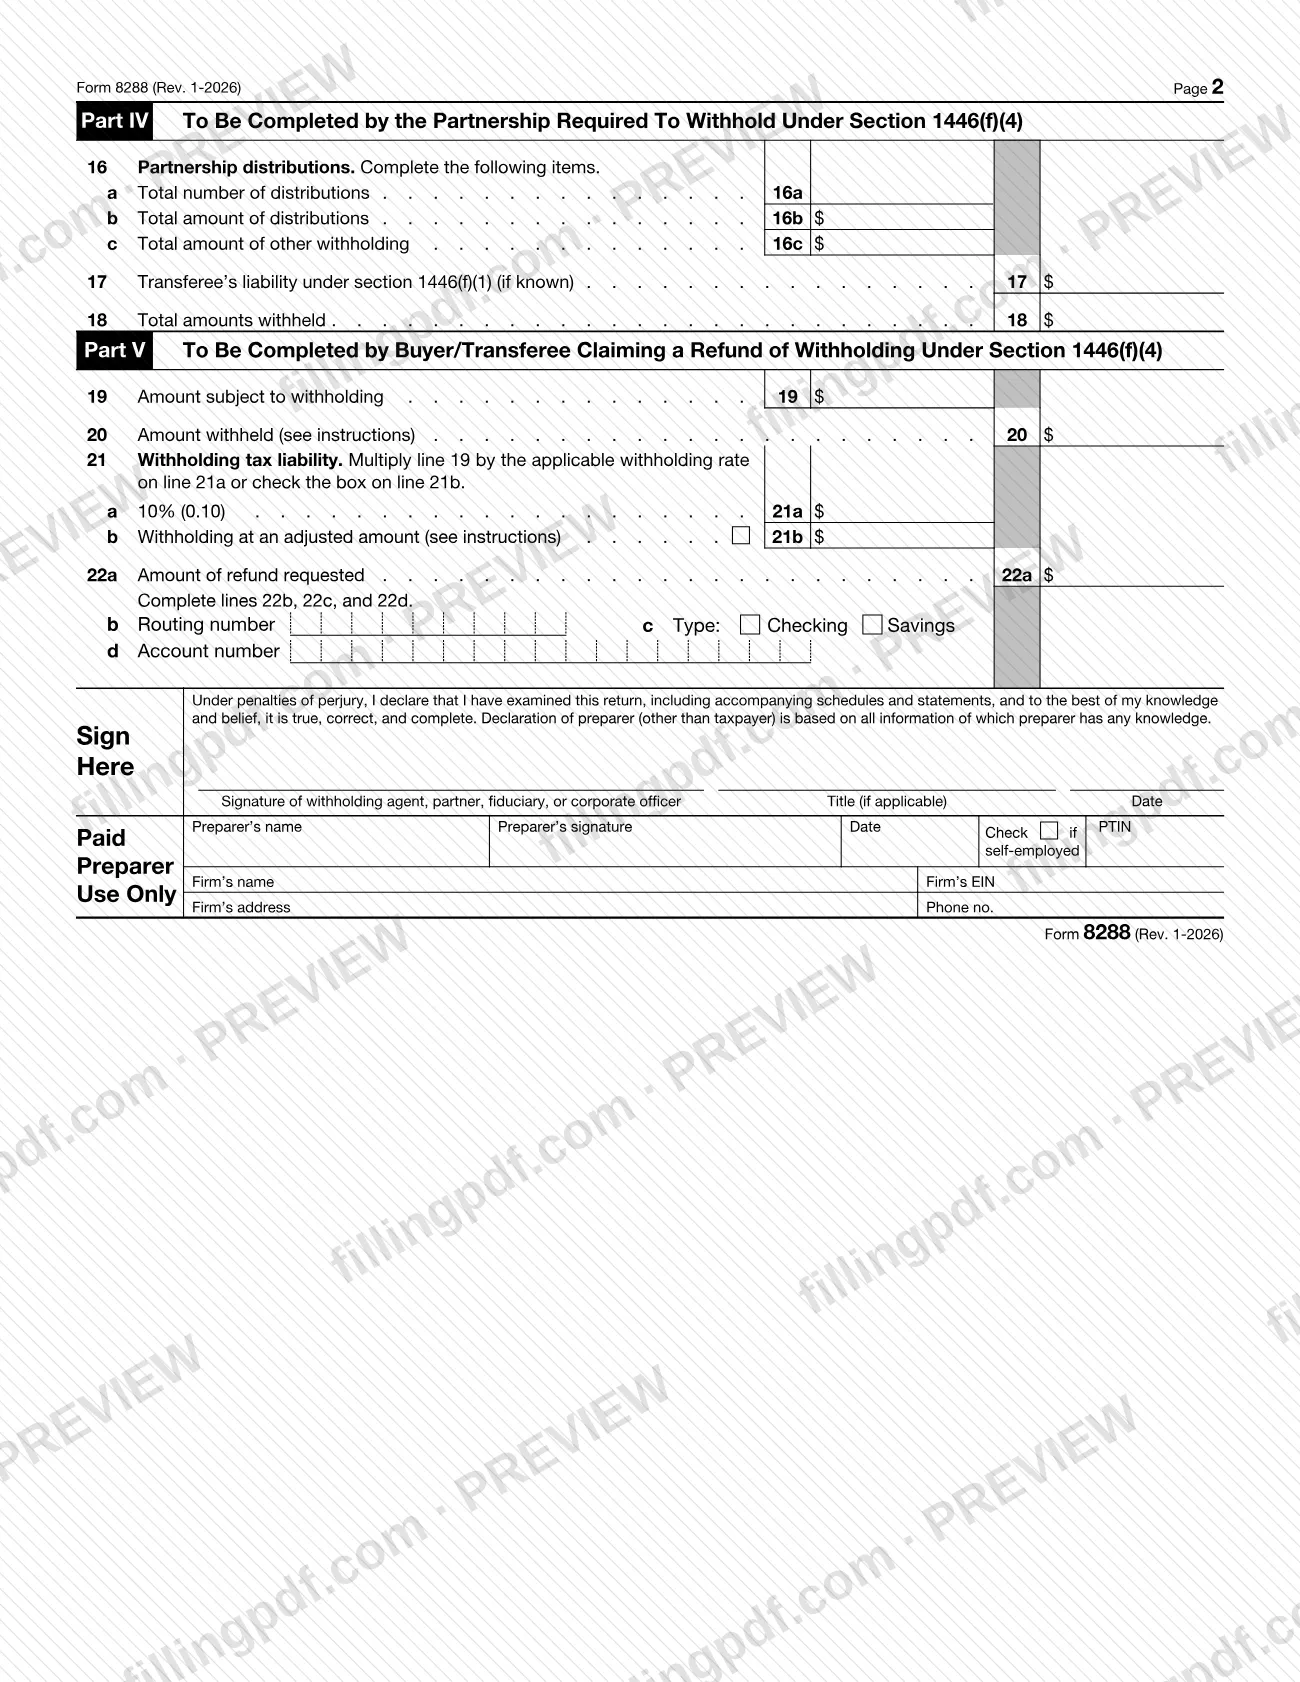
Form 8288, U.S. Withholding Tax Return for Certain Dispositions by Foreign Persons, is the Internal Revenue Service (IRS) return on which a buyer, transferee, partnership or other withholding agent reports and pays over tax withheld when a foreign person disposes of a U.S. real property interest or a partnership interest. It is also used for certain distributions and for claiming a refund of excess section 1446(f)(4) withholding. On this page you can fill out the form online on FillingPDF and download or print the completed PDF; the original PDF and the instructions are published by the IRS at irs.gov/Form8288.
Last updated
What is 8288?
Form 8288, U.S. Withholding Tax Return for Certain Dispositions by Foreign Persons, is the Internal Revenue Service (IRS) return on which a withholding agent reports and sends in tax withheld on certain dispositions and distributions covered by sections 1445 and 1446(f).
The IRS instructions tie the form to three withholding obligations:
- Section 1445: generally falls on the buyer or other transferee when a U.S. real property interest (USRPI) is acquired from a foreign person. It also applies to certain distributions by foreign and domestic corporations, qualified investment entities (QIEs), and fiduciaries of certain trusts and estates.
- Section 1446(f)(1): generally falls on the buyer or other transferee of a partnership interest acquired from a foreign person, when the transferor realized a gain, any part of which is treated as effectively connected with a U.S. trade or business.
- Section 1446(f)(4): falls on a partnership that makes a distribution to a transferee that failed to withhold under section 1446(f)(1). A transferee can claim a refund of excess section 1446(f)(4) withholding for transfers on or after January 1, 2023.
The form has a withholding agent block and Parts I through V, one for each situation. Each Form 8288 reports only one disposition. It travels with Form 8288-A (Parts I to III) or Form 8288-C (Part IV). Applications to reduce or eliminate withholding use a withholding certificate, which in certain cases is requested on Form 8288-B.
Form 8288 is not used for every foreign-person payment. The instructions send certain trust and QIE distributions, publicly traded partnership (PTP) distributions and transfers of PTP interests to Forms 1042 and 1042-S instead.
Who needs to file 8288?
The main filer is the buyer or other transferee required to withhold. Which part you complete depends on the obligation:
- Part I: a buyer or other transferee of a USRPI required to withhold under section 1445(a).
- Part II: a corporation, QIE or fiduciary required to withhold under section 1445(e), including a trust making the large trust election.
- Part III: a buyer or transferee of a partnership interest required to withhold under section 1446(f)(1).
- Part IV: a partnership required to withhold under section 1446(f)(4) on distributions to a transferee that failed to withhold.
- Part V: a buyer or transferee claiming a refund of section 1446(f)(4) withholding.
If two or more persons are joint transferees, each must withhold, but the obligation is met if one of them withholds and sends in the full amount.
Complete only one of Parts I through V, except that a Part V claim by a transferee that has not previously filed Part III is filed with Parts III and V both completed.
Do not use Forms 8288 and 8288-A for the distributions and transfers the instructions assign to Forms 1042 and 1042-S. No withholding is required in the situations the instructions list as exceptions, such as a valid certification of nonforeign status from the transferor.
When to file 8288
A transferee must file Form 8288 and send in the tax withheld by the 20th day after the date of transfer. A partnership filing Part IV has the same period, counted from the date of the distribution to the transferee.
If an application for a withholding certificate is or has been submitted to the IRS, you must still withhold on the date of transfer. You then do not have to file or send in the withholding until the 20th day after the day the IRS mails you the certificate or a notice of denial. If the application's principal purpose was to delay payment, interest and penalties run from the 21st day after the transfer. A certificate that excuses withholding means you need not file; one that only reduces withholding still requires the form, with a copy attached.
For installment payments, withhold the full amount at the first installment. After a late notice that a certification was false, withhold from remaining payments and report each by the 20th day after the payment.
Documents you need
- Copies A and B of Form 8288-A for each person subject to withholding, when you complete Part I, II or III. Copy C stays in your records.
- Copy A of Form 8288-C, when a partnership completes Part IV. Attach only the Form 8288-C for the current distribution; file a separate Form 8288 for each distribution.
- A copy of the IRS withholding certificate, when you enter an adjusted amount on line 7c, 11d, 14b or 21b.
- For a Part V refund claim: the Form(s) 8288-C received from the partnership, with Copy B attached to support line 20.
- For a Part V refund claim: copies of Form 8288-A amounts withheld, any IRS notice payment, or proof of tax the transferor paid (such as Form 4669), as the line 21 instructions direct.
- The payment of the amount withheld, which is sent with the return.
How to fill out 8288
Mark an amended return
Check the box at the top of page 1 only if this Form 8288 amends one you already filed.
Enter the withholding agent information
On lines 1a through 1i, enter the name, TIN, street address (no P.O. box), apartment or suite, city, state or province, country, postal code and optional phone number of the buyer or other party responsible for withholding. Do not enter a title or mortgage company unless it is the actual withholding agent.
Describe the property and dates
On line 2, give the location and description of the USRPI or the partnership interest transferred. Enter the date of transfer on line 3, the date of the withholding certificate or distribution on line 4, and the number of Forms 8288-A or 8288-C attached on line 5.
Complete Part I for buyers
If you must withhold under section 1445(a), enter the amount subject to withholding on line 6. On line 7, complete only one of 7a (10%), 7b (15%) or 7c (adjusted amount, with the box checked and the certificate attached), then enter the amount actually withheld on line 8.
Complete Part II for entities
If you are a section 1445(e) entity, check line 9 for a large trust election. Enter the amount subject to withholding on line 10, one of lines 11a to 11d on line 11, and the amount withheld on line 12.
Complete Part III for partnership interests
For a section 1446(f)(1) transfer, enter the amount subject to withholding on line 13, either line 14a (10%) or 14b (adjusted amount, box checked) and the amount withheld on line 15. Use a separate Form 8288 for each transfer.
Complete Part IV for partnerships
On line 16, enter the cumulative number of distributions (16a), their total amount (16b) and any other withholding (16c). Enter the transferee's section 1446(f)(1) liability on line 17 if known, and the total section 1446(f)(4) amounts withheld on line 18.
Complete Part V to claim a refund
Enter the amount subject to withholding on line 19 and the amount the partnership withheld on line 20. On line 21 complete only 21a or 21b, enter the refund requested on line 22a, and for direct deposit give the nine-digit routing number (22b), account type (22c) and account number (22d).
Sign and add preparer details
The withholding agent, partner, fiduciary or corporate officer signs, adds a title if applicable and dates the return. A paid preparer signs and enters a PTIN, firm name, EIN, address and phone number.
Review, download and attach copies
Check that only the applicable part is completed and that line 5 matches the attached Forms 8288-A or 8288-C. Download or print the completed PDF from FillingPDF, then assemble the package described under How to submit.
How to submit 8288
Form 8288 is filed by mail to the IRS Ogden Service Center, together with the amount withheld and the required copies of Form 8288-A or 8288-C. The form and instructions name no other channel.
- By mail (Parts I to III): send Form 8288 with the amount withheld and Copies A and B of Form(s) 8288-A to Ogden Service Center, P.O. Box 409101, Ogden, UT 84409.
- By mail (Part IV): send Form 8288 with the amount withheld and Copy A of Form(s) 8288-C to the same address. Copy B of Form 8288-C goes to the transferee, and Copy C stays in your records.
- Related notices: a notice of nonrecognition goes to the same address by the 20th day after the date of transfer, with a cover letter giving your name, address and TIN. For a treaty-benefit certification under exception 6, mail a copy and cover letter within 30 days after the transfer.
You do not have to give a copy of Form 8288 or 8288-A directly to the transferor; the IRS stamps Copy B of each Form 8288-A and forwards it. Do not send the return to the IRS Tax Forms and Publications address in Washington, DC. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Reporting more than one disposition on a single Form 8288; the form says to report only one disposition on each form filed.
- Entering a P.O. box on line 1c; the form says not to use one for the street address.
- Entering the title company or mortgage company as the withholding agent when it is not the person actually responsible for withholding.
- Completing several of Parts I through V when the instructions say to complete only one, other than the Part III and V claim case.
- Entering amounts on more than one of lines 7a, 7b and 7c, or on more than one line in the 11, 14 and 21 groups, where only one applies.
- Filing without Copies A and B of Form 8288-A, or without Copy A of Form 8288-C for Part IV.
- Combining several distributions on one Part IV return instead of filing a separate Form 8288 for each distribution, with only that distribution's Form 8288-C.
- Delaying the return because an application for a withholding certificate is pending; withholding is still required on the transfer date.
- Skipping filing because the transferor's TIN is missing; you must still file Forms 8288 and 8288-A.
- Mailing the return to the Washington, DC address for form comments instead of the Ogden Service Center address.
Frequently asked questions
What is Form 8288 used for?
Form 8288 is the IRS return used to report and send in tax withheld on certain dispositions and distributions under sections 1445 and 1446(f), such as a buyer acquiring a U.S. real property interest from a foreign person. It is also used to claim a refund of excess section 1446(f)(4) withholding.
When is Form 8288 due?
The transferee must file and send in the tax withheld by the 20th day after the date of transfer. A partnership filing Part IV has until the 20th day after the distribution. If a withholding certificate application is pending, the deadline moves to the 20th day after the IRS mails the certificate or denial.
Where do I mail Form 8288?
Mail it with the amount withheld and the required copies of Form 8288-A or 8288-C to Ogden Service Center, P.O. Box 409101, Ogden, UT 84409. Do not send it to the Washington, DC address the instructions give for comments on the form.
Who is the withholding agent: the buyer or the settlement agent?
The buyer or other transferee, not the settlement agent. The instructions' example has a corporate buyer completing Forms 8288 and 8288-A even though the settlement agent withheld at closing. Do not list a title or mortgage company unless it is the person actually responsible for withholding.
Do I have to attach Form 8288-A?
Yes for Parts I to III: anyone who completes Form 8288 must complete a Form 8288-A for each person subject to withholding and attach Copies A and B. Part IV uses Copy A of Form 8288-C instead. Several 8288-A forms for one transaction can go with one Form 8288.
Can I fill out Form 8288 online?
You can fill out the PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the return or pay the tax; you mail it to the IRS Ogden Service Center with the amount withheld.
Do I need to file if the seller gives me a certification of nonforeign status?
Generally no withholding is required under section 1445 if you receive the transferor's signed certification of nonforeign status, which includes a valid Form W-9. Keep it in your records for 5 years after the year of transfer. Withholding can still be collected from you if you knew the certification was false.
How do I file an amended Form 8288?
Check the box at the top of page 1 that says this is an amended return, then complete the form with the corrected information. The instructions give no separate address for amended returns, so use the same Ogden Service Center address.
Ready to fill out 8288?
Fill out 8288 now