
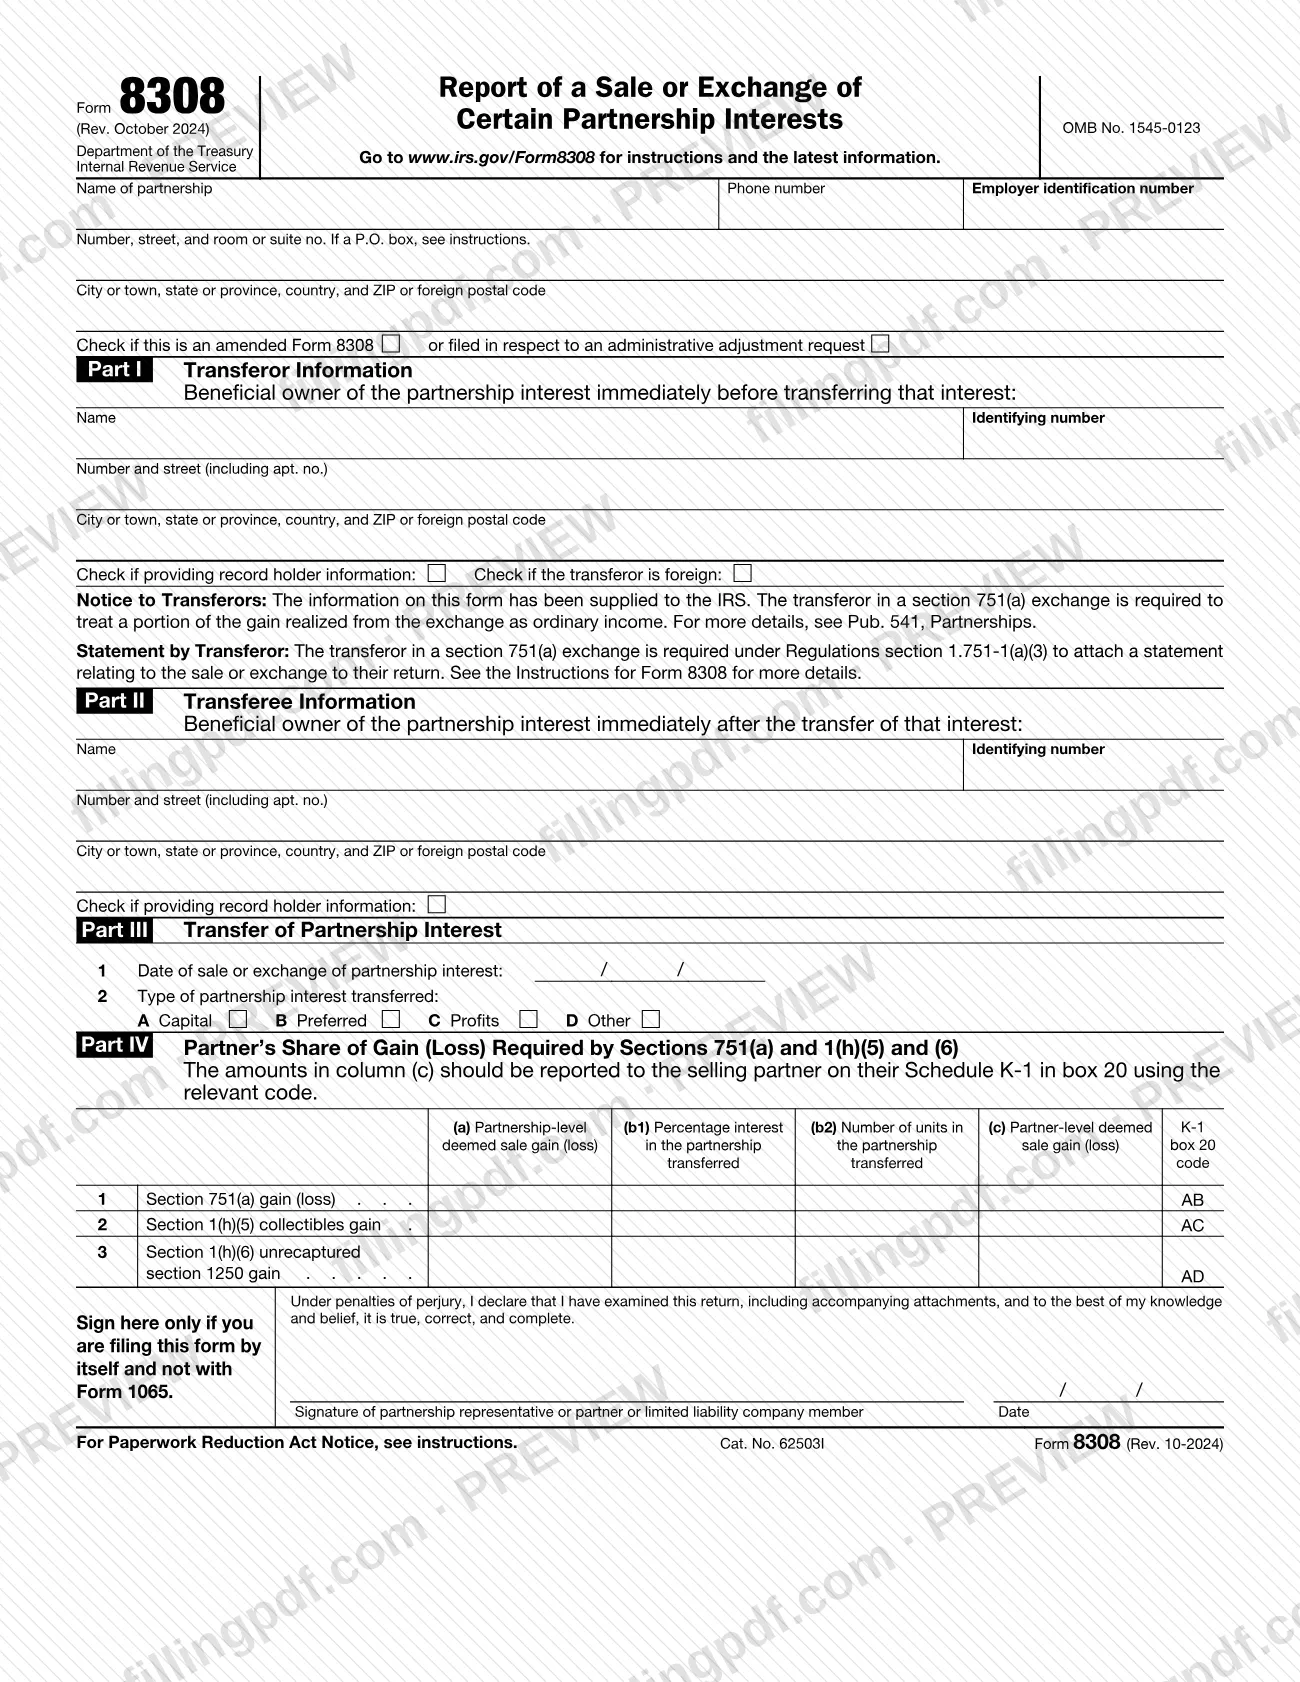
Form 8308, Report of a Sale or Exchange of Certain Partnership Interests, is the Internal Revenue Service (IRS) form a partnership files when a partner sells or exchanges all or part of an interest and some of what the partner receives is attributable to unrealized receivables or inventory items. The partnership files it, normally as an attachment to Form 1065, and gives the transferor and transferee a copy of Parts I through III. On this page you can fill out the form online on FillingPDF and download or print the completed PDF; the form and its instructions are published by the IRS at www.irs.gov/Form8308.
Last updated
What is 8308?
Form 8308, Report of a Sale or Exchange of Certain Partnership Interests, is the IRS form a partnership files to report a partner's sale or exchange of all or part of a partnership interest when money or other property received is attributable to unrealized receivables or inventory items, known as a section 751(a) exchange.
The IRS instructions explain that a section 751(a) exchange occurs when money or any property is exchanged for a partnership interest, or part of one, that is attributable to unrealized receivables or inventory items. Generally, any sale or exchange of an interest at a time when the partnership has any unrealized receivables or inventory items is a section 751(a) exchange.
The form has four parts:
- Part I: transferor information, the beneficial owner of the interest immediately before the transfer.
- Part II: transferee information, the beneficial owner immediately after the transfer.
- Part III: the date of the sale or exchange and the type of interest transferred (capital, preferred, profits or other).
- Part IV: the partner's share of gain (loss) under sections 751(a) and 1(h)(5) and (6), reported in columns (a), (b1), (b2) and (c).
The form also tells the transferor that part of the gain must be treated as ordinary income and that a statement must be attached to the transferor's return. A transfer that is entirely a gift for federal income tax purposes is not a section 751(a) exchange, and no section 6050K returns or statements are required for a transfer that is not one.
Who needs to file 8308?
A partnership must file a separate Form 8308 for each section 751(a) exchange of an interest in that partnership. The partnership also furnishes a Form 8308 with Parts I through III filled out to each transferor and each transferee.
Other groups and conditions in the IRS instructions:
- Partnerships in doubt. If a partnership is unsure whether its property is an unrealized receivable or inventory item, or whether a transfer is a section 751(a) exchange, it may file Form 8308 to avoid the risk of a failure-to-file penalty.
- Transferors. A transferor must notify the partnership of the exchange, unless Form 1099-B is required under section 6045. The transferor also attaches a separate statement to the income tax return for the year of the sale or exchange, as Regulations section 1.751-1(a)(3) requires.
- Transferees. They receive Parts I through III from the partnership.
Form 8308 does not have to be filed if Form 1099-B, Proceeds From Broker and Barter Exchange Transactions, is required to be filed for the sale or exchange under section 6045. A partnership may rely on a written statement from the transferor that the transfer was not a section 751(a) exchange, unless it has knowledge to the contrary.
When to file 8308
A partnership must file Form 8308 once it has notice of the section 751(a) exchange. It has notice when it receives the transferor's written notification (with both parties' names and addresses, the identifying numbers of the transferor and, if known, the transferee, and the date of the exchange), or when it knows of a transfer of an interest while it held unrealized receivables or inventory items.
Generally, file Form 8308 (Parts I through IV) as an attachment to Form 1065 for the partnership tax year that includes the last day of the calendar year in which the exchange took place. It is due when the partnership return is due, including extensions.
Copies of Parts I through III go to the transferor and transferee by January 31 of the year following the calendar year of the exchange or, if later, 30 days after the partnership has notice. Partnerships no longer have to furnish Part IV by January 31.
Late or corrected reporting follows other timing. A non-BBA partnership notified after filing files Form 8308 with an amended Form 1065 within 30 days of notification. A partnership that reported the correct gain but did not file Form 8308 files it separately within 30 days of notification.
Documents you need
- Form 1065, U.S. Return of Partnership Income: attach Form 8308, with Parts I through IV completed, to the partnership return for the year that includes the last day of the calendar year of the exchange.
- Amended Form 1065: attach Form 8308 to it when a non-BBA partnership learns of a missed or incorrect section 751(a) exchange after filing and the time for a superseding return has expired.
- Administrative adjustment request (AAR), with Form 8082 and Form 1065-X per their instructions: attach Form 8308 to it when a BBA partnership must correct reporting of a section 751(a) exchange.
- Separate statement by the transferor: the transferor attaches it to the income tax return for the year of the sale or exchange, showing the date, the gain or loss on section 751(a) property and the capital gain or loss on the interest.
How to fill out 8308
Enter the partnership's details
At the top, enter the name of the partnership, phone number, employer identification number and address. Include the suite or room number, and show the P.O. box number only if the post office does not deliver to the street address.
Mark amended or AAR filings
Check the box at the top if this is an amended Form 8308 or is filed in respect to an administrative adjustment request.
Complete Part I for the transferor
Enter the name, identifying number and address of the beneficial owner of the interest immediately before the transfer. Check the record holder box only if the beneficial owner is unknown, and check the foreign box if the transferor is foreign.
Complete Part II for the transferee
Enter the name, identifying number and address of the beneficial owner immediately after the transfer. If the transferee is a disregarded entity, list its first regarded owner.
Enter the date on Part III, line 1
Enter the date of the sale or exchange of the partnership interest in the month, day and year spaces.
Check the interest type on line 2
Check box A Capital, B Preferred, C Profits or D Other. Other means an interest that is not capital, profits or preferred.
Enter Part IV, column (a) amounts
For line 1 section 751(a) gain (loss), line 2 section 1(h)(5) collectibles gain and line 3 section 1(h)(6) unrecaptured section 1250 gain, enter the partnership-level deemed sale gain (loss).
Enter percentage or units in (b1) or (b2)
Enter the percentage interest transferred in column (b1) or the number of units in column (b2), not both. Enter zero if the partner is treated as transferring because of a distribution and ownership is unchanged.
Enter partner-level gain in column (c)
Enter the partner's allocable share of the column (a) amounts for the portion of the interest sold. The preprinted box 20 codes are AB, AC and AD, and column (c) amounts are reported on Schedule K-1 box 20.
Sign the form only if filing alone
Sign and date at the bottom only if you file the form by itself and not with Form 1065. The signer is the partnership representative or a partner or limited liability company member.
Review and download the completed PDF
Check names, identifying numbers and the date against your records, then download or print the completed PDF from FillingPDF. Give Parts I through III to the transferor and transferee and file the full form as described under How to submit.
How to submit 8308
Form 8308 is filed with the IRS as an attachment to the partnership's return or, in some late-reporting cases, on its own; copies of Parts I through III go to the partners.
- With Form 1065: attach the completed Form 8308, with all of Parts I through IV filled out, to Form 1065, U.S. Return of Partnership Income, and file it as the Form 1065 instructions direct.
- With an amended return: a non-BBA partnership notified of a missed or incorrect section 751(a) exchange files Form 8308 with an amended Form 1065 within 30 days of notification, with the service center where Form 1065 was filed, and gives amended Schedules K-1 to the affected partners.
- With an AAR: a BBA partnership in the same situation files an administrative adjustment request and attaches Form 8308. See the instructions for Forms 8082 and 1065-X, and IRS.gov/BBAAAR.
- By itself: a partnership that did not file Form 8308 with its Form 1065 but reported the correct gain files it separately within 30 days of notification with the service center where Form 1065 was filed. Sign the form only if you file it by itself and not with Form 1065.
- To partners: furnish a Form 8308 with Parts I through III completed to each transferor and transferee.
Do not send Form 8308 to the Tax Forms and Publications Division address printed in the instructions; it is only for comments. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Filing Form 8308 for a transfer that is not a section 751(a) exchange, such as one that is entirely a gift for federal income tax purposes.
- Attaching a Form 8308 to Form 1065 with only Parts I through III completed; the copy filed with the return needs Parts I through IV.
- Filing one Form 8308 for several exchanges; a separate form is required for each section 751(a) exchange of an interest in the partnership.
- Listing a nominee, agent or custodian in Part I or II instead of the beneficial owner; if the beneficial owner is unknown, check the record holder box and give the record holder's information.
- Checking the record holder box when the beneficial owner is also the record holder.
- Entering both a percentage in column (b1) and units in column (b2); enter one or the other, and zero where a distribution changed no ownership interest.
- Leaving the foreign transferor box unchecked when the transferor is foreign; if the owner is unknown, check it when the record holder is foreign.
- Sending the completed form to the Washington, DC address in the instructions, which is for comments only.
- Signing the form when it is attached to Form 1065; the signature line applies only if you file the form by itself.
Frequently asked questions
What is Form 8308 used for?
Form 8308 is the IRS form a partnership files to report a partner's sale or exchange of all or part of a partnership interest when money or property received is attributable to unrealized receivables or inventory items, a section 751(a) exchange.
Who has to file Form 8308?
The partnership files it, one separate form for each section 751(a) exchange of an interest in that partnership. The transferor must notify the partnership of the exchange, unless Form 1099-B is required under section 6045, in which case Form 8308 need not be filed.
When is Form 8308 due?
Generally with Form 1065 for the partnership year that includes the last day of the calendar year of the exchange, including extensions. Parts I through III go to the transferor and transferee by January 31 of the following year, or 30 days after notice if later.
Where do I send Form 8308?
Attach it to Form 1065. In late-reporting cases it goes with an amended Form 1065 or an AAR, or is filed separately, within 30 days of notification, with the service center where Form 1065 was filed. Do not send it to the Washington, DC comments address.
Do I have to give partners a copy of Form 8308?
Yes. The partnership must furnish a Form 8308 with Parts I through III filled out to each transferor and transferee. The copy filed with Form 1065 needs Parts I through IV, but partners' copies need only Parts I through III.
What are the penalties for not filing Form 8308?
Penalties may be imposed for each failure to file a correct Form 8308 by the due date, and for each failure to furnish a correct copy to either party. They may be waived for reasonable cause and not willful neglect; see sections 6721, 6722, 6724 and 6698.
Does Form 8308 need a signature?
Only if you file it by itself and not with Form 1065. The form says to sign and date, as partnership representative or partner or limited liability company member, only in that case.
Can I fill out Form 8308 online?
Yes. You can fill out the PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the form with the IRS or give it to partners; you do that through the IRS channels.
Ready to fill out 8308?
Fill out 8308 now