
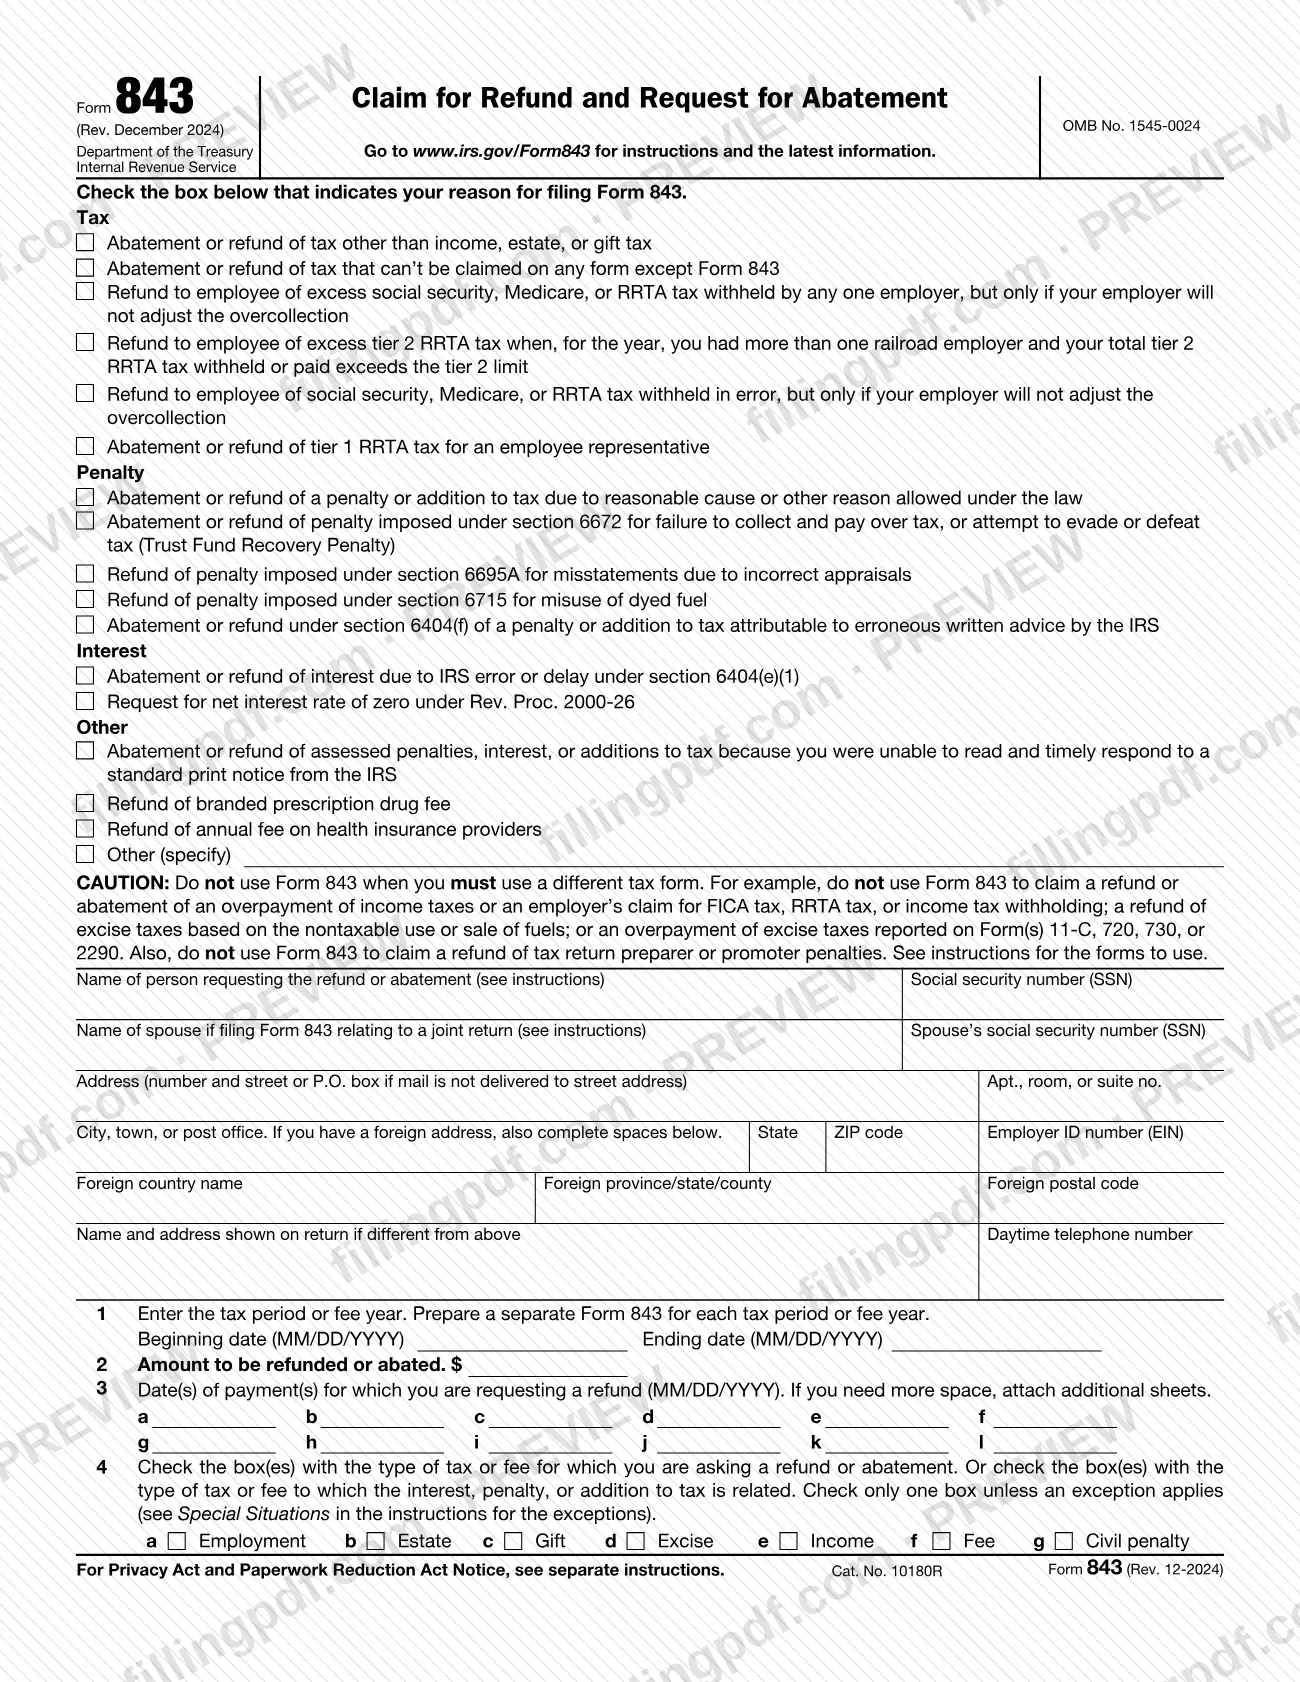
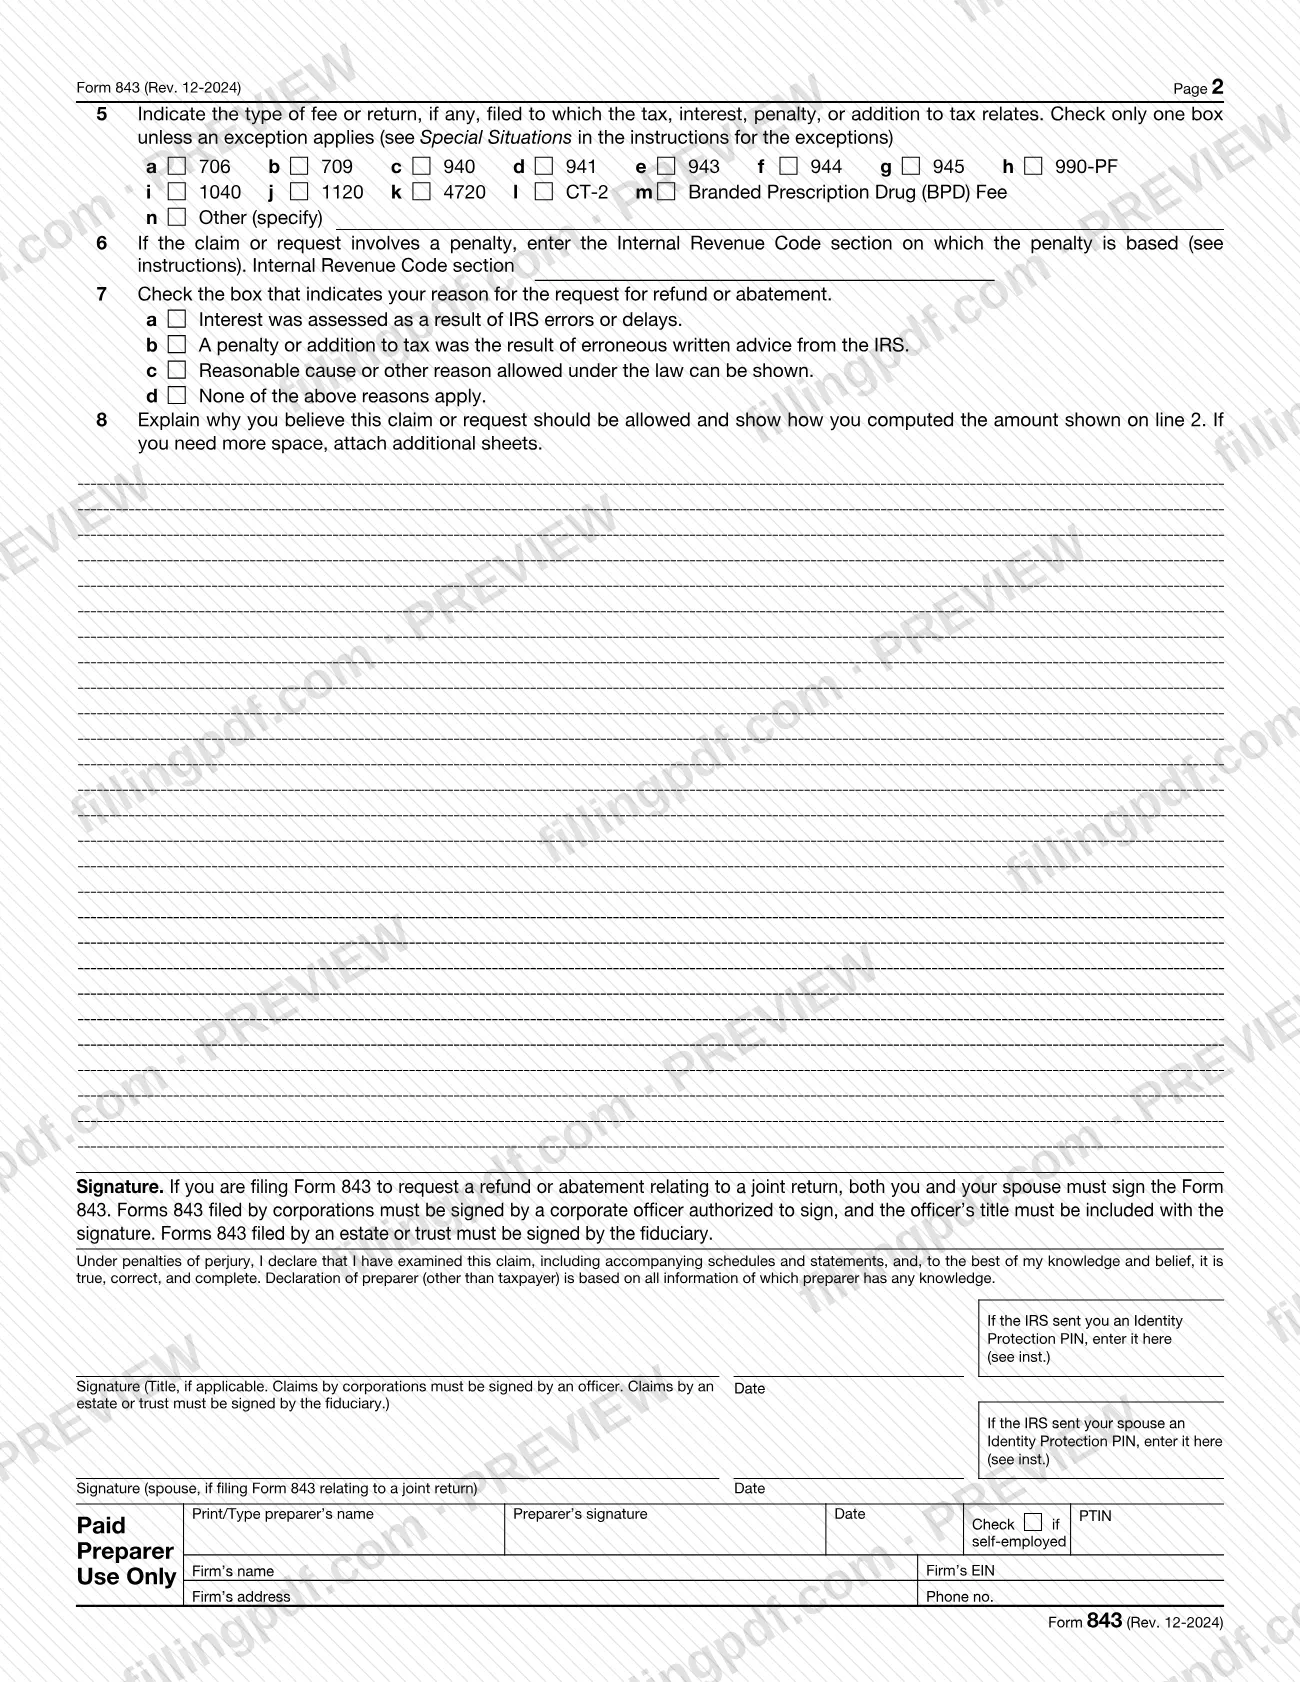
Form 843, Claim for Refund and Request for Abatement, is the Internal Revenue Service (IRS) form for claiming a refund or requesting an abatement of certain taxes, penalties, additions to tax, interest and fees. You check one reason at the top of the form, identify the tax period and amount, and explain your claim on line 8. On FillingPDF you can fill out Form 843 online and download or print the completed PDF; the form and its instructions are published by the IRS at www.irs.gov/Form843, and the claim goes to the IRS by mail.
Last updated
What is Form 843?
Form 843, Claim for Refund and Request for Abatement, is the Internal Revenue Service (IRS) form used to claim a refund or request an abatement of certain taxes, penalties, additions to tax, interest and fees. It is issued under OMB No. 1545-0024; the revision printed on it is Rev. December 2024.
The form is built around a reason box at the top. The reasons include abatement or refund of tax other than income, estate or gift tax; refunds to employees of excess or mistakenly withheld social security, Medicare or RRTA tax; abatement or refund of a penalty or addition to tax for reasonable cause; the Trust Fund Recovery Penalty under section 6672; interest caused by IRS error or delay under section 6404(e)(1); a net interest rate of zero under Rev. Proc. 2000-26; the branded prescription drug fee; and the annual fee on health insurance providers. An Other (specify) box covers reasons not listed.
Form 843 is not a universal refund form. The IRS instructions say not to use it when a different tax form must be used, for example to amend an income tax return (Form 1040-X, Form 1120-X), to correct employment tax returns (Forms 941-X, 943-X, 944-X, 945-X), for refunds of excise taxes (Form 8849, Form 720-X) or for return preparer and promoter penalties (Form 6118). If an IRS notice told you how to respond, follow the notice; you may not have to file Form 843.
Who needs to file Form 843?
You use Form 843 if your reason for a refund or abatement appears in the list at the top of the form and no other tax form is required for it. You can file it yourself, or your authorized representative can file it for you.
- Taxpayers seeking abatement or refund of a penalty or addition to tax because of reasonable cause or another reason allowed by law, including the Trust Fund Recovery Penalty (section 6672).
- Taxpayers asking the IRS to abate interest caused by its error or delay (section 6404(e)(1)), or to compute a net interest rate of zero on overlapping underpayments and overpayments.
- Employees claiming a refund of excess social security, Medicare or RRTA tax withheld by one employer, or tax withheld in error, but only if the employer will not adjust the overcollection.
- Payers of the branded prescription drug fee, and health insurance providers claiming a refund of the annual fee.
- Taxpayers who could not read and timely respond to a standard print notice from the IRS.
Do not use Form 843 to request an abatement of income, estate or gift tax, or a refund of income tax or Additional Medicare Tax. Employers cannot use it for FICA tax, RRTA tax or income tax withholding. A representative must attach Form 2848; a legal representative of a decedent has additional attachments (see Required documents).
When to file Form 843
Generally, you must file a claim for a credit or refund within 3 years from the date you filed your original return or 2 years from the date you paid the tax, whichever is later. If you do not file within that period, you may no longer be entitled to a credit or refund.
Some claims have their own timing. A request to abate a penalty or addition to tax caused by erroneous written advice from the IRS is allowed only if you submit it within the period allowed for collection of the penalty, or you paid it within the period allowed for claiming a credit or refund. Generally, file a separate Form 843 for each tax period, fee year or type of tax or fee; the instructions list exceptions under Special Situations. The IRS instructions give no processing time.
Documents you need
- Form 2848, Power of Attorney and Declaration of Representative (original or copy): attach it if an authorized representative files Form 843 for you; you must sign it.
- Statement that you filed the return and still act as the decedent's representative: attach it if you file for a decedent whose return you filed.
- Certified copies of letters testamentary, letters of administration or similar evidence of authority: attach them if you are a decedent's legal representative and did not file the decedent's return.
- Form 1310, Statement of Person Claiming Refund Due a Deceased Taxpayer: file it with Form 843 if you are the legal representative of a decedent.
- Employer statement for a refund of excess social security, Medicare or RRTA tax, if possible: amounts repaid or credit claimed by the employer, and that it supports your claim. Otherwise attach your own statement explaining why you could not get one.
- Copy of your Form W-2: attach it to prove the social security, Medicare or RRTA tax withheld; copies of your Forms W-2 for the year are required for excess tier 2 RRTA tax.
- For abatement or refund based on erroneous written IRS advice: your written request for advice, the advice you relied on, and the report of tax adjustments identifying the penalty or addition to tax, if any.
- Form 8947, Report of Branded Prescription Drug Information: attach a copy that supported the fee as calculated by the IRS when claiming a branded prescription drug fee refund.
- Documentation substantiating that you are the taxpayer entitled to the interest due on the overpayment, plus background material such as examination reports or IRS interest computations: for a net interest rate of zero request.
- Additional sheets, if line 3 or line 8 needs more space: include your name and SSN, ITIN or EIN on each sheet.
How to fill out Form 843
Check your reason for filing
At the top, check the one box that gives your reason, under Tax, Penalty, Interest or Other. Do not check more than one; if your reason is not listed, check Other (specify) and state it.
Enter name, TIN and address
Enter the name of the person requesting the refund or abatement and the SSN (or ITIN, or EIN for an entity). For a joint return, also enter the spouse's name and SSN from that return, plus your daytime telephone number and, if different, the name and address shown on the return.
Enter the tax period on line 1
Enter the beginning and ending dates in MM/DD/YYYY format. For a branded prescription drug fee, enter the fee year on the beginning date line; leave line 1 blank for a net interest rate of zero request.
Enter the amount on line 2
Enter the dollar amount you want refunded or abated. For a net interest rate of zero request you may enter an amount or leave it blank.
List payment dates on line 3
If you are requesting a refund of payments already made, enter each payment date (MM/DD/YYYY) in spaces a through l, and attach additional sheets if needed. Skip line 3 where the instructions say so, such as for excess tier 2 RRTA tax.
Check the tax or fee type on line 4
Check the box (Employment, Estate, Gift, Excise, Income, Fee or Civil penalty) for the tax or fee you are claiming, or to which the interest, penalty or addition to tax relates. Check only one unless an exception applies.
Indicate the return or fee on line 5
Check the box for the return or fee your claim relates to, such as 941, 1040 or Branded Prescription Drug (BPD) Fee. Use box i (1040) for other individual returns such as Form 1040-SR or 1040-NR, or Other (specify).
Enter the Code section on line 6
If the claim involves a penalty, enter the Internal Revenue Code section on which it is based. You can generally find it on the Notice of Assessment from the IRS.
Select your reason on line 7
Check a for interest caused by IRS errors or delays, b for erroneous written IRS advice, or c for reasonable cause or another reason allowed by law. If a, b and c do not apply, check d.
Explain your claim on line 8
Explain in detail why the claim should be allowed and show how you computed the amount on line 2. Attach supporting evidence and any additional sheets with your name and SSN, ITIN or EIN.
Follow special-situation instructions
If your claim involves excess RRTA tax, a penalty based on IRS written advice, interest abatement, a net interest rate of zero or the branded prescription drug fee, follow the line-by-line directions for that case in the IRS instructions.
Sign and date the claim
Sign and date under penalties of perjury. Both spouses sign a claim relating to a joint return, a corporate officer signs with title, and a fiduciary signs for an estate or trust. Enter an Identity Protection PIN if the IRS sent you one.
Complete the paid preparer section
If a paid tax return preparer completes the form, the preparer signs and fills in the preparer name, PTIN, firm details and phone number. A preparer who does not charge you should not sign.
Review and download the completed PDF
Check each line, the signatures and the attachments. Download or print the completed PDF from FillingPDF and mail the package to the IRS address described under How to submit.
How to submit Form 843
You mail Form 843 to the IRS; the address depends on why you file. Check the Where To File table in the IRS instructions for Form 843 before mailing.
- In response to an IRS notice about a tax or fee: the return address from which the notice was sent.
- Claim for refund in a Form 706 or 709 tax matter: Internal Revenue Service, Attn: E&G, Stop 824G, 7940 Kentucky Drive, Florence, KY 41042-2915.
- Response to Letter 4658 (branded prescription drug fee): Internal Revenue Service, Mail Stop 4921 BPDF, 1973 N. Rulon White Blvd., Ogden, UT 84201-0051.
- Response to Letter 5067C (annual fee on health insurance providers, final fee): Internal Revenue Service, Mail Stop 4921 IPF, 1973 N. Rulon White Blvd., Ogden, UT 84201.
- Net interest rate of zero: the service center where you filed your most recent return.
- Nonresident alien refund of social security or Medicare tax withheld in error: the address in Pub. 519.
- Requests related to Form 8300: Internal Revenue Service, Rosa Parks Federal Building, P.O. Box 32621, Detroit, MI 48232.
- Penalties, or any other reason: the service center where you would file a current-year return for the tax your claim relates to.
Do not send the form to the Tax Forms and Publications address printed in the instructions; it is for comments only. If you moved after filing, use Form 8822 (or Form 8822-B for a business) to update your address. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Using Form 843 to claim a refund of income tax or Additional Medicare Tax, or to amend an income or employment tax return; the instructions direct these to other forms such as Form 1040-X or Form 941-X.
- Checking more than one reason box at the top of the form; the instructions say not to check more than one.
- Filing one Form 843 for several tax periods, fee years or types of tax when the instructions require a separate form for each, except in the listed Special Situations.
- Leaving line 7 unanswered or choosing a, b or c without support; if a, b and c do not apply, check box d.
- Attaching extra sheets for line 3 or line 8 without your name and SSN, ITIN or EIN on each sheet.
- Signing a joint-return claim with only one signature; both spouses from the related joint return must sign.
- Signing a corporate claim without the officer's title, or an estate or trust claim by someone other than the fiduciary.
- Entering a P.O. box when the post office delivers mail to your home, or abbreviating the country name on a foreign address.
- Filling in lines the instructions say to skip, such as line 3 for excess tier 2 RRTA tax or a net interest rate of zero request (leave line 1 blank).
- Mailing the form to the address printed for comments instead of the address in the Where To File table.
Frequently asked questions
What is Form 843 used for?
Form 843 is the IRS form used to claim a refund or request an abatement of certain taxes, penalties, additions to tax, interest and fees. You check the reason for filing at the top, such as a penalty for reasonable cause or interest caused by IRS error or delay.
Can I use Form 843 to get a refund of income tax?
No. The IRS instructions say not to use Form 843 to request a refund of income tax or to amend a filed income tax return. Use the corrected return instead, such as Form 1040-X for individuals or Form 1120-X for corporations.
What is the deadline to file Form 843?
Generally, within 3 years from the date you filed your original return or 2 years from the date you paid the tax, whichever is later. Claims based on erroneous written IRS advice have their own timing rules, described in the IRS instructions.
Where do I mail Form 843?
It depends on why you file. If you respond to an IRS notice, mail it to the return address on the notice. Otherwise use the Where To File table in the instructions, for example the service center where you would file a current-year return for the tax involved.
Do I need a separate Form 843 for each tax year?
Generally yes: file a separate Form 843 for each tax period or fee year or type of tax or fee. The instructions list exceptions, such as a net interest rate of zero request and interest abatement from a single IRS error affecting several tax years.
What do I write on line 8 of Form 843?
Explain in detail why the claim should be allowed and show how you computed the amount on line 2. Attach supporting evidence. If you add sheets, put your name and SSN, ITIN or EIN on each one. Special situations list further items to include.
Can someone else file Form 843 for me?
Yes. Your authorized representative can file it if the original or a copy of Form 2848 is attached and you have signed it. A decedent's legal representative attaches proof of authority and files Form 1310 with Form 843.
Can I fill out Form 843 online on FillingPDF?
Yes. You can fill out the fillable PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the claim with the IRS; you mail the signed form to the IRS address that applies to your claim.
Ready to fill out Form 843?
Fill out Form 843 now