
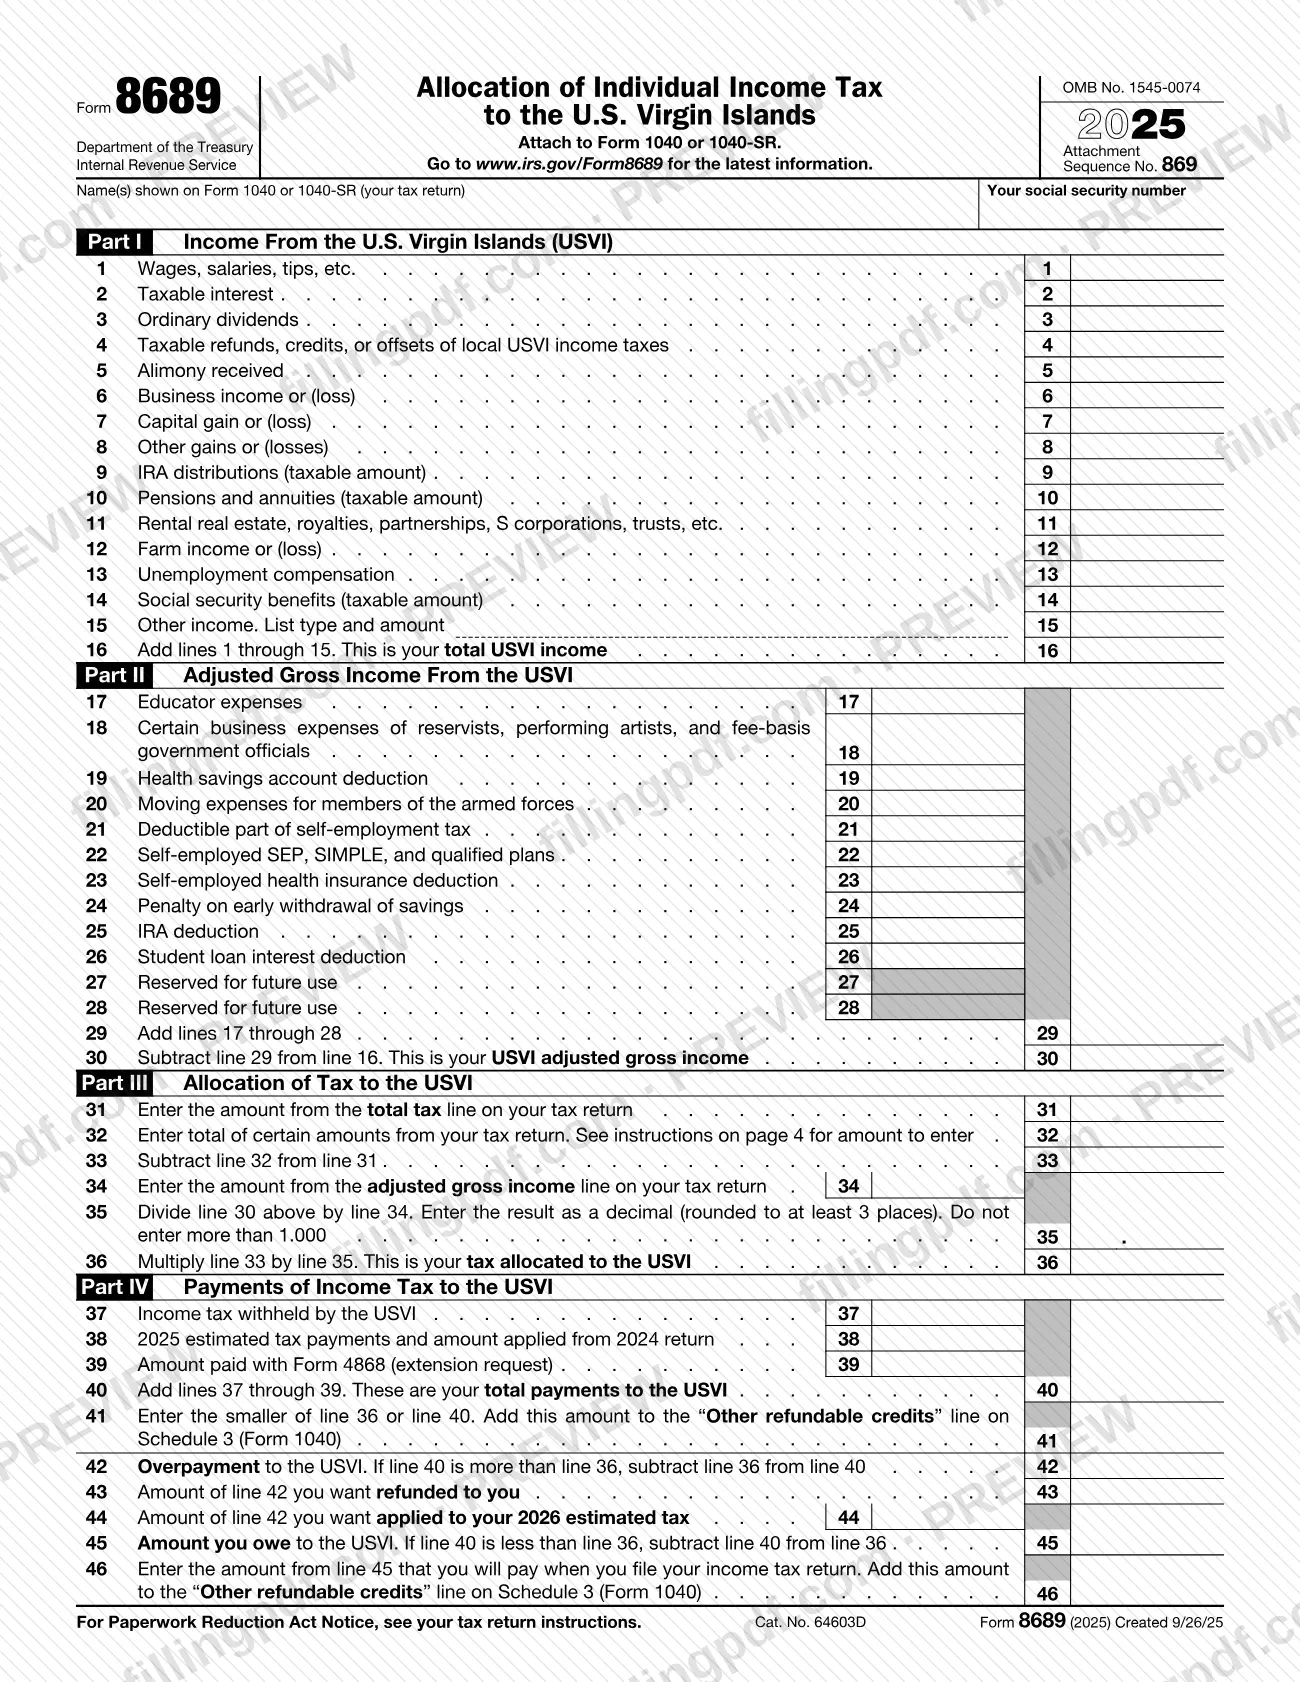
Form 8689, Allocation of Individual Income Tax to the U.S. Virgin Islands, is the Internal Revenue Service (IRS) form used to figure how much of your U.S. tax is allocable to the U.S. Virgin Islands (USVI). It is for U.S. citizens and resident aliens who are not bona fide residents of the USVI but had USVI income, and it is attached to Form 1040 or 1040-SR. On this page you can fill out the form online on FillingPDF and download or print the completed PDF; the original form and its latest information are published by the IRS at www.irs.gov/Form8689.
Last updated
What is 8689?
Form 8689, Allocation of Individual Income Tax to the U.S. Virgin Islands is the IRS form that U.S. citizens and resident aliens use to figure the amount of U.S. tax allocable to the U.S. Virgin Islands (USVI), which becomes their USVI tax liability.
The USVI tax liability is a percentage of your U.S. tax liability. The form works in four parts:
- Part I (lines 1 to 16) totals your income from the USVI.
- Part II (lines 17 to 30) turns that into your USVI adjusted gross income.
- Part III (lines 31 to 36) divides USVI adjusted gross income by the adjusted gross income on your tax return and applies the resulting decimal to your tax, giving the tax allocated to the USVI on line 36.
- Part IV (lines 37 to 46) compares that tax with what you already paid the USVI and shows any overpayment or amount owed.
The form is attached to Form 1040 or 1040-SR (OMB No. 1545-0074, Attachment Sequence No. 869) and is not filed on its own. The IRS instructions point to Pub. 570, Tax Guide for Individuals With Income From U.S. Territories, for the source-of-income rules and for where to file. Form 8689 does not replace the USVI return itself: you file identical returns with the United States and the USVI. It is also not for bona fide residents of the USVI for the entire tax year.
Who needs to file 8689?
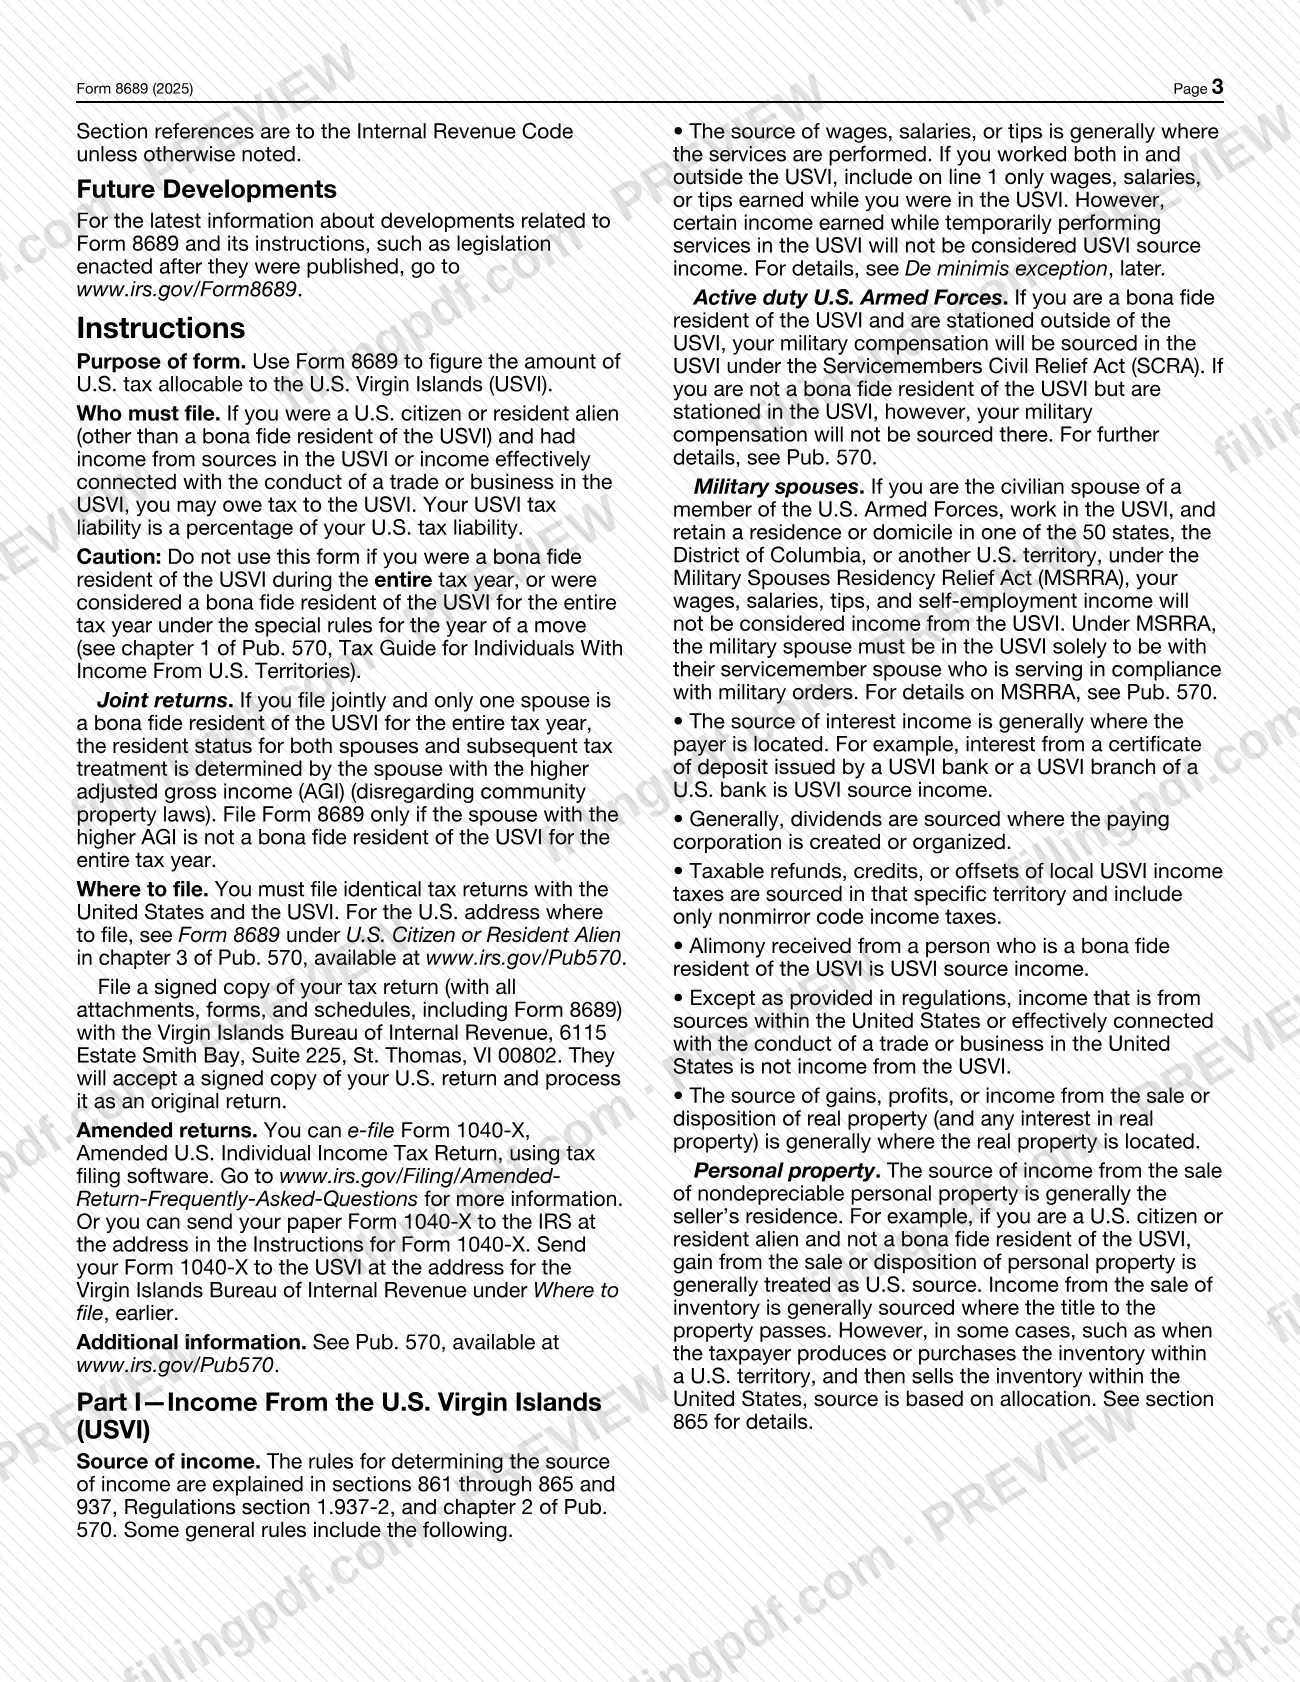
You must file Form 8689 if you were a U.S. citizen or resident alien, other than a bona fide resident of the USVI, and had income from sources in the USVI or income effectively connected with the conduct of a trade or business in the USVI. You may owe tax to the USVI.
Do not use this form if you were a bona fide resident of the USVI during the entire tax year, or were considered a bona fide resident for the entire year under the special rules for the year of a move (see chapter 1 of Pub. 570).
Other conditions in the IRS instructions:
- Joint returns: if only one spouse is a bona fide USVI resident for the entire year, the status of both spouses is determined by the spouse with the higher adjusted gross income. File Form 8689 only if that spouse is not a bona fide resident for the entire year.
- Active duty military: a bona fide USVI resident stationed outside the USVI has military pay sourced in the USVI. A non-resident stationed in the USVI does not.
- Military spouses: under the Military Spouses Residency Relief Act (MSRRA), wages and self-employment income of a civilian spouse who is in the USVI solely to be with a servicemember spouse are not USVI income.
- De minimis exception: certain pay for temporary services in the USVI is not USVI income, as explained on page 4 of the form.
When to file 8689
Form 8689 is due with the tax return it is attached to, Form 1040 or 1040-SR, so it has no separate due date printed on it. The triggering event is having USVI source income, or income effectively connected with a USVI trade or business, as a U.S. citizen or resident alien who is not a bona fide USVI resident for the entire year.
The 2025 form refers to 2025 estimated tax payments (line 38) and to any amount paid with Form 4868, the extension request (line 39), and it lets you apply an overpayment to your 2026 estimated tax (line 44). If you became or ceased to be a bona fide resident of a U.S. territory, you may also be required to file Form 8898; a penalty may apply if you fail to provide the information required.
Documents you need
- Form 1040 or 1040-SR: Form 8689 is attached to it, and several lines (31, 32, 34) take amounts from that return.
- A signed copy of your tax return with all attachments, forms and schedules, including Form 8689, for the Virgin Islands Bureau of Internal Revenue.
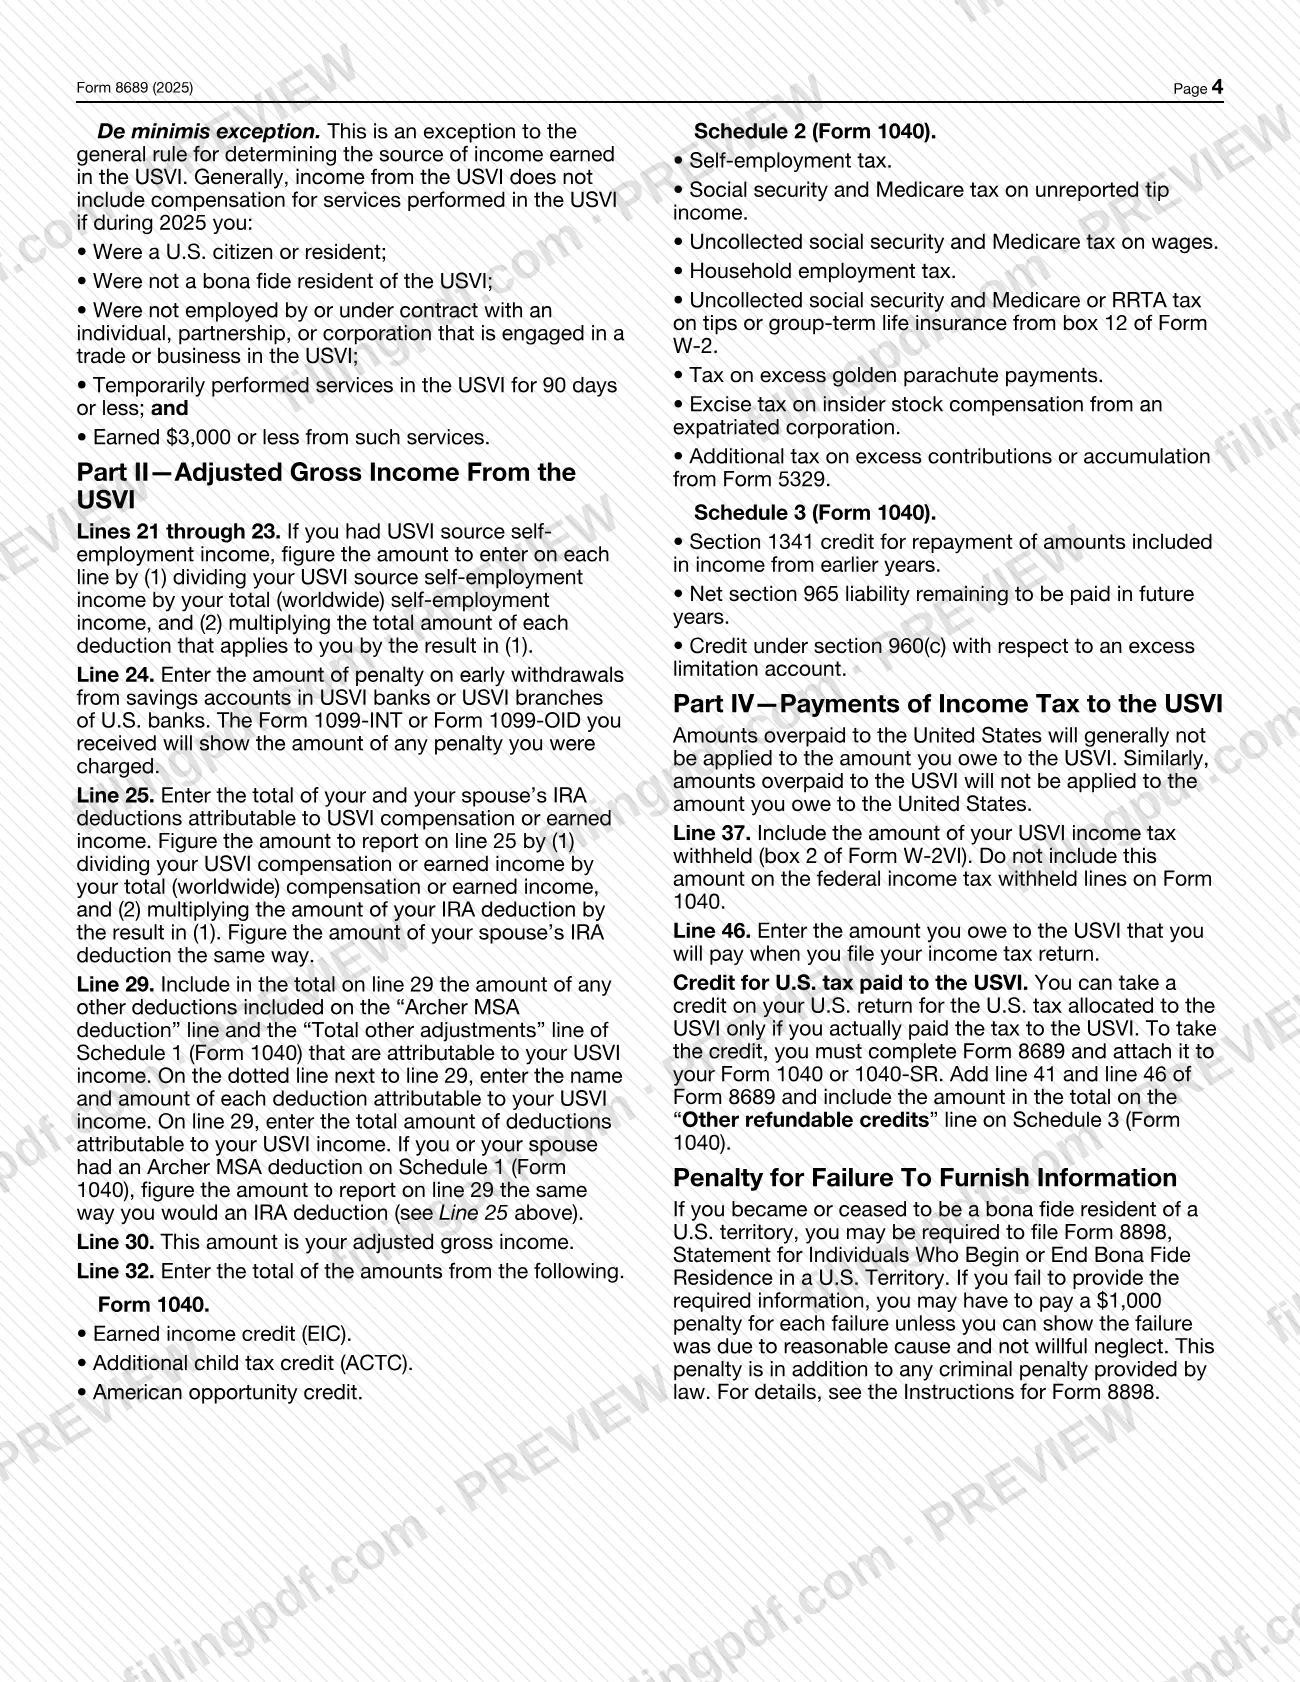
- Form W-2VI: box 2 shows the USVI income tax withheld that you enter on line 37.
- Form 1099-INT or Form 1099-OID: shows any penalty on early withdrawal from a USVI bank or USVI branch of a U.S. bank, entered on line 24.
- Schedule 3 (Form 1040): lines 41 and 46 amounts are added to its Other refundable credits line, so complete it with the return.
How to fill out 8689
Enter your name and SSN
At the top, enter the name(s) shown on Form 1040 or 1040-SR and your social security number.
Report USVI income in Part I
On lines 1 through 14, enter only the income from USVI sources for each type: wages, interest, dividends, refunds, alimony, business, gains, IRA, pensions, rental and similar income, farm income, unemployment and taxable social security. Apply the source rules in the instructions.
Total your USVI income
On line 15 list the type and amount of any other income, then add lines 1 through 15 on line 16 for your total USVI income.
Enter adjustments in Part II
On lines 17 through 26, enter only the part of each deduction attributable to USVI income. For lines 21 through 23, divide USVI self-employment income by total self-employment income and multiply each deduction by the result. Lines 27 and 28 are reserved for future use.
Figure USVI adjusted gross income
Add lines 17 through 28 on line 29, including other Schedule 1 deductions tied to USVI income, named on the dotted line. Subtract line 29 from line 16 on line 30.
Start the tax allocation in Part III
Enter your return's total tax on line 31 and the certain credits and taxes the instructions list on line 32. Subtract line 32 from line 31 on line 33.
Compute the allocation percentage
Enter your return's adjusted gross income on line 34. On line 35, divide line 30 by line 34 as a decimal rounded to at least 3 places, never more than 1.000.
Calculate tax allocated to the USVI
Multiply line 33 by line 35 and enter the result on line 36.
Enter payments in Part IV
Enter USVI income tax withheld (Form W-2VI, box 2) on line 37, 2025 estimated payments and the amount applied from 2024 on line 38, and any Form 4868 payment on line 39. Add them on line 40.
Find the credit amount
On line 41 enter the smaller of line 36 or line 40. Add that amount to the Other refundable credits line on Schedule 3 (Form 1040).
Complete overpayment or amount owed
If line 40 exceeds line 36, enter the difference on line 42, then split it between a refund (line 43) and 2026 estimated tax (line 44). If line 40 is less, enter the difference on line 45 and the amount you will pay with your return on line 46, adding it to Schedule 3.
Review and download the PDF
Check each line against the instructions and your return, then download or print the completed PDF from FillingPDF and attach it to your Form 1040 or 1040-SR.
How to submit 8689
Form 8689 is submitted with your tax return to two places: the IRS and the Virgin Islands Bureau of Internal Revenue. The IRS instructions say you must file identical tax returns with the United States and the USVI.
- To the IRS: attach Form 8689 to Form 1040 or 1040-SR. For the U.S. address, see Form 8689 under U.S. Citizen or Resident Alien in chapter 3 of Pub. 570, at www.irs.gov/Pub570.
- To the USVI: file a signed copy of your tax return, with all attachments, forms and schedules including Form 8689, with the Virgin Islands Bureau of Internal Revenue, 6115 Estate Smith Bay, Suite 225, St. Thomas, VI 00802. The Bureau accepts a signed copy of your U.S. return and processes it as an original return.
- Amended returns: you can e-file Form 1040-X with tax filing software or mail a paper Form 1040-X to the IRS at the address in its instructions. Send your Form 1040-X to the USVI at the Bureau address above.
The form's Part IV addresses payment: line 46 is the amount you owe the USVI that you will pay when you file. Amounts overpaid to one jurisdiction are generally not applied to what you owe the other. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Filing Form 8689 as a bona fide resident of the USVI for the entire tax year, or as someone treated as one under the special rules for the year of a move; the caution on the form says not to use it.
- Filing Form 8689 on a joint return when the spouse with the higher AGI is a bona fide USVI resident for the entire year.
- Entering a line 35 decimal above 1.000; the form says not to enter more than 1.000 and to round to at least 3 places.
- Including USVI income tax withheld (Form W-2VI, box 2) on the federal income tax withheld lines of Form 1040 instead of line 37 of Form 8689.
- Taking the credit for U.S. tax allocated to the USVI when you have not actually paid that tax to the USVI.
- Counting wages earned outside the USVI on line 1; if you worked both in and outside the USVI, include only pay earned while in the USVI.
- Not adding lines 41 and 46 to the Other refundable credits line on Schedule 3 (Form 1040).
- Expecting an overpayment to one jurisdiction to cover what you owe the other; overpayments are generally not applied across.
- Filing with the USVI only the Form 8689 instead of a signed copy of the whole return with all attachments.
Frequently asked questions
What is Form 8689 used for?
Form 8689 is used to figure the amount of U.S. tax allocable to the U.S. Virgin Islands. A U.S. citizen or resident alien who is not a bona fide USVI resident and has USVI source income uses it, and the result is the USVI tax liability, a percentage of the U.S. tax.
Who has to file Form 8689?
U.S. citizens and resident aliens, other than bona fide residents of the USVI, who had income from USVI sources or income effectively connected with a USVI trade or business. Bona fide USVI residents for the entire year do not use it.
Where do I file Form 8689?
Attach it to Form 1040 or 1040-SR for the IRS, and file a signed copy of the whole return with the Virgin Islands Bureau of Internal Revenue, 6115 Estate Smith Bay, Suite 225, St. Thomas, VI 00802. The U.S. address is in chapter 3 of Pub. 570.
Can I fill out Form 8689 online?
Yes. You can fill out the PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the form with the IRS or the USVI; you submit it through the channels the IRS instructions describe.
How do I figure the decimal on line 35 of Form 8689?
Divide line 30, your USVI adjusted gross income, by line 34, the adjusted gross income on your tax return. Round the decimal to at least 3 places and never enter more than 1.000. Line 36 is line 33 multiplied by this decimal.
Is pay for a short job in the USVI counted as USVI income?
Not under the de minimis exception, if during 2025 you were a U.S. citizen or resident, not a bona fide USVI resident, not employed by a USVI business, worked there 90 days or less and earned $3,000 or less. You must meet all conditions.
Can I take a U.S. credit for tax allocated to the USVI?
Only if you actually paid the tax to the USVI. Complete Form 8689, attach it to Form 1040 or 1040-SR, then add lines 41 and 46 and include the total on the Other refundable credits line of Schedule 3 (Form 1040).
How do I amend a return that includes Form 8689?
Use Form 1040-X. You can e-file it with tax filing software or mail a paper copy to the IRS at the address in its instructions. Send your Form 1040-X to the Virgin Islands Bureau of Internal Revenue at the St. Thomas address as well.
Ready to fill out 8689?
Fill out 8689 now