
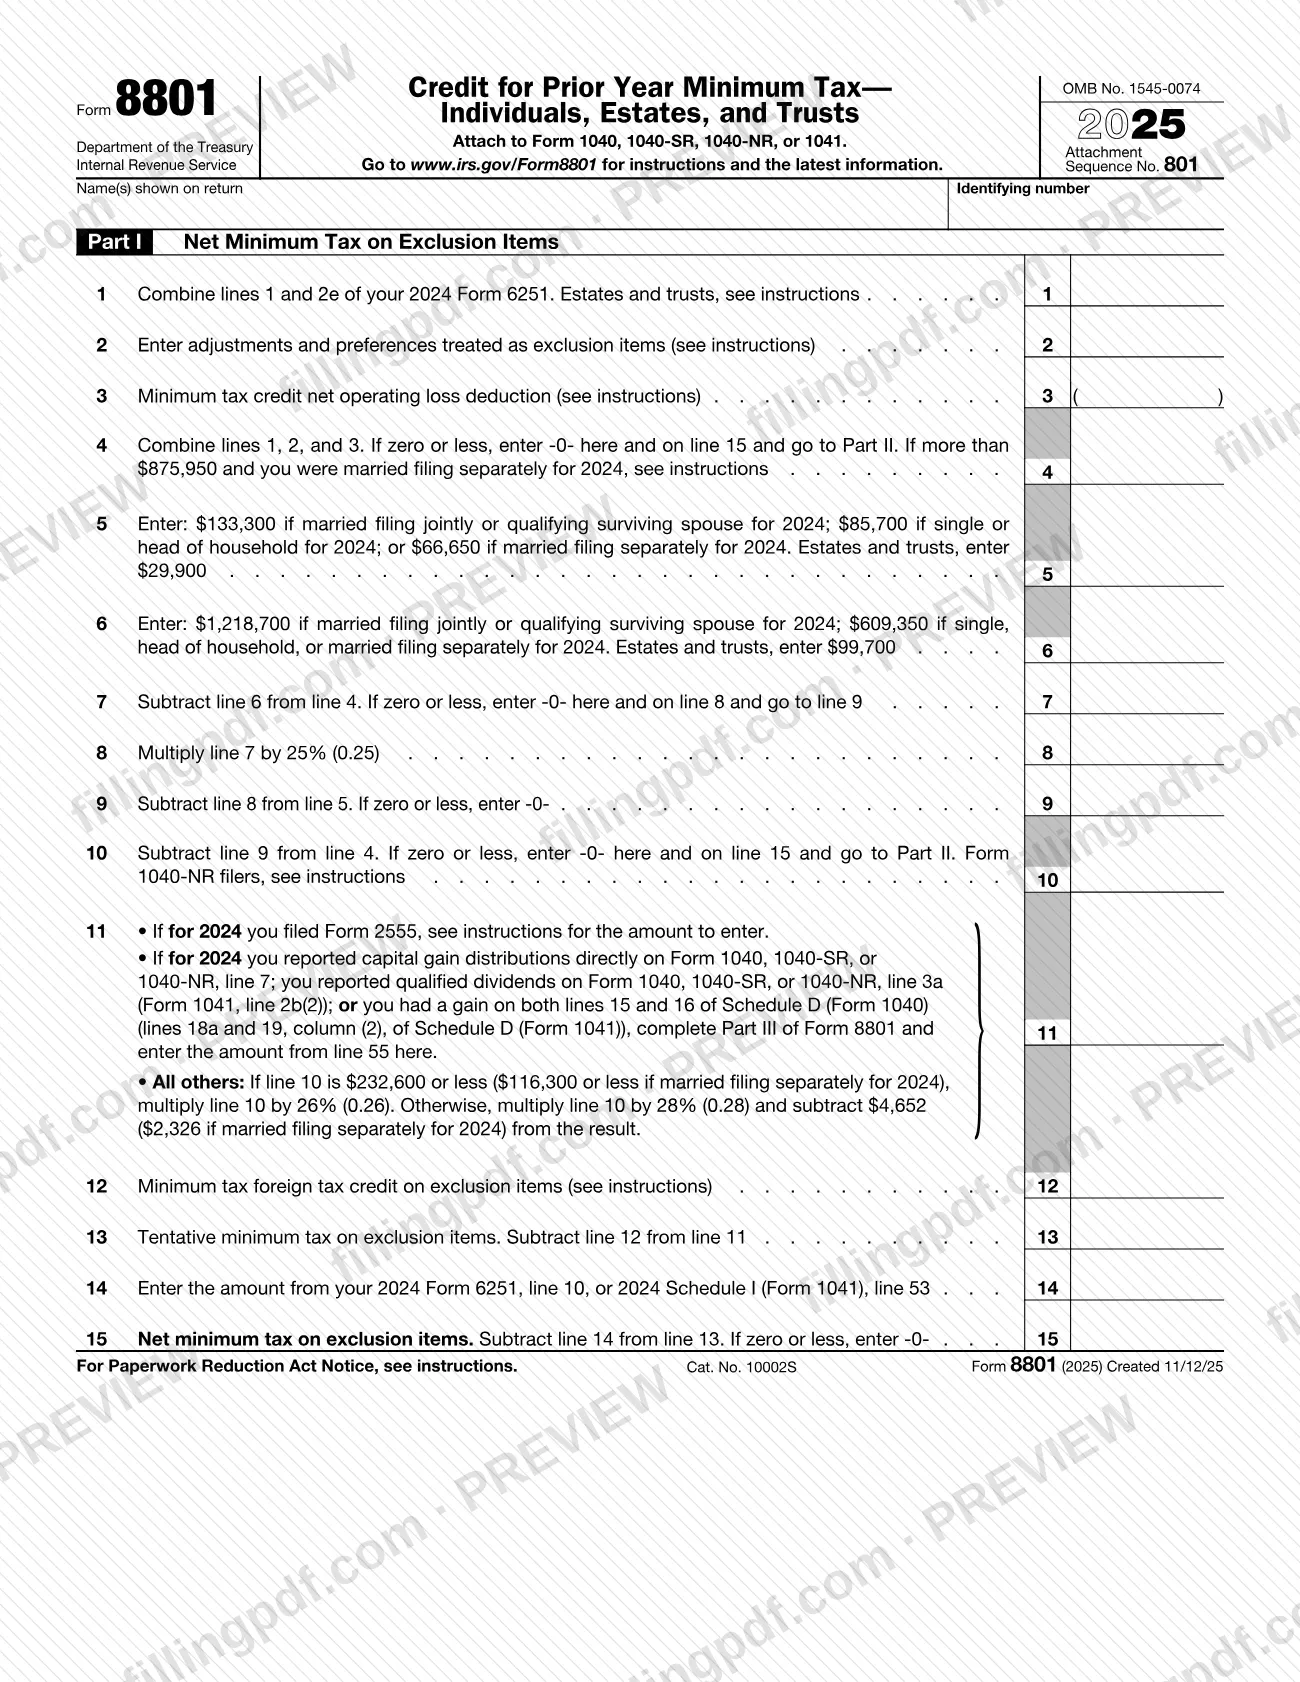
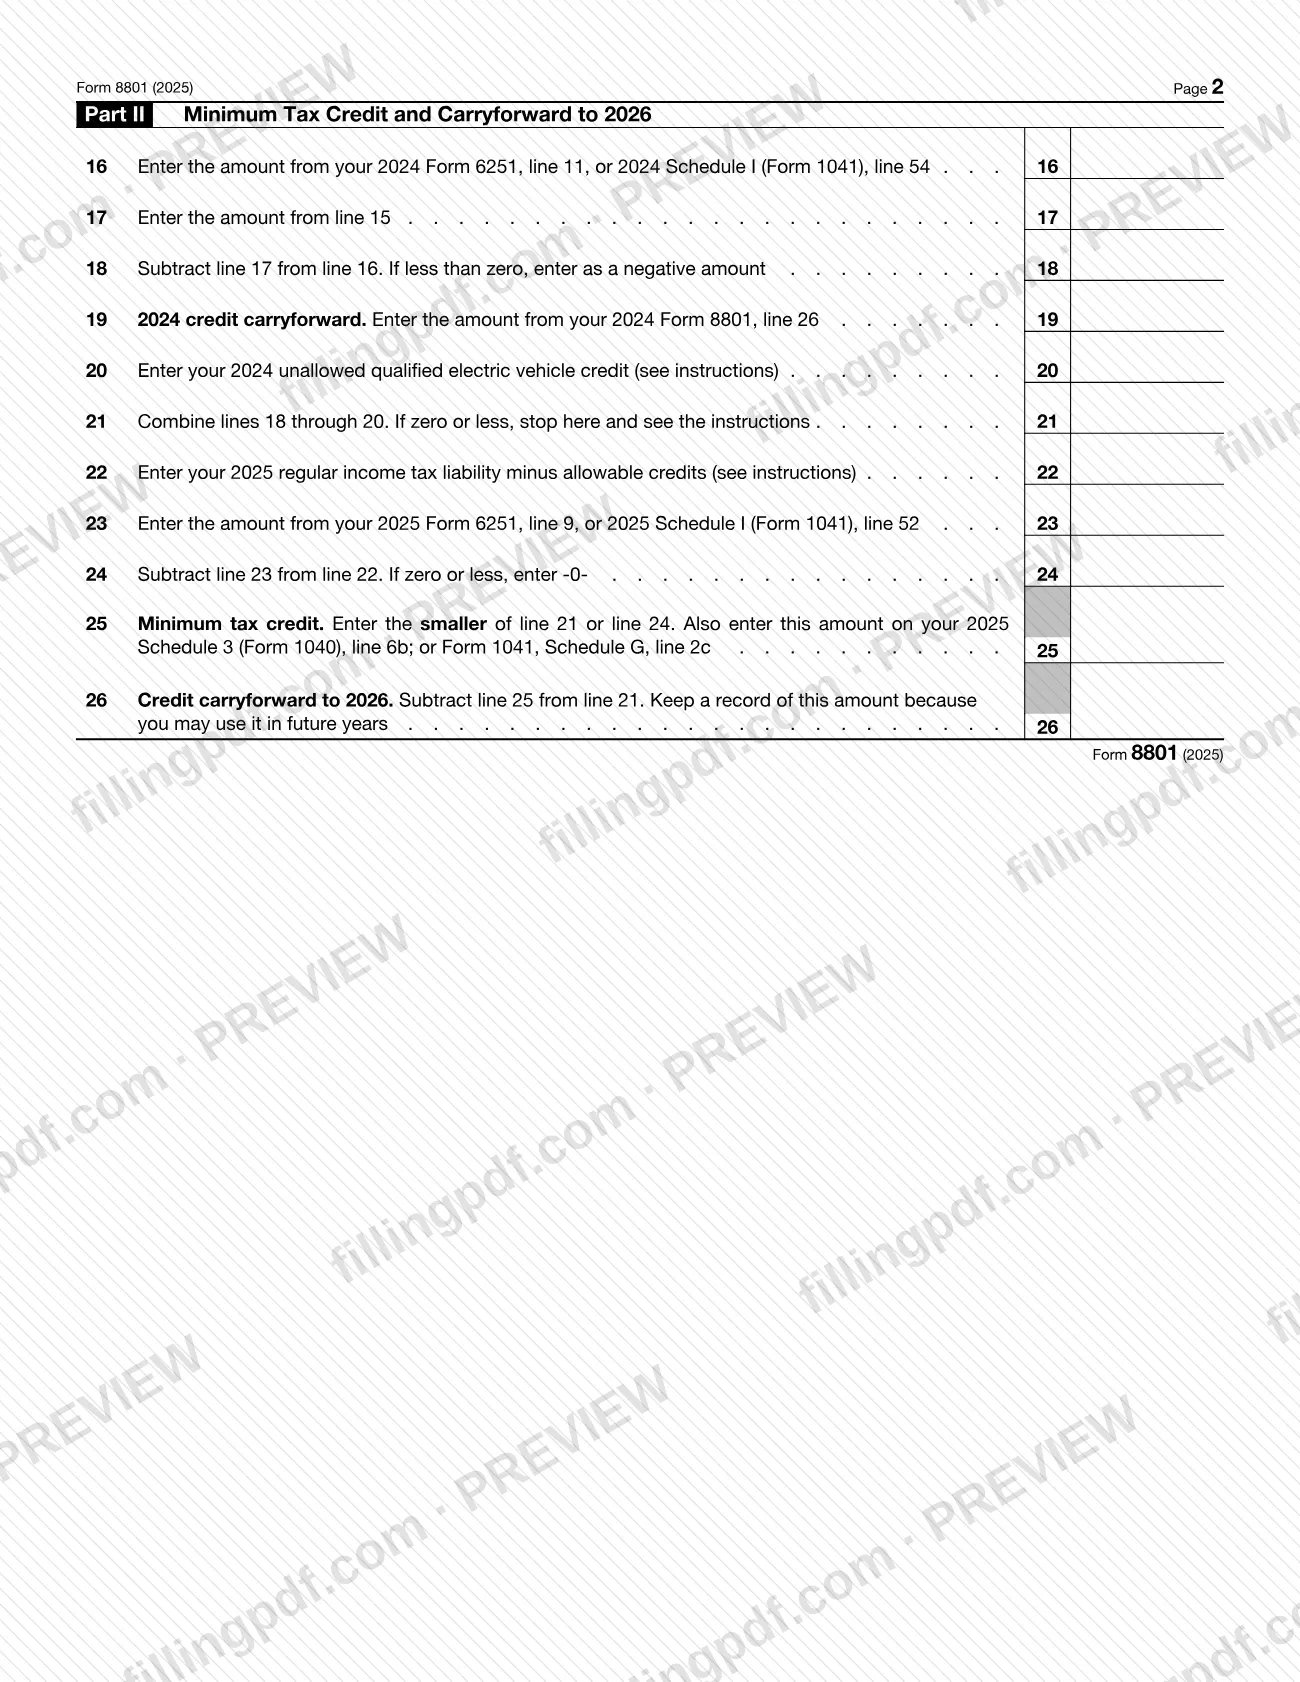
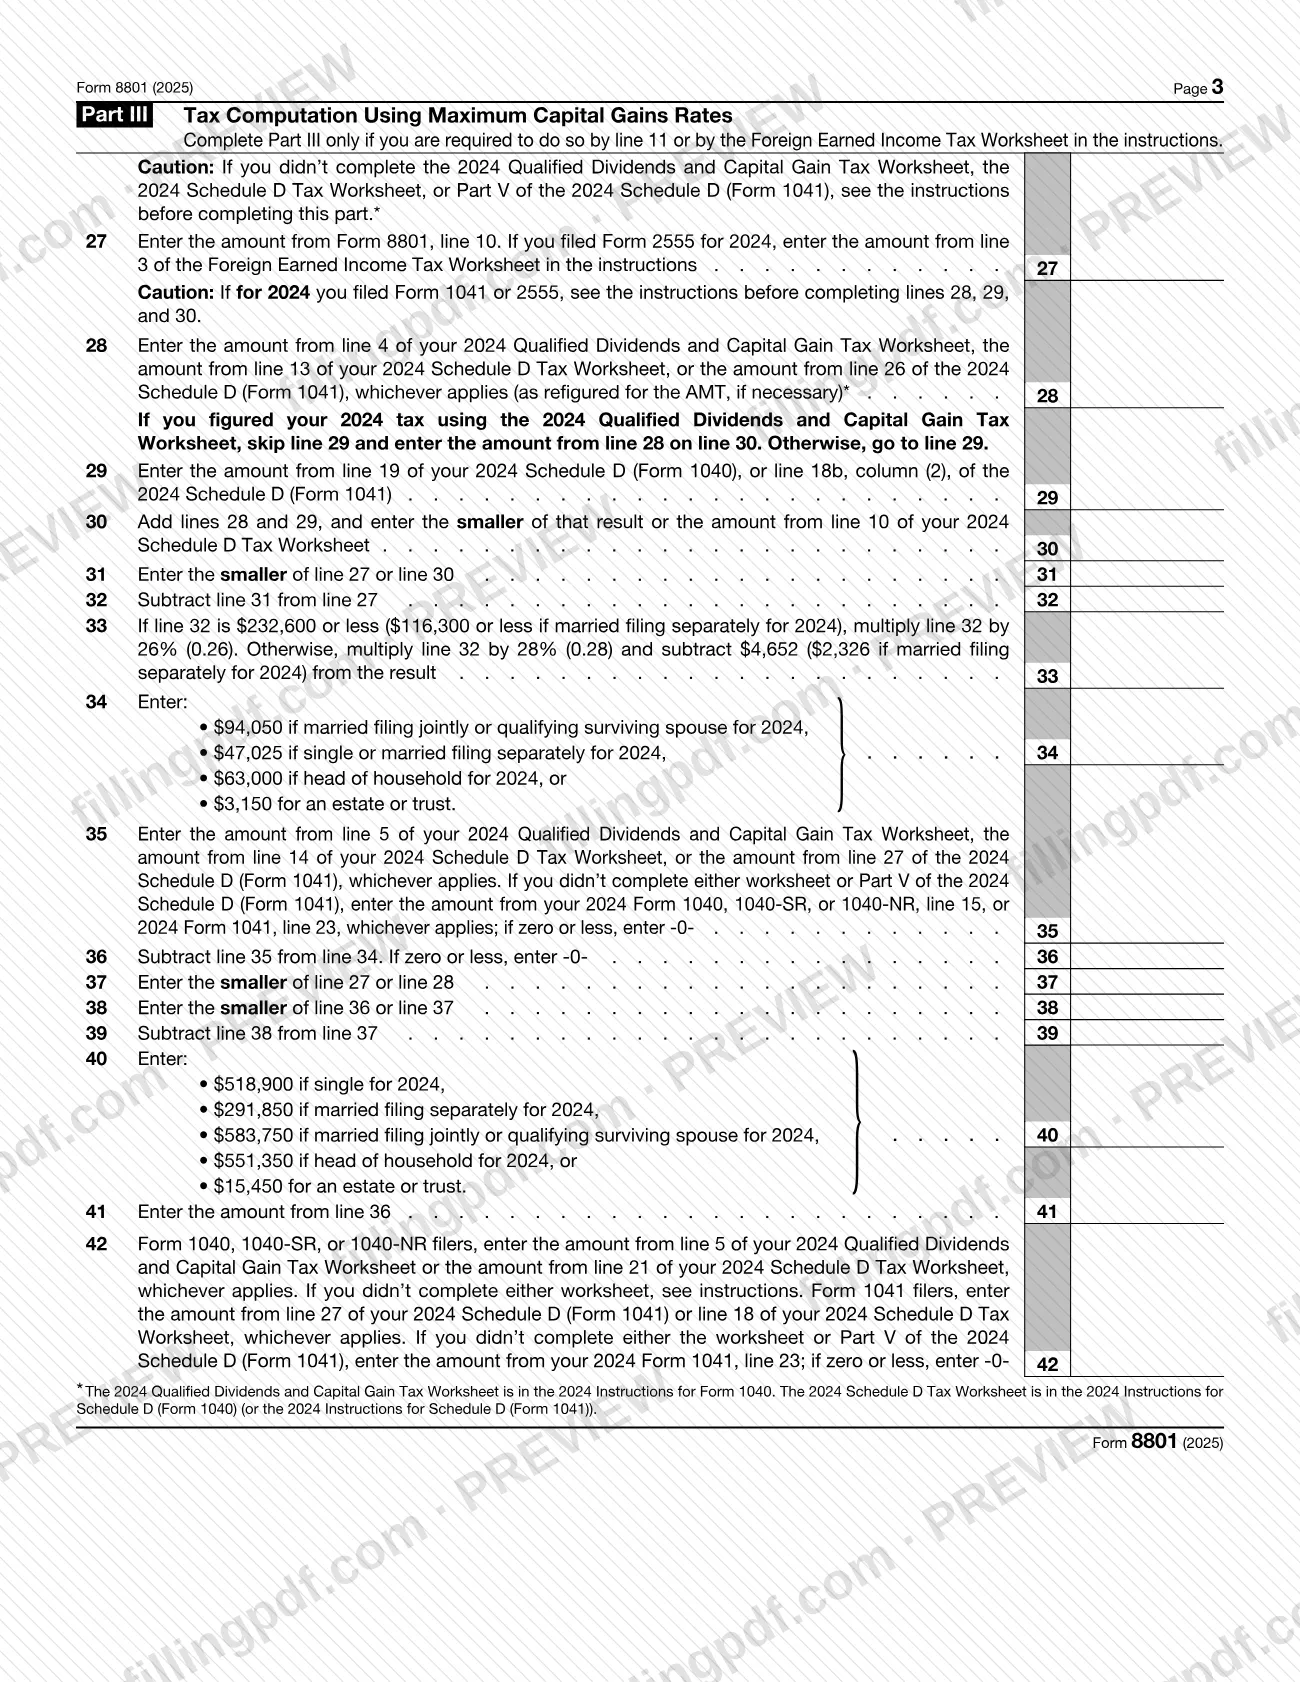
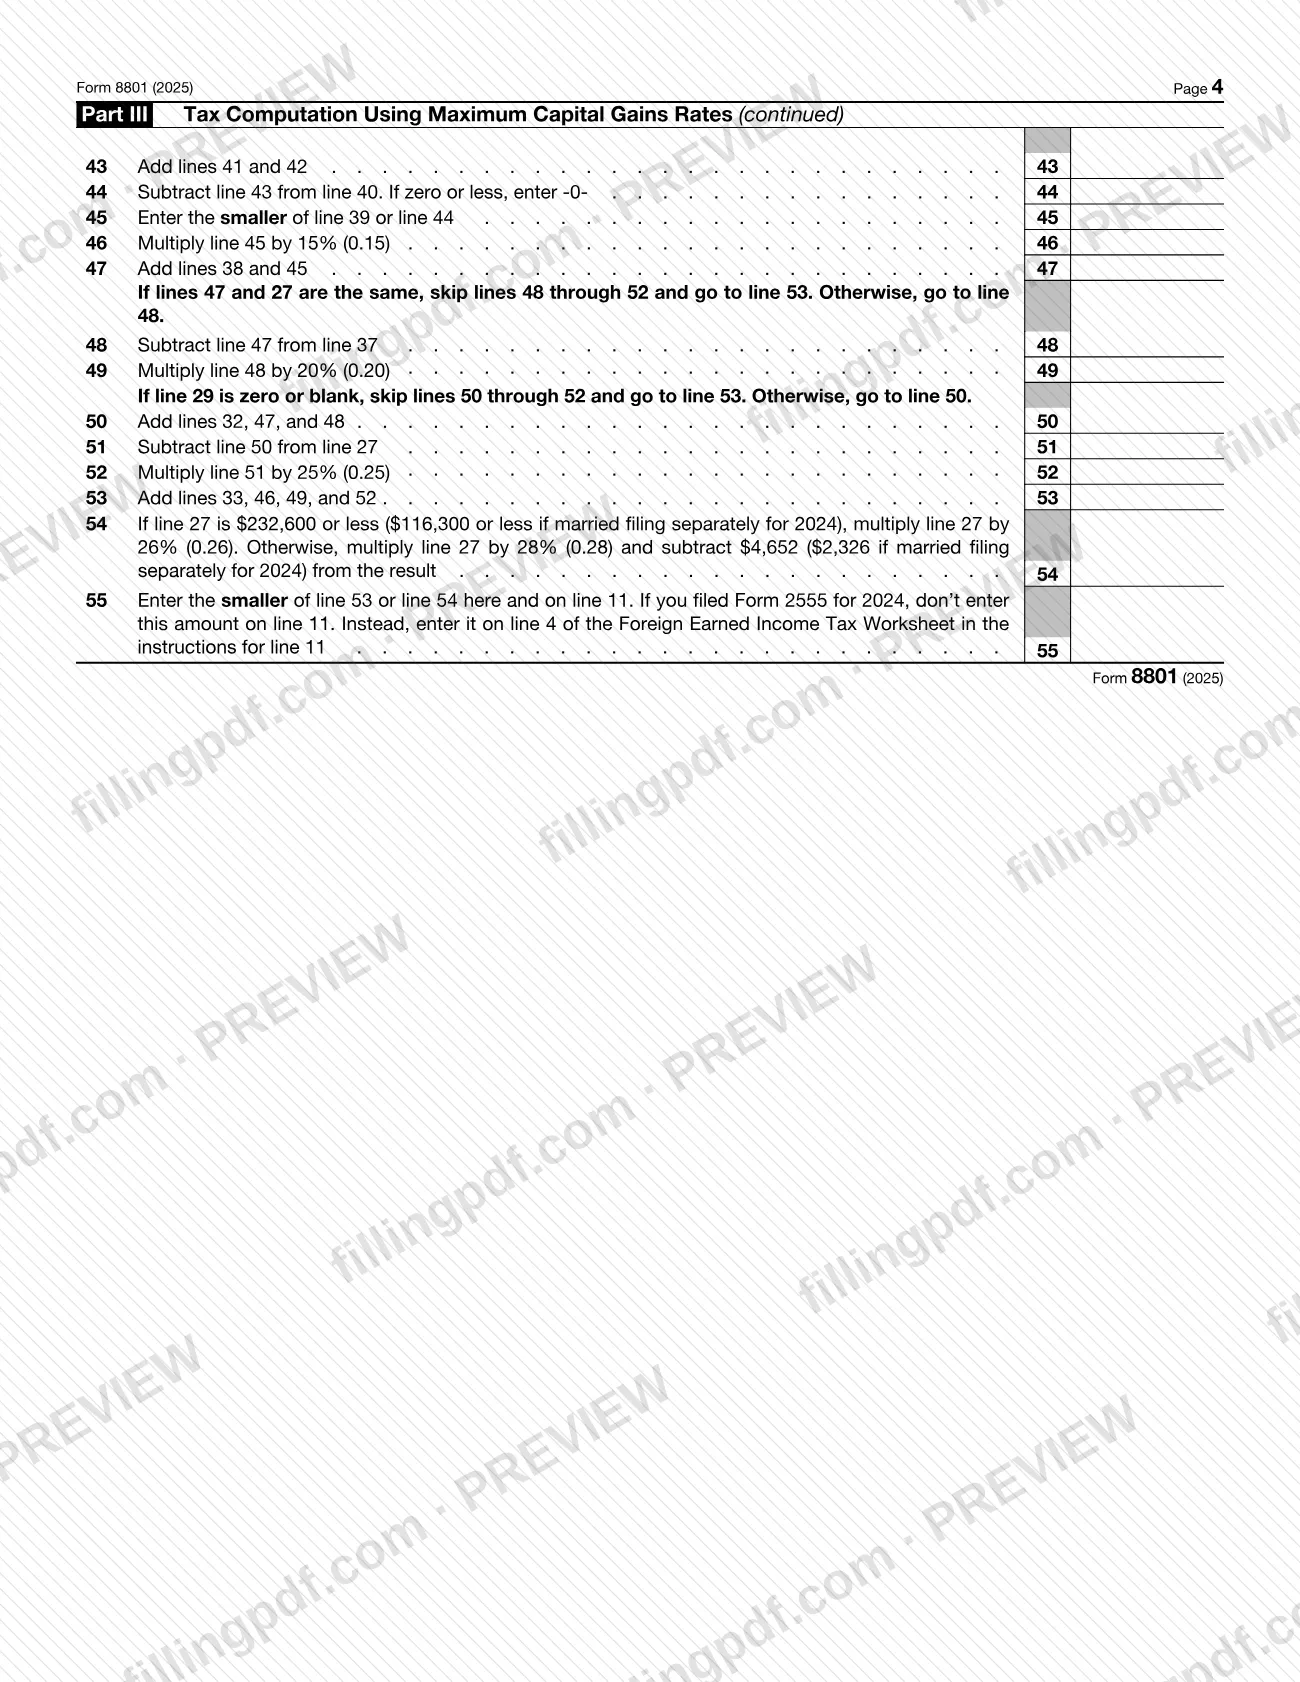
Form 8801 is the Internal Revenue Service (IRS) form that individuals, estates, and trusts use to figure the minimum tax credit, if any, for alternative minimum tax (AMT) incurred in prior years, and any credit carryforward to 2026. It is attached to Form 1040, 1040-SR, 1040-NR, or 1041, and the instructions say to file it only if line 21 is more than zero. On FillingPDF you can fill out Form 8801 online and download or print the completed PDF; the IRS publishes the original PDF and instructions at www.irs.gov/Form8801.
Last updated
What is Form 8801?
Form 8801, Credit for Prior Year Minimum Tax—Individuals, Estates, and Trusts, is the IRS form that individuals, estates, and trusts use to figure the minimum tax credit for alternative minimum tax (AMT) incurred in prior tax years and any credit carryforward to 2026.
The IRS instructions explain the idea behind the credit. The AMT is a separate tax imposed in addition to regular tax and is caused by two kinds of adjustments and preferences: deferral items (for example, depreciation) and exclusion items (for example, the standard deduction). Deferral items generally do not create a permanent difference in taxable income over time, while exclusion items do. The minimum tax credit is allowed only for AMT caused by deferral items, so Part I of the form strips out the net minimum tax on exclusion items.
The form has three parts:
- Part I, Net Minimum Tax on Exclusion Items (lines 1 to 15), built from your 2024 Form 6251 (or 2024 Schedule I (Form 1041) for estates and trusts).
- Part II, Minimum Tax Credit and Carryforward to 2026 (lines 16 to 26). Line 25 is the credit, and line 26 is the carryforward to keep for future years.
- Part III, Tax Computation Using Maximum Capital Gains Rates (lines 27 to 55), completed only when line 11 or the Foreign Earned Income Tax Worksheet in the instructions requires it.
The credit from line 25 goes on Schedule 3 (Form 1040), line 6b, or Form 1041, Schedule G, line 2c.
Who needs to file Form 8801?
Complete Form 8801 if you are an individual, estate, or trust that for 2024 had any of the following, according to the IRS instructions:
- an AMT liability and adjustments or preferences other than exclusion items;
- a credit carryforward to 2025, shown on line 26 of your 2024 Form 8801; or
- an unallowed qualified electric vehicle credit (see the instructions for line 20).
File Form 8801 only if line 21 is more than zero. If line 21 is zero or less, you do not have a minimum tax credit or a credit carryforward; the instructions say not to complete the rest of the form and not to file it.
Estates and trusts follow special line 1 instructions: they skip lines 1 through 3 and figure the line 4 amount by completing Parts I and II of another 2024 Schedule I (Form 1041) as a worksheet. Form 1040-NR filers who had a net gain on the disposition of U.S. real property interests in 2024 have a limit on line 10. Filers who claimed the foreign earned income exclusion, housing exclusion, or housing deduction on Form 2555 for 2024 use the Foreign Earned Income Tax Worksheet for line 11.
When to file Form 8801
Form 8801 is filed with your 2025 income tax return, because it is an attachment to Form 1040, 1040-SR, 1040-NR, or 1041. It has no separate due date printed on it, so it follows the due date of the return it accompanies.
The triggering test is line 21 (the total of your 2024 credit and carryforward items). If line 21 is more than zero, complete and file the form. If it is zero or less, you have no minimum tax credit or credit carryforward, and the instructions say not to file it.
The form is a yearly calculation: line 19 takes the carryforward from your 2024 Form 8801, line 26, and line 26 of the 2025 form gives the amount you may use in future years, so keep a record of it.
Documents you need
- The income tax return the form is attached to: Form 1040, 1040-SR, 1040-NR, or 1041 for 2025. Carry the line 25 credit to Schedule 3 (Form 1040), line 6b, or Form 1041, Schedule G, line 2c.
- Your 2024 Form 6251 (or 2024 Schedule I (Form 1041)): lines 1 and 14 of Form 8801 and lines 16 and 23 draw their amounts from it. Keep it at hand; the instructions do not ask you to attach it.
- Your 2024 Form 8801, line 26: the credit carryforward entered on line 19 of the 2025 form. Needed only if you had a 2024 carryforward.
- Forms 1116 marked "MTFTCE": needed only if you must figure the minimum tax foreign tax credit on exclusion items for line 12. Keep them; do not attach them to the return.
- Foreign Earned Income Tax Worksheet from the instructions: needed only if you filed Form 2555 for 2024. It is kept for your records.
How to fill out Form 8801
Enter your name and identifying number
At the top of page 1, enter the name(s) shown on your return and your identifying number. The form is attached to Form 1040, 1040-SR, 1040-NR, or 1041.
Combine 2024 Form 6251 amounts (lines 1 to 3)
Line 1: combine lines 1 and 2e of your 2024 Form 6251; estates and trusts skip lines 1 through 3 and see the instructions. Line 2: enter adjustments and preferences treated as exclusion items. Line 3: enter the minimum tax credit net operating loss deduction, in parentheses.
Figure the Part I base on lines 4 to 10
Line 4: combine lines 1, 2, and 3; if zero or less, enter -0- on lines 4 and 15 and go to Part II. Enter the filing-status amounts on lines 5 and 6, then complete lines 7 to 10 as printed.
Compute tentative minimum tax (lines 11 to 13)
Line 11: use the rate calculation printed on the form, or enter the line 55 amount if Part III applies; Form 2555 filers use the Foreign Earned Income Tax Worksheet. Line 12: enter the minimum tax foreign tax credit on exclusion items. Line 13: subtract line 12 from line 11.
Find the net minimum tax on lines 14 and 15
Line 14: enter the amount from your 2024 Form 6251, line 10, or 2024 Schedule I (Form 1041), line 53. Line 15: subtract line 14 from line 13; if zero or less, enter -0-.
Start Part II with lines 16 to 21
Line 16: 2024 Form 6251, line 11, or Schedule I (Form 1041), line 54. Line 17: the line 15 amount. Line 18: line 16 minus line 17 (negative if less than zero). Line 19: your 2024 Form 8801, line 26. Line 20: any unallowed qualified electric vehicle credit. Line 21: combine lines 18 through 20; if zero or less, stop and see the instructions.
Enter regular tax liability (lines 22 to 24)
Line 22: your 2025 regular income tax liability minus allowable credits, figured from the return as the instructions direct. Line 23: 2025 Form 6251, line 9, or 2025 Schedule I (Form 1041), line 52. Line 24: subtract line 23 from line 22; if zero or less, enter -0-.
Figure the credit and carryforward (lines 25, 26)
Line 25: enter the smaller of line 21 or line 24, and also enter it on Schedule 3 (Form 1040), line 6b, or Form 1041, Schedule G, line 2c. Line 26: subtract line 25 from line 21, and keep a record of it.
Complete Part III only when required
Fill in lines 27 to 55 only if line 11 or the Foreign Earned Income Tax Worksheet requires it. Enter the 2024 worksheet amounts on lines 28, 29, 30, 35, and 42 as directed, and carry the line 55 result to line 11 (or to the worksheet if you filed Form 2555).
Review and download the completed PDF
Check that the lines you completed follow the printed instructions and that line 21 is more than zero. Download or print the completed PDF from FillingPDF and attach it to your income tax return.
How to submit Form 8801
Form 8801 is not filed on its own: it is attached to your income tax return (Form 1040, 1040-SR, 1040-NR, or 1041) and goes to the IRS with that return, by whichever method you use to file it. The form and its instructions print no separate mailing address, portal, or appointment rule.
- With the return: attach the completed Form 8801 to the return, and carry the line 25 credit to Schedule 3 (Form 1040), line 6b, or to Form 1041, Schedule G, line 2c.
- Records you keep: do not attach the Forms 1116 used to figure the minimum tax foreign tax credit on exclusion items (line 12); keep them for your records. Estates and trusts that use a 2024 Schedule I (Form 1041) as a worksheet for line 4 also keep it and do not attach it.
Find the latest information and instructions at www.irs.gov/Form8801. FillingPDF lets you fill out and download the PDF; submission follows the IRS channels used for your tax return.
Common mistakes to avoid
- Filing Form 8801 when line 21 is zero or less; the instructions say that means no credit or carryforward, so the rest of the form should not be completed or filed.
- Including deferral items (such as depreciation) on line 2; line 2 is limited to exclusion items like certain itemized deductions, tax-exempt interest, depletion, the section 1202 exclusion, and the standard deduction.
- Including any amount from line 2j of the 2024 Form 6251 on line 2 instead of the exclusion item amount from Schedule(s) K-1 (Form 1041), box 12, code J.
- Entering the line 11 amount without using the Foreign Earned Income Tax Worksheet when you claimed the foreign earned income exclusion, housing exclusion, or housing deduction on Form 2555 for 2024.
- Skipping the extra amount on line 4 when you were married filing separately for 2024 and line 4 exceeds the threshold printed on the form.
- Leaving out Part III when line 11 requires it because of 2024 capital gain distributions, qualified dividends, or a gain on both lines 15 and 16 of Schedule D.
- Counting the credit for prior year minimum tax on line 6b or a Form 8912 credit when figuring line 22; the instructions exclude them.
- Attaching the Forms 1116 used for the MTFTCE, or the 2024 Schedule I worksheet, to the return instead of keeping them for your records.
- Failing to keep a record of the line 26 carryforward to 2026, which you may use in future years.
Frequently asked questions
What is Form 8801 used for?
Form 8801 is the IRS form for figuring the minimum tax credit, if any, for alternative minimum tax you incurred in prior tax years, and any credit carryforward to 2026. Individuals, estates, and trusts use it, attached to their income tax return.
Who has to file Form 8801?
Individuals, estates, and trusts that for 2024 had an AMT liability with adjustments or preferences other than exclusion items, a credit carryforward to 2025 on 2024 Form 8801, line 26, or an unallowed qualified electric vehicle credit. File only if line 21 is more than zero.
What if line 21 on Form 8801 is zero or less?
Stop. The IRS instructions say that if line 21 is zero or less you have no minimum tax credit or credit carryforward, so you should not complete the rest of the form and should not file it.
Where do I send Form 8801?
You do not send it separately. Attach it to Form 1040, 1040-SR, 1040-NR, or 1041 and submit it with that return. The form prints no separate address. Carry the line 25 credit to Schedule 3 (Form 1040), line 6b, or Form 1041, Schedule G, line 2c.
Can I fill out Form 8801 online?
Yes. You can fill out the fillable PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the form with the IRS; you submit it with your tax return through the IRS channels.
What is the difference between deferral items and exclusion items on Form 8801?
Deferral items, such as depreciation, generally do not cause a permanent difference in taxable income, while exclusion items, such as the standard deduction, do. The minimum tax credit is allowed only for AMT caused by deferral items, which is why Part I removes exclusion items.
When do I have to complete Part III of Form 8801?
Only if line 11 or the Foreign Earned Income Tax Worksheet requires it. Line 11 points to Part III if for 2024 you reported capital gain distributions directly on your return, reported qualified dividends, or had a gain on both lines 15 and 16 of Schedule D (Form 1040).
What do I do with the credit carryforward on line 26?
Keep a record of it. Line 26 is the credit carryforward to 2026, figured as line 21 minus line 25, and the instructions say you may use it in future years. Next year it is entered on line 19 of that year's Form 8801.
Do I attach the Forms 1116 I used for line 12?
No. If you figure the minimum tax foreign tax credit on exclusion items with Forms 1116, marked "MTFTCE" with the category of income, the instructions say to keep them but not attach them to your tax return.
Ready to fill out Form 8801?
Fill out Form 8801 now