
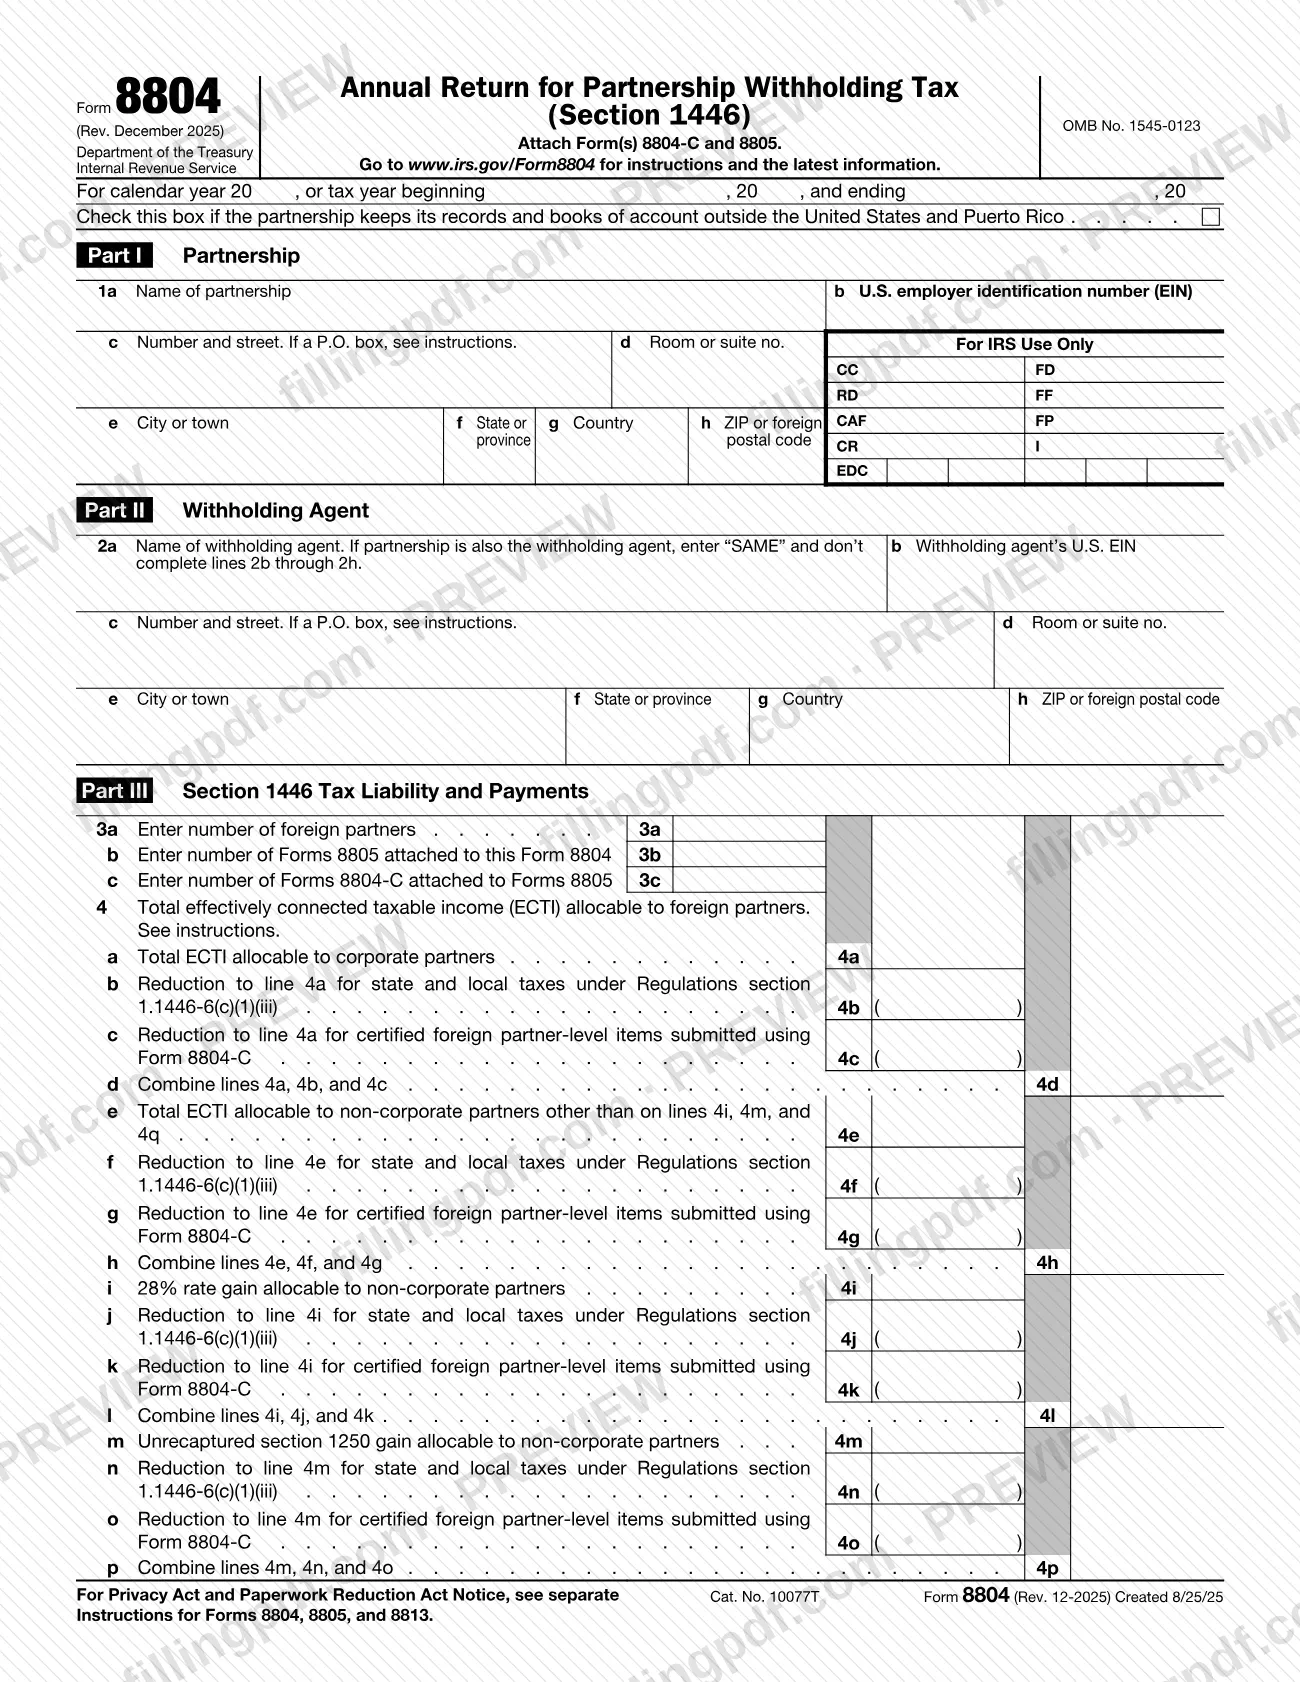
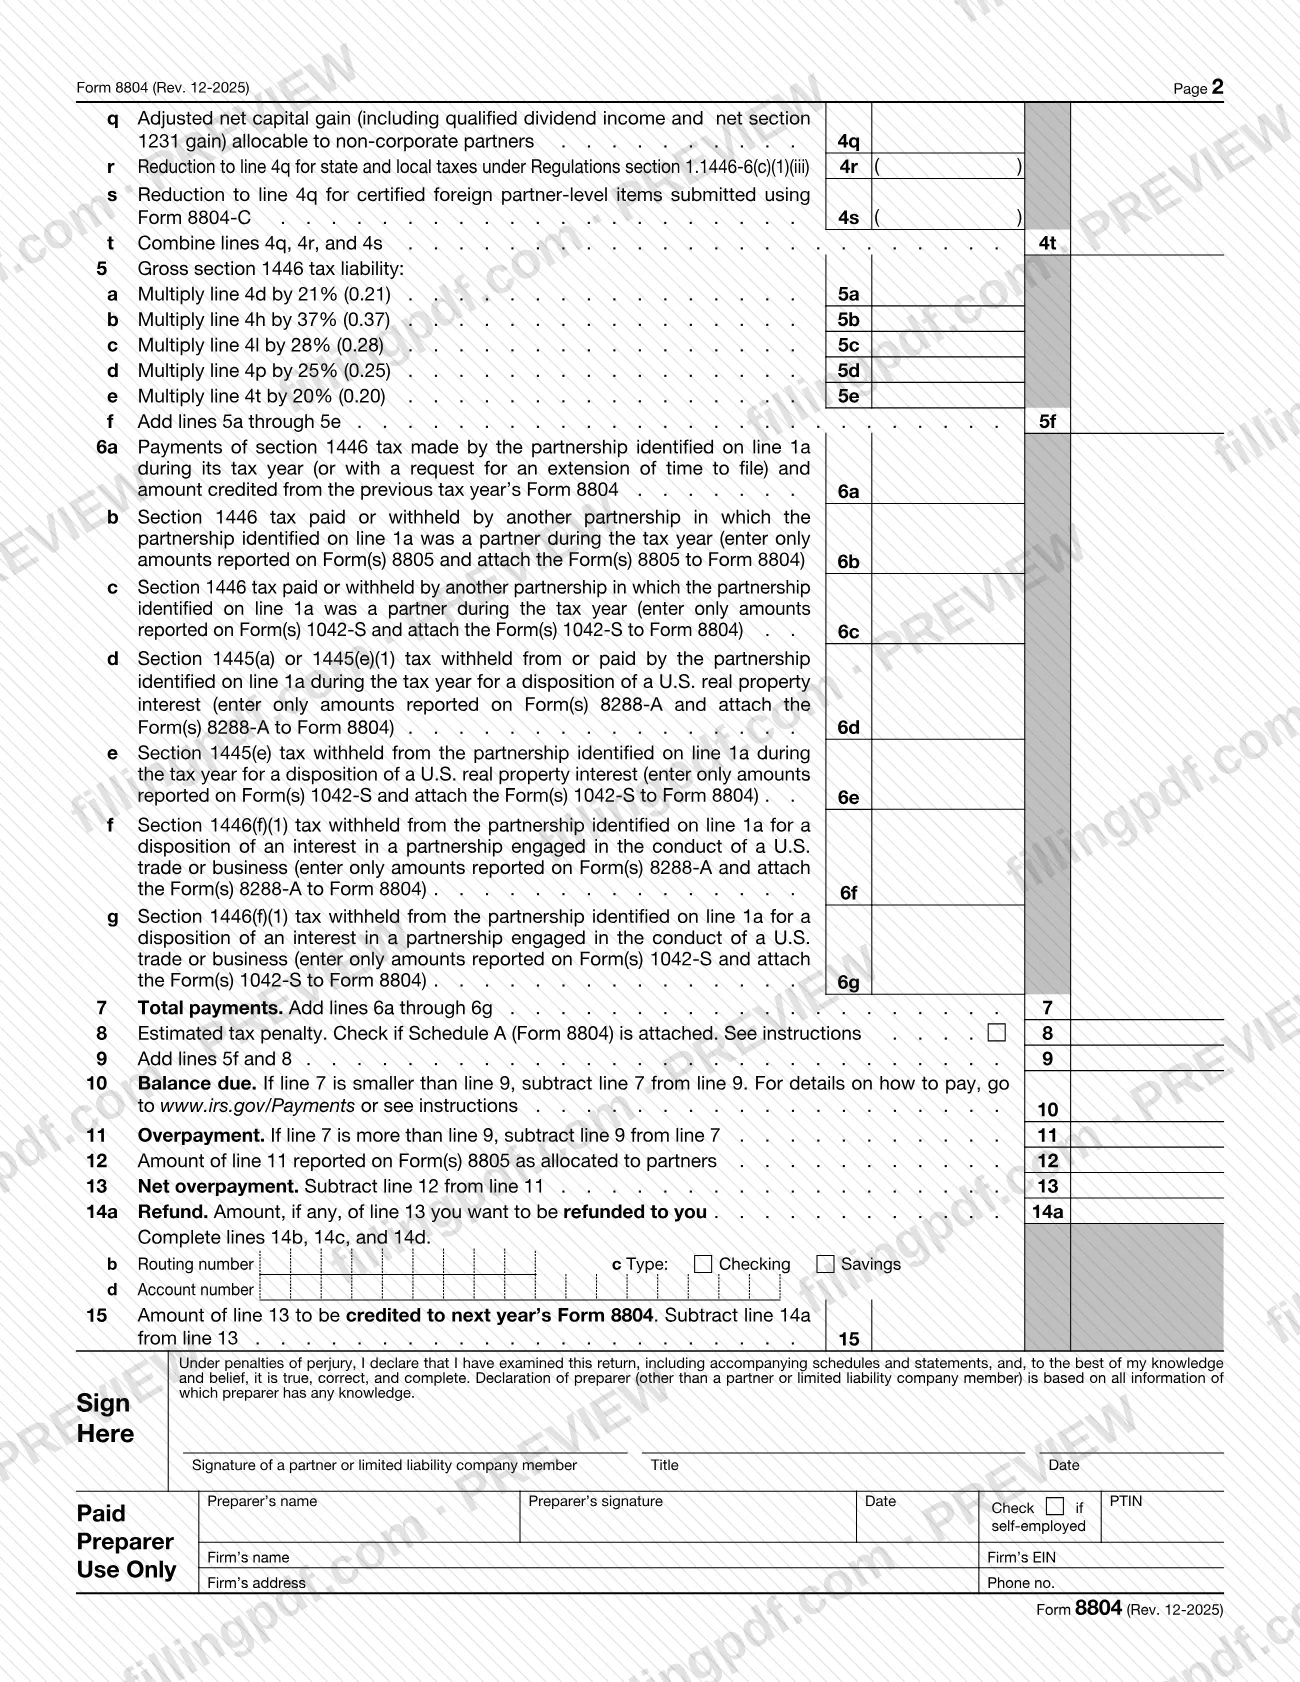
Form 8804 is the Internal Revenue Service (IRS) annual return on which a partnership reports its total tax liability under section 1446 for its tax year. It also serves as the transmittal form for Form(s) 8805, so the two travel together. Partnerships and their withholding agents use it to show effectively connected taxable income (ECTI) allocable to foreign partners, the payments already made and the balance due or overpayment. On this page you can fill out Form 8804 online on FillingPDF and download or print the completed PDF; the form and its instructions are published by the IRS at www.irs.gov/Form8804.
Last updated
What is 8804?
Form 8804, Annual Return for Partnership Withholding Tax (Section 1446), is the IRS form a partnership uses to report its total liability under section 1446 for the tax year, to list the payments credited against that liability, and to transmit Form(s) 8805.
The Department of the Treasury's Internal Revenue Service (IRS) issues the form under OMB No. 1545-0123. The printed revision is Rev. December 2025, and the form says to attach Form(s) 8804-C and 8805.
The return has three parts. Part I identifies the partnership. Part II identifies the withholding agent; if the partnership is also the withholding agent, you enter "SAME". Part III covers the section 1446 tax liability and payments: the number of foreign partners and attached forms (line 3), the ECTI allocable to foreign partners by category (line 4), the gross section 1446 tax liability (line 5), the payments and credits (lines 6a through 7), and the balance due, overpayment, refund or credit to next year's Form 8804 (lines 9 through 15).
Schedule A (Form 8804), published by the IRS as a separate schedule with its own instructions, is used by partnerships with ECTI allocable to foreign partners to determine whether the penalty for underpayment of estimated tax applies and, if so, its amount. The result is carried to line 8 of Form 8804.
Who needs to file 8804?
Partnerships that have to report a tax liability under section 1446 for their tax year use Form 8804, according to the IRS page for the form. The return identifies the partnership (Part I) and a withholding agent (Part II), and counts the foreign partners (line 3a).
- The partnership. It enters its name, U.S. employer identification number (EIN) and address, and reports ECTI allocable to foreign partners.
- The withholding agent. If someone other than the partnership is the withholding agent, enter that person's name, U.S. EIN and address on lines 2a through 2h. If the partnership is its own agent, enter "SAME" on line 2a and skip lines 2b through 2h.
- Partnerships whose records are kept abroad. Check the box at the top of page 1 if the partnership keeps its books and records outside the United States and Puerto Rico.
- Signers. A partner or limited liability company member signs the return. A paid preparer who is not a partner or LLC member completes the preparer block.
Partnerships that need to compute the estimated tax penalty also complete Schedule A (Form 8804). The form itself does not describe which partnerships fall outside section 1446; check the instructions at www.irs.gov/Form8804 for eligibility questions.
When to file 8804
Form 8804 is an annual return: you complete it for the partnership's tax year, entered at the top as a calendar year or as a tax year with beginning and ending dates. No due date is printed on the form; the filing deadline is in Instructions for Forms 8804, 8805, and 8813, available at www.irs.gov/Form8804.
Timing also shows up in the payment lines. Line 6a counts section 1446 tax paid during the tax year or with a request for an extension of time to file, and any amount credited from the previous tax year's Form 8804. Line 15 lets you credit an overpayment to next year's Form 8804. Because the form transmits Form(s) 8805, the 8805 copies are prepared at the same time and attached to the return.
Documents you need
- Form(s) 8805: attach them to Form 8804, which acts as their transmittal; line 3b asks for the number attached.
- Form(s) 8804-C: the form says to attach them; line 3c asks for the number attached to Forms 8805, and lines 4c, 4g, 4k, 4o and 4s reduce ECTI for certified foreign partner-level items submitted with them.
- Form(s) 8805 from another partnership: attach them if you enter on line 6b section 1446 tax paid or withheld by another partnership in which you were a partner.
- Form(s) 1042-S: attach them for amounts entered on lines 6c, 6e or 6g, as each line states.
- Form(s) 8288-A: attach them for amounts entered on lines 6d or 6f.
- Schedule A (Form 8804): attach it if you check the box on line 8 for the estimated tax penalty.
How to fill out 8804
Enter the tax year
At the top of page 1, enter the calendar year, or the tax year beginning and ending dates. Check the box if the partnership keeps its records and books of account outside the United States and Puerto Rico.
Identify the partnership
In Part I, enter the partnership's name on line 1a, its U.S. EIN on line 1b, and its address on lines 1c through 1h. If you use a P.O. box on line 1c, see the instructions.
Identify the withholding agent
In Part II, enter the withholding agent's name on line 2a and U.S. EIN on line 2b, then the address on lines 2c through 2h. If the partnership is also the withholding agent, enter "SAME" on line 2a and skip lines 2b through 2h.
Count foreign partners and attachments
Enter the number of foreign partners on line 3a, the number of Forms 8805 attached on line 3b and the number of Forms 8804-C attached to Forms 8805 on line 3c.
Report ECTI of corporate partners
On line 4a enter total ECTI allocable to corporate partners. Enter the reductions on lines 4b and 4c in parentheses, then combine lines 4a, 4b and 4c on line 4d.
Report ECTI of non-corporate partners
On line 4e enter total ECTI allocable to non-corporate partners, other than amounts on lines 4i, 4m and 4q. Enter reductions on lines 4f and 4g, then combine them on line 4h.
Complete the gain categories
Repeat the same pattern for 28% rate gain (lines 4i through 4l), unrecaptured section 1250 gain (lines 4m through 4p) and adjusted net capital gain (lines 4q through 4t), entering each reduction in parentheses and combining on the last line of each group.
Figure the gross section 1446 tax
On lines 5a through 5e, multiply lines 4d, 4h, 4l, 4p and 4t by the rate printed on each line. Add lines 5a through 5e on line 5f.
Enter payments and credits
Report payments and credits on lines 6a through 6g, entering only the amounts reported on the form each line names, and attach those forms. Add lines 6a through 6g on line 7.
Add the estimated tax penalty
On line 8 enter the estimated tax penalty and check the box if Schedule A (Form 8804) is attached. Add lines 5f and 8 on line 9.
Complete balance due or overpayment
If line 7 is smaller than line 9, enter the difference on line 10 as the balance due. If line 7 is larger, enter the overpayment on line 11, then the amount on Forms 8805 on line 12 and the net overpayment on line 13.
Choose a refund or a credit
Enter the refund you want on line 14a and, for direct deposit, the routing number, account type and account number on lines 14b through 14d. Enter the remainder, line 13 minus line 14a, on line 15 as the credit to next year's Form 8804.
Sign and add preparer details
A partner or limited liability company member signs, enters a title and dates the return. A paid preparer who is not a partner or LLC member completes the preparer block, including the PTIN and the firm's EIN.
Review and download the completed PDF
Check every line, the attachments and the counts on lines 3a through 3c. Download or print the completed PDF from FillingPDF and submit it as described under How to submit.
How to submit 8804
The form prints no mailing address, portal or appointment rule of its own; it directs you to www.irs.gov/Form8804 for the instructions and the latest information, so check Instructions for Forms 8804, 8805, and 8813 for where to send the return.
- What goes with the return. Attach Form(s) 8804-C and 8805. Also attach Form(s) 8805, 1042-S or 8288-A for the payments you claim on lines 6b through 6g, as each line states, and Schedule A (Form 8804) if you check the box on line 8.
- Payment. If line 10 shows a balance due, the form points you to www.irs.gov/Payments or the instructions for how to pay. The IRS page for the form notes that partnerships may use EFTPS.
- Refund. To receive a refund on line 14a, complete the routing number, account type and account number on lines 14b through 14d.
- Signature. A partner or limited liability company member must sign and date the return.
FillingPDF lets you fill out and download the PDF; submission follows the IRS channels described in the instructions.
Common mistakes to avoid
- Completing lines 2b through 2h after entering "SAME" on line 2a; the form says not to when the partnership is also the withholding agent.
- Entering on lines 6b through 6g amounts that are not reported on the matching Form 8805, 1042-S or 8288-A; each line says to enter only reported amounts.
- Leaving out the Form 8805, 1042-S or 8288-A that a line 6 entry requires you to attach.
- Not attaching Form(s) 8804-C and 8805, which the heading of the form says to attach.
- Skipping the box at the top of page 1 when the partnership keeps its records and books of account outside the United States and Puerto Rico.
- Entering the reductions on lines 4b, 4c, 4f, 4g, 4j, 4k, 4n, 4o, 4r and 4s as positive amounts; they print in parentheses as reductions.
- Requesting a refund on line 14a without completing the routing number, account type and account number on lines 14b through 14d.
- Checking the line 8 box without attaching Schedule A (Form 8804).
- Leaving the return unsigned; a partner or limited liability company member must sign it.
Frequently asked questions
What is Form 8804 used for?
Form 8804 is the IRS annual return on which a partnership reports its total section 1446 liability for the tax year, lists the payments credited against it and shows the balance due or overpayment. It is also the transmittal form for Form(s) 8805.
What is the difference between Form 8804 and Form 8805?
Form 8804 is the partnership's return reporting the total section 1446 liability, while Form 8805 is attached to it and transmitted with it. The IRS page calls Form 8804 a transmittal form for Form(s) 8805, and line 3b asks how many are attached.
What do I enter on line 2a if the partnership is its own withholding agent?
Enter "SAME" on line 2a and do not complete lines 2b through 2h. If another person acts as withholding agent, enter that person's name on line 2a and complete the U.S. EIN and address lines.
Do I need to attach Schedule A to Form 8804?
Only if you check the box on line 8. Schedule A (Form 8804) determines whether the penalty for underpayment of estimated tax applies and its amount, and the IRS describes it for partnerships with ECTI allocable to foreign partners.
Where do I find the Form 8804 instructions and due date?
The form directs you to www.irs.gov/Form8804 for instructions and the latest information. The 8804 instructions are Instructions for Forms 8804, 8805, and 8813; the form itself prints no due date or mailing address.
How do I pay the balance due on Form 8804?
Line 10 points you to www.irs.gov/Payments or the instructions for how to pay. The IRS page for the form also notes that partnerships may use EFTPS. The amount owed is the line 9 total minus line 7.
Can I get a refund of an overpayment on Form 8804?
Yes, if line 7 exceeds line 9. After subtracting the amount shown on Forms 8805 (line 12), enter the refund you want on line 14a with your routing number, account type and account number, or credit the remainder to next year's Form 8804 on line 15.
Can I fill out Form 8804 online?
Yes. You can fill out the PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the return with the IRS; you submit it through the channels in the IRS instructions.
Ready to fill out 8804?
Fill out 8804 now