
Form 8805 is the Internal Revenue Service (IRS) statement that reports a foreign partner's share of a partnership's effectively connected taxable income (ECTI) and the section 1446 tax credit allowed to that partner. It is attached to Form 8804, and the partner uses its copy to claim the credit on a federal return such as Form 1040-NR or Form 1120-F. On this page you can fill out Form 8805 online on FillingPDF and download or print the completed PDF; the IRS publishes the form and its instructions at www.irs.gov/Form8805.
Last updated
What is 8805?
Form 8805, Foreign Partner's Information Statement of Section 1446 Withholding tax is the IRS form that shows the amount of effectively connected taxable income (ECTI) and the total tax credit allocable to a foreign partner for the partnership's tax year.
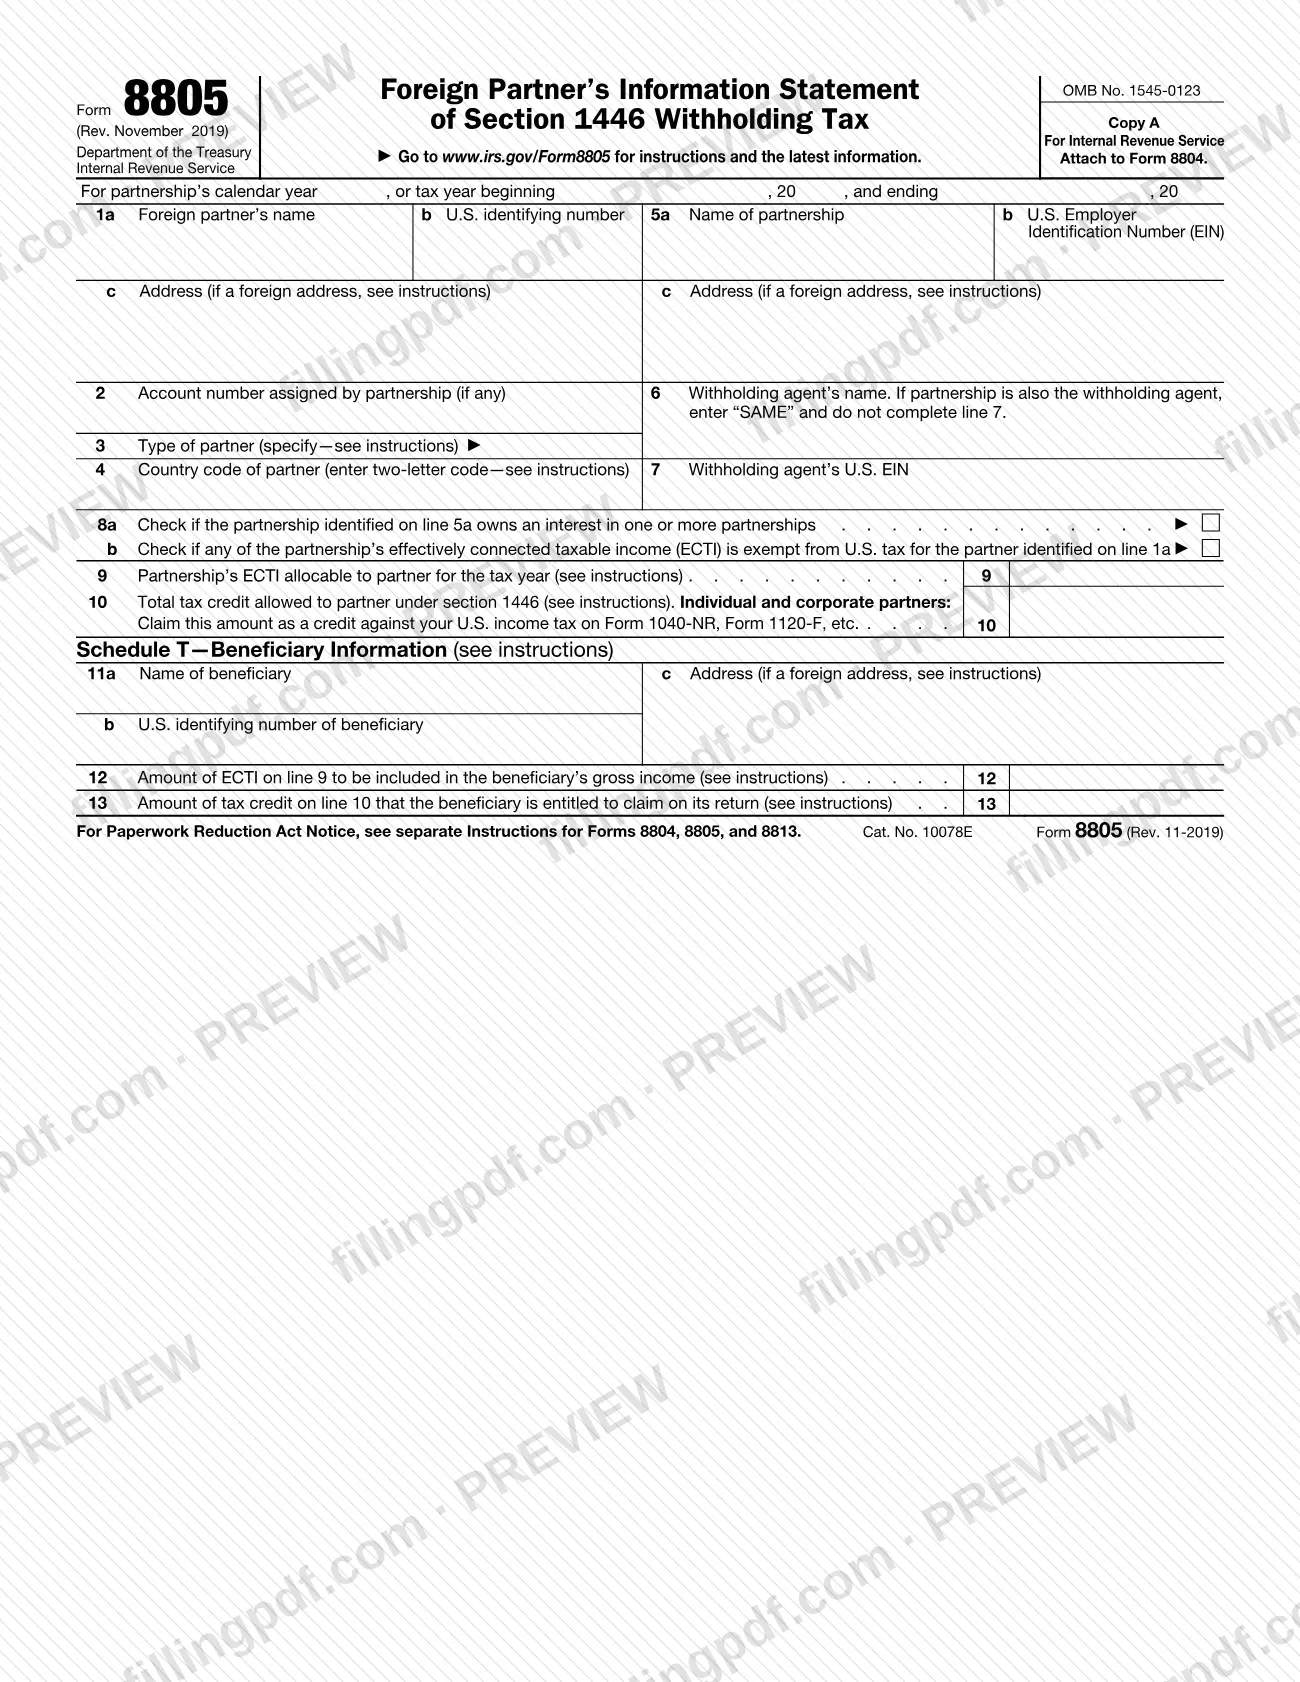
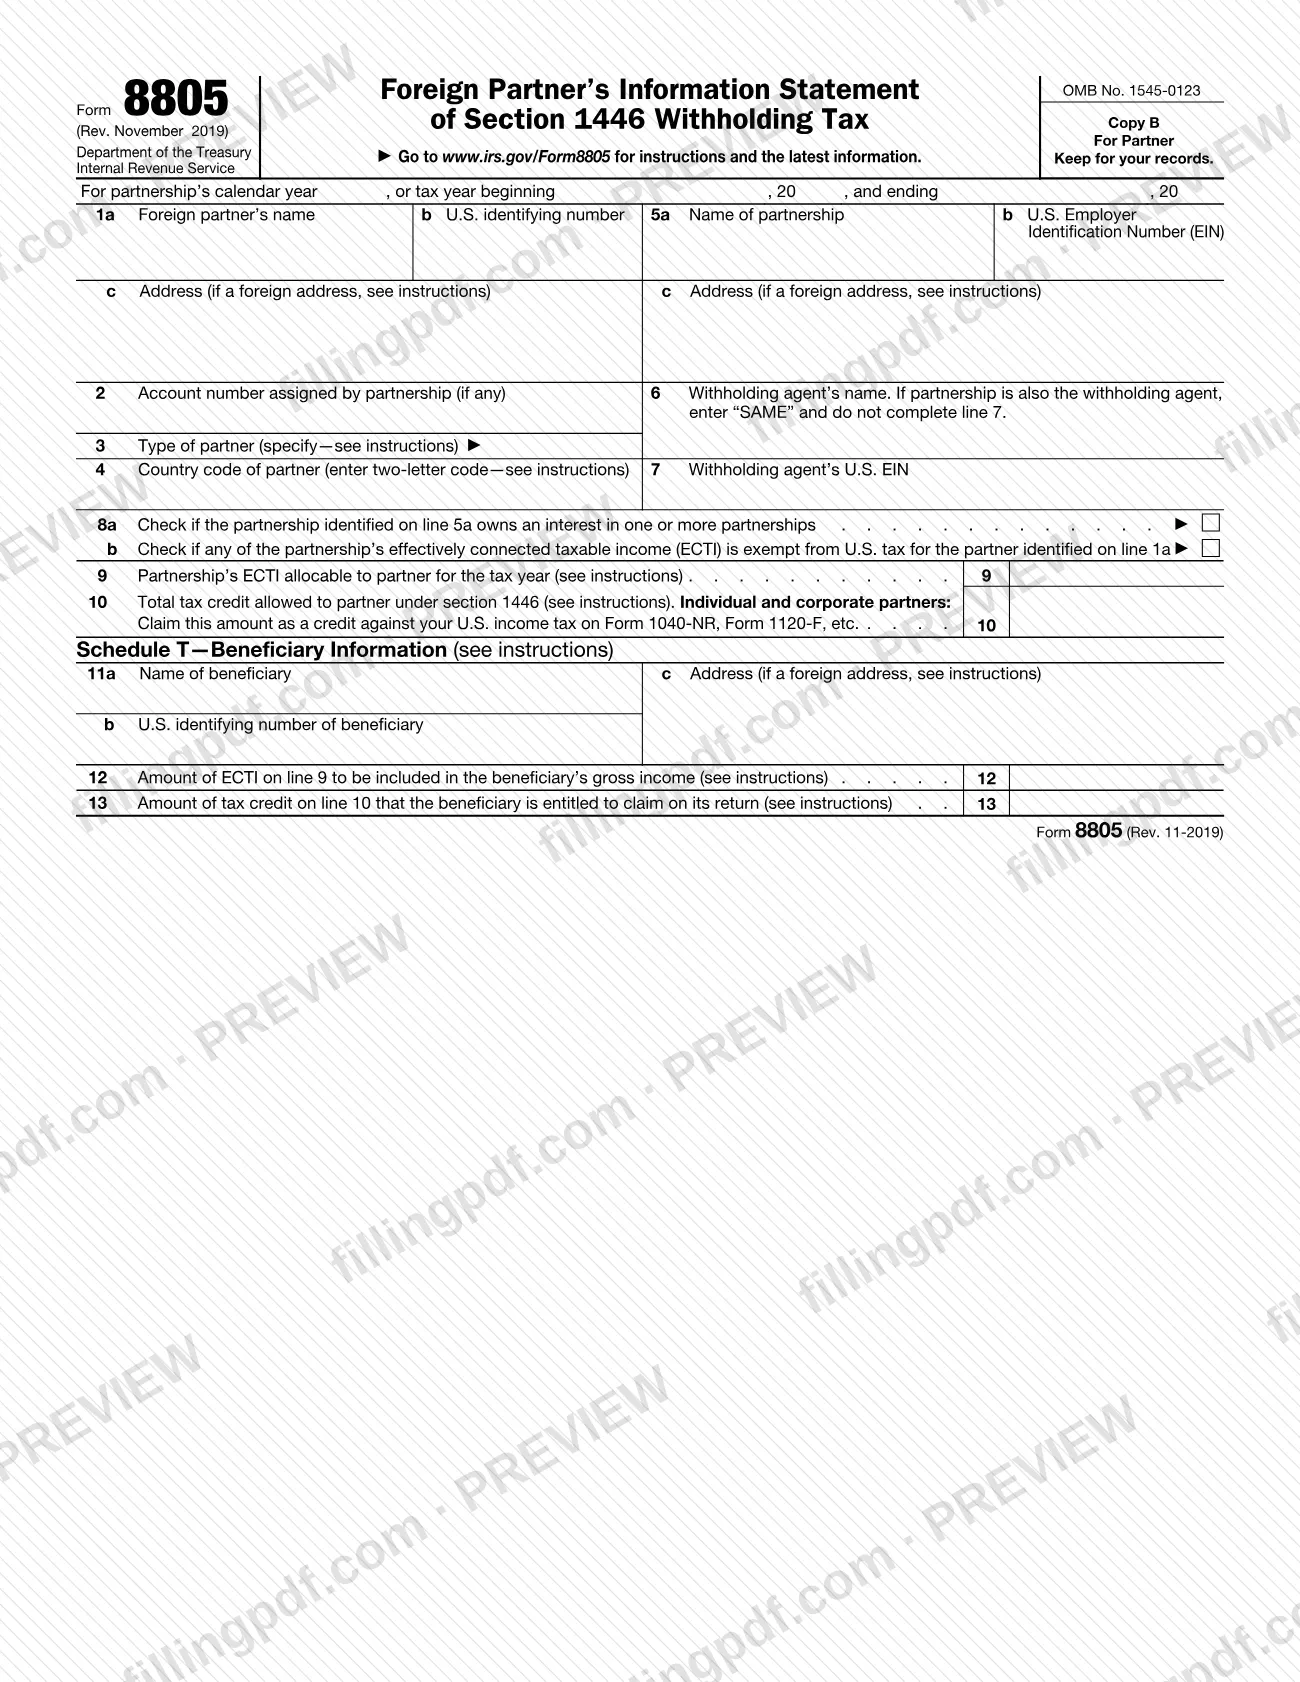
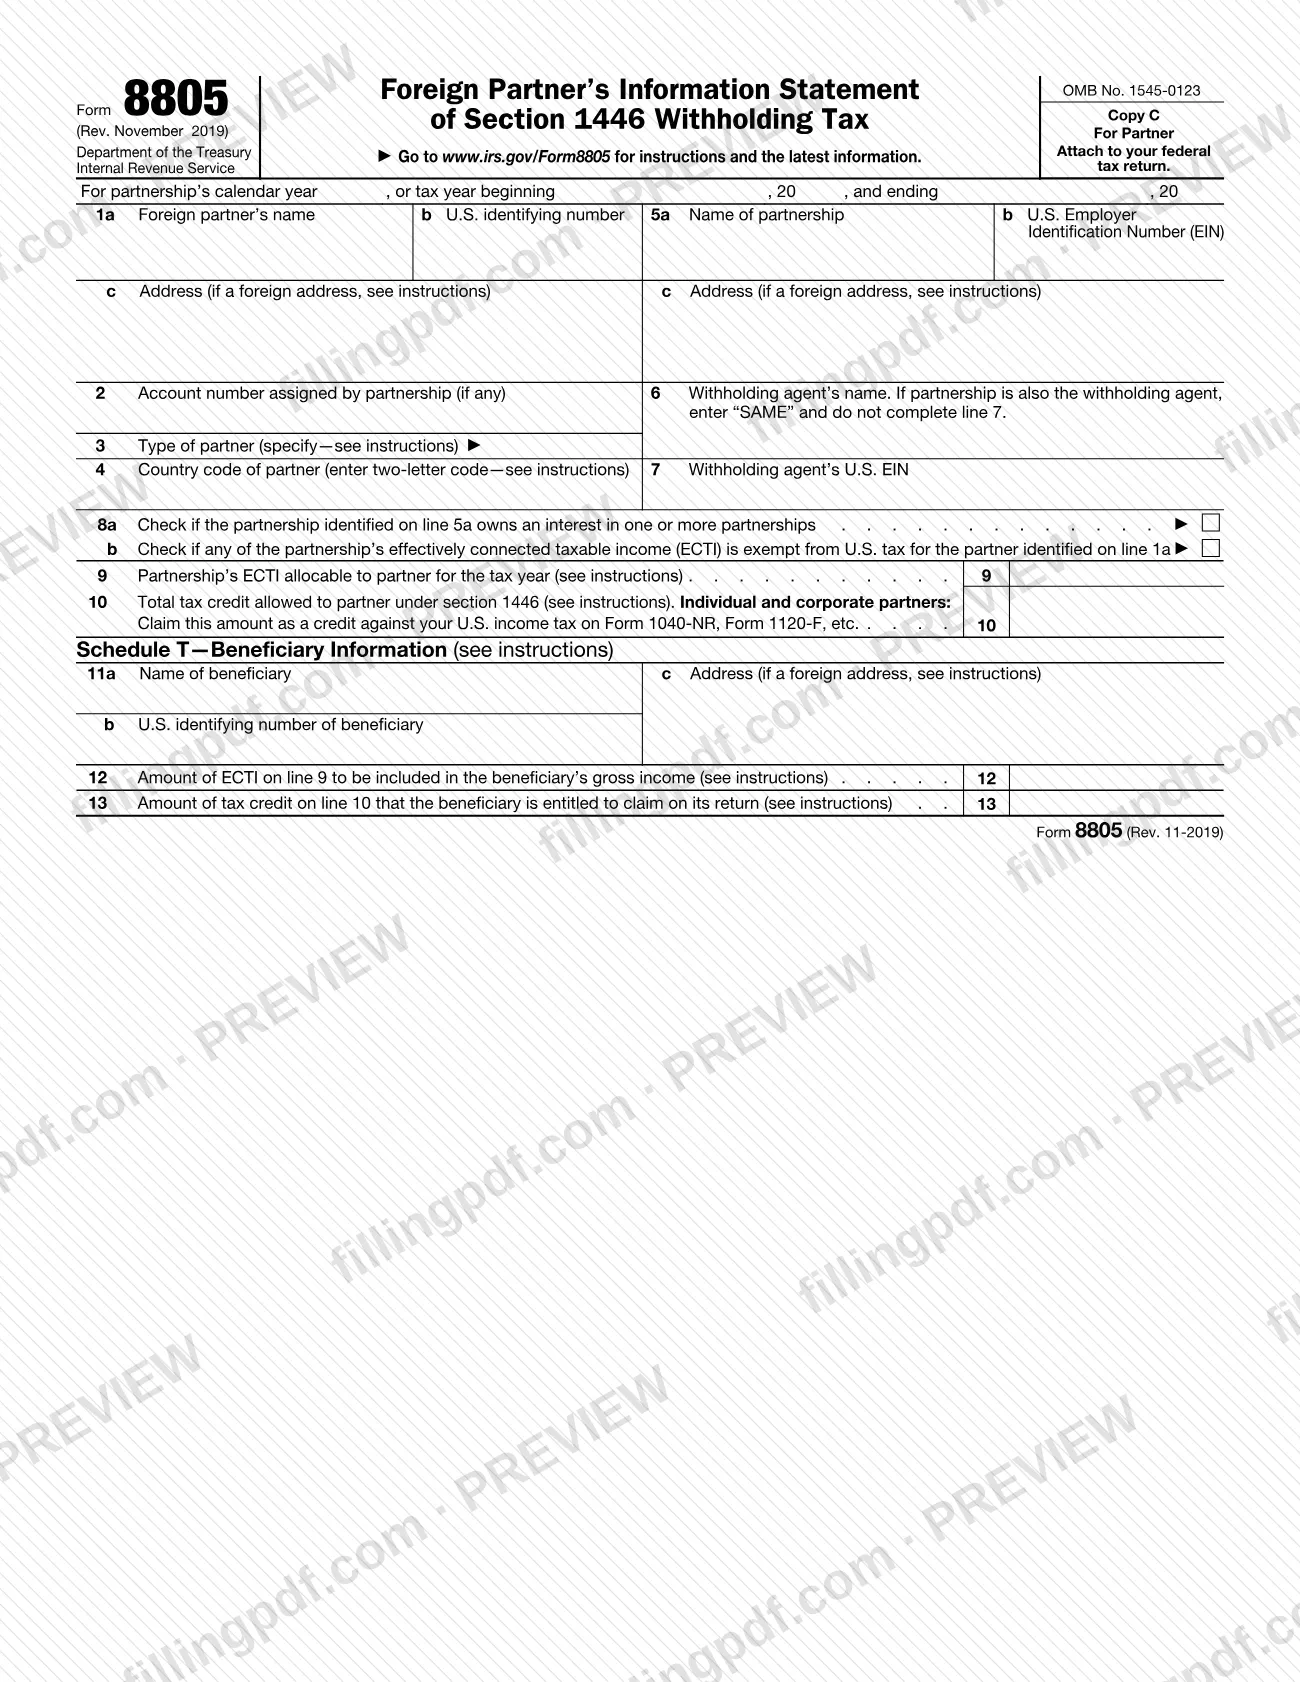
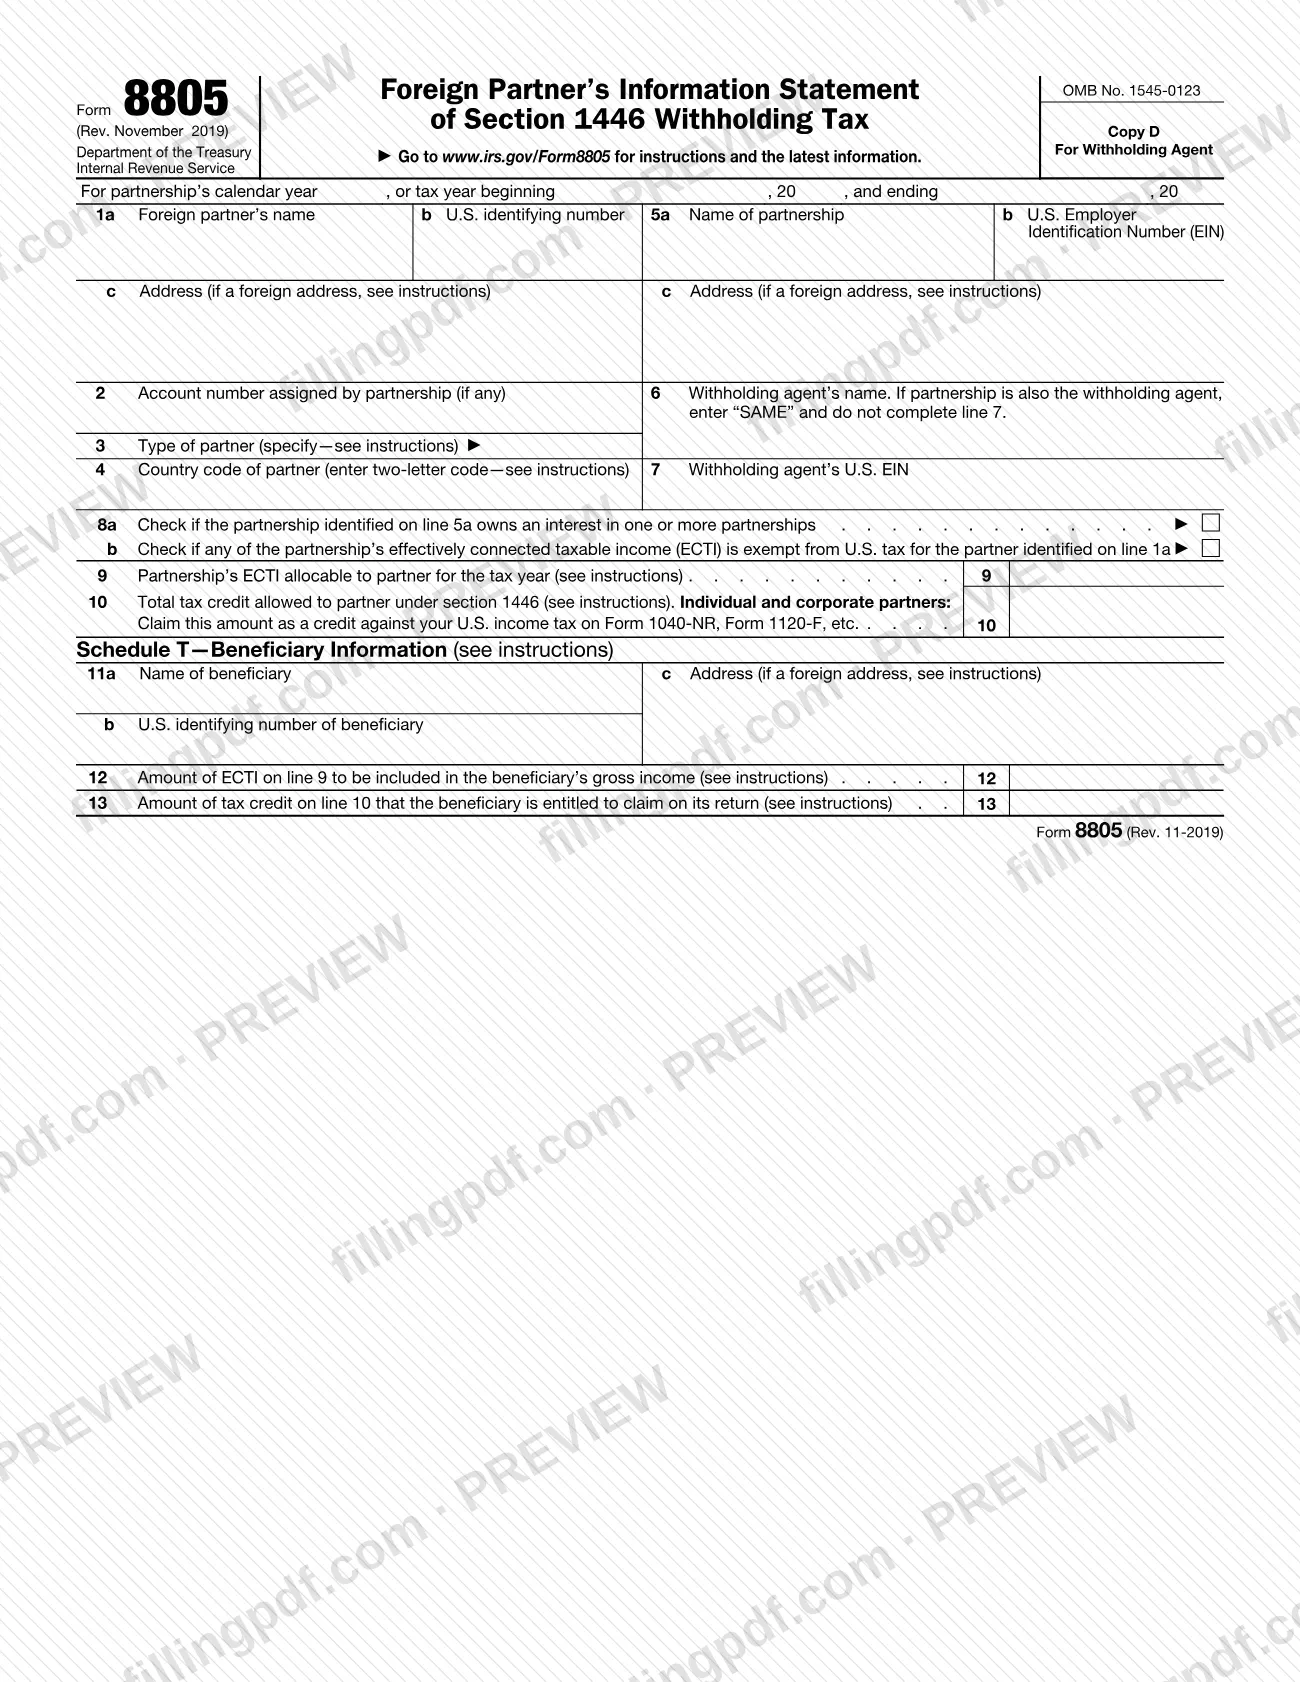
The PDF contains four copies of the same statement, each with its own destination printed at the top:
- Copy A, for the Internal Revenue Service, to be attached to Form 8804.
- Copy B, for the partner, to keep for its records.
- Copy C, for the partner, to attach to its federal tax return.
- Copy D, for the withholding agent.
Each copy identifies the foreign partner (line 1a to line 4), the partnership (line 5a to 5c) and the withholding agent (lines 6 and 7). Lines 8a and 8b are check boxes: one for a partnership that owns an interest in other partnerships, one for ECTI that is exempt from U.S. tax for the partner. Line 9 reports the partnership's ECTI allocable to the partner, and line 10 the total tax credit allowed to the partner under section 1446. Individual and corporate partners claim the line 10 amount as a credit against their U.S. income tax on Form 1040-NR, Form 1120-F, etc.
Schedule T—Beneficiary Information (lines 11a to 13) splits the ECTI and the credit when a beneficiary is entitled to part of them. The form is issued under OMB No. 1545-0123, and the IRS publishes the separate Instructions for Forms 8804, 8805, and 8813.
Who needs to file 8805?
Form 8805 is completed for a foreign partner of a partnership, using the partnership's calendar year or tax year printed at the top. The statement names the partnership on line 5a and, on line 6, the withholding agent; if the partnership is also the withholding agent, it enters "SAME" on line 6.
How each group uses it:
- The partnership or withholding agent prepares the statement for the foreign partner, attaches Copy A to Form 8804 and gives the partner its copies. Copy D is marked for the withholding agent.
- The foreign partner keeps Copy B for its records and attaches Copy C to its federal tax return. Individual and corporate partners claim the line 10 credit on Form 1040-NR, Form 1120-F, etc.
- A beneficiary of the partner appears on Schedule T (lines 11a to 13) when part of the ECTI and the credit is to be included on the beneficiary's return.
The form itself does not say who must sign, and it prints no exclusions; the IRS Instructions for Forms 8804, 8805, and 8813 and the page at www.irs.gov/Form8805 explain the rules for who is a foreign partner and when a statement is required.
When to file 8805
Form 8805 has no separate due date printed on it: Copy A says to attach it to Form 8804, so it goes to the IRS whenever that form is submitted. Copy C is attached to the partner's federal tax return, so the partner uses it with that return.
The statement covers the partnership's calendar year, or the tax year beginning and ending on the dates entered at the top of the form, so each partnership tax year needs its own statement for each foreign partner. For any filing deadline, extension or penalty rule, check the Instructions for Forms 8804, 8805, and 8813 and www.irs.gov/Form8805.
Documents you need
- Form 8804, to which Copy A of Form 8805 is attached; the form states "Attach to Form 8804."
- The partner's federal tax return, to which the partner attaches Copy C; Copy C states "Attach to your federal tax return."
- Section 1446 credit claim: individual and corporate partners claim the line 10 amount on Form 1040-NR, Form 1120-F, etc., as the form states.
How to fill out 8805
Enter the partnership's tax year
At the top, enter the partnership's calendar year, or the beginning and ending dates of its tax year (the form prints "20" for each year).
Identify the foreign partner
Line 1a: the foreign partner's name. Line 1b: its U.S. identifying number. Line 1c: its address; if the address is foreign, see the instructions.
Add the account number and partner type
Line 2: the account number the partnership assigned to the partner, if any. Line 3: specify the type of partner, following the instructions.
Enter the partner's country code
Line 4: the partner's country as a two-letter code, as the instructions explain.
Identify the partnership
Line 5a: the partnership's name. Line 5b: its U.S. employer identification number (EIN). Line 5c: its address, following the instructions for a foreign address.
Identify the withholding agent
Line 6: the withholding agent's name. If the partnership is also the withholding agent, enter "SAME" and do not complete line 7; otherwise enter the agent's U.S. EIN on line 7.
Check lines 8a and 8b if they apply
Line 8a: check if the partnership on line 5a owns an interest in one or more partnerships. Line 8b: check if any of the partnership's ECTI is exempt from U.S. tax for the partner on line 1a.
Enter the ECTI on line 9
Line 9: the partnership's ECTI allocable to the partner for the tax year, figured as the instructions direct.
Enter the tax credit on line 10
Line 10: the total tax credit allowed to the partner under section 1446, following the instructions.
Complete Schedule T for a beneficiary
If a beneficiary is entitled to part of the ECTI and credit, enter its name on line 11a, U.S. identifying number on 11b and address on 11c. Enter its ECTI share on line 12 and its credit on line 13.
Review and download the completed PDF
Check that every copy shows the same entries and that each line follows the IRS instructions. Download or print the completed PDF from FillingPDF, then distribute Copies A to D as described under How to submit.
How to submit 8805
Form 8805 is not mailed alone: its four copies go to four places.
- Copy A (for the IRS): attach it to Form 8804. The form prints no separate address for it.
- Copy B (for the partner): the partner keeps it for its records.
- Copy C (for the partner): the partner attaches it to its federal tax return.
- Copy D (for the withholding agent): the withholding agent keeps it.
Send Copy A the way you submit Form 8804, and check the Instructions for Forms 8804, 8805, and 8813 for the current address and filing method. The IRS page for the form lists a development dated 25-SEPT-2024 stating that partnerships may use EFTPS, the IRS electronic tax payment system. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Completing line 7 when the partnership is also the withholding agent; the form says to enter "SAME" on line 6 and not complete line 7.
- Not attaching Copy A to Form 8804; the form prints "Attach to Form 8804" on it.
- Keeping Copy C instead of attaching it to the partner's federal tax return, as Copy C directs.
- Writing the full country name on line 4 instead of the two-letter country code the line asks for.
- Entering a foreign address on line 1c or 5c without following the address rules in the instructions, as the form directs.
- Leaving out the check on line 8a or 8b when it applies: 8a for a partnership that owns an interest in other partnerships, 8b for ECTI exempt from U.S. tax for the partner.
- Entering ECTI on line 11a to 13 for a beneficiary without completing line 12 and line 13 as the instructions require; Schedule T is used only when there is a beneficiary.
- Treating line 10 as a payment: individual and corporate partners claim it as a credit against U.S. income tax on Form 1040-NR, Form 1120-F, etc.
Frequently asked questions
What is Form 8805?
Form 8805 is the IRS Foreign Partner's Information Statement of Section 1446 Withholding tax. It shows the effectively connected taxable income (ECTI) and the total tax credit allocable to a foreign partner for the partnership's tax year, and Copy A is attached to Form 8804.
What are Copies A, B, C and D of Form 8805 for?
Copy A is for the IRS and is attached to Form 8804. Copy B is for the partner's records. Copy C is for the partner to attach to its federal tax return. Copy D is for the withholding agent.
What do I enter on line 6 if the partnership is the withholding agent?
Enter "SAME" on line 6 and do not complete line 7. If someone else is the withholding agent, enter that agent's name on line 6 and its U.S. EIN on line 7.
How does a partner use the line 10 credit?
Line 10 is the total tax credit allowed to the partner under section 1446. Individual and corporate partners claim this amount as a credit against their U.S. income tax on Form 1040-NR, Form 1120-F, etc., attaching Copy C to the return.
Where do I find the 8805 instructions?
The form points to www.irs.gov/Form8805 for instructions and the latest information, and to the separate Instructions for Forms 8804, 8805, and 8813 for the Paperwork Reduction Act Notice. Those instructions explain lines such as the partner type and country code.
What is Schedule T on Form 8805?
Schedule T—Beneficiary Information (lines 11a to 13) names a beneficiary and splits the amounts: line 12 is the part of the line 9 ECTI to include in the beneficiary's gross income, and line 13 is the part of the line 10 credit the beneficiary may claim.
Can I fill out Form 8805 online?
Yes. You can fill out the PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the form with the IRS; Copy A goes to the IRS with Form 8804 through the IRS channels.
Ready to fill out 8805?
Fill out 8805 now