
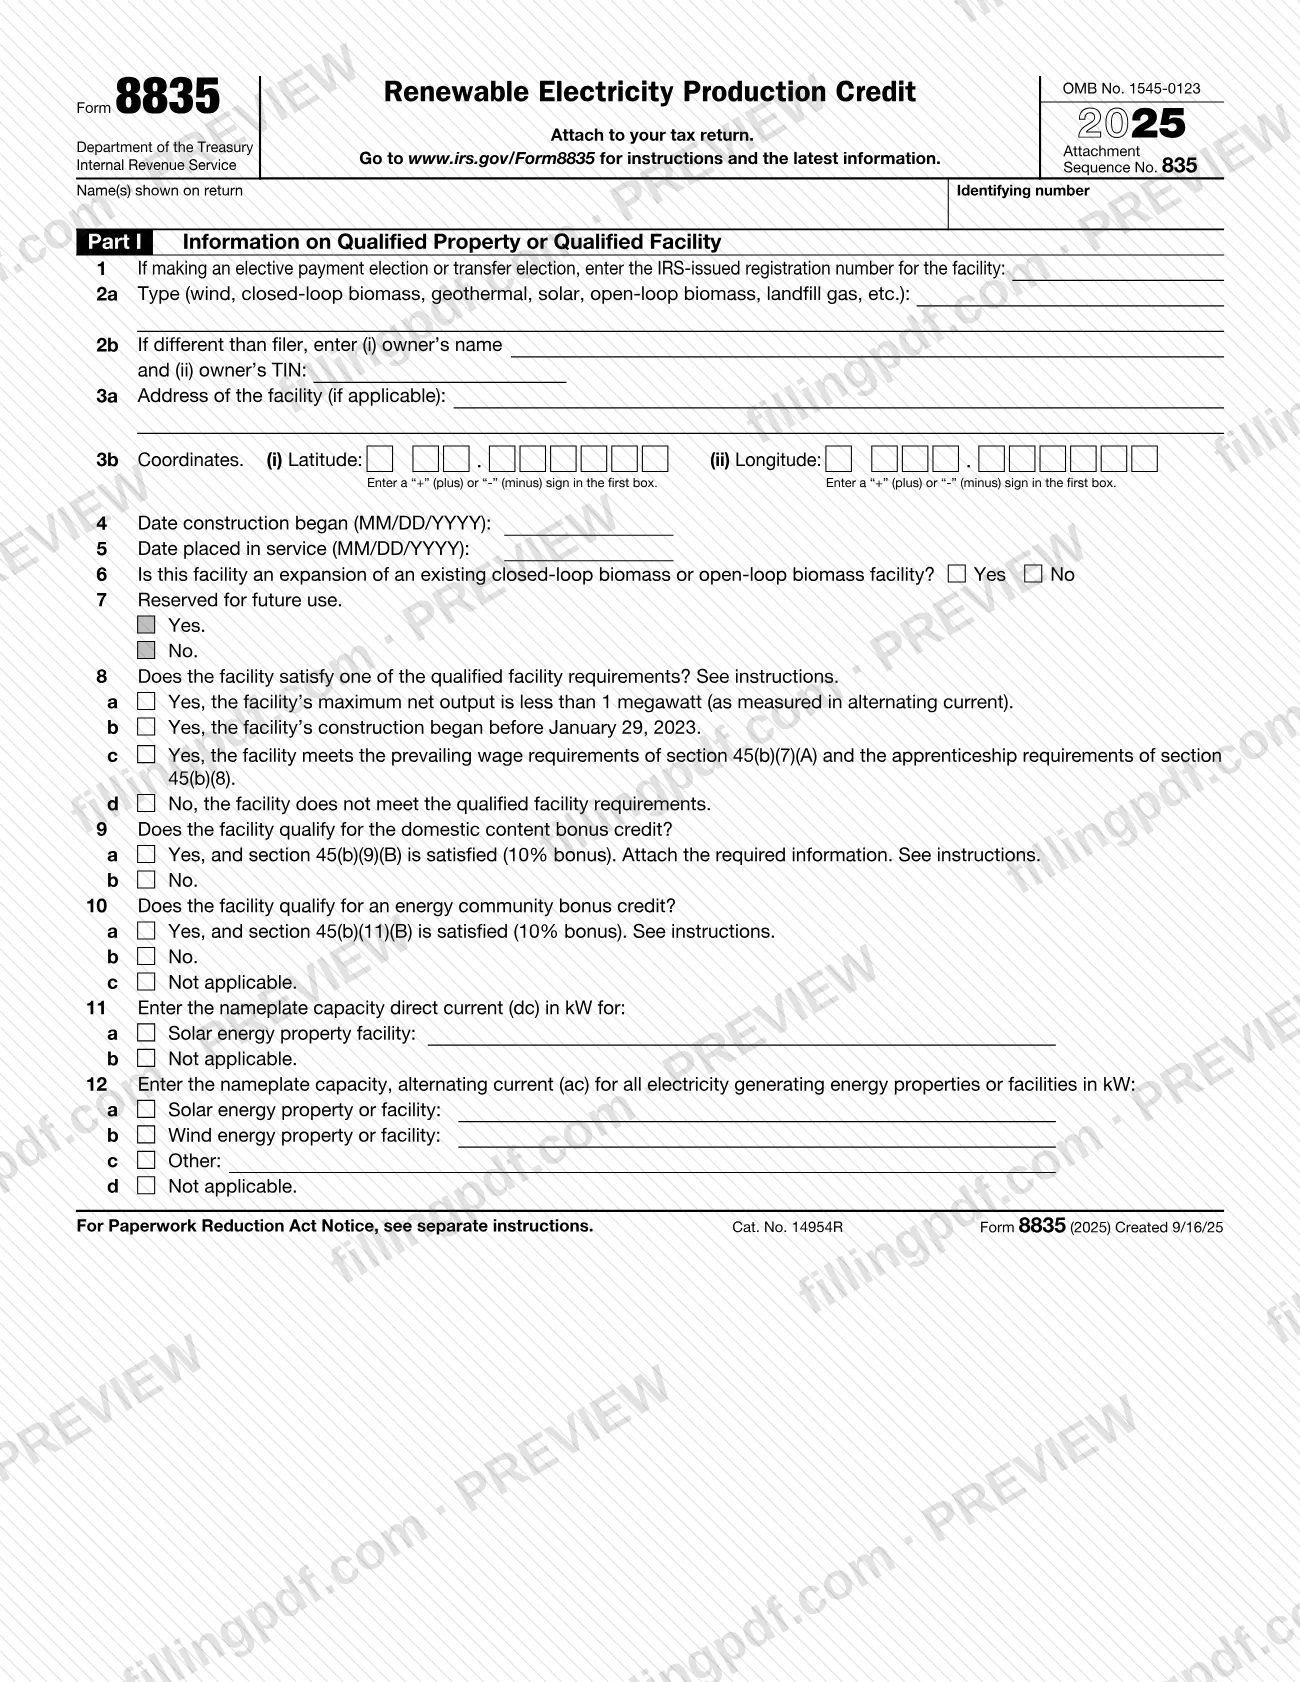
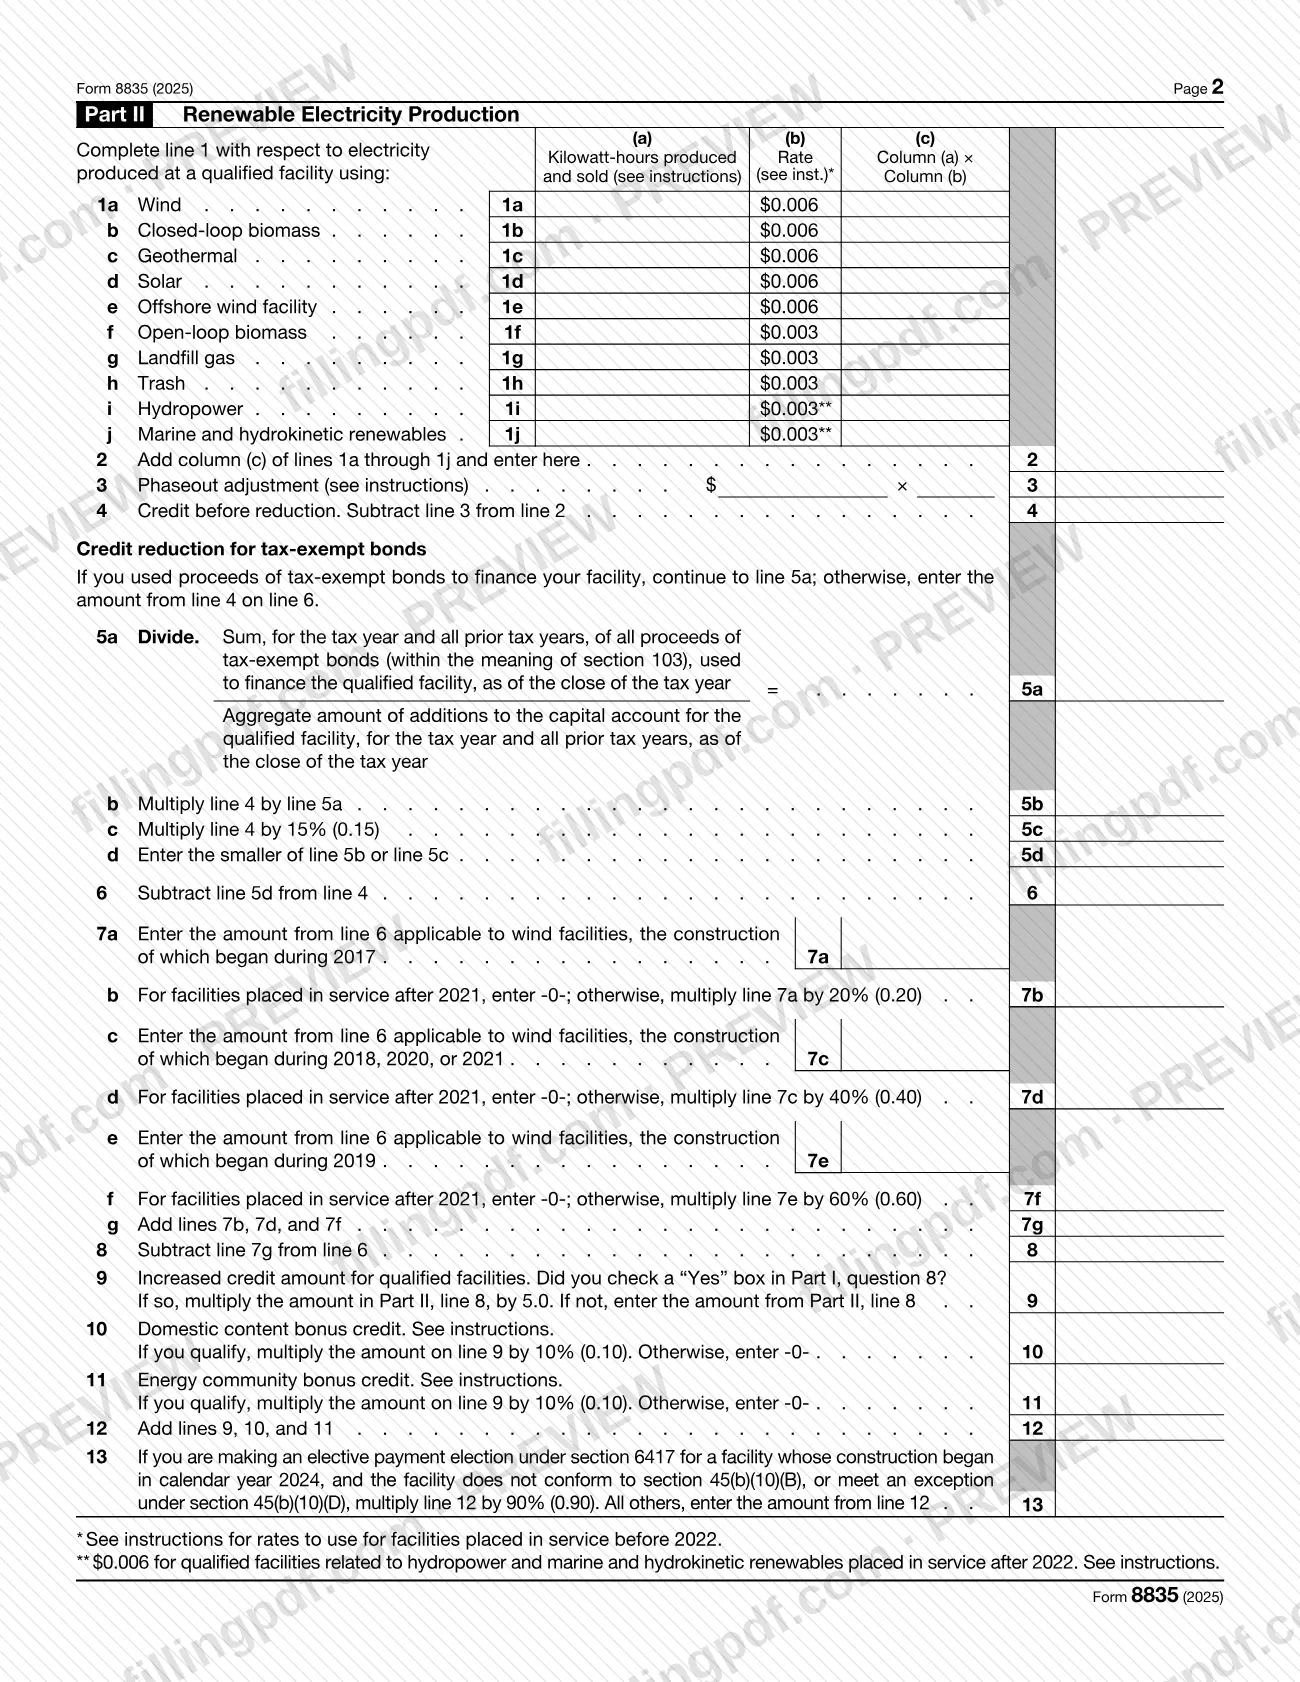
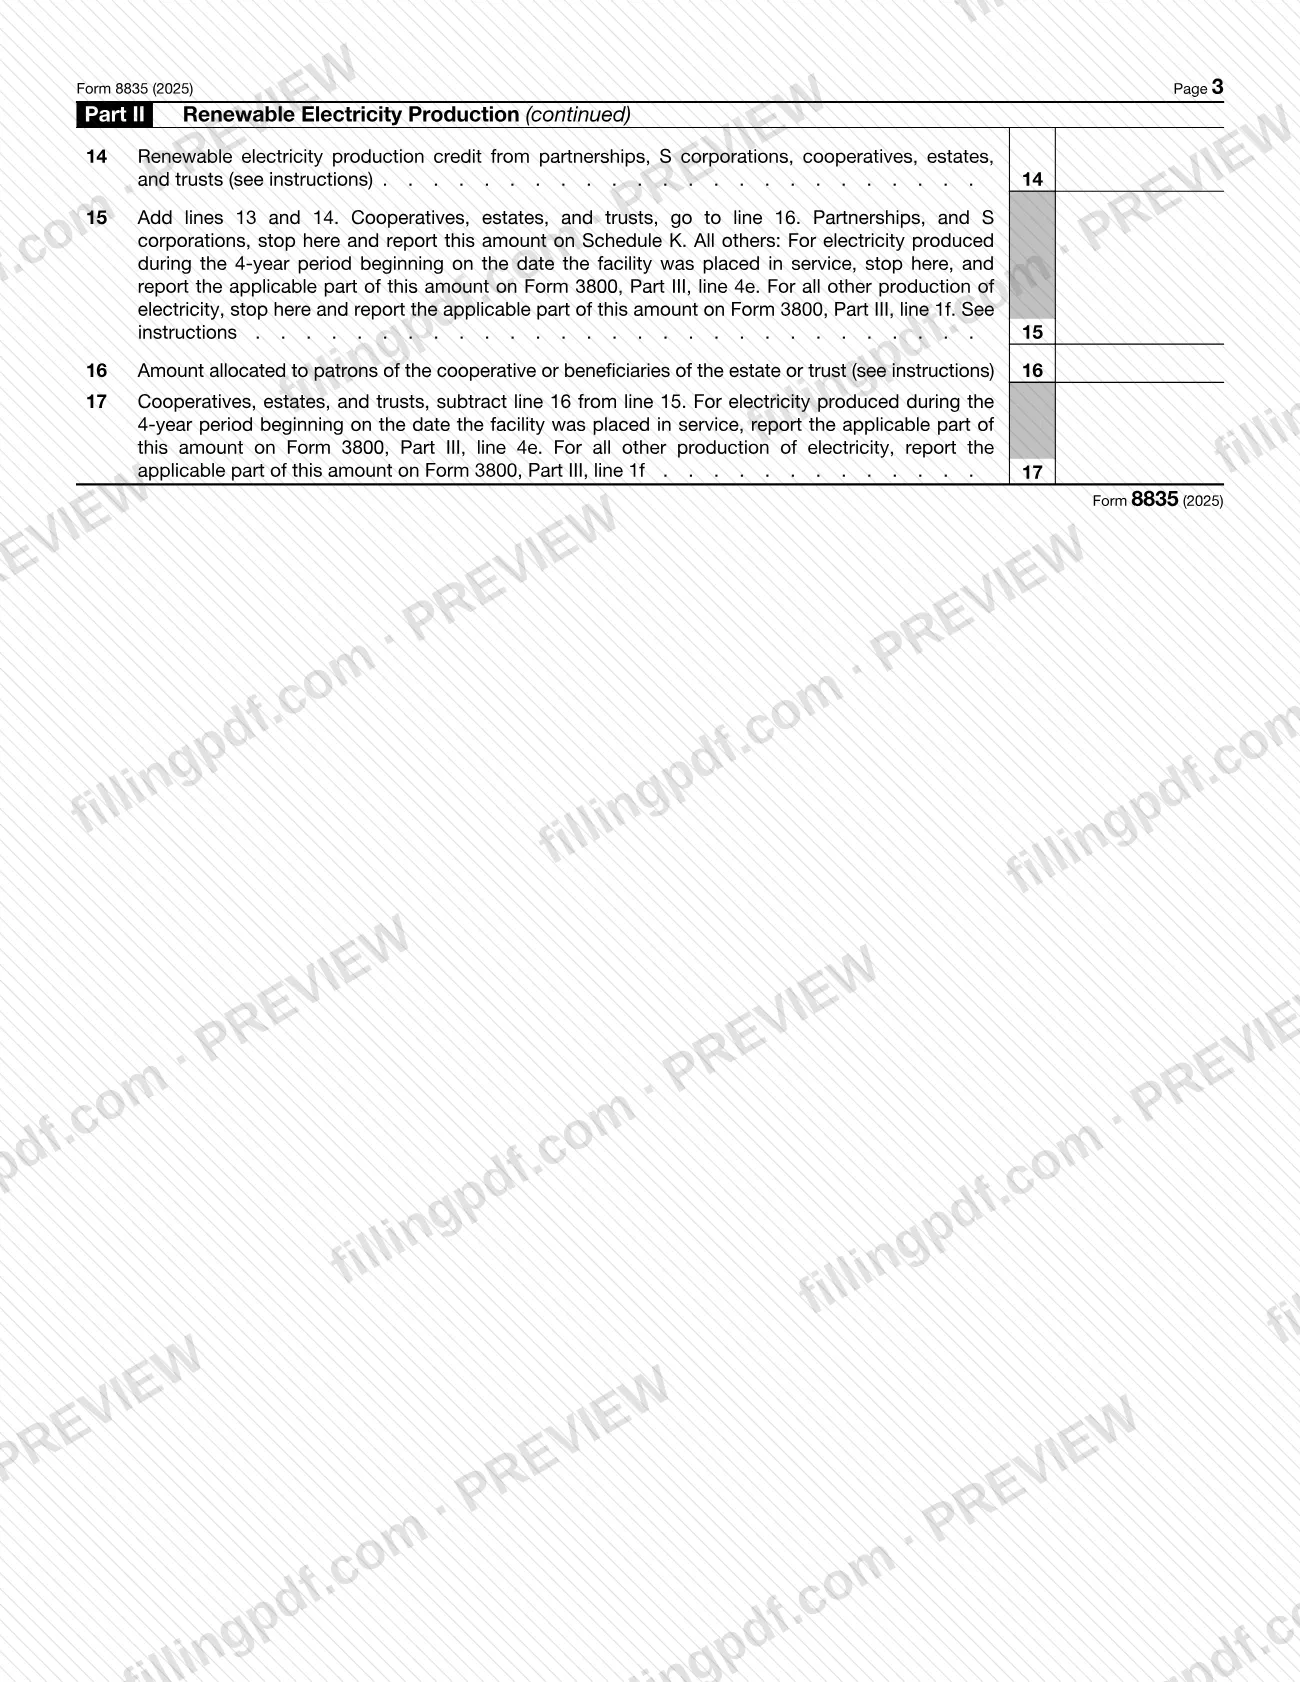
Form 8835, Renewable Electricity Production Credit, is the Internal Revenue Service (IRS) form used to claim the credit for electricity produced from qualified renewable resources at a qualified facility and sold to an unrelated person. You complete a separate form for each facility: Part I describes the property or facility, and Part II figures the credit. On this page you can fill out the form online on FillingPDF and download or print the completed PDF; the IRS publishes the form and its instructions at www.irs.gov/Form8835.
Last updated
What is 8835?
Form 8835, Renewable Electricity Production Credit, is the Internal Revenue Service (IRS) form for claiming the credit on electricity you produced from certain renewable resources at a qualified facility and sold to an unrelated person during the tax year. The credit is allowed only for the sale of electricity produced in the United States or U.S. territories.
The form has two parts:
- Part I, Information on Qualified Property or Qualified Facility, records the IRS-issued registration number (when you make an elective payment or transfer election), the facility type, owner, address and coordinates, the dates construction began and the facility was placed in service, and your answers on the qualified facility requirements, the domestic content bonus, the energy community bonus and nameplate capacity.
- Part II, Renewable Electricity Production, lists kilowatt-hours produced and sold by resource (wind, closed-loop biomass, geothermal, solar, offshore wind, open-loop biomass, landfill gas, trash, hydropower, marine and hydrokinetic renewables) and carries the amounts through the phaseout adjustment, the tax-exempt bond reduction, the increased credit amount and the bonus credits.
The form does not pay the credit by itself. Partnerships and S corporations report the result on Schedule K; other filers report the applicable part on Form 3800, General Business Credit, Part III, line 4e or line 1f. Companion forms named in the instructions include Form 7220, Prevailing Wage and Apprenticeship (PWA) Verification and Corrections, and Form 3468, Investment Credit, which is where an eligible facility reports if it elects to be treated as energy property under section 48(a)(5) instead of claiming this production credit.
Who needs to file 8835?
Taxpayers, applicable entities, partnerships and S corporations that claim the credit for electricity produced at a qualified facility used in their trade or business complete this form, one for each qualified facility. Generally the owner of the facility takes the credit. For closed-loop biomass facilities modified to co-fire with coal or other biomass, and for open-loop biomass facilities, the lessee or operator is eligible if the owner is not the producer of the electricity.
Others who only receive the credit from a partnership, S corporation, estate, trust or cooperative are generally not required to file this form. They can report their share directly on Form 3800, General Business Credit. Two exceptions apply:
- An estate or trust whose credit can be allocated to beneficiaries.
- A cooperative whose credit can or must be allocated to patrons.
Applicable entities that make an elective payment election under section 6417 file Form 8835 with the applicable attachments, Form 3800 and Form 990-T or another applicable income tax return.
The credit does not cover a landfill gas facility using municipal solid waste if its production is allowed a credit under section 45K, or a facility that produces electricity from gas from qualified biogas property if a section 48 credit is allowed for that property. A section 1603 grant for the same property also bars the section 45 credit.
When to file 8835
Form 8835 is attached to your tax return, so it is filed when the return that claims the credit is filed; the form prints no separate due date. The attachments for the increased credit amount must go with a timely filed return, including extensions.
Timing rules in the IRS instructions:
- If you intend to make an elective payment or transfer election on Form 3800, complete the pre-filing registration for each facility before you file your return.
- Generally the credit covers electricity produced and sold during the 10-year period beginning on the date the facility was originally placed in service.
- A cooperative's election to allocate credit to patrons is not effective unless made on a timely filed return, including extensions. If you filed on time without making it, you can still make it on an amended return within 6 months of the due date, excluding extensions, writing "Filed pursuant to section 301.9100-2" on it.
- A domestic content certification statement is attached for the year the project is placed in service, and a copy in each later tax year.
The IRS forms page also lists reporting relief for tax years 2023, 2024 and 2025, dated 20-MAR-2026.
Documents you need
- Separate statement for each qualified facility, attached to a timely filed return, when you check a Yes box in Part I, question 8a, 8b or 8c and enter an increased credit amount on Part II, line 9. It carries your name, TIN, facility description and a perjury declaration.
- Form 7220, Prevailing Wage and Apprenticeship (PWA) Verification and Corrections, one per facility, if you check box 8c. Not required if you checked the Yes box in question 8a or 8b.
- Domestic content certification statement for each Applicable Project, if you check box 9a, in the year placed in service, with a copy in each later tax year.
- Statement signed under penalties of perjury, if you claim an exception to the elective payment phaseout on line 13 for a facility whose construction began in 2024, as set out in the IRS instructions.
- Calculations for each calendar year, with "FY" written in the margin, if you are a fiscal year filer whose rate or phaseout adjustment differs between 2025 and 2026 sales.
- Pre-filing registration number issued by the IRS, entered on line 1, if you are making an elective payment or transfer election for the facility.
How to fill out 8835
Enter your name and identifying number
At the top of page 1, write the name(s) shown on your return and your identifying number. Use a separate Form 8835 for each qualified facility.
Enter registration number, type and owner
Line 1: the IRS-issued registration number, if you make an elective payment or transfer election. Line 2a: the facility type, such as wind, solar or geothermal. Line 2b: the owner's name and TIN if the owner differs from the filer.
Enter the facility address and coordinates
Line 3a: the facility address, if applicable. Line 3b: latitude and longitude, entering a "+" or "-" sign in the first box of each.
Enter construction and service dates
Line 4: the date construction began, and line 5: the date placed in service, both as MM/DD/YYYY. On line 6, check Yes or No on whether this expands an existing closed-loop or open-loop biomass facility. Line 7 is reserved for future use.
Answer the qualified facility question
Line 8 applies to facilities placed in service after December 31, 2021. Check 8a (under 1 megawatt ac), 8b (construction began before January 29, 2023), 8c (prevailing wage and apprenticeship requirements met) or 8d (none apply), and attach the statements described in the instructions.
Answer the bonus credit questions
Line 9: check 9a if the facility qualifies for the domestic content bonus (attach the required information) or 9b if not. Line 10: check 10a for the energy community bonus, 10b for No or 10c for Not applicable.
Enter nameplate capacity
Line 11a: the solar nameplate capacity in dc kW, or 11b if not applicable. Line 12: the ac nameplate capacity in kW for solar (12a), wind (12b) or other (12c), or 12d if not applicable.
Enter kilowatt-hours by resource
On page 2, Part II, lines 1a through 1j, enter in column (a) the kilowatt-hours produced and sold for each resource that applies. Apply the rate in column (b) under the instructions and enter the product in column (c).
Figure the credit before reduction
Line 2: add column (c) of lines 1a through 1j. Line 3: the phaseout adjustment; calendar year filers enter -0-. Line 4: subtract line 3 from line 2.
Reduce for tax-exempt bonds
If tax-exempt bond proceeds financed the facility, complete lines 5a through 5d and subtract line 5d from line 4 on line 6. Otherwise enter the line 4 amount on line 6.
Complete the wind facility lines
Lines 7a through 7g apply to wind facilities by the year construction began (2017; 2018, 2020 or 2021; 2019). For facilities placed in service after 2021, enter -0- on lines 7b, 7d and 7f. Subtract line 7g from line 6 on line 8.
Apply increased and bonus credit lines
Line 9: if you checked a Yes box in Part I, question 8, multiply line 8 by the factor printed there; otherwise copy line 8. Complete lines 10 and 11 for the bonuses you claimed, add lines 9 through 11 on line 12, and apply the elective payment adjustment on line 13 only if it fits your case.
Complete lines 14 through 17
Line 14: credits from partnerships, S corporations, cooperatives, estates and trusts; on a separate Form 8835, write "Credits From Pass-Through Entities" on line 2a of Part I. Add lines 13 and 14 on line 15; cooperatives, estates and trusts continue to lines 16 and 17.
Review and download the completed PDF
Check that Part I and Part II agree, that the attachments listed in the instructions are ready, and that the amount carries to Schedule K or Form 3800 as line 15 or 17 directs. Download or print the completed PDF from FillingPDF and attach it to your return.
How to submit 8835
Form 8835 has no filing address of its own: you attach it to your tax return and submit the return through the channels that return uses.
- With your return. Attach the completed form to your income tax return. The result then moves to Schedule K (partnerships and S corporations) or to Form 3800, Part III, line 4e or 1f (all others).
- Applicable entities making an elective payment election. File Form 8835 with any applicable attachments, Form 3800 and Form 990-T or another applicable income tax return.
- Pre-filing registration. For an elective payment or transfer election, register each facility before you file at IRS.gov/Credits-Deductions/Register-for-Elective-Payment-or-Transfer-of-Credits. Pub. 5884 describes the registration tool.
- Statements and forms. Attach the required statements, Form 7220 where it applies, and any fiscal-year calculations to the form. Where to mail the return depends on the return itself; see its instructions.
Instructions and the latest information are at www.irs.gov/Form8835. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Combining several qualified facilities on one form; the instructions call for a separate Form 8835 for each qualified facility.
- Checking a Yes box in question 8a, 8b or 8c and entering an increased amount on line 9 without attaching the required statement for that facility.
- Checking box 8c without filing Form 7220 for that facility; one Form 7220 is needed for each facility claiming the increased amount.
- Checking box 9a for the domestic content bonus without attaching the domestic content certification statement.
- Making an elective payment or transfer election without completing the pre-filing registration first, or leaving the registration number off line 1.
- Completing lines 1 through 13 when the only credit you hold was allocated to you by a partnership, S corporation, estate, trust or cooperative.
- Entering anything but -0- on line 3 as a calendar year filer; the instructions say calendar year filers enter -0-.
- Reporting a partnership or S corporation credit transfer under section 6418 on Schedule K instead of on Form 3800, Part III, line 1f or 4e.
- Claiming the credit for electricity that was not sold to an unrelated person or was produced outside the United States and U.S. territories.
Frequently asked questions
What is Form 8835 used for?
Form 8835 is the IRS form for claiming the renewable electricity production credit. It covers electricity produced from qualified renewable resources at a qualified facility and sold to an unrelated person. Part I describes the facility and Part II figures the credit.
Do I need a separate Form 8835 for each facility?
Yes. The IRS instructions say taxpayers, applicable entities, partnerships and S corporations must file a separate form for each qualified facility used in their trade or business to claim the credit.
Who can claim the renewable electricity production credit?
Generally the owner of the facility. For closed-loop biomass facilities modified to co-fire with coal or other biomass, and for open-loop biomass facilities, the lessee or operator can claim it if the owner is not the producer of the electricity.
What do I attach to Form 8835 to claim the increased credit amount?
A separate statement for each qualified facility, attached to your timely filed return. If you check box 8c, also attach Form 7220 for each facility. Form 7220 is not required if you checked the Yes box in question 8a or 8b.
Where do I file Form 8835?
Attach it to your tax return; the form has no separate mailing address. Partnerships and S corporations carry the amount to Schedule K. Others report the applicable part on Form 3800, Part III, line 4e or line 1f, depending on when the electricity was produced.
Do I need to register before an elective payment or transfer election?
Yes, if you intend to make the election on Form 3800 for the credit figured in Part II. Complete the IRS pre-filing registration for each facility before you file your return, and enter the IRS-issued registration number on line 1.
Can I fill out Form 8835 online?
You can fill out the PDF online on FillingPDF and download or print it. FillingPDF is an independent service: it does not file the form with the IRS, so you submit it with your tax return through the IRS channels.
What is the difference between Form 8835 and Form 3468?
Form 8835 claims the production credit for electricity sold. Form 3468 is where an eligible facility reports an investment credit if it makes the irrevocable section 48(a)(5) election to be treated as energy property instead of claiming the production credit on Form 8835.
How do partners and S corporation shareholders report this credit?
If the only credit allocated to you is the renewable electricity production credit, do not report it on Form 8835. Report it directly on Form 3800, Part III, line 1f or 4e, as applicable, using your Schedule K-1 information.
Ready to fill out 8835?
Fill out 8835 now