
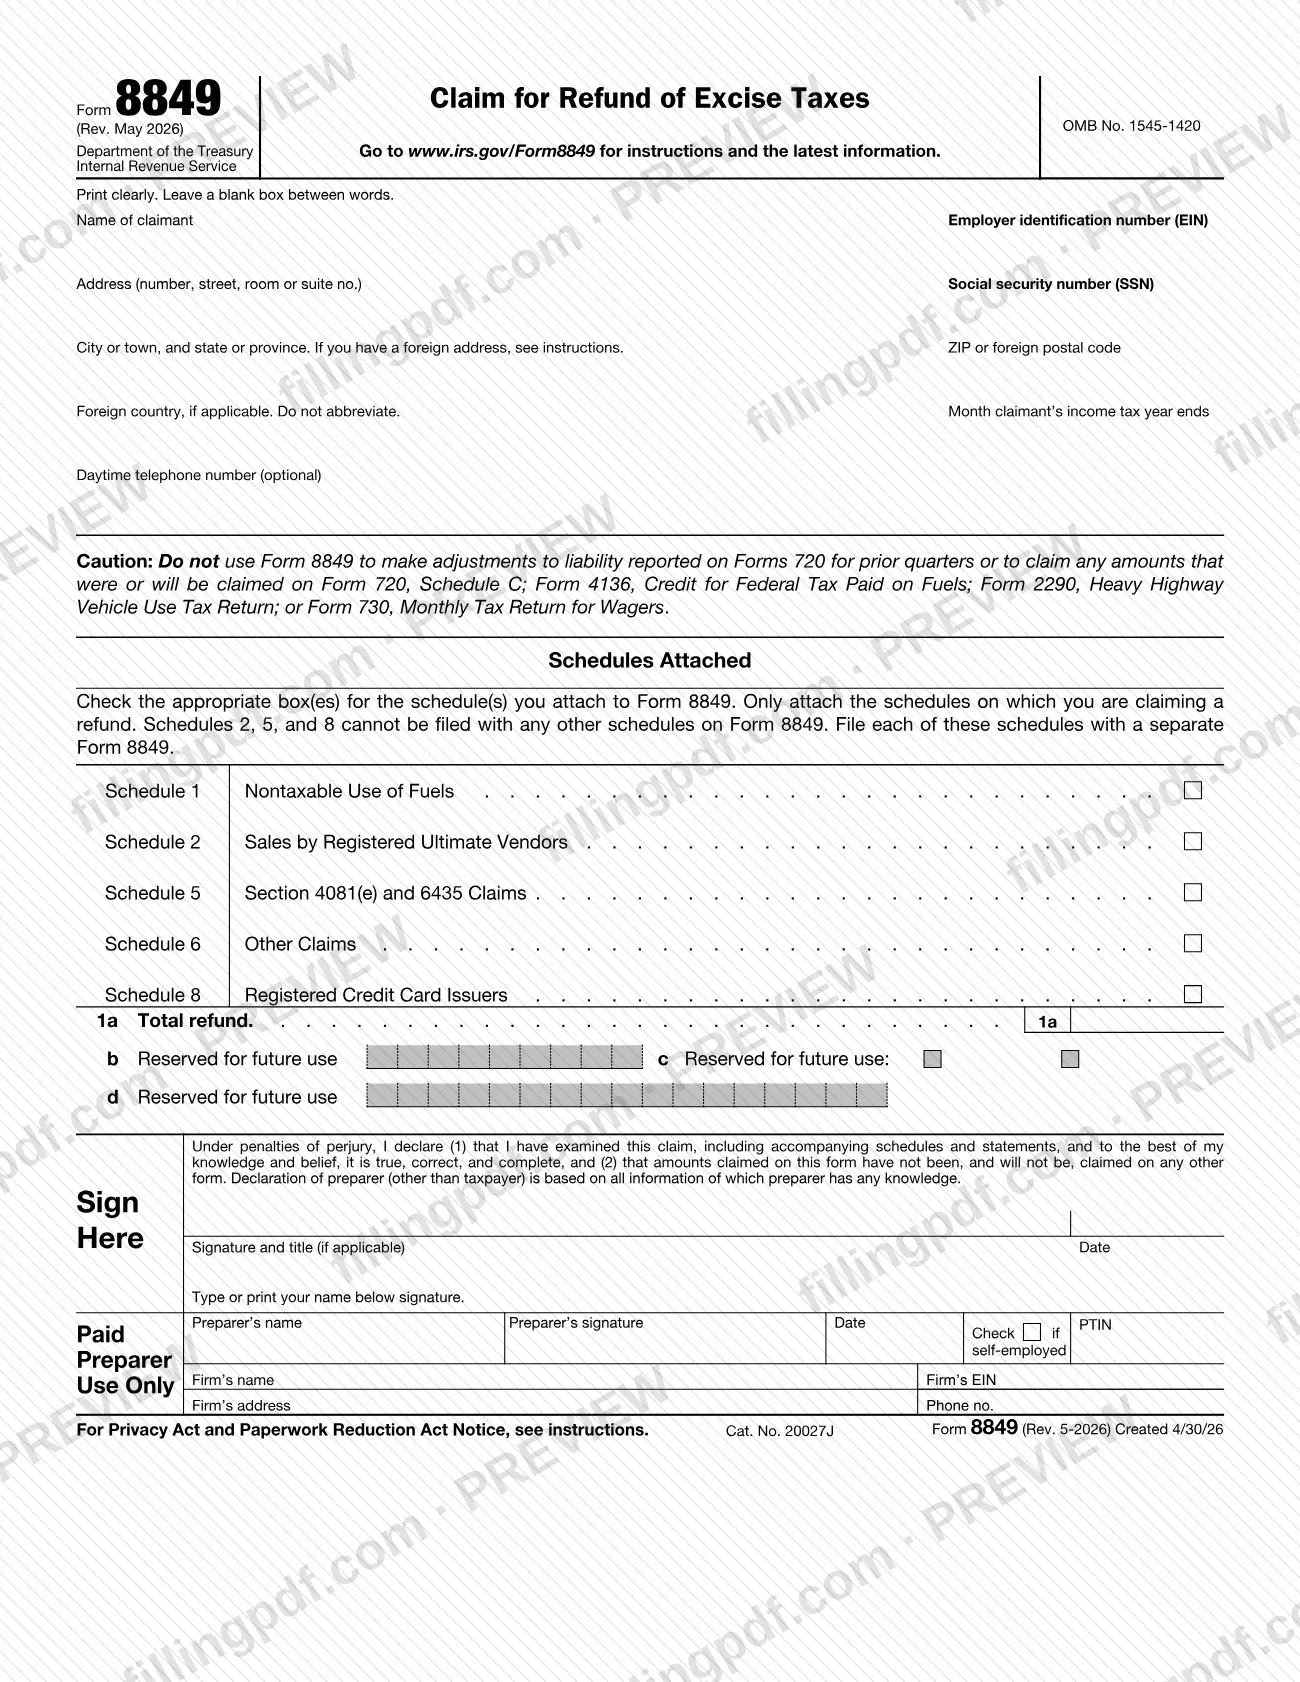
Form 8849, Claim for Refund of Excise Taxes, is the Internal Revenue Service (IRS) form for claiming a refund of certain federal excise taxes. It works as a cover form: you check the boxes for the schedules you attach (Schedules 1, 2, 5, 6 and 8), enter the total refund on line 1a and sign. On this page you can fill out the form online on FillingPDF and download or print the completed PDF; the form and its instructions are published by the IRS at www.irs.gov/Form8849.
Last updated
What is Form 8849?
Form 8849, Claim for Refund of Excise Taxes, is the IRS form used to claim a refund of excise taxes. Fuel-related refunds, such as refunds for nontaxable uses or sales of fuels, are claimed on Schedules 1, 2, 5 and 8 attached to it.
The form itself holds only the claimant's identifying information, the boxes for the attached schedules, the total refund on line 1a, the penalties-of-perjury declaration and the paid preparer section. The claim is made on the schedules, and filers only need to complete and attach the schedules that apply:
- Schedule 1, Nontaxable Use of Fuels: used by an ultimate purchaser of gasoline, gasohol, aviation gasoline, diesel fuel, kerosene, aviation fuel (other than gasoline) and liquefied gas (LPG).
- Schedule 2, Sales by Registered Ultimate Vendors: for a registered ultimate vendor of un-dyed diesel fuel, un-dyed kerosene, kerosene sold for use in aviation, gasoline or aviation gasoline.
- Schedule 5, Section 4081(e) and 6435 Claims: for a person who paid and reported a section 4081 tax when a prior section 4081 tax on that fuel was also paid and reported.
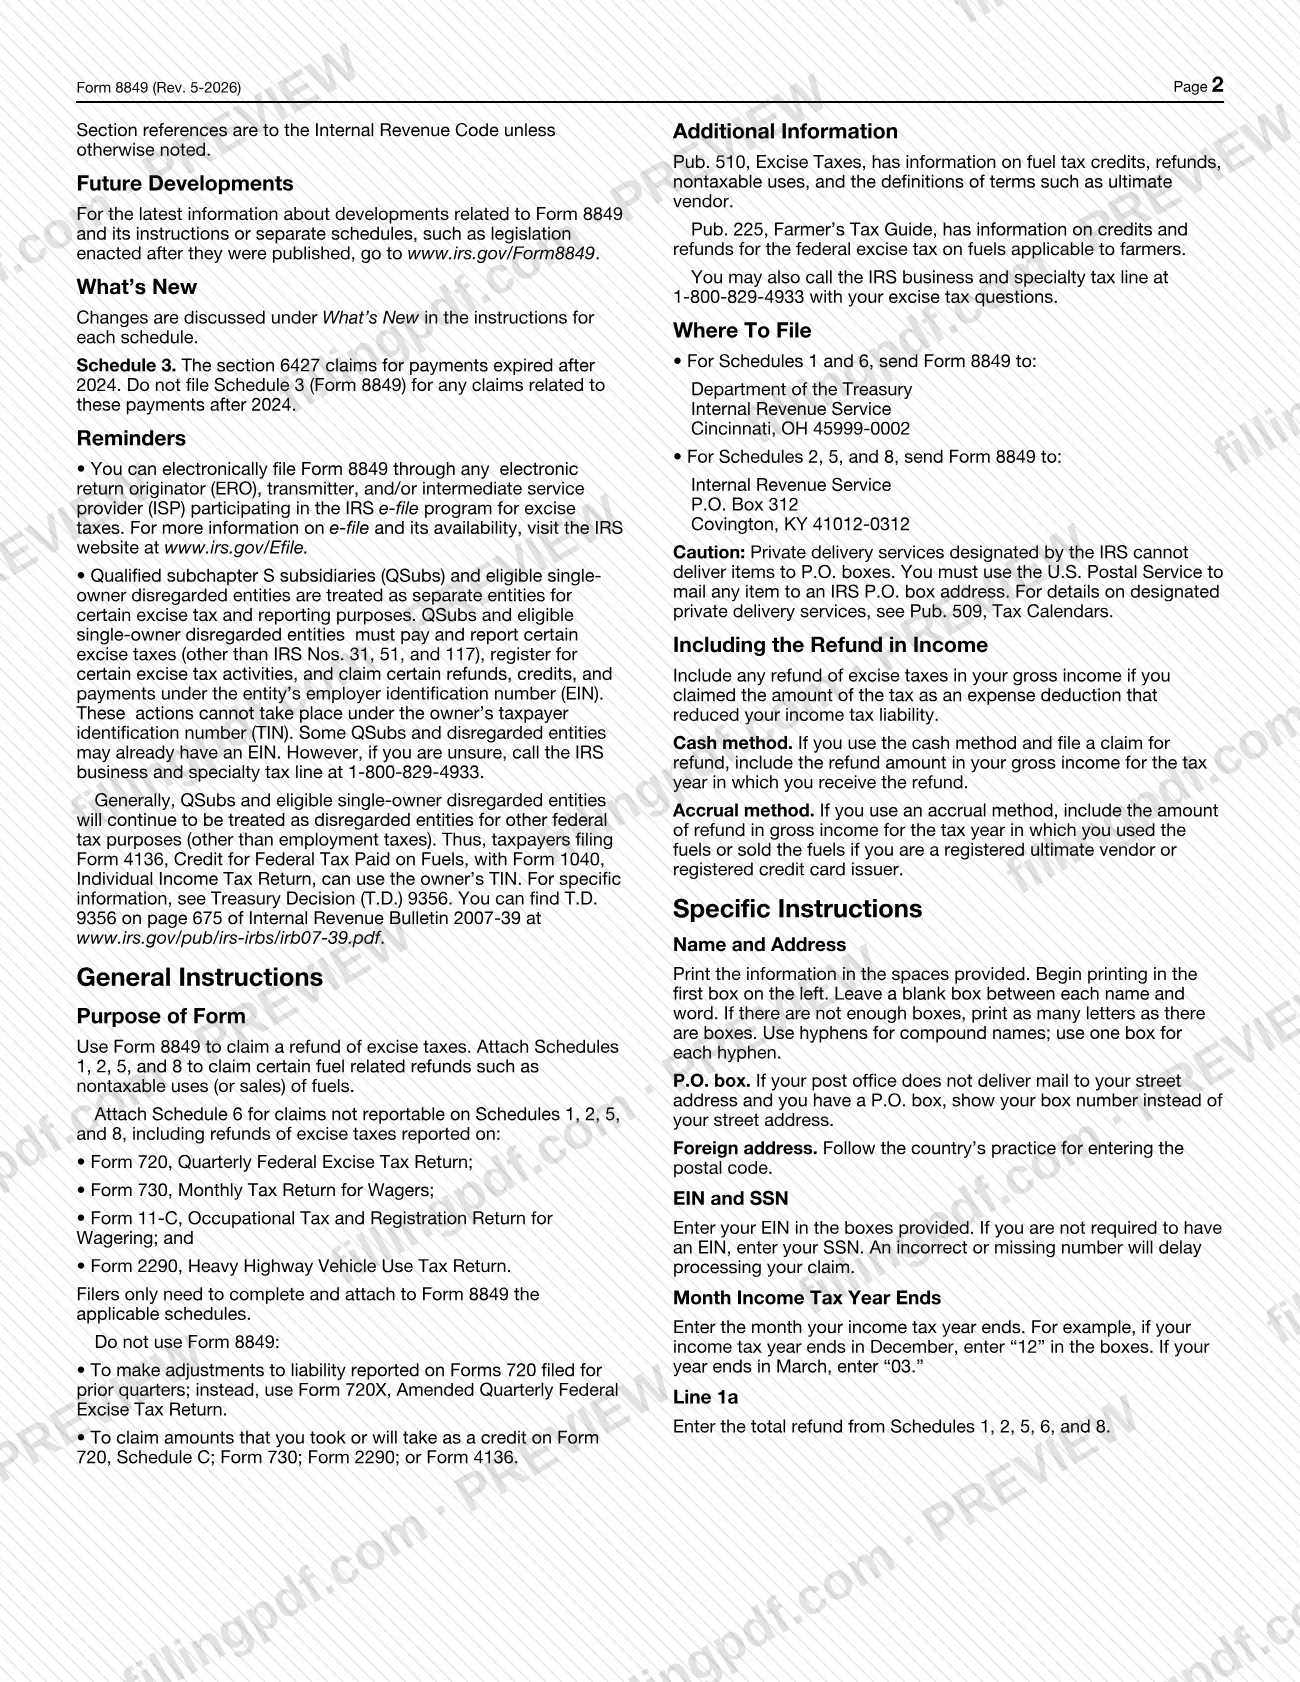
- Schedule 6, Other Claims: for claims not reportable on Schedules 1, 2, 5 and 8, including refunds of excise taxes reported on Form 720, Form 730, Form 11-C and Form 2290.
- Schedule 8, Registered Credit Card Issuers: for certain sales of taxable fuel to state and local governments and certain sales of gasoline to nonprofit educational organizations.
Form 8849 is not used to adjust liability reported on prior-quarter Forms 720 (use Form 720X) or to claim amounts taken or to be taken on Form 720 Schedule C, Form 730, Form 2290 or Form 4136.
Who needs to file Form 8849?
Anyone entitled to a refund of excise taxes that is reportable on one of the Form 8849 schedules uses this form, with the schedule that matches the claim.
- Ultimate purchasers of fuels claiming nontaxable use file Schedule 1.
- Registered ultimate vendors file Schedule 2.
- Persons who paid a section 4081 tax after a prior section 4081 tax on the same fuel file Schedule 5.
- Claimants whose refund is not reportable on another schedule, such as refunds of taxes reported on Forms 720, 730, 11-C or 2290, file Schedule 6.
- Registered credit card issuers file Schedule 8.
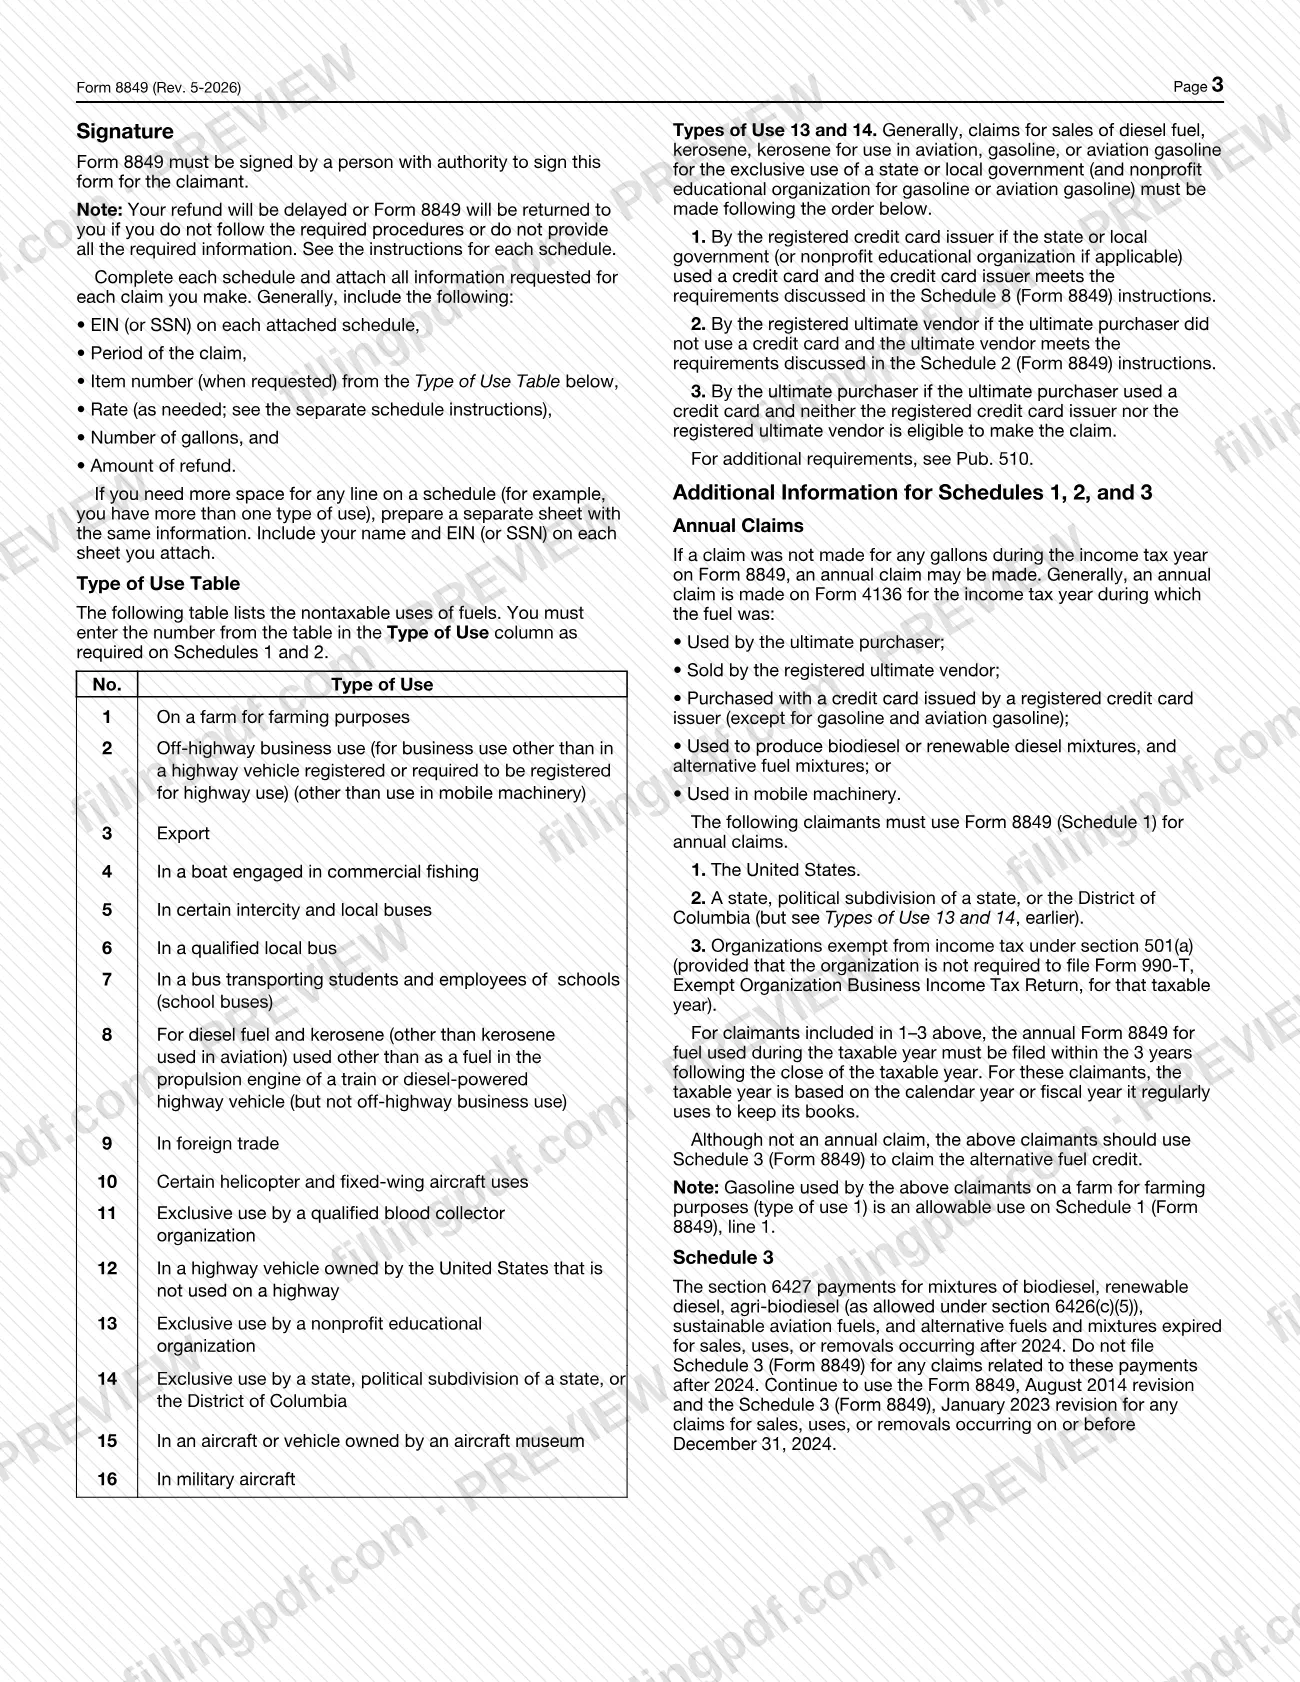
The United States, a state or political subdivision of a state or the District of Columbia, and organizations exempt under section 501(a) (that are not required to file Form 990-T for the year) must use Schedule 1 for annual claims.
Do not use Form 8849 to adjust liability reported on prior-quarter Forms 720, or to claim amounts taken or to be taken on Form 720 Schedule C, Form 4136, Form 2290 or Form 730. Schedule 3 claims for payments expired after 2024 are not filed on the current revision.
The form must be signed by a person with authority to sign for the claimant. A paid preparer who is not an employee of the filing entity also signs and completes the Paid Preparer Use Only section.
When to file Form 8849
File Form 8849 when you have a refund claim that belongs on one of its schedules; the form prints no single due date. For some claimants the instructions set one: the United States, states, political subdivisions, the District of Columbia and section 501(a) organizations must file their annual Form 8849 for fuel used during the taxable year within the 3 years following the close of that taxable year. Their taxable year follows the calendar or fiscal year they regularly use for their books.
If no claim was made on Form 8849 for any gallons during the income tax year, an annual claim may be made, generally on Form 4136, for fuel used, sold or purchased in that year as the instructions describe.
Schedule 3 is no longer filed for payments expiring after 2024. For claims for sales, uses or removals on or before December 31, 2024, the instructions say to keep using the August 2014 revision of Form 8849 and the January 2023 revision of Schedule 3.
Documents you need
- The schedules for the claims you make (Schedule 1, 2, 5, 6 or 8): attach only the schedules on which you are claiming a refund.
- A separate Form 8849 for each of Schedules 2, 5 and 8: these schedules cannot be filed with any other schedules.
- A separate sheet with the same information, including your name and EIN (or SSN), if you need more space for any line on a schedule, for example when you have more than one type of use.
- EIN (or SSN), period of the claim, Type of Use item number, rate, number of gallons and amount of refund on the schedules, as each schedule asks; see the separate schedule instructions and Pub. 510 for additional requirements.
How to fill out Form 8849
Enter the claimant's name and address
Fill in Name of claimant and the address lines, starting in the first box on the left and leaving a blank box between words. Use a P.O. box only if your post office does not deliver to your street address; enter the foreign country without abbreviating it if you have a foreign address.
Enter your EIN or SSN
Enter your employer identification number (EIN) in the boxes provided. If you are not required to have an EIN, enter your social security number (SSN); an incorrect or missing number delays the claim.
Enter the month your tax year ends
In Month claimant's income tax year ends, enter two digits, for example "12" for December or "03" for March.
Add a daytime telephone number
The Daytime telephone number line is marked optional on the form.
Check the schedules you attach
Check the box for each of Schedule 1, 2, 5, 6 or 8 that you attach, and only the ones on which you claim a refund. Schedules 2, 5 and 8 each require their own separate Form 8849.
Complete each attached schedule
Fill out each schedule following its own instructions, including EIN (or SSN), period of the claim, Type of Use number where requested, rate, gallons and refund amount. Use a separate sheet with your name and EIN (or SSN) if you need more space.
Enter the total refund on line 1a
On line 1a, enter the total refund from Schedules 1, 2, 5, 6 and 8. Leave the lines marked reserved for future use blank.
Sign and date the claim
Under the penalties-of-perjury declaration, sign with your title if applicable, date it and print your name below. A person with authority to sign for the claimant must sign.
Complete the paid preparer section
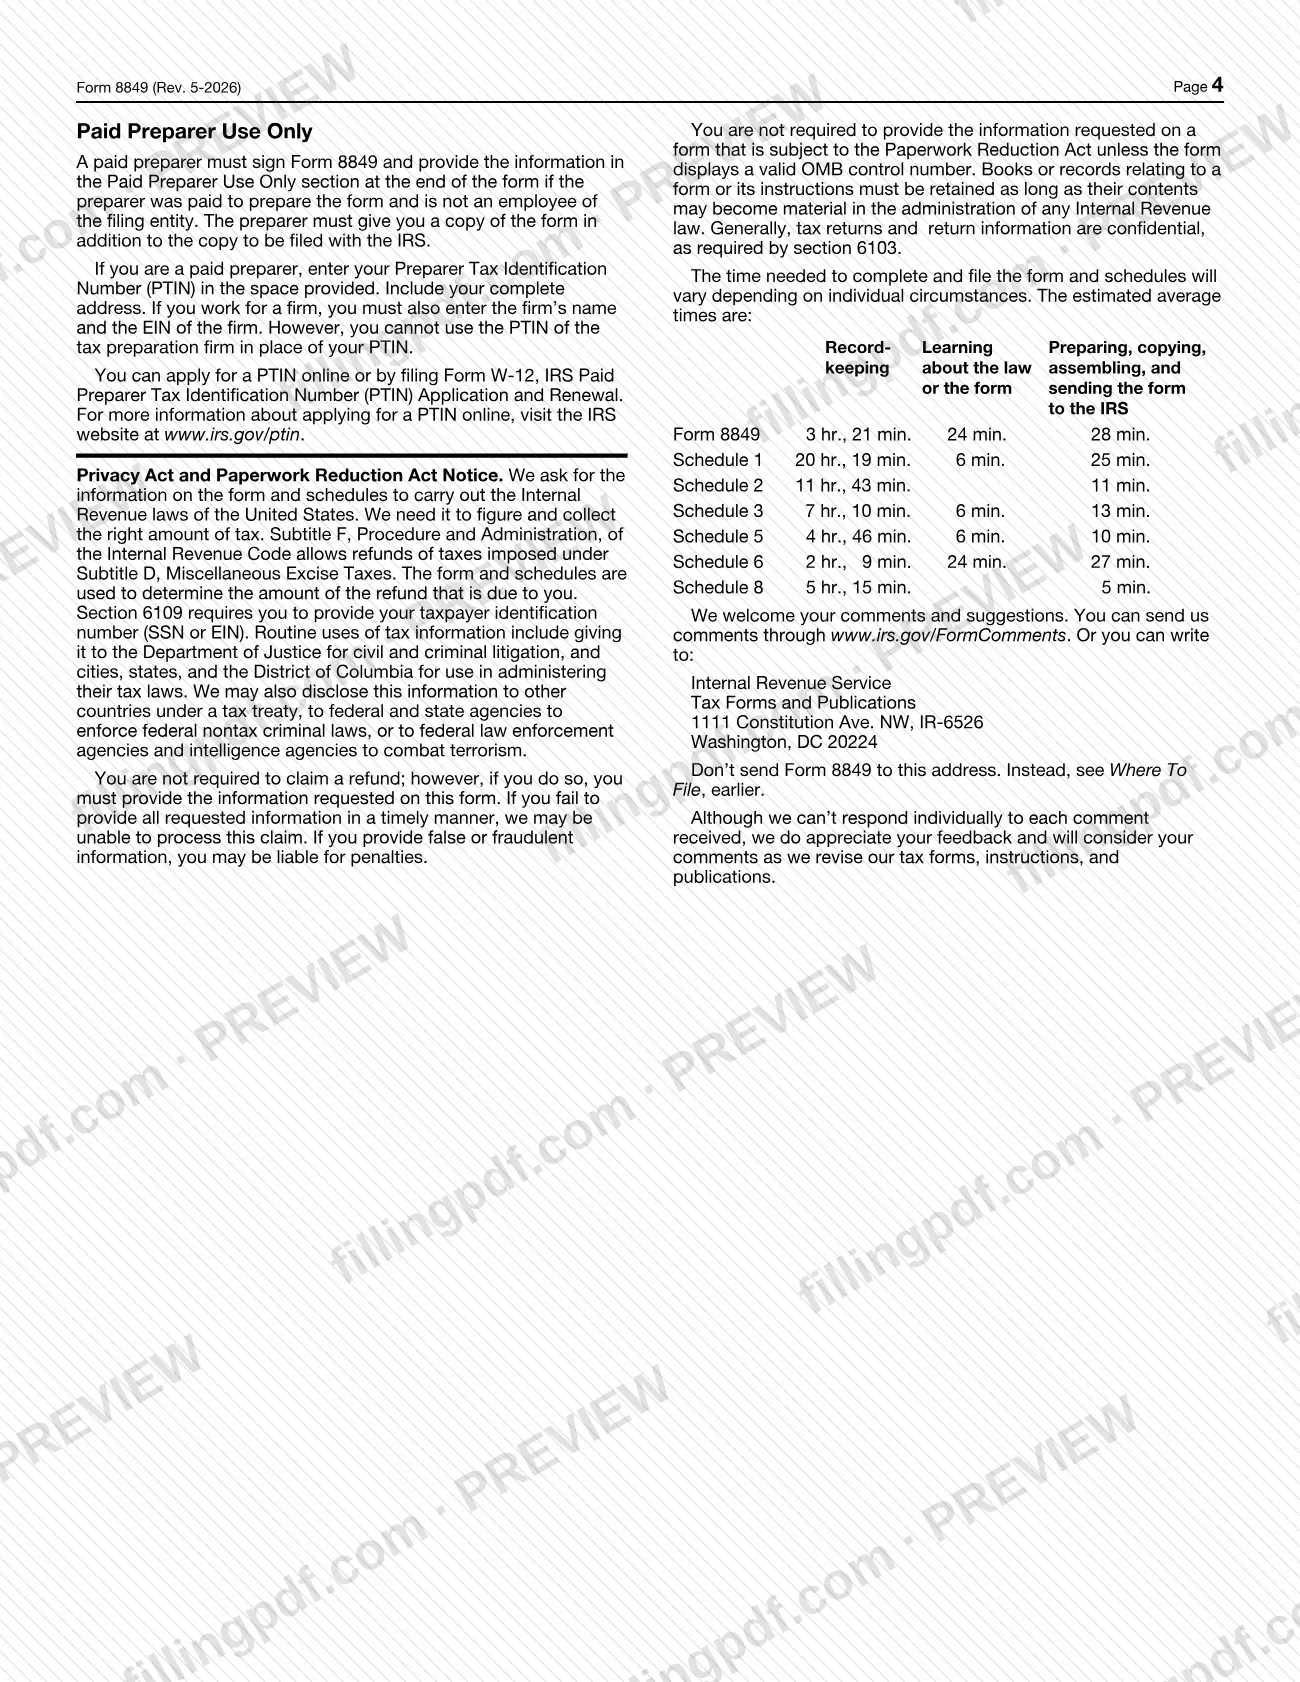
If a paid preparer who is not an employee of the filing entity prepared the form, the preparer signs and enters name, PTIN, firm name, firm EIN, address and phone number, and checks the box if self-employed.
Review and download the completed PDF
Check names, numbers and the line 1a total against your schedules, then download or print the completed PDF from FillingPDF and send it as described under How to submit.
How to submit Form 8849
You can send Form 8849 by mail or file it electronically through a participating provider. The mailing address depends on the schedules attached.
- Mail, Schedules 1 and 6: Department of the Treasury, Internal Revenue Service, Cincinnati, OH 45999-0002.
- Mail, Schedules 2, 5 and 8: Internal Revenue Service, P.O. Box 312, Covington, KY 41012-0312. Schedules 2, 5 and 8 cannot be filed with any other schedules, so each goes with its own separate Form 8849.
- Electronic filing: you can e-file Form 8849 through any electronic return originator (ERO), transmitter or intermediate service provider (ISP) participating in the IRS e-file program for excise taxes. See www.irs.gov/Efile.
Private delivery services designated by the IRS cannot deliver to P.O. boxes; use the U.S. Postal Service for the Covington P.O. box address. Do not mail the form to the Tax Forms and Publications address in Washington, DC printed in the instructions. For excise tax questions, call the IRS business and specialty tax line at 1-800-829-4933.
The instructions warn that a refund will be delayed, or the form returned, if required procedures are not followed or information is missing. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Using Form 8849 to adjust liability reported on a prior-quarter Form 720; the instructions say to use Form 720X instead.
- Claiming amounts on Form 8849 that were or will be claimed on Form 720 Schedule C, Form 4136, Form 2290 or Form 730.
- Filing Schedule 2, 5 or 8 together with another schedule on one Form 8849; each of these needs its own separate form.
- Attaching schedules on which you are not claiming a refund; only attach the schedules you claim on.
- Entering an incorrect or missing EIN or SSN, which the instructions say will delay processing of the claim.
- Sending a Schedule 2, 5 or 8 claim by private delivery service to the Covington P.O. box; only the U.S. Postal Service can deliver to an IRS P.O. box.
- Mailing Schedule 1 or 6 to the P.O. Box 312 address, or Schedule 2, 5 or 8 to the Cincinnati address.
- Filing a Schedule 3 claim for payments after 2024; the section 6427 payments expired, and earlier claims use the older revisions.
- Leaving the form unsigned or without the preparer information when a paid preparer who is not your employee prepared it.
Frequently asked questions
What is Form 8849 used for?
Form 8849 is the IRS Claim for Refund of Excise Taxes. You attach Schedules 1, 2, 5, 6 or 8 to claim refunds such as nontaxable uses or sales of fuels, or other excise tax refunds, including taxes reported on Forms 720, 730, 11-C and 2290.
Where do I mail Form 8849?
Mail Schedules 1 and 6 to Department of the Treasury, Internal Revenue Service, Cincinnati, OH 45999-0002. Mail Schedules 2, 5 and 8 to Internal Revenue Service, P.O. Box 312, Covington, KY 41012-0312, using the U.S. Postal Service, since private delivery services cannot deliver to P.O. boxes.
Can I file Form 8849 electronically?
Yes. The instructions say you can e-file Form 8849 through any electronic return originator, transmitter or intermediate service provider participating in the IRS e-file program for excise taxes. See www.irs.gov/Efile for availability.
Can I file Schedules 2, 5 and 8 on one Form 8849?
No. Schedules 2, 5 and 8 cannot be filed with any other schedules on Form 8849. File each of them with a separate Form 8849. Schedules 1 and 6 use the Cincinnati address, while 2, 5 and 8 go to the Covington P.O. box.
Should I use Form 8849 or Form 720X to correct a Form 720?
Use Form 720X. The instructions say not to use Form 8849 to adjust liability reported on Forms 720 for prior quarters. Form 8849 also cannot claim amounts that were or will be claimed on Form 720 Schedule C, Form 4136, Form 2290 or Form 730.
Is Schedule 3 of Form 8849 still available?
Not for payments after 2024. The section 6427 payments expired for sales, uses or removals after 2024. For claims on or before December 31, 2024, the instructions say to keep using the August 2014 Form 8849 and the January 2023 Schedule 3.
Do I enter an EIN or an SSN on Form 8849?
Enter your EIN. If you are not required to have an EIN, enter your SSN instead. An incorrect or missing number will delay processing your claim, and the EIN or SSN also goes on each attached schedule.
Do I have to report a Form 8849 refund as income?
Include the refund in gross income if you claimed the tax as an expense deduction that reduced your income tax liability. Cash-method filers include it for the year they receive it; accrual filers include it for the year the fuel was used or sold.
Can I fill out Form 8849 online on FillingPDF?
Yes. You can fill out the fillable PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the claim with the IRS; you send it by mail or through an IRS e-file provider.
Ready to fill out Form 8849?
Fill out Form 8849 now