
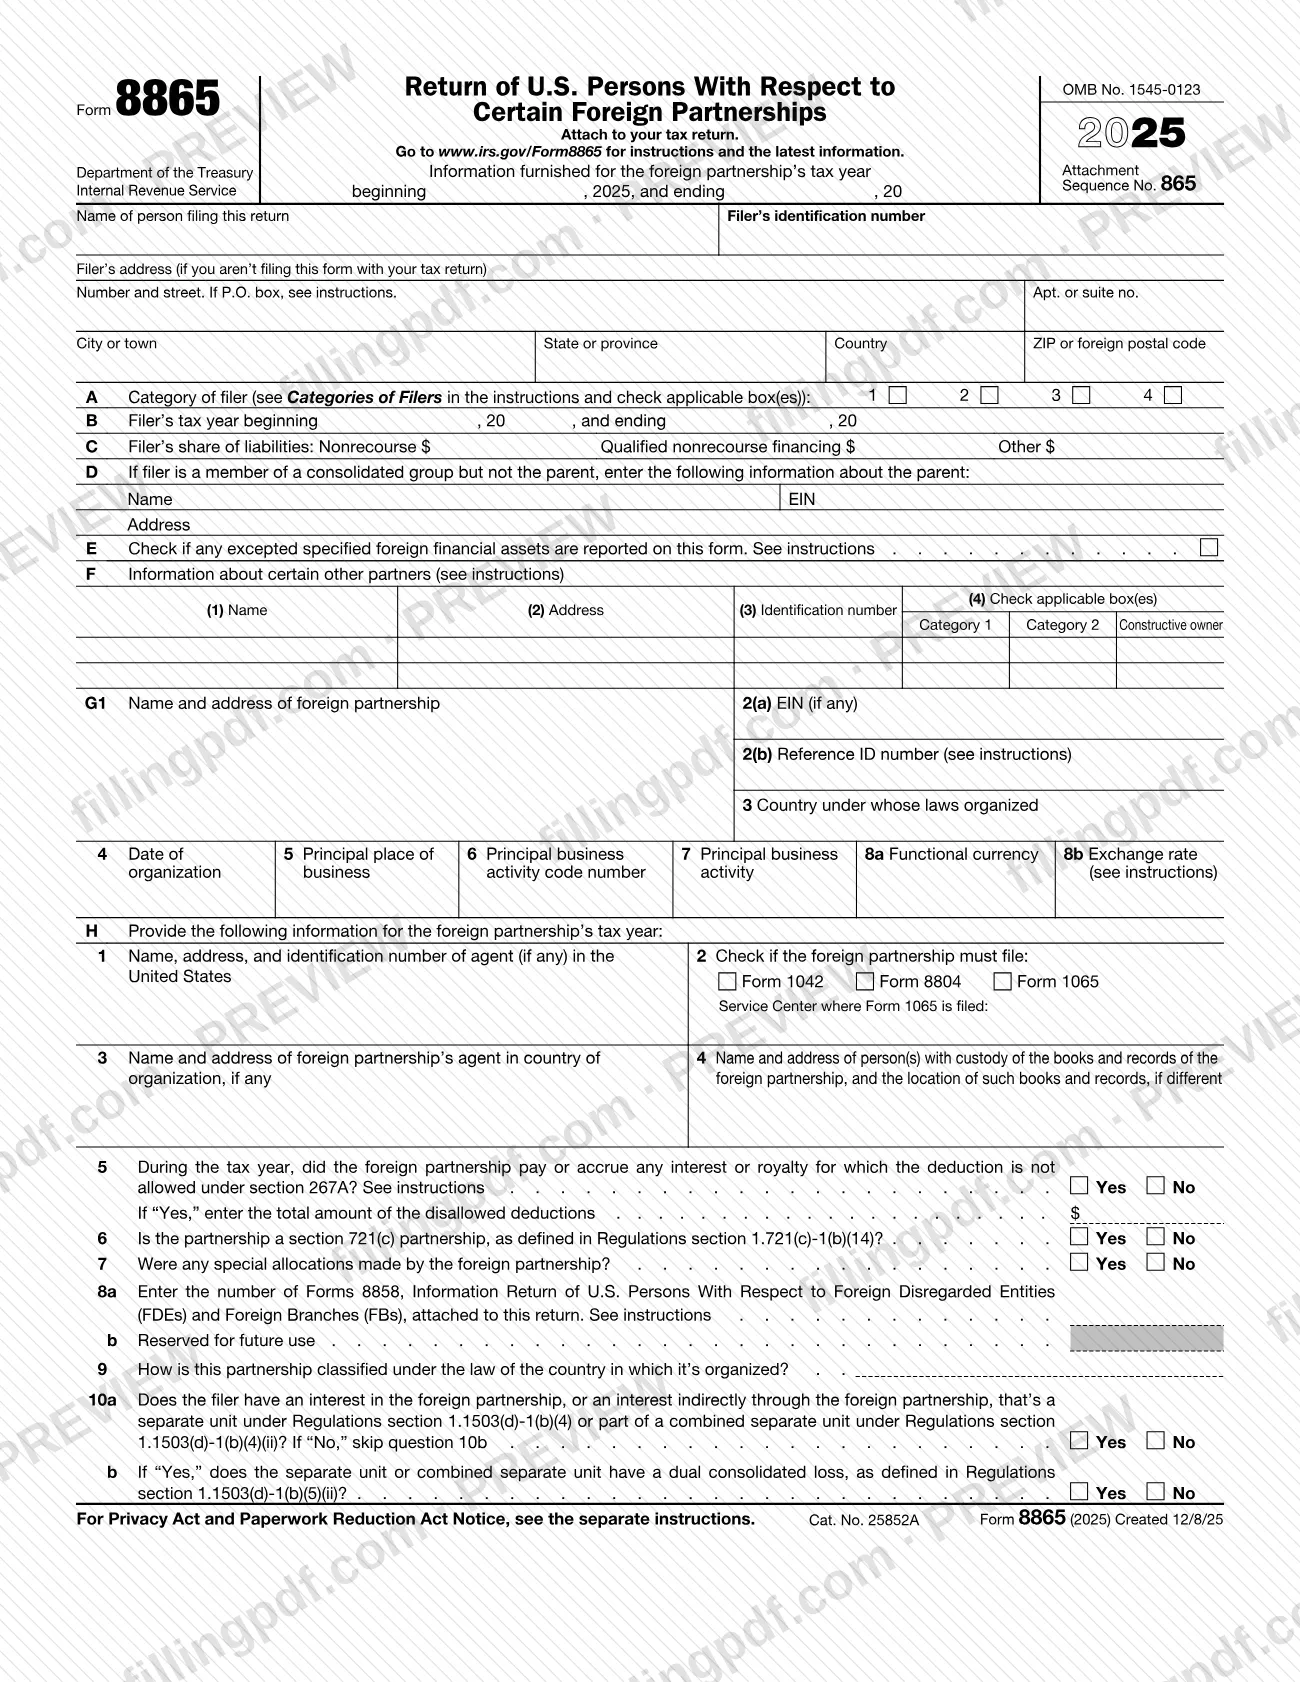
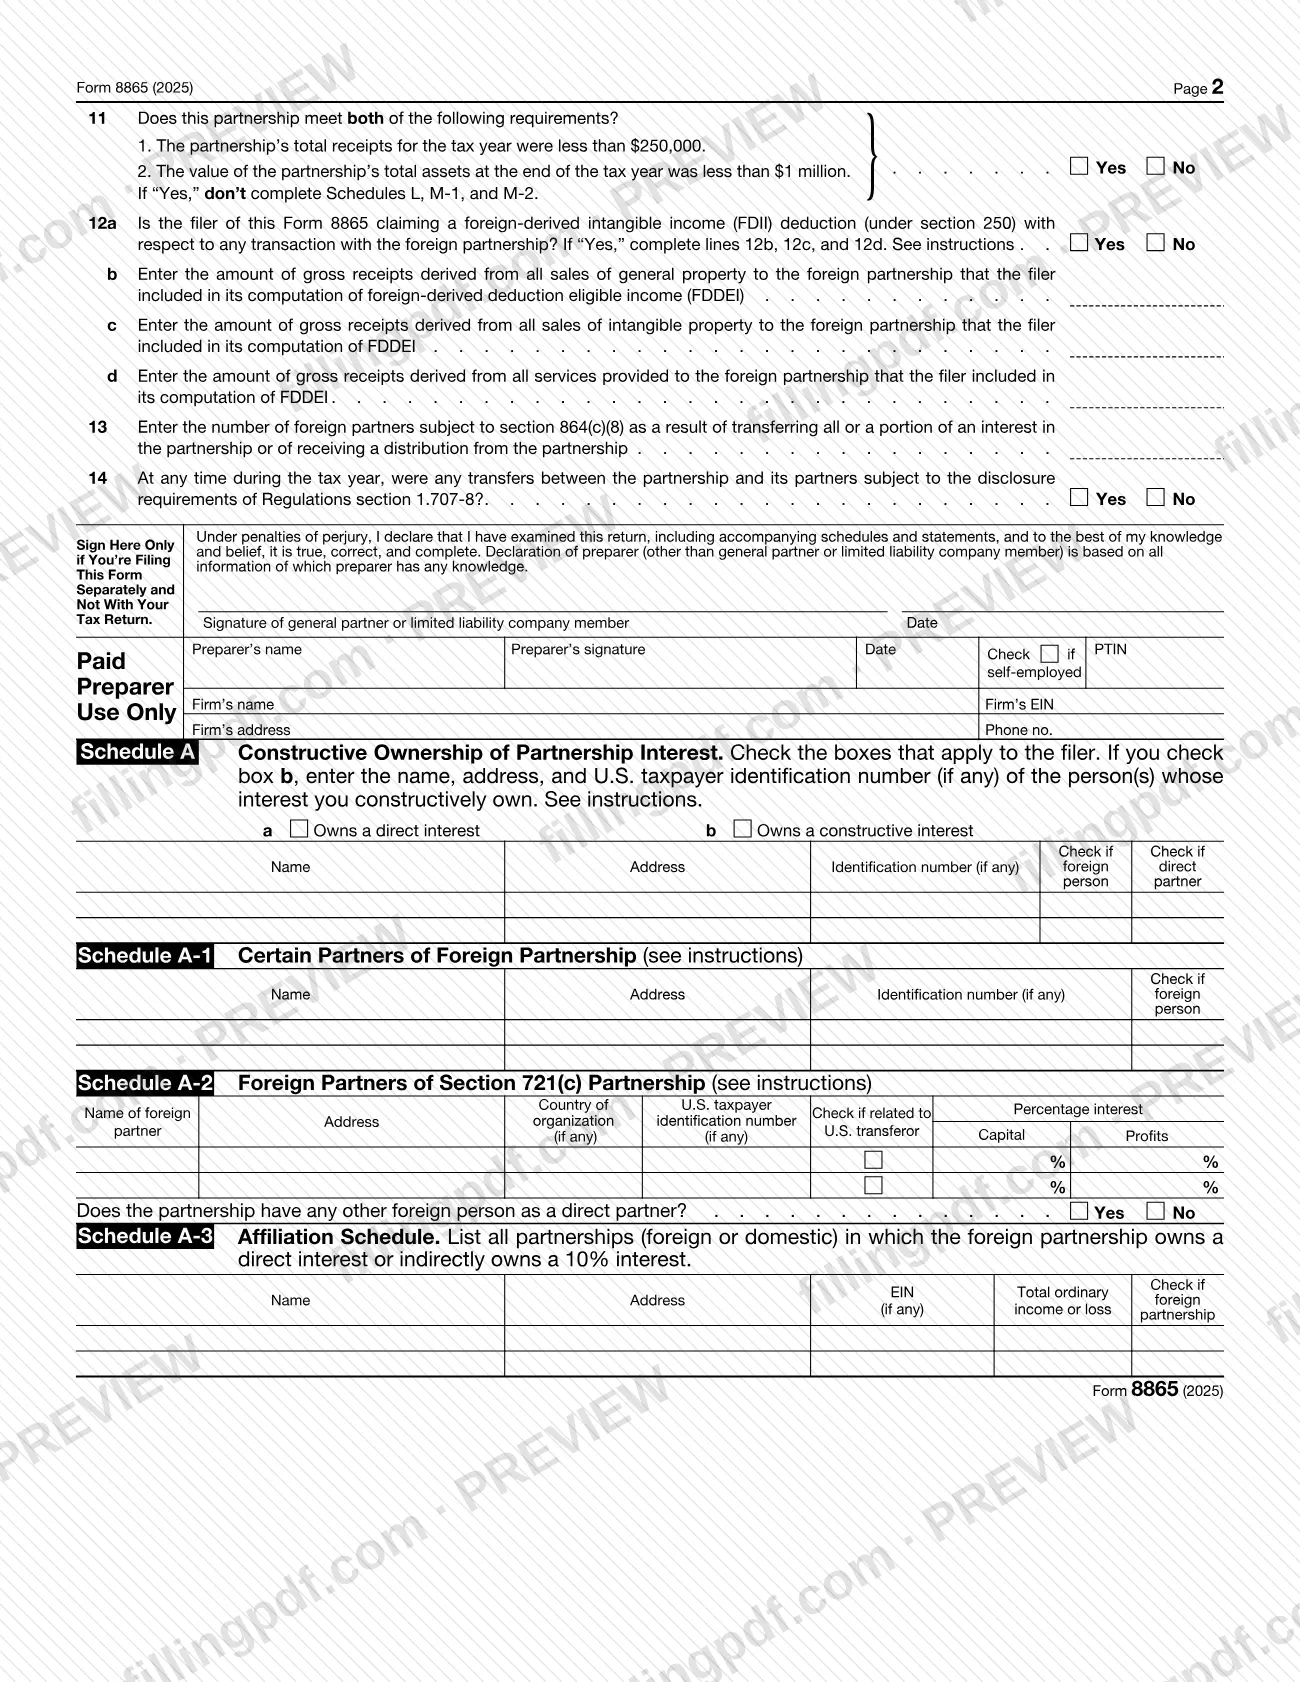
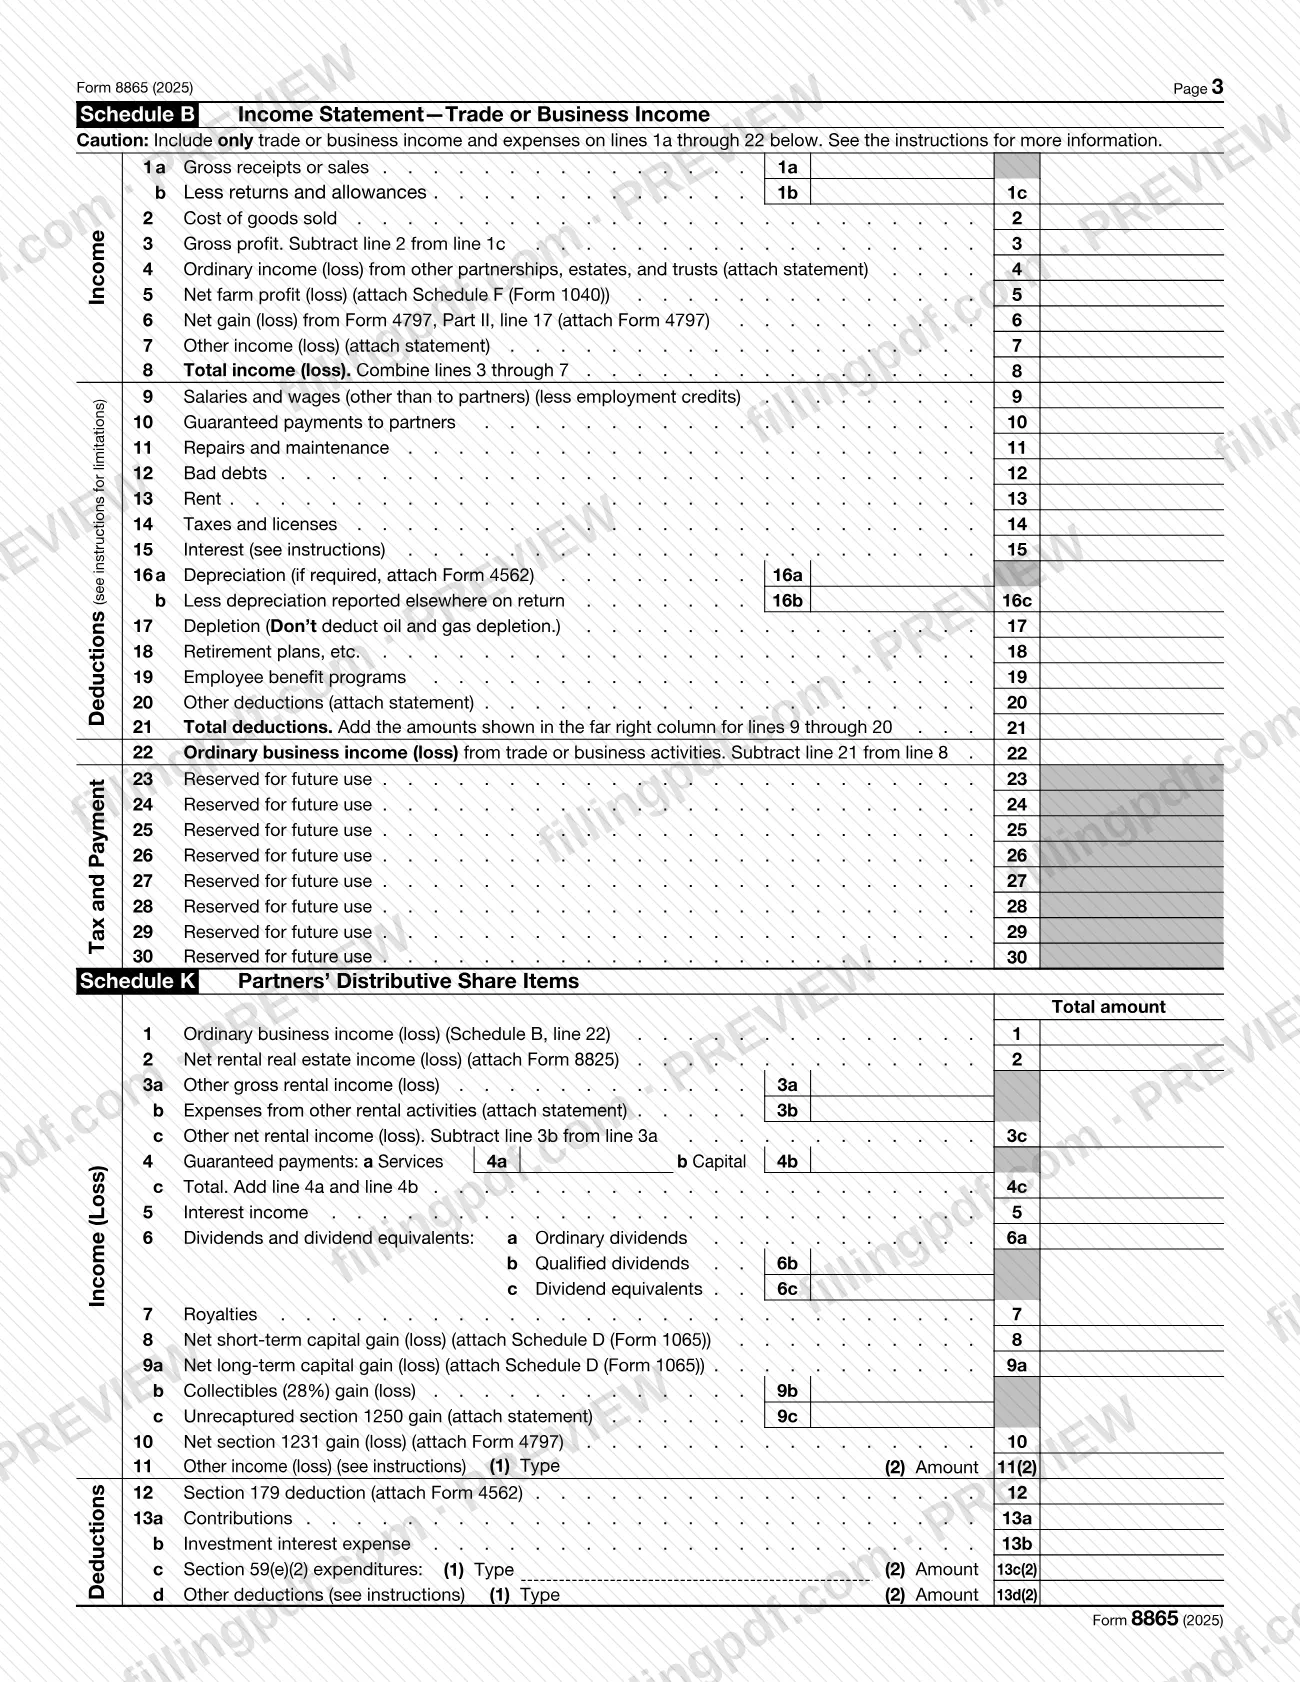
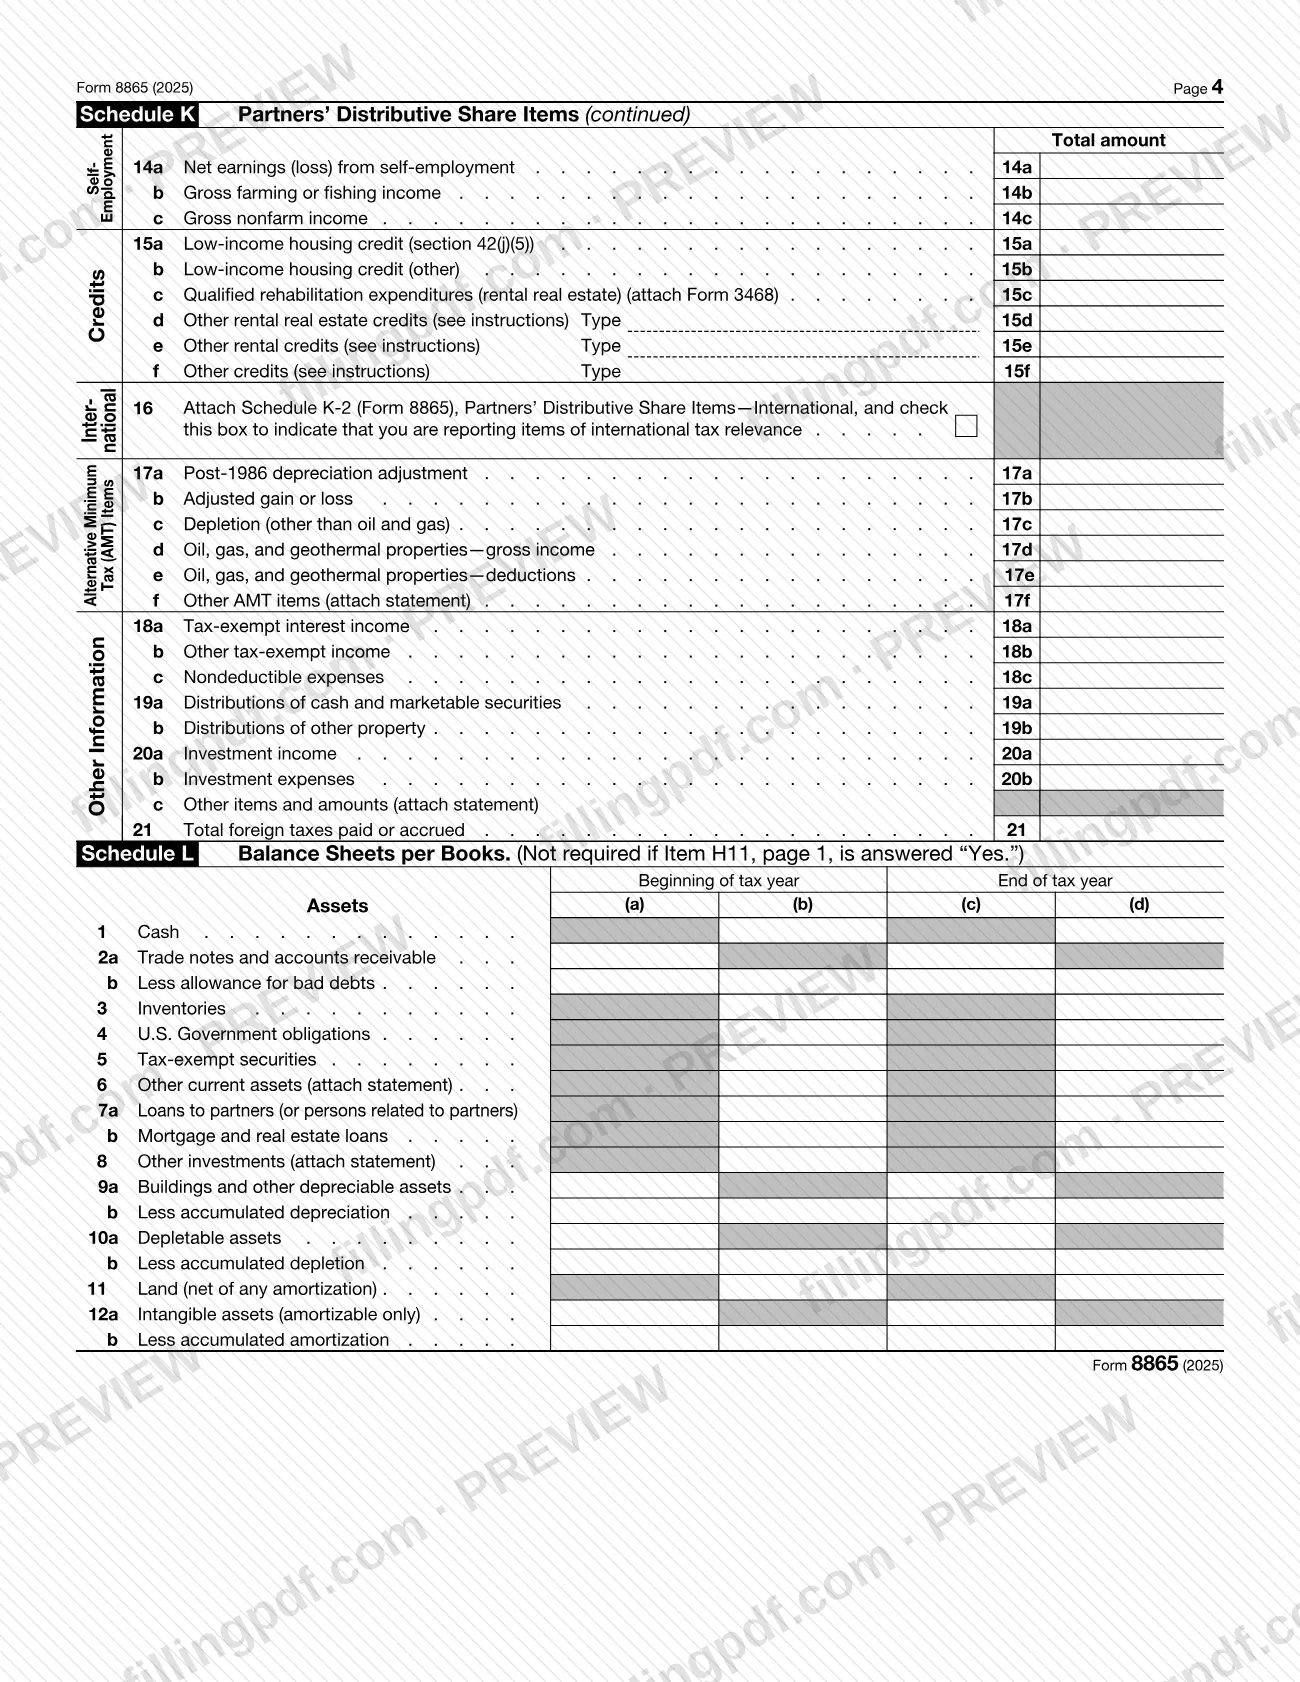
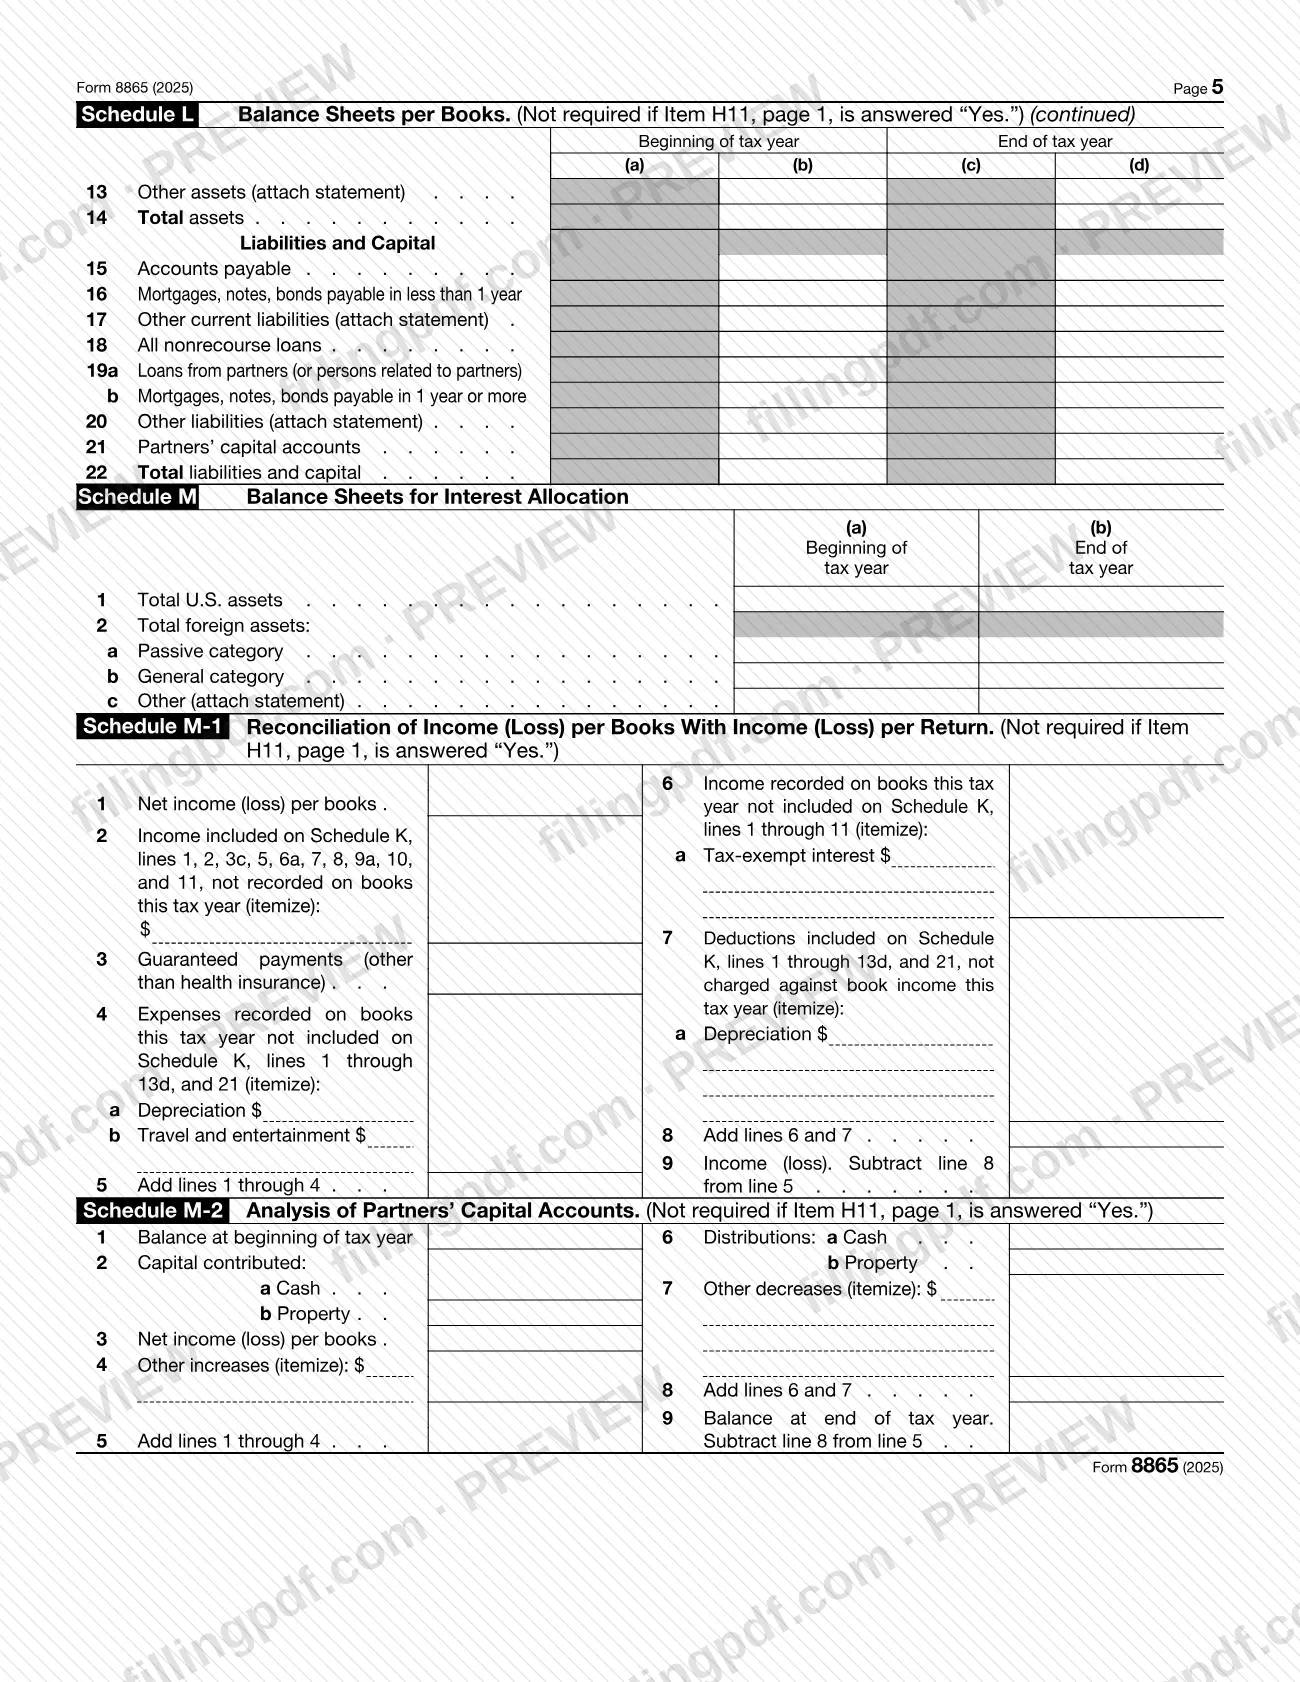
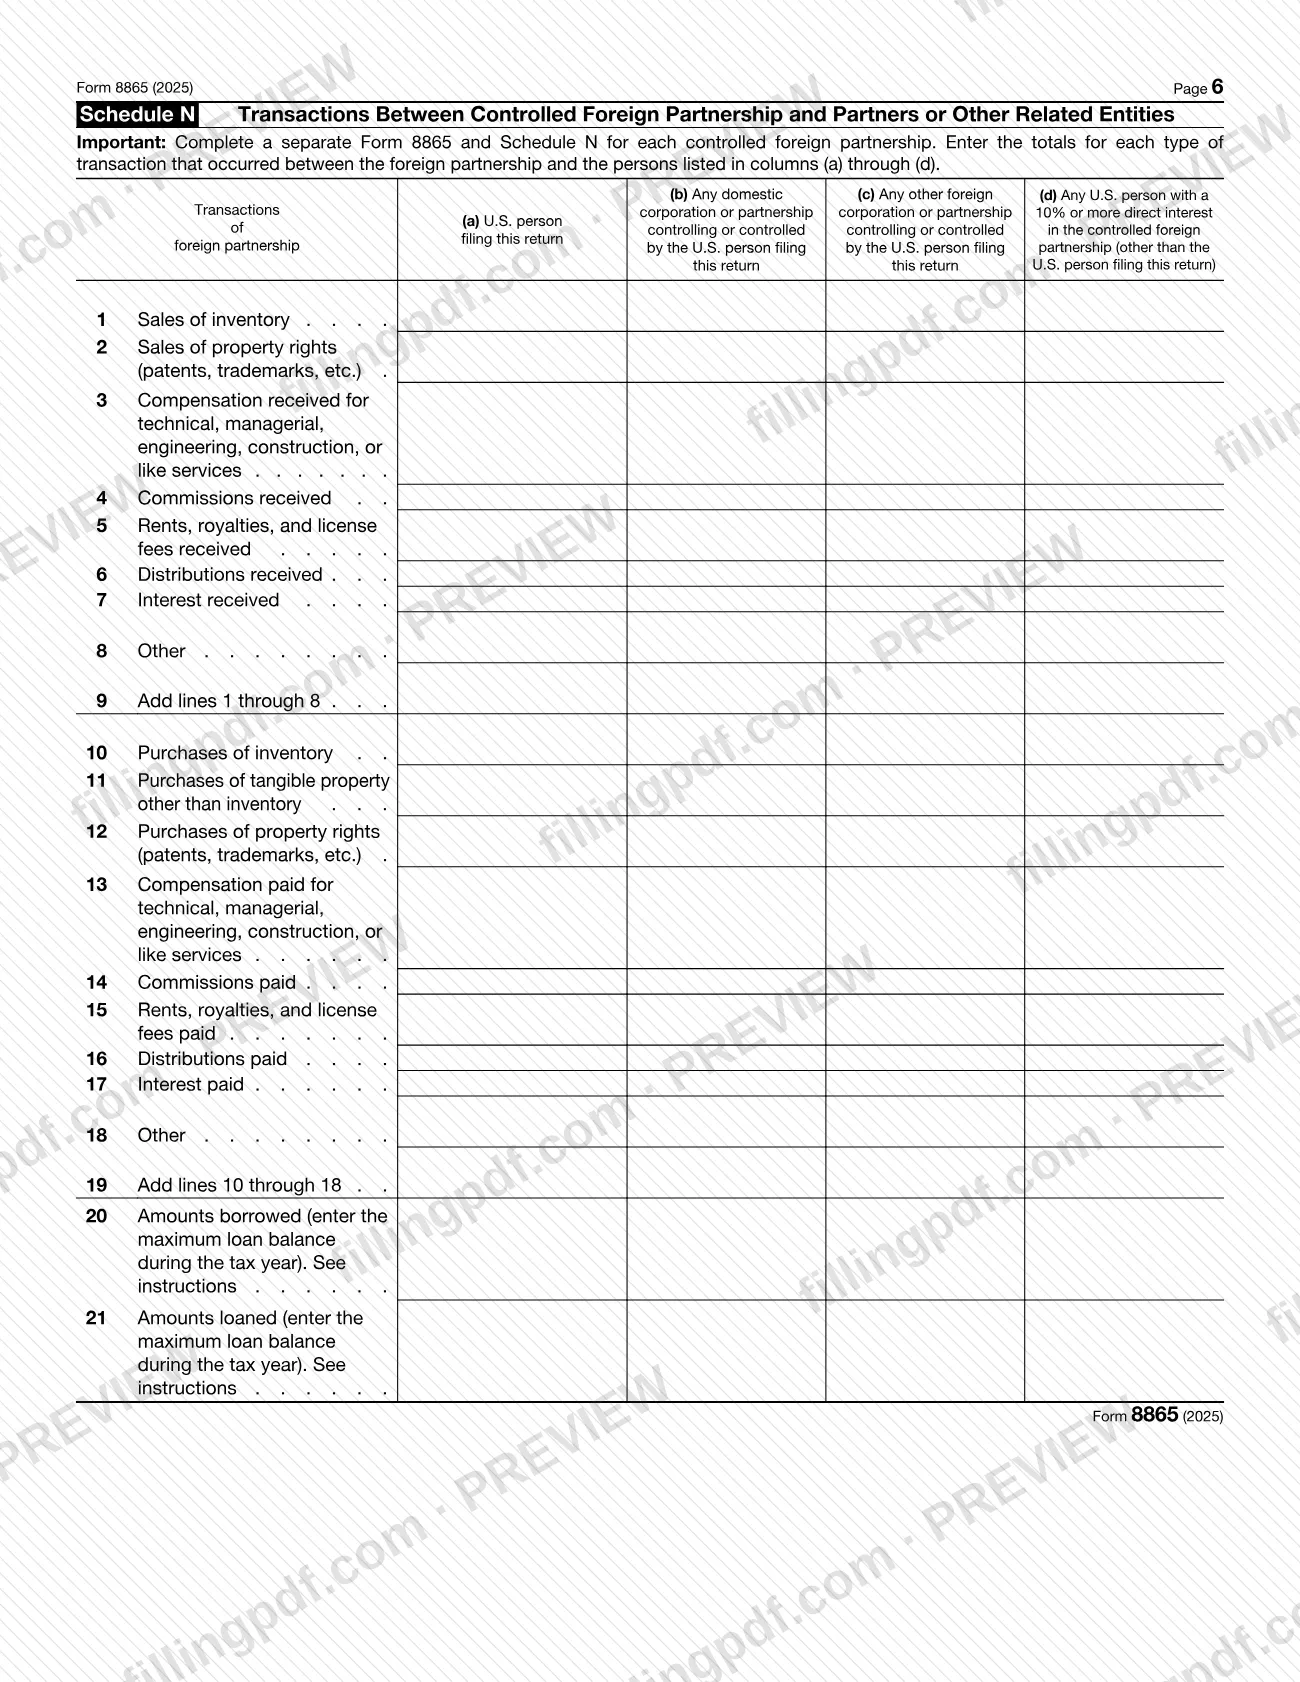
Form 8865 is the Internal Revenue Service (IRS) return on which a U.S. person reports a foreign partnership it controls, owns a 10% or greater interest in, contributes property to, or acquires or disposes of an interest in. It is attached to your income tax return, and a separate Form 8865 is completed for each foreign partnership. On this page you can fill out Form 8865 online on FillingPDF and download or print the completed PDF; the form and its instructions are published by the IRS at www.irs.gov/Form8865.
Last updated
What is Form 8865?
Form 8865, Return of U.S. Persons With Respect to Certain Foreign Partnerships, is the IRS form a U.S. person uses to report information about a foreign partnership required under sections 6038, 6038B and 6046A of the Internal Revenue Code. It is issued under OMB No. 1545-0123.
The three code sections cover different events. Section 6038 is reporting with respect to controlled foreign partnerships, section 6038B is reporting of transfers to foreign partnerships, and section 6046A is reporting of acquisitions, dispositions and changes in foreign partnership interests.
What you complete depends on your Category of Filer (1 through 4), which you check at item A on page 1. The IRS instructions contain a Filing Requirements for Categories of Filers chart that lists which schedules each category submits. If you qualify under more than one category for the same partnership, you submit everything required for each of them.
The form has page 1 and 2 identifying items and questions, followed by Schedules A, A-1, A-2, A-3, B, K, L, M, M-1, M-2 and N. Other schedules (G, H, K-1, K-2, K-3, O and P) are separate attachments described in the instructions. Form 8865 is a return of the partner, not of the partnership itself, and it is not filed alone unless you have no income tax return to attach it to.
Who needs to file Form 8865?
A U.S. person who qualifies under one or more of the four Categories of Filers must complete and file Form 8865. A U.S. person is a citizen or resident of the United States, a domestic partnership, a domestic corporation, or an estate or trust that isn't foreign.
- Category 1: a U.S. person who controlled the foreign partnership (more than a 50% interest) at any time during its tax year.
- Category 2: a U.S. person who owned a 10% or greater interest while U.S. persons each owning at least 10% controlled the partnership. If the partnership had a Category 1 filer in that tax year, no one is a Category 2 filer.
- Category 3: a U.S. person who contributed property to a foreign partnership for an interest and either owned at least a 10% interest right afterward or contributed property above the value limit stated in the instructions.
- Category 4: a U.S. person with a reportable event under section 6046A (an acquisition, a disposition or a change in proportional interest).
The instructions list exceptions: only one of several Category 1 filers need file, certain constructive owners can file a "Controlled Foreign Partnership Reporting" statement instead, a common parent may file for a consolidated group, and trusts relating to state and local government employee retirement plans need not file.
When to file Form 8865
Attach Form 8865 to your income tax return (or partnership or exempt organization return, if that applies) and file both by the due date, including extensions, of that return. The 2025 Form 8865 goes with your income tax return for your tax year beginning in 2025.
If you don't have to file an income tax return, file Form 8865 separately with the IRS at the time and place you would have to file the return. In that case you also sign the form; a filer attaching it to a return does not sign it.
The tax year you report is the foreign partnership's tax year that ends with or within your own tax year (Category 1 and 2 filers). Category 3 and 4 filers report transactions during their own tax year on Schedules O and P. If you later find the form incomplete or incorrect, file a corrected Form 8865 with an amended return, write "corrected" at the top and attach a statement explaining the changes.
Documents you need
- Your income tax return, or the partnership or exempt organization return that applies; Form 8865 is attached to it, unless you file Form 8865 separately because you have no return to file.
- Form 8858 for each foreign disregarded entity the partnership is the tax owner of, or foreign branch it operates, when you are a Category 1 or 2 filer; enter the number attached at item H8a.
- Schedule K-1 (Form 8865) for each partner it must cover: Category 1 and 2 filers for their own direct interest, and Category 1 filers for each U.S. person directly owning a 10% or greater interest.
- Schedules K-2 and K-3 (Form 8865), when the partnership has items of international tax relevance; check the box on Schedule K, line 16.
- Schedule O (Form 8865) for Category 3 filers and Schedule P (Form 8865) for Category 4 filers, unless an exception in the instructions applies.
- Schedules G and H (Form 8865), when a section 721(c) partnership and the gain deferral method apply and the instructions call for them.
- Statement entitled "Controlled Foreign Partnership Reporting", attached to your income tax return, if you rely on the multiple Category 1 filers or constructive owners exception instead of filing Form 8865.
- A copy of the waiver of treaty benefits for the reportable section 721(c) property, if Schedule G, Part V, line 7a is answered "Yes".
- Schedule D (Form 1065) and a copy of Form 8832, only when the instructions require them for your situation, such as capital gains and losses of the partnership or a Form 8832 filed for the current tax year.
- Separate statements for information that exceeds the space on the form, in the same size and format as the printed form.
How to fill out Form 8865
Enter filer name and tax year
At the top, enter the foreign partnership's tax year that ended with or within your tax year (Category 1 and 2 filers). Then enter the name of the person filing and the filer's identification number: an EIN for partnerships, corporations, estates and trusts, or an SSN or other number for individuals.
Add your address if filing separately
Complete the Filer's address line only if you aren't filing this form with your tax return. Put the suite or unit number after the street address, and use a P.O. box only if the post office doesn't deliver to the street address.
Check your category at item A
Check the box for each Category of Filer (1, 2, 3 or 4) that describes you. If more than one applies, check all that apply.
Complete items B, C and D
Item B: your own tax year. Item C: your share of nonrecourse liabilities, qualified nonrecourse financing and other liabilities. Item D: the name, address and EIN of the common parent, only if you belong to a consolidated group but aren't the parent.
Answer items E and F if they apply
Check item E only if you also file Form 8938 and report excepted specified foreign financial assets on this form. Complete item F only if you report other persons under the multiple Category 1 filers or consolidated return exception.
Identify the foreign partnership at item G
Enter name and address (G1), EIN or reference ID number (G2a, G2b), country of organization (G3), date of organization (G4), principal place of business (G5), activity code (G6, G7), functional currency (G8a) and exchange rate (G8b).
Answer the item H questions
Provide the agent, books and records details, the Forms 1042, 8804 or 1065 the partnership must file, and answer H5 through H14. Only Category 1 and 2 filers complete H8, and only Category 1 filers answer H10 and H11.
Complete Schedules A, A-1, A-2 and A-3
All filers complete Schedule A (box a for a direct interest, box b for a constructive interest) and Schedule A-3. Schedule A-1 is for Category 1 filers and certain Category 3 filers; Schedule A-2 is required when item H6 is "Yes" and the instructions' gain deferral conditions are met.
Complete Schedules B, K, L, M-1 and M-2
Category 1 filers complete these using the instructions for the matching Form 1065 schedules; Schedule M reports balance sheets for interest allocation. Skip Schedules L, M-1 and M-2 if item H11 is "Yes".
Complete Schedule N
Category 1 filers report all transactions of the controlled foreign partnership; Category 2 filers complete columns (a), (b) and (c). Enter the largest outstanding loan balances on lines 20 and 21, not year-end balances.
Add the other schedules you need
Attach Schedule K-1, K-2 and K-3, Schedule O (Category 3), Schedule P (Category 4), Schedules G and H and Form 8858 where the instructions require them. Use attached statements if a section runs out of space.
Review, sign if required and download
Sign and date only if you are filing Form 8865 separately, adding the paid preparer section if applicable. Check each item, then download or print the completed PDF from FillingPDF and attach it to your tax return.
How to submit Form 8865
Form 8865 is submitted attached to your income tax return, or separately with the IRS if you have no return to file.
- With your return: attach the completed form and schedules to the income tax return (or partnership or exempt organization return) and file both by the return's due date, including extensions. If the return is filed electronically, the IRS instructions refer you to the electronic filing publications named in your return's instructions.
- Separately: if you aren't required to file a U.S. income tax return, file Form 8865 with the IRS at the time and place you would file that return. Sign the form and, if a paid preparer helped, complete the preparer section.
- Corrections: file a corrected Form 8865 with an amended return, marked "corrected" at the top with an explanatory statement.
The form prints no mailing address of its own; use the one for your return and see www.irs.gov/Form8865 for the latest information. Everything must be in English and amounts in U.S. dollars. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Completing one Form 8865 for several foreign partnerships; the instructions require a separate form and schedules for each foreign partnership.
- Checking only one category at item A when you qualify under more than one, and submitting only that category's schedules.
- Entering "FOREIGNUS" or "APPLIED FOR" in item G2(a) or G2(b), or leaving G2(b) blank when the partnership has no EIN.
- Reporting the exchange rate at item G8b as U.S. dollars per unit of foreign currency; it must be the units of foreign currency equal to one U.S. dollar, rounded to at least four places.
- Abbreviating the foreign country name or placing the city, state or province and country out of order in the foreign address.
- Signing the form, or completing the paid preparer section, when Form 8865 is attached to your income tax return; sign only when filing it separately.
- Answering items H10 and H11 when you aren't a Category 1 filer, or completing Schedules L, M-1 and M-2 after answering "Yes" to item H11.
- Reporting a foreign dollar amount or non-English text; all information must be in English and amounts in U.S. dollars.
- Filing the form late or incomplete, which can bring the penalties the instructions describe for Category 1 through 4 filers.
Frequently asked questions
What is Form 8865 used for?
Form 8865 is the IRS return a U.S. person uses to report a foreign partnership under sections 6038, 6038B and 6046A: control or ownership of 10% or more, contributions of property, and acquisitions, dispositions or changes in interest. What you complete depends on your Category of Filer.
Who has to file Form 8865?
A U.S. person who qualifies as a Category 1, 2, 3 or 4 filer must file. That covers controlling partners, 10% partners in a U.S.-controlled partnership, persons contributing property to a foreign partnership, and persons with a reportable acquisition, disposition or change in interest.
When is Form 8865 due?
File it with your income tax return by that return's due date, including extensions. If you don't have to file an income tax return, file Form 8865 separately with the IRS at the time and place you would file the return.
Do I sign Form 8865?
No, not when it is attached to your income tax return. Sign it, and complete the paid preparer section if applicable, only when you file Form 8865 separately because you aren't required to file a U.S. income tax return.
Do I need a separate Form 8865 for each foreign partnership?
Yes. The IRS instructions say to complete a separate Form 8865 and the applicable schedules for each foreign partnership. Schedule N also requires a separate form for each controlled foreign partnership.
What happens if I file Form 8865 late or incomplete?
Penalties can apply. The instructions describe penalties per foreign partnership and tax year for Category 1 and 2 filers, a reduction of foreign tax credits, penalties for Category 3 and 4 filers, and possible criminal penalties. Check the penalties section of the instructions.
Can I fill out Form 8865 online?
Yes. You can fill out the Form 8865 PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the form with the IRS; you submit it with your return or separately through IRS channels.
How do I correct a Form 8865 I already filed?
File a corrected Form 8865 with an amended tax return, following the instructions for the return you originally filed with. Write "corrected" at the top of the form and attach a statement identifying and explaining the changes.
Ready to fill out Form 8865?
Fill out Form 8865 now