
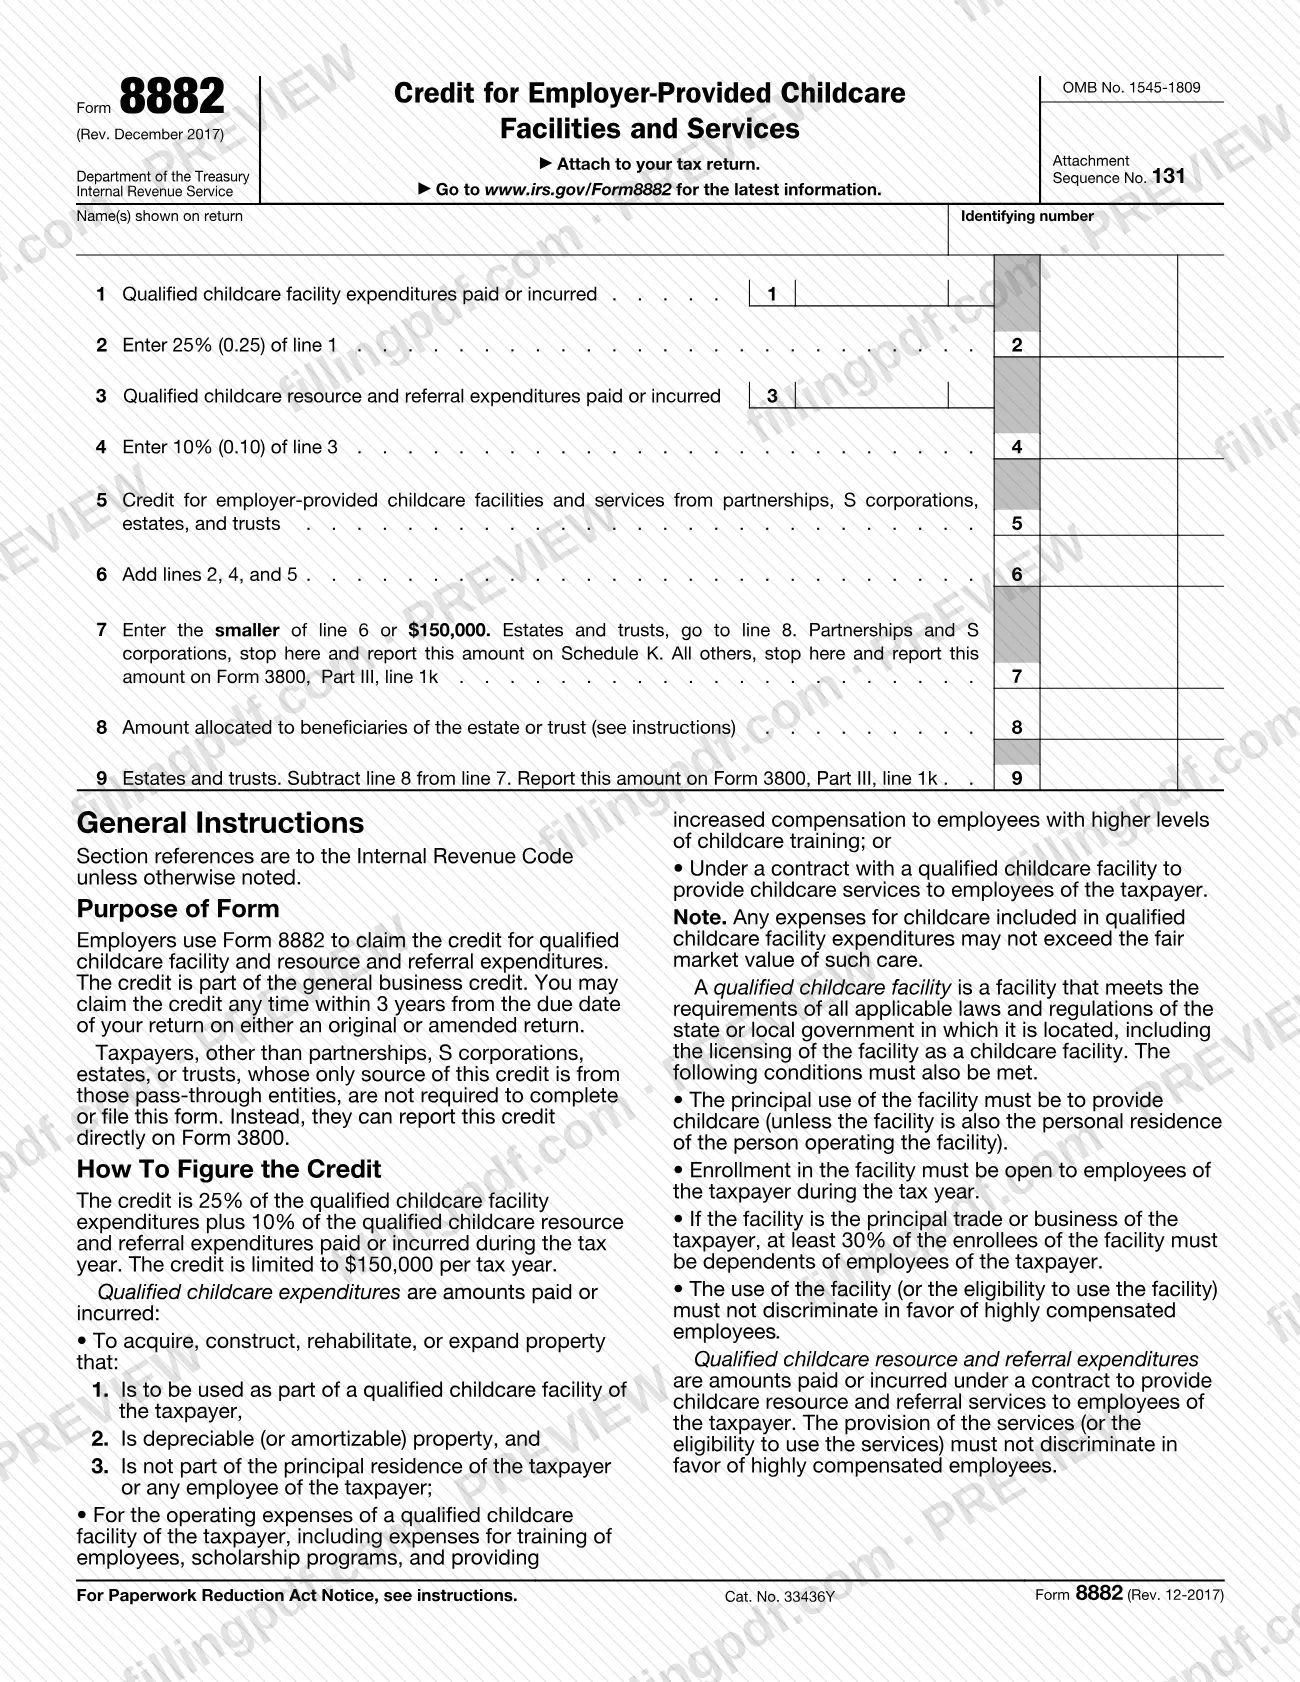
Form 8882 is the Internal Revenue Service (IRS) form that employers use to claim the credit for qualified childcare facility expenditures and qualified childcare resource and referral expenditures. The credit is part of the general business credit, and the form is attached to the filer's tax return. You can fill out Form 8882 online on FillingPDF and download or print the completed PDF; the IRS publishes the original form and the latest information at www.irs.gov/Form8882.
Last updated
What is 8882?
Form 8882, Credit for Employer-Provided Child Care Facilities and Services, is the IRS form on which employers claim the credit for qualified childcare facility expenditures and qualified childcare resource and referral expenditures. It is attached to the filer's tax return.
The credit is part of the general business credit. The form figures it in a short sequence: a percentage of qualified childcare facility expenditures (lines 1 and 2), a percentage of qualified resource and referral expenditures (lines 3 and 4), plus any credit passed through from partnerships, S corporations, estates and trusts (line 5). Line 6 adds these amounts, and line 7 limits the total to the per-year cap printed on the form. The result is reported on Schedule K (partnerships and S corporations) or on Form 3800, Part III, line 1k (everyone else).
The instructions printed with the form define the expenditures. Facility expenditures include amounts to acquire, construct, rehabilitate or expand depreciable property used in a qualified childcare facility, operating costs of that facility, and amounts paid under a contract with a qualified childcare facility. Resource and referral expenditures are amounts paid under a contract for childcare resource and referral services to employees.
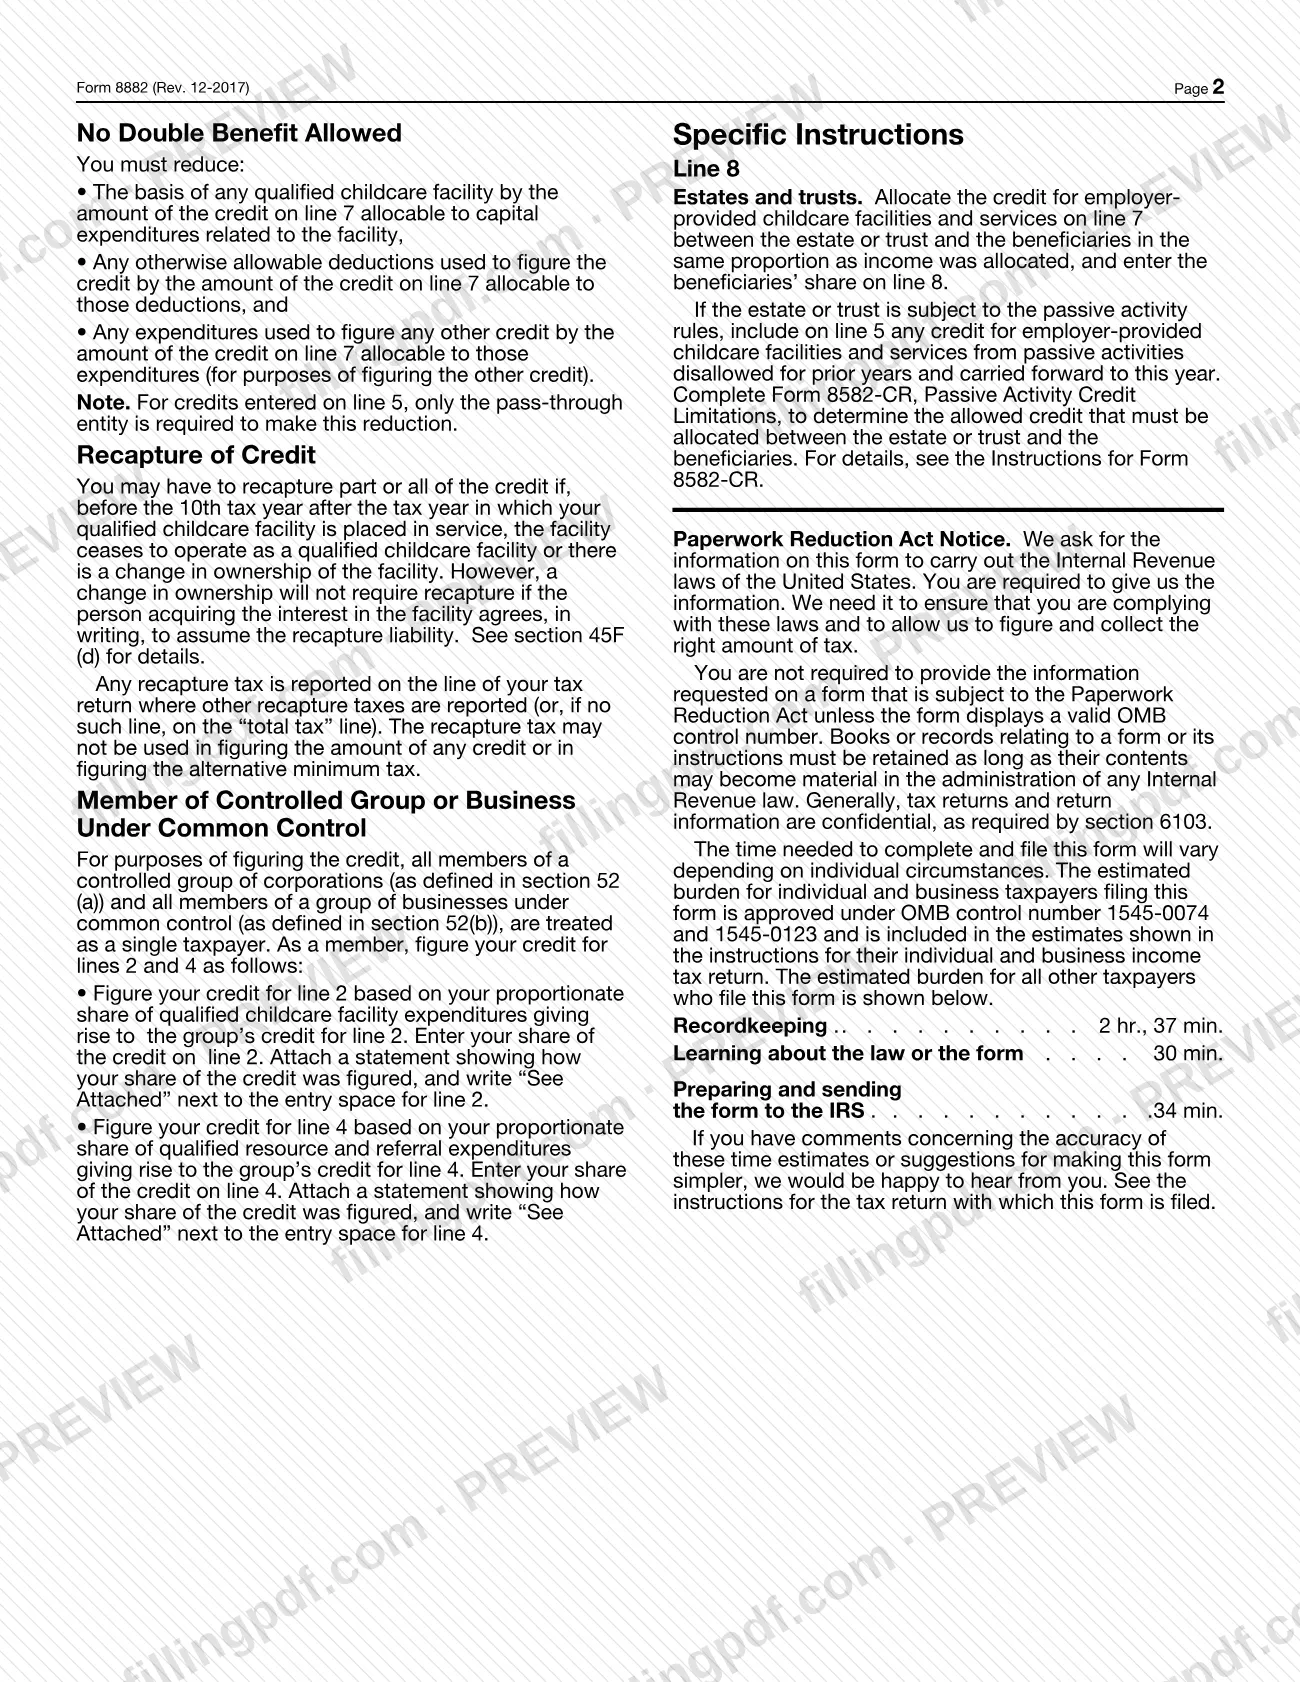
The form also covers reducing basis and deductions to avoid a double benefit, recapture of the credit, and the single-taxpayer rule for controlled groups and businesses under common control. It is the pass-through credit's source form: taxpayers whose only source of the credit is a pass-through entity report it directly on Form 3800 instead.
Who needs to file 8882?
Employers that pay or incur qualified childcare facility expenditures or qualified childcare resource and referral expenditures during the tax year use Form 8882 to claim the credit. Partnerships and S corporations complete it and report the result on Schedule K. Estates and trusts complete it through line 9, allocating part of the credit to beneficiaries on line 8.
Who does not need to file it: taxpayers other than partnerships, S corporations, estates or trusts whose only source of this credit is one of those pass-through entities are not required to complete or file the form. They report the credit directly on Form 3800.
Qualifying facilities and services must meet conditions in the instructions. A qualified childcare facility must meet the state or local requirements where it is located, including licensing. Enrollment must be open to the taxpayer's employees, and use of the facility, or of resource and referral services, must not discriminate in favor of highly compensated employees. If the facility is the taxpayer's principal trade or business, at least 30% of the enrollees must be dependents of employees.
Members of a controlled group of corporations or of businesses under common control are treated as a single taxpayer and figure their share as the instructions describe.
When to file 8882
Form 8882 is filed with the tax return on which you claim the credit, so it has no separate due date. The instructions allow you to claim the credit at any time within 3 years from the due date of your return, on either an original or an amended return.
Timing also matters after the credit is claimed. You may have to recapture part or all of the credit if, before the 10th tax year after the tax year in which your qualified childcare facility is placed in service, the facility ceases to operate as a qualified childcare facility or there is a change in ownership. A change in ownership does not require recapture if the person acquiring the interest agrees in writing to assume the recapture liability. See section 45F(d) for details.
Documents you need
- Your tax return, to which Form 8882 is attached; the credit is claimed with the return.
- For members of a controlled group or businesses under common control: a statement showing how your share of the credit on line 2 or line 4 was figured, with "See Attached" written next to that entry space.
- For estates and trusts subject to the passive activity rules: Form 8582-CR, Passive Activity Credit Limitations, to determine the allowed credit to allocate between the estate or trust and the beneficiaries.
- For a change in ownership of a facility: a written agreement by the person acquiring the interest to assume the recapture liability, if you want to avoid recapture.
How to fill out 8882
Enter your name and identifying number
At the top, enter the name(s) shown on your return and your identifying number.
Enter facility expenditures on lines 1 and 2
Line 1: qualified childcare facility expenditures paid or incurred during the tax year. Line 2: enter the percentage of line 1 that the form prints.
Enter referral expenditures on lines 3 and 4
Line 3: qualified childcare resource and referral expenditures paid or incurred. Line 4: enter the percentage of line 3 that the form prints.
Enter pass-through credits on line 5
Enter the credit for employer-provided childcare facilities and services received from partnerships, S corporations, estates and trusts. Estates and trusts under the passive activity rules include allowed prior-year carryforwards here.
Add lines 2, 4 and 5
Enter the total on line 6.
Apply the limit on line 7
Enter the smaller of line 6 or the dollar limit printed on line 7. Partnerships and S corporations stop and report this on Schedule K; all others except estates and trusts stop and report it on Form 3800, Part III, line 1k.
Allocate to beneficiaries on line 8
Estates and trusts only: allocate the line 7 credit between the estate or trust and its beneficiaries in the same proportion as income was allocated, and enter the beneficiaries' share on line 8.
Subtract on line 9
Estates and trusts only: subtract line 8 from line 7 and report the result on Form 3800, Part III, line 1k.
Add the controlled group statement
If you are a member of a controlled group or of businesses under common control, enter your proportionate share on line 2 or line 4, attach a statement showing how it was figured, and write "See Attached" next to that entry space.
Review and download the completed PDF
Check each line against the instructions, then download or print the completed PDF from FillingPDF and attach it to your tax return.
How to submit 8882
Form 8882 is not filed on its own: it is attached to your tax return and submitted through whatever channel you use for that return.
- Partnerships and S corporations: report the line 7 amount on Schedule K.
- All other filers except estates and trusts: report the line 7 amount on Form 3800, Part III, line 1k.
- Estates and trusts: complete lines 8 and 9, then report line 9 on Form 3800, Part III, line 1k.
- Controlled group members: attach a statement showing how your share of the credit was figured on line 2 or line 4 and write "See Attached" next to that entry space.
Any recapture tax is reported on the line of your tax return where other recapture taxes are reported or, if there is no such line, on the "total tax" line. The form prints no mailing address or portal of its own; use the instructions for the return it accompanies, and see www.irs.gov/Form8882 for the latest information. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Filing Form 8882 when your only source of the credit is a partnership, S corporation, estate or trust; those taxpayers report the credit directly on Form 3800.
- Reporting line 7 in the wrong place: partnerships and S corporations use Schedule K, estates and trusts go on to line 8, and all others use Form 3800, Part III, line 1k.
- Counting childcare expenses above the fair market value of the care; the form's note says they may not exceed it.
- Claiming expenditures for a facility that is not licensed or does not meet state or local requirements, or that is not open to the taxpayer's employees.
- Not reducing the facility's basis, the related deductions or the expenditures used for another credit by the line 7 credit amount, as the "No Double Benefit Allowed" rule requires.
- Forgetting recapture when the facility stops operating as a qualified childcare facility, or ownership changes, before the 10th tax year after it is placed in service.
- Entering a controlled group member's full credit instead of your proportionate share, or omitting the attached statement and "See Attached" note.
- Allocating the estate or trust credit to beneficiaries in a different proportion than income was allocated.
Frequently asked questions
What is Form 8882 used for?
Form 8882 is the IRS form employers use to claim the credit for qualified childcare facility expenditures and qualified childcare resource and referral expenditures. The credit is part of the general business credit and the form is attached to the filer's tax return.
Who has to file Form 8882?
Employers claiming the credit directly, plus partnerships, S corporations, estates and trusts that pass it through. Taxpayers whose only source of the credit is a partnership, S corporation, estate or trust are not required to file it and report the credit directly on Form 3800.
Where do I report the amount from line 7 of Form 8882?
Partnerships and S corporations report it on Schedule K. Estates and trusts go on to line 8 and report line 9 on Form 3800, Part III, line 1k. All other filers report line 7 on Form 3800, Part III, line 1k.
How long do I have to claim the employer-provided childcare credit?
You may claim the credit any time within 3 years from the due date of your return, on either an original or an amended return. The form sets no separate filing date because it travels with the tax return.
What is recapture of the childcare credit?
You may have to repay part or all of the credit if, before the 10th tax year after the facility is placed in service, it stops operating as a qualified childcare facility or ownership changes. A new owner who agrees in writing to assume the liability avoids recapture for that change.
Can a controlled group each claim its own credit on Form 8882?
No. All members of a controlled group of corporations or businesses under common control are treated as a single taxpayer. Each member figures its proportionate share for lines 2 and 4 and attaches a statement, writing "See Attached" next to the entry space.
Can I fill out Form 8882 online?
Yes. You can fill out the PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the form with the IRS; you attach it to your tax return and submit it through your return's channel.
Ready to fill out 8882?
Fill out 8882 now