
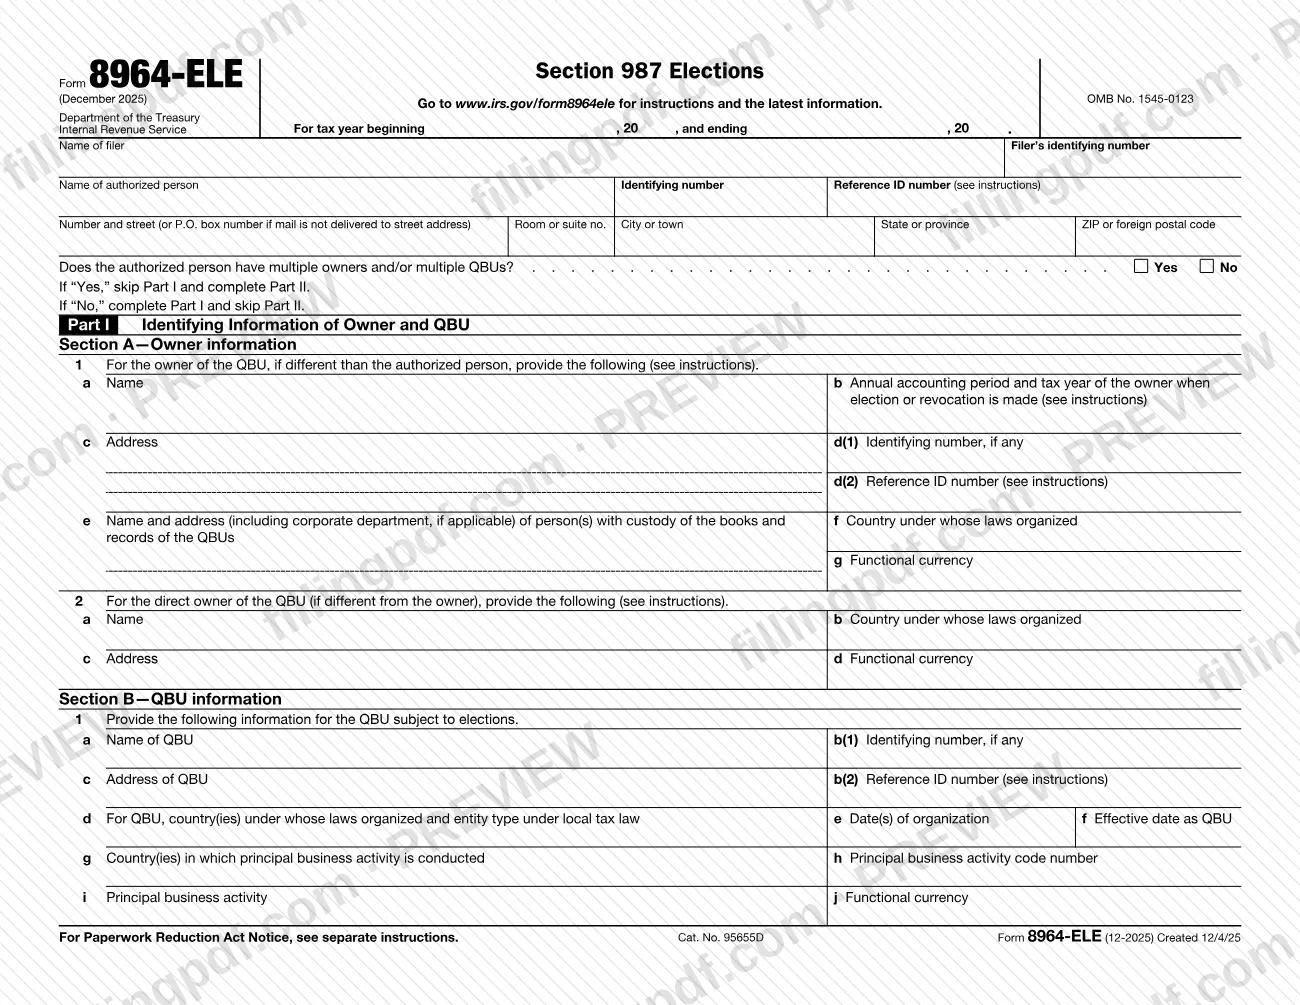
Form 8964-ELE, Section 987 Elections, is the Internal Revenue Service (IRS) form used to make or revoke elections under the section 987 regulations. The authorized person files it for the owner of a section 987 qualified business unit (QBU), normally attached to the original, timely filed return. On this page you can fill out the form online on FillingPDF and download or print the completed PDF; the IRS publishes the form and its instructions at www.irs.gov/form8964ele.
Last updated
What is Form 8964-ELE?
Form 8964-ELE, Section 987 Elections, is the IRS form used to make or revoke elections under the section 987 regulations and to satisfy the reporting requirements of Regulation section 1.987-1(g). It is issued by the Internal Revenue Service under OMB No. 1545-0123.
Section 987 applies to any taxpayer that has a qualified business unit (QBU) with a functional currency other than the dollar. An authorized person files the form on behalf of the QBU owner, and an authorized person who files it according to the instructions is deemed to satisfy the statement requirement of Regulations section 1.987-1(g)(3)(i).
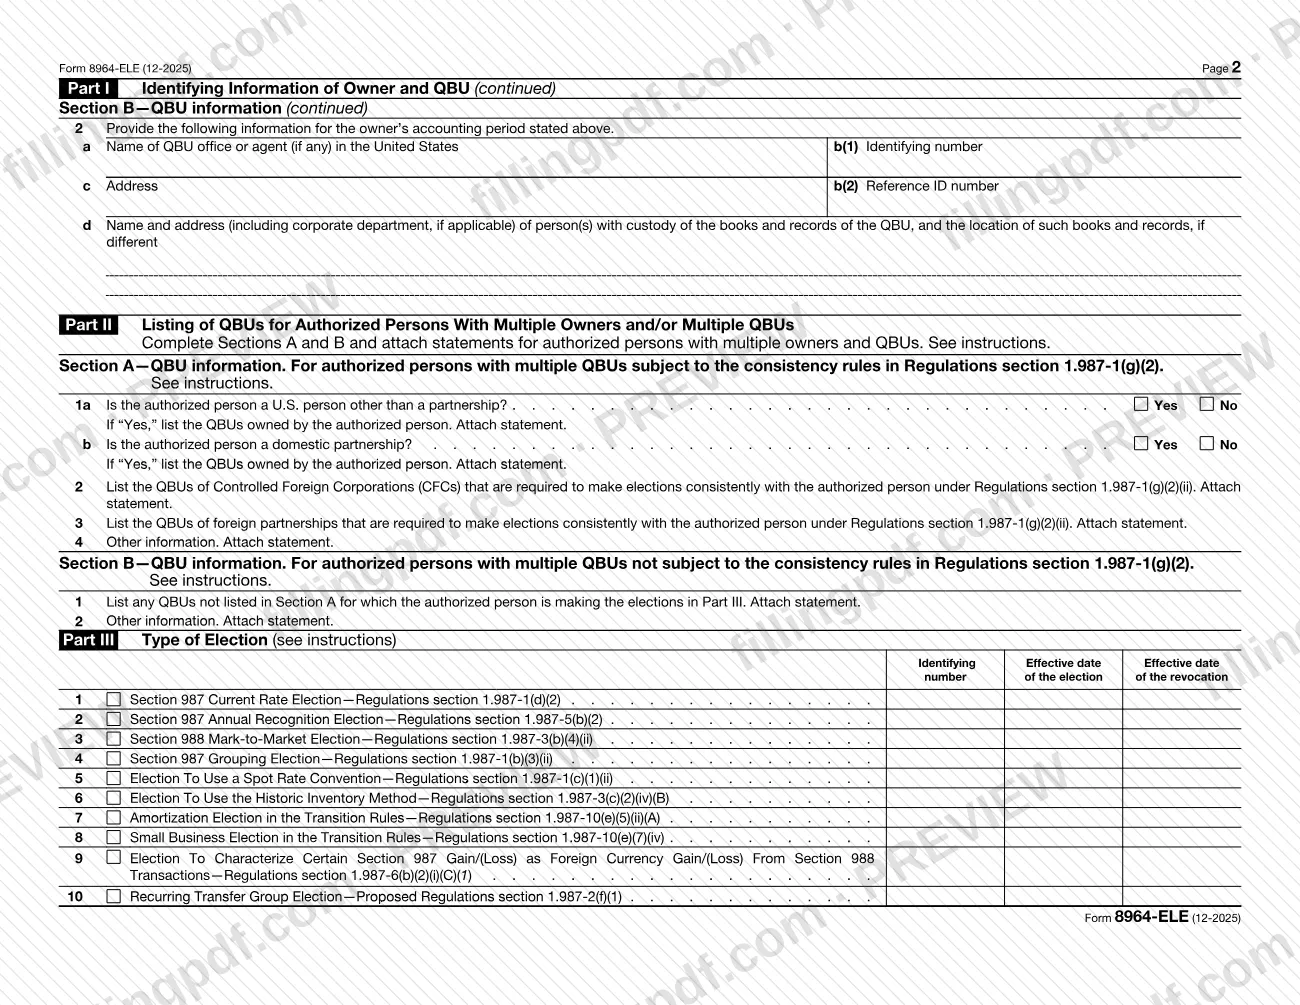
Part III lists the ten elections the form covers:
- Section 987 Current Rate Election
- Section 987 Annual Recognition Election
- Section 988 Mark-to-Market Election
- Section 987 Grouping Election
- Election To Use a Spot Rate Convention
- Election To Use the Historic Inventory Method
- Amortization Election in the Transition Rules
- Small Business Election in the Transition Rules
- Election To Characterize Certain Section 987 Gain/(Loss) as Foreign Currency Gain/(Loss) From Section 988 Transactions
- Recurring Transfer Group Election
Form 8964-ELE is not the transition-information form. An owner that must compute pretransition gain or loss files Form 8964-TRA, Section 987 Transition Information, separately. U.S. persons with foreign branches or foreign disregarded entities may also have to file Form 8858.
Who needs to file Form 8964-ELE?
The authorized person files Form 8964-ELE. A section 987 election is made or revoked for the owner of a section 987 QBU by the authorized person, who is defined by the type of owner:
- U.S. person owner: the owner is the authorized person.
- CFC owner: the controlling domestic shareholders of the controlled foreign corporation (CFC) are treated as the authorized person; if there are several, they act in concert.
- Member of a consolidated group: the common parent or another agent for the group makes the election.
- Partnership owner: the partnership makes or revokes the election.
The filer is typically the authorized person. If the filer is not the authorized person, the form also asks for the authorized person's name and identifying or reference ID number.
An authorized person acting for multiple QBU owners, or for an owner with multiple section 987 QBUs, checks Yes on the multiple owners question and completes Part II instead of Part I. Everyone else checks No and completes Part I.
Elections also reach related entities: all members of a consolidated group, and all members of a section 987 electing group, must make or revoke elections consistently. A corporation, partnership, trust, estate or disregarded entity is not itself a QBU, although its activities may be one.
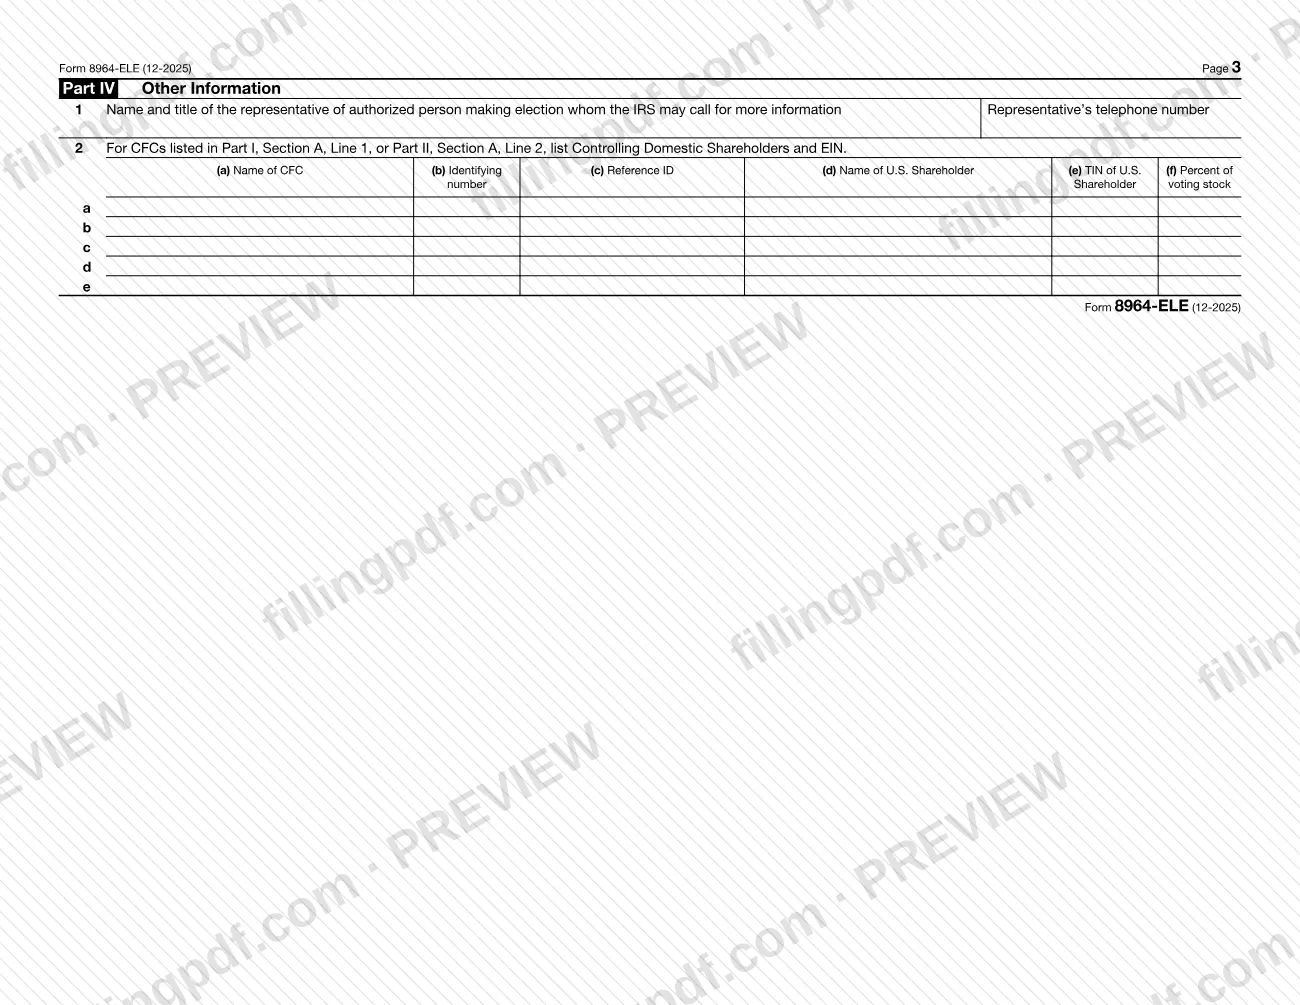
A representative with power of attorney who can respond to IRS inquiries is listed in Part IV, line 1; the instructions refer to Form 2848 for that authority.
When to file Form 8964-ELE
Attach Form 8964-ELE to the original, timely filed return (including extensions) for the tax year for which the elections are made. Additional requirements apply in later years and for some elections.
- First year the section 987 regulations apply to an owner, or the first year the owner (or a member of its consolidated group or section 987 electing group) owns a section 987 QBU: attaching the form to the timely filed return is all that is required.
- Subsequent years, current rate, annual recognition or section 988 mark-to-market election: file the form before the start of the tax year for which the election is made, by e-Fax, and also attach it to the timely filed return.
- Subsequent years, other elections: these can be made or revoked only with the Commissioner's consent, obtained through a private letter ruling; a copy of the ruling is attached to the form.
- Amortization and small business transition elections: these can be made only in the first year.
A current rate, annual recognition or section 988 mark-to-market election cannot be revoked without the Commissioner's consent for any taxable year beginning within 60 months of the first day of the year it was made. If you find the filed form incomplete or incorrect, file a corrected form with an amended return.
Documents you need
- Statements for Part II, Sections A and B: list the QBUs and owners the authorized person covers, including QBUs of CFCs and foreign partnerships, where the line says to attach a statement.
- A statement describing the spot rate convention, only if you are making the Election To Use a Spot Rate Convention (Part III, line 5).
- A copy of the private letter ruling granting the Commissioner's consent, only when you make or revoke an election in a subsequent year that requires consent.
- The IRS approval letter, only if you file a computer-generated Form 8964-ELE that deviates from the official form and schedules.
- A statement identifying the changes, with "Corrected" entered at the top of the form, only when you file a corrected form with an amended return.
- Additional sheets conforming to the IRS version of the section, only when the information exceeds the space provided in that section.
- A statement for Part IV, line 2, only if more space is needed to list the CFC's controlling domestic shareholders.
How to fill out Form 8964-ELE
Enter the tax year and period
At the top, complete the "For tax year beginning ... and ending ..." line with the annual accounting period of the person furnishing the information.
Enter the filer's details
Provide the name and identifying number of the person filing (an EIN or a reference ID number), plus the address. If the filer is a member of a consolidated group, list the common parent as filer.
Identify the authorized person
If the filer is not the authorized person, enter the authorized person's name, identifying number and reference ID number. Show any name used within the past 3 years in parentheses after the current name.
Answer the multiple owners question
Check Yes if the authorized person has multiple owners and/or multiple QBUs, and skip to Part II. Check No to complete Part I and skip Part II.
Complete Part I, Section A
On lines 1a to 1g, enter the QBU owner's details only if it differs from the authorized person; use the ISO 4217 three-character code for the functional currency on line 1g. Complete lines 2a to 2d only if the direct owner differs from the owner.
Complete Part I, Section B, line 1
Enter the QBU's name, identifying number, address, countries of organization with two-letter codes and entity type (or "branch"), dates, effective date as a QBU, principal business activity code (line 1h), description (line 1i) and functional currency (line 1j).
Enter the QBU's U.S. office or agent
On Section B, line 2, enter the name, identifying number and address of the QBU's U.S. office or agent, and the person with custody of the books and records and their location, if different.
Complete Part II if you checked Yes
Use Section A for QBUs subject to the consistency rules of Regulations section 1.987-1(g)(2) and Section B for QBUs that are not. Answer lines 1a and 1b and attach the statements the lines call for.
Check the elections in Part III
Check the box for each election you are making or revoking, and for any earlier election still in effect. Enter the EIN of the authorized person and the effective date of the election or of the revocation.
Complete Part IV
On line 1, enter the name, title and telephone number of the representative the IRS may call. If the authorized person elects for a CFC, list on line 2 the CFC and its controlling domestic shareholders with TIN and percent of voting stock.
Review, attach and download the PDF
Check the entries, add the required statements, and download or print the completed PDF from FillingPDF. Then submit it through the channels described under How to submit.
How to submit Form 8964-ELE
Form 8964-ELE goes to the IRS in two ways, depending on the election and the year: attached to a tax return, or sent by e-Fax before the tax year begins.
- Attached to the return: attach the form to the original, timely filed return (including extensions) for the tax year for which the elections are made, and file it with that return as the return's instructions direct.
- By e-Fax: for elections that must be filed before the start of the year (subsequent years after the first year the regulations apply), e-Fax the form to 833-312-2650 and file a copy with your timely filed return.
- Computer-generated forms: these generally need prior IRS approval. Send the request to [email protected] or mail it to Internal Revenue Service, Attention: Substitute Forms Program, C:DC:TS:CAR:MP:P:TP, 1111 Constitution Ave. NW, Room 6554, Washington, DC 20224. A computer-generated form that conforms to and does not deviate from the official form may be filed without prior approval, and no approval letter is attached. Otherwise attach the approval letter to the form.
- Corrections: file a corrected form with an amended return, following that return's instructions.
If a section needs more space than the form gives, complete every entry space and attach the remaining information on additional sheets that conform to the IRS version of that section. FillingPDF lets you fill out and download the PDF; submission follows the IRS channels above.
Common mistakes to avoid
- Entering "See attached" in a section and putting all the information on extra sheets; complete every entry space first and attach only the remainder.
- Entering "FOREIGNUS" or "APPLIED FOR" in a column that asks for an EIN or reference ID number; enter a reference ID number if no EIN is available.
- Using a reference ID number with spaces or special characters, longer than 50 characters, or different from the one used in earlier years.
- Filing a subsequent-year current rate, annual recognition or section 988 mark-to-market election only with the return, without e-Faxing it before the start of the tax year.
- Completing both Part I and Part II; check Yes and complete only Part II for multiple owners or QBUs, otherwise check No and complete only Part I.
- Abbreviating the country name on a foreign address, or entering the address in a different order than city, province or state, and country.
- Leaving out prior names when the filer, authorized person, CFCs or controlling domestic shareholders changed names within the past 3 years.
- Making or revoking a later-year election that needs the Commissioner's consent without attaching the private letter ruling.
- Filing a corrected form without "Corrected" at the top and a statement identifying the changes.
- Making the Election To Use a Spot Rate Convention without attaching a statement describing the convention.
Frequently asked questions
What is Form 8964-ELE used for?
Form 8964-ELE, Section 987 Elections, is used to make or revoke elections under the section 987 regulations. It also satisfies the reporting requirements of Regulation section 1.987-1(g). The authorized person files it on behalf of the owner of a section 987 QBU.
Who is the authorized person on Form 8964-ELE?
For a U.S. person owner, the owner. For a CFC, its controlling domestic shareholders acting in concert. For a consolidated group member, the common parent or another group agent. For a partnership owner, the partnership itself makes or revokes the election.
When is Form 8964-ELE due?
Attach it to the original, timely filed return, including extensions, for the tax year of the elections. In later years, a current rate, annual recognition or section 988 mark-to-market election must also be filed before the start of that tax year, by e-Fax.
Where do I e-Fax Form 8964-ELE?
Send it to 833-312-2650 when the election must be filed before the start of the tax year, which applies to subsequent years after the first year the section 987 regulations apply. You must also file a copy with your timely filed return.
Can I revoke a section 987 election?
Yes, but a current rate, annual recognition or section 988 mark-to-market election cannot be revoked without the Commissioner's consent for years beginning within 60 months of the first day of the year it was made. Other later-year elections also need consent, requested by private letter ruling.
How do I correct a Form 8964-ELE I already filed?
File a corrected Form 8964-ELE with an amended tax return, following the amended return instructions for the return you first filed it with. Write "Corrected" at the top of the form and attach a statement identifying the changes.
What is the difference between Form 8964-ELE and Form 8964-TRA?
Form 8964-ELE makes or revokes section 987 elections. Form 8964-TRA, Section 987 Transition Information, is a separate form an owner files to compute pretransition gain or loss for each QBU under Regulations section 1.987-10(e).
Can I fill out Form 8964-ELE online and file it through FillingPDF?
You can fill out the fillable PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file or send the form; you submit it to the IRS by attaching it to the return or by e-Fax, as the instructions direct.
Ready to fill out Form 8964-ELE?
Fill out Form 8964-ELE now