
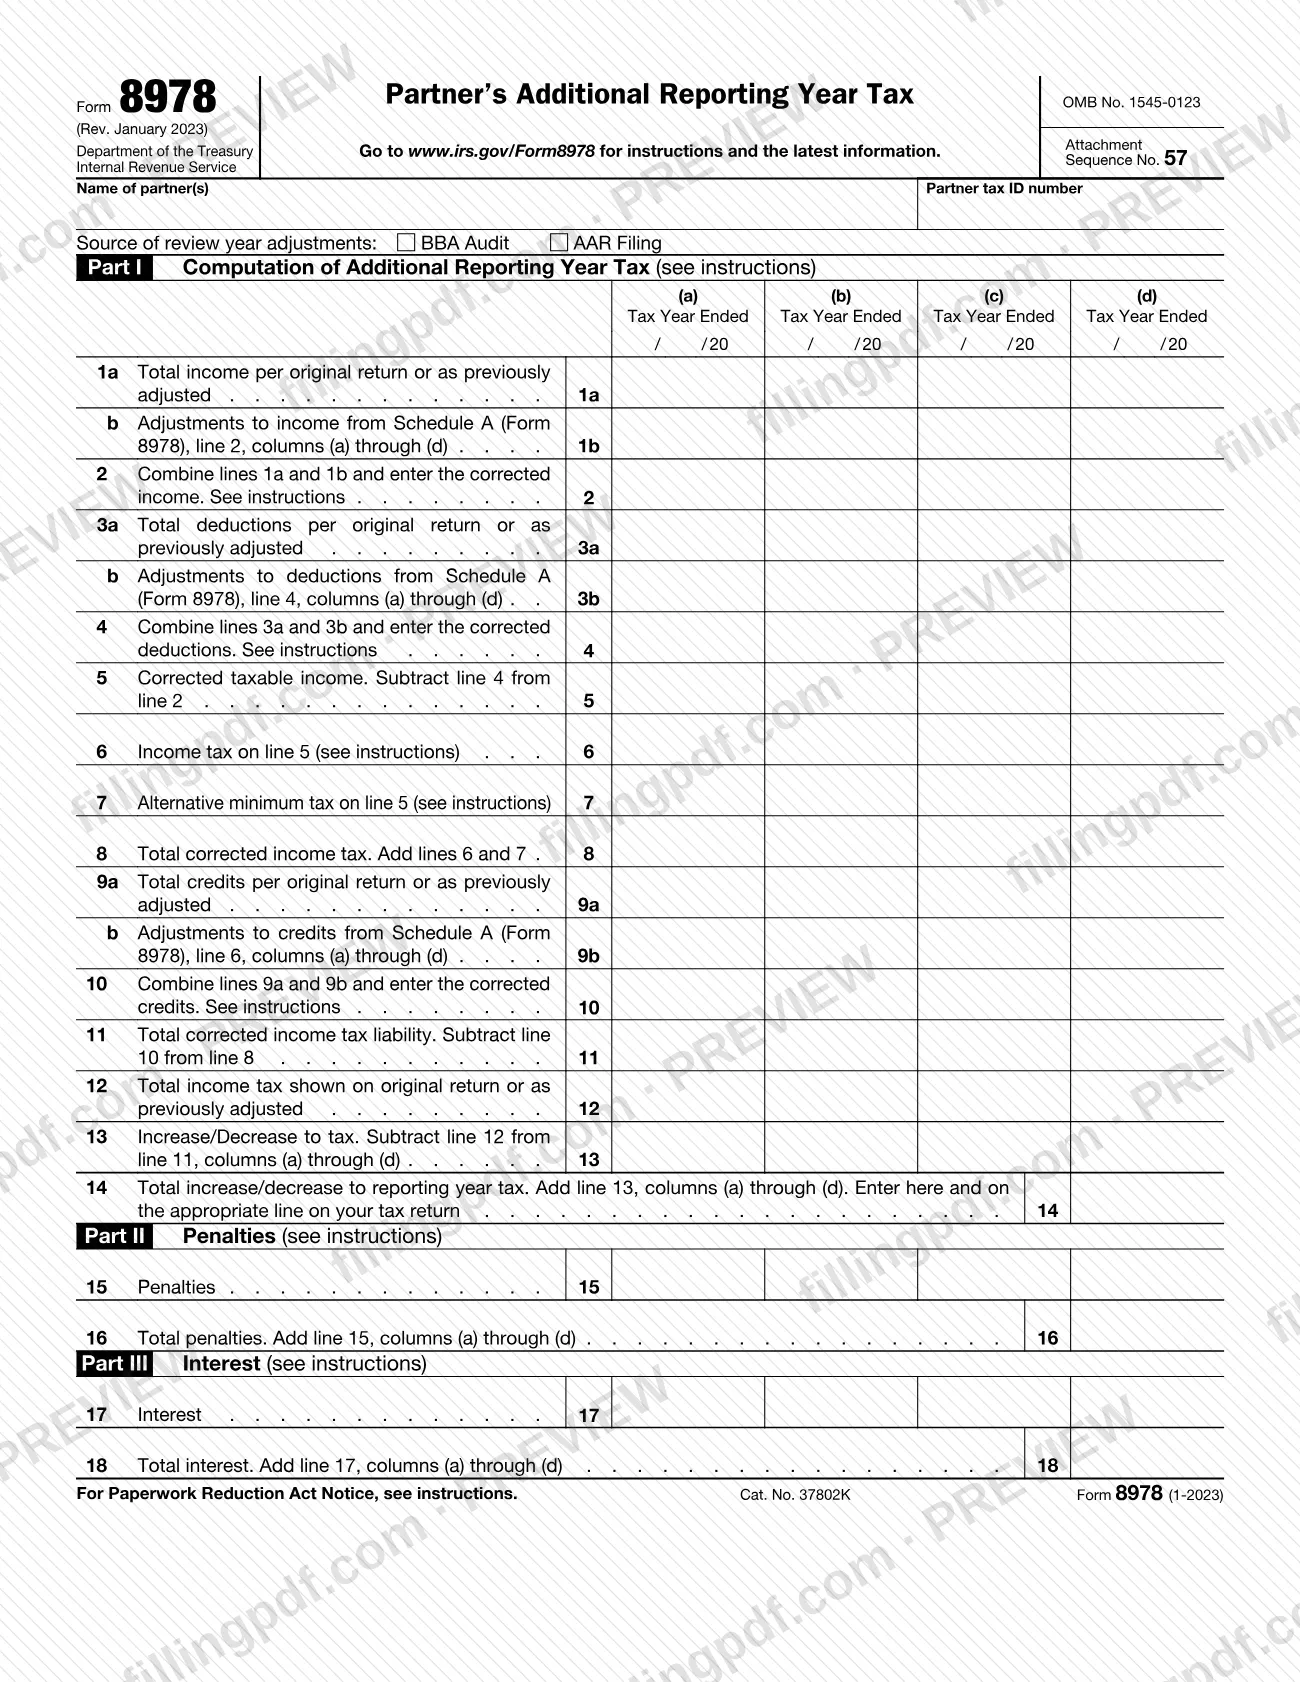
Form 8978, Partner's Additional Reporting Year Tax, is the Internal Revenue Service (IRS) form on which a partner figures the change in income tax caused by adjustments a partnership pushed out on Form 8986. It is used by partners that are not pass-through partners, together with Schedule A (Form 8978), and it is attached to the partner's income tax return for the reporting year. On FillingPDF you can fill out the form online and download or print the completed PDF; the IRS publishes the original PDF and the instructions at irs.gov.
Last updated
What is 8978?
Form 8978, Partner's Additional Reporting Year Tax, is the IRS form a partner uses to calculate the additional tax, penalties and interest that result from adjustments shown on Form 8986, which a partnership sends after a BBA audit or an administrative adjustment request (AAR).
The form belongs to the centralized partnership audit regime of the Bipartisan Budget Act of 2015 (BBA). When a partnership elects under section 6226 to push adjustments out to its partners, each partner receives Form 8986 and uses Form 8978 to re-figure tax for the first affected year and any intervening years. The total change is then carried to the partner's reporting year return as an increase or decrease to tax, so the partner does not file a refund claim.
The form has three parts: Part I computes the additional reporting year tax in up to four tax-year columns (a) through (d), Part II reports penalties and Part III reports interest. Schedule A (Form 8978), which is part of the same instructions, lists the adjustments from Form 8986 and the related changes to partner-level tax attributes, and its totals feed lines 1b, 3b and 9b.
Form 8978 is only for changes to income tax. Non-income tax changes, such as self-employment tax, go on an amended return for the partner's first affected year.
Who needs to file 8978?
Every partner, except a pass-through partner, that receives a Form 8986 from a pass-through entity must file Form 8978 to report any additional reporting year tax from its share of the reviewed year adjustments. Reviewed year partners and affected partners both file it with their federal income tax return for the reporting year.
Specific situations the IRS instructions address:
- Partners other than pass-through partners, such as individuals and corporations, use Form 8978 and Schedule A (Form 8978).
- An entity such as a trust or estate can be both a taxable partner and a pass-through partner. It uses Form 8978 for items taxable at the entity level and follows the Forms 8985 and 8986 instructions for items that pass through to its owners or beneficiaries.
- Foreign corporate partners complete separate Forms 8978 and Schedules A for effectively connected income (ECI) and for fixed, determinable, annual, periodical (FDAP) income.
- A partner with adjustments from both a BBA audit and an AAR files separate forms for each source.
Pass-through partners, meaning partnerships required to file under section 6031(a), S corporations, most trusts and decedents' estates, do not use Form 8978 for pass-through items.
When to file 8978
File Form 8978 with the federal income tax return for your reporting year, which is the tax year that includes the date the audited or AAR partnership furnished Form 8986 to its partners. That date is on Form 8986, Part II, item G.
The IRS instructions give an example: if the partnership furnished Forms 8986 on March 1, 2024, the reporting year for a calendar-year partner is 2024, and the completed Form 8978 is attached to the return due April 15, 2025, without regard to extensions. If you hold interest through a pass-through partner that passes the forms down later, your reporting year is still the year that includes the date the forms were furnished to you by the partner you hold interest through.
The form has no separate due date: it travels with the income tax return. Interest on an increase in tax runs from the original due date of the return for each affected tax year.
Documents you need
- Schedule A (Form 8978): lists the Form 8986 adjustments to income, deductions and credits; its totals on lines 2, 4 and 6 carry to Form 8978 lines 1b, 3b and 9b. Include one for each Form 8978.
- A statement showing how corrected income tax was figured, supporting line 6, and how corrected AMT was figured, supporting line 7 if AMT applies.
- A separate statement for line 5 or line 11 only if corrected taxable income or corrected tax liability differs from the result of the subtraction shown on the form.
- A statement showing how penalties were figured, if Form 8986, Part V, shows applicable penalties and you enter an amount on line 15.
- Your interest computation for line 17, when interest applies to an increase in tax.
- For foreign corporate partners: a statement on each ECI Form 8978 and FDAP Form 8978 explaining how the line 13 income tax adjustments were calculated.
- Optional: Forms 3800 labeled "Form 3800 for Form 8978 Calculation Only" to support first affected year or intervening year calculations.
- If you made an IRC 6603 deposit: a statement asking that it be applied to the underpayment, with deposit dates and amounts, the partnership's name and TIN, the reviewed year and its Audit Control Number.
How to fill out 8978
Identify the partner and adjustment source
Enter the name of the partner(s) and the partner tax ID number at the top. Check BBA Audit or AAR Filing as the source of the review year adjustments; for AAR, also enter the employer identification number of the entity that issued Form 8986.
Enter the tax years in columns
In columns (a) through (d), enter the tax year ended date (MM/DD/20YY) for the first affected year and each impacted intervening year. Years that were not impacted need not be shown.
Complete income, lines 1a through 2
Line 1a is total income per the original or amended return or as adjusted by the IRS; line 1b is Schedule A, line 2. Line 2 is the sum of 1a and 1b. Enter negative amounts in parentheses.
Complete deductions, lines 3a through 4
Line 3a is total deductions per the return or as previously adjusted; line 3b is Schedule A, line 4. Line 4 combines 3a and 3b.
Figure taxable income and tax
Line 5 is line 2 minus line 4. Enter income tax on line 6 and AMT on line 7, each supported by a separate statement, and add them on line 8.
Complete credits, lines 9a through 11
Line 9a is total credits per the return or as previously adjusted; line 9b is Schedule A, line 6. Line 10 combines them, and line 11 is line 8 minus line 10, without non-income taxes.
Find the change in tax
Enter on line 12 the total tax shown on the return or as previously adjusted. Line 13 is line 11 minus line 12 for each column, and line 14 is the sum of line 13, columns (a) through (d).
Report penalties in Part II
If Form 8986, Part V, lists applicable penalties, enter the amount for each tax year on line 15 and attach a statement of how they were figured. Add the columns on line 16.
Report interest in Part III
Enter interest on increases in tax for each applicable year on line 17, with your interest computation attached, and total the columns on line 18. Do not figure interest on decreases.
Complete Schedule A (Form 8978)
List each Form 8986, Part V adjustment under lines 1, 3 and 5 with its description and tracking number, then enter the totals on lines 2, 4 and 6. Include any inconsistent-position amounts.
Review, sign off and download the PDF
Check that each column matches its tax year, the totals carry between Schedule A and Form 8978, and statements are ready. Download or print the completed PDF from FillingPDF and attach it to your return as described under How to submit.
How to submit 8978
Form 8978 is not filed on its own: you attach it, with Schedule A (Form 8978) and your calculation statements, to your federal income tax return for the reporting year and send the return through the channels that return uses.
- Attach to the return. Put Form 8978, each Schedule A and the statements behind lines 5, 6, 7, 11, 15 and 17 with the return. Follow the instructions for the applicable income tax return (for example, Form 1040) to find the line where the total from line 14 is entered.
- Pay with the return. Additional penalties and interest are not reported on the return and are not part of line 14, but the IRS instructions say to include them in the net payment calculation for the reporting year.
- Withholding. If the partnership or a pass-through partner withheld on your additional reporting year tax and sent Form 1042-S or Form 8805, you may claim the withholding credit on your income tax return.
- Interest deposits. If you made a deposit under IRC 6603 to suspend interest, attach a statement asking that it be applied to the underpayment, with the deposit dates and amounts, the partnership's name and TIN, the reviewed year and the Audit Control Number.
The form prints no separate mailing address. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Reporting adjustments from a BBA audit and from an AAR on the same Form 8978; each source type needs its own Form 8978 and Schedule A, with the AAR Filing or BBA Audit box checked.
- Using one Form 8978 for more than four applicable tax years; the form and schedule hold four columns, so additional forms are needed.
- Using Form 8978 for non-income tax changes such as self-employment tax, which belong on an amended return for the first affected year.
- Reporting changes to credits from the pushout statement on Form 3800 as well, which duplicates them; only Forms 3800 labeled for calculation support are allowed.
- Entering amounts without a statement showing how line 6 income tax and line 7 AMT were figured.
- Calculating interest on a decrease in tax on line 13; interest is figured only on increases.
- Leaving the tracking number blank for a Form 8986 adjustment instead of using the number at the top of Form 8986, the audit control number or the issuing entity's TIN.
- Entering unmodified amounts instead of the Form 8986, Part V, column (h) amounts, which reflect adjustments net of approved modifications.
- Reporting penalties and interest on the return line for line 14; they go into the payment calculation but not into the additional reporting year tax.
Frequently asked questions
What is Form 8978 used for?
Form 8978 is the IRS form a partner uses to figure additional reporting year tax, penalties and interest from adjustments shown on Form 8986. The partnership pushes those adjustments out after a BBA audit or an AAR, and the total on line 14 goes on the partner's income tax return.
Who has to file Form 8978?
Every partner that receives a Form 8986 from a pass-through entity, other than a pass-through partner, must file it. Pass-through partners such as partnerships, S corporations, most trusts and estates follow the Forms 8985 and 8986 instructions for items that pass through.
When is Form 8978 due?
It is due with your income tax return for the reporting year, the tax year that includes the date the partnership furnished Form 8986. The IRS example uses a calendar-year partner furnished on March 1, 2024, who attaches it to the 2024 return due April 15, 2025.
Where do I send Form 8978?
You do not send it separately. Attach Form 8978, Schedule A and your statements to your federal income tax return for the reporting year and file the return as its instructions direct. The form prints no mailing address of its own.
Do I need a separate Form 8978 for an AAR and for an audit?
Yes. If you have adjustments from both a BBA audit and an AAR, complete the AAR Form 8978 and Schedule A first, then a separate set for the audit. Add line 14 from each form and report the sum on your return.
What is the difference between Form 8978 and Form 8986?
Form 8986 is the statement the partnership furnishes to a partner showing the pushed-out adjustments. Form 8978 is what the partner completes to turn those adjustments into additional reporting year tax, with Schedule A listing the adjustments.
Can I fill out Form 8978 online?
You can fill out the PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the form with the IRS; you attach it to your return and submit that return through the IRS channels.
What if I have more than four tax years of adjustments?
Prepare additional Forms 8978, each with all lines completed and its own Schedule A. Add the line 14 amounts from all of them and report the total on the appropriate line of your return.
Ready to fill out 8978?
Fill out 8978 now