
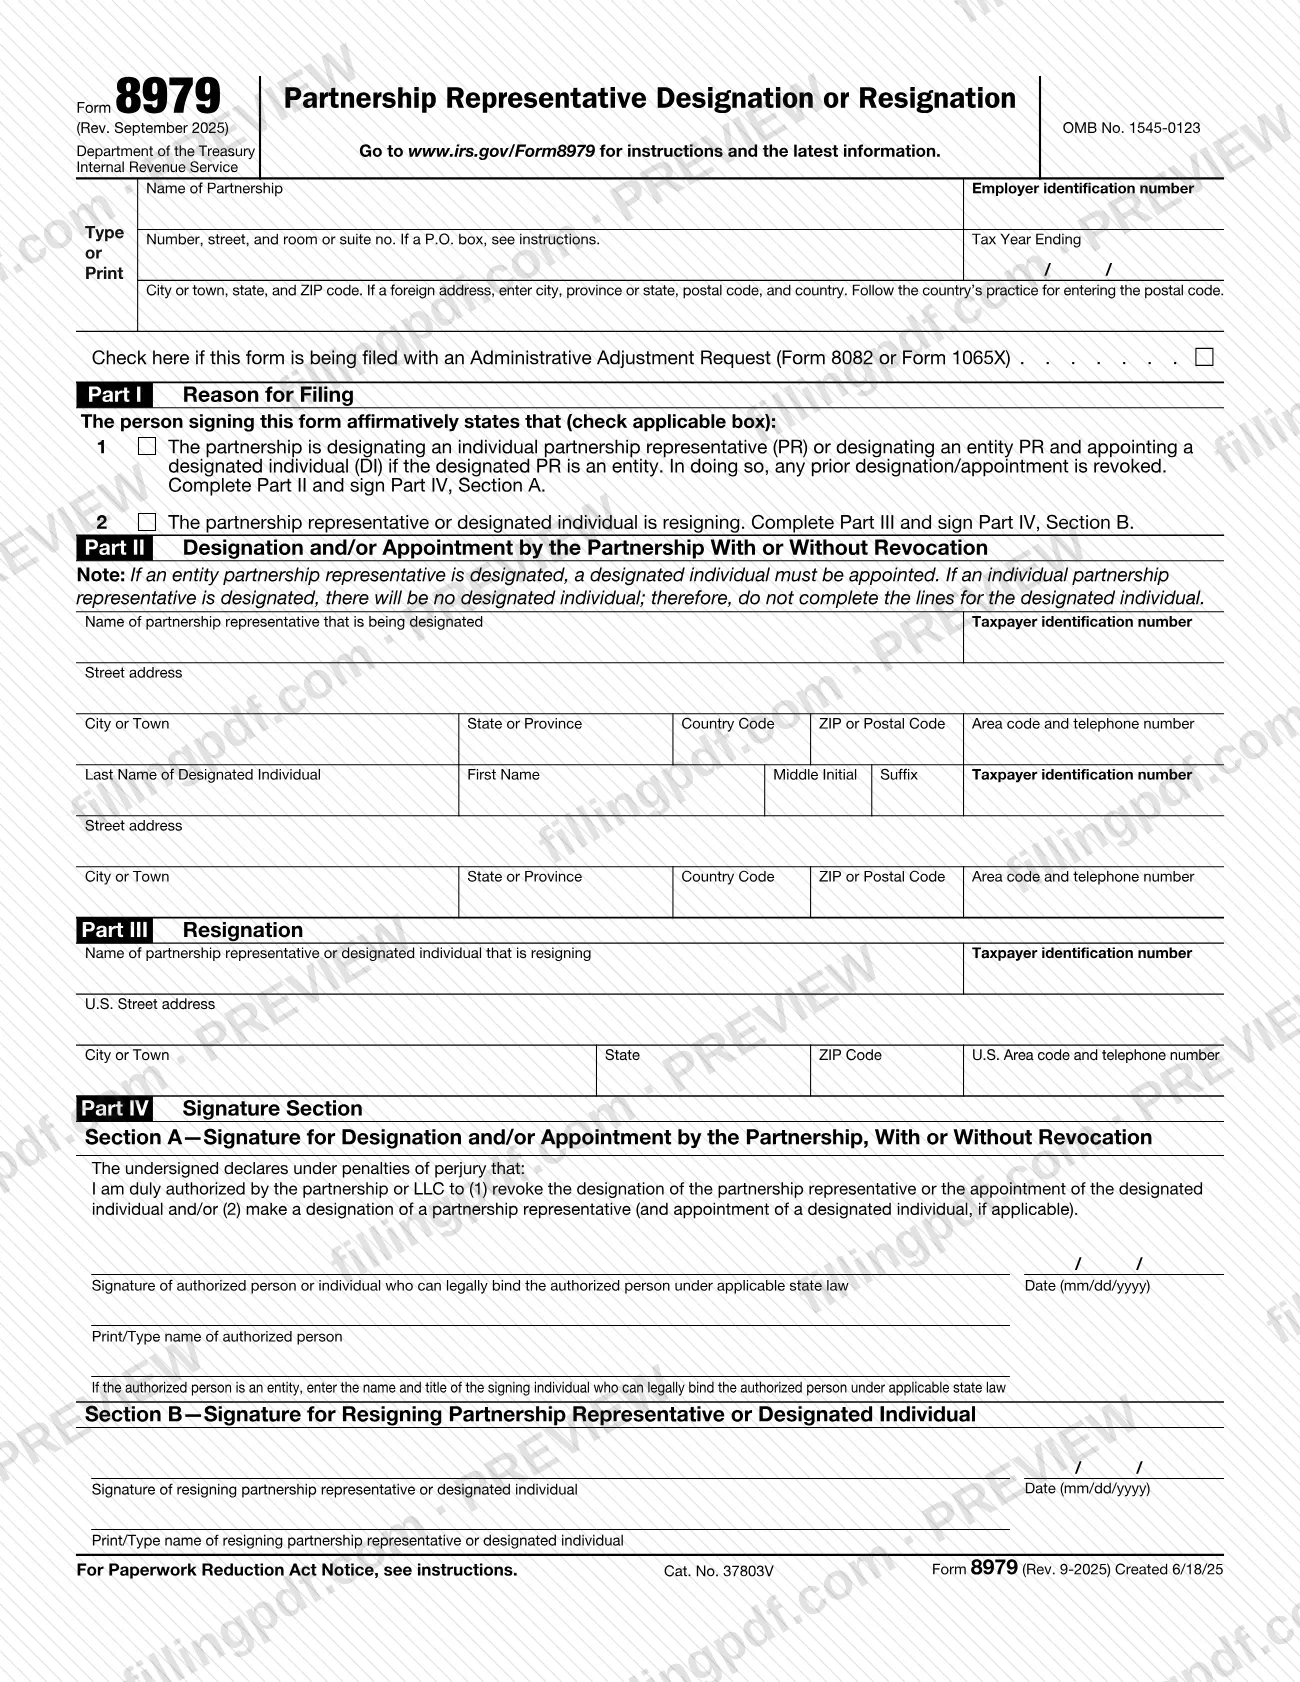
Form 8979, Partnership Representative Designation or Resignation, is the Internal Revenue Service (IRS) form a partnership uses to name its partnership representative (PR), and to appoint a designated individual (DI) when the PR is an entity. A PR or DI who wants to step down uses the same form to resign. On this page you can fill out the form online on FillingPDF and download or print the completed PDF. The IRS publishes the form and its instructions at www.irs.gov/Form8979.
Last updated
What is Form 8979?
Form 8979, Partnership Representative Designation or Resignation, is the IRS form on which a partnership designates its partnership representative (PR) and appoints a designated individual (DI) if the PR is an entity, and on which a PR or DI resigns.
A partnership may designate any person as PR, including an entity or the partnership itself. If the PR is an entity, the partnership must appoint a DI to act for it. Both the PR and the DI must have substantial presence in the United States. At any time during a partnership tax year there can be only one designated PR, and a valid new designation automatically revokes the existing PR designation and DI appointment.
The form has four parts:
- Part I, Reason for Filing: line 1 to designate or appoint, line 2 to resign.
- Part II, designation and appointment by the partnership.
- Part III, resignation.
- Part IV, signatures: Section A for the partnership's authorized person, Section B for the resigning PR or DI.
The September 2025 revision retitles the form. It was previously called "Partnership Representative Revocation, Designation, and Resignation," and Parts I to IV were cut down to the two-way structure above.
Form 8979 does not appoint a power of attorney. A new PR for a BBA partnership that wants to appoint a person as power of attorney must submit Form 2848. It also does not change an address on file with the IRS.
Who needs to file Form 8979?
Partnerships file Form 8979, through an authorized person, to designate a PR and appoint a DI if the PR is an entity. The same applies when no PR designation is in effect, including because the partnership did not designate a PR on its originally filed Form 1065. An authorized person is someone who was a partner at any time during the partnership tax year to which the designation or revocation relates. If the authorized person is an entity, the individual who signs must be able to legally bind it under applicable state law.
A partnership representative or designated individual files the form to resign.
Rules that affect who can be named:
- The PR, and the DI if the PR is an entity, must have substantial presence in the United States. That means being available to meet the IRS in person at a reasonable time and place, having a U.S. taxpayer identification number (TIN), and having a U.S. street address and a telephone number with a U.S. area code.
- A BBA partnership is one subject to the centralized partnership audit regime of the Bipartisan Budget Act of 2015. Partnerships with tax years beginning after 2017 are BBA partnerships unless they validly elect out.
Do not use Form 8979 to change your last known address with the IRS; the instructions point to Form 8822 or Form 8822-B for that.
When to file Form 8979
File Form 8979 only in the situations the IRS instructions list. A partnership may submit it:
- directly to the current IRS employee point of contact after Letter 2205-D, Letter 5893 or Letter 5893-A has been issued;
- with an administrative adjustment request (AAR) filed for a reason other than only making a designation, before any of those letters is issued;
- with a Form 8985 submitted by a pass-through partnership that has not elected out of the BBA, or with Form 8988;
- any time a BBA partnership makes a request of the IRS that requires it to extend a statute.
When a PR or DI resigns, the form goes directly to the current IRS employee point of contact after Letter 2205-D, Letter 5893 or Letter 5893-A has been issued.
If the IRS notifies the partnership that no designation is in effect, the partnership has 30 days from the date the IRS mails the notice to submit Form 8979. If it does not designate a PR, the IRS will designate one. A designation submitted with an AAR is treated as made before the AAR and effective on the date the AAR is filed.
Documents you need
- Form 2848, Power of Attorney and Declaration of Representative: only if a new PR for a BBA partnership wants to appoint a person as power of attorney to represent the PR; required even if that person was appointed by a prior PR for the same year.
- Form 8082 or Form 1065X: the administrative adjustment request (AAR) the form travels with, only when you file Form 8979 with an AAR; check the box above Part I.
- Form 8985 or Form 8988: only when Form 8979 is submitted with one of them, as the instructions describe for pass-through partnerships and elections under IRC section 6226.
How to fill out Form 8979
Enter partnership information
At the top, enter the partnership's name, address, employer identification number (EIN) and the tax year ending date for the year the designation or resignation applies to. If the post office does not deliver to the street address and the partnership has a P.O. box, enter the box number.
Check the AAR box if it applies
If you file this form with an administrative adjustment request (Form 8082 or Form 1065X), check the box just above Part I.
Select the reason in Part I
Check line 1 if the partnership is designating a PR (and appointing a DI if the PR is an entity), which revokes any prior designation. Check line 2 if the PR or DI is resigning.
Designate an individual PR
In Part II, enter the individual PR's name, U.S. mailing address, TIN and telephone number with a U.S. area code. Leave the designated individual lines blank.
Designate an entity PR and a DI
Complete the PR lines with the entity's name, address, TIN and telephone number, and the designated individual lines with last, first and middle name, suffix, address, TIN and telephone number. Both need a U.S. address and U.S. area code.
Complete the resignation in Part III
If you checked line 2, enter the name, U.S. street address, TIN and telephone number of the resigning PR or DI. If an entity PR resigns, the DI appointment ends too.
Sign Part IV, Section A
For a designation, an authorized person signs and dates (mm/dd/yyyy) and prints their name. If that person is an entity, also enter the name and title of the individual who can legally bind it; leave that line blank for an individual.
Sign Part IV, Section B
For a resignation, the resigning PR or DI signs, dates and prints their name, adding a description such as "resigning Partnership Representative of [partnership name]." A DI resigning for an entity PR writes "Designated Individual" on behalf of the entity.
Review and download the completed PDF
Check that only one box is marked in Part I, that a DI is named for any entity PR and that the right Part IV section is signed. Download or print the completed PDF from FillingPDF and send it as described under How to submit.
How to submit Form 8979
Form 8979 goes to the IRS by mail or fax to a named IRS contact, or with an AAR. The instructions give no separate mailing address or portal for the form.
- Mail or fax: address it to the attention of the current IRS employee point of contact, such as the revenue agent, appeals officer or counsel.
- With an AAR: check the box immediately above Part I and see How to file an AAR at IRS.gov/BBAAAR.
- With Form 8985: see the Instructions for Form 8985 for how to submit Form 8979 in response to an exam as opposed to an AAR filing.
Address details entered on the form do not change your last known address with the IRS. Use Form 8822 (home address) or Form 8822-B (business address) for that. The instructions state no fee for this form. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Designating an entity as partnership representative without appointing a designated individual; the designation is invalid and the current PR designation stays in effect.
- Completing the designated individual lines when you designate an individual PR; the instructions say there is no DI in that case.
- Naming a PR or DI who lacks substantial presence in the United States, such as no U.S. TIN, no U.S. street address or no telephone number with a U.S. area code.
- Forgetting to check the box above Part I when the form is filed with an AAR (Form 8082 or Form 1065X).
- Submitting a resignation to anyone other than the current IRS employee point of contact, or before Letter 2205-D, Letter 5893 or Letter 5893-A has been issued.
- Entering a P.O. box when the post office delivers mail to the partnership's street address; use the box number only when it does not.
- Filling in the third signature line when the authorized person is an individual; it stays blank, and only an entity lists the name and title of the individual who can bind it.
- Expecting the addresses on Form 8979 to update the IRS's records; use Form 8822 or Form 8822-B for that.
Frequently asked questions
What is Form 8979 used for?
Form 8979 is the IRS form a partnership uses to designate a partnership representative (PR) and appoint a designated individual (DI) when the PR is an entity. A PR or DI also uses it to resign. A valid new designation automatically revokes the prior PR and DI.
Who can sign Form 8979 for a partnership?
An authorized person signs, meaning someone who was a partner at any time during the partnership tax year to which the designation relates. If that person is an entity, the signer is an individual who can legally bind it under applicable state law, listed with name and title.
Can a partnership representative be an entity?
Yes. A partnership may designate any person, including an entity or itself, as PR. If it designates an entity, it must appoint a designated individual at the same time, or the designation is invalid and the current PR designation stays in effect.
Where do I send Form 8979?
Mail or fax it to the attention of the current IRS employee point of contact, such as the revenue agent, appeals officer or counsel. If you file it with an AAR, see How to file an AAR at IRS.gov/BBAAAR. The instructions give no other address.
When can a partnership representative resign using Form 8979?
A PR or DI should submit the resignation directly to the current IRS employee point of contact after the IRS issues Letter 2205-D, Letter 5893 or Letter 5893-A. A valid resignation leaves no PR in effect, and the IRS will ask the partnership to make a designation.
What happens if the IRS says no partnership representative is in effect?
The partnership has 30 days from the date the IRS mails the notification to submit Form 8979 designating a PR and, if needed, a DI. If it fails to do so, the IRS will designate a PR and appoint a DI.
Does Form 8979 give someone power of attorney?
No. A new PR for a BBA partnership that wants to appoint a power of attorney must submit Form 2848, even if that person was appointed by a prior PR of the same partnership for the same taxable year.
Can I fill out Form 8979 online?
Yes. You can fill out the PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file the form with the IRS; you submit it through the IRS channels described above.
Ready to fill out Form 8979?
Fill out Form 8979 now