
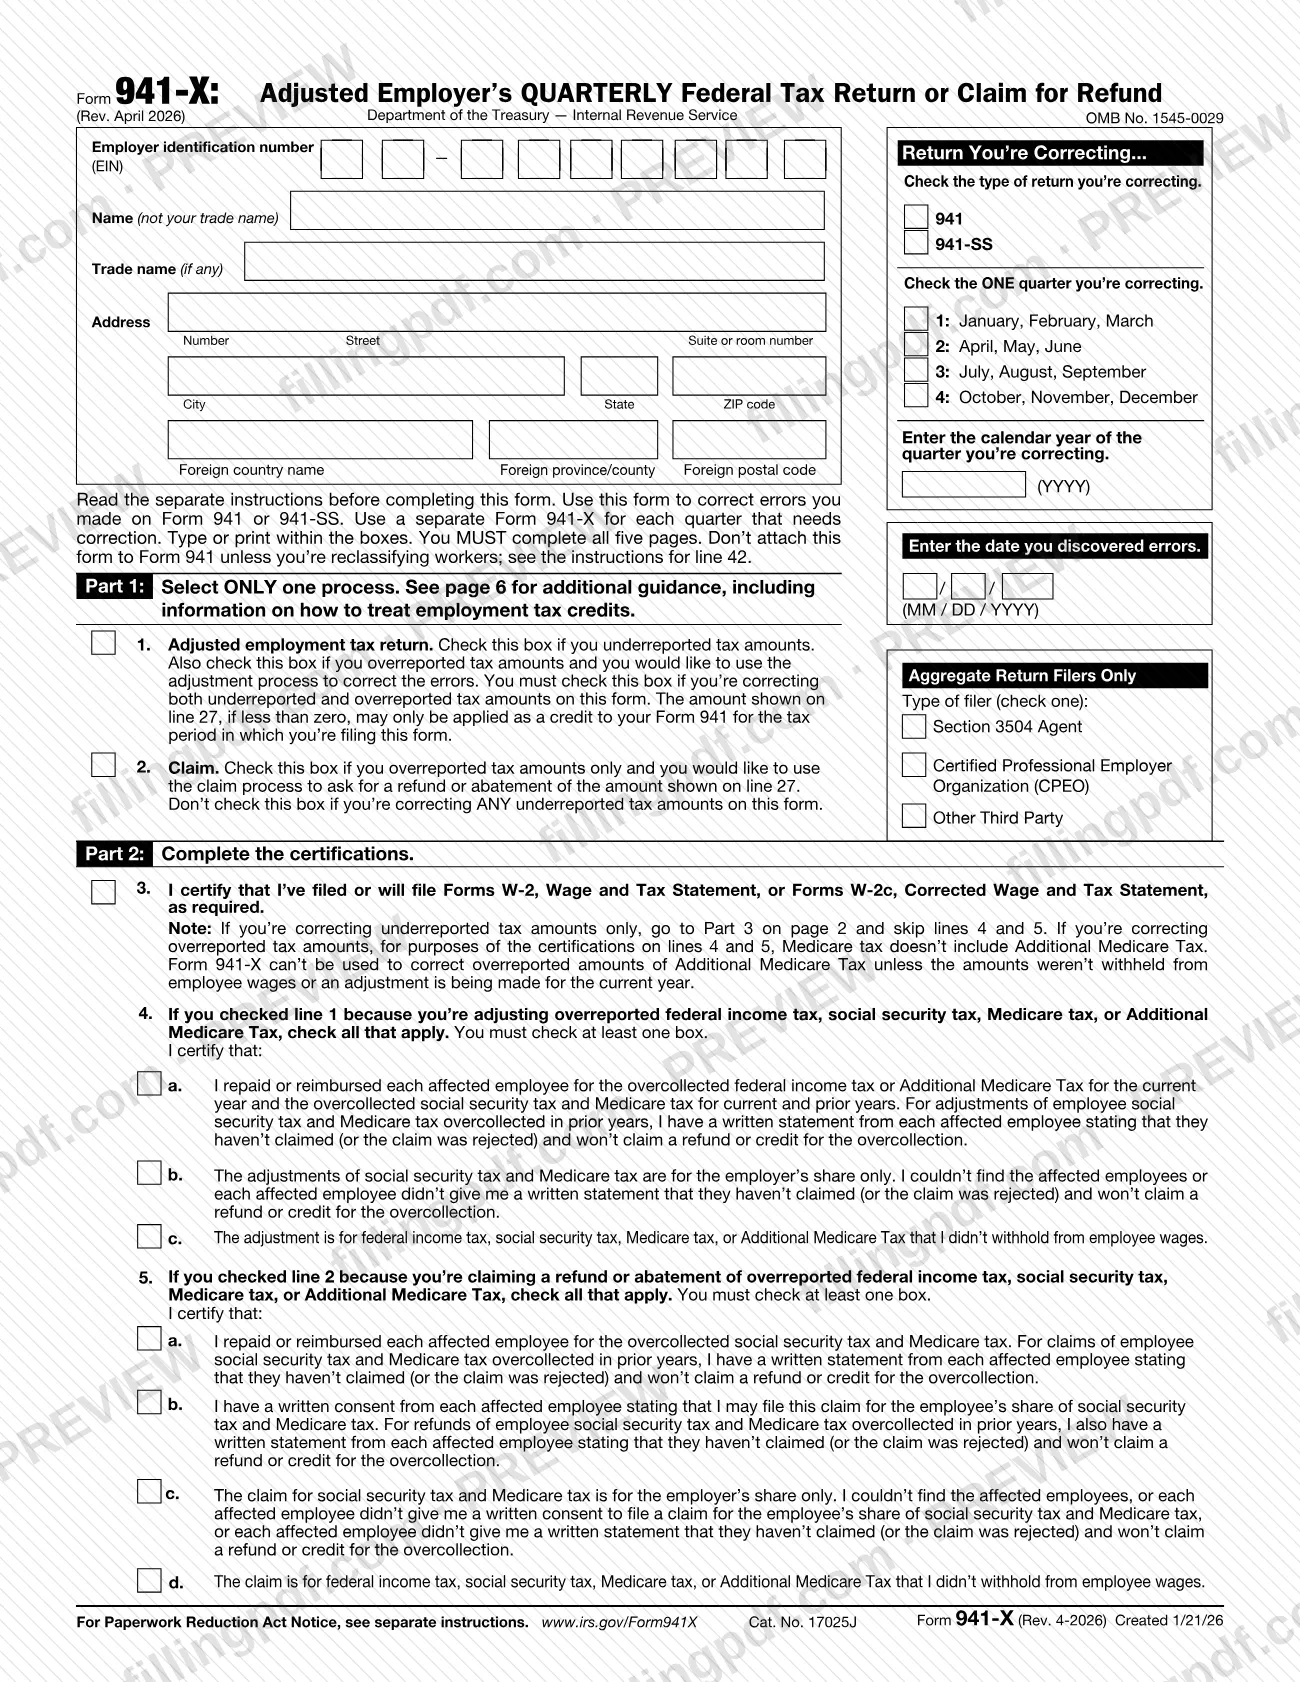
The 941x is Form 941-X, the Internal Revenue Service (IRS) form that employers use to correct errors on a Form 941 or Form 941-SS they already filed. You file one Form 941-X for each quarter you are correcting, and you choose either the adjustment process (an adjusted return) or the claim process (a refund or abatement). On FillingPDF you can fill out the form online and download or print the completed PDF; the IRS publishes the original form at irs.gov and receives it only through the channels described below.
Last updated
What is 941-X?
Form 941-X, Adjusted Employer's QUARTERLY Federal Tax Return or Claim for Refund, is the IRS form an employer uses to correct errors on a previously filed Form 941 or 941-SS, either as an adjusted return or as a claim for refund or abatement.
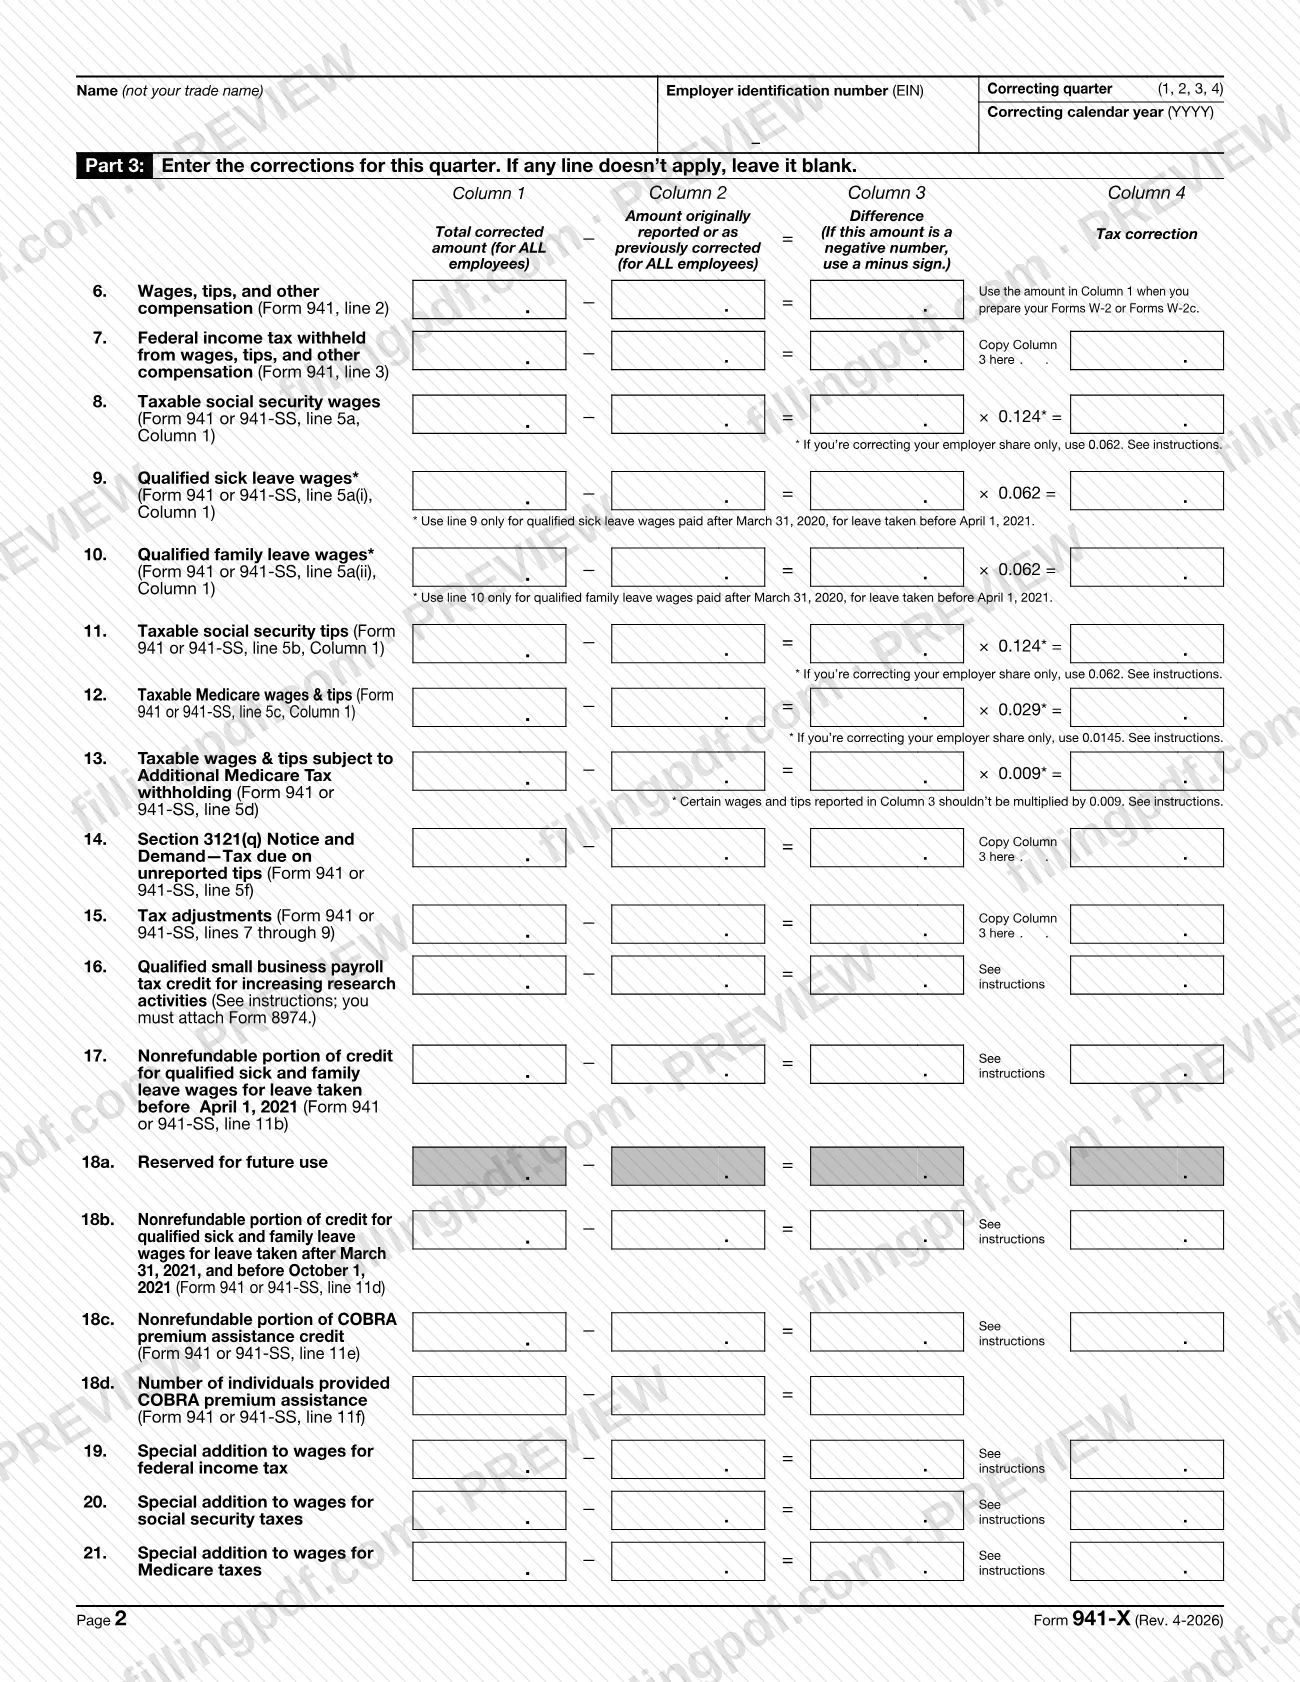
The form works from the original return. In Part 3 you enter, line by line, the corrected amount for all employees, the amount you originally reported or previously corrected, and the difference. Lines 6 to 13 cover wages, tips, federal income tax withheld, social security, Medicare and Additional Medicare Tax; later lines cover tax adjustments, the qualified small business payroll tax credit for increasing research activities, the qualified sick and family leave credits and the COBRA premium assistance credit. Part 4 requires a detailed explanation of how you figured each correction, and Part 5 is signed under penalties of perjury.
The IRS instructions use "correct" to include interest-free adjustments and claims for refund or abatement. Form 941-X is not the form to correct Form CT-1, 943, 944 or 945; each has its own "X" form (CT-1 X, 943-X, 944-X, 945-X). It is also not used to request a refund or abatement of assessed interest or penalties, which goes on Form 843. Form 941-SS was discontinued after 2023, but Form 941-X still corrects a Form 941-SS filed for the fourth quarter of 2023 or earlier. Puerto Rico Form 941-PR filings for those periods are corrected on Form 941-X (PR), and Form 941 (sp) is corrected on Form 941-X (sp).
Who needs to file 941-X?
Employers who filed Form 941, or Form 941-SS for quarters before 2024, and later discover an error on it use Form 941-X. This includes errors in wages, tips and other compensation, federal income tax withheld, taxable social security and Medicare wages and tips, Additional Medicare Tax wages, and certain employment tax credits.
Aggregate return filers use it too and must check their type of filer: a section 3504 agent, a Certified Professional Employer Organization (CPEO) or an other third party.
Do not use Form 941-X in these cases:
- You never filed Form 941 for the quarter. File Form 941 for that quarter instead.
- Your only errors concern the number of employees on Form 941, line 1, or the tax liabilities reported in Part 2 or on Schedule B (Form 941).
- You are correcting Form CT-1, 943, 944 or 945; use the matching "X" form.
- You want a refund or abatement of assessed interest or penalties; use Form 843.
Form 941-X cannot correct federal income tax actually withheld in a prior year for nonadministrative errors, and a refund claim cannot correct federal income tax or Additional Medicare Tax actually withheld from employees. Each quarter needs its own form.
When to file 941-X
File Form 941-X when you discover an error on a previously filed Form 941. The due date depends on whether you underreported or overreported tax.
Underreported tax: file by the due date of the return for the period in which you discovered the error, and pay the amount owed when you file. If you discover the error in January through March, the due date is April 30; April through June, July 31; July through September, October 31; October through December, January 31. A date that falls on a weekend or legal holiday moves to the next business day. If you file late, attach an amended Schedule B (Form 941) to avoid a possible "averaged" failure-to-deposit penalty.
Overreported tax: under the adjustment process, file soon after discovery but more than 90 days before the period of limitations expires. Under the claim process, file any time before it expires. The period is generally 3 years from the date Form 941 was filed or 2 years from the date you paid the tax, whichever is later. Forms 941 for a calendar year count as filed on April 15 of the next year if filed earlier. Within the last 90 days, you must use the claim process.
Documents you need
- Schedule R (Form 941), Allocation Schedule for Aggregate Form 941 Filers: attach it if you are a section 3504 agent or CPEO filing an aggregate Form 941-X, or an other third-party payer reporting credits for clients.
- A corrected Form 8974: attach it if you make a correction on line 16, the qualified small business payroll tax credit for increasing research activities.
- An amended Schedule B (Form 941): attach it if you file Form 941-X to correct underreported tax after the due date of the return for the period in which you discovered the error.
- Form 941-X attached to Form 941: required only if you did not previously file Form 941 because you treated workers as nonemployees and are now reclassifying them; see the instructions for line 42.
How to fill out 941-X
Identify the return and quarter
At the top of page 1, enter your EIN, name (not your trade name), trade name if any, and address. Check the type of return you are correcting (941 or 941-SS), check the ONE quarter, and enter the calendar year (YYYY).
Enter the date you discovered errors
Enter the date as MM/DD/YYYY. If you found several errors at different times, enter the earliest date and report later dates on line 43.
Identify yourself if you file an aggregate return
Aggregate return filers only: check Section 3504 Agent, Certified Professional Employer Organization (CPEO) or Other Third Party. Most other employers skip this box.
Select one process in Part 1
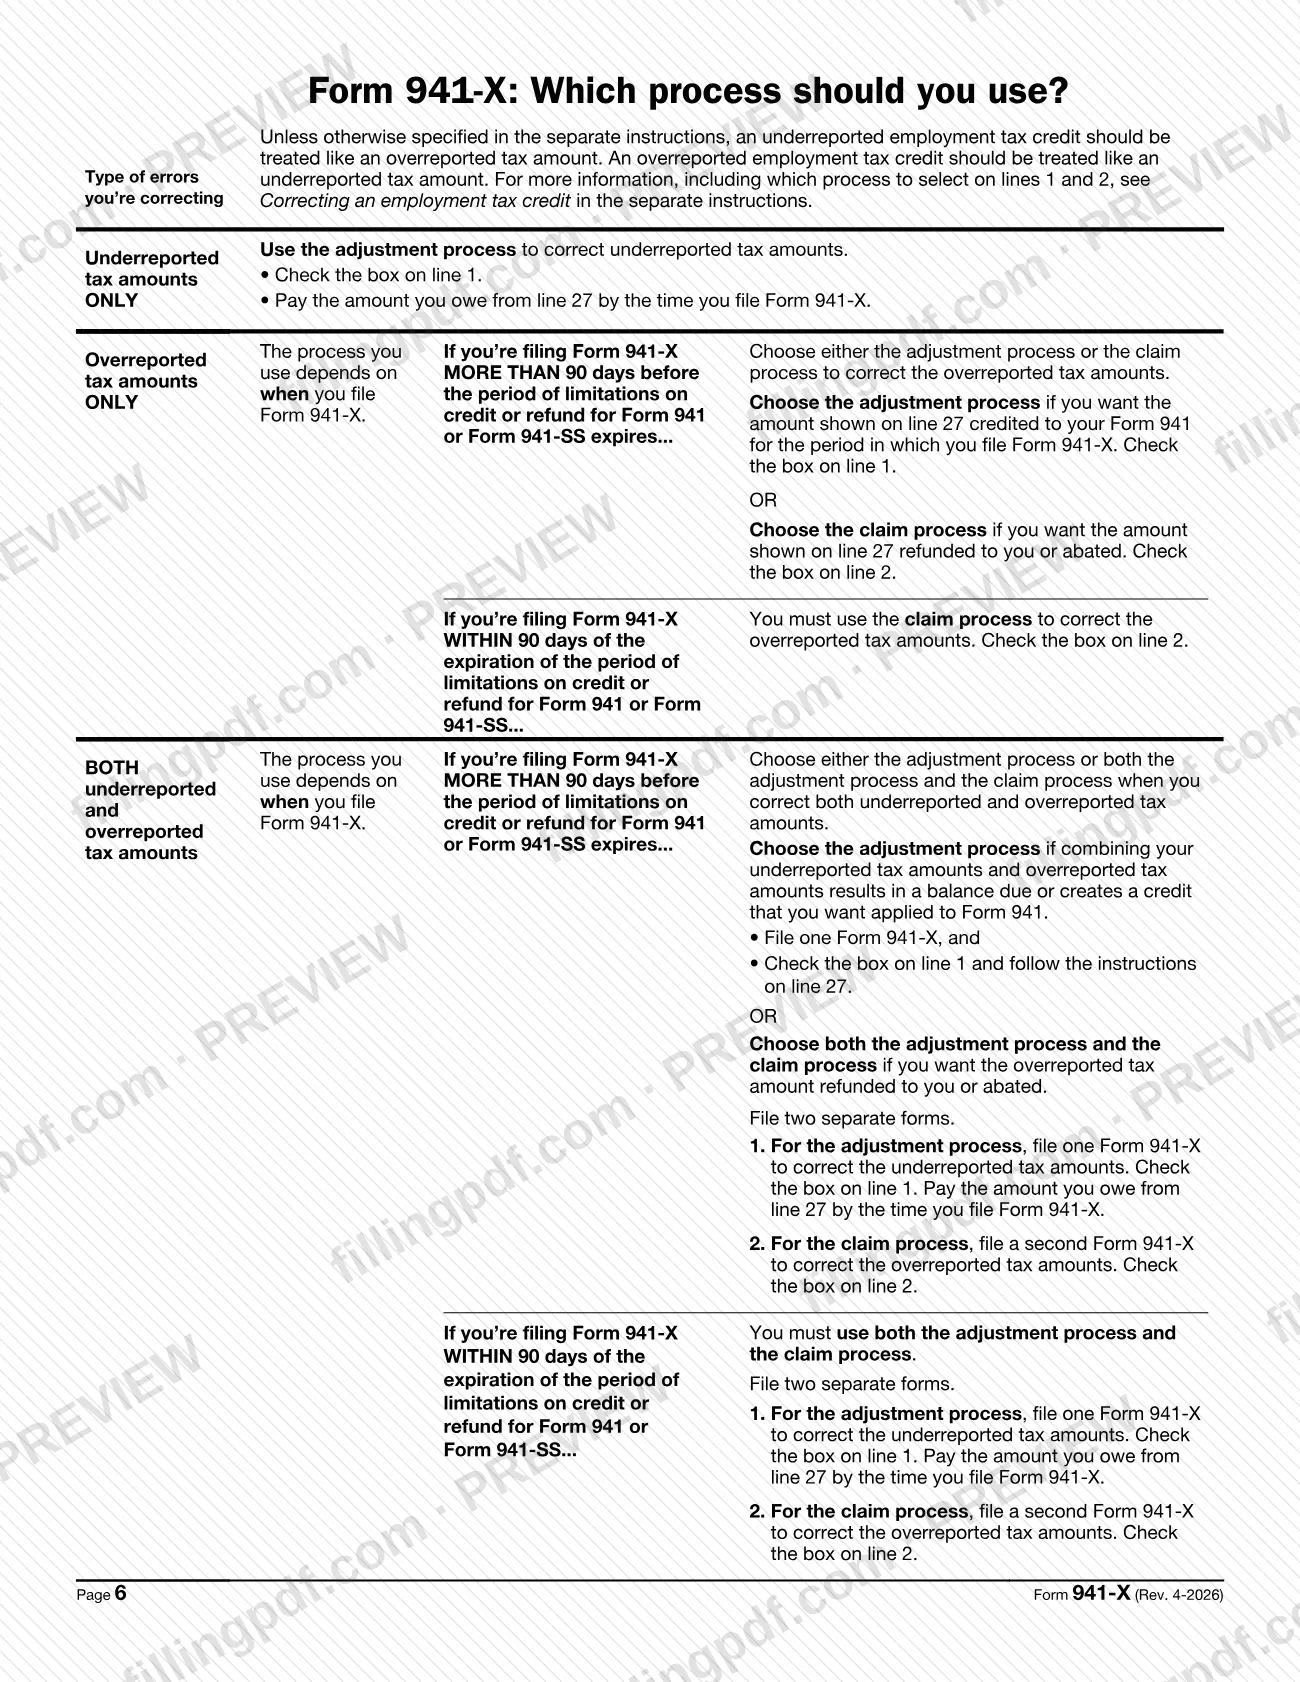
Check line 1 (adjusted employment tax return) or line 2 (claim), never both. Use the chart on page 6 of the form to choose; line 2 is only for overreported amounts.
Complete the certifications in Part 2
Check line 3 to certify you filed or will file Forms W-2 or W-2c. If you are correcting overreported amounts, check at least one applicable box on line 4 (if you checked line 1) or line 5 (if you checked line 2); skip lines 4 and 5 for underreported amounts only.
Correct wages and taxes on lines 6-13
For each line you are correcting, enter the total corrected amount for all employees in column 1, the original or previously corrected amount in column 2, and the difference in column 3 (minus sign if negative). Copy column 3 to column 4 on line 7; on lines 8 to 13 multiply by the rate printed in column 4.
Complete lines 14 to 22 as needed
Use line 14 for the Section 3121(q) Notice and Demand, line 15 for tax adjustments, line 16 for the research payroll credit (attach Form 8974), lines 17 to 18d for credits, and lines 19 to 22 for special additions to wages. Leave inapplicable lines blank.
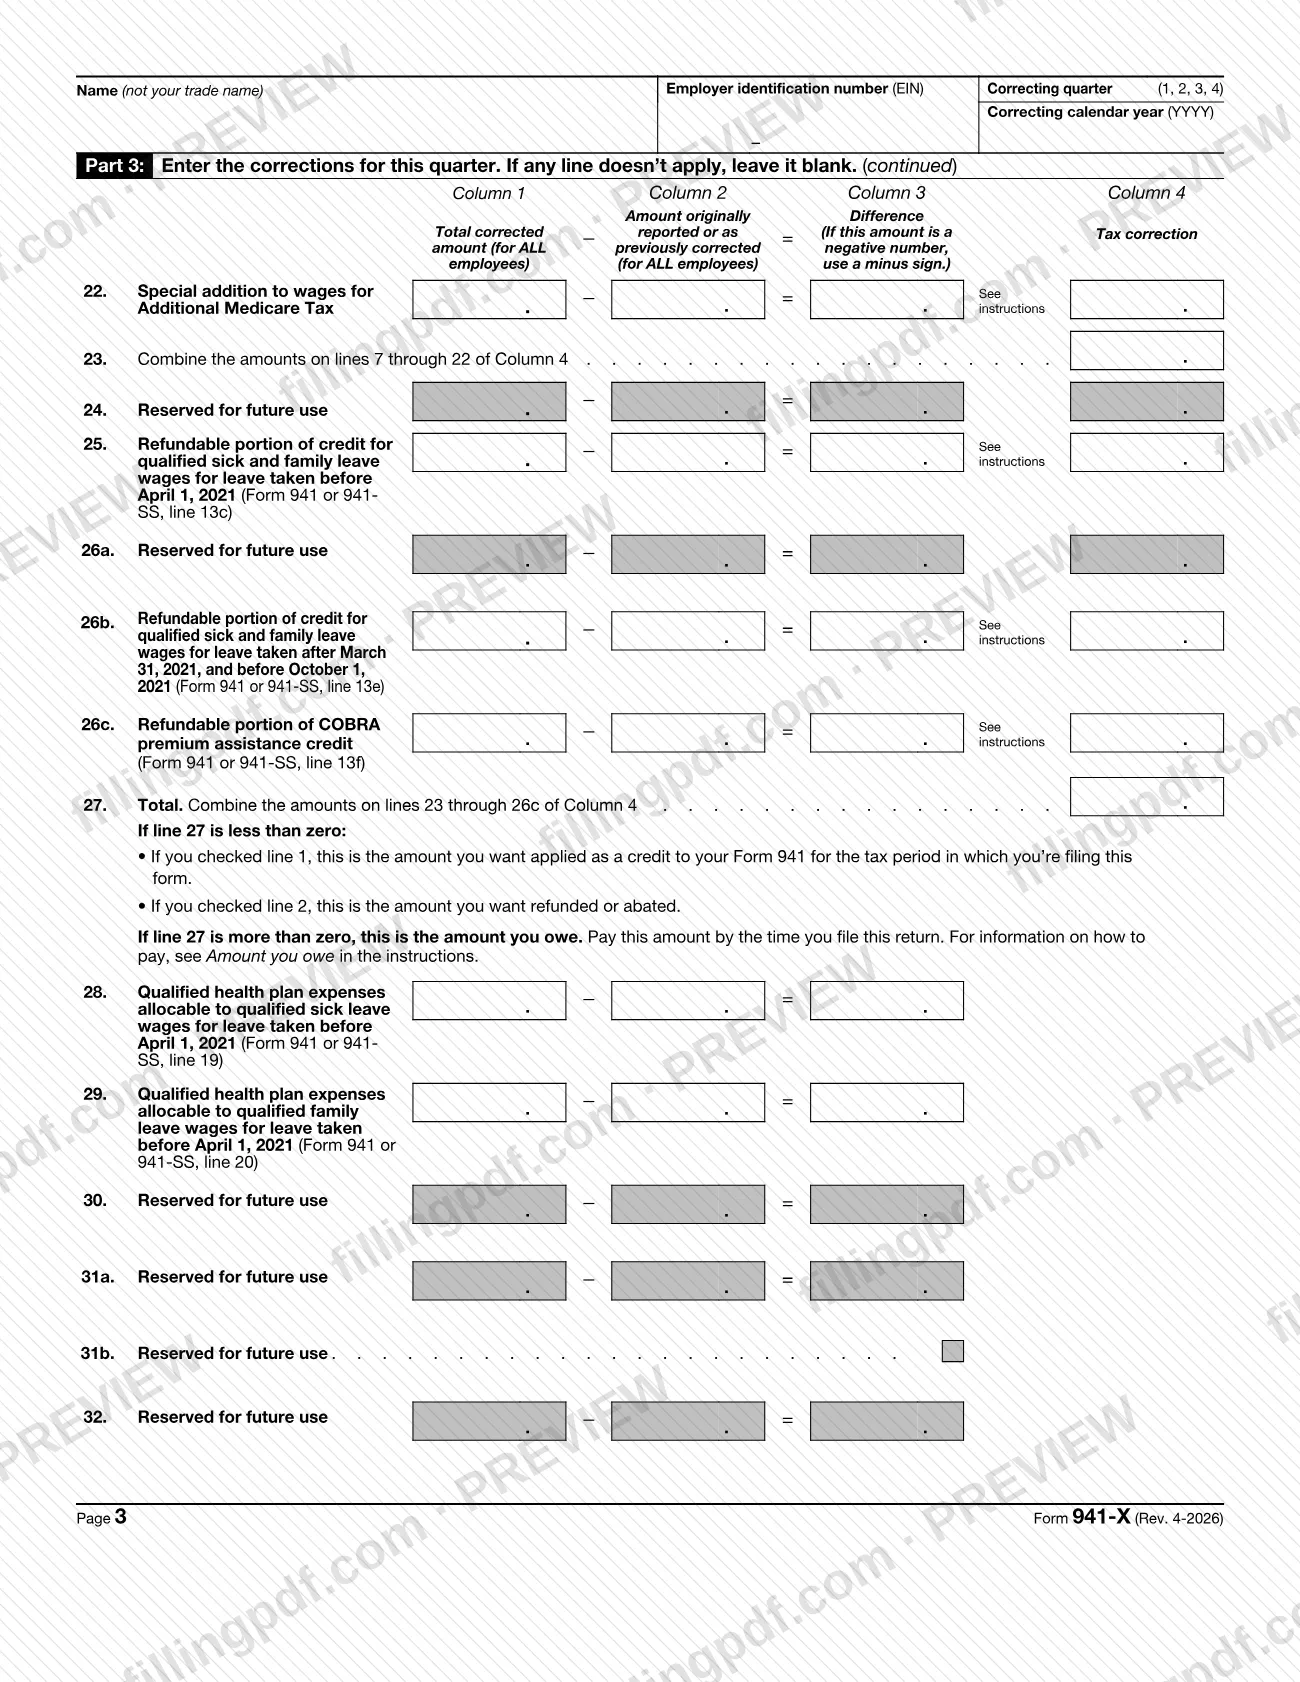
Total your corrections on lines 23-27
Line 23 combines column 4 of lines 7 through 22. Enter refundable credits on lines 25 to 26c, then combine lines 23 through 26c on line 27. A negative line 27 is a credit (line 1) or a refund or abatement (line 2); a positive amount is tax you owe.
Enter health plan and leave amounts
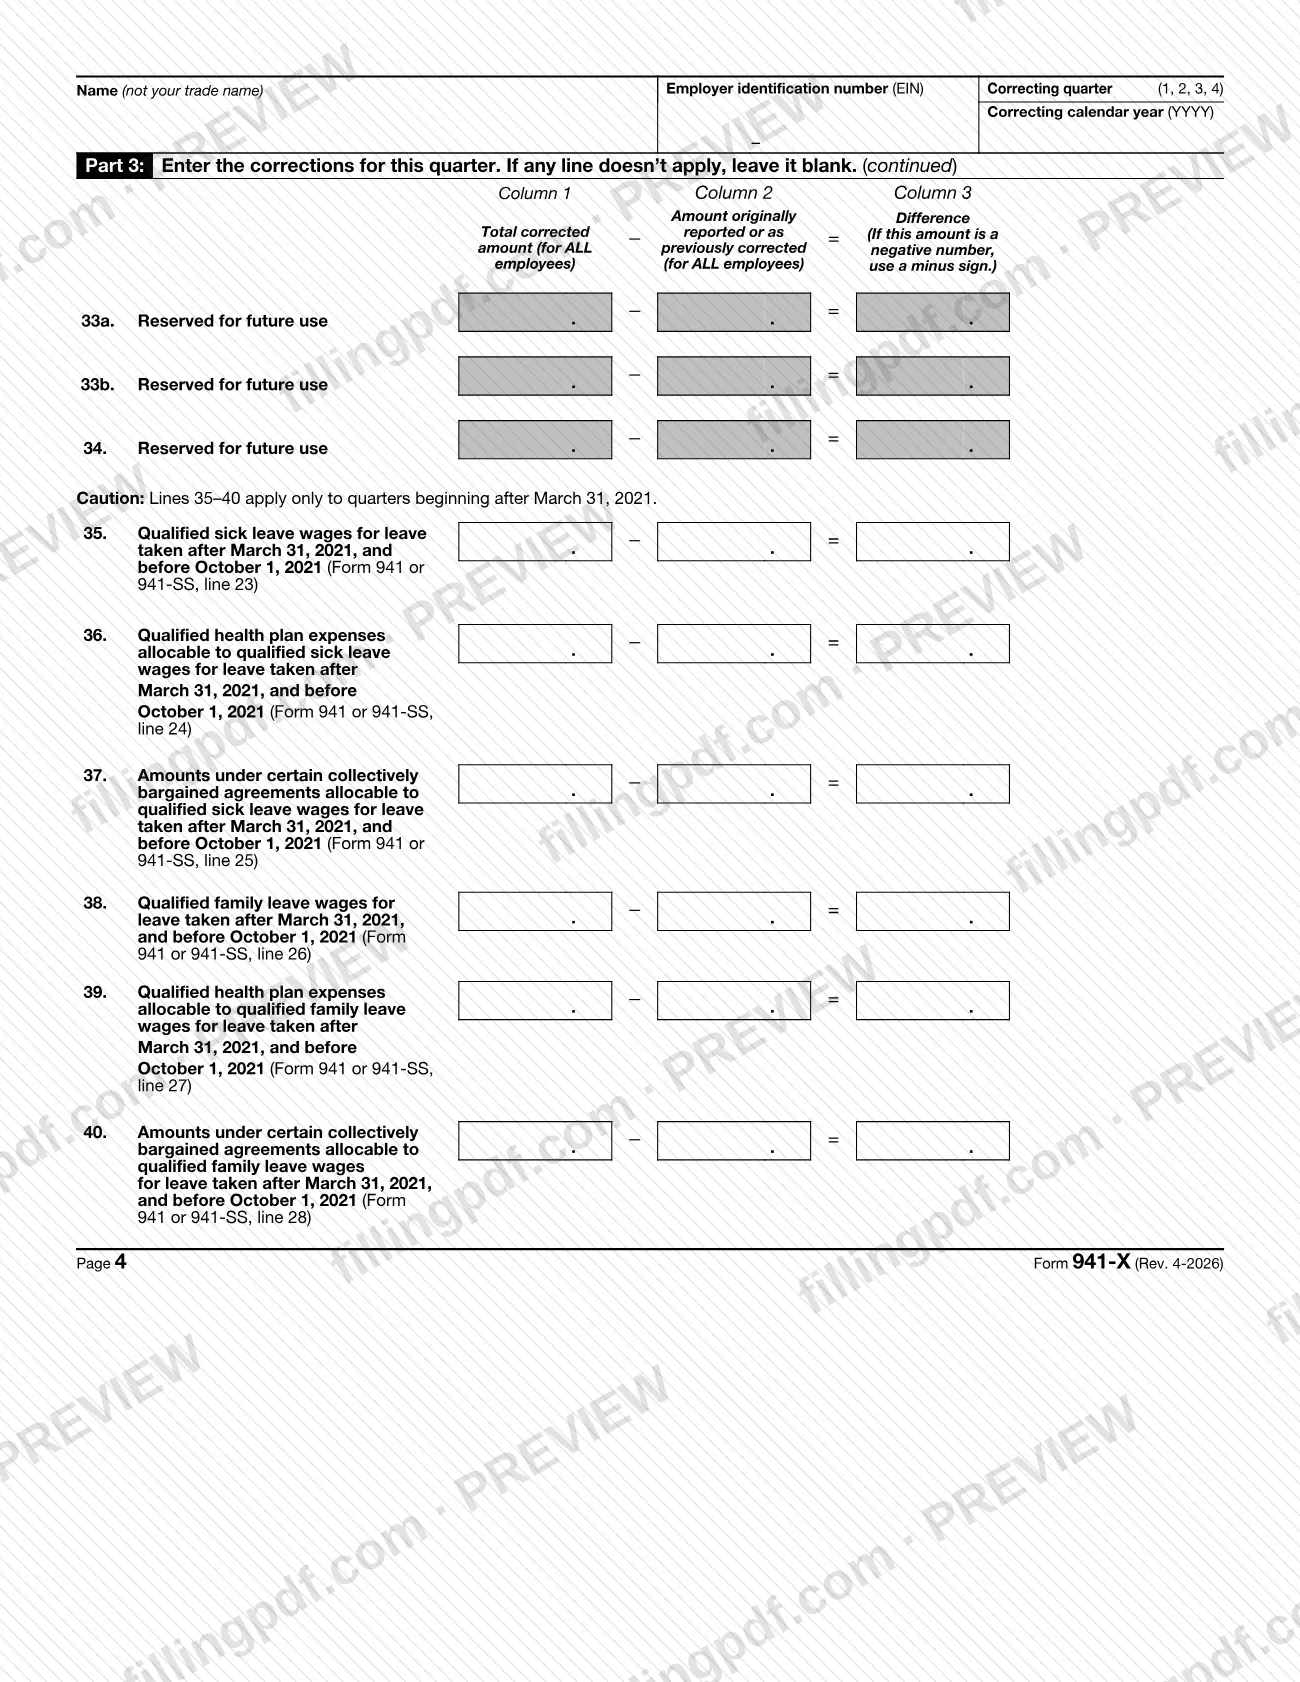
Use lines 28 and 29 and lines 35 to 40 only for the qualified sick and family leave items they describe. Lines 35 to 40 apply only to quarters beginning after March 31, 2021; lines marked Reserved for future use stay blank.
Explain your corrections in Part 4
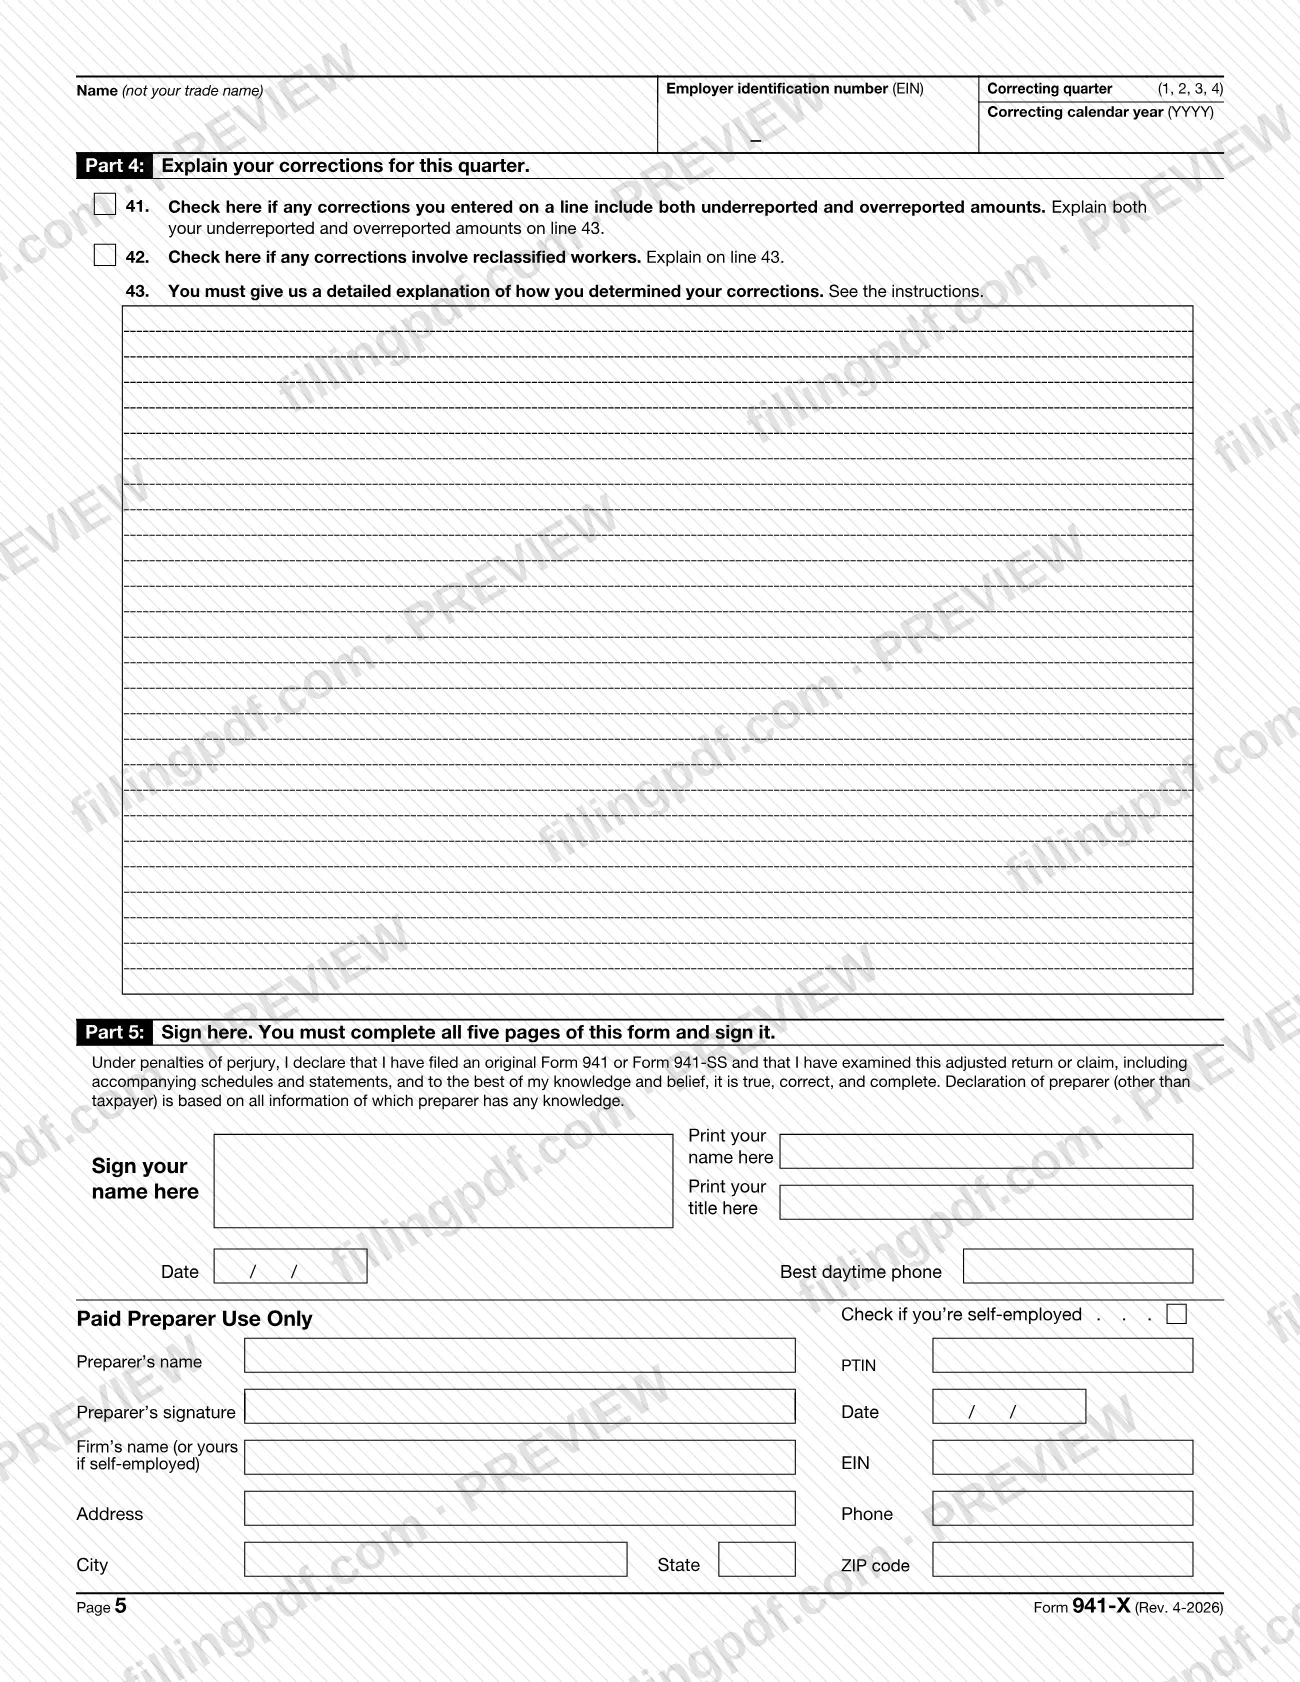
Check line 41 if a correction includes both underreported and overreported amounts, and line 42 if any correction involves reclassified workers. On line 43, give a detailed explanation of how you determined each correction.
Review, sign and download the PDF
Check that your name and EIN, the quarter and the year appear on pages 2 to 5. Sign and date in Part 5 (a paid preparer completes the preparer block), then download or print the completed PDF from FillingPDF.
How to submit 941-X
You can file Form 941-X electronically or on paper by mail, either through the U.S. Postal Service (USPS) or an IRS-designated private delivery service (PDS).
- Electronically: the IRS encourages e-filing through Modernized e-File (MeF). See IRS.gov/EmploymentEfile.
- By USPS mail: use the address for your location. CT, DE, DC, FL, GA, IL, IN, KY, ME, MD, MA, MI, NH, NJ, NY, NC, OH, PA, RI, SC, TN, VT, VA, WV or WI: Department of the Treasury, Internal Revenue Service, Cincinnati, OH 45999-0005. AL, AK, AZ, AR, CA, CO, HI, ID, IA, KS, LA, MN, MS, MO, MT, NE, NV, NM, ND, OK, OR, SD, TX, UT, WA or WY: Department of the Treasury, Internal Revenue Service, Ogden, UT 84201-0005. No legal residence or principal place of business in any state: Internal Revenue Service, P.O. Box 409101, Ogden, UT 84409. Exempt organizations, federal, state and local governmental entities and Indian tribal governmental entities, wherever located: Department of the Treasury, Internal Revenue Service, Ogden, UT 84201-0005.
- By PDS: Ogden—Internal Revenue Submission Processing Center, 1973 Rulon White Blvd., Ogden, UT 84201, even if your business is in a state that files in Cincinnati. PDSs cannot deliver to P.O. boxes; see IRS.gov/PDS.
Staple multiple sheets in the upper-left corner and do not attach Form 941-X to Form 941, except when reclassifying workers (line 42). Pay any amount owed from line 27 by the time you file. For help, call the IRS Business and Specialty Tax Line at 800-829-4933. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Checking both boxes in Part 1, or checking line 2 (claim) when any correction on the form is an underreported amount. You must check only one, and line 1 is required if you correct both underreported and overreported amounts.
- Using the adjustment process (line 1) for overreported tax when the period of limitations expires within 90 days of filing. In that window you must use the claim process on line 2.
- Combining several quarters on one Form 941-X. Use a separate form for each Form 941 you are correcting.
- Leaving out the date you discovered the errors, or failing to explain each correction in detail on line 43; both are conditions for interest-free treatment of underreported tax.
- Entering amounts for only the affected employees in columns 1 and 2 of lines 6 to 13. Those columns show the amounts for all of your employees.
- Rounding to whole dollars, omitting cents, or using parentheses for negative numbers in columns 3 and 4. Show cents even if zero and use a minus sign unless your software allows only parentheses.
- Sending employee statements or consents to the IRS. Keep them with your records; copies are submitted only if the IRS requests them.
- Filling lines 18b, 18c, 18d, 26b, 26c or 35 to 40 when correcting a quarter that began before April 1, 2021. The instructions say to leave them blank.
- Filing Form 941-X to correct federal income tax withheld in a prior year because you withheld the wrong amount. Only administrative errors and section 3509 errors can be corrected for prior years.
- Not completing all five pages, or leaving Part 5 unsigned.
Frequently asked questions
What is the 941x form used for?
Form 941-X, often searched as 941x, corrects errors on a Form 941 or 941-SS you already filed. It serves as an adjusted return when you owe tax or want a credit applied to Form 941, or as a claim when you want a refund or abatement of overreported tax.
Do I file a separate Form 941-X for each quarter?
Yes. Use a separate Form 941-X for each Form 941 you are correcting. If you found errors on the third and fourth quarters of 2025, file one Form 941-X for the third quarter and a second one for the fourth quarter.
What is the difference between the adjustment process and the claim process?
The adjustment process (line 1) applies a credit to your next Form 941 and is the only option for underreported tax. The claim process (line 2) requests a refund or abatement of overreported tax and cannot be used if you are correcting any underreported amount on that form.
What is the deadline to file Form 941-X?
For underreported tax, it is the due date of the return for the period in which you found the error (April 30, July 31, October 31 or January 31). For overreported tax, you generally have 3 years from filing Form 941 or 2 years from payment, whichever is later.
Where do I mail Form 941-X?
Mail it to the Cincinnati, OH 45999-0005 or Ogden, UT 84201-0005 address that matches your state, or to P.O. Box 409101, Ogden, UT 84409 if you have no legal residence or principal place of business in any state. You can also e-file it through MeF.
Do I attach Form 941-X to my current Form 941?
No. Form 941-X is generally filed separately. The exception is when you did not file Form 941 because you treated workers as nonemployees and are now reclassifying them; the instructions for line 42 explain that case.
Do I have to send employee consents or statements with a claim?
No. Keep the written statements and consents with your records and do not send them to the IRS; copies must be provided if the IRS asks. Employment tax records should generally be kept for at least 4 years.
Can I fill out Form 941-X online on FillingPDF?
Yes. You can fill out the PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not file it with the IRS; you submit it electronically or by mail through the IRS channels.
Ready to fill out 941-X?
Fill out 941-X now