
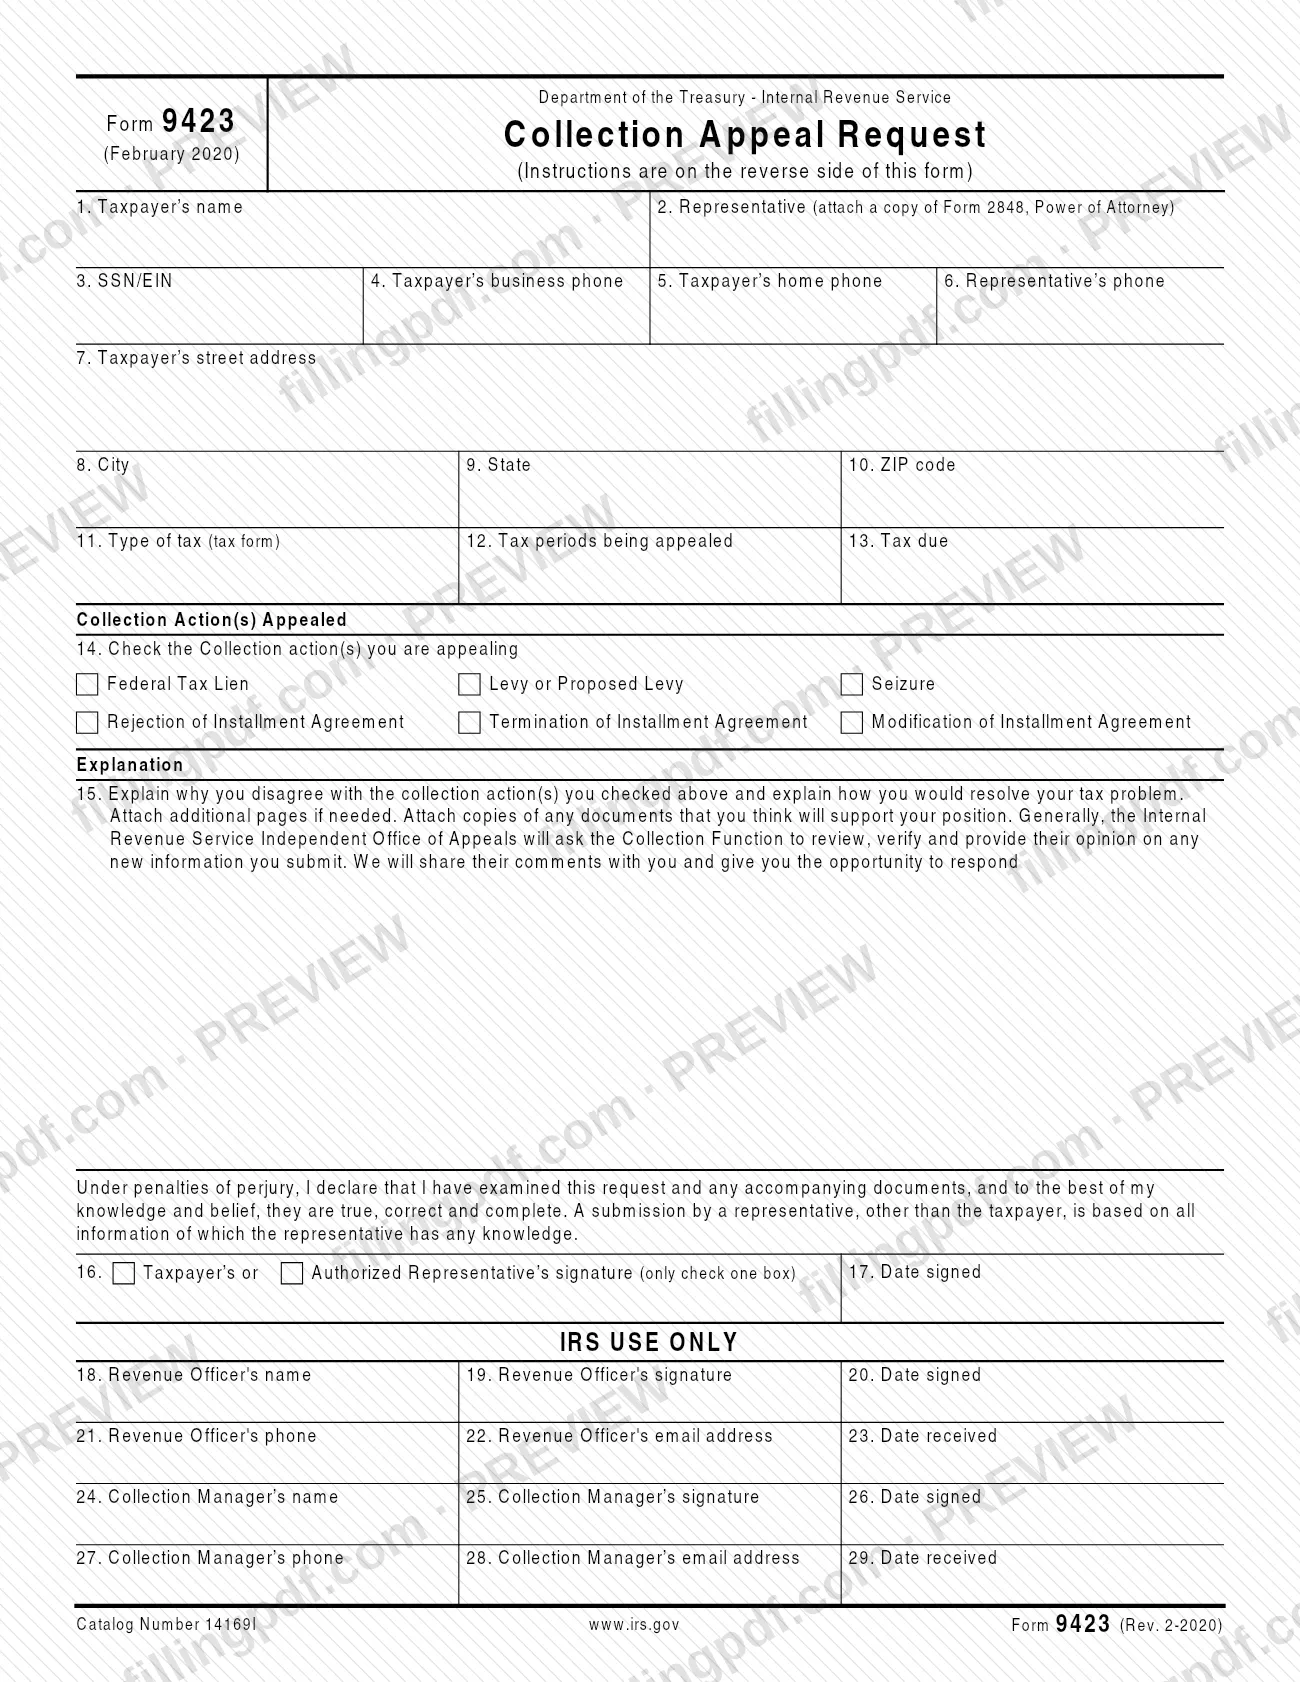
Form 9423 is the Collection Appeal Request, the Internal Revenue Service (IRS) form you use to ask the IRS Independent Office of Appeals to review a collection action under the Collection Appeals Program (CAP). It covers liens, levies, seizures, and rejected, modified or terminated installment agreements. The form is not sent straight to Appeals: it goes to the Collection office that took the action. On this page you can fill out the form online on FillingPDF and download or print the completed PDF; the IRS publishes the original at irs.gov.
Last updated
What is Form 9423?
Form 9423, Collection Appeal Request, is the Internal Revenue Service (IRS) form that a taxpayer, or a third party whose property is subject to a collection action, uses to appeal that action to the IRS Independent Office of Appeals under the Collection Appeals Program (CAP).
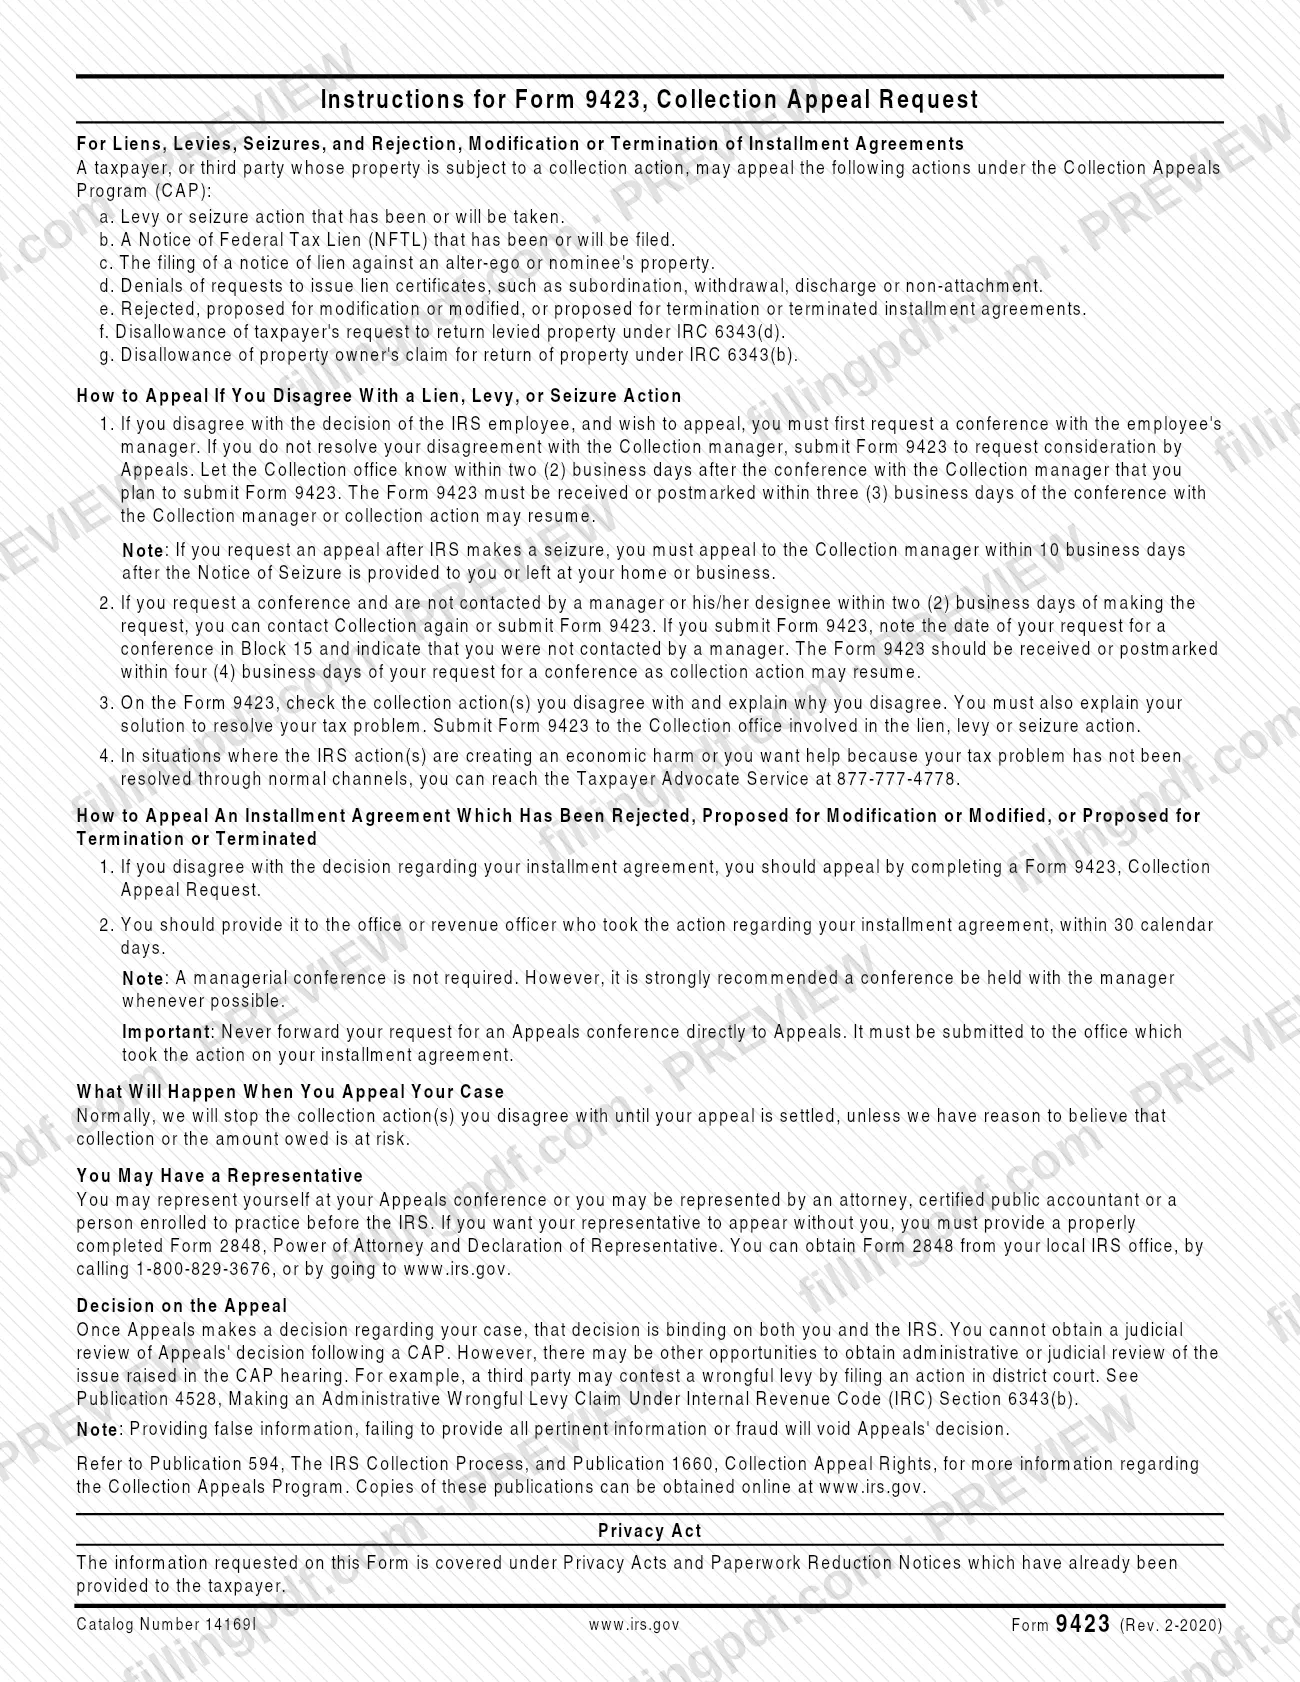
The instructions printed on the reverse of the form list the actions that can be appealed under CAP:
- a levy or seizure that has been or will be taken;
- a Notice of Federal Tax Lien (NFTL) that has been or will be filed, or a notice of lien against an alter-ego or nominee's property;
- a denied request for a lien certificate, such as subordination, withdrawal, discharge or non-attachment;
- an installment agreement that was rejected, proposed for modification or modified, or proposed for termination or terminated;
- disallowance of a request to return levied property under IRC 6343(d), or of a property owner's claim for return of property under IRC 6343(b).
On the form you check the collection action you are appealing (line 14), explain why you disagree and how you would resolve the tax problem (line 15), and sign under penalties of perjury. A block marked IRS USE ONLY is completed by the IRS revenue officer and collection manager.
Once Appeals decides, the decision binds both you and the IRS, and the instructions say you cannot obtain judicial review of it following a CAP. The IRS points to Publication 594, The IRS Collection Process, and Publication 1660, Collection Appeal Rights, for more detail.
Who needs to file Form 9423?
A taxpayer, or a third party whose property is subject to a collection action, may use Form 9423 to appeal one of the actions listed in the IRS instructions: a levy, seizure or Notice of Federal Tax Lien, a denied lien certificate request, a disallowed return-of-property request, or a rejected, modified or terminated installment agreement (or one proposed for modification or termination).
For a lien, levy or seizure, you first request a conference with the employee's manager. You submit Form 9423 only if you do not resolve the disagreement with the Collection manager, or if no manager contacts you within two business days of your request. For an installment agreement, a managerial conference is not required, although the instructions strongly recommend one when possible.
You may represent yourself or be represented by an attorney, a certified public accountant or a person enrolled to practice before the IRS. If you want your representative to appear without you, the representative must have a properly completed Form 2848, Power of Attorney and Declaration of Representative, and a copy is attached to Form 9423 (line 2).
If IRS action is creating economic harm, or your problem has not been resolved through normal channels, the instructions also point to the Taxpayer Advocate Service at 877-777-4778.
When to file Form 9423
The deadline depends on the action you are appealing, and it starts with your conference with the Collection manager.
- Lien, levy or seizure: tell the Collection office within two business days after the conference that you plan to submit Form 9423. The form must be received or postmarked within three business days of the conference, or collection action may resume.
- No manager contact: if no manager or designee contacts you within two business days of your conference request, you can contact Collection again or submit the form. Note the date of your request in Block 15 and say you were not contacted. Submit it so it is received or postmarked within four business days of your request.
- After a seizure: the instructions say to appeal to the Collection manager within 10 business days after the Notice of Seizure is provided to you or left at your home or business.
- Installment agreement: give the form to the office or revenue officer that took the action within 30 calendar days.
Normally, the IRS stops the collection action you disagree with until the appeal is settled, unless it believes collection or the amount owed is at risk.
Documents you need
- Form 2848, Power of Attorney and Declaration of Representative: attach a copy when a representative is named on line 2; required for a representative to appear without you.
- Additional pages: attach them if your explanation on line 15 does not fit on the form.
- Copies of any documents you think support your position, such as records related to the collection action you are appealing.
How to fill out Form 9423
Enter taxpayer name and ID
Line 1: the taxpayer's name. Line 3: the SSN or EIN.
Name your representative
Line 2: enter your representative, if any, and attach a copy of Form 2848. Line 6: the representative's phone number.
Add phone numbers
Line 4: the taxpayer's business phone. Line 5: the taxpayer's home phone.
Enter your address
Line 7: street address. Lines 8, 9 and 10: city, state and ZIP code.
Identify the tax and periods
Line 11: type of tax (tax form). Line 12: the tax periods being appealed. Line 13: the tax due.
Check the collection actions
Line 14: check each collection action you are appealing: Federal Tax Lien, Levy or Proposed Levy, Seizure, or Rejection, Termination or Modification of Installment Agreement.
Explain your disagreement and solution
Line 15: explain why you disagree with each action you checked and how you would resolve your tax problem. Attach additional pages if needed.
Note conference details if needed
If you are submitting because no manager contacted you within two business days of your conference request, enter the date of the request in Block 15 and state that you were not contacted.
Attach supporting documents
Attach copies of any documents that support your position, and a copy of Form 2848 if you have a representative.
Sign and date the request
Line 16: the taxpayer or authorized representative signs, checking only one box. Line 17: the date signed. Leave the IRS USE ONLY block (lines 18 to 29) for the IRS.
Review and download the PDF
Check that each line is complete and the explanation is clear. Download or print the completed PDF from FillingPDF and send it as described under How to submit.
How to submit Form 9423
Submit Form 9423 to the IRS Collection office involved in the lien, levy or seizure action, or, for an installment agreement, to the office or revenue officer that took the action. The form prints no mailing address, portal or fax number.
- Lien, levy or seizure: send the form to the Collection office involved, after your conference with the Collection manager. It must be received or postmarked within the time limits described under When to file.
- Installment agreement: provide it to the office or revenue officer that took the action on your agreement, within 30 calendar days.
- Never directly to Appeals: the instructions say never to forward your request for an Appeals conference straight to Appeals.
Attach copies of any documents that support your position and, if a representative signs or appears for you, a copy of Form 2848. The IRS says the Independent Office of Appeals will generally ask the Collection Function to review, verify and comment on any new information you submit, share those comments with you and let you respond. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Sending Form 9423 directly to Appeals; the instructions say it must go to the Collection office that took the action.
- Missing the short window after the Collection manager conference: the form must be received or postmarked within three business days or collection may resume.
- Skipping the manager conference for a lien, levy or seizure appeal before submitting the form.
- Waiting beyond 30 calendar days to appeal a rejected, modified or terminated installment agreement.
- Checking an action on line 14 but leaving line 15 without an explanation of both your disagreement and how you would resolve the tax problem.
- Not noting the date of your conference request and that no manager contacted you in Block 15, when you submit because of no contact.
- Naming a representative without attaching a copy of Form 2848.
- Providing false or incomplete information; the instructions say this, or fraud, will void Appeals' decision.
Frequently asked questions
What is Form 9423 used for?
Form 9423, Collection Appeal Request, is used to appeal an IRS collection action to the Independent Office of Appeals under the Collection Appeals Program. It covers liens, levies, seizures, denied lien certificates, and rejected, modified or terminated installment agreements.
Where do I send Form 9423?
Send it to the Collection office involved in the lien, levy or seizure, or to the office or revenue officer that took action on your installment agreement. The instructions say never to forward the request directly to Appeals. The form prints no address.
What is the deadline to file Form 9423?
For a lien, levy or seizure, it must be received or postmarked within three business days of your conference with the Collection manager. For an installment agreement, provide it within 30 calendar days to the office or officer that took the action.
Do I have to talk to a Collection manager before filing Form 9423?
For a lien, levy or seizure, yes: request a conference with the employee's manager first, and file the form if you do not resolve it. For an installment agreement, a conference is not required, but the IRS strongly recommends one when possible.
Will the IRS stop collection while my appeal is pending?
Normally, yes. The instructions say the IRS will stop the collection action you disagree with until the appeal is settled, unless it has reason to believe that collection or the amount owed is at risk.
Can a representative file Form 9423 for me?
Yes. You may be represented by an attorney, certified public accountant or person enrolled to practice before the IRS. For a representative to appear without you, attach a properly completed Form 2848, Power of Attorney and Declaration of Representative.
Can I challenge the Appeals decision in court?
The instructions say Appeals' decision is binding on you and the IRS and that you cannot obtain judicial review of it following a CAP. Other administrative or judicial review of the underlying issue may exist, such as a wrongful levy action by a third party.
Can I fill out Form 9423 online on FillingPDF?
Yes. You can fill out the Form 9423 PDF online on FillingPDF and download or print it. FillingPDF is an independent service and does not submit the form to the IRS; you deliver it to the Collection office yourself.
Ready to fill out Form 9423?
Fill out Form 9423 now