
Form 944 (sp), Employer's ANNUAL Federal Tax Return (Spanish Version), is the Spanish-language edition of Form 944 that the Internal Revenue Service (IRS) publishes for tax year 2025. It is meant for the smallest employers, the ones the IRS has told in writing to report payroll taxes once a year instead of on quarterly Forms 941. On FillingPDF you can fill out the form online and download or print the completed PDF; the IRS publishes the original PDF and the Spanish instructions at irs.gov, and you submit the return through the IRS channels described below.
Last updated
What is 944 (sp)?
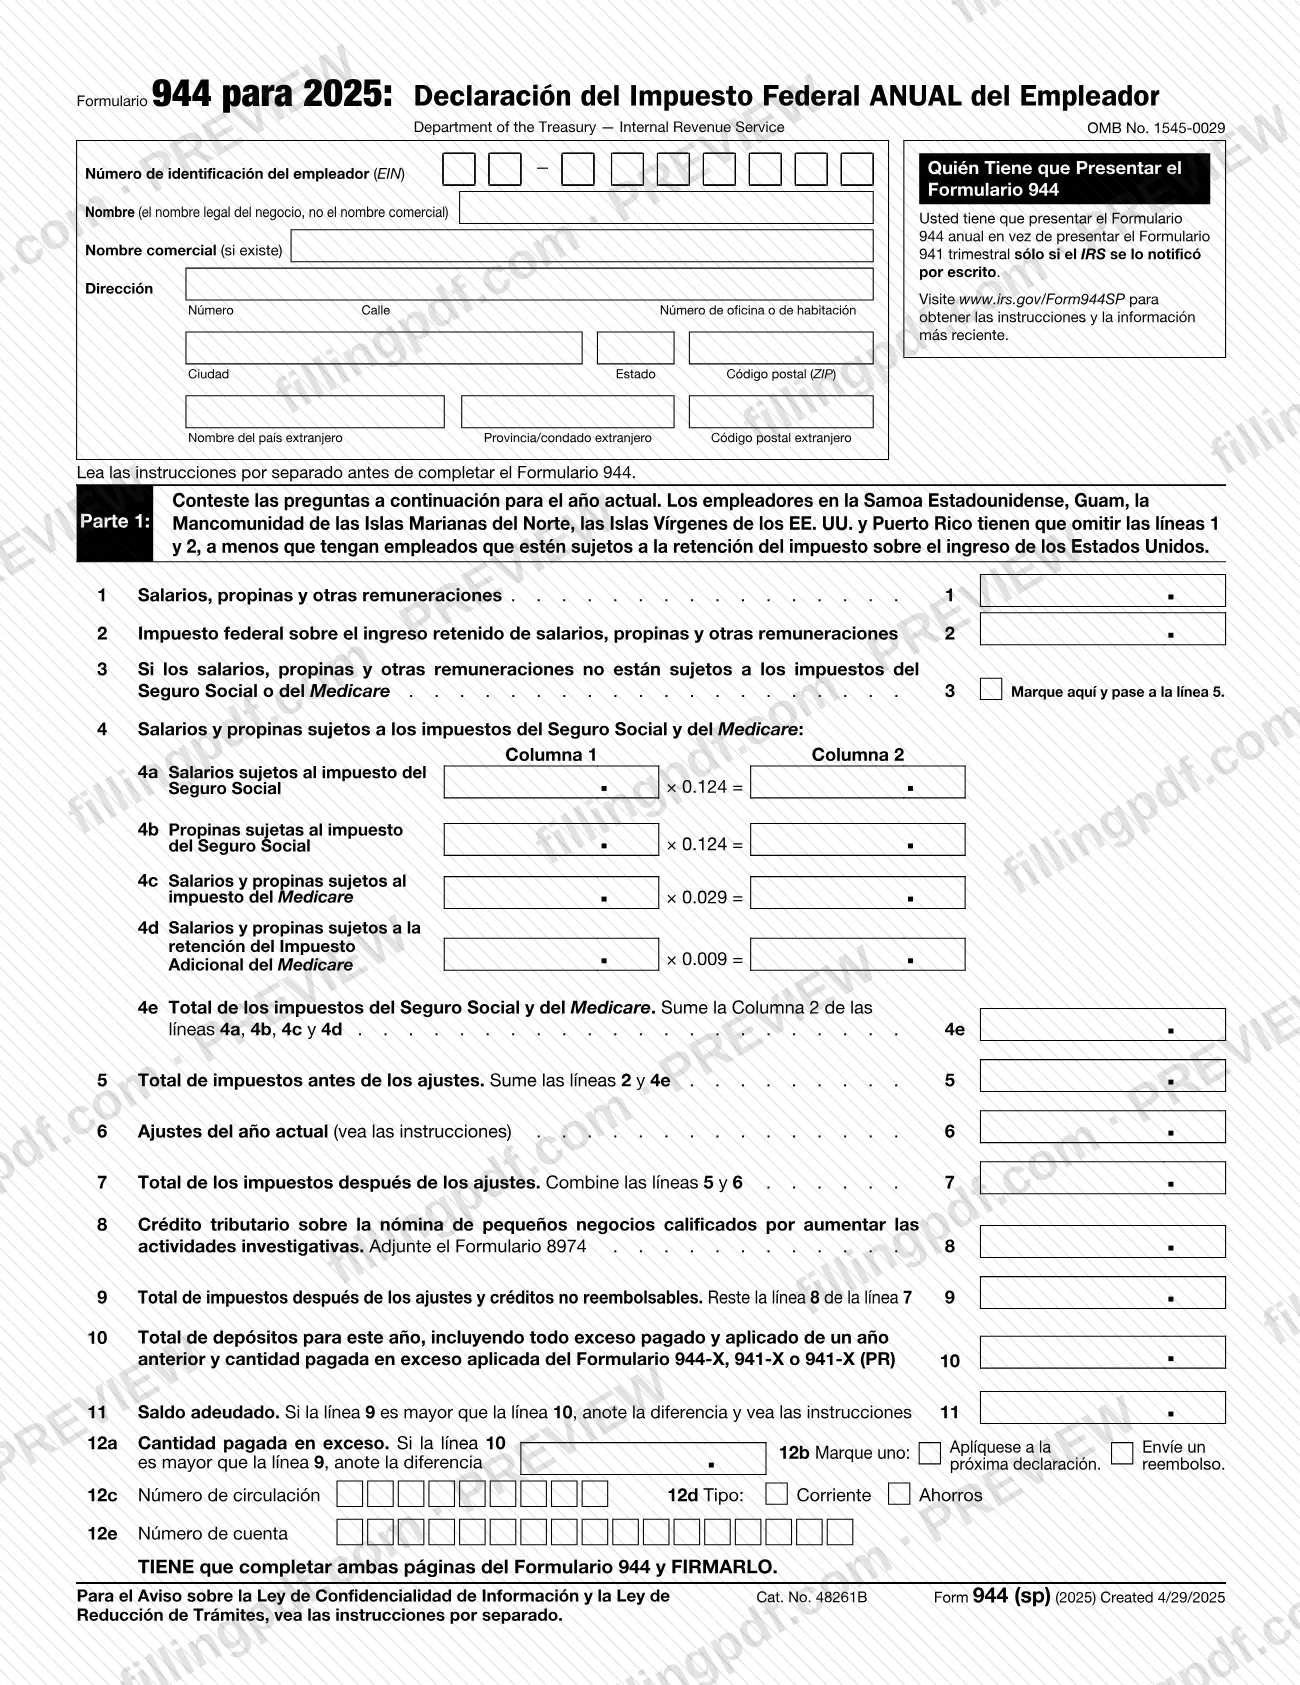
Form 944 (sp), Employer's ANNUAL Federal Tax Return (Spanish Version), is the Internal Revenue Service (IRS) form, printed in Spanish, on which small employers report wages, tips, withheld federal income tax and Social Security and Medicare taxes once a year instead of every quarter.
The IRS designed Form 944 for the smallest employers, those whose annual liability for Social Security, Medicare and withheld federal income taxes is $1,000 or less. The (sp) edition carries the same lines as Form 944 under OMB No. 1545-0029, with Spanish labels, and is read with the Spanish Instructions for Form 944.
The return has five parts:
- Part 1: lines 1 to 12, covering wages, withheld income tax, Social Security and Medicare taxes, adjustments, credits, deposits, balance due or overpayment.
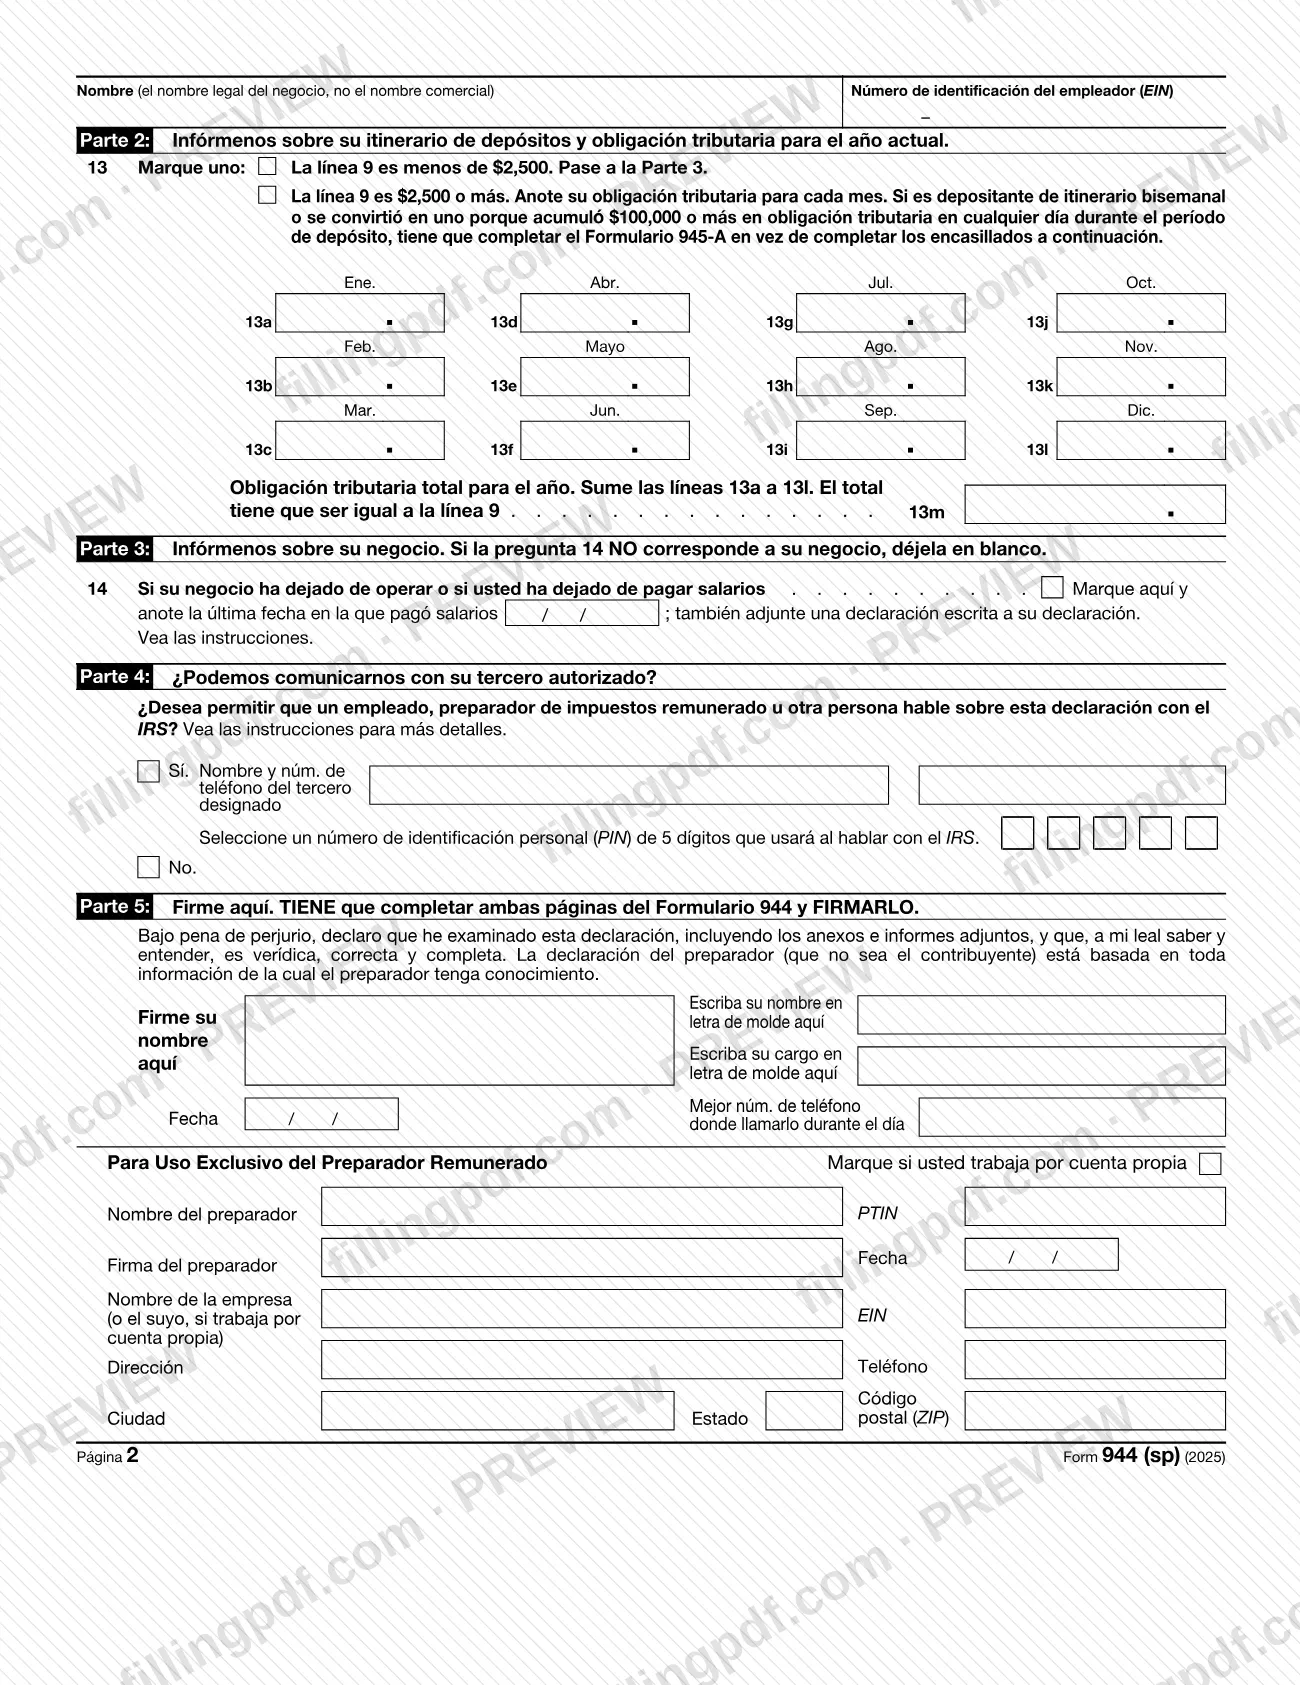
- Part 2: line 13, the monthly tax liability, needed when line 9 is $2,500 or more.
- Part 3: line 14, for a business that has stopped operating or paying wages.
- Part 4: the third-party designee.
- Part 5: the signature and the paid preparer section.
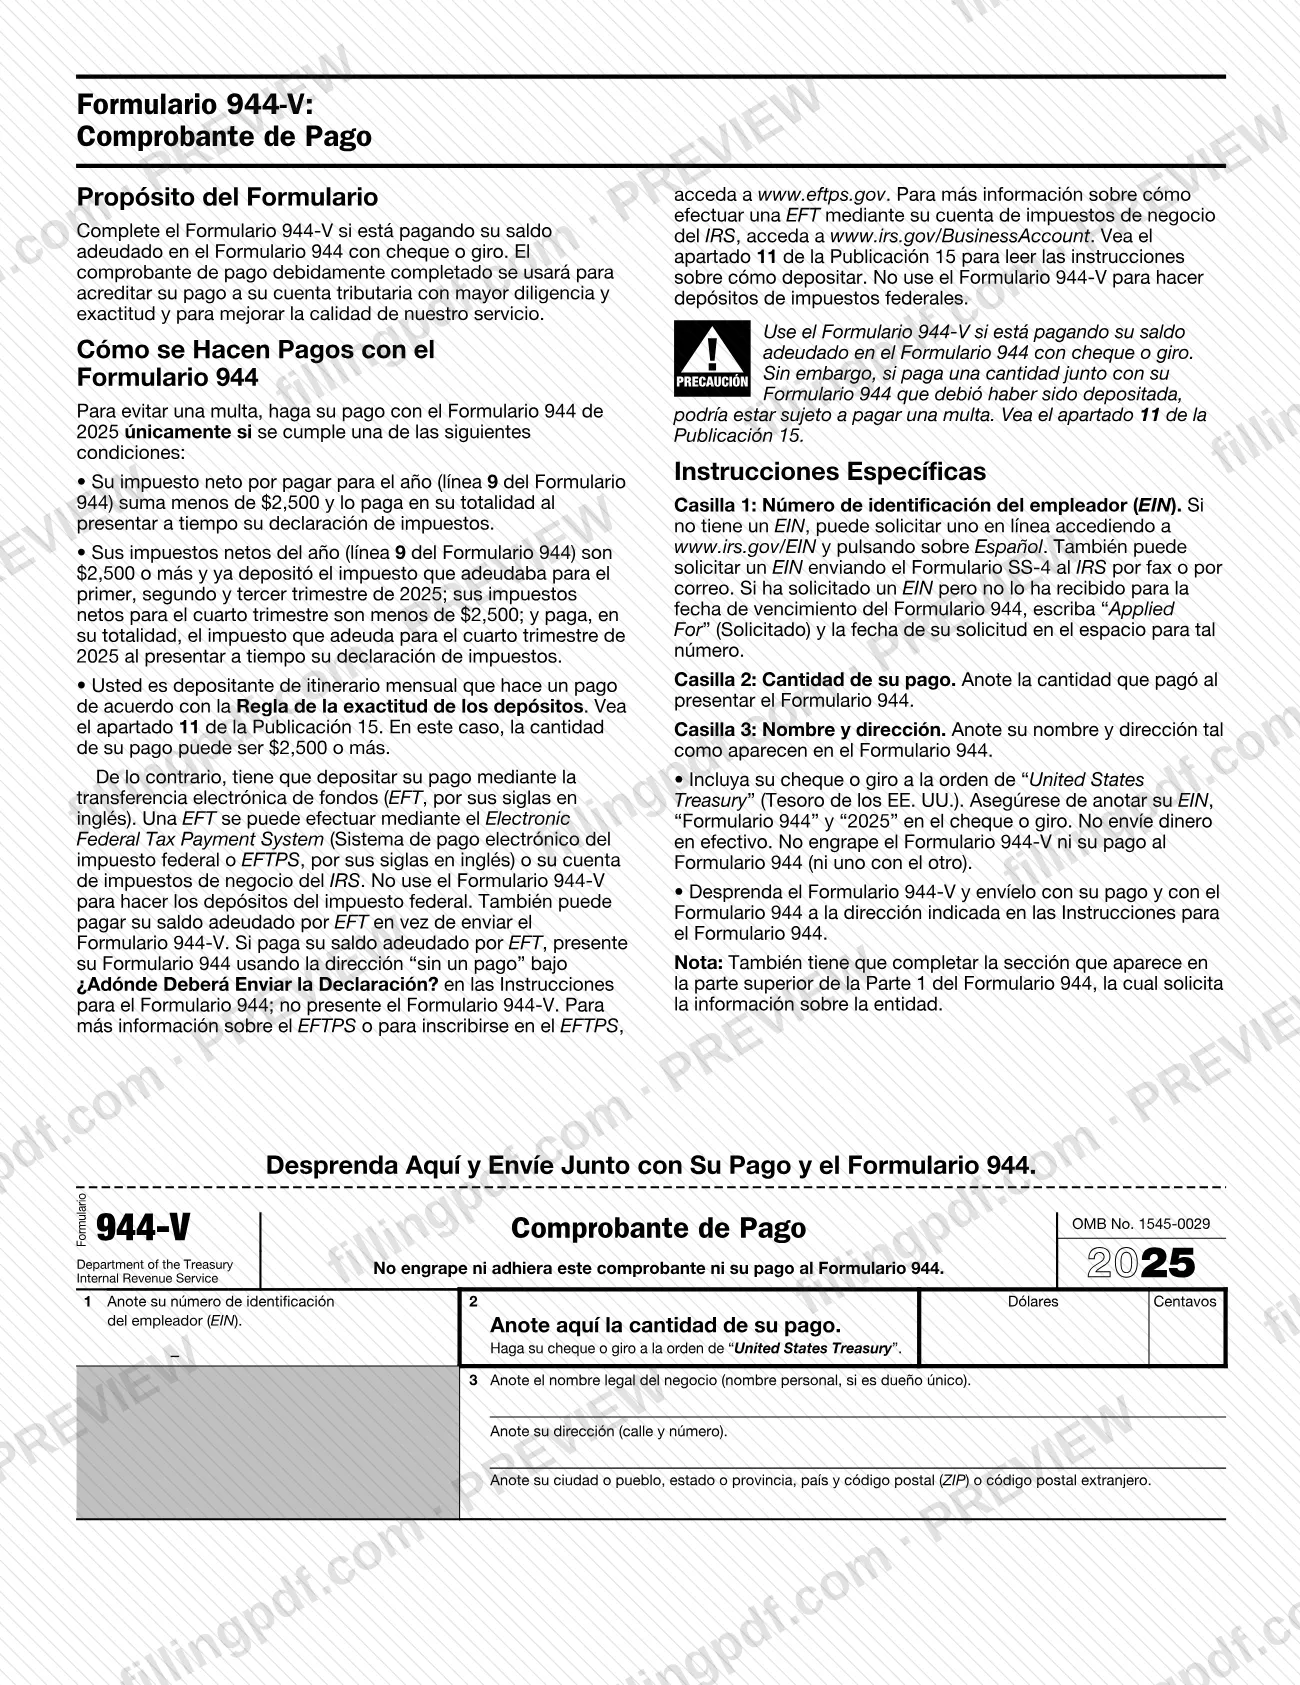
The PDF also includes Form 944-V, the payment voucher used when you pay a balance due by check or money order.
Form 944 replaces the quarterly Form 941 only for employers the IRS has notified. It is not used to correct an earlier return: errors on a filed Form 944 are fixed on a separate Form 944-X.
Who needs to file 944 (sp)?
Employers whom the IRS has notified in writing to file Form 944 file it in place of quarterly Forms 941. If you were notified, you file Form 944, not Form 941, even if your 2025 tax liability exceeds $1,000.
Do not file Form 944 if you are in one of these groups:
- You employ only household employees (see Publication 926 and Schedule H (Form 1040)).
- You employ only agricultural employees (see Publication 15 and Form 943).
- The IRS notified you to file quarterly Forms 941, including when you asked for and received written confirmation of the change.
- The IRS has not notified you to file Form 944. If you want to file it anyway for 2026 and expect payroll tax liability of $1,000 or less, the IRS instructions say to call 800-829-4933 (267-941-1000 from outside the United States, toll call) between January 1, 2026 and April 1, 2026, or send a written request postmarked between January 1, 2026 and March 16, 2026. Employers who want to switch from Form 944 to Form 941 use the same procedure.
Employers in the U.S. territories who were not notified to file Form 944 file Form 941 or, if they prefer Spanish, Form 941 (sp).
Who signs: the sole proprietor; an authorized officer of a corporation; a partner, member or other responsible officer of a partnership or other unincorporated business; the owner of a single-member LLC treated as a disregarded entity; the fiduciary of a trust or estate; or an agent holding a valid power of attorney on file with the IRS. A paid preparer also signs the preparer section.
When to file 944 (sp)
For 2025, file Form 944 (sp) by February 2, 2026. If you made timely deposits that paid your total tax for the year in full, you may file by February 10, 2026.
File only one Form 944 for each calendar year. If you filed it electronically, do not also send a paper return. A paper return that arrives late is treated as timely if the envelope is properly addressed, has enough postage and carries a U.S. Postal Service postmark, or a date from an IRS-approved private delivery service, no later than the due date.
If you close your business permanently or stop paying wages, the 2025 return is your final return: check the box on line 14 and enter the last date you paid wages. If you sell or transfer the business in 2025, you and the new owner each file Form 944 or 941, whichever applies, for the year of the transfer, reporting only the wages you paid.
Late returns and late payments are charged penalties and interest.
Documents you need
- Form 8974, attached when you enter an amount on line 8 (qualified small business payroll tax credit for increasing research activities).
- Form 945-A, filed with the return if you are a semiweekly schedule depositor or became one by accumulating $100,000 or more in liability; do not complete lines 13a to 13m in that case.
- Written statement attached to the return if you check line 14 for a final return, giving the name of the person keeping the payroll records and the address where they will be kept.
- Written statement attached if you sold or transferred the business in 2025: new owner's name, type of entity, kind of change, date of change, and the person and address keeping payroll records.
- Form 944-V, payment voucher, sent with the return and a check or money order only if you pay a balance due that way; do not staple it to the return or the payment.
- Written statement (or Form 8655 on file) is not required of a reporting agent in general; a power of attorney on file is needed only when an agent signs for the taxpayer.
How to fill out 944 (sp)
Enter EIN, name and address
At the top of page 1, enter your EIN, the legal business name (not the trade name), a trade name only if you have one, and your address. Never use an SSN or ITIN; if you applied for an EIN but do not have it, write "Applied For" and the date. Repeat name and EIN at the top of page 2.
Report wages and withheld tax
Line 1: wages, tips and other compensation, matching box 1 of your Forms W-2. Line 2: federal income tax withheld. Employers in American Samoa, Guam, the CNMI, the U.S. Virgin Islands and Puerto Rico skip lines 1 and 2 unless they have employees subject to U.S. income tax withholding.
Mark line 3 if it applies
Check the box on line 3 only if the wages, tips and other compensation are not subject to Social Security or Medicare tax, then go to line 5. Otherwise leave it blank.
Complete lines 4a through 4e
Enter the amounts in column 1 for Social Security wages (4a), Social Security tips (4b), Medicare wages and tips (4c) and Additional Medicare Tax wages (4d), and multiply by the printed rates to fill column 2. Add the column 2 amounts of lines 4a to 4d on line 4e.
Figure lines 5 through 7
Line 5: add lines 2 and 4e. Line 6: current-year adjustments, shown with a minus sign (or parentheses) when they reduce tax. Line 7: combine lines 5 and 6.
Enter the research credit on line 8
If you claim the qualified small business payroll tax credit for increasing research activities, enter the amount from line 12 or, if applicable, line 17 of Form 8974, and attach Form 8974.
Compute total tax on line 9
Subtract line 8 from line 7. The result cannot be less than zero, and line 9 is the one line where you enter a zero value.
Enter deposits and balance due
Line 10: total deposits for the year, including overpayments applied from the prior year or from Form 944-X, 941-X or 941-X (PR). Line 11: if line 9 is more than line 10, enter the difference as the balance due.
Handle an overpayment on lines 12a to 12e
If line 10 is more than line 9, enter the difference on line 12a and never on line 11. On line 12b check one box: apply to next return or send a refund. For a refund by direct deposit, complete the routing number (12c), account type (12d) and account number (12e).
Report monthly liability in Part 2
On line 13, check the first box if line 9 is under $2,500 and go to Part 3. If line 9 is $2,500 or more, check the second box and enter the liability for each month on lines 13a to 13l; line 13m must equal line 9. Semiweekly depositors complete Form 945-A instead.
Answer Parts 3 and 4
Line 14: check the box and enter the last date you paid wages only if your business has stopped operating or paying wages, and attach the written statement; otherwise leave it blank. In Part 4, check Yes and give the designee's name, phone number and 5-digit PIN, or check No.
Sign, review and download the PDF
In Part 5, sign, print your name and title, and enter the date and daytime phone number; a paid preparer completes the preparer section. Confirm both pages are complete and that name and EIN are on page 2, then download or print the completed PDF from FillingPDF.
How to submit 944 (sp)
You can file Form 944 (sp) electronically or on paper by mail; the IRS encourages e-filing.
- Electronically: see IRS.gov/EmploymentEfile. A fee may be charged for e-filing. If you e-file, a valid EIN is required and you do not mail a paper return.
- By mail, with a payment: Internal Revenue Service, P.O. Box 932100, Louisville, KY 40293-2100, with Form 944-V.
- By mail, without a payment: the address depends on your state. The table in the IRS instructions assigns states to Department of the Treasury, Internal Revenue Service, Kansas City, MO 64999-0044 (for example Connecticut, Georgia, New York, Ohio) or Department of the Treasury, Internal Revenue Service, Ogden, UT 84201-0044 (for example California, Florida, Texas). Employers with no state location use Internal Revenue Service, P.O. Box 409101, Ogden, UT 84409. Tax-exempt organizations and government entities use the Ogden, UT 84201-0044 address.
- Private delivery services: only IRS-approved services count for timely filing, and they cannot deliver to P.O. boxes. Street addresses are at IRS.gov/PDSstreetAddresses.
Do not send the return or any payment to the Social Security Administration. Staple all sheets at the top left, and do not staple Form 944-V or your payment to the return.
Payment: if line 9 is $2,500 or more you generally must deposit by electronic funds transfer (EFTPS or your IRS business tax account). A balance due can also be paid by card, electronic funds withdrawal, or check or money order payable to "United States Treasury" with your EIN, "Formulario 944" and the tax year written on it. FillingPDF lets you fill out and download the PDF; submission follows the channels above.
Common mistakes to avoid
- Filing Form 944 (sp) when the IRS has not notified you in writing to do so, or when you were notified to file quarterly Forms 941.
- Entering your Social Security number or ITIN instead of the EIN, or leaving the name and EIN off page 2.
- Completing only page 1, or not signing page 2; both pages must be completed and the return signed.
- Entering dollar signs or decimal points, rounding to whole dollars, or omitting cents; the instructions say always enter the cents, even when they are zeros.
- Entering zero on lines other than line 9; leave zero-value entries blank except line 9.
- Entering an amount on both line 11 and line 12a; never enter an amount on both.
- Making the monthly total on line 13m different from line 9; the two must match for deposits to count as timely.
- Stapling Form 944-V or the payment to the return, or using Form 944-V for federal tax deposits.
- Paying with the return an amount that should have been deposited, which can bring a penalty.
- Mailing the return or payment to the Social Security Administration, or filing a paper return after e-filing.
Frequently asked questions
What is Form 944 (sp)?
Form 944 (sp) is the Spanish-language edition of the IRS Form 944, Employer's ANNUAL Federal Tax Return, for tax year 2025. Smaller employers use it to report wages, tips, withheld federal income tax and Social Security and Medicare taxes once a year instead of on quarterly Forms 941.
Who has to file Form 944 instead of Form 941?
Only employers the IRS has notified in writing to file Form 944. Once notified, you file it even if your 2025 liability exceeds $1,000. Employers with only household or only agricultural employees cannot file it, and neither can employers the IRS has not notified.
When is Form 944 (sp) due for 2025?
The due date is February 2, 2026. If you made timely deposits that paid your total tax for the year in full, you may file by February 10, 2026. File only one Form 944 per calendar year, and do not send a paper copy if you e-filed.
Where do I mail Form 944 (sp)?
With a payment, mail it to Internal Revenue Service, P.O. Box 932100, Louisville, KY 40293-2100. Without a payment, the address depends on your state: Kansas City, MO 64999-0044 or Ogden, UT 84201-0044, as listed in the IRS instructions. Do not send it to the Social Security Administration.
Can I file Form 944 (sp) electronically?
Yes. The IRS encourages e-filing and points to IRS.gov/EmploymentEfile. A fee may be charged for e-filing, and a valid EIN is required when you file. If you e-file, do not also mail a paper Form 944.
How do I pay the balance due on Form 944 (sp)?
If line 9 is under $2,500, you can pay with the return by electronic funds transfer, card, electronic funds withdrawal, or check or money order with Form 944-V. If line 9 is $2,500 or more, you generally must deposit by electronic funds transfer instead.
What if my business closes before filing?
File a final return: check the box on line 14 and enter the last date you paid wages. Attach a written statement naming the person who will keep the payroll records and the address where they will be kept.
How do I correct a Form 944 I already filed?
Use Form 944-X, which is filed separately from Form 944. Do not send a second Form 944 for the same year. The Instructions for Form 944-X and section 13 of Publication 15 explain the correction process.
Can I fill out Form 944 (sp) online on FillingPDF?
Yes. You can fill out the fillable PDF online on FillingPDF and download or print it. FillingPDF is independent of the IRS and does not file the return; you submit it through the IRS channels described under How to submit.
Ready to fill out 944 (sp)?
Fill out 944 (sp) now